
- Home
- »
- Communications Infrastructure
- »
-
Data Center Automation Market Size Report, 2026-2033GVR Report cover

Data Center Automation Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Solution, Services), By Deployment (Cloud, On-premise), By Enterprise Size (Large Enterprise), By End-use (IT & Telecom, BFSI, Healthcare), By Region, And Segment Forecasts
Market Size, 2025
$11.6BMarket Estimate, 2026
$13.4BMarket Forecast, 2033
$43.2BCAGR, 2026–2033
18.1%Data Center Automation Market Summary
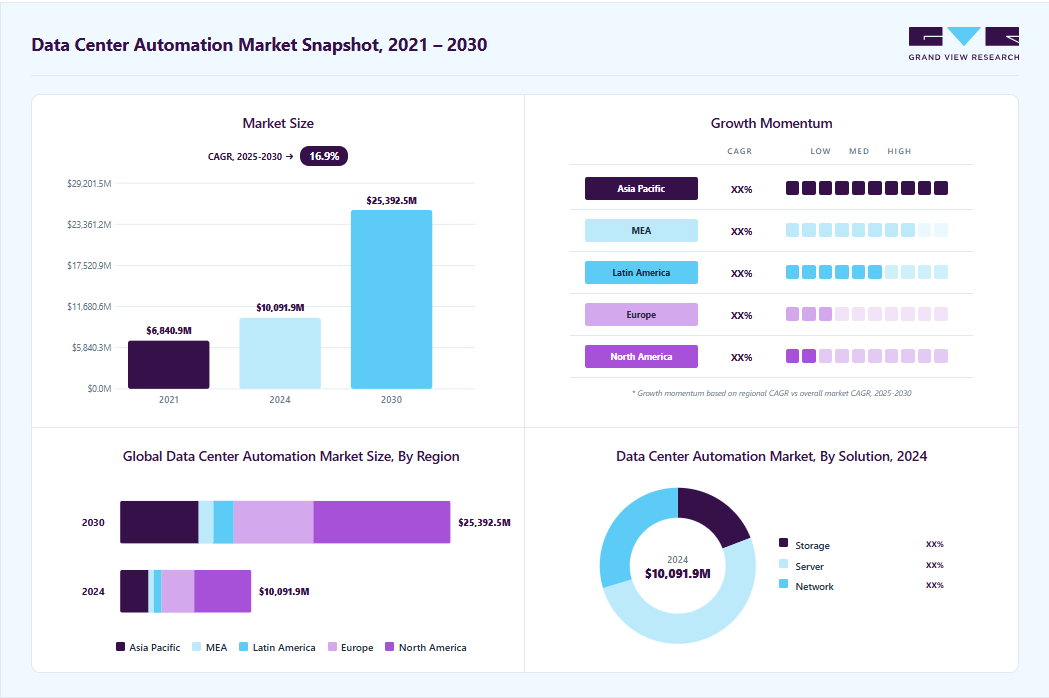
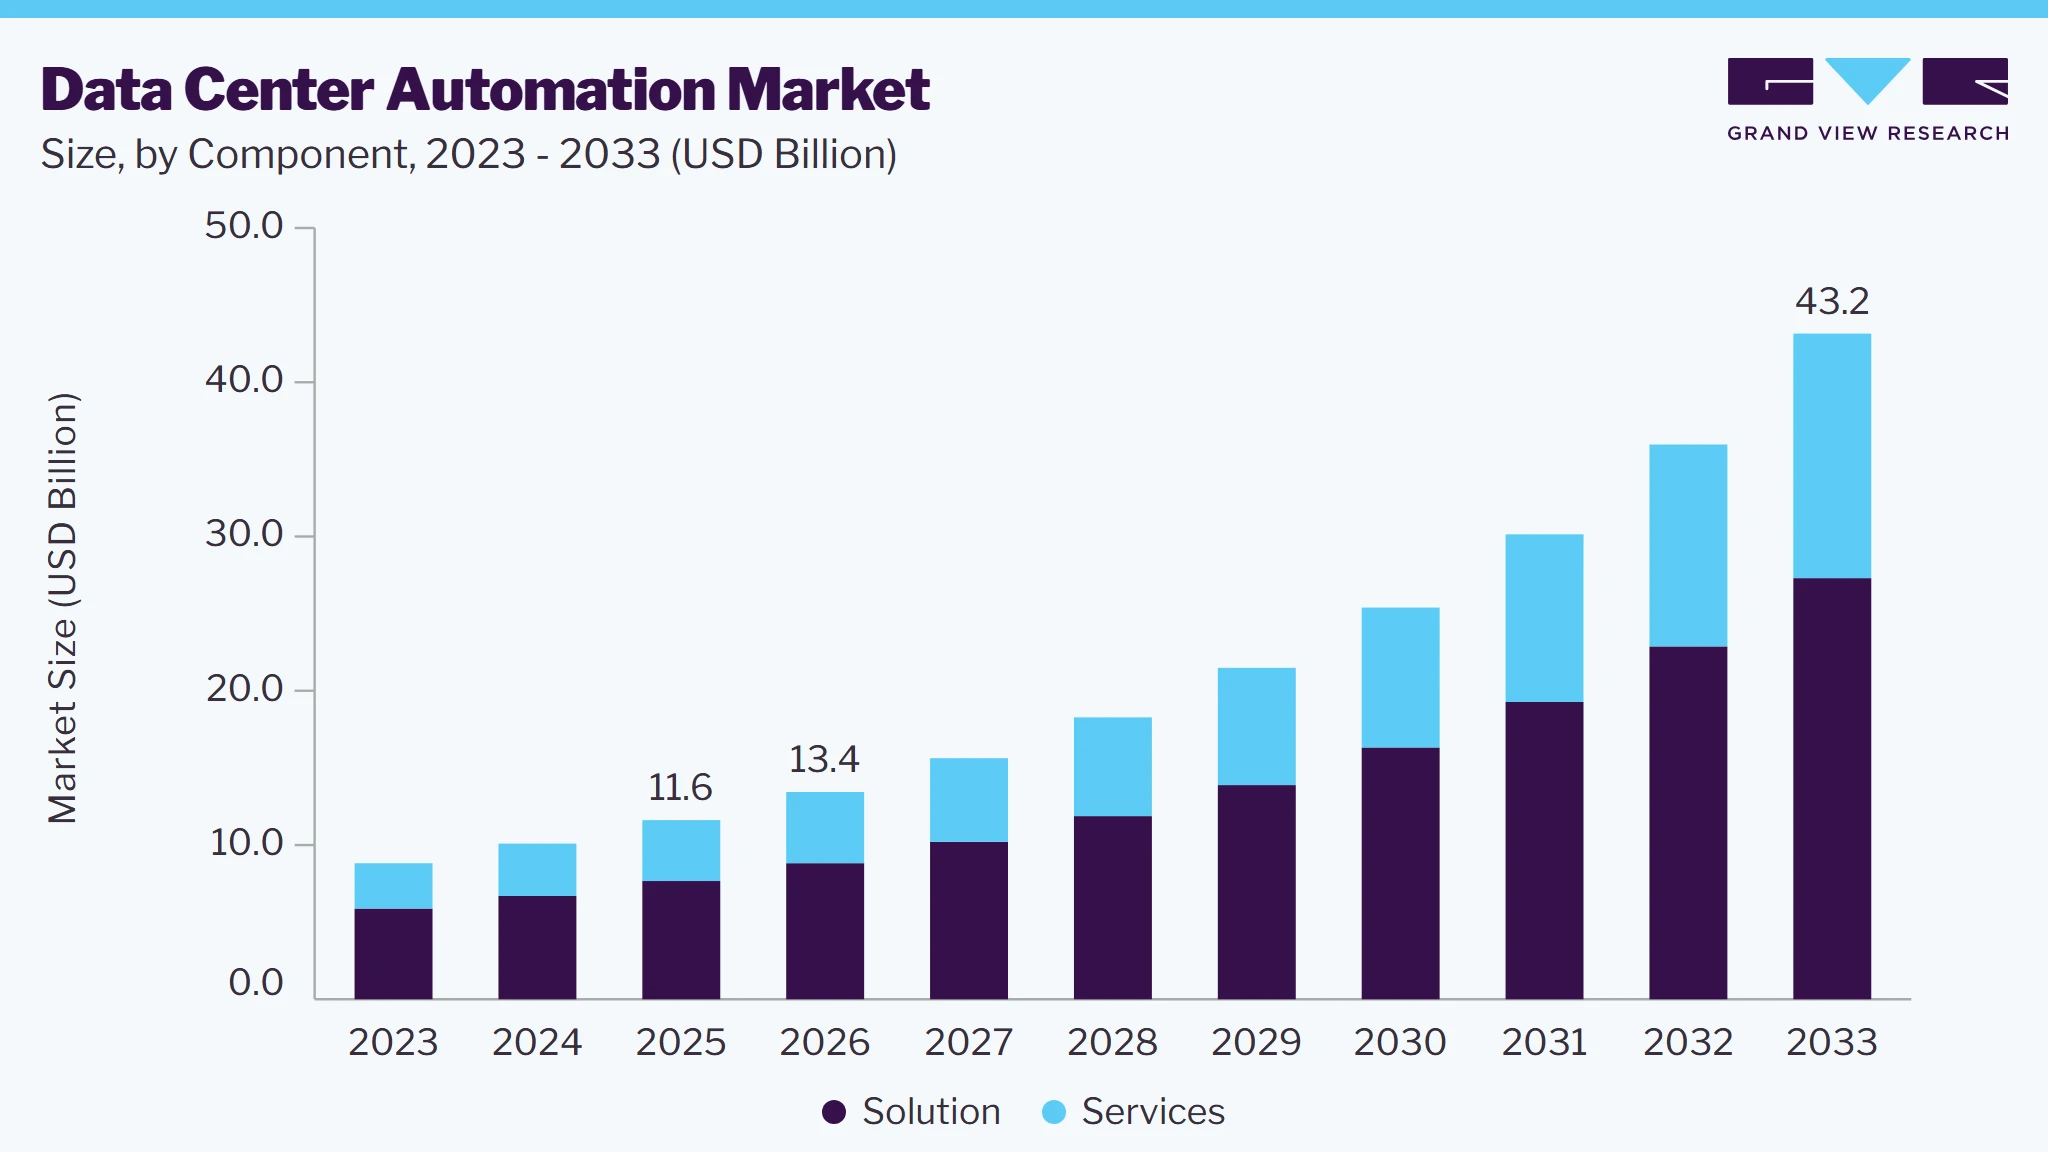
The global data center automation market size was valued at USD 11.6 billion in 2025 and is projected to grow from USD 13.4 billion in 2026 to USD 43.2 billion in 2033, at a CAGR of 18.1% from 2026 to 2033. North America dominated the market, accounting for the revenue share of 41.2% in 2025. The widespread adoption of artificial intelligence (AI), generative AI, and high-performance computing is significantly increasing infrastructure complexity across North American data centers.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Solution segment dominated the market, with a revenue share of 66.0% in 2025.
- By deployment: On-Premise segment held the largest market share of 52.8% in 2025.
- By enterprise size: Large enterprises segment held the largest revenue share of 68.6% in 2025.
- By end use: IT & Telecom segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (41.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 11.6 Billion
- Estimated market size in 2026: USD 13.4 Billion
- Projected market size by 2033: USD 43.2 Billion
- CAGR (2026-2033): 18.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Automation platforms streamline GPU cluster provisioning, workload scheduling, resource allocation, and cooling optimization, enabling organizations to maximize compute utilization while maintaining high availability and minimizing manual intervention.As enterprises increasingly migrate to hybrid and multi-cloud environments, the need for automated systems to manage complex IT infrastructures has grown significantly. Automation technologies enable data centers to streamline workflows, enhance resource allocation, and minimize human intervention, thereby reducing the potential for error and downtime. In addition, advancements in AI and machine learning are further propelling automation capabilities, enabling predictive maintenance, optimized energy usage, and improved system resilience. Rising data volumes from digital transformation initiatives across sectors such as finance, healthcare, and retail are also fueling this demand as companies seek to manage large datasets more effectively while ensuring compliance and security.
 To learn more about this report, Download Free Sample Report
The escalating demand for efficiency, scalability, and reduced operational costs in managing modern data centers is a key driver of the data center automation market. As organizations face growing complexities in data management, fueled by surging data volumes and the adoption of hybrid and multi-cloud infrastructures, they increasingly seek automation solutions to streamline operations. Automation enables data centers to optimize resource allocation, enhance workload management, and lower operational expenses by reducing reliance on manual processes, which are often time-consuming and prone to error. Scalability, a critical requirement for adapting to fluctuating workloads, is supported by automation tools that allow data centers to adjust capacity without significant cost increases dynamically. Furthermore, automation mitigates downtime risks, enhances resilience, and enables predictive maintenance, thus directly contributing to cost efficiency and operational stability. This convergence of needs positions data center automation as essential for modern enterprises striving to remain competitive and agile in an increasingly data-intensive environment.
The growing awareness about the advances in the latest technologies and the growing use of solutions based on automation is expected to drive the growth of the data center automation market across various industries over the forecast period. Increasing automation trends in the manufacturing and healthcare industries are gaining global traction, which is driving the growth of the market. Several manufacturing companies are embracing data center automation to reduce operational expenses (OPEX) and increase the entire manufacturing process's effectiveness.
The rise of cloud computing, artificial intelligence, and machine learning to support data center management means less monotonous activities and more time and energy for high-level issues. The transition to AI-powered computing is also having a huge impact on data centers. Data center workers can prepare for the AI computing transition by broadening their understanding of AI and machine learning as applied to application use cases. This allows the business to develop new services and products and achieve a competitive advantage in the market.
Market Dynamics
The data center automation market is witnessing strong growth as organizations increasingly modernize IT infrastructure to support cloud computing, artificial intelligence (AI), hybrid and multi-cloud environments, edge computing, and digital transformation initiatives. Data center automation solutions enable enterprises, hyperscale cloud providers, colocation operators, telecommunications companies, financial institutions, government agencies, and healthcare organizations to automate infrastructure provisioning, configuration management, workload orchestration, resource allocation, monitoring, and lifecycle management. By reducing manual intervention, improving operational efficiency, and minimizing human errors, automation enhances data center agility, reliability, scalability, and service availability. The rapid expansion of hyperscale and edge data centers, coupled with the growing complexity of distributed IT environments, is significantly increasing demand for intelligent automation platforms capable of managing compute, storage, networking, security, and power infrastructure from a centralized framework. Furthermore, rising adoption of Infrastructure-as-Code (IaC), Software-Defined Data Centers (SDDC), containerized applications, Kubernetes, DevOps, and AIOps is accelerating the implementation of automated provisioning, policy-based management, predictive maintenance, and self-healing infrastructure across modern data centers. Additionally, continuous advancements in AI-driven orchestration, machine learning-based analytics, digital twins, robotic process automation (RPA), and autonomous infrastructure management are expected to further accelerate the growth of the data center automation market over the forecast period.
The increasing adoption of hybrid cloud environments and Software-Defined Data Centers (SDDC) is a major driver of the data center automation market. Enterprises are modernizing their IT infrastructure to support cloud-native applications, distributed workloads, and digital transformation initiatives, creating a need for automated provisioning, configuration, orchestration, and lifecycle management. Data center automation enables organizations to efficiently manage compute, storage, networking, and security resources through centralized policy-based controls while reducing manual intervention and operational complexity. As businesses continue expanding hybrid and multi-cloud deployments, demand for intelligent automation solutions that improve scalability, service availability, and operational efficiency is accelerating globally.
High implementation complexity and integration with legacy infrastructure remain significant restraints for the data center automation market. Many organizations operate heterogeneous IT environments consisting of legacy hardware, multiple virtualization platforms, and diverse management tools that are difficult to automate through a unified platform. Deploying automation solutions often requires significant investments in software, infrastructure modernization, system integration, employee training, and process redesign. Additionally, concerns related to cybersecurity, operational disruptions during migration, interoperability issues, and the shortage of skilled automation professionals can delay implementation, particularly among small and medium-sized enterprises (SMEs) with limited IT resources and budgets.
The growing adoption of AI-driven automation and autonomous data center operations presents a significant opportunity for the data center automation market. Organizations are increasingly leveraging artificial intelligence, machine learning (ML), AIOps, predictive analytics, and digital twins to automate infrastructure monitoring, workload optimization, predictive maintenance, capacity planning, and incident response. These intelligent automation capabilities improve operational efficiency, minimize downtime, optimize energy consumption, and enable self-healing infrastructure with minimal human intervention. Furthermore, the rapid expansion of hyperscale cloud facilities, edge data centers, and sustainable digital infrastructure is creating new opportunities for automation vendors. As enterprises continue investing in intelligent infrastructure management and autonomous IT operations, demand for advanced data center automation platforms is expected to grow substantially over the forecast period.
Analyst Perspective
The data center automation market is driven by the rapid adoption of hybrid and multi-cloud environments, AI, edge computing, SDDC, and complex IT infrastructures. Enterprises, hyperscalers, colocation providers, and other organizations are investing in automation solutions to streamline provisioning, workload orchestration, monitoring, and infrastructure management while reducing manual intervention and improving operational efficiency. Growing investments in hyperscale and edge data centers, AI-powered infrastructure management, digital twins, autonomous operations, and energy optimization are expected to further support market growth. As enterprises increasingly adopt cloud-native and autonomous infrastructure, demand for scalable, interoperable, and intelligent automation platforms is expected to rise globally.
Component Insights
Based on component, the solution segment led the market with the largest revenue share of 66.0% in 2025 and is expected to grow at the significant CAGR over the forecast period, driven by the need for integrated platforms that can streamline data center operations and enhance overall infrastructure efficiency. Solutions, including automation software and infrastructure management tools, enable organizations to automate repetitive tasks, optimize resource allocation, and improve data center uptime. These solutions also facilitate seamless integration with existing IT environments, allowing for more flexible and scalable infrastructure management. As data centers grow in complexity, organizations are increasingly investing in comprehensive solutions to reduce operational bottlenecks, enhance performance, and improve energy efficiency.
The services segment is expected to grow at a significant rate during the forecast period, propelled by the rising demand for expertise and support in implementing, maintaining, and optimizing automated data center systems. Services, such as consulting, integration, and managed services, are essential for organizations seeking to customize automation tools to meet specific operational needs and ensure smooth implementation. Moreover, ongoing support and maintenance services are crucial for sustaining performance, mitigating cybersecurity risks, and keeping automation systems up to date. As businesses face rapid technological changes, they rely on service providers to deliver expert insights, continuous support, and strategic guidance to maximize the long-term value of their automation investments.
Deployment Insights
Based on deployment, the on-premise segment led the market with the largest revenue share of 52.8% in 2025, largely driven by organizations prioritizing data security, control, and regulatory compliance. On-premise solutions enable companies to maintain direct oversight over their infrastructure, which is particularly crucial for industries handling sensitive data, such as finance, healthcare, and government. This deployment approach allows for tailored security protocols and ensures that data resides within a controlled environment, mitigating potential risks associated with third-party data management. In addition, companies with legacy systems or specific operational requirements find on-premise automation beneficial for seamless integration and customization, supporting unique workloads and compliance standards without sacrificing control or visibility.
The cloud segment is expected to grow at a significant rate during the forecast period, propelled by the growing need for scalability, flexibility, and cost-effectiveness in data center management. Cloud-based automation allows organizations to expand or reduce their infrastructure dynamically, enabling agile responses to fluctuating workloads without the need for significant capital investments in physical infrastructure. This model supports a faster deployment of automation tools, reduces maintenance overhead, and enables remote management, which is advantageous for global enterprises and distributed teams. Furthermore, advancements in cloud security and compliance frameworks are alleviating concerns over data privacy, making cloud-based automation increasingly viable across various industries looking to streamline operations, enhance resilience, and lower operational costs.
Enterprise Size Insights
Based on enterprise size, the large enterprises segment led the market with the largest revenue share of 68.6% in 2025. The adoption of the data center automation market among large enterprises is primarily driven by their need to manage vast, complex IT infrastructures with greater efficiency, scalability, and resilience. With extensive data volumes and highly distributed environments, large organizations seek automation solutions to streamline workflows, reduce manual oversight, and optimize resource utilization. Automation tools enable large enterprises to minimize downtime, lower operational costs, and respond to growing demands for data processing and storage while ensuring compliance with regulatory requirements. In addition, automation supports robust security measures, predictive maintenance, and real-time monitoring, all of which are essential for enterprises managing critical operations on a global scale. This focus on improving operational agility and resilience makes data center automation a strategic investment for large enterprises.
The small & medium enterprise segment is expected to grow at a significant rate during the forecast period. For small and medium enterprises (SMEs), the adoption of data center automation is largely driven by the need for cost efficiency, agility, and simplified IT management. SMEs often operate with limited resources, making automation a valuable tool for optimizing operational processes without requiring extensive human intervention. Automation solutions enable SMEs to improve productivity, maintain uptime, and scale their infrastructure as their business grows without incurring significant costs. In addition, by automating routine tasks, SMEs can allocate their resources toward innovation and growth-focused initiatives. The cloud-based deployment of automation solutions is particularly appealing to SMEs, offering flexible, affordable options that eliminate the need for substantial capital investments in physical infrastructure while still providing robust support for their evolving IT needs.
End-use Insights
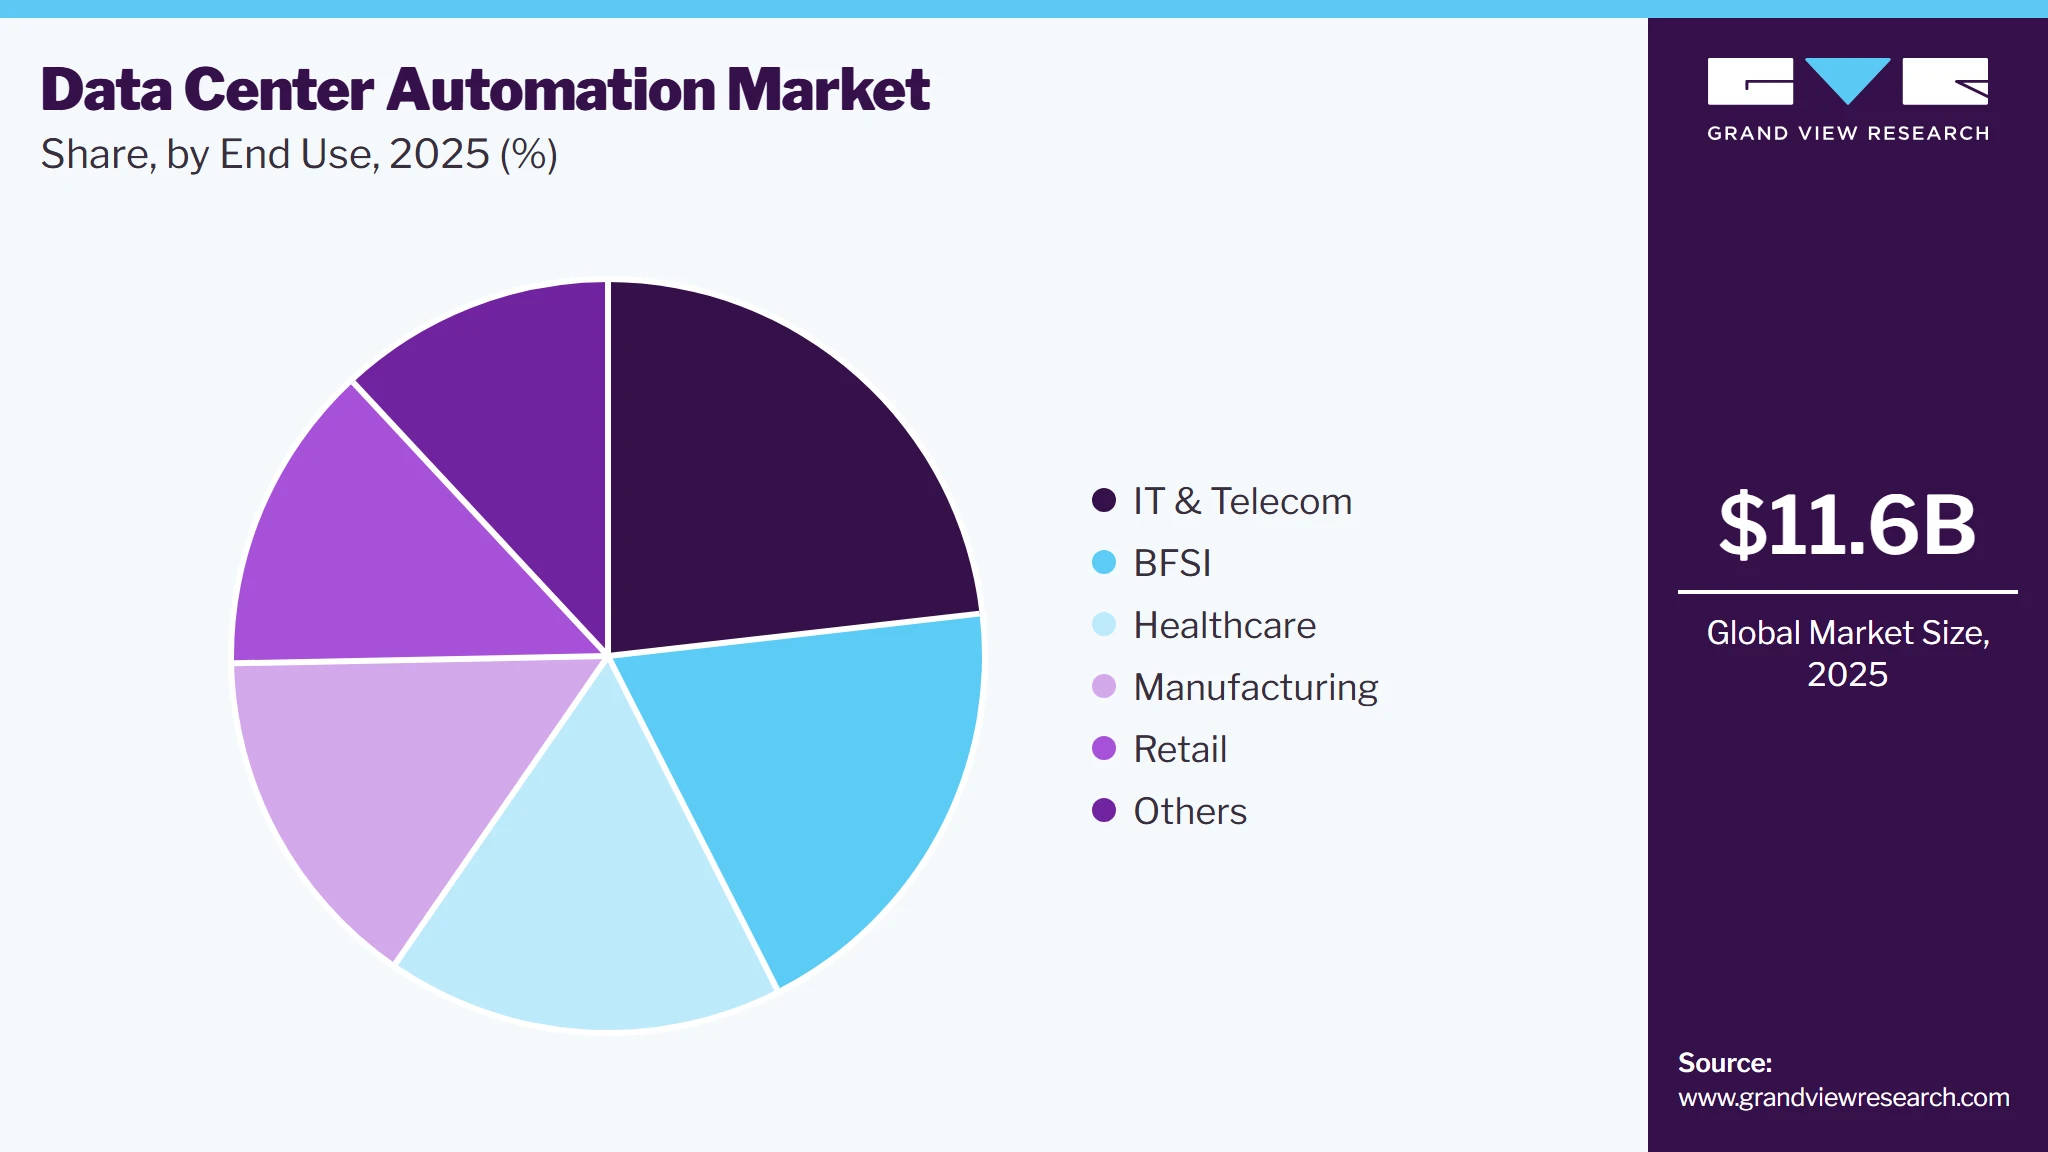
Based on end use, the IT & Telecom segment led the market with the largest revenue share of 23.2% in 2025, primarily driven by the industry’s need to manage vast data volumes, maintain network uptime, and deliver seamless digital services. As digital connectivity and mobile data usage surge, IT and telecom companies rely on automation to streamline data center operations, optimize resource allocation, and minimize manual processes. Automation enables them to support rapid scaling, handle unpredictable workloads, and ensure high availability for critical infrastructure. Moreover, data center automation supports proactive monitoring, predictive maintenance, and robust security protocols, which are essential for minimizing downtime and maintaining uninterrupted service delivery in this highly competitive and fast-evolving industry. As IT and telecom companies expand their infrastructure to support 5G, IoT, and other advanced technologies, automation provides the necessary operational agility and efficiency to keep pace with these advancements.
 To learn more about this report, Download Free Sample Report
The BFSI segment is expected to grow at a significant rate during the forecast period. In the BFSI sector, the adoption of data center automation is primarily driven by stringent regulatory requirements, data security needs, and the demand for operational efficiency. Financial institutions handle sensitive and high-volume transactions, which require consistent reliability, speed, and security. Automation in data centers helps BFSI companies achieve greater control over their IT environments, ensuring compliance with industry regulations, enhancing data protection, and reducing the risks associated with human error. In addition, automation enables real-time data processing, reduces latency, and supports 24/7 operational continuity, all of which are critical for financial transactions and customer services. With automation, BFSI organizations can improve disaster recovery capabilities, enhance fraud detection, and manage their IT resources more efficiently, enabling them to adapt to changing market demands and deliver secure, uninterrupted services to customers.
Regional Insights
North America dominated the data center automation market with the largest revenue share of 41.2% in 2025. In North America, the market is witnessing a significant trend towards hybrid cloud environments, driven by the increasing adoption of multi-cloud strategies among enterprises. Organizations are seeking to integrate their on-premise infrastructure with cloud services to enhance flexibility and scalability while optimizing operational costs. Furthermore, there is a growing emphasis on advanced technologies such as AIML for predictive analytics and intelligent automation, which help in optimizing resource allocation and improving operational efficiency.
 To learn more about this report, Download Free Sample Report
U.S. Data Center Automation Market Trends
The data center automation market in the U.S. held the largest share in the North America region in 2025. Edge computing is becoming increasingly important in Data Center Automation (EDM) as companies in the U.S. are looking to process data closer to its source, especially with the growth of the Internet of Things (IoT) devices. This approach reduces latency and bandwidth usage by performing data processing and analysis at the edge of the network, which is crucial for applications that require real-time insights and actions.
Europe Data Center Automation Market Trends
The data center automation market in Europe is growing significantly at a CAGR of over 16% from 2025 to 2030. In Europe, the market is characterized by a strong focus on sustainability and energy efficiency. European organizations are increasingly adopting automation solutions that enable better resource management and reduce energy consumption, aligning with the region's stringent environmental regulations and sustainability goals. The trend towards green data centers is gaining momentum, with businesses investing in technologies that optimize cooling systems, energy usage, and waste management processes.
The UK data center automation market is expected to grow rapidly in the coming years. In the UK, data center automation is driven primarily by rapid digital transformation across industries. With a focus on improving operational efficiency, reducing energy consumption, and meeting sustainability goals, enterprises are increasingly adopting automation solutions. The government's emphasis on digital infrastructure development and the rising demand for cloud computing further bolster the market.
The Germany data center automation market held a substantial market share in 2024. Germany's data center automation market is propelled by the country's established industrial base and commitment to Industry 4.0. The need to streamline data center operations and support IoT-based initiatives encourages automation. In addition, strict regulations regarding data security and energy efficiency push organizations toward advanced automation to ensure compliance.
Asia Pacific Data Center Automation Market Trends
The data center automation market in the Asia Pacific is growing significantly at a CAGR of over 18% from 2025 to 2030. In the Asia Pacific region, the market is experiencing rapid growth, driven by the expanding digital transformation initiatives across various industries. The increasing demand for cloud services and the proliferation of data centers in emerging economies are fostering a heightened focus on automation to streamline operations and manage the growing data influx. In addition, governments and enterprises are investing in infrastructure development and smart technologies, leading to a surge in the adoption of automation solutions that enhance efficiency, scalability, and cost-effectiveness.
The China data center automation market held a substantial market share in 2024. China's data center automation market benefits from strong government support for technology development. The rapid expansion of internet services, cloud adoption, and e-commerce drive the need for efficient data centers. Furthermore, automation is crucial to managing large-scale data facilities and reducing operational costs in this highly competitive environment.
The Japan data center automation market held a substantial market share in 2024. In Japan, the data center automation market is influenced by the country's focus on technology-driven innovation. Automation is essential in Japan's aging workforce context, where labor shortages make efficient data center management critical. Furthermore, the growth of AI and IoT solutions in Japan has heightened the need for automated data centers to support complex, data-intensive applications.
In India, the data center automation market is growing rapidly, driven by the rise of digital initiatives across sectors. India's data center automation market is growing due to increasing digitalization and the government's Digital India initiative. The demand for seamless data management from sectors such as telecom, IT, and BFSI is pushing companies toward automation to enhance productivity. In addition, the rise of cloud services and edge computing contributes to the adoption of data center automation solutions.
Key Data Center Automation Company Insights
Key players operating in the data center automation market include ABB, BMC Software, Inc., Cisco Systems, Inc., Citrix Systems, Inc., FUJITSU, Hewlett Packard Enterprise Development LP, Microsoft, Oracle, ServiceNow, and VMWare. The companies are focusing on various strategic initiatives, including new product development, partnerships & collaborations, and agreements to gain a competitive advantage over their rivals. The following are some instances of such initiatives.
-
In September 2024, ATS Global announced a partnership with ABB that enhances its capabilities in data center automation. This collaboration enables the design and implementation of solutions utilizing ABB Ability, ABB's platform for the control, monitoring, and optimization of mission-critical data center infrastructure, incorporating mechanical (BMS), electrical (EPMS), DCIM, and SCADA functionalities. ABB Ability offers numerous advantages, including the elimination of manual data entry for utilization metrics and other KPIs, real-time access to both aggregate and granular overviews of data center infrastructure, and the automation of cooling and electrical systems for continuous optimization and improved uptime. Coupled with the organization's extensive experience in over 100 mission-critical projects, this partnership is expected to enhance customer uptime and increase system availability, supported by prompt local assistance.
-
In June 2024, Cisco Systems announced a series of advancements intended to transform data center infrastructure, IT operations, and enterprise defenses. In collaboration with NVIDIA, Cisco introduced the Cisco Nexus HyperFabric AI cluster solution, an innovative end-to-end arrangement designed to expand generative AI workloads efficiently. This solution incorporates Cisco’s AI-native networking abilities with NVIDIA’s AI software and accelerated computing, further enhanced by VAST’s robust data storage platform.
Key Data Center Automation Companies
The following key companies have been profiled for this study on the data center automation market.
-
ABB
-
BMC Software, Inc.
-
Cisco Systems, Inc.
-
Citrix Systems, Inc.
-
FUJITSU
-
Hewlett Packard Enterprise Development LP
-
Microsoft
-
Oracle
-
ServiceNow
-
VMWare
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (IBM, Cisco Systems, Hewlett Packard Enterprise (HPE), Dell Technologies, VMware Microsoft)
- Established players focus on delivering comprehensive data center automation platforms that integrate infrastructure provisioning, orchestration, configuration management, workload scheduling, virtualization, AIOps, and hybrid cloud management.
- Their strategies emphasize AI-driven automation, Software-Defined Data Centers (SDDC), Infrastructure-as-Code (IaC), Kubernetes orchestration, strategic acquisitions, and partnerships with hyperscale cloud providers and enterprise IT vendors to expand intelligent infrastructure management capabilities.
- Established players possess extensive enterprise customer bases, strong global distribution networks, mature software ecosystems, and significant R&D investments.
- Their integrated portfolios spanning servers, storage, networking, virtualization, cloud management, cybersecurity, and automation enable end-to-end infrastructure management.
- Strong partner ecosystems, recurring subscription revenues, global support services, and deep expertise in hybrid cloud and enterprise IT provide a substantial competitive advantage.
- These companies face challenges related to integrating automation across heterogeneous legacy infrastructures, high development and maintenance costs, lengthy enterprise sales cycles, and increasing competition from cloud-native automation platforms.
- Complex product portfolios, interoperability issues, cybersecurity risks, and the need for continuous innovation in AI-driven automation may affect deployment speed and profitability.
Emerging Players (Nutanix, HashiCorp, Platform9, Rafay Systems, Park Place Technologies)
- Emerging players primarily focus on cloud-native automation, Infrastructure-as-Code (IaC), multi-cloud orchestration, Kubernetes management, AIOps, infrastructure observability, and automated lifecycle management.
- Their strategies emphasize SaaS-based delivery models, API-driven automation, DevOps integration, AI-powered infrastructure optimization, and partnerships with cloud providers and managed service providers to accelerate enterprise adoption.
- Emerging players offer agile development cycles, innovative automation capabilities, simplified deployment models, cloud-native architectures, and strong integration with DevOps, containers, and multi-cloud environments.
- Their flexible subscription pricing, rapid feature releases, and focus on automation-first platforms enable them to address evolving enterprise requirements more quickly than traditional infrastructure vendors.
- Emerging vendors often have limited global market presence, smaller customer bases, and fewer financial resources compared to established competitors.
- Dependence on strategic partnerships, lower brand recognition, integration challenges with legacy enterprise systems, and intense competition from large infrastructure and cloud vendors may limit scalability and enterprise adoption. They also face increasing pressure to expand product capabilities while maintaining interoperability across diverse IT environments.
Data Center Automation Market Report Scope
Report Attribute
Details
Market Size in 2025
USD 11.6 billion
Estimated Market Size in 2026
USD 13.4 billion
Projected Market Size by 2033
USD 43.2 billion
Growth rate
CAGR of 18.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component; deployment; enterprise; end use; region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
ABB; BMC Software, Inc.; Cisco Systems, Inc.; Citrix Systems, Inc.; FUJITSU; Hewlett Packard Enterprise Development LP; Microsoft; Oracle; ServiceNow; VMWare
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Data Center Automation Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global data center automation market report based on component, deployment, enterprise size, end-use, and region:
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Solution
-
Storage
-
Server
-
Network
-
-
Services
-
-
Deployment Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cloud
-
On-premise
-
-
Enterprise Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Small & Medium Enterprise
-
Large Enterprise
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
IT & Telecom
-
BFSI
-
Retail
-
Healthcare
-
Manufacturing
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
U.A.E
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The data center automation market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each data center automation segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Solution
Solutions comprise software platforms that automate the provisioning, configuration, monitoring, orchestration, and management of data center infrastructure. These solutions streamline operations across compute, storage, networking, security, power, and cooling systems while improving efficiency, reducing manual intervention, and enabling policy-driven infrastructure management.
Services
Services include consulting, implementation, integration, customization, training, maintenance, technical support, and managed services that assist organizations in deploying, optimizing, and maintaining data center automation solutions.
Segment - Deployment
Revenue capture definition
Cloud
Cloud deployment refers to data center automation solutions hosted on public, private, or hybrid cloud platforms. These solutions offer scalability, remote accessibility, automated updates, and flexible resource management without requiring extensive on-premises infrastructure.
On-premise
On-premise deployment refers to automation software installed and managed within an organization's own data center infrastructure. This deployment model provides greater control over data, security, compliance, and customization, making it suitable for organizations with stringent regulatory or operational requirements.
Segment - Enterprise Size
Revenue capture definition
Small & Medium Enterprise (SME)
The SMEs segment, with respect to the number of employees, generally includes organizations employing between 10 and 999 employees.
Large Enterprise
The Large enterprises segment, with respect to the number of employees, typically comprises organizations employing more than 1,000 employees for multinational corporations.
Segment - End Use
Revenue capture definition
IT & Telecom
The IT & Telecom sector uses data center automation to manage cloud infrastructure, telecommunications networks, virtualization platforms, edge computing environments, and hyperscale data centers while improving service delivery, network performance, and operational efficiency.
BFSI
Banks, financial institutions, and insurance companies deploy data center automation to ensure high system availability, automate infrastructure management, strengthen cybersecurity, support digital banking services, and comply with regulatory requirements.
Retail
Retail organizations use automation to manage e-commerce infrastructure, digital payment platforms, inventory systems, customer analytics, and omnichannel operations while ensuring scalability, business continuity, and optimized application performance.
Healthcare
Healthcare providers implement data center automation to manage electronic health records (EHRs), medical imaging systems, telemedicine platforms, research workloads, and healthcare applications while ensuring regulatory compliance, data security, and high availability.
Manufacturing
Manufacturers utilize data center automation to support Industry 4.0 initiatives, industrial IoT (IIoT), smart factory operations, predictive maintenance, production analytics, and real-time operational monitoring through automated infrastructure management.
Others
This segment includes government, education, energy & utilities, media & entertainment, transportation & logistics, and other industries that adopt data center automation to improve IT infrastructure efficiency, enhance service reliability, automate operational processes, and support digital transformation initiatives.
Estimation Model
Layer
Question
Analysis
Data Center Automation Addressable Demand Layer
Who can benefit from Data Center Automation?
Identify organizations operating large-scale IT infrastructure, including hyperscale cloud providers, colocation operators, enterprises, government agencies, BFSI institutions, healthcare organizations, manufacturers, telecom operators, retailers, educational institutions, and managed service providers (MSPs). Analyze automation demand across compute, storage, networking, virtualization, power, cooling, and infrastructure management to define the total addressable market.
Digital Infrastructure & Automation Adoption Layer
Where is demand for Data Center Automation generated?
Evaluate demand driven by cloud computing, hybrid and multi-cloud environments, Software-Defined Data Centers (SDDC), virtualization, edge computing, AI workloads, DevOps, Infrastructure-as-Code (IaC), containerized applications, Kubernetes, and digital transformation initiatives. Assess investments in hyperscale data centers, enterprise IT modernization, and intelligent infrastructure management to determine the operational reachable market.
Automation Deployment & Infrastructure Layer
Who actively deploys Data Center Automation solutions?
Analyze adoption among hyperscale cloud providers, colocation facilities, enterprise data centers, government data centers, telecom operators, financial institutions, healthcare providers, and managed service providers. Evaluate deployment across cloud and on-premises environments, including automation of server provisioning, storage management, network orchestration, workload scheduling, security policy enforcement, monitoring, predictive maintenance, and AIOps to identify active deployment potential.
Monetization Layer
How is revenue generated?
Assess revenue generated through automation software platforms, infrastructure orchestration solutions, server, storage, and network automation software, AI-driven monitoring platforms, AIOps solutions, licensing and subscription models (SaaS), professional services (consulting, integration, deployment, training), managed services, maintenance and support contracts, infrastructure upgrades, and recurring software subscriptions to estimate the overall market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Data Center Automation Vendor Competitive Benchmarking
Assessed leading data center automation vendors based on automation capabilities, AI-driven operations (AIOps), infrastructure orchestration, server, storage and network automation, hybrid and multi-cloud management, Infrastructure-as-Code (IaC), Kubernetes integration, pricing models, deployment flexibility, partnerships, product roadmaps, and market positioning.
Enables stakeholders to benchmark competitors, identify technology gaps, evaluate product differentiation, and formulate competitive product development, partnership, and go-to-market strategies.
Regional Data Center Automation Demand & Infrastructure Assessment
Evaluated regional investments in hyperscale and colocation data centers, enterprise IT modernization, hybrid cloud adoption, edge computing deployments, AI infrastructure expansion, digital transformation initiatives, regulatory landscape, automation maturity, and demand across North America and Europe.
Provides actionable insights into regional growth opportunities, infrastructure investment priorities, automation adoption trends, competitive landscapes, and long-term market expansion strategies across key geographies.
Industry-wise Automation Adoption Analysis
Evaluated automation adoption across BFSI, IT & Telecom, Healthcare, Manufacturing, Retail, Government, Energy & Utilities, and Education, including key use cases, investment priorities, and deployment challenges.
Assists vendors in identifying high-growth industry verticals and developing targeted sales and product strategies.
Frequently Asked Questions About This Report
The global data center automation market size was estimated at USD 11.6 billion in 2025 and is expected to reach USD 13.4 billion in 2026.
The global data center automation market is expected to grow at a compound annual growth rate of 18.1% from 2026 to 2033 to reach USD 43.2 billion by 2033.
Key factors include the escalating demand for efficiency, scalability, and reduced operational costs in managing modern data centers. As enterprises increasingly migrate to hybrid and multi-cloud environments, the need for automated systems to manage complex IT infrastructures has grown significantly. Automation technologies enable data centers to streamline workflows, enhance resource allocation, and minimize human intervention, thereby reducing the potential for error and downtime.
Asia Pacific is the fastest-growing region over the forecast period.
The solution segment led with a 66.0% revenue share in 2025, while services segment is the fastest-growing segment.
The on premise segment led with a 52.8% revenue share in 2025, while cloud segment is the fastest-growing segment.
The large enterprise segment held the largest share (over 68.0%) in 2025, while small & medium enterprise segment is the fastest-growing segment.
Some key players operating in the data center automation market include ABB, BMC Software, Inc., Cisco Systems, Inc., Citrix Systems, Inc., FUJITSU, Hewlett Packard Enterprise Development LP, Microsoft, Oracle, ServiceNow, and VMWare
North America dominated with 41.2% revenue share in 2025.
About the Author(s)
Communications Infrastructure Research Team
Technology · Communications InfrastructureThis report was authored by the communications infrastructure research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the communications infrastructure segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


