
- Home
- »
- Next Generation Technologies
- »
-
Debt Collection Software Market Size, Growth Report, 2026-2033GVR Report cover

Debt Collection Software Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Software, Services), By Deployment, By Enterprise Size, By End-User, By Region, And Segment Forecasts
Market Size, 2025
$5.8BMarket Estimate, 2026
$6.3BMarket Forecast, 2033
$13.0BCAGR, 2026–2033
10.9%Debt Collection Software Market Summary
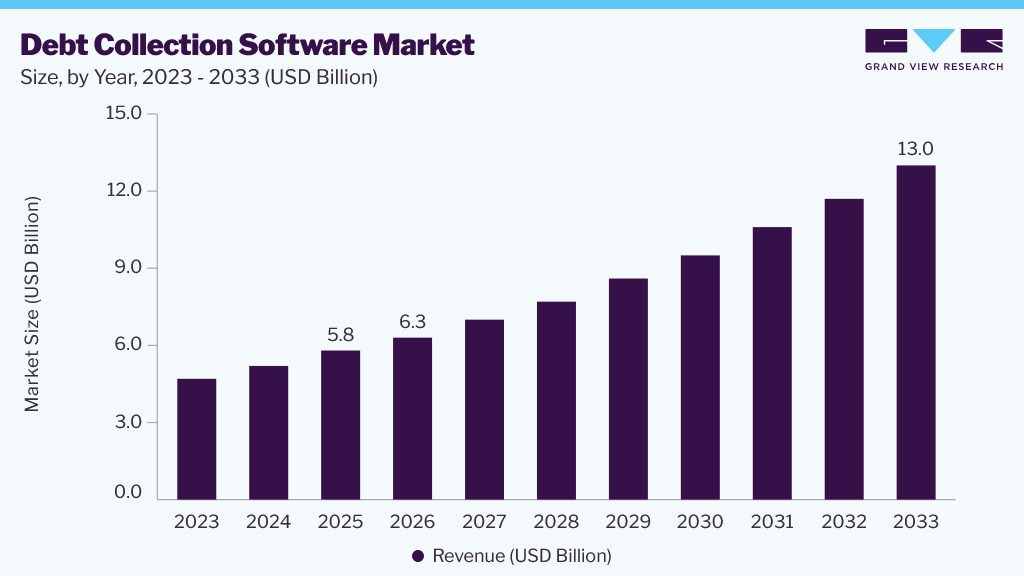
The global debt collection software market size was valued at USD 5.8 billion in 2025 and is projected to grow from USD 6.3 billion in 2026 to USD 13.0 billion in 2033, at a CAGR of 10.9% from 2026 to 2033. The North America dominated the market, accounting for a revenue share of 30.0% in 2025. The market's growth is driven by increasing demand for efficient debt-recovery processes and the need to minimize bad debts while optimizing cash flow.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: The software segment dominated the market with a share of around 65.0% in 2025.
- By deployment: The cloud segment held the largest market share owing to the increasing need for data sharing and interconnectivity between users and their clients.
- By enterprise size: The large enterprise segment dominated the market in 2025 due to the increased data complexity and the rise of stringent regulations.
- By end user: The financial institutions segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (30.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 5.8 Billion
- Estimated market size in 2026: USD 6.3 Billion
- Projected market size by 2033: USD 13.0 Billion
- CAGR (2026-2033): 10.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Global debt levels have been rising due to attractive loan schemes offered by banks and the simplification of the loan application process. According to the International Monetary Fund (IMF), as of September 2025, global debt remained high at over 235% of global GDP, amounting to approximately USD 251 trillion. The report indicated that private debt was a significant part of global borrowing, accounting for nearly 143% of global GDP. This reflects persistently high levels of household and corporate liabilities in major economies. Rising debt levels and heightened credit exposure have prompted financial institutions, lenders, and collection agencies to adopt advanced debt-collection software solutions. These solutions utilize automation, analytics, and AI-driven decision-making to improve recovery efficiency, manage delinquent accounts, and streamline repayment processes.
Advancements in artificial intelligence have led companies to integrate AI with debt collection software to create a more sophisticated collection experience. Companies can enhance efficiency, reduce costs, and streamline processes by automating repetitive tasks, such as sending reminders, generating reports, and managing communications with debtors. For instance, in November 2025, CreditNirvana, a Perfios company, launched Maestro, an intelligent debt-collection platform that uses AI to automate end-to-end recovery operations. This platform utilizes generative AI collection agents to handle digital outreach, voice interactions, account allocations, payment settlements, and recovery workflows, enabling lenders to minimize manual intervention and enhance collection efficiency.
In addition, the expansion of fintech companies is contributing to market growth. For example, in February 2025, Mastercard reported significant growth in the fintech ecosystem in Latin America and the Caribbean, with over 3,000 fintech companies operating across 26 countries. The report highlighted that the region has seen a 340% increase in fintech providers since 2017, driven by the growing adoption of digital financial services, improved access to credit, and increased reliance on technological financial solutions. This rapid growth of fintech platforms is expected to boost the demand for scalable debt collection software, as lenders and digital financial providers seek automated solutions to manage expanding customer portfolios, improve repayment rates, and enhance collection efficiency.
Analyst Perspective
The market is experiencing steady growth due to the increasing volume of outstanding debt, rising adoption of digital financial services, and growing demand for efficient, automated, and customer-friendly debt recovery solutions across sectors such as banking, financial services, and healthcare. The market is seeing an uptick in the adoption of AI-powered analytics, automation, and machine learning. These technologies enhance decision-making, facilitate omnichannel communication, and support cloud-based collection systems. Organizations are focusing on improving recovery rates, reducing operational costs, and enhancing compliance with evolving regulatory requirements. Despite challenges such as data privacy issues, integration complexities with existing financial systems, varying regulations across regions, and the need for personalized customer engagement, advancements in predictive analytics, digital payment solutions, and intelligent workflow automation are creating new growth opportunities. Companies that invest in innovative, secure, and data-driven debt collection platforms are expected to benefit from the market's long-term expansion, as these solutions enable more efficient recovery processes, improve customer experiences, and support the modernization of financial operations.
Component Insights
The software segment dominated the market, representing around 65.0% of the total in 2025. The ongoing global Industry 4.0 initiative is driving growth in this segment. The core functionalities of the software include case management, automated workflows, payment processing, reporting and analytics, and compliance management. In addition, it offers supplementary features such as skip tracing, credit reporting, negotiation tools, chatbots, AI-powered communication, document management, team collaboration tools, and integrations with existing software, all of which assist users with automation and debt recovery.
The service segment is expected to experience the fastest CAGR throughout the forecast period due to increasing demand for Software-as-a-Service (SaaS) models, which offer reduced upfront costs and greater flexibility and scalability. Many companies are introducing advanced solutions to meet this demand. For example, in May 2025, Vymo launched CollectIQ, an AI-powered debt collection solution specifically designed for banks and non-banking financial companies. This platform aims to enhance collection operations by automating processes and enabling agents. It helps financial institutions streamline collection workflows, optimize account prioritization, and improve efficiency in both field and digital collections, all without significant technology investments.
Deployment Insights
The cloud segment held the largest market share owing to the increasing need for data sharing and interconnectivity between users and their clients. Cloud-based solutions offer advantages such as real-time collaboration, seamless communication, and data integration. In addition, they provide remote access and mobility, enabling users to access data from any location at any time. Cloud deployment is cost-effective, scalable, and flexible, offering automatic updates, maintenance, and enhanced security. It ensures disaster recovery capabilities, which are crucial in the event of unexpected system failures or data loss.
The on-premise segment is projected to experience significant growth at a compound annual growth rate (CAGR) during the forecast period. On-premise solutions offer organizations optimum control, customization, and data privacy. They allow businesses to adapt the software to their specific collection processes, compliance needs, and team structures. This approach enables organizations to maintain full control over their sensitive data and implement their own security protocols, resulting in higher security levels.
On-premises systems are typically less vulnerable to cybersecurity threats compared to cloud-based solutions. This added level of security is crucial for businesses that manage highly sensitive data. According to IBM’s Cost of a Data Breach Report 2025, the global average cost of a data breach has increased to USD 4.88 million, highlighting the escalating financial impact of cybersecurity incidents. The report also emphasizes that breaches occurring in sensitive sectors, such as financial services and critical data systems, are among the most costly. This underscores the importance of implementing stronger data controls, tighter access governance, and secure infrastructure choices, such as on-premises deployments, especially for organizations that handle confidential customer debt and repayment information.
Enterprise Size Insights
The large enterprise segment dominated the market in 2025 due to the increased data complexity and the rise of stringent regulations. Large enterprises operating in highly regulated industries and regions prioritize compliance. To ensure compliance with legal requirements and mitigate risks, large enterprises require debt collection software with robust compliance features, including automated regulatory updates, audit trails, and secure data handling.
The SME segment is expected to witness significant growth, driven by the increasing focus on Customer Relationship Management (CRM). Software that incorporates CRM features enables SMEs to effectively manage customer interactions, personalize communication, and maintain a positive customer experience throughout the debt collection process. Debt collection software is an effective tool that helps businesses preserve their reputation and foster customer loyalty, ultimately leading to long-term financial prosperity.
End User Insights
The financial institutions segment held the largest market share in 2025. The rising need for fraud detection is driving the segment growth. Financial institutions are particularly vulnerable to fraud due to the sensitive financial information they handle. Debt collection software plays a crucial role in safeguarding against fraudulent activities. It offers advanced features such as suspicious activity monitoring, multiple account correlations, and device and IP address checks. These features help identify unusual transactions, suspicious login attempts, and geographically inconsistent activity.
The telecom & utilities segment is expected to grow at a significant CAGR over the forecast period. This can be attributed to the rise in fraudulent accounts, resulting in bad debts and impacts on revenue streams. Debt collection software can be crucial in detecting and preventing these fraudulent accounts. It helps detect fraud, integrate with external databases, trigger alerts, implement verification procedures, and segment customer data based on risk profiles. These factors bode well for the segment growth.
Regional Insights
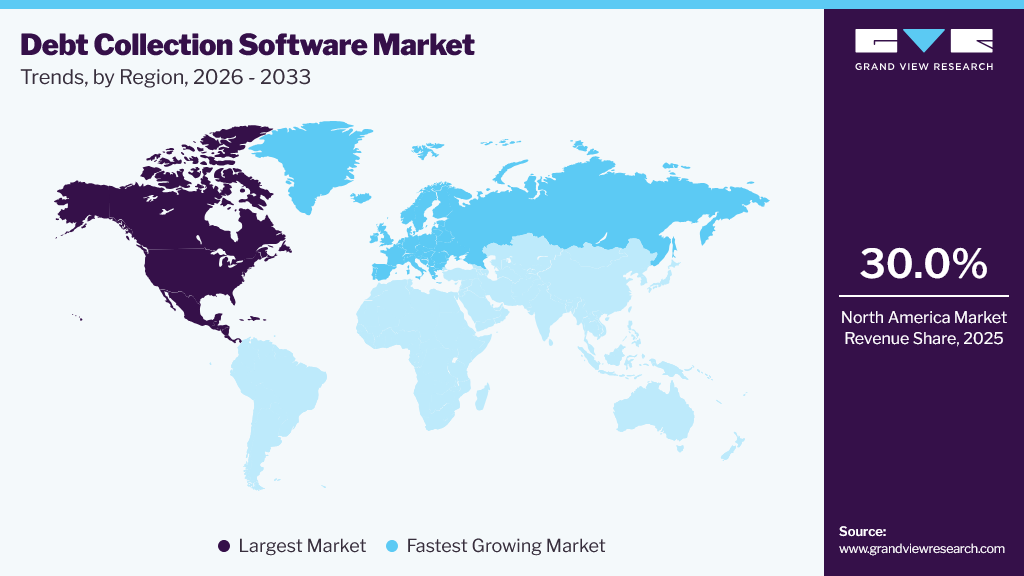
North America dominated the market, accounting for a revenue share of 30.0% of revenue in 2025. The region’s well-established technological ecosystem and rapid adoption of digital solutions continue to support market growth. As a leading center for technological innovation, North America is witnessing increasing integration of Artificial Intelligence (AI), machine learning, cloud-based platforms, and advanced analytics into debt collection operations. These technologies enable organizations to strengthen debtor engagement, streamline collection workflows, improve repayment tracking, and enhance overall operational efficiency.
 To learn more about this report, Download Free Sample Report
For instance, in May 2025, Consumer Portfolio Services implemented an AI-powered servicing and collections platform in collaboration with Salient. The platform leverages conversational AI and machine-learning-driven automation to optimize borrower communication, automate payment collection, manage due date modifications, and conduct insurance verification. Such advancements are helping lenders improve repayment performance, minimize manual intervention, and efficiently scale collection operations across large borrower portfolios.
U.S. Debt Collection Software Market Trends
The debt collection software market in the U.S. dominated North America, holding a prominent share in 2025, owing to the country's stringent regulations. The U.S. has a complex regulatory environment governing debt collection practices, including federal laws such as the Fair Debt Collection Practices Act (FDCPA) and the Telephone Consumer Protection Act (TCPA), as well as state-level regulations. Debt collection software tailored to the U.S. market is designed to ensure compliance with these regulations, helping businesses avoid legal liabilities and penalties.
Canada debt collection software market is expected to grow at the fastest CAGR over the forecast period, attributed to the advent of digital transformation in Canada. Canadian government programs, such as the Strategic Innovation Fund, promote digitalization and technology adoption across various industries by providing financial support.
Europe Debt Collection Software Market Trends
The debt collection software market in Europe is highly lucrative, driven by the emerging need for cross-border debt collection. Increasing cross-border trade necessitates software capable of handling complex international regulations and facilitating efficient cross-border debt recovery.
Germany debt collection software market held a substantial market share. German companies prioritize innovation and invest heavily in Research and Development (R&D) to maintain technological leadership, resulting in better infrastructure for adopting debt collection software and thus driving the market.
The debt collection software market in France is expected to grow significantly over the forecast period. With the implementation of the General Data Protection Regulation (GDPR) in the European Union, including France, there is a heightened focus on data privacy and protection. Debt collection software providers in France invest in robust data security measures, encryption protocols, and compliance certifications to safeguard client data and ensure GDPR compliance.
Asia Pacific Debt Collection Software Market Trends
The debt collection software market in the Asia Pacific is anticipated to grow the fastest. This can be attributed to the region’s widespread adoption of technology, driven by rising internet penetration, smartphone usage, and digitalization initiatives. Debt collection software solutions leverage technologies such as Artificial Intelligence (AI), machine learning, and data analytics to optimize collection strategies, improve debtor engagement, and enhance operational efficiency, aligning with these trends and driving market growth.
China debt collection software market is expected to grow substantially over the forecast period. China has experienced rapid adoption of mobile payments and digital platforms, facilitated by the widespread use of smartphones and internet connectivity. Debt collection software solutions in China often integrate with popular mobile payment platforms and digital channels to facilitate convenient payment options, communication with debtors, and account management.
The debt collection software market in India is expected to grow significantly over the forecast period, owing to the rise in digital transformation in the country. The Digital India initiative is one of the most prominent government initiatives that has increased digitalization adoption, encouraged technological development, and prompted local startups and established players to invest in innovative debt collection software solutions.
Middle East & Africa Debt Collection Software Market Trends
The debt collection software market in MEA is expected to grow substantially over the forecast period, driven by rising economic growth, which is increasing access to credit and raising debt levels. As access to credit expands and debts rise, businesses in the MEA region face challenges in effectively managing delinquent accounts and recovering outstanding debts. Debt collection software offers advanced tools and features that streamline the debt recovery process, enhance operational efficiency, and improve collection outcomes.
The UAE debt collection software market held a significant revenue share in the global market. The UAE is experiencing a diversified debt portfolio due to rising disposable income and greater access to credit, leading to higher credit card usage and personal loan borrowing, resulting in market growth.
Key Debt Collection Software Company Insights
Some of the key players operating in the market include Experian, CGI, TransUnion, FIS, Pair Finance, Credgenics, and ZestMoney.
- Fidelity National Information Services, commonly known as FIS, is a global financial technology company that provides a wide range of solutions for financial institutions, enterprises, and consumers. The company has established a strong market presence through solutions designed to streamline debt recovery operations, enhance collection efficiency, and support regulatory compliance. Its offerings include FIS Getpaid, a debt collection and credit management solution that helps businesses automate collections, manage receivables, and improve cash flow performance.
- TransUnion is an information and insights company that delivers credit data and financial solutions to businesses and consumers worldwide. The company offers debt collection software and risk management solutions to improve collection efficiency, enhance customer engagement, and increase recovery rates. Its portfolio includes TruLookup Investigative Solutions, TruContact Communications Solutions, and TruVision Risk Management Solutions, which support organizations in identity verification, customer communication, and risk assessment activities.
- PAIR Finance is a debt collection company focused on providing technology-driven software solutions that optimize and modernize debt recovery processes. The company utilizes Artificial Intelligence (AI), machine learning, and behavioral science to improve communication strategies, enhance recovery performance, and deliver customer-centric collection services. PAIR Finance emphasizes ethical, digital-first debt collection practices while helping businesses improve operational efficiency and the customer experience.
Key Debt Collection Software Companies
The following key companies have been profiled for this study on the debt collection software market:
-
Experian
-
Fair Isaac Corporation
-
Constellation Software Inc.
-
CGI Group Inc.
-
TransUnion
-
Nucleus Software Exports Ltd.
-
Chetu Inc.
-
CDS Software
-
Pegasystems Inc.
-
Temenos Group AG
-
AMEYO
-
PAIR Finance
-
Credgenics
Recent Developments
-
In March 2026, CGI launched new AI capabilities in CGI Credit Studio, introducing embedded AI agents for collections operations to improve recovery performance, operational efficiency, and compliance across regulated financial environments.
-
In August 2025, Credgenics expanded its AI-driven SaaS debt collections platform through partnerships and acquisitions, including the CG Setu initiative with Arrise. The expansion strengthened field collections digitization, borrower engagement, and omnichannel recovery capabilities across India.
-
In April 2025, Nucleus Software announced that Deem Finance expanded its partnership to implement FinnOne Neo Collections, enabling AI-driven analytics, intelligent customer engagement, and automated collections workflows to improve recovery efficiency and reduce non-performing assets.
-
In April 2025, TransUnion enhanced its OneTru platform capabilities across North America by integrating AI and advanced analytics to improve risk segmentation, predictive modeling, and decision-making capabilities supporting credit lifecycle management and collections optimization.
Debt Collection Software Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.8 billion
Estimated market size in 2026
USD 6.3 billion
Projected market size by 2033
USD 13.0 billion
Growth rate
CAGR of 10.9% from 2026 to 2033
Actual data
2021 – 2025
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, deployment, enterprise size, end user, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; UK; Germany; France; Italy; China; India; Japan; Australia; South Korea; Brazil; Mexico; Argentina; UAE; Saudi Arabia; South Africa
Key companies profiled
Experian; Fair Isaac Corporation; Constellation Software Inc.; CGI Group Inc.; TransUnion; Nucleus Software Exports Ltd.; Chetu Inc.; CDS Software; Pegasystems Inc.; Temenos Group AG; AMEYO; PAIR Finance; Credgenics
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Debt Collection Software Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global debt collection software market report based on component, deployment, enterprise size, end user, and region:
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Services
-
Software
-
Consulting
-
Integration & Implementation
-
Training & Support
-
-
-
Deployment Outlook (Revenue, USD Billion, 2021 - 2033)
-
On-premise
-
Cloud
-
-
Enterprise Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Large Enterprise
-
Small & Medium Enterprise
-
-
End User Outlook (Revenue, USD Billion, 2021 - 2033)
-
Healthcare
-
Financial Institutions
-
Collection Agencies
-
Government
-
Telecom & Utilities
-
Others (Real Estate & Retail)
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
Italy
-
France
-
-
Asia Pacific
-
Australia
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
The global debt collection software market size was valued at USD 5.8 billion in 2025 and is estimated at USD 6.3 billion in 2026.
The global debt collection software market is expected to grow at a CAGR of 10.9% from 2026 to 2033, reaching USD 13.0 billion.
North America dominated with an approximately 30.0% revenue share in 2025
Key players in the market include Experian, Fair Isaac Corporation, Constellation Software Inc., CGI Group Inc., TransUnion, Nucleus Software Exports Ltd., Chetu Inc., CDS Software, Pegasystems Inc., Temenos Group AG, AMEYO, PAIR Finance, Credgenics, and others
The cloud segment held the largest market share owing to the increasing need for data sharing and interconnectivity between users and their clients.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


