
- Home
- »
- Medical Devices
- »
-
Dental Bone Grafts And Substitutes Market Report, 2033GVR Report cover

Dental Bone Grafts And Substitutes Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material Type (Allograft, Xenograft, Synthetic), By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$901.1MMarket Estimate, 2026
$973.1MMarket Forecast, 2033
$1,784.9MCAGR, 2026–2033
9.1%Dental Bone Grafts And Substitutes Market Summary
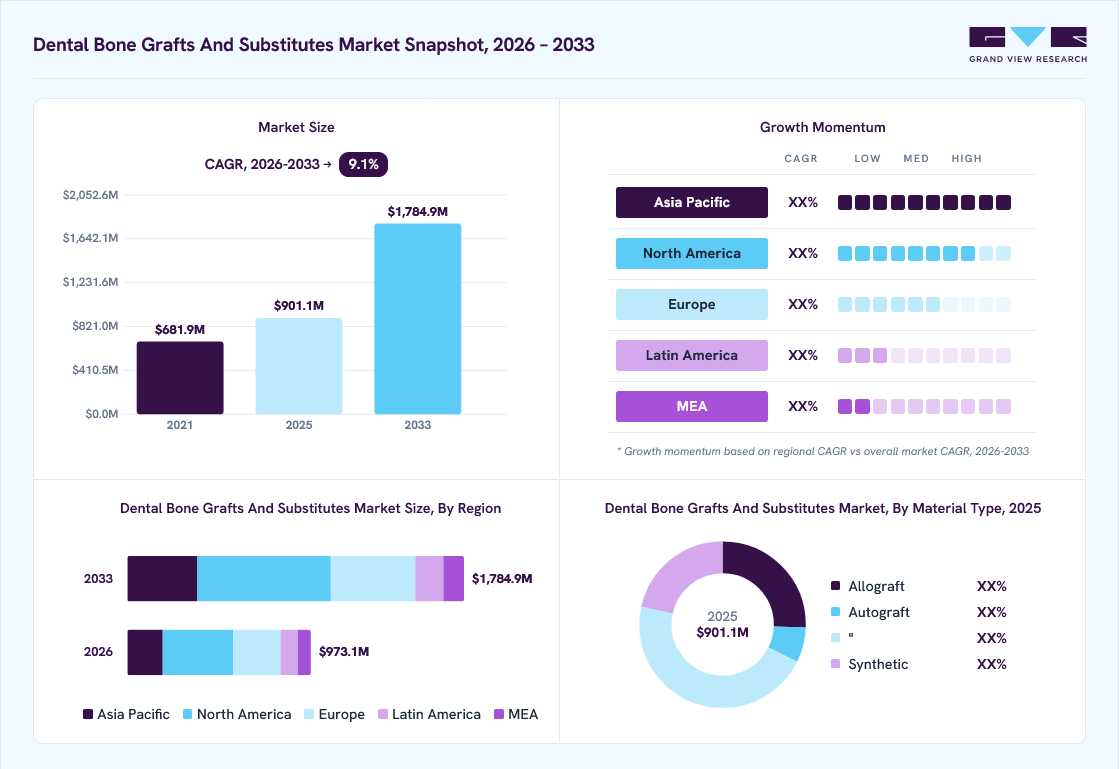
The global dental bone grafts and substitutes market size was valued at USD 901.1 million in 2025 and is projected to grow from USD 973.1 million in 2026 to USD 1,784.9 million by 2033, at a CAGR of 9.1% from 2026 to 2033. North America dominated the dental bone grafts and substitutes market with the largest revenue share of 38.3% in 2025. Increasing the use of bone grafts in density, and a growing number of dental implant surgeries are propelling the revenue.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material type: Xenograft segment held the largest market share of 46.1% in 2025.
- By application: Socket preservation segment held the largest market share of 30.5% in 2025.
- By end use: Dental clinics segment held the largest market share of 70.1% in 2025.
Regional Highlights
- Largest regional market: North America (38.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 901.1 Million
- Estimated market size in 2026: USD 973.1 Million
- Projected market size by 2033: USD 1,784.9 Million
- CAGR (2026-2033): 9.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The advent of COVID-19 resulted in significant revenue losses, especially in the first and second quarters of 2021. This was mainly due to the fact that the majority of dental practices around the globe were halted in light of surging COVID-19 cases and the risk of disease transmission. However, as the dental bone graft market is recovering from the impact of COVID-19 as dental treatments have been resumed drastically as measures to curb the virus have been successful.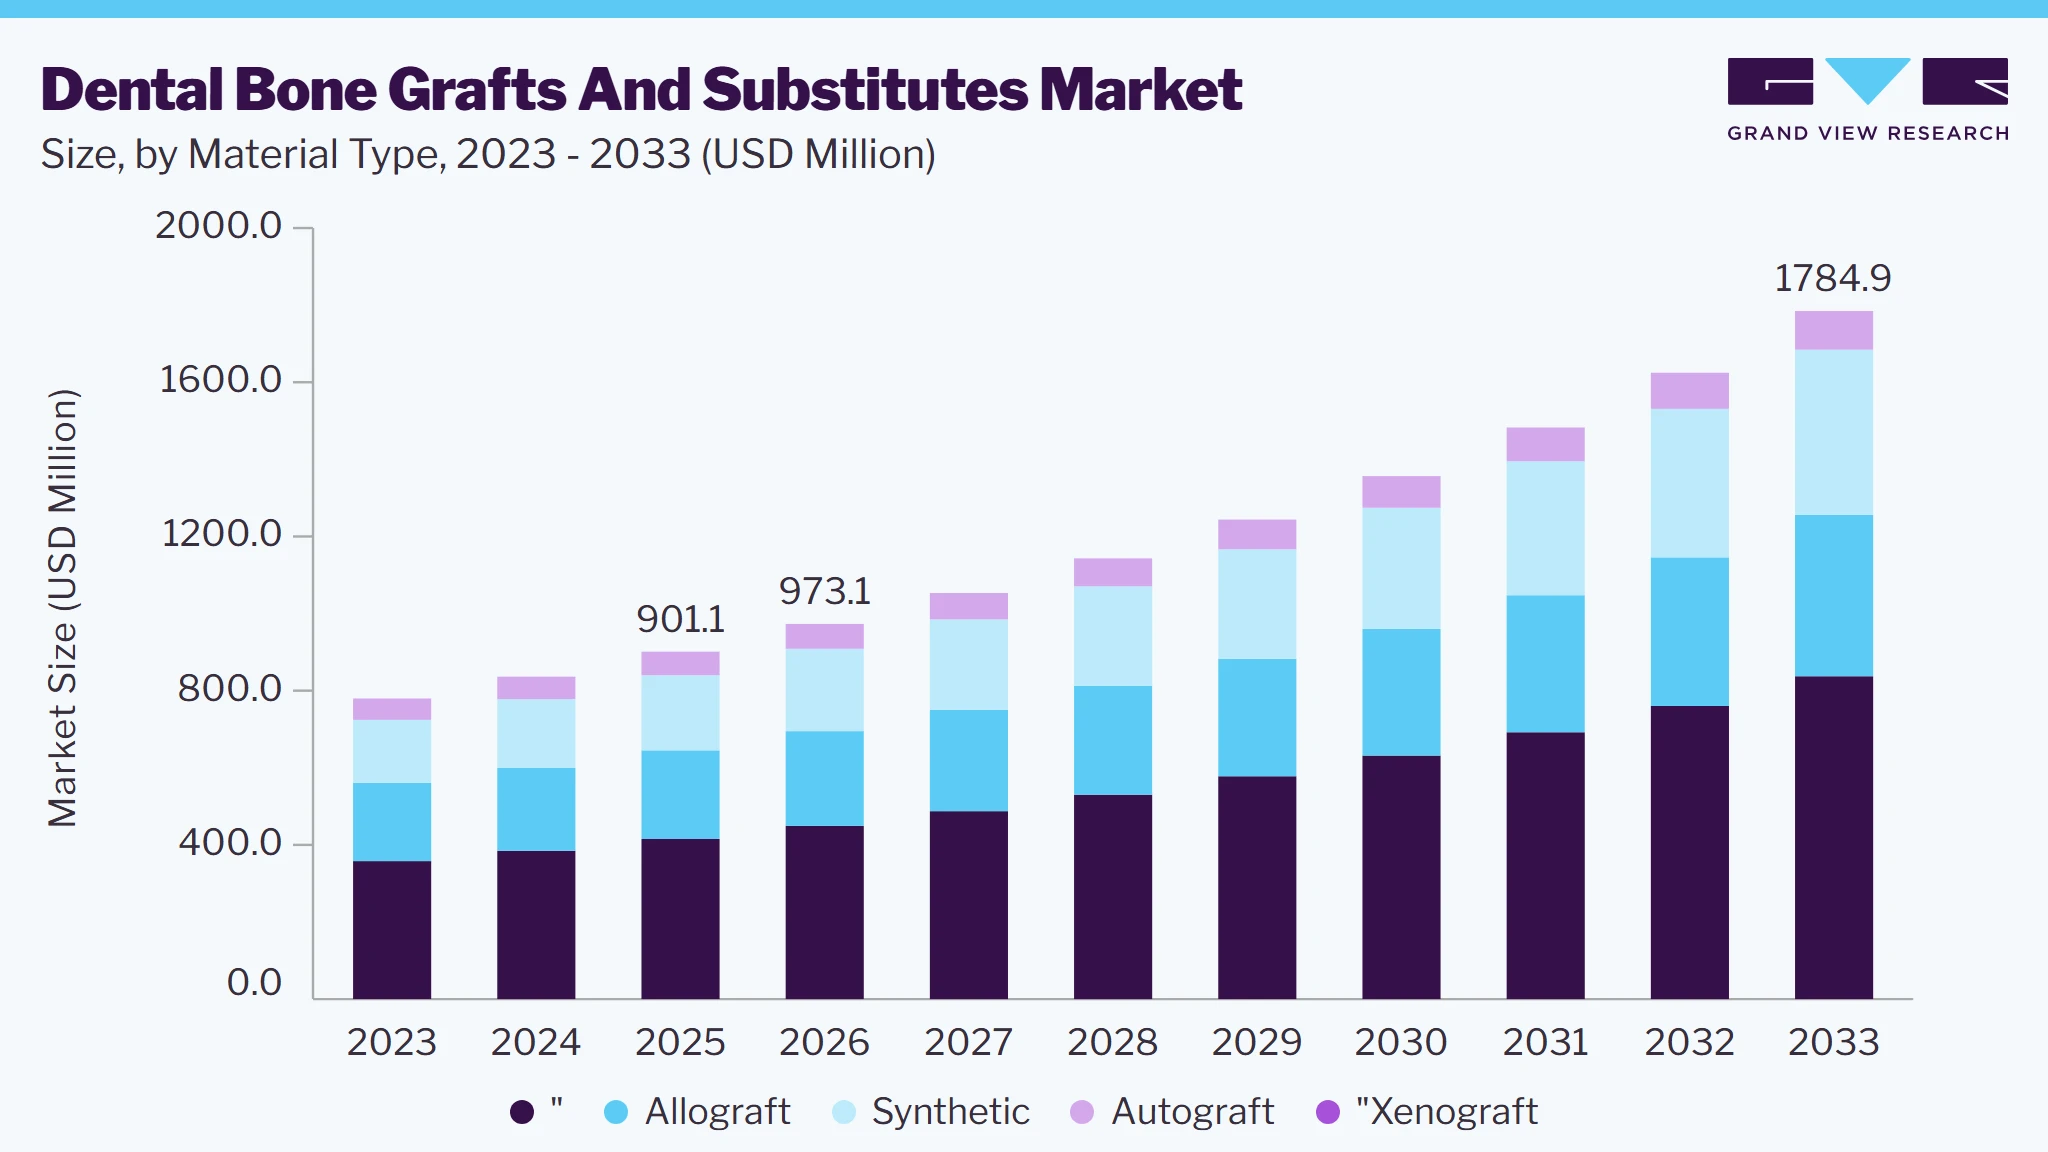 To learn more about this report, Download Free Sample Report
Dental implant surgery has now become very popular with advanced surgical techniques such as bone grafts and bone regeneration. Moreover, increasing success rates of these surgeries are fueling the market. According to the American Dental Association report, around 95% to 98% success rate has been reported for implant surgeries as of 2019. Around 5 million implant procedures are performed in the U.S. every year. Bone grafting prior to implant placement helps to maintain the existing jaw and increases the chances of successful implant surgery, thus fueling revenue.
The U.S. allograft product segment is expected to witness a high compound annual growth of 9.8% during the forecast period. The use of biocompatible and synthetic dental grafts is a growth-propelling factor for the market. TCP is mostly used as a synthetic scaffold in dentistry. It provides higher osteoconductivity as compared to allografts. The increasing initiatives by the industry players such as new product launch, merger & acquisition is also affecting the revenue. For instance, In May 2018, Dentsply Sirona collaborated with Datum Dental, Ltd. for the distribution of the OSSIX brand which is indicated for bone and tissue regeneration.
Growing dental tourism in developing countries is propelling the market. Asia Pacific region especially China, and India is one of the major contributors to this growth. The low cost of dental treatment and the availability of surgeons will lead to an increase in the number of foreign patient visits for these procedures. The cost for socket preservation and ridge augmentation is nearly 1/4th as compared to the U.S. and Europe. The aforementioned factors are expected to propel revenue in the coming years.
The rising target population plays a significant role in the growth of the dental bone grafts & substitutes market. According to the Department of Economic and Social Affairs Population Division, the global share of people 60 years and above has grown from 9.2% in 1990 to 11.7% in 2013, and this share is expected to rise to 21.1% by 2050. With an elevated prevalence of periodontal disease,root caries, and edentulous along with the geriatric population the demand for dental grafting is increasing.
The onset of the pandemic strained the dental industry as measures were taken by the state governments globally to curb the transmission of the virus and as dental treatments are high-contact services, the majority of dental practices were halted. Companies like Dentsply Sirona and Institut Straumann AG reported operational and supply chain constraints as a result of the pandemic which directly affected their revenues. However, dental practices resumed by the end of 2020 under strict Covid-19 protocols and guidelines, after the introduction of an effective vaccine. Dentsply Sirona stated that its End-Use and Equipment segment which comprises dental bone graft materials reported a 28.7% growth in 2021.
Market Dynamics
The dental bone grafts and substitutes market is experiencing significant growth due to the increasing prevalence of tooth loss, periodontal diseases, dental trauma, and the rising number of dental implant procedures worldwide. Growing awareness of oral health, improving access to dental care, and the expanding elderly population, which is more susceptible to bone loss and edentulism, are driving demand for bone grafting materials used in implantology and oral reconstruction. The market is further supported by the increasing adoption of cosmetic and restorative dentistry, as patients seek long-lasting and aesthetically pleasing tooth replacement solutions. Technological advancements in regenerative biomaterials, including synthetic bone grafts, xenografts, allografts, collagen membranes, and bioactive materials, are improving bone regeneration outcomes and reducing healing time. In addition, the growing use of digital dentistry, 3D imaging, computer-guided implant surgery, and minimally invasive procedures is enhancing treatment precision and clinical success.
The increasing adoption of dental implants as a preferred solution for tooth replacement is significantly driving demand for bone grafts and substitutes. Many patients undergoing implant procedures require sufficient jawbone volume and density for successful implant placement. As a result, bone grafting materials are widely used in ridge augmentation, sinus lift procedures, and socket preservation. The growing prevalence of tooth loss due to aging, periodontal diseases, and dental trauma is further accelerating implant procedures globally, thereby directly boosting the consumption of autografts, allografts, xenografts, and synthetic bone graft materials.
The high cost of dental bone grafting procedures acts as a significant restraint in the dental bone grafts and substitutes market. These procedures involve multiple cost components, including advanced biomaterial grafts, surgical interventions, diagnostic imaging such as CBCT scans, and post-operative care and follow-ups. Premium graft materials like xenografts and bioactive synthetic substitutes further increase the overall treatment expense. In many developing and price-sensitive regions, limited reimbursement coverage for dental procedures forces patients to bear the full cost out-of-pocket, making treatment less accessible. In addition, the requirement for skilled dental surgeons and specialized clinical infrastructure adds to procedural costs. The overall financial burden discourages a large segment of patients from opting for implant-supported restorations, especially in low- and middle-income populations. Even in developed markets, insurance limitations for elective dental procedures restrict affordability.
The development of next-generation synthetic and bioactive bone graft materials presents a major growth opportunity in the dental bone grafts and substitutes market. Advances in biomaterials science are enabling the creation of highly biocompatible grafts with improved osteoconductive, osteoinductive, and resorbable properties. Innovations such as nanotechnology-based scaffolds, 3D-printed bone substitutes, and growth factor–enriched biomaterials are significantly enhancing bone regeneration outcomes. These advanced materials promote faster healing, better integration with natural bone, and reduce risk of disease transmission compared to traditional grafts. They also help minimize dependence on autografts and allografts, reducing patient morbidity and donor-related limitations. Increasing research in tissue engineering and regenerative dentistry is accelerating product development and commercialization.
Analyst Perspective
The dental bone grafts and substitutes market is expected to grow steadily due to the rising prevalence of tooth loss, periodontal diseases, and increasing adoption of dental implants worldwide. Growing demand for regenerative dental procedures, an aging population, greater oral health awareness, and advancements in biomaterials such as synthetic grafts, xenografts, DBM, and bioactive substitutes are supporting market expansion. Companies investing in innovative regenerative technologies and maintaining strong partnerships with dental clinics, hospitals, and implant manufacturers are well positioned for growth. Increasing dental implant procedures, rising healthcare spending, growing demand for aesthetic dentistry, and continued advancements in regenerative medicine are expected to drive long-term market development.
Material Type Insights
Based on material type, the xenograft segment led the market with the largest revenue share of 46.1% in 2025, while synthetic is expected to grow at the fastest CAGR over the forecast period. the market is segmented into xenograft, allograft, and synthetic material. A xenograft is a bone taken from an animal source such as a bovine and implanted into the human body. The most commonly used xenograft is Bio-Oss. Key industry players are taking the initiative to launch new xenograft products for better penetration. For instance, in 2019 Marks Biotech Inc. launched Novobone, a xenograft in order to improve its bone grafting product portfolio. The other key players include ACE Surgical, BioHorizons, etc.
The synthetic segment is expected to exhibit the highest growth of 10.6% over the forecast period. The growth can be attributed to its higher osteoconductivity, hardness, and better acceptance. There are various types of synthetic materials available in the market such as ceramic, polymer-based, BMPs, etc. The chance of disease transmission is low with synthetic grafting as compared to xenograft & allograft, which further boosts the growth. Moreover, increasing demand to develop biocompatible grafts to reduce adverse reactions is driving this segment.
Increasing uses of synthetic grafts with HAP and TCP which have shown better biocompatibility as compared to others are fueling the growth. The polymer-based grafts also have shown good biocompatibility. The industry players are continuously trying to develop new products with better biocompatibility, bioactivity, and suitable mechanical properties. For instance, in June 2019, Biogennix received 510(K) clearance from USFDA for Agilon, which is fully biocompatible with human bone. The aforementioned factors are boosting revenue.
Application Insights
Based on application, the socket preservation segment led the market with the largest revenue share of 30.5% in 2025. Advancements in bone grafting materials, such as the advent of synthetic bone materials, have led to an increase in the adoption of socket preservation procedures which captures 33.3% as of 2022. The application segment includes Ridge Augmentation, Sinus Lift, Periodontal Defect Regeneration, Implant Bone Regeneration, and Socket Preservation. It is a method that is used to decrease bone loss after tooth extraction from a tooth socket in the alveolar bone. An escalating number of dental implant surgeries and increasing awareness among people about oral health care are the driving factors for the growth of this segment.
The sinus lift segment is expected to register the fastest CAGR of 10.4% over the forecast period. Ridge augmentation also held a significant revenue share owing to its quick recovery time and painless procedure. The demand for this procedure is increasing in order to achieve long-term survival and successful implant placement. Moreover, alveolar volume gain is also possible with the help of ridge augmentation, thus boosting growth. Some of the most common grafting materials used are Puros by Zimmer Biomet, Bio-Oss by Osteohealth, INFUSE bone graft by Medtronic, etc.
End-use Insights
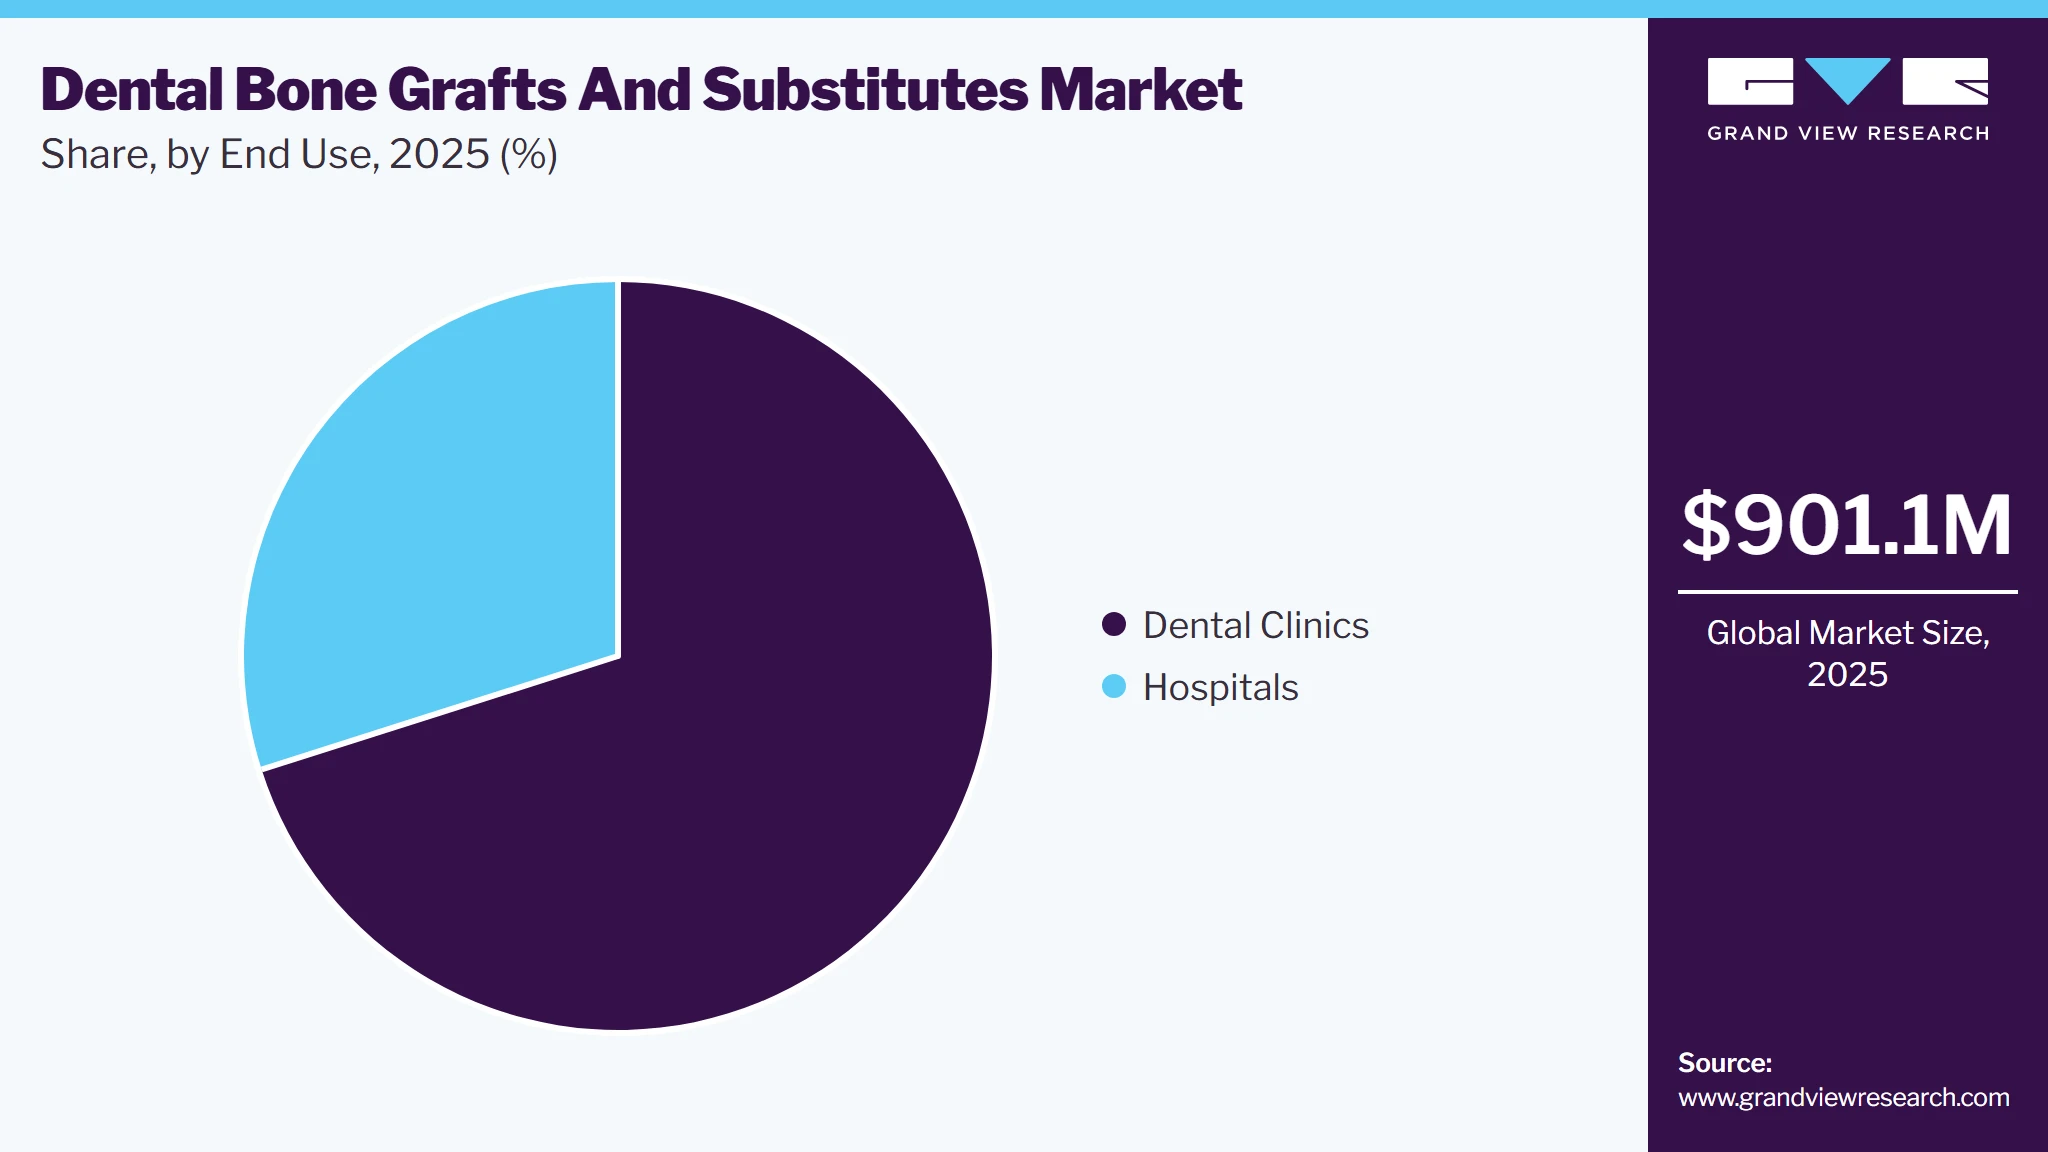
Based on end use, the dental clinics segment led the market with the largest revenue share of 70.1% in 2025. With a growing number of dental graft surgeries performed annually, clinics are gaining popularity due to their convenience, and easy availability of surgeons. Compared to hospitals, these clinics are specialized to deliver safer and quicker same-day procedures. Moreover, growing awareness regarding oral health is further propelling the market.
 To learn more about this report, Download Free Sample Report
Private dental clinics or specialty clinics are present in large numbers and typically have skilled practitioners specializing in bone grafting procedures. Manufacturing companies have a wide delivery network and target dental clinics primarily through direct sales; multiple smaller clinics tend to collectively bring in more customers than a single hospital. For instance, the Institute Straumann stated in its annual report that its professionals primarily operated in 1,300 dental clinics, as of 2020, and place 300,000 implants annually.
The hospital segment is anticipated to witness the highest growth rate of 10.2% over the forecast period. The growth can be attributed to the availability of a wide range of reconstructive procedures under these facilities. Few hospitals are self-funded and are associated with tissue banks aiming to provide class-leading services. Moreover, hospitals collaborate with various insurance companies for better and fast reimbursement. Owing to all these benefits the overall footfall in hospitals is more as compared to clinics.
Regional Insights
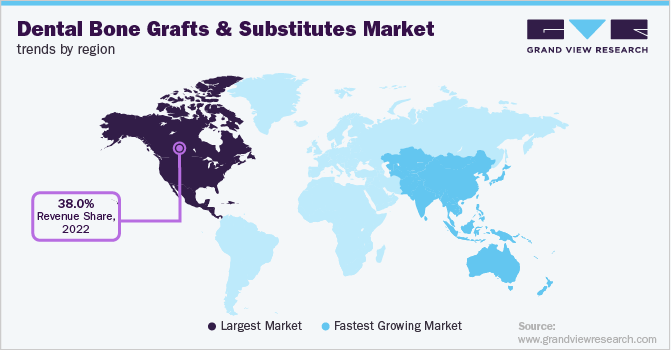
North America dominated the dental bone grafts and substitutes market with the largest revenue share of 38.3% in 2025. The increasing target population and the increasing number of dental implant surgeries in this region are driving growth. Europe held the second-largest share and is expected to show lucrative growth in the coming years. Asia Pacific region is expected to show the highest growth of rate 10.9% over the forecast period. The growth can be attributed to an increased number of medical tourism and government initiatives. Moreover, a growing aging population in this region is further increasing the risk of dental problems. On the contrary, stringent regulatory guidelines in some countries can limit growth in the near future. In South Korea, the product should be approved by the Korean Food and Drug Administration (KFDA) before marketing. In the case of Australia, the graft products are regulated by Therapeutic Goods Administration (TGA). The stringent regulatory scenario in these countries creates a barrier for foreign players to enter the market.
 To learn more about this report, Download Free Sample Report
Medical tourism in India and China for dental grafting surgeries is another growth-propelling factor for the market. In addition, the availability of resources that enable the development of advanced End-Use at a cheaper cost is resulting in an increased number of manufacturing facilities in these countries.China has released Order 650 (former Order 276), Regulations for the Supervision and Administration of Medical Devices, to restrict foreign investment in the country, mainly to protect the domestic medical devices manufacturing industry. As a result, the number of local bone graft manufacturers is anticipated to grow in near future.
Key Companies & Market Share Insights
The industry is marked by the presence of various small and large industry players. The market is highly fragmented and competitive in nature. Geistlich, ACE Surgical, Zimmer Biomet & BioHorizons held the major share of the U.S. as of 2022. The players are constantly involved in strategic initiatives such as acquisitions, new product launches, technological advancements, and collaborations in order to gain deeper penetration. For instance, In March 2021, Institut Straumann signed an investment agreement with the Shanghai Xin Zhuang Industrial Park to establish its first Campus in China which will comprise a manufacturing plant, education, and innovation center in the country.
The China Campus will provide various educational programs as well as products from the Straumann Group’s implant and orthodontics portfolio for China, catering to the rapidly growing demands of Chinese dentists and patients for dental solutions. In March 2019, BioHorizons acquired Intra-Lock to include the IntraSpin system in its portfolio for better penetration. Some of the prominent players in the global dental bone gratfs and substitutes market include:
Key Dental Bone Grafts And Substitutes Companies
The following key companies have been profiled for this study on the dental bone grafts and substitutes market.
-
Orthogen.
-
Rti Surgicals
-
Zimmer Biomet
-
Institut Straumann AG
-
ZimVie
-
Dentsply Sirona
-
Nobel Biocare (Envista)
-
Geistlich Pharma
-
Medtronic
-
BioHorizons
-
botiss
-
Henry Schein
-
NovaBone
-
LifeNet Health
-
Neoss
-
Salvin
-
Dentium USA
-
Implant Direct
-
SigmaGraft
-
Regenity (GUIDOR)
-
GC America Inc.
-
Others
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Institut Straumann AG, Geistlich Pharma AG, ZimVie Inc., Nobel Biocare Services AG, Dentsply Sirona, Inc., Medtronic)
- Focus on expanding comprehensive dental bone graft and regenerative portfolios through continuous R&D investments, product innovation, and integration of advanced biomaterials, allografts, xenografts, synthetic grafts, and regenerative membranes.
- Strengthening market presence through strategic acquisitions, global distribution networks, collaborations with dental professionals, and expansion across hospitals, dental clinics, and academic institutions.
- Strong global brand recognition, extensive product portfolios, well-established distribution channels, advanced manufacturing capabilities, and significant investments in clinical research.
- Broad regulatory expertise, strong financial resources, and long-standing relationships with dental practitioners enable rapid commercialization and widespread market penetration.
- High R&D and regulatory compliance costs, dependence on product approvals and reimbursement policies in certain markets, and challenges associated with integrating acquired businesses.
- Intense competition, pricing pressures, and the need for continuous innovation may impact long-term profitability.
Emerging Players (Botiss, Neoss Inc., Advanced Medical Solutions Group plc, Tecnoss S.r.l., B&B Dental S.r.l., NovaBone Products LLC)
- Focus on developing specialized bone graft substitutes, regenerative biomaterials, collagen membranes, and innovative tissue regeneration solutions tailored for implantology and oral surgery.
- Expand market presence through partnerships with regional distributors, dental laboratories, research institutes, and clinician education programs while targeting niche and high-growth markets.
- Strong specialization in regenerative biomaterials, greater flexibility in product development, faster innovation cycles, and the ability to address specific clinical applications.
- Agile business models enable quicker adoption of emerging technologies and competitive positioning in specialized dental regeneration segments.
- Limited global distribution networks, lower brand recognition, and comparatively smaller financial resources than multinational competitors.
- Dependence on strategic partnerships, regulatory approvals, and limited commercialization capabilities may restrict expansion into highly competitive international markets.
Dental Bone Grafts And Substitutes Market Report Scope
Report Attribute
Details
Market size in 2025
USD 901.1 million
Estimated market size in 2026
USD 973.1 million
Projected market size by 2033
USD 1,784.9 million
Growth rate
CAGR of 9.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material type, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark, Sweden, Norway, China; Japan; India; Australia; Thailand; South Korea, Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Institut Straumann AG, Geistlich Pharma AG, ZimVie Inc., Botiss, Nobel Biocare Services AG, Dentsply Sirona, Inc., Medtronic, Neoss Inc., Advanced Medical Solutions Group plc, BioHorizons, Inc., Tecnoss S.r.l., B&B Dental S.r.l., NovaBone Products LLC, Regenity, and Maxigen Biotech Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Dental Bone Grafts And Substitutes Market Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global dental bone grafts and substitutes market report on the basis of material type, application, end-use, and region:
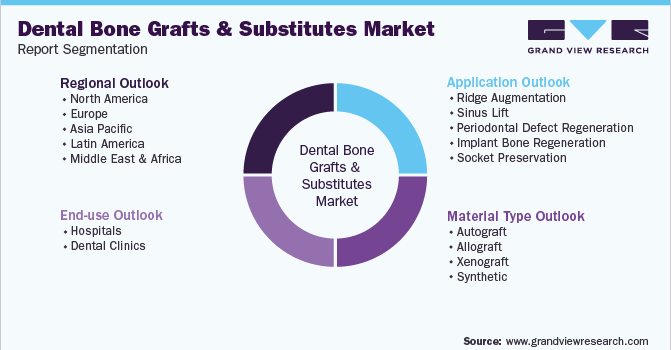 To learn more about this report, Download Free Sample Report
-
Material Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Autograft
-
Allograft
-
Demineralized Bone Matrix
-
Others
-
-
Xenograft
-
Bovine Derived
-
Porcine Derived
-
Others
-
-
Synthetic
-
Hydroxyapatite (HA)
-
Tricalcium Phosphate (TCP)
-
Bioactive Glass
-
Others
-
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Ridge Augmentation
-
Sinus Lift
-
Periodontal Defect Regeneration
-
Implant Bone Regeneration
-
Socket Preservation
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Dental Clinics
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The dental bone grafts and substitutes market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each dental bone grafts and substitutes segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Material Type
Revenue capture definition
Autograft
Revenue is generated from the sale and use of autologous bone grafting procedures, including surgical instruments, bone harvesting systems, and related products used for bone regeneration in dental implant and oral reconstructive procedures.
Allograft
Revenue is generated from the commercialization of human donor-derived bone graft materials processed by tissue banks for use in dental bone regeneration, ridge preservation, sinus augmentation, and periodontal procedures.
Xenograft
Revenue is generated from the sale of animal-derived bone graft substitutes, primarily bovine or porcine sources, used to support bone regeneration, dental implant placement, and oral surgical applications.
Synthetic
Revenue is generated from the sale of synthetic bone graft substitutes manufactured from biocompatible materials such as hydroxyapatite, beta-tricalcium phosphate (β-TCP), bioactive glass, and calcium phosphate composites used in dental bone regeneration procedures.
Estimation Model
Layer Name
Key Question
Description
Bottom-Up Estimation
How is the dental bone grafts and substitutes market estimated from manufacturer and supplier revenues?
Market revenue is estimated by aggregating the annual revenues generated by manufacturers and suppliers of dental bone grafts and substitutes across different material types, applications, and end-use settings worldwide. The analysis considers product sales of autografts, allografts, xenografts, and synthetic grafts, utilized in ridge augmentation, sinus lift procedures, periodontal defect regeneration, implant bone regeneration, and socket preservation. ASP per procedure and product volume usage across hospitals and dental clinics are applied to estimate the overall market size.
Top-Down Approach
How is the dental bone grafts and substitutes market derived from the broader dental biomaterials and regenerative dentistry market?
The overall dental bone grafts and substitutes market is analyzed within the broader dental biomaterials and regenerative dentistry market framework. Total market size is derived based on the volume of dental implant procedures, periodontal surgeries, oral reconstruction procedures, and bone regeneration treatments performed globally. Market share allocation is determined by assessing the adoption rates of various graft materials, clinical preferences, procedural trends, and penetration levels across hospitals and dental clinics in both developed and emerging markets.
Supply-Side Analysis
What manufacturing capabilities and market factors determine the supply of dental bone grafts and substitutes?
This approach evaluates the manufacturing capacity, product portfolio, and revenue generation of leading dental bone graft and substitute manufacturers. The assessment includes analysis of production capabilities for autograft alternatives, allografts, xenografts, and synthetic graft materials. Key factors evaluated include R&D investments, regulatory approvals, distribution networks, strategic partnerships, geographic presence, manufacturing facilities, and product innovation initiatives to assess the competitive landscape and overall market potential.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking & End-Use Assessment
Evaluated leading manufacturers of dental bone grafts and substitutes based on product portfolio, graft material offerings, distribution capabilities, geographic presence, strategic partnerships, regulatory approvals, and innovation initiatives.
Assessed product adoption across hospitals and dental clinics, including procurement trends, clinician preferences, and advancements in regenerative biomaterials and bone regeneration technologies.
Supports competitive benchmarking, identifies innovation opportunities, enables optimization of channel strategies across hospitals and dental clinics, and helps companies strengthen market positioning by addressing the evolving needs of dental practitioners and oral healthcare providers.
Regional Demand & Adoption Analysis
Conducted an in-depth assessment of regional demand patterns for dental bone grafts and substitutes across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
Evaluated country-level adoption of autografts, allografts, xenografts, synthetic grafts, and DBM products based on dental implant penetration, prevalence of dental diseases, healthcare expenditure, reimbursement scenarios, and availability of advanced dental care infrastructure.
Assists stakeholders in identifying high-growth geographic markets, prioritizing expansion opportunities, understanding regional treatment preferences, and developing targeted market entry and distribution strategies.
Technology Innovation & Product Pipeline Assessment
Assessed emerging technologies and innovation trends in the dental bone grafts and substitutes market, including bioactive synthetic materials, growth factor-enhanced grafts, stem cell-based regenerative solutions, 3D-printed bone substitutes, and next-generation biomaterials.
Evaluated ongoing R&D activities, product launches, patent landscapes, regulatory developments, and strategic collaborations among key market participants.
Enables companies to identify future growth opportunities, benchmark innovation capabilities, monitor competitive developments, and align product development strategies with evolving regenerative dentistry trends and clinician requirements.
Frequently Asked Questions About This Report
The global dental bone grafts and substitutes market size was valued at USD 901.1 million in 2025 and is estimated at USD 973.1 million for 2026.
Based on material type, the xenograft segment held the largest share of 46.1% in 2025, while synthetic is the fastest-growing segment over the forecast period.
North America dominated with a 38.3% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The socket preservation held the largest share of 30.5% in 2025, while sinus lift is the fastest-growing segment over the forecast period.
The dental clinics held the largest share of 70.1% in 2025, while hospitals is the fastest-growing segment over the forecast period.
Some key players operating in the dental bone grafts and substitutes market include Institut Straumann AG, Geistlich Pharma AG, ZimVie Inc., Botiss, Nobel Biocare Services AG, Dentsply Sirona, Inc., Medtronic, Neoss Inc., Advanced Medical Solutions Group plc, BioHorizons, Inc., Tecnoss S.r.l., B&B Dental S.r.l., NovaBone Products LLC, Regenity, and Maxigen Biotech Inc.
Key factors include the increasing prevalence of tooth loss, periodontal diseases, and dental trauma, which are driving demand for dental implants and bone regeneration procedures.
The global dental bone grafts and substitutes market is expected to grow at a CAGR of 9.1% from 2026 to 2033, reaching USD 1,784.9 million in 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


