
- Home
- »
- Clinical Diagnostics
- »
-
Drug Screening Market Size & Share Report, 2026-2033GVR Report cover

Drug Screening Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Instruments, Rapid Testing Devices, Consumables, Services & Others), By Sample (Urine Sample, Breath Sample, Oral Samples), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$11.1BMarket Estimate, 2026
$11.8BMarket Forecast, 2033
$19.1BCAGR, 2026–2033
7.1%Drug Screening Market Summary
The global drug screening market size was valued at USD 11.1 billion in 2025 and is projected to grow from USD 11.8 billion in 2026 to USD 19.1 billion by 2033, at a CAGR of 7.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 38.6% in 2025. The growth of the market is attributed to the rising substance abuse, stringent regulations, government funding, technological advancements, and increasing demand for substance testing across sectors like healthcare and sports, driven by the need for effective substance abuse detection and management.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Consumables segment dominated the drug screening market, accounting for the largest revenue share of 34.8% in 2025.
- By sample type: Urine sample segment held the largest share of the drug screening market, accounting for 41.5% in 2025.
- By end use: The drug treatment centers segment dominated the drug screening market, accounting for the largest revenue share of 26.3% in 2025.
Regional Highlights
- Largest regional market: North America (38.6% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 11.1 Billion
- Estimated market size in 2026: USD 11.8 Billion
- Projected market size by 2033: USD 19.1 Billion
- CAGR (2026-2033): 7.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
Market Dynamics
The drug screening market is witnessing steady growth driven by increasing emphasis on workplace safety, rising substance abuse monitoring, expanding regulatory oversight, and growing adoption of rapid testing technologies across healthcare, law enforcement, and occupational settings. Organizations are increasingly implementing routine drug screening programs to comply with workplace regulations, reduce safety risks, and improve operational productivity. Continuous advancements in immunoassay systems, chromatography technologies, oral fluid testing, and breath analysis are improving testing efficiency while supporting faster decision making across decentralized testing environments. For instance, in August 2024, the U.S. Department of Transportation implemented a final rule permitting oral fluid testing as an additional methodology for regulated workplace drug testing programs, expanding the adoption of less invasive testing approaches while strengthening testing integrity. The market is also benefiting from increasing investments in portable testing solutions, broader availability of point of care devices, and continued expansion of laboratory testing services. These developments are supporting wider acceptance of drug screening across public and private sectors while improving accessibility, compliance, and long-term market growth.
The growing emphasis on workplace safety, regulatory compliance, and employee health are key drivers of the drug screening market. Employers across transportation, manufacturing, construction, healthcare, and public safety sectors are strengthening pre-employment, random, and post incident drug testing programs to minimize occupational risks and maintain regulatory compliance. Rising concerns regarding substance misuse and its impact on workplace productivity and accident prevention are encouraging organizations to adopt rapid and laboratory-based drug screening solutions. The availability of point of care testing devices and improvements in testing accuracy are further supporting broader implementation across diverse work environments. For instance, in January 2025, the U.S. Department of Health and Human Services published updated Mandatory Guidelines for Federal Workplace Drug Testing Programs that added fentanyl to authorized testing panels for federal workplace testing, strengthening standardized screening practices across government agencies. Such regulatory developments continue to encourage employers and testing providers to expand drug screening capabilities and improve workplace safety programs.
The drug screening market continues to face challenges related to false positive and false negative results, particularly in rapid screening methods that require confirmatory laboratory testing before clinical or legal decisions can be made. Cross reactivity with prescription medications, over the counter products, and certain dietary substances may influence preliminary screening outcomes, increasing the need for confirmatory analysis using chromatography-based techniques. These additional testing requirements increase operational costs, extend reporting timelines, and create workflow complexity for laboratories and employers. Variations in testing policies, specimen collection procedures, and legal frameworks across countries further affect market adoption and standardization. Privacy concerns associated with workplace and individual drug testing also influence acceptance in certain regions. Consequently, healthcare providers, employers, and regulatory agencies continue to emphasize standardized testing protocols and confirmatory laboratory procedures to improve reliability while maintaining compliance with established regulatory and legal requirements.
The increasing demand for convenient and rapid drug screening solutions is creating significant opportunities for manufacturers and service providers to expand decentralized testing capabilities. Growing adoption of point of care technologies, home based testing services, and digital reporting platforms is enabling faster decision making while reducing dependence on centralized laboratories. These solutions are gaining traction across workplaces, occupational health programs, law enforcement agencies, and individual users seeking timely screening results. Continuous product innovation is also improving accessibility and operational efficiency through simplified sample collection and faster result interpretation. For instance, in June 2025, InOut Labs, together with Novir, launched the InstaCLEAR drug testing platform to provide flexible testing services for employers and individuals across home, workplace, and mobile settings, expanding access to decentralized drug screening services. Such developments are expected to strengthen market penetration by addressing the growing demand for accessible, convenient, and efficient drug testing solutions across multiple end user segments.
Market Concentration & Characteristics
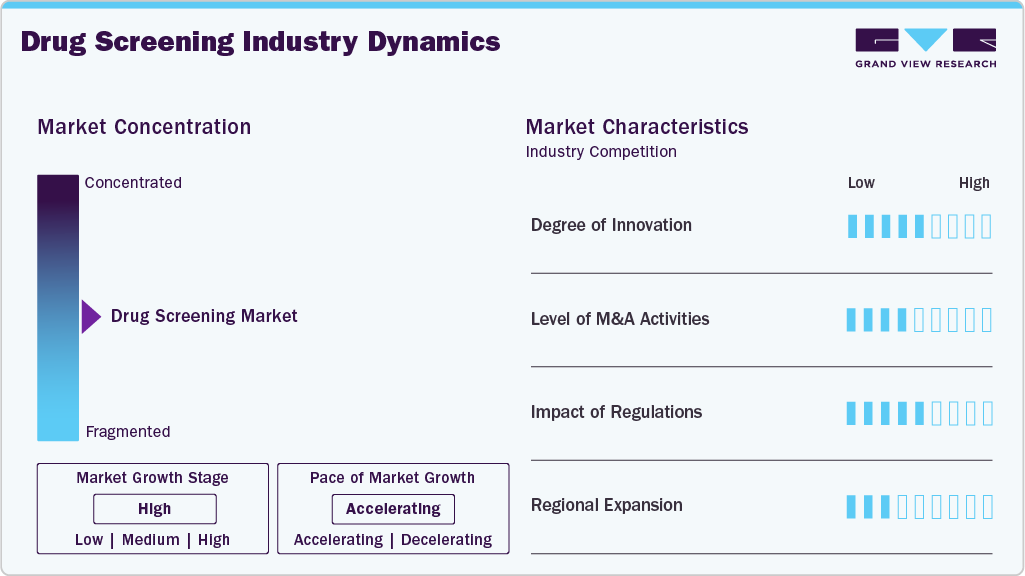
The degree of innovation is high in the market, particularly in the development of sensitive lab-based testing methods and wearable devices for real-time monitoring of drug use and metabolites. Saliva-based testing, known for its non-invasiveness and quick results, is developing, promising increased accessibility and accuracy in the future.
Several players in the drug screening market are actively engaged in mergers and acquisitions to strengthen their market positions and accelerate technological advancement. This strategy enables companies to enhance capabilities, expand product portfolios, improve competency, and gain access to new customer segments across clinical, workplace, and forensic testing applications. M&A activities also support integration of advanced technologies such as rapid immunoassays, point-of-care testing platforms, and laboratory-based confirmatory methods, thereby improving diagnostic accuracy and turnaround time. For instance, in November 2025, Premier Biotech acquired National Test Systems (NTS), a provider of rapid drug screening solutions, to expand its point-of-care testing portfolio and strengthen its distribution network across the behavioral health and government sectors. The acquisition further enabled Premier Biotech to reinforce its end-to-end drug and alcohol testing capabilities.
 To learn more about this report, Download Free Sample Report
Strict regulations for drug screening products act as a key restraint in the market. They slow down innovation, extend product development timelines, and increase compliance and approval costs for manufacturers. In many high-potential regions with large patient populations, regulatory requirements such as extensive clinical validation, documentation, and multi-stage approvals delay the introduction of new screening solutions. For instance, in the U.S., drug screening devices must comply with stringent U.S. FDA regulations, which require detailed performance data and clinical evidence before approval. Similarly, in Europe, compliance with CE-IVD requirements under the In Vitro Diagnostic Regulation (IVDR) involves rigorous safety and effectiveness assessments, often resulting in longer approval timelines. As a result, companies often face delayed commercialization, which can limit the rapid availability of advanced, more accurate drug-screening products.
The industry is witnessing strong regional expansion driven by stricter regulatory frameworks and increasing adoption of workplace and clinical testing programs. In developed regions, the market is driven by well-established healthcare systems and mandatory workplace testing policies, which sustain consistent demand for drug screening solutions. At the same time, emerging regions are experiencing faster growth as governments strengthen healthcare infrastructure, expand laboratory capacity, and introduce stricter regulations to enhance public safety and workplace compliance. Overall, the market is expanding globally, with both developed and developing regions contributing to sustained demand growth, although at different rates.
Analyst Perspective
The drug screening market is expected to witness sustained growth, driven by increasing focus on workplace safety, expanding substance abuse monitoring programs, and strengthening regulatory requirements across healthcare, transportation, criminal justice, and occupational sectors. Drug screening serves as an essential tool for detecting the use of illicit substances, prescription drug misuse, and alcohol consumption, supporting timely clinical intervention, regulatory compliance, and public safety initiatives. The market is benefiting from the growing adoption of rapid testing devices, automated immunoassay analyzers, chromatography based confirmatory testing, oral fluid testing technologies, and portable breath analyzers that improve testing accessibility and diagnostic accuracy. Furthermore, increasing acceptance of point of care testing, expansion of laboratory testing services, rising employer awareness regarding workplace drug policies, and ongoing investments in innovative screening technologies are supporting market development. Continued advancements in decentralized testing platforms, digital reporting solutions, laboratory automation, and broader integration of drug screening into occupational health and clinical care pathways are expected to strengthen the market's long term growth outlook.
Product Insights
Based on product, consumables segment dominated the drug screening market, accounting for the largest revenue share of 34.8% in 2025, due to the fact that consumables, such as assay kits, sample collection devices, and calibrators & controls, are crucial for on-site Illicit substance testing, readily available, and must be repeatedly purchased due to their one-time use nature. In addition, immunoassay analyzers, which are often used with consumables, provide quick, cost-effective screening of samples across various matrices, further underscoring the segment's significance in the market. This reliance on consumables for accurate and efficient drug testing processes highlights their pivotal role in the drug screening industry. Moreover, product launches by the industry player further contribute to the segment growth. Moreover, product launches by industry players further contribute to segment growth. For instance, in October 2025, AccuBioTech launched the Accu-Tell Multi-Drug Midstream Pro (Saliva), a next-generation oral fluid drug-screening device that enables rapid detection of 20+ drugs and metabolites within 10 minutes using immunoassay technology, strengthening the adoption of rapid, single-use consumables in on-site testing applications.
The services & others segment is anticipated to grow at the significant CAGR of 7.16% over the forecast period, due to their significant role in providing essential services and support for substance screening processes. This segment encompasses screening, laboratory, and other related services that are crucial for accurate and efficient testing. For instance, major diagnostic service providers such as Quest Diagnostics operate large-scale laboratory networks offering drug testing and toxicology services across clinical settings. In addition, this segment includes analytical instruments, rapid testing devices, and drug screening services that are vital to conducting drug tests effectively. The growth of this segment is driven by the increasing demand for reliable screening measures, the rise in substance abuse issues, and the need for innovative testing technologies to address evolving challenges in drug testing. The emphasis on providing comprehensive services and advanced solutions to cater to diverse industries and end users contributes to the dominance of the services and others segment in the marketplace.
Sample Insights
Based on sample type, urine sample segment held the largest share of the drug screening market, accounting for 41.5% in 2025. Urine is most often the preferred test substance because of ease of collection. Urine testing is non-invasive, detecting a wide range of drugs, including illegal and prescription drugs, and provides a longer detection window for drug use identification. The rising application of urine drug testing for monitoring patients with long-term opioid therapy further propelled the growth of the Urine Samples segment. In addition, urine drug testing is generally more cost-effective compared to other testing methods, such as hair testing. These advantages, along with the growing demand for comprehensive and reliable drug screening, contributed to the dominance of the urine samples segment.
The other samples segment is expected to grow significantly over the forecast period due to increasing preference for non-invasive, convenient testing methods. These samples are easier to collect compared to traditional urine or blood samples and are therefore widely adopted for workplace testing, roadside screening, and point-of-care settings. Technological advancements have also improved the accuracy and reliability of these testing methods, increasing their acceptance among healthcare providers and regulatory authorities. The growing focus on workplace safety regulations, the expansion of rapid testing solutions, and the rising demand for on-site, instant screening are further driving this segment's growth.
End Use Insights
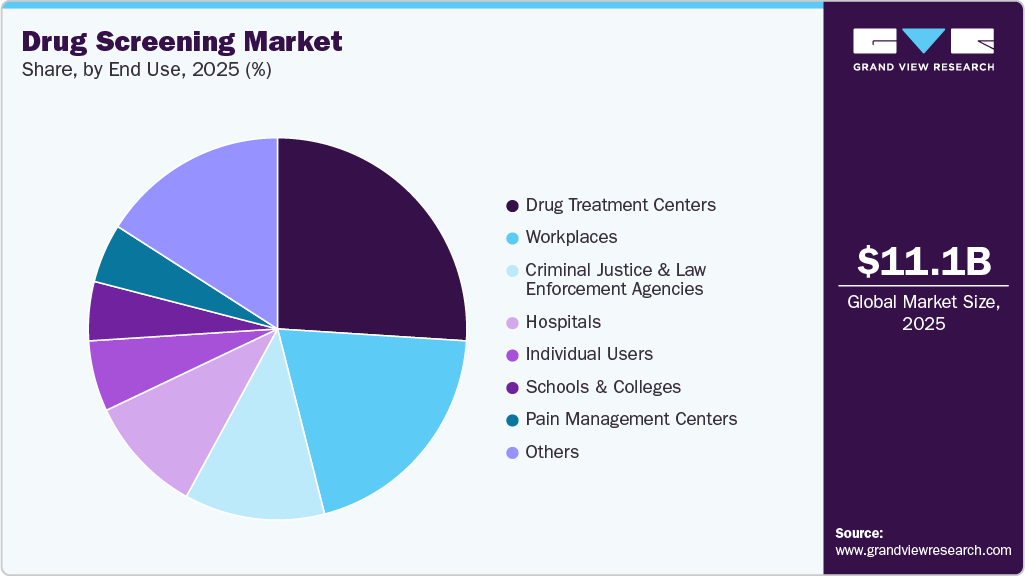
The drug treatment centers segment dominated the drug screening market, accounting for the largest revenue share of 26.3% in 2025. The segment dominance can be attributed to the increasing focus on substance abuse treatment and rehabilitation, leading to a higher demand for drug testing services in these centers. Drug treatment centers play a crucial role in providing comprehensive care and support to individuals struggling with substance abuse, making drug screening an essential component of their services. In addition, the rising prevalence of drug addiction contributes to the segment's share. According to The Adult Substance Misuse Treatment Statistics 2024-2025 report shows a continued rise in demand for drug and alcohol treatment services in England, where between April 2024 and March 2025, around 329,646 adults were in contact with structured treatment services, marking a 6% increase compared to the previous year and the highest level recorded since reporting began, further highlighting the growing burden on treatment systems and the need for continuous monitoring and screening within rehabilitation settings.
 To learn more about this report, Download Free Sample Report
The hospitals segment is expected to grow at the fastest CAGR over the forecast period, due to the increasing need for rapid, accurate toxicology testing in emergency and critical care settings. Hospitals frequently handle cases such as drug overdose, poisoning, road accidents, and substance abuse-related emergencies, where immediate screening is essential for timely treatment decisions. In addition, growing patient admissions and rising prevalence of substance use disorders are increasing the demand for routine drug testing in hospital laboratories. Further, hospitals are increasingly adopting advanced point-of-care and automated drug screening systems to improve diagnostic efficiency and reduce turnaround time. Strengthening regulatory requirements for patient safety, pre-assessment protocols for surgery, and medico-legal documentation also contribute to higher testing volumes in hospital settings. Together, these factors are driving strong, sustained growth in the hospitals segment of the drug screening market.
Regional Insights
North America drug screening industry accounted for the largest revenue share of 38.6% in 2025 and is anticipated to grow at fastest growth over the forecast period, supported by persistently high rates of drug use and strong enforcement of workplace and clinical testing policies. According to the CDC, the U.S. recorded an estimated 107,543 drug overdose deaths in 2023, with around 81,083 deaths involving opioids, including synthetic opioids such as fentanyl, which remain the primary driver of fatalities. Despite this recent decline, overdose mortality remains historically high, with synthetic opioids involved in the majority of cases, underscoring continued public health concern and sustained demand for effective drug screening and monitoring systems. This ongoing burden of substance misuse, combined with workplace safety regulations and rising awareness of drug-related risks, continues to reinforce North America’s dominant position in the global market.
 To learn more about this report, Download Free Sample Report
U.S. Drug Screening Market Trends
The drug screening market in the U.S. held the largest share in the North America region in 2025, due to the increasing prevalence of substance abuse and the strong presence of strict workplace and federal drug testing regulations. Employers across industries in the U.S. are required to conduct regular drug testing to ensure workplace safety, which is driving consistent demand for screening services and products. The country also benefits from advanced healthcare infrastructure, high adoption of rapid and point-of-care testing technologies, and continuous technological innovations in drug testing methods. Moreover, growing awareness about employee health and safety, along with expanding use of drug screening in criminal justice and rehabilitation programs, is further contributing to the market’s strong growth outlook.
Europe Drug Screening Market Trends
The drug screening industry in Europe is expected to witness significant growth during the forecast period, due to a combination of regulatory, social, and healthcare factors. Increasing enforcement of stringent workplace drug testing regulations across industries such as transportation, construction, and healthcare is driving higher adoption of screening solutions. In addition, the rising prevalence of substance abuse and illicit drug consumption in several European countries is creating greater demand for preventive and diagnostic testing. Moreover, advancements in rapid testing technologies and the increasing availability of accurate, cost-effective screening kits are improving accessibility and boosting usage. The expansion of healthcare infrastructure and rising awareness of early detection and treatment of drug dependence also contribute to the market’s growth in the European Union.
The UK drug screening industry is expected to grow over the forecast period, driven by increasing regulatory enforcement, rising substance abuse cases, and growing emphasis on workplace and public safety. The expanding adoption of advanced testing technologies such as rapid immunoassays and point-of-care drug testing solutions is improving detection accuracy and enabling faster results across healthcare and non-healthcare settings. In addition, increasing government initiatives, stricter compliance requirements, and broader implementation of mandatory drug testing policies are supporting market expansion. Continuous technological advancements and increasing awareness regarding early detection and prevention of drug misuse are also contributing to sustained growth across regions, including the European Union.
The drug screening industry in Germany is expected to grow over the forecast period, driven by the rising prevalence of substance abuse and the increasing need for reliable toxicology testing across healthcare, workplace, and forensic settings. The growing burden of substance misuse is supporting the adoption of advanced drug screening solutions such as immunoassay-based testing, chromatography techniques, and rapid point-of-care testing across hospitals, rehabilitation centers, and forensic laboratories in Germany. In addition, increasing workplace drug testing regulations, expanding addiction treatment programs, and continuous advancements in highly sensitive and rapid screening technologies are further driving market growth in the country.
Asia Pacific Drug Screening Market Trends
The drug screening industry in the Asia Pacific is anticipated to witness the fastest growth over the forecast period. The presence of a large target population, high unmet clinical needs, and developing healthcare systems are anticipated to drive high growth potential for the industry in the region. The region's increasing investment in healthcare infrastructure and research and development activities is leading to advancements in technologies and methodologies. In addition, the rising prevalence of chronic diseases, the need for effective disease monitoring, and the growing trend of outsourcing drug discovery services have fueled the demand in the Asia Pacific region. For instance, the region's growing population, particularly in countries such as China and India, is driving the demand for healthcare services, including substance screening. Furthermore, the increasing awareness about the importance of illicit substance screening in the diagnosis and treatment of diseases is also contributing to the growth of the Asia Pacific region.
The China drug screening industry is witnessing significant growth, driven by the increasing prevalence of substance abuse, stringent government regulations, and rising demand for workplace and forensic testing. The growing burden of illicit drug consumption, particularly in urban and industrial regions, is contributing to higher adoption of drug screening solutions across hospitals, rehabilitation centers, law enforcement agencies, and workplace testing programs. In addition, the expansion of healthcare infrastructure, strengthening of national drug control policies, and increasing use of rapid immunoassay-based testing, chromatography techniques, and laboratory-based confirmatory testing are further supporting market growth in China. The growing emphasis on public safety, occupational screening compliance, and rehabilitation monitoring is also accelerating the adoption of advanced drug screening technologies nationwide.
Latin America Drug Screening Market Trends
The drug screening industry in Latin America is identified as a lucrative region in the industry, driven by increasing concerns over substance abuse, rising crime rates linked to illicit drug consumption, and expanding government initiatives to strengthen public safety and workplace compliance. In addition, growing awareness of the benefits of alcohol and illicit substance testing in workplaces, transportation sectors, and criminal justice systems is significantly contributing to market expansion. Countries such as Brazil and Argentina are witnessing increased implementation of drug screening programs in law enforcement agencies, rehabilitation centers, and occupational health services. Furthermore, rising investments in healthcare infrastructure, coupled with strengthening regulatory frameworks for drug-free workplace policies, are expected to further support sustained market growth across Latin America.
Middle East and Africa Drug Screening Market Trends
The drug screening industry in the Middle East & Africa is witnessing steady growth, driven by rising concerns about substance abuse, stricter regulatory enforcement, and greater emphasis on workplace safety and criminal justice applications. The region is also experiencing a gradual expansion of healthcare infrastructure and laboratory capabilities, improving access to toxicology testing, urine analysis, oral fluid testing, and hair drug screening.
Key Drug Screening Company Insights
Key players operating in the market are undertaking various initiatives to strengthen their market presence and increase the reach of their technology and services. Strategies such as expansion activities and partnerships are playing a key role in propelling the market growth.
Key Drug Screening Companies
The following key companies have been profiled for this study on the drug screening market.
-
Abbott
-
Quest Diagnostics Incorporated
-
F. Hoffmann-La Roche Ltd
-
Thermo Fisher Scientific Inc.
-
Siemens Healthcare AG
-
Laboratory Corporation of America Holdings
-
Alfa Scientific Designs, Inc.
-
OraSure Technologies, Inc.
-
Omega Laboratories, Inc.
-
Drägerwerk AG & Co. KGaA
-
Bio-Rad Laboratories, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well Established Players (Abbott, Quest Diagnostics, Thermo Fisher Scientific, F. Hoffmann La Roche, Siemens Healthineers, Laboratory Corporation of America Holdings, OraSure Technologies)
- Focus on expanding comprehensive drug screening portfolios through immunoassay analyzers, chromatography systems, rapid testing devices, oral fluid testing, breath analyzers, and laboratory services. Emphasize regulatory compliance, product innovation, laboratory network expansion, strategic acquisitions, and partnerships with employers, hospitals, law enforcement agencies, and occupational health providers to strengthen market presence.
- Strong global distribution networks, established laboratory infrastructure, broad product portfolios, recognized brands, extensive regulatory expertise, and long standing relationships with healthcare providers, government agencies, and workplace testing organizations. Ability to support high testing volumes through scalable laboratory operations and advanced analytical technologies.
- High dependence on regulatory compliance, pricing pressure from competitive bidding, significant capital investment in laboratory infrastructure, and ongoing costs associated with product development, quality assurance, and laboratory accreditation. Growing competition from specialized rapid testing providers may also affect market share in decentralized testing.
Emerging & Regional Players (Alfa Scientific Designs, Omega Laboratories, Drägerwerk AG & Co. KGaA, Premier Biotech, Cannabix Technologies, USDTL)
- Focus on specialized drug screening solutions including rapid testing devices, oral fluid testing, breath analysis technologies, forensic toxicology services, and workplace screening programs. Emphasize innovation in portable testing, regional expansion, strategic partnerships, contract laboratory services, and cost effective solutions to address evolving regulatory and customer requirements.
- Flexibility in product development, faster commercialization of niche technologies, competitive pricing, specialized expertise in workplace and forensic drug testing, and strong regional customer relationships. Ability to rapidly respond to changing testing requirements through focused product offerings and customized laboratory services.
- Limited international presence, smaller commercial infrastructure, narrower product portfolios, and lower financial resources compared with multinational companies. Dependence on regional markets, distributor networks, and regulatory approvals may restrict global expansion and reduce competitiveness against established industry leaders.
Recent Developments
-
In April 2026, InOut Labs launched nationwide oral fluid drug testing for employers, enabling centralized management of workplace screening programs through a digital platform. The solution offers tamper-resistant testing designed to detect recent substance use, supporting compliance-focused, efficient, and legally defensible drug screening across distributed workforces and industries.
-
In March 2026, Cannabix Technologies announced the commercial launch of its Marijuana Breath Test (MBT), marking a phased rollout of its non-invasive breath-based drug screening system. The solution detects recent cannabis use within hours of consumption and is being deployed across the workplace, law enforcement, and safety-sensitive sectors to enhance rapid impairment-focused testing.
Drug Screening Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.1 billion
Estimated market size in 2026
USD 11.8 billion
Projected market size by 2033
USD 19.1 billion
Growth rate
CAGR of 7.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, Sample Type, End Use, Regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; and Kuwait
Key companies profiled
Abbott, Quest Diagnostics Incorporated, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Siemens Healthcare AG, Laboratory Corporation of America Holdings, Alfa Scientific Designs, Inc., OraSure Technologies, Inc., Omega Laboratories, Inc., Drägerwerk AG & Co. KGaA, Bio-Rad Laboratories, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Drug Screening Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global drug screening market report based on product, sample, end use, and region.
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Instruments
-
Immunoassays Analyzers
-
Chromatography Instruments
-
Breath Analyzer
-
Fuel Cell Breath Analyzer
-
Semi-Conductor Breath Analyzer
-
Others Breath Analyzer
-
-
-
Rapid Testing Devices
-
Urine Testing Devices
-
Drug Testing Cups
-
Dip Cards
-
Drug Testing Cassettes
-
-
Oral Fluid Testing Devices
-
-
Consumables
-
Assay Kits
-
Sample Collection Devices
-
Calibrators & Controls
-
Other Consumables
-
-
Services and Others
-
-
Sample Outlook (Revenue, USD Billion, 2021 - 2033)
-
Urine Samples
-
Breath Samples
-
Oral Fluid Samples
-
Hair Samples
-
Other Samples
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals
-
Criminal Justice & Law Enforcement Agencies
-
Workplaces
-
Drug Treatment Centers
-
Individual Users
-
Pain Management Centers
-
Schools & Colleges
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
Kuwait
-
UAE
-
-
Research Methodology
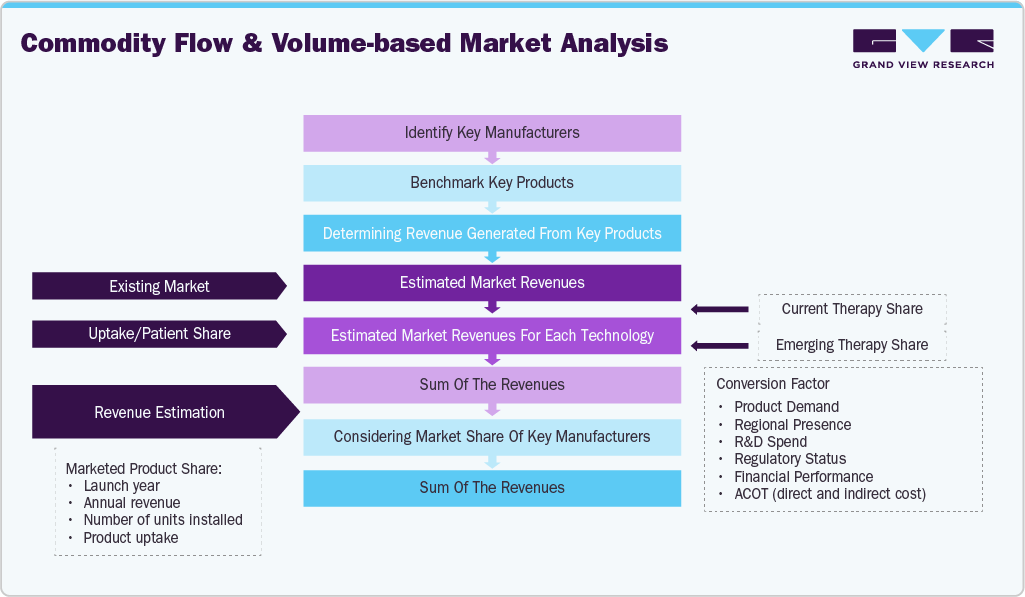
The drug screening market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each drug screening segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment
Market Definition (Revenue Capture-Based)
Instruments
Market value is captured through sales of laboratory and point of care equipment used to detect, identify, and quantify drugs of abuse across clinical, forensic, workplace, and law enforcement testing applications.
Immunoassay Analyzers
Revenue is primarily derived from automated analyzers performing immunoassay based screening for rapid qualitative or semi quantitative detection of drugs of abuse in biological specimens.
Chromatography Instruments
Revenue flows from gas chromatography and liquid chromatography systems, often coupled with mass spectrometry, used for confirmatory drug testing requiring high analytical sensitivity and specificity.
Breath Analyzer
Market demand is driven by analyzers that detect alcohol or drug related compounds in exhaled breath for roadside, workplace, and law enforcement screening applications.
Fuel Cell Breath Analyzer
Revenue is generated through fuel cell based breath analyzers that accurately measure breath alcohol concentration for evidential and workplace alcohol screening programs.
Semi Conductor Breath Analyzer
Market value is captured through semiconductor sensor based breath analyzers designed for rapid alcohol screening in personal, workplace, and law enforcement settings.
Others Breath Analyzer
Revenue encompasses infrared spectroscopy and other breath analysis technologies developed for alcohol detection and emerging drug screening applications.
Rapid Testing Devices
Revenue is primarily derived from portable screening devices providing rapid qualitative drug detection at the point of care without requiring centralized laboratory analysis.
Urine Testing Devices
Market demand is driven by disposable devices designed to rapidly detect drugs of abuse in urine samples across workplaces, hospitals, rehabilitation centers, and forensic settings.
Drug Testing Cups
Revenue flows from integrated collection and screening cups combining urine specimen collection with multi panel drug testing for convenient point of care screening.
Dip Cards
Revenue is captured through multi panel dip cards that provide rapid qualitative screening of urine samples for commonly abused drugs in decentralized testing environments.
Drug Testing Cassettes
Market value originates from cassette based immunoassay devices used for qualitative drug screening of urine or other biological samples in clinical and workplace settings.
Oral Fluid Testing Devices
Revenue is generated through rapid screening devices that detect drugs of abuse in saliva, supporting noninvasive testing across roadside, workplace, and forensic applications.
Consumables
Revenue is primarily derived from recurring purchases of reagents, collection supplies, controls, calibrators, and laboratory materials consumed during drug screening procedures.
Assay Kits
Revenue flows from immunoassay and analytical kits containing reagents required for detecting specific drugs or drug classes in biological specimens.
Sample Collection Devices
Market demand is driven by specimen collection products including urine cups, saliva collectors, breath sampling accessories, and transport devices supporting accurate sample integrity.
Calibrators & Controls
Revenue is captured through calibration standards and quality control materials used to validate instrument performance and ensure reliable drug screening results.
Other Consumables
Revenue encompasses laboratory consumables including buffers, reagents, pipette tips, tubes, and accessories required throughout routine drug screening workflows.
Services and Others
Market value is captured through laboratory testing services, confirmatory analysis, equipment maintenance, training, consulting, and outsourced drug screening solutions.
Segment
Market Definition (Revenue Capture-Based)
Urine Samples
Revenue is primarily derived from drug screening tests performed on urine specimens for detecting recent use of illicit drugs, prescription medications, and controlled substances.
Breath Samples
Revenue flows from alcohol and emerging drug screening tests conducted using exhaled breath specimens for roadside, workplace, and occupational safety applications.
Oral Fluid Samples
Market value is captured through saliva based drug screening that enables convenient, observed, and noninvasive detection of recent substance use across multiple testing environments.
Hair Samples
Revenue is generated from hair based drug testing used to evaluate long term patterns of substance use for workplace, forensic, and legal investigations.
Other Samples
Revenue encompasses drug screening performed using blood, sweat, nails, and other biological specimens selected for specialized clinical, forensic, or research applications.
Segment
Market Definition (Revenue Capture-Based)
Hospitals
Revenue is primarily derived from drug screening conducted within hospital settings for emergency care, toxicology assessment, patient management, and clinical decision making.
Criminal Justice & Law Enforcement Agencies
Market demand is driven by drug screening used by police departments, correctional facilities, probation services, and forensic agencies for legal enforcement and public safety purposes.
Workplaces
Revenue flows from employer sponsored drug testing programs supporting pre employment, random, post incident, and return to duty screening across occupational settings.
Drug Treatment Centers
Revenue is captured through routine drug monitoring services used to assess treatment adherence, relapse prevention, and patient recovery within substance abuse rehabilitation programs.
Individual Users
Market value originates from self administered drug screening products purchased directly by consumers for personal monitoring, family safety, or home testing purposes.
Pain Management Centers
Revenue is generated through drug screening performed to monitor prescription medication adherence, detect substance misuse, and support responsible opioid management among chronic pain patients.
Schools & Colleges
Revenue is primarily derived from institutional drug testing programs implemented to support student safety, athletic participation, and substance abuse prevention initiatives.
Others
Revenue encompasses drug screening conducted by military organizations, research institutions, insurance providers, occupational health clinics, and other specialized organizations requiring substance testing services.
Estimation Model
The drug screening market is expected to witness steady growth, driven by increasing regulatory requirements for substance abuse testing, rising adoption of workplace drug screening programs, and growing demand for rapid and reliable testing across healthcare, forensic, and occupational settings. Drug screening tests play a critical role in detecting the presence of illicit drugs, prescription medications, alcohol, and other controlled substances, supporting clinical diagnosis, workplace safety, law enforcement activities, rehabilitation programs, and public health initiatives. The market is benefiting from advancements in immunoassay technologies, chromatography based confirmatory testing, portable breath analyzers, oral fluid testing devices, and point of care diagnostics that improve testing accuracy, turnaround time, and operational efficiency. In addition, expanding implementation of drug testing regulations, increasing investments in decentralized testing solutions, broader adoption of oral fluid testing, and growing laboratory service capabilities are supporting market expansion. Continued product innovation, strengthening regulatory frameworks, and increasing collaborations among diagnostic manufacturers, laboratories, employers, and government agencies are expected to support the long term growth of the global drug screening market.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
Drug Screening Market Competitive Landscape & Market Assessment
Assessed the global drug screening market landscape, covering immunoassay analyzers, chromatography instruments, breath analyzers, rapid testing devices, consumables, laboratory services, and point of care drug screening solutions. Analyzed leading market participants, technology adoption trends, regulatory developments, workplace testing requirements, commercialization strategies, and competitive positioning across hospitals, workplaces, criminal justice agencies, and diagnostic laboratories.
Drug Screening Technology & Product Benchmarking Study
Delivered a comprehensive benchmarking of drug screening technologies including immunoassay analyzers, chromatography systems, oral fluid testing devices, urine testing devices, breath analyzers, assay kits, and laboratory information solutions. Evaluated analytical performance, testing accuracy, workflow efficiency, turnaround time, portability, regulatory compliance, and product differentiation among leading manufacturers.
Drug Screening Commercialization & Market Access Assessment
Assessed laboratory infrastructure, workplace testing programs, hospital adoption, regulatory frameworks, reimbursement considerations, distribution channels, occupational health requirements, and commercialization pathways supporting drug screening adoption. Evaluated customer purchasing behavior, implementation challenges, service delivery models, and expansion opportunities across developed and emerging markets.
Frequently Asked Questions About This Report
Key factors that are driving the market growth include rising substance abuse, stringent regulations, government funding, technological advancements, and increasing demand for substance testing across sectors like healthcare and sports, driven by the need for effective substance abuse detection and management.
Some key players operating in the drug screening market include Abbott; Quest Diagnostics Incorporated; F. Hoffmann-La Roche Ltd; Thermo Fisher Scientific Inc.; Siemens Healthcare AG; Laboratory Corporation of America Holdings; Alfa Scientific Designs, Inc.; OraSure Technologies, Inc.; Omega Laboratories, Inc.; Drägerwerk AG & Co. KGaA; Bio-Rad Laboratories, Inc.
The drug screening industry in the Asia Pacific is anticipated to witness the fastest growth over the forecast period. The presence of a large target population, high unmet clinical needs, and developing healthcare systems are anticipated to drive high growth potential for the industry in the region.
Based on product, consumables segment dominated the drug screening market, accounting for the largest revenue share of 34.8% in 2025.
Based on sample type, urine sample segment held the largest share of the drug screening market, accounting for 41.5% in 2025.
The increasing demand for convenient and rapid drug screening solutions is creating significant opportunities for manufacturers and service providers to expand decentralized testing capabilities.
The global drug screening market size was estimated at USD 11.1 billion in 2025 and is expected to reach USD 11.8 billion in 2026.
The global drug screening market is expected to grow at a compound annual growth rate of 7.1% from 2026 to 2033 to reach USD 19.1 billion by 2033.
North America dominated the drug screening market with a share of 38.6% in 2025. The region's high consumption of illegal substances and the necessity for workplace drug tests significantly contributed to its market share.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


