
- Home
- »
- Advanced Interior Materials
- »
-
Edge Banding Materials Market Size Report, 2026-2035GVR Report cover

Edge Banding Materials Market (2026 - 2035)
Size, Share & Trends Analysis Report By Material Type (PVC, ABS, Melamine, Melamine, Others), By End Use Industry (Residential, Commercial, Industrial, Others), By Region, And Segment Forecasts
Market Size, 2025
$1.9BMarket Estimate, 2026
$1.9BMarket Forecast, 2035
$3.1BCAGR, 2026–2035
5.5%Edge Banding Materials Market Summary
The global edge banding materials market size was valued at USD 1.9 billion in 2025 and is projected to grow from USD 1.9 billion in 2026 to USD 3.1 billion by 2035, at a CAGR of 5.5% from 2026 to 2035. Asia Pacific dominated the market, accounting for the largest revenue share in 2025. The market is witnessing steady growth, driven by increasing demand for modular furniture, rising residential and commercial construction activities, and expanding interior design and home renovation projects.
Key Market Trends & Insights
- By material type: The PVC (Polyvinyl Chloride) segment held the largest market share in 2025.
- By end use: The residential segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2035)
Market Size & Forecast
- Market size in 2025: USD 1.9 Billion
- Estimated market size in 2026: USD 1.9 Billion
- Projected market size by 2035: USD 3.1 Billion
- CAGR (2026-2035): 5.5%
Prism AI by Grand View Research Free to tryAsk a question about the edge banding materials marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Growing adoption of durable, aesthetically appealing, and sustainable edge banding materials, increasing use of engineered wood panels, and advancements in furniture manufacturing technologies are further supporting market expansion worldwide. The edge banding materials market is experiencing steady growth, fueled by the rising demand for modular furniture, customized interiors, and high-quality wood-based products across residential and commercial sectors. Rapid urbanization, increasing disposable incomes, and growing investments in housing and office infrastructure are encouraging the adoption of edge banding materials that improve the durability, appearance, and moisture resistance of furniture. In addition, the expansion of the ready-to-assemble (RTA) furniture market and increasing use of engineered wood panels are creating sustained demand for advanced edge banding solutions.
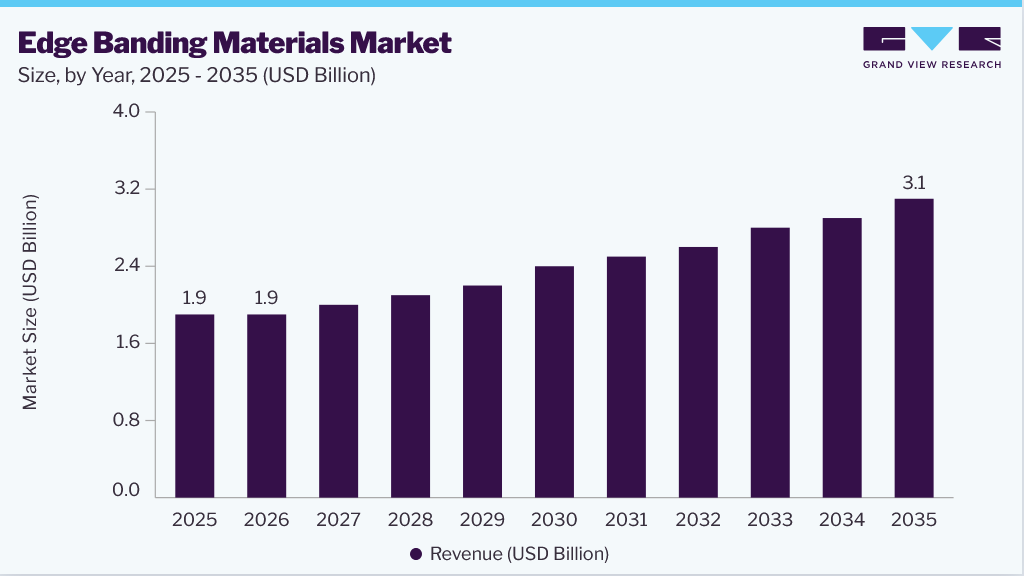 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Despite favorable market conditions, the industry faces challenges related to fluctuations in raw material prices, particularly for petroleum-based plastics such as PVC and ABS. Growing environmental concerns over plastic waste and increasingly stringent regulations on the use of non-recyclable materials are also encouraging manufacturers to rethink conventional product offerings. These factors can increase production costs and create pricing pressure, especially for manufacturers serving cost-sensitive markets.
The market presents significant opportunities as demand for sustainable and eco-friendly furniture materials continues to grow worldwide. Manufacturers are investing in recyclable, low-emission, and bio-based edge banding materials to meet evolving environmental standards and consumer preferences. Meanwhile, technological advancements in laser edge banding, digital printing, and seamless bonding techniques are enabling furniture manufacturers to deliver premium-quality products with improved aesthetics and durability. The continued growth of e-commerce furniture sales and commercial renovation projects is expected to support long-term market expansion.
Analyst Perspective
The edge banding materials market is growing alongside the expanding furniture and interior design industries, driven by demand for quality, durability, and visual appeal. Rising demand for modular furniture, customized living spaces, and sustainable building materials is encouraging manufacturers to develop high-performance edge banding solutions with improved aesthetics and longer service life. While raw material price volatility and environmental regulations remain notable challenges, ongoing innovation in recyclable materials, laser edge banding technology, and low-emission manufacturing processes is expected to create new growth opportunities. Companies that prioritize sustainability and product innovation are likely to strengthen their competitive position over the forecast period.
Material Type Insights
The PVC (Polyvinyl Chloride) segment held the largest market share in 2025. The segment's dominance is attributed to its excellent durability, flexibility, moisture resistance, and cost-effectiveness, making it the preferred material for furniture, cabinetry, and other wood-based applications. PVC edge banding is available in a wide range of colors, textures, and finishes, allowing manufacturers to achieve attractive aesthetics while providing effective edge protection against wear, impact, and moisture. Its compatibility with automated edge banding equipment, ease of processing, and long service life further support its widespread adoption in both residential and commercial furniture manufacturing. Its affordability and consistent performance continue to strengthen its position as the leading material in the market.
The ABS (Acrylonitrile Butadiene Styrene) segment is expected to register the fastest CAGR during the forecast period. The segment is gaining significant traction due to the growing preference for environment-friendly and recyclable materials in furniture manufacturing. Unlike PVC, ABS is chlorine-free, making it a more sustainable option while offering excellent impact resistance, dimensional stability, and surface quality. Rising environmental regulations, increasing consumer awareness of sustainable products, and the growing demand for premium modular furniture are accelerating its adoption. Furthermore, continuous advancements in manufacturing technologies and surface finishing techniques are improving the performance, design flexibility, and application range of ABS edge banding materials, making them increasingly attractive for modern residential and commercial furniture applications.
End Use Insights
The residential segment held the largest market share in 2025, driven by the growing demand for modular kitchens, wardrobes, living room furniture, and other ready-to-assemble home furnishing products. Rapid urbanization, rising disposable incomes, and increasing investments in residential construction and home renovation projects have significantly boosted the demand for edge banding materials. Consumers are increasingly seeking aesthetically appealing, durable, and moisture-resistant furniture, encouraging manufacturers to adopt high-quality edge banding solutions. The expansion of the e-commerce furniture industry and growing preference for customized interior designs continue to support the widespread use of edge banding materials in residential applications.
The commercial segment is expected to register the fastest CAGR during the forecast period. Growth of this segment is driven by rising investments in office buildings, hotels, educational institutions, healthcare facilities, retail outlets, and hospitality infrastructure. The increasing demand for premium interior spaces and durable furniture in commercial environments is accelerating the adoption of high-performance edge banding materials. Businesses are also emphasizing modern aesthetics, sustainability, and long-lasting furniture solutions, creating opportunities for advanced edge banding products. Furthermore, the expansion of commercial real estate projects and workplace modernization initiatives across developing and developed economies is expected to drive sustained demand throughout the forecast period.
Regional Insights
The Asia Pacific region held the largest market share in 2025. The region's dominance is driven by its well-established furniture manufacturing industry, rapid urbanization, and increasing residential and commercial construction activities. Countries such as China, India, Vietnam, and Japan serve as major manufacturing hubs for furniture and wood-based products, creating strong demand for edge banding materials. Rising disposable incomes, expanding middle-class populations, and growing investments in home renovation and interior decoration are further supporting market growth. In addition, the presence of leading furniture manufacturers, readily available raw materials, and cost-effective production capabilities continue to strengthen the region's position in the global market. In March 2025, SURTECO, through its China subsidiary, participated in CIFM/interzum Guangzhou 2025, showcasing its latest decorative surface materials and edge banding solutions for the furniture manufacturing industry. The participation underscores the company's ongoing commitment to strengthening its presence across the Asia Pacific region and supporting the region's expanding furniture and interior manufacturing sector.
North America Edge Banding Materials Market Trends
The North America region is expected to register the fastest CAGR during the forecast period, supported by increasing demand for premium and customized furniture, rising home remodeling activities, and strong investments in commercial infrastructure. Consumers are increasingly favoring high-quality, durable, and environmentally sustainable furniture, encouraging manufacturers to adopt advanced edge banding materials such as recyclable ABS and low-emission products. Furthermore, the growing popularity of modular furniture, expansion of the e-commerce furniture market, and continuous technological advancements in automated furniture manufacturing are expected to drive demand. Supportive sustainability initiatives and increasing adoption of innovative edge finishing technologies are also contributing to the region's long-term market growth.
Key Edge Banding Materials Market Company Insights
The edge banding materials market is highly competitive, with global and regional manufacturers focusing on product innovation, sustainable material development, and capacity expansion to strengthen their market positions. Leading companies are investing in recyclable edge banding materials, advanced surface technologies, automated manufacturing processes, and strategic partnerships to meet the growing demand from the furniture and interior design industries. Continuous innovation in aesthetics, durability, and environmentally friendly solutions remains a key competitive differentiator across the market.
Key Edge Banding Materials Companies
The following key companies have been profiled for this study on the edge banding materials market
-
REHAU Industries SE & Co. KG
-
SURTECO GmbH
-
FRITZ EGGER GmbH & Co. OG
-
Wilsonart LLC
-
Teknaform Inc.
-
Moderne Kunststoff-Technik GmbH & Co. KG
-
Dongguan Huali Industry Co., Ltd.
-
Dura Edge, Inc.
Recent Developments
-
In October 2025, REHAU Industries SE & Co. KG showcased its latest RAUKANTEX edgeband innovations at SICAM 2025 under the theme "Attention to every detail." The company highlighted advancements including RAUKANTEX pigmento, RAUKANTEX canvas, and RAUKANTEX eco, alongside its ReTurn edge band take-back concept, with a strong emphasis on sustainability, design integration, and processing-friendly solutions for the furniture industry. The showcase reinforced REHAU's commitment to expanding its portfolio of premium, design-matched, and circular economy-focused edge banding solutions.
-
In April 2025, REHAU Industries SE & Co. KG announced its participation at interzum 2025 under the theme Beauty for All Shapes and Forms. The company revealed plans to showcase its RAUKANTEX edgeband portfolio alongside decorative surfaces and furniture component solutions, highlighting design-matched products, sustainable material concepts, and integrated solutions for modern furniture manufacturing. The showcase underscored REHAU's continued focus on innovation, premium design, and sustainability within the edge banding materials market.
Edge Banding Materials Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.9 Billion
Estimated market size in 2026
USD 1.9 Billion
Projected market size by 2035
USD 3.1 Billion
Growth rate
CAGR of 5.5% from 2026 to 2035
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2035
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2035
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material type, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; China; Japan; India; Australia; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
REHAU Industries SE & Co. KG; SURTECO GmbH; FRITZ EGGER GmbH & Co. OG; Wilsonart LLC; Teknaform Inc.; Moderne Kunststoff-Technik GmbH & Co. KG; Dongguan Huali Industry Co., Ltd.; Dura Edge, Inc.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Edge Banding Materials Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2035. For this study, Grand View Research has segmented the global Edge Banding Materials market report based on material type, end use, and region:
-
Material Type Outlook (Revenue, USD Billion, 2021 - 2035)
-
PVC (Polyvinyl Chloride)
-
ABS (Acrylonitrile Butadiene Styrene)
-
Melamine
-
Wood Veneer
-
Others
-
-
End Use Industry Outlook (Revenue, USD Billion, 2021 - 2035)
-
Residential
-
Commercial
-
Industrial
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2035)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
The global edge banding materials market size was valued at USD 1.9 billion in 2025 and is estimated at USD 1.9 billion for 2026.
The PVC (Polyvinyl Chloride) segment accounted for the largest revenue share in 2025.
Asia Pacific regional market dominated with the largest revenue share in 2025.
Key players in the market include REHAU Industries SE & Co. KG; SURTECO GmbH; FRITZ EGGER GmbH & Co. OG; Wilsonart LLC; Teknaform Inc.; Moderne Kunststoff-Technik GmbH & Co. KG; Dongguan Huali Industry Co., Ltd.; and Dura Edge, Inc.
The global edge banding materials market is expected to grow at a CAGR of 5.5% from 2026 to 2035, reaching USD 3.1 billion.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


