
- Home
- »
- Power Distribution
- »
-
Electrical Insulator Market Size & Share Report, 2026-2033GVR Report cover

Electrical Insulator Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Ceramic, Glass, Composite), By Application (Transformer, Cable, Busbars, Switchgear), By Voltage, By Region, And Segment Forecasts
Market Size, 2025
$14.0BMarket Estimate, 2026
$14.7BMarket Forecast, 2033
$21.7BCAGR, 2026–2033
5.7%Electrical Insulator Market Summary
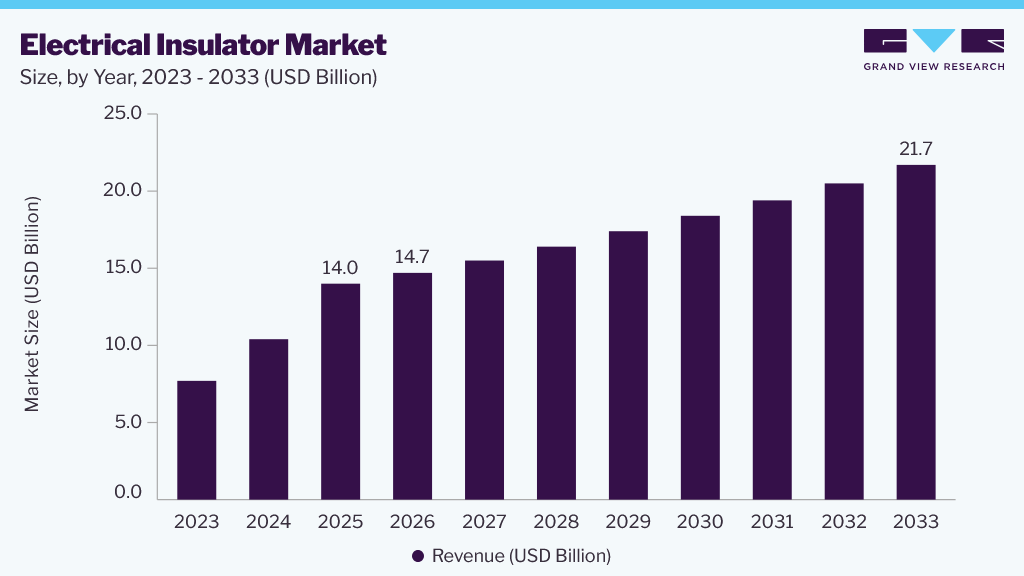
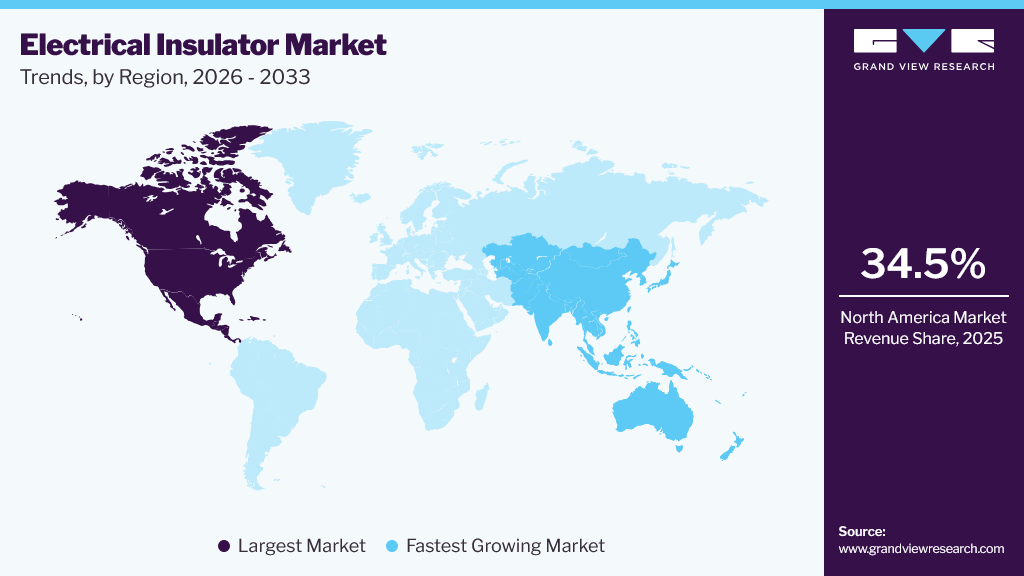
The global electrical insulator market size was valued at USD 14.0 billion in 2025 and is projected to grow from USD 14.7 billion in 2026 to USD 21.7 billion by 2033, at a CAGR of 5.7% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 34.5% in 2025. Rapid modernization of power transmission and distribution infrastructure, coupled with the expansion of renewable energy networks, continues to increase the requirement for reliable insulation systems capable of supporting higher operating voltages and long-term grid performance. As utilities upgrade aging electrical infrastructure and expand grid connectivity, demand for advanced electrical insulators is expected to remain strong.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: The ceramic insulator segment dominated the market and accounted for a share of around 40.0% in 2025.
- By application: The cable segment dominated the market and accounted for a share of over 32.5% in 2025.
- By voltage: The low voltage segment dominated the market and accounted for a share of more than 40.5% in 2025.
Regional Highlights
- Largest regional market: North America (34.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 14.0 Billion
- Estimated market size in 2026: USD 14.7 Billion
- Projected market size by 2033: USD 21.7 Billion
- CAGR (2026-2033): 5.7%
Prism AI by Grand View Research Free to tryAsk a question about the electrical insulator marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Composite insulators are increasingly replacing conventional ceramic alternatives in transmission and distribution networks because they offer lower weight, superior resistance to contamination, and reduced maintenance requirements. Their ability to withstand harsh environmental conditions, including coastal pollution, industrial contamination, and extreme weather, makes them suitable for high-voltage transmission lines, substations, and renewable energy installations.
Continuous investment in grid expansion, cross-border transmission projects, and smart grid modernization is creating sustained opportunities for high-performance insulation materials. The increasing adoption of ultra-high-voltage (UHV) transmission systems, offshore wind infrastructure, and grid resilience initiatives is encouraging manufacturers to develop insulators with improved mechanical strength, weather resistance, and longer service life, thereby supporting technological advancement across the electrical infrastructure sector.
Analyst Perspective
The electrical insulator market is entering a phase of steady technological advancement, driven by the modernization of power infrastructure and the growing integration of renewable energy into transmission networks. Utilities are increasingly prioritizing insulators that offer superior mechanical strength, long service life, and reliable performance under harsh environmental conditions to improve grid reliability and reduce maintenance costs. The transition toward high-voltage and ultra-high-voltage transmission systems is also driving demand for advanced composite insulation materials capable of supporting higher electrical loads and withstanding challenging operating conditions.
Type Insights
By type, the ceramic insulator segment held the largest market share, accounting for a share of around 40.0% in 2025. Ceramic insulators continue to be widely used across transmission and distribution networks due to their proven long-term reliability, excellent dielectric strength, and ability to withstand high mechanical loads under demanding operating conditions. Their extensive deployment in overhead transmission lines, substations, and utility infrastructure has established a large installed base, particularly in conventional power grids. In addition, ceramic insulators offer stable electrical performance over long service periods, making them a preferred choice for utilities undertaking grid expansion and refurbishment projects where durability and operational reliability remain critical.
The composite insulator segment is expected to register the fastest CAGR during the forecast period. Utilities are increasingly adopting composite insulators because of their lightweight construction, hydrophobic surface properties, and superior resistance to pollution, moisture, ultraviolet radiation, and harsh weather conditions. These advantages reduce maintenance requirements, simplify installation, and improve the reliability of power transmission systems, particularly in coastal, industrial, and high-contamination environments. For instance, in June 2025, Ensto launched its Composite Line Post Insulators for 24 kV overhead distribution networks. These products are designed to replace traditional porcelain insulators by offering lower weight, higher mechanical strength, and improved resistance to pollution and severe weather conditions. The growing modernization of transmission infrastructure and increasing investments in renewable energy integration are expected to further accelerate the adoption of composite insulators.
Application Insights
By application, the cable segment accounted for over 32.5% of the market in 2025. Extensive expansion of transmission and distribution networks, together with continuous investments in underground and overhead power infrastructure, has sustained strong demand for electrical insulators used in cable systems. Insulators are essential for preventing current leakage, maintaining electrical isolation, and ensuring the safe and reliable operation of power cables under varying voltage conditions. The increasing deployment of high-voltage and extra-high-voltage cable networks, coupled with the modernization of aging grid infrastructure, continues to drive the widespread adoption of electrical insulators in cable applications across utility, industrial, and infrastructure projects.
The transformer segment is expected to register the fastest CAGR during the forecast period. Growing investments in grid modernization, renewable energy integration, and power transmission capacity are increasing demand for advanced transformer insulation systems capable of operating under higher electrical loads and varying operating conditions. Reliable insulation is critical for improving transformer efficiency, extending equipment life, and minimizing operational failures in modern power networks. For instance, in February 2025, Eaton announced a USD 340 million investment to establish a new transformer manufacturing facility in South Carolina. The investment is intended to expand production capacity for power transformers supporting grid modernization, electrification, and data center infrastructure. Rising deployment of transmission transformers worldwide is expected to further accelerate demand for electrical insulation components.
Voltage Insights
By voltage, the low-voltage segment accounted for more than 40.5% of the market in 2025. Extensive deployment of low-voltage electrical networks across residential buildings, commercial facilities, and light industrial applications continues to sustain demand for low-voltage insulators. These insulators are widely used in distribution equipment, service connections, switchboards, and low-voltage power systems, where reliable electrical isolation is essential for safe and uninterrupted power delivery. Rapid urban development, expanding residential construction, and continuous installation of low-voltage distribution infrastructure are expected to maintain the segment's leading position in the industry.
The medium-voltage segment is expected to register the fastest CAGR during the forecast period. Increasing investments in distribution network modernization, industrial electrification, renewable energy integration, and urban grid expansion are driving demand for medium-voltage insulation systems. Medium-voltage insulators are extensively used in distribution lines, substations, switchgear, and industrial power networks to ensure reliable operation under higher electrical loads. For instance, in November 2024, Sterlite Power announced multiple medium-, high- and extra-high-voltage power cable projects for utility and infrastructure customers. The projects reflect continued investment in strengthening power transmission and distribution networks, supporting demand for electrical insulation solutions used across medium-voltage applications.
Regional Insights
North America's electrical insulator market held the largest share, at approximately 34.5% in 2025, driven by an extensive transmission and distribution network that requires continuous replacement and upgrading of aging electrical infrastructure. Utilities are increasingly deploying advanced insulation solutions to improve equipment reliability under higher operating loads and diverse climatic conditions. Growing investments in transmission expansion, substation modernization, and grid resilience projects are further supporting the adoption of high-performance insulators across utility and industrial applications. In addition, increasing electrification of transportation, industrial facilities, and data centers is creating sustained demand for reliable power infrastructure, reinforcing the need for durable electrical insulation systems throughout the region.
 To learn more about this report, Download Free Sample Report
U.S. Electrical Insulator Market Trends
The U.S. represented the largest share of the North American market in 2025. Ongoing expansion of domestic electrical equipment manufacturing and continued investment in power infrastructure are supporting demand for electrical insulators across transmission, distribution, and substation applications. Modernization of utility assets, together with increasing deployment of medium- and high-voltage equipment, is encouraging manufacturers to adopt advanced insulation technologies that improve operational reliability and service life. For instance, in March 2025, Schneider Electric announced plans to invest more than USD 700 million across its U.S. operations through 2027 to expand manufacturing capacity and strengthen the country's energy infrastructure. The expansion is expected to support the growing production of electrical equipment used across modern power networks, creating additional demand for electrical insulation components.
Asia Pacific Electrical Insulator Market Trends
The Asia Pacific electrical insulator market is expected to grow at the fastest CAGR during the forecast period, driven by the burgeoning population and the need for a more reliable electricity supply. To meet rising electricity demand, manufacturers are expanding their facilities and operations. For instance, in February 2025, Schneider Electric Infrastructure approved the expansion of its medium power transformer manufacturing capacity at its Vadodara facility in India by 1,500 MVA per year. The investment was made to meet growing market demand for transformers, supporting higher consumption of electrical insulators used in transformer manufacturing.
Europe Electrical Insulator Market Trends
The Europe electrical insulator market is experiencing significant growth as the emphasis on renewable energy integration and the electrification of transportation systems boost demand for advanced insulators. The region's automotive sector, transitioning towards electric vehicles, requires robust insulators to support efficient charging infrastructure and grid stability.
Key Electrical Insulator Company Insights
The electrical insulator market is characterized by established global manufacturers competing through product innovation, manufacturing expansion, and strategic partnerships. Companies are investing in advanced composite insulation technologies, expanding production capacity, and strengthening regional supply chains to address growing demand from transmission, distribution, and renewable energy infrastructure projects.
Key Electrical Insulator Companies
The following key companies have been profiled for this study on the electrical insulator market:
-
ABB Ltd.
-
GE Vernova Inc.
-
Siemens AG
-
Bharat Heavy Electricals Limited
-
Toshiba Corporation
-
LAPP Insulators GmbH
-
MacLean-Fogg Company
-
NGK INSULATORS, LTD.
-
Hubbell Incorporated
-
Seves Group S.à r.l.
-
TE Connectivity plc
-
Grasim Industries Limited
Recent Developments
-
In August 2025, Hitachi Energy India announced the expansion of its Mysuru manufacturing facility to increase production capacity for high-voltage laminated board and pressboard used in power and distribution transformers. The investment supports the growing demand for transformer insulation materials across the electricity transmission infrastructure.
-
In April 2025, PFISTERER Holding SE acquired Power CSL, a UK-based specialist in subsea cable connection systems. The acquisition expands PFISTERER's portfolio of subsea cable joints, connection systems, and fiber-optic technologies for offshore electricity transmission applications.
-
In December 2024, PFISTERER expanded its collaboration with Nippon Katan Co., Ltd. through a cooperation and licensing agreement for the production and commercialization of composite insulators for overhead power transmission lines in Japan.
Electrical Insulator Market Report Scope
Report Attribute
Details
Market size in 2025
USD 14.0 billion
Estimated Market size in 2026
USD 14.7 billion
Projected Market size by 2033
USD 21.7 billion
Growth rate
CAGR of 5.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, voltage, application, region
Regional Scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand; South Korea; Brazil; Argentina; South Africa; UAE
Key companies profiled
ABB Ltd.; GE Vernova Inc.; Siemens AG; Bharat Heavy Electricals Limited; Toshiba Corporation; LAPP Insulators GmbH; MacLean-Fogg Company; NGK INSULATORS, LTD.; Hubbell Incorporated; Seves Group S.à r.l.; TE Connectivity plc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Electrical Insulator Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each sub segment from 2021 to 2033. For this study, Grand View Research has segmented global electrical insulator market report on the basis of type, voltage, application, and region.
- Type Outlook (Revenue, USD Billion; 2021 - 2033)
- Ceramic Insulator
- Composite Insulator
- Glass Insulator
- Voltage Outlook (Revenue, USD Billion; 2021 - 2033)
- Low
- Medium
- High
- Application Outlook (Revenue, USD Billion; 2021 - 2033)
- Cable
- Transformer
- Switchgear
- Busbars
- Others
- Regional Outlook (Revenue, USD Billion; 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- UK
- Spain
- France
- Italy
- Asia Pacific
- China
- India
- Japan
- South Korea
- Central & South America
- Brazil
- Argentina
- Middle East & Africa
- Saudi Arabia
- UAE
- South Africa
- North America
Frequently Asked Questions About This Report
The global electrical insulator market size was valued at USD 14.0 billion in 2025 and is estimated at USD 14.7 billion for 2026.
The ceramic insulator segment accounted for the largest revenue share of around 40.0% in 2025.
The global electrical insulator market is expected to grow at a CAGR of 5.7% from 2026 to 2033, reaching USD 21.7 billion.
North America dominated with an approximately 34.5% revenue share in 2025.
Key players in the market include ABB Ltd., GE Vernova Inc., Siemens AG, Bharat Heavy Electricals Limited, Toshiba Corporation, LAPP Insulators GmbH, MacLean-Fogg Company, NGK INSULATORS, LTD., Hubbell Incorporated, Seves Group S.à r.l., and TE Connectivity plc. and others.
About the Author(s)
Power Distribution Research Team
Energy & Power · Power DistributionThis report was authored by the power distribution research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the power distribution segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


