
- Home
- »
- Medical Devices
- »
-
Electronic Drug Delivery Systems Market Size Report, 2033GVR Report cover

Electronic Drug Delivery Systems Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Auto Injectors), By Application (Cardiovascular Disease), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies), By Region, And Segment Forecasts
Market Size, 2025
$13.0BMarket Estimate, 2026
$14.2BMarket Forecast, 2033
$26.5BCAGR, 2026–2033
9.3%Electronic Drug Delivery Systems Market Summary
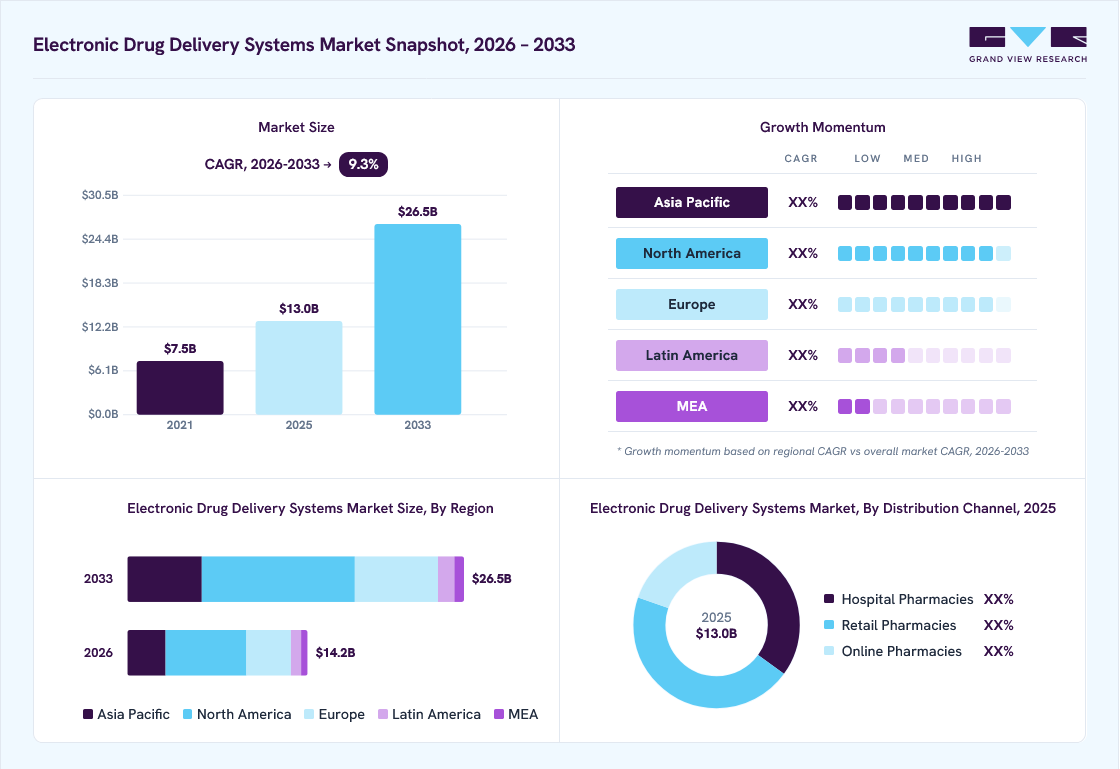
The global electronic drug delivery systems market size was valued at USD 13.0 billion in 2025 and is projected to grow from USD 14.2 billion in 2026 to USD 26.5 billion by 2033, at a CAGR of 9.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 44.8% in 2025. The major factors driving the market include the increasing prevalence of chronic diseases, such as cardiovascular diseases (CVDs), asthma, and diabetes, and technological advancements in the development of smart drug delivery systems.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Wearable infusion pumps segment led the market with the largest revenue share of 41.3% in 2025.
- By application: Diabetes segment led the market with the largest revenue share of 36.5% in 2025.
- By distribution channel: Retail pharmacies segment led the market with the largest revenue share of 45.3% in 2025.
Regional Highlights
- Largest regional market: North America (44.8% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 13.0 Billion
- Estimated market size in 2026: USD 14.2 Billion
- Projected market size by 2033: USD 26.5 Billion
- CAGR (2026-2033): 9.3%
Prism AI by Grand View Research Free to tryAsk a question about the electronic drug delivery systems marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Electronic drug delivery systems are portable devices that provide patients with convenient solutions, including enhanced adherence to treatment, quick administration times, precise dosing, and simplified drug delivery. The introduction of advanced minimally invasive drug delivery systems allows patients with chronic illnesses to administer their regular doses, reducing the need for hospital visits and associated costs.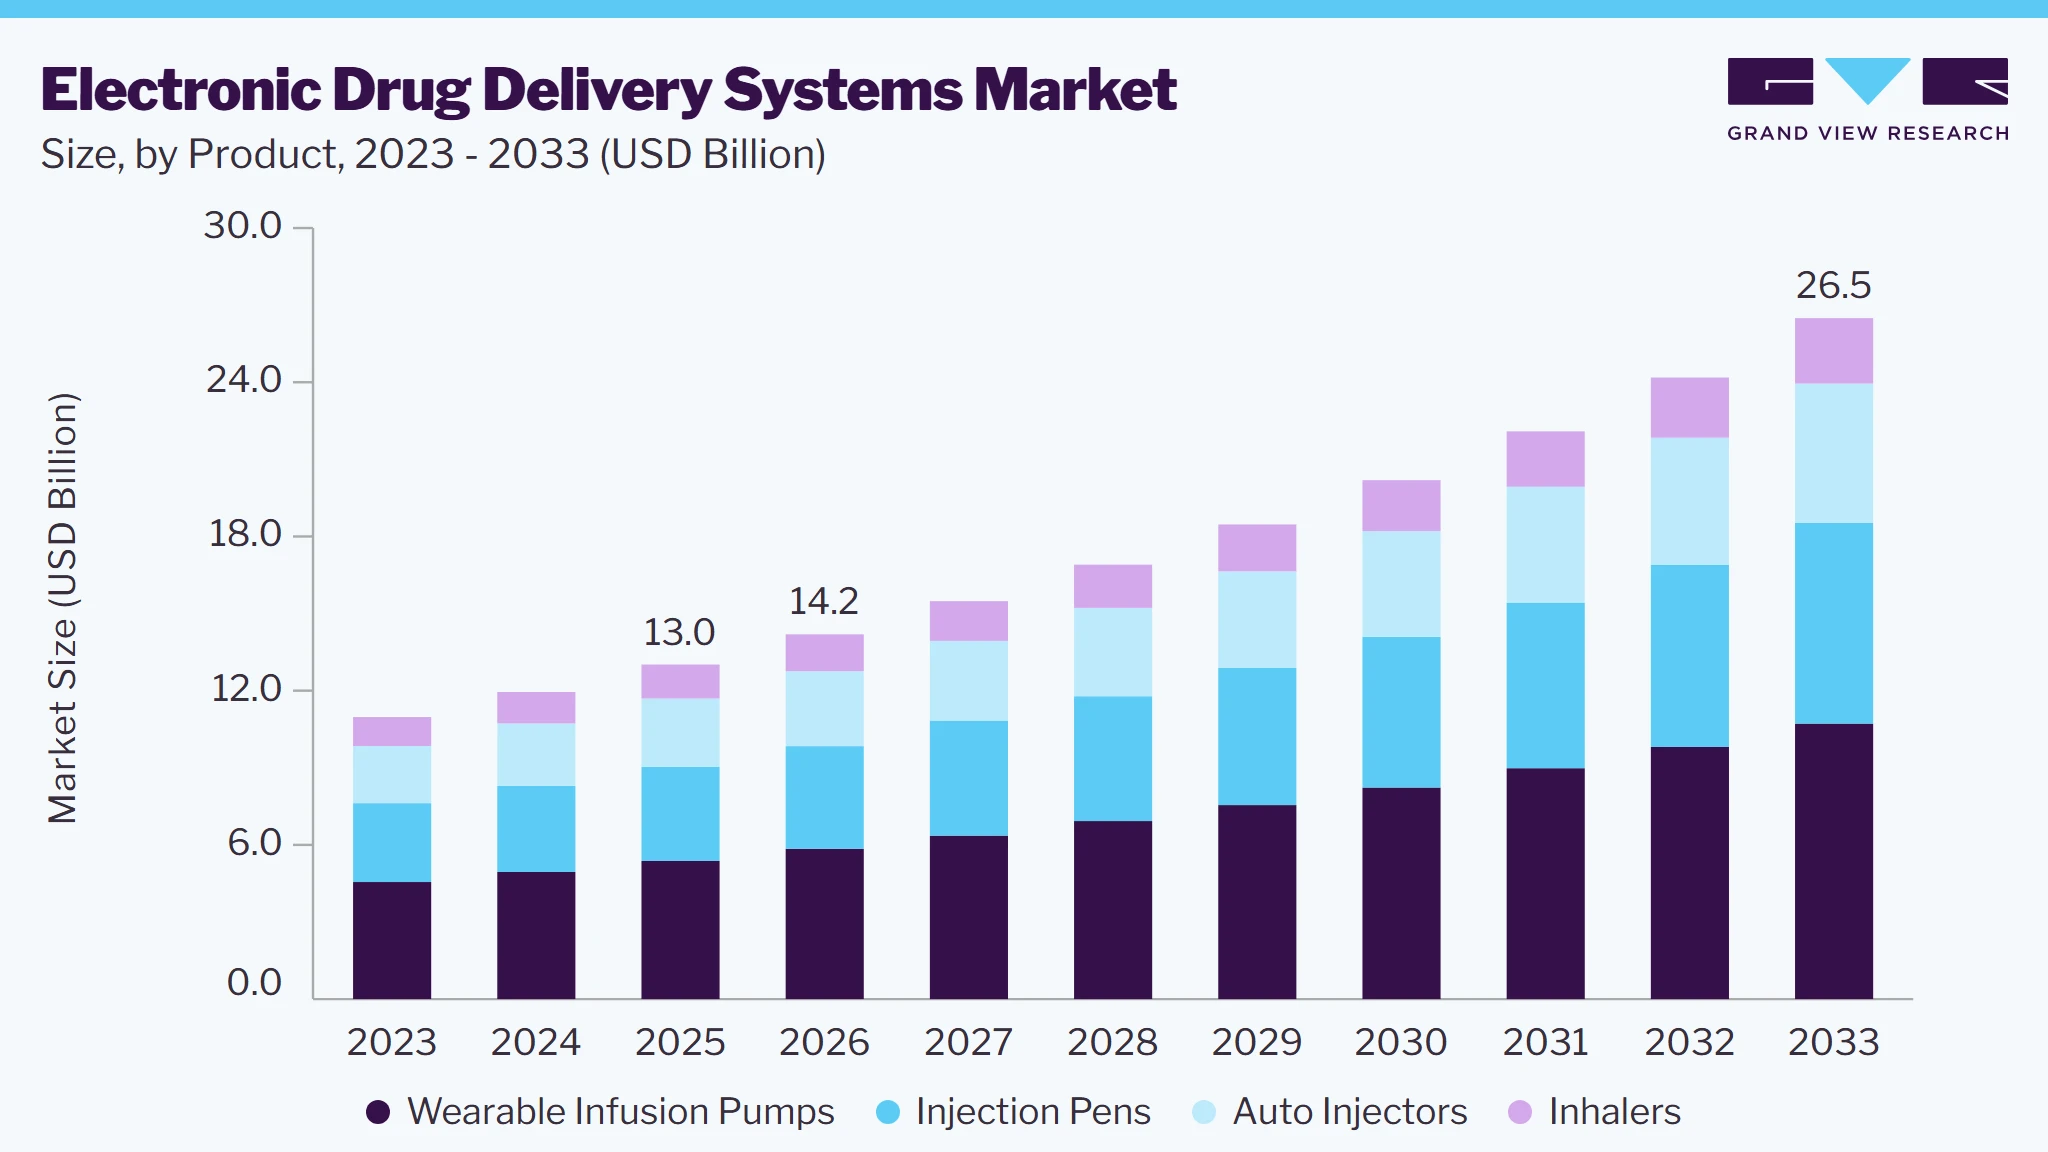 To learn more about this report, Download Free Sample Report
The rising prevalence of chronic diseases such as cardiovascular diseases, asthma, and diabetes drives the electronic drug delivery systems market. These conditions require efficient and precise medication management, which electronic systems facilitate. According to the World Health Organization (WHO), diabetes is a chronic metabolic disease affecting around 830 million people worldwide, with a significant burden in low- and middle-income countries. Type 2 diabetes, the most common form, is rising dramatically due to lifestyle changes, while type 1 diabetes involves little to no insulin production by the pancreas. Despite global efforts to halt its rise by 2025, over half of those affected lack access to critical treatments, including insulin, highlighting a significant healthcare gap.
The adoption of advanced minimally invasive drug delivery systems has enabled patients with chronic illnesses to self-administer regular doses with ease and accuracy. This innovation enhances patient convenience and adherence to treatment regimens, reducing dependency on healthcare facilities. Such advancements are key drivers for the growth of the electronic drug delivery systems market, addressing the demand for patient-centric solutions. For instance, in February 2024, Koninklijke Philips N.V. launched the LumiGuide system, a 3D, light-powered navigation solution designed for minimally invasive surgeries, offering radiation-free precision. It employs advanced imaging and proprietary algorithms to provide surgeons with real-time guidance, improving accuracy and reducing patient trauma. LumiGuide represents a significant leap in medical imaging, focusing on safety and efficiency, and aligns with Philips' patient-centric approach to innovation.
Market Dynamics
The electronic drug delivery systems market is experiencing significant growth as healthcare providers, pharmaceutical companies, and patients increasingly seek advanced drug administration technologies that improve treatment accuracy, medication adherence, and patient convenience. Electronic drug delivery systems utilize programmable electronics, sensors, connectivity features, and automated dosing mechanisms to precisely administer medications across a wide range of therapeutic areas, including diabetes, oncology, autoimmune diseases, cardiovascular disorders, neurological conditions, and pain management. These systems encompass electronic autoinjectors, smart infusion pumps, wearable injectors, insulin delivery devices, connected inhalers, and other digitally enabled drug delivery platforms. Growing demand for self-administration therapies, home-based healthcare, and personalized medicine is accelerating market adoption globally.
In addition, advancements in digital health technologies, wireless connectivity, artificial intelligence, remote monitoring, and cloud-based healthcare platforms are enhancing the functionality and clinical value of electronic drug delivery devices. The integration of smart sensors, dose tracking capabilities, real-time adherence monitoring, and mobile health applications enables healthcare providers to optimize treatment outcomes and improve patient engagement. Rising prevalence of chronic diseases, increasing biologics utilization, expanding telehealth infrastructure, and growing emphasis on reducing hospital visits continue to support market growth. Furthermore, pharmaceutical companies are increasingly developing drug-device combination products that leverage electronic delivery technologies to improve therapeutic effectiveness and patient experience.
The increasing adoption of connected drug delivery technologies and home-based treatment models is a major factor driving growth in the global electronic drug delivery systems market. Healthcare systems worldwide are shifting toward patient-centric care models that emphasize convenience, treatment adherence, and reduced dependence on hospital-based services. Electronic drug delivery systems enable accurate dosing, automated administration, treatment tracking, and remote monitoring, making them particularly valuable for managing chronic conditions requiring long-term therapy. The growing prevalence of diabetes, autoimmune diseases, cardiovascular disorders, and cancer is generating substantial demand for self-administered and digitally connected treatment solutions.
Advancements in wearable injectors, smart insulin delivery systems, electronic autoinjectors, and connected infusion technologies are further supporting market expansion. These devices provide real-time data sharing, medication reminders, and adherence monitoring, enabling healthcare providers to track treatment progress remotely and intervene when necessary. Increasing integration with mobile applications and telemedicine platforms is enhancing patient engagement while supporting personalized treatment strategies. As healthcare providers and payers continue to prioritize improved outcomes, reduced hospitalization rates, and cost-effective care delivery, demand for electronic drug delivery systems is expected to increase significantly across both developed and emerging healthcare markets.
One of the primary restraints limiting the growth of the electronic drug delivery systems market is the high cost associated with device development, manufacturing, and implementation. Electronic drug delivery systems incorporate sophisticated technologies including microelectronics, sensors, software platforms, wireless communication modules, batteries, and advanced drug delivery mechanisms, all of which contribute to higher product costs compared to conventional delivery devices. These elevated costs can create affordability challenges for healthcare providers, payers, and patients, particularly in developing regions and cost-sensitive healthcare environments.
In addition, electronic drug delivery products often face complex regulatory pathways due to their classification as combination products that integrate both medical devices and pharmaceutical therapies. Manufacturers must demonstrate not only drug safety and efficacy but also device reliability, software performance, cybersecurity protection, connectivity functionality, and long-term operational safety. Compliance with evolving regulatory standards can increase development timelines and commercialization expenses. Furthermore, concerns related to device malfunctions, data privacy, cybersecurity risks, and reimbursement variability may affect adoption rates. These factors continue to present challenges to widespread market penetration despite the growing clinical benefits and technological advancements associated with electronic drug delivery systems.
Analyst Perspective
The electronic drug delivery systems market is positioned for robust growth as healthcare systems increasingly prioritize precision medicine, patient-centric care, and digital health integration. Rising prevalence of chronic diseases such as diabetes, cardiovascular disorders, respiratory diseases, and autoimmune conditions is creating sustained demand for advanced drug delivery technologies that improve treatment adherence and clinical outcomes. The transition from hospital-based administration to self-injection and home-based care is accelerating the adoption of wearable infusion pumps, smart injection pens, connected inhalers, and electronic autoinjectors.
From an industry perspective, the convergence of medical devices, pharmaceuticals, connectivity technologies, and data analytics is transforming drug administration and disease management. Manufacturers are increasingly developing connected drug-device combination products that offer automated dosing, adherence monitoring, remote patient management, and real-time treatment insights. Artificial intelligence, cloud connectivity, and mobile health applications are further enhancing the value proposition of electronic drug delivery systems.
Product Insights
Based on product type, the wearable infusion pumps segment led the market with the largest revenue share of 41.3% in 2025. The growing demand for minimally invasive, user-friendly devices for managing chronic conditions such as diabetes is a key driving factor for wearable infusion pumps in the electronic drug delivery systems market. For instance, in September 2024, Embecta Corp received FDA clearance for its insulin patch pump for managing Type 1 and Type 2 diabetes. The compact, wearable device provides a minimally invasive solution for continuous insulin delivery, enhancing convenience and improving patient quality of life. This development underscores the company's commitment to advancing diabetes care through innovative drug delivery technologies.
The injection pens segment is expected to grow at the fastest CAGR of 9.9% over the forecast period. This growth can be attributed to the growing prevalence of chronic diseases such as diabetes, rheumatoid arthritis, and multiple sclerosis, requiring regular medication administration. Enhanced patient compliance and convenience due to injection pens' ease of use and precision further boost their adoption. In addition, advancements in technology, such as electronic tracking, dose adjustments, and increased awareness about self-administered therapies, are key contributors to market growth.
Application Insights
Based on application, the diabetes segment led the market with the largest revenue share of 36.5% in 2025. This can be attributed to the increasing demand for automated and precise insulin delivery systems to improve blood glucose management and reduce manual intervention. For instance, in August 2024, the FDA cleared the first device enabling automated insulin dosing for individuals with Type 2 diabetes. This system integrates continuous glucose monitoring and insulin pump technology to provide precise, automated insulin delivery tailored to patients' needs. This advancement aims to improve blood glucose management, reduce manual intervention, and enhance the quality of life for those managing Type 2 diabetes.
The respiratory diseases segment is expected to grow significantly over the forecast period. This growth can be attributed to the rising prevalence of respiratory conditions such as asthma and COPD due to urbanization and pollution. Technological advancements, such as smart inhalers and IoT-enabled devices, enhance drug delivery efficiency and patient compliance. These systems offer real-time tracking and remote monitoring capabilities, promoting better disease management. Increasing awareness and demand for personalized, user-friendly solutions further boost market growth.
Distribution Channel Insights
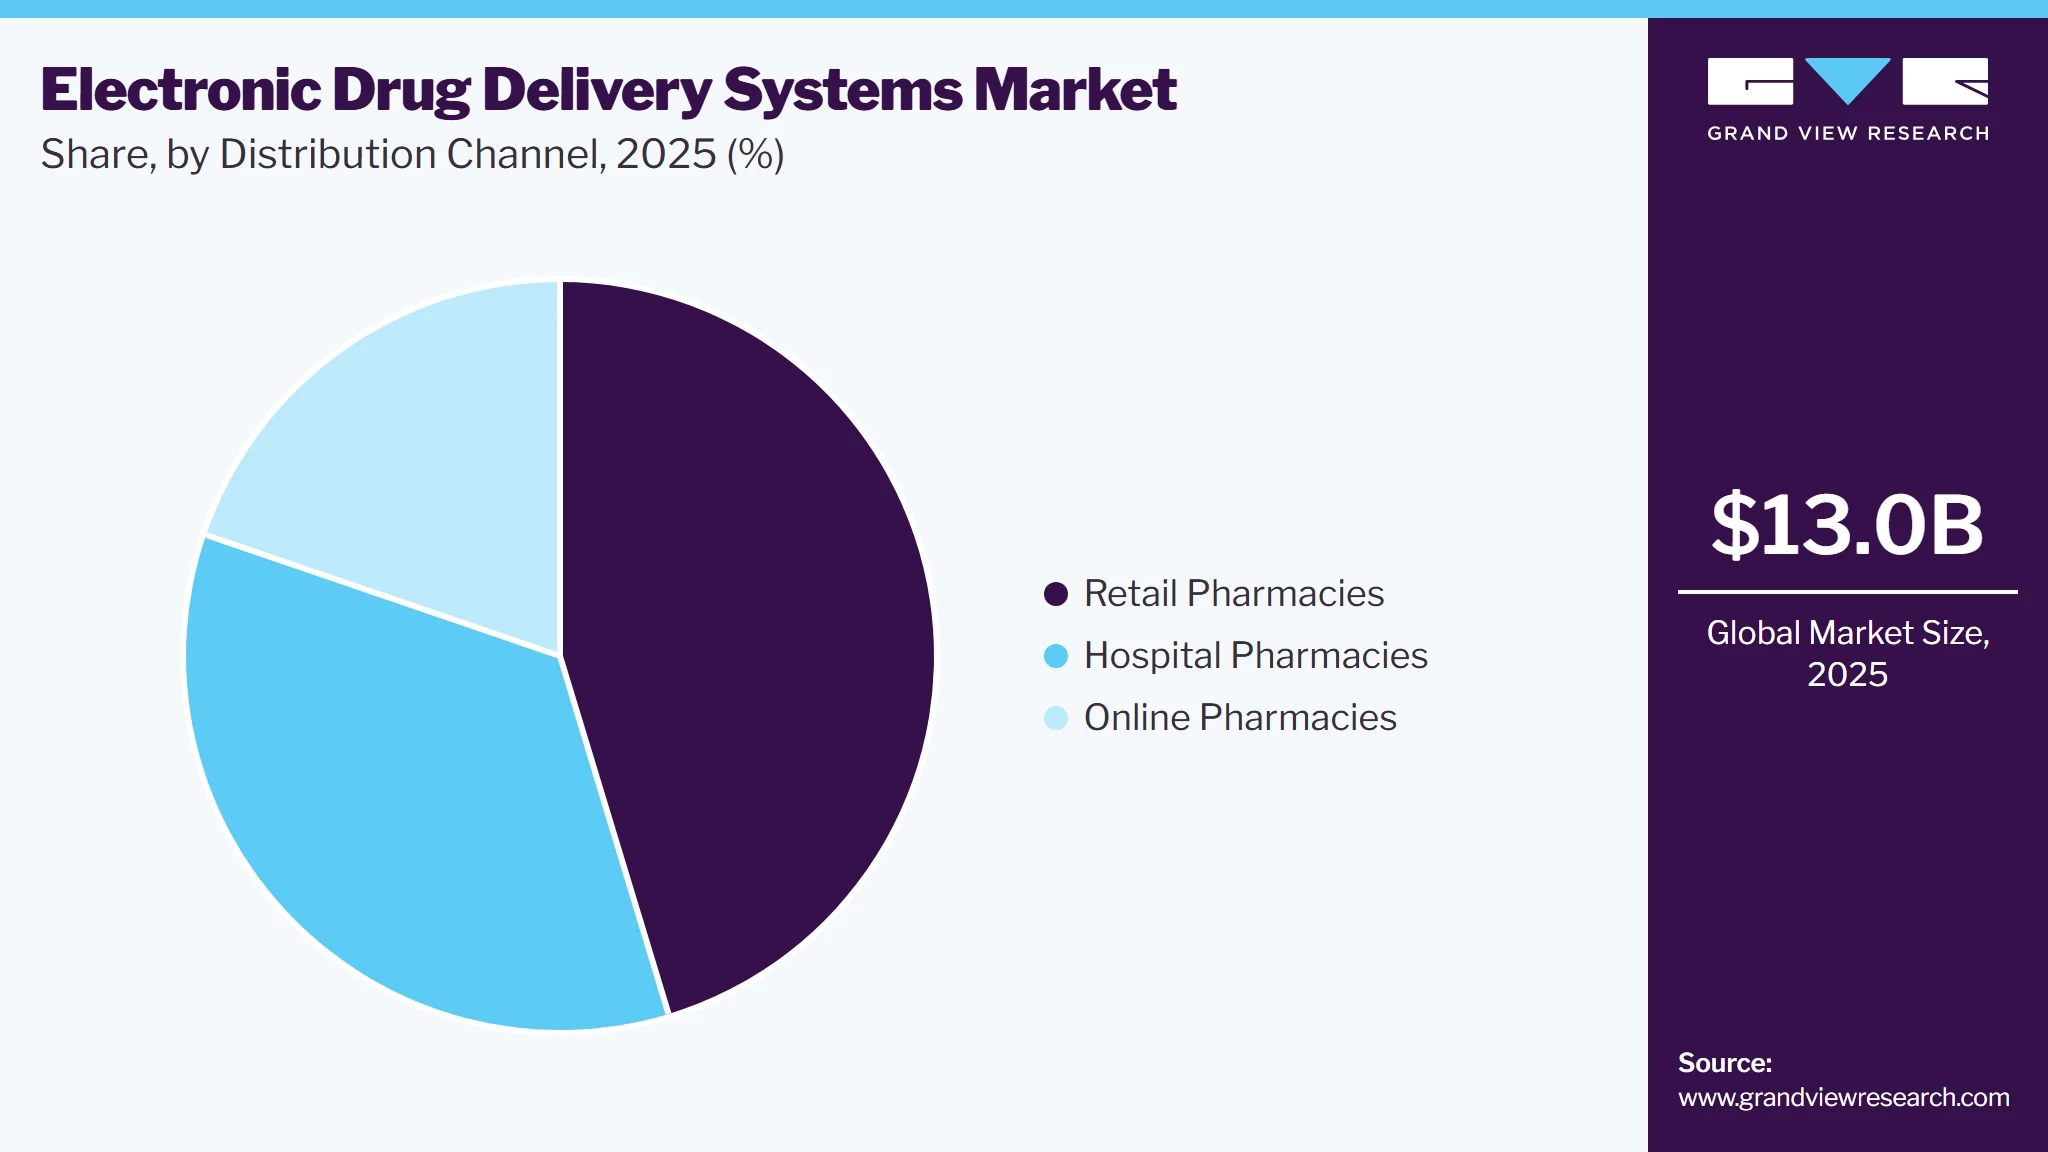
Based on distribution channel, the retail pharmacies segment led the market with the largest revenue share of 45.3% in 2025. The growing demand for convenient home delivery of prescription medications, driven by advancements in digital pharmacy services and fulfillment networks, is a key driving factor for the segment. For instance, in March 2024, Eli Lilly and Company partnered with Amazon Pharmacy (Amazon.com, Inc.) to deliver its weight-loss drug, Zepbound, and other medications for diabetes and migraines via LillyDirect, a direct-to-consumer digital pharmacy service. This collaboration was expected to enable convenient home delivery of prescribed medicines, leveraging Amazon's fulfillment network. The growing demand for weight-loss drugs, driven by their potential for significant weight reduction, is fueling the expansion of this service.
 To learn more about this report, Download Free Sample Report
The online pharmacies segment is projected to grow at the fastest CAGR of 10.6% over the forecast period. Online pharmacies are rising due to the increasing consumer demand for the convenience of home delivery, which allows easy access to medications. With lower operational costs than traditional pharmacies, online platforms can offer more affordable pricing. This cost efficiency, combined with convenience, is attracting more consumers to opt for online pharmacy services.
Regional Insights
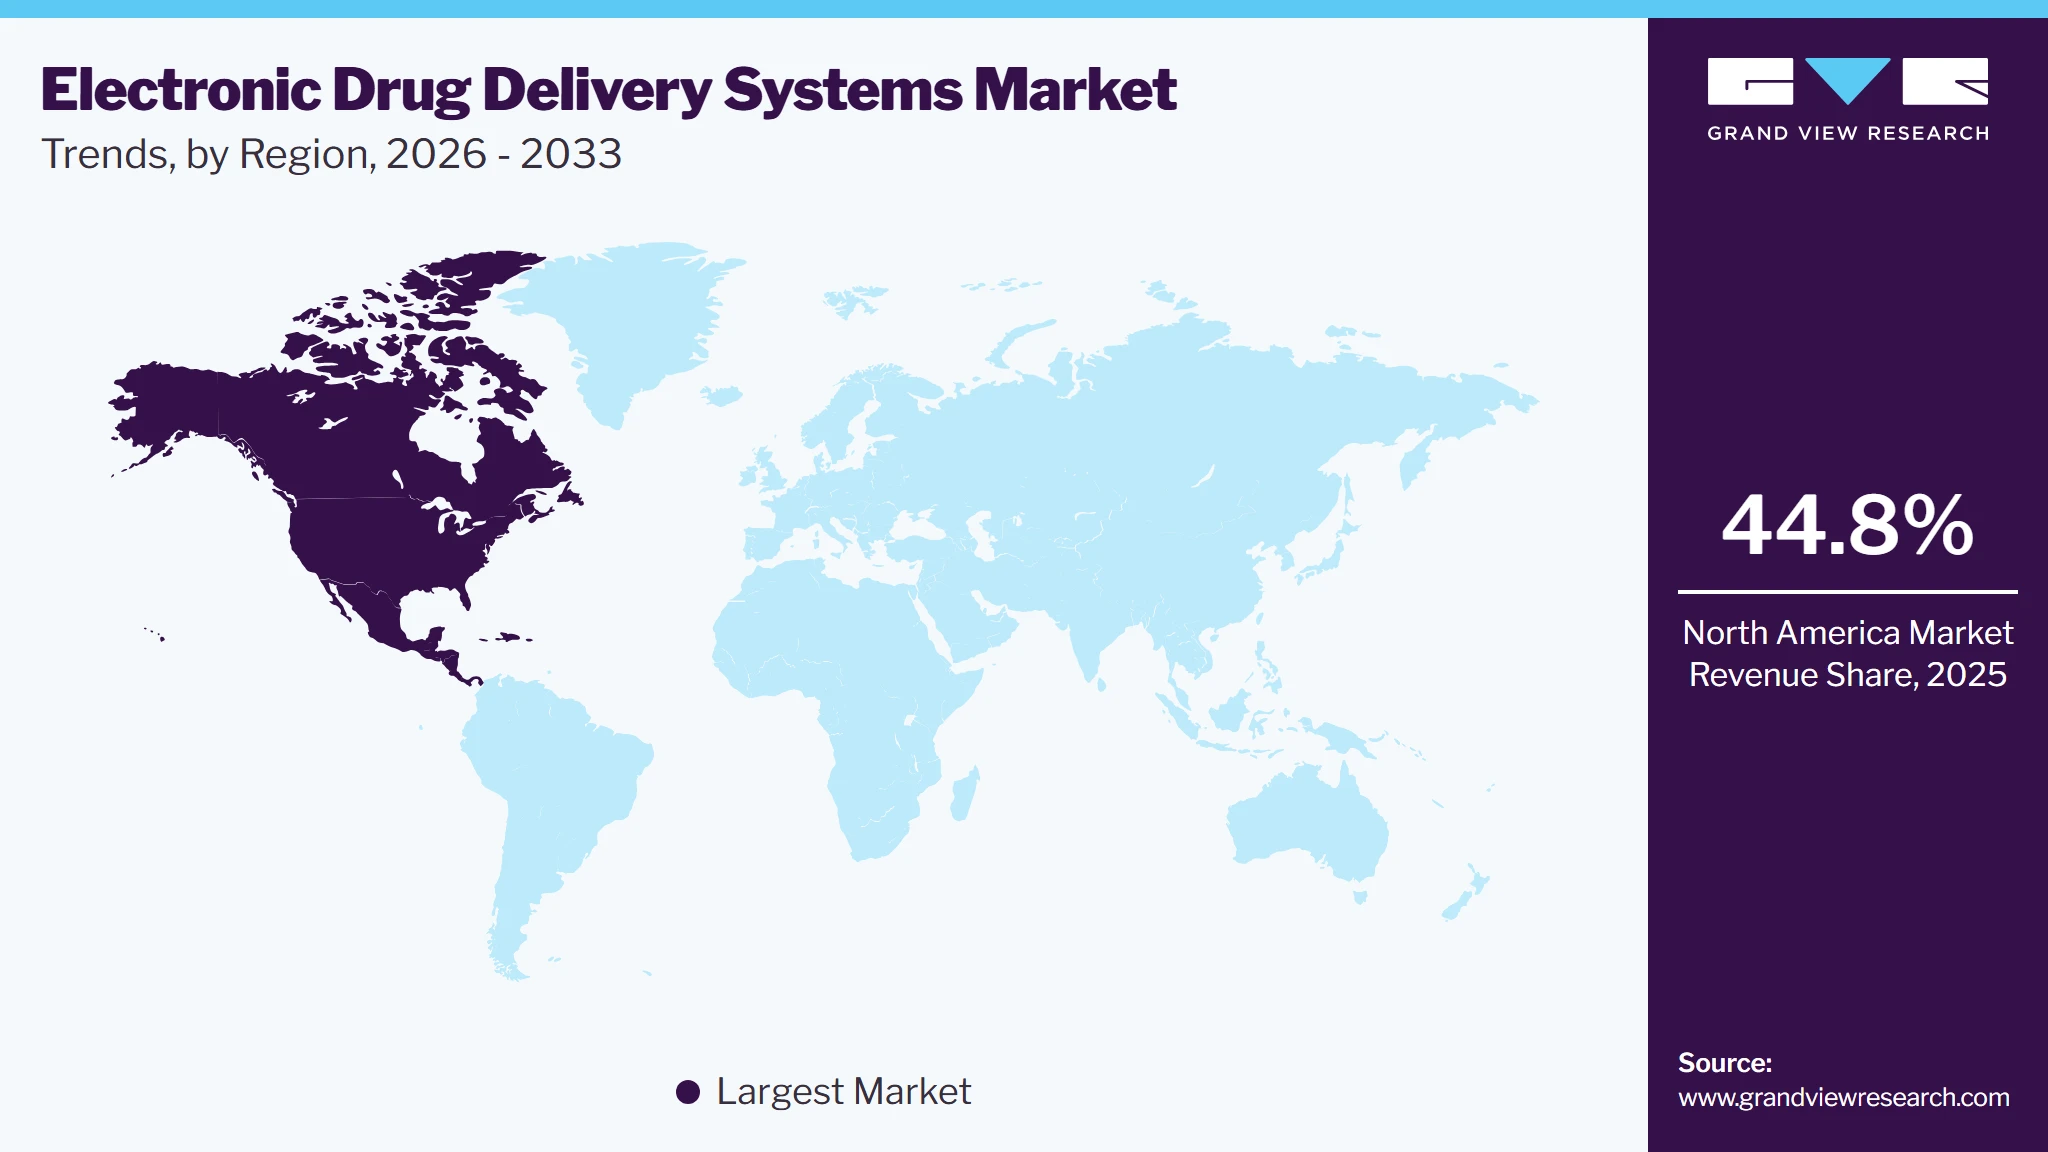
North America dominated the electronic drug delivery systems market with the largest revenue share of 44.8% in 2025, which can be attributed to the increasing demand for precise, reliable, and ISO-compliant testing solutions for autoinjectors, ensuring optimal performance and safety in drug delivery devices. For instance, in July 2024, Instron (Illinois Tool Works Inc.) introduced its next-generation Autoinjector Testing System, designed for comprehensive functionality testing of pen and autoinjectors according to ISO 11608 standards. In collaboration with pharmaceutical companies and CDMOs, the system evaluates key performance factors, including needle depth, injection time, activation force, dose accuracy, cap removal, and needle guard lockout. This innovative solution ensures precise and reliable performance for autoinjector devices.
 To learn more about this report, Download Free Sample Report
U.S. Electronic Drug Delivery Systems Market Trends
The electronic drug delivery systems market in the U.S. held the largest share in the North America region in 2025 due to the increasing adoption of smart connected devices to improve medication adherence and enhance patient outcomes. For instance, in February 2022, AptarGroup, Inc. launched the HeroTracker Sense, a smart connected device that integrates with pressurized metered dose inhalers (pMDIs) to enhance respiratory treatment management. It features sensors to monitor inhaler usage, providing patients and healthcare providers with real-time adherence data via digital platforms.
Europe Electronic Drug Delivery Systems Market Trends
The Europe electronic drug delivery systems market was identified as a lucrative region in 2025. The growing adoption of automated and connected drug delivery systems to enhance chronic disease management is driving the Europe electronic drug delivery systems market. For instance, in February 2024, Insulet Corporation's Omnipod 5 insulin pump, integrated with Abbott's FreeStyle Libre 2 continuous glucose monitor (CGM), received regulatory approval in the European Union. This system automates insulin delivery based on real-time glucose readings, enhancing diabetes management for patients aged two and older. The approval underscored advancements in connected healthcare technology, aiming to improve convenience and glycemic control for individuals with diabetes.
Asia Pacific Electronic Drug Delivery Systems Market Trends
The Asia Pacific electronic drug delivery systems market is anticipated to grow at a CAGR of 9.8% over the forecast period. The rising prevalence of diabetes and related complications in the Asia Pacific region is driving the demand for advanced electronic drug delivery systems for better disease management and early intervention. According to the WHO, in India, around 77 million adults are affected by type 2 diabetes, with nearly 25 million at risk of developing it due to prediabetes. Over 50% of individuals with diabetes are unaware of their condition, which can lead to severe complications such as heart attacks, strokes, nerve damage, foot ulcers, blindness, and kidney failure. Early detection and treatment are crucial to managing the health risks associated with diabetes.
The China electronic drug delivery systems market held a substantial market share in 2025 and is expected to grow at the fastest CAGR over the forecast period owing to the rising prevalence of chronic diseases such as diabetes and respiratory disorders, increasing adoption of smart healthcare devices, technological advancements, and growing demand for improved drug adherence and patient management solutions. In addition, government initiatives supporting healthcare modernization and expanding digital health solutions further fuel market growth.
Key Electronic Drug Delivery Systems Company Insights
Some of the key companies in the electronic drug delivery systems market include Bayer AG, Gerresheimer AG, Medtronic, Elcam Medical, and others. Organizations are focusing on increasing customer base to gain a competitive edge in the industry. Therefore, key players are taking several strategic initiatives, such as mergers and acquisitions and partnerships with other major companies.
-
Bayer AG focuses on discovering, developing, and producing products for human health and agriculture. Its offerings include medicines for various diseases, crop protection solutions, seeds, and non-prescription products. The company markets its healthcare and agricultural products through wholesalers, pharmacies, hospitals, and retailers.
-
Medtronic is a global medical technology company that designs, develops, and manufactures various medical devices for treating heart valve disorders, heart failure, vascular diseases, neurological disorders, and musculoskeletal issues. The company also provides biologic solutions for orthopedics and dental markets.
Key Electronic Drug Delivery Systems Companies:
The following key companies have been profiled for this study on the electronic drug delivery systems market.
-
Bayer AG
-
Gerresheimer AG
-
Medtronic
-
Elcam Medical
-
Novo Nordisk A/S
-
Insulet Corporation
-
Unilife Corporation (Amgen Inc.)
-
BD
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Bayer AG; Gerresheimer AG; Medtronic, BD)
- Established companies focus on expanding comprehensive electronic drug delivery portfolios comprising wearable infusion pumps, electronic autoinjectors, smart injection pens, connected inhalers, and digital drug-device combination platforms. They emphasize clinical validation, software integration, regulatory compliance, healthcare provider partnerships, and global commercialization strategies. These companies also invest heavily in connectivity solutions, remote patient monitoring capabilities, and integration with digital health ecosystems to strengthen market position and support chronic disease management.
- Strong brand recognition, extensive global distribution networks, and established relationships with pharmaceutical manufacturers, healthcare providers, and payers support sustained market leadership. Broad product portfolios, advanced engineering capabilities, regulatory expertise, and significant R&D investments enable continuous innovation in connected drug delivery technologies. Their experience in large-scale manufacturing and commercialization facilitates rapid market penetration across multiple therapeutic areas and geographic regions.
- High operational costs associated with R&D, software development, cybersecurity compliance, and regulatory approvals may impact profitability. Dependence on complex supply chains and pharmaceutical partnerships can create operational risks. Large organizational structures may reduce agility in responding to emerging technologies, evolving patient preferences, and rapidly changing digital healthcare requirements.
Emerging Players (Elcam Medical; Novo Nordisk A/S; Insulet Corporation; Unilife Corporation (Amgen Inc.)
- Emerging companies prioritize next-generation connected drug delivery solutions, patient-centric device designs, wearable technologies, and specialized platforms for chronic disease management. They focus on innovation in smart dosing systems, miniaturized delivery devices, digital health integration, and personalized treatment solutions. Strategic collaborations with pharmaceutical companies and healthcare technology providers are commonly used to accelerate commercialization and expand market presence.
- Agile product development processes enable faster innovation and adaptation to evolving healthcare needs. Specialized expertise in wearable technologies, diabetes management, connected care solutions, and patient engagement platforms supports differentiation. Their ability to develop niche solutions and rapidly incorporate emerging digital health technologies creates opportunities to gain market share in high-growth therapeutic segments.
- Limited global distribution infrastructure and lower brand recognition compared with multinational competitors may restrict large-scale market expansion. Smaller financial resources can constrain investments in clinical studies, regulatory approvals, cybersecurity infrastructure, and global commercialization efforts. Dependence on strategic partnerships and competitive pressure from established medical device manufacturers may challenge long-term growth and profitability.
Recent Developments
-
In November 2024, Medtronic’s InPen, a smart insulin pen, received FDA approval for the management of type 1 and 2 diabetes. The device integrates with a mobile app, allowing users to track insulin doses, provide real-time dosage recommendations, and monitor blood glucose levels.
-
In May 2023, Medtronic announced its definitive agreement to acquire EOFlow, a South Korean company specializing in wearable insulin patch pumps. This acquisition aimed to enhance Medtronic's diabetes management portfolio by integrating EOFlow's innovative technology with its existing products.
-
In March 2021, Jabil Inc. entered into a collaboration agreement with E3D, granting exclusive rights to develop a high-volume reusable auto-injector and connected variants.
Electronic Drug Delivery Systems Market Report Scope
Report Attribute
Details
Market size in 2025
USD 13.0 billion
Estimated market size in 2026
USD 14.2 billion
Projected market size by 2033
USD 26.5 billion
Growth rate
CAGR of 9.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, application, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Thailand; Brazil; Argentina; Colombia; Saudi Arabia; South Africa; UAE
Key companies profiled
Bayer AG; Gerresheimer AG; Medtronic; Elcam Medical; Novo Nordisk A/S; Insulet Corporation; Unilife Corporation (Amgen Inc.); BD
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Electronic Drug Delivery Systems Market Report Segmentation
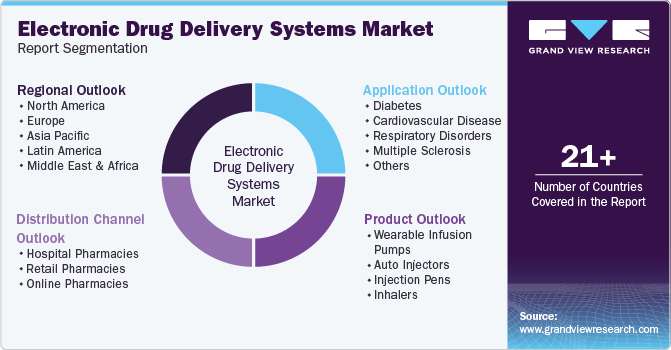
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global electronic drug delivery systems market report based on product, application, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Wearable Infusion Pumps
-
Auto Injectors
-
Injection Pens
-
Inhalers
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Diabetes
-
Cardiovascular Disease
-
Respiratory Disorders
-
Multiple Sclerosis
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Online Pharmacies
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Sweden
-
Denmark
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The electronic drug delivery systems market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each electronic drug delivery systems segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
Wearable Infusion Pumps
Revenue captured from electronically controlled wearable infusion pumps designed to deliver medications continuously or at programmed intervals. These devices are widely used for insulin delivery, biologics administration, pain management, and chronic disease treatment. Revenue includes device sales, accessories, consumables, and associated software platforms.
Auto Injectors
Revenue generated from electronic and smart autoinjector devices that enable automated administration of injectable medications with improved dosing accuracy and patient convenience. These systems are commonly used for biologics, emergency medications, autoimmune therapies, and chronic disease management.
Injection Pens
Revenue derived from electronic injection pens used for precise and user-friendly delivery of medications such as insulin, growth hormones, and other injectable therapies. The segment includes reusable and disposable smart pen systems equipped with dose-tracking and connectivity features.
Inhalers
Revenue captured from electronic and connected inhaler systems designed for the delivery of respiratory medications. These devices incorporate digital monitoring, dose-tracking, and adherence-enhancing technologies to improve disease management and treatment outcomes.
Segment - Application
Revenue capture definition
Diabetes
Revenue generated from electronic drug delivery systems used for diabetes management, including smart insulin pens, wearable insulin pumps, and connected delivery devices. This segment benefits from the growing global prevalence of diabetes and increasing demand for automated glucose-linked treatment solutions.
Cardiovascular Disease
Revenue captured from electronic drug delivery devices used to administer therapies for cardiovascular disorders, including anticoagulants, lipid-lowering agents, and other chronic cardiovascular medications. These systems support accurate dosing and long-term treatment adherence.
Respiratory Disorders
Revenue derived from electronic inhalers and connected respiratory drug delivery systems used for asthma, chronic obstructive pulmonary disease (COPD), and other pulmonary conditions. The segment focuses on improving medication adherence and optimizing disease management.
Multiple Sclerosis
Revenue generated from electronic autoinjectors and wearable delivery devices used for administering disease-modifying therapies and biologics for multiple sclerosis patients. These systems enhance self-administration, treatment convenience, and dosing precision.
Others
Revenue captured from electronic drug delivery systems utilized in oncology, autoimmune diseases, neurological disorders, pain management, hormone therapies, rare diseases, and other therapeutic applications requiring precise medication administration.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Revenue generated from electronic drug delivery systems distributed through hospital pharmacies and healthcare institutions. These facilities supply devices for inpatient care, specialty treatments, chronic disease management programs, and physician-supervised therapy administration.
Retail Pharmacies
Revenue captured from electronic drug delivery devices sold through retail pharmacy chains, community pharmacies, and specialty pharmacies. This segment supports patient access to self-administration devices and chronic disease treatment products in outpatient settings.
Online Pharmacies
Revenue derived from electronic drug delivery systems distributed through e-commerce platforms and online pharmacy channels. The segment benefits from increasing digital healthcare adoption, home delivery services, and growing patient preference for convenient purchasing options.
Estimation Model
Methodology
Question / Objective
Process Steps
Data Sources
Scope Definition
What is being sized?
- Triangulate data from pharmaceutical companies, device manufacturers
- Scope Product Type, Application, and Distribution Channel Segments
- Establish Geographic Coverage (Global/Regional)
- 4Align on base year & forecast horizon (2026-2033)
ASCRS, ESCP, WHO, FDA, CE Mark
Build the Product Base
How large is total addressable market?
- Gather patient population data across diabetes, cardiovascular disease, respiratory disorders, multiple sclerosis, and other chronic conditions requiring long-term drug administration.
- Estimate annual treatment volumes, prescription rates, and device utilization across key therapeutic areas.
- Apply patient eligibility, adherence rates, self-administration trends, and therapy utilization assumptions.
- Forecast demand based on disease prevalence, biologics adoption, home-based care expansion, and patient preference for self-administration.
National inpatient databases, hospital procurement databases, health ministry surgery registries
Estimate Penetration
What portion of procedures use disposable devices?
- Assess adoption rates of electronic drug delivery systems
- Analyze penetration across different healthcare settings and clinical specialties.
- Evaluate the impact of digital health adoption, reimbursement support, and connected care initiatives on market penetration.
- Validate adoption estimates using clinical studies
Primary interviews, company filings, trade surveys
Revenue Conversion
How does volume become revenue?
- Determine ASPs by Product Category
- Segment revenues by product type, application, distribution channel, and geography.
- Apply Regional Pricing Variations
- Cross-check with Company Revenues and Trade Data
Distributor pricing sheets, procurement data, import/export databases, expert interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Technological Advancements in Electronic Drug Delivery Systems
Conducted a comprehensive assessment of technological innovations in the electronic drug delivery systems market, focusing on smart autoinjectors, wearable infusion pumps, connected injection pens, digital inhalers, wireless connectivity, mobile health integration, and automated dosing technologies. The study evaluated advancements in sensor-enabled monitoring, dose tracking, adherence management, cloud-based healthcare platforms, artificial intelligence integration, and remote patient monitoring capabilities. Product launches, regulatory approvals, software innovations, and strategic collaborations between pharmaceutical and medical device companies were also analyzed.
This analysis enables stakeholders to identify emerging technology trends and innovation-driven growth opportunities. The insights support product development, commercialization planning, and strategic investment decisions while highlighting advancements that improve medication adherence, patient engagement, treatment outcomes, and healthcare efficiency.
Competitive Landscape and Product Benchmarking Analysis
Conducted an in-depth evaluation of leading electronic drug delivery system manufacturers based on product portfolios, technology platforms, regulatory approvals, connectivity features, therapeutic area focus, distribution networks, and geographic presence. The assessment benchmarked device functionality, usability, digital integration, patient adherence features, software capabilities, and clinical performance. Strategic initiatives including mergers, acquisitions, partnerships, and new product launches were also analyzed.
This assessment helps stakeholders benchmark competitive positioning, identify product differentiation opportunities, and understand strategic approaches adopted by market leaders. The findings support partnership evaluation, investment planning, competitive intelligence, and market entry strategies while providing insights into evolving industry dynamics.
Geographical Expansion Analysis – Global Electronic Drug Delivery Systems Market
Conducted a detailed regional assessment across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. The study analyzed chronic disease prevalence, healthcare digitization trends, reimbursement frameworks, home healthcare adoption, regulatory environments, and pharmaceutical-device ecosystem development. Country-level opportunities, adoption patterns, and market penetration strategies were also examined.
This geographical analysis enables stakeholders to identify high-growth regions and optimize expansion strategies. The study highlights regional differences in healthcare infrastructure, digital health adoption, reimbursement policies, and patient preferences, supporting informed strategic and investment decisions across global markets.
Frequently Asked Questions About This Report
The global electronic drug delivery systems market size was estimated at USD 13.0 billion in 2025 and is expected to reach USD 14.2 billion in 2026.
The global electronic drug delivery systems market is expected to grow at a compound annual growth rate of 9.3% from 2026 to 2033 to reach USD 26.5 billion by 2033.
Based on application, the diabetes segment dominated the electronic drug delivery systems market with a share of 36.5% in 2025. This is attributable to factors such as high availability of electronic drug delivery devices such as insulin pumps and injection pens by major market players for type 1 and 2 diabetes management, rising adoption of smartphone apps, and increasing penetration of digital platforms.
Some key players operating in the electronic drug delivery systems market include Bayer AG; Gerresheimer AG; Medtronic Plc; Elcam Medical Group; Novo Nordisk; Insulet Corporation; Becton, Dickinson and Company; Sanofi S.A.; and Unilife Corporation.
Key factors that are driving the electronic drug delivery systems market growth include increasing prevalence of chronic diseases such as diabetes, asthma and cardiovascular disease and technological advancements in development of smart drug delivery systems.
Asia Pacific is the fastest-growing region over the forecast period.
North America dominated the electronic drug delivery systems market with the largest revenue share of 44.8% in 2025.
Based on product type, the wearable infusion pumps segment led the market with the largest revenue share of 41.3% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


