
- Home
- »
- Healthcare IT
- »
-
Electronic Health Record Apps Market Size Report, 2033GVR Report cover

Electronic Health Record Apps Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Android, iOS), By Application (Clinical, Administrative, e-Prescribing), By End-use (Hospitals, Ambulatory Care Centers), By Region, And Segment Forecasts
Market Size, 2025
$912.6MMarket Estimate, 2026
$989.4MMarket Forecast, 2033
$1,885.2MCAGR, 2026–2033
8.3%Electronic Health Record Apps Market Summary
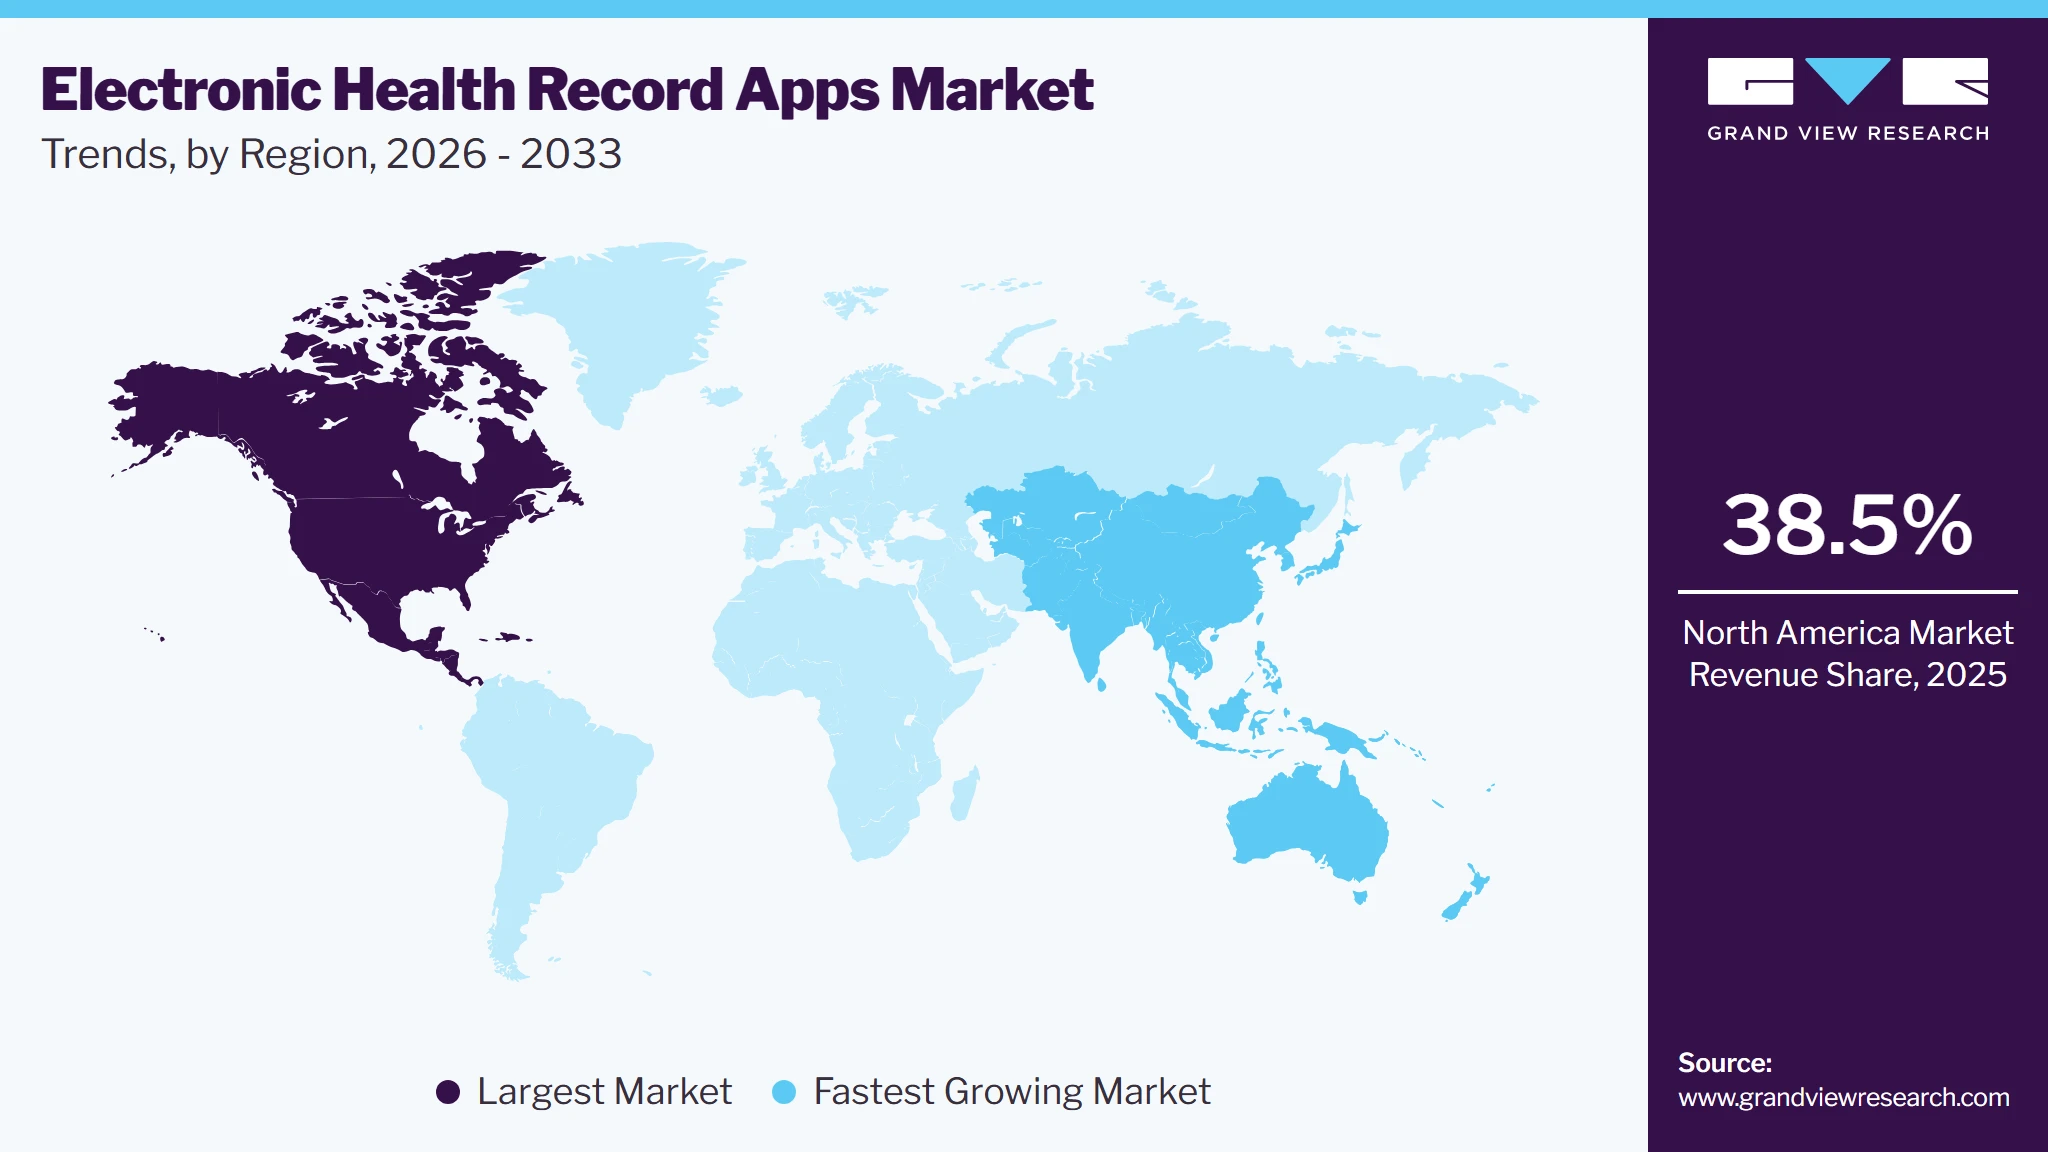
The global electronic health record apps market size was valued at USD 912.6 million in 2025 and is projected to grow from USD 989.4 million in 2026 to USD 1,885.2 million by 2033, at a CAGR of 8.3% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 38.5% in 2025. The market is poised for significant growth, driven by increasing demand for efficient healthcare management and rising digitalization.
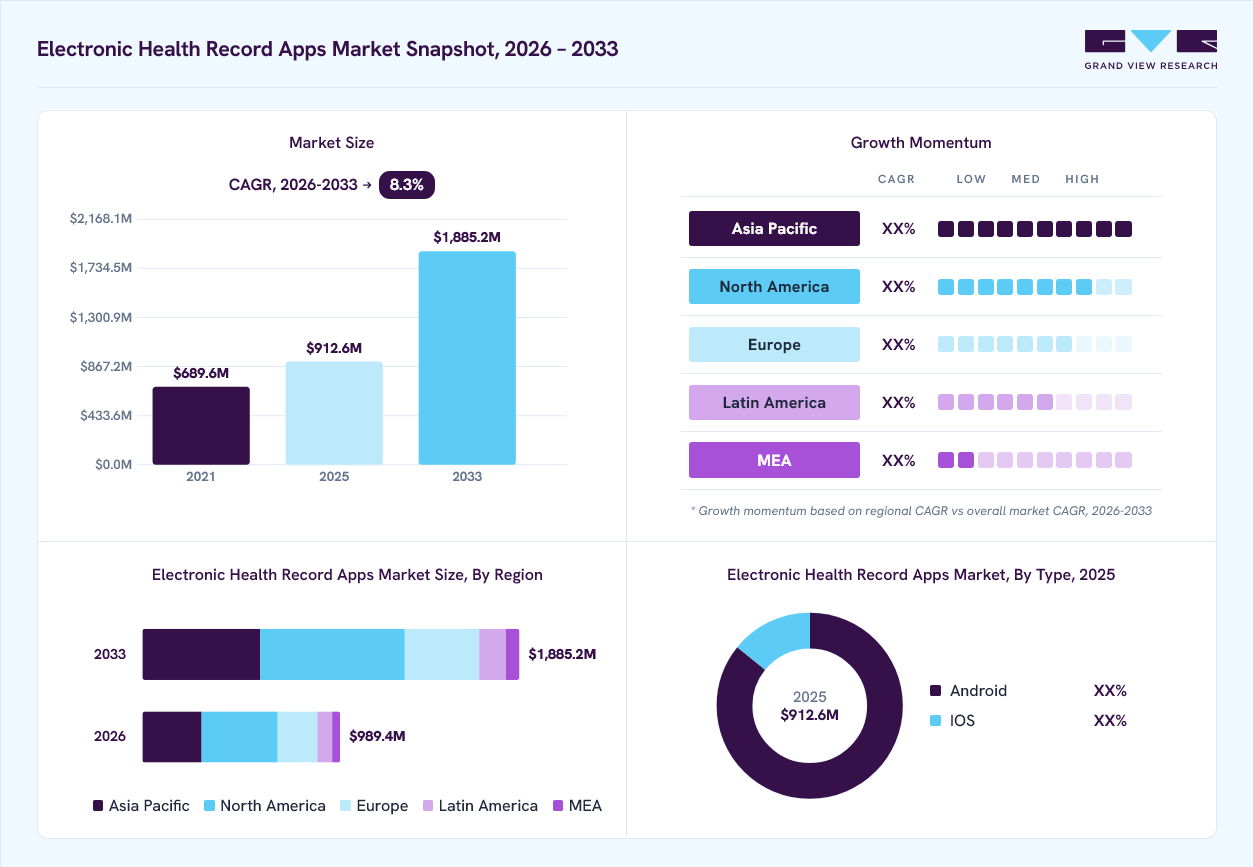 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Android segment led the market with the largest revenue share of 85.7% in 2025.
- By application: Administrative segment led the market with the largest revenue share of 32.5% in 2025.
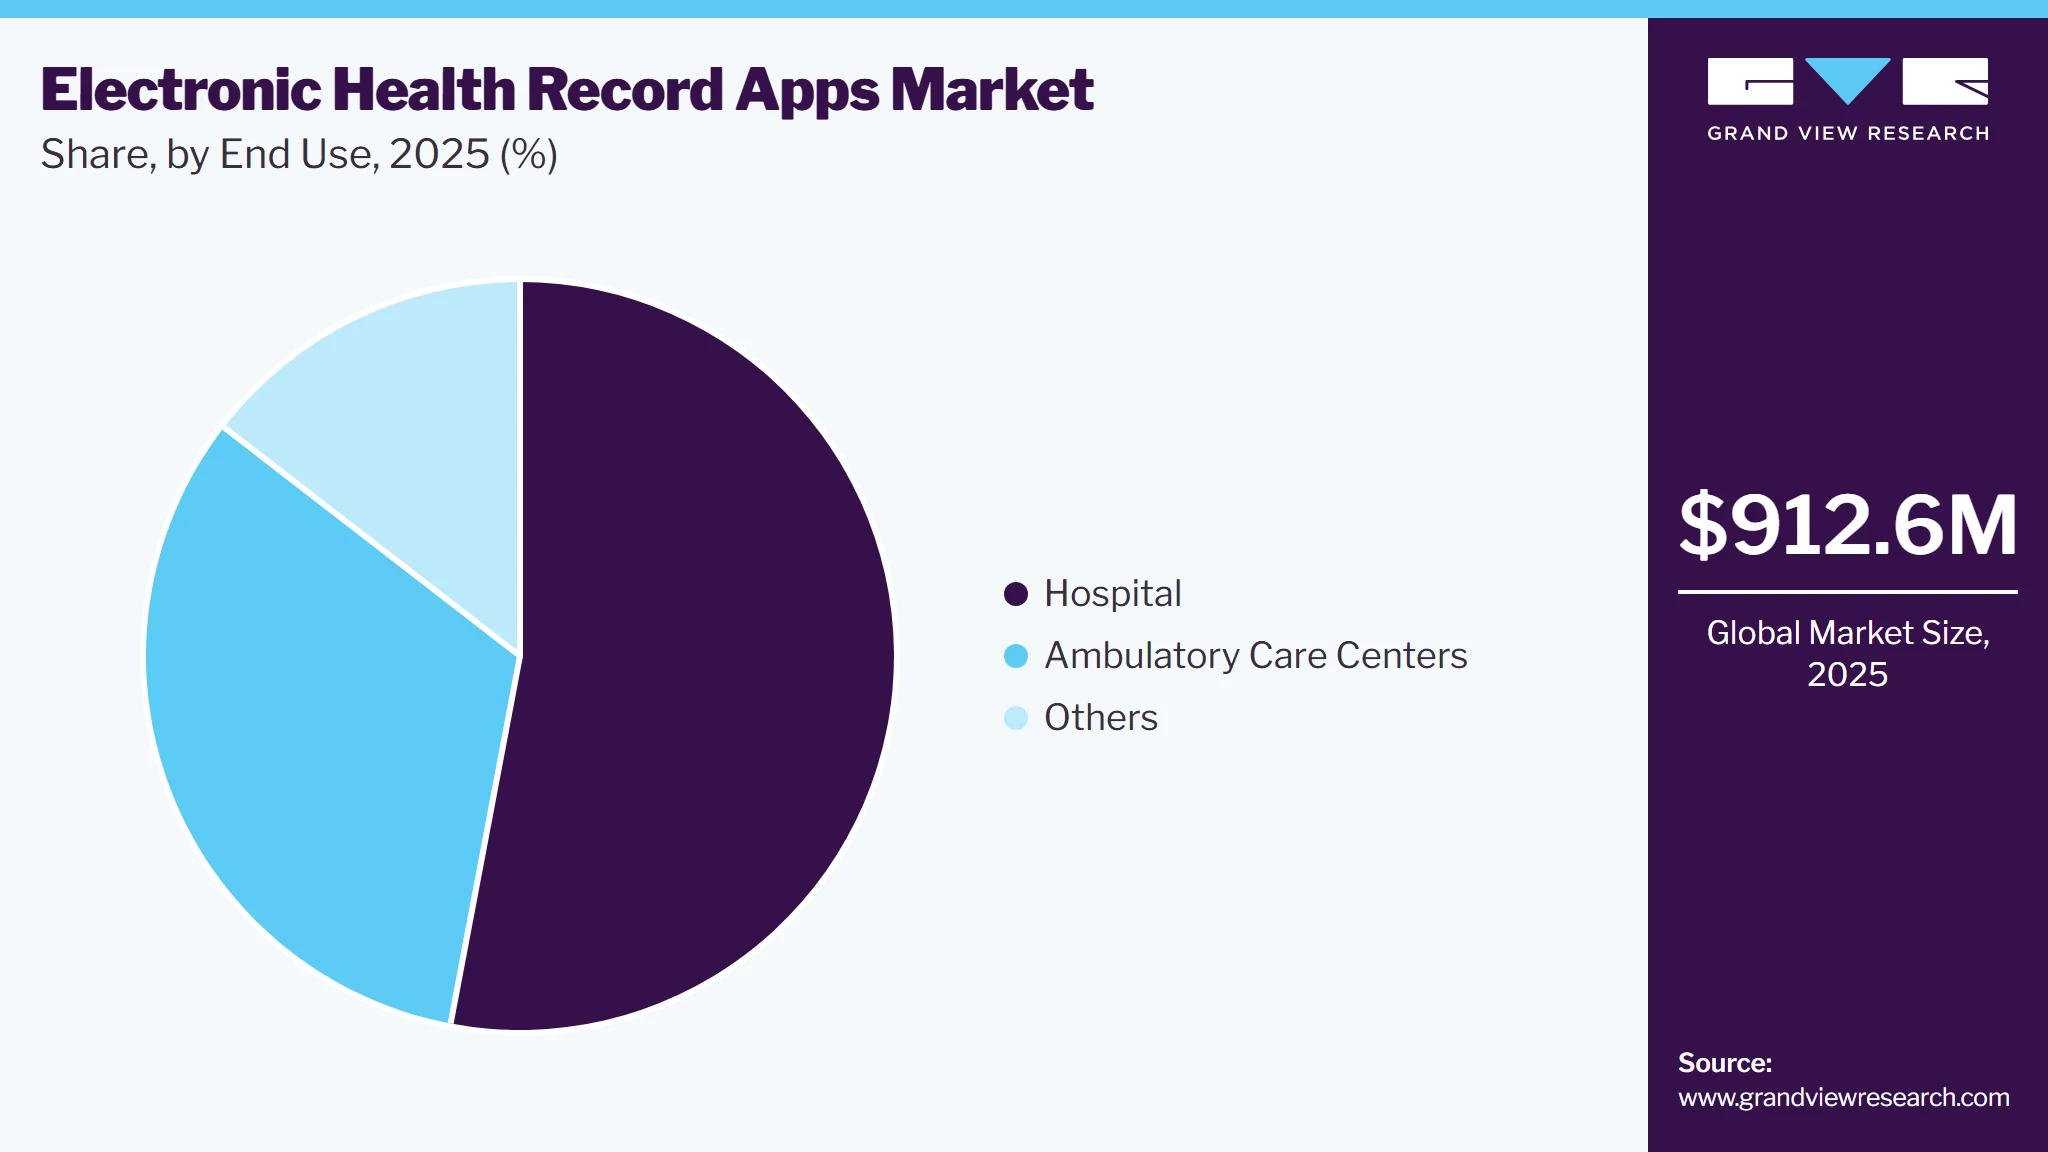
- By end-use: Hospital segment led the market with the largest revenue share of 53.0% in 2025.
Regional Highlights
- Largest regional market: North America (38.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 912.6 Million
- Estimated market size in 2026: USD 989.4 Million
- Projected market size by 2033: USD 1,885.2 Million
- CAGR (2026-2033): 8.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Key drivers include the need for streamlined patient data access, regulatory mandates, and growing adoption of telemedicine. COVID-19 pandemic accelerated this trend, highlighting the importance of digital health solutions. As healthcare continues to prioritize technology integration, the market is expected to substantially expand over the forecast period. Widespread use of electronic health records (EHRs) in medical practices has facilitated rapid adoption of mobile EHR solutions. According to GSM Association's "Mobile Economy 2024" report, more than 5 billion people were connected to mobile services in 2023, with unique mobile subscribers projected to reach 6.3 billion by 2030. Smartphone penetration, which was 69% in 2023, is expected to rise to 74% by 2030. This increasing adoption of smartphones is a significant driver for the growth of EHR applications, as improved network infrastructure and expanded coverage enhance the usability and accessibility of these apps.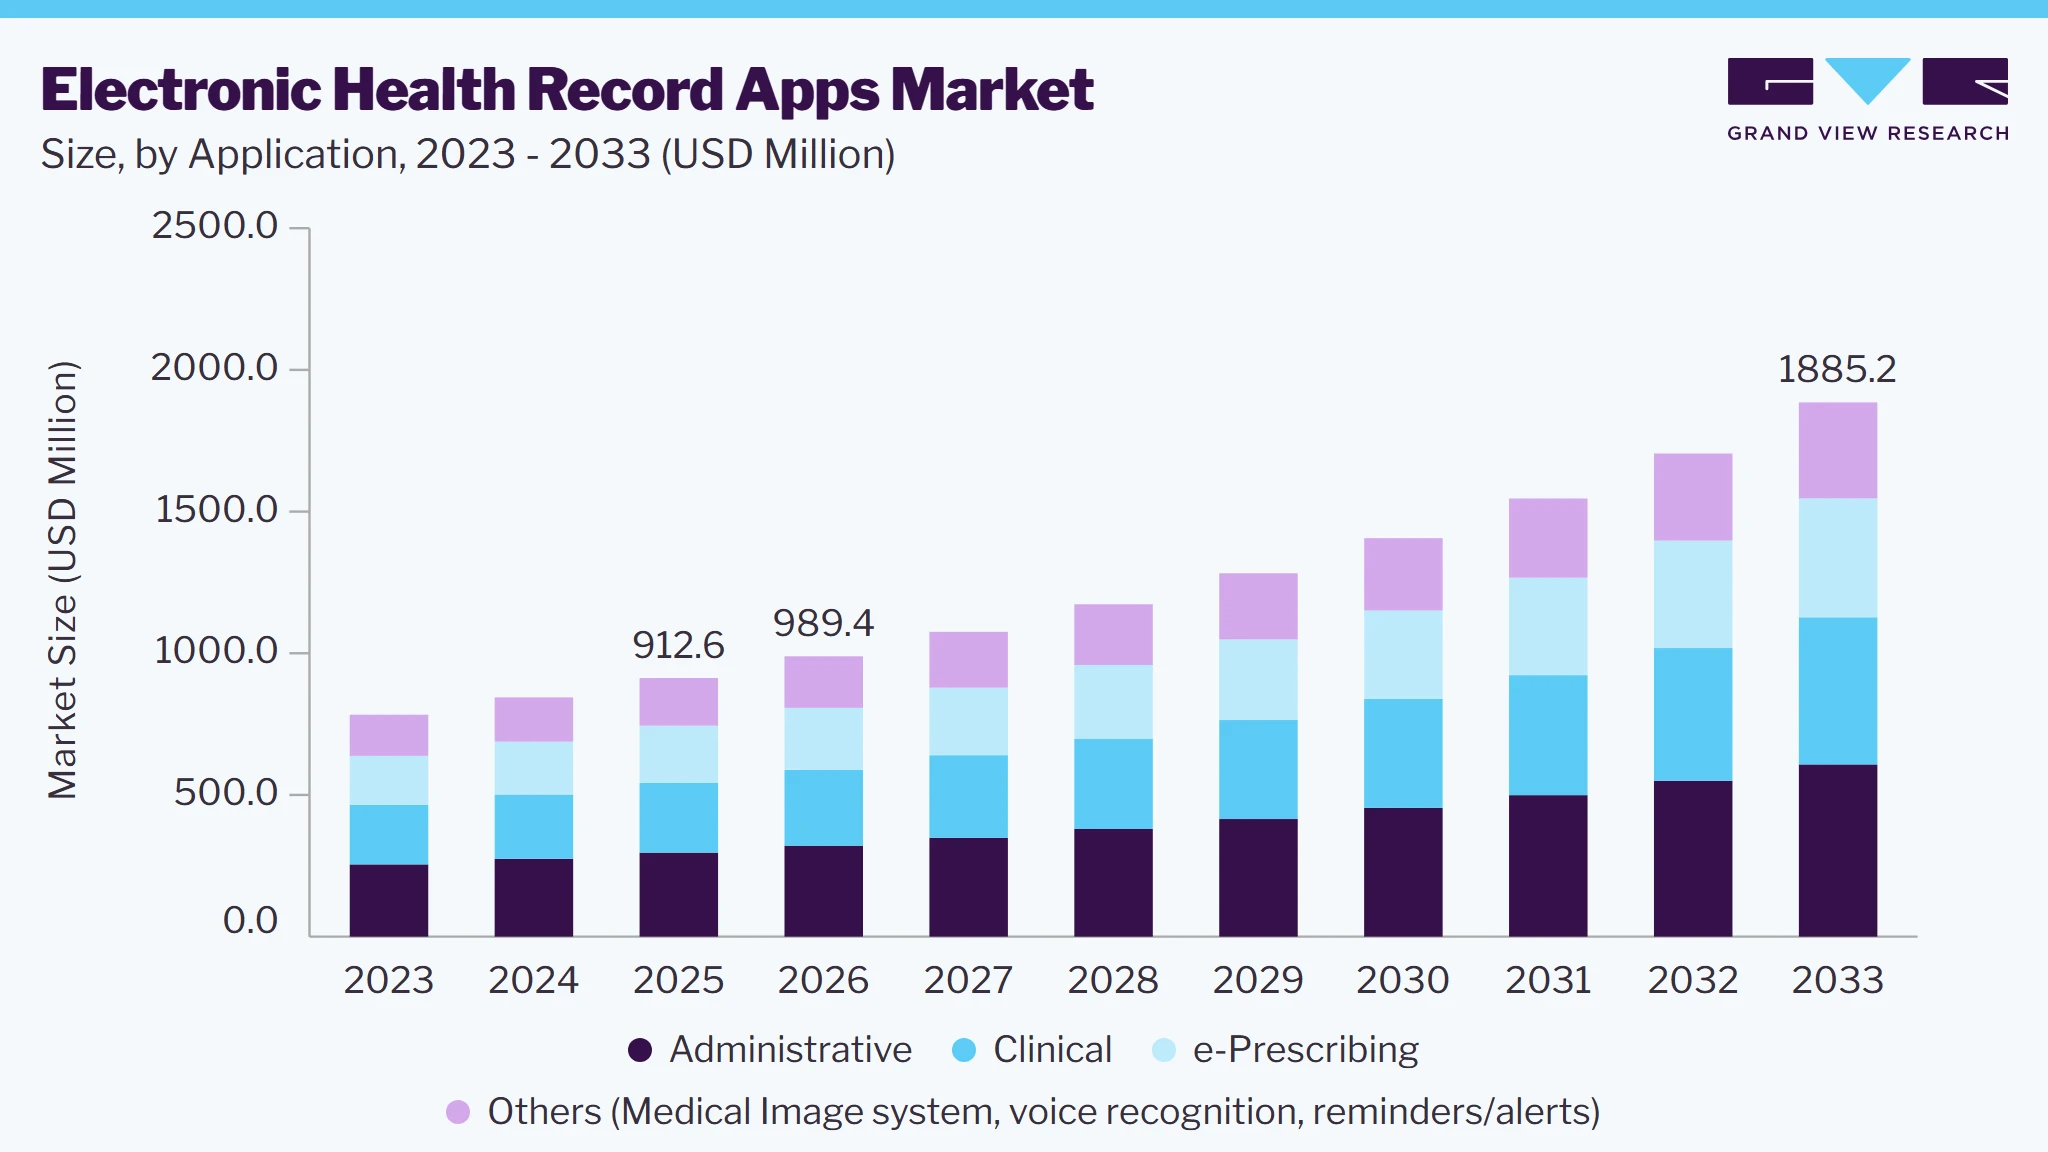 To learn more about this report, Download Free Sample Report
Furthermore, the Hospital Vision Study by Zebra in 2022 revealed that 62% of nursing staff at surveyed hospitals access patient EHRs on their mobile devices, with 57% using them for diagnostic lab results. By leveraging mobile devices and predictive analytics, hospital staff aim to enhance diagnostic accuracy and personalize patient care.
Hospitals have already experienced productivity gains by equipping key personnel with mobile devices. The Zebra study highlighted that in 2022, 97% of nurses used mobile devices at the bedside, a trend anticipated to extend to other medical disciplines, including emergency room nurses, pharmacists, and lab technicians. This is driven by the integration of advanced applications, remote patient monitoring, and artificial intelligence. These advancements are expected to empower clinicians with greater insights and information, transforming the daily work experience and enhancing patient treatment.
Market Dynamics
The electronic health record (EHR) apps market is driven by the increasing digitalization of healthcare, growing adoption of mobile health technologies, and rising demand for real-time access to patient information. Healthcare providers are leveraging EHR apps to improve clinical efficiency, streamline documentation, and enhance care coordination. Advancements in AI, cloud computing, and voice-enabled documentation are further strengthening application capabilities. Despite challenges related to data privacy, cybersecurity, and implementation costs, supportive government initiatives, investments in interoperable healthcare infrastructure, and the growing focus on patient-centric care are expected to drive market growth over the forecast period.
Governments across developed and emerging economies are promoting the adoption of electronic health records (EHRs) through digital health policies, interoperability initiatives, and financial incentives aimed at improving care coordination, patient safety, and healthcare efficiency. As healthcare organizations transition from paper-based to digital records, the demand for mobile EHR applications is increasing, enabling clinicians to securely access patient information, streamline workflows, and support remote care delivery.
For instance, according to the U.S. Office of the National Coordinator for Health Information Technology (ONC), as of 2024, 91% of office-based physicians and over 99% of non-federal acute care hospitals in the United States had adopted certified electronic health record (EHR) systems. This high level of digitalization is driving demand for mobile EHR applications that facilitate secure access to patient records, interoperability, and real-time clinical decision-making across hospitals and ambulatory care settings.
Despite the increasing adoption of EHR apps, concerns related to data privacy, cybersecurity, and regulatory compliance remain significant barriers to market growth. These applications store and transmit highly sensitive patient information, making them attractive targets for cyberattacks, including data breaches, ransomware, and unauthorized access. Such incidents can disrupt healthcare operations, compromise patient confidentiality, and result in significant financial, legal, and reputational consequences for healthcare organizations.
For instance, according to the U.S. Department of Health and Human Services (HHS), over 276 million healthcare records were exposed in data breaches during 2024, highlighting the growing cybersecurity risks associated with digital healthcare platforms. Thus, healthcare providers must invest heavily in advanced encryption technologies, identity management systems, cybersecurity infrastructure, and regulatory compliance measures such as HIPAA and GDPR, increasing implementation costs and slowing adoption among smaller healthcare facilities.
The integration of artificial intelligence (AI) into electronic health record (EHR) applications presents a significant growth opportunity by improving clinical efficiency, reducing administrative burden, and enhancing patient engagement. AI-powered features such as ambient clinical documentation, predictive analytics, intelligent clinical decision support, voice recognition, automated coding, and conversational AI are transforming EHR apps into intelligent healthcare platforms that streamline workflows and support faster, more informed clinical decision-making.
For instance, in September 2025, Oracle introduced new AI capabilities for the Oracle Health Patient Portal, enabling patients to securely interact with their electronic health records through conversational AI powered by OpenAI. The solution provides plain-language explanations of diagnoses, laboratory results, and treatment plans, while allowing patients to ask context-aware questions directly within the patient portal. These enhancements strengthen patient engagement, improve health literacy, and demonstrate the growing role of AI-enabled EHR applications in delivering more personalized and efficient healthcare services.
This development highlights the increasing adoption of AI-driven capabilities within EHR platforms, creating significant opportunities for vendors to enhance user experience, improve clinical workflows, and support better patient outcomes.
Electronic Health Record Apps of Prominent Companies
Company
Application
Features
Epic Systems Corporation
Mobile access to patient charts, secure messaging, order entry, clinical documentation, and real-time patient updates.
Meditab
(IMS Go)
Mobile charting, e-prescribing, appointment scheduling, patient records access, and billing integration.
AdvancedMD, Inc.
Voice-enabled charting, mobile documentation, e-prescribing, task management, and secure patient data access.
eClinicalWorks
Remote patient chart access, telehealth support, secure messaging, e-prescribing, and clinical documentation.
EverHealth Solutions Inc. (DrChrono)
iPad/iPhone-based electronic health record, medical dictation, e-prescribing, patient scheduling, medical billing, and telehealth integration.
Altera Digital Health Inc.
Mobile clinical workflows, bedside documentation, medication administration, patient monitoring, and interoperability support.
Market Concentration & Characteristics
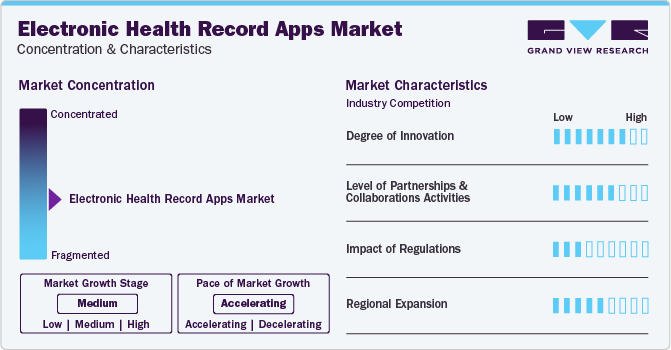
The chart below illustrates the relationship between market concentration, industry characteristics, and industry participants. The x-axis represents the level of industry concentration, ranging from low to high. The y-axis represents various industry characteristics, including industry competition, degree of innovation, level of mergers & acquisitions activities, impact of regulations, and geographic expansion. The electronic health record apps market is fragmented, with many small players entering the market and offering new services. The degree of innovation is high, and the level of partnerships & collaborations activities is high. The impact of regulations on the market is moderate and the regional expansion of the market is medium.
 To learn more about this report, Download Free Sample Report
The market is experiencing significant innovation, with various market players offering new products to enhance their market presence. Companies like DrChrono AdvancedMD, Inc., eClinicalWorks, Networking Technology, Inc., and others are offering advanced mobile EHR applications that not only streamline clinical workflows but also enhance overall practitioner performance. For instance, DrChrono's iOS mobile EHR app is designed to ensure that practitioners’ clinical workflows are optimized and run smoothly. This mobile EHR app enables faster patient charting, which is important for maintaining accurate and up-to-date patient records.
The impact of partnership & collaborations on the market is high due to several key market players, including Epic Systems Corporation, Meditab, CompuGroup Medical, AdvancedMD, Inc., eClinicalWorks, EverHealth Solutions Inc. (DrChrono), and others, are involved in partnership & collaborations activities to expand their market presence. For instance, in April 2023, Epic embraced generative AI's role in healthcare by expanding its collaboration with Microsoft. It is integrating OpenAI services, like GPT-4, into Epic's EHR. Pilot programs for these services have already commenced at select health systems, including UC San Diego Health, UW Health, and Stanford Health Care.
Impact of regulations on the market is moderate. However, market is expected to experience growth due to favorable government policies and laws that ensure safety and efficacy of EHR apps. Market players need to consider regulations such as HIPAA (Health Insurance Portability and Accountability Act) during EHR apps development to protect privacy and security of patient health information in U.S. healthcare system.
Regional expansion in the market is moderate, influenced by regulatory changes and specific demands of target customers in low- and medium-income countries. However, some market players extend their presence in different regions to capture market share. For instance, in January 2022, Vanderbilt University Medical Center launched a smartphone application called mUzima. App is compatible with Google's Android operating system and is tailored to integrate smoothly with OpenMRS, an EHR system widely used in low- and middle-income countries (LMICs).
Analyst Perspective
The electronic health record apps market is growing rapidly as healthcare providers prioritize mobile access to patient data, clinical documentation, and real-time care coordination. Advances in AI, cloud computing, voice recognition, and interoperability standards such as FHIR are transforming electronic health record apps into intelligent clinical workflow platforms. Large healthcare systems drive demand through enterprise-wide deployments, while cloud-based and mobile-first solutions are increasingly adopted by ambulatory care centers and physician practices for their cost efficiency and scalability. Moreover, regulatory support for digital health, the expansion of telehealth, and greater smartphone use among healthcare professionals are expected to further accelerate market growth.
Type Insights
Based on type, the android segment led the market with the largest revenue share of 85.7% in 2025. This is attributed to Android's widespread availability across various smartphone and tablet manufacturers, unlike iOS, which is exclusive to Apple products. Additionally, the cost-effectiveness and rising usage of Android smartphones have fueled this segment's growth. For instance, in February 2023, Business of Apps reported that Android is the most popular operating system worldwide, with over 3 billion active users across more than 190 countries. The expanding base of Android users is expected to further propel this segment's growth during the forecast period.
However, the iOS segment is anticipated to experience the significant growth in the coming years. This projected growth is driven by the increasing adoption of iPhone devices among consumers. Data from BankMyCell.com indicated that the iOS smartphone market share in the U.S. grew from 58.10% in 2023 to 61.45% in 2024. Such trends show the potential for substantial growth in the iOS segment, contributing to the overall expansion of the market.
Application Insights
Based on application, the administrative segment led the market with the largest revenue share of 32.5% in 2025. The segment includes appointment management, billing management, document management, patient portals, and scheduling. These functions streamline healthcare operations, enhance patient engagement, and improve efficiency. By simplifying administrative tasks, EHR apps reduce errors, save time, and facilitate better patient care. Demand for integrated, user-friendly solutions is fueling market expansion, making administrative capabilities a key driver of EHR app adoption.
Clinical segment is expected to experience the fastest growth during the forecast period. EHR apps enhance clinical workflows by providing real-time access to patient data, supporting decision-making, and improving diagnostic accuracy. Features such as lab results integration, and clinical documentation streamline patient care processes. By improving efficiency, reducing errors, and enhancing patient outcomes, clinical segment's advancements in EHR are expected to drive segment growth.
End-use Insights
Based on end-use, the hospital segment led the market with the largest revenue share of 53.0% in 2025. This is attributed to the large amount of medical data generated daily by hospitals, which EHRs efficiently manage. The use of EHRs helps large-scale hospitals save both costs and time, thereby fueling market growth. Additionally, the ease of EHR deployment in small and midsized hospitals contributes to their high adoption rates, further driving the market growth.
 To learn more about this report, Download Free Sample Report
Ambulatory care centers are projected to witness the highest CAGR over the forecast period. This growth is driven by the global increase in chronic diseases and the rising adoption of healthcare IT services in these centers. Ambulatory care centers offer significant convenience to both patients and healthcare providers, making them an attractive option for medical care. The increasing number of ambulatory care centers in both developed and developing economies is expected to drive the market growth over the forecast period.
Regional Insights
North America dominated electronic health record apps market with the largest revenue share of 38.5% in 2025. This is attributed to robust healthcare infrastructure, increased adoption of digital health technologies, and favorable government policies that support the adoption of EHRs & the availability of infrastructure with high digital literacy. Furthermore, improving support for the adoption of HCIT by payers and healthcare providers is expected to boost regional growth.
 To learn more about this report, Download Free Sample Report
U.S. Electronic Health Record Apps Market Trends
The electronic health record apps market in the U.S. held the largest share in the North America region in 2025. Favorable government regulations for monitoring the safety of healthcare IT solutions are expected to fuel the market in the U.S. For instance, in May 2020, the federal government proposed the Federal Health IT Strategic Plan 2020-2025, which mandates meaningful usage of EHR by healthcare providers.
Europe Electronic Health Record Apps Market Trends
The Europe market is anticipated to grow significantly over the forecast period. The presence of developed economies such as Germany, the UK, France, Spain, and Italy is expected to fuel the market in Europe during the forecast period. Strong regulatory frameworks, widespread digitalization initiatives, and substantial investments in healthcare IT are favorable for market growth. Additionally, robust support from governmental bodies and increasing awareness of digital health benefits contribute to Europe's significant role in expanding the market.
The UK electronic health record apps market is expected to grow significantly over the forecast period. This can be attributed to the country's healthcare sector rapidly digitizing, supported by government initiatives and increased healthcare expenditure. The National Health Service (NHS) is committed to digitizing patient records and driving the adoption of electronic health records and related platforms.
Electronic health record apps market in Germany is expected to grow at a substantial pace over the forecast period. This is attributed to the goal of having 80% of statutorily insured patients using EHRs by 2025, the Federal Ministry of Health is focusing on key initiatives. This includes developing telematics infrastructure, implementing an opt-out principle for EHRs, and establishing a competence center for digitization and care, ensuring a robust expansion of EHR apps adoption across the country.
Asia Pacific Electronic Health Record Apps Market Trends
Asia Pacific market is expected to witness the fastest growth during the forecast period. Healthcare organizations are focusing on deliv ering quality healthcare treatment for patients amid resource and cost restraints. Such factors are fueling the incorporation of smart technologies, such as EHRs, which can leverage integration and interoperability. This region’s growth can also be attributed to R&D investments specifically in the field of AI to produce technologically advanced healthcare solutions.
Japan electronic health record apps market is expected to grow significantly over the forecast period. The country's healthcare system is shifting towards digitization, with the government promoting the adoption of EHRs. The market players are involved in strategic development activities, including new product launches, strategic collaborations, and regional expansion for instance, in January 2023, Fujitsu and Sapporo Medical University collaborated to develop EHR systems. With this collaboration, Fujitsu is expected to develop a mobile app that enables users to view healthcare data on their iPhones.
India electronic health record apps market is expected to witness the fastest growth during the forecast period. This is attributed due to the Government of India enhancing digital health through initiatives like the Integrated Health Information Platform (IHIP). Significant investments in healthcare IT infrastructure aim to create standard compliant EHRs, ensuring integration and interoperability. This initiative seeks to reduce healthcare costs, involve patients in care management, and optimize information exchange for better health outcomes.
Latin America Electronic Health Record Apps Market Trends
Latin America market is anticipated to grow significantly over the forecast period. Major countries contributing to the growth of the market are Brazil and Argentina. Rapid economic growth in these countries is one of the key factors propelling growth during the forecast period.
Brazil electronic health record apps market is expected to grow significantly over the forecast period. The country has made significant progress in digitizing its healthcare system, with the number of primary care units using EHR systems increasing by 61% from 2016 to 2019 according to the OECD. Key factors driving this growth include government initiatives to promote EHR adoption, rising demand for digital health solutions, and increasing use of ICT devices.
MEA Electronic Health Record Apps Market Trends
The market is comparatively underdeveloped in the Middle East and Africa. The market is hindered by the lack of affordability and availability of EHR systems in countries including Turkey and Kuwait. However,the Saudi Arabian government has undertaken various efforts to implement IT systems in the healthcare sector. Several hospitals in the country use these information systems to improve patient care. Improvements in the healthcare sector and an increase in the integration of IT in healthcare are expected to drive the market growth during the forecast period.
South Africa electronic health record apps market is growing at a slower pace, majorly due to lack of established healthcare infrastructure and awareness regarding technological advancements. Although the South African market is in the nascent stage, an increase in the adoption of IT in healthcare is expected in the coming years.
Key Electronic Health Record Apps Company Insights
The market is fragmented, with the presence of many country-level players. The key participants in the market are undertaking various strategic initiatives to expand their business footprint and gain a competitive edge in the global market. Some of the emerging players in the market include Quest Diagnostics Incorporated., AssureCare LLC, Qualifacts, Valant, ChiroTouch, and Practice Fusion, Inc.
Key Electronic Health Record Apps Companies
The following key companies have been profiled for this study on the electronic health record apps market.
-
Epic Systems Corporation.
-
Meditab
-
CompuGroup Medical
-
AdvancedMD, Inc.
-
eClinicalWorks
-
EverHealth Solutions Inc. (DrChrono)
-
Athenahealth
-
Oracle
-
Networking Technology, Inc.
-
Altera Digital Health Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Epic Systems Corporation, Oracle, Athenahealth, eClinicalWorks, CompuGroup Medical.)
- Focus on enterprise-wide electronic health record deployments, long-term contracts, and integrated healthcare ecosystems.
- Invest in AI-enabled clinical workflows, interoperability, cloud migration, and strategic partnerships with large health systems.
- Strong global brand recognition, extensive customer base, comprehensive product portfolio, and high interoperability capabilities.
- Robust R&D investments, regulatory compliance expertise, and strong integration with hospital information systems.
- High implementation and maintenance costs, lengthy deployment cycles, and complex system customization.
- Large-scale platforms may require significant staff training and dedicated IT resources.
Emerging Players (e.g., Meditab, AdvancedMD, Inc., EverHealth Solutions Inc. (DrChrono), Networking Technology, Inc., Altera Digital Health Inc.)
- Focus on cloud-native, mobile-first electronic health record solutions targeting physician practices and ambulatory care providers.
- Emphasize rapid implementation, subscription-based pricing, customization, and continuous product innovation.
- Agile product development, user-friendly interfaces, lower implementation costs, and flexible deployment models.
- Faster feature updates, strong customer support, and specialization in niche clinical and ambulatory workflows.
- Limited global presence, smaller customer base, and comparatively lower financial resources for large-scale expansion.
- Limited enterprise functionality and integration capabilities compared to leading electronic health record vendors.
Recent Developments
-
In February 2024, Oracle launched the Oracle Identity Governance integration for Oracle Health EHR, previously known as Cerner Millennium. This integration intended to empower healthcare institutions to oversee user access to EHR, synchronize data, and bolster security & operational effectiveness. The connector facilitates automated data exchange, streamlines provisioning processes, and aids in meeting regulatory standards.
-
In April 2023, eClinicalWorks integrated ChatGPT, cognitive services, and machine learning models into its EHR and Practice Management Solution. This integration aimed to enhance value for customers by leveraging advanced AI capabilities for improved functionality & efficiency.
-
In January 2022, athenahealth expanded its mobile EHR voice capabilities for healthcare providers. This voice assistant is designed to help healthcare professionals enhance the patient experience, improve documentation accuracy, and save time.
Electronic Health Record Apps Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 912.6 million
Market size value in 2026
USD 989.4 million
Revenue forecast in 2033
USD 1,885.2 million
Growth rate
CAGR of 8.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Epic Systems Corporation.; Meditab; CompuGroup Medical; AdvancedMD, Inc.; eClinicalWorks; athenahealth; Oracle; Networking Technology, Inc.; Altera Digital Health Inc.; Practice Fusion, Inc.; EverHealth Solutions Inc. (DrChrono)
Customization scope
Free report customization (equivalent to up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
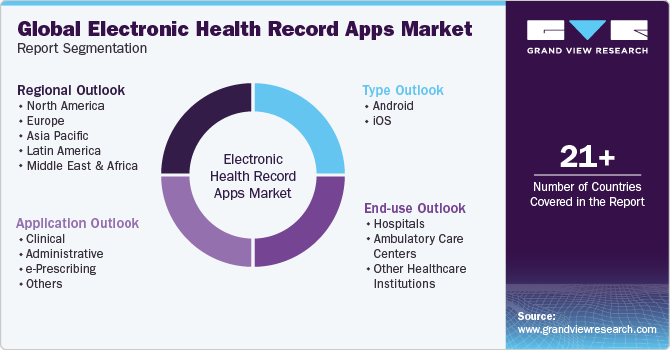
Global Electronic Health Record Apps Market Report SegmentationThis report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global electronic health record apps market report based on type, application, end-use, and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Android
-
iOS
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Clinical
-
Administrative
-
e-Prescribing
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Care Centers
-
Other Healthcare Institutions
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The electronic health record apps market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each electronic health record apps segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment
Revenue capture definition
By Type
Android
Android-based electronic health record apps are electronic health record applications designed to operate on Android smartphones and tablets. These apps enable healthcare professionals to securely access, update, and manage patient records while supporting mobility and real-time clinical workflows.
IOS
iOS-based electronic health record apps are electronic health record applications developed for Apple devices such as iPhones and iPads. They provide secure access to patient information, clinical documentation, and healthcare workflows within the Apple ecosystem.
By Application
Clinical
Clinical electronic health record apps support healthcare providers in managing patient care through features such as medical history documentation, clinical notes, diagnosis recording, treatment planning, and laboratory result access. These applications improve clinical decision-making and care coordination.
Administrative
Administrative electronic health record apps facilitate non-clinical healthcare operations, including patient registration, appointment scheduling, billing, insurance verification, and workflow management. They help streamline administrative processes and improve operational efficiency.
e-Prescribing
e-Prescribing electronic health record apps enable healthcare providers to create, transmit, and manage electronic prescriptions directly to pharmacies. These applications reduce prescription errors, improve medication safety, and enhance prescribing efficiency.
Others (Medical Image system,
voice recognition, reminders/alerts)
This segment includes electronic health record applications offering specialized functionalities such as medical image viewing, voice-enabled clinical documentation, automated reminders, alerts, and clinical decision support tools. These features enhance productivity, communication, and patient safety.
By End Use
Hospital
Hospitals use electronic health record apps to manage patient records, clinical documentation, medication administration, and multidisciplinary care across inpatient and outpatient departments. These applications improve care coordination, workflow efficiency, and regulatory compliance.
Ambulatory Care Centers
Ambulatory care centers utilize electronic health record apps to support patient documentation, appointment management, e-prescribing, and continuity of care for same-day and outpatient medical services. These apps enable efficient patient management without requiring hospitalization.
Others
The others segment includes physician clinics, specialty practices, diagnostic centers, long-term care facilities, rehabilitation centers, and home healthcare providers using electronic health record apps for patient record management and healthcare documentation.
Estimation Model
Model Details
The global Electronic Health Record (EHR) Apps market was estimated using a multi-layered analytical framework integrating EHR adoption rates, vendor revenues, and application-level penetration across healthcare providers. The methodology combines bottom-up and top-down approaches supported by extensive primary interviews and secondary research to estimate the market across platform, application, end user, and geography for the period 2021–2033.
The final market size was derived by triangulating four independent estimation models.
Model
Objective
Estimation Steps
Model 2: Company Revenue Extrapolation Model
Estimates the market using revenues generated by EHR app vendors.
Step 1: Identified major EHR app vendors through company reports, product portfolios, healthcare IT databases, and industry publications.
Step 2: Estimated revenues attributable to mobile EHR applications using financial statements, investor presentations, subscription data, and primary interviews.
Step 3: Adjusted revenues for private companies, regional vendors, deployment models, and geographic distribution.
Step 4: Estimated revenues from software licensing, SaaS subscriptions, premium mobile features, maintenance, and professional services.
Step 5: Aggregated company revenues to estimate country, regional, and global market values.
Step 6: Forecast incorporated customer expansion, AI-enabled features, interoperability enhancements, and recurring SaaS revenue growth.Model 3: EHR Market Derivation Model
Estimates the EHR apps market as a subset of the broader Electronic Health Record market.
Step 1: Established the size of the overall Electronic Health Record (EHR) market across key regions using published market data, company disclosures, procurement databases, and healthcare IT reports.
Step 2: Estimated the proportion of EHR spending attributable to mobile EHR applications based on application penetration, mobile user adoption, healthcare workforce mobility, and vendor product portfolios.
Step 3: Applied regional penetration rates across hospitals, physician practices, and ambulatory care centers.
Step 4: Derived country-level EHR app revenues from the broader EHR market using platform-specific adoption ratios.
Step 5: Aggregated estimates to regional and global market values.
Step 6: Forecast assumptions incorporated increasing smartphone usage among clinicians, BYOD adoption, cloud-native EHR platforms, and mobile-first healthcare strategies.Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Digital Health Adoption & User Base Analysis
Developed a comprehensive assessment of EHR app adoption across healthcare providers, patients, and administrative users. The study evaluates active user base, digital maturity, healthcare IT penetration, mobile health adoption, and regional differences in EHR utilization across hospitals, clinics, and ambulatory care settings.
Enables stakeholders to identify high-growth digital health markets, prioritize customer segments, and align commercialization strategies with regions demonstrating strong healthcare IT adoption and digital transformation initiatives.
Technology & Platform Innovation Assessment
Evaluated emerging innovations in EHR applications, including AI-assisted clinical documentation, voice recognition, predictive analytics, cloud-native architecture, mobile-first platforms, cybersecurity enhancements, and generative AI-enabled clinical decision support.
Identifies future technology investment opportunities, supports product roadmap development, enhances platform differentiation, and strengthens competitive positioning in the evolving digital healthcare ecosystem.
Competitive Benchmarking & Vendor Ecosystem Analysis
Benchmarked leading EHR app providers based on platform capabilities, deployment models, pricing strategies, interoperability features, regulatory compliance, user experience, partnerships, and innovation initiatives across key regional markets.
Enables stakeholders to benchmark competitors, identify strategic partnership opportunities, evaluate market gaps, and develop effective go-to-market and product expansion strategies.
Frequently Asked Questions About This Report
The global electronic health record apps market size was estimated at USD 912.6 million in 2025 and is projected to grow from USD 989.4 million in 2026.
The global electronic health record apps market is expected to grow at a compound annual growth rate of 8.3% from 2026 to 2033 to reach USD 1,885.2 million by 2033.
The android segment led with a 85.7% revenue share in 2025, and is the fastest-growing segment.
Some key players operating in the electronic health record apps market include Epic Systems Corporation., Meditab, CompuGroup Medical, AdvancedMD, Inc., eClinicalWorks, athenahealth, Oracle, Networking Technology, Inc., Altera Digital Health Inc., Practice Fusion, Inc., EverHealth Solutions Inc. (DrChrono)
North America dominated electronic health records apps market with the largest revenue share of 38.5% in 2025
Asia Pacific is the fastest-growing region over the forecast period.
The administrative segment led with a 32.5% revenue share in 2025, and clinical is the fastest-growing segment.
The hospital segment led with a 53.0% revenue share in 2025, and ambulatory care centers is the fastest-growing segment.
Key factors that are driving the EHR apps market growth include rising demand of health and medical apps for smartphones, increasing use of mobile device for accessing healthcare data, and technological advancement.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


