
- Home
- »
- Next Generation Technologies
- »
-
Enterprise Generative AI Market Size & Share Report, 2033GVR Report cover

Enterprise Generative AI Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Software, Services), By Model Type (Text, Image, Audio, Code), By Application, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$3.9BMarket Estimate, 2026
$5.2BMarket Forecast, 2033
$61.5BCAGR, 2026–2033
42.9%Enterprise Generative AI Market Summary
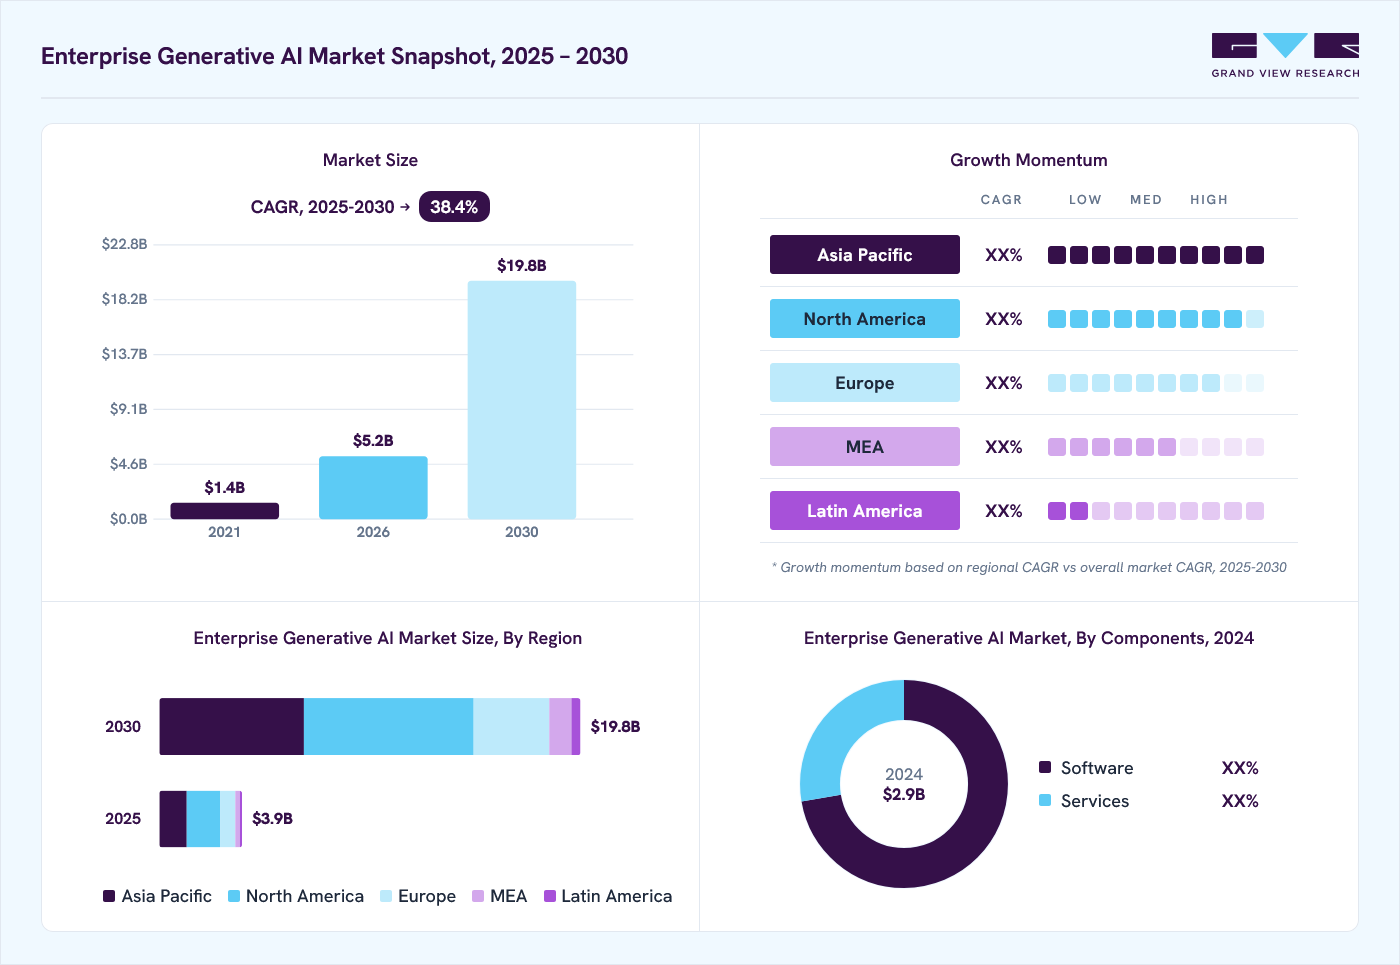
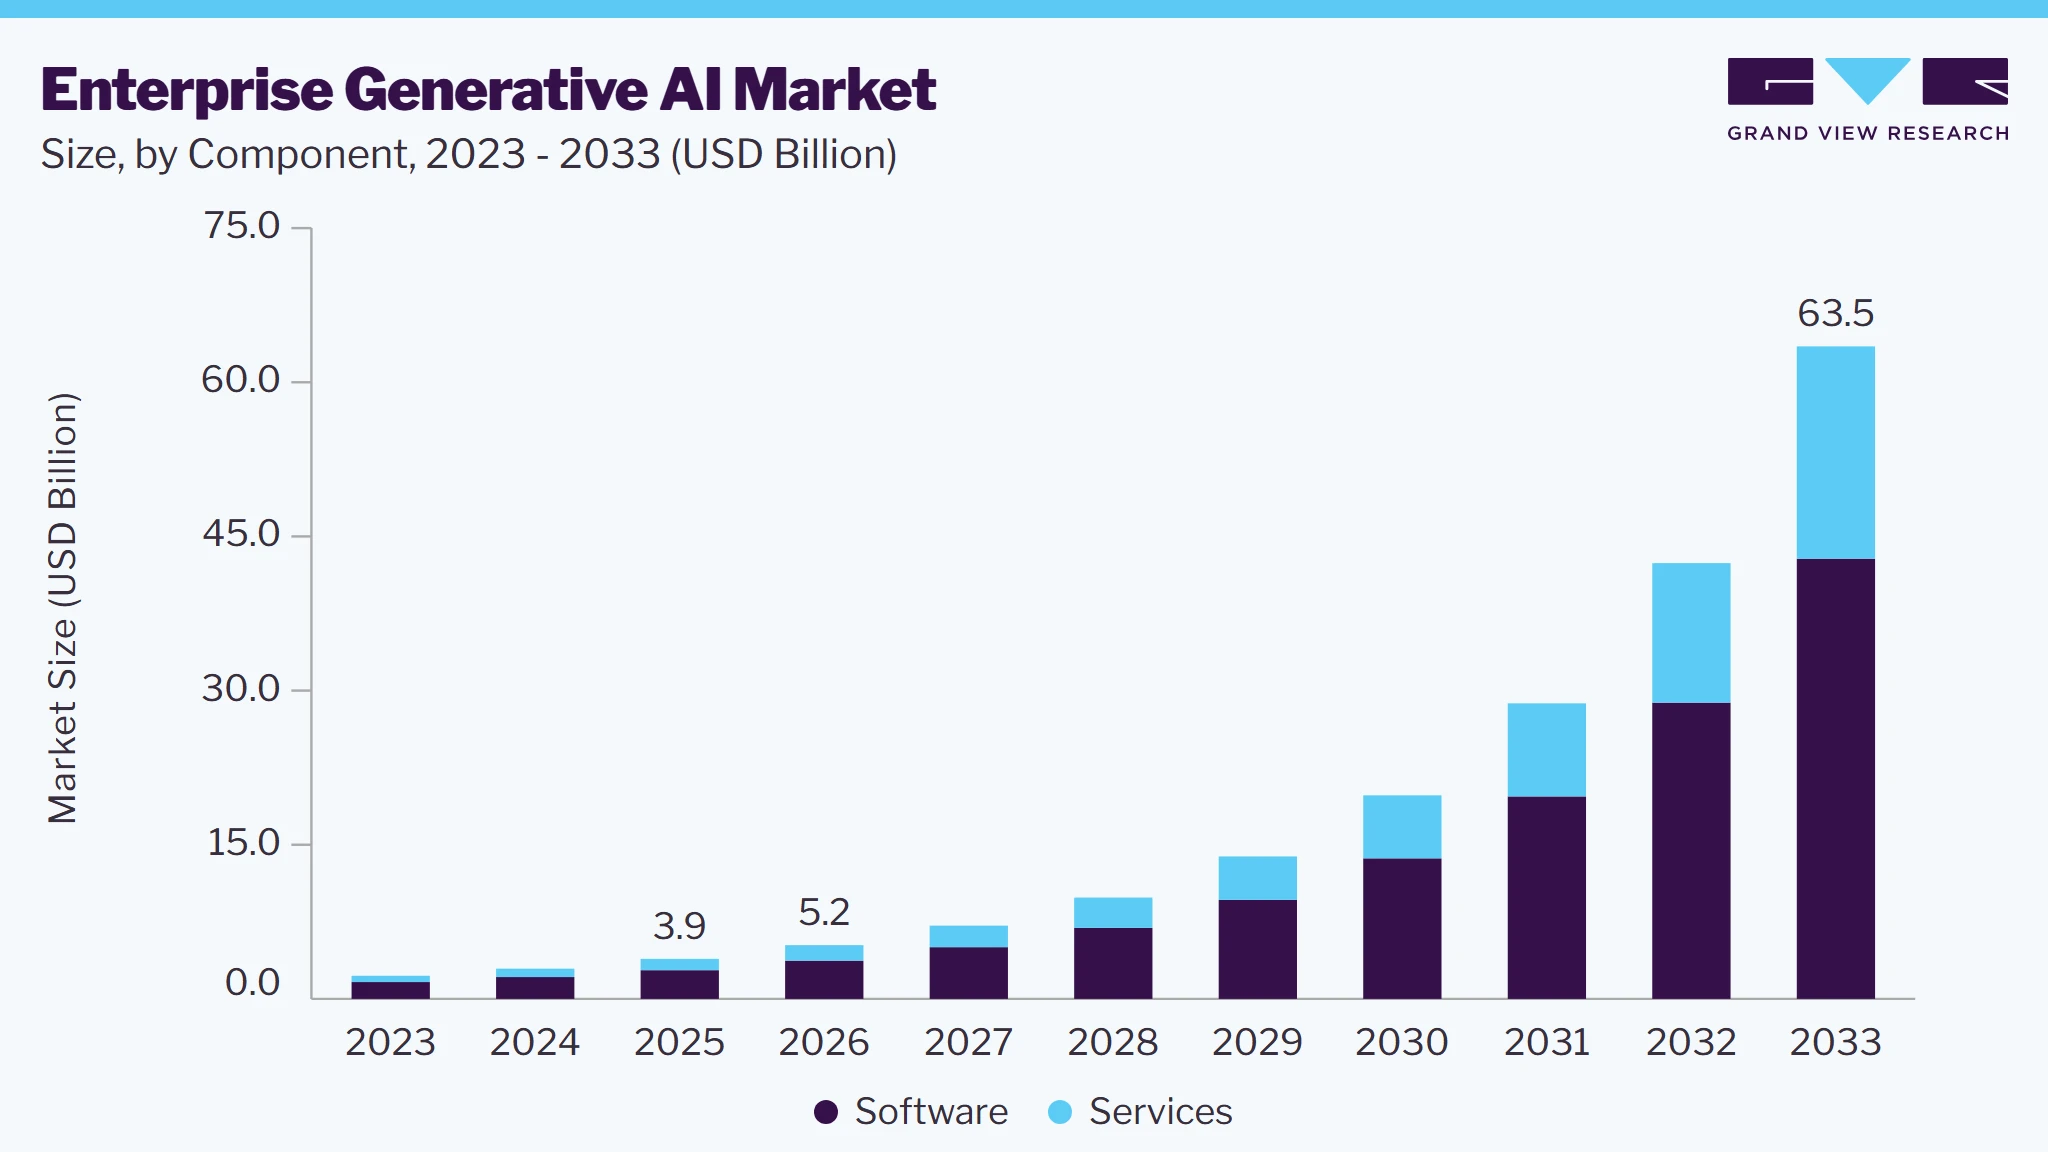
The global enterprise generative AI Market size was valued at USD 3.9 billion in 2025 and is projected to grow from USD 5.2 billion in 2026 to USD 63.5 billion by 2033, at a CAGR of 42.9 % from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.2% in 2025. The enterprise generative AI sector is experiencing significant growth, marked by an increasing number of startups entering the field.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Software segment led the market with the largest revenue share of 71.7% in 2025.
- By model type: Text segment led the market with the largest revenue share of 39.3% in 2025.
- By end-use: IT & Telecom segment led the market with the largest revenue share of 31.1% in 2025.
- By application: Marketing and Sales segment led the market with the largest revenue share of 32.5% in 2025.
Regional Highlights
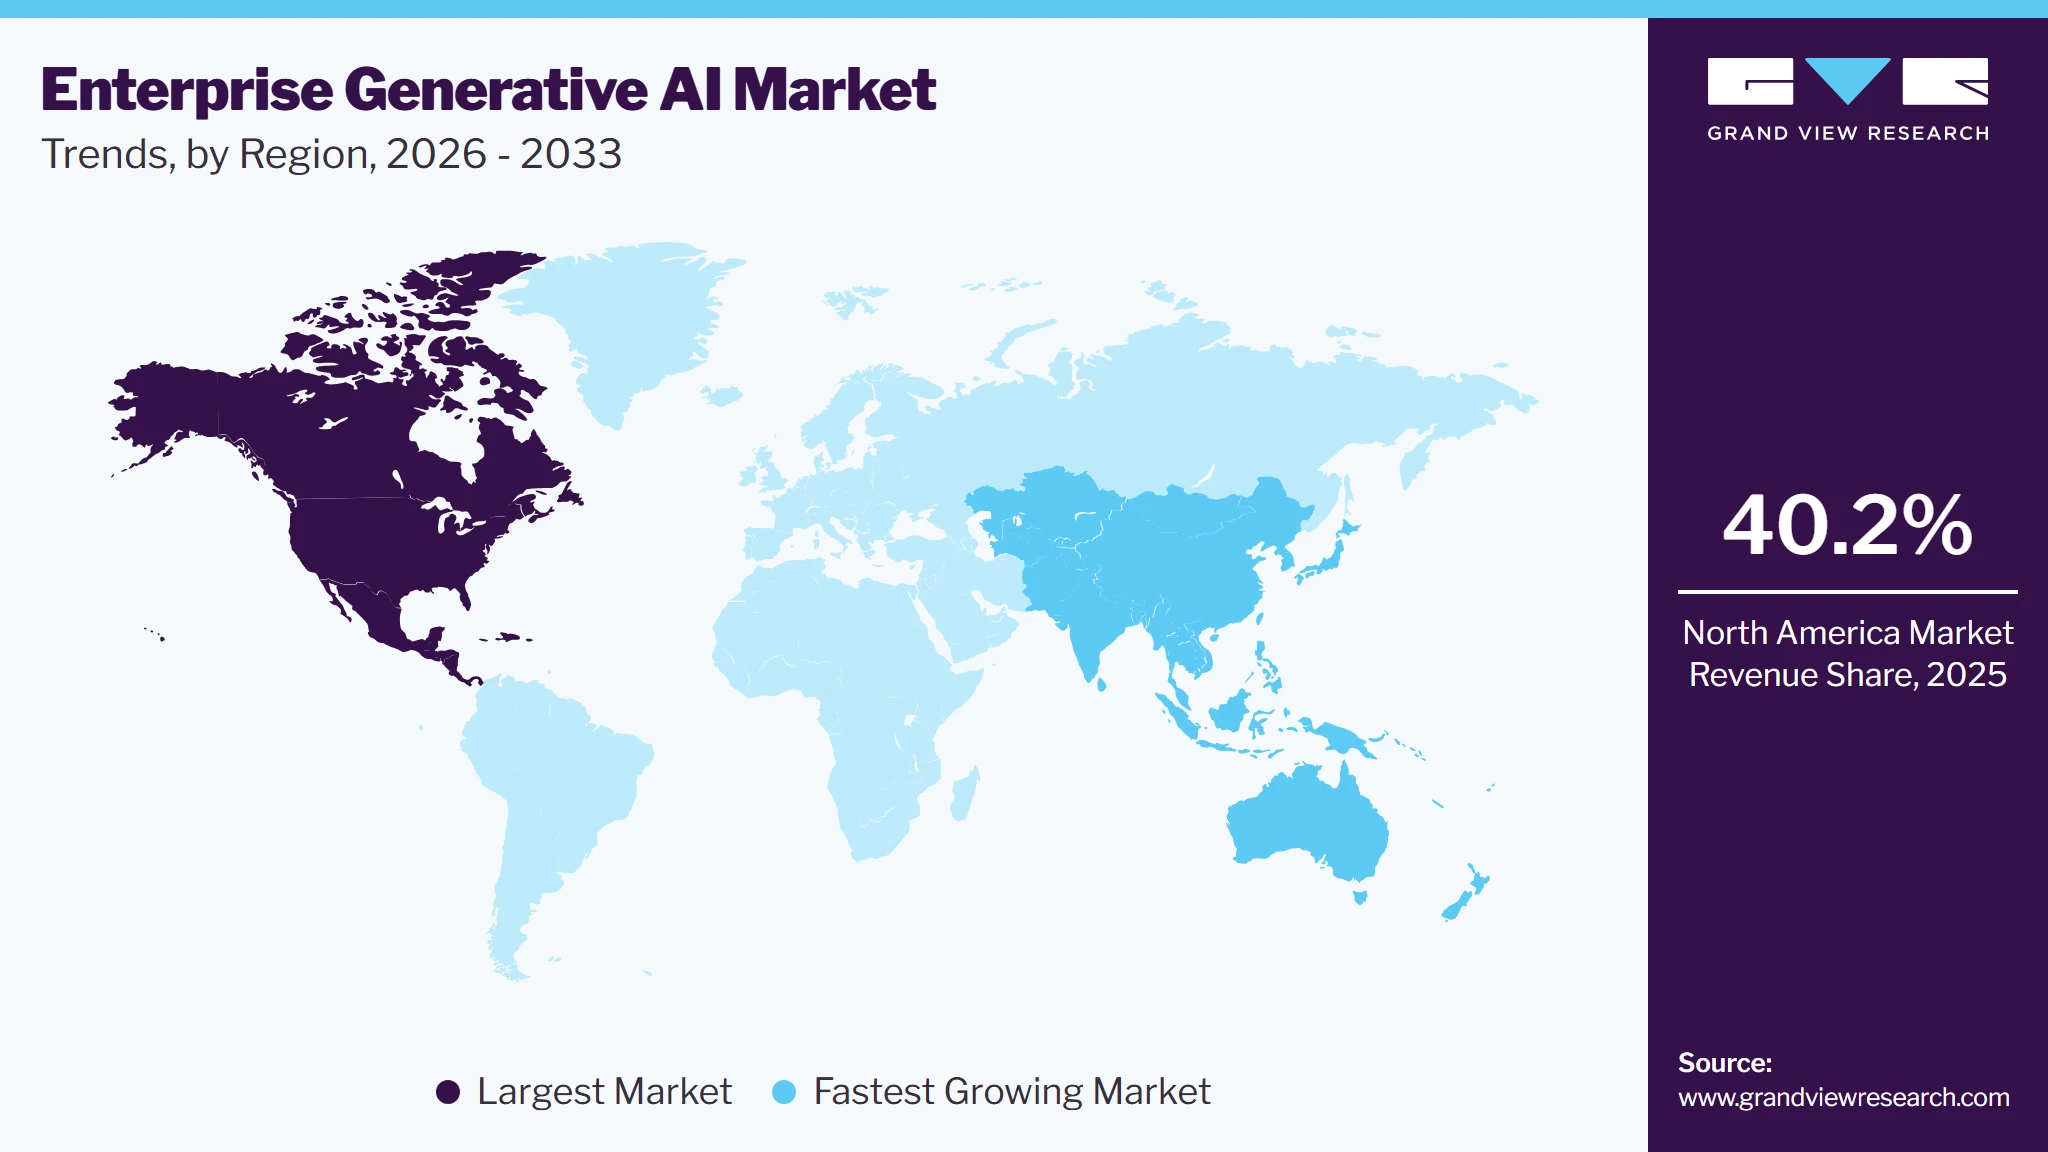
- Largest regional market: North America (40.2% revenue share, 2025)
- Fastest regional market: Asia Pacific (Highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.9 Billion
- Estimated market size in 2026: USD 5.2 Billion
- Projected market size by 2033: USD 63.5 Billion
- CAGR (2026-2033): 42.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The region's leadership is attributed to the strong presence of leading AI technology providers, cloud service companies, and enterprise software vendors, coupled with the rapid adoption of generative AI across industries such as banking, healthcare, retail, manufacturing, IT & telecommunications, and professional services. Enterprises are increasingly investing in generative AI solutions to automate business processes, enhance customer engagement, improve software development, accelerate content generation, and support data-driven decision-making.
These companies are focusing on various aspects of quantum technology, including hardware, software, and diverse applications. Moreover, there has been a notable rise in investments within the enterprise generative AI market, with both private sectors and governments contributing substantial funding. Governments, in particular, are dedicating significant resources to advancing quantum research and development, with the aim of remaining competitive in the rapidly evolving landscape of emerging technologies.
 To learn more about this report, Download Free Sample Report
The utilization of enterprise generative AI has surged due to its ability to create realistic images, engaging animations, and immersive audio, particularly benefiting graphic design and video marketing efforts. This technology has also become invaluable in streamlining administrative tasks such as claims processing, appointment scheduling, and overall operational management. Its adaptability and effectiveness make it an indispensable tool across various industries. The emergence and adoption of enterprise-ready generative AI models are on the rise, with platforms such as Google Cloud’s Vertex AI integrating these solutions. As these advancements continue, business leaders are discovering that generative AI can drive their organizations to unprecedented levels of speed, scalability, and execution efficiency.
Businesses are progressively embracing industry-tailored generative AI solutions. For instance, in October 2024, Wipro Limited, an Indian IT company, partnered with NVIDIA Corporation to utilize its AI technologies, including generative AI, through WeGA Studio and NIM Agent Blueprints. This partnership aims to create customized solutions for customer service, healthcare, and supply chain management. In healthcare, AI models support the analysis of medical images, facilitating the diagnosis and treatment strategies. Likewise, financial sectors benefit from AI algorithms aiding in assessing risks and detecting fraudulent activities. Retail industries rely on AI for customized product suggestions and managing inventory effectively. This trend encompasses the customization of AI models to tackle sector-specific hurdles, enhancing operational efficiencies, and outcomes while complying with industry regulations.
Market Dynamics
The enterprise generative AI market is witnessing substantial growth, driven by the rapid proliferation of artificial intelligence (AI) and machine learning (ML) applications across consumer electronics, automotive, healthcare, industrial automation, telecommunications, and cloud computing. As AI models become increasingly complex and computationally intensive, organizations are adopting dedicated neural processors, including Neural Processing Units (NPUs) and AI accelerators, to deliver high-performance computing with lower power consumption and minimal latency. The growing adoption of edge AI, generative AI, computer vision, natural language processing (NLP), robotics, and autonomous systems is significantly increasing demand for specialized AI hardware. Additionally, continuous advancements in semiconductor technology, heterogeneous computing architectures, and on-device AI capabilities are accelerating market expansion. However, high semiconductor development costs, manufacturing complexities, and supply chain challenges remain key constraints. Despite these challenges, increasing investments in edge computing, AI-enabled consumer devices, autonomous mobility, and intelligent industrial systems are expected to create significant growth opportunities during the forecast period.
The enterprise generative AI market is experiencing robust growth owing to the increasing demand for dedicated AI acceleration across edge and cloud computing environments. Neural processors enable faster execution of AI workloads while delivering superior energy efficiency compared to traditional CPUs and GPUs for inference-intensive applications. The rapid integration of NPUs into smartphones, AI-enabled PCs, autonomous vehicles, robotics, surveillance systems, healthcare devices, and industrial IoT equipment is driving widespread adoption. Furthermore, the growing deployment of generative AI, computer vision, speech recognition, large language models (LLMs), and real-time analytics is encouraging semiconductor manufacturers to develop advanced neural processing architectures capable of supporting increasingly sophisticated AI workloads while minimizing latency and power consumption.
Despite strong growth prospects, the enterprise generative AI market faces several challenges associated with designing and manufacturing next-generation AI processors. Developing advanced neural processors requires substantial investments in research and development, access to leading-edge semiconductor fabrication technologies, and sophisticated chip design expertise. In addition, dependence on advanced foundries, limited fabrication capacity, supply chain disruptions, and geopolitical uncertainties continue to impact production and component availability. Rapid advancements in AI algorithms and evolving software frameworks also require continuous hardware optimization, increasing product development complexity and time-to-market for semiconductor vendors.
The rapid expansion of on-device AI and edge computing is creating significant opportunities for the Neural Processor Market. Increasing consumer demand for intelligent smartphones, AI PCs, wearable devices, smart home systems, autonomous drones, robotics, and connected industrial equipment is accelerating the integration of dedicated neural processors capable of executing AI workloads locally. On-device AI enables enhanced privacy, lower latency, reduced cloud dependency, and improved energy efficiency, making neural processors essential for next-generation intelligent devices. Moreover, growing investments in Industry 4.0, autonomous transportation, smart healthcare, edge data centers, and multimodal generative AI applications are expected to drive sustained demand for high-performance neural processors, creating substantial long-term growth opportunities for market participants.
Market Concentration & Characteristics
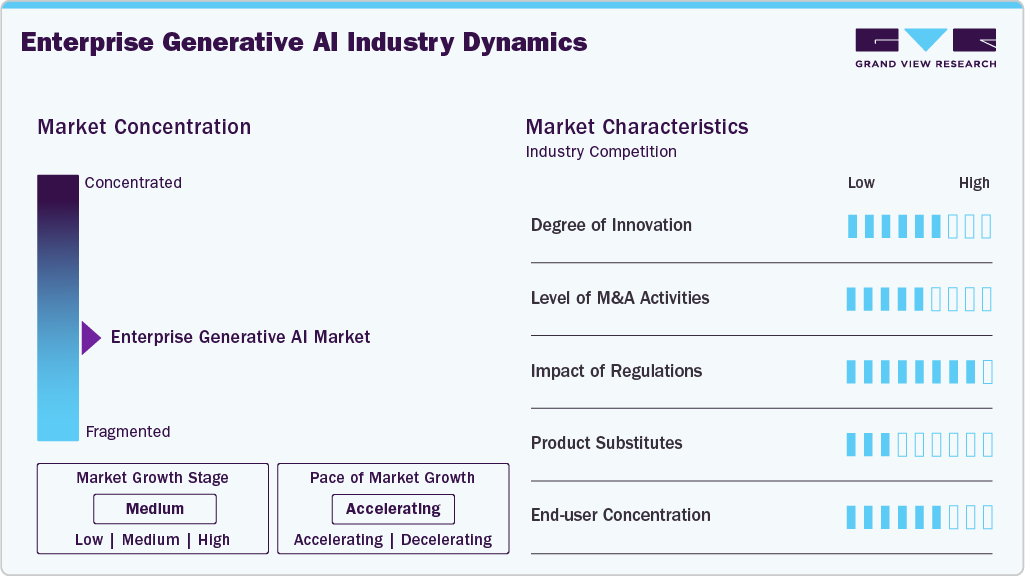
The enterprise generative AI Market is moderately concentrated, with competition driven by leading cloud service providers, enterprise software companies, AI platform developers, and specialized generative AI solution providers. Market participants compete on the basis of foundation model capabilities, enterprise-grade security, scalability, cloud integration, model customization, multimodal AI capabilities, and seamless integration with existing enterprise workflows. Continuous investments in large language models (LLMs), retrieval-augmented generation (RAG), AI agents, responsible AI frameworks, and industry-specific generative AI applications are reshaping the competitive landscape. Strategic partnerships, product innovations, acquisitions, and investments in AI infrastructure and cloud ecosystems are further strengthening market competitiveness.
 To learn more about this report, Download Free Sample Report
Key market participants include AWS Inc., Google LLC, H2O.ai, IBM Corporation, Intel Corporation, Jasper.ai, Microsoft Corporation, NVIDIA Corporation, OpenAI, Oracle Corporation, and Synthesis AI. These companies are focused on expanding their enterprise generative AI portfolios through advanced foundation models, AI development platforms, cloud-based AI services, enterprise copilots, synthetic data generation, and AI infrastructure solutions. Their strategies emphasize enhancing model accuracy, improving data privacy and governance, enabling secure enterprise deployments, optimizing AI performance, and strengthening collaborations across cloud, software, and industry ecosystems to accelerate enterprise AI adoption worldwide.
Analyst Perspective
The Enterprise Generative AI Market is rapidly evolving into a critical enabler of enterprise digital transformation, driven by the growing demand for intelligent automation, enhanced productivity, and data-driven decision-making across industries. Organizations are increasingly adopting generative AI to automate content creation, software development, customer engagement, knowledge management, and business process optimization, enabling significant improvements in operational efficiency and innovation. The widespread availability of large language models (LLMs), multimodal AI, AI agents, and retrieval-augmented generation (RAG) technologies, combined with scalable cloud infrastructure, is accelerating enterprise adoption across both large enterprises and small and medium-sized businesses.
The market is further supported by continuous advancements in foundation models, responsible AI frameworks, enterprise-grade security, and seamless integration with existing business applications. As organizations prioritize AI-powered transformation, investments in generative AI platforms, cloud services, AI infrastructure, and industry-specific solutions are expected to increase significantly. Looking ahead, the growing adoption of AI copilots, autonomous AI agents, multimodal enterprise applications, and customized foundation models will position enterprise generative AI as a strategic technology, creating substantial opportunities for innovation, competitive differentiation, and long-term market growth throughout the forecast period.
Components Insights
Based on component, the software segment led the market with the largest revenue share of 71.7% in 2025. In the software sector of enterprise generative AI market, there's a clear trend towards an expanding range of specialized tools and platforms designed for specific business needs. These offerings cover various functions, including generating text, creating images, and specialized creative design applications. Both new startups and established companies are dedicated to developing adaptable software solutions to meet the distinct requirements of enterprises in different industries. For instance, in February 2024, Google LLC launched Gemini Business and Gemini Enterprise to provide businesses with customized AI software solutions to enhance productivity and drive growth. These plans offer specialized tools designed to meet the specific needs of organizations, enabling more effective utilization of generative AI.
The increase in the demand for Enterprise Generative AI within the service sector revolves around the rising presence of consulting firms and service providers offering specialized skills in implementing Generative AI solutions customized for enterprises. These services encompass guiding strategies, evaluating potential applications, and actively assisting during the implementation phase. Businesses are increasingly seeking this support to navigate the intricate process of effectively integrating Generative AI into their day-to-day operations, aiming to achieve peak efficiency and gain a competitive edge. Consulting firms play a pivotal role by sharing valuable insights and best practices, ensuring that businesses harness the full potential of Generative AI while staying aligned with their specific business goals.
Model Type Insights
Based on model type, the text segment led the market with the largest revenue share of 39.3% in 2025. The rise of customized language models customized to specific industries is driving innovation in enterprise generative AI, with a focus on enhancing text generation, comprehension, and ensuring data privacy. For instance, in July 2024, Fujitsu and Cohere, a U.S.-based artificial intelligence company, partnered to develop Takane, a Japanese language model for private cloud use, providing secure generative AI solutions for enterprises. This collaboration combines Fujitsu's AI expertise with Cohere’s advanced language models to boost productivity in industries such as finance and government.
The audio segment is projected to experience the fastest growth rate from 2025 to 2033. This growth is driven by advancements in speech recognition and natural language processing technologies. Increased adoption of voice-activated devices and applications across industries is contributing to the surge in demand for audio-based AI solutions. As a result, businesses are increasingly integrating audio-focused generative AI to enhance user experiences and streamline operations. Furthermore, the growing popularity of podcasts, audiobooks, and virtual assistants is also fueling the demand for audio AI innovations.
Application Insights
Based on application, the Marketing and Sales segment led the market with the largest revenue share of 32.5% in 2025. This dominance is driven by the increasing adoption of generative AI to personalize customer experiences and optimize marketing strategies. Businesses are utilizing AI to automate content creation, improve customer engagement, and deliver targeted advertising more efficiently. Moreover, AI-powered tools are enhancing sales forecasting, lead generation, and customer insights, which are crucial for driving revenue growth. As a result, companies are increasingly investing in AI-driven marketing and sales solutions to maintain a competitive edge.
The advancement of generative AI is transforming customer service by enhancing the analysis of sentiments and emotion recognition in customer interactions. Utilizing advanced natural language processing and machine learning techniques, these AI systems can decode the complexities of customer emotions conveyed through both text and speech. By accurately understanding customer sentiments, companies can tailor their responses and support to meet individual needs, providing more empathetic and personalized experiences. This leads to greater customer satisfaction and fosters increased loyalty.
End Use Insights
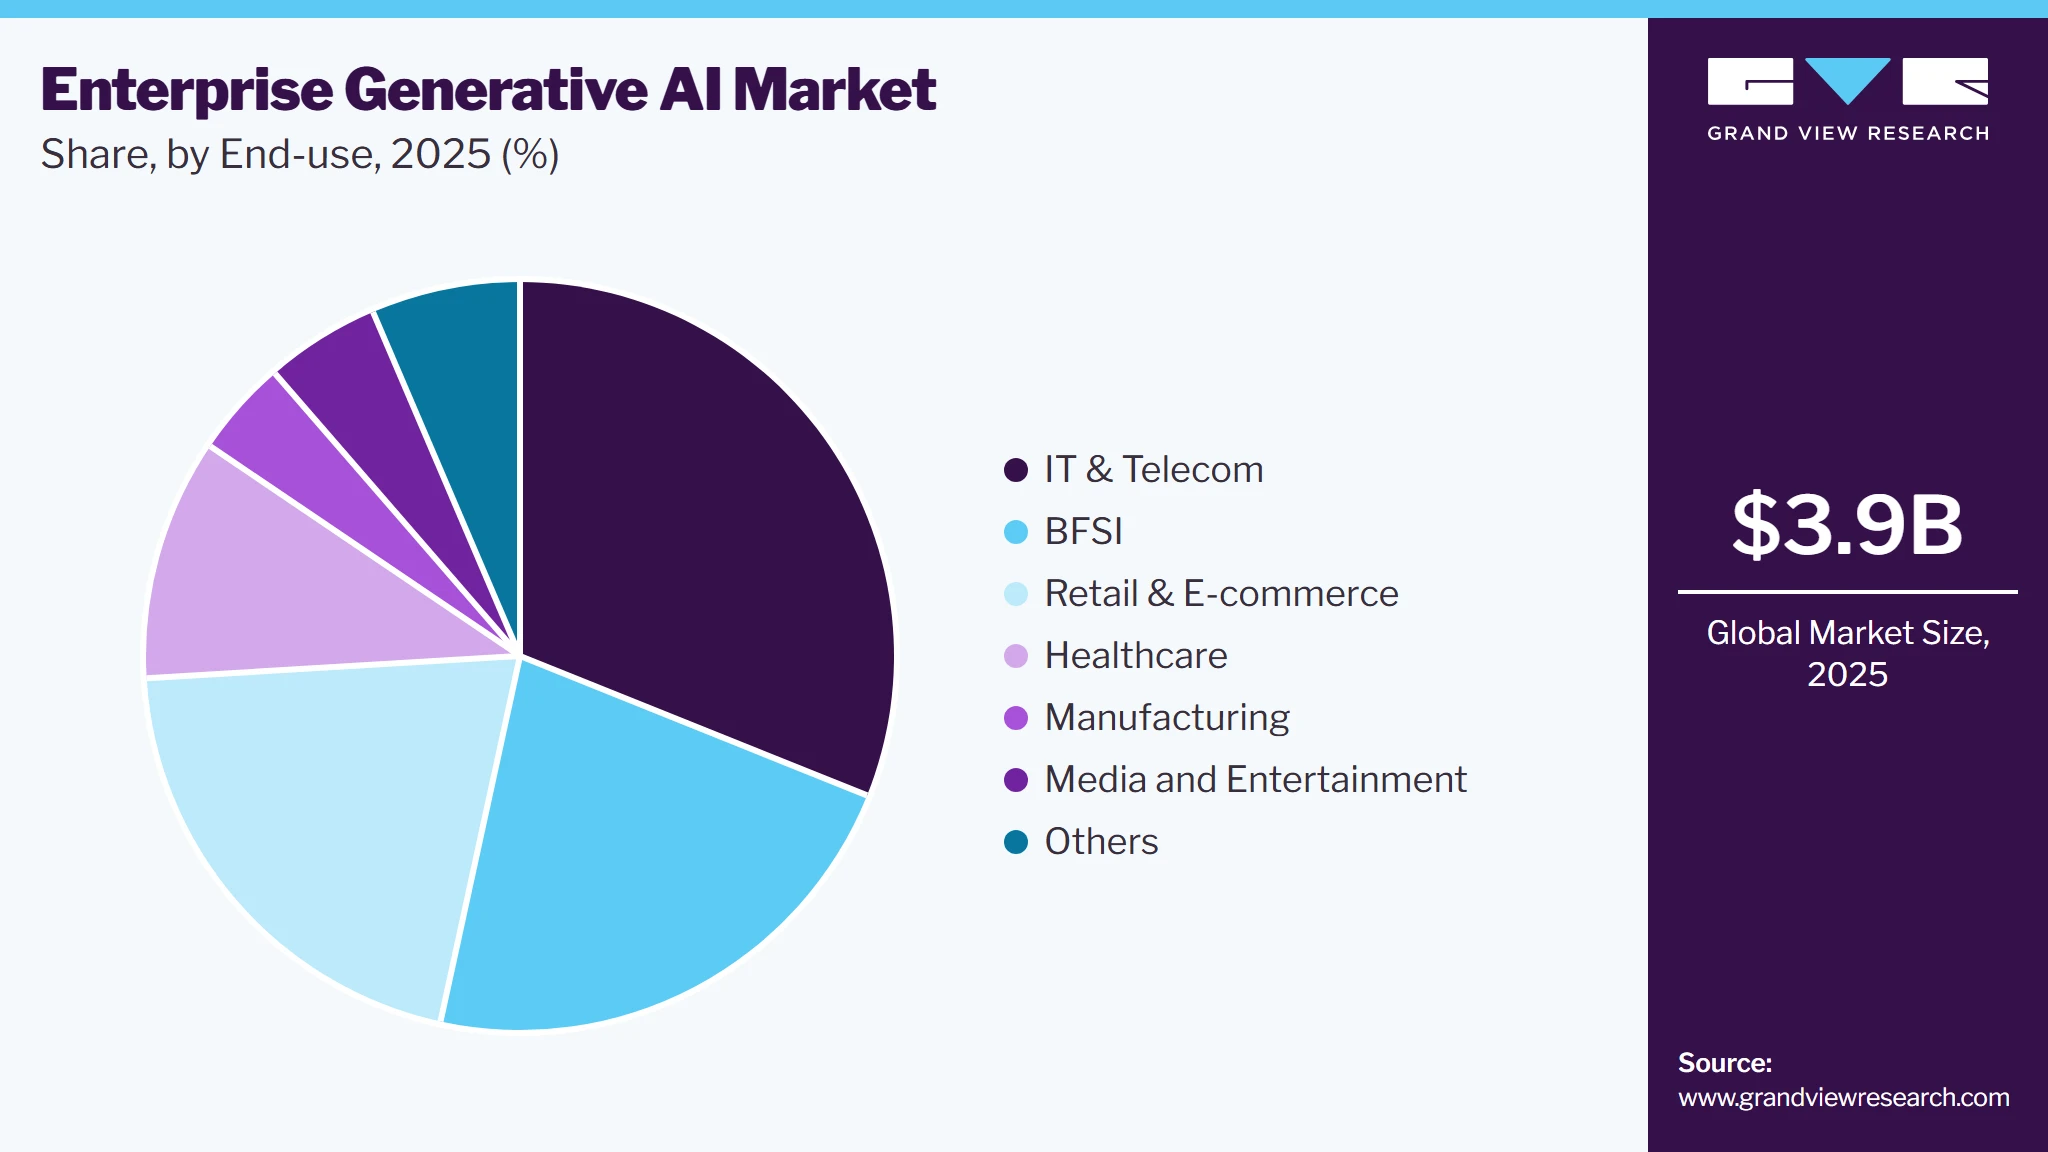
Based on end-use, the IT & Telecom segment led the market with the largest revenue share of 31.1% in 2025, driven by the growing adoption of generative AI in network optimization, customer support, and automation. For example, telecom companies are using AI-powered chatbots for customer service, automating routine inquiries, and improving response times. Moreover, AI is being utilized to enhance network management by predicting failures and optimizing performance, reducing operational costs. As a result, the IT & Telecom sector is increasingly integrating generative AI to improve efficiency, customer experience, and overall service quality. Furthermore, AI's ability to handle large-scale data analysis enables telecom providers to deliver real-time insights and make informed decisions.
 To learn more about this report, Download Free Sample Report
The Retail & E-commerce segment is witnessing significant growth in the adoption of generative AI, driven by the need for personalized customer experiences and efficient operations. AI is being used to enhance product recommendations, customer service, and inventory management by analyzing consumer behavior and preferences. Moreover, generative AI tools are simplifying content creation for marketing, allowing retailers to generate product descriptions, ads, and promotional content more efficiently. E-commerce platforms are utilizing AI to automate pricing strategies and optimize supply chains, reducing costs and improving customer satisfaction.
Regional Insights
North America dominated the enterprise generative AI market with the largest revenue share of 40.2% in 2025, due to the presence of major technology companies such as OpenAI, Microsoft, and Google LLC, which are driving innovation in AI applications. The region benefits from robust research and development investments, particularly in the U.S., where AI adoption is accelerating across various industries. Sectors such as healthcare, finance, and media are increasingly leveraging generative AI for tasks such as drug discovery, fraud detection, and content creation, further boosting market growth. With strong infrastructure and a growing number of startups, North America continues to lead in the development and deployment of generative AI technologies across enterprises.
 To learn more about this report, Download Free Sample Report
U.S. Enterprise Generative AI Market Trends
The enterprise generative AI market in the U.S. held the largest share in the North America region in 2025. The U.S. enterprise generative ai market is characterized by widespread adoption of generative AI across industries such as technology, finance, healthcare, and entertainment. Major tech hubs such as Silicon Valley and Seattle are home to leading AI companies and startups that drive innovation in the field. The integration of generative AI with cloud computing services from giants such as Amazon Web Services (AWS) and Microsoft Azure enables scalable and efficient deployment of AI solutions. In addition, strong collaboration between academia and industry fosters continuous advancements in generative AI research and applications, further accelerating the market's growth.
Europe Enterprise Generative AI Market Trends
Europe's enterprise generative AI market is experiencing steady growth, driven by stringent data privacy regulations and a focus on ethical AI development. Countries such as Germany, the UK, and France are leading the adoption of generative AI technologies in sectors such as manufacturing, automotive, and the creative industries. The European Union's initiatives to establish a unified AI strategy and increase funding for AI research are key drivers of market expansion. Furthermore, the emphasis on sustainable and responsible AI practices encourages enterprises to implement generative AI solutions that comply with regulatory standards and meet societal expectations.
Asia Pacific Enterprise Generative AI Market Trends
The Asia Pacific region is experiencing the fastest growth in the enterprise generative AI market, fueled by rapid digital transformation, increasing investments in AI technologies, and the expanding presence of technology giants in countries such as China, Japan, South Korea, and India. The widespread adoption of mobile technologies and the growing e-commerce sector in the region present significant opportunities for generative AI applications in personalized marketing, customer service, and content generation. Government initiatives that promote AI research and development, along with a thriving startup ecosystem, further accelerate market expansion. These factors collectively contribute to the region's strong growth and adoption of generative AI technologies across industries.
Key Enterprise Generative AI Company Insights
The industry is characterized by fierce competition, dominated by a few major global players who possess significant market control. The focus revolves around developing groundbreaking products and promoting cooperation among key players within the industry. For instance, in April 2024, Microsoft, a U.S.-based technology company and Cognizant extended their partnership to deploy Microsoft's generative AI and Copilots, enhancing business operations and accelerating innovation in various industries. This initiative includes significant investments in AI training and technology for sectors such as healthcare, retail, and financial services.
Similarly, in September 2024, Cloudera collaborated with Amazon Web Services (AWS) to advance reliable enterprise generative AI. This collaboration enables Cloudera to utilize AWS offerings, aiming to provide ongoing advancements and cost reductions for customers utilizing Cloudera's open data lake house on AWS, specifically designed for trusted enterprise generative AI. Cloudera has opted for AWS to operate essential elements of the Cloudera Data Platform (CDP), encompassing aspects such as the data lake, data warehouse, operational database, artificial intelligence/machine learning capabilities, master data management, and comprehensive security measures.
Key Enterprise Generative AI Companies:
The following key companies have been profiled for this study on the enterprise generative AI market.
-
AWS Inc.
-
Google LLC
-
H20.ai
-
IBM Corporation
-
Intel Corporation
-
Jasper.ai
-
Microsoft Corporation
-
Nvidia Corporation
-
OpenAI
-
Oracle Corporation
-
Synthesis AI
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players: AWS Inc.; Google LLC; IBM Corporation; Intel Corporation; Microsoft Corporation; NVIDIA Corporation; OpenAI; Oracle Corporation
Focus on expanding enterprise generative AI capabilities through foundation models, cloud AI platforms, enterprise copilots, AI infrastructure, and industry-specific AI solutions. These companies invest heavily in large language models (LLMs), AI infrastructure, responsible AI frameworks, cloud ecosystems, and strategic partnerships to accelerate enterprise AI adoption across industries.
Strong global presence, extensive cloud infrastructure, advanced AI research capabilities, comprehensive enterprise software portfolios, large customer bases, robust partner ecosystems, significant R&D investments, and the ability to deliver scalable and secure AI solutions.
High infrastructure and model development costs, increasing regulatory and compliance requirements, growing competition in foundation models, dependence on high-performance computing resources, concerns related to AI governance and data privacy, and the need for continuous innovation to maintain market leadership.
Emerging Players: H2O.ai; Jasper.ai; Synthesis AI
Focus on developing specialized enterprise generative AI applications, including AI-powered content generation, synthetic data creation, no-code AI platforms, and domain-specific AI solutions. These companies emphasize innovation, ease of deployment, model customization, and enterprise-focused AI capabilities to address evolving business requirements.
Strong innovation capabilities, agile product development, expertise in niche AI applications, flexible deployment models, rapid feature enhancements, and the ability to deliver customized solutions for specific enterprise use cases.
Limited global market presence, smaller customer base, comparatively lower financial resources, dependence on strategic partnerships and cloud infrastructure providers, and challenges in scaling operations while competing with established technology leaders.
Recent Development
-
In August 2024, NVIDIA Corporation, a computer manufacturing company, launched NIM Agent Blueprints, a collection of customizable AI workflows to help enterprises quickly create and implement generative AI applications for use cases such as customer service, drug discovery, and data extraction. Partners such as Accenture and Deloitte are enabling businesses to customize these solutions for faster digital transformation.
-
In June 2024, Amazon Web Services, Inc., Inc. announced a USD 230 million commitment aimed at accelerating the development of generative AI applications by startups across the globe. This initiative will offer startups, particularly those in their early stages, with mentorship, AWS credits, and educational resources to advance their use of AI and ML technologies.
-
In May 2024, Accenture, an IT company in Ireland, and Oracle partnered to accelerate generative AI adoption, focusing on transforming financial planning and analysis for CFOs using Oracle Cloud Infrastructure (OCI) Generative AI. Their collaboration aims to streamline tasks such as procurement spend analysis, financial forecasting, and dynamic scenario planning, enabling enterprises to optimize operations, improve decision-making, and drive growth.
-
In April 2024, AWS has announced the general availability of Amazon Q. This advanced generative artificial intelligence (AI)-powered assistant is designed to accelerate software development and utilize companies' internal data. Amazon Q excels at generating precise code, testing and debugging it, and offers multi-step planning and reasoning capabilities. It can transform existing code, such as performing Java version upgrades, and implement new code based on developer requests.
-
In March 2024, Adobe Inc. partnered with NVIDIA Corporation to harness the potential of generative AI to enhance creative workflows. The collaboration aimed to develop advanced generative AI models deeply integrated into applications utilized by top creators and marketers worldwide. The partnership is built on the longstanding relationship between the two companies in R&D, emphasizing the importance of generative AI in transforming creative processes and enabling more innovative outputs in the marketing domain.
-
In January 2024, Essential AI and Google Cloud announced a strategic partnership to streamline and drive the development of full-stack generative AI products and empower enterprise users to make more informed, data-driven decisions. As a preferred cloud provider, Google Cloud would enable Essential AI to deliver LLMs customized for enterprises, enhancing business productivity by automating repetitive and time-consuming tasks.
Enterprise Generative AI Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.9 billion
Estimated market size in 2026
USD 5.2 billion
Projected market size by 2033
USD 63.5 billion
Growth rate
CAGR of 42.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, model type, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; China; India; Japan; South Korea; Australia; Brazil; Mexico; KSA; UAE; South Africa
Key companies profiled
AWS; Google LLC; H20.ai; IBM; Intel Corporation; Jasper.ai; Microsoft Corporation; Nvidia Corporation; OpenAI; Oracle; Synthesis AI
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Enterprise Generative AI Market Report Segmentation
This report forecasts revenue growth on global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global enterprise generative AI report based on component, model type, application, end use, and region:
-
Components Outlook (Revenue, USD Million, 2021 - 2033)
-
Software
-
Services
-
-
Model Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Text
-
Image/Video
-
Audio
-
Code
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Marketing and Sales
-
Customer Service
-
Product Development
-
Supply Chain Management
-
Others (Research and Development, Risk Management, etc.)
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
IT & Telecom
-
BFSI
-
Retail & E-commerce
-
Healthcare
-
Manufacturing
-
Media and Entertainment
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The enterprise generative AI market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each enterprise generative AI segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Components
Revenue capture definition
Software
Revenue in this segment is generated through the development and deployment of enterprise generative AI software that enables organizations to create, automate, and optimize content, code, workflows, and business processes using advanced artificial intelligence models. These software solutions leverage large language models (LLMs), multimodal AI, natural language processing (NLP), machine learning (ML), and retrieval-augmented generation (RAG) to support applications such as intelligent assistants, content generation, software development, document processing, customer engagement, and enterprise knowledge management.
Services
Revenue in this segment is generated through consulting, implementation, integration, customization, training, support, maintenance, and managed services associated with enterprise generative AI solutions. These services help organizations assess AI readiness, deploy and fine-tune foundation models, integrate generative AI with existing enterprise applications, establish governance and security frameworks, and optimize AI performance.
Segment -Model Type
Revenue capture definition
Text
Revenue in this segment is generated through generative AI solutions designed to create, summarize, translate, and analyze textual content for enterprise applications. These solutions leverage large language models (LLMs), natural language processing (NLP), and machine learning (ML) to automate tasks such as content creation, document drafting, customer support, knowledge management, report generation, and code generation
Image/Video
Revenue in this segment is generated through enterprise generative AI solutions that create, edit, and enhance images and videos for business applications. These solutions leverage diffusion models, generative adversarial networks (GANs), multimodal AI, and computer vision technologies to produce high-quality visual content for marketing, product design, training, digital media, advertising, and customer engagement
Audio
Revenue in this segment is generated through enterprise generative AI solutions that create, synthesize, transcribe, translate, and enhance audio content for business applications. These solutions leverage speech recognition, text-to-speech (TTS), speech-to-text (STT), natural language processing (NLP), and generative AI models to support applications such as virtual assistants, customer service automation, voice analytics, multilingual communication, media production, and enterprise collaboration
Code
Revenue in this segment is generated through enterprise generative AI solutions that assist in software development by generating, completing, reviewing, debugging, testing, and optimizing source code. These solutions leverage large language models (LLMs), machine learning (ML), and natural language processing (NLP) to automate coding tasks, accelerate application development, improve code quality, and support multiple programming languages and development frameworks
Segment -Application
Revenue capture definition
Marketing and Sales
Revenue in this segment is generated through enterprise generative AI solutions that support marketing and sales functions by automating content creation, personalizing customer interactions, generating campaign materials, and optimizing sales processes. These solutions leverage large language models (LLMs), machine learning (ML), natural language processing (NLP), and multimodal AI to create marketing copy, product descriptions, emails, advertisements, presentations, and sales proposals while providing customer insights and lead recommendations.
Customer Service
Revenue in this segment is generated through enterprise generative AI solutions that enhance customer support by automating interactions, resolving inquiries, and delivering personalized assistance across multiple communication channels. These solutions leverage large language models (LLMs), natural language processing (NLP), machine learning (ML), and conversational AI to power virtual assistants, AI chatbots, automated ticket resolution, knowledge management, and multilingual customer suppor
Product Development
Revenue in this segment is generated through enterprise generative AI solutions that accelerate product innovation by supporting ideation, design, simulation, prototyping, testing, and documentation throughout the product lifecycle. These solutions leverage large language models (LLMs), machine learning (ML), multimodal AI, computer vision, and generative design technologies to analyze market requirements, generate design concepts, optimize product features, and automate engineering workflows
Supply Chain Management
Revenue in this segment is generated through enterprise generative AI solutions that optimize supply chain operations by enhancing demand forecasting, inventory planning, procurement, logistics, and supplier collaboration. These solutions leverage large language models (LLMs), machine learning (ML), predictive analytics, and natural language processing (NLP) to analyze supply chain data, automate documentation, generate operational insights, and support real-time decision-making
Others
Revenue in this segment is generated through enterprise generative AI solutions deployed across a wide range of business functions beyond core applications, including human resources, finance, legal, compliance, research and development, cybersecurity, and enterprise knowledge management. These solutions leverage large language models (LLMs), machine learning (ML), natural language processing (NLP), and multimodal AI to automate routine tasks, generate insights, streamline documentation, support decision-making, and improve operational efficiency.
Segment -End User
Revenue capture definition
IT & Telecom
Revenue in this segment is generated through the adoption of enterprise generative AI solutions that automate software development, IT operations, network management, customer support, and enterprise knowledge management. These solutions leverage large language models (LLMs), machine learning (ML), natural language processing (NLP), and AI-powered automation to assist with code generation, incident resolution, predictive maintenance, cybersecurity, service desk automation, and network optimization
BFSI
Revenue in this segment is generated through the adoption of enterprise generative AI solutions that enhance banking, financial services, and insurance operations by automating customer interactions, document processing, fraud detection, risk assessment, compliance management, and financial analysis. These solutions leverage large language models (LLMs), machine learning (ML), natural language processing (NLP), and predictive analytics to generate insights, streamline workflows, support personalized financial services, and improve decision-making
Retail & E-commerce
Revenue in this segment is generated through the adoption of enterprise generative AI solutions that enhance merchandising, customer engagement, marketing, inventory management, and sales operations. These solutions leverage large language models (LLMs), machine learning (ML), natural language processing (NLP), and multimodal AI to generate product descriptions, personalize recommendations, automate customer support, optimize pricing strategies, and create marketing content.
Healthcare
Revenue in this segment is generated through the adoption of enterprise generative AI solutions that improve clinical, administrative, and operational workflows across healthcare organizations. These solutions leverage large language models (LLMs), machine learning (ML), natural language processing (NLP), and multimodal AI to automate clinical documentation, support medical research, assist in diagnostics, generate patient communications, and streamline healthcare administration.
Manufacturing
Revenue in this segment is generated through the adoption of enterprise generative AI solutions that optimize product design, production planning, quality control, predictive maintenance, and supply chain operations. These solutions leverage large language models (LLMs), machine learning (ML), computer vision, and generative design technologies to automate engineering documentation, improve process optimization, support digital twins, and enhance decision-making across manufacturing workflows
Media and Entertainment
Revenue in this segment is generated through the adoption of enterprise generative AI solutions that automate content creation, video and image generation, scriptwriting, visual effects, localization, and audience engagement. These solutions leverage large language models (LLMs), multimodal AI, computer vision, and machine learning (ML) to produce personalized content, generate digital assets, enhance post-production workflows, and optimize content recommendations across streaming, broadcasting, gaming, and digital media platforms.
Others
Revenue in this segment is generated through the adoption of enterprise generative AI solutions across industries such as education, government, energy and utilities, transportation and logistics, legal services, hospitality, and professional services. These solutions leverage large language models (LLMs), machine learning (ML), natural language processing (NLP), and multimodal AI to automate documentation, generate insights, enhance decision-making, streamline workflows, and improve customer and employee experiences.
Estimation Model
Layer Name
Key Question
Description
Addressable End-user Base Layer
Which organizations generate demand for enterprise generative AI solutions?
Identify the global addressable base of enterprises adopting generative AI to improve business operations and decision-making. Include organizations across BFSI, IT & telecommunications, healthcare, retail & e-commerce, manufacturing, media & entertainment, government, education, professional services, and other industries implementing AI-powered enterprise solutions
Application Layer
Which enterprise applications drive generative AI adoption?
Assess demand across key enterprise applications, including content generation, customer service automation, software development and code generation, marketing and sales, product development, knowledge management, document processing, supply chain optimization, human resources, finance, legal assistance, and business intelligence powered by generative AI models.
Technology Adoption Layer
How extensively are enterprise generative AI solutions utilized?
Estimate technology adoption based on the deployment of large language models (LLMs), multimodal AI, retrieval-augmented generation (RAG), AI agents, foundation models, natural language processing (NLP), machine learning (ML), synthetic data generation, and cloud- and on-premises AI platforms integrated into enterprise workflows, business applications, and productivity tools.
Revenue Generation Layer
How much revenue is generated?
Calculate market revenue by assessing enterprise spending on generative AI software, cloud-based AI platforms, foundation model APIs, AI infrastructure, implementation and integration services, consulting, customization, training, support, managed services, and subscription-based licensing. Revenue is generated through software subscriptions, usage-based AI services, professional services, platform licensing, and strategic partnerships that enable enterprise-wide generative AI adoption.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Intelligence & Market Positioning Assessment
Performed an in-depth evaluation of leading enterprise generative AI providers, cloud platform vendors, foundation model developers, and enterprise software companies. Assessed market positioning, AI model capabilities, product portfolios, cloud ecosystems, strategic partnerships, acquisitions, enterprise deployment capabilities, regional presence, and recent developments across the enterprise generative AI ecosystem.
Enables stakeholders to identify key market participants, benchmark competitive positioning, evaluate AI platform capabilities, assess partnership and acquisition opportunities, and gain insights into the evolving competitive landscape of the Enterprise Generative AI Market.
Enterprise Adoption Patterns & Application-Specific Analysis
Analyzed adoption trends across key enterprise applications, including content generation, customer service, software development, marketing and sales, product development, document processing, supply chain management, knowledge management, and business process automation.
Provides actionable insights into enterprise adoption trends, application-specific growth opportunities, investment priorities, and implementation strategies, supporting informed decisions related to product development, market expansion, AI investments, and commercialization initiatives.
Technology Advancements & Future Growth Potential Evaluation
Assessed the impact of large language models (LLMs), multimodal AI, AI agents, retrieval-augmented generation (RAG), foundation models, synthetic data generation, responsible AI frameworks, and cloud-based AI platforms on market development. Identified emerging innovation areas, evolving enterprise AI use cases, and high-growth opportunities across intelligent automation, enterprise productivity, customer engagement, and industry-specific AI solutions.
Supports long-term strategic planning by identifying attractive investment opportunities, prioritizing AI platform innovation, uncovering future revenue streams, and understanding the key technological trends shaping the evolution of the Enterprise Generative AI Market.
Frequently Asked Questions About This Report
Some key players operating in the enterprise generative AI market include AWS, Google LLC, H20.ai, IBM, Intel Corporation, Jasper.ai, Microsoft Corporation, Nvidia Corporation, OpenAI, Oracle, and Synthesis AI.
Key factors that are driving the market growth include the availability of large datasets for training AI models, improved cloud computing infrastructure, growing interest in personalized customer experiences, and the expanding use of AI in sectors such as healthcare, finance, and manufacturing.
North America dominated the market, accounting for a revenue share of 40.2% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Software leads the component segment with revenue share of 71.7% in 2025, while service is the fastest growing component.
IT & Telecom leads the end user segment with revenue share of 31.1% in 2025, while manufacturing is the fastest growing end-user.
The global enterprise generative AI market size was valued at USD 3.9 billion in 2025 and is estimated at USD 5.2 billion in 2026.
The global enterprise generative AI market is expected to grow at a CAGR of 42.9% from 2026 to 2033 and reach USD 63.5 billion by 2033
Text segment leads the model type segment with revenue share of 39.3% in 2025, while Image/Video is the fastest growing model type.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


