
- Home
- »
- Green Building Materials
- »
-
Environment Health & Safety Market Size Report, 2026-2033GVR Report cover

Environment Health And Safety Market (2026 - 2033)
Size, Share & Trends Analysis Report By Deployment Mode (Cloud), By Product (Software), By End-use (Chemicals & Petrochemicals, Energy & Mining, Healthcare, Telecom & IT), By Region, And Segment Forecasts
Market Size, 2025
$55.5BMarket Estimate, 2026
$59.1BMarket Forecast, 2033
$95.7BCAGR, 2026–2033
7.1%Environment Health And Safety Market Summary
The global environment health & safety market size was valued at USD 55.5 billion in 2025 and is projected to grow from USD 59.1 billion in 2026 to USD 95.7 billion by 2033, at a CAGR of 7.1% from 2026 to 2033. North America dominated the global market with the largest revenue share of 37.6% in 2025. Rising public concerns regarding environmental issues over the past few years have resulted in the development of environmental protection laws, which are expected to drive the market growth.
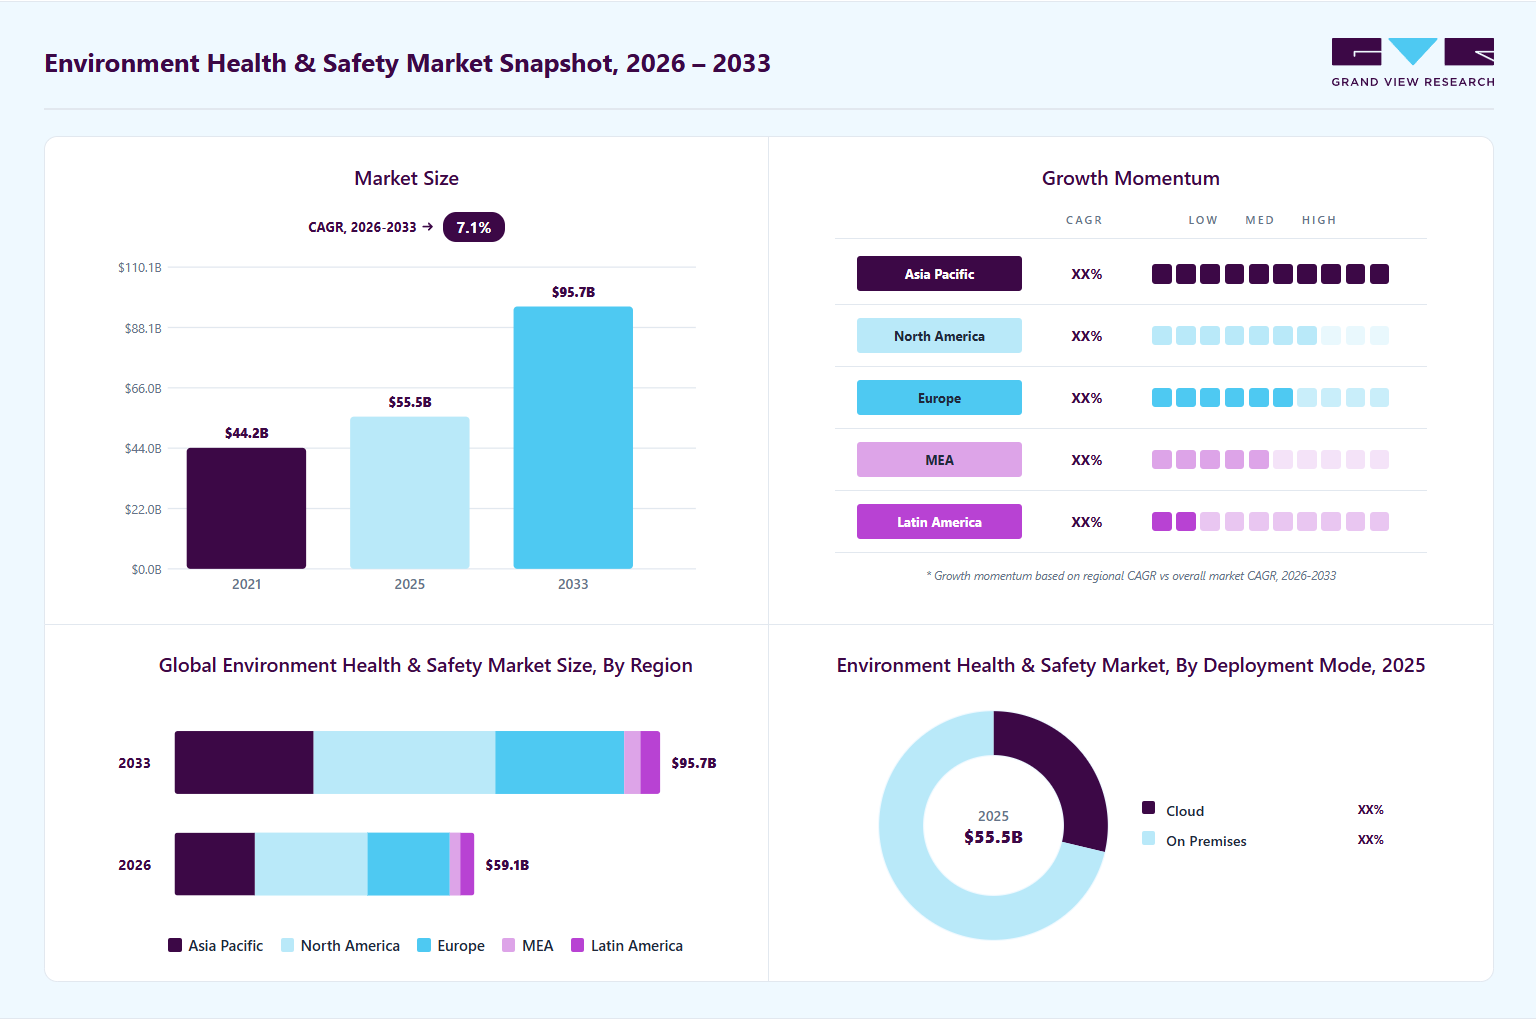 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Services segment led the market with the largest revenue share of 96.1% in 2025.
- By deployment mode: On premises segment led the market with the largest revenue share of 71.3% in 2025.
- By end use: Chemicals & petrochemicals segment led the market with the largest revenue share of 25.0% in 2025.
Regional Highlights
- Largest regional market: North America (37.6% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 55.5 Billion
- Estimated market size in 2026: USD 59.1 Billion
- Projected market size by 2033: USD 95.7 Billion
- CAGR (2026-2033): 7.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The global environment health & safety market is witnessing strong growth, driven by rapid industrialization across sectors such as oil & gas, chemicals, construction, and manufacturing. Increasing regulatory pressure from government bodies and global organizations pushes companies to adopt advanced EHS solutions to ensure compliance and reduce risks. The rising emphasis on achieving “Zero Incidents” and creating a workplace safety culture further boosts demand for EHS software and services worldwide. To learn more about this report, Download Free Sample Report
Technological advancements, including integrated risk management platforms and real-time monitoring tools, enhance operational efficiency and accountability. However, limited awareness and adoption in developing regions may restrain the market’s full potential over the forecast period.
Market Dynamics
The environmental health and safety (EHS) market is driven by increasingly stringent workplace safety and environmental regulations, growing industrialization, and rising awareness of employee well-being and sustainability. Organizations across manufacturing, energy, construction, healthcare, and transportation are investing in EHS solutions to reduce workplace incidents, manage environmental risks, and ensure regulatory compliance. The adoption of digital technologies, including IoT sensors, artificial intelligence, cloud-based EHS platforms, and real-time monitoring systems, is improving hazard detection and operational efficiency. However, high implementation costs and the complexity of integrating EHS systems across large organizations can limit adoption, particularly among small and medium-sized enterprises.
The environmental health and safety market is being driven by increasingly stringent regulations aimed at protecting workers, communities, and the environment. Governments and regulatory bodies are strengthening requirements for occupational safety, hazardous material handling, emissions control, waste management, and environmental reporting across industries. Companies are investing in EHS solutions to comply with these regulations, reduce workplace incidents, and avoid legal penalties and operational disruptions. Industries such as manufacturing, construction, energy, chemicals, mining, and healthcare are expanding the use of EHS management systems to improve risk assessment and incident prevention. The growing emphasis on environmental, social, and governance (ESG) initiatives and corporate sustainability strategies is further supporting market growth. In addition, digital technologies such as IoT sensors, cloud platforms, and real-time monitoring systems are helping organizations improve compliance management and operational safety, making EHS solutions an essential part of modern industrial operations.
Organizations often need to invest in software platforms, monitoring equipment, workplace safety devices, environmental testing systems, employee training, and ongoing compliance programs. Large enterprises with multiple facilities may face additional challenges in integrating EHS solutions across different locations and operational processes. Small and medium-sized businesses can find these investments difficult due to budget limitations and resource constraints, slowing market adoption. Frequent updates to environmental and workplace safety regulations require continuous system modifications and staff training, increasing operational expenses. Managing large volumes of compliance and safety data while maintaining cybersecurity and data accuracy also adds complexity. In addition, the shortage of skilled EHS professionals capable of managing advanced digital systems can limit the effective implementation of modern EHS programs, creating barriers to broader market growth.
Organizations are increasingly shifting from traditional compliance-based approaches to proactive and data-driven safety management systems. Cloud-based EHS platforms, artificial intelligence, machine learning, IoT sensors, wearable safety devices, and predictive analytics enable real-time monitoring of workplace conditions and environmental performance. These technologies help identify potential hazards before incidents occur, improving risk management and reducing operational downtime. The expansion of smart factories, industrial automation, and connected infrastructure is creating demand for integrated EHS solutions that provide centralized monitoring and reporting across multiple sites. Growing corporate commitments to sustainability and ESG objectives are also encouraging investments in digital tools that support environmental performance tracking and regulatory reporting. Emerging economies undergoing rapid industrialization offer additional growth opportunities as businesses modernize operations and adopt advanced EHS technologies to improve workplace safety, environmental stewardship, and long-term operational efficiency.
Market Concentration & Characteristics
The market is moderately fragmented, with a mix of established players and emerging solution providers. The market features various services and software offerings tailored to various industries, leading to diverse competition. Technological innovation and region-specific compliance needs further contribute to the fragmented structure. However, the growing demand for integrated platforms gradually drives consolidation through strategic partnerships and acquisitions.
The global EHS market is marked by steady innovation, particularly in digital technologies like AI, IoT, and cloud-based compliance platforms. Companies invest in advanced analytics and predictive tools to enhance incident prevention and environmental monitoring. Integrated risk management systems and mobile EHS applications are also gaining traction. These innovations aim to improve operational efficiency, ensure real-time reporting, and support data-driven decision-making.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions are increasingly shaping the global EHS landscape, as larger players seek to expand their portfolios and geographic reach. Strategic acquisitions enable companies to integrate complementary technologies like risk visualization and audit tools. Recent deals, like Wolters Kluwer acquiring CGE Risk Management, highlight this trend. M&A activity also helps consolidate the market, improve service capabilities, and accelerate innovation.
Stringent global regulations from bodies like OSHA, EPA, and EU-OSHA are a key driver of EHS market growth. These mandates compel industries to adopt advanced EHS solutions for compliance, reporting, and risk mitigation. Regulatory updates and penalties for non-compliance encourage continuous system upgrades. Region-specific frameworks also push companies to implement tailored EHS strategies aligned with local laws.
Analyst Perspective
The environmental health and safety (EHS) market is expected to maintain growth, supported by stricter regulatory frameworks, increasing workplace safety requirements, and the growing integration of sustainability and ESG initiatives into corporate strategies. Organizations are shifting from reactive compliance management to proactive risk mitigation through digital EHS platforms, AI-driven analytics, and IoT-enabled monitoring systems. Cloud-based deployments are gaining traction due to their scalability and real-time data capabilities, while demand from manufacturing, construction, energy, healthcare, and chemical industries remains strong. Although implementation costs and integration complexities present challenges, ongoing industrial digitalization and rising investments in operational resilience are expected to support long-term market expansion and innovation.
Deployment Mode Insights
Based on deployment mode, the on premises segment led the market with the largest revenue share of 71.3% in 2025. Large enterprises in sectors like oil and gas and chemicals prefer on-site systems to comply with stringent internal and external regulations. These solutions offer greater customization and integration with legacy infrastructure. Additionally, regulatory-sensitive industries favor on-premises models to maintain compliance assurance.
Cloud-based EHS solutions are growing fastest, driven by flexibility, scalability, and lower upfront costs. Organizations increasingly adopt cloud platforms for real-time access, remote monitoring, and automated updates. The demand for mobile-compatible and user-friendly systems is accelerating this shift. Advancements in cloud security are also reducing hesitancy around data privacy concerns.
Product Insights
Based on product, the services segment led the market with the largest revenue share of 96.1% in 2025. Companies often outsource these functions to ensure alignment with ever-evolving global regulations. Service providers offer tailored solutions suited to diverse industries and geographies. The complexity of environmental and safety requirements continues to drive demand for hands-on consulting and support services.
Software is the fastest growing segment in the global EHS market, driven by increased digitization and the need for centralized, automated compliance systems. Organizations leverage EHS software for real-time monitoring, data management, and streamlined regulatory reporting. The growing focus on predictive analytics and integration with ERP and HR systems accelerates adoption.
End Use Insights
Based on end use, the chemicals & petrochemicals segment led the market with the largest revenue share of 25.0% in 2025. Rapid expansion in shale production and growing demand for petrochemical derivatives have amplified the need for robust EHS practices. Companies in this sector prioritize compliance, risk management, and environmental protection across all project stages. EHS providers support these goals through tailored audits, training, and safety monitoring solutions.
 To learn more about this report, Download Free Sample Report
The healthcare segment is experiencing significant growth in the market, driven by increasing regulatory scrutiny and a heightened focus on patient and worker safety. The rise in global healthcare infrastructure and biohazard waste management needs is boosting EHS demand. Facilities are adopting digital safety systems to ensure compliance with hygiene, disposal, and occupational health standards. Additionally, post-pandemic priorities have intensified investment in sustainable and safe healthcare environments.
Regional Insights
North America dominated the environment health & safety market with the largest revenue share of 37.6% in 2025. The presence of key market players and a mature industrial base further strengthens regional dominance. High awareness of workplace safety and environmental compliance drives strong adoption across sectors. Additionally, industries like oil & gas and chemicals rely heavily on EHS solutions for operational risk management.
 To learn more about this report, Download Free Sample Report
U.S. Environment Health And Safety Market Trends
The environment health & safety market in the U.S. held the largest share in the North America region in 2025. The U.S. leads the North American EHS market due to well-established regulatory bodies like OSHA, EPA, and the Department of Labor. High industrialization, especially in sectors like chemicals, oil and gas, and manufacturing, drives strong demand for EHS solutions. The presence of major market players and advanced digital infrastructure further boosts adoption. Continuous emphasis on workplace safety and sustainability reinforces the country's leading position.
Mexico is the fastest-growing market in North America for EHS, fueled by rapid industrial expansion and foreign investment in manufacturing. Growing enforcement of environmental and labor safety regulations prompts companies to adopt EHS systems.
Europe Environment Health And Safety Market Trends
The Europe EHS market is growing steadily due to stringent EU-wide regulations focused on sustainability, occupational health, and emissions control. The region's strong emphasis on ESG compliance and green practices promotes widespread use of EHS solutions. Industries across Germany, France, and the UK are upgrading safety protocols and environmental monitoring systems. Additionally, digital transformation efforts are further modernizing compliance infrastructure.
Germany dominates the European EHS market due to its strong chemical, automotive, and engineering industrial base. The country enforces strict environmental and occupational safety regulations, driving widespread adoption of EHS solutions. High investment in R&D and sustainability initiatives further supports market leadership. German companies prioritize advanced compliance systems to maintain operational excellence and meet EU directives.
The UK is the fastest-growing market in Europe, driven by post-Brexit regulatory shifts and an increased focus on environmental and workplace safety standards. Rapid digital transformation across industries is accelerating the adoption of cloud-based EHS software. The country's strong commitment to net-zero goals and ESG reporting also boosts demand. Additionally, growth in sectors like healthcare and construction is fueling market expansion.
Asia Pacific Environment Health And Safety Market Trends
Asia Pacific is the fastest-growing region with a CAGR of 8.1% in the EHS market, fueled by rapid industrialization, urbanization, and growing environmental concerns. Countries like China and India are increasingly enforcing environmental and worker safety regulations. Rising foreign investments and the expansion of manufacturing hubs also elevate the need for advanced EHS systems. Government initiatives to improve sustainability and public health are accelerating market growth.
China dominates the Asia Pacific EHS market due to its vast industrial landscape and rising environmental concerns. The government has tightened regulations on pollution control, worker safety, and industrial emissions. Manufacturing, mining, and energy sectors are key adopters of EHS solutions. Additionally, national policies promoting sustainable development drive widespread implementation of compliance systems.
India is the fastest-growing EHS market at CAGR 9.3% in Asia Pacific, fueled by rapid industrialization and increasing regulatory enforcement. Rising awareness of workplace safety and environmental risks encourages companies to adopt structured EHS practices. Expansion in sectors like construction, pharmaceuticals, and infrastructure is creating strong demand. Government initiatives such as “Make in India” and environmental reforms further accelerate market growth.
Middle East & Africa Environment Health And Safety Market Trends
The Middle East & Africa region is experiencing moderate growth in the EHS market, supported by expansion in oil & gas, construction, and healthcare sectors. Government-led safety mandates and environmental policies are gradually gaining traction in countries like UAE, Saudi Arabia, and South Africa. Infrastructure development and global partnerships are driving demand for modern EHS systems. However, regulatory fragmentation and low awareness in some areas limit faster market expansion.
Saudi Arabia leads the environmental health & safety market in the Middle East & Africa region due to its extensive oil & gas operations and large-scale industrial projects. The government’s Vision 2030 initiative emphasizes sustainable development and stricter compliance with environmental and safety regulations. Major infrastructure and energy investments are driving the need for advanced EHS solutions. Additionally, increased focus on workforce safety and environmental impact is supporting market growth.
Central & South America Environment Health And Safety Market Trends
Central & South America is witnessing gradual growth in the EHS market due to increasing awareness of environmental risks and worker safety. Governments are enhancing regulatory frameworks, particularly in mining, oil, and manufacturing sectors. Countries like Brazil and Mexico are investing in industrial safety reforms and environmental protection initiatives. However, economic instability and inconsistent enforcement still pose challenges to wider adoption.
Brazil dominates the Central & South America environment health & safety market due to its strong industrial base in mining, oil & gas, and agriculture. The government has been progressively enhancing environmental and occupational safety regulations. Growing public awareness and corporate responsibility are driving the adoption of EHS solutions. Additionally, Brazil's participation in international climate and safety agreements supports long-term market growth.
Key Environment Health And Safety Company Insights
Some of the key players operating in the market include AECOM, Jacobs, and Intelex Technologies.
-
AECOM provides integrated EHS solutions focused on environmental compliance, sustainability reporting, and occupational health strategies for complex infrastructure and industrial projects. The company supports clients across sectors such as energy, transportation, and defense with tailored EHS risk management frameworks. AECOM leverages data analytics and digital platforms to improve monitoring and regulatory alignment. It also plays a key role in large-scale environmental remediation and ESG-driven consulting services.
-
Jacobs offers comprehensive EHS and compliance services, specializing in high-risk sectors like aerospace, pharmaceuticals, and nuclear energy. The firm delivers advanced EHS management systems, risk assessments, and health impact analyses aligned with global standards. Jacobs supports clients with lifecycle safety solutions, from project planning to decommissioning. Its EHS offerings are closely tied to digital innovation and sustainability goals, including climate resilience and zero-incident programs.
Key Environment Health & Safety Companies:
The following key companies have been profiled for this study on the environment health and safety market.
-
AECOM
-
Jacobs
-
Intelex Technologies
-
Enablon
-
Tetra Tech, Inc.
-
SAP SE
-
Golder Associates
-
SGS SA.
-
ERM Group, Inc.
-
VelocityEHS
-
John Wood Group PLC
-
RPS Group
-
ETQ
-
Cority (Medgate)
-
Sphera
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Sphera, Enablon, Intelex Technologies, VelocityEHS, Cority (Medgate))
- Mature EHS providers focus on expanding integrated software ecosystems, strengthening cloud capabilities, acquiring niche technology firms, and offering end-to-end compliance, occupational health, and ESG solutions through long-term enterprise contracts and global service networks.
- Established companies benefit from extensive customer bases, recognized brands, broad product portfolios, global implementation expertise, and strong regulatory knowledge. Their ability to integrate EHS with enterprise systems and provide comprehensive support strengthens long-term customer relationships.
- Mature players face challenges from complex legacy systems, higher implementation costs, slower product innovation cycles, and lengthy deployment processes. Large organizational structures reduce flexibility when adapting to rapidly changing regulations and customer expectations.
Emerging & Regional Players (e.g., ETQ, ERM Group, Inc., RPS Group, John Wood Group PLC, Golder Associates)
- Emerging players concentrate on cloud-native platforms, AI-driven analytics, industry-specific solutions, and flexible subscription models. They target underserved SMEs and regional markets, emphasizing rapid deployment, product innovation, and strategic partnerships to accelerate market penetration.
- Emerging companies gain advantages through technological agility, lower implementation costs, user-friendly interfaces, and faster feature updates. Their specialized offerings, advanced analytics, and customizable solutions enable them to address evolving customer needs and niche industry requirements.
- Emerging players often have limited global presence, smaller customer portfolios, and constrained financial resources. They may face difficulties in scaling operations, meeting complex enterprise requirements, building brand recognition, and competing for large multinational contracts.
Recent Developments
-
In May 2025, AECOM was awarded an environmental remediation contract exceeding USD 80 million for work at Vandenberg Space Force Base in California. The project involves investigating and cleaning contaminated sites to support ongoing military operations. AECOM will apply advanced remediation techniques and regulatory compliance frameworks throughout the project. This contract reinforces AECOM’s leadership in delivering large-scale, mission-critical environmental solutions for federal clients.
-
In March 2025, Intelex Technologies introduced Intelex Essentials, a simplified EHS software designed for small and mid-sized enterprises. The solution offers key tools like incident tracking, inspection management, document control, and built-in analytics. It features an easy-to-use interface and guided setup, helping businesses quickly implement safety programs. Early users have noted faster onboarding and improved efficiency in managing safety tasks.
Environment Health & Safety Market Report Scope
Report Attribute
Details
Market size in 2025
USD 55.5 billion
Estimated market size in 2026
USD 59.1 billion
Projected market size by 2033
USD 95.7 billion
Growth rate
CAGR of 7.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end-use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Spain; Italy; China; Japan; India ; South Korea; Australia, Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
AECOM; Jacobs; Intelex Technologies; Enablon; Tetra Tech, Inc; SAP SE; Golder Associates; SGS SA.; ERM Group, Inc; VelocityEHS; John Wood Group PLC; RPS Group; ETQ; Cority (Medgate); Sphera
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Environment Health And Safety Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global environment health and safety market on the basis of product, deployment mode, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Software
-
Services
-
Analytics
-
Project Deployment & Implementation
-
Business Consulting & Advisory
-
Audit, Assessment, & Regulatory Compliance
-
Certification
-
Others
-
-
-
Deployment Mode Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cloud
-
On Premises
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Chemical & Petrochemical
-
Energy & Mining
-
Healthcare
-
Telecom & IT
-
Construction
-
Manufacturing
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
-
Research Methodology
The environment health and safety market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each environment health and safety segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue Capture Definition
Software
Revenue is generated through the licensing and subscription of EHS software platforms used for incident management, regulatory compliance, risk assessment, environmental reporting, occupational health, audit management, and sustainability tracking. Demand is driven by digital transformation and increasing workplace safety requirements.
Services
Revenue is captured through consulting, implementation, integration, training, maintenance, managed services, and regulatory advisory for EHS solutions. Demand is supported by the need for customized deployments, ongoing compliance management, and optimization of safety and environmental programs.
Segment - Deployment Mode
Revenue Capture Definition
Cloud
Revenue is generated through cloud-based EHS platforms delivered via subscription models, including software access, data storage, analytics, remote monitoring, and managed services. Demand is driven by scalability, real-time collaboration, and centralized management across multiple business locations.
On Premises
Revenue is captured through EHS software installed within an organization's own IT infrastructure, including software licenses, implementation, upgrades, and support services. Demand is supported by industries requiring enhanced data security, regulatory control, and customized system integration.
Segment - End-use
Revenue Capture Definition
Chemicals & Petrochemicals
Revenue is generated through EHS solutions used for process safety management, hazardous chemical handling, emissions monitoring, environmental compliance, and occupational health programs. Demand is driven by stringent regulations and the need to minimize operational and environmental risks.
Energy & Mining
Revenue is captured through EHS platforms and services supporting worker safety, environmental monitoring, risk management, emergency response, and regulatory compliance across mining, oil and gas, utilities, and renewable energy operations.
Healthcare
Revenue is generated through EHS systems used for infection prevention, hazardous waste management, chemical safety, occupational health monitoring, and healthcare compliance. Demand is supported by increasing patient safety standards and stringent healthcare regulations.
Telecom & IT
Revenue is captured through EHS solutions for workplace safety, field workforce protection, facility management, environmental reporting, and data center risk management. Demand is driven by expanding digital infrastructure and occupational safety requirements.
Construction
Revenue is generated through EHS platforms used for site safety management, contractor compliance, hazard identification, incident reporting, equipment inspections, and environmental monitoring. Demand is supported by infrastructure development and stricter workplace safety standards.
General Manufacturing
Revenue is captured through EHS solutions for industrial safety, machine risk assessment, environmental compliance, waste management, occupational health, and sustainability reporting. Demand is driven by factory automation and regulatory requirements for safer production environments.
Others
Revenue is generated through EHS solutions deployed across transportation, logistics, agriculture, food and beverage, retail, government, and public utilities. Demand is supported by expanding workplace safety programs, environmental regulations, and enterprise risk management initiatives.
Estimation Model
Layer Name
Key Question
Description
Regulatory & Compliance Demand Layer
Which factors create demand for EHS solutions?
The estimation begins by assessing workplace safety regulations, environmental protection laws, and ESG reporting requirements across industries. Growing compliance obligations in manufacturing, chemicals, healthcare, construction, energy, and mining establish the base demand for EHS software and services.
Enterprise Adoption Layer
Where are EHS solutions deployed?
The market base is refined by evaluating EHS adoption across end-use industries and enterprise sizes. Factors such as workforce scale, operational risk, digital maturity, and multi-site operations determine the penetration of EHS platforms, occupational health systems, and environmental management solutions.
Digital Transformation & Investment Layer
What drives annual EHS spending?
Annual demand is estimated by analyzing cloud migration, software upgrades, regulatory changes, ESG initiatives, and workplace safety investments. New facility developments, industrial automation, and replacement of legacy compliance systems also contribute to recurring EHS expenditure and technology adoption.
Market Revenue Layer
How is market revenue calculated?
Revenue is estimated by aggregating software subscriptions, on-premises installations, consulting services, implementation projects, training, maintenance, and managed services across deployment models and end-use industries.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed regional analysis was conducted across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, including country-level assessment for key markets such as the U.S., Germany, China, India, Brazil, and Saudi Arabia. The study evaluated regulatory frameworks, workplace safety standards, industrialization trends, ESG initiatives, digital transformation, and sector-specific EHS adoption across manufacturing, construction, energy, mining, healthcare, chemicals, and telecom industries.
Helped identify high-growth regional markets, country-specific compliance opportunities, and evolving demand trends for EHS software and services. The analysis also supported market entry strategies, regional expansion planning, and identification of industries with increasing investments in workplace safety and environmental management.
Competitive Benchmarking
Comprehensive benchmarking was carried out for major market participants based on product portfolio, software capabilities, cloud and on-premises offerings, AI and analytics integration, regulatory expertise, regional presence, pricing strategies, implementation capabilities, and service network strength. The assessment also compared established and emerging players operating in the EHS market.
Assisted clients in understanding competitor positioning, technology capabilities, and competitive gaps within the market. The study supported strategic planning, partnership evaluation, product differentiation, and investment decisions across workplace safety, environmental compliance, occupational health, and ESG management solutions.
Opportunity Assessment
In-depth opportunity assessment was conducted by analyzing industrial digitalization, ESG reporting requirements, workplace safety regulations, cloud adoption, IoT-enabled monitoring, AI-driven risk management, and sustainability initiatives. The study also identified emerging opportunities in predictive safety analytics, connected worker technologies, integrated EHS-ESG platforms, and real-time environmental monitoring systems.
Enabled clients to identify high-growth investment areas, prioritize regional expansion strategies, and evaluate future revenue opportunities across manufacturing, construction, healthcare, energy, mining, chemicals, and telecom sectors. The analysis also supported product development planning, digital transformation strategies, and long-term business growth initiatives in the environmental health and safety market.
Frequently Asked Questions About This Report
The services segment led the market with the largest revenue share of 96.1% in 2025.
Some of the key players operating in the environment health & safety (EHS) market include AECOM, Jacobs, Intelex Technologies, Enablon, Tetra Tech, Inc, SAP SE, Golder Associates, and among others
The key factors that are driving the environment health & safety (EHS) market include the increasing regulations by the government in various economies act as the primary growth driver. Industries, such as energy and chemicals deploy environment health & safety (EHS) services and software for the prevention of accidents at work as employees in these industries deal with hazardous materials.
The global environment health & safety market size was estimated at USD 55.5 billion in 2025 and is expected to be USD 59.1 billion in 2026.
The global environment health & safety market, in terms of revenue, is expected to grow at a compound annual growth rate of 7.1% from 2026 to 2033.
North America dominated the environment health & safety market with the largest revenue share of 37.6% in 2025.
The chemicals & petrochemicals segment led the market with the largest revenue share of 25.0% in 2025.
The on-premises segment accounted for the largest revenue share of 71.3% in 2025.
About the Author(s)
Green Building Materials Research Team
Advanced Materials · Green Building MaterialsThis report was authored by the green building materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the green building materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


