
- Home
- »
- Clinical Diagnostics
- »
-
Epigenetics Diagnostics Market Size, Growth Report, 2026-2033GVR Report cover
![Epigenetics Diagnostics Market (2026 - 2033)Report]()
Epigenetics Diagnostics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Reagents, Kits, Instruments, Enzymes, Services), By Technology (Histone Methylation), By Application (Oncology, Non-oncology), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$17.5BMarket Estimate, 2026
$19.5BMarket Forecast, 2033
$51.9BCAGR, 2026–2033
15.0%Epigenetics Diagnostics Market Trends
The global epigenetics diagnostics market size was valued at USD 17.5 billion in 2025 and is projected to grow from USD 19.5 billion in 2026 to USD 51.9 billion in 2033, at a CAGR of 15.0% from 2026 to 2033. North America epigenetics diagnostics market held the largest revenue share of over 35.0% in 2025. The market growth is mainly attributed to increased investment, funding, and approvals for epigenetics research & development, the growing applications of epigenetics in drug discovery & development, and the increased affordability of genome sequencing.
Key Market Trends & Insights
- By product: Reagents accounted for the largest share of over 30.0% in 2025.
- By technology: DNA methylation technology segment held the largest market share of more than 40.0% in 2025.
- By application: Oncology segment dominated the market in 2025, capturing a market share of around 70.0%.
- By end use: Academic research segment accounted for the largest market share of over 35.0% in 2025.
Regional Highlights
- Largest regional market: North America (over 35.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market Size in 2025: USD 17.5 Billion
- Estimated Market Size in 2026: USD 19.5 Billion
- Projected Market Size by 2033: USD 51.9 Billion
- CAGR (2026-2033): 15.0%
Three ways to get this report
Buy it, customize it, or ask a question.Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
External stimuli, including the causative agents, such as heavy metals, pesticides, smoke, hormones, radiation, viruses, environmental factors, and essential nutrients can influence the function of these epigenetic pathways. Increasing awareness regarding epigenetic testing and the increasing demand for such kits and assays is one of the crucial factors in the growth of this market. Increased healthcare R&D spending globally is also anticipated to fuel market expansion over the forecast period. According to the WHO report published in April 2023, the weighted average health GERD as% of GDP increased the most in high-income nations (0.25%) compared to the previous analysis (0.21%). The increase in cases of GERD in several high-income countries can be largely attributed to significant investments in research and development. Notably, the Republic of Korea has seen the most substantial rise, having invested over 112 trillion won (approximately $84.6 billion) in this area.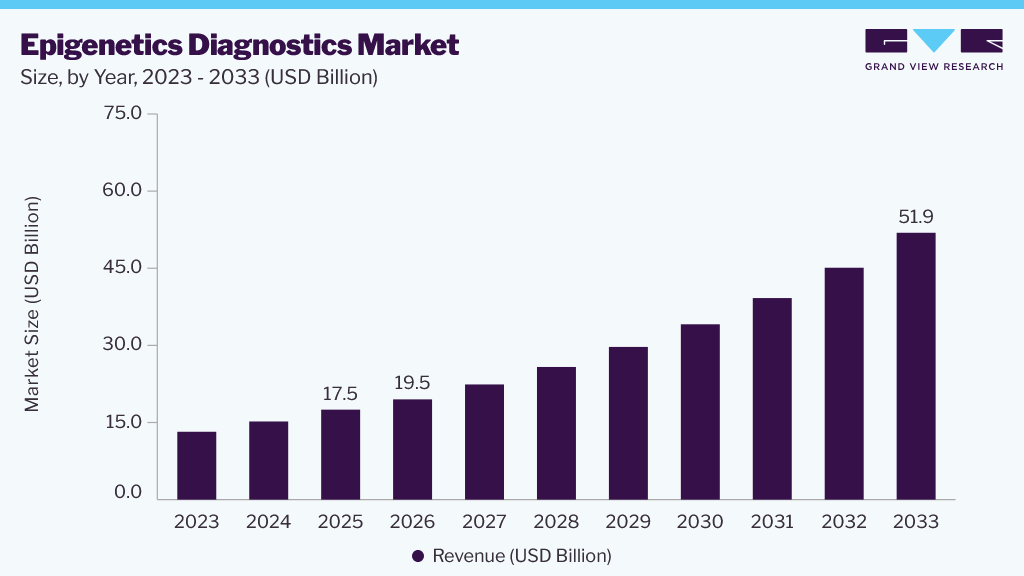
For instance, in November 2024, Oxford Nanopore partnered with UK Biobank to create the world’s first extensive epigenetic dataset, large scale. This dataset will include 50,000 samples and aid in the early detection and diagnosis of diseases.
Market Dynamics
The increasing investment in epigenetics research and development is a key driver of the epigenetics diagnostics market. Governments, research institutions, and biotechnology companies are investing heavily in understanding epigenetic mechanisms and their role in disease development, diagnosis, and treatment. Rising healthcare R&D expenditure, growing awareness of epigenetic testing, and increasing demand for advanced diagnostic assays are further supporting market growth. In addition, the expanding application of epigenetics in oncology, cardiovascular diseases, autoimmune disorders, and neurological conditions is accelerating the adoption of epigenetic diagnostic technologies. For instance, in November 2024, Oxford Nanopore partnered with UK Biobank to create the world’s first large-scale epigenetic dataset comprising 50,000 samples, supporting early disease detection and diagnosis. Such initiatives are expected to drive innovation and expand the adoption of epigenetic diagnostics during the forecast period.
The difficulty in interpreting epigenetic data remains a key challenge restraining the growth of the epigenetics diagnostics market. Epigenetic pathways are influenced by multiple factors, including environmental exposures, lifestyle habits, genetic variations, hormones, and disease conditions, making the identification of clinically relevant biomarkers highly complex. In addition, the large volume of genomic and epigenomic data generated through advanced sequencing technologies requires sophisticated analytical tools, specialized expertise, and substantial computational resources. Variability in epigenetic signatures across patient populations further complicates data interpretation and clinical validation. These challenges may increase development costs and limit the widespread adoption of epigenetics-based diagnostic solutions across healthcare settings.
The expanding application of epigenetics in non-oncology diseases is creating significant opportunities for the epigenetics diagnostics market. Researchers are increasingly exploring epigenetic biomarkers for the diagnosis and monitoring of cardiovascular disorders, autoimmune diseases, reproductive disorders, and neurological conditions. Growing evidence supporting the role of epigenetic pathways in disease progression is encouraging the development of novel diagnostic assays and precision medicine approaches. For instance, in January 2025, Illumina expanded its multiomics and epigenomics research capabilities through new sequencing and analysis solutions designed to accelerate biomarker discovery and clinical research across multiple disease areas. Such advancements are expected to create substantial growth opportunities for epigenetics diagnostics providers.
Market Concentration & Characteristics
The market growth stage is high, and the pace of market growth is accelerating. The epigenetics diagnostics industry is characterized by growing technological advancements, driven by high research and development investments. In August 2024, Illumina, Inc. received FDA approval for the in vitro diagnostic test TruSight, which profiles a patient's solid tumor to help identify actionable, targeted biomarkers that facilitate targeted therapy.
The epigenetics diagnostics industry is marked by the emergence of innovative therapies developed by leading companies. This growth can be attributed to several factors, including the rising incidence of cancer, technological advancements, genome sequencing advancements, and positive government support for new initiatives.
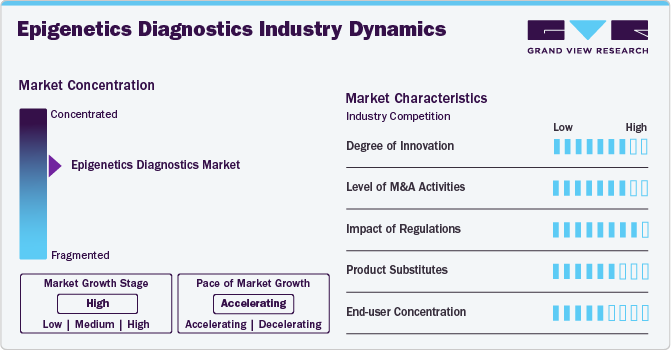
The epigenetics diagnostics industry is subject to dynamic regulatory outlook. These regulations help reduce potential issues such as misdiagnosis, ambiguous data, and breach of a patient’s database. As a result, governments and regulatory bodies around the world are framing regulations to govern the development and use of epigenetic diagnostics. Rising development of epigenetic diagnostic methodologies and growing awareness among people are also contributing to the need for evolving regulations and guidelines.
There are a limited number of direct substitutes for epigenetic diagnostics. However, there are a number of alternate techniques that can be used to achieve outcomes similar to those of epigenetic diagnostics. Despite the availability of current techniques, companies are making huge investments in the R&D of epigenetic diagnostic methodologies.
Analyst Perspective
The epigenetics diagnostics market is gradually moving from a research-focused field to a clinically relevant segment of precision medicine. Its strategic importance lies in the potential to detect disease earlier, improve patient stratification, and support more informed treatment decisions. However, commercial success will depend less on scientific innovation alone and more on the ability to generate strong clinical evidence and gain acceptance among physicians, laboratories, and healthcare systems. Companies that can translate complex epigenetic insights into practical diagnostic tools are likely to be best positioned to capture value. Over time, the market is expected to favor solutions that fit seamlessly into existing clinical workflows and deliver clear benefits for both providers and patients, making clinical utility a more important differentiator than technology alone.
Product Insights
Reagents accounted for the largest share of over 30.0% in 2025, mainly due to the high use of reagents in epigenetic research. The two main categories of reagents used in epigenetics are histone and DNA modifiers. Epigenetics is the study of persistent, possibly reversible changes in gene expression that occur without altering the DNA sequence permanently, yet still transfer from one generation to the next. Without any changes to the DNA, epigenetic mechanisms can trigger or suppress genes.
The services segment is expected to record the fastest CAGR during the forecast period. Demand in the service segment is driven by trends including the rising prevalence of chronic diseases, advances in sequencing technologies, and increased research and development investments.
The kits segment is anticipated to grow rapidly during the forecast period. Epigenetic kit demand is fueled by trends such as a rise in chronic disease cases, a growing aging population, and an increase in the application of epigenetic treatments. In addition, the growing awareness among people and an increasing number of companies involved in the development of advanced kits will push segment growth further.
Technology Insights
DNA Methylation held the largest market share of more than 40.0% in 2025. DNA is treated biochemically and enzymatically with methylation-sensitive enzymes as part of the DNA methylation process, which prepares DNA for methylation analysis. The DNA methylation method holds great promise for unraveling the functional mechanisms underlying complex disorders and for developing personalized medicines. The rising demand for DNA methylation techniques is responsible for market growth. Advancements in technology are making it possible to evaluate locus-specific DNA methylation on a genome-wide scale more frequently. In October 2024, EpiMedTech announced the launch of a tool called epiGeneComplete, which will use next-generation sequencing to provide insights about various health factors.
The histone acetylation segment is expected to register the fastest CAGR during the forecast period, driven by improved efficacy enabled by the development of innovative methods. Many studies indicate that histone acetylation can provide therapeutic benefits for conditions such as solid tumors, inflammation, leukemia, and viral infections. Histone Acetyltransferase 1 (HAT1), General Control Norepressible 5 (GNC5), CREB-binding protein (CBP), P300/CBP-binding protein (PCAF), MYST family, P300, TAFII250, and Rtt109 are the HAT subfamilies that have received the most attention to date. It has commonly been claimed that HAT1 contributes to carcinogenesis. With such wide therapeutic potential applications, the market is likely to flourish during the forecast period.
Application Insights
The oncology segment dominated the market in 2025, capturing approximately 70.0% market share. Cancer is currently the primary focus of epigenetics research. With the rising number of cancer cases, the market for epigenetic diagnostics related to cancer is expected to expand. According to the American Cancer Society, the estimated number of new cancer cases in the U.S. in 2024 was 2.01 million, with around 6,11,720 deaths caused by cancer.
The non-oncology application segment is projected to grow at the fastest CAGR over the forecast period. There has been growing interest in epigenetic studies of non-oncology diseases. Epigenetics applications in non-oncology diseases include neurological disorders, such as Alzheimer’s disease, Parkinson’s disease, etc., and developmental disorders, such as ASDs, CVDs, metabolic disorders, and many others. The increasing use of epigenetics in non-oncology indications will further drive this segment's growth.
End-use Insights
The academic research segment accounted for the largest market share, over 35.0% in 2025, driven by increased investments in research and development and the growing demand for personalized medicine. For instance, in April 2025, the Swedish government announced it would allocate around USD 8.0 million to enhance precision in genomic medicine within cancer care. Such initiatives highlight the global emphasis on advancing healthcare through genomics and underscore the critical role of academic institutions in pioneering innovative research.
The clinical research segment is expected to grow at the fastest CAGR over the forecast period. Advanced technologies and an increased awareness of epigenetic modifications in disease development drive the market. In January 2025, at Leuven (CME), researchers developed a new diagnostic method that detects both genetic and epigenetic anomalies and gives quick diagnoses in a single analysis.
Regional Insights
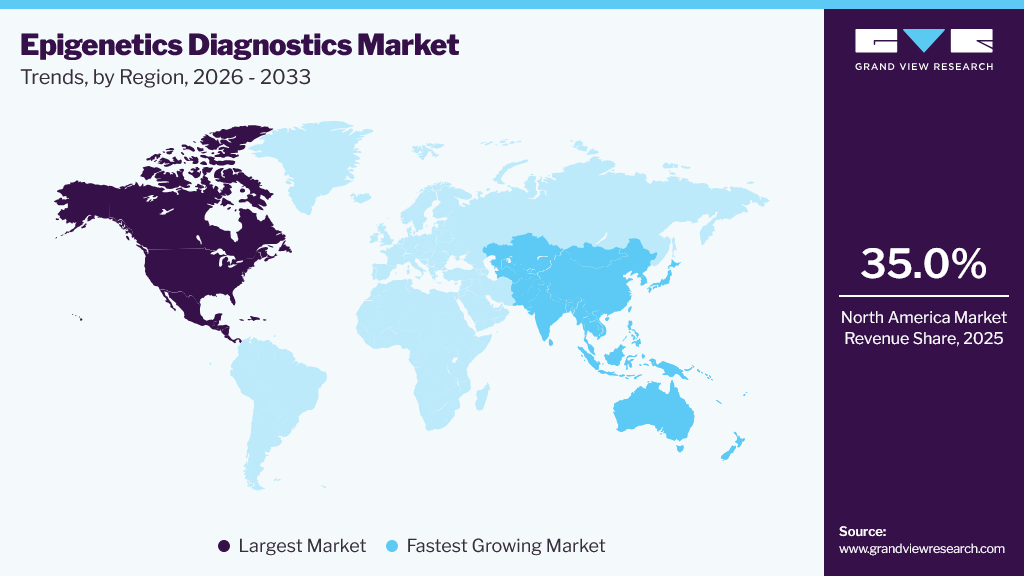
The North America epigenetics diagnostics market held the largest share of over 35.0% in 2025. High awareness among people, advanced medical infrastructure, and high R&D expenditure support the region's market growth. Moreover, the high prevalence of chronic diseases and the increasing investment by market participants in developing epigenetics will further boost regional growth.
U.S. Epigenetic Diagnostic Market Trends
The U.S. dominated the North American epigenetic diagnostics market in 2025 due to government support and funding, as well as increased investment in R&D for epigenetic research. In January 2024, the U.S. government allocated USD 1.5 million towards research-focused epigenetic reprogramming. This funding reflects a national commitment to advancing precision medicine and age-related disease management through epigenetic innovation.
Europe Epigenetic Diagnostics Market Trends
The European epigenetics diagnostics market was identified as a lucrative region in 2025. The increasing prevalence of chronic diseases and the adoption of advanced technology drive its growth. In January 2025, the European Commission launched the European Cancer Imaging Initiative platform, making imaging datasets, cancer-related data, and advanced analytics resources available across EU member states. The initiative is expected to accelerate cancer research, biomarker discovery, precision medicine, and the development of advanced diagnostic technologies, including epigenetics-based diagnostics. highlighting the growing prevalence and significant health burden of cancer across the region. The UK epigenetics diagnostics market held a substantial market share in 2025, driven by advancements in gene editing and increased focus on chronic diseases.
Asia Pacific Epigenetic Diagnostics Market Trends
The Asia Pacific epigenetic diagnostic market is anticipated to grow at a notable CAGR % from 2026 to 2033 owing to increasing investment in research & development activities by the government and growing incidences of cancer. For instance, in March 2025, BGI Genomics partnered with Chile-based Nomad Genetics to introduce its SENTIS™ Cancer+ Discovery (ctDNA) technology and support precision medicine initiatives through technology transfer and advanced molecular diagnostics. The collaboration highlights the growing adoption of genomics and epigenomics technologies for early disease detection and precision diagnostics, supporting the growth of the epigenetics diagnostics market across emerging regions. The growing adoption of epigenetics in developing economies will boost regional market growth during the forecast period. The Indian epigenetics diagnostics market is expected to grow at the fastest CAGR for the forecasted period. This is attributed to drivers such as increased research and development investments and advancements in sequencing technologies.
Key Epigenetics Diagnostics Company Insights
Technological advancements are expected to boost market growth over the forecast period. The market is consolidated due to the presence of major players, including Roche Diagnostics, Thermo Fisher Scientific, Inc., Eisai Co. Ltd., and Novartis AG. These players focus on growth strategies, such as new type launches, collaborations, partnerships, expansions, and mergers & acquisitions.
-
In March 2025, L’Oréal partnered with Tru Diagnostic to advance research on beauty and longevity. The collaboration will explore how epigenetic markers relate to skin and hair health, driving innovation in long-term beauty solutions.
-
In March 2025, the Ontario Brain Institute partnered with EpiSign to enhance the diagnosis of genetic disorders by leveraging AI and machine learning, ultimately improving patient outcomes.
-
In October 2025, EpiSign launched METRIC (Methylation-based Episignature Testing and Reference-based Interpretation & Classification), a cloud-based software platform designed to transform epigenomic diagnostics. The AI-powered solution enables healthcare providers and laboratories to efficiently interpret DNA methylation profiles and generate actionable clinical insights, improving access to epigenetic diagnostics worldwide.
Key Epigenetics Diagnostics Companies
The following key companies have been profiled for this study on the epigenetics diagnostics market.
-
Hoffmann- La Roche Ltd.
-
Thermo Fisher Scientific, Inc.
-
Eisai Co. Ltd.
-
Novartis AG
-
Element Biosciences, Inc.
-
Cantata Bio (Dovetail Genomics LLC.)
-
Illumina, Inc.
-
ValiRx plc.
-
Abcam Ltd.
Recent Developments
- In March 2025, the Ontario Brain Institute partnered with EpiSign to enhance the diagnosis of genetic disorders by leveraging AI and machine learning, ultimately improving patient outcomes.
Epigenetic Diagnostics Market Report Scope
Report Attribute
Details
Market size value in 2026
USD 17.5 billion
Market share value in 2025
USD 19.5 billion
Revenue forecast in 2033
USD 51.9 billion
Growth rate
CAGR of 15.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, technology, application, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Roche Diagnostics; Thermo Fisher Scientific, Inc.; Eisai Co. Ltd.; Novartis AG; Element Biosciences, Inc.; Cantata Bio (Dovetail Genomics LLC.); Illumina, Inc.; ValiRx Plc; Abcam plc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Epigenetics Diagnostics Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global epigenetic diagnostics market report based on product, technology, application, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Reagents
-
Kits
-
Chip Sequencing Kit
-
Whole Genomic Amplification kit
-
Bisulfite Conversion kit
-
RNA Sequencing kit
-
-
Instruments
-
Enzymes
-
Service
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Oncology
-
Solid Tumors
-
Others
-
-
Non - Oncology
-
Inflammatory Diseases
-
Metabolic Diseases
-
Infectious Diseases
-
Cardiovascular Diseases
-
Others
-
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
DNA Methylation
-
Reagents
-
Kits
-
Instruments
-
Enzymes
-
Services
-
-
Histone Methylation
-
Reagents
-
Kits
-
Instruments
-
Enzymes
-
Services
-
-
Histone Acetylation
-
Reagents
-
Kits
-
Instruments
-
Enzymes
-
Services
-
-
Large Non - Coding RNA
-
Reagents
-
Kits
-
Instruments
-
Enzymes
-
Services
-
-
MicroRNA Modification
-
Reagents
-
Kits
-
Instruments
-
Enzymes
-
Services
-
-
Chromatin Structures
-
Reagents
-
Kits
-
Instruments
-
Enzymes
-
Services
-
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Academic Research
-
Clinical Research
-
Hospitals & Clinics
-
Pharmaceutical & Biotechnology Companies
-
Other Users
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global epigenetics diagnostics market size was valued at USD 17.5 billion in 2025 and is estimated at USD 19.5 billion for 2026.
North America dominated with a 35.0% revenue share in 2025.
Key players include Roche Diagnostics; Thermo Fisher Scientific, Inc.; Eisai Co. Ltd.; Novartis AG; Element Biosciences, Inc.; Cantata Bio (Dovetail Genomics LLC.); Illumina, Inc.; ValiRx Plc; Abcam plc.
Oncology dominated the E-commerce logistics market with a share of 70.0% in 2025, while DNA methylation technology is the fastest-growing segment.
The global epigenetics diagnostics market is expected to grow at a CAGR of 15.0% from 2026 to 2033, reaching USD 51.9 billion.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


