
- Home
- »
- Animal Health
- »
-
Europe Veterinary Pharmaceuticals Market Size Report 2033GVR Report cover

Europe Veterinary Pharmaceuticals Market (2026 - 2033)
Size, Share & Trends Analysis Report By Animal (Production Animals, Companion Animals), By Product, By Drug Type, By Type, By Route of Administration, By Sales Channel, By Country, And Segment Forecasts
Market Size, 2025
$7.9BMarket Estimate, 2026
$8.6BMarket Forecast, 2033
$17.1BCAGR, 2026–2033
10.3%Europe Veterinary Pharmaceuticals Market Summary
The Europe veterinary pharmaceuticals market size was valued at USD 7.9 billion in 2025 and is projected to grow from USD 8.6 billion in 2026 to USD 17.1 billion by 2033, at a CAGR of 10.3% from 2026 to 2033. The growing awareness about zoonoses, the humanization of pets, the availability of pet insurance, and R&D initiatives by market players are the key factors anticipated to fuel market growth in the coming years.
Key Market Trends & Insights
- By animal: Production animals segment led the market with the largest revenue share of 65.4% in 2025.
- By product: Parasiticides segment led the market with the largest revenue share of 35.1% in 2025.
- By drug type: Branded segment led the market with the largest revenue share of 58.6% in 2025.
- By type: Prescription segment dominated the market, with a revenue share of 62.0% in 2025.
- By route of administration: Oral segment held the largest market share of 43.3% in 2025.
Market Size & Forecast
- Market Size in 2025: USD 7.9 Billion
- Estimated Market Size in 2026: USD 8.6 Billion
- Projected Market Size by 2033: USD 17.1 Billion
- CAGR (2026-2033): 10.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
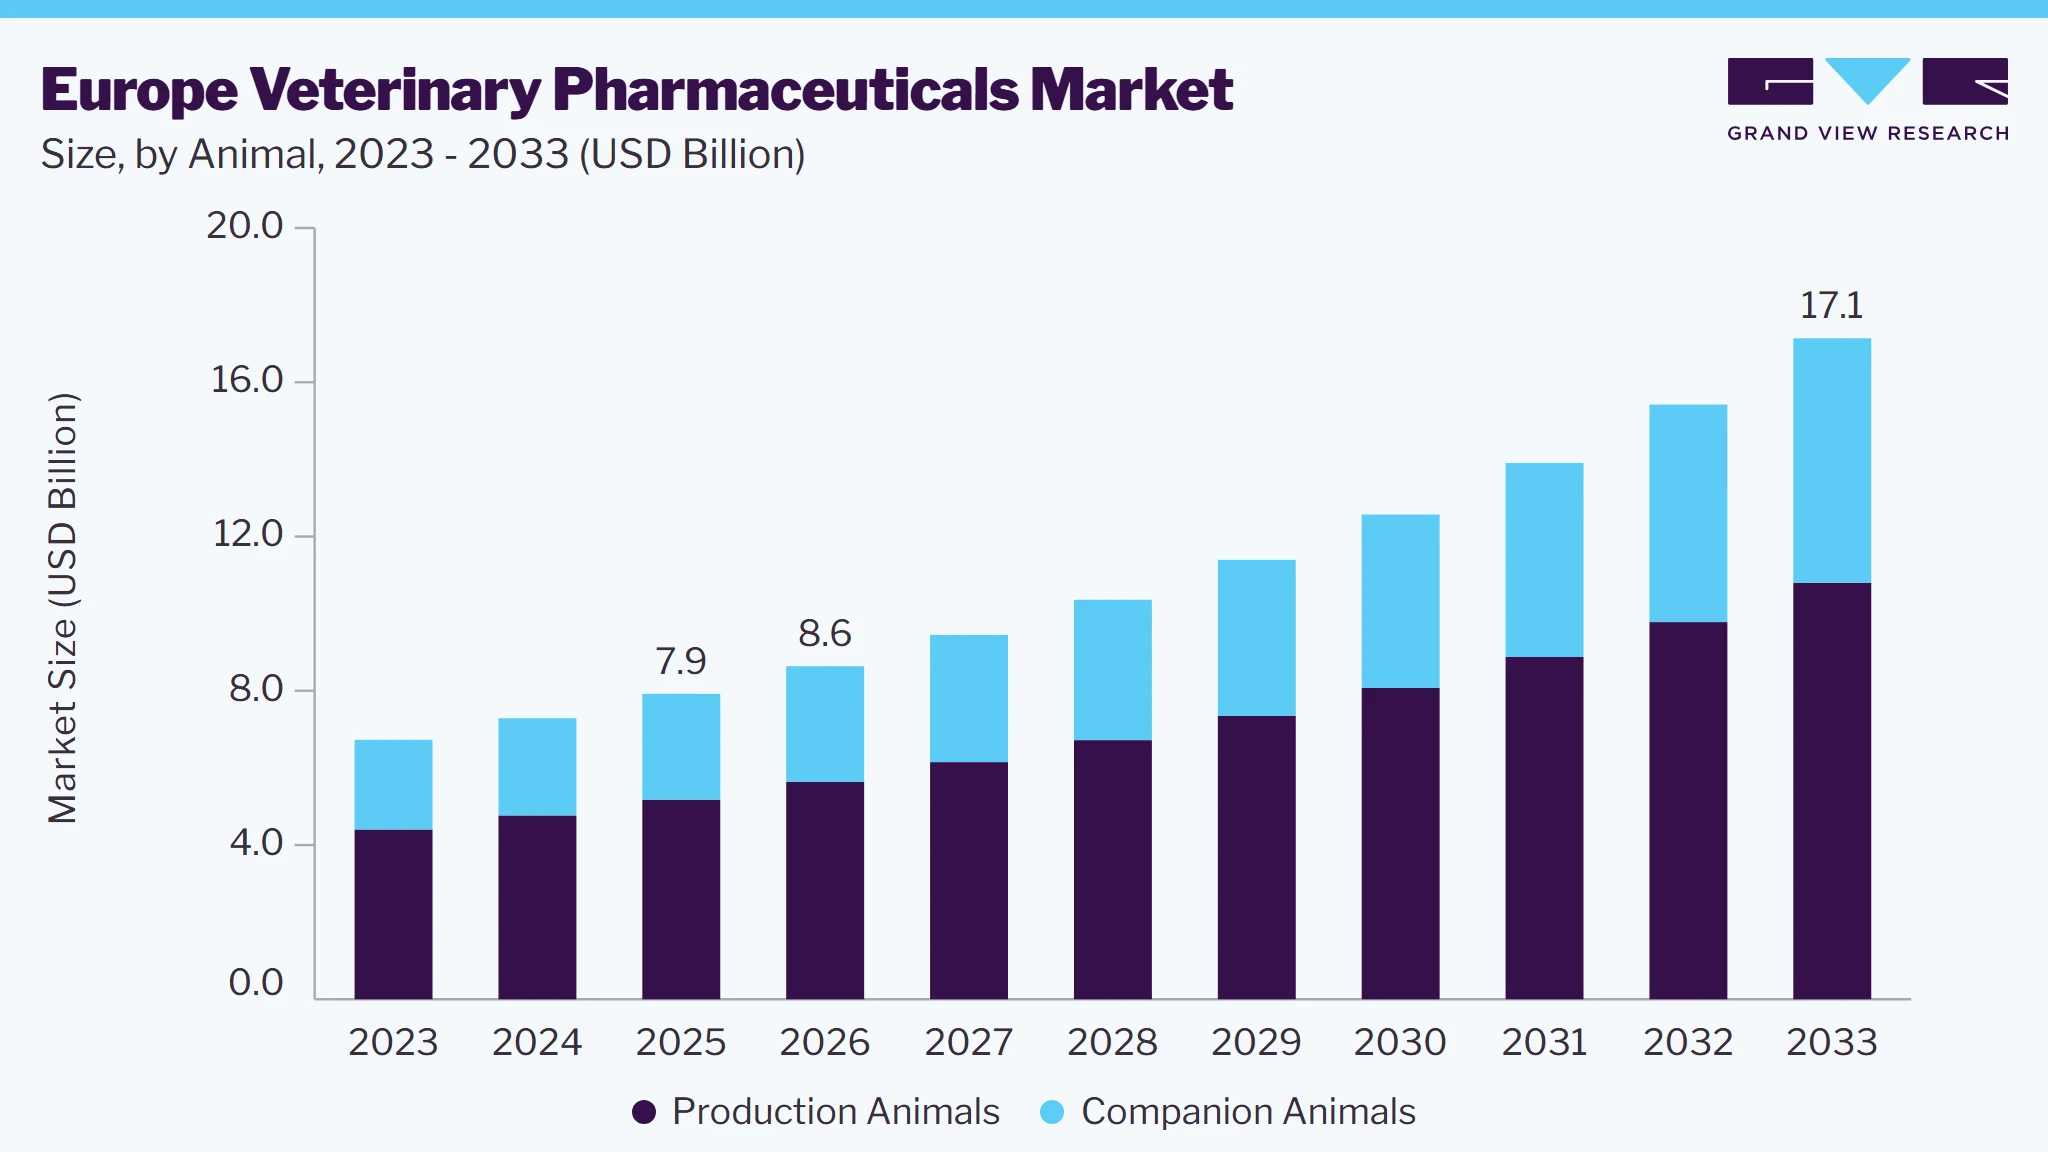 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Market Dynamics
The growing companion-animal population and increasing focus on preventive healthcare are key factors driving the Europe veterinary pharmaceutical market. In addition, higher pet ownership and rising attention to animal health are increasing demand for routine vaccinations, parasiticides, and treatments for infectious and chronic diseases, supporting recurring pharmaceutical consumption across veterinary clinics and hospitals. For instance, in June 2026, the European Pet Food Industry Federation (FEDIAF) reported that 140 million European households, representing 49% of households, owned pets, with the total pet population reaching 306 million.
Furthermore, the growing focus on preventive healthcare is encouraging pharmaceutical companies to develop products that protect companion animals against multiple infectious diseases and improve long-term disease management. For instance, in April 2025, the European Commission granted marketing authorization for Omeprazole TriviumVet, a gastro-resistant capsule for dogs indicated as an aid in treating non-steroidal anti-inflammatory drug (NSAID)-induced gastric ulceration. This authorization expands the range of oral medicines available for veterinary gastrointestinal care.
Stringent regulatory requirements and high product development costs are key factors restraining the Europe veterinary pharmaceutical market. Manufacturers must demonstrate the safety, quality, and efficacy of veterinary medicines and comply with applicable manufacturing standards, pharmacovigilance, and post-marketing surveillance requirements to obtain and maintain marketing authorizations. These obligations increase development expenditure and extend the time required to commercialize new products, particularly for smaller manufacturers and companies developing specialized treatments for less commercially attractive animal diseases. In addition, the costs associated with clinical trials, regulatory documentation, quality control, and ongoing compliance can limit investment in new product development and reduce the commercial viability of certain medicines. Consequently, regulatory complexity and high compliance costs can delay product launches, discourage market entry, and constrain the availability of specialized veterinary pharmaceuticals across Europe.
The growing need for effective treatments for chronic diseases in companion animals presents an opportunity for the Europe veterinary pharmaceutical market. Increasing attention to the long-term management of conditions such as diabetes, cardiovascular disorders, and osteoarthritis is creating scope for pharmaceutical manufacturers to develop disease-specific medicines and improve existing treatment options. The development of oral therapies and alternative treatment approaches can also broaden the options available to veterinarians and pet owners, particularly when conventional treatments require ongoing administration. For instance, in August 2026, the European Commission granted marketing authorization to Bexatil (bexagliflozin), a tablet indicated for reducing high blood glucose levels in cats with diabetes mellitus that have not previously received insulin treatment. This approval expands the range of pharmacological options available for feline diabetes management and creates opportunities for pharmaceutical companies to develop specialized treatments for chronic companion-animal conditions, broaden their therapeutic portfolios, and address evolving veterinary healthcare needs.
Market Concentration & Characteristics
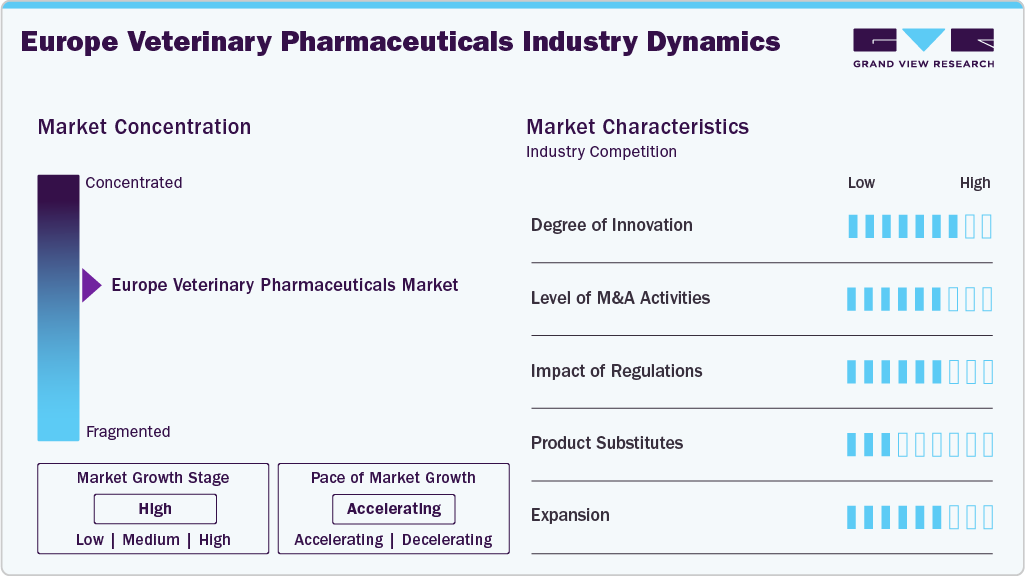
The Europe veterinary pharmaceuticals market demonstrates a diverse competitive landscape, comprising established multinational animal health companies, specialized veterinary pharmaceutical manufacturers, and regional players offering vaccines, anti-infectives, parasiticides, anti-inflammatory drugs, biologics, and other veterinary medicines. In addition, key participants are benefitting from broad product portfolios, established relationships with veterinarians and distributors, strong research and development capabilities, and expertise in European regulatory requirements.
The degree of innovation in the Europe veterinary pharmaceuticals market is moderate to high, driven by combination parasiticides, targeted therapies, biologics, and improved formulations. For instance, in July 2025, Elanco Animal Health secured received European Commission approval for Zenrelia (ilunocitinib), a once-daily oral tablet for controlling pruritus associated with allergic dermatitis and clinical manifestations of atopic dermatitis in dogs aged at least 12 months. Such advances expand treatment options, support parasite control, and address health needs across companion and production animals.
 To learn more about this report, Download Free Sample Report
The Europe Veterinary Pharmaceuticals Market indicates a moderate level of merger and acquisition (M&A) activity, characterized by targeted acquisitions of specialty medicines and established pharmaceutical portfolios. In addition, companies are seeking to expand their therapeutic offerings, gain access to niche treatments, and improve distribution across companion and livestock animal segments. For instance, in April 2025, Swedencare completed its acquisition of UK-based Summit Veterinary Pharmaceuticals, expanding its specialty veterinary medicine portfolio for dogs, cats, horses, and veterinary clinics. Such developments support portfolio diversification and access to specialized treatments.
Regulations have a high impact on the Europe Veterinary Pharmaceuticals Market because product marketing authorization, safety assessment, environmental risk evaluation, and post-marketing pharmacovigilance determine market entry and continued product availability. The EU Veterinary Medicinal Products Regulation (EU) 2019/6 establishes harmonized requirements while providing centralized and national authorization pathways. These requirements increase compliance costs and documentation requirements but support product quality, safety, and cross-border market access. Furthermore, restrictions on routine antimicrobial use and growth promotion affect demand for anti-infectives and encourage more targeted treatment approaches.
The threat of product substitutes in the Europe veterinary pharmaceuticals market is low to moderate, as alternative disease-prevention and animal-health management approaches can reduce pharmaceutical use in selected applications. Vaccination, improved farm biosecurity, hygiene, and better animal husbandry can lower the incidence of infectious diseases, while probiotics, prebiotics, bacteriophages, and immunomodulators are being investigated as alternatives to certain antimicrobial treatments.
Regional expansion in the Europe Veterinary Pharmaceuticals Market is driven by investments in manufacturing capacity, wider product distribution, and the expansion of established veterinary medicine portfolios across European countries. In addition, companies are strengthening regional production capabilities to meet demand for medicines used in companion and livestock animals, improve supply continuity, and serve export markets. For instance, in March 2025, Elanco initiated an expansion of its manufacturing facility in Huningue, France, with an investment of USD 39.5 million. The expansion supports the supply of companion-animal medicines, including antiparasitics and anti-inflammatory products, and strengthens the company's European manufacturing base.
Analyst Perspective
The Europe veterinary pharmaceuticals market is entering a phase where therapeutic specialization, product portfolio breadth, regulatory compliance, and distribution reach are becoming stronger determinants of competitive position than basic medicine availability. Established pharmaceutical categories, including parasiticides, anti-infectives, analgesics, and anti-inflammatory medicines, remain central to routine animal healthcare, while specialized treatments for chronic companion-animal conditions and disease management in production animals are creating opportunities for portfolio expansion. Manufacturers are competing through improvements in oral, injectable, and topical formulations, alongside branded and generic product offerings. At the same time, antimicrobial stewardship, pharmacovigilance requirements, generic competition, and differences in national market access are influencing product development and commercialization strategies across Europe.
Animal Insights
The production animal segment accounted for the largest share of 65.4% in 2025.The segment includes cattle, pigs, sheep, goats, poultry, and other livestock species that require pharmaceutical products to prevent and treat infectious diseases, parasitic infestations, inflammatory conditions, and other animal health disorders. The demand is increasing as commercial livestock producers seek to maintain herd and flock health, reduce mortality, improve productivity, and comply with animal health and food safety requirements. The growing use of parasiticides, anti-infectives, and anti-inflammatory drugs across European livestock farming is further supporting segment demand.
The companion animals segment is anticipated to register the fastest CAGR during the forecast period. The segment includes dogs, cats, horses, and other companion animals that require pharmaceutical products for the prevention and treatment of infectious diseases, parasitic infestations, inflammatory conditions, and chronic disorders. In addition, increasing pet humanization and growing demand for preventive treatments are supporting segment growth across Europe.
R&D Landscape
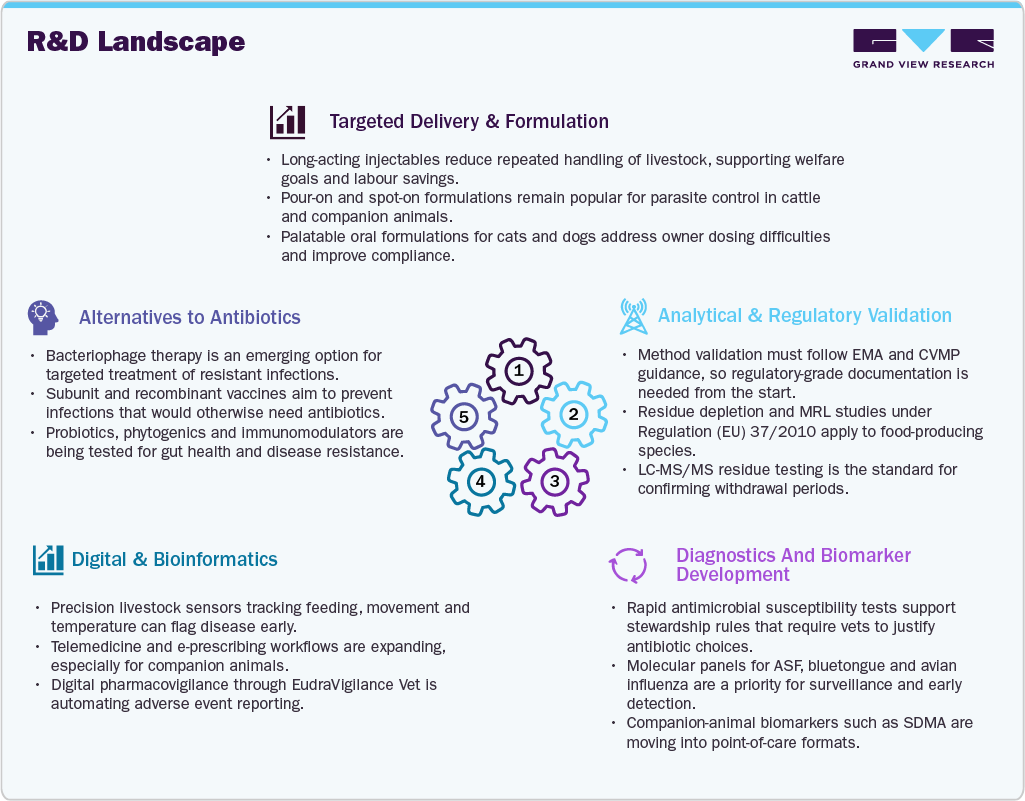
Research and development in the Europe veterinary pharmaceuticals market is being shaped by antimicrobial stewardship requirements, regulatory compliance, advances in diagnostic technologies, and demand for improved treatment outcomes. Regulation (EU) 2019/6 restricts the prophylactic use of antimicrobials and prohibits their use for growth promotion, creating opportunities for rapid diagnostic testing, preventive vaccines, and alternatives to conventional antibiotics.
 To learn more about this report, Download Free Sample Report
In addition, key innovation areas include molecular diagnostics and biomarkers for early disease detection, analytical testing and regulatory validation, long-acting injectable and palatable formulations that improve treatment administration, and alternative therapies such as bacteriophages, probiotics, phytogenics, and immunomodulators. Digital technologies, including precision livestock monitoring, electronic prescribing, and automated pharmacovigilance systems, are supporting data-driven veterinary care and pharmaceutical safety management.
Product Insights
The parasiticides segment dominated the Europe veterinary pharmaceuticals market, accounting for 35.1% of the market in 2025. The segment is driven by the widespread need to prevent and treat endoparasitic and ectoparasitic infestations across companion and livestock animals. Dogs and cats require regular protection against fleas, ticks, mites, and intestinal worms, while livestock requires parasite control to maintain animal health, productivity, and welfare. In addition, the availability of oral, topical, and injectable parasiticides supports treatment adoption across European veterinary practices and livestock farms.
The other product anticipated to register the fastest CAGR during the forecast period. It comprises veterinary pharmaceutical products used to treat conditions outside the major therapeutic categories of parasiticides, anti-infectives, analgesics, and anti-inflammatory drugs. The segment is driven by the need to manage diverse health conditions across companion and livestock animals, including reproductive disorders, digestive problems, respiratory diseases, and conditions requiring anesthesia or sedation.
Drug Type Insights
The branded segment accounted for the largest market share of 58.6% in 2025. This is attributed to the presence of established veterinary pharmaceutical companies, strong brand recognition, and veterinarians' familiarity with existing products. Branded medicines benefit from established distribution networks, product quality standards, and government authorizations. In addition, continuous product development and the availability of medicines for a wide range of animal diseases also support demand throughout veterinary clinics, hospitals, and livestock farms.
The generics segment is projected to register the highest CAGR over the forecast period. The growth is supported by the lower cost of generic veterinary medicines compared with branded alternatives, making treatments more affordable for clinics, animal owners, and livestock producers. In addition, the availability of generic medicines also increases treatment options for common animal diseases. For instance, in April 2025, the European Medicines Agency published a positive opinion for Emevet, a generic veterinary medicine containing maropitant for treating conditions such as vomiting in animals. The availability of such products supports competition and access to affordable veterinary treatments across Europe.
Type Insights
The prescription segment accounted for the largest market share of 62.0% in 2025. This is attributed to the need for veterinary diagnosis and professional supervision when treating complex animal diseases. Prescription medicines are widely used to treat bacterial infections, inflammatory conditions, and other health problems requiring specific treatment plans. In addition, regulations governing the sale and use of certain veterinary medicines support demand through veterinary hospitals and clinics. The availability of prescription treatments for companion and livestock animals further contributes to segment growth.
The OTC segment is projected to register the highest CAGR over the forecast period. The segment is driven by rising pet ownership, greater awareness of animal health, and demand for accessible treatment options. OTC veterinary medicines allow animal owners to manage certain minor health conditions and routine healthcare needs without obtaining a prescription, where permitted by regulations. In addition, wider availability through veterinary pharmacies, retail outlets, and online channels is expected to improve product access. Growing interest in preventive animal healthcare is anticipated to support segment growth.
Route of Administration Insights
The oral segment accounted for the largest market share of 43.3% in 2025, driven due to the ease of administration, convenience, and wide availability of veterinary medicines in the form of tablets, capsules, liquids, and powders. Oral medicines are used to treat infections, digestive disorders, and other health conditions in companion and livestock animals. They allow pet owners to administer treatments at home and enable livestock producers to provide medicines through feed or drinking water, where appropriate. The increasing developments are further increasing the segment growth. For instance, in September 2026, the European Medicines Agency (EMA) recommended an update to the marketing authorization for Firocoxib CP-Pharma chewable tablets to add horses as a target species for treating pain and inflammation associated with osteoarthritis. This development supports the use of oral veterinary medicines across additional animal species.
The other routes segment is projected to register the highest CAGR over the forecast period. The other routes segment includes veterinary pharmaceutical products administered through ophthalmic, otic, intranasal, inhalation, rectal, vaginal/intrauterine, transdermal, and other specialized routes. The growth for these products is driven by the need for targeted treatment of eye and ear infections, respiratory conditions, and reproductive health problems in companion and livestock animals. These administration routes provide alternative treatment options when oral or injectable medicines are unsuitable or difficult to administer. Advancements in drug formulations and delivery systems are also supporting the availability of specialized veterinary medicines. The growing need for effective treatment across different animal species is expected to support segment growth in Europe.
Sales Channel Insights
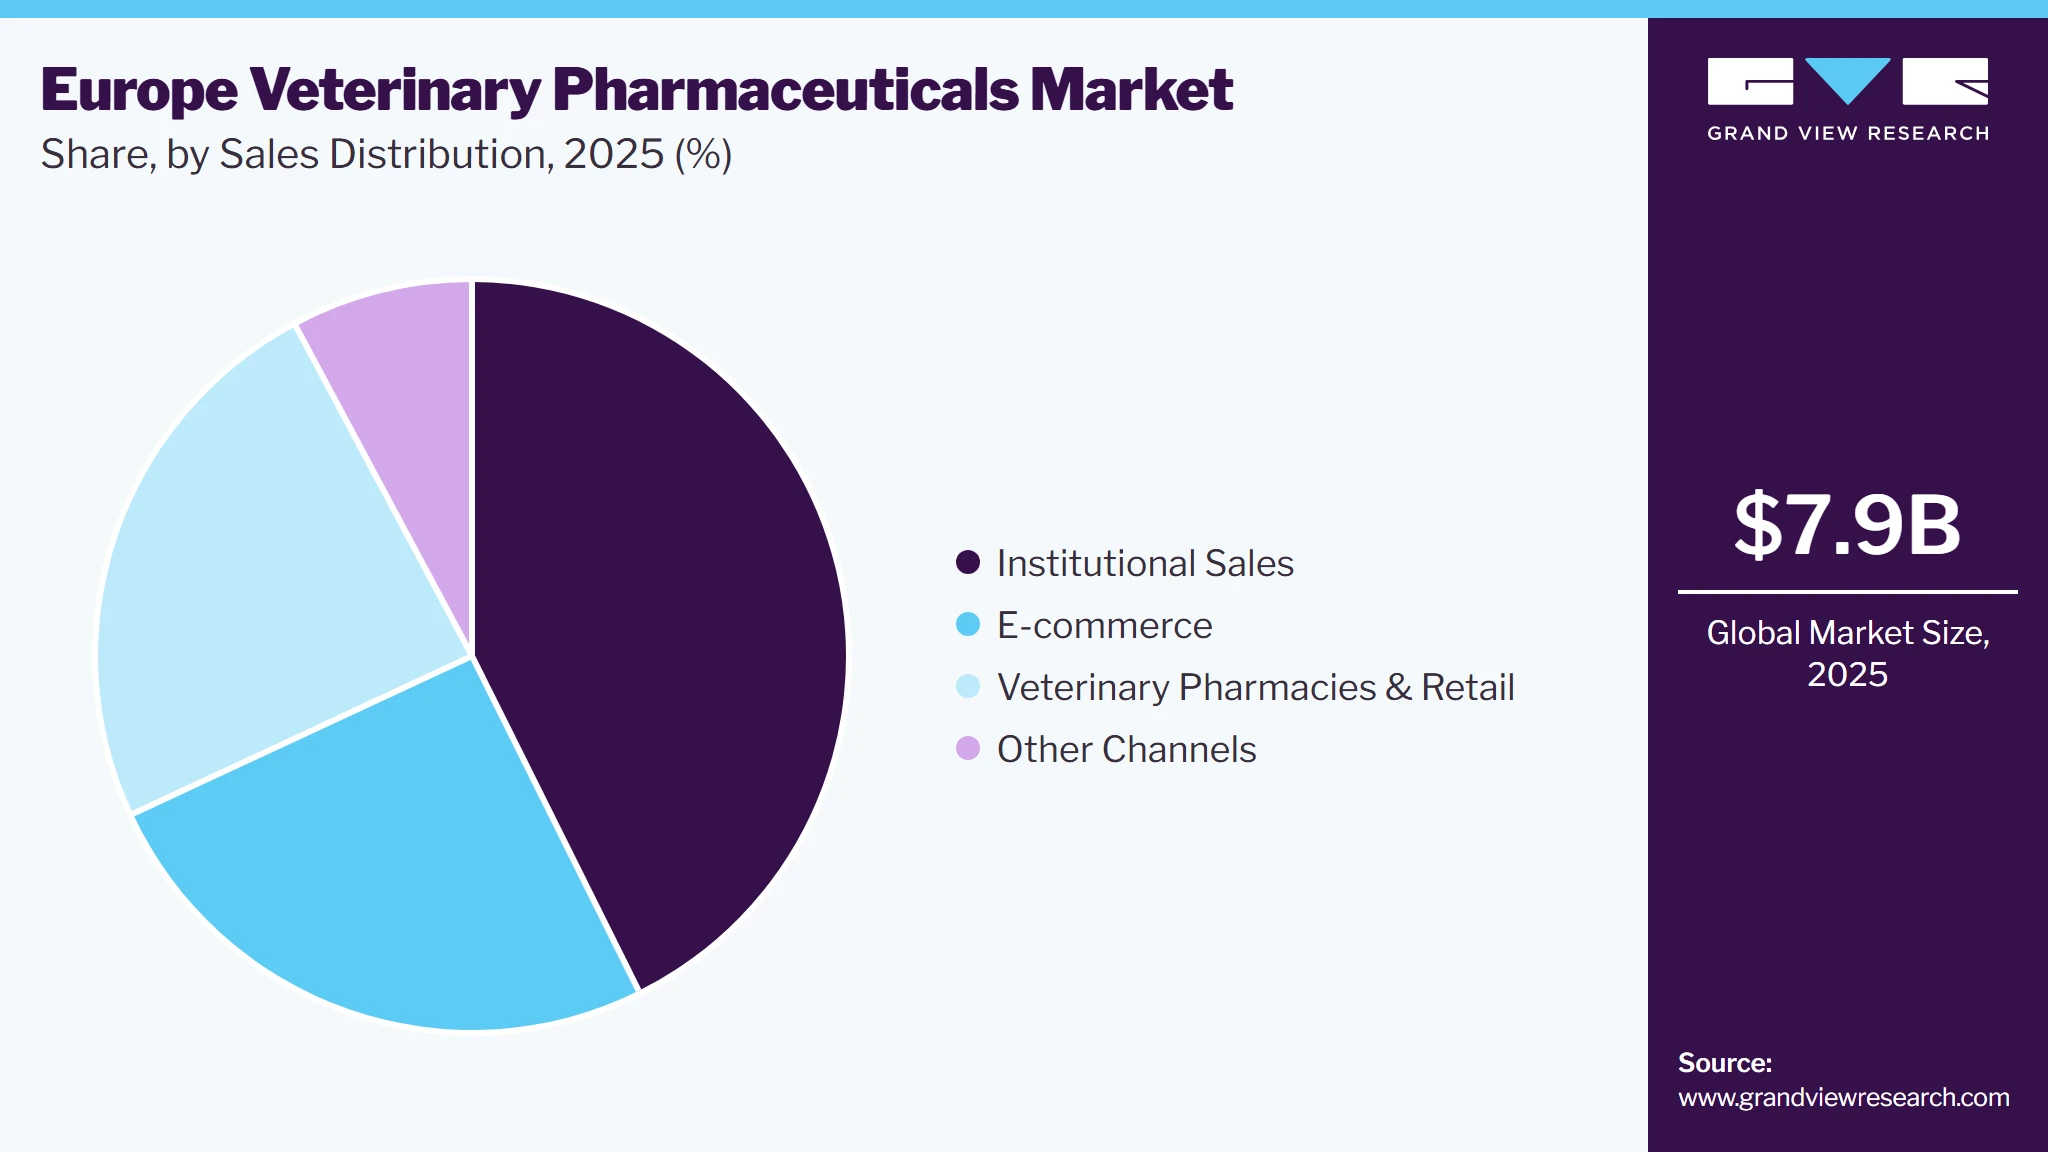
The institutional sales segment led the Europe veterinary pharmaceuticals market, accounting for the largest revenue share of 42.6% in 2025. The segment is fueled by regular pharmaceutical purchases by veterinary hospitals, clinics, commercial livestock producers, and integrated farms. These buyers require medicines across various therapeutic categories to treat animal diseases and maintain animal health. The growing demand for companion animal healthcare and disease management in livestock operations further supports institutional purchases. In addition, established procurement relationships and the need for a consistent supply of veterinary medicines also contribute to segment growth. The segment is expected to maintain its leading position as veterinary professionals and organized livestock producers remain major purchasers of veterinary pharmaceutical products.
 To learn more about this report, Download Free Sample Report
The e-commerce segment is expected to register the fastest CAGR over the forecast period, driven by the convenience of online purchasing, wider product availability, and home delivery of eligible veterinary pharmaceutical products. Online platforms allow companion animal owners to purchase routine healthcare products, including eligible parasiticides and other non-prescription medicines. The expansion of digital retail platforms and greater use of online shopping are also improving access to veterinary products across Europe. In addition, demand for recurring-use products supports repeat online purchases. However, the sale of prescription veterinary medicines remains subject to applicable European and national regulations, which influence the range of products available through e-commerce channels.
Country Insights
Germany’s veterinary pharmaceuticals marketis driven by companion animal population and demand for preventive treatments and medicines for acute and chronic conditions. According to the ZZF, Germany had 15.7 million cats and 10.0 million dogs in 2025, with companion animals present in 43% of households. This population supports recurring demand for parasiticides, anti-infectives, analgesics, anti-inflammatory products, and specialty medicines distributed through veterinary hospitals and clinics. Pharmaceutical innovation for chronic conditions is expanding treatment options for companion animals. For instance, in July 2025, the European Commission granted marketing authorization to Numelvi (atinvicitinib), an oral veterinary medicine for dogs experiencing pruritus associated with allergic dermatitis and clinical manifestations of atopic dermatitis. This development expands the availability of targeted dermatological treatments and supports demand for prescription veterinary medicines in Germany.
The UK veterinary pharmaceuticals market is supported by demand for companion-animal treatments and pharmaceutical interventions across livestock production. Routine parasite prevention, infection management, pain control, and vaccination programs contribute to medicine procurement by veterinary practices, animal hospitals, and livestock producers. The need to manage infectious diseases in cattle and sheep sustains demand for parasiticides, anti-infectives, anti-inflammatory medicines, analgesics, and vaccines to reduce disease-related health risks and production losses. In companion animals, the management of chronic conditions and acute illnesses further supports demand for prescription veterinary medicines, while established veterinary healthcare infrastructure facilitates access to a broad range of pharmaceutical products.
The Sweden veterinary pharmaceutical market is expected to grow at the fastest CAGR over the forecast period. The country is driven by demand for companion-animal healthcare, livestock disease management, and preventive treatments. In addition, rising demand for parasiticides, and medicines for infectious and chronic diseases supports pharmaceutical consumption across veterinary clinics and hospitals. In livestock, cattle health management and disease prevention contribute to demand for veterinary medicines. Furthermore, Sweden’s strict regulatory requirements influence prescribing patterns and product selection, creating opportunities for manufacturers of approved vaccines, targeted therapies, and other preventive treatments.
Key Europe Veterinary Pharmaceuticals Company Insights
The Europe veterinary pharmaceuticals market is highly competitive, with leaders competing through broad portfolios, strong R&D capabilities, regulatory approvals, manufacturing scale, and extensive veterinary distribution networks. Competition is further intensified by specialized players targeting specific vaccine technologies, species, and regional markets. Market share remains distributed across leading companies rather than dominated by a single participant, creating a fragmented competitive structure.
Key Europe Veterinary Pharmaceuticals Companies
-
Merck & Co., Inc.,
-
Ceva
-
Vetoquinol
-
Zoetis Services LLC
-
Boehringer Ingelheim International GmbH
-
Elanco
-
Virbac
-
Calier
-
Bimeda Corporate
-
Prodivet Pharmaceuticals SA/NV
Recent Developments:
-
In June 2026, Alivira Animal Health, a subsidiary of Viyash Scientific Limited, signed a binding agreement to acquire 100% of Italy-based BioForLife Italia, a company specializing in companion-animal medicines, nutritional supplements, and rapid diagnostic tests. The acquisition is intended to expand Alivira’s presence in Italy, facilitate the introduction of its pipeline products, and broaden its companion-animal healthcare portfolio, supporting growth in the Europe veterinary pharmaceuticals market.
-
In 2025, the European Medicines Agency (EMA) reported expanded indications for Bravecto TriUNO for treating Angiostrongylus vasorum infections in dogs and NexGard and NexGard Spectra for reducing the risk of certain parasite-transmitted infections. Such developments support demand for parasite-control products across Europe.
Europe Veterinary Pharmaceuticals Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.9 billion
Estimated market size in 2026
USD 8.6 billion
Projected market size by 2033
USD 17.1 billion
Growth rate
CAGR of 10.3% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Animal, product, drug type, type, route of administration, sales channel, country
Regional scope
Europe
Country scope
Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway
Key companies profiled
Merck & Co., Inc.; Ceva; Vetoquinol; Zoetis Services LLC; Boehringer Ingelheim International GmbH; Elanco; Virbac; Calier; Bimeda Corporate; Prodivet pharmaceuticals sa/nv
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Europe Veterinary Pharmaceuticals Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the Europe veterinary pharmaceuticals market report based on animal type, product, drug type, type, route of administration, sales channel, and country.
-
Animal Outlook (Revenue, USD Million, 2021 - 2033)
-
Production Animals
-
Poultry
-
Swine
-
Bovine
-
Ovine & Caprine
-
Others
-
-
Companion Animals
-
Canine
-
Feline
-
Equine
-
Others
-
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Parasiticides
-
Anti-infectives
-
Anti-inflammatory
-
Analgesics
-
Other Products
-
-
Drug Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Branded
-
Generics
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Prescription
-
OTC
-
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Oral
-
Injectable
-
Topical
-
Other Routes
-
-
Sales Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Institutional Sales
-
Veterinary Pharmacies & Retail
-
E-Commerce
-
Other Channels
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
Research Methodology
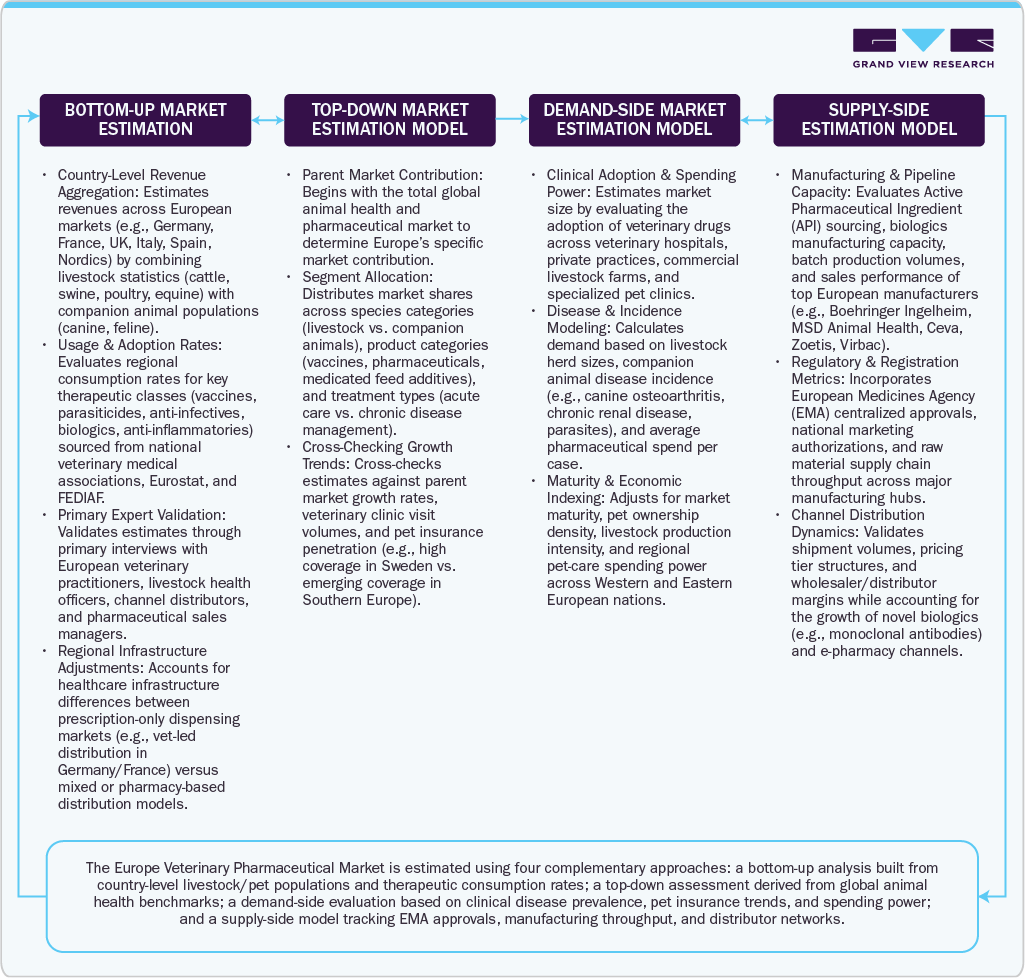
The Europe veterinary pharmaceuticals market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Europe veterinary pharmaceuticals segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Production Animal
Definition
Poultry
The segment captures revenue generated from veterinary pharmaceutical products used in commercially raised birds for meat, egg production, breeding, and other agricultural purposes across Europe.
Swine
The segment captures revenue generated from veterinary pharmaceutical products used in pigs across breeding, nursery, growing, and finishing stages to prevent, control, or treat health conditions in Europe.
Bovine
The segment captures revenue generated from veterinary pharmaceutical products used in cattle and buffalo across beef, dairy, breeding, growing, and other production systems in Europe.
Ovine & Caprine
The segment captures revenue generated from veterinary pharmaceutical products used in sheep and goats raised for meat, milk, fiber, breeding, and other commercial production purposes across Europe.
Others
The segment captures revenue generated from veterinary pharmaceutical products used in production-animal species not separately classified under poultry, swine, bovine, or ovine and caprine categories in Europe.
Companion Animal
Definition
Canine
The segment captures revenue generated from veterinary pharmaceutical products formulated for dogs across breeds, sizes, ages, life stages, and health conditions in Europe.
Feline
The segment captures revenue generated from veterinary pharmaceutical products formulated for domestic cats across different life stages and health conditions in Europe.
Equine
The segment captures revenue generated from veterinary pharmaceutical products used in horses and other domesticated equids kept for companionship, recreation, sport, breeding, or working purposes across Europe.
Others
The segment captures revenue generated from veterinary pharmaceutical products intended for companion and specialty animals other than dogs, cats, and equines in Europe.
Product
Definition
Parasiticides
The segment captures revenue generated from veterinary pharmaceutical products intended to prevent, control, or treat parasitic infections and infestations in animals across Europe.
Anti-infectives
The segment captures revenue generated from veterinary pharmaceutical products intended to prevent or treat infectious diseases caused by susceptible bacterial, viral, fungal, and other pathogenic organisms in animals across Europe.
Analgesics
The segment captures revenue generated from veterinary pharmaceutical products primarily intended to manage or reduce pain in animals across Europe.
Anti-inflammatory
The segment captures revenue generated from veterinary pharmaceutical products primarily intended to reduce or manage inflammation and associated inflammatory conditions in animals across Europe.
Other Products
The segment captures revenue generated from veterinary pharmaceutical products addressing therapeutic areas not separately classified under parasiticides, anti-infectives, analgesics, or anti-inflammatory products in Europe.
Drug Type
Definition
Branded
The segment captures revenue generated from veterinary pharmaceutical products marketed under proprietary brand names owned or licensed by manufacturers or marketing authorization holders in Europe.
Generics
The segment captures revenue generated from veterinary pharmaceutical products containing active ingredients equivalent to established reference products and marketed as generic or non-originator products in Europe.
Type
Definition
Prescription
The segment captures revenue generated from veterinary pharmaceutical products that require a veterinary prescription or other legally authorized professional authorization under applicable European regulations.
OTC
The segment captures revenue generated from veterinary pharmaceutical products legally available for purchase without a veterinary prescription across applicable European markets.
Route of Administration
Definition
Oral
The segment captures revenue generated from veterinary pharmaceutical products administered through the mouth or in oral dosage forms to animals across Europe.
Injectable
The segment captures revenue generated from veterinary pharmaceutical products administered by injection into an animal's body across Europe.
Topical
The segment captures revenue generated from veterinary pharmaceutical products applied directly to the skin, coat, or localized external body surfaces of animals across Europe.
Other Routes
The segment captures revenue generated from veterinary pharmaceutical products administered through routes other than oral, injectable, or topical administration across Europe.
Sales Channel
Definition
Institutional Sales
The segment captures revenue generated from veterinary pharmaceutical products sold to institutional and professional animal-health customers, including veterinary practices, hospitals, farms, and other large end users across Europe.
Veterinary Pharmacies & Retail
The segment captures revenue generated from veterinary pharmaceutical products sold through veterinary pharmacies, animal-health retailers, specialty stores, and other specialized retail outlets across Europe, including prescription and OTC products where legally permitted.
E-commerce
The segment captures revenue generated from veterinary pharmaceutical products sold through internet-based channels, including online retailers and digital intermediaries, in accordance with applicable European regulations.
Other Channels
The segment captures revenue generated from veterinary pharmaceutical products sold through channels not separately classified under institutional sales, veterinary pharmacies and retail, or e-commerce in Europe.
Estimation Model
 To learn more about this report, Download Free Sample Report
Customization Table
Client Request
Customization Delivered
Value Adds
Market Intelligence & Stakeholder GTM Study: Europe Veterinary Pharmaceuticals (Companion & Livestock)
Detailed evaluation of European veterinary reference networks, veterinary hospital groups (IVC Evidensia, AniCura, VetPartners), and livestock integrators across EU-27 & UK. Covers pharmaceutical adoption for parasiticides, biologics/vaccines, anti-infectives under EMA Regulation (EU) 2019/6, and chronic disease management. Includes target customer segmentation, pricing elasticity analysis, and phased market-entry roadmaps.
Supports European market-entry sequencing, prioritizes corporate veterinary clinic groups for early formulation adoption, and strengthens product positioning against legacy therapeutics under strict EU antimicrobial stewardship guidelines. Enables alignment with EMA clinical guidelines and EU online pharmacy/dispensing standards.
Regulatory & Trade-Flow Assessment: European Veterinary Pharmaceuticals
In-depth assessment of EMA (CVMP) centralized/national authorization pathways, EU Maximum Residue Limits (MRLs), and GMP standards (EudraLex Vol. 4). Covers country-level registration requirements across target EU member states and UK (VMD), bioequivalence benchmarks, clearance timelines, and supply chain cold-chain logistics. Identifies regulatory bottlenecks and EU-wide digital prescription tracking mandates.
Helps organizations select optimal formulation pathways, anticipate EMA approval timelines, minimize compliance risks, and structure European distribution partnerships to streamline market entry.
Competitive Benchmarking: European Veterinary Pharmaceutical Suppliers in Key Growth Markets
Comparative profiling of established and emerging veterinary pharma suppliers active in Europe (Zoetis, Boehringer Ingelheim, MSD, Elanco, Virbac, Ceva, Dechra, Vetoquinol). Evaluates species focus (companion animals, bovine, porcine, poultry, equine, aquaculture), active portfolio breadth (parasiticides, anti-infectives, NSAIDs), manufacturing footprint, and regional distributor alliances. Includes SWOT analysis and identification of white-space opportunities in novel therapeutics..
Enables clients to map competitive gaps in the European veterinary market, identify corporate clinic or regional distributor partnership opportunities, benchmark pharmaceutical pricing, and design differentiated go-to-market strategies tailored to EU disease priorities.
Frequently Asked Questions About This Report
The production animal segment led with a 65.4% revenue share in 2025 while companion animals segment is expected to be the fastest-growing market.
Some key players operating in the Europe veterinary pharmaceuticals market include MSD, Ceva, Vetoquinol S.A., Zoetis, Boehringer Ingelheim GmbH, Elanco, Virbac, Calier, Bimeda, Inc., and Prodivet Pharmaceuticals sa/nv.
Key factors that are driving the Europe veterinary pharmaceuticals market growth include growing pet ownership, increasing livestock population, and rising adoption of pet insurance.
Prescription segment dominated the market, with a revenue share of 62.0% in 2025.
The parasiticides segment led with a 35.1% revenue share in 2025.The segment is driven by the widespread need to prevent and treat endoparasitic and ectoparasitic infestations across companion and livestock animals.
The branded segment led with a 58.6% revenue share in 2025 and generics segment is second fastest growing market
The Europe veterinary pharmaceutical market size was valued at USD 7.9 billion in 2025 and is estimated at USD 8.6 billion for 2026.
The Europe veterinary pharmaceuticals market is expected to grow at a CAGR of 10.3% from 2026 to 2033, reaching USD 17.1 billion by 2033.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


