
- Home
- »
- Advanced Interior Materials
- »
-
Flare Gas Recovery System Market Size Report, 2026-2033GVR Report cover

Flare Gas Recovery System Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Compressor-Based Systems), By Pressure (6 To 10 Bar), By Flow Rate (3 To 5 MMSCFD), By End Use (Oil & Gas), By Region (Europe, Asia Pacific), And Segment Forecasts
Market Size, 2025
$2.5BMarket Estimate, 2026
$2.6BMarket Forecast, 2033
$3.8BCAGR, 2026–2033
5.6%Flare Gas Recovery System Market Summary
The global flare gas recovery system market size was valued at USD 2.5 billion in 2025 and is projected to grow from USD 2.6 billion in 2026 to USD 3.8 billion by 2033, at a CAGR of 5.6% from 2026 to 2033. North America dominated the flare gas recovery system market with the largest revenue share of 32.0% in 2025. The flare gas recovery system (FGRS) market is experiencing significant growth, driven by stringent environmental regulations and the economic benefits of capturing and repurposing flare gas.
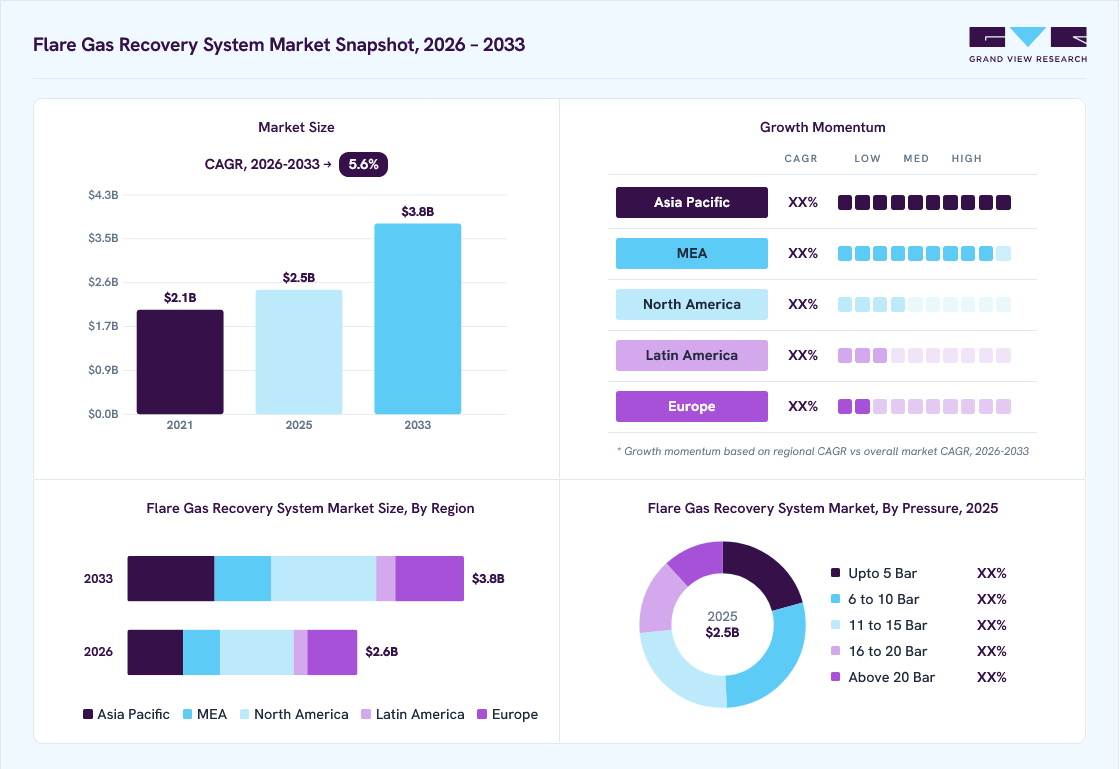 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Compressor-based systems segment held the largest market share of 76.0% in 2025.
- By pressure: 6 to 10 bar segment held the largest market share of 28.4% in 2025.
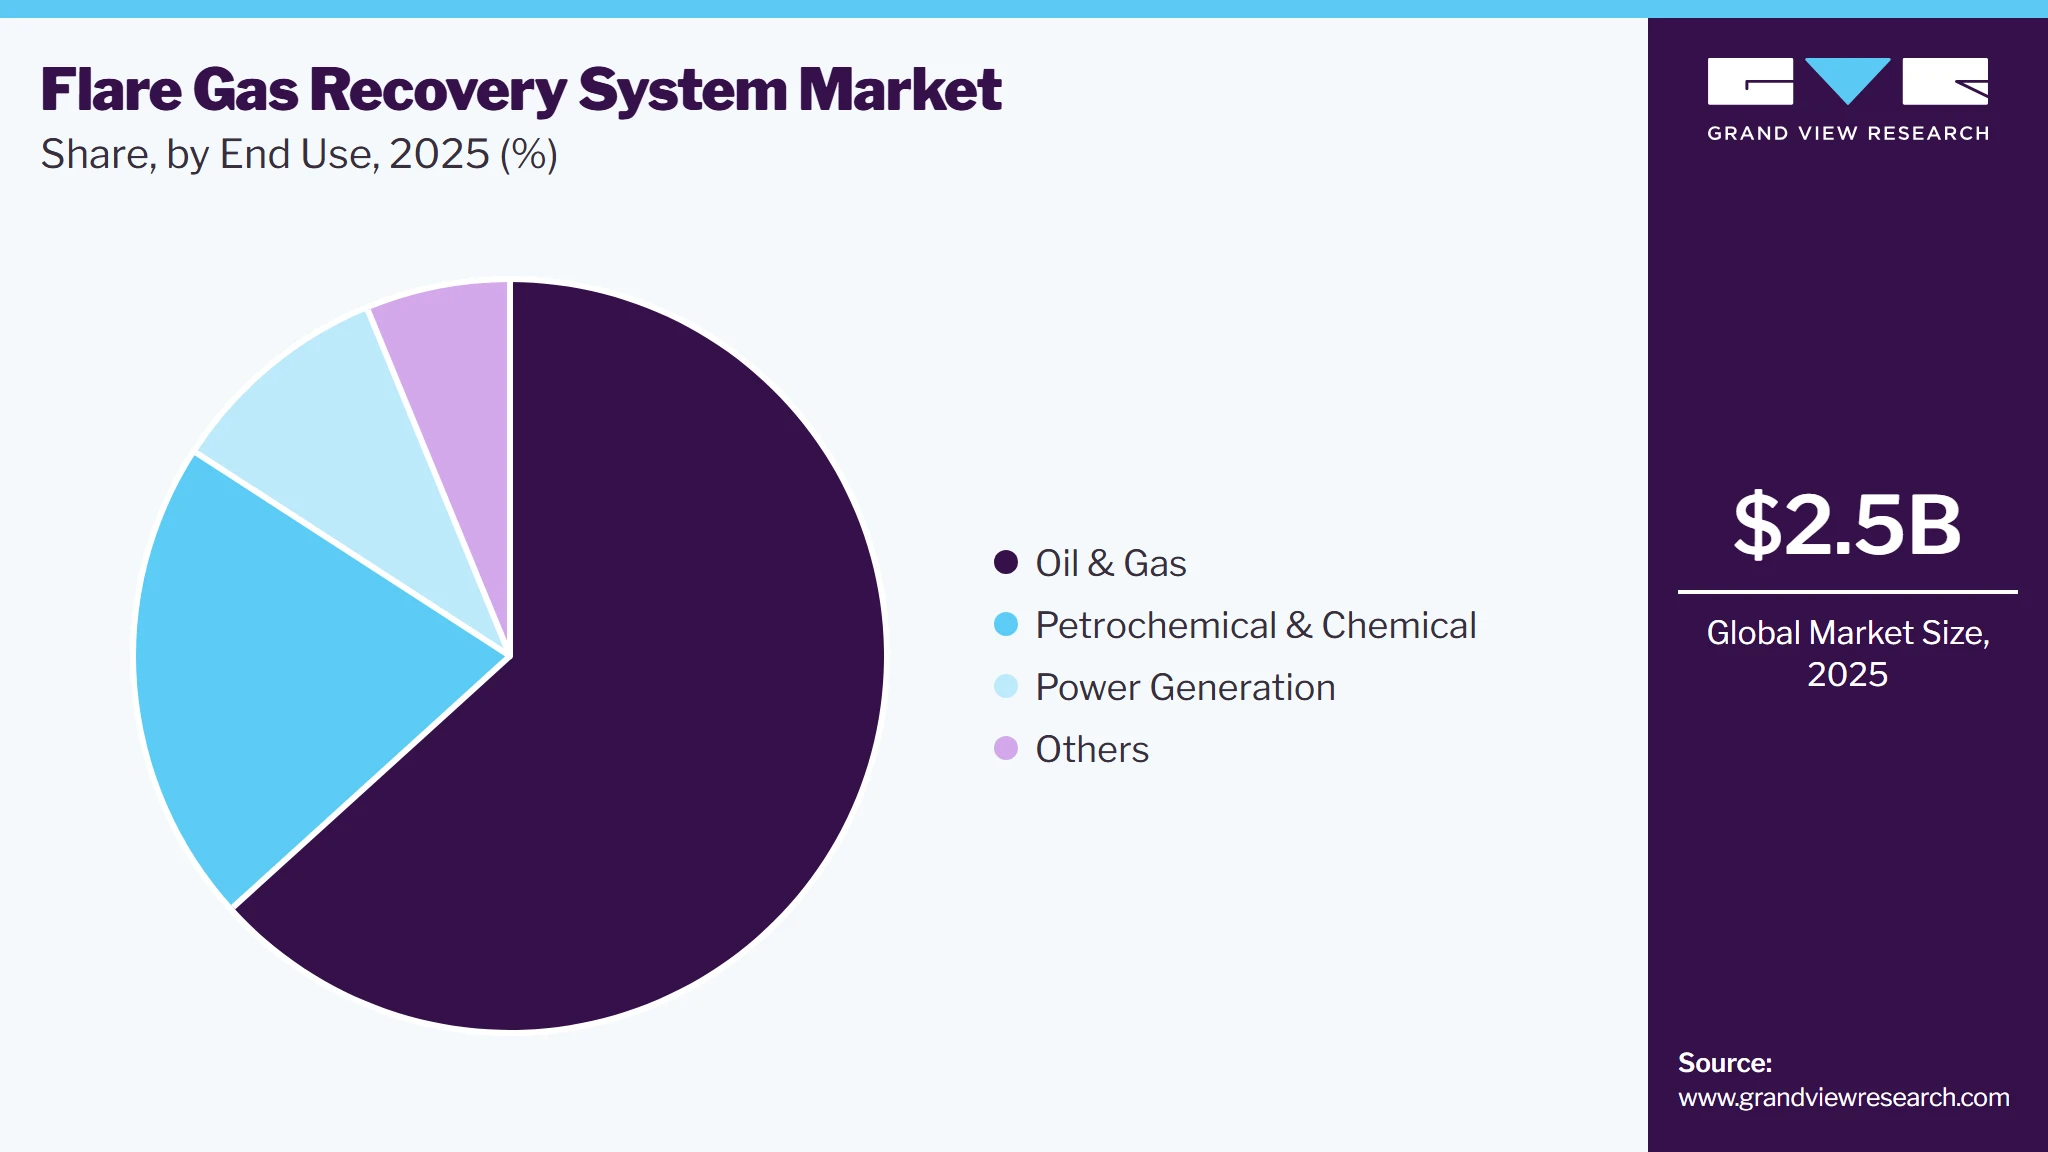
- By end use: Oil & gas segment held the largest market share of 63.3% in 2025.
- By installation location: Onshore segment held the largest market share of 71.1% in 2025.
Regional Highlights
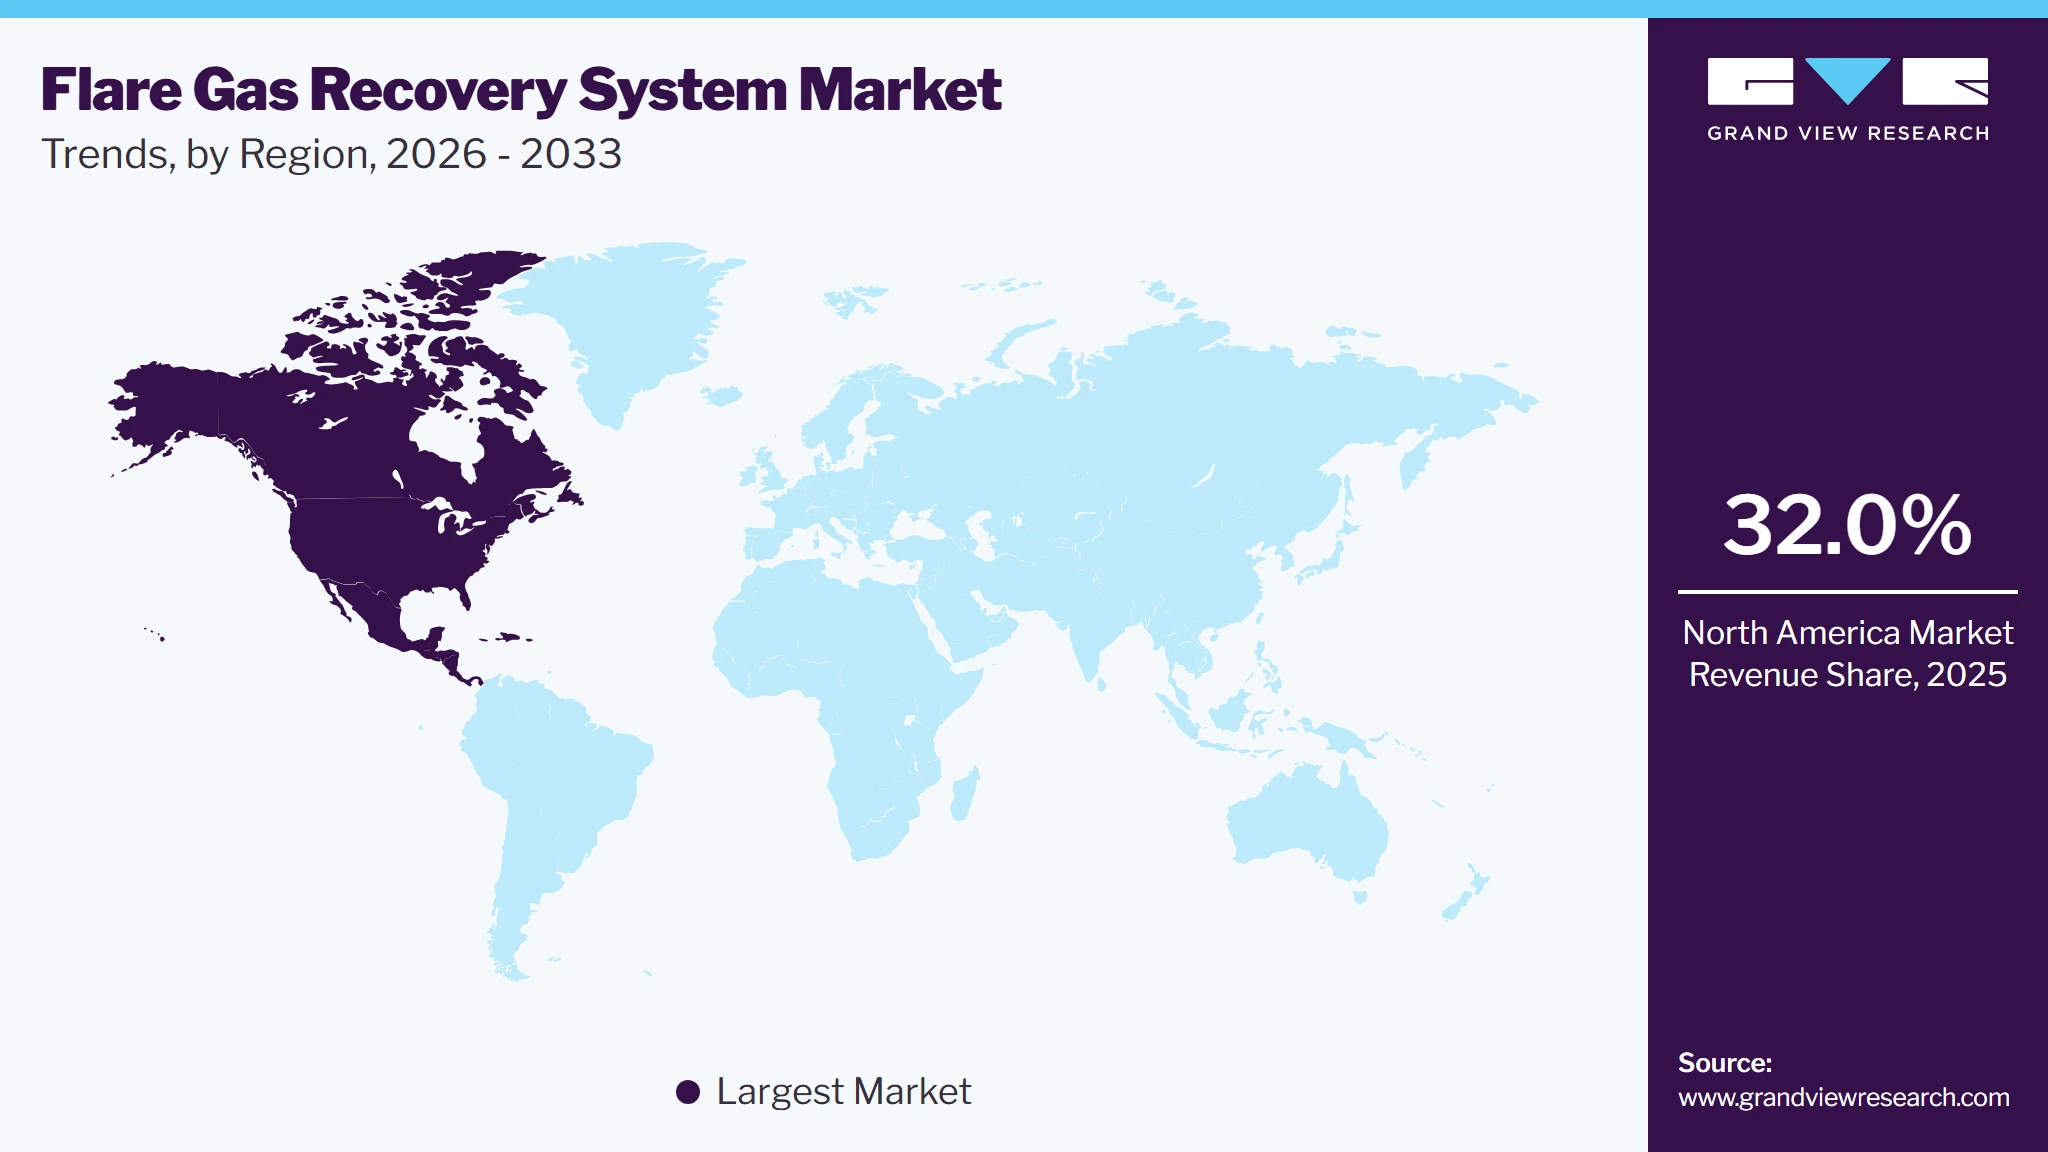
- Largest regional market: North America (32.0% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 2.5 Billion
- Estimated market size in 2026: USD 2.6 Billion
- Projected market size by 2033: USD 3.8 Billion
- CAGR (2026-2033): 5.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Governments worldwide are enforcing stricter emission controls, compelling industries to adopt FGRS to reduce greenhouse gas emissions and avoid penalties. Additionally, these systems enable companies to convert waste gases into usable energy, leading to cost savings and enhanced operational efficiency.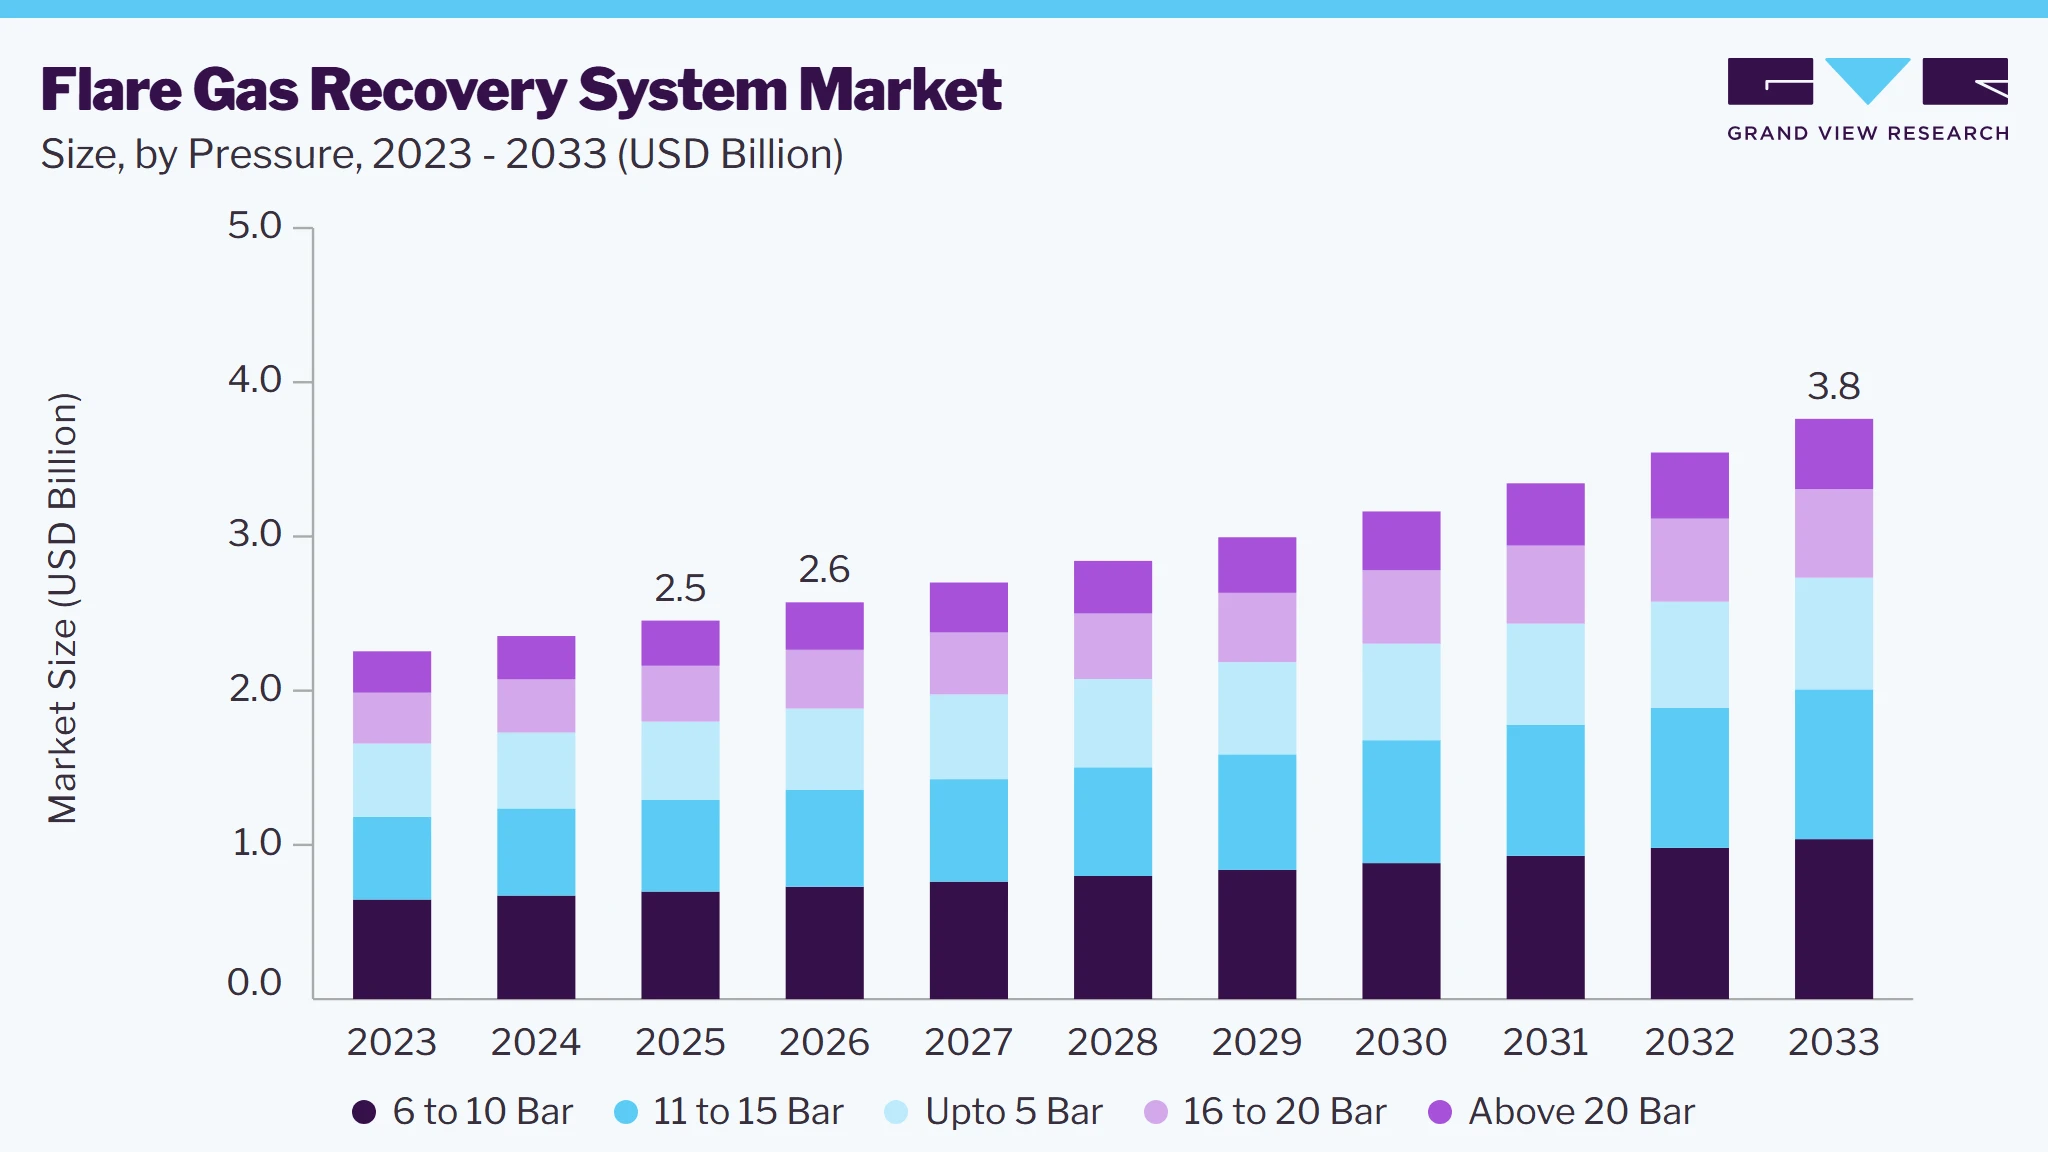 To learn more about this report, Download Free Sample Report
Technological advancements, particularly the integration of digital solutions such as IoT and AI, are enhancing the efficiency and scalability of FGRS, presenting new opportunities for market expansion. Emerging markets, especially in developing countries with expanding oil and gas industries, are increasingly adopting FGRS to comply with international sustainability standards, further driving market growth.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The flare gas recovery system market is witnessing steady growth as governments and energy companies intensify efforts to reduce routine gas flaring, lower greenhouse gas emissions, and improve resource utilization. Oil and gas operators are increasingly investing in flare gas recovery systems to capture and reuse associated gas for fuel, power generation, reinjection, or petrochemical feedstock, helping improve operational efficiency while complying with stringent environmental regulations. Rising investments in refinery modernization, LNG infrastructure, and petrochemical capacity expansion are further supporting market growth, while advancements in compressor technologies, automation, and digital monitoring are enhancing system reliability and recovery efficiency.
Governments and environmental agencies across major oil-producing regions are implementing stricter regulations aimed at minimizing routine flaring and reducing methane emissions. Initiatives such as zero routine flaring targets, carbon reduction commitments, and tighter emission standards are encouraging operators to deploy flare gas recovery systems instead of burning valuable hydrocarbons. These regulations are creating sustained demand across upstream, midstream, and downstream facilities.
In addition to regulatory compliance, companies are recognizing the economic benefits of recovering flare gas. Captured gas can be reused as plant fuel, compressed for transportation, or utilized as feedstock for industrial processes, reducing fuel costs and generating additional revenue. This combination of environmental compliance and operational savings is making flare gas recovery systems an increasingly attractive investment for energy producers worldwide.
The installation of flare gas recovery systems requires significant upfront investment in compressors, piping, control systems, and plant modifications. Integrating these systems into existing facilities can be technically challenging, particularly at older refineries and oil production sites where infrastructure upgrades are required. These factors may delay project implementation and limit adoption among smaller operators with constrained capital budgets.
Increasing investments in refinery modernization, natural gas processing facilities, LNG terminals, and petrochemical plants are creating substantial opportunities for flare gas recovery system providers. As operators seek to improve energy efficiency and maximize hydrocarbon utilization, flare gas recovery is becoming an integral part of new facility designs as well as brownfield expansion projects. The growing emphasis on sustainable operations and carbon reduction strategies is expected to further accelerate the deployment of advanced flare gas recovery technologies across both developed and emerging energy markets.
Market Concentration & Characteristics
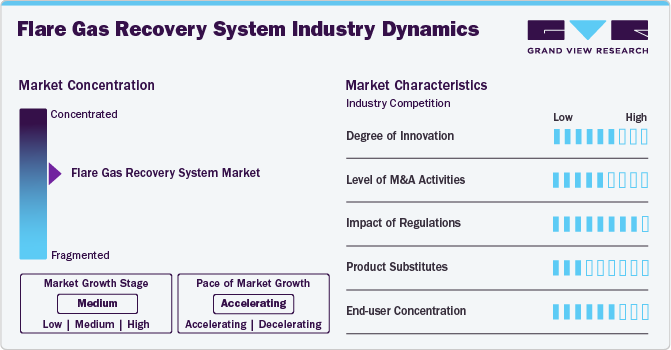
The flare gas recovery system market exhibits a moderately fragmented landscape, characterized by the presence of both established industry leaders and emerging players. Key companies such as John Zink Hamworthy Combustion LLC, Gardner Denver Holdings Inc., Honeywell International Inc., MAN SE, and SoEnergy International Inc. have secured significant market positions through extensive product portfolios and global reach. Additionally, regional players contribute to the competitive dynamics by catering to local demands and adhering to specific regulatory requirements.
The market is significantly influenced by stringent environmental regulations aimed at reducing greenhouse gas emissions. Governments worldwide are enforcing policies that mandate the reduction of gas flaring, compelling industries to adopt FGRS to comply with these standards. This regulatory environment not only drives demand but also fosters innovation as companies develop more efficient and cost-effective recovery solutions.
 To learn more about this report, Download Free Sample Report
Technological advancements play a crucial role in shaping the market's characteristics. Innovations in compressor technologies, such as the development of liquid ring compressors, have enhanced the efficiency and reliability of FGRS. These technological improvements enable systems to handle varying gas compositions and flow rates, making them more adaptable to different operational conditions.
Regionally, North America holds a substantial share of the FGRS market, driven by extensive oil and gas exploration activities and supportive regulatory frameworks. Europe follows closely, with countries like Russia contributing significantly due to their focus on minimizing the environmental impact of flaring activities. The Asia-Pacific region is also witnessing growth, propelled by increasing industrialization and energy demands, particularly in countries such as China and India.
Analyst Perspective
The flare gas recovery system market is expected to witness steady growth over the forecast period, driven by increasing regulatory pressure to reduce routine gas flaring, rising investments in refinery modernization, and growing emphasis on methane emission reduction. Oil and gas operators are increasingly viewing flare gas as a valuable resource that can be recovered and reused to improve operational efficiency and lower energy costs. Technological advancements in compressor-based systems, digital monitoring, and automation are further enhancing system performance and reliability. In addition, expanding upstream production, LNG infrastructure, and petrochemical projects, particularly in the Middle East, North America, and Asia Pacific, are expected to create sustained demand for advanced flare gas recovery solutions.
Technology Insights
Based on technology, compressor-based systems segment led the market with the largest revenue share of 76.0% in 2025. Compressor-based systems utilize mechanical compressors to pressurize and recover flare gas, enabling its reuse in power generation or process heating. They are highly effective in handling variable gas flow rates and pressures, making them suitable for complex industrial operations. These systems offer high recovery efficiency but typically require significant capital investment and maintenance. Due to their robustness and scalability, they are widely deployed in large-scale oil refineries and petrochemical plants.
Ejector-based systems operate on a jet-pump principle, using high-pressure motive gas to entrain and compress flare gas without moving parts. They are cost-effective, simple to install, and require minimal maintenance, making them ideal for smaller-scale applications. While they are less efficient than compressor-based systems at handling variable flow, they are more reliable in harsh environments. These systems are particularly useful where energy efficiency and operational simplicity are prioritized over high recovery volumes.
Pressure Insights
Based on pressure, 6 to 10 bar segment led the market with the largest revenue share of 28.4% in 2025. Flare gas recovery systems operating in the 6 to 10 bar pressure range are typically deployed in mid-sized industrial facilities such as small refineries, petrochemical plants, or chemical manufacturing units. This range offers a practical balance between energy efficiency and operational capability, making it suitable for capturing and reusing moderate volumes of flare gas. Systems within this pressure range are often chosen for their adaptability, ease of integration into existing setups, and relatively lower capital investment compared to higher-pressure alternatives.
Systems designed to operate within the 11 to 15 bar pressure range are geared toward high-capacity industrial environments, including large oil and gas processing plants and integrated petrochemical complexes. This higher pressure range enables the recovery and reintegration of large volumes of flare gas into high-pressure fuel systems or processing units, significantly enhancing overall energy efficiency and reducing emissions. Although these systems require more sophisticated equipment and higher upfront investment, they deliver superior performance in demanding operational contexts.
Flow Rate Insights
Based on flow rate, 3 to 5 MMSCFD segment led the market with the largest revenue share of 26.3% in 2025. Flare gas recovery systems with flow rates between 3 to 5 million standard cubic feet per day (MMSCFD) are commonly implemented in medium-sized industrial facilities, such as regional refineries and chemical plants. This capacity range effectively balances operational efficiency with cost considerations, making it suitable for facilities aiming to reduce emissions and optimize energy use without incurring the higher expenses associated with larger systems.
Systems designed for 6 to 10 MMSCFD flow rates are typically employed in larger industrial complexes, including major oil refineries and extensive petrochemical facilities. These systems accommodate higher volumes of flare gas, providing substantial opportunities for energy recovery and significant reductions in greenhouse gas emissions. The demand for this capacity range is increasing as large-scale industries prioritize environmental compliance and seek to enhance energy efficiency.
Installation Location Insights
Based on installation location, onshore segment led the market with the largest revenue share of 71.1% in 2025. Onshore installations of flare gas recovery systems are predominantly found in refineries, petrochemical plants, and gas processing facilities situated on land. These settings provide easier access to infrastructure, maintenance resources, and integration with existing utility networks. Onshore systems benefit from lower installation and logistical costs compared to offshore setups, and they are more adaptable to system upgrades and expansions.
Offshore installations of flare gas recovery systems are more complex due to space constraints, harsher environmental conditions, and logistical challenges associated with remote locations. These systems are typically deployed on oil and gas platforms where flaring occurs during production or processing activities. Despite the higher capital and maintenance costs, the demand for offshore FGRS is rising as operators aim to comply with stricter international environmental standards and reduce the carbon footprint of offshore operations.
End Use Insights
Based on end use, oil & gas segment led the market with the largest revenue share of 63.3% in 2025. In the oil & gas industry, flare gas recovery systems are primarily used to capture and repurpose gas that would otherwise be flared during exploration, production, and refining processes. These systems help operators reduce emissions, recover valuable hydrocarbons, and improve overall energy efficiency. By integrating FGRS into upstream and downstream operations, companies can comply with environmental regulations while turning waste into a usable resource, such as fuel for process heating or power generation.
 To learn more about this report, Download Free Sample Report
Flare gas recovery systems in the petrochemical and chemical sectors are employed to manage and utilize excess process gas generated during chemical reactions or system venting. These systems help maintain safety by controlling pressure levels while simultaneously enabling the reuse of gases as feedstock or energy sources within the facility. Implementing FGRS not only contributes to emission reductions but also enhances operational cost-efficiency by minimizing the need for external fuel inputs.
Regional Insights
North America dominated the flare gas recovery system market with the largest revenue share of 32.0% in 2025. The flare gas recovery system market in North America is mature, supported by strict environmental policies and substantial investments in emission-reduction technologies. Regulatory frameworks like the EPA’s New Source Performance Standards (NSPS) have accelerated adoption in oil and gas operations. Technological innovation and retrofitting of aging infrastructure continue to drive system upgrades.
 To learn more about this report, Download Free Sample Report
U.S. Flare Gas Recovery System Market Trends
The flare gas recovery system market in the U.S. held the largest share in the North America region in 2025. The U.S. leads regional demand, with shale gas production and tight oil extraction activities contributing to high flare volumes. Adoption of FGRS is driven by state-level mandates, especially in Texas and North Dakota, where flaring has been under increasing scrutiny. Operators are leveraging recovery systems not just for compliance but also to improve energy efficiency.
The flare gas recovery system market in Canada is expected to grow at a CAGR of 4.0% from 2025 to 2030. In Canada, flare gas recovery growth is influenced by federal and provincial regulations aimed at achieving methane emission reductions under the Pan-Canadian Framework. Alberta, a major oil-producing province, is enforcing strict flaring limits that are pushing upstream facilities to implement FGRS. The market also sees support from government incentives for emission-reduction technologies.
Europe Flare Gas Recovery System Market Trends
Europe exhibits a progressive FGRS market with operators motivated by aggressive emission targets under the EU Green Deal. Recovery systems are being integrated into energy transition strategies, particularly in the natural gas and refining sectors. Compliance with the Industrial Emissions Directive (IED) mandates flare minimization, supporting market penetration. Additionally, carbon pricing mechanisms are increasing the economic incentive for flare gas recovery.
Germany flare gas recovery system market held 17.9% share in the European market. The market growth is driven by its ambitious decarbonization goals and advanced industrial base. The chemical and refining sectors are actively investing in FGRS to support process optimization and emission control. Regulatory alignment with EU sustainability targets has accelerated system implementation. German manufacturers are also contributing to innovation in compressor and control systems for enhanced gas capture.
UK flare gas recovery system market is driven by the country's commitment to net-zero emissions by 2050 and regulatory oversight by the Oil and Gas Authority (OGA). North Sea operations are undergoing major retrofitting initiatives to reduce flaring. The market also reflects strong public and political pressure for cleaner offshore practices. Investment in modular and compact FGRS is rising due to space constraints on offshore rigs.
Asia Pacific Flare Gas Recovery System Market Trends
Asia Pacific is witnessing rapid FGRS market growth, fueled by industrial expansion and tightening regional environmental standards. Countries are investing in flare minimization as part of broader energy efficiency programs. The integration of FGRS in large refining and petrochemical complexes is becoming more common. International collaborations and funding mechanisms are also encouraging technology adoption.
China flare gas recovery system market held a significant share in the Asia Pacific market. China’s FGRS market is expanding rapidly due to state-mandated environmental reforms targeting industrial emissions. Major refineries and gas processing units are deploying recovery systems as part of the national low-carbon strategy. Government-backed infrastructure upgrades are supporting adoption in both state-owned and private energy enterprises.
The flare gas recovery system market in India is expected to grow at a CAGR of 7.3% from 2025 to 2030. India is pushing for greater adoption of flare gas recovery systems through its Clean Energy Mission and environmental regulations under the Petroleum and Natural Gas Regulatory Board (PNGRB). The focus is on reducing waste in major public-sector refineries and enhancing process efficiency. FGRS adoption is also gaining momentum in industrial corridors like Gujarat and Maharashtra.
Middle East & Africa Flare Gas Recovery System Market Trends
The Middle East & Africa region shows rising interest in FGRS, driven by national sustainability agendas and global decarbonization pressures. Countries are increasingly integrating recovery systems into mega-projects in refining and LNG. However, regulatory enforcement remains inconsistent across markets. The presence of multinational energy firms in the region is supporting the introduction of best practices and advanced technologies.
Saudi Arabia flare gas recovery system market is advancing as part of the Vision 2030 framework and the Aramco-led initiative to end routine flaring. The kingdom is integrating recovery systems into both upstream and downstream facilities to improve energy efficiency. Local fabrication and deployment capabilities are being developed through public-private partnerships.
Latin America Flare Gas Recovery System Market Trends
Latin America’s FGRS market is emerging, led by regulatory developments and environmental commitments in oil-rich nations. Adoption is focused around energy hubs, with national oil companies exploring flare minimization strategies. Infrastructure challenges and policy gaps still hinder large-scale implementation.
Brazil flare gas recovery system market is growing due to the country’s initiatives are centered on Petrobras-led projects and deepwater offshore production sites. Regulatory pressures under ANP (Agência Nacional do Petróleo) are fostering cleaner production mandates. FGRS systems are being integrated into new platform designs, ensuring compliance from the planning phase. Domestic engineering firms are also collaborating on localized system adaptations for offshore use.
Key Flare Gas Recovery System Company Insights
Some of the key players operating in the market include Ingersoll Rand, Honeywell International Inc., among others
-
Ingersoll Rand is a global leader in industrial technology, specializing in providing innovative solutions for air compression, fluid handling, and power tools. Founded in 1871, the company offers a wide range of products and services that support industries such as manufacturing, oil and gas, healthcare, and automotive. Ingersoll Rand's portfolio includes air compressors, blowers, industrial cooling systems, and equipment for fluid management. Headquartered in Davidson, North Carolina, Ingersoll Rand has a significant global presence, operating in over 40 countries.
-
Honeywell International Inc. operates through four reportable business segments, namely aerospace, building technologies, performance materials & technologies, and safety & productivity solutions. The personal protective equipment business comes under the safety & productivity solutions segment. It provides a wide range of safety equipment, including personal protective equipment, to various end-use industries such as construction, healthcare & life sciences, distribution centers, manufacturing, aerospace, and defense. Honeywell has a global presence in North America, Asia, Europe, South America, Australia, and Africa. The company has a presence in over 80 countries and is located at 750 sites.
Key Flare Gas Recovery System Companies
The following key companies have been profiled for this study on the flare gas recovery system market.
-
Zeeco, Inc.
-
AERZEN
-
Gardner Denver
-
John Zink Hamworthy
-
Honeywell International Inc.
-
Wärtsilä
-
SoEnergy
-
Aerzen
-
K. LUND Offshore
-
Koch Industries, Inc.
-
Ingersoll Rand
-
MAN Energy Solutions SE
-
Transvac Systems Limited
-
Sunpower Technology (Jiangsu) Co., Ltd
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Zeeco, Inc., John Zink Hamworthy, Honeywell International Inc., Wärtsilä, Ingersoll Rand, MAN Energy Solutions SE)
- Deliver turnkey flare gas recovery systems for large-scale refinery, petrochemical, and upstream oil & gas projects.
- Invest in advanced compressor technologies, automation, and digital monitoring to improve system efficiency.
- Expand global presence through EPC partnerships, long-term service agreements, and regional engineering centers.
- Strong brand recognition with extensive experience in executing complex flare gas recovery projects.
- Comprehensive product portfolios capable of serving diverse pressure and flow rate requirements.
- Global service networks and technical expertise ensure reliable project execution and lifecycle support.
- Higher system and installation costs than regional suppliers.
- Longer sales and implementation cycles due to project complexity.
- Business performance is closely tied to capital investments in the oil & gas industry.
Emerging & Regional Players (e.g., AERZEN, Gardner Denver, SoEnergy, K. LUND Offshore, Transvac Systems Limited, Sunpower Technology (Jiangsu) Co., Ltd.)
- Focus on cost-effective and customized flare gas recovery solutions for regional industrial projects.
- Target niche applications such as modular systems and offshore-specific recovery technologies.
- Strengthen market presence through local partnerships, distributors, and engineering support.
- Competitive pricing and greater flexibility in addressing customer-specific requirements.
- Faster project execution and localized technical support in regional markets.
- Ability to develop specialized solutions for small- and medium-capacity flare gas recovery applications.
- Limited international presence and lower brand visibility compared to multinational competitors.
- Smaller product portfolios and fewer turnkey project capabilities.
- Limited investment capacity for large-scale R&D and global expansion initiatives.
Recent Developments
- In June 2024, Wood secured a USD 46 million, three-year contract with TotalEnergies in Iraq. Wood will deliver design, procurement, and construction support for the 1st phase of the Associated Gas Upstream Project. This initiative aimed to capture flared gas in Basra for power generation and includes the development of a seawater treatment facility and a 1GW solar power plant.
Flare Gas Recovery System Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.5 billion
Estimated market size in 2026
USD 2.6 billion
Projected market size by 2033
USD 3.8 billion
Growth rate
CAGR of 5.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, pressure, flow rate, installation location, end use, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; Russia; Italy; Norway; China; South Korea; India; Australia; Indonesia; Brazil; Argentina; Saudi Arabia; Qatar; UAE
Key companies profiled
Zeeco, Inc.; AERZEN; Gardner Denver; John Zink Hamworthy; Honeywell International Inc.; Wärtsilä; SoEnergy; Aerzen; K. LUND Offshore; Koch Industries Inc.; Ingersoll Rand; MAN Energy Solutions SE; Transvac Systems Limited; Sunpower Technology (Jiangsu) Co., Ltd
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Flare Gas Recovery System Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global flare gas recovery system market report based on technology, pressure, flow rate, end use, installation location, and region.
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Compressor-Based Systems
-
Ejector-Based Systems
-
-
Pressure Outlook (Revenue, USD Million, 2021 - 2033)
-
Upto 5 Bar
-
6 to 10 Bar
-
11 to 15 Bar
-
16 to 20 Bar
-
Above 20 Bar
-
-
Flow Rate Outlook (Revenue, USD Million, 2021 - 2033)
-
Upto 2 MMSCFD
-
3 to 5 MMSCFD
-
6 TO 10 MMSCFD
-
11 TO 20 MMSCFD
-
21 to 50 MMSCFD
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Oil & Gas
-
Petrochemical & Chemical
-
Power Generation
-
Others
-
-
Installation Location Outlook (Revenue, USD Million, 2021 - 2033)
-
Onshore
-
Offshore
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
Russia
-
Norway
-
Italy
-
UK
-
-
Asia Pacific
-
China
-
India
-
Indonesia
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
UAE
-
Qatar
-
-
Research Methodology
The flare gas recovery system market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each flare gas recovery system segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Technology
Revenue Capture Definition
Compressor-Based Systems
Revenue generated from the sale of compressor-driven systems designed to capture, compress, and recover flare gas for reuse or processing.
Ejector-Based Systems
Revenue generated from sale of ejector-driven flare gas recovery solutions that utilize motive fluid or gas to recover low-pressure flare gas with minimal mechanical components.
Pressure
Revenue Capture Definition
Upto 5 Bar
Revenue captured from the sale of flare gas recovery systems rated to operate at pressures up to 5 bar.
6 to 10 Bar
Revenue generated from sale of flare gas recovery systems operating within the 6 to 10 bar pressure range for medium-pressure applications.
11 to 15 Bar
Revenue generated from sale of systems engineered to recover flare gas at operating pressures between 11 and 15 bar.
16 to 20 Bar
Revenue generated from sale of flare gas recovery systems designed for applications requiring operating pressures of 16 to 20 bar.
Above 20 Bar
Revenue captured from the sale of high-pressure flare gas recovery systems operating above 20 bar.
Flow Rate
Revenue Capture Definition
Upto 2 MMSCFD
Revenue captured from the sale of flare gas recovery systems with gas handling capacities up to 2 MMSCFD.
3 to 5 MMSCFD
Revenue captured from the sale of flare gas recovery systems with flow capacities between 3 and 5 MMSCFD.
6 TO 10 MMSCFD
Revenue captured from the sale of flare gas recovery systems with flow capacities ranging from 6 to 10 MMSCFD.
11 TO 20 MMSCFD
Revenue captured from the sale of flare gas recovery systems with flow capacities between 11 and 20 MMSCFD.
21 to 50 MMSCFD
Revenue captured from the sale of high-capacity flare gas recovery systems with flow capacities between 21 and 50 MMSCFD.
Installation Location
Revenue Capture Definition
Onshore
Revenue captured from the sale of flare gas recovery systems used at onshore oil and gas production sites, refineries, gas processing plants, petrochemical complexes, LNG terminals, and other land-based industrial facilities to recover and utilize flare gas.
Offshore
Revenue captured from the sale of flare gas recovery systems for use on offshore oil and gas platforms, floating production storage and offloading (FPSO) units, and offshore processing facilities to minimize gas flaring, improve operational efficiency, and comply with environmental regulations.
End Use
Revenue Capture Definition
Oil & Gas
Revenue captured from the sale of flare gas recovery systems to upstream, midstream, and downstream oil & gas facilities, including oil fields, gas processing plants, refineries, LNG terminals, and pipeline infrastructure.
Petrochemical & Chemical
Revenue captured from the sale of flare gas recovery systems to petrochemical and chemical manufacturing plants for recovering process gases, reducing emissions, and improving energy efficiency across production operations.
Power Generation
Revenue captured from the sale of flare gas recovery systems to power generation facilities for capturing flare gas and utilizing it as a fuel source to improve plant efficiency and reduce fuel consumption.
Others
Revenue captured from the sale of flare gas recovery systems to other industrial sectors, including fertilizer, steel, cement, and industrial manufacturing facilities, for emission reduction, gas recovery, and energy optimization applications.
Estimation Model
Layer Name
Key Question
Description
Flare Gas Generation Base
Where is recoverable flare gas generated?
Identify the oil & gas production sites, refineries, petrochemical plants, gas processing facilities, LNG terminals, and power plants that generate routine flare gas requiring recovery solutions.
Technology Adoption Assessment
Which facilities are likely to adopt flare gas recovery systems?
Evaluates adoption based on environmental regulations, flaring reduction targets, plant capacity, operating pressure, flow rate requirements, project economics, and new versus retrofit installations across onshore and offshore facilities.
System Demand Estimation
What is the annual demand for flare gas recovery systems?
Estimates demand by technology (compressor-based and ejector-based), pressure range, flow rate, installation location, and end-use industry, considering new projects, facility expansions, and replacement demand.
Revenue Estimation
What is the total market revenue generated?
Estimates total market revenue based on the annual sales of flare gas recovery systems across different technologies, pressure ranges, flow capacities, end-use industries, and installation locations worldwide.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
A detailed regional assessment of the flare gas recovery system market was developed across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, highlighting market size, growth potential, key demand drivers, regulatory landscape, and adoption trends. The analysis also identified country-level hotspots where investments in refinery, petrochemical, LNG, and upstream oil & gas infrastructure are driving demand.
The regional analysis enabled the client to identify high-growth geographies, compare market maturity across regions, and prioritize expansion opportunities based on regulatory stringency, industrial development, and planned hydrocarbon infrastructure investments, supporting more targeted regional business strategies.
Competitive Benchmarking
A comprehensive competitive benchmarking analysis was conducted, comparing leading manufacturers based on product portfolio, financial strength, technology capabilities, regional presence, end-use focus, strategic initiatives, partnerships, and recent developments. The assessment also evaluated competitive positioning across key application areas within the oil & gas and petrochemical sectors.
The benchmarking provided a clear understanding of competitors' strengths, differentiation strategies, and market positioning, enabling the client to identify competitive gaps, evaluate potential partners or acquisition targets, and refine product and market positioning strategies.
Opportunity Assessment
A detailed opportunity assessment was performed to identify high-potential growth areas across applications, industries, and regions. The study evaluated opportunities arising from stricter methane emission regulations, refinery modernization, LNG capacity expansion, petrochemical investments, and increasing emphasis on flare gas utilization and emissions reduction.
The opportunity assessment helped the client prioritize the most attractive investment areas by highlighting emerging demand pockets, technology adoption trends, and long-term growth opportunities, enabling informed resource allocation and strategic market entry decisions.
Frequently Asked Questions About This Report
The global flare gas recovery system market size was estimated at USD 2.5 billion in 2025 and is projected to grow from USD 2.6 billion in 2026.
The compressor-based systems segment dominated the flare gas recovery system market, accounting for 76.0% of the global revenue share in 2025. Its leadership is attributed to higher gas recovery efficiency, the ability to handle varying gas compositions, and widespread deployment across refineries, gas processing plants, and upstream oil & gas facilities.
The 6 to 10 bar segment held the largest revenue share of 28.4% in 2025. This pressure range is widely used in refinery and gas processing operations due to its compatibility with medium-pressure flare gas recovery applications and operational efficiency.
The oil & gas segment led the market with a 63.3% revenue share in 2025. Increasing investments in upstream and downstream infrastructure, combined with stricter flaring reduction regulations and methane emission targets, continue to support strong adoption across the industry.
Asia Pacific is projected to register the fastest CAGR of 6.6% during the forecast period. The growth is driven by expanding refinery and petrochemical capacities, rising natural gas infrastructure investments, increasing industrialization, and the implementation of stricter environmental regulations aimed at reducing routine gas flaring across emerging economies.
The global flare gas recovery system market, in terms of revenue, is expected to grow at a compound annual growth rate of 5.6% from 2026 to 2033 to reach USD 3.8 billion by 2033.
North America dominated the global flare gas recovery system market, accounting for 32.0% of the revenue share in 2025. The region benefits from stringent environmental regulations, extensive shale oil and gas production, significant refinery capacity, and continuous investments in emission reduction technologies.
Some of the key players operating in the flare gas recovery system market include Zeeco, Inc.; AERZEN; Gardner Denver; John Zink Hamworthy; Honeywell International Inc.; Wärtsilä; SoEnergy; Aerzen; K. LUND Offshore; Koch Industries Inc.; Ingersoll Rand; MAN Energy Solutions SE; Transvac Systems Limited; Sunpower Technology (Jiangsu) Co., Ltd
The primary factor driving the flare gas recovery system market is the growing global focus on reducing gas flaring and methane emissions through stringent environmental regulations. Governments and oil & gas operators are increasingly investing in flare gas recovery technologies to comply with emission standards, improve resource utilization, lower carbon footprints, and convert waste gas into valuable fuel or feedstock, thereby enhancing both operational efficiency and economic returns.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


