
- Home
- »
- Advanced Interior Materials
- »
-
Friction Stir Welding Equipment Market Report, 2026-2033GVR Report cover

Friction Stir Welding Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Fixed FSW Equipment, Mobile FSW Equipment, Robotic FSW Equipment), By End-use (Aerospace, Automotive, Shipbuilding, Railways), By Region, And Segment Forecasts
Market Size, 2025
$262.4MMarket Estimate, 2026
$279.2MMarket Forecast, 2033
$449.7MCAGR, 2026–2033
7.0%Friction Stir Welding Equipment Market Summary
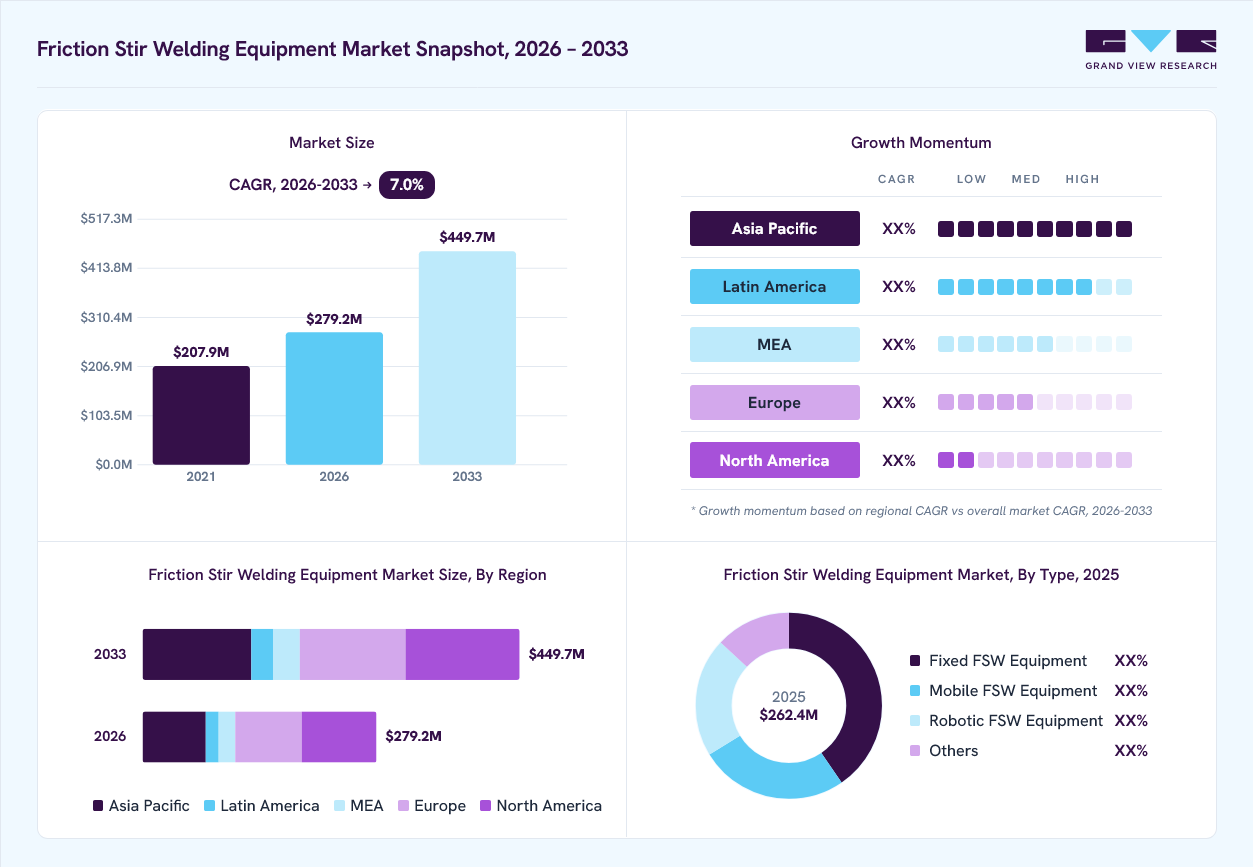
The global friction stir welding equipment market size was valued at USD 262.4 million in 2025 and is projected to grow from USD 279.2 million in 2026 to USD 449.7 million by 2033, at a CAGR of 7.0% from 2026 to 2033. The market in North America dominated with a revenue share of 32.2% in 2025. The increasing demand for high-quality, cost-effective, and environment-friendly welding technologies in industries such as aerospace, automotive, and shipbuilding is driving the growth of the friction stir welding (FSW) equipment market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Fixed FSW equipment segment held the largest market share of 40.4% in 2025.
- By end use: Aerospace segment held the largest market share of 29.8% in 2025.
Regional Highlights
- Largest regional market: North America (32.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 262.4 Million
- Estimated market size in 2026: USD 279.2 Million
- Projected market size by 2033: USD 449.7 Million
- CAGR (2026-2033): 7.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
FSW is a solid-state joining process that is particularly effective for welding lightweight alloys, providing superior joint strength and durability. Technological advancements in FSW equipment, such as robotic and mobile systems development, are presenting significant growth opportunities. These advancements improve the effectiveness and adaptability of FSW processes, enabling their use across various applications. In addition, the growing focus on reducing manufacturing costs and improving product performance is driving the adoption of FSW technology across various industries. The expansion of the aerospace and automotive industries and the need for lightweight and fuel-efficient vehicles are further expected to bolster the market demand.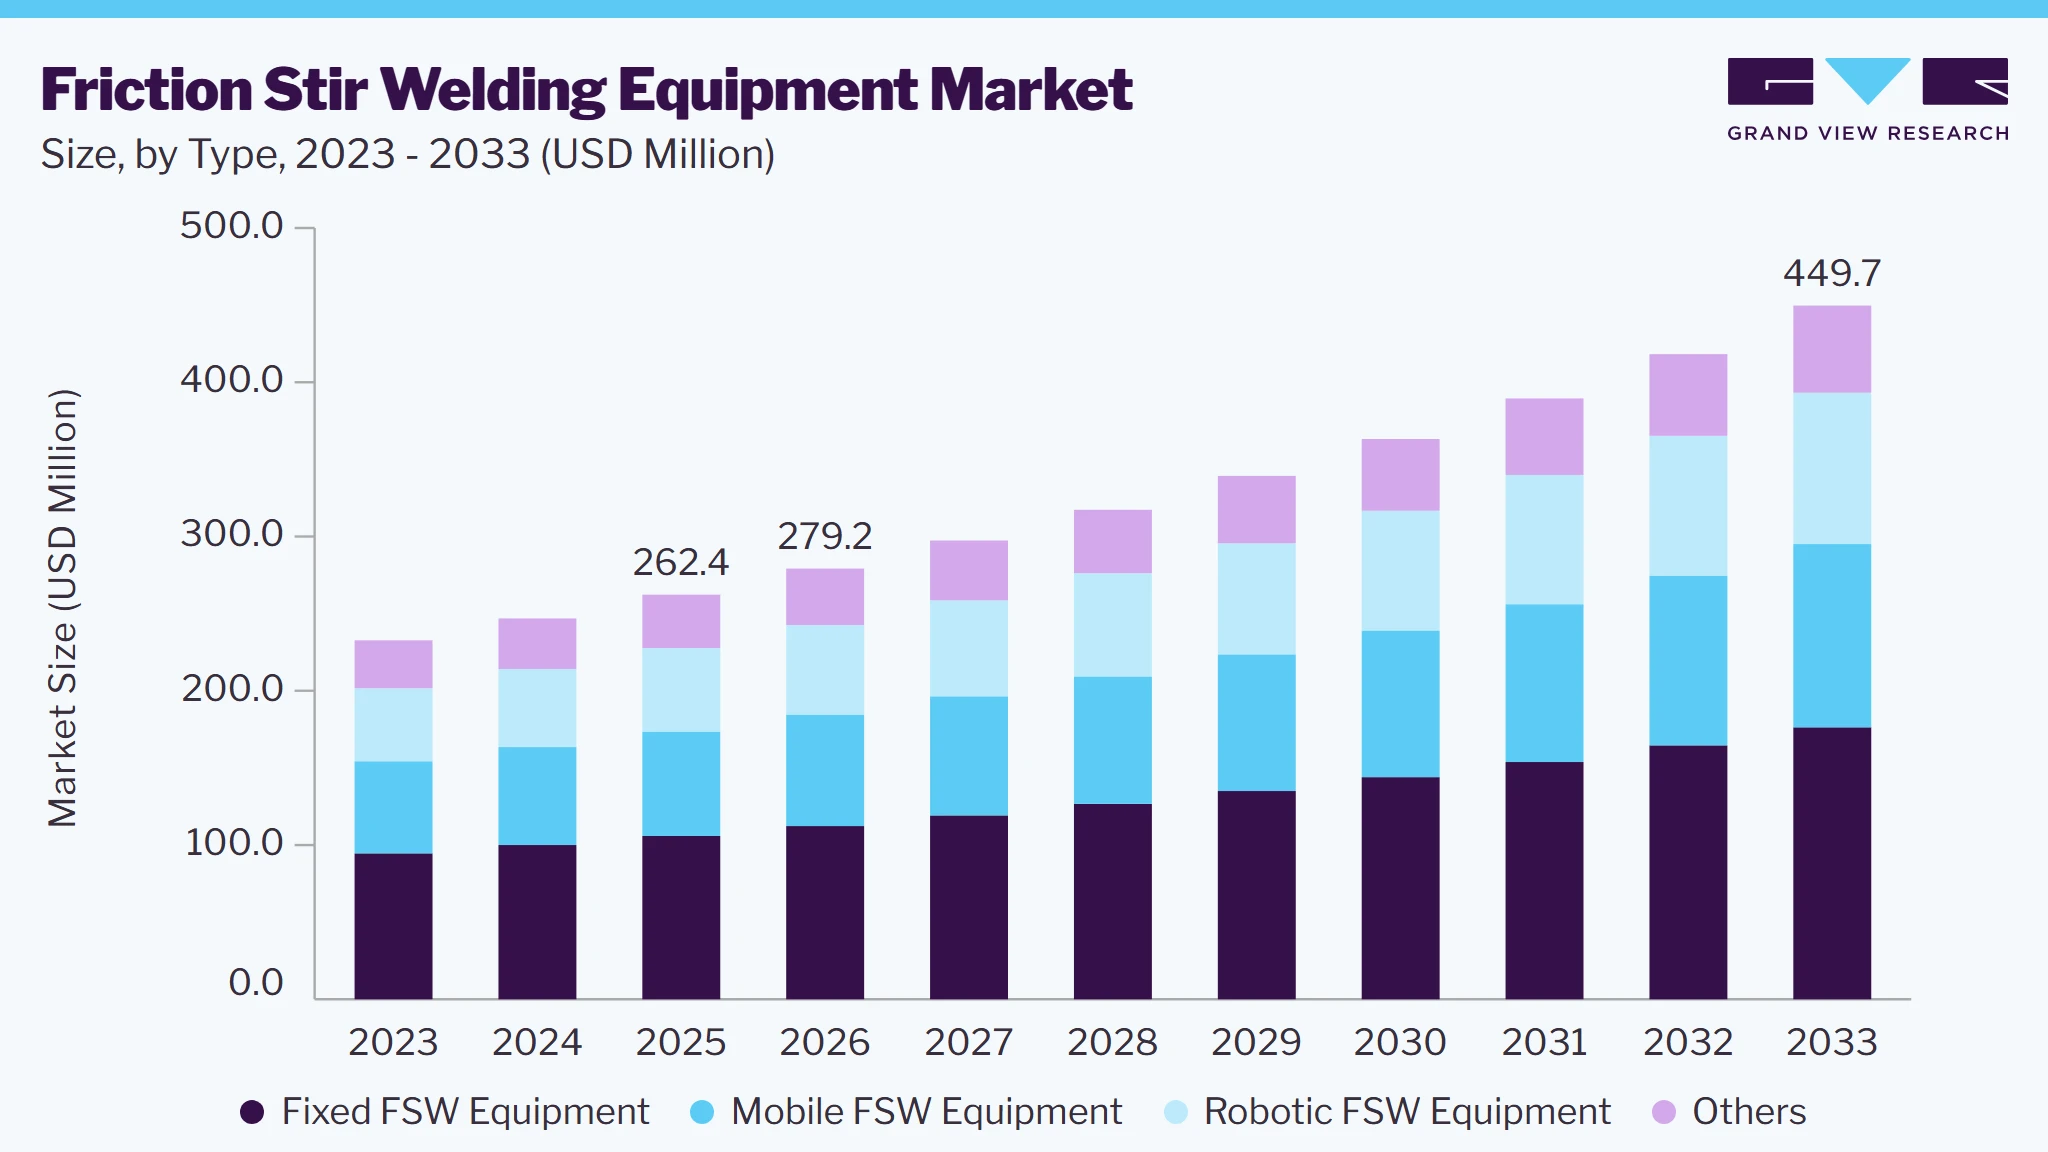 To learn more about this report, Download Free Sample Report
FSW technology is recognized for its lower energy consumption compared to traditional welding methods, making it an excellent fit for global sustainability goals. As manufacturers aim to meet these goals and adopt more eco-friendly practices, the demand for FSW equipment is expected to increase. The growing need for high-strength, defect-free welds in critical sectors such as aerospace, automotive, and shipbuilding is driving demand for friction stir welding equipment. The rising use of lightweight materials such as aluminum and magnesium alloys in these industries is further contributing to the demand for this equipment. FSW's benefits, including reduced energy use, fewer welding defects, and enhanced mechanical properties, are also expected to support market expansion.
Environmental concerns and stringent regulations regarding emissions and energy consumption are also influencing the friction stir welding (FSW) equipment market. FSW technology is known for its lower energy consumption compared to traditional welding methods, which aligns well with global sustainability goals. As manufacturers seek to comply with these regulations and adopt greener manufacturing processes, the demand for FSW equipment is expected to rise.
Market Dynamics
The friction stir welding (FSW) equipment market is experiencing growth due to increasing demand for lightweight, high-strength metal joining solutions across aerospace, automotive, railways, and shipbuilding industries. Manufacturers are increasingly adopting FSW technology because it produces superior weld quality, reduces material distortion, and improves operational efficiency compared to conventional fusion welding methods. The growing use of aluminum and advanced alloys in transportation and industrial applications, coupled with rising automation trends and investments in electric vehicle (EV) production, is further supporting market expansion.
One of the primary drivers of the friction stir welding equipment market is the increasing adoption of lightweight materials, particularly aluminum alloys, across aerospace, automotive, railways, and marine industries. Manufacturers are under constant pressure to improve fuel efficiency, reduce emissions, and enhance overall vehicle performance. As a result, lightweight materials are replacing traditional steel components in many applications. Friction stir welding offers an effective solution for joining these materials while maintaining high mechanical strength and minimizing defects, making it a preferred welding technology for critical structural components.
The rapid growth of electric vehicles has further accelerated demand for FSW equipment. EV manufacturers extensively use aluminum battery enclosures, cooling systems, and lightweight chassis structures that require high-quality welding processes. Similarly, aerospace companies are increasingly utilizing FSW for aircraft fuselages, fuel tanks, and wing structures due to its ability to produce durable, fatigue-resistant joints. These trends are expected to sustain strong demand for advanced FSW equipment over the coming years.
A significant restraint affecting market growth is the high capital investment required for purchasing, installing, and maintaining friction stir welding equipment. Advanced fixed and robotic FSW systems involve substantial upfront costs, making adoption challenging for small and medium-sized manufacturers. Additionally, successful implementation requires skilled operators, specialized tooling, and process optimization expertise, which can increase operational expenses. These factors may limit market penetration, particularly in cost-sensitive industries and developing regions where conventional welding methods remain more economically attractive.
The growing trend toward industrial automation presents a significant opportunity for the friction stir welding equipment market. Manufacturers are increasingly integrating robotic FSW systems into production lines to improve productivity, ensure consistent weld quality, and reduce dependence on manual labor. Automated systems enable precise welding of complex geometries and support high-volume manufacturing environments, particularly in automotive and aerospace sectors. As Industry 4.0 adoption expands and manufacturers seek greater operational efficiency, demand for robotic and intelligent FSW equipment is expected to increase substantially, creating new revenue opportunities for equipment suppliers and technology developers.
Analyst Perspective
The friction stir welding equipment market is positioned for steady long-term growth, driven by increasing adoption of lightweight materials and advanced manufacturing technologies across transportation and industrial sectors. The market is benefiting from rising demand for high-strength, defect-free welding solutions in aerospace, automotive, shipbuilding, and railway applications, where conventional welding methods often face performance limitations. The growing shift toward automation and robotic manufacturing is further accelerating demand for advanced FSW systems, particularly in electric vehicle and aerospace production. While high capital costs may restrict adoption among smaller manufacturers, ongoing investments in manufacturing modernization, sustainability initiatives, and precision engineering are expected to support market expansion and create opportunities for equipment suppliers offering innovative and application-specific welding solutions.
Type Insights
Based on type, fixed FSW equipment segment led the market with the largest revenue share of 40.4% in 2025. The growth is driven by its widespread use in manufacturing plants for producing large, consistent welds. These systems are typically used in high-volume production settings, where robust and reliable welding solutions are critical. The demand for fixed FSW equipment is expected to continue to grow due to its efficiency and ability to produce high-quality welds.
The U.S. manufacturing output exceeded expectations in February 2025, driven by a significant increase in motor vehicle production. Factory output rose by 0.9% in February 2025, following a revised 0.1% gain in January 2025, according to the Federal Reserve's report.
The robotic FSW equipment segment is expected to grow at the fastest CAGR of 7.8% over the forecast period. This category of equipment is gaining popularity due to its ability to automate the welding process, resulting in higher precision and consistency. These systems are increasingly used in the automotive and aerospace industries to produce complex and high-precision welds. The integration of robotics in FSW is expected to drive market growth by enhancing productivity and reducing labor costs. According to China Briefing, China's aerospace and commercial space industries are expanding quickly, with the sector expected to reach a value of over USD 900 billion by 2029.
End-use Insights
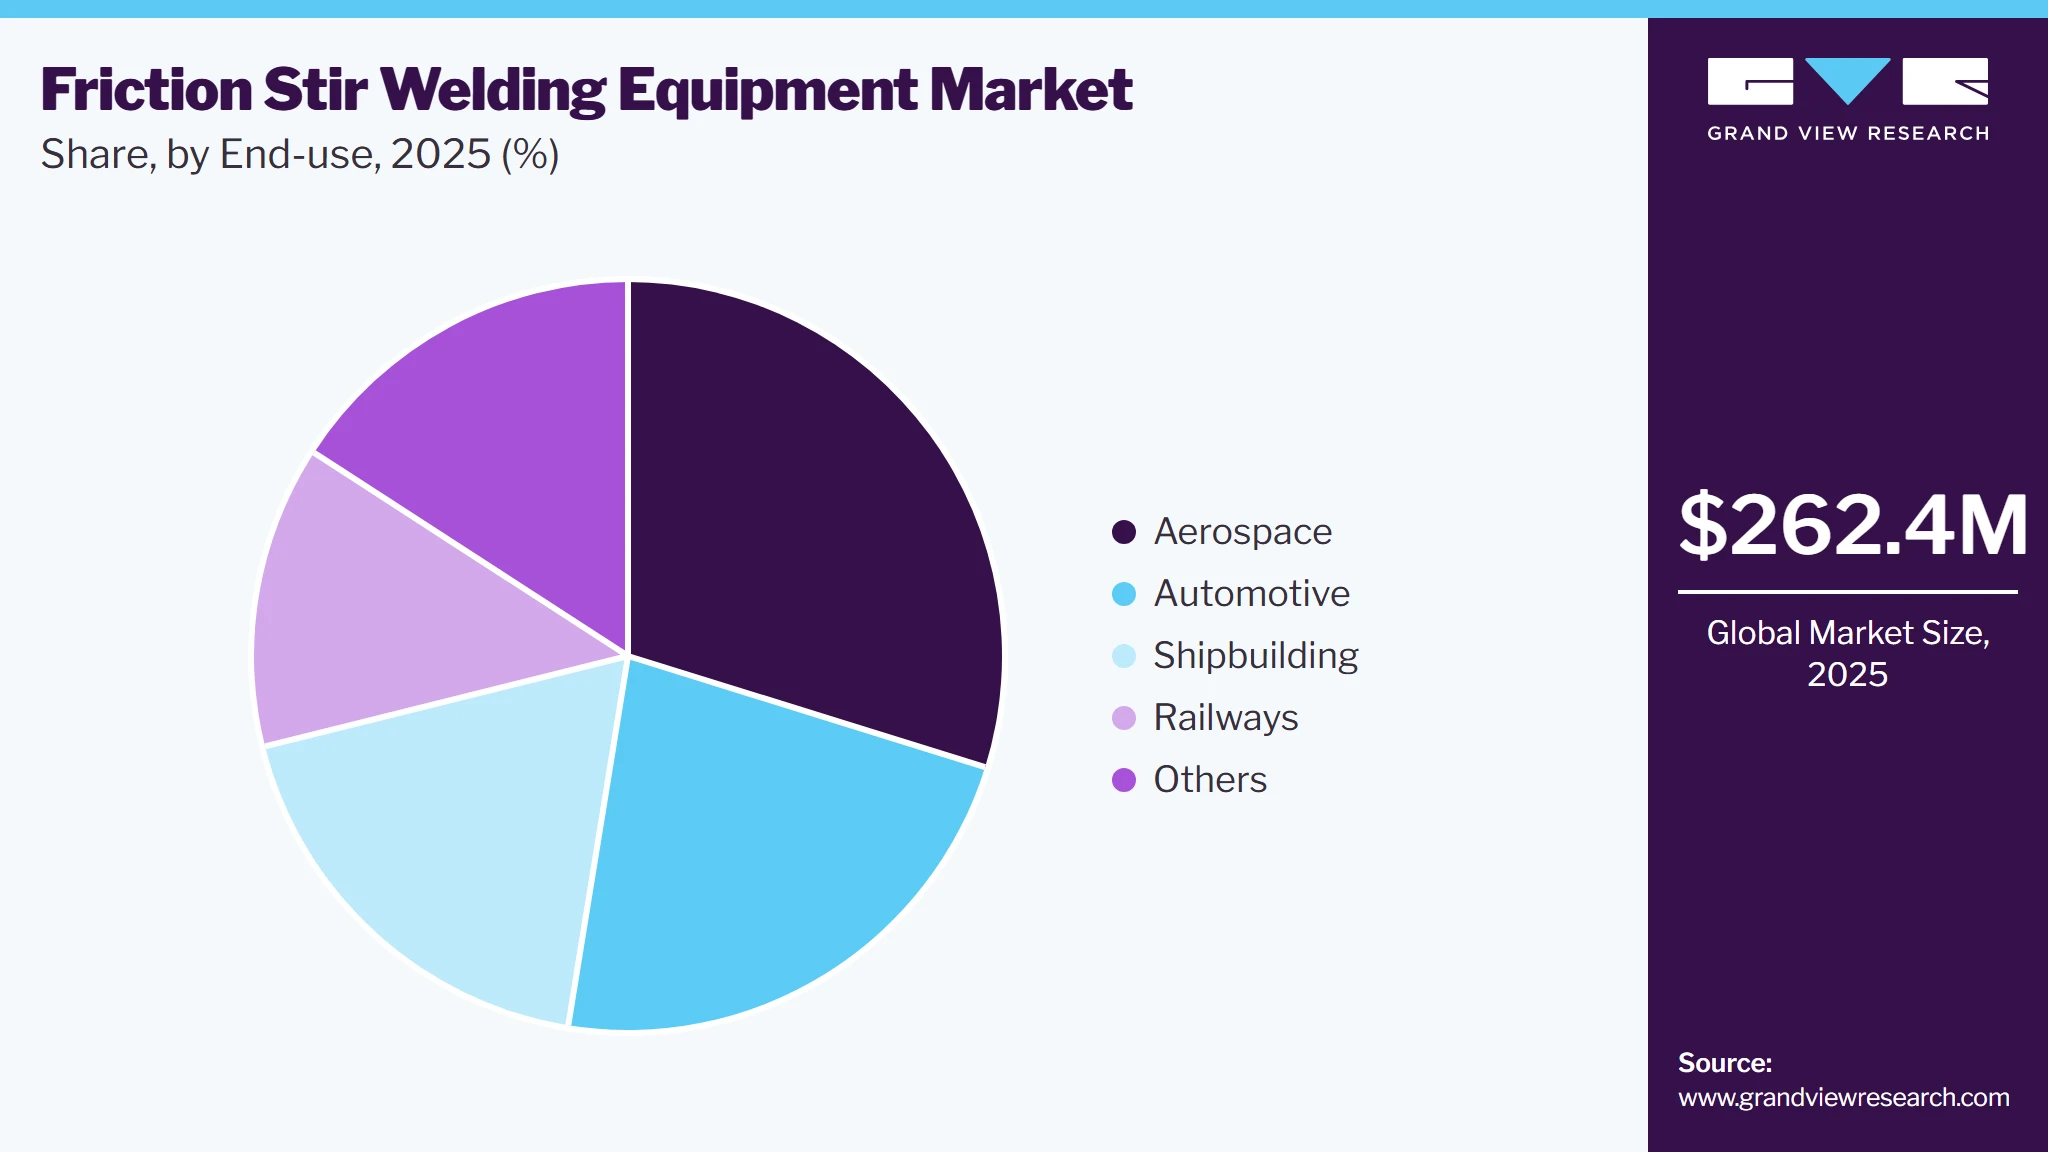
Based on end use, aerospace segment led the market with the largest revenue share of 29.8% in 2025. FSW is extensively utilized in the production of aircraft components, including fuselages, wings, and fuel tanks, because of its ability to produce high-strength, defect-free welds. The increasing production of commercial and military aircraft is expected to drive the demand for FSW equipment in this segment. According to ACI World, an electronic payments company, the global passenger traffic is expected to exceed 10 billion passengers in 2025. This marks a 6% increase from 2024 and a rise of over 16% compared to 2019. Avolon has forecasted a 20% increase in aircraft deliveries in 2025.
 To learn more about this report, Download Free Sample Report
The automotive industry is expected to grow at the fastest CAGR of 7.7% over the forecast period. It uses the technology for welding lightweight materials. The increasing demand for lightweight and fuel-efficient vehicles is accelerating the use of FSW in automotive production.
The trend toward EVs and the need for lightweight and strong battery enclosures are projected to propel market growth in the coming years. India's electric vehicle (EV) industry is gaining significant momentum, driven by the launch of new models, the expansion of charging infrastructure, and a steady rise in sales. In 2024, nearly 100,000 EVs were sold, marking a 20% increase from the previous year. Meanwhile, total light vehicle sales in India reached approximately 4.9 million units as automakers race to capitalize on the growing demand in this emerging market.
Regional Insights
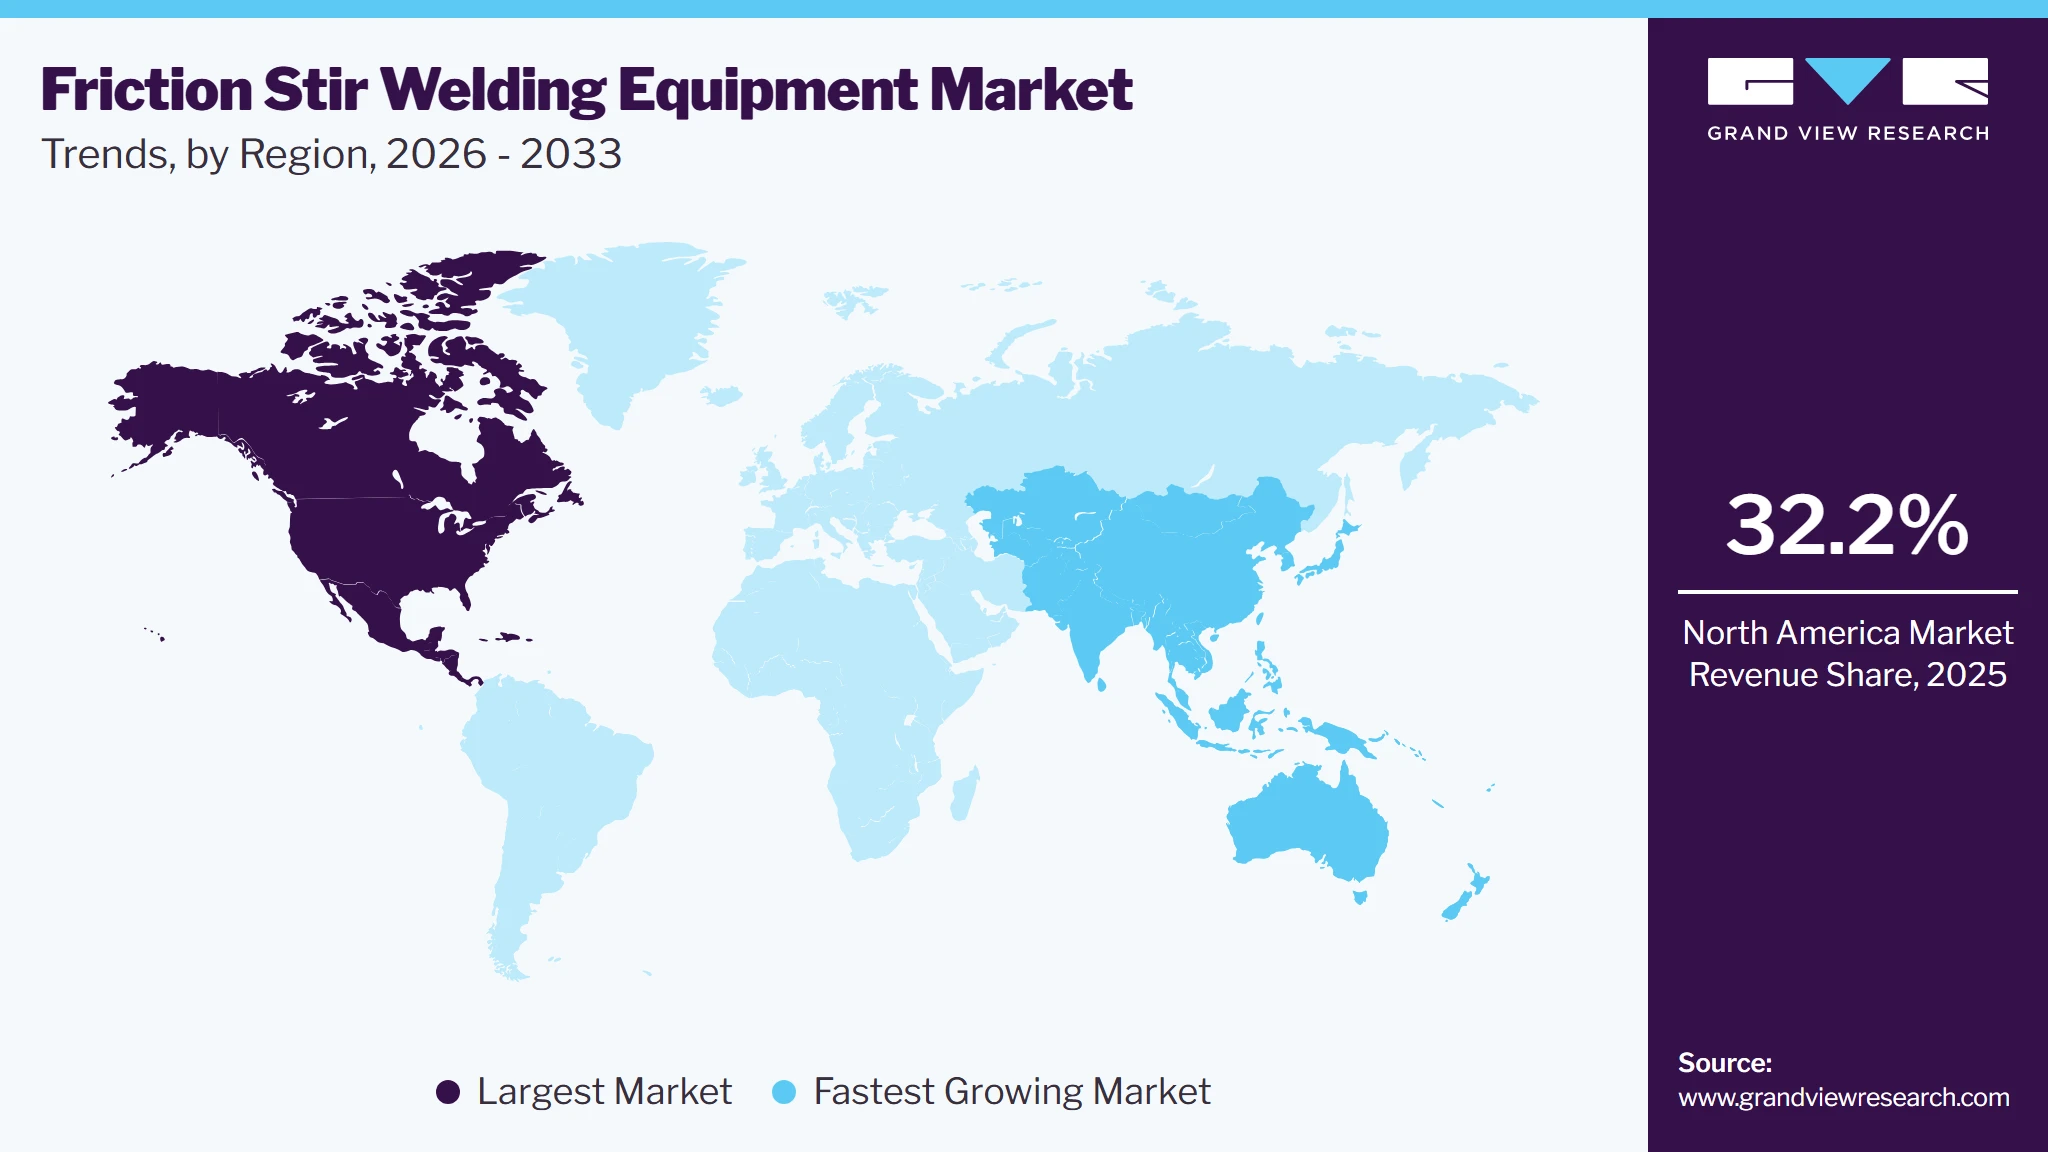
North America dominated the friction stir welding equipment market with the largest revenue share of 32.2% in 2025. The region's advanced manufacturing infrastructure and emphasis on high-quality, durable products are key drivers for the adoption of FSW technology. The U.S. and Canada are investing heavily in modernizing their manufacturing capabilities, with a focus on reducing energy consumption and improving environmental performance. The presence of leading aerospace companies and the push for lightweight, fuel-efficient vehicles are expected to sustain the growth of the FSW equipment industry in North America.
 To learn more about this report, Download Free Sample Report
U.S. Friction Stir Welding Equipment Market Trends
The friction stir welding equipment market in the U.S. held the largest share in the North America region in 2025. The growth is driven by its leading position in the aerospace and automotive industries. The demand for high-strength, lightweight materials in these sectors is a major factor boosting the adoption of FSW technology. The U.S. government’s focus on promoting advanced manufacturing and sustainable industrial practices is also contributing to the growth of the friction stir welding equipment industry. Significant investments in research & development and collaborations between industry and academic institutions are driving innovations in FSW technology.
Asia Pacific Friction Stir Welding Equipment Market Trends
The friction stir welding equipment market in Asia Pacific is estimated to grow at the fastest CAGR of 8.1% over the forecast period. The expansion of the region's industrial sector and rising investments in advanced manufacturing technologies are driving growth. China, Japan, and South Korea are at the forefront of adopting FSW technology, supported by their strong automotive and electronics sectors. The increasing need for lightweight, high-strength materials in these industries is further expected to favor market.
Europe Friction Stir Welding Equipment Market Trends
The European friction stir welding equipment market held a substantial market share in 2025. The growth is driven by the region's strong manufacturing base and focus on advanced manufacturing technologies. Europe is home to several major automotive and aerospace manufacturers, which are increasingly adopting FSW to enhance the performance and quality of their products. Stringent environmental regulations and the push for sustainable manufacturing practices are further accelerating the adoption of energy-efficient FSW technologies in the region.
Key Friction Stir Welding Equipment Company Insights
Some of the major friction stir welding equipment industry players are ETA Technology, YAMAZAKI MAZAK CORPORATION, FOOKE GmbH, and PAR Systems. These companies stay competitive by investing in advanced technology, offering high-quality, cost-effective solutions, and continuously innovating their processes. They focus on building strong customer relationships, diversifying into new industries, and optimizing production efficiency. Additionally, they prioritize sustainability, improving their environmental footprint, and expanding their global presence to meet diverse market demands and regulatory requirements.
-
ETA Technology is a company that provides innovative engineering solutions, focusing on advanced manufacturing processes and automation. They offer a range of products and services, including precision welding, robotics, and custom-designed systems for various industries.
-
YAMAZAKI MAZAK CORPORATION is a manufacturer of advanced machine tools, offering solutions for industries such as aerospace, automotive, and medical. The company specializes in CNC (computer numerical control) machines, automation systems, and related services. It focuses on innovation, precision, and providing integrated manufacturing solutions worldwide.
Key Friction Stir Welding Equipment Companies
The following key companies have been profiled for this study on the friction stir welding equipment market.
-
ETA Technology
-
YAMAZAKI MAZAK CORPORATION
-
FOOKE GmbH
-
PAR Systems
-
Hitachi Power Solutions Co., Ltd.
-
NITTO SEIKI CO., LTD.
-
Grenzebach Group
-
Bond Technologies, LLC.
-
PTG
-
TRA-C industrie.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., YAMAZAKI MAZAK CORPORATION, PAR Systems, Hitachi Power Solutions Co., Ltd., Bond Technologies, LLC.)
- Focus on serving high-value industries such as aerospace, automotive, and defense through advanced FSW systems.
- Continuously invest in automation, robotic integration, and R&D to enhance welding efficiency and precision.
- Strong global brand recognition and extensive customer relationships across industrial sectors.
- Broad technological expertise and proven track record in delivering large-scale, high-performance FSW solutions.
- Higher equipment costs compared to regional and niche competitors.
- Less flexibility in addressing small-volume or highly customized projects.
Emerging & Regional Players (e.g., ETA Technology, FOOKE GmbH, NITTO SEIKI CO., LTD., Grenzebach Group, PTG, TRA-C industrie.)
- Focus on specialized applications and customized FSW solutions tailored to specific customer requirements.
- Expand market presence through regional partnerships and targeted industry projects.
- Greater flexibility and faster response to evolving customer and industry needs.
- Ability to offer cost-effective and application-specific solutions in niche market segments.
- Limited global reach and smaller service networks compared to established competitors.
- Lower brand visibility and fewer large-scale reference installations in international markets.
Recent Developments
-
In March 2025, TWI Ltd and Stirweld hosted a joint event at TWI's Cambridge facility to showcase TWI's advanced tank welding technology with Stirweld's retractable pin Friction Stir Welding (FSW) technology. The event, a part of the UK’s Aerospace Technology Institute (ATI) MASTER project, featured live welding demonstrations and speakers from organizations such as GKN Aerospace. The collaboration aimed to improve aluminum hydrogen storage tank manufacturing for the aerospace sector, reflecting a shared commitment to advancing FSW technology for future industrial needs.
-
In November 2022, Friction Welding Technologies Pvt. Ltd. (FWT) announced its acquisition by Manufacturing Technologies, Inc. (MTI), a leading provider of friction and resistance welding technologies with operations in the US and UK.
Friction Stir Welding Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 262.4 million
Estimated market size in 2026
USD 279.2 million
Projected market size by 2033
USD 449.7 million
Growth rate
CAGR of 7.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end use, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; Italy; Spain; UK; China; India; Japan; South Korea; Australia; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
ETA Technology; YAMAZAKI MAZAK CORPORATION; FOOKE GmbH; PAR Systems; Hitachi Power Solutions Co.,Ltd.; NITTO SEIKI CO., LTD.; Grenzebach Group; Bond Technologies, LLC.; PTG; and TRA-C industrie.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Friction Stir Welding Equipment Market Report Segmentation
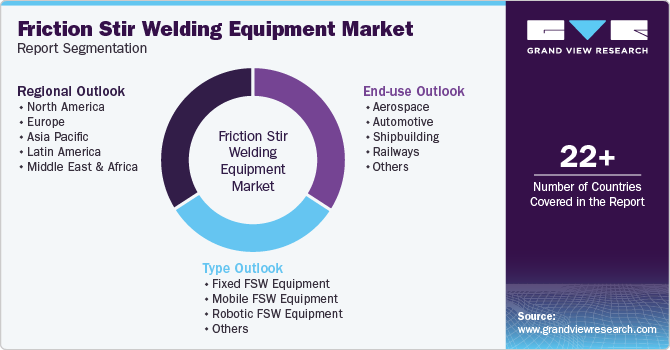
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global friction stir welding equipment market report based on type, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Fixed FSW Equipment
-
Mobile FSW Equipment
-
Robotic FSW Equipment
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Aerospace
-
Automotive
-
Shipbuilding
-
Railways
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Spain
-
UK
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The friction stir welding equipment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each friction stir welding equipment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Type
Revenue Capture Definition
Fixed FSW Equipment
Revenue is generated from the sale of stationary friction stir welding machines purchased by manufacturers for dedicated production lines and large-scale fabrication facilities.
Mobile FSW Equipment
Revenue is generated from the sale of portable and field-deployable friction stir welding systems used for on-site manufacturing, maintenance projects, and large-structure welding applications.
Robotic FSW Equipment
Revenue is generated from the sale of robotic friction stir welding cells, automated welding platforms, robotic integration systems, and related hardware deployed in advanced manufacturing environments.
Others
Revenue is generated from the sale of customized, gantry-based, hybrid, laboratory-scale, and other friction stir welding equipment designed for specialized industrial requirements.
Application
Revenue Capture Definition
Aerospace
Revenue is attributed to equipment sales made to aircraft, spacecraft, and aerospace component manufacturers for structural welding applications.
Automotive
Revenue is attributed to equipment sales for vehicle production facilities, including applications involving lightweight structures, battery enclosures, and electric vehicle components.
Shipbuilding
Revenue is attributed to equipment sales supporting ship construction, marine structure fabrication, and aluminum vessel manufacturing.
Railways
Revenue is attributed to equipment sales used in railcar body manufacturing, train component fabrication, and railway infrastructure projects.
Others
Revenue is attributed to equipment sales across various industrial sectors such as electronics, construction, defense, and other utilizing friction stir welding technology for production and fabrication activities.
Estimation Model
Layer Name
Key Question
Description
End-Use Industry Assessment
Which industries generate demand for FSW equipment?
Analyze the adoption of friction stir welding equipment across aerospace, automotive, shipbuilding, railways, and other industrial sectors. This layer identifies the major demand-generating industries and evaluates the impact of lightweight material usage, manufacturing expansion, and production requirements on equipment demand.
Equipment Demand Analysis
What type of FSW equipment is being purchased?
Assess demand across fixed, mobile, robotic, and other FSW equipment categories. The analysis considers factors such as production volume, automation requirements, application complexity, and end-user preferences to determine the market share and growth potential of each equipment type.
Installation & Replacement Assessment
How many new systems are installed or replaced annually?
Estimate annual equipment installations by evaluating new manufacturing facilities, capacity expansion projects, automation upgrades, and replacement of aging welding systems. This layer helps quantify the total unit demand generated from both new investments and replacement cycles.
Revenue Estimation
What is the total market revenue generated?
Estimate the total market revenue by assessing industry demand, equipment adoption patterns, technological advancements, regional market activity, and investments across key end-use sectors. This layer represents the final market size and growth outlook for the Friction Stir Welding Equipment Market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The report delivered a comprehensive regional assessment of the friction stir welding equipment market across major geographies, including demand patterns, industrial development trends, manufacturing activity, adoption of advanced welding technologies, and growth prospects across key end-use industries such as aerospace, automotive, shipbuilding, and railways.
Enabled the client to identify high-growth regions, evaluate market attractiveness, prioritize geographic expansion strategies, and understand region-specific demand drivers and challenges.
Competitive Benchmarking
The report provided an in-depth analysis of the competitive landscape, including market participant categorization, strategic positioning, technology focus, operational strengths, and competitive dynamics. The assessment also examined key business strategies and market differentiation factors influencing industry competition.
Assisted the client in understanding the competitive environment, identifying market gaps, evaluating competitor strengths and weaknesses, and supporting strategic decision-making for market entry or expansion.
Opportunity Assessment
The report identified major growth opportunities across equipment types and end-use industries, focusing on automation trends, increasing use of lightweight materials, expansion of advanced manufacturing facilities, and rising adoption of friction stir welding technologies in high-performance applications.
Helped the client prioritize growth areas, align investment decisions with emerging market trends, identify future revenue opportunities, and develop long-term business strategies based on evolving industry requirements.
Frequently Asked Questions About This Report
North America dominated the friction stir welding equipment market with the largest revenue share of 32.2% in 2025.
Asia Pacific is anticipated to be the fastest-growing regional market over the forecast period, driven by expanding aerospace manufacturing, increasing industrial automation, and growing investments in advanced welding technologies.
The aerospace segment accounted for the largest revenue share of 29.8% in 2025.
Key trends include increasing adoption of automated welding systems, growing use of friction stir welding in electric vehicle manufacturing, rising demand for lightweight structural components, and advancements in robotic FSW technologies.
The global friction stir welding equipment market size was valued at USD 262.4 million in 2025 and is estimated at USD 279.2 million for 2026.
The global friction stir welding equipment market is expected to grow at a CAGR of 7.0% from 2026 to 2033, reaching USD 449.7 million by 2033.
The fixed FSW equipment segment led with a 40.4% revenue share in 2025, while the robotic FSW equipment segment is the fastest-growing type.
Some of the key players operating in the friction stir welding equipment market include ETA Technology, YAMAZAKI MAZAK CORPORATION, FOOKE GmbH, PAR Systems, Hitachi Power Solutions Co.,Ltd., NITTO SEIKI CO., LTD., Grenzebach Group, Bond Technologies, PTG, Groupe TRA-C industries.
The friction stir welding equipment market is driven by increasing demand for high-quality, cost-effective, and environmentally friendly welding technologies in industries such as aerospace, automotive, and shipbuilding.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


