
- Home
- »
- Renewable Energy
- »
-
Fuel Ethanol Market Size, Growth Report, 2026-2033GVR Report cover

Fuel Ethanol Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Starch-based, Sugar-based, Cellulosic), By Technology (Wet Mill, Dry Mill), By Application (Conventional Fuel Vehicles), By Region, And Segment Forecasts
Market Size, 2025
$112.5BMarket Estimate, 2026
$118.2BMarket Forecast, 2033
$167.4BCAGR, 2026–2033
5.1%Fuel Ethanol Market Summary
The global fuel ethanol market size was valued at USD 112.5 billion in 2025 and is projected to grow from USD 118.2 billion in 2026 to USD 167.4 billion by 2033, growing at a CAGR of 5.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 56.0% in 2025. This growth is driven by increased demand for renewable fuels, rising environmental concerns, and regulations requiring a shift away from traditional fossil fuels. In addition, the automotive industry, which is growing rapidly with advances in science and technology, has faced challenges in controlling air pollution.
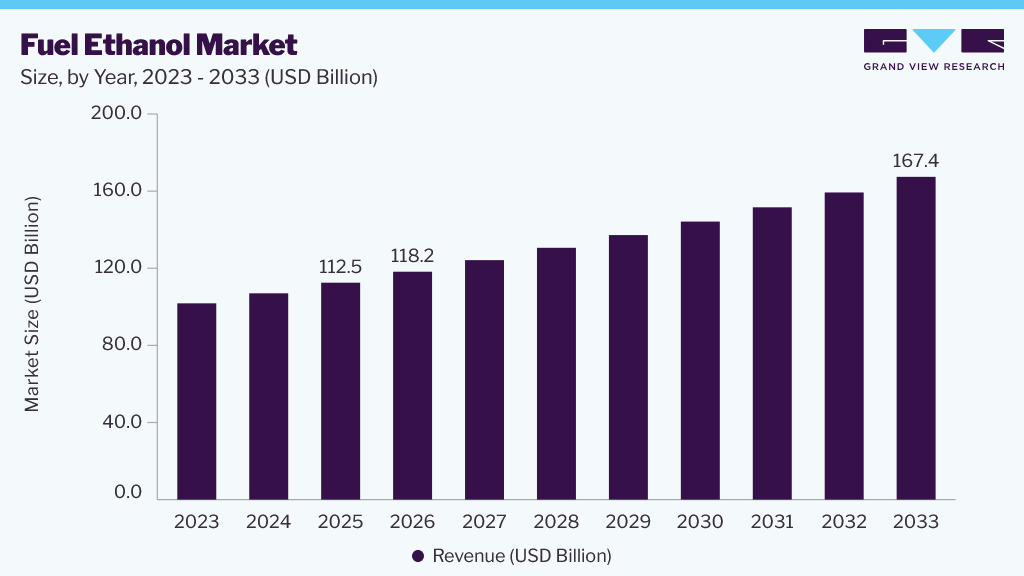 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The starch-based segment dominated the market, with a revenue share of about 75.0% in 2025.
- By technology: The dry mill segment held the largest revenue share of over 90.0% in 2025.
- By application: The conventional fuel vehicles segment held the largest revenue share of over 83.0% in 2025.
Regional Highlights
- Largest regional market: North America (56.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (Highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 112.5 Billion
- Estimated market size in 2026: USD 118.2 Billion
- Projected market size by 2033: USD 167.4 Billion
- CAGR (2026-2033): 5.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The use of fuel ethanol offers significant advantages, such as improved fuel economy and increased thermal efficiency, which are likely to drive demand over the forecast period. To minimize carbon emissions from gasoline in the automotive & transportation industries, the use of ethanol as a bio-based additive has been increasing over the past couple of years. In addition, advancements in production technology have further helped convert cellulosic biomass into ethanol, making fuel ethanol more cost-effective and scalable. For instance, in March 2024, Blue Biofuels Inc. successfully produced commercial cellulosic ethanol from biomass using its cellulose-to-sugar pilot line. Such developments are likely to boost market growth over the forecast period.
Ethanol is an alternative transportation fuel that is more effective than other high- and volatile-priced conventional fuels. For instance, in May 2024, according to the Renewable Fuels Association, the average national wholesale price of ethanol was around USD 1.20 per gallon lower than the petroleum gasoline blendstock. The low cost of such renewable energy has boosted rapid market growth.
The availability of feedstocks such as corn, sugarcane, wheat, and agricultural waste in major producing regions is enabling increased fuel ethanol production capacity. For instance, challenges such as storage and sales associated with the overproduction of food grains and sugar are mitigated with the help of fuel. Moreover, starch-based crops are used to produce biofuels. According to the European Technology and Innovation Platform, about 2% of Europe’s grain supply and 0.7% of EU agricultural land has been used to produce renewable ethanol, thereby mitigating the challenges of overproduction of starch crops. These factors are expected to drive market growth.
Analyst Perspective
The market is witnessing steady expansion, driven by global efforts to reduce greenhouse gas emissions, enhance energy security, and diversify transportation fuel sources. Government mandates such as blending targets, renewable fuel standards, and low-carbon fuel policies are playing a critical role in accelerating ethanol adoption across major economies, including the United States, Brazil, India, China, and several European countries. Rising volatility in crude oil prices is further strengthening the economic attractiveness of ethanol as an alternative fuel. Technological advancements in feedstock processing, including second-generation and cellulosic ethanol production, are improving efficiency, feedstock utilization, and sustainability outcomes. However, challenges such as feedstock price volatility, supply chain constraints, and concerns regarding food-versus-fuel dynamics may impact market growth. Overall, the market is expected to maintain a positive growth trajectory, supported by decarbonization goals, advancements in biofuel technologies, and global renewable energy transition initiatives.
Product Insights
By product, starch-based products dominated the market, accounting for approximately 75.0% in 2025. The segment’s dominance is primarily attributed to the widespread availability of feedstocks such as corn, wheat, and cassava, as well as well-established production infrastructure in major ethanol-producing countries. Starch-based ethanol has lower lifecycle greenhouse gas emissions than conventional fossil fuels, making it a preferred fuel for reducing transportation-related emissions. This has significantly supported segment growth. For instance, in October 2023, according to the National Renewable Energy Laboratory, replacing petroleum-based fuel with sustainable biofuel can produce about 410-640 million metric tonnes (Mt) of carbon dioxide equivalent per year over the life cycle, representing a 68%- 73% reduction in GHG emissions compared with petroleum-based fuels.
Cellulosic is expected to grow at the fastest CAGR over the forecast period, as it can be easily produced from non-food feedstocks such as agricultural waste, forest residues, municipal solid waste, and dedicated energy crops. Technological advancements in pretreatment, hydrolysis, and fermentation are making cellulosic ethanol production more efficient and cost-effective. Advancements in second-generation biofuel technologies and increasing investments in non-food biomass utilization are accelerating the commercialization of cellulosic ethanol. For instance, in June 2024, BP Plc announced plans to develop second-generation (2G) ethanol through its wholly owned BP Bunge Bioenergia business, using sugarcane residues (bagasse and straw) as feedstocks. Increasing investment in second-generation ethanol technologies and agricultural residue-based feedstocks is expected to accelerate growth in the cellulosic ethanol segment over the forecast period.
Technology Insights
The dry mill dominated the market and accounted for a market share of approximately 90.0% in 2025. It can be attributed to lower capital and operating costs and to the technology's ability to use the entire corn kernel, reducing waste and increasing efficiency. Some key innovations and developments in dry milling are improving efficiency for fuel ethanol production, such as improved automation and control systems, enhanced grinding and separation techniques, and co-product optimization, which is anticipated to drive rapid market growth. Increasing adoption of cost-efficient ethanol production technologies and continuous process automation are driving the growth of dry milling facilities worldwide. In February 2025, Cargill Incorporated acquired the remaining 50% stake in SJC Bioenergia, strengthening its integrated sugarcane and corn ethanol production platform. The acquisition enhances the company's ability to optimize feedstock utilization and improve ethanol production efficiency. Such investments in integrated ethanol production assets and process optimization are expected to support the growth of efficient dry milling technologies over the forecast period.
The wet mill segment is expected to grow significantly over the forecast period. It can be attributed to wet mill technology's ability to produce a greater variety of by-products, achieve finer particle size reduction, improve the final product's physical properties, and use a wider range of feedstocks, which is expected to boost segment growth in the future. The wet mill segment is driven by its ability to maximize ethanol yield while generating high-value co-products such as corn oil, gluten feed, and starch, improving the overall economics of fuel ethanol production. The ability to integrate ethanol production with co-product commercialization further supports segment growth. For instance, in June 2025, Cargill Incorporated announced an investment of nearly USD 90 million to modernize and expand its corn milling facility in Fort Dodge, Iowa. The investment is aimed at increasing corn processing capacity and operational efficiency, strengthening the production of corn-derived products, including ethanol and value-added co-products used across food and industrial applications. Continued investments in advanced corn milling infrastructure are enhancing production efficiency and supporting the dominance of wet milling technology.
Application Insights
Based on application, conventional fuel vehicles dominated the market and accounted for a market share of approximately 83.0% in 2025. This can be attributed to growing requirements to boost the fuel economy of these vehicles in several countries, which is expected to increase product consumption in the coming years. Ethanol acts as an anti-knock additive, or octane enhancer, and helps modern higher-compression engines run more efficiently. E10 includes a blend of 10% ethanol with unleaded gasoline in conventional vehicles. The growing implementation of ethanol blending mandates and the widespread compatibility of E10 gasoline with existing internal combustion engine vehicles continue to drive ethanol consumption in conventional fuel vehicles. For instance, in 2025, India accelerated the rollout of E20 fuel at retail fuel stations to support higher ethanol blending in conventional vehicles, strengthening ethanol demand in the transportation sector. Such policy-driven initiatives are expected to support continued segment growth over the forecast period.
The flexible fuel vehicles segment is expected to grow at the fastest CAGR over the forecast period. The segment’s growth is primarily attributed to the increasing adoption of vehicles capable of operating on gasoline and higher ethanol blends, including E20 to E85. Flexible fuel vehicles offer significant environmental benefits, as ethanol is a cleaner-burning fuel that helps reduce greenhouse gas emissions and harmful tailpipe emissions compared to conventional gasoline. Growing government support for higher ethanol blending and rising investments in flex-fuel vehicle development are further driving segment growth. For instance, in August 2023, Toyota Kirloskar Motor showcased its flex-fuel strong hybrid electric vehicle in India, supporting the country’s transition toward higher ethanol-blended fuels and low-emission mobility solutions. Such developments are expected to accelerate the adoption of flexible fuel vehicles over the forecast period.
Regional Insights
The North America fuel ethanol market dominated the market, accounting for a revenue share of 56.0%. It can be attributed to the presence of the well-established automotive industry and its strict regulations over particulate emissions. In addition, stringent environmental laws in this region are promoting a shift from traditional fossil fuels, making fuel ethanol with clean-burning properties a highly attractive option. Growing investments in renewable feedstocks and low-carbon industrial solutions are strengthening the bioethanol value chain across North America, supporting broader adoption of sustainable fuels and bio-based products. For instance, in March 2024, Braskem and Shell Chemicals introduced certified bio-attributed and bio-circular polypropylene and propylene to the U.S. market. The products utilize renewable feedstocks, including bioethanol-derived inputs, through a mass-balance approach. The increasing integration of bioethanol-derived feedstocks into industrial applications is strengthening North America's renewable fuels ecosystem and supporting long-term growth of the fuel ethanol value chain.
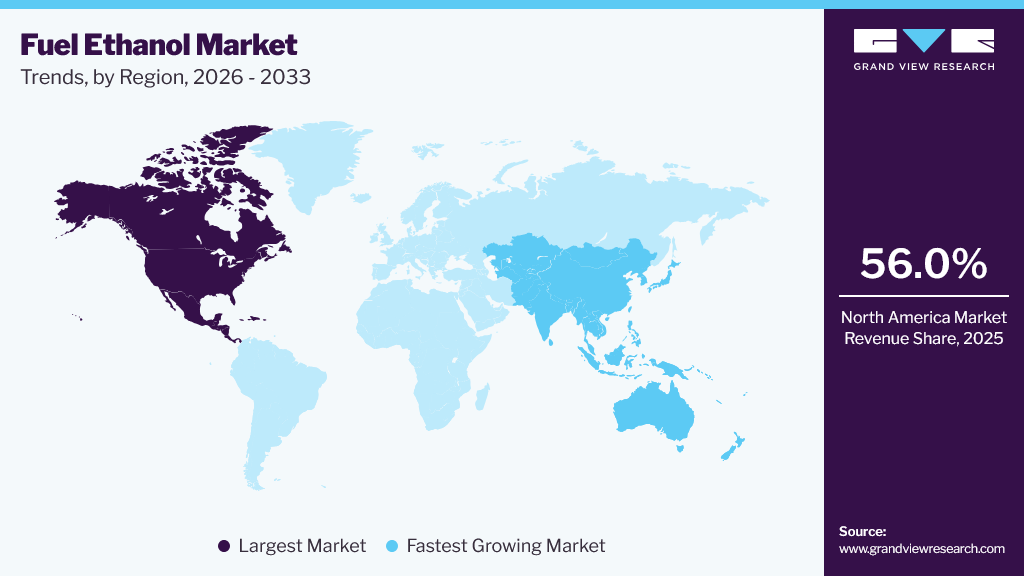 To learn more about this report, Download Free Sample Report
U.S. Fuel Ethanol Market Trends
The fuel ethanol market in the U.S. accounted for approximately for 48.0% share of the global market in 2025. It can be attributed to the continuous technological and material advancements used in ethanol production and improving the efficiency and cost-effectiveness of production in the U.S. Various policies/programs and investments to promote the use of ethanol, including blending mandates and incentives for production, have been introduced by the government of the U.S. For instance, in June 2023, the U.S. Department of Agriculture, from the Inflation Reduction Act, announced its plan to invest up to USD 500 million to increase the availability of domestic biofuels. All these factors have contributed to the boost in the U.S. market.
Asia Pacific Fuel Ethanol Market Trends
The fuel ethanol market in the Asia Pacific is expected to grow at the fastest CAGR over the forecast period. It can be attributed to the rising number of investments and the various government initiatives and developments for sustainable development. For instance, in January 2024, China launched a trial for an annual ethanol production capacity of 600,000 tonnes, considered the world’s largest. This equipment increases the added value of coal and provides a feasible way for the low-carbon development of steel and petrochemical industries. For instance, in March 2024, the Ministry of Petroleum and Natural Gas of India announced the E20 program, and with the launch of ETHANOL100 at 183 Indian Oil, the target of 20% ethanol blending is expected to become closer by 2025-2026.
Europe Fuel Ethanol Market Trends
The fuel ethanol market in Europe is expected to grow steadily over the forecast period. It can be attributed to technological innovations that enhance ethanol's competitiveness and improve the sustainability of production processes. European governments offer various support mechanisms to promote ethanol production and use, including blending mandates, tax incentives, and subsidies. The demand for ethanol continues to grow, primarily driven by the take-up of super-ethanol E85 and SP95-E10, particularly in France. For instance, in June 2023, ArcelorMittal announced the first industrial production of ethanol by using LanzaTech's carbon biorecycling process.
MEA Fuel Ethanol Market Trends
The fuel ethanol market in MEA was identified as an emerging region in 2025. Although it accounted for a relatively smaller market share, demand is increasing due to rising environmental awareness and growing interest in alternative transportation fuels. South Africa remains one of the key markets in the region due to its abundant cultivation of sugarcane, corn, and sorghum, which provide sufficient feedstock for ethanol production. The country’s favorable climatic conditions and diverse agricultural landscape further support the availability of feedstocks for bioethanol production. In addition, supportive regulatory initiatives are expected to strengthen the regional market. For instance, South Africa’s biofuels regulatory framework mandates bioethanol blending levels of 2% to 10% in petrol, supporting long-term demand for fuel ethanol and encouraging investments in domestic bioethanol production capacity.
Key Fuel Ethanol Company Insights
Some of the key companies in the market include Braskem, BP p.l.c., Cargill Incorporated, and INEOS. These companies are growing their market revenue by launching new products, entering into collaborations, and adopting other strategies.
- Cargill is a U.S.-based agribusiness company engaged in corn processing and fuel ethanol production. The company operates multiple corn wet-milling and bioindustrial facilities across North America, supplying ethanol for fuel-blending applications. Cargill focuses on improving production efficiency and advancing low-carbon biofuel solutions through investments in sustainable processing technologies.
- HBL is an India-based company with ethanol production primarily for supply to oil marketing companies for blending with gasoline under India's Ethanol Blending Program. The company focuses on zero-effluent discharge and uses renewable energy sources.
Key Fuel Ethanol Companies
The following key companies have been profiled for this study on the fuel ethanol market:
-
Braskem
-
BP p.l.c
- Cargill, Incorporated
- INEOS
- HBL
- LyondellBasell Industries Holdings B.V.
- Mitsubishi Chemical Corporation
- SABIC
- Sasol Limited
- Solvay
Recent Developments
-
In June 2024, BP Plc acquired bp Bunge Bioenergia for new biofuels projects, which can produce around 50,000 barrels a day of ethanol equivalent using sugarcane with the help of 11 agro-industrial units of bp Bunge Bioenergia across five states in Brazil.
-
In June 2023, Hindustan Petroleum Corporation Limited started a pilot study on vehicles that used ethanol-blended diesel fuel and E27 fuel.
Fuel Ethanol Market Report Scope
Report Attribute
Details
Market size in 2025
USD 112.5 billion
Estimated market size in 2026
USD 118.2 billion
Projected market size by 2033
USD 167.4 billion
Growth rate
CAGR of 5.1% from 2026 to 2033
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Product, technology, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
CCountry scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia; South Korea; Thailand; Indonesia; Brazil; Malaysia; Argentina; KSA; South Africa
Key companies profiled
Braskem; BP p.l.c; Cargill, Incorporated; INEOS; HBL; LyondellBasell Industries Holdings B.V.; Mitsubishi Chemical Corporation; SABIC; Sasol Limited; Solvay
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Fuel Ethanol Market Segmentation
This report forecasts revenue growth at regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global fuel ethanol market based on product, technology, application, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Starch-based
-
Sugar-based
-
Cellulosic
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Wet Mill
-
Dry Mill
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Conventional Fuel Vehicles
-
Flexible Fuel Vehicles
-
Others
-
-
Regional Outlook (Revenue, USD Billion; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
APAC
-
China
-
India
-
Japan
-
South Korea
-
Thailand
-
Indonesia
-
Malaysia
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
-
Frequently Asked Questions About This Report
The global fuel ethanol market size was valued at USD 112.5 billion in 2025 and is estimated at USD 118.2 billion in 2026
North America dominated with a 56.0% revenue share in 2023.
Key players in the market include Braskem S.A., BP Plc, Cargill Incorporated, INEOS Group Limited, HBL, LyondellBasell Industries Holdings B.V., Mitsubishi Chemical Corporation, SABIC, Sasol Limited, Solvay SA, and others.
The starch-based segment accounted for the largest revenue share of approximately 75.0% in 2025.
The global fuel ethanol market is expected to grow at a CAGR of 5.1% from 2026 to 2033, reaching USD 167.4 billion.
About the Author(s)
Renewable Energy Research Team
Energy & Power · Renewable EnergyThis report was authored by the renewable energy research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable energy segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


