
- Home
- »
- Conventional Energy
- »
-
Gas Turbine Services Market Size, Share Report, 2026-2033GVR Report cover

Gas Turbine Services Market (2026 - 2033)
Size, Share & Trends Analysis Report By Turbine Type (Heavy Duty, Industrial), By Turbine Capacity (< 100 MW,), By Service Type, By Service Provider (OEM, Non-OEM), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$45.1BMarket Estimate, 2026
$46.2BMarket Forecast, 2033
$92.5BCAGR, 2026–2033
10.4%Gas Turbine Services Market Summary
The global gas turbine services market size was valued at USD 45.1 billion in 2025 and is projected to grow from USD 46.2 billion in 2026 to USD 92.5 billion by 2033, at a CAGR of 10.4% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 35.8% in 2025. The market is witnessing rapid expansion, driven by the modernization of aging turbine fleets and the growing need to enhance operational efficiency and reliability.
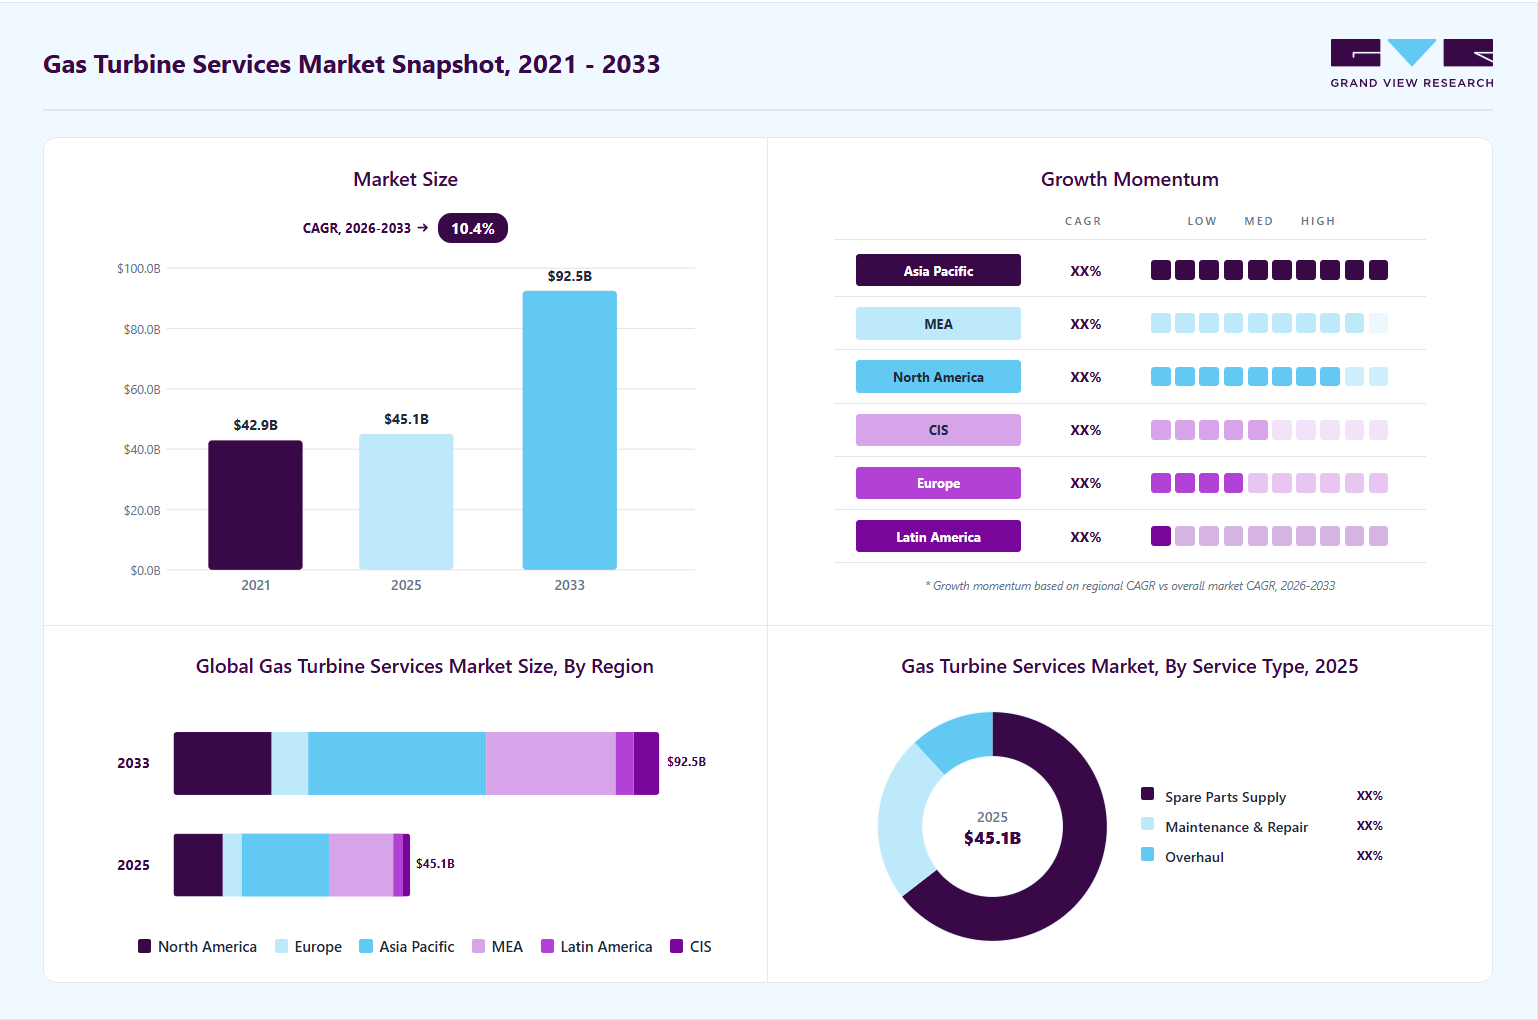 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By turbine type: Heavy-duty segment held the largest market share of 51.6% in 2025.
- By turbine capacity: 100 to 200 MW segment held the largest market share of 41.5% in 2025.
- By service type: Spare parts supply segment held the largest market share of 64.5% in 2025.
- By service provider: OEMs segment held the largest market share of 61.5% in 2025.
- By End-Use: Power generation segment held the largest market share of 68.2% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (35.8% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 45.1 Billion
- Estimated market size in 2026: USD 46.2 Billion
- Projected market size by 2033: USD 92.5 Billion
- CAGR (2026-2033): 10.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The increasing demand for flexible, fast-ramping power to support the integration of renewable energy sources is further accelerating market growth.The global gas turbine services industry is experiencing robust growth, driven by the expanding installed base of gas turbines and the aging of existing infrastructure across power generation and industrial sectors. As a significant number of turbines reach mid-life or late-life stages, the demand for maintenance, repair, and overhaul services is increasing to ensure operational reliability, efficiency, and extended asset lifespan. This ongoing need for lifecycle management is becoming a key factor supporting steady market expansion.
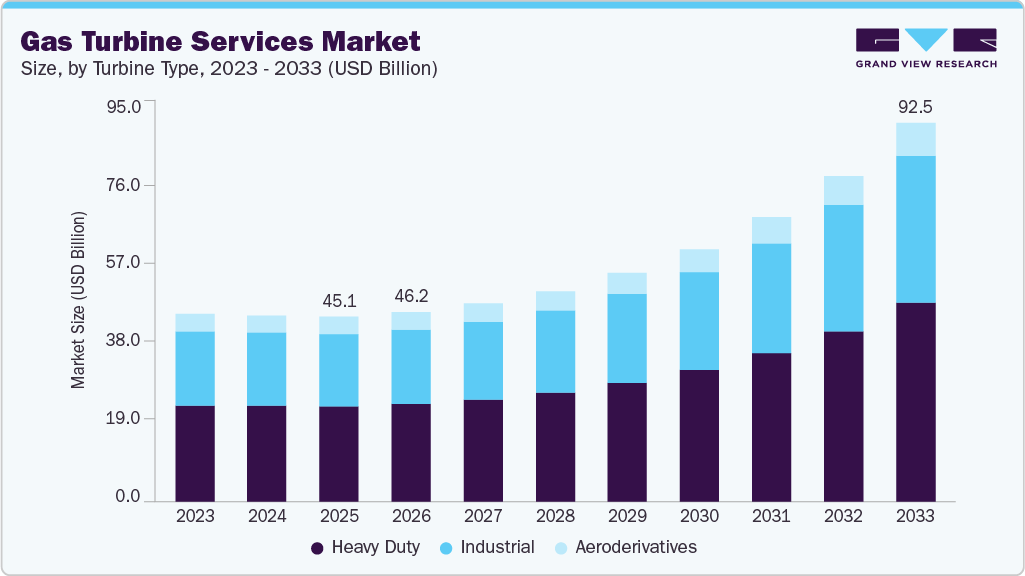 To learn more about this report, Download Free Sample Report
The rising integration of renewable energy sources is further accelerating demand for gas turbine services. Gas turbines play a critical role in maintaining grid stability by offering fast-ramping and peak-shaving capabilities to balance intermittent power generation from wind and solar. This growing reliance on flexible power generation is driving the need for consistent servicing, performance optimization, and technological upgrades, thereby creating new opportunities and sustained growth in the market.
Drivers, Opportunities & Restraints
The primary factor driving the market is the expanding installed turbine base and the aging of existing assets, which are driving higher demand for maintenance, repair, and overhaul (MRO) services. As turbines progress into mid- and late-life, operators increasingly focus on servicing, upgrades, and performance improvements to maintain efficiency, reliability, and longer operating life. This sustained need for lifecycle management continues to underpin market growth. Advancements in digital monitoring and predictive maintenance technologies are further enhancing service efficiency and reducing unplanned downtime.
A key opportunity in the global market lies in hydrogen-compatible retrofits, as the industry moves toward low and zero-carbon power generation. Service providers are increasingly focusing on modifying existing turbine combustion systems to operate on hydrogen-natural gas blends and eventually transition to 100% hydrogen fuel. These retrofits enable asset owners to decarbonize their operations without replacing entire turbine systems, making it a cost-effective pathway toward net-zero emissions.
However, a major challenge in the gas turbine services industry is the surge in equipment and maintenance costs, which is placing significant financial pressure on operators. Gas turbine prices have been rising due to supply chain constraints, material costs, and advanced technology integration, while maintenance expenses continue to escalate, accounting for a substantial share of total operational costs, often up to 32%. These high service and upkeep costs can limit investment in upgrades and long-term service contracts, particularly for smaller operators, and may impact overall profitability.
Shortage of highly skilled labor required to manage increasingly complex and technologically advanced turbine systems is one of the concerning restraints for the market. Modern high-efficiency turbines are integrated with digital monitoring, AI-driven diagnostics, and predictive maintenance tools, which demand specialized technical expertise. However, the limited availability of trained professionals to handle these advanced systems is creating operational challenges for service providers and operators.
Turbine Type Insights
The heavy-duty segment led the market with the largest revenue share of 51.6% in 2025 and is projected to grow at the fastest CAGR during the forecast period, driven by its extensive deployment in large-scale power generation applications. These turbines operate under high loads and continuously, making them more prone to wear and tear and requiring frequent maintenance, repair, and overhaul services. The heavy-duty turbines represent a significant share of the global installed base, especially in utility-scale power plants, further driving consistent service demand.
The industrial segment is projected to register the second-fastest CAGR of 10.3% during 2026-2033, primarily driven by the increasing deployment of gas turbines across energy-intensive industries such as refining, petrochemicals, chemicals, and manufacturing, where uninterrupted power and process reliability are critical. The rising trend of captive power generation and combined heat and power (CHP) systems is further accelerating demand for recurring maintenance, repair, and overhaul services.
Turbine Capacity Insights
The 100 to 200 MW segment led the market with the largest revenue share of 41.5% in 2025, driven by its widespread use across both utility-scale power generation and industrial applications. Turbines in this range offer an optimal balance between efficiency, flexibility, and cost, making them a preferred choice for combined-cycle plants and mid-sized power projects. Their role in supporting grid stability and meeting variable power demand further reinforces the need for regular servicing, contributing to the segment’s dominant position.
The >200 MW segment is projected to grow at the fastest CAGR of 10.8% over the forecast period, supported by increasing investments in large-scale power generation and the expansion of high-efficiency combined-cycle power plants. These high-capacity turbines are critical for meeting rising electricity demand and supporting grid reliability, especially in rapidly developing regions. As these units operate under intensive conditions and play a central role in base-load power supply, they require frequent and advanced maintenance, repair, and overhaul services.
Service Type Insights
The spare parts supply segment led the market with the largest revenue share of 64.5% in 2025, due to the continuous and recurring need for component replacements to keep turbines operating efficiently. Critical parts such as blades, vanes, and combustor components are subject to high temperatures and mechanical stress, leading to regular wear and degradation over time. The extensive global installed base of gas turbines ensures a steady, long-term demand for replacement components, making spare parts supply a dominant contributor to overall service revenues.
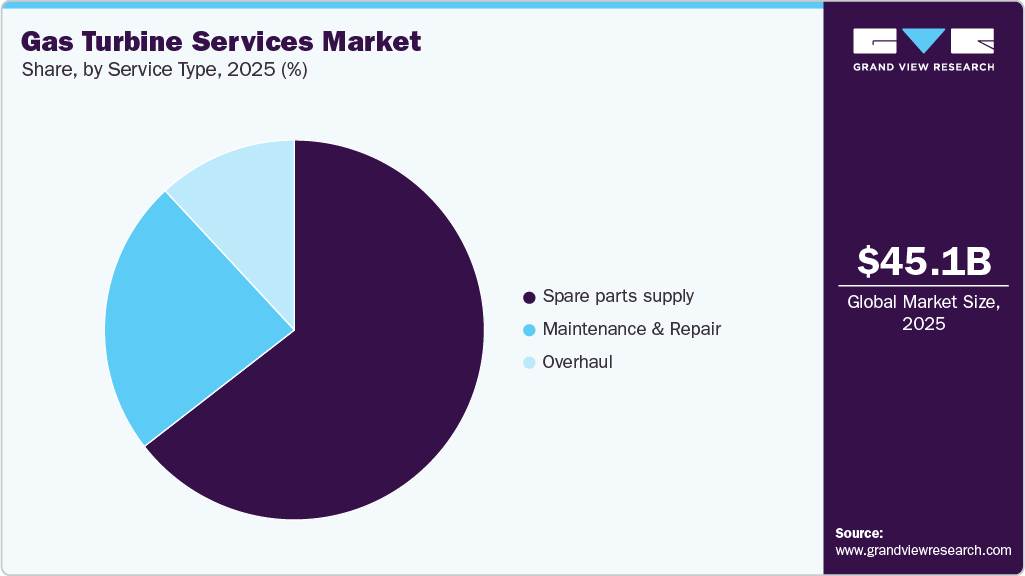 To learn more about this report, Download Free Sample Report
The maintenance & repair segment is projected to register at the fastest CAGR of 10.8% over the forecast period, driven by the increasing need to ensure continuous and efficient turbine operations. The growing integration of digital monitoring and predictive maintenance technologies is enabling more proactive and condition-based servicing, further boosting demand. The need to minimize downtime, improve reliability, and optimize performance across power generation and industrial applications is accelerating growth in this segment.
Service Provider Insights
The OEMs segment led the market with the largest revenue share of 61.5% in 2025 and is projected to grow at the fastest CAGR during the forecast period, driven by their in-depth technical expertise and strong familiarity with proprietary turbine technologies. As original equipment manufacturers, they provide certified spare parts, advanced diagnostics, and specialized service capabilities that non-OEM providers often cannot fully replicate. This ensures higher reliability, performance optimization, and compliance with operational standards, making OEMs the preferred choice for critical maintenance and long-term service agreements.
The non-OEM segment is projected to grow at the second-fastest CAGR of 10.2% during 2026-2033, driven by increasing demand for cost-effective and flexible service alternatives to OEM offerings, particularly among operators of aging turbine fleets and in price-sensitive markets. Independent service providers are gaining traction by offering 20-30% lower service costs, customized solutions, and shorter turnaround times, while leveraging advanced reverse engineering capabilities and access to high-quality third-party spare parts. The expiration of long-term service agreements (LTSAs) with OEMs is enabling end users to diversify their service providers, further accelerating Non-OEM adoption.
End-Use Insights
The power generation segment led the market with the largest revenue share of 68.2% in 2025 and is projected to grow at the fastest CAGR during the forecast period, supported by the extensive use of gas turbines in utility-scale electricity production. Power plants rely heavily on gas turbines for both baseload and peak-load operations, making regular maintenance, repair, and overhaul essential to ensure continuous and efficient performance. The growing need for reliable and flexible power to support grid stability and integrate renewable energy sources further strengthens the dominance of the power generation segment.
The oil & gas segment is projected to grow at the slowest CAGR of 9.3% during 2026-2033, primarily due to capex discipline and cyclical investment patterns across upstream and midstream operations, which constrain new turbine installations and defer non-essential service activities. The sector is undergoing a gradual energy transition, with increasing capital allocation toward lower-carbon solutions, thereby limiting the long-term expansion of gas-turbine-dependent infrastructure. Mature assets in key regions are also witnessing optimization-driven operations, reducing service frequency through efficiency improvements and digital monitoring.
Regional Insights
The gas turbine services market in North America is driven by the ongoing shift from coal to natural gas in power generation. Regulatory pressures to reduce emissions, along with abundant and low-cost shale gas supplies, are accelerating the transition toward natural gas-fired, combined-cycle power plants across the United States and Canada. This shift is expanding the installed base of gas turbines and increasing their utilization, thereby driving demand for MRO services. As operators focus on efficiency, reliability, and compliance with environmental standards, the need for advanced turbine servicing continues to grow across the region.
U.S. Gas Turbine Services Market Trends
The gas turbine services market in the U.S. held a significant share in North America in 2025, supported by the ongoing shale gas boom that has made natural gas a highly cost-effective fuel for power generation. The availability of low-cost natural gas has increased the attractiveness of gas-fired power plants, leading to higher operational hours for gas turbines. This intensified usage is driving greater demand for maintenance, repair, and overhaul services to ensure reliability and efficiency. The need for consistent and advanced turbine servicing continues to grow across the country.
Asia Pacific Gas Turbine Services Market Trends
Asia Pacific dominated the global gas turbine services market with the largest revenue share of 35.8% in 2025 and is projected to grow at the fastest CAGR during the forecast period, driven by its extensive and growing installed base of gas turbines installed across power generation and industrial sectors. Rapid urbanization, industrial expansion, and rising electricity demand in countries such as China, India, and Japan have led to significant deployment of gas-fired power plants. Many turbines in the region are entering middle and later phases of operation, increasing the need for maintenance, repair, and overhaul services, thereby strengthening the Asia Pacific’s dominant market position.
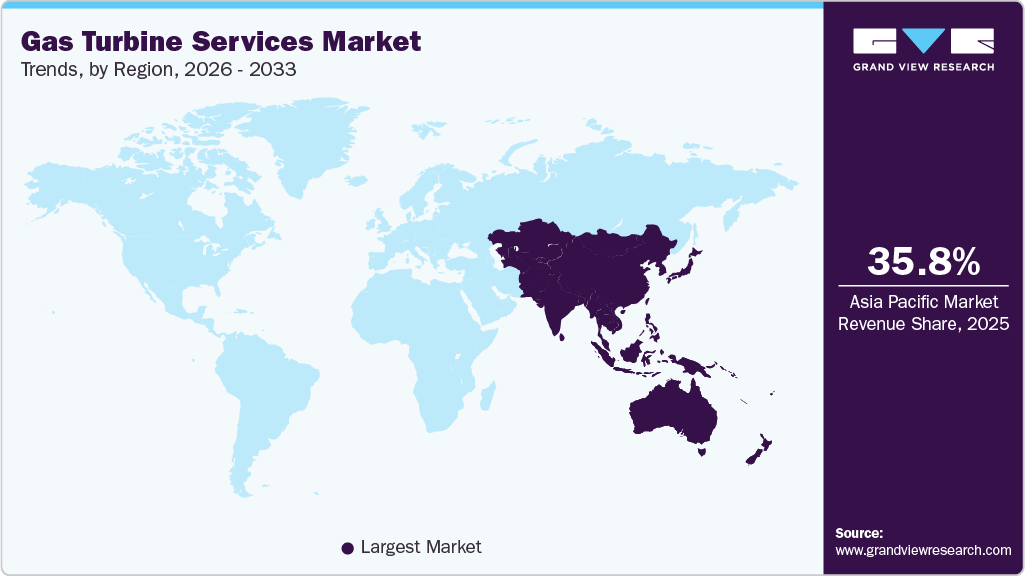 To learn more about this report, Download Free Sample Report
The gas turbine services market in China accounted for the largest market revenue share in the Asia Pacific in 2025, driven by its expanding fleet of gas-fired power plants and strong policy support for cleaner energy. The country’s ongoing shift toward lower-emission energy sources is accelerating service demand. Notably, decarbonization policies by the Chinese government aimed at reducing coal dependency are increasing the utilization of gas-fired power plants, directly boosting the need for maintenance, repair, and overhaul services. This transition is reinforcing China’s pivotal role in driving market growth across the region.
Europe Gas Turbine Services Market Trends
The gas turbine services market in Europe is growing, driven by the widespread adoption of combined heat and power (CHP) systems to improve energy efficiency and reduce emissions. Industrial facilities and municipal utilities across the region rely heavily on CHP-based gas turbines for simultaneous electricity and heat generation, which requires consistent maintenance, repair, and specialized servicing. Countries such as Germany are at the forefront of CHP adoption, further sustaining demand for advanced turbine services. This strong dependence on efficient, integrated energy systems continues to support steady growth in the region.
The Germany gas turbine services market is a mature yet strategically evolving market, supported by its strong installed base of gas-fired power plants and industrial cogeneration (CHP) systems. The country’s ongoing energy transition (Energiewende) is driving increased reliance on gas turbines as a flexible backup to intermittent renewable energy sources such as wind and solar, thereby sustaining demand for maintenance, repair, and upgrade services. The phase-out of coal and nuclear power is reinforcing the role of high-efficiency gas turbines, particularly in balancing grid stability.
The Commonwealth of Independent States (CIS) Gas Turbine Services Market Trends
The gas turbine services market in CIS is driven by abundant natural gas availability and strong reliance on gas-fired power generation. Countries such as Russia, Azerbaijan, Kazakhstan, Tajikistan, Turkmenistan, and Uzbekistan possess large hydrocarbon reserves, which continue to support widespread use of gas-fired turbines for electricity generation. This strong dependence on natural gas-based power systems necessitates consistent maintenance, repair, and overhaul services to ensure operational reliability and efficiency. The demand for gas turbine services remains steady across the region.
Latin America Gas Turbine Services Market Trends
The gas turbine services market in Latin America is driven by increasing industrialization and rising power demand across key economies. The expansion of the manufacturing, petrochemical, and oil & gas sectors, particularly in Brazil and Argentina, is boosting the adoption of on-site power generation and combined heat and power (CHP) systems. These systems rely heavily on gas turbines for efficient and reliable energy supply, creating a steady need for maintenance, repair, and overhaul services. As industrial activity continues to grow, the demand for consistent and specialized turbine servicing is expected to increase across the region.
Middle East & Africa Gas Turbine Services Market Trends
The gas turbine services market in the Middle East & Africa is growing due to the region’s strong dependence on gas-fired power generation, supported by abundant natural gas resources and rising electricity demand. Ongoing investments in power infrastructure, particularly in countries such as Saudi Arabia and the United Arab Emirates, are expanding the installed base of gas turbines, thereby increasing the need for maintenance, repair, and overhaul services. The efforts to improve energy access and grid reliability across parts of Africa, along with the gradual integration of renewable energy sources, are boosting the demand for flexible, fast-ramping power solutions.
Key Gas Turbine Services Company Insights
Some of the key participants in the global gas turbine services industry include Siemens Energy, Mitsubishi Power, Ltd., Kawasaki Heavy Industries, Ltd., Solar Turbines Inc., Ansaldo Energia, Bharat Heavy Electricals Ltd., Destinus Energy, Flowserve, GE Vernova, and Hanwha Power. These companies are focusing on enhancing turbine performance, operational efficiency, and cost optimization while ensuring long-term reliability of gas turbine assets. Strategic initiatives such as technological innovation, service portfolio expansion, and digital solution integration are helping them strengthen their competitive position.
Their operations typically include turbine MRO, component refurbishment, spare parts supply, and performance upgrades, ensuring efficient and scalable service delivery. Industry leaders are emphasizing advanced diagnostics, predictive maintenance, and digital monitoring solutions to enhance reliability and operational visibility. Significant investments are being made in remote monitoring systems, advanced materials for high-temperature components, and upgrade solutions to improve turbine output and efficiency. The adoption of AI-driven analytics and smart maintenance systems is further improving service efficiency and reducing unplanned outages.
As global demand for reliable and flexible power generation continues to rise, companies are prioritizing expanding service contracts, implementing lifecycle management solutions, and enhancing supply chain resilience. Strategic collaborations, long-term service agreements, and vertical integration across the value chain are key growth strategies in the market. Advancements in digitalization, performance optimization technologies, and low-emission turbine upgrades are reshaping the competitive landscape. Continuous innovation in service capabilities and turbine technologies is expected to drive long-term market growth.
Key Gas Turbine Services Companies:
The following key companies have been profiled for this study on the gas turbine services market.
- Ansaldo Energia
- Bharat Heavy Electricals Ltd.
- Destinus Energy
- Flowserve
- GE Vernova
- Hanwha Power
- Kawasaki Heavy Industries, Ltd.
- Mitsubishi Power, Ltd.
- Siemens Energy
- Solar Turbines Inc.
Recent Developments
- In December 2025, Flowserve Corporation acquired Greenray Turbine Solutions, expanding its aftermarket service capabilities in the industrial gas turbine segment. This strategic move aligns with the company’s objective to strengthen its service portfolio, enhance maintenance and repair offerings, and reinforce its position in the global market by delivering improved lifecycle support and operational efficiency solutions.
Gas Turbine Services Market Report Scope
Report Attribute
Details
Market Definition
The Gas Turbine Services market refers to the global revenue generated from maintenance, repair, overhaul, spare parts supply, and upgrade services provided for gas turbines.
Market size in 2025
USD 45.1 billion
Estimated market size in 2026
USD 46.2 billion
Projected market size by 2033
USD 92.5 billion
Growth rate
CAGR of 10.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Turbine type, turbine capacity, service type, service provider, end use, region
Regional scope
North America; Europe; Asia Pacific; The Commonwealth of Independent States (CIS); Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; India;Japan; Indonesia; Malaysia; Vietnam; Bangladesh; Pakistan; Singapore; Thailand; South Korea; Taiwan; Azerbaijan; Kazakhstan; Russia; Turkey; Turkmenistan; Ukraine; Uzbekistan; Brazil; Argentina; UAE; Oman; Iraq; Qatar; Lebanon; Algeria; Tunisia; Kuwait; Ghana; South Africa; Saudi Arabia; Egypt
Key companies profiled
Siemens Energy; Mitsubishi Power, Ltd.; Kawasaki Heavy Industries, Ltd.; Solar Turbines Inc.; Ansaldo Energia; Bharat Heavy Electricals Ltd.; Destinus Energy; Flowserve; GE Vernova; Hanwha Power
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Gas Turbine Services Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global gas turbine services market report based on the turbine type, turbine capacity, service type, service provider, end use, and region:
-
Turbine Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Heavy Duty
-
Industrial
-
Aeroderivatives
-
-
Capacity Outlook (Revenue, USD Billion, 2021 - 2033)
-
< 100 MW
-
100 to 200 MW
-
>200 MW
-
-
Service Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Maintenance & Repair
-
Overhaul
-
Spare parts supply
-
-
Service Provider Outlook (Revenue, USD Billion, 2021 - 2033)
-
OEM
-
Non-OEM
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Power Generation
-
Oil & Gas
-
Other Industrial
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Indonesia
-
Malaysia
-
Vietnam
-
Bangladesh
-
Pakistan
-
Singapore
-
Thailand
-
South Korea
-
Taiwan
-
-
Commonwealth of Independent States (CIS)
-
Azerbaijan
-
Kazakhstan
-
Russia
-
Turkey
-
Turkmenistan
-
Ukraine
-
Uzbekistan
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
UAE
-
Oman
-
Iraq
-
Qatar
-
Lebanon
-
Algeria
-
Tunisia
-
Kuwait
-
Ghana
-
South Africa
-
Saudi Arabia
-
Egypt
-
-
Frequently Asked Questions About This Report
The heavy-duty segment led with a 51.6% revenue share in 2025, and is the fastest-growing turbine type.
The 100 to 200 MW segment led with a 41.5% revenue share in 2025, while the >200 MW segment is the fastest-growing.
The spare parts supply segment led with a 64.5% revenue share in 2025, while the maintenance & repair segment is the fastest-growing.
OEMs segment held the largest share (over 61.0%) in 2025, while the OEMs segment is the fastest-growing.
The power generation segment led with a 68.2% revenue share in 2025, and is the fastest-growing End-Use.
The global gas turbine services market size was valued at USD 45.1 billion in 2025 and is estimated at USD 46.2 billion for 2026.
The global gas turbine services market is expected to grow at a CAGR of 10.4% from 2026 to 2033, reaching USD 92.5 billion by 2033.
Asia Pacific dominated with a 35.8% revenue share in 2025.
Key players include Siemens Energy; Mitsubishi Power, Ltd.; Kawasaki Heavy Industries, Ltd.; Solar Turbines Inc.; Ansaldo Energia; Bharat Heavy Electricals Ltd.; Destinus Energy; Flowserve; GE Vernova; Hanwha Power
The global gas turbine services market is primarily driven by an aging turbine infrastructure, utilities are increasingly upgrading or replacing outdated systems to improve reliability and operational performance. The need for higher efficiency and the growing demand for flexible, fast-ramping power solutions are rising to effectively balance the variability of renewable energy sources like solar and wind.
About the Author(s)
Conventional Energy Research Team
Energy & Power · Conventional EnergyThis report was authored by the conventional energy research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the conventional energy segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


