
- Home
- »
- Advanced Interior Materials
- »
-
Geopipes Market Size, Share And Trends Report, 2026-2033GVR Report cover

Geopipes Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (High Density Polyethylene (HDPE), Polyvinyl Chloride (PVC)), By Application (Drainage And Sewer, Irrigation And Agriculture), By Region (Asia Pacific, MEA), And Segment Forecasts
Market Size, 2025
$2.4BMarket Estimate, 2026
$2.6BMarket Forecast, 2033
$5.1BCAGR, 2026–2033
10.0%Geopipes Market Summary
The global geopipes market size was valued at USD 2.4 billion in 2025 and is projected to grow from USD 2.6 billion in 2026 to USD 5.1 billion by 2033, at a CAGR of 10.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 44.0% in 2025, driven by the growing demand for sustainable infrastructure solutions, particularly in the construction and civil engineering sectors. Geopipes, made from environmentally friendly and durable materials, offer a sustainable alternative to traditional piping systems.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: High-density polyethylene (HDPE) segment dominated the market, with a revenue share of 60.8% in 2025.
- By application: Drainage & sewer systems segment held the largest market share of 38.2% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (44.0% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.4 Billion
- Estimated market size in 2026: USD 2.6 Billion
- Projected market size by 2033: USD 5.1 Billion
- CAGR (2026-2033): 10.0%
Prism AI by Grand View Research Free to tryAsk a question about the geopipes marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
As governments and organizations around the world focus on reducing carbon emissions and promoting eco-friendly construction practices, the adoption of geopipes is gaining momentum. These pipes are not only more durable and resistant to corrosion but also provide long-term cost savings due to their low maintenance requirements. As a result, industries are increasingly turning to geopipes to meet both environmental and operational goals. The advancement of construction technologies and innovations in materials is also propelling the growth of the geopipes industry. Modern construction techniques, such as trenchless technology, have made it easier and more efficient to install geopipes without extensive digging, reducing labor costs and disruptions. This has made geopipes an increasingly attractive option for both new construction projects and the renovation of existing infrastructure. As these technologies continue to evolve, the versatility and cost-effectiveness of geopipes are expected to further enhance their adoption across various sectors, including municipal infrastructure, Irrigation & Agriculture facilities, and residential developments.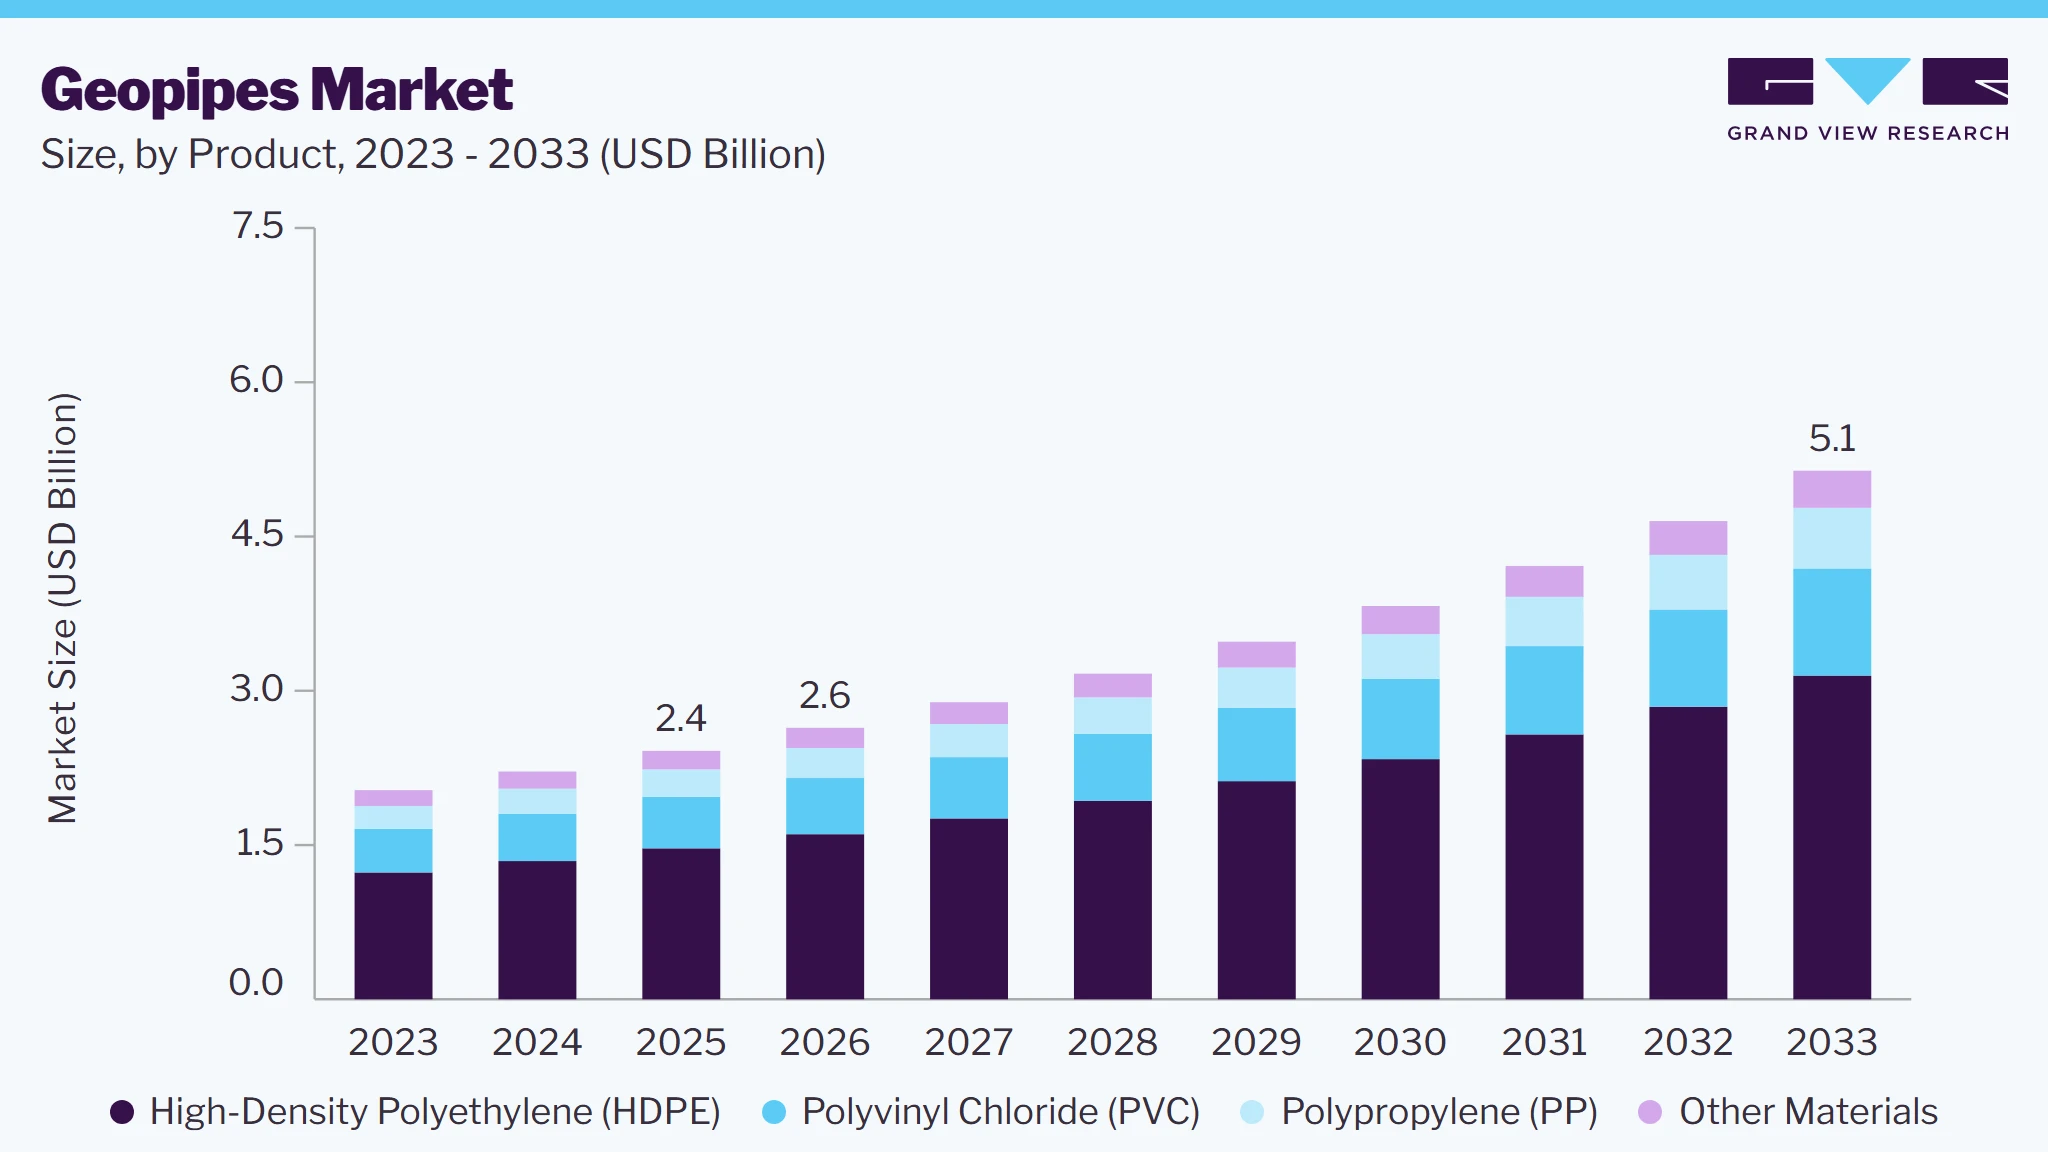 To learn more about this report, Download Free Sample Report
Rising regulations and standards for environmental protection and infrastructure durability are also playing a significant role in driving the geopipes industry. In many regions, stricter environmental regulations are being enforced, prompting industries to adopt sustainable alternatives to conventional piping systems. Geopipes, with their reduced carbon footprint and enhanced durability, meet these regulatory requirements, making them a preferred choice for governments and private sector companies alike. These regulations, coupled with growing environmental awareness, are expected to accelerate the transition towards geopipes in the coming years.
Market Dynamics
The geopipes market is witnessing steady growth driven by increasing investments in water supply, wastewater management, irrigation systems, mining operations, and transportation infrastructure. The growing need for durable, corrosion-resistant, and cost-effective piping solutions has accelerated the adoption of geopipes across municipal, industrial, and agricultural applications. Governments worldwide are investing in underground utility networks, stormwater management systems, and sustainable infrastructure projects, further supporting market expansion. In addition, advancements in polymer technologies, improved pipe manufacturing processes, and the increasing adoption of high-density polyethylene (HDPE) and polypropylene (PP) geopipes are creating new opportunities for the market.
Rapid urbanization, population growth, and aging water infrastructure are driving substantial investments in water supply, wastewater treatment, and stormwater management systems worldwide. Governments and municipal authorities are increasingly replacing deteriorating pipeline networks while expanding access to safe drinking water and sanitation services. Geopipes are gaining widespread adoption in these projects owing to their excellent corrosion resistance, chemical inertness, lightweight design, long service life, and lower maintenance requirements compared to conventional concrete and metal pipes. Their ease of transportation and installation also helps reduce project timelines and overall lifecycle costs.
In addition, increasing investments in smart cities, industrial water management, and climate-resilient infrastructure are further strengthening demand for geopipes. Rapid expansion of residential and commercial developments, coupled with stricter environmental regulations governing wastewater collection and water conservation, is encouraging the adoption of advanced piping systems. Continuous investments in underground utility networks, desalination plants, recycled water infrastructure, and flood management projects are expected to sustain the demand for geopipes across municipal, industrial, and infrastructure applications throughout the forecast period.
The geopipes market is influenced by fluctuations in the prices of polymer-based raw materials such as polyethylene (PE), polypropylene (PP), and polyvinyl chloride (PVC), which directly affect manufacturing costs and profit margins. In addition, large-scale pipeline projects often require substantial initial investments for excavation, installation, and specialized equipment. Regulatory compliance, project approval timelines, and budget constraints in public infrastructure projects can further delay deployments, limiting market growth in certain regions.
Growing investments in agricultural irrigation, mining operations, renewable energy projects, and climate-resilient infrastructure are creating significant growth opportunities for the geopipes market. Increasing adoption of efficient irrigation systems, underground cable protection, landfill drainage, and industrial fluid transportation is expanding the application scope of geopipes. Moreover, the development of recyclable polymer materials, advanced multilayer pipe technologies, and smart pipeline monitoring solutions is expected to enhance product performance, improve operational efficiency, and support long-term market growth.
Market Concentration & Characteristics
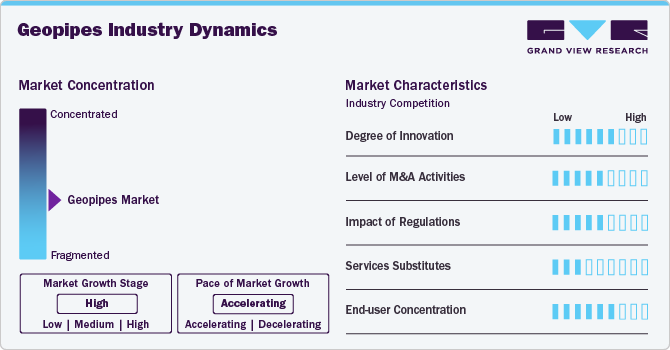
The global geopipes market exhibits a moderate to a high degree of innovation, driven by the increasing demand for sustainable and eco-friendly solutions in infrastructure projects. Geopipes, made from advanced composite materials, are being developed with improved durability, corrosion resistance, and ease of installation, making them a preferred choice for various applications in industries such as water management, gas Road & Highway Construction, and sewage systems. Companies in this market are constantly innovating to improve the performance of geopipes, introducing new materials and manufacturing techniques. These innovations are often aimed at reducing environmental impact, enhancing pipe lifespan, and improving the efficiency of fluid and gas Road & Highway Construction.
 To learn more about this report, Download Free Sample Report
Merger and acquisition activities in the geopipes industry are relatively limited, but there is a trend towards consolidation among major manufacturers to strengthen their product portfolios and expand their geographical presence. Regulatory frameworks, particularly environmental and safety standards, have a significant impact on the market by dictating the materials and processes used in the manufacturing of geopipes. Additionally, the availability of service substitutes, such as traditional metal or plastic pipes, remains a key factor affecting the market dynamics. The end-user concentration is moderately diversified, with industries such as construction, agriculture, and utilities playing prominent roles. However, demand for geopipes is particularly concentrated in regions experiencing rapid urbanization and infrastructure development, which further drives the adoption of these advanced piping solutions.
Analyst Perspective
The geopipes market is transitioning from a conventional piping solutions market to a performance-driven infrastructure segment, supported by increasing investments in water security, underground utility modernization, and climate-resilient infrastructure. Demand is increasingly shifting toward HDPE, PVC, and PP geopipes due to their superior corrosion resistance, longer service life, lower lifecycle costs, and ease of installation compared to conventional concrete and metal pipes. Market participants are focusing on developing high-strength, recyclable, and application-specific piping solutions while expanding manufacturing capacities to address growing demand from municipal water systems, irrigation networks, mining operations, and industrial infrastructure. In addition, stricter environmental regulations, rising investments in sustainable water management, and the replacement of aging pipeline networks are expected to accelerate product adoption and create long-term growth opportunities for manufacturers offering technologically advanced and durable geopipe solutions.
Product Insights
Based on product, the high-density polyethylene (HDPE) segment led the market with the largest revenue share of 60.8% in 2025 and is expected to grow at a CAGR of 10.1% over the forecast period, driven by its exceptional durability, resistance to corrosion, and cost-effectiveness in a wide range of applications. HDPE pipes are highly preferred in the construction, wastewater management, and agriculture sectors due to their strength, flexibility, and long lifespan, making them ideal for underground piping systems and infrastructure projects.
Polypropylene (PP) segment is expected to grow at the fastest CAGR of 10.2% over the forecast period, driven by the material’s superior mechanical and chemical properties, making it an ideal choice for various infrastructure and Irrigation & Agriculture applications. Polypropylene geopipes offer excellent resistance to corrosion, chemicals, and abrasion, ensuring durability in harsh environmental conditions. This has led to their widespread adoption in water distribution, wastewater management, and Irrigation & Agriculture drainage systems, where long-term performance and minimal maintenance are critical.
Application Insights
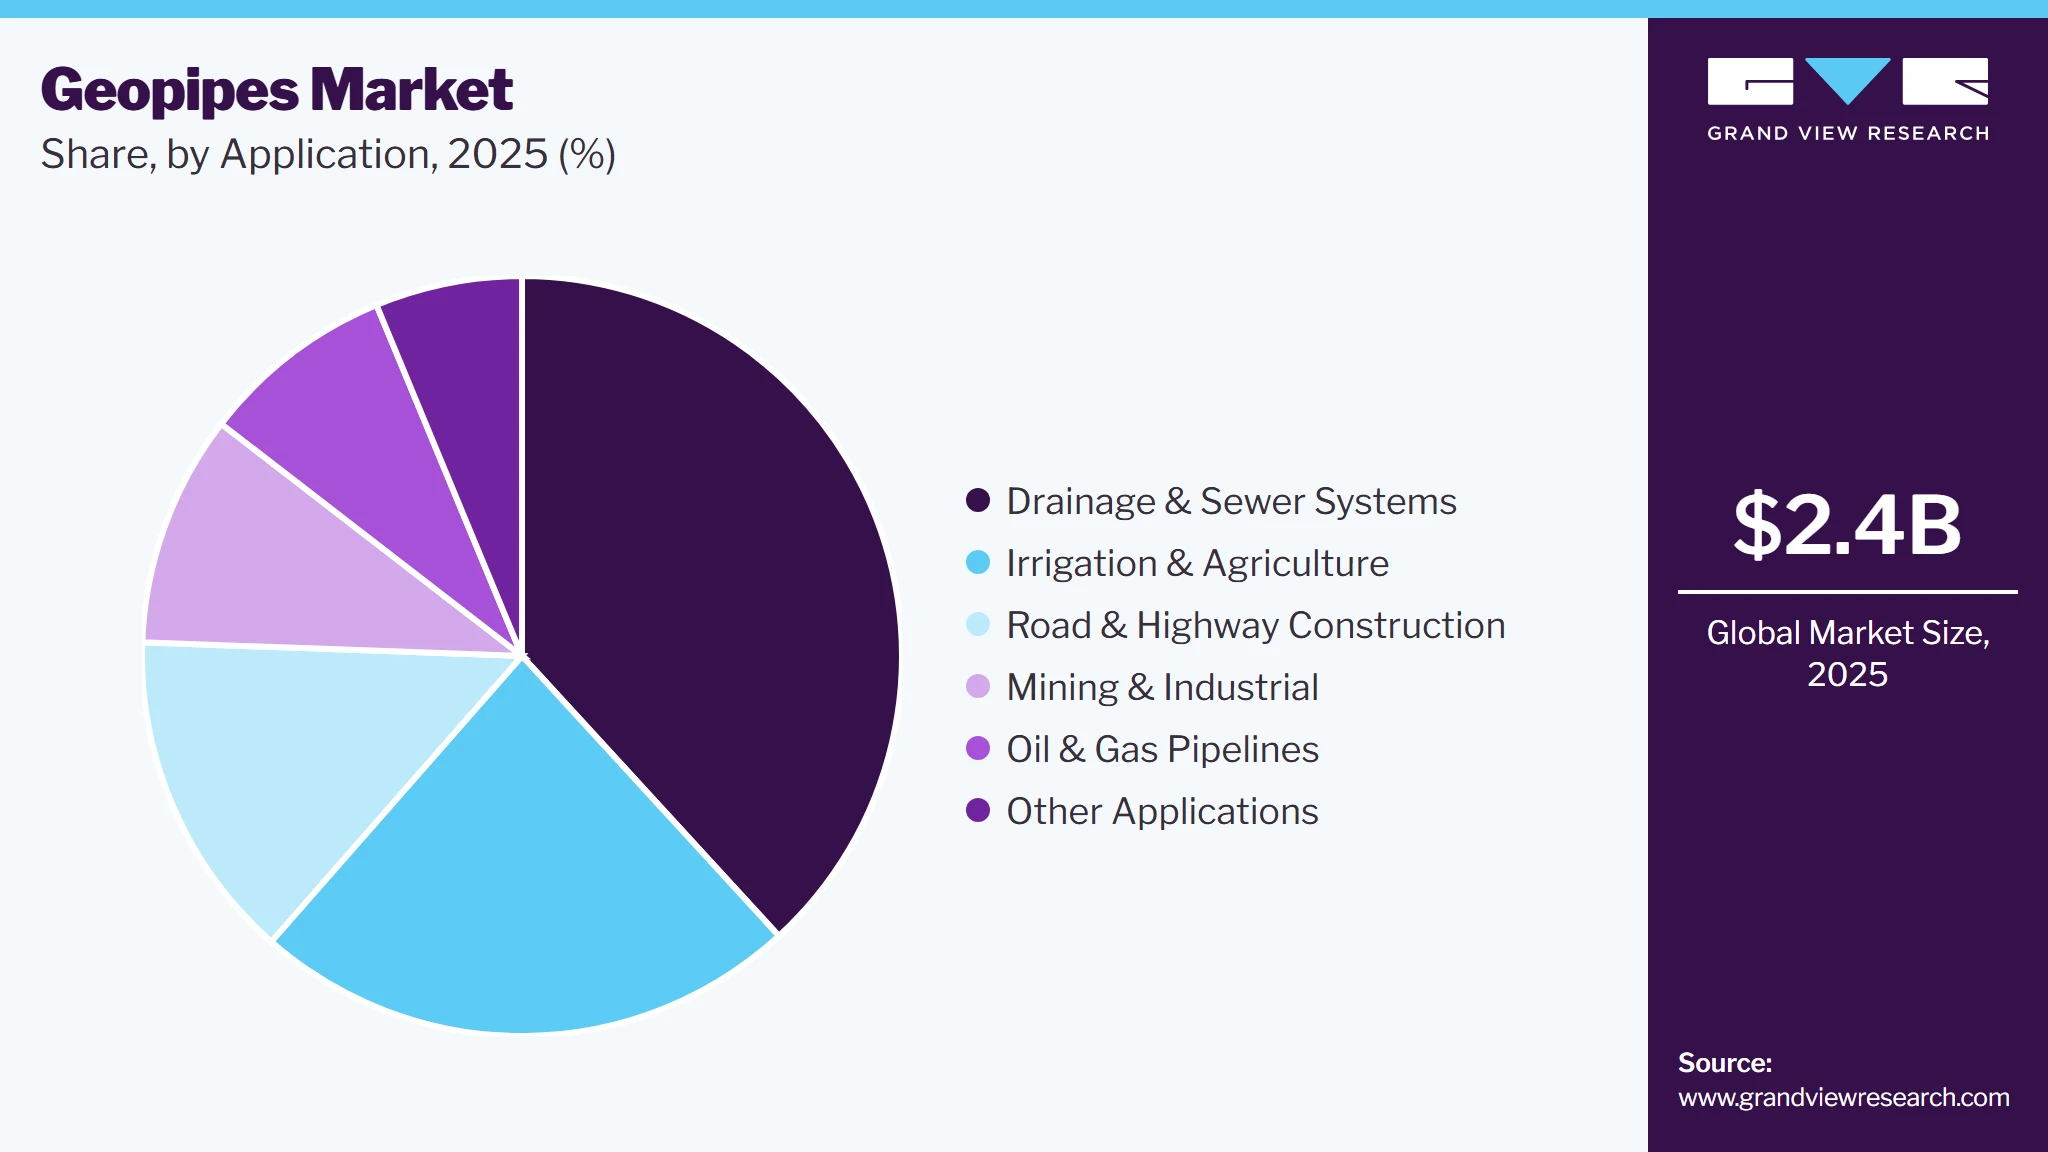
Based on end use, the drainage & sewer systems segment led the market with the largest revenue share of 38.2% in 2025 and is expected to grow at a CAGR of 10.2% over the forecast period, driven by increasing urbanization, infrastructure development, and the rising need for efficient wastewater management. As cities expand and populations grow, the demand for durable, corrosion-resistant, and cost-effective piping solutions for drainage and sewer systems has intensified. Geopipes, known for their lightweight nature, high chemical resistance, and long lifespan, are emerging as a preferred choice over traditional materials such as concrete and metal.
 To learn more about this report, Download Free Sample Report
Irrigation & agriculture segment is expected to grow at the fastest CAGR of 10.1% over the forecast period. The adoption of advanced agricultural techniques, such as precision irrigation and drip irrigation, is fueling the demand for geopipes. Farmers and agribusinesses are increasingly investing in infrastructure that enhances water efficiency, reduces wastage, and improves crop yields. Geopipes play a crucial role in these systems by enabling controlled water flow, maintaining consistent pressure, and reducing the need for frequent maintenance.
Regional Insights
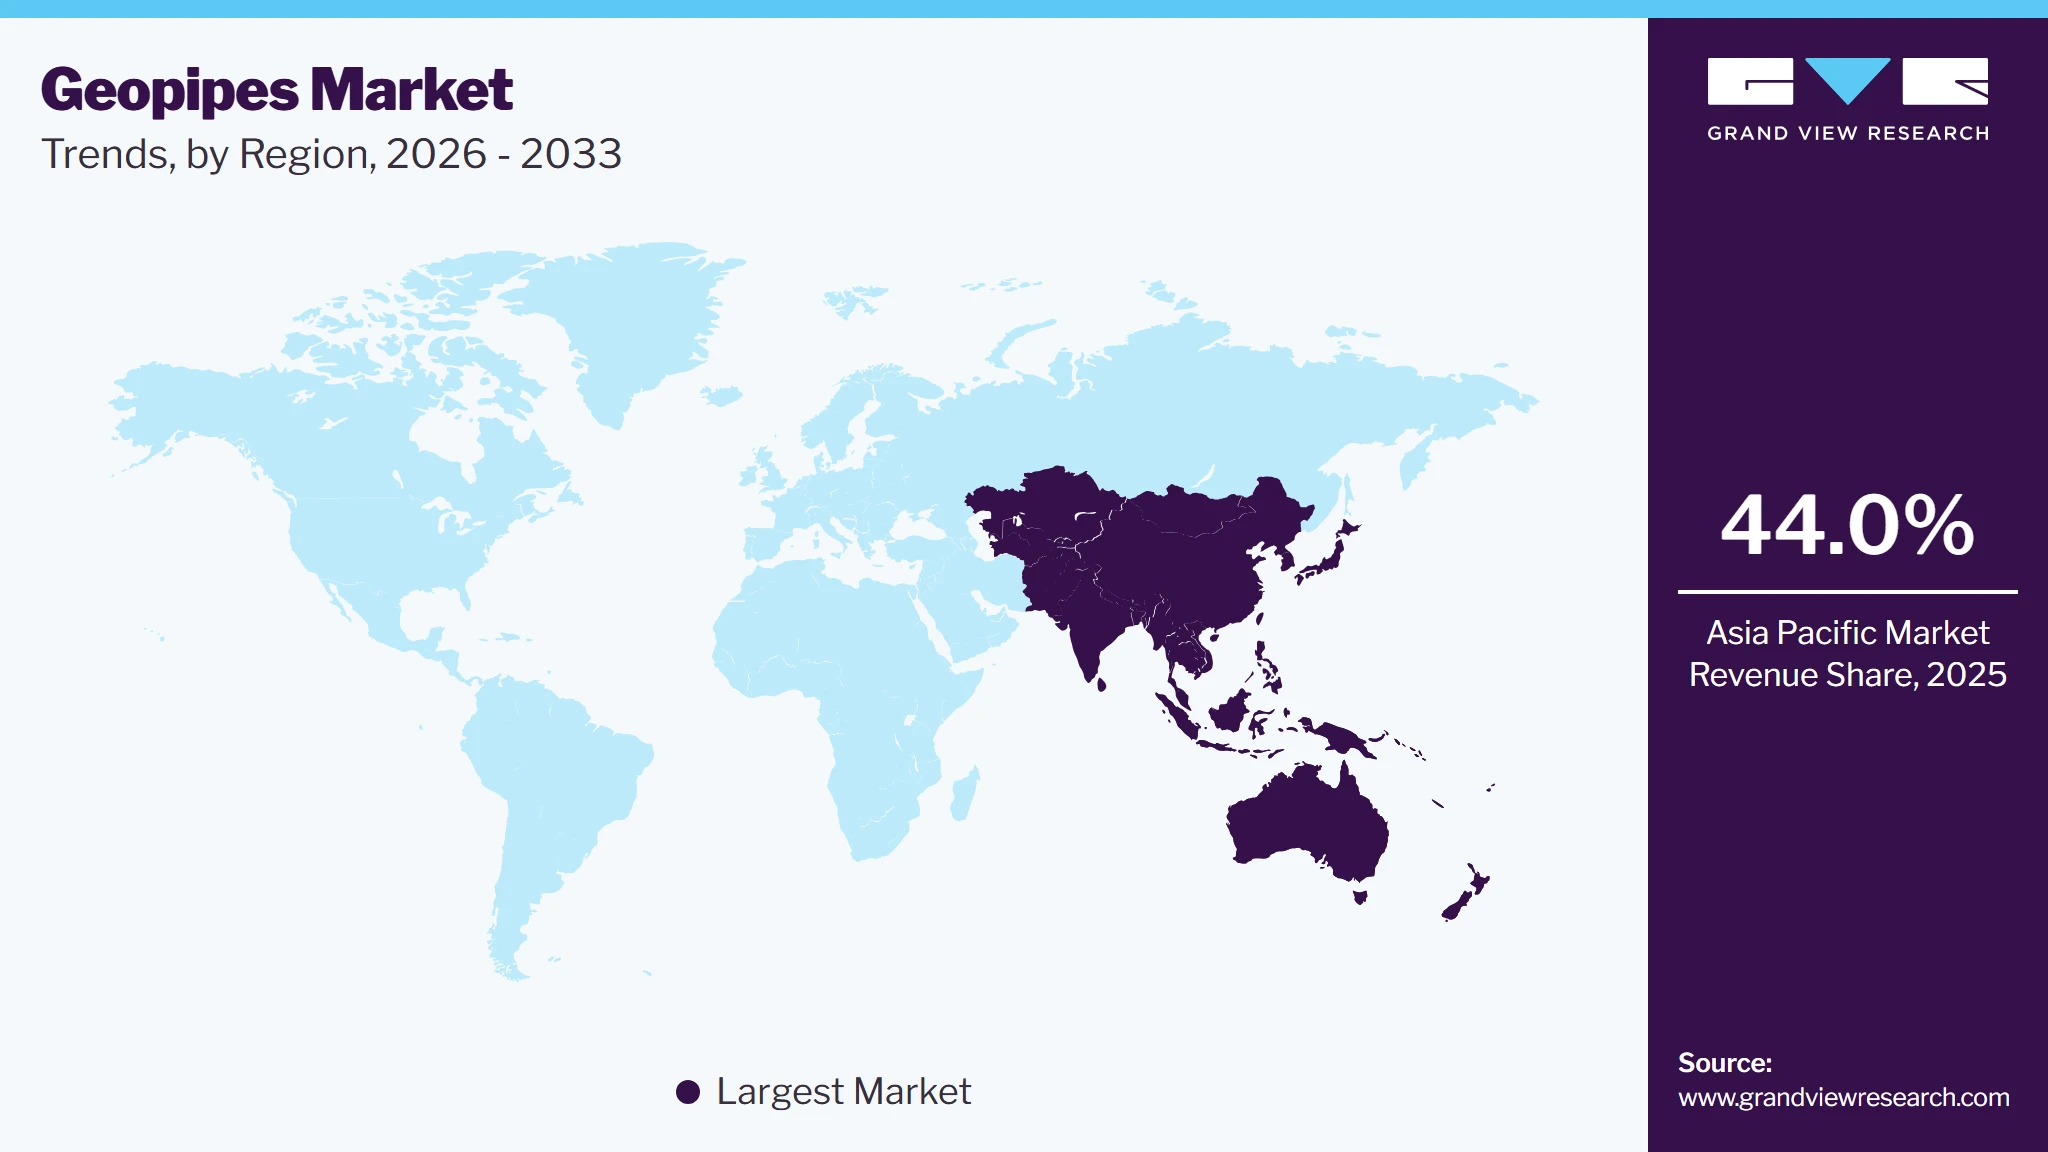
Asia Pacific dominated the geopipes market with the largest revenue share of 44.0% in 2025, driven by the rapid urbanization and infrastructure development taking place across the region. The geopipes market in China held the largest share in the Asia Pacific region in 2025. As countries like China, India, and other Southeast Asian nations experience significant growth in population and Irrigation & Agricultureization, there is an increasing demand for efficient and sustainable piping systems. Geopipes, known for their durability and environmental benefits, are gaining popularity as essential components in water management, sewage systems, and gas Road & Highway Construction networks. The need for reliable infrastructure to support urban growth and ensure environmental sustainability is boosting the demand for geopipes in these regions.
 To learn more about this report, Download Free Sample Report
The geopipes market in China is driven by the ongoing development of smart cities across the country that further supports the demand for advanced piping solutions. Geopipes are increasingly being integrated into smart city infrastructure due to their high performance and ability to support sophisticated monitoring and maintenance systems. As the country pushes forward with digitalizing urban infrastructure, the need for modern and reliable piping systems that can handle increasing urban demands is growing, further boosting the geopipes market.
Europe Geopipes Market Trends
The European Union geopipes market has implemented stringent regulations on wastewater treatment and management, creating a significant demand for durable, high-performance piping solutions. Geopipes, with their resistance to corrosion and chemical degradation, are ideal for use in sewage and wastewater systems. These regulations are encouraging municipalities and private entities to opt for geopipes to ensure compliance with standards while maintaining the efficiency of their infrastructure. Urbanization across Europe continues to drive the demand for improved infrastructure. As cities expand, the need for efficient piping systems for water, gas, and sewage increases. Geopipes, being lightweight and durable, provide a cost-effective and long-lasting solution for these growing cities. The shift towards modern infrastructure that can withstand environmental stresses has further bolstered the market for geopipes.
The geopipes market in Germany is gaining traction in renewable energy infrastructure projects in Germany, including biogas and geothermal energy systems. Their durability and ability to withstand extreme environmental conditions make them ideal for energy transmission and fluid handling applications, where efficiency and long-term sustainability are critical. The oil and gas industry in Germany is increasingly turning to advanced materials, such as geopipes, for pipeline infrastructure. Geopipes' superior performance in harsh conditions, such as extreme temperatures and corrosive environments, makes them suitable for the Road & Highway Construction of gases and liquids in this sector, where safety and efficiency are paramount.
North America Geopipes Market Trends
The increasing focus on infrastructure renewal and replacement in the North America geopipes market is driving the regional market. Many cities across the region are dealing with aging infrastructure, particularly in terms of water and wastewater pipelines. Geopipes provide an ideal solution for these replacement projects, as they offer better resistance to corrosion and longer service life compared to traditional materials like steel or PVC. With ongoing investment in upgrading and renewing infrastructure, the demand for high-performance materials like geopipes is expected to grow steadily in the coming years.
U.S. Geopipes Market Trends
The rise of the renewable energy sector in the geopipes market of the U.S. is another factor contributing to the demand for geopipes. Geopipes are ideal for applications in renewable energy infrastructure, such as geothermal energy systems, where corrosion resistance and longevity are essential. As the U.S. continues to expand its renewable energy initiatives, geopipes are being increasingly utilized in energy-efficient systems. Their application in geothermal heat exchange systems, wind energy projects, and solar panel installations enhances the overall sustainability of these energy solutions, contributing to the wider adoption of geopipes in the energy sector. The rise of smart cities is also fueling the demand for geopipes in the U.S. Smart city projects emphasize the integration of advanced technology into urban infrastructure to enhance efficiency and sustainability.
Latin America Geopipes Market Trends
The growing focus on reducing carbon emissions and minimizing environmental impacts is driving the demand for the Latin America geopipes market. Governments and organizations are actively working towards green building certifications and sustainable construction practices. The use of geopipes aligns with these goals as they contribute to energy-efficient and environmentally friendly infrastructure. In addition to their environmental benefits, geopipes' ability to reduce long-term maintenance costs due to their resistance to corrosion and wear makes them an attractive option for construction projects seeking to optimize lifecycle costs.
Middle East & Africa Geopipes Market Trends
The oil and gas sector in the geopipes market of the Middle East is a major driver for the geopipes market. With extensive pipelines required for transporting crude oil, natural gas, and other petrochemical products, geopipes offer a durable, non-corrosive, and cost-effective solution compared to traditional materials. As the region’s oil and gas industry continues to thrive, the demand for high-performance pipes that can withstand the harsh conditions of oil fields and pipeline networks grows.
Key Geopipes Company Insights
Some key players operating in the market include Geosynthetics Limited, and TenCate Geosynthetics
-
Geosynthetics Limited is a leading manufacturer and supplier of high-performance geosynthetic products, offering solutions for various civil engineering applications. The company provides a range of geopipes designed for the Road & Highway Construction of water, gas, and wastewater, with a focus on long-lasting performance and environmental sustainability. Their product offerings include composite geosynthetics for pipeline protection and drainage systems, suitable for both residential and Irrigation & Agriculture infrastructure.
-
TenCate Geosynthetics is a renowned manufacturer of geosynthetic materials, offering innovative solutions for the civil engineering, construction, and environmental sectors. Their geopipes are designed for applications in drainage, waste management, and stormwater systems, providing superior durability and environmental compatibility. The company also offers geotextile-lined geopipes that are ideal for areas requiring additional protection against corrosion and erosion.
SKAPS Industries, and HUESKER are some emerging market participants in the geopipes market.
-
SKAPS Industries is a major player in the manufacturing of geosynthetic materials, providing high-quality products for use in Road & Highway Construction, construction, and environmental sectors. Their geopipes offerings include a wide range of drainage and filtration pipes that are designed for both domestic and Irrigation & Agriculture applications.
-
HUESKER is an international manufacturer of geosynthetic materials, offering innovative solutions for infrastructure, environmental protection, and agricultural applications. Their geopipes are part of a broad range of products, including geotextiles and drainage systems designed for use in civil engineering projects.
Key Geopipes Companies:
The following key companies have been profiled for this study on the geopipes market.
-
Geosynthetics Limited
-
GSE Environmental
-
TenCate Geosynthetics
-
SKAPS Industries
-
HUESKER
-
Officine Maccaferri
-
ABG Ltd.
-
Terram
-
Thrace Group
-
Ocean Global
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (TenCate Geosynthetics, HUESKER, Officine Maccaferri, Thrace Group, GSE Environmental)
- Expand global manufacturing capacity and distribution networks.
- Invest in high-performance geosynthetic and geopipe solutions for infrastructure and environmental applications.
- Strengthen market presence through product innovation, strategic partnerships, and large infrastructure projects.
- Strong global presence with diversified geosynthetic product portfolios.
- Advanced technical expertise and established relationships with infrastructure developers.
- Extensive manufacturing capabilities and well-developed distribution networks.
- High dependence on infrastructure and public sector investments.
- Exposure to fluctuations in polymer raw material prices.
- Stringent environmental regulations and competitive pricing pressure.
Emerging Players (Geosynthetics Limited, SKAPS Industries, ABG Ltd., Terram, Ocean Global)
- Focus on expanding regional presence through customized geosynthetic solutions.
- Develop application-specific products for drainage, erosion control, and utility infrastructure.
- Strengthen customer relationships through technical support and project-specific offerings.
- Strong regional market expertise and flexible product offerings.
- Ability to provide customized solutions for niche infrastructure applications.
- Faster response to local customer requirements and project specifications.
- Limited global footprint compared to multinational competitors.
- Smaller production capacity and distribution network.
- Higher dependence on regional infrastructure spending and construction activity.
Geopipes Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.4 billion
Estimated market size in 2026
USD 2.6 billion
Projected market size by 2033
USD 5.1 billion
Growth rate
CAGR of 10.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Argentina
Key companies profiled
Geosynthetics Limited; GSE Environmental; TenCate Geosynthetics; SKAPS Industries; HUESKER; Officine Maccaferri; ABG Ltd.; Terram, Thrace Group; Ocean
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Geopipes Market Report Segmentation
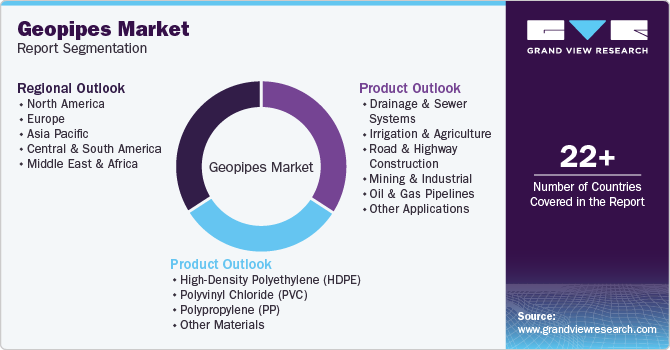
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global geopipes market report based on product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
High-Density Polyethylene (HDPE)
-
Polyvinyl Chloride (PVC)
-
Polypropylene (PP)
-
Other Materials
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Drainage & Sewer Systems
-
Irrigation & Agriculture
-
Road & Highway Construction
-
Mining & Industrial
-
Oil & Gas Pipelines
-
Other Applications
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Research Methodology
The geopipes market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each geopipes segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
High-Density Polyethylene (HDPE)
Revenue generated from the sale of high-density polyethylene (HDPE) geopipes used in water supply, wastewater, drainage, irrigation, mining, industrial fluid transport, and cable protection applications owing to their high strength, corrosion resistance, flexibility, and long service life.
Polyvinyl Chloride (PVC)
Revenue generated from the sale of polyvinyl chloride (PVC) geopipes utilized in potable water distribution, sewerage systems, irrigation networks, and industrial piping applications due to their chemical resistance, durability, smooth internal surface, and cost-effectiveness.
Polypropylene (PP)
Revenue generated from the sale of polypropylene (PP) geopipes employed in drainage, sewer systems, stormwater management, industrial applications, and underground utility infrastructure because of their high impact resistance, lightweight nature, thermal stability, and excellent chemical resistance.
Other Materials
Revenue generated from the sale of geopipes manufactured from other materials, including glass fiber-reinforced plastic (GRP), reinforced concrete, steel, and other specialty polymers, used in demanding infrastructure, industrial, oil & gas, and specialized fluid transportation applications requiring enhanced mechanical performance and durability.
Segment - Application
Revenue capture definition
Drainage & Sewer Systems
Revenue generated from the sale of geopipes used in municipal drainage networks, sanitary sewer systems, stormwater management, culverts, and wastewater collection infrastructure for efficient transportation and disposal of water and sewage.
Irrigation & Agriculture
Revenue generated from the sale of geopipes utilized in agricultural irrigation systems, water conveyance networks, drainage systems, and farm infrastructure to improve water distribution efficiency and support modern agricultural practices.
Road & Highway Construction
Revenue generated from the sale of geopipes used in road and highway infrastructure for stormwater drainage, culverts, sub-surface drainage, utility protection, and pavement drainage systems to improve roadway durability and water management.
Mining & Industrial
Revenue generated from the sale of geopipes employed in mining and industrial operations for slurry transport, process water conveyance, tailings management, chemical transportation, and industrial drainage applications requiring high abrasion and corrosion resistance.
Oil & Gas Pipelines
Revenue generated from the sale of geopipes used in oil & gas production, gathering, water injection, produced water handling, and pipeline infrastructure owing to their corrosion resistance, pressure-bearing capability, and suitability for harsh operating environments.
Other Applications
Revenue generated from the sale of geopipes used in applications such as landfill drainage, marine infrastructure, renewable energy projects, utility protection, telecommunications, and other specialized civil and industrial infrastructure projects.
Estimation Model
Layer Name
Key Question
Description
Infrastructure & End-Use Industry Assessment
Which end-use industries and infrastructure investments are driving demand for geopipes?
Evaluates demand across water supply & wastewater management, irrigation & agriculture, road & highway construction, mining, oil & gas, and industrial infrastructure by analyzing construction activity, infrastructure investments, urbanization, government water management initiatives, and regional economic development.
Material Type & Application Penetration Analysis
Which geopipe materials and applications contribute the most to market revenue?
Assesses the adoption of HDPE, PVC, PP, and other geopipe materials based on production volumes, material properties, durability, pressure requirements, corrosion resistance, installation costs, and application suitability across municipal, industrial, agricultural, and energy sectors.
Manufacturer Revenue & Supply Chain Validation
How much revenue is generated by geopipe manufacturers and suppliers?
Estimates market size through company revenues, production capacities, capacity utilization, pricing trends, raw material availability, manufacturing technologies, distribution networks, import-export analysis, and value chain assessment, validated through primary interviews and secondary industry sources.
Regional Demand & Forecast Validation
How will regional demand and market opportunities evolve over the forecast period?
Validates market estimates by evaluating regional infrastructure spending, water and wastewater projects, irrigation expansion, mining activities, oil & gas investments, regulatory standards, sustainability initiatives, pipeline replacement programs, and future construction and industrial development across major geographic markets.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Market Analysis
Comprehensive regional assessment covering market size, growth trends, infrastructure investments, application-wise demand, regulatory framework, import-export scenario, manufacturing hubs, and country-level opportunities across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
Enables businesses to identify high-growth regional markets, optimize expansion strategies, evaluate country-specific risks and opportunities, and allocate investments based on regional demand and infrastructure development.
Technology & Sustainability Assessment
In-depth assessment of advancements in geopipe materials, manufacturing technologies, product innovations, recyclable polymer solutions, smart pipeline technologies, and sustainability initiatives aimed at improving durability, operational efficiency, and environmental performance.
Helps stakeholders understand emerging technology trends, evaluate sustainable product innovations, identify opportunities for product differentiation, and align business strategies with evolving regulatory and environmental requirements.
Supply Chain & Value Chain Analysis
Detailed evaluation of the complete value chain, including raw material sourcing, geopipe manufacturing, distribution channels, contractor ecosystem, pricing trends, import-export dynamics, and regulatory compliance across major markets.
Provides actionable insights to optimize procurement strategies, improve supply chain resilience, strengthen distribution networks, reduce operational risks, and enhance long-term business competitiveness.
Frequently Asked Questions About This Report
Asia Pacific region led the market and accounted for the largest revenue share of 44.0% in 2025.
Drainage & sewer systems segment held the largest market share of 38.2% in 2025 while irrigation & agriculture segment is expected to be the fastest-growing market.
The global geopipes market size was valued at USD 2.4 billion in 2025 and is estimated at USD 2.6 billion for 2026.
The global geopipes market is expected to grow at a CAGR of 10.0% from 2026 to 2033, reaching USD 5.1 billion by 2033.
Some of the key players operating in the geopipes market include Geosynthetics Limited, GSE Environmental, TenCate Geosynthetics, SKAPS Industries, HUESKER, Officine Maccaferri, ABG Ltd., Terram, Thrace Group, Ocean Global.
The high-density polyethylene (HDPE) segment led the market and accounted for the largest revenue share of 60.8% in 2025, driven by its exceptional durability, resistance to corrosion, and cost-effectiveness in a wide range of applications.
The key factors that are driving the geopipes market include increasing demand for efficient water management solutions, rapid infrastructure development, rising adoption of sustainable irrigation systems, advancements in geosynthetic materials, and government initiatives supporting modern agricultural practices.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


