
- Home
- »
- Performance Chemicals
- »
-
Glycols Market Size, Share & Trends Report, 2026-2033GVR Report cover

Glycols Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Ethylene Glycol, Propylene Glycol), By Grade (Industrial Grade, Food Grade), By Application, By End Use (Automotive, Textiles), By Region, And Segment Forecasts
Market Size, 2025
$31.6BMarket Estimate, 2026
$33.3BMarket Forecast, 2033
$49.5BCAGR, 2026–2033
5.8%Glycols Market Summary
The global glycols market size was valued at USD 31.6 billion in 2025 and is projected to grow from USD 33.3 billion in 2026 to USD 49.5 billion by 2033, at a CAGR of 5.8% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 41.3% in 2025. The global market expansion is supported by increasing demand across polyester and PET manufacturing, automotive fluids, construction, coatings, pharmaceuticals, and other industrial applications.
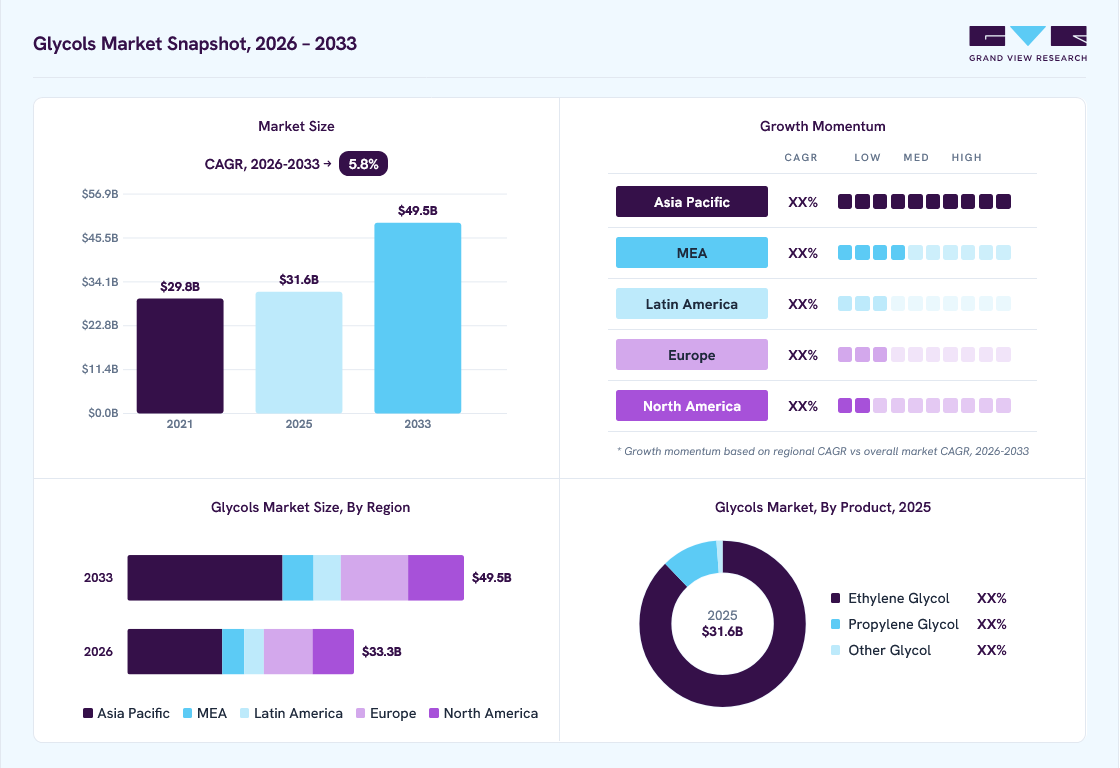 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Ethylene glycol segment held the largest revenue share of 87.7% in 2025.
- By grade: The industrial grade segment dominated with a share of 73.9% in 2025.
- By application: Polyester & pet production segment led the market with a share of 37.6% 2025.
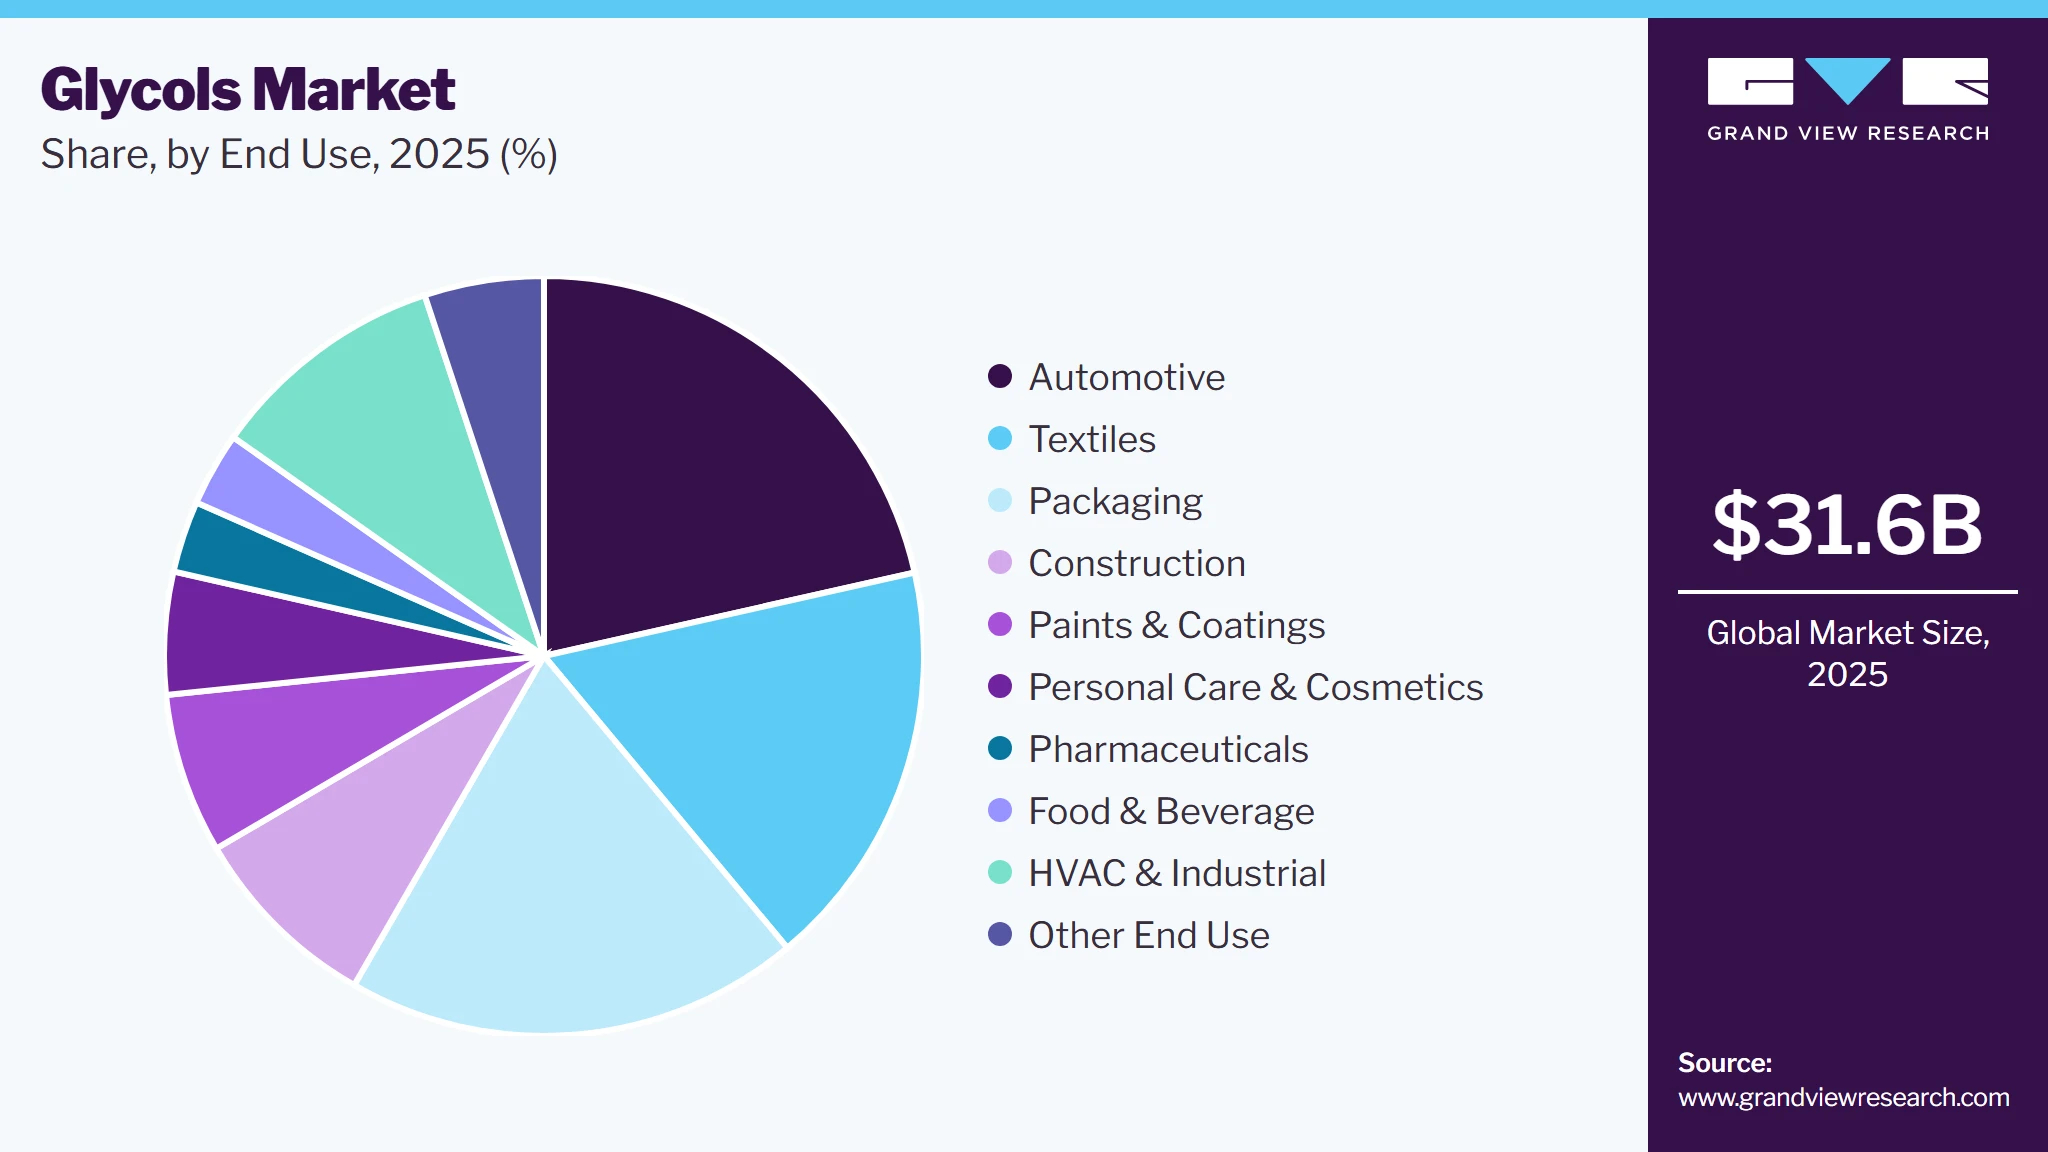
- By end use: The automotive segment held the highest revenue share of 21.5% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (41.3% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 31.6 Billion
- Estimated market size in 2026: USD 33.3 Billion
- Projected market size by 2033: USD 49.5 Billion
- CAGR (2026-2033): 5.8%
GVR research-powered AIAsk Prism AI about the glycols marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
The industry growth is supported by widespread consumption across polyester manufacturing, antifreeze and coolants, paints and coatings, plastics, personal care, pharmaceuticals, and industrial formulations. EG remains closely associated with polyester fiber and PET production, while PG benefits from its use as a solvent, humectant, heat-transfer fluid, and formulation ingredient. Rising automotive output, construction activity, packaging demand, and consumer-product manufacturing are sustaining consumption across key end-use sectors. Producers are focusing on higher-purity grades, application-specific solutions, and process efficiencies to address changing customer requirements.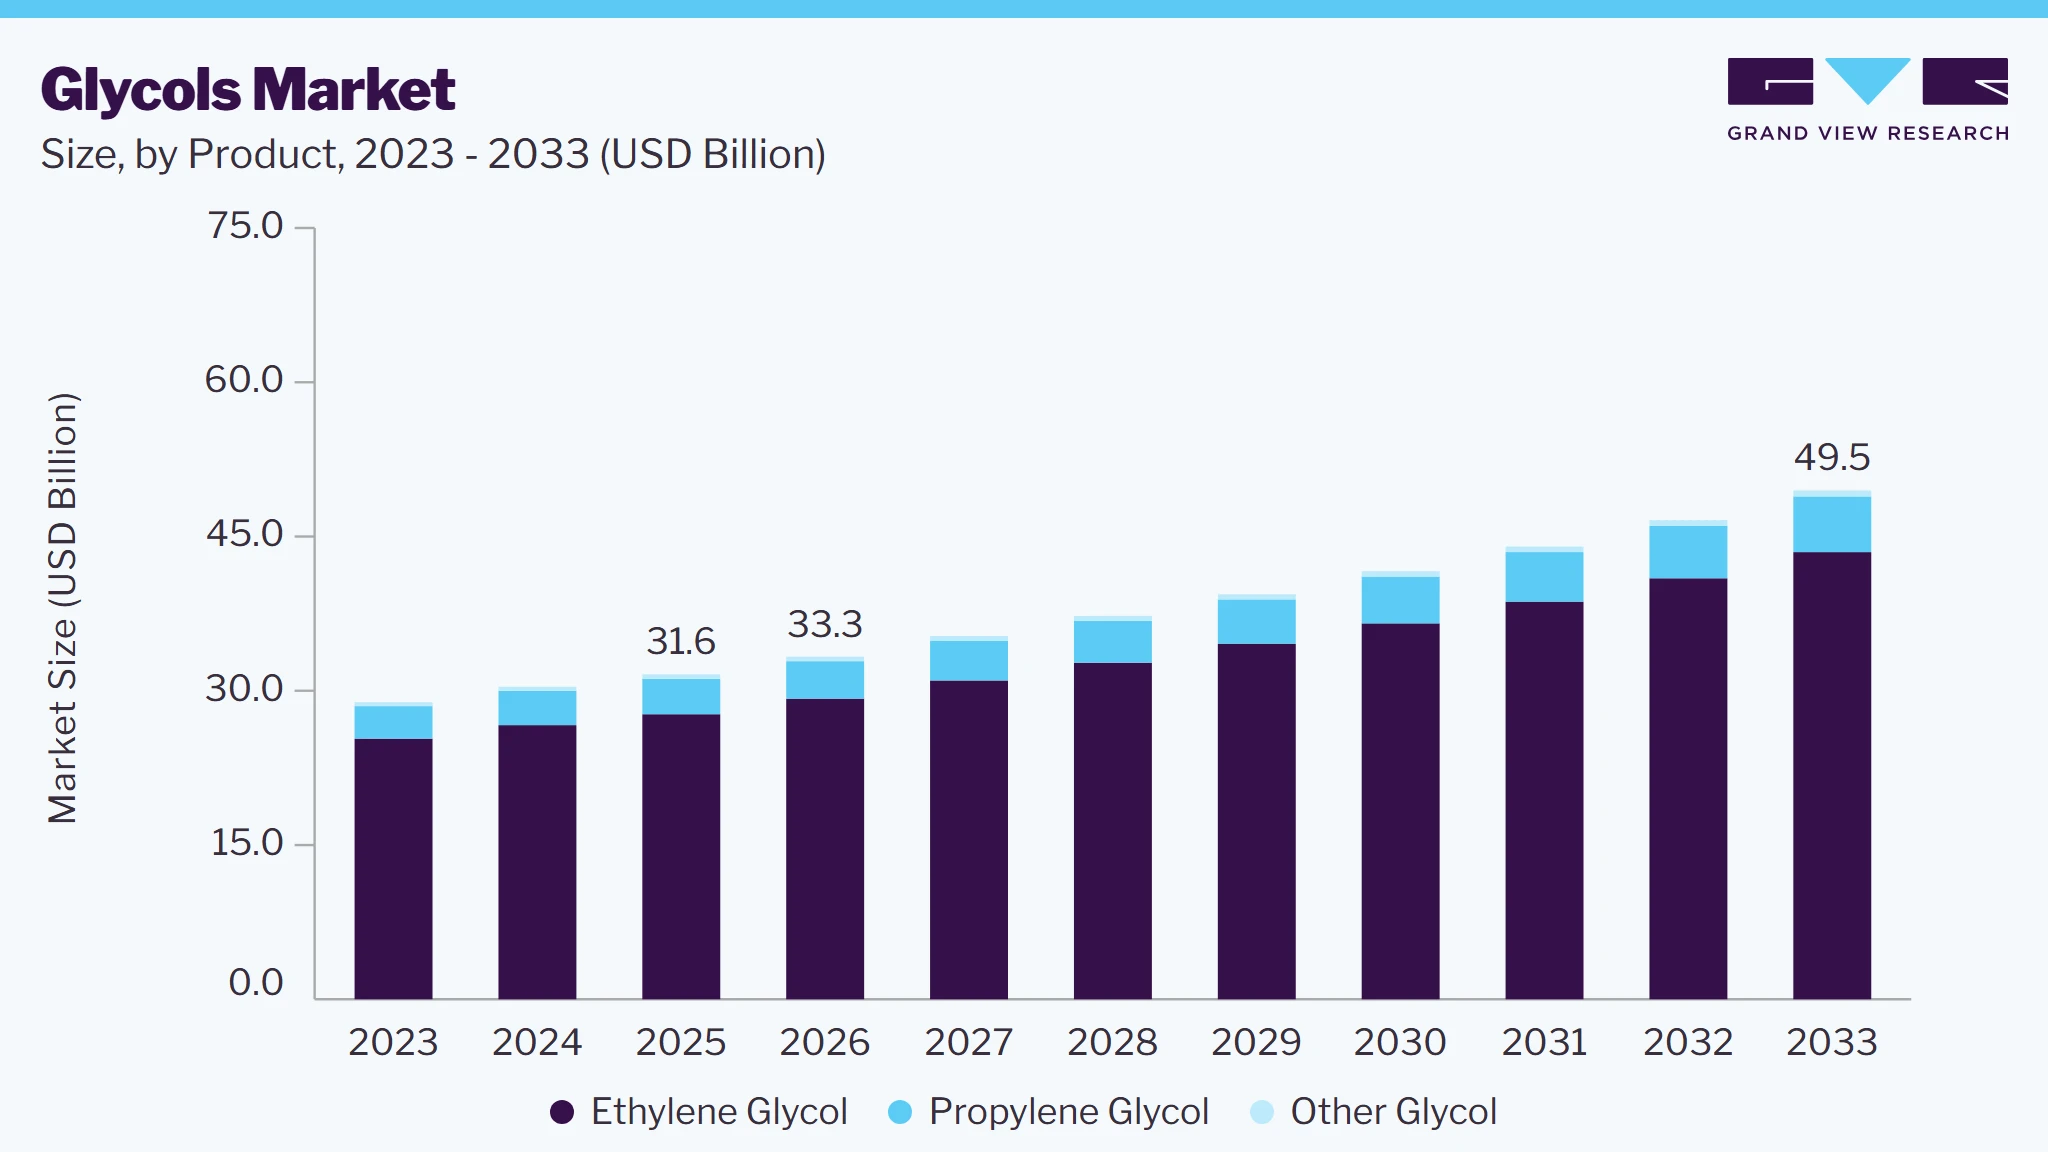 To learn more about this report, Download Free Sample Report
Bio-based and recycled-content alternatives can support downstream manufacturers seeking to reduce the environmental footprint of polyester, packaging, personal-care, and industrial products. Capacity expansion across Asia Pacific, particularly within integrated petrochemical complexes, is also creating scope for greater regional supply and downstream diversification. In addition, increasing requirements for high-purity grades used in pharmaceutical, electronics, food, and personal-care applications could enable producers to expand into higher-value segments and strengthen product differentiation.
Market Dynamics
Demand is being supported by the extensive use of EG, PG, and related derivatives across polyester, PET, automotive coolants, paints and coatings, plastics, pharmaceuticals, personal care, and industrial formulations. Expanding packaging and textile production, alongside rising vehicle ownership and construction activity, is creating sustained consumption across major application areas. Manufacturers are also pursuing capacity expansions and process optimization to strengthen supply reliability and respond to regional demand growth. At the same time, volatility in crude oil, natural gas, and petrochemical feedstock prices remains a key factor influencing production economics and selling prices. Environmental considerations are encouraging producers to explore bio-based feedstocks, recycled inputs, and lower-emission manufacturing routes, creating opportunities for differentiated offerings. Increasing requirements for high-purity grades in pharmaceutical, food, electronics, and specialty applications are further supporting value-added product development.
A major growth catalyst is the increasing consumption of EG in polyester fibers, polyethylene terephthalate (PET) resin, and packaging applications. Rising demand for lightweight packaging, beverage containers, films, and synthetic textiles is supporting downstream production volumes, particularly across Asia Pacific. Urbanization, changing consumption patterns, and the expansion of organized retail are encouraging greater use of packaged beverages and consumer goods, which in turn are driving PET resin demand. At the same time, textile manufacturers continue to use polyester for its durability, cost-effectiveness, and versatility across apparel, home furnishings, and industrial fabrics. Expansion of polyester and PET capacity, particularly in countries with established petrochemical and manufacturing ecosystems, is therefore generating additional requirements -based feedstocks and strengthening long-term procurement opportunities for producers.
Further momentum is being generated by investments in integrated petrochemical facilities that link feedstock processing to downstream polyester and PET production. Such integration can improve raw-material availability, reduce logistical dependence, and provide manufacturers with greater control over production economics. Producers are also expanding regional capabilities to serve rapidly developing packaging and textile industries closer to consumption centers. These developments support more consistent offtake by downstream converters while enabling suppliers to optimize production scale and supply chain efficiency.
Variations in the prices of crude oil, natural gas, ethylene, propylene, and other key inputs can exert considerable pressure on producers' cost structures. Conventional manufacturing remains closely tied to petrochemical feedstocks, making operating expenses sensitive to energy-market movements, refinery utilization, geopolitical disruptions, and regional supply conditions. When input costs rise rapidly, manufacturers may struggle to pass the full increase through to customers, particularly in commodity-grade applications where pricing competition is intense. This can narrow profit margins and affect the commercial viability of certain production runs. Cost instability also complicates procurement, inventory management, and capacity planning. Producers with vertically integrated operations can benefit from greater control over feedstock availability, while independent manufacturers may remain more exposed to external purchasing conditions.
The transition toward more sustainable chemical inputs presents a significant opportunity for manufacturers to develop bio-based, renewable, and lower-carbon alternatives. Increasing environmental commitments among brand owners and downstream processors are encouraging the adoption of materials with reduced dependence on fossil-based feedstocks. Bio-based mono-ethylene can serve as a renewable component in polyester and PET production, enabling manufacturers to meet sustainability objectives without fundamentally altering established downstream applications. Companies capable of demonstrating reliable feedstock sourcing, consistent product quality, traceability, and credible emissions reductions can potentially differentiate their offerings from conventional grades.
This shift also creates scope for technological innovation and portfolio diversification. Producers can invest in renewable raw materials, circular feedstocks, improved process efficiency, and certification systems to develop differentiated grades for customers seeking lower-impact inputs. Demand from sustainable packaging, textiles, personal care, and industrial formulations can provide additional avenues for commercialization.
Market Concentration & Characteristics
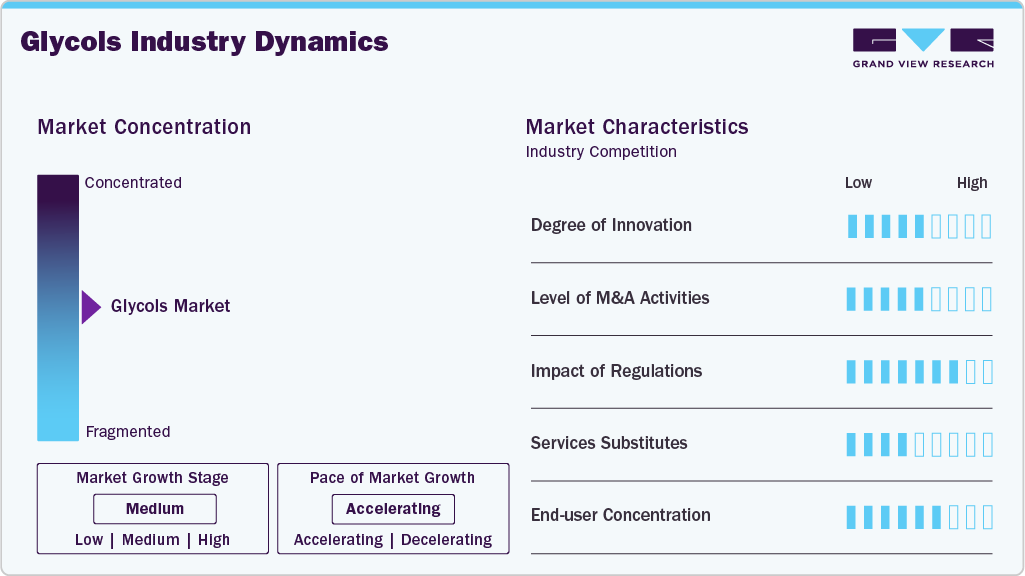
Competition is characterized by the presence of large integrated petrochemical groups alongside specialized chemical producers serving commodity and value-added applications. Major participants such as Dow, BASF, Shell, INEOS, SABIC, LyondellBasell, and PETRONAS Chemicals benefit from extensive manufacturing networks, captive feedstocks, technological capabilities, and established relationships with downstream polyester, packaging, automotive, coatings, pharmaceutical, and personal-care customers. Their scale enables efficient production of high-volume grades while supporting geographic diversification and supply reliability.
 To learn more about this report, Download Free Sample Report
Regional manufacturers, including India Glycols, Reliance Industries, LOTTE Chemical, and Oriental Union Chemical, contribute to a more diversified competitive environment, particularly across Asia Pacific. Differentiation increasingly extends beyond production volume, with manufacturers focusing on product purity, customized grades, renewable feedstocks, circular inputs, technical support, and application-specific solutions. Strategic investments in low-carbon manufacturing and bio-based alternatives are creating additional avenues for portfolio development. Meanwhile, fluctuations in feedstock costs and periodic capacity additions can intensify price competition in standard grades, encouraging producers to improve operating efficiency and target specialized applications.
Analyst Perspective
The industry is moving beyond volume-driven growth, with producers increasingly focusing on efficiency, product differentiation, and supply security. Strong demand from polyester, PET, automotive fluids, and specialty formulations continues to provide a stable consumption base. Asia Pacific remains central to capacity expansion, supported by its large manufacturing ecosystem and expanding downstream industries. Sustainability is becoming a meaningful differentiator, particularly through bio-based feedstocks, circular inputs, and lower-emission production routes. At the same time, feedstock price volatility and periodic oversupply can place pressure on margins and intensify competition.
Product Insights
The ethylene glycol segment dominated the market with a revenue share of 87.7% in 2025, reflecting its widespread use in high-volume industrial operations. Its primary outlet is polyester and PET manufacturing, where it serves as a key feedstock for polyester fibers, films, and PET resins used in packaging. Considerable quantities are also utilized in automotive antifreeze and coolant formulations, heat-transfer fluids, and various industrial processes. Well-established manufacturing infrastructure, broad downstream applicability, and integration with petrochemical value chains continue to underpin its substantial contribution to overall revenue.
Propylene glycol is projected to be the fastest-growing product segment, with a CAGR of 5.8% during the forecast period, supported by expanding utilization in food and beverage, pharmaceutical, personal-care, cosmetic, and industrial formulations. Its low toxicity, favorable solvency, and moisture-retention properties make it suitable for products requiring controlled formulation performance. Greater use of pharmaceutical preparations, processed foods, cosmetics, and specialty fluids is creating additional requirements for high-purity and application-specific grades. Meanwhile, growing interest in bio-based is encouraging portfolio diversification and enabling producers to address sustainability-oriented procurement needs.
Grade Insights
The industrial grade segment accounted for 73.9% of revenue share in 2025, primarily owing to the substantial volumes consumed in manufacturing and process-oriented activities. EG is extensively utilized in antifreeze, coolants, heat-transfer fluids, polyester manufacturing, and polyurethane production, while industrial-grade propylene glycol finds use in coatings, lubricants, resins, and chemical processing. Cost efficiency, consistent specifications, commercial-scale availability, and compatibility with established production systems remain key purchasing considerations. Its position is further reinforced by the extensive manufacturing infrastructure maintained by integrated petrochemical producers.
The food grade segment is expected to be the fastest-growing segment at a CAGR of 7.6% during the forecast period, driven by greater use of propylene glycol as a humectant, carrier, solvent, and formulation aid in food and beverage processing. Rising consumption of processed foods, convenience products, flavors, colors, and other formulated goods is generating additional needs for materials that satisfy stringent food-safety specifications. Producers are also placing greater emphasis on traceability, purity, and adherence to applicable regulatory standards. These factors are prompting suppliers to strengthen quality-control systems and formulate grades tailored to food-processing requirements.
Application Insights
The polyester & PET production represented the leading application segment in 2025, with a 37.6% revenue share. EG is a fundamental feedstock for producing polyester fibers, PET bottles, films, sheets, and other polymer products. Expanding beverage packaging, greater preference for lightweight containers, and continued polyester use in apparel and home textiles are supporting substantial requirements. In parallel, rising PET recycling and the development of recycled-content packaging are influencing procurement patterns, encouraging producers to explore manufacturing routes based on recycled and renewable feedstocks.
The personal care & cosmetics segment is projected to be the fastest-growing application, registering a CAGR of 7.8% from 2026 to 2033, largely driven by increased use of propylene and polyethylene derivatives. These materials serve as solvents, humectants, carriers, viscosity modifiers, and formulation aids in skincare, haircare, fragrances, oral-care products, and cosmetics. Expansion of premium beauty offerings, multifunctional formulations, and specialized personal-care preparations is increasing the need for consistent, high-purity ingredients. The transition toward safer, more sustainable, and multifunctional formulation systems is also encouraging suppliers to develop grades that align with evolving cosmetic requirements.
End Use Insights
The automotive segment held the largest market share of 21.5% in 2025, reflecting substantial utilization in engine coolants, antifreeze formulations, thermal-management systems, and selected polymer applications. It remains widely adopted because it provides freeze protection and efficient thermal transfer across varied vehicle operating conditions. Rising global vehicle production and the expanding installed vehicle base continue to support both replacement and factory-fill requirements. At the same time, evolving thermal management needs associated with hybrid and electric vehicles are creating additional opportunities for formulations.
 To learn more about this report, Download Free Sample Report
Food & beverage is anticipated to be the fastest-growing end use segment, with a CAGR of 8.0% from 2026 to 2033, supported by rising consumption of processed, packaged, and convenience-oriented products. Propylene glycol is utilized in selected applications as a humectant, solvent, carrier, and processing ingredient, facilitating the formulation and delivery of flavors, colors, and other components. Greater preference for shelf-stable products and sophisticated ingredient systems is contributing to higher usage. Meanwhile, stricter food-quality standards are encouraging manufacturers to procure high-purity materials with consistent specifications and dependable regulatory documentation.
Regional Insights
Asia Pacific Glycols Market Trends
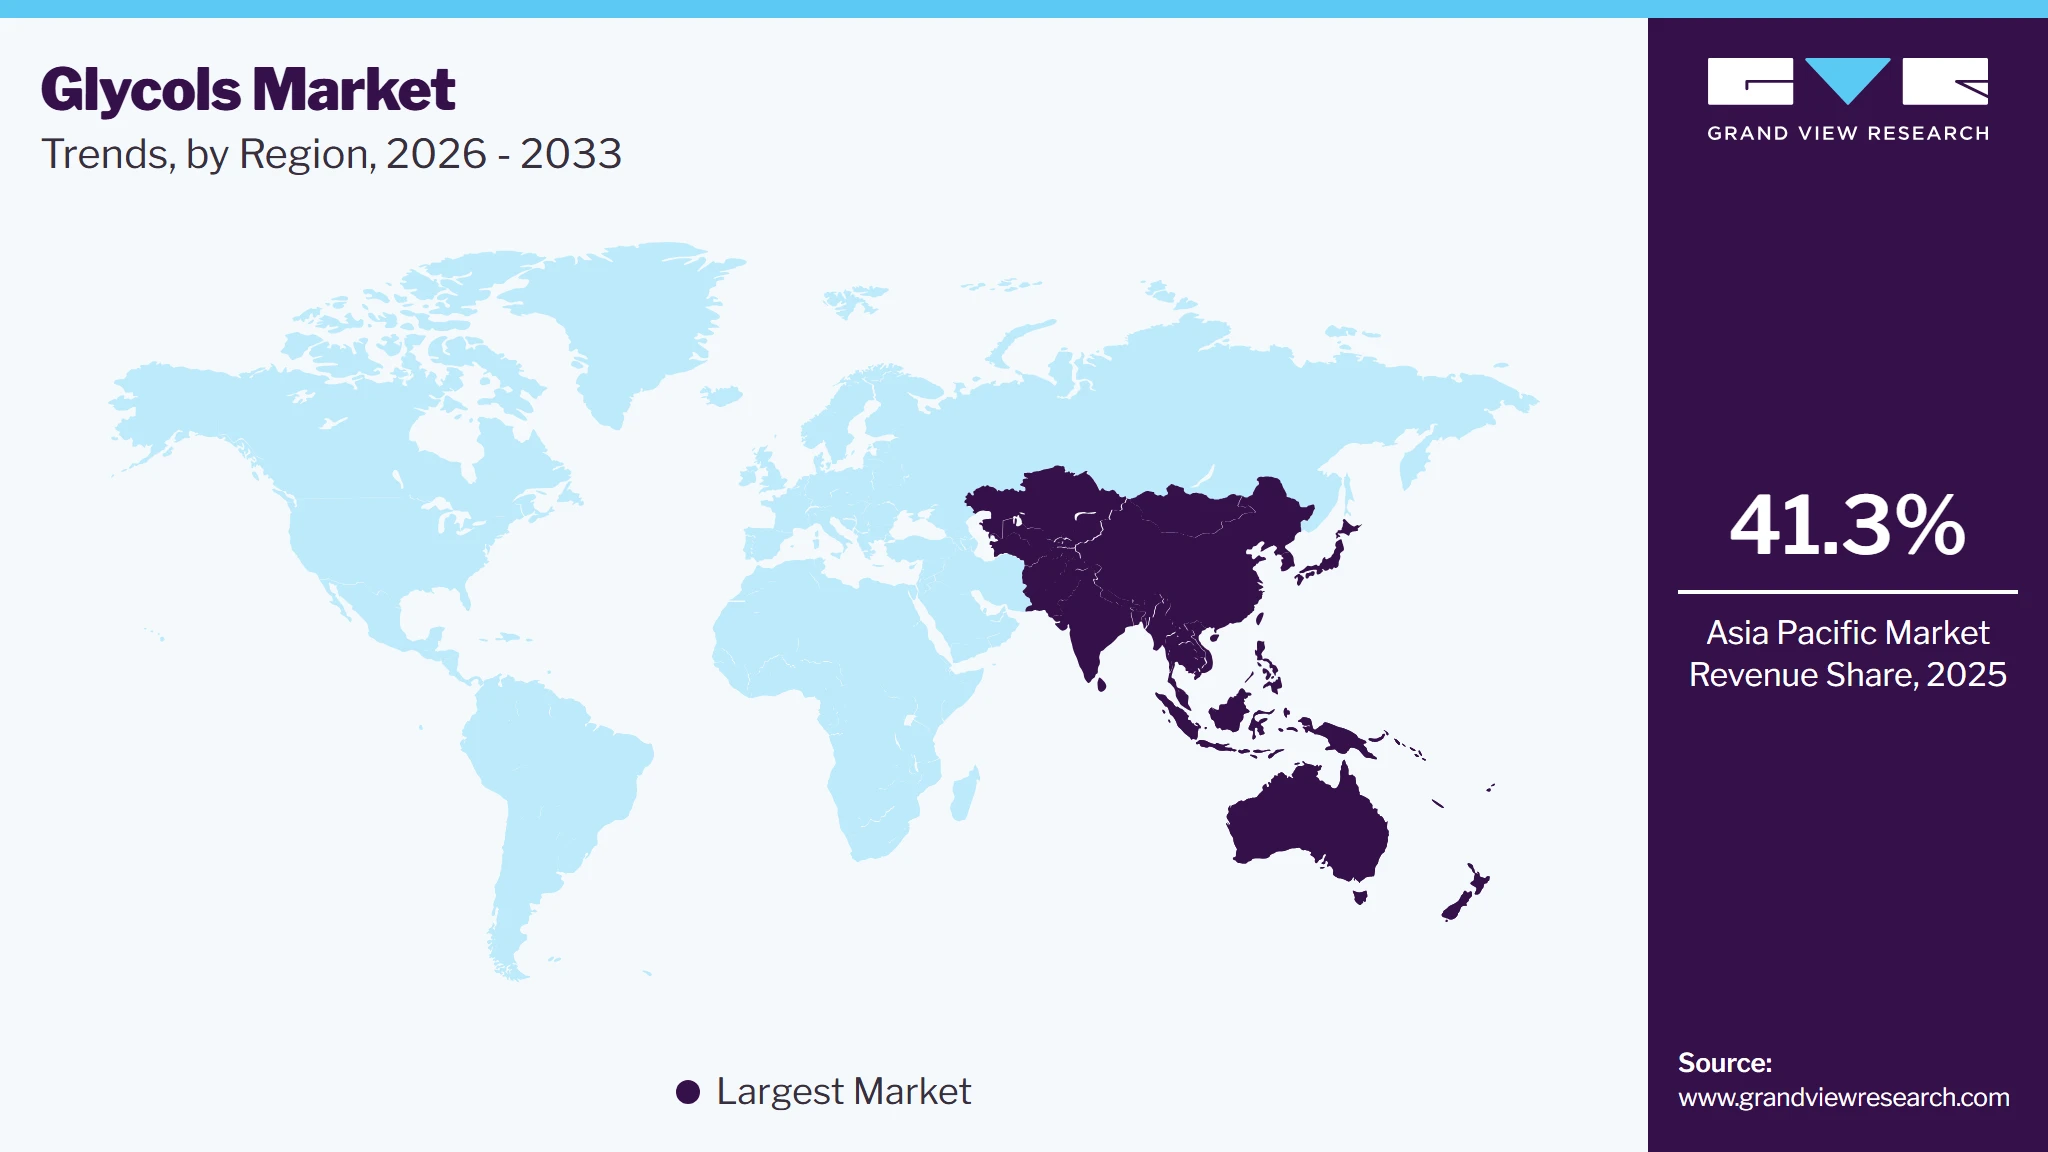
The glycols industry in Asia Pacific dominated the market with a revenue share of 41.3% in 2025, and is also projected to witness the fastest CAGR of 7.3% over the forecast period. Asia Pacific represents a major production and consumption center, supported by its large polyester, PET, automotive, construction, pharmaceutical, and personal-care industries. China, India, South Korea, Japan, and Southeast Asian economies host substantial petrochemical and downstream manufacturing capacity, creating consistent requirements for ethylene glycol, propylene glycol, and related derivatives. Strong packaging and textile output, together with continued investments in integrated chemical complexes, is supporting regional demand. Producers are also increasing their focus on bio-based and lower-carbon grades as sustainability requirements become more prominent among downstream manufacturers. The region's extensive manufacturing infrastructure, expanding domestic consumption, and access to petrochemical feedstocks continue to attract capacity investments.
 To learn more about this report, Download Free Sample Report
China glycols industry is expected to grow at a CAGR of 8.1% during the forecast period. This growth is due to its extensive polyester, PET resin, textile, packaging, automotive, and chemical-processing industries. The country has developed significant integrated petrochemical infrastructure, enabling large-scale production of ethylene glycol and related products. Its sizeable polyester manufacturing base generates substantial downstream consumption, particularly for fiber and bottle-grade PET applications. Domestic producers are simultaneously expanding chemical integration and improving production efficiency to strengthen their position within regional supply chains. Demand is also being supported by consumer-product manufacturing and infrastructure development.
North America Glycols Market Trends
The glycols industry in North America benefits from a mature petrochemical ecosystem, abundant hydrocarbon resources, and established downstream industries. The U.S. and Canada have extensive capabilities spanning ethylene, propylene, polyester intermediates, automotive fluids, coatings, pharmaceuticals, and personal-care formulations. Integrated production assets allow major manufacturers to secure feedstocks and optimize conversion economics, supporting reliable availability of key glycol grades. Demand from automotive manufacturing, packaging, construction, and industrial applications provides a broad consumption base. Producers are also exploring circular and bio-based feedstocks in response to sustainability commitments.
U.S. Glycols Market Trends
The U.S. glycols industry is a significant manufacturing and consumption hub, supported by its extensive ethylene and propylene infrastructure and large end-use industries. Glycol consumption is closely associated with polyester and PET production, automotive coolants, paints and coatings, pharmaceuticals, food processing, and personal-care products. Leading chemical companies operate integrated facilities that provide access to feedstocks, large-scale processing capabilities, and established distribution networks. Growth in packaging, automotive production, and industrial manufacturing continues to underpin requirements for conventional grades, while demand for higher-purity and sustainable alternatives is creating additional avenues for suppliers.
Europe Glycols Market Trends
The glycols industry in Europe maintains a well-developed chemical manufacturing base with strong capabilities in specialty chemicals, automotive products, coatings, pharmaceuticals, packaging, and consumer goods. Demand is supported by established manufacturing industries and the region's emphasis on higher-performance and technically specified chemical products. Major producers are increasingly incorporating renewable feedstocks, mass-balance approaches, recycled inputs, and lower-emission technologies into their portfolios. Regulatory requirements surrounding carbon emissions, chemical safety, and sustainability are influencing investment priorities and product development.
Germany glycols industry is one of Europe's most important chemical manufacturing centers and has a broad industrial customer base spanning automotive, engineering, construction, coatings, pharmaceuticals, and plastics. Its highly integrated chemical clusters provide infrastructure for producing and processing ethylene derivatives, polymers, and specialty formulations. Established manufacturers such as BASF maintain extensive domestic production capabilities and contribute to both local supply and international trade. Demand is reinforced by the country's automotive and industrial sectors, although elevated energy expenses and the transition toward lower-carbon production are influencing investment decisions. Manufacturers are increasingly prioritizing energy efficiency, renewable electricity, circular raw materials, and specialized products to preserve competitiveness.
Middle East & Africa Glycols Market Trends
The glycols industry in the Middle East & Africa is expected to grow at a CAGR of 5.0% from 2026 to 2033, as the region offers opportunities driven by its strong petrochemical feedstock base, expanding downstream processing capabilities, and growing industrial activity. Gulf countries, particularly Saudi Arabia and the United Arab Emirates, possess substantial ethylene and related petrochemical infrastructure, supporting the production of glycol intermediates and downstream materials. Investments in integrated complexes are gradually increasing the region's ability to move from feedstock exports toward higher-value chemical products. Demand is also developing across construction, automotive fluids, packaging, paints, and industrial applications as economic diversification progresses. Africa offers longer-term potential through urbanization, infrastructure investment, and expanding manufacturing activity, although local production remains comparatively limited in many countries.
Latin America Glycols Market Trends
Latin America glycols industry is supported by demand from automotive, construction, packaging, textiles, food and beverage, and consumer-product manufacturing. Brazil represents the region's principal industrial and chemical hub, providing a substantial customer base for ethylene glycol, propylene glycol, and related derivatives. Expanding packaging consumption and polyester applications are creating additional demand for glycol-based intermediates, while industrial and automotive uses provide a diversified foundation for demand. Regional manufacturers and international suppliers are also seeking to strengthen distribution networks and supply reliability to serve fragmented downstream markets.
Key Glycols Company Insights
Companies are strengthening their position through capacity expansions, vertical integration, and investments in advanced production technologies to improve supply reliability and cost efficiency. They are also diversifying portfolios toward bio-based, recycled-content, high-purity, and application-specific grades, while pursuing strategic partnerships and geographic expansion to access growing end-use industries.
-
LOTTE Chemical Corporation is a major South Korean chemical manufacturer with an integrated portfolio spanning basic chemicals, polymers, specialty materials, and ethylene oxide/ethylene glycol (EO/EG) products. Its glycol operations benefit from upstream integration and established production infrastructure, enabling the company to serve polyester, PET, industrial, and other downstream applications. The company continues to strengthen its chemical portfolio through investments in advanced materials, sustainable products, and production efficiency, while its broad international manufacturing and sales network supports customers across key Asian and global markets.
-
Mitsubishi Chemical Group is a diversified Japanese chemical manufacturer with operations spanning performance products, chemicals, polymers, specialty materials, and industrial solutions. Its expertise in ethylene glycol and related chemical technologies complements a broad downstream portfolio serving automotive, electronics, packaging, healthcare, and industrial applications. The group has developed proprietary technologies for glycol production and maintains manufacturing and technology capabilities across multiple regions. Its ongoing emphasis on portfolio transformation, resource efficiency, and higher-value materials is supporting the development of differentiated chemical solutions.
Key Glycols Companies
The following key companies have been profiled for the study on the glycols market.
-
Dow Inc.
-
BASF SE
-
Shell plc / Shell Chemicals
-
INEOS Oxide / INEOS Group
-
SABIC
-
LyondellBasell Industries
-
PETRONAS Chemicals Group Berhad
-
LOTTE Chemical Corporation
-
Mitsubishi Chemical Group
-
Reliance Industries Ltd.
-
India Glycols Ltd.
-
Oriental Union Chemical Corporation (OUCC)
Company Categorization
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Dow Inc.; BASF SE; Shell plc / Shell Chemicals; INEOS Oxide / INEOS Group; SABIC; LyondellBasell Industries; PETRONAS Chemicals Group Berhad; LOTTE Chemical Corporation; Mitsubishi Chemical Group; Reliance Industries Ltd.
- Expand integrated production capabilities to secure feedstock availability and optimize conversion costs.
- Increase plant efficiency through process automation, debottlenecking, and technology upgrades.
- Maintain broad product portfolios to serve commodity as well as specialized applications.
- Strengthen regional manufacturing networks to improve supply continuity and customer responsiveness.
- Large-scale manufacturing assets provide economies of scale and consistent commercial output.
- Strong vertical integration offers greater control over raw materials and production economics.
- Established relationships with global customers support recurring demand across multiple industries.
- Significant R&D capabilities enable development of differentiated and sustainable glycol grades.
- Large production networks can result in higher fixed costs and greater exposure during demand downturns.
- Commodity-oriented operations remain sensitive to fluctuations in feedstock and energy prices.
- Complex organizational structures may make rapid adaptation to niche customer requirements more difficult.
- Extensive exposure to mature markets can limit growth compared with faster-developing specialty applications.
Emerging Players: India Glycols Ltd.; Oriental Union Chemical Corporation (OUCC)
- Focus on targeted applications and higher-value grades rather than competing solely on production volume.
- Invest selectively in capacity additions to align manufacturing expansion with customer demand.
- Develop bio-based, sustainable, and application-specific products to capture evolving requirements.
- Build strategic relationships with international customers to expand exports and strengthen market access.
- Greater operational flexibility can enable quicker responses to changing customer requirements.
- Lower-cost manufacturing locations can provide advantages in selected production categories.
- Focused product portfolios allow specialization in specific glycol grades and applications.
- Expansion-oriented companies can achieve faster capacity and geographic growth from a smaller existing base.
- Smaller manufacturing footprints can restrict economies of scale compared with multinational producers.
- Greater reliance on external feedstock or technology providers can increase cost exposure.
- Limited geographic diversification may make companies more vulnerable to regional demand fluctuations.
- Lower brand recognition and fewer established multinational customer relationships can create barriers to global expansion.
Recent Developments
-
In October 2025, BASF commissioned a new 80,000-metric-ton-per-year neopentyl glycol (NPG) plant at its Zhanjiang Verbund site in China. The addition increased BASF's global NPG capacity from 255,000 to 335,000 metric tons annually, strengthening its supply position in Asia Pacific.
-
In February 2026, Dow reported that the 80,000 MT/year expansion of its Map Ta Phut PG facility had increased total capacity to 250,000 MT/year; the additional capacity came online in 2024 and supported food and pharmaceutical applications in the region.
Glycols Market Report Scope
Report Attribute
Details
Market size in 2025
USD 31.6 billion
Estimated Market size in 2026
USD 33.3 billion
Revenue forecast in 2033
USD 49.5 billion
Growth rate
CAGR of 5.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, volume in Kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue & volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, grade, application, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Argentina; Saudi Arabia; South Africa.
Key companies profiled
Dow Inc.; BASF SE; Shell plc / Shell Chemicals; INEOS Oxide / INEOS Group; SABIC; LyondellBasell Industries; PETRONAS Chemicals Group Berhad; LOTTE Chemical Corporation; Mitsubishi Chemical Group; Reliance Industries Ltd.; India Glycols Ltd.; Oriental Union Chemical Corporation (OUCC)
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Glycols Market Report Segmentation
This report forecasts volume & revenue growth at regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global glycols market report based on product, grade, application, end use, and region:
-
Product Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Ethylene Glycol
-
Propylene Glycol
-
Other Glycols
-
-
Grade Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Industrial Grade
-
USP/EP/Pharmaceutical Grade
-
Food Grade
-
Specialty/Technical Grade
-
Other Grades
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Polyester & PET Production
-
Antifreeze & Coolants
-
Polyurethane & Polyols
-
Solvents
-
Heat Transfer Fluids & Deicing Fluids
-
Personal Care & Cosmetics
-
Pharmaceuticals
-
Food & Beverage
-
Other Applications
-
-
End Use Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Automotive
-
Textiles
-
Packaging
-
Construction
-
Paints & Coatings
-
Personal Care & Cosmetics
-
Pharmaceuticals
-
Food & Beverage
-
HVAC & Industrial
-
Other End Use
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
-
Research Methodology
The glycols market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each glycols segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Ethylene Glycol
Revenue is generated from sales of monoethylene glycol (MEG), diethylene glycol (DEG), and triethylene glycol (TEG) used across polyester and PET manufacturing, antifreeze formulations, solvents, gas dehydration, and other industrial processes. Purchasing value is influenced by purity, production scale, feedstock economics, and downstream consumption.
Propylene Glycol
Value is derived from the sale of mono propylene glycol (MPG), including industrial, USP/EP, and other high-purity grades used in personal care, pharmaceuticals, food processing, coatings, resins, and thermal-management formulations. Demand varies according to specification, regulatory requirements, and application performance.
Other Glycols
Commercial income encompasses specialty glycols such as neopentyl glycol (NPG), dipropylene glycol (DPG), tripropylene glycol (TPG), polyethylene glycols (PEGs), and other glycol derivatives. Their utilization spans coatings, lubricants, cosmetics, pharmaceuticals, plastics, and specialty formulations, with value determined by functionality, purity, and application-specific requirements.
Segment - Grade
Revenue capture definition
Industrial Grade
Sales originate from glycols manufactured to meet industrial specifications for applications including coolants, heat-transfer systems, resins, coatings, solvents, plastics, and chemical processing. Purchasing decisions are shaped by consistent quality, cost efficiency, volume availability, and suitability for demanding operating environments.
USP/EP/Pharmaceutical Grade
Revenue is captured through high-purity materials conforming to pharmacopeial requirements and used in medicines, pharmaceutical formulations, medical products, and selected personal-care applications. Premium value is associated with stringent purity controls, traceability, regulatory compliance, and batch-to-batch consistency.
Food Grade
Expenditure reflects glycol products meeting applicable food-contact and food-processing requirements, particularly propylene glycol used as a humectant, carrier, solvent, and formulation aid. Demand is influenced by regulatory compliance, purity, safety specifications, and compatibility with processed-food and beverage formulations.
Specialty/Technical Grade
Income comes from tailored glycol grades designed for applications requiring specific molecular characteristics, performance parameters, or formulation behavior. These materials serve coatings, lubricants, electronics, personal care, pharmaceuticals, and other specialized industries where technical specifications and functional performance command greater importance.
Other Grades
Revenue encompasses glycol grades manufactured for applications that fall outside standard industrial, pharmaceutical, food, or specialty classifications. Product selection is generally determined by required purity, physical properties, processing conditions, customer specifications, and cost-performance considerations.
Segment - Application
Revenue capture definition
Polyester & PET Production
Customer spending covers glycol feedstocks, particularly MEG, consumed in polyester fibers, PET resins, films, bottles, and related materials. Consumption is closely tied to polymerization capacity, textile output, beverage packaging, and demand for lightweight plastic packaging.
Antifreeze & Coolants
Revenue arises from glycol consumption in automotive and industrial cooling formulations designed to regulate freezing and boiling points while supporting heat removal. Volumes are influenced by vehicle production, equipment fleets, replacement-fluid demand, and requirements for reliable thermal management.
Polyurethane & Polyols
Commercial value is generated from glycol and glycol-based polyol consumption in polyurethane foams, elastomers, sealants, coatings, adhesives, and insulation materials. Demand reflects construction activity, furniture production, automotive manufacturing, and requirements for lightweight and durable materials.
Solvents
Spending is associated with glycol products used as solvents, co-solvents, coupling agents, and formulation aids across paints, coatings, inks, cleaners, pharmaceuticals, cosmetics, and industrial chemicals. Selection depends on solvency, evaporation characteristics, compatibility, and formulation stability
Heat Transfer Fluids & Deicing Fluids
Revenue is captured through glycol-based fluids used to transfer heat or prevent ice formation in HVAC equipment, industrial systems, aircraft, roads, and other temperature-sensitive operations. Purchasing patterns depend on system efficiency, operating temperatures, climate conditions, and fluid service life.
Personal Care & Cosmetics
Demand encompasses glycols used as humectants, solvents, viscosity modifiers, carriers, and formulation stabilizers in skincare, haircare, oral-care, and cosmetic products. Product choice is influenced by purity, sensory characteristics, regulatory suitability, and compatibility with active ingredients.
Pharmaceuticals
Commercial expenditure covers high-purity glycols used as solvents, plasticizers, humectants, carriers, and excipients in pharmaceutical preparations. Requirements for controlled composition, pharmacopeial compliance, traceability, and formulation stability influence purchasing decisions.
Food & Beverage
Sales are generated through food-compatible glycol products, particularly propylene glycol, used as a humectant, solvent, carrier, and processing aid in selected food and beverage applications. Consumption is governed by food-safety standards, formulation requirements, purity specifications, and permitted-use regulations.
Other Applications
Incremental revenue comes from glycol consumption in applications such as gas dehydration, tobacco processing, electronic chemicals, lubricants, detergents, printing inks, and chemical intermediates. Demand varies according to process requirements, product functionality, and industrial operating conditions.
Segment - End Use
Revenue capture definition
Automotive
Spending is associated with glycols incorporated into engine coolants, antifreeze formulations, brake-related fluids, lubricants, and selected polymeric materials. Requirements for thermal stability, freeze protection, corrosion control, and dependable vehicle operation shape product selection.
Textiles
Revenue is generated from MEG consumption in polyester fiber and filament production, which supports apparel, home furnishings, technical textiles, and industrial fabrics. Market requirements are influenced by polyester manufacturing volumes, fiber capacity additions, and global textile consumption.
Packaging
Commercial value stems primarily from MEG used to manufacture PET bottles, containers, films, and packaging materials. Demand follows beverage consumption, food packaging, consumer-goods distribution, and the expansion of lightweight and recyclable packaging formats.
Construction
Expenditure covers glycol utilization in antifreeze systems, polyurethane insulation, coatings, sealants, adhesives, and other construction-related formulations. Consumption is supported by building activity, infrastructure development, energy-efficient insulation requirements, and cold-weather applications.
Paints & Coatings
Sales arise from glycol use as solvents, coalescing agents, intermediates, and formulation components in architectural, industrial, automotive, and protective coatings. Purchasing priorities include solvency, film formation, drying behavior, compatibility, and surface-finish requirements.
Personal Care & Cosmetics
Revenue is captured from glycol ingredients incorporated into skincare, haircare, fragrances, oral-care products, and cosmetic formulations. Demand is driven by their roles in moisture retention, ingredient solubilization, texture control, preservation support, and formulation stability.
Pharmaceuticals
Commercial activity reflects consumption of pharmaceutical-grade glycols in drug formulations, topical preparations, oral products, and manufacturing processes. Buyers prioritize stringent purity, regulatory compliance, consistent specifications, and reliable documentation.
Food & Beverage
Spending encompasses approved glycol grades used in food processing and formulations, particularly as humectants, carriers, and solvents. Demand is determined by permitted applications, food-safety requirements, formulation performance, and growth in processed-food production.
HVAC & Industrial
Income is derived from glycol-based heat-transfer fluids, coolants, deicing formulations, and process fluids used in HVAC installations and industrial equipment. Requirements for efficient heat exchange, freeze protection, corrosion resistance, and long operating life influence adoption.
Other End Uses
Additional revenue originates from applications across electronics, chemicals, lubricants, agriculture, tobacco processing, printing, and gas treatment. Consumption is typically driven by specialized functional requirements and the ability of specific glycol grades to meet process and performance specifications.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Raw Material & Production Layer
What forms the supply base?
Examine the feedstocks and manufacturing infrastructure supporting glycol production, including ethylene, propylene, ethylene oxide, propylene oxide, natural gas, petroleum-derived inputs, and renewable or recycled raw materials. The assessment covers feedstock availability, cracking and oxidation processes, hydrolysis, purification, separation, refining, and integrated petrochemical operations. It also considers plant scale, capacity utilization, energy requirements, storage facilities, quality management, sustainability certifications, and regulatory compliance.
02
Application Adoption Layer
Where are glycols utilized?
Assess utilization across polyester and PET manufacturing, antifreeze and coolants, polyurethane and polyols, solvents, heat-transfer fluids, deicing formulations, pharmaceuticals, food and beverage, personal care, coatings, and other industrial applications. Adoption depends on attributes such as thermal stability, solvency, hygroscopicity, purity, freezing-point depression, and compatibility with downstream formulations. Industry production levels, technical specifications, regulatory standards, and substitution possibilities also influence uptake.
03
Consumption Intensity Layer
How extensively are glycols consumed?
Analyze consumption according to glycol type, grade, formulation, application, dosage, production scale, and end-use output. Usage intensity varies considerably between high-volume polymer manufacturing and lower-volume specialty applications, with MEG requirements closely linked to polyester and PET production and PG consumption distributed across industrial, pharmaceutical, food, and personal-care uses. Purchasing patterns are further shaped by plant utilization, formulation requirements, product purity, replacement cycles, and shifts toward sustainable or higher-performance grades.
04
Revenue Layer
How is market revenue generated?
Revenue is realized through the sale of MEG, DEG, TEG, PG, NPG, DPG, TPG, PEG, and other glycol grades to polymer producers, formulators, chemical processors, and industrial users. Commercial value is determined by product specification, purity, feedstock costs, manufacturing efficiency, order volumes, application requirements, geographic availability, and supply reliability. Higher-value opportunities emerge through pharmaceutical and food-grade materials, specialty derivatives, renewable-feed stock products, customized solutions, and long-term supply arrangements.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional segmentation
The assessment provides country-level market sizing and forecasts, supported by analysis of glycol production capacity, petrochemical feedstock availability, polyester and PET output, automotive manufacturing, construction activity, industrial production, trade flows, import dependence, and regulatory conditions. It examines regional manufacturing clusters, integrated chemical complexes, infrastructure, energy economics, supply routes, and the development of sustainable glycol production across major countries.
Supports geographic expansion, capacity planning, sourcing strategies, supply-chain optimization, distributor selection, and investment decisions by identifying locations with strong production infrastructure, favorable feedstock economics, expanding downstream industries, and attractive demand conditions.
Opportunity Assessment
Comprehensive evaluation of growth avenues across polyester and PET, automotive fluids, polyurethane, coatings, pharmaceuticals, food processing, personal care, HVAC, and specialty chemical applications. The analysis considers opportunities associated with bio-based and circular feedstocks, high-purity grades, specialty glycols, low-carbon manufacturing, downstream integration, and rising demand from emerging industrial applications.
Helps identify promising product categories, application areas, customer segments, and geographic markets by assessing consumption trends, technological developments, sustainability requirements, capacity additions, and evolving procurement priorities. Findings can guide portfolio diversification, plant investments, product development, strategic alliances, and market-entry initiatives.
Competitive Benchmarking
Comparative evaluation of major producers based on glycol portfolio, manufacturing capacity, feedstock integration, geographic reach, production technology, operational scale, product quality, R&D capabilities, sustainability initiatives, and customer coverage. The assessment also examines recent capacity additions, facility investments, product introductions, certifications, partnerships, acquisitions, and initiatives involving renewable or recycled feedstocks.
Enables companies to assess relative capabilities, identify portfolio and geographic gaps, and determine potential areas for differentiation. The findings support decisions involving capacity expansion, technology upgrades, sustainable product development, vertical integration, strategic partnerships, customer acquisition, and competitive positioning.
Frequently Asked Questions About This Report
The glycols market size was estimated at USD 31.6 billion in 2025 and is expected to reach USD 33.3 billion in 2026.
Ethylene glycol segment dominated with a revenue share of 87.7% in 2025, reflecting its extensive use across high-volume industrial applications. Its principal consumption comes from polyester and PET production, where it serves as a key raw material for manufacturing polyester fibers, films, and PET resins used in packaging.
Some of the key players operating in the glycols market include Dow Inc.; BASF SE; Shell plc / Shell Chemicals; INEOS Oxide / INEOS Group; SABIC; LyondellBasell Industries; PETRONAS Chemicals Group Berhad; LOTTE Chemical Corporation; Mitsubishi Chemical Group; Reliance Industries Ltd.; India Glycols Ltd.; Oriental Union Chemical Corporation (OUCC).
The glycols market is expected to grow at a compound annual growth rate of 5.8% from 2026 to 2033 to reach USD 49.5 billion by 2033.
Asia Pacific dominated the market with a revenue share of 41.3% in 2025, as it represents a major production and consumption center, supported by its large polyester, PET, automotive, construction, pharmaceutical, and personal-care industries.
Polyester & pet production segment dominated with a share of 37.6% in 2025 making it the largest application area. Ethylene glycol is a fundamental feedstock in the manufacture of polyester fibers, PET bottles, films, sheets, and other polymer products.
Automotive segment held the largest share of 21.5% in 2025, reflecting extensive glycol consumption in engine coolants, antifreeze formulations, heat-management systems, and selected polymer applications.
Industrial grade segment dominated with a revenue share of 73.9% in 2025. primarily because large volumes of glycols are consumed in manufacturing and process-oriented applications. Ethylene glycol is extensively used in antifreeze, coolants, heat-transfer fluids, polyester manufacturing.
Expanding automotive, construction, and industrial activity is increasing consumption of propylene glycol and ethylene glycol in coolants, antifreeze, polyurethane, coatings, and heat-transfer applications.
About the Author(s)
Performance Chemicals Research Team
Specialty & Fine Chemicals · Performance ChemicalsThis report was authored by the performance chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the performance chemicals segment of the specialty & fine chemicals industry. All findings are based on proprietary specialty & fine chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


