
- Home
- »
- Next Generation Technologies
- »
-
GNSS Simulators Market Size & Share Report, 2026-2033GVR Report cover

GNSS Simulators Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Software, Services, Hardware), By Type (Single Channel, Multichannel), By GNSS Receiver, By Application, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$207.3MMarket Estimate, 2026
$227.4MMarket Forecast, 2033
$434.8MCAGR, 2026–2033
9.7%GNSS Simulators Market Summary
The global GNSS simulators market size was valued at USD 207.3 million in 2025 and is projected to grow from USD 227.4 million in 2026 to USD 434.8 million in 2033, at a CAGR of 9.7% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.0% in 2025. The market for GNSS (Global Navigation Satellite System) simulators is growing due to the increasing need for accurate positioning solutions in various sectors such as aerospace, defense, and transportation. Advancements in simulation technology, expanding applications of GNSS in emerging industries, and the need for cost-effective testing and training solutions are driving product adoption.
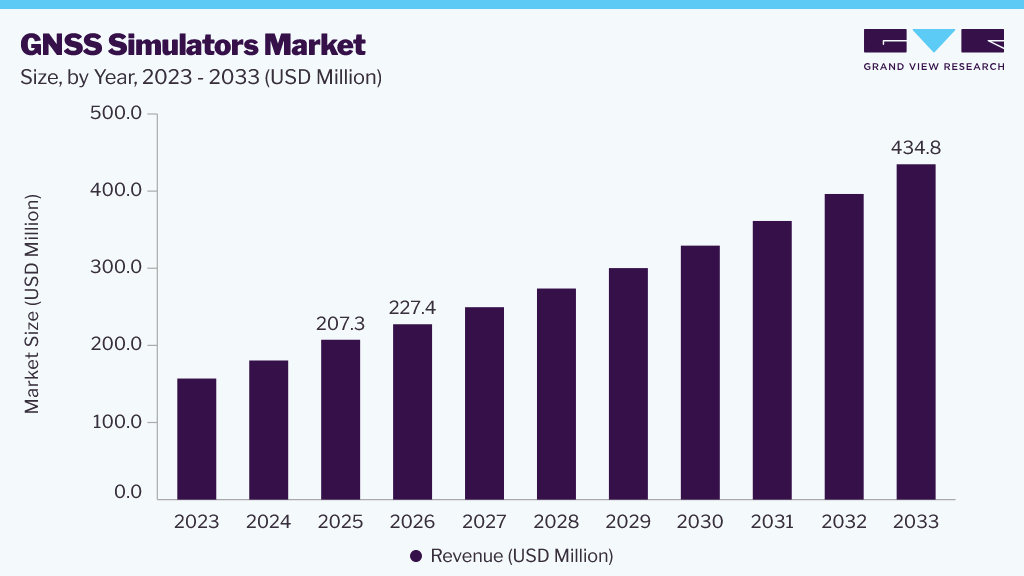 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: The hardware segment accounted for the largest revenue share, over 46.0% in 2025, and is anticipated to experience the fastest growth during the forecast period.
- By end use: The consumer electronics segment accounted for the largest revenue share in 2025.
- By type: The multichannel segment accounted for the largest revenue share in 2025.
- By GNSS receivers: The GPS segment accounted for the largest revenue share in 2025.
- By application: The navigation & mapping segment accounted for the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (37.0% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 207.3 Million
- Estimated market size in 2026: USD 227.4 Million
- Projected market size by 2033: USD 434.8 Million
- CAGR (2026-2033): 9.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
GNSS technology is rapidly advancing through the development of new satellite constellations, enhanced receiver capabilities, and improved positioning accuracy, driving market growth. As navigation systems become more sophisticated, demand for reliable simulation tools continues to increase to support testing, validation, and operator training across diverse operational environments.The expansion of satellite networks has increased the complexity of signal interactions across multiple constellations and frequencies. This has created a growing need for advanced simulation environments capable of replicating real-world conditions and interference scenarios. In addition, the increasing focus on higher positioning accuracy, anti-jamming resilience, and support for applications such as autonomous vehicles, precision agriculture, and location-based services is driving demand for more advanced GNSS simulation capabilities. GNSS simulators play a critical role in validating navigation technologies by enabling manufacturers, businesses, and research institutions to test system performance, improve reliability, and accelerate product development under controlled conditions.
Analyst Perspective
The market is expected to grow strongly, driven by the increasing adoption of satellite navigation technologies across aerospace, defense, automotive, autonomous vehicles, UAVs, telecommunications, and precision agriculture. The growing reliance on accurate positioning, navigation, and timing (PNT) systems is encouraging commercial enterprises, government agencies, and research institutions to invest in advanced simulation platforms to validate GNSS performance, reduce development costs, and accelerate product deployment. The rising demand for multi-constellation and multi-frequency testing, along with increasing concerns about GNSS spoofing, jamming, and signal interference, is further driving the adoption of high-fidelity simulators with cybersecurity and hardware-in-the-loop (HIL) capabilities. In addition, advancements in software-defined radio (SDR), digital twin technologies, and next-generation satellite navigation systems are expected to create significant growth opportunities by enabling more accurate, scalable, and efficient testing solutions across both commercial and defense applications.
Component Insights
The hardware segment accounted for the largest revenue share of over 46.0% in 2025 and is anticipated to experience the fastest growth during the forecast period. Advancements in semiconductor and RF (Radio Frequency) technologies play a significant role in driving growth in the hardware segment. The development of high-performance, low-power radio-frequency (RF) components enables the creation of improved GNSS simulator hardware that can simulate multiple satellite constellations, signals, and environmental conditions with greater accuracy and reliability.
The software segment is anticipated to experience significant growth during the forecast period due to continuous advancements in software algorithms, signal processing techniques, and simulation technologies. Software-based GNSS simulators offer high flexibility and scalability, enabling users to customize simulation parameters, replicate complex operating scenarios, and analyze test results with greater accuracy and efficiency. Growth in this segment is further driven by increasing demand for multi-constellation and multi-frequency simulation, real-time scenario modeling, and advanced interference-testing capabilities. The rising adoption of software-defined radio (SDR), cloud-based simulation platforms, and hardware-in-the-loop (HIL) testing is also accelerating demand for software-based solutions. These platforms help improve simulation accuracy, reduce testing complexity, and lower operational costs across aerospace, defense, automotive, and research applications.
End Use Insights
The consumer electronics segment accounted for the largest revenue share in 2025, driven by rising demand for precise positioning and navigation capabilities in portable devices. Accurate GNSS functionality is crucial as people increasingly use smartphones and wearables for navigation, location-based services, and fitness tracking. The rapid expansion of GNSS-enabled technologies across autonomous vehicles, unmanned aerial vehicles (UAVs), aerospace systems, and connected devices is driving the demand for GNSS simulators. These simulators enable manufacturers to accurately test, validate, and optimize positioning, navigation, and timing (PNT) performance under diverse real-world conditions, reducing development time, ensuring regulatory compliance, and enhancing the reliability of GNSS-dependent applications.
Automotive is expected to grow fastest during the forecast period, driven by the increasing integration of advanced navigation and driver assistance systems in modern vehicles. The rise of self-driving technologies and the growing demand for advanced in-car navigation experiences led car manufacturers to provide precise and dependable GNSS functionality. GNSS simulators enable automotive manufacturers to validate the performance of their navigation systems across diverse scenarios, including urban environments, tunnels, and challenging weather conditions, ensuring seamless operation and precision in real-world driving. In January 2024, Spirent Communications partnered with dSPACE to integrate Spirent’s GNSS simulator into dSPACE’s AD-HIL framework. This integration enables developers to validate vehicle performance in location-sensitive scenarios using precise satellite signal simulation, helping accelerate development cycles and reduce time-to-market for autonomous driving solutions.
Type Insights
The multichannel segment accounted for the largest revenue share in 2025, driven by growing demand for advanced GNSS testing solutions capable of simultaneously simulating multiple satellite signals, constellations, and frequencies. As navigation systems become increasingly complex, multichannel simulators are essential for accurately replicating real-world operating conditions and validating system performance. Growth in this segment is further supported by the rising adoption of multi-constellation GNSS receivers across automotive, aerospace, defense, and autonomous systems applications. The increasing need for high-precision positioning, improved signal reliability, and robust interference testing is accelerating demand for multichannel simulation platforms. These solutions enable users to evaluate receiver performance under dynamic scenarios, including signal blockage, interference, spoofing, and challenging environmental conditions.
The single-channel segment is anticipated to witness the fastest growth during the forecast period. The increasing adoption of advanced navigation systems and the emphasis on safety standards serve as growth drivers for the market. The aviation industry is moving towards performance-based and satellite-based navigation systems, which has increased demand for high-fidelity single-channel GNSS simulators. These simulators are essential for aviation authorities, airlines, and aircraft manufacturers to test and validate GNSS receiver performance and ensure compliance with strict regulatory requirements.
GNSS Receiver Insights
The GPS segment accounted for the largest revenue share in 2025 and is anticipated to witness the fastest growth during the forecast period. The growth is attributed to the integration of GPS technology across various industries and applications, including automotive, aviation, agriculture, and telecommunications. The demand for precise positioning and navigation solutions continues to surge, driven by the rise of location-based services, IoT devices, and autonomous technologies. For instance, in March 2025, u-blox launched the ZED-X20P, an all-band GNSS receiver module designed for industrial automation, robotics, precision agriculture, and autonomous systems. The module supports concurrent multi-band and multi-constellation GNSS reception, delivering centimeter-level positioning accuracy. This development highlights the growing demand for advanced GNSS testing and simulation solutions to validate receiver performance across diverse operating conditions.
Galileo is anticipated to witness substantial growth during the forecast period. The adoption of Galileo extends beyond traditional navigation applications to include a wide range of emerging use cases, such as precision agriculture, unmanned aerial vehicles (UAVs), and location-based services. These diverse applications demand specialized testing environments that accurately replicate Galileo signals and operational scenarios. According to the DJI Agriculture's Drone Insight Report, more than 200,000 agricultural drones were deployed worldwide, spanning approximately 200 million hectares. These drones aimed to bolster efficiency in farmland management via digital solutions.
Application Insights
The navigation & mapping segment accounted for the largest revenue share in 2025 and is expected to witness significant growth during the forecast period. Growth in this segment is driven by the rapid expansion of location-based services and digital mapping applications across transportation, logistics, urban planning, and outdoor recreation. The increasing reliance on accurate positioning and geospatial data is driving demand for reliable GNSS testing and validation solutions to support route optimization, asset tracking, and spatial analysis. As navigation systems become more advanced, GNSS simulators play a critical role in validating positioning accuracy and ensuring dependable performance across diverse operating environments. For instance, in March 2026, Septentrio launched the AsteRx EB, a compact high-precision GNSS receiver designed for robotics, logistics, and industrial automation applications. The receiver supports multi-frequency and multi-constellation positioning, delivering reliable performance in demanding environments. This development highlights the growing need for advanced GNSS simulators to validate positioning accuracy and system reliability before deployment.
The surveying segment is expected to experience robust growth during the forecast period, driven by the increasing adoption of high-precision GNSS technologies for land surveying, mapping, and geospatial data collection. Growing demand for accurate positioning solutions continues to rise due to increasing infrastructure development, urban planning, and natural resource management projects worldwide. GNSS simulators play a critical role in surveying applications by enabling the replication of real-world operating conditions, including signal obstructions and challenging terrain. These solutions help surveyors validate and optimize GNSS receiver and antenna performance, improving positioning accuracy and operational reliability under diverse field conditions.
Regional Insights
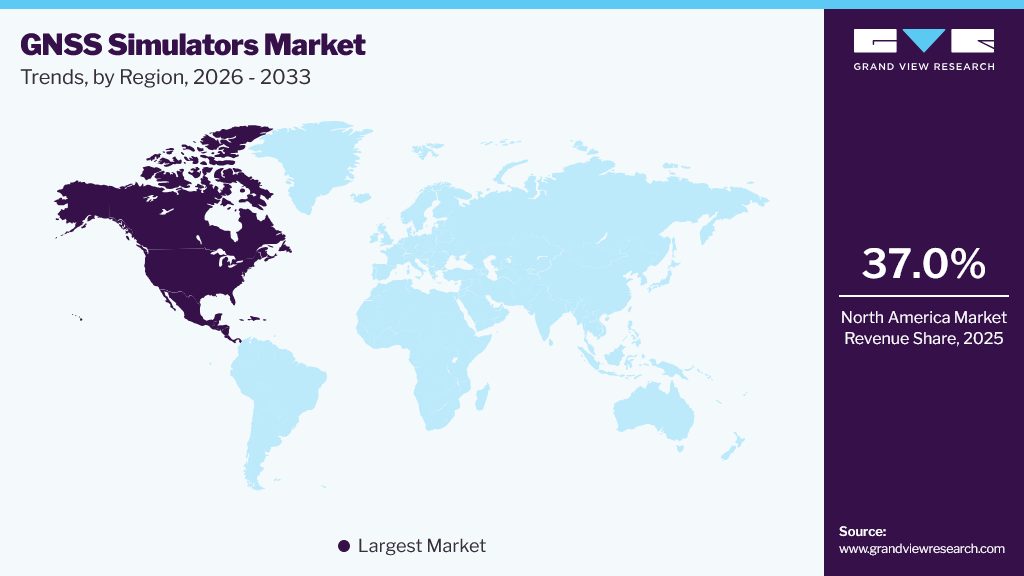
North America dominated the market with over 37.0% share in 2025, driven by the widespread use of GNSS technology across industries such as aerospace, defense, transportation, and telecommunications. The global positioning system (GPS) was created in the U.S. and is a widely used GNSS system worldwide, which constantly requires GNSS simulators to test and improve navigation systems, satellite communication networks, and location-based services. The region's regulatory environment is supportive, and significant investment in research and development is driving the development of advanced GNSS simulation solutions to meet the requirements of diverse industries and applications.
 To learn more about this report, Download Free Sample Report
U.S. GNSS Simulators Market Trends
The GNSS simulators market in the U.S. accounted for approximately 23.0% of North America in 2025. The U.S. Government's ongoing investment in GNSS infrastructure and modernization programs is driving market growth. For instance, in June 2026, the U.S. Space Force awarded Lockheed Martin a USD 514 million contract for two additional GPS IIIF satellites, expanding the next-generation GPS constellation. The satellites are designed with enhanced anti-jamming capabilities, improved civilian and military navigation signals, and digital payload flexibility, reinforcing the modernization of the GPS architecture and increasing the need for advanced GNSS simulators to validate performance in contested, interference-heavy environments. The U.S. operates the GPS, one of the most widely used GNSS systems globally, and is committed to enhancing its capabilities to meet evolving user needs and technological advancements. Initiatives such as GPS III, the Next-Generation Operational Control System (OCX), and the National Timing Resilience and Security Act highlight the government's commitment to maintaining the integrity, resilience, and security of the GPS infrastructure.
Europe GNSS Simulators Market Trends
The GNSS simulators market in Europe is expected to grow at a lucrative pace over the forecast period due to the presence and development of the Galileo satellite navigation system. Galileo, Europe's satellite constellation, is steadily expanding its reach and capabilities, offering enhanced accuracy and reliability compared to other GNSS systems. This expansion of Galileo drives the demand for GNSS simulators in Europe as manufacturers and developers seek comprehensive testing solutions to ensure compatibility and optimize performance with the Galileo system. For instance, in January 2024, Qualinx partnered with the European Union Agency for the Space Program (EUSPA) to create a low-power GNSS receiver tailored for EUSPA's GNSS authentication service. The project aims to ensure that users receive accurate data from Galileo satellites while also tackling spoofing incidents.
The UK GNSS simulators market is expected to grow at a substantial rate over the forecast period due to the increasing demand for precise navigation and positioning solutions across various industries, such as automotive and manufacturing. Automotive companies heavily rely on GNSS technology for applications such as vehicle navigation, fleet management, and logistics optimization. GNSS simulators play a crucial role in testing and validating the performance of these systems under various environmental conditions, ensuring accuracy and reliability, which are vital to the country's industrial competitiveness and efficiency.
Asia Pacific GNSS Simulators Market Trends
The GNSS simulators market in the Asia Pacific is expected to experience significant growth during the forecast period. The rapid advancements in GNSS technology, including satellite constellations such as Galileo, BeiDou, and the Indian Regional Navigation Satellite System (IRNSS), have transformed the capabilities of GNSS simulators across the Asia-Pacific region. Government initiatives to support infrastructure development, smart city projects, and digitalization efforts fuel the demand for GNSS technologies in the region.
China GNSS simulators market is expected to grow lucratively over the forecast period due to the rapid expansion of China's satellite navigation infrastructure with the BeiDou Navigation Satellite System (BDS). There is a growing demand for GNSS simulators to support the development, testing, and validation of BeiDou-enabled devices and applications as China aims to establish BeiDou as a global navigation system. This initiative aims to invest in the GNSS ecosystem in China by developing advanced simulation technologies personalized to the BeiDou constellation.
The GNSS simulators market in India is driven by the increasing adoption of GNSS technology across various sectors. Various sectors, such as transportation, agriculture, telecommunications, and defense, use GNSS systems for applications ranging from vehicle tracking and fleet management to precision farming and military operations. For instance, the Indian Space Research Organization continued expanding its Navigation with Indian Constellation (NavIC) program through the NVS-series satellites to improve signal continuity, enhance positioning accuracy, and strengthen multi-band navigation services across L1, L5, and S-band frequencies. These advancements reflect India’s efforts to build a more resilient regional navigation system, increasing the need for GNSS simulators to validate receiver performance, ensure interoperability with global GNSS constellations, and test system reliability under diverse operating conditions.
Key GNSS Simulators Company Insights
Some of the key players operating in the market include Accord Software & Systems Private Limited, SAFRAN, and VIAVI Solutions Inc.
-
Accord Software & Systems Private Limited specializes in GNSS technology, avionics, and real-time embedded systems. The company offers a broad portfolio of solutions, including GNSS receivers, GNSS simulators, and software-based simulation tools. Accord has developed space-grade GPS receivers deployed in multiple Indian satellite and launch vehicle programs, strengthening its expertise in navigation and positioning technologies. The company has also expanded its GNSS capabilities for small satellites by developing compact receivers optimized for low Earth orbit (LEO) applications.
-
SAFRAN offers advanced GNSS simulation solutions for testing and validating navigation systems across aerospace, defense, and commercial applications. Through its navigation and timing portfolio, including Skydel-based simulation platforms, the company provides high-performance simulators that support multi-constellation and multi-frequency signal generation, as well as real-time scenario simulation. SAFRAN’s solutions are widely used to test resilient positioning, navigation, and timing (PNT) systems, including anti-jamming and GNSS-denied-environment applications.
Key GNSS Simulators Companies
The following are the leading companies in the GNSS simulators market. These companies collectively hold the largest market share and dictate industry trends.
-
Accord Software & Systems Private Limited
-
Averna
-
CAST Navigation, LLC
-
Hexagon AB
-
Keysight Technologies
-
Rohde & Schwarz
-
SAFRAN
-
IFEN
-
Tersus GNSS Inc
-
u-blox
-
VIAVI Solutions Inc.
Recent Developments
-
In April 2026, Rohde & Schwarz introduced Pulsar signal simulation capabilities, enabling manufacturers to test next-generation LEO-based navigation systems and allowing early validation of receiver performance under advanced positioning, navigation, and timing (PNT) conditions.
-
In February 2026, Safran Electronics & Defense acquired Syntony GNSS to strengthen its resilient PNT portfolio, integrating software-defined GNSS simulation and anti-jamming technologies to support navigation in GNSS-denied environments. The acquisition underscores the growing strategic importance of GNSS simulators in validating next-generation navigation and timing systems under contested operational conditions.
GNSS Simulators Market Report Scope
Report Attribute
Details
Market size in 2025
USD 207.3 million
Estimated market size in 2026
USD 227.4 million
Projected market size by 2033
USD 434.8 million
Growth rate
CAGR of 9.7% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, type, GNSS receiver, application, end-use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; UK; Germany; France; Italy; China; India; Japan; South Korea; Australia; Brazil; Mexico; Argentina; UAE; Saudi Arabia; South Africa
Key companies profiled
Accord Software & Systems Private Limited; Averna; CAST Navigation, LLC; Hexagon AB; Keysight Technologies; Rohde & Schwarz; SAFRAN; IFEN; Tersus GNSS Inc; u-blox; VIAVI Solutions Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
GNSS Simulators Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global GNSS Simulators market report based on component, type, GNSS receiver, application, end-use, and region:
- Component Outlook (Revenue, USD Million, 2021 - 2033)
- Hardware
- Software
- Services
- Type Outlook (Revenue, USD Million, 2021 - 2033)
- Single Channel
- Multichannel
- GNSS Receiver Outlook (Revenue, USD Million, 2021 - 2033)
- GPS
- Galileo
- GLONASS
- BeiDou
- Others
- Application Outlook (Revenue, USD Million, 2021 - 2033)
- Navigation & Mapping
- Surveying
- Vehicle Assistance System
- Location-based Services
- Others
- End Use Outlook (Revenue, USD Million, 2021 - 2033)
- Automotive
- Aerospace
- Defense
- Consumer Electronics
- Others
- Regional Outlook (Revenue, USD Million, 2021 - 2033)
- North America
- U.S.
- Canada
- Europe
- UK
- Germany
- Italy
- France
- Asia Pacific
- China
- India
- Japan
- South Korea
- Australia
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East & Africa
- UAE
- Saudi Arabia
- South Africa
- North America
Frequently Asked Questions About This Report
The hardware segment accounted for the largest revenue share of approximately 46.0% in 2025.
The global GNSS Simulators market size was valued at USD 207.3 million in 2025 and is estimated at USD 227.4 million for 2026.
Key players in the market are Accord Software & Systems Private Limited, Averna, CAST Navigation, LLC, Hexagon AB, Keysight Technologies, Rohde & Schwarz, SAFRAN, IFEN, Tersus GNSS Inc., u-blox, VIAVI Solutions Inc., and others.
The global GNSS Simulators market is expected to grow at a CAGR of 9.7% from 2026 to 2033, reaching USD 434.8 million.
The North America market dominated with a revenue share of approximately 37.0% in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


