
- Home
- »
- Advanced Interior Materials
- »
-
Graphite Mining Market Size, Share & Trends Report, 2033GVR Report cover

Graphite Mining Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Flake, Amorphous, Vein/Lump), By Application (Refractories, Batteries), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$1.8BMarket Estimate, 2026
$1.9BMarket Forecast, 2033
$3.6BCAGR, 2026–2033
9.6%Graphite Mining Market Summary
The global graphite mining market was valued at USD 1.8 billion in 2025 and is projected to grow from USD 1.9 billion in 2026 to USD 3.6 billion by 2033, at a CAGR of 9.6% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 83.6% in 2025. Growth is primarily driven by the increasing demand for natural graphite across lithium-ion battery manufacturing, particularly for electric vehicles and energy storage systems. Graphite is a key anode material due to its high electrical conductivity, electrochemical stability, and ability to support efficient energy storage.
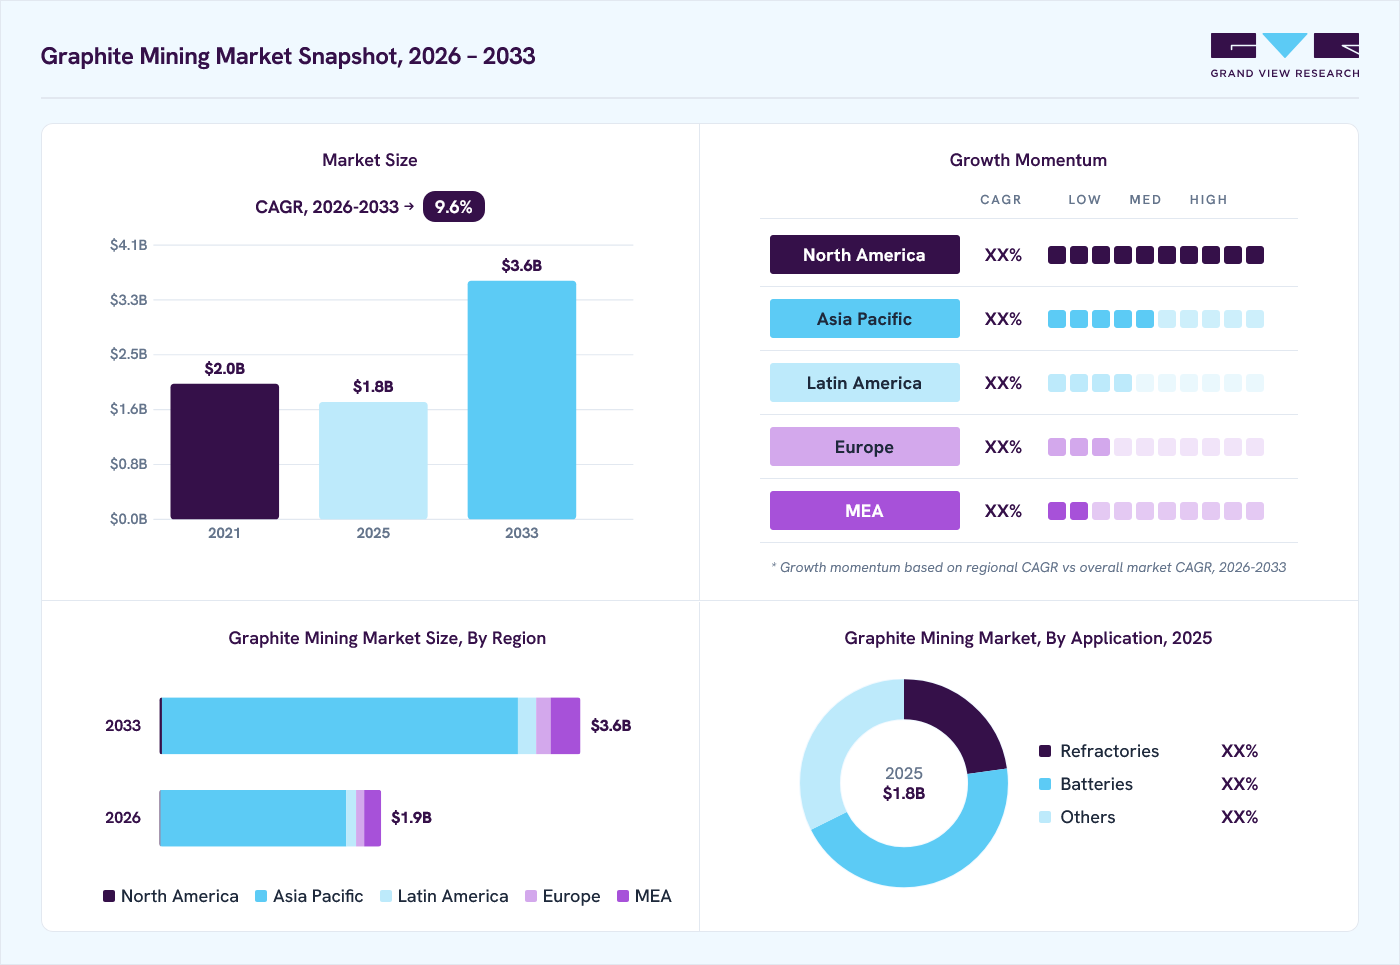 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Flake accounted for the largest market revenue share of 85.9% in 2025.
- By application: Batteries segment is anticipated to register the fastest CAGR of 9.7% from 2026 to 2033.
Regional Highlights
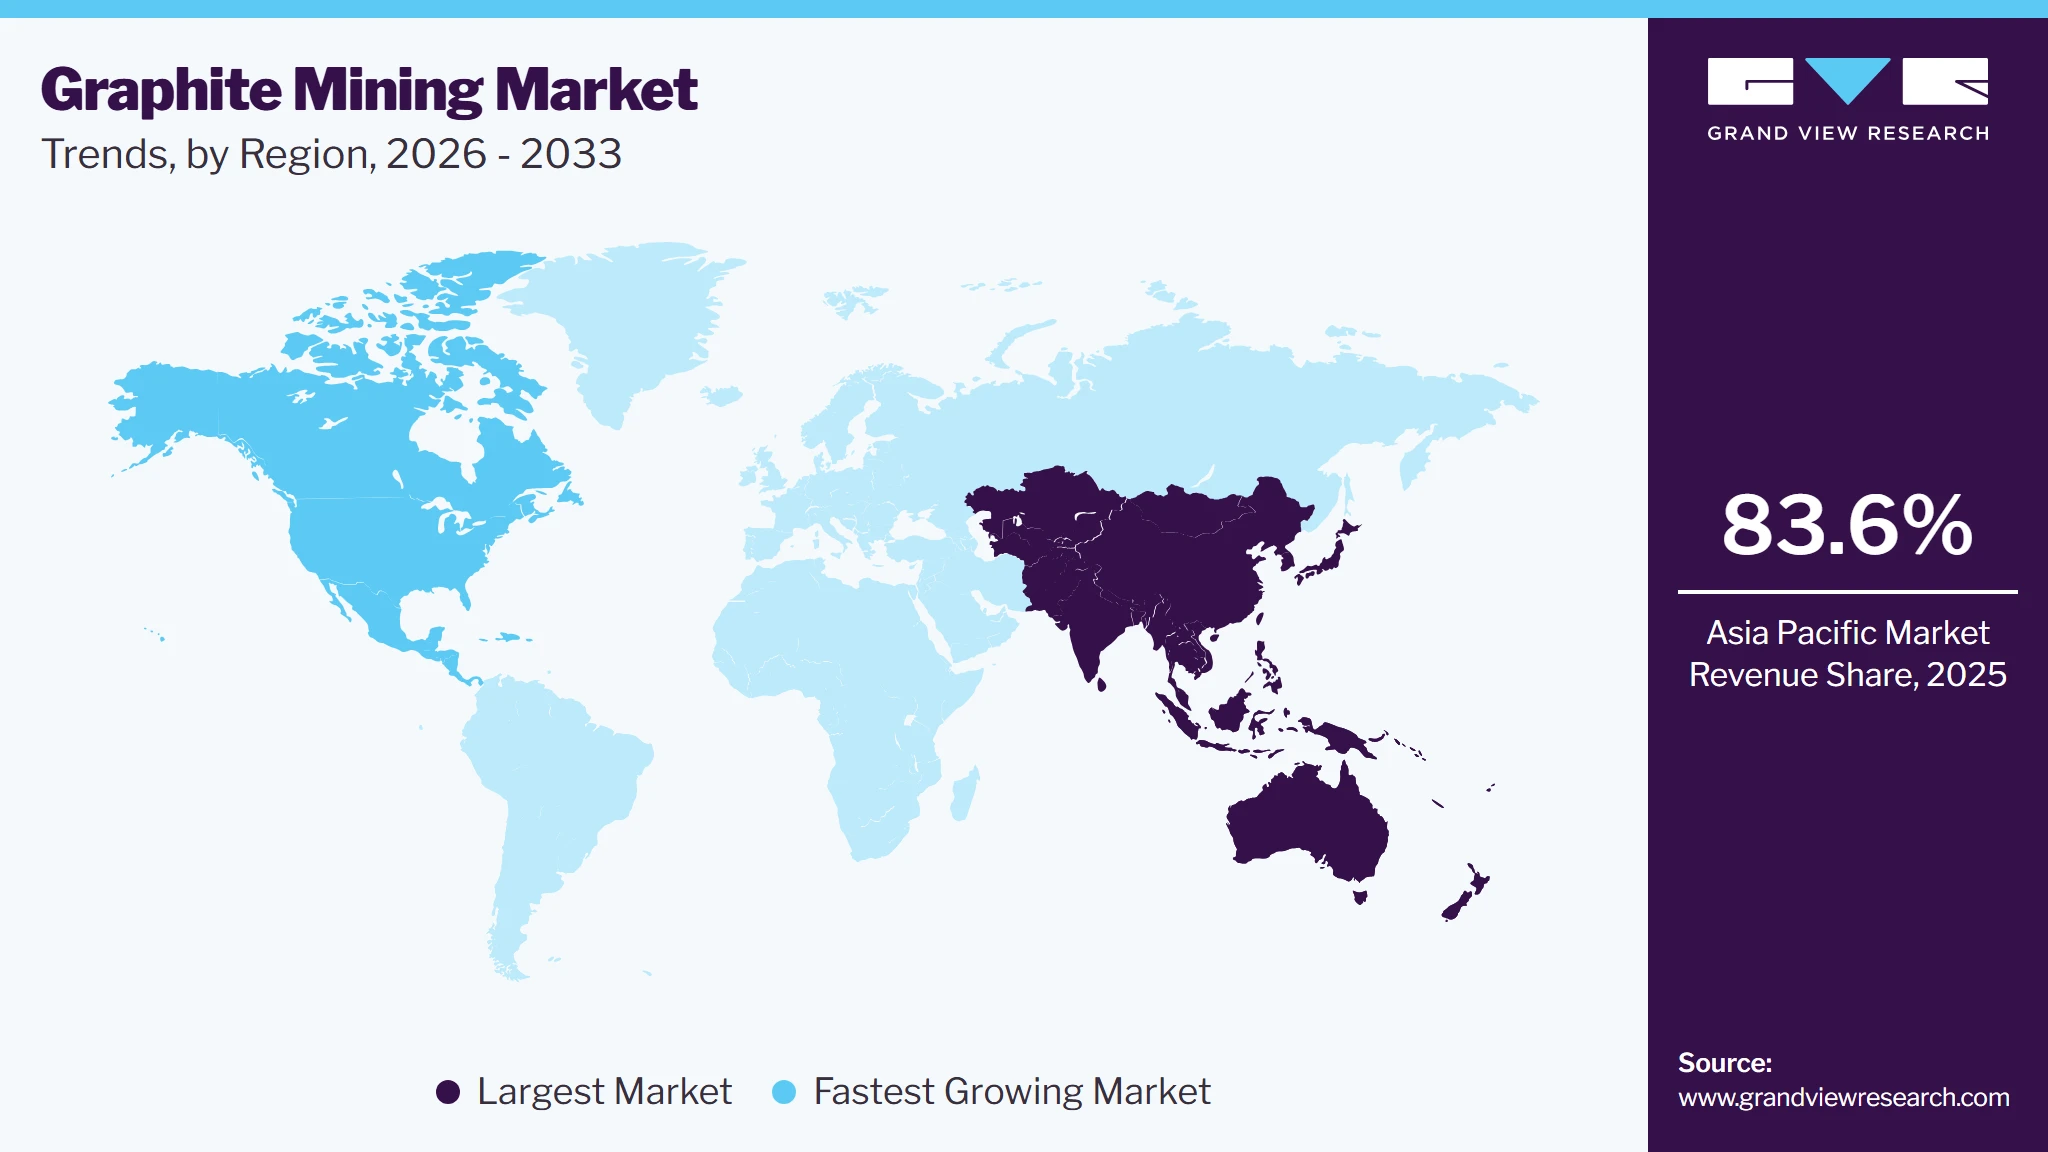
- Largest regional market: Asia Pacific (83.6% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.8 billion
- Estimated market size in 2026: USD 1.9 billion
- Projected market size by 2033: USD 3.6 billion
- CAGR (2026-2033): 9.6%
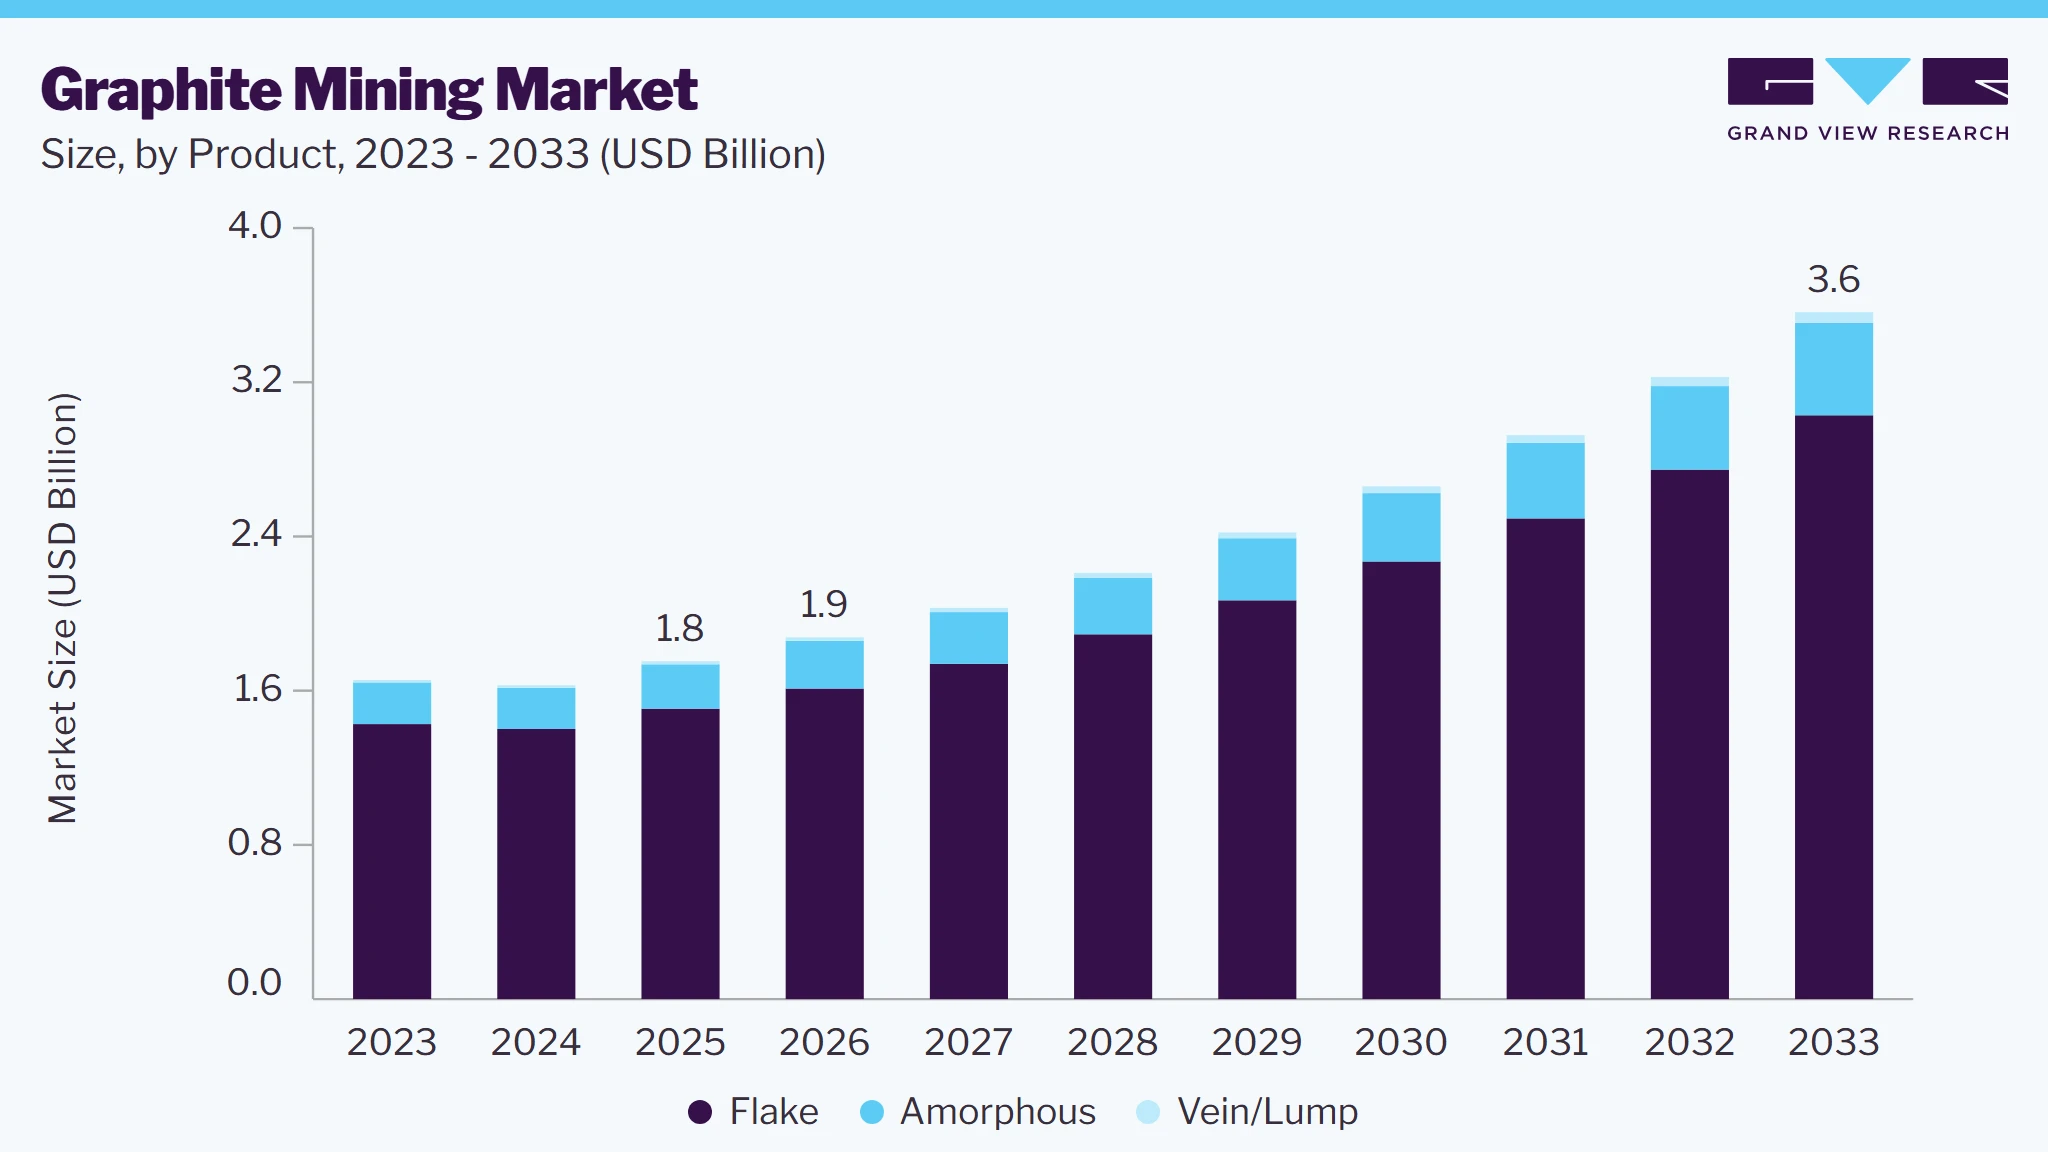
Prism AI by Grand View Research Free to tryAsk a question about the graphite mining marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The market is being shaped by increasing demand for natural graphite across battery manufacturing, steelmaking, refractories, foundries, and other industrial applications. Technological advancements in mining, beneficiation, and graphite purification are improving extraction efficiency, mineral recovery, and product quality. Natural flake graphite is gaining importance due to its suitability for lithium-ion battery anodes, while amorphous and vein/lump varieties continue to support specialized industrial applications.
 To learn more about this report, Download Free Sample Report
From a sustainability perspective, responsible graphite extraction and processing are becoming increasingly important as demand for natural graphite expands across industrial and energy storage applications. Mining companies are focusing on improving resource utilization, reducing energy and water consumption, managing mining waste, and minimizing land disturbance throughout extraction and beneficiation activities. However, environmental challenges persist, particularly regarding tailings disposal, chemical use during purification, water management, and rehabilitation of mined land. Market participants are increasingly investing in cleaner processing technologies, renewable energy integration, improved waste management, and responsible mining practices to reduce environmental impacts, improve operational efficiency, and strengthen the long-term sustainability of graphite production.
Market Dynamics
The growing adoption of electric vehicles and the expansion of renewable energy storage systems are major factors supporting demand for natural graphite. Graphite is a critical anode material in conventional lithium-ion batteries due to its electrical conductivity, electrochemical stability, and ability to support repeated charging and discharging cycles. Increasing investments in battery manufacturing facilities, particularly across China, North America, and Europe, are strengthening requirements for natural and synthetic graphite. Furthermore, the development of silicon-graphite anode technologies is creating additional opportunities by improving battery energy density while retaining graphite's established role in anode formulations.
Additionally, rising investments in renewable energy projects and grid-scale battery storage installations are supporting long-term consumption. The increasing integration of solar and wind power into electricity networks requires efficient energy storage solutions to manage intermittent power generation and maintain grid stability. This is encouraging battery manufacturers to expand production capacities and secure reliable supplies of high-quality graphite. Government initiatives promoting electric mobility, domestic battery manufacturing, and critical mineral supply-chain diversification are encouraging investments in mining and processing projects, thereby supporting the expansion of extraction capacities across major producing regions.
Environmental challenges, processing complexity, and geographical concentration of production continue to constrain the market expansion. Natural graphite extraction can result in land disturbance, water consumption, and waste generation, while the conversion of mined graphite into battery-grade spherical purified graphite involves energy-intensive processing and chemical purification. Additionally, China's dominant position in natural graphite mining and downstream processing creates supply-chain vulnerabilities for battery manufacturers in other regions. Export restrictions, trade policy changes, environmental regulations, and fluctuations in raw material availability can further affect procurement costs and supply continuity.
As governments and battery makers look to diversify critical mineral supply chains, new opportunities are opening up in graphite mining and processing outside China. Countries like Mozambique, Madagascar, Tanzania, Brazil, Canada, and Australia are drawing investment in natural graphite extraction and downstream processing. The rising demand for battery-grade spherical graphite, along with more investment in purification and anode material manufacturing, is giving vertically integrated mining companies more chances to grow.
Analyst Perspective
The graphite mining market is evolving with increasing demand for natural graphite across battery manufacturing, steelmaking, refractories, foundries, and other industrial applications. The growing adoption of electric vehicles and expansion of renewable energy storage systems are strengthening requirements for high-quality flake graphite, while amorphous and vein/lump varieties continue to serve specialized industrial applications. China remains a significant production and processing hub. However, fluctuations in graphite prices, environmental regulations, mining costs, processing requirements, and geographical concentration of production continue to influence market dynamics.
Product Insights
Flake accounted for the largest revenue share of 85.9% in 2025 and is expected to register strong growth over the forecast period, driven by its increasing consumption in lithium-ion battery anodes and other energy storage applications. This grade is widely preferred for battery manufacturing due to its crystalline structure, electrical conductivity, and suitability for conversion into spherical purified graphite. The rapid expansion of electric vehicle production, coupled with increasing investments in battery manufacturing facilities and advanced anode technologies, is strengthening demand.
Vein/lump graphite is projected to grow at a CAGR of 16.7% over the forecast period, supported by its increasing utilization in specialized industrial applications requiring high purity, crystallinity, and electrical conductivity. It is used in high-performance lubricants, electrical components, refractory products, and selected specialty applications. Additionally, its role as a reducing agent in certain metallurgical processes and as an input in the production of specialty metals and high-performance materials is supporting demand.
Application Insights
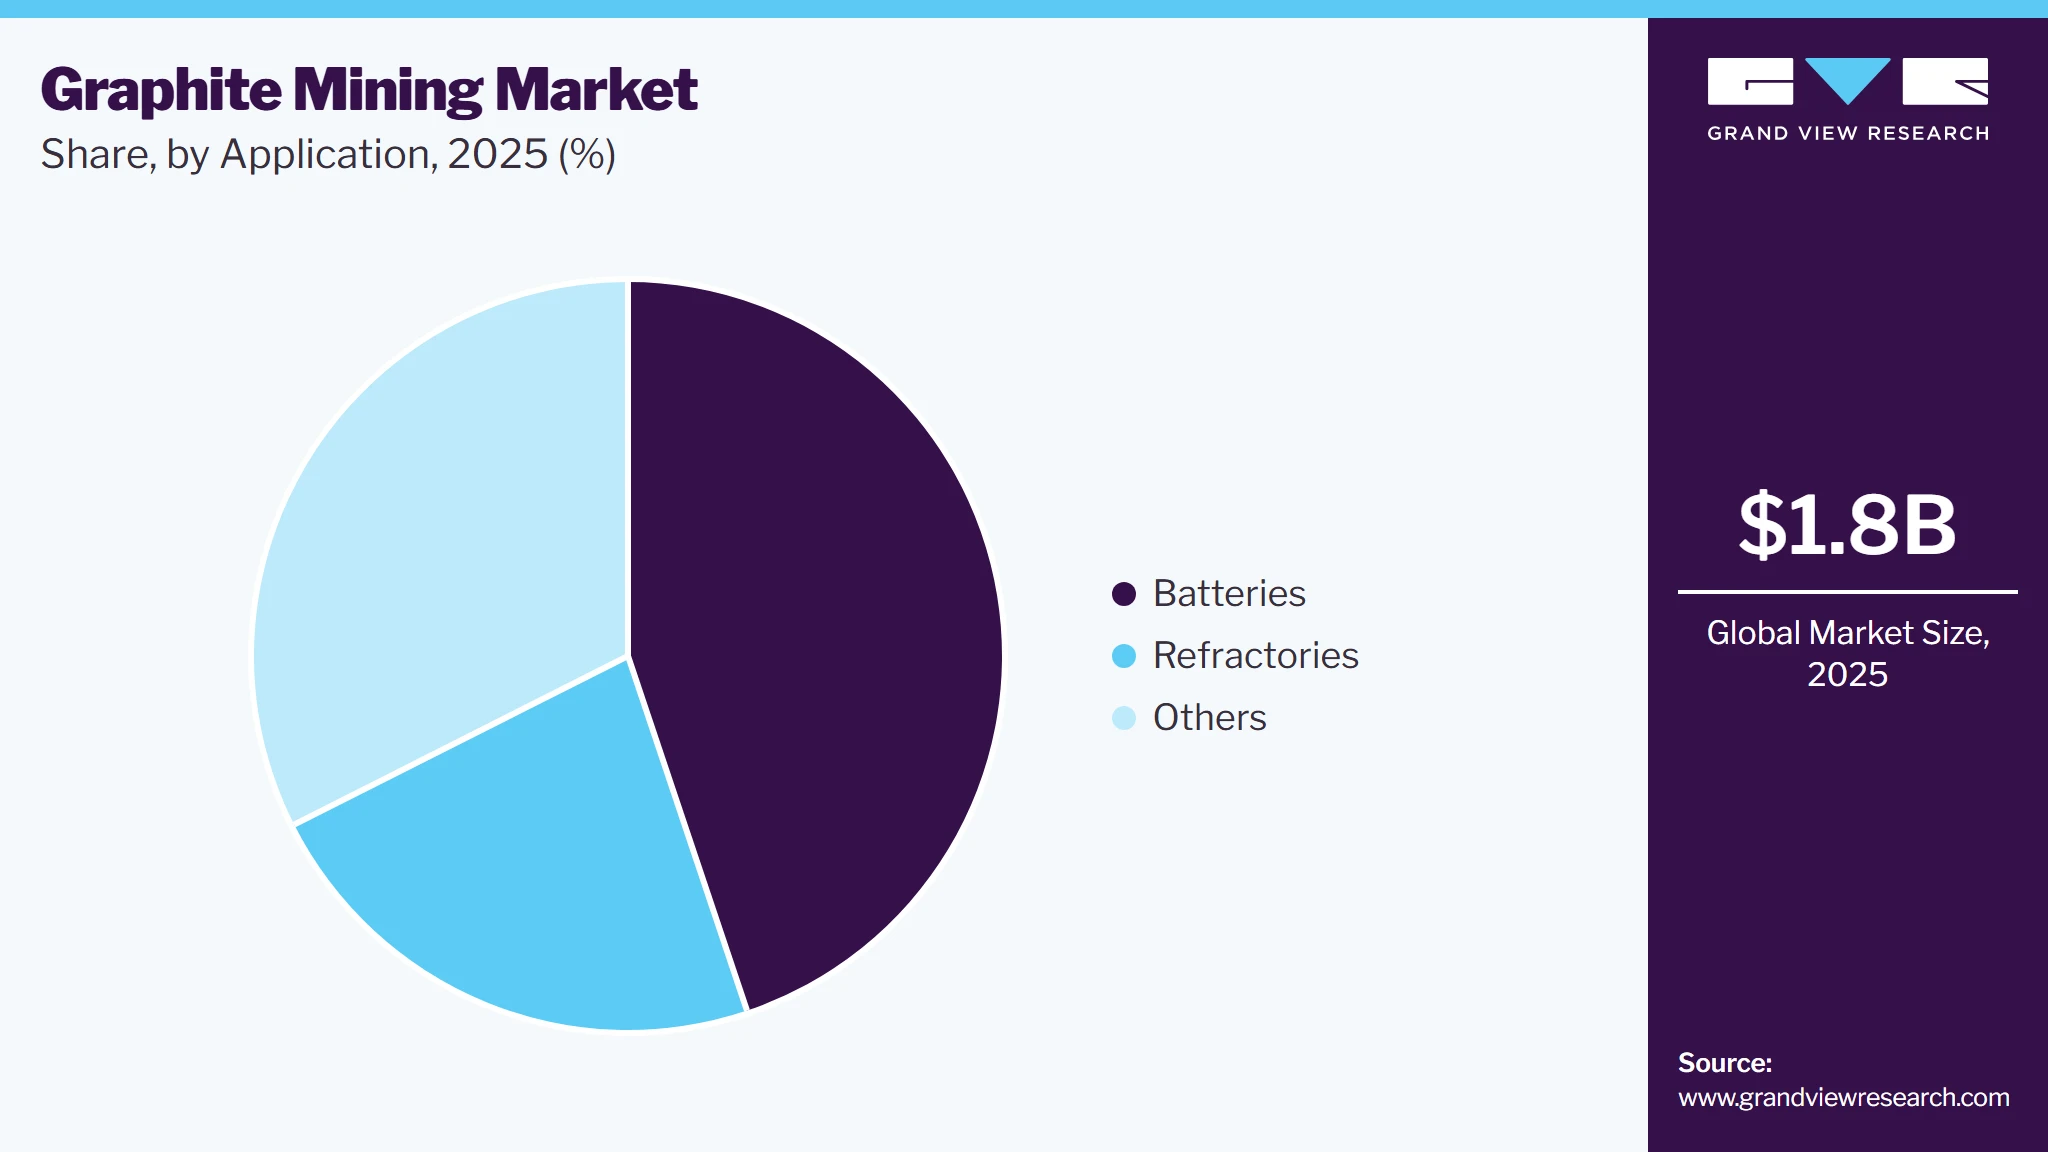
The batteries segment is anticipated to register the fastest CAGR of 9.7% from 2026 to 2033, driven by the increasing adoption of graphite in lithium-ion battery anodes for electric vehicles and energy storage systems. Rising investments in battery manufacturing, coupled with the expansion of electric vehicle production and renewable energy storage installations, are strengthening consumption. Furthermore, advancements in silicon-graphite anode formulations and selected next-generation battery architectures are creating additional opportunities. Increasing demand for high-purity flake graphite and improvements in purification and processing technologies are also supporting the development of battery-grade materials.
 To learn more about this report, Download Free Sample Report
In 2025, the refractories segment captured a significant revenue share, driven by the widespread use of natural graphite in steelmaking, foundries, and high-temperature industrial processes. Its thermal conductivity, high-temperature resistance, and chemical stability make it ideal for refractory bricks, crucibles, magnesia-carbon refractories, and furnace linings. Rising steel production, especially from electric arc furnace operations, continues to drive demand in refractory applications.
Regional Insights
North America Graphite Mining Market Trends
In North America, demand is supported by investments in electric vehicle manufacturing, lithium-ion battery production, and renewable energy storage systems. The growing focus on developing domestic sources of natural graphite and battery-grade processing capabilities is encouraging investments in mining projects across the region. Automotive manufacturers and battery developers are increasingly securing long-term supplies of graphite to strengthen supply chain resilience. Government initiatives promoting critical mineral development and local battery manufacturing are expected to create additional opportunities for mining companies and material suppliers.
Canada Graphite Mining Market Trends
In Canada, increasing investments in natural graphite extraction, mineral processing, and battery material manufacturing are supporting market growth. The country's substantial graphite resources, particularly in Quebec and Ontario, provide opportunities to expand domestic mining and strengthen its position in the global battery supply chain. Growing electric vehicle production and investments in energy storage systems are increasing demand for high-purity graphite used in lithium-ion battery anodes.
Europe Graphite Mining Market Trends
Across Europe, the transition toward low-emission transportation and the expansion of battery manufacturing capabilities are creating opportunities for natural graphite suppliers. Automotive manufacturers and battery producers are increasingly focusing on securing reliable supplies of battery-grade materials to support electric vehicle production. Investments in domestic extraction, graphite purification, and anode manufacturing are also gaining importance as countries seek to reduce dependence on imported materials.
Asia Pacific Graphite Mining Market Trends
Asia Pacific dominated the graphite mining market with the largest revenue share of 83.6% in 2025. In Asia Pacific, an established battery manufacturing base, expanding electric vehicle production, and strong industrial consumption underpin demand. The presence of major graphite producers, battery manufacturers, and anode material suppliers supports regional extraction and downstream processing activities. Increasing investments in high-purity graphite production, spherical purification, and advanced anode technologies are strengthening the region's position within the global battery supply chain. Furthermore, government initiatives promoting electric mobility, renewable energy storage, and domestic critical mineral development are expected to support continued industrial expansion.
 To learn more about this report, Download Free Sample Report
China Graphite Mining Market Trends
In China, extensive natural graphite production, established processing infrastructure, and an integrated battery manufacturing ecosystem support its leading position in the market. The country has a strong presence across graphite extraction, purification, spherical processing, and anode material manufacturing, supplying domestic battery producers as well as international customers. Increasing electric vehicle production and investments in energy storage systems are further strengthening consumption.
Latin America Graphite Mining Market Trends
Across Latin America, growing interest in critical mineral development and the expansion of battery material supply chains are creating opportunities for natural graphite producers. Brazil represents an important regional source of natural graphite, supported by its mineral resources and established mining activities. Increasing investments in mineral processing, infrastructure development, and industrial manufacturing could strengthen the region's participation in international supply chains.
Middle East & Africa Graphite Mining Market Trends
In the Middle East & Africa region, investments in industrial diversification, renewable energy, and electric mobility are creating emerging opportunities. Middle Eastern countries are exploring battery manufacturing and critical mineral processing as part of broader economic diversification and clean energy strategies. In Africa, countries such as Mozambique, Madagascar, and Tanzania have significant natural graphite production potential and are attracting investments in mining and processing projects.
Key Graphite Mining Company Insights
Some of the key players operating in the market include China Graphite Group Limited, Heilongjiang Hagong Carbon-based Materials Technology Co., Ltd., and others.
-
China Graphite Group Limited is a China-focused graphite mining and processing company established in 2021, with operations in Heilongjiang Province. The company operates through its subsidiaries, Heilongjiang Baoquanling Farmland Yixiang Graphite Company Limited and Yixiang New Energy Materials Company Limited and holds mining rights to the Beishan Graphite Mine in Luobei County, where extraction commenced in 2019. Its product portfolio includes natural flake graphite concentrate, spherical graphite, and other processed graphite products, primarily used in lithium-ion battery anodes, refractories, metallurgy, and industrial applications.
-
Heilongjiang Hagong Carbon-based Materials Technology Co., Ltd. is a Chinese graphite mining and advanced carbon materials company established in 2018 and headquartered in Jixi, Heilongjiang Province. The company has developed an integrated operating structure through subsidiaries involved in natural graphite mining, beneficiation, and downstream processing, including Guorun Mining, which holds mining rights to the Ping'an Graphite Mine in Jixi, and Hagong Graphite, which owns the Liangzhongchang Graphite Mine in Mishan.
-
Nacional de Grafite Ltd. is a Brazilian company established in 1939, specializing in the mining, beneficiation, and processing of natural crystalline graphite. The company operates three production facilities in Minas Gerais, Brazil, supported by established mineral extraction and processing infrastructure. Its product portfolio includes natural flake graphite, fine crystalline graphite, expandable graphite, micronized graphite, and specialized graphite grades used in refractories, metallurgy, steelmaking, foundries, lubricants, polymers, agriculture, and energy storage applications.
Key Graphite Mining Companies
The following key companies have been profiled for this study on the graphite mining market.
-
China Graphite Group Limited
-
DH Mining Development Limited
-
Jixi Aoyu Graphite Co., Ltd.
-
Jixi Puchen Graphite Co., Ltd.
-
Longxing Graphite
-
Nacional de Grafite Ltda.
-
Northern Graphite Corporation
-
Qingdao Haida Graphite Co., Ltd.
-
Syrah Resources Limited
-
Walkabout Resources Limited
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Syrah Resources Limited, Nacional de Grafite Ltd., Northern Graphite Corporation, China Graphite Group Limited, Longxing Graphite, Qingdao Haida Graphite Co., Ltd.)
- Expand natural graphite extraction and beneficiation capacities to strengthen production volumes and supply reliability.
- Invest in mining infrastructure, processing technologies, and product quality improvements to meet industrial and battery-grade specifications.
- Establish long-term supply agreements and strategic partnerships with battery manufacturers, refractory producers, steelmakers, and industrial customers.
- Strengthen geographical diversification and downstream integration to improve supply-chain control and revenue realization.
- Established mining operations, access to natural graphite deposits, and experience in extraction and beneficiation.
- Existing customer relationships across battery manufacturing, steelmaking, refractories, and industrial applications.
- Technical capabilities in graphite concentration, purification, and product customization.
- Greater production experience and established distribution networks compared with early-stage developers.
- High capital requirements for mine development, infrastructure, and processing facilities.
- Exposure to fluctuations in natural graphite prices and changing demand from battery and industrial customers.
- Environmental regulations, mining permits, and processing requirements can increase operating costs.
- Geographical concentration of mining and processing activities creates supply-chain risks.
Emerging & Regional Players (e.g., DH Mining Development Limited, Jixi Aoyu Graphite Co., Ltd., Jixi Puchen Graphite Co., Ltd., Walkabout Resources Limited)
- Develop new graphite mining projects and expand regional extraction and processing capabilities.
- Focus on specific graphite deposits and product grades to serve regional industrial and battery material customers.
- Invest selectively in beneficiation, infrastructure, and production efficiency to improve commercial viability.
- Establish partnerships with international buyers, distributors, and downstream graphite processors to secure offtake opportunities.
- Access to regionally concentrated natural graphite deposits and opportunities to develop new mining assets.
- Flexibility to target specific graphite grades and customized customer requirements.
- Potential to benefit from growing demand for diversified natural graphite supply outside established producing regions.
- Opportunities to develop operations with modern mining and processing technologies.
- Limited operating scale and production history compared with established producers.
- High initial investment requirements for mine development, processing infrastructure, and logistics.
- Dependence on financing, regulatory approvals, infrastructure availability, and customer qualification.
- Exposure to graphite price volatility and uncertainty regarding the commercial ramp-up of new projects.
Recent Development
-
In October 2026, Syrah Resources Limited reported that its Balama Graphite Operation in Mozambique produced 19.3 thousand tons of natural graphite during a production campaign in the September quarter. The company also continued ramping up commercial operations at its Vidalia active anode material facility in the U.S. to build saleable inventory, with initial commercial sales targeted for the December 2026 quarter, subject to customer qualification.
-
In September 2026, Northern Graphite Corporation filed an appeal with the Court of Quebec challenging the suspension of the mining lease for its Lac des Iles graphite mine in Quebec, Canada. The suspension was related to an outstanding payment associated with an increased financial guarantee for future site restoration. The appeal temporarily stayed the suspension pending a final court decision, allowing the mining lease to remain in effect during the proceedings.
-
In January 2026, DH Mining Development Limited commenced a significant expansion of graphite processing activities in Mozambique with the inauguration of a new processing facility at its Nipepe graphite mining project. The facility has an annual processing capacity of approximately 200,000 tonnes and represents an investment of around USD 200 million. The project is part of Mozambique's efforts to increase domestic mineral beneficiation and move beyond exporting unprocessed graphite.
Graphite Mining Market Report Scope
Report Attribute
Details
Market Definition
The graphite mining market size represents the annual value of natural graphite (crystalline flake, amorphous and vein/lump) extracted through mining activities worldwide. Synthetic graphite is excluded.
Market size in 2025
USD 1.8 billion
Estimated market size in 2026
USD 1.9 billion
Projected market size by 2033
USD 3.6 billion
Growth Rate
CAGR of 9.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative Units
Revenue in USD million, volume in tons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country scope
Canada; Mexico; Russia; Turkey; Norway; China; India; Brazil; Madagascar; Mozambique; Tanzania
Key companies profiled
China Graphite Group Limited, DH Mining Development Limited, Jixi Aoyu Graphite Co., Ltd., Jixi Puchen Graphite Co., Ltd., Longxing Graphite, Nacional de Grafite Ltda., Northern Graphite Corporation, Qingdao Haida Graphite Co., Ltd., Syrah Resources Limited, Walkabout Resources Limited
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Graphite Mining Market Report Segmentation
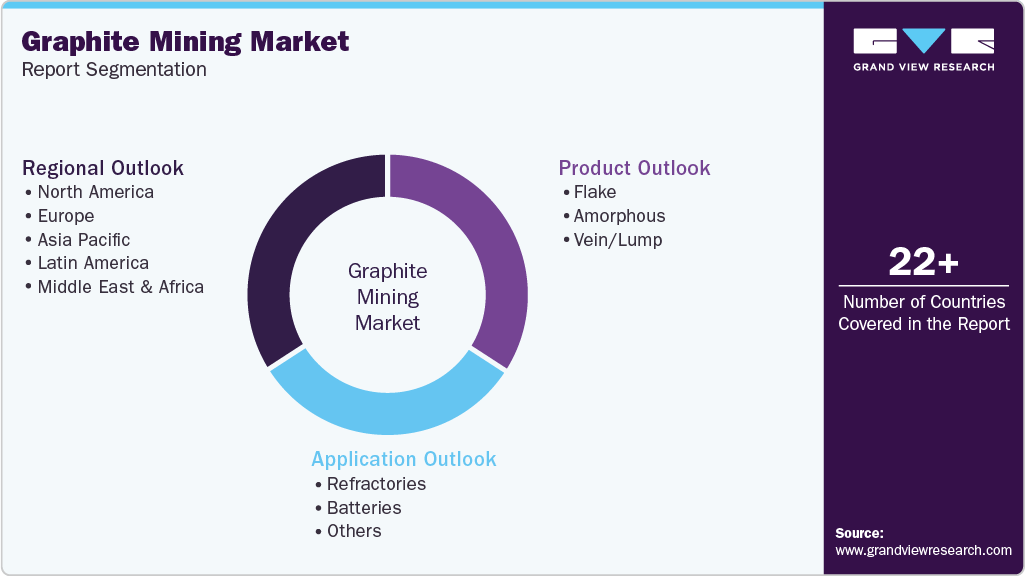
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global graphite mining market report on the basis of application, product, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Tons; Revenue, USD Million; 2021 - 2033)
-
Flake
-
Amorphous
-
Vein/Lump
-
-
Application Outlook (Volume, Tons; Revenue, USD Million; 2021 - 2033)
-
Refractories
-
Batteries
-
Others
-
-
Regional Outlook (Volume, Tons; Revenue, USD Million; 2021 - 2033)
-
North America
-
Canada
-
Mexico
-
-
Europe
-
Russia
-
Turkey
-
Norway
-
-
Asia Pacific
-
China
-
India
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Madagascar
-
Mozambique
-
Tanzania
-
-
Research Methodology
The graphite mining market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each graphite mining segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue Capture Definition
Flake
The flake segment captures revenue generated from natural flake graphite mining and the sale of graphite concentrates used in lithium-ion battery anodes, refractory products, foundries, lubricants, and other industrial applications. Demand is supported by electric vehicle manufacturing, energy storage installations, and increasing requirements for high-purity graphite.
Amorphous
The amorphous segment represents revenue generated from the extraction and sale of fine-grained natural graphite used in refractories, foundries, lubricants, friction materials, pencils, and metallurgical applications.
Vein/Lump
The vein/lump segment captures revenue generated from naturally occurring high-purity graphite extracted from vein deposits. It is used in specialized applications, including high-performance lubricants, electrical components, refractory products, crucibles, and battery-related materials.
Application
Revenue Capture Definition
Refractories
The refractories segment captures revenue generated from natural graphite mining used in refractory bricks, magnesia-carbon bricks, crucibles, furnace linings, and other high-temperature materials.
Batteries
The batteries segment represents revenue generated from natural graphite mining used as an anode material or feedstock for battery-grade graphite in lithium-ion batteries. Its applications include electric vehicles, consumer electronics, industrial batteries, and stationary energy storage systems.
Others
The others segment includes revenue generated from natural graphite mining used in lubricants, foundries, friction products, pencils, conductive materials, carbon brushes, expandable graphite, and other industrial applications not covered under the primary categories.
Estimation Model
Layer Name
Key Question
Description
Graphite Resource & Mining Assessment Layer
Where is natural graphite available and extracted?
Assess global natural graphite reserves, identified deposits, geological characteristics, mining locations, and extraction potential. Evaluate major producing countries, including China, Mozambique, Madagascar, Brazil, India, and Tanzania. Examine operating mines, production capacities, mining methods, project development timelines, and planned capacity expansions to establish the global supply base.
Mine Production & Processing Assessment Layer
How much graphite is produced and recovered?
Evaluate annual mined graphite production, processing capacity, beneficiation techniques, and recovery rates across major mining operations. Assess differences between flake, amorphous, and vein/lump graphite, considering ore grades, carbon content, particle-size distribution, processing losses, and product quality. Account for mine utilization, operational interruptions, capacity additions, and commissioning of new mining projects to estimate saleable graphite concentrate volumes.
Graphite Consumption & Trade Assessment Layer
Where is mined graphite consumed and traded?
Estimate natural graphite consumption across refractories, batteries, foundries, lubricants, steelmaking, and other industrial applications. Analyze domestic production, imports, exports, inventory movements, and cross-border trade flows to determine apparent consumption by country and region. Evaluate demand for different graphite grades and product forms, alongside battery manufacturing expansion, steel production, and industrial activity to allocate consumption across applications.
Revenue Estimation & Forecasting Layer
How is mining revenue generated and projected?
Calculating revenue generated from the sale of natural graphite concentrates using annual production volumes and average selling prices differentiated by graphite type, carbon content, particle size, and product specifications. Benchmark pricing against published natural graphite concentrate assessments and available company disclosures. Develop historical estimates and forecasts by product, application, country, and region, incorporating mine capacity expansions, production costs, supply-demand balances, price fluctuations, and new project commissioning.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Natural Graphite Raw Material Cost and Price Sensitivity
Comparison of natural graphite prices across selected countries and regions, considering product type (flake, amorphous, and vein/lump), carbon content, particle size, product grade, mining and beneficiation costs, import duties, transportation, and handling expenses. The analysis evaluates domestic versus imported supply, regional price differences, landed costs, and the impact of supply-demand fluctuations on selling prices.
Supports procurement planning, cost benchmarking, pricing strategies, and assessment of exposure to raw material price volatility. Helps identify cost-efficient sourcing destinations and potential supply-chain risks.
Graphite Trade Flow and Regional Supply Chain Analysis
Country-level analysis of natural graphite production, imports, exports, major trading partners, HS code classifications, trade restrictions, tariffs, and transportation routes. The study compares domestic production with imported supply and identifies major exporters, importing countries, and regional supply dependencies.
Supports international sourcing strategies, trade risk assessment, identification of alternative suppliers, and evaluation of regional supply-chain vulnerabilities.
Global Graphite Mining Project Pipeline and Capacity Assessment
Assessment of operating, planned, and under-development natural graphite mining projects across major producing countries. The analysis covers project locations, ownership, estimated reserves and resources, annual production capacity, commissioning schedules, expansion plans, mining methods, and expected saleable graphite output.
Helps identify upcoming supply sources, assess future production availability, evaluate competitive positioning, and understand potential supply-demand imbalances. Supports investment decisions and long-term sourcing strategies.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


