
- Home
- »
- Clinical Diagnostics
- »
-
Guillain-Barre Syndrome Diagnostics Market Report, 2033GVR Report cover

Guillain-Barre Syndrome Diagnostics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Test (Lumbar Puncture, Electromyography, Nerve Conduction Studies), By End Use (Hospitals and Clinics, Diagnostic Laboratories), By Region, And Segment Forecasts
Market Size, 2025
$148.1MMarket Estimate, 2026
$151.9MMarket Forecast, 2033
$186.8MCAGR, 2026–2033
3.0%Guillain-Barre Syndrome Diagnostics Market Summary
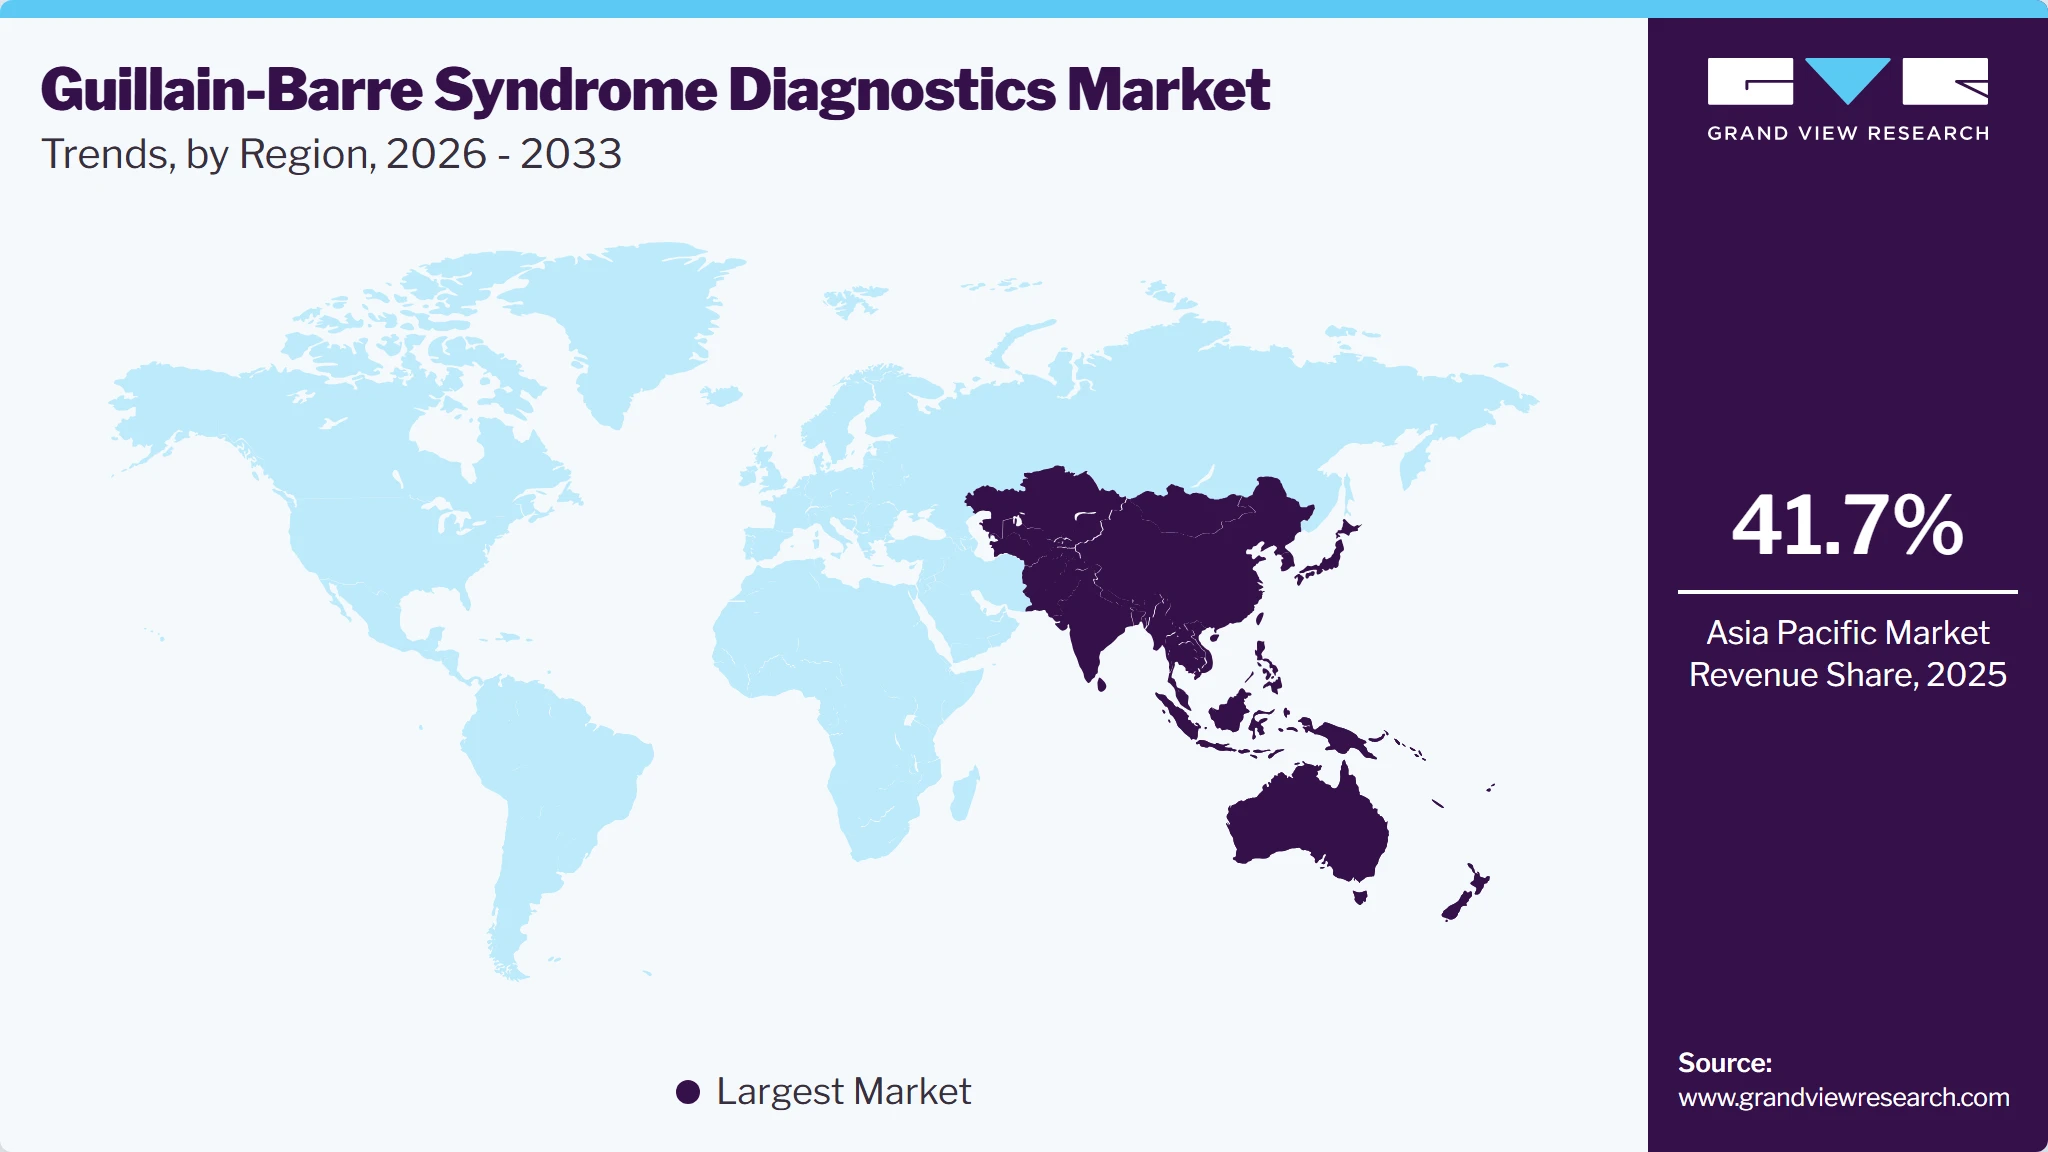
The global guillain-barre syndrome diagnostics market size was valued at USD 148.1 million in 2025 and is projected to grow from USD 151.9 million in 2026 to USD 186.8 million by 2033, at a CAGR of 3.0% from 2026 to 2033. The Asia Pacific market dominated with a revenue share of 41.7% in 2025. The global market growth is driven by the increasing incidence of Guillain-Barré syndrome (GBS), growing awareness of early diagnosis, and wider adoption of electrodiagnostic techniques such as nerve conduction studies (NCS) and electromyography (EMG) for accurate disease assessment.
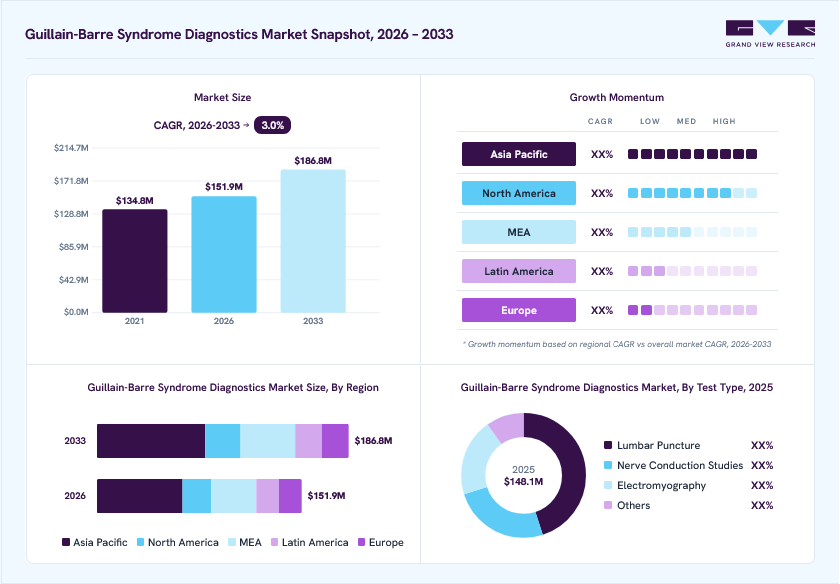 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
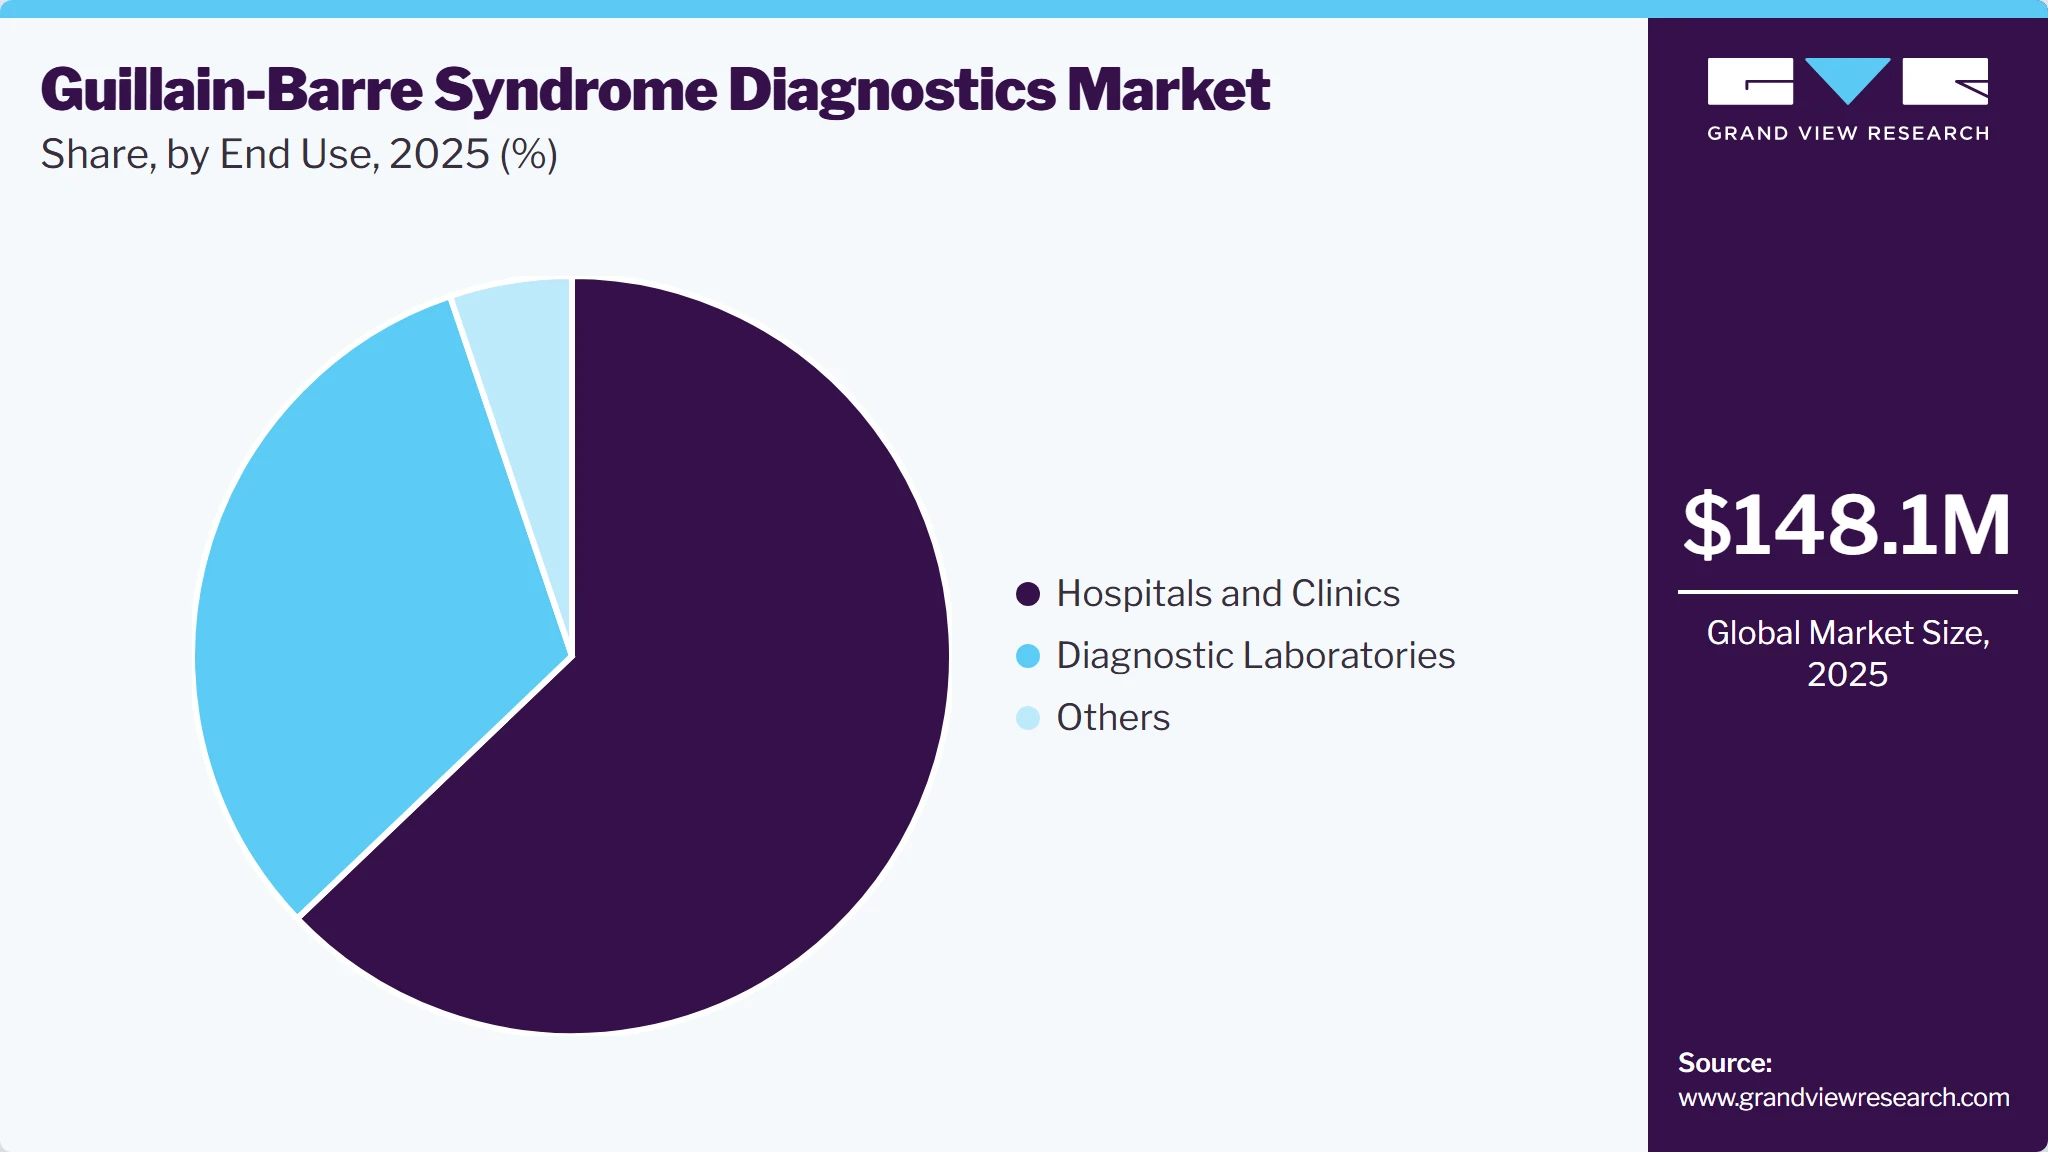
- By end use: Hospitals and clinics segment held the largest market share of 62.9% in 2025.
- By test: Lumbar puncture segment held the largest market share of 45.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (41.7% revenue share, 2025)
- By country: India held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 148.1 Million
- Estimated market size in 2026: USD 151.9 Million
- Projected market size by 2033: USD 186.8 Million
- CAGR (2026-2033): 3.0%
Prism AI by Grand View Research Free to tryAsk a question about the Guillain-Barre syndrome diagnostics market✓Every figure cited from GVR research Prefer the report? Download free sample →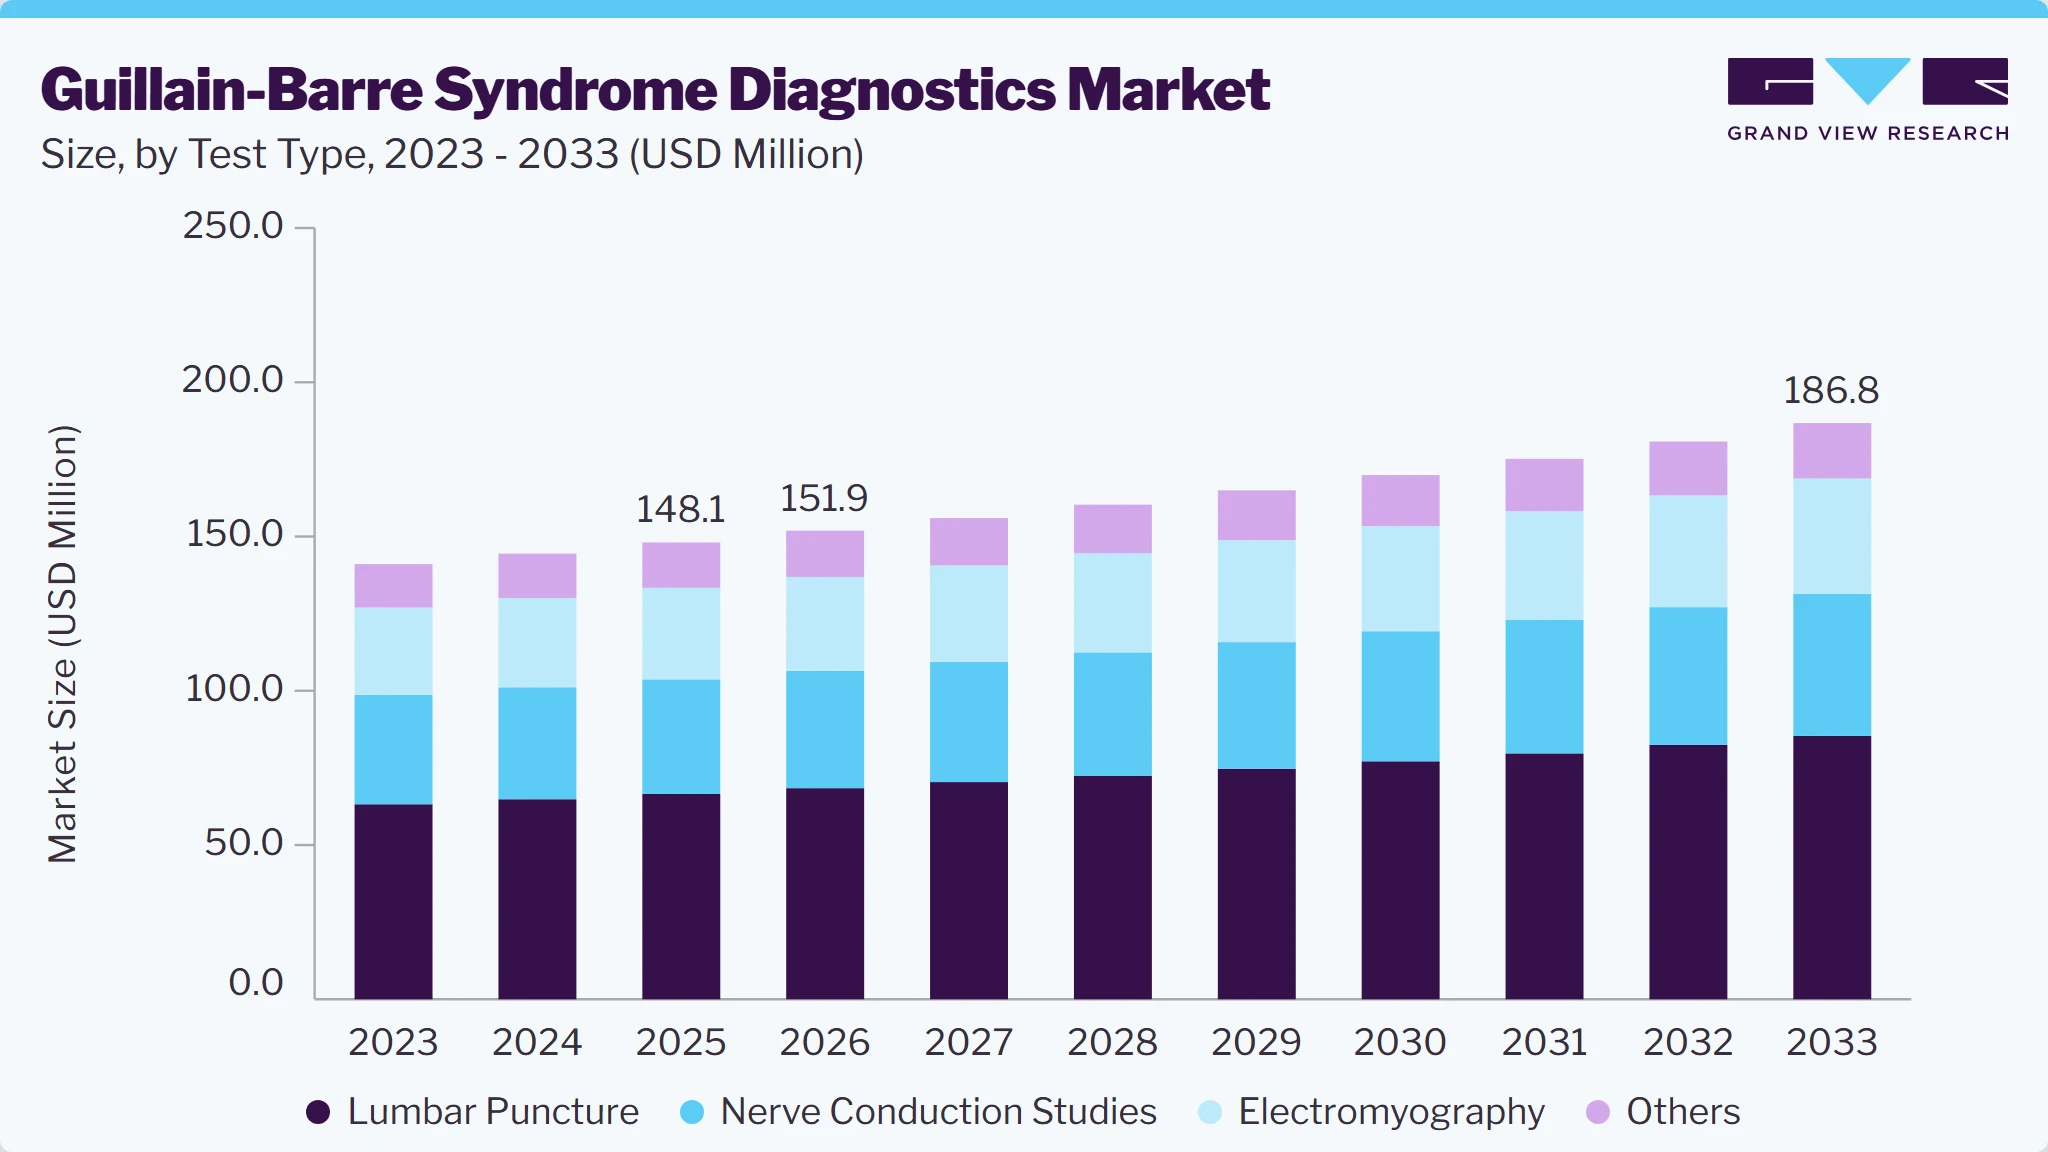 To learn more about this report, Download Free Sample Report
In addition, advancements in neuromuscular diagnostic technologies, including integrated EMG-ultrasound systems and enhanced laboratory testing for autoimmune neuropathies, are improving diagnostic efficiency and supporting market expansion.Market Dynamics
The growing adoption of integrated neurodiagnostic technologies is driving the Guillain-Barré syndrome diagnostics industry by improving the efficiency and accuracy of peripheral nerve disorder evaluation. Healthcare providers are increasingly seeking diagnostic platforms that combine complementary modalities to support comprehensive neurological assessment while reducing diagnostic complexity. The integration of imaging and electrophysiological testing enhances clinical confidence, facilitates earlier diagnosis, and improves workflow efficiency in hospitals and specialized neurology centers. Manufacturers are responding by expanding their neurodiagnostic portfolios with integrated solutions that address evolving clinical requirements. For instance, in April 2025, Natus Medical integrated the InVisus Pro Neuromuscular Ultrasound platform with its Elite EMG software, enabling clinicians to perform neuromuscular ultrasound alongside electromyography and nerve conduction studies within a unified workflow. This advancement supports more comprehensive evaluation of peripheral nerve disorders, reinforcing the adoption of advanced neurodiagnostic systems and contributing to the growth of the Guillain-Barré syndrome diagnostics industry.
The Guillain-Barré syndrome diagnostics industry is restrained by the complexity of accurately diagnosing the condition during its early stages. Initial symptoms such as muscle weakness, tingling, and numbness often overlap with those of other neurological disorders, making clinical differentiation challenging. Confirmation typically requires multiple diagnostic procedures, including nerve conduction studies, electromyography, and cerebrospinal fluid analysis, which may not be readily available in all healthcare settings. Limited access to specialized neurodiagnostic equipment and trained neurologists, particularly in resource constrained regions, can further delay diagnosis and treatment. In addition, the absence of a single definitive diagnostic test increases reliance on comprehensive clinical evaluation, which may lead to variability in diagnostic timelines. These factors can limit the adoption of advanced diagnostic technologies and pose challenges to the consistent growth of the Guillain-Barré syndrome diagnostics industry.
The increasing adoption of integrated neurodiagnostic technologies presents a significant opportunity for the Guillain-Barré syndrome diagnostics industry. Healthcare providers are seeking comprehensive diagnostic solutions that combine complementary modalities to improve diagnostic confidence, enhance workflow efficiency, and support timely evaluation of peripheral nerve disorders. The integration of electrophysiological testing with advanced imaging technologies enables clinicians to obtain more comprehensive neurological assessments while reducing procedural complexity. This trend is expected to encourage greater investment in next generation neurodiagnostic platforms across hospitals and specialized neurology centers. For instance, in April 2025, Cadwell Industries launched the latest Sierra software release featuring fully synchronized electromyography and neuromuscular ultrasound capabilities, enabling real time integration of electrophysiological data and ultrasound imaging on a single platform. The product launch reflects the industry's focus on integrated diagnostic solutions and creates opportunities for broader adoption of advanced neurodiagnostic technologies in the Guillain-Barré syndrome diagnostics industry.
Market Concentration & Characteristics
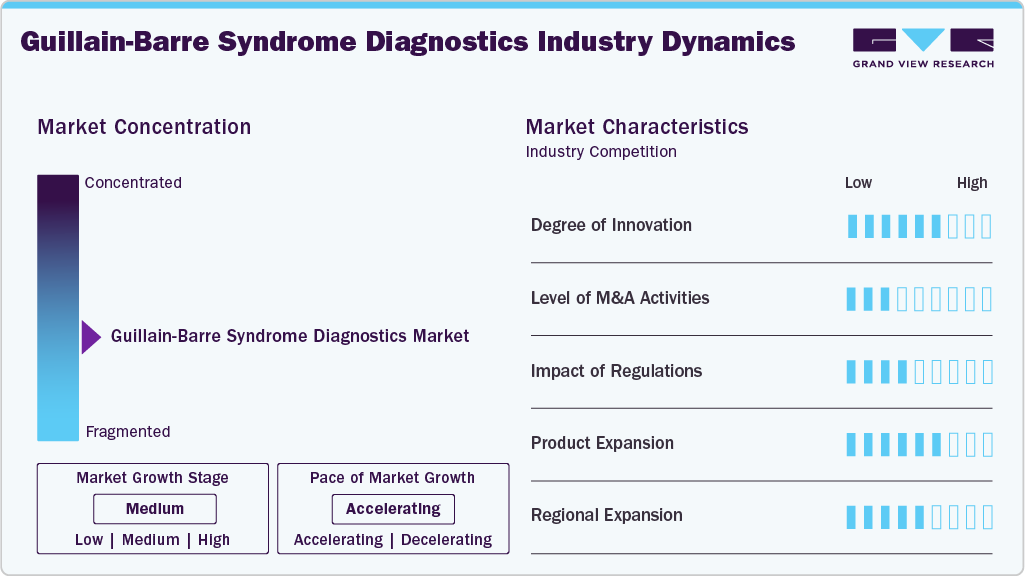
The Guillain-Barré syndrome (GBS) diagnostics industry is characterized by moderate innovation, with technological advancements focused on enhancing electrodiagnostic systems, biomarker-based laboratory testing, and integrated neurological diagnostic workflows rather than the development of disease-specific diagnostic assays. Market participants are prioritizing solutions that improve diagnostic accuracy, enable earlier disease detection, and optimize the evaluation of peripheral neuropathies through advanced laboratory and neurodiagnostic technologies. For instance, in March 2025, Mayo Clinic Laboratories and Amprion announced a strategic collaboration to expand access to advanced cerebrospinal fluid (CSF)-based neurological diagnostic testing, strengthening biomarker-driven neurology diagnostics and enhancing laboratory capabilities for the assessment of neurological disorders, including Guillain-Barré syndrome. Such developments are expected to support incremental innovation and improve the efficiency of neurological diagnostic pathways.
The market is characterized by a low level of merger and acquisition activity, primarily due to its niche clinical focus and reliance on well-established diagnostic modalities such as nerve conduction studies (NCS), electromyography (EMG), and cerebrospinal fluid (CSF) analysis. Market participants are predominantly focused on strengthening their product portfolios through technological enhancements, strategic collaborations, and incremental innovations rather than pursuing acquisitions specific to GBS diagnostics. Consequently, merger and acquisition activity remains limited, with companies prioritizing the expansion of broader neurological diagnostic capabilities and integrated diagnostic solutions to support improved clinical outcomes and operational efficiency.
 To learn more about this report, Download Free Sample Report
The Guillain-Barre syndrome diagnostics industry is moderately influenced by regulations governing in vitro diagnostic devices, neurodiagnostic equipment, and laboratory testing, ensuring the safety, accuracy, and clinical reliability of diagnostic procedures. Regulatory agencies continue to strengthen standards for diagnostic validation and clinical evidence, supporting the adoption of high-quality diagnostic technologies. For instance, in December 2024, Hansa Biopharma initiated enrollment for a Phase II trial evaluating imlifidase in combination with standard intravenous immunoglobulin (IVIG) therapy for Guillain-Barré syndrome. While the trial is treatment-focused, it is expected to generate clinical evidence that may support improved disease understanding and optimize patient management.
The Guillain Barre syndrome diagnostics industry is characterized by moderate product expansion, with manufacturers focusing on expanding neurodiagnostic portfolios and autoimmune testing capabilities rather than introducing disease-specific diagnostic products. Companies are broadening assay menus and laboratory automation solutions to improve the diagnosis and differential evaluation of peripheral neuropathies. For instance, in February 2026, EUROIMMUN expanded the neurology portfolio of its UNIQO 160 automated immunofluorescence platform by adding nine new indirect immunofluorescence assays, strengthening its serological neurological diagnostics offering. The expansion enhances autoimmune neurology testing capabilities and supports the differential evaluation of neurological disorders, including Guillain Barre syndrome.
The Guillain Barre syndrome diagnostics industry is witnessing limited regional expansion, with companies strengthening their presence by expanding neurological diagnostic portfolios, laboratory networks, and distribution partnerships across emerging markets. These initiatives improve access to advanced diagnostic technologies, enhance testing capabilities, and support earlier diagnosis and management of Guillain Barre syndrome in underserved regions.
Analyst Perspective
The Guillain-Barré syndrome diagnostics industry is expected to witness steady growth, supported by the increasing emphasis on early diagnosis of acute peripheral neuropathies and continuous advancements in neurodiagnostic technologies. The adoption of integrated electromyography and nerve conduction study platforms is improving diagnostic accuracy and clinical workflow efficiency across hospitals and specialized neurology centers. Manufacturers are focusing on product innovation, software enhancements, and strategic collaborations to strengthen their market position. Although the relatively low incidence of Guillain-Barré syndrome (GBS) and dependence on specialized diagnostic infrastructure may limit rapid expansion, ongoing technological advancements and increasing investment in neurological care are expected to support long term market development.
Test Insights
The lumbar puncture segment accounted for the largest revenue share of 45.0% in 2025, driven by its essential role in confirming Guillain Barre syndrome through the detection of albuminocytologic dissociation in cerebrospinal fluid (CSF). The procedure remains a cornerstone of the diagnostic pathway and is routinely performed alongside neurological examination and electrodiagnostic testing to improve diagnostic accuracy and differentiate Guillain Barre syndrome from other acute neuropathies. Its widespread availability in hospital settings and strong recommendation in clinical practice guidelines further support its adoption as a standard diagnostic procedure. In addition, growing awareness of early diagnosis and timely treatment is contributing to the sustained demand for lumbar puncture in the clinical evaluation of suspected GBS cases.
The electromyography segment is expected to show lucrative growth over the forecast period, at a CAGR of 3.0%, owing to its critical role in evaluating nerve and muscle function and confirming Guillain Barre syndrome, particularly in the early stages when clinical findings may be inconclusive. Increasing adoption of advanced EMG systems, integration with neuromuscular ultrasound, and improvements in diagnostic accuracy are further supporting segment growth. For instance, in April 2025, Cadwell Industries introduced a major software update for its Sierra Summit and Sierra NMUS1 EMG systems, adding synchronized electromyography and neuromuscular ultrasound workflows, enhanced reporting capabilities, and advanced Q-Mode analysis. These advancements improve electrodiagnostic efficiency and support more comprehensive evaluation of peripheral nerve disorders, including Guillain Barre syndrome.
End Use Insights
The hospitals and clinics segment accounted for the largest revenue share of 62.9% in 2025, driven by the availability of advanced neurodiagnostic infrastructure, specialized neurology departments, and multidisciplinary care teams capable of managing acute Guillain Barre syndrome cases. Hospitals remain the primary setting for diagnosis due to their access to comprehensive diagnostic procedures, including lumbar puncture, electromyography (EMG), nerve conduction studies (NCS), and laboratory testing. Furthermore, the need for rapid diagnosis, continuous patient monitoring, and timely initiation of intravenous immunoglobulin (IVIG) or plasma exchange therapy continues to support the segment's dominant market share.
 To learn more about this report, Download Free Sample Report
The diagnostic laboratories segment is expected to register lucrative growth during the forecast period, owing to the increasing demand for specialized neurological testing, laboratory automation, and adoption of advanced immunoassay platforms for autoimmune disease diagnosis. For instance, in April 2025, Grifols partnered with IBL International to develop an advanced multiplex immunoassay platform based on single molecule counting technology, initially targeting neurological and oncological biomarker panels for clinical laboratories. The collaboration enhances laboratory capabilities by enabling high-throughput, ultra-sensitive biomarker testing, supporting the broader adoption of specialized neurological diagnostics.
Regional Insights
North America Guillain-Barre Syndrome Diagnostics Market Trends
North America Guillain Barre syndrome (GBS) diagnostics industry accounted for a significant global share in 2025, supported by its advanced healthcare infrastructure, high adoption of neurodiagnostic technologies, and well-established neurological care network. The region benefits from widespread availability of specialized neurology centers, tertiary hospitals, and accredited diagnostic laboratories equipped with advanced EMG, NCS, CSF analysis, and imaging capabilities. Strong reimbursement systems, standardized clinical guidelines, and increasing awareness regarding early diagnosis of autoimmune neurological disorders contribute to consistent demand for diagnostic testing. Furthermore, ongoing investments in neurological research, laboratory automation, and advanced diagnostic technologies, coupled with the presence of leading diagnostic manufacturers, are expected to support continued market expansion throughout the forecast period.
U.S. Guillain-Barre Syndrome Diagnostics Market Trends
The U.S. Guillain-Barre syndrome diagnostics industry accounted for the largest share of the North American market in 2025, driven by its advanced neurological care infrastructure, widespread availability of specialized diagnostic facilities, and strong adoption of electrodiagnostic technologies. A well-established network of tertiary hospitals, neurology centers, and accredited diagnostic laboratories supports timely diagnosis through electromyography (EMG), nerve conduction studies (NCS), cerebrospinal fluid (CSF) analysis, and magnetic resonance imaging (MRI). Favorable reimbursement policies standardized clinical practice guidelines, and high healthcare expenditure further contribute to the routine use of advanced diagnostic procedures. In addition, increasing investments in neurological research, expansion of laboratory automation, and growing awareness among healthcare professionals regarding early diagnosis of autoimmune neurological disorders are expected to support continued market growth throughout the forecast period.
Europe Guillain-Barre Syndrome Diagnostics Market Trends
The Europe GBS diagnostics industry accounted for a significant share of the global market in 2025, driven by well-established healthcare systems, comprehensive neurological care networks, and standardized clinical protocols for diagnosing peripheral neuropathies. The region has a robust network of university hospitals, specialized neurology centers, and accredited diagnostic laboratories equipped with advanced electromyography (EMG), nerve conduction studies (NCS), cerebrospinal fluid (CSF) analysis, and magnetic resonance imaging (MRI) capabilities. Continuous investments in healthcare infrastructure, expanding laboratory modernization initiatives, and greater adoption of automated diagnostic technologies are enhancing diagnostic efficiency across the region. In addition, supportive reimbursement frameworks, increasing focus on early neurological disease detection, and collaborative clinical research programs are expected to strengthen diagnostic capabilities and support sustained market growth throughout the forecast period.
Germany Guillain-Barre syndrome diagnostics industry accounted for the largest share of the Europe market in 2025, driven by its advanced healthcare infrastructure, well-established neurological care network, and widespread availability of specialized diagnostic services. The country has an extensive network of university hospitals, neurology clinics, and accredited diagnostic laboratories equipped with advanced electromyography (EMG), nerve conduction studies (NCS), cerebrospinal fluid (CSF) analysis, and magnetic resonance imaging (MRI) capabilities. Strong healthcare funding, favorable reimbursement policies, and continuous investments in laboratory modernization support the adoption of advanced neurodiagnostic technologies. Furthermore, increasing emphasis on early diagnosis of neurological disorders, growing clinical research activities, and collaboration between healthcare institutions and research organizations are expected to enhance diagnostic capabilities and support sustained market growth throughout the forecast period.
Asia Pacific Guillain-Barre Syndrome Diagnostics Market Trends
Asia Pacific Guillain Barre syndrome diagnostics industry dominated the global market in 2025, accounting for the largest regional share owing to its large population base, expanding healthcare infrastructure, and increasing access to specialized neurological diagnostic services. The region has witnessed significant investments in tertiary care hospitals, diagnostic laboratories, and advanced neurophysiology facilities capable of performing electromyography (EMG), nerve conduction studies (NCS), cerebrospinal fluid (CSF) analysis, and magnetic resonance imaging (MRI). Countries such as Japan, India, South Korea, and Australia continue to strengthen neurological healthcare through greater adoption of advanced diagnostic technologies and laboratory modernization. Rising healthcare expenditure, improving awareness of autoimmune neurological disorders, and government initiatives to enhance healthcare accessibility are expected to support sustained market growth across the region during the forecast period.
 To learn more about this report, Download Free Sample Report
Japan Guillain-Barre syndrome diagnostics industry accounted for the largest share of the Asia Pacific region in 2025, driven by its advanced healthcare infrastructure, aging population, and widespread adoption of sophisticated neurodiagnostic technologies. The country has a well-established network of tertiary care hospitals, university medical centers, and specialized neurology clinics equipped with advanced electromyography (EMG), nerve conduction studies (NCS), cerebrospinal fluid (CSF) analysis, and magnetic resonance imaging (MRI) capabilities. Continuous investments in medical technology, laboratory automation, and neurological research support early and accurate diagnosis of peripheral nerve disorders. In addition, favorable reimbursement policies, strong clinical guideline adherence, and increasing emphasis on early detection of neurological diseases are expected to enhance diagnostic capabilities and support sustained market growth throughout the forecast period.
India Guillain-Barre syndrome diagnostics industry dominated the Asia Pacific market in 2025, driven by its large patient population, expanding healthcare infrastructure, and increasing access to specialized neurological diagnostic services. The country has witnessed significant growth in tertiary care hospitals, accredited diagnostic laboratories, and neurology centers offering electromyography (EMG), nerve conduction studies (NCS), cerebrospinal fluid (CSF) analysis, and magnetic resonance imaging (MRI) for the diagnosis of peripheral neuropathies. Rising healthcare expenditure, growing awareness among healthcare professionals, and government initiatives to strengthen neurological disease surveillance continue to support market growth. For instance, in 2025, the Indian Council of Medical Research (ICMR), in collaboration with the National Centre for Disease Control (NCDC), expanded nationwide surveillance and laboratory investigations during Guillain-Barre syndrome outbreaks, strengthening diagnostic capacity and improving early case identification across multiple states. These initiatives are expected to further support the adoption of advanced diagnostic services throughout the forecast period.
Latin America Guillain-Barre Syndrome Diagnostics Market Trends
The Latin America Guillain-Barre syndrome diagnostics industry is expected to witness steady growth over the forecast period, driven by improving healthcare infrastructure, expanding access to neurological care, and increasing investments in diagnostic services across major economies such as Brazil, Mexico, and Argentina. Growing awareness of autoimmune neurological disorders and the strengthening of hospital-based diagnostic capabilities are supporting the adoption of electromyography (EMG), nerve conduction studies (NCS), cerebrospinal fluid (CSF) analysis, and magnetic resonance imaging (MRI). In addition, government initiatives to enhance infectious disease surveillance and neurological healthcare, coupled with the expansion of accredited diagnostic laboratories, are improving access to early diagnosis. These factors, along with increasing healthcare expenditure and ongoing modernization of clinical laboratory infrastructure, are expected to support sustained market growth throughout the forecast period.
Brazil Guillain-Barre syndrome diagnostics industry accounted for the largest share of the Latin America market in 2025, driven by its extensive public healthcare network, expanding access to specialized neurological care, and growing availability of advanced diagnostic services. The country has a well-established network of tertiary hospitals, university medical centers, and accredited diagnostic laboratories offering electromyography (EMG), nerve conduction studies (NCS), cerebrospinal fluid (CSF) analysis, and magnetic resonance imaging (MRI) for the diagnosis of peripheral neuropathies. The country's continued strengthening of arbovirus surveillance and neurological complication monitoring following recurrent Zika and dengue outbreaks has reinforced the need for timely Guillain-Barre syndrome diagnosis and expanded diagnostic capacity across referral hospitals and public health laboratories. In addition, increasing healthcare investments, laboratory modernization initiatives, and greater awareness of autoimmune neurological disorders are expected to support sustained market growth throughout the forecast period.
MEA Guillain-Barre Syndrome Diagnostics Market Trends
The Middle East & Africa Guillain-Barre syndrome diagnostics industry is expected to witness steady growth over the forecast period, driven by improving healthcare infrastructure, expanding access to specialized neurological care, and increasing investments in diagnostic capabilities across countries such as Saudi Arabia, the UAE, and South Africa. Growing government initiatives to strengthen healthcare systems, coupled with the expansion of tertiary care hospitals and accredited diagnostic laboratories, are supporting the adoption of electromyography (EMG), nerve conduction studies (NCS), cerebrospinal fluid (CSF) analysis, and magnetic resonance imaging (MRI). Rising awareness of autoimmune neurological disorders, increasing laboratory modernization, and broader availability of advanced diagnostic technologies are further enhancing early disease detection. These developments, along with continued healthcare investments and improving access to specialized neurological services, are expected to support sustained market growth throughout the forecast period.
Key Guillain-Barre Syndrome Diagnostics Company Insights
The Guillain-Barre syndrome diagnostics industry is moderately fragmented, with competition centered on manufacturers of neurodiagnostic equipment, electrophysiology systems, and neurological testing solutions rather than disease-specific diagnostic assays. Market participants compete through product innovation, software enhancements, geographic expansion, distribution partnerships, and service capabilities to strengthen their presence in hospitals, neurology clinics, and diagnostic laboratories. Increasing demand for early diagnosis of peripheral nerve disorders is encouraging companies to develop advanced electromyography (EMG), nerve conduction study (NCS), and neurophysiology platforms with improved workflow efficiency and diagnostic accuracy.
Key Guillain-Barre Syndrome Diagnostics Companies:
The following key companies have been profiled for this study on the guillain-barre syndrome diagnostics market:
-
Cadwell Industries, Inc
-
Natus Medical Incorporated
-
Nihon Kohden Corporation
-
Medtronic plc
-
Bionen Medical Devices
-
Deymed Diagnostic
-
Neurosoft
-
Alpine Biomed
-
EMS Biomedical
-
Rochester Electro-Medical, Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Natus Medical Incorporated
- Expand neurodiagnostic portfolio through continuous innovation in EMG, nerve conduction studies (NCS), and neuromuscular ultrasound systems.
- Strengthen global commercialization through distributor partnerships and healthcare provider collaborations.
- Invest in workflow automation, integrated diagnostic software, and service support to improve clinical efficiency.
- Strong global presence with an established distribution network and customer base.
- Comprehensive neurodiagnostic product portfolio covering EMG, NCS, EEG, and neuromuscular ultrasound.
- Extensive clinical expertise, regulatory experience, and after-sales service capabilities.
- High capital investment required for advanced neurodiagnostic systems.
- Regulatory approvals and reimbursement challenges may delay product adoption.
- Dependence on hospital capital budgets may limit purchasing in resource-constrained settings.
Emerging Players: Deymed Diagnostic
- Focus on developing cost-effective EMG and neurophysiology systems for hospitals and diagnostic laboratories.
- Expand through regional distributors and strategic partnerships in emerging markets.
- Invest in compact diagnostic platforms, software enhancements, and workflow optimization.
- .
- Strong innovation agility with flexible and user-friendly neurodiagnostic solutions.
- Competitive pricing and customized systems for small and mid-sized healthcare facilities.
- Rapid product development and responsive customer support.
- Limited global commercial footprint compared with established manufacturers.
- Greater reliance on distribution partners for international expansion.
- Smaller installed customer base and financial resources may limit large-scale market penetration.
- .
Recent Development
-
In April 2025, Cadwell Industries launched the next-generation Sierra software for its Sierra Summit EMG systems, integrating synchronized electromyography (EMG) and neuromuscular ultrasound (NMUS), enhanced Q-Mode, EMG/US Guidance+, and Sierra Analytics. The upgraded platform improves the diagnosis of peripheral nerve disorders by enhancing workflow efficiency, diagnostic precision, and real-time neuromuscular assessment capabilities.
-
In May 2025, Natus Medical introduced InVisus Pro Neuromuscular Ultrasound, integrated with Natus Elite software, expanding its neurodiagnostic portfolio for peripheral nerve evaluation. The solution combines high-resolution neuromuscular ultrasound with electrophysiological testing, enabling clinicians to improve the diagnosis and assessment of neuromuscular disorders such as Guillain-Barre syndrome through comprehensive nerve imaging and functional analysis.
Guillain-Barre Syndrome Diagnostics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 148.1 million
Estimated market size in 2026
USD 151.9 million
Projected market size by 2033
USD 186.8 million
Growth rate
CAGR of 3.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Test, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Cadwell Industries, Inc.; Natus Medical Incorporated; Nihon Kohden Corporation; Medtronic plc; Bionen Medical Devices; Deymed Diagnostic; Neurosoft; Alpine Biomed; EMS Biomedical; Rochester Electro-Medical, Inc.
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope.
Global Guillain-Barre Syndrome Diagnostics Market Report Segmentation
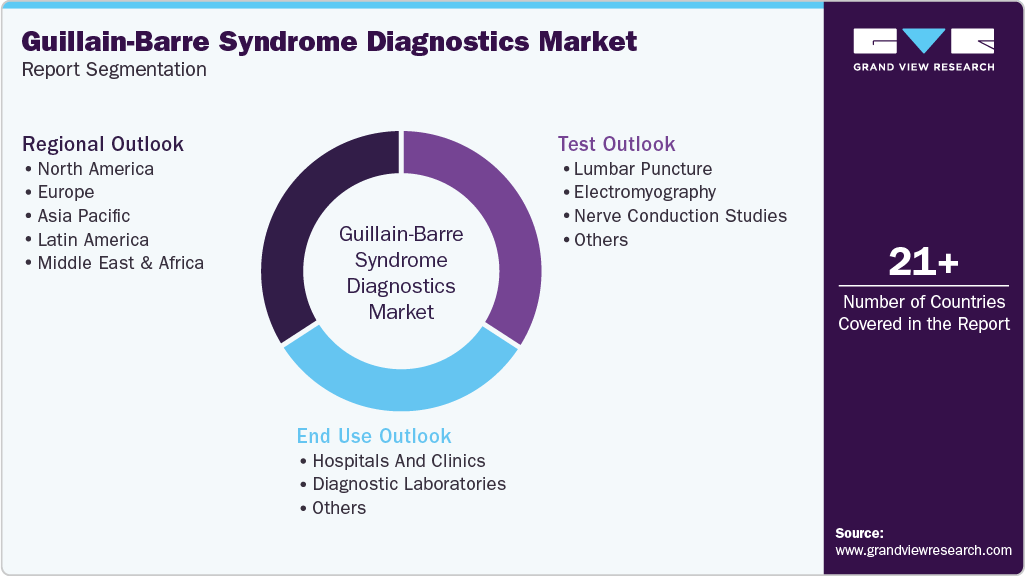
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global Guillain-Barre syndrome diagnostics market report based on test, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Test Outlook (Revenue, USD Million, 2021 - 2033)
-
Lumbar Puncture
-
Electromyography
-
Nerve Conduction Studies
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals and Clinics
-
Diagnostic Laboratories
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The guillain-barre syndrome diagnostics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each guillain-barre syndrome diagnostics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Test type
Revenue capture definition
Lumbar Puncture
Revenue is primarily captured through lumbar puncture procedures, cerebrospinal fluid collection kits, spinal needles, collection tubes, laboratory analysis of CSF samples, and associated hospital or diagnostic service charges used to support Guillain-Barré syndrome diagnosis.
Electromyography (EMG)
Revenue flows from electromyography systems, needle and surface electrodes, EMG software, disposable accessories, equipment maintenance, diagnostic procedure fees, and neurophysiology testing services performed for evaluation of muscle and peripheral nerve function.
Nerve Conduction Studies (NCS)
Market value is derived from nerve conduction study instruments, stimulation and recording electrodes, nerve stimulators, consumables, software upgrades, calibration services, and diagnostic testing procedures assessing peripheral nerve conduction abnormalities.
Others
Revenue is captured through complementary diagnostic procedures including neurological examination, blood tests, imaging studies, pulmonary function assessment, autonomic function testing, and associated clinical consultation services that aid Guillain-Barré syndrome diagnosis.
Segment - End use
Revenue capture definition
Hospitals and Clinics
Revenue is primarily captured through inpatient and outpatient Guillain-Barré syndrome diagnostic procedures, electromyography and nerve conduction testing, lumbar puncture services, physician consultations, diagnostic equipment utilization, and integrated neurological care provided in hospitals and clinics.
Diagnostic Laboratories
Revenue flows from cerebrospinal fluid analysis, blood testing, specimen processing, referral based diagnostic services, laboratory testing fees, and specialized neurological diagnostic support provided to hospitals, clinics, and physicians.
Others
Market value is derived from diagnostic services offered by academic medical centers, neurological research institutes, ambulatory care facilities, and specialty neuroscience centers performing complementary assessments for Guillain-Barré syndrome diagnosis and clinical evaluation.
Estimation Model
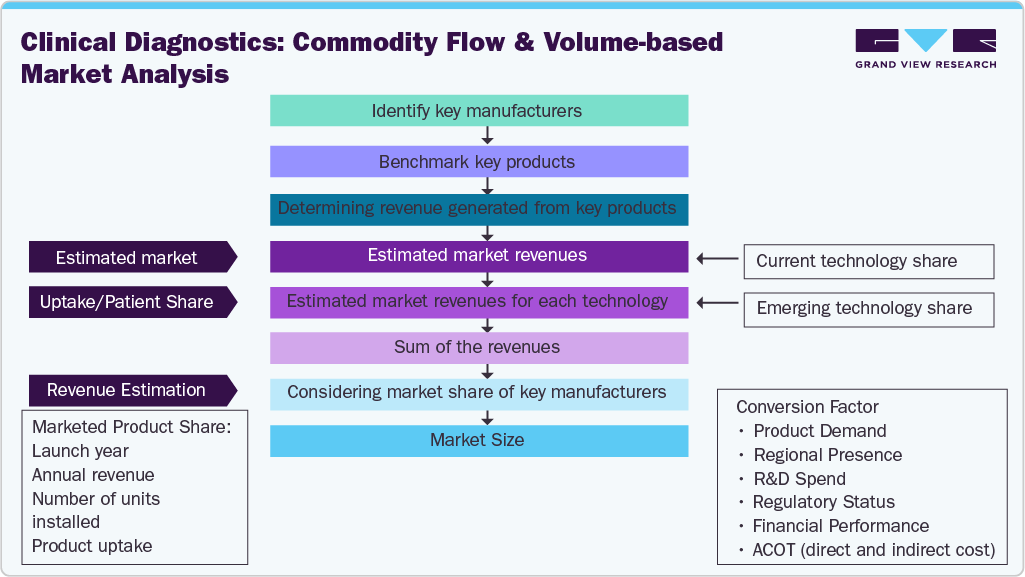
The Guillain-Barré syndrome diagnostics market was estimated by identifying key manufacturers of neurodiagnostic systems and benchmarking their product portfolios, including electromyography, nerve conduction study, and lumbar puncture related diagnostic solutions. Revenue generated from these product categories was assessed along with technology adoption and patient uptake across healthcare settings to estimate segment wise market revenues. The aggregated revenues were further validated by considering the market share of leading manufacturers to derive the overall market size.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Guillain-Barré Syndrome Diagnostics Competitive Landscape & Technology Assessment
Assessed the global Guillain-Barré syndrome diagnostics market across lumbar puncture, electromyography, nerve conduction studies, cerebrospinal fluid analysis, and emerging neurodiagnostic technologies. Analyzed key manufacturers, competitive positioning, product portfolios, technology adoption trends, regulatory approvals, product launches, and regional commercialization strategies across hospitals, diagnostic laboratories, and neurology centers.
Enabled the client to identify high growth diagnostic technologies, benchmark competitors, evaluate product differentiation, prioritize investments in neurodiagnostic solutions, and understand technology adoption trends influencing the Guillain-Barré syndrome diagnostics market.
Guillain-Barré Syndrome Diagnostics Product Benchmarking Study
Delivered a comprehensive benchmarking assessment of Guillain-Barré syndrome diagnostic solutions based on diagnostic accuracy, electrophysiological performance, workflow efficiency, portability, software integration, ease of use, regulatory status, and product differentiation among leading neurodiagnostic companies.
Helped the client assess product competitiveness, identify technology innovation opportunities, benchmark advanced neurodiagnostic platforms, and prioritize investments in next generation electromyography and nerve conduction study systems for neurological diagnostics.
Guillain-Barré Syndrome Diagnostics Commercialization & Market Entry Assessment
Assessed commercialization strategies, regulatory pathways, reimbursement landscape, distribution networks, healthcare adoption trends, strategic collaborations, and market readiness across hospitals, diagnostic laboratories, specialty neurology clinics, and academic medical centers. Evaluated competitive intensity, procurement practices, and adoption barriers for advanced neurodiagnostic systems.
Supported commercialization planning by identifying high potential market opportunities, evaluating partnership and distribution strategies, assessing regulatory and reimbursement requirements, mitigating commercialization risks, and strengthening long term growth strategies within the Guillain-Barré syndrome diagnostics market.
Frequently Asked Questions About This Report
The global Guillain-Barre syndrome diagnostics market is expected to grow at a CAGR of 3.0% from 2026 to 2033, reaching USD 186.8 million by 2033.
The hospitals and clinics segment led with a 62.9% revenue share in 2025, driving significant growth through the integration of advanced diagnostic tools and improved patient management protocols.
Innovations such as nerve conduction studies and electromyography have improved the accuracy and speed of GBS diagnosis, enabling healthcare providers to initiate appropriate treatments promptly. These technological advancements not only enhance patient outcomes but also contribute to the expansion of the diagnostics market by increasing the demand for advanced diagnostic equipment and procedures.
The global Guillain-Barre syndrome diagnostics market size was valued at USD 148.1 million in 2025 and is estimated at USD 151.9 million for 2026.
Asia Pacific dominated the Guillain-Barre syndrome diagnostics market with a share of 41.7% in 2025. This is attributable to rising awareness, improving healthcare infrastructure, and increasing diagnostic rates.
Some key players operating in the Guillain-Barré Syndrome (GBS) diagnostics market include Cadwell Industries, Inc, Natus Medical Incorporated, Nihon Kohden Corporation, Medtronic plc, Bionen Medical Devices, Deymed Diagnostic, Neurosoft, Alpine Biomed, EMS Biomedical, Rochester Electro-Medical, Inc.
Key factors driving market growth include the increasing prevalence of GBS, advancements in diagnostic techniques, and heightened awareness of the condition among healthcare professionals and the general public.
The lumbar puncture segment led with a 45.0% revenue share in 2025 and is expected to experience the fastest CAGR during the forecast period, driven by its essential role in confirming GBS diagnosis
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


