
- Home
- »
- Clinical Diagnostics
- »
-
HbA1c Testing Devices Market Size Report, 2026-2033GVR Report cover
![HbA1c Testing Devices Market (2026 - 2033)Report]()
HbA1c Testing Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Laboratory-based Testing Devices, Point-of-care (POC) Testing Devices), By Technology, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$2.4BMarket Estimate, 2026
$2.6BMarket Forecast, 2033
$4.2BCAGR, 2026–2033
7.3%HbA1c Testing Devices Market Summary
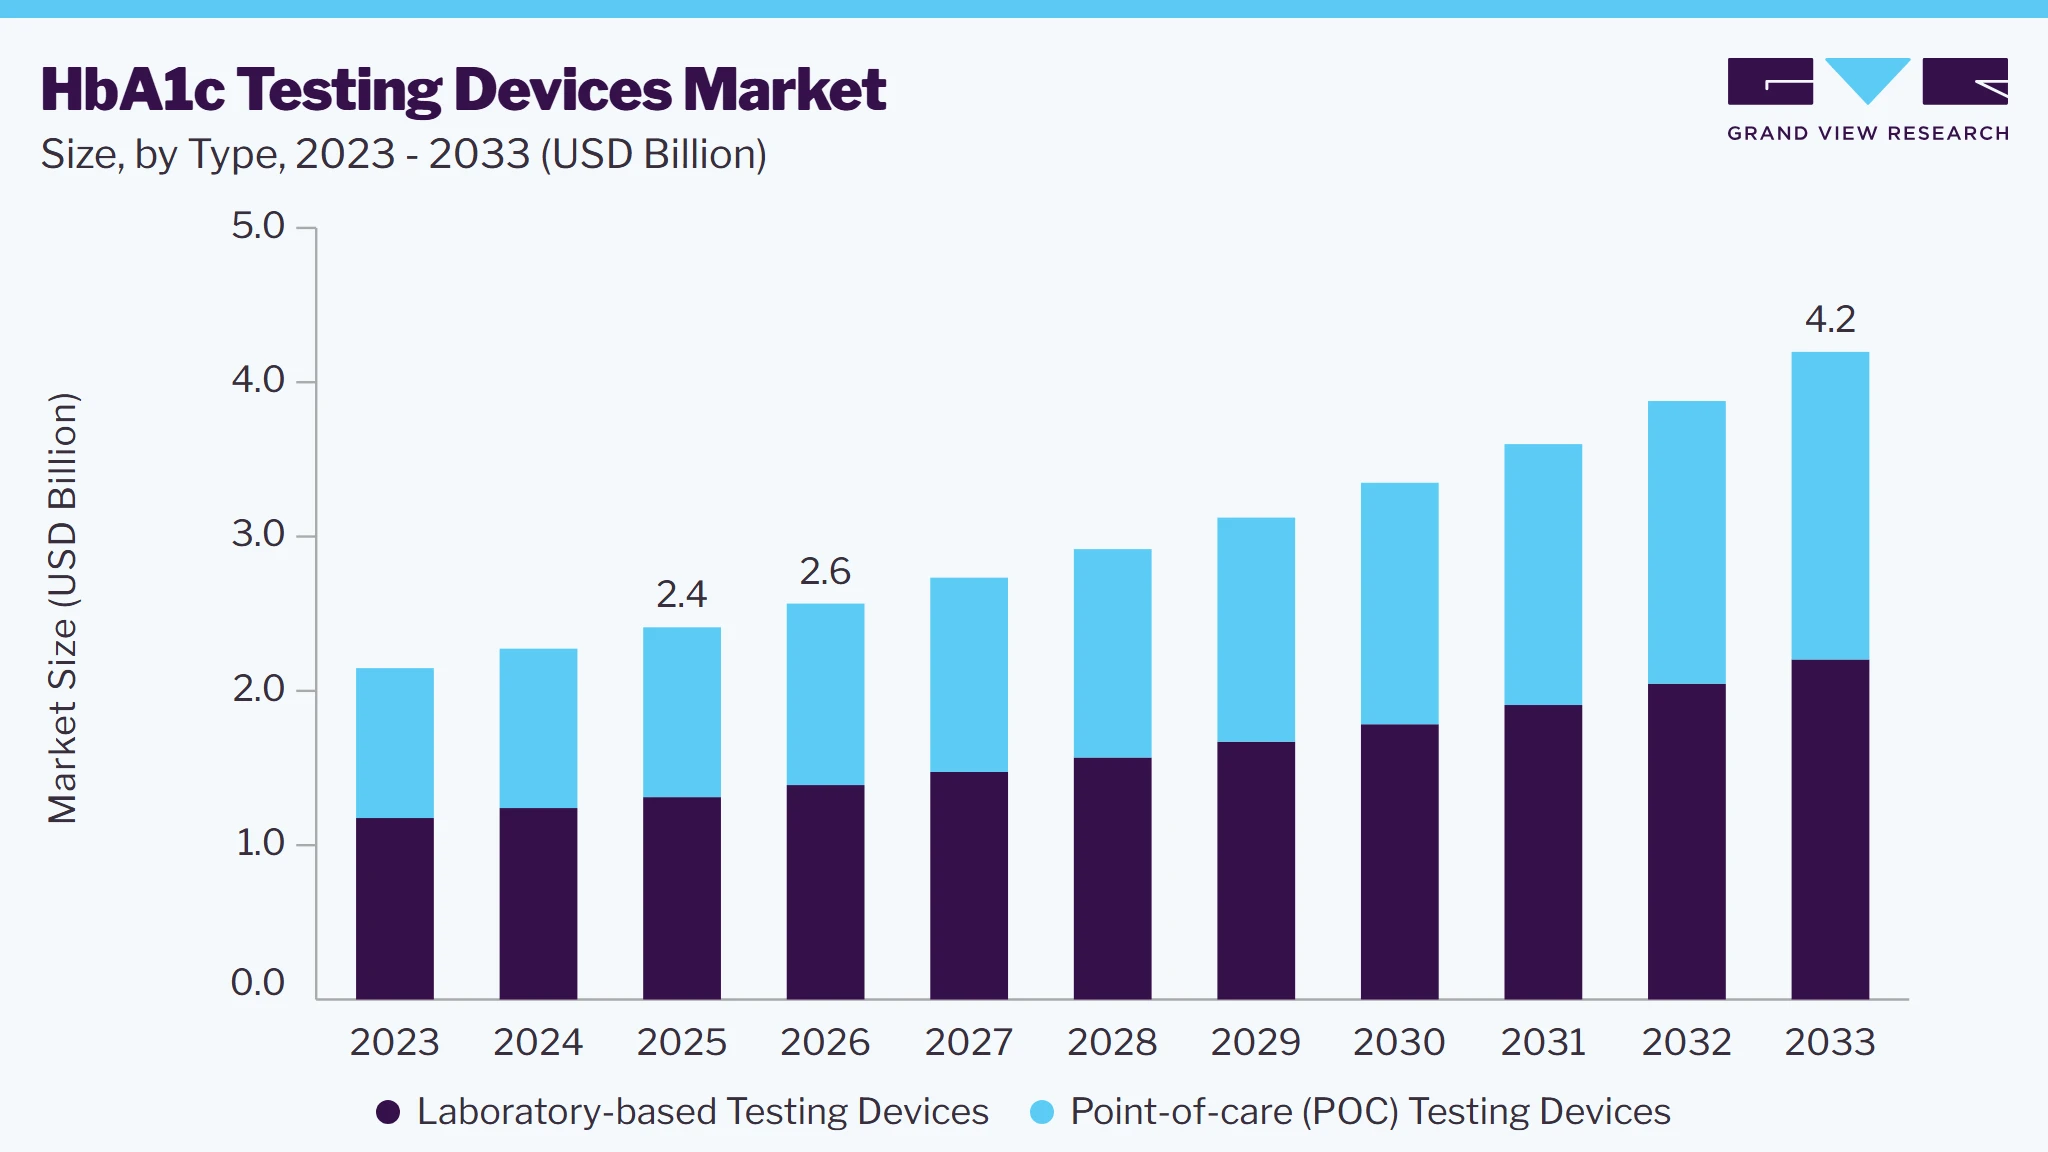
The global HbA1c testing devices market size was valued at USD 2.4 billion in 2025 and is projected to grow from USD 2.6 billion in 2026 to USD 4.2 billion by 2033, at a CAGR of 7.3% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 33.8% in 2025. The continuing rise in diabetes prevalence, combined with a substantial population that remains undiagnosed, is creating a structural demand base for the global HbA1c testing devices market.

Key Market Trends & Insights
- By Type: The laboratory-based testing devices segment dominated the global market, accounting for 54.4% of the total market revenue in 2025.
- By Technology: The ion-exchange chromatography segment led the market with the largest revenue share of 33.6% in 2025.
- By End use: The hospitals & clinics segment led the market with the largest revenue share of 57.1% in 2025.
Regional Highlights
- Largest regional market: North America (33.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held a significant market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.4 Billion
- Estimated market size in 2026: USD 2.6 Billion
- Projected market size by 2033: USD 4.2 Billion
- CAGR (2026-2033): 7.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Market Dynamics
HbA1c testing is used throughout the diabetes care continuum, including identifying individuals with abnormal glycemic levels, supporting diagnosis, and monitoring long-term glycemic control in patients receiving treatment. Consequently, the expanding diabetes population directly increases the number of HbA1c tests performed across hospitals, diagnostic laboratories, physician offices, diabetes clinics, and primary care facilities. The undiagnosed population further strengthens market demand by representing patients who are likely to enter the diabetes care pathway as screening programs expand. As these individuals are identified, demand extends beyond initial diagnosis to recurring HbA1c monitoring, supporting sustained utilization of both high-throughput laboratory analyzers and decentralized point-of-care testing systems.
For instance, in January 2026, according to data published by the U.S. Centers for Disease Control and Prevention (CDC), approximately 40.1 million people in the United States had diagnosed or undiagnosed diabetes in 2023, representing nearly 12.0% of the population. More importantly, around 11.0 million adults with diabetes remained undiagnosed, accounting for 27.6% of all adults with diabetes, highlighting the continued need for improved diabetes detection even in mature healthcare systems. In addition, according to data published by the Australian Institute of Health and Welfare (AIHW) in 2026, approximately 6.5% of Australian adults, or 1.3 million people, had diabetes based on self-reported information and measured HbA1c results collected during 2022–2024. This included 5.6% with known diabetes and 0.9% with newly diagnosed diabetes, demonstrating the importance of HbA1c testing in identifying previously unrecognized cases and supporting timely disease management.
The expanding diabetes burden is also driving commercial investments and reinforcing the long-term growth outlook for the HbA1c testing devices market. In March 2026, Trinity Biotech announced the commercial rollout of its next-generation Premier Hb9210 HbA1c column system in Brazil following regulatory approval. The company identified Brazil as one of the world's major diabetes markets, with an estimated 16–18 million adults living with diabetes, directly linking the growing disease burden to increasing demand for reliable HbA1c testing technologies. Furthermore, according to a report published by the World Health Organization (WHO) in November 2024, more than 800 million adults worldwide were living with diabetes, while global adult diabetes prevalence increased from approximately 7% in 1990 to 14% in 2022. The WHO emphasized strengthening prevention, early detection, and treatment, particularly in low- and middle-income countries, reinforcing sustained demand for both laboratory-based and point-of-care HbA1c testing solutions.
The high acquisition cost of HbA1c testing devices, combined with ongoing expenditure on proprietary reagents, analytical columns, calibrators, quality-control materials, maintenance, and servicing, continues to restrain the growth of the global HbA1c testing devices market. The financial burden is particularly significant for smaller diagnostic laboratories, physician offices, primary care facilities, and healthcare providers operating in resource-constrained settings. Advanced laboratory-based analyzers, especially those based on high-performance liquid chromatography (HPLC), require sophisticated fluidics, chromatography columns, automated sample handling, calibration systems, laboratory information system connectivity, and specialized technical expertise, substantially increasing the total cost of ownership. As a result, purchasing decisions increasingly consider long-term operational expenditure rather than the initial instrument price alone. Although point-of-care HbA1c systems reduce infrastructure requirements, recurring costs associated with cartridges and reagent kits can significantly increase the cost per test, particularly in facilities with high testing volumes. These financial constraints often encourage healthcare providers to outsource HbA1c testing to centralized laboratories, postpone equipment replacement, or opt for lower-cost platforms with reduced throughput and functionality, particularly in low- and middle-income countries where laboratory budgets must support multiple essential diagnostic services.
For instance, in July 2026, West Suffolk NHS Foundation Trust in the UK published a procurement for haemoglobinopathy and HbA1c analytical equipment with an estimated total value of £350,000 excluding VAT. The HbA1c biochemistry lot alone was valued at approximately £280,000, supporting a high-volume service performing around 400–500 tests per day. The Trust specified a preference for a cost-per-reportable-result procurement model while also considering reagent rental and managed-service arrangements. This procurement approach demonstrates that healthcare providers increasingly evaluate HbA1c testing platforms based on lifetime operating costs, including instrument servicing, consumables, maintenance, and workflow efficiency, rather than focusing solely on the initial purchase price.
Overall, high capital investment and recurring operating expenses continue to limit the adoption of HbA1c testing systems despite the expanding global demand for diabetes diagnosis and monitoring. Large hospitals and reference laboratories are generally better positioned to distribute equipment and maintenance costs across high testing volumes, making advanced automated analyzers economically viable. In contrast, smaller healthcare facilities often lack sufficient testing volumes to justify dedicated HbA1c platforms, especially when the ongoing expenses for reagents, analytical columns, quality-control materials, servicing, software, and connectivity are considered. Consequently, affordability remains a critical factor influencing purchasing decisions and market penetration, particularly in emerging economies, where constrained healthcare budgets continue to limit investment in advanced diagnostic technologies.
The increasing number of product launches and portfolio expansions is creating a significant growth opportunity for the global HbA1c testing devices market. Manufacturers are continually strengthening their HbA1c portfolios to meet evolving requirements across central laboratories, hospitals, diabetes clinics, physicians' offices, pharmacies, and primary care facilities. Next-generation HbA1c systems are being developed with features such as faster turnaround times, compact footprints, higher throughput, automated workflows, enhanced connectivity, simplified operation, and improved management of hemoglobin-variant interference. Simultaneously, companies are integrating HbA1c testing into broader clinical chemistry and decentralized diagnostic platforms, enabling laboratories with varying testing volumes and infrastructure capabilities to adopt suitable solutions. For instance, in April 2026, Sinocare showcased an expanded digital healthcare portfolio at the 93rd China International Medical Equipment Fair, covering home monitoring, primary care, and clinical settings. The company introduced integrated diagnostic solutions comprising HbA1c systems, portable multifunction analyzers, and non-invasive diabetes-risk screening technologies for community clinics, pharmacies, and health centers, demonstrating its strategy to extend HbA1c testing beyond conventional hospital laboratories and broaden market reach across multiple healthcare settings.
The commercial opportunity is further strengthened by manufacturers expanding their geographic presence and introducing higher-capacity systems to support growing diabetes testing volumes. Continued portfolio expansion not only encourages replacement of aging installed instruments but also enables manufacturers to strengthen recurring revenue through increased demand for associated reagents, analytical columns, calibrators, quality-control materials, and servicing contracts. Furthermore, in December 2025, Trinity Biotech plc announced that it had secured regulatory clearances in multiple countries, enabling the expanded commercial rollout of its next-generation high-capacity Premier Hb9210 HbA1c column system, which became available in more than 10 countries, including the United States. The upgraded platform significantly improves testing throughput and laboratory operational efficiency while supporting greater recurring consumable revenue and reinforcing the company's competitive position across international HbA1c testing markets.
Overall, continued product innovation and portfolio expansion are broadening the range of HbA1c testing solutions available across centralized laboratories and decentralized healthcare settings. Rather than competing solely on analytical performance, manufacturers are increasingly differentiating their offerings through automation, connectivity, throughput, workflow efficiency, ease of operation, portability, and integration with broader diagnostic platforms. These developments enable healthcare providers with diverse infrastructure capabilities to adopt solutions that align with their operational requirements while accelerating the replacement of legacy systems. As diabetes screening and long-term disease monitoring continue to expand globally, ongoing product innovation is expected to increase instrument placements across multiple care settings and generate sustained recurring revenue through long-term demand for consumables, software, maintenance services, and platform upgrades.
Market Concentration & Characteristics
The HbA1c testing devices market exhibits a moderate to high degree of innovation, driven by advancements in analytical performance, automation, workflow efficiency, and point-of-care testing. Manufacturers are introducing next-generation analyzers with higher throughput, enhanced connectivity, improved hemoglobin variant detection, and compact designs while integrating HbA1c testing into broader diagnostic platforms. These innovations improve accessibility, laboratory efficiency, and long-term diabetes management, supporting market growth and the replacement of legacy systems.
The HbA1c testing devices industry demonstrates a moderate level of mergers and acquisitions (M&A) activity. Market participants primarily focus on product innovation, regulatory approvals, portfolio expansion, strategic collaborations, and geographic expansion to strengthen their competitive positions. While acquisitions occur selectively to enhance diagnostic capabilities, expand diabetes-testing portfolios, or access new markets, organic growth through new product launches and commercialization remains the dominant competitive strategy. Established diagnostics companies and specialized HbA1c testing manufacturers continue to invest in technology development, distribution partnerships, and laboratory automation, indicating a market where targeted acquisitions complement, rather than drive, overall industry growth.
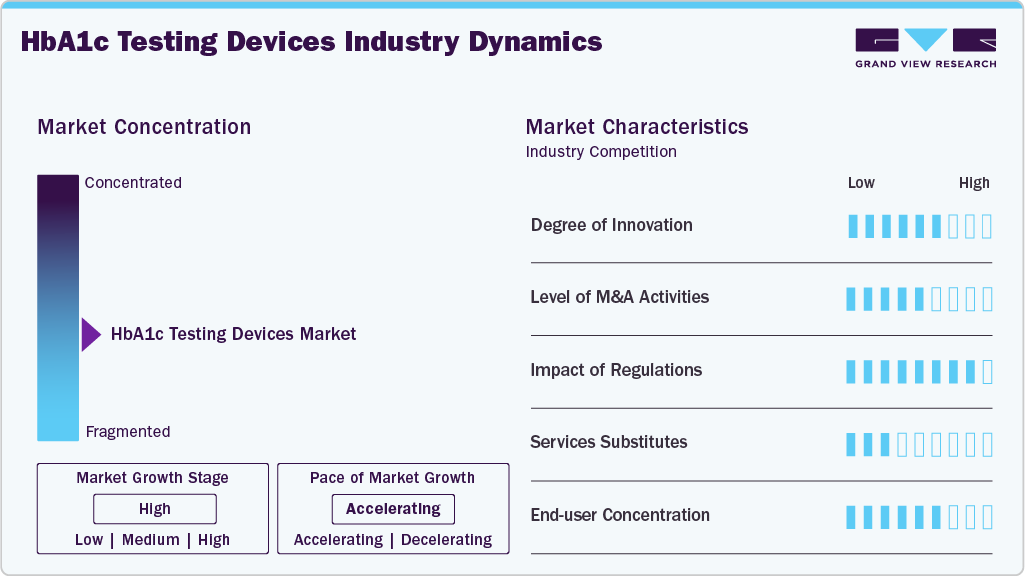
The market is characterized by a high regulatory impact, with manufacturers required to comply with stringent standards for analytical performance, quality management, and product approval. Compliance with regulations and HbA1c standardization programs ensures product reliability and supports global commercialization, although it increases development timelines and costs.
The industry exhibits a high level of product expansion, driven by continuous portfolio enhancements across laboratory-based and point-of-care (POC) platforms. Manufacturers are introducing advanced analyzers with improved automation, throughput, connectivity, and compact designs while expanding into new markets through regulatory approvals and product launches. These initiatives strengthen instrument adoption and generate recurring revenue from associated consumables.
The market for HbA1c testing devices demonstrates a high level of regional expansion, supported by manufacturers strengthening their presence through regulatory approvals, product launches, distribution partnerships, and commercialization across developed and emerging markets. Companies are expanding access to HbA1c testing solutions in North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa to address the growing global burden of diabetes and improve diagnostic accessibility across diverse healthcare settings.
Analyst Perspective
The HbA1c testing devices market is poised for sustained growth, driven by the increasing global burden of diabetes, expanding screening programs, and the growing emphasis on early diagnosis and long-term glycemic monitoring. Continuous innovation in laboratory-based and point-of-care technologies is improving analytical accuracy, automation, connectivity, and workflow efficiency, enabling broader adoption across hospitals, diagnostic laboratories, clinics, and homecare settings. Emerging markets present significant opportunities due to expanding healthcare infrastructure and large, undiagnosed populations with diabetes. Meanwhile, recurring demand for HbA1c testing, coupled with ongoing product innovation and regulatory support, is expected to strengthen market penetration and support stable long-term revenue growth for industry participants.
Type Insights
The laboratory-based testing devices segment dominated the global HbA1c testing devices market, accounting for 54.4% of the total market revenue in 2025, driven by their widespread adoption in hospitals, diagnostic laboratories, and reference laboratories for high-volume diabetes testing. These systems offer superior analytical accuracy, standardized measurement, high throughput, automated sample processing, and effective detection of hemoglobin variant interference, making them the preferred choice for routine diabetes diagnosis and long-term glycemic monitoring. Continuous advancements in HPLC and automated laboratory platforms, coupled with increasing demand for efficient workflow integration, are further supporting segment growth. Additionally, recurring demand for reagents, analytical columns, calibrators, controls, and maintenance services strengthens the commercial value of laboratory-based testing devices, ensuring their continued leadership throughout the forecast period.
The Point-of-care (POC) testing devices segment is expected to register the fastest CAGR during the forecast period, driven by the growing shift toward decentralized diabetes management and the increasing demand for rapid, near-patient HbA1c testing. These devices enable same-visit clinical decision-making, reduce follow-up visits, and improve access to diabetes monitoring across physician offices, outpatient clinics, pharmacies, and community healthcare settings. In May 2026, Tosoh launched the HLC-723GX2, a next-generation compact HbA1c analyzer developed for point-of-care settings, reducing measurement time from 2.2 minutes to 1.6 minutes per sample while targeting expansion across Europe, Africa, Latin America, Southeast Asia, and India. Continuous product innovation and expanding adoption in primary care are expected to support the sustained growth of the POC testing devices segment.
Technology Insights
The ion-exchange chromatography segment dominated the global HbA1c testing devices market, accounting for 33.6% of revenue in 2025, owing to its high analytical accuracy, excellent separation of hemoglobin fractions, effective detection of hemoglobin variants, and compatibility with automated high-throughput laboratory workflows. The technology remains the preferred choice for centralized and reference laboratories because it generates detailed chromatograms that help identify analytical interference and improve diagnostic confidence. Its widespread adoption is further supported by global standardization programs and continuous technological advancements. In June 2025, the U.S. FDA cleared MEDCONN's Glycated Hemoglobin Test System, comprising the MQ-3000 and MQ-3000PT analyzers. The platform uses ion-exchange HPLC, automatically performs whole-blood hemolysis and dilution, separates hemoglobin fractions through buffers of increasing ionic strength, and generates a chromatogram for each specimen. FDA documentation shows that the system was evaluated across multiple analyzers, reagent lots, and HbA1c concentrations, and was traceable to the DCCT and IFCC reference frameworks and certified through NGSP.
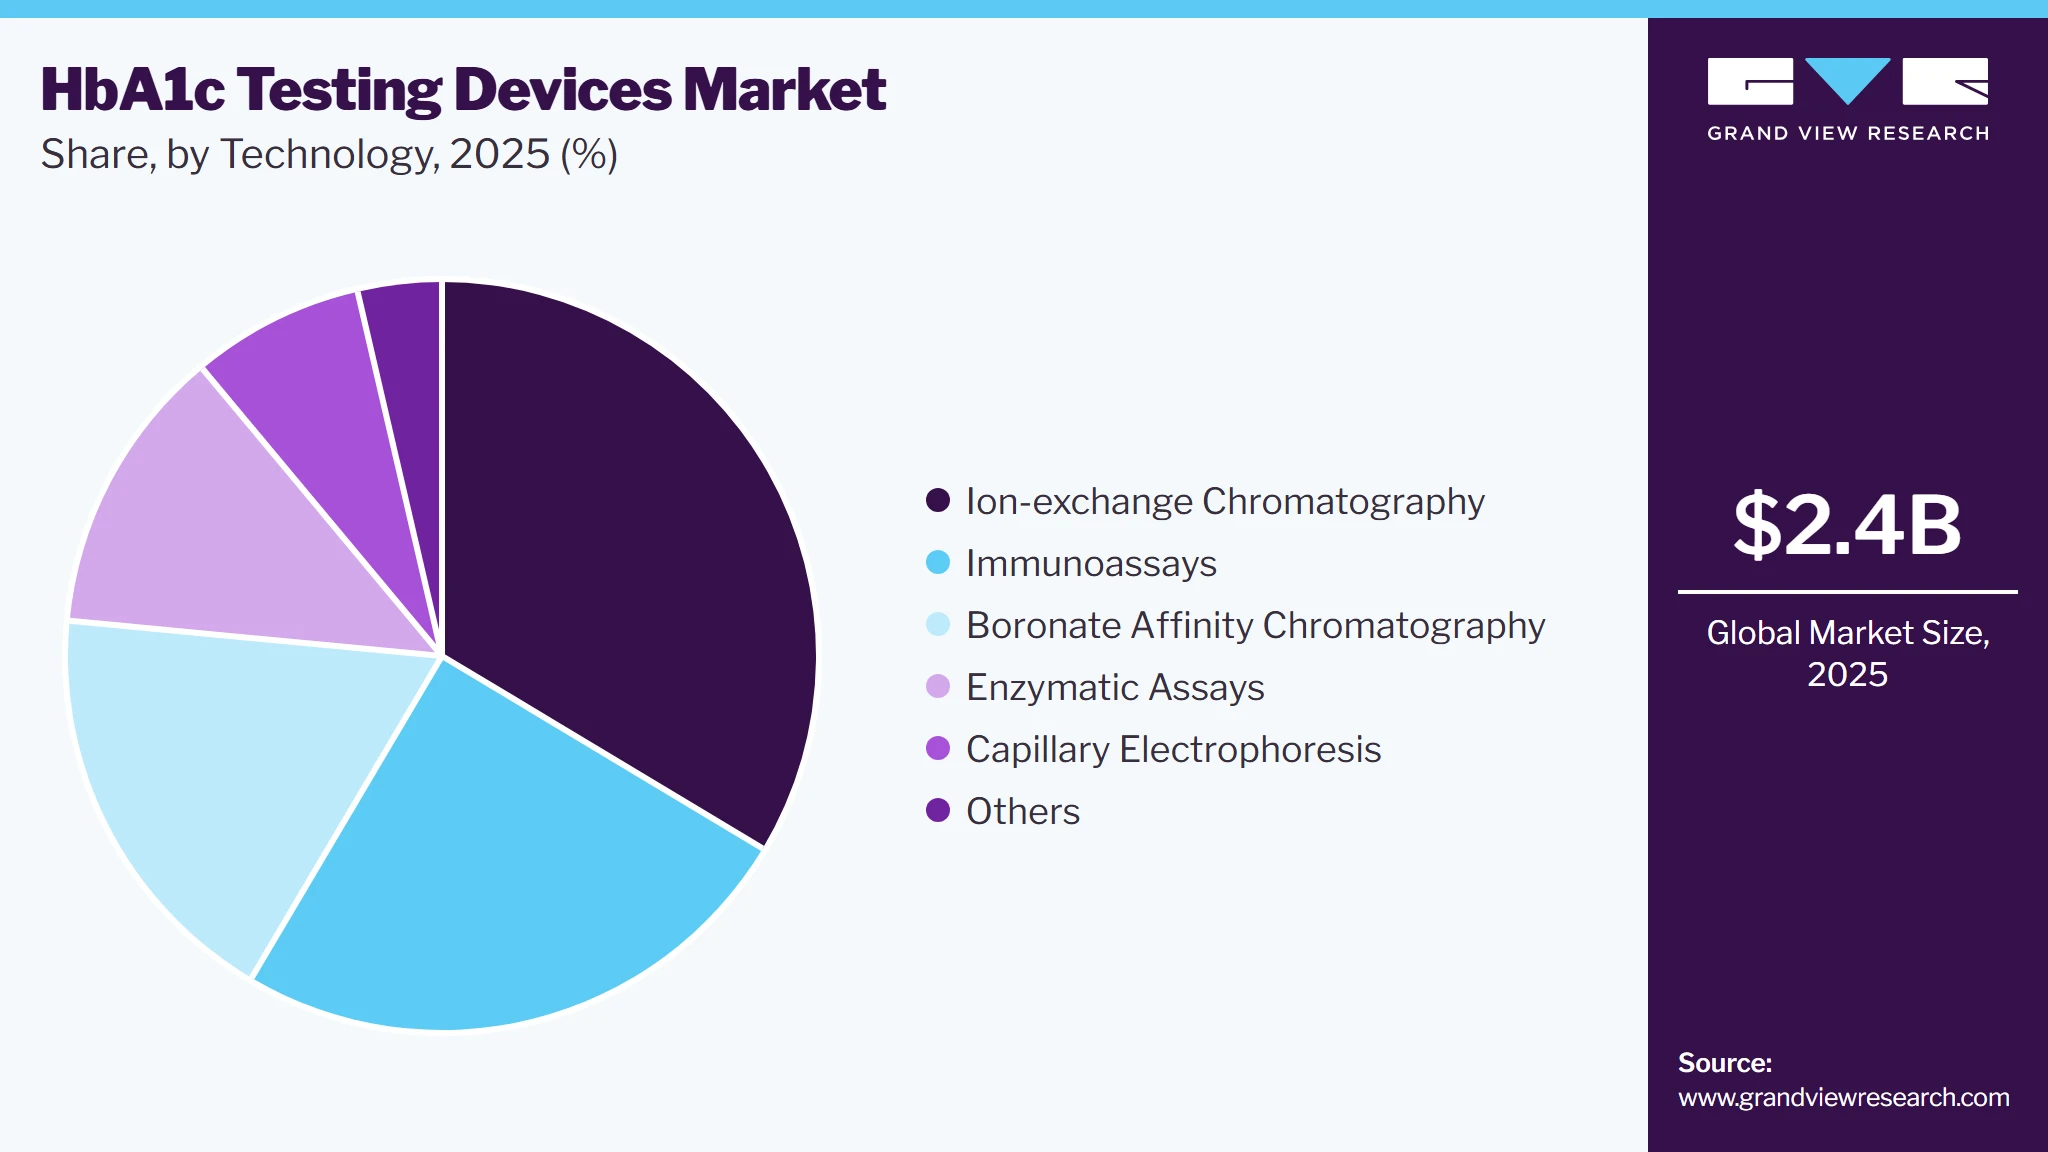
The boronate affinity chromatography segment is poised to be the fastest-growing technology segment in the HbA1c testing devices market, driven by its high specificity for glycated hemoglobin, reduced susceptibility to interference from hemoglobin variants, and standardized HbA1c measurement across diverse patient populations. The technology is gaining traction through advancements in column design, workflow efficiency, portability, and regulatory expansion. In March 2026, Trinity Biotech commenced the commercial rollout in Brazil of its next-generation Premier Hb9210 column system following local regulatory approval, which specifically identifies the upgraded system as a boronate affinity column platform and highlights its reduced sensitivity to hemoglobin variants. Additionally, in November 2025, SG Diagnostics highlighted its PreciS HbA1c Analysis System, which uses boronate affinity chromatography, requires approximately 3 µL of capillary blood, provides results within six minutes, and is traceable to IFCC and NGSP reference systems, supporting wider adoption in near-patient testing.
End Use Insights
The hospitals & clinics segment accounted for the largest revenue share of 57.1% in 2025 and remain the dominant end use segment in the HbA1c testing devices market, driven by high diabetes patient volumes, routine HbA1c monitoring, integrated laboratory infrastructure, and the availability of both centralized and point-of-care testing. These facilities support rapid clinical decision-making through seamless integration of HbA1c testing into patient care pathways. In July 2026, Siemens Healthineers launched capillary-blood testing on its Atellica CH, IM, and CI analyzers following CE marking for 24 capillary testing claims, including HbA1c, enabling hospitals to expand testing through existing laboratory infrastructure. Additionally, in August 2025, Medconn Diagnostics showcased its MQ-series HPLC HbA1c analyzers at ADLM 2025, including the FDA-cleared MQ-3000 with integrated laboratory information system capabilities, further strengthening connected hospital diagnostics.
The homecare settings segment is anticipated to register the fastest CAGR during the forecast period, driven by the growing adoption of self-management for diabetes, increasing availability of compact fingerstick-based HbA1c devices, and rising demand for convenient testing outside traditional healthcare facilities. Greater accessibility through online distribution channels and simplified device operation further support home-based HbA1c monitoring. In April 2026, PTS Diagnostics updated its A1CNow Self Check offering for home users, positioning it for patients recommended to measure A1C two to four times annually. The FDA-cleared, NGSP-certified, and IFCC-traceable system delivers results in five minutes from a 5 µL fingerstick sample without maintenance. Additionally, in 2025, PTS Diagnostics expanded its consumer-facing A1CNow distribution infrastructure, making the Self Check system directly available through an online retail partner, further improving accessibility and supporting the expansion of home-based HbA1c testing.
Regional Insights
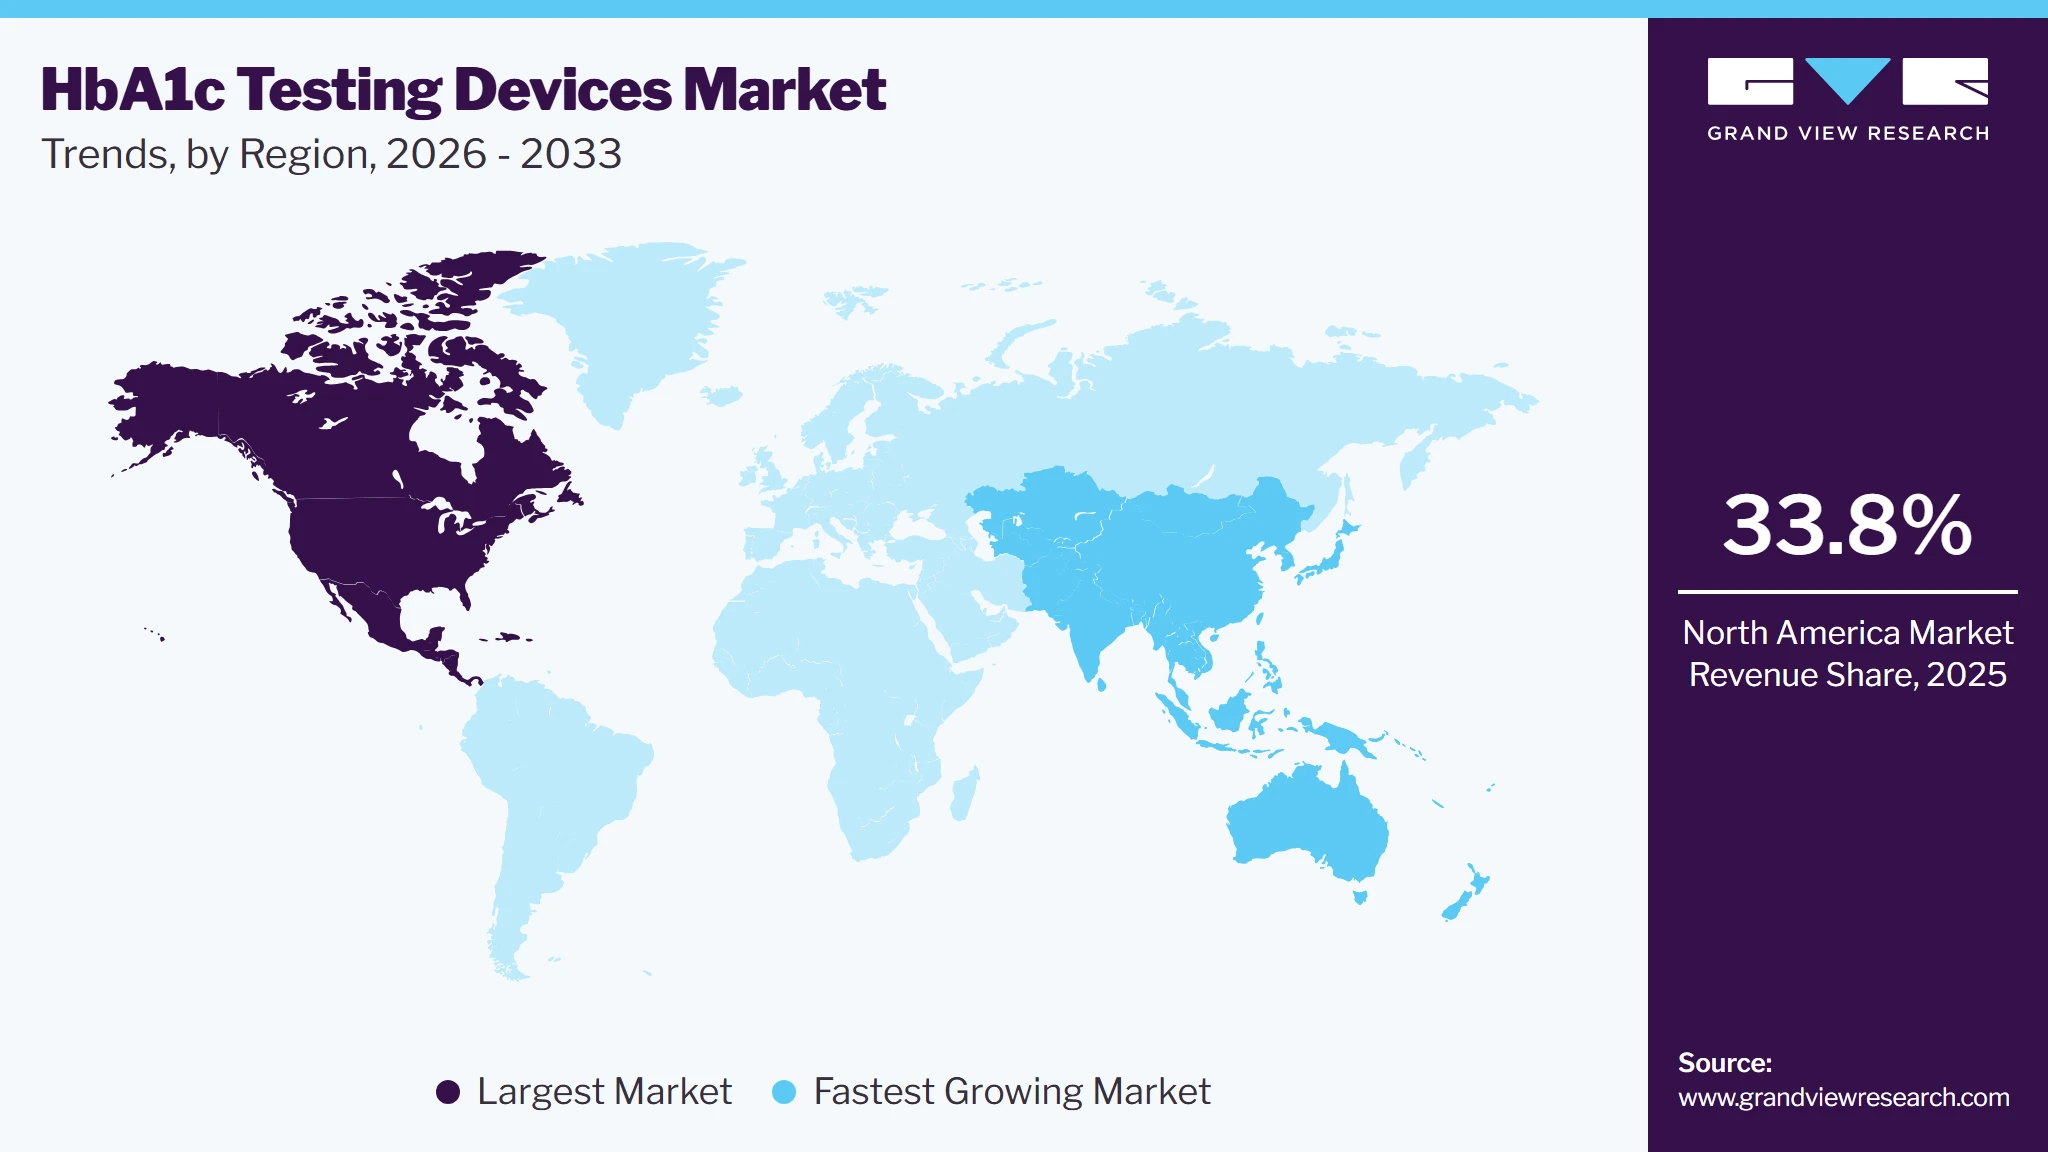
The North America HbA1c testing devicesindustry dominated the global market and accounted for the 33.8% share in 2025, driven by a large diabetes population, well-established healthcare infrastructure, and strong adoption of laboratory-based and point-of-care HbA1c testing. The region benefits from recurring demand for diabetes diagnosis and long-term glycemic monitoring supported by structured chronic disease management programs. According to the U.S. Centers for Disease Control and Prevention’s January 2026 National Diabetes Statistics Report, approximately 40.1 million people in the U.S. had diagnosed or undiagnosed diabetes in 2023, while an estimated 115.2 million adults had prediabetes. Furthermore, Government of Canada data updated in November 2025 showed that approximately 3.9 million people were living with diagnosed diabetes in 2023–2024, reinforcing sustained demand for HbA1c testing across the region.
U.S. HbA1c Testing Devices Market Trends
The HbA1c testing devices industry in the U.S.held a significant share of North America market in 2025, supported by advanced laboratory infrastructure, widespread point-of-care testing, favorable reimbursement policies, and continuous product innovation. Strong competition among leading manufacturers is driving improvements in analytical accuracy, automation, throughput, and laboratory connectivity. In June 2026, HORIBA announced the expansion of its U.S. diagnostic laboratory portfolio through a new strategic partnership with MEDCONN Diagnostics, enabling distribution of the MEDCONN MQ-3000 and MQ-8000 systems to strengthen diabetes testing capabilities across the country. Furthermore, in October 2025, Tosoh Bioscience received U.S. FDA 510(k) clearance for its next-generation HLC-723GR01 HbA1c analyzer, reinforcing continued investment in high-throughput laboratory technologies and supporting sustained growth of the U.S. HbA1c testing devices market.
Europe HbA1c Testing Devices Market Trends
The HbA1c testing devices industry in Europe accounted for a significant share of the global market in 2025. Europe represents one of the most established markets for HbA1c testing devices, supported by a high diabetes burden, well-developed healthcare infrastructure, and structured chronic disease management programs. Strong adoption of standardized laboratory and point-of-care testing, coupled with recurring HbA1c monitoring, continues to drive market demand across the region. According to the 2025 IDF Diabetes Atlas, approximately 65.6 million adults aged 20–79 years were living with diabetes in Europe in 2024, while around 22 million people remained undiagnosed, highlighting significant opportunities for early diagnosis and monitoring. Furthermore, in July 2024, Siemens Healthineers introduced the next-generation point-of-care Atellica DCA Analyser, enabling rapid HbA1c and ACR testing with a compact design and laboratory-quality accuracy, supporting timely diabetes diagnosis and management across diverse clinical settings.
The UK HbA1c testing devices industry held a significant share of the Europe market in 2025, supported by widespread NHS diabetes monitoring, advanced laboratory infrastructure, and growing adoption of point-of-care diagnostics. Market growth is driven by demand for rapid turnaround, standardized analytical performance, workflow automation, and connectivity with laboratory and electronic health record systems. In September 2025, F. Hoffmann-La Roche Ltd. showcased the cobas click system at the IBMS Congress in Birmingham as part of its UK point-of-care portfolio. Designed for pharmacies, physicians' offices, and clinics, the system delivers HbA1c results in approximately 4–6 minutes while offering enhanced connectivity, barcode-supported quality control, and improved management of hemoglobin variant interference, supporting the expansion of decentralized diabetes testing across the UK.
The HbA1c testing devices industry in Germany held a notable share of the Europe market in 2025, supported by a well-established laboratory network, structured diabetes management programs, and the presence of major diagnostics manufacturers. Market growth is driven by increasing demand for high-throughput analyzers, automation, capillary blood testing, and integrated laboratory workflows. In July 2026, Siemens Healthineers launched capillary testing on the Atellica CH, IM, and CI Analyzers following CE marking for 24 capillary blood testing claims, including HbA1c, enabling laboratories to expand testing using existing analyzer infrastructure. Furthermore, in March 2026, F. Hoffmann-La Roche Ltd. announced significant diagnostics investments in Germany, including a new innovation center in Penzberg and a diagnostics distribution center in Mannheim, strengthening the country's diagnostic research, manufacturing, and supply capabilities.
Asia Pacific HbA1c Testing Devices Market Trends
The HbA1c testing devices industry in the Asia Pacific is expected to be the fastest-growing market, driven by a large and expanding diabetes population, high rates of undiagnosed disease, strengthening primary healthcare, and increasing adoption of advanced diagnostic technologies. The region benefits from rising laboratory capacity and growing demand for both laboratory-based and point-of-care HbA1c testing. According to the 2025 IDF Diabetes Atlas, approximately 215 million adults aged 20–79 years were living with diabetes in the Western Pacific in 2024, with nearly 108 million remaining undiagnosed, highlighting significant opportunities for early diagnosis and disease monitoring. Furthermore, in July 2024, China's National Health Commission introduced the Healthy China Action—Diabetes Prevention and Control Action Implementation Plan (2024–2030) to strengthen diabetes screening, primary care management, and the deployment of innovative diagnostic technologies nationwide.
The China HbA1c testing devices industry held a significant share of the Asia Pacific market in 2025, driven by its large diabetes population, expanding primary healthcare infrastructure, and the rapid growth of domestic diagnostics manufacturers. Increasing adoption of decentralized testing, portable analyzers, and integrated laboratory platforms is strengthening market expansion across community clinics and healthcare centers. In April 2026, Sinocare showcased an expanded diabetes diagnostics portfolio at the 93rd China International Medical Equipment Fair (CMEF) in Shanghai, featuring the PCH-50 portable HbA1c analyzer, which uses boronate-affinity liquid chromatography, delivers results in approximately 3.5 minutes, and supports LIS connectivity. Additionally, in April 2024, Sinocare launched the iCARE-1300 multifunction analyzer, expanding HbA1c testing capabilities across primary healthcare institutions and lower-throughput clinical settings.
The HbA1c testing devices industry in Japan represents one of the most technologically advanced markets in Asia Pacific, supported by strong domestic manufacturers, widespread adoption of HPLC technology, and continuous innovation in automated diabetes diagnostics. Demand is driven by the need for faster turnaround, compact analyzers, lower sample volumes, and improved laboratory efficiency across hospitals and diabetes clinics. In May 2026, Tosoh Corporation launched the HLC-723 GX2 automated glycohemoglobin analyzer in Japan, reducing analytical time from 2.2 minutes to 1.6 minutes per sample while minimizing interference from major hemoglobin variants. Furthermore, in August 2025, HORIBA launched the Yumizen Banalyst M120, a compact analyzer capable of delivering HbA1c results in approximately 5 minutes and 10 seconds from a 4 µL blood sample, supporting faster and more efficient diabetes testing workflows.
Latin America HbA1c Testing Devices Market Trends
The HbA1c testing devices industry in Latin America has emerged as a high-growth market, driven by a rising diabetes burden, a large undiagnosed population, expanding primary healthcare programs, and increasing adoption of standardized diabetes diagnostics. Growing investments in laboratory infrastructure and decentralized testing are further supporting market expansion across the region. According to the 2025 IDF Diabetes Atlas, approximately 35.4 million adults aged 20–79 years were living with diabetes across South and Central America in 2024, with around 11 million remaining undiagnosed. Furthermore, in February 2026, Brazil's Ministry of Health updated the national Clinical Protocol and Therapeutic Guidelines for Type 2 Diabetes, recognizing HbA1c as a method for diagnosing and monitoring diabetes, thereby supporting broader adoption of HbA1c testing across primary healthcare and hospital settings.
Middle East and Africa HbA1c Testing Devices Market Trends
The HbA1c testing devices industry in the Middle East & Africa (MEA) represents a high-potential market for HbA1c testing devices, driven by the rising diabetes burden, expanding government-led screening programs, improving laboratory infrastructure, and increasing adoption of structured diabetes management. Growing investments in healthcare modernization and decentralized diagnostic services are further supporting market growth across the region. According to the 2025 IDF Diabetes Atlas, approximately 84.7 million adults aged 20–79 years were living with diabetes in the Middle East and North Africa in 2024, while around 32 million remained undiagnosed. Furthermore, in October 2025, Saudi Arabia's Ministry of Health launched the Diabetes Command & Control Center, a nationwide platform for real-time diabetes monitoring and preventive care, strengthening long-term disease management and supporting greater utilization of HbA1c testing.
Key HbA1c Testing Devices Company Insights
The HbA1c testing devices market is moderately consolidated, with leading companies competing through product innovation, analytical accuracy, automation, regulatory approvals, and global distribution networks. Established players are strengthening their market positions by expanding high-throughput laboratory analyzers, point-of-care (POC) testing solutions, and integrated diabetes diagnostics portfolios. Strategic initiatives such as product launches, regulatory clearances, geographic expansion, distribution partnerships, and investments in digital connectivity and workflow automation remain central to competitive strategies. In addition, companies are focusing on improving testing speed, reducing hemoglobin variant interference, enhancing laboratory connectivity, and expanding recurring revenue through reagents and consumables. Emerging manufacturers are increasing competition by introducing compact, cost-effective HbA1c analyzers and targeting underserved regional markets, particularly across Asia Pacific and other emerging economies.
Key HbA1c Testing Devices Companies
The following key companies have been profiled for this study on the HbA1c Testing Devices Market.
-
Bio-Rad Laboratories, Inc.
-
Abbott
-
F. Hoffmann-La Roche Ltd
-
Siemens Healthineers AG
-
HUMAN
-
Trinity Biotech
-
Menarini Diagnostics s.r.l
-
SAKAE CO. LTD.
-
Ceragem Medisys Inc
-
SEKISUI MEDICAL CO., LTD.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Bio-Rad Laboratories, Inc., Abbott, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Tosoh Corporation, ARKRAY, Inc
- Leverage established HbA1c franchises across central laboratories and point-of-care settings, with portfolios spanning HPLC, immunoassay, enzymatic assays, and cartridge-based POC testing. Bio-Rad and ARKRAY maintain extensive HPLC portfolios, while Abbott and Siemens have strong POC offerings and Roche integrates HbA1c into its cobas clinical chemistry ecosystem.
- Strengthen recurring revenues through proprietary reagents, cartridges, columns, calibrators, and controls, while emphasizing NGSP/IFCC standardization and integration with laboratory and hospital information systems.
- Strong brand recognition and established HbA1c product franchises, supported by long-term relationships with hospital laboratories, diagnostic laboratories, clinics, and healthcare networks.
- Broad technology coverage enables companies to address high-volume centralized laboratories as well as decentralized POC environments. Abbott's Afinion 2, for example, delivers HbA1c results in approximately three minutes, while ARKRAY's HA-8190V HPLC system can process HbA1c samples in 24 seconds in fast mode.
- Large organizational structures and sizeable legacy product portfolios may reduce speed of product repositioning compared with smaller HbA1c-focused competitors.
- Premium automated platforms and proprietary reagent or cartridge ecosystems can create higher acquisition or ongoing testing costs, potentially limiting penetration among highly price-sensitive laboratories and healthcare systems.
Emerging Players: Trinity Biotech, EKF Diagnostics Holdings plc, A. Menarini Diagnostics s.r.l, Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
- Focus on differentiated HbA1c technologies and targeted workflow niches. Trinity Biotech is strengthening its boronate-affinity Premier Hb9210 platform, while EKF targets decentralized testing with Quo-Test and Quo-Lab using boronate fluorescence quenching technology.
- Expand through product-performance improvements and regulatory and geographic penetration. Trinity expanded its high-capacity Hb9210 column rollout in 2025 and received IFCC Gold Classification for the Premier Hb9210 in 2026.
- Greater specialization and product focus allow these players to address specific unmet requirements such as hemoglobin-variant interference, affordable decentralized testing, compact laboratory workflows, and integration with existing chemistry infrastructure.
- Smaller and more focused portfolios can enable faster targeting of regional laboratories, diabetes clinics, and price-sensitive customers, particularly where compact instrumentation and operational simplicity are important.
- Relative to major multinational diagnostics companies, these players generally have a smaller HbA1c installed base and commercial footprint in some markets, potentially limiting rapid customer conversion.
- Narrower instrument and assay ecosystems may provide fewer cross-platform laboratory consolidation opportunities than companies such as Roche or Siemens, which can integrate HbA1c into much broader chemistry portfolios.
Recent Developments
-
In June 2026, HORIBA announced the introduction of the MQ-3000 and MQ-8000 HbA1c analyzers in the U.S. through a strategic partnership with MEDCONN Diagnostics. The collaboration expands HORIBA's diagnostics portfolio into dedicated HPLC-based HbA1c testing while strengthening clinical laboratory capabilities across the U.S. diabetes diagnostics market.
-
In May 2026, Tosoh Corporation launched the HLC-723GX2 automated glycohemoglobin analyzer, a next-generation compact HPLC system for HbA1c testing. The analyzer reduced testing time from 2.2 minutes to 1.6 minutes per sample and features a smaller footprint, supporting faster and more efficient diabetes testing workflows.
-
In December 2025, Trinity Biotech announced the expanded global rollout of its high-capacity column system for the FDA-cleared Premier Hb9210 HbA1c testing platform. The upgraded column provides up to four times the testing capacity of the previous system while reducing downtime, maintenance requirements, and operator workload, improving laboratory efficiency for high-volume HbA1c testing.
-
In September 2025, ARKRAY, Inc. announced an agreement to transfer the manufacturing and sales rights for its CinQ HbA1c in-vitro diagnostic reagent to Shino-Test Corporation, with the transfer scheduled for 2026. The agreement is expected to strengthen product commercialization and expand the availability of HbA1c diagnostic solutions through Shino-Test's manufacturing and distribution capabilities.
-
In July 2024, F. Hoffmann-La Roche Ltd. completed the acquisition of LumiraDx's Point of Care technology, including its multi-assay POC platform, research and development capabilities, and related commercial operations. The acquisition expands Roche's decentralized diagnostics portfolio, strengthens its point-of-care testing capabilities, and complements its clinical chemistry and immunochemistry businesses, supporting broader access to rapid HbA1c testing.
HbA1c Testing Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.4 billion
Estimated market size in 2026
USD 2.6 billion
Projected market size by 2033
USD 4.2 billion
Growth rate
CAGR of 7.3% from 2026 to 2033
Actual Data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, technology, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; and MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Bio-Rad Laboratories, Inc.; Abbott; F. Hoffmann-La Roche Ltd; Siemens Healthineers AG; HUMAN; Trinity Biotech; Menarini Diagnostics s.r.l.; SAKAE CO. LTD.; Ceragem Medisys Inc.; SEKISUI MEDICAL CO., LTD.
Customization scope
Free report customization (equivalent up to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global HbA1c Testing Devices Market Report Segmentation
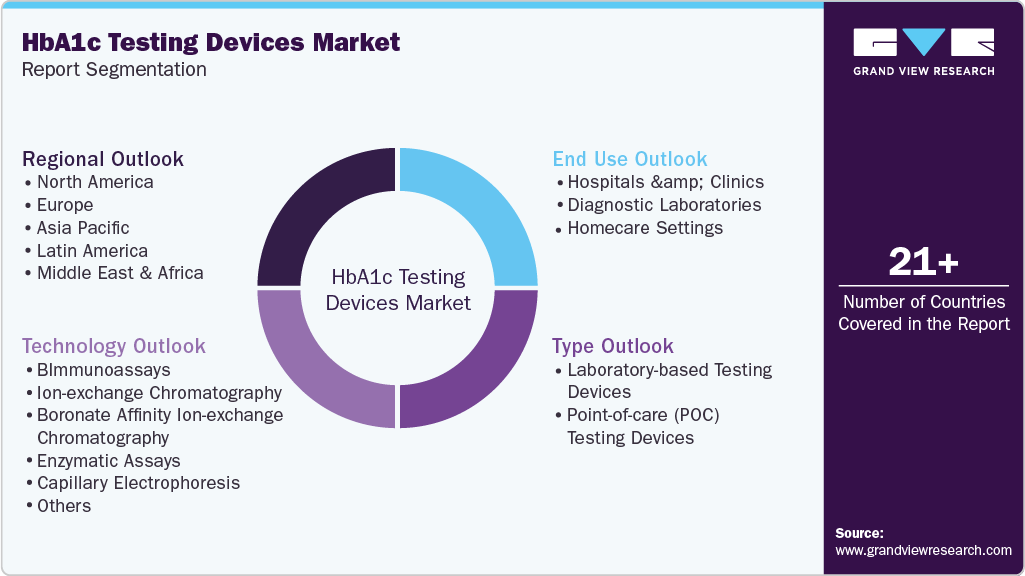
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global Hba1c testing devices market report based on type, technology, end use, and region:
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Laboratory-based Testing Devices
-
Point-of-care (POC) Testing Devices
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Immunoassays
-
Ion-exchange Chromatography
-
Boronate Affinity Ion-exchange Chromatography
-
Enzymatic Assays
-
Capillary Electrophoresis
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals & Clinics
-
Diagnostic Laboratories
-
Homecare Settings
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
Kuwait
-
UAE
-
-
Research Methodology
The HbA1c testing devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each HbA1c testing devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Type
Revenue capture definition
Laboratory-based Testing Devices
Includes high-throughput HbA1c analyzers installed in hospitals, diagnostic laboratories, and reference laboratories for centralized testing. Revenue is primarily captured through analyzer placements, replacement systems, service contracts, and recurring sales of reagents, columns, calibrators, and quality-control materials.
Point-of-care (POC) Testing Devices
Covers compact HbA1c analyzers used in physician offices, outpatient clinics, pharmacies, community healthcare centers, and homecare settings for near-patient testing. Revenue flows from instrument sales, disposable test cartridges, consumables, maintenance services, software connectivity, and replacement of portable testing systems.
Segment – Technology
Revenue capture definition
Immunoassays
Includes HbA1c testing systems that quantify glycated hemoglobin using antigen-antibody reactions on automated clinical chemistry and immunochemistry analyzers. Market value is captured through analyzer utilization, assay kits, reagents, calibrators, controls, and ongoing consumable replenishment.
Ion-exchange Chromatography
Covers HbA1c analyzers that separate hemoglobin fractions based on ionic charge using HPLC technology. Commercial value is derived from analyzer installations, chromatography columns, buffers, reagents, maintenance services, and periodic system upgrades in high-volume laboratories.
Boronate Affinity Chromatography
Encompasses HbA1c testing platforms that selectively bind glycated hemoglobin using boronate affinity technology, minimizing interference from hemoglobin variants. Revenue streams originate from dedicated analyzers, affinity columns, reagent cartridges, quality-control materials, and replacement consumables.
Enzymatic Assays
Includes HbA1c measurement methods based on enzyme-mediated reactions performed on routine clinical chemistry analyzers. Revenue is primarily realized through assay reagents, enzyme kits, calibrators, controls, and utilization of existing automated chemistry platforms.
Capillary Electrophoresis
Covers HbA1c testing systems that separate hemoglobin fractions using electrophoretic migration in capillaries for highly standardized analysis. Business value is captured through electrophoresis instruments, separation reagents, capillary consumables, maintenance contracts, and laboratory service support.
Others
Includes alternative HbA1c measurement technologies not classified under the primary methods, such as emerging or niche analytical platforms. Revenue contribution arises from specialized instruments, proprietary assays, consumables, software, and associated technical support services.
Segment –End use
Revenue capture definition
Hospitals & Clinics
Includes HbA1c testing devices deployed in hospitals, specialty clinics, and outpatient facilities for diabetes diagnosis and long-term glycemic monitoring. Revenue is primarily captured through instrument procurement, routine test volumes, consumables, maintenance agreements, and software integration.
Diagnostic Laboratories
Covers independent, reference, and commercial laboratories performing centralized HbA1c testing for healthcare providers. Revenue flows from high-throughput analyzer utilization, recurring reagent and column purchases, calibrators, quality-control materials, laboratory service contracts, and replacement instruments.
Homecare Settings
Encompasses HbA1c testing devices designed for self-monitoring by patients in home environments. Commercial value is generated through portable device sales, single-use test cartridges, lancets, consumables, digital connectivity solutions, and replacement testing kits.
Estimation Model
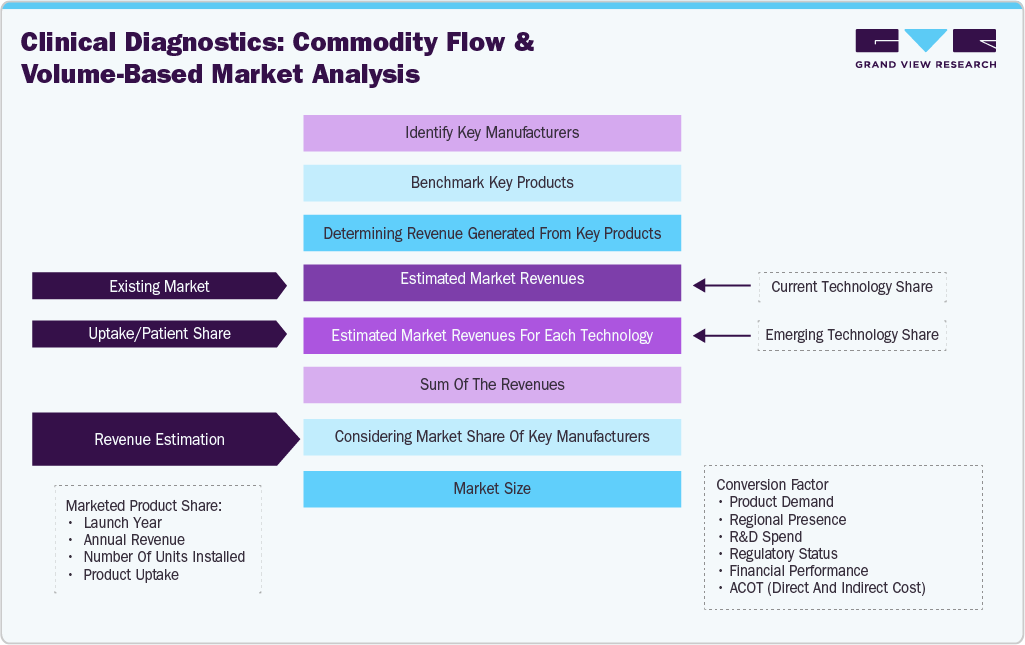
The HbA1c Testing Devices Market size was estimated using a bottom-up approach by identifying key manufacturers, benchmarking their HbA1c testing portfolios, and analyzing product-level revenues. Technology-wise revenue was derived using patient uptake and adoption rates, followed by aggregation across segments and validation through market share analysis of leading companies, primary interviews, and secondary research to determine the final market size.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
HbA1c Testing Devices Competitive Landscape & Technology Assessment
Assessed the market across laboratory-based and POC testing devices, key technologies, and leading manufacturers. Evaluated product portfolios, competitive positioning, technology adoption, regulatory approvals, commercialization strategies, and regional competitive dynamics across major end users.
Enabled the client to identify high-growth technologies, benchmark competitors, evaluate product differentiation, prioritize investments in advanced HbA1c testing platforms, and understand technology adoption trends shaping the global market..
HbA1c Testing Devices Product Benchmarking Study
Benchmarked HbA1c testing solutions based on analytical accuracy, throughput, automation, connectivity, hemoglobin variant detection, regulatory status, and product differentiation across leading companies. Compared laboratory-based and point-of-care platforms to identify technology strengths and performance gaps.
Helped the client compare product competitiveness, identify innovation opportunities, benchmark next-generation laboratory and point-of-care analyzers, and prioritize investments in advanced diabetes diagnostic technologies.
HbA1c Testing Devices Commercialization & Market Entry Assessment
Assessed commercialization strategies, regulatory pathways, reimbursement, distribution networks, adoption trends, strategic partnerships, and market readiness across key healthcare settings. Analyzed regional opportunities, procurement trends, and adoption barriers influencing market expansion.
Supported commercialization planning by identifying high-potential regional opportunities, evaluating partnership and distribution strategies, assessing regulatory and reimbursement requirements, mitigating market-entry risks, and strengthening long-term growth strategies within the HbA1c testing devices market.
Frequently Asked Questions About This Report
Some key players operating in the HbA1c testing devices market include Bio-Rad Laboratories, Inc., Abbott, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, HUMAN, Trinity Biotech, Menarini Diagnostics s.r.l, SAKAE CO. LTD., Ceragem Medisys Inc, and SEKISUI MEDICAL CO., LTD.
Key factors that are driving the market growth include increasing diabetes prevalence, technological advancement in clinical diagnostics, and an increasing focus on research for development of novel diagnostics in the market.
By type, the Point-of-care (POC) Testing Devices segment led the market with the largest revenue share of 45.6% in 2025.
By technology, the Ion-exchange Chromatography segment led the market with the largest revenue share of 33.6% in 2025.
Asia Pacific is expected to be one of the fastest-growing markets for HbA1c testing devices, driven by a large and expanding diabetes population, high rates of undiagnosed disease, strengthening primary healthcare, and increasing adoption of advanced diagnostic technologies
The increasing number of product launches and portfolio expansions is creating a significant growth opportunity for the global HbA1c testing devices market. Manufacturers are continuously strengthening their HbA1c portfolios to address evolving requirements across central laboratories, hospitals, diabetes clinics, physician offices, pharmacies, and primary care facilities.
The global HbA1c testing devices market size was valued at USD 2.4 billion in 2025 and is estimated at USD 2.6 billion for 2026.
The global HbA1c testing devices market is expected to grow at a CAGR of 7.3% from 2026 to 2033, reaching USD 4.2 billion by 2033.
North America dominated the AI in cytology screening device market with the largest revenue share of 33.8% in 2025
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


