
- Home
- »
- Healthcare IT
- »
-
Healthcare Interoperability Solutions Market Report, 2026-2033GVR Report cover

Healthcare Interoperability Solutions Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Solutions, Services), By Level, By Application, By Deployment Method, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$4.5BMarket Estimate, 2026
$5.1BMarket Forecast, 2033
$12.9BCAGR, 2026–2033
14.2%Healthcare Interoperability Solutions Market Summary
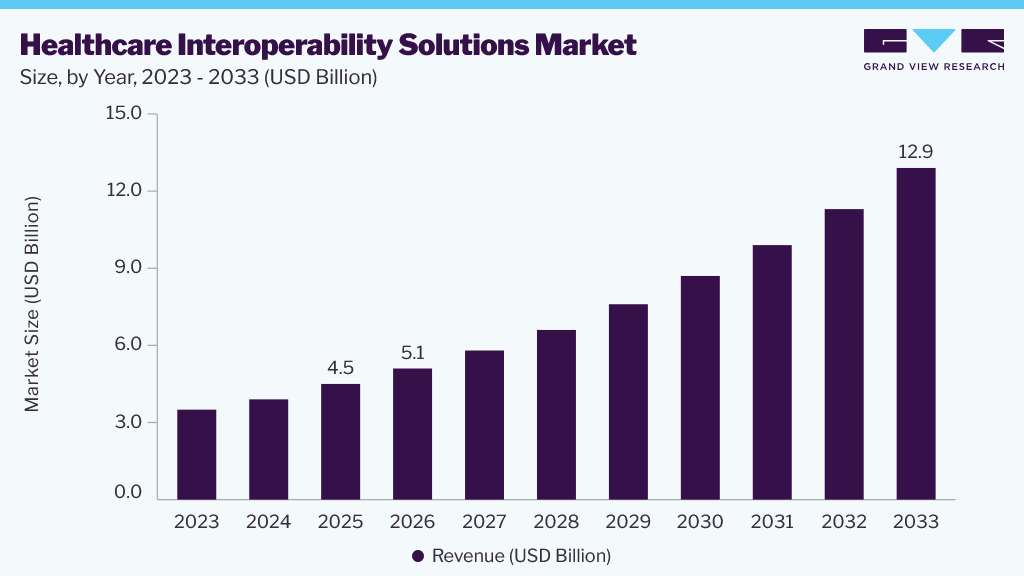
The global healthcare interoperability solutions market size was valued at USD 4.5 billion in 2025 and is projected to grow from USD 5.1 billion in 2026 to USD 12.9 billion in 2033, at a CAGR of 14.2% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 41.0% in 2025. An increase in the adoption of interoperability solutions by healthcare authorities, rising investments to enhance healthcare facilities, favorable government initiatives to improve patient care, high government funding, and a focus on patient-centric care are major factors propelling market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: The services segment led the market with the largest revenue share of approximately 55.0% in 2025.
- By level: The structural segment led the market with the largest revenue share in 2025.
- By deployment: The on-premise segment led the market with the largest revenue share in 2025.
- By application: The diagnosis segment held the market in 2025.
- By end use: The hospital segment dominated the market with the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (41.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 4.5 Billion
- Estimated market size in 2026: USD 5.1 Billion
- Projected market size by 2033: USD 12.9 Billion
- CAGR (2026-2033): 14.2%
Prism AI by Grand View Research Free to tryAsk a question about the healthcare interoperability solutions marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Several governments are promoting information interoperability through campaigns and programs as the demand for high-quality healthcare increases. For instance, in March 2025, the European Health Data Space (EHDS) Regulation entered into force in the European Union, establishing a framework for the secure exchange and access of electronic health data across member states. The initiative is expected to enhance cross-border interoperability, improve patient care, and support healthcare innovation. Similarly, governments across North America and the Asia Pacific are expanding investments in digital health infrastructure and interoperable electronic health record (EHR) systems to strengthen healthcare delivery. Such government initiatives and public-sector investments are anticipated to support market growth.
Furthermore, interoperability is expected to reduce the overall costs associated with delayed diagnosis and treatment by providing timely access to healthcare data. However, increasing system complexity, lack of standardized data formats, and data privacy concerns are key factors that may hinder the adoption of interoperability solutions over the forecast period.
Healthcare interoperability offers several benefits, including improved clinical decision-making, efficient care delivery, reduced duplication of diagnostic procedures, and better coordination across healthcare systems. It also supports secure data sharing among healthcare stakeholders and enables faster access to patient information, which is expected to contribute to wider adoption over the forecast period.
Analyst Perspective
The market is experiencing significant growth, driven by the increasing digitalization of healthcare systems, regulatory initiatives that promote standardized data exchange, and the rising adoption of electronic health records (EHRs), telehealth, and cloud-based healthcare IT solutions. Interoperability is increasingly becoming an essential component of modern healthcare infrastructure, supporting efficient information exchange across providers, payers, pharmacies, laboratories, and public health organizations.
Type Insights
The services segment led the market with the largest revenue share, at approximately 55.0% in 2025. This can be attributed to the paradigm shift toward cloud computing & cloud-based platforms to reduce operational costs and improve the performance of business applications & processes. Furthermore, repeat purchases of services, including software updates and maintenance, contribute to segment growth. In addition, organizations are expanding their interoperability service capabilities to facilitate the secure exchange of health information. For instance, in May 2025, Oracle Health Information Network achieved Candidate Qualified Health Information Network (QHIN) status under the Trusted Exchange Framework and Common Agreement (TEFCA), enabling the company to advance nationwide interoperable health data exchange and strengthen its interoperability service offerings for healthcare providers, payers, and government agencies. Such strategic developments are expected to boost demand for interoperability implementation and managed services, thereby supporting the growth of the services segment.
The solutions segment is anticipated to witness the fastest CAGR over the forecast period. The solutions segment is further bifurcated into EHR interoperability, HIE interoperability, enterprise interoperability, and others. The demand for the segment is anticipated to increase due to the rising need for greater access to patient health information and the growing implementation of healthcare IT solutions to improve care quality & enhance patient satisfaction. In addition, increasing demand for seamless data integration across multiple healthcare systems and growing emphasis on improving care coordination are further driving segment growth. Rising regulatory focus on healthcare data standardization and interoperability compliance is also accelerating the adoption of interoperability solutions. For instance, the increasing adoption of standards such as HL7 and FHIR across healthcare organizations is enhancing interoperability capabilities by enabling efficient and secure exchange of patient health information across platforms.
Level Insights
The structural segment led the market with the largest revenue share in 2025, owing to the high adoption of technologies such as e-prescribing, in which prescribers and pharmacists use the same data. The segment is also benefiting from increasing demand for standardized data formatting and structured data exchange across healthcare systems, enabling seamless communication between disparate platforms. For instance, in June 2025, HL7 International and openEHR announced a strategic collaboration to align the HL7 Fast Healthcare Interoperability Resources (FHIR) and openEHR standards to improve semantic and structural interoperability across healthcare systems worldwide. The initiative aims to enhance standardized health data exchange, facilitate seamless integration between electronic health record (EHR) systems, and accelerate the adoption of interoperable healthcare information systems. Such developments are expected to support the growth of the structural segment.
Foundational is projected to witness the fastest CAGR over the forecast period. It enables basic data exchange between systems. This level is vital for establishing the interconnectivity requirements that enable one system to securely communicate with another. The segment is expected to grow due to increasing demand for seamless healthcare data exchange across disparate systems and rising adoption of digital health infrastructure among healthcare providers. The growing emphasis on improving communication among healthcare stakeholders and reducing data silos is supporting segment growth. For instance, the increasing adoption of standards such as HL7 and FHIR across healthcare organizations is strengthening foundational interoperability by enabling secure and efficient exchange of patient information between systems.
Deployment Methods Insights
The on-premise segment led the market with the largest revenue share in 2025, owing to increasing demand for data exchange. The key providers operating in the industry are offering novel on-premises solutions. The segment continues to benefit from growing concerns regarding data security and privacy, encouraging healthcare organizations to maintain greater control over sensitive patient information. In addition, increasing preference for customized infrastructure and better integration with existing legacy systems is supporting the adoption of on-premise interoperability solutions.
Cloud-based is projected to witness the fastest CAGR over the forecast period. This software enables safe and efficient data exchange in less time. Broader information exchange is possible with this cloud-based software. Moreover, the increasing focus of industry participants on cloud-based platforms is expected to propel the segment growth. Several industry players are launching cloud-based platforms for exchanging healthcare data. Furthermore, the rising adoption of scalable digital healthcare infrastructure and the increasing demand for remote access are accelerating segment growth. In addition, lower upfront infrastructure costs and improved deployment flexibility are further encouraging healthcare providers to adopt cloud-based interoperability solutions.
Application Insights
Diagnosis accounted for the largest share of revenue in 2025. This can be attributed to the growing need for effective information flow in diagnosing diseases. Accurate and timely diagnoses enable healthcare professionals to fully assess patients’ conditions, including information such as medical history & allergies. The increasing adoption of electronic health records and the growing demand for real-time access to patient data across healthcare systems are further supporting segment growth. In addition, rising emphasis on improving clinical decision-making and reducing diagnostic errors is accelerating the adoption of interoperability solutions for diagnostic applications.
The other segment is projected to witness the fastest CAGR over the forecast period. The demand for the segment is expected to increase due to growing focus on the digitalization of healthcare infrastructure and rising adoption of interoperability products and services by market participants. Furthermore, increasing investments in connected healthcare ecosystems and the growing need for seamless data exchange across multiple care settings are expected to drive segment growth. In addition, rising demand for integrated healthcare workflows and enhanced operational efficiency is further contributing to market expansion.
End Use Insights
The hospital segment dominated the market, accounting for the largest revenue share in 2025, driven by the increasing adoption of interoperability platforms across hospitals. According to data published by the Office of the National Coordinator for Health Information Technology (ONC), 76% of U.S. hospitals engaged in all four domains of interoperable exchange, sending, receiving, finding, and integrating electronic health information, in 2025, reflecting continued progress in hospital-level interoperability adoption. Furthermore, ONC reported that approximately 9 in 10 hospitals enabled patient access to health information via APIs in 2024, highlighting growing investments in connected healthcare infrastructure. Thus, rising demand from hospitals for seamless health information exchange solutions is expected to support segment growth.
The ambulatory surgical centers segment is projected to witness the fastest CAGR over the forecast period. As ambulatory surgical centers conduct more complex procedures, they are increasingly focusing on digital tools. The growing need for seamless data exchange across care settings to improve operational efficiency is further supporting the adoption of interoperability solutions in these facilities. In addition, rising patient volumes and increasing emphasis on coordinated care are encouraging ambulatory surgical centers to invest in integrated healthcare IT infrastructure.
Regional Insights
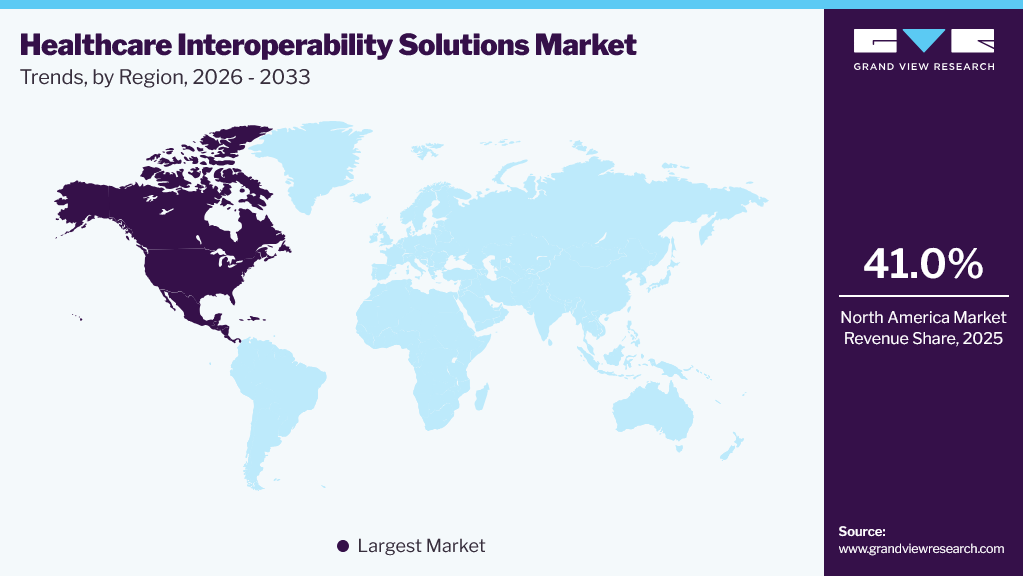
North America dominated the market, accounting for approximately 41.0% of revenue in 2025. The rise in demand for efficient healthcare services, the need to reduce healthcare expenditure, and the effective implementation of EHRs by healthcare organizations are major factors driving the adoption of interoperability solutions in this region. In addition, increasing government support for healthcare data exchange and interoperability standards is expected to further drive regional market growth.
 To learn more about this report, Download Free Sample Report
U.S. Healthcare Interoperability Solutions Market Trends
The healthcare interoperability solutions market in the U.S. is expected to grow at the fastest CAGR over the forecast period due to several U.S. government initiatives aimed at increasing access to interoperability solutions. For instance, in July 2025, the Assistant Secretary for Technology Policy/Office of the National Coordinator for Health Information Technology (ASTP/ONC) released the United States Core Data for Interoperability (USCDI) Version 6, introducing new standardized health data elements to further enhance interoperability across healthcare systems and support more consistent electronic health information exchange nationwide. Such favorable government initiatives are expected to support the regional market expansion.
Europe Healthcare Interoperability Solutions Market Trends
The healthcare interoperability solutions market in Europe was identified as a lucrative region in this industry. This growth is attributable to the increasing focus by industry participants on the regional market and the rising number of favorable initiatives launched by European government authorities. In addition, industry stakeholders are organizing events and conferences to raise awareness and knowledge of healthcare interoperability systems. For instance, in April 2026, NHS England reported that the Federated Data Platform is being adopted across NHS organizations to securely integrate patient and operational data, improving clinical decision-making, patient flow, and healthcare service delivery. Such government-led initiatives to strengthen connected healthcare systems are anticipated to propel the regional market.
The UK healthcare interoperability solutions market is expected to grow at the fastest CAGR over the forecast period due to the presence of major industry players such as Oracle (Cerner) and the increasing focus of government bodies on improving interoperability in the medical field. Authorities such as NHS England are providing an interoperability framework and a Data Standards Directory, which can help propel the country's market.
The healthcare interoperability solutions market in France is expected to grow over the forecast period due to rising healthcare costs and increasing adoption of healthcare interoperability solutions and digital platforms. In addition, growing government investments in healthcare digitalization and increasing emphasis on improving care coordination across healthcare facilities are expected to support market growth. Furthermore, the rising adoption of electronic health records and increasing focus on secure health data exchange are further contributing to the expansion of the market in France.
Asia Pacific Healthcare Interoperability Solutions Market Trends
The healthcare interoperability solutions market in the Asia Pacific is anticipated to witness the fastest CAGR over the forecast period. The regional market is expected to be driven by the rising demand for quality healthcare and increasing government expenditure on healthcare facilities. In addition, the rapid adoption of digital health infrastructure and electronic health records across developing economies is expected to support market growth.
China healthcare interoperability solutions market is expected to grow at the fastest CAGR over the forecast period due to the large patient pool in this highly populated country, which generates substantial data annually, creating a need for effective data exchange among pharmacies and hospitals. Furthermore, increased investment in healthcare digitalization and smart hospital development is expected to drive market expansion.
The healthcare interoperability solutions market in Japan is expected to grow at the fastest CAGR during the forecast period due to the increasing number of digital healthcare platform launches in the country. In addition, the presence of major players such as FUJITSU and their expansion strategies, such as partnerships and product launches, is expected to propel the country's growth. Moreover, growing adoption of cloud-based healthcare IT systems is expected to further accelerate market growth in the country.
Key Healthcare Interoperability Solutions Company Insights
Some of the leading players operating in the global market include Infor, Koninklijke Philips N.V., Oracle, Orion Health Group of Companies, NXGN Management, LLC, OSP, Epic Systems Corporation, ViSolve.com, InterSystems Corporation, iNTERFACEWARE Inc., Jitterbit, and Veradigm LLC, among others. These companies are focusing on expanding their market presence through product innovation, platform enhancements, strategic partnerships, and acquisitions to strengthen their competitive position in the industry.
Market participants are increasingly investing in advanced interoperability solutions to support seamless data exchange across healthcare systems, improve care coordination, and enhance operational efficiency. Companies are also emphasizing cloud-based integration platforms, API-enabled connectivity, and electronic health record interoperability to address the growing demand for connected healthcare infrastructure.
Key Healthcare Interoperability Solutions Companies
The following key companies have been profiled for this study on the healthcare interoperability solutions market:
-
Infor
-
Koninklijke Philips N.V.
-
Oracle
-
Orion Health group of companies.
-
NXGN Management, LLC.
-
OSP
-
Epic Systems Corporation
-
ViSolve.com
-
InterSystems Corporation
-
iNTERFACEWARE Inc.
-
Jitterbit
-
Veradigm LLC
Recent Developments
-
In June 2026, the Indian National Health Authority, under the Ministry of Health and Family Welfare, announced the launch of multiple digital health initiatives, including Aarogya Setu 2.0, new provider-centric solutions, health registries, and electronic health record (EHR) data standards under the Ayushman Bharat Digital Mission. These initiatives are designed to strengthen healthcare interoperability, expand access to digital health services, and enable secure, standardized exchange of electronic health information across India's healthcare ecosystem.
-
In August 2025, Oracle introduced its next-generation AI-driven electronic health record (EHR), designed to embed artificial intelligence directly into clinical workflows. The new platform features AI-powered clinical documentation, intelligent chart summarization, conversational search, automated workflow assistance, and advanced decision support, enabling healthcare providers to reduce administrative burden, improve care coordination, and enhance clinical efficiency. The launch reinforces Oracle's strategy to modernize healthcare IT through cloud-native, AI-enabled, and interoperable EHR solutions.
Healthcare Interoperability Solutions Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.5 billion
Estimated market size in 2026
USD 5.1 billion
Projected market size by 2033
USD 12.9 billion
Growth rate
CAGR of 14.2% from 2026 to 2033
Base year estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, level, deployment methods, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; Denmark; Sweden; Russia; Norway; China; Japan; India; South Korea; Australia; Singapore; Thailand; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Infor; Koninklijke Philips N.V.; Oracle; Orion Health group of companies; NXGN Management, LLC.; OSP; Epic Systems Corporation; ViSolve.com; InterSystems Corporation; iNTERFACEWARE Inc.; Jitterbit; Veradigm LLC.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Healthcare Interoperability Solutions Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global Healthcare Interoperability Solutions market report based on type, level, deployment methods, application, end use, and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Solutions
-
EHR Interoperability
-
HIE Interoperability
-
Enterprise Interoperability
-
Others
-
-
Services
-
-
Level Outlook (Revenue, USD Million, 2021 - 2033)
-
Foundational
-
Structural
-
Semantic
-
-
Deployment Methods Outlook (Revenue, USD Million, 2021 - 2033)
-
Cloud Based
-
On-premise
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Diagnosis
-
Treatment
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgical Centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Russia
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Singapore
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global healthcare interoperability solutions market size was valued at USD 4.5 billion in 2025 and is estimated at USD 5.1 billion in 2026
Key factors that are driving the healthcare interoperability solutions market growth include increase in the adoption of interoperability solutions by healthcare authorities, rise in investments to enhance healthcare facilities, favorable government initiatives to improve patient care, high government funding, and focus on patient-centric care.
Asia Pacific is the fastest-growing region over the forecast period.
The global healthcare interoperability solutions market is expected to grow at a compound annual growth rate of 14.2% from 2026 to 2033, reaching USD 12.9 billion by 2033
Services segment dominated the market, with a revenue share of 55.0% in 2025 while solutions segment is expected to be the fastest-growing market.
The structural segment led the market with the largest revenue share in 2025
The on-premise segment led the market with the largest revenue share in 2025
North America dominated the healthcare interoperability solutions market with a share of 41.0% in 2025.
Some key players operating in the healthcare interoperability solutions market include Infor, Koninklijke Philips N.V., Oracle, Orion Health group of companies, NXGN Management, LLC., OSP, Epic Systems Corporation, ViSolve.com, InterSystems Corporation, iNTERFACEWARE Inc., Jitterbit, Veradigm LLC., and others.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


