
- Home
- »
- Clinical Diagnostics
- »
-
Helicobacter Pylori Diagnostics Market Report, 2026-2033GVR Report cover

Helicobacter Pylori Diagnostics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Instruments, Reagents, Services), By Technology (Immunoassays, POC, Molecular Diagnostics), By End Use, By Region And Segment Forecasts
Market Size, 2025
$740.9MMarket Estimate, 2026
$784.4MMarket Forecast, 2033
$1,106.4MCAGR, 2026–2033
5.0%Helicobacter Pylori Diagnostics Market Summary
The global helicobacter pylori diagnostics market size was valued at USD 740.9 million in 2025 and is projected to grow from USD 784.4 million in 2026 to USD 1,106.4 million by 2033, at a CAGR of 5.0% from 2026 to 2033. The market in North America dominated with a revenue share of 47.8% in 2025. North America dominated the market, accounting for a 48.0% revenue share in 2024. The increasing risk of developing gastritis, gastric ulcers, and stomach cancer, among others, has led to an increase in the demand for the diagnosis of helicobacter pylori at an early stage of infection.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Reagents segment held the largest market share of 44.7% in 2025.
- By end use: Hospitals segment held the largest market share of 44.6% in 2025.
- By technology: Immunoassays segment held the largest market share of 43.6% in 2025.
Regional Highlights
- Largest regional market: North America (47.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 740.9 Million
- Estimated market size in 2026: USD 784.4 Million
- Projected market size by 2033: USD 1,106.4 Million
- CAGR (2026-2033): 5.0%
Prism AI by Grand View Research Free to tryAsk a question about the helicobacter pylori diagnostics marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Moreover, the increasing geriatric population and growing adoption of non-invasive diagnostic techniques are further anticipated to increase the market growth. For instance, according to the National Library of Medicine, about 10% of H.pylori-infected individuals develop a peptic ulcer, and 1 to 3% of people develop gastric adenocarcinoma.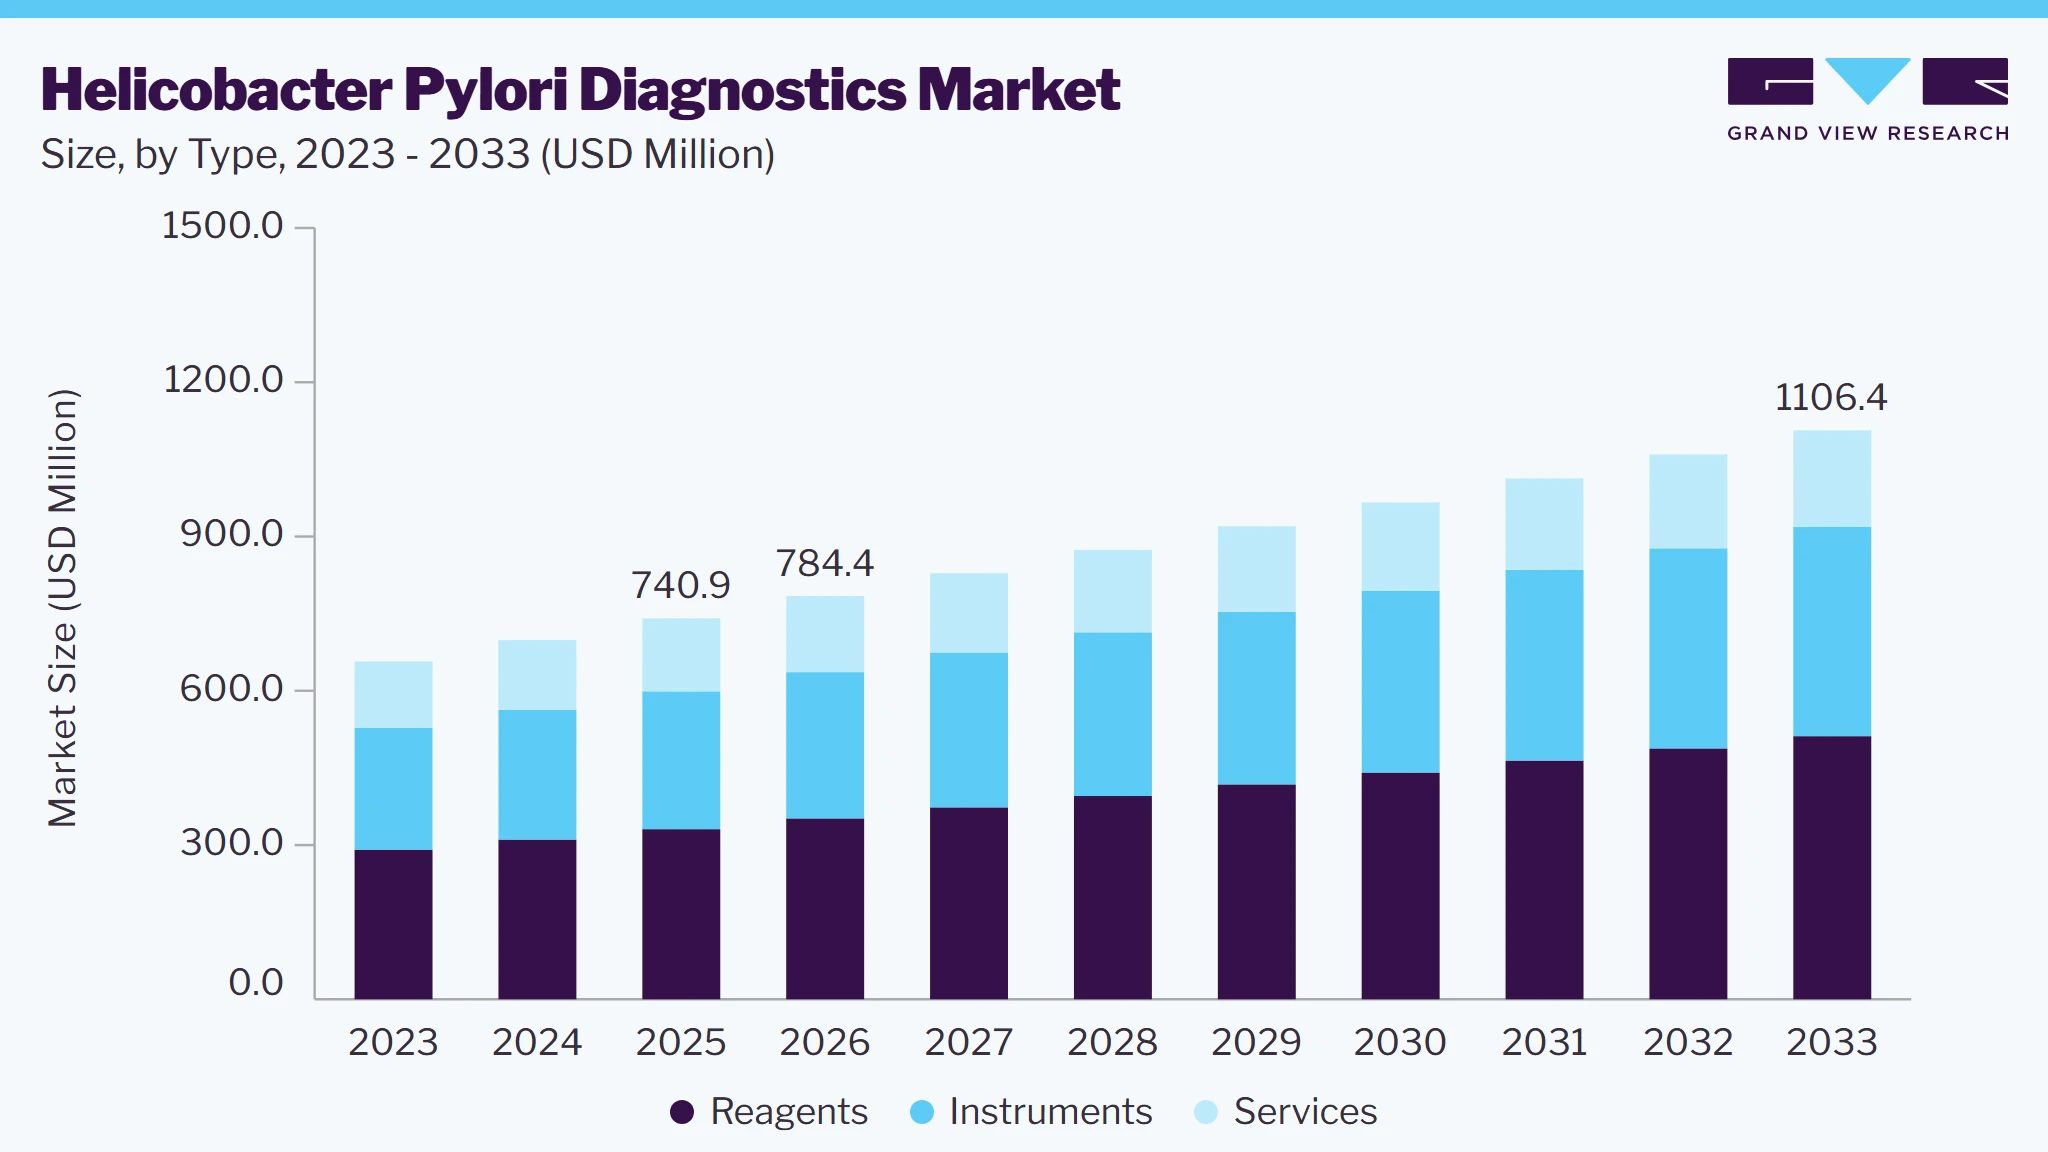 To learn more about this report, Download Free Sample Report
Helicobacter pylori, a bacterium linked to chronic gastritis, peptic ulcer disease, and gastric cancer, continues to drive advancements in diagnostic and therapeutic solutions. In recent years, groundbreaking developments have been seen, particularly in nanotechnology, which offers potential alternatives to traditional endoscopic procedures. Biosensors, capable of detecting antigens or antibodies associated with H. pylori, have emerged as a promising innovation. These devices leverage piezoelectric, thermal, and sensor array technologies to produce precise results, presenting a less invasive and cost-effective diagnostic approach compared to PCR tests and immunoassays.
PCR and real-time PCR testing have revolutionized the diagnosis of Helicobacter pylori, providing high specificity and sensitivity. These techniques can identify H. pylori in diverse sample types, including stomach biopsy, digestive fluid, saliva, dental plaque, and stool. PCR's ability to detect spiral and coccoid forms of H. pylori makes it superior to many traditional diagnostic methods. In addition, PCR's capability to analyze DNA from mailed urease test samples without strict transportation requirements further enhances its practicality. However, its utility in stool samples may be constrained by low DNA copy numbers and PCR inhibitors. Despite these challenges, real-time PCR with fluorescence resonance energy transfer probes is emerging as a promising tool for assessing clarithromycin resistance with exceptional accuracy. However, the cost, equipment, and technical expertise required for PCR limit its widespread adoption, particularly in developing countries.
Peptide Mass Fingerprinting (PMF) technology, exemplified by MALDI-TOF MS, offers a rapid, cost-effective, and accurate approach to identifying and characterizing microorganisms, including H. pylori. This method uses an ultraviolet laser to ionize microbial biomass and sorts particles based on mass-to-charge ratios. MALDI-TOF MS has been instrumental in building a comprehensive Helicobacter library, enabling differentiation between various Helicobacter species and even detecting antibiotic resistance. The system has been enhanced with specialized software like Compass Explorer 4.1 to create main spectrum library (MSP) dendrograms, aiding in precise species identification. This technology's ability to identify antimicrobial resistance and support demographic research highlights its role in managing bacterial infections and informing public health initiatives. MALDI-TOF MS represents a significant advancement in clinical microbiology, offering a powerful tool for diagnosing H. pylori and other pathogens. Together, PCR and PMF technologies are shaping the future of H. pylori diagnostics, offering precise, efficient, and innovative approaches to detection and management.
Furthermore, Meridian Bioscience recently expanded its H. pylori product line with the FDA-cleared Premier HpSA FLEX. This non-invasive stool antigen test detects H. pylori-specific antigens in fresh, frozen, or preserved samples. Its enhanced workflow allows greater flexibility in sample types, aligning with the needs of evolving healthcare practices. Similarly, TECHLAB introduced the H. PYLORI QUIK CHEK and H. PYLORI CHEK tests, offering rapid and reliable antigen detection within 30 minutes to one hour. These tests simplify sample collection and provide high diagnostic accuracy, addressing the need for effective, non-invasive H. pylori detection.
These advancements in H. pylori diagnostics underscore the importance of innovation in addressing global health challenges. The field is moving toward more accurate, efficient, and patient-friendly solutions, from biosensors and nanotechnology to next-generation diagnostic tools.
Market Dynamics
The Helicobacter pylori diagnostics market is supported by the high clinical burden of H. pylori infection, increasing awareness of its association with peptic ulcer disease and gastric malignancies, and growing emphasis on timely diagnosis and eradication therapy. Chronic H. pylori infection is an established cause of non-cardia gastric cancer and gastric mucosa-associated lymphoid tissue lymphoma, strengthening the clinical importance of identifying infected patients before severe gastrointestinal complications develop. Healthcare providers are increasingly adopting non-invasive diagnostic approaches, including stool antigen tests and urea breath tests, as these methods can support the detection of active infection and post-treatment confirmation without requiring an invasive endoscopic procedure. The market is also benefiting from the wider availability of rapid immunoassays, automated laboratory testing solutions, and molecular diagnostic methods capable of detecting H. pylori and, in selected applications, antibiotic-resistance-associated mutations. For instance, in March 2026, Biomerica, Inc., a global biomedical technology company, announced that the company has received its first commercial order for Hp Detect, an H. pylori stool antigen test, from one of the largest clinical laboratory chains operating across Europe. The initial order was intended for the United Kingdom, where the product received registration from the Medicines and Healthcare products Regulatory Agency in February 2026. According to the company, the order marked an important step in integrating Hp Detect into routine laboratory workflows and supporting its broader commercialization across European markets. Continued expansion of gastrointestinal testing services, growing laboratory demand for reliable non-invasive assays, and increased attention to antimicrobial resistance are expected to support the market over the forecast period.
The high global burden of Helicobacter pylori infection is a major growth driver for the H. pylori diagnostics market because it creates a large and continuously replenished population requiring initial diagnosis, treatment-linked testing, and confirmation of eradication. In January 2024, the U.S. National Cancer Institute reported that approximately 50% of the world’s population carries H. pylori in the stomach, demonstrating that the infection is not confined to a small clinical subgroup but represents a widespread global health concern. Although many infected individuals remain asymptomatic, persistent infection can cause chronic gastritis, peptic ulcer disease, gastric mucosa-associated lymphoid tissue lymphoma, and gastric cancer, thereby increasing the need for reliable testing when patients present with dyspepsia, recurrent abdominal discomfort, gastrointestinal bleeding, unexplained iron-deficiency anaemia, or ulcer-related symptoms. The relationship between infection burden and future cancer burden further strengthens the commercial importance of diagnosis. In July 2025, the International Agency for Research on Cancer estimated that 15.6 million gastric cancer cases could occur over the lifetimes of people born between 2008 and 2017 under current control measures, with 76% of those cases attributable to H. pylori infection. IARC’s 2025 implementation guidance consequently supports consideration of population-based H. pylori screen-and-treat strategies in appropriate settings, which could expand testing beyond symptomatic patients toward organized prevention programs. This underlying demand is also translating into commercial activity among diagnostic manufacturers. In March 2026, Biomerica announced its first commercial order for its Hp Detect stool antigen assay from a major European clinical laboratory chain, with the product intended for integration into routine laboratory testing workflows.
The risk of inaccurate results caused by medication use and improper testing conditions is restraining the growth of the Helicobacter pylori diagnostics market by reducing confidence in test outcomes, complicating patient preparation, and increasing the likelihood of delayed or repeated testing. Proton-pump inhibitors, potassium-competitive acid blockers, antibiotics, and bismuth-containing medicines can temporarily suppress H. pylori density or urease activity without fully eliminating the infection. Consequently, urea breath tests, stool antigen assays, rapid urease tests, histology, and culture may produce a negative result even when infection remains present. According to the data published by the U.S. National Institutes of Health’s PubMed Central platform in 2025, it reported that the previously documented false-negative rates for urea breath testing among patients using proton-pump inhibitors ranged from approximately 30% to 40%. This is commercially important because acid-suppressive medicines are frequently used by patients with dyspepsia, reflux, gastritis, and ulcer-like symptoms the same population commonly evaluated for H. pylori infection. When medication history is incomplete or treatment cannot be stopped safely, the reliability of a negative result becomes uncertain, limiting the value of a single diagnostic procedure and weakening clinician confidence in routine testing pathways.
Opportunity - Development of molecular tests that detect infection and antibiotic-resistance markers
The development of molecular tests that can simultaneously detect Helicobacter pylori infection and antibiotic-resistance-associated mutations represents a significant growth opportunity for the H. pylori diagnostics market during the forecast period. Conventional diagnostic methods including urea breath tests, stool antigen assays, histology, rapid urease tests, and serology can establish or support the presence of infection, but most do not provide information on whether the infecting strain is likely to respond to a particular antibiotic. This creates an important gap in clinical decision-making because the success of H. pylori eradication therapy increasingly depends on local and patient-specific antimicrobial resistance patterns. Molecular assays can address this gap by detecting H. pylori DNA and identifying genetic mutations linked to resistance within the same diagnostic workflow, enabling clinicians to move from empirical treatment toward susceptibility-guided therapy. The opportunity is being strengthened by the growing clinical consequences of clarithromycin resistance. The World Health Organization’s 2024 Bacterial Priority Pathogens List includes clarithromycin-resistant H. pylori among antibiotic-resistant pathogens of public-health importance. This recognition signals a continuing need for better diagnostic, surveillance, and treatment-selection tools. In addition, the American College of Gastroenterology’s 2024 guideline recommends that proton-pump-inhibitor-based clarithromycin triple therapy should not be used unless antibiotic susceptibility has been assessed and clarithromycin sensitivity has been demonstrated. The guideline commentary further notes that eradication rates with clarithromycin-containing regimens can fall to approximately 30% when clarithromycin-resistant strains are present.
Analyst Perspective
The Helicobacter pylori diagnostics market is shifting from symptom-driven testing toward a broader clinical pathway linking infection detection with ulcer management, gastric cancer prevention, treatment selection, and post-eradication confirmation. The market is expected to remain attractive due to the high prevalence of H. pylori infection and the large number of undiagnosed cases, sustaining testing demand across hospitals, diagnostic laboratories, gastroenterology clinics, and primary-care settings. Demand is expected to remain concentrated in non-invasive formats, particularly stool antigen assays and urea breath tests, as they detect active infection and confirm eradication without endoscopy. Their clinical value supports routine diagnosis, follow-up testing, and high-volume laboratory workflows. Reagents are expected to generate the most recurring revenue, as each test requires assay kits, substrates, controls, cartridges, collection materials, and other consumables. Instruments generate less frequent revenue but remain important for automated immunoassay systems, breath-test analyzers, PCR platforms, and laboratory workflow solutions.
Type Insights
Based on type, the reagents segment led the market with the largest revenue share of 44.7% in 2025. The reagents segment plays a crucial role in the industry, driven by advancements in diagnostic assays such as enzyme immunoassays (EIA), rapid antigen tests, and molecular diagnostics like PCR. The increased global prevalence of H. pylori-related gastrointestinal diseases, including peptic ulcers and gastric cancer, fuels the demand for reliable and efficient reagents. Innovations in reagent formulations for stool antigen tests and non-invasive diagnostic methods further drive market growth. Moreover, the growing adoption of point-of-care testing and the need for precise and rapid diagnostics in clinical and laboratory settings contribute significantly to expanding the reagents segment.
Moreover, the instrument segment is anticipated to experience a considerable market share over the forecast period driven by technological advancements in diagnostic tools such as urea breath analyzers, PCR systems, and immunoassay platforms. Increasing demand for non-invasive diagnostic techniques, such as breath tests and stool antigen detection, has spurred the adoption of advanced instruments. Integrating automation and real-time PCR technology in molecular diagnostics ensures higher precision and speed, making instruments indispensable for accurate H. pylori detection. Furthermore, the growing prevalence of gastric disorders and an emphasis on early diagnosis and monitoring drive investments in innovative diagnostic instruments globally.
End Use Insights
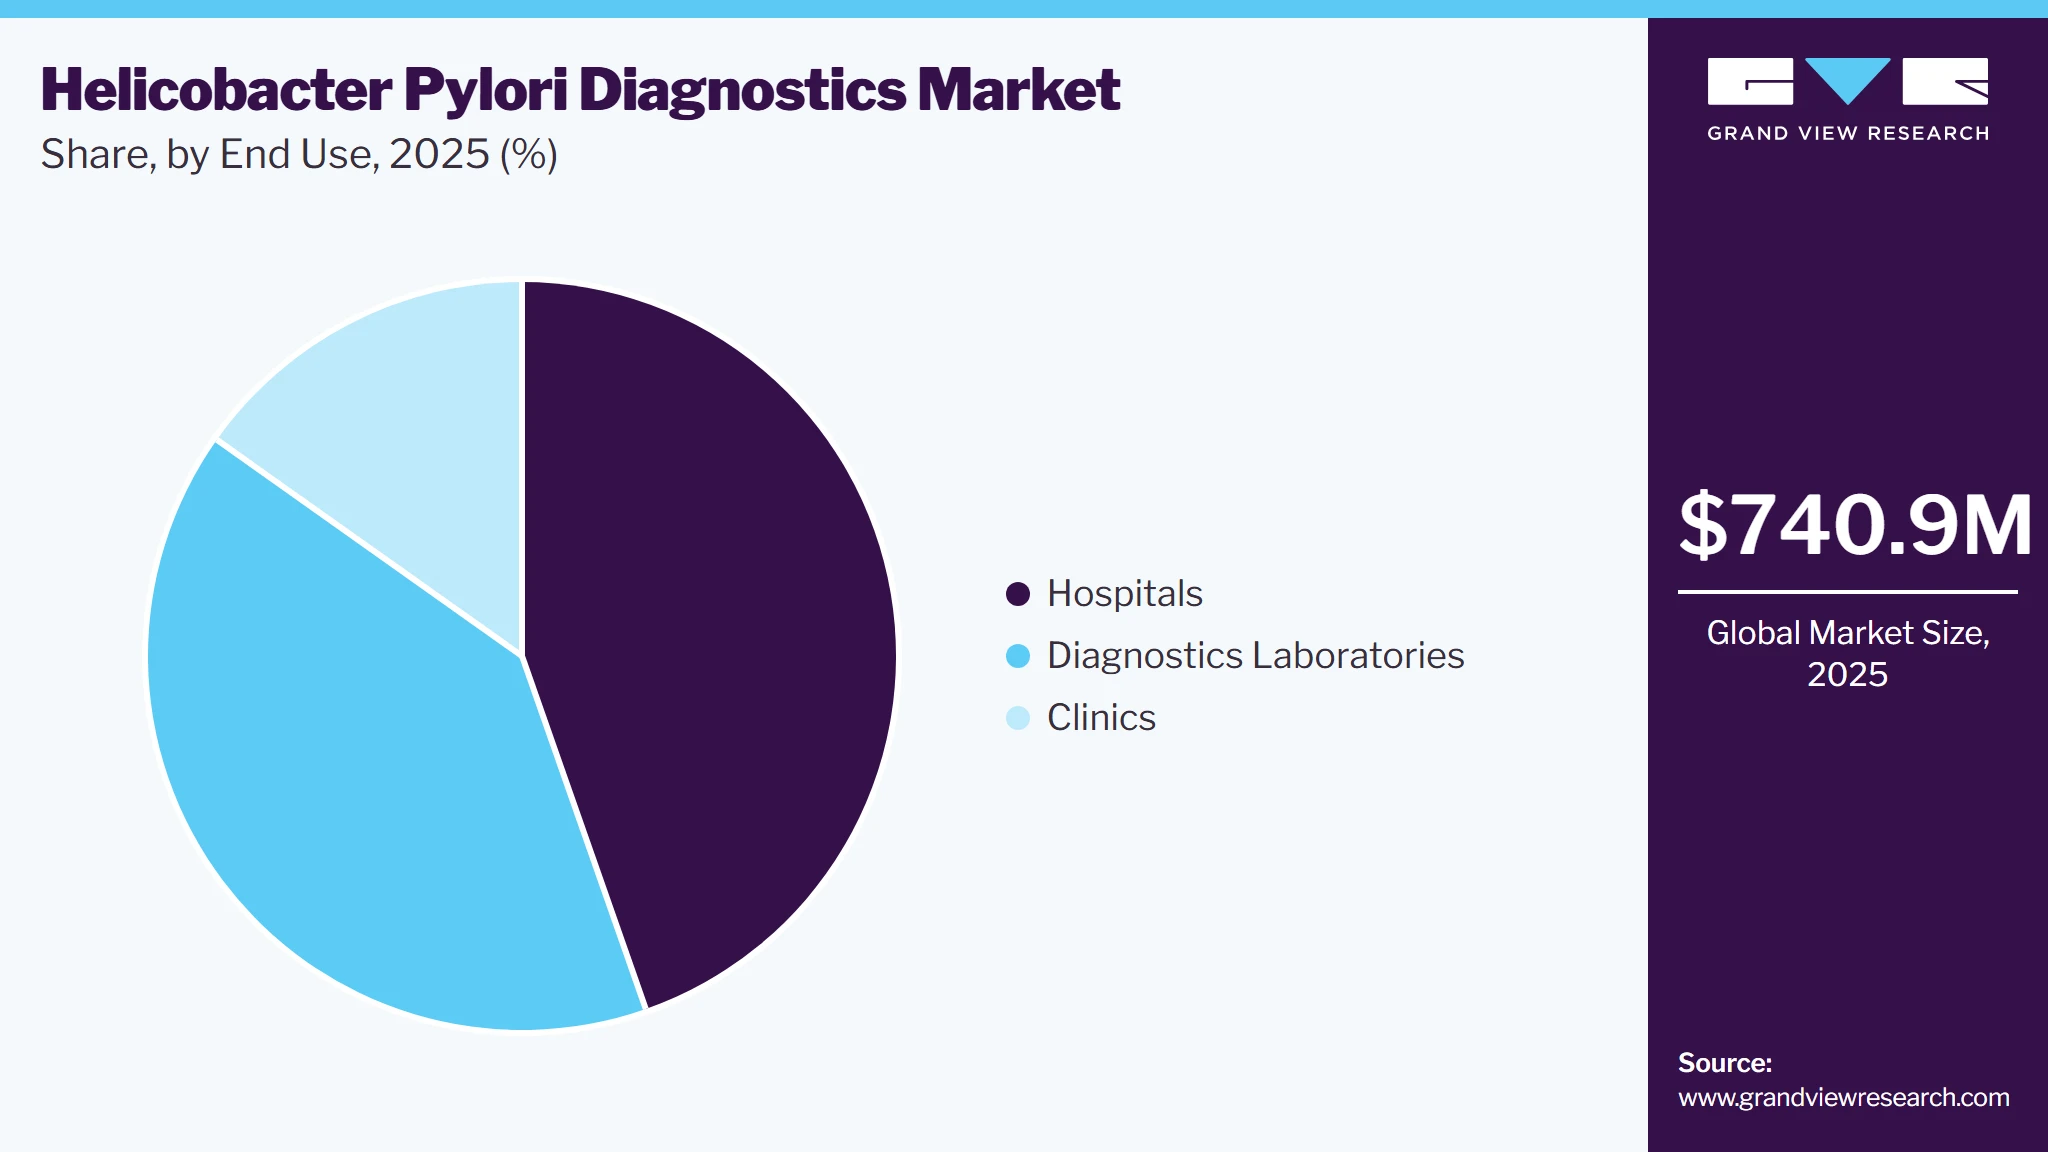
Based on end use, the hospitals segment led the market with the largest revenue share of 44.6% in 2025. This is attributed to the convenience of diagnosing and treating diseases such as duodenal ulcers, gastric ulcers, gastritis, stomach cancer, and small intestine infections in hospital settings. Hospitals provide access to advanced diagnostic instruments and skilled healthcare professionals, enabling accurate and timely diagnosis. In addition, the increasing prevalence of digestive disorders further fuels this segment.
 To learn more about this report, Download Free Sample Report
The diagnostics laboratories segment is anticipated to experience the fastest growth rate over the forecast period. The increasing prevalence of H. pylori infections, a leading cause of gastric ulcers and cancer, drives the Helicobacter pylori diagnostics market. Rising awareness about early detection has boosted demand for advanced diagnostic tools such as urea breath tests, stool antigen tests, and molecular diagnostics. For example, laboratories like Quest Diagnostics and LabCorp offer comprehensive H. pylori testing services. In addition, advancements in non-invasive and accurate diagnostic technologies contribute to improved patient outcomes, fueling market growth in diagnostic laboratories.
Technology Insights
Based on Technology, the immunoassays segment led the market with the largest revenue share of 43.6% in 2025. Conventional diagnostic methods are based on microscopic & macroscopic identification of pathogens through gram stain, pathogen culturing, biochemical methods, and serology tests. Relatively higher availability of conventional methods, compared to modern techniques, across a large number of labs and clinics is a key factor that has enabled this segment to dominate the market. However, these tests exhibit certain speed, timeline, and accuracy limitations. Furthermore, rapid technological advances are compelling end users to opt for diagnostics laboratories over conventional methods.
Diagnostics Laboratories is anticipated to experience the fastest growth rate over the forecast period. An increase in R&D for molecular diagnostic techniques and a rise in demand for point-of-care products is expected to boost the market growth at a CAGR of 5.04% by 2033. American Leprosy Missions (ALM) has launched an innovative project to develop molecular diagnostics for detecting five skin-neglected tropical diseases (NTDs): leprosy, Buruli ulcer, yaws, cutaneous leishmaniasis, and mycetoma. Supported by the Anesvad and Raoul Follereau Foundations, this initiative aims to create a multiplex assay that simplifies the simultaneous detection of these diseases, which require similar diagnostic and management approaches. Collaborating with Biomeme, Inc., ALM leverages advanced qPCR technology, including a mobile thermocycler and smartphone integration. This portable setup enables rapid DNA and RNA detection, delivering results in 30-45 minutes without electricity or complex logistics. Building on prior successes, ALM has already developed assays for Buruli ulcer and leprosy, which are undergoing prequalification and evaluation phases. The new multiplex assay is poised to address diagnostic challenges in low-resource settings, significantly reducing delays and costs while advancing global efforts to eliminate skin NTDs.
Regional Insights
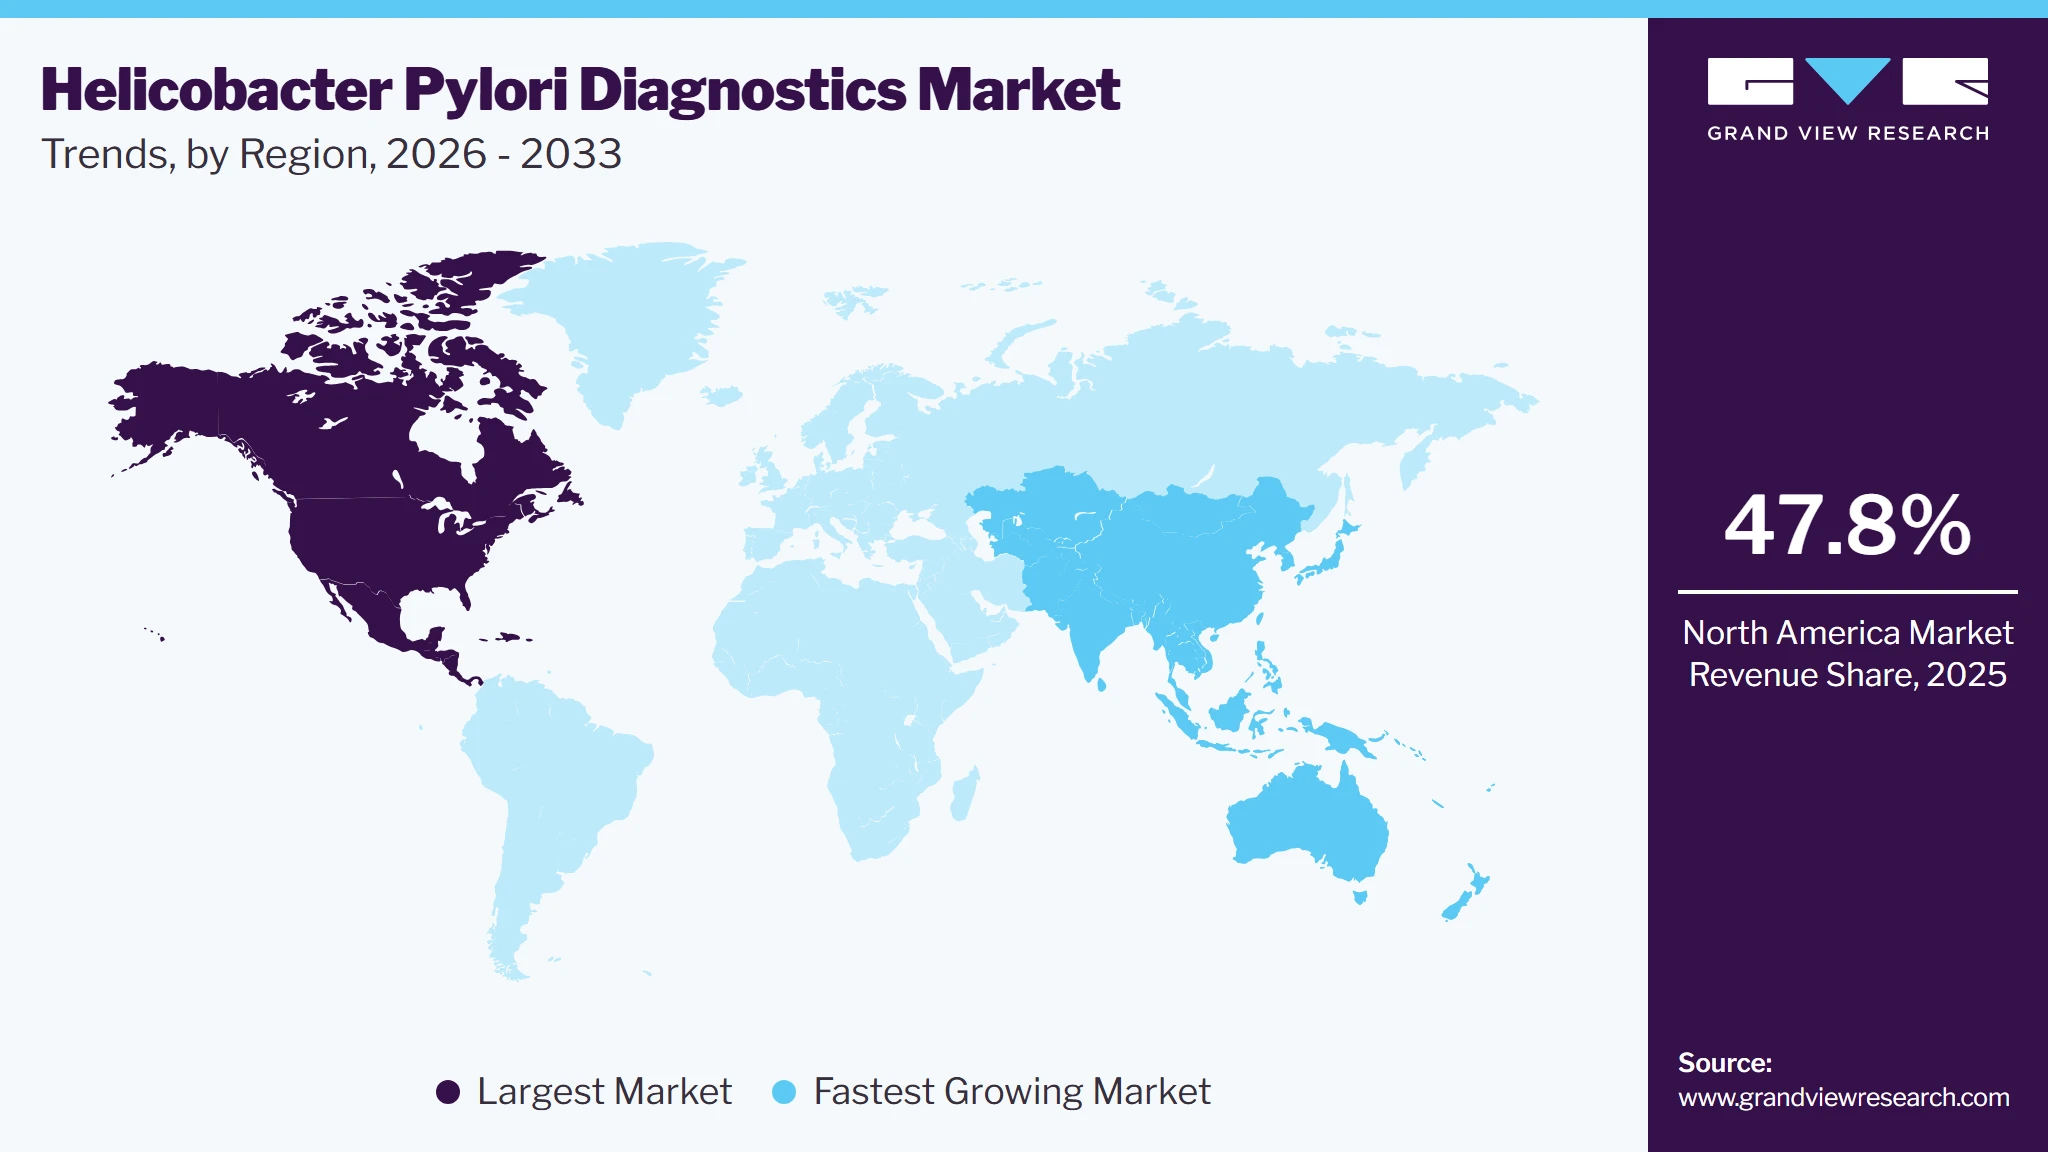
North America dominated the helicobacter pylori diagnostics market with the largest revenue share of 47.8% in 2025. The region's high infection rate and growing government healthcare expenditures drive market growth. For instance, according to a recent article published by the Canadian Association of Gastroenterology in March 2022, the prevalence of Helicobacter pylori is estimated between 23% and 38 %. The high number of H. pylori infections is expected to drive the market over the forecast period.
 To learn more about this report, Download Free Sample Report
U.S. Helicobacter Pylori Diagnostics Market Trends
The helicobacter pylori diagnostics market in the U.S. held the largest share in the North America region in 2025. The U.S. helicobacter pylori diagnostics market is experiencing growth driven by the increasing prevalence of gastrointestinal disorders, rising awareness about early detection, and advancements in diagnostic technologies. Non-invasive testing methods such as urea breath tests (UBT) and stool antigen tests are gaining traction due to their accuracy and patient convenience. Furthermore, the growing adoption of molecular diagnostic techniques like PCR enhances sensitivity and specificity. Key challenges include cost considerations and accessibility in rural areas.
Europe Helicobacter Pylori Diagnostics Market Trends
The helicobacter pylori diagnostics market in Europe is shaped by rising awareness of gastrointestinal health and the increasing prevalence of H. pylori infections. Non-invasive diagnostic methods, such as urea breath tests and stool antigen tests, are gaining traction due to their accuracy and patient convenience. Adopting advanced molecular diagnostics, supported by technological advancements, also drives market growth. Furthermore, government initiatives promoting early detection of gastric diseases are encouraging the expansion of diagnostic services across healthcare facilities in the region.
The UK helicobacter pylori diagnostics market is expanding due to the increasing prevalence of H. pylori infections, which are linked to conditions like gastritis and peptic ulcers. Rising public health initiatives promoting early detection and treatment are boosting demand for diagnostic tests. The market also benefits from integrating advanced technologies such as immunoassays and multiplex PCR for accurate detection. Growing awareness among healthcare providers and patients about H. pylori’s role in gastric cancer prevention is another key driver, along with a steady increase in government and private sector healthcare funding.
The helicobacter pylori diagnostics market in France is witnessing steady growth, fueled by increasing cases of gastric infections and ulcers caused by H. pylori. A robust healthcare system and widespread adoption of advanced diagnostic technologies such as ELISA and histological testing support market expansion. Public health campaigns emphasizing early detection of H. pylori to reduce the risk of gastric cancer are driving awareness. In addition, the growing use of serological tests for screening and research initiatives aimed at improving diagnostic accuracy further propels market demand. The presence of skilled healthcare professionals ensures the effective implementation of diagnostic protocols.
Germany helicobacter pylori diagnostics market is growing due to the increasing focus on preventive healthcare and the rising incidence of gastrointestinal diseases linked to H. pylori infections. Demand is supported by advancements in diagnostic technologies, such as non-invasive breath and stool tests, which are becoming more widely adopted for convenience and reliability. The market also benefits from government-backed healthcare initiatives to reduce gastric cancer risks. Moreover, high awareness among patients and clinicians about early detection, combined with the integration of molecular diagnostic tools in clinical settings, is driving market expansion.
Asia Pacific Helicobacter Pylori Diagnostics Market Trends
The helicobacter pylori diagnostics market in Asia Pacific is driven by the high prevalence of H. pylori infections and increasing healthcare awareness across the region. Rising demand for non-invasive diagnostic methods, such as urea breath tests and stool antigen tests, is a key trend. Rapid urbanization and improved healthcare infrastructure further support market growth. Countries like China and India are witnessing significant adoption of advanced diagnostic tools, fueled by growing investments in healthcare technology and initiatives promoting early detection of gastric disorders.
China helicobacter pylori diagnostics market is experiencing rapid growth due to the high prevalence of H. pylori infections, a leading cause of gastritis and peptic ulcers in the region. Increasing investments in healthcare infrastructure and advancements in diagnostic technologies, such as rapid antigen tests and polymerase chain reaction (PCR), are fueling market demand. Public health initiatives promoting awareness of H. pylori-associated gastric cancer risks encourage early testing. Furthermore, the growing middle class and rising disposable incomes have improved access to healthcare services, further driving the adoption of diagnostic solutions across urban and rural areas.
The helicobacter pylori diagnostics market in Japan is advancing steadily, driven by a high prevalence of H. pylori infections and the country's aging population, which is more susceptible to gastrointestinal disorders. National healthcare policies mandating H. pylori testing for patients with gastritis and other related conditions are a significant growth driver. The market benefits from the widespread use of advanced diagnostic techniques, such as urea breath tests (UBT) and endoscopic biopsies, which offer high accuracy. Increased awareness of the link between H. pylori and gastric cancer has further boosted demand for early detection and treatment options.
Latin America Helicobacter Pylori Diagnostics Market Trends
The helicobacter pylori diagnostics market in Latin America is expanding due to the high prevalence of H. pylori infections across the region, often linked to suboptimal sanitation and limited access to clean water. Growing awareness campaigns about the health risks of untreated infections, including gastritis and gastric cancer, are driving demand for diagnostic services. Non-invasive tests such as stool antigen tests and urea breath tests are gaining popularity due to their affordability and ease of use. Moreover, improving healthcare infrastructure and increasing government investments in public health programs support market growth across urban and rural areas.
Brazil helicobacter pylori diagnostics market is growing, driven by a high prevalence of H. pylori infections and an increasing focus on gastrointestinal health. Rising public awareness about the connection between H. pylori and conditions like peptic ulcers and gastric cancer has boosted demand for diagnostic testing. Non-invasive methods, such as urea breath tests and stool antigen tests, are gaining traction due to their cost-effectiveness and simplicity. Government initiatives to improve healthcare accessibility and expanded insurance coverage for diagnostic services are further propelling market growth, particularly in underserved rural areas.
Middle East & Africa Helicobacter Pylori Diagnostics Market Trends
The helicobacter pylori diagnostics market in MEA is growing due to the rising prevalence of H. pylori infections and increased awareness of gastrointestinal health. Due to their convenience and reliability, the adoption of noninvasive diagnostics, such as stool antigen tests and urea breath tests, is expanding. Investments in healthcare infrastructure across the Middle East, along with government initiatives for early detection and treatment of gastric diseases, are driving the market. Moreover, advancements in molecular diagnostics are gradually penetrating the region, enhancing diagnostic accuracy.
Saudi Arabia Helicobacter pylori diagnostics market is growing due to increasing awareness about gastrointestinal health and the rising prevalence of H. pylori infections linked to lifestyle and dietary factors. Advancements in healthcare infrastructure and the adoption of modern diagnostic techniques, such as urea breath tests and stool antigen tests, are enhancing early detection rates. Public health initiatives and government investments to reduce the burden of gastric diseases are key drivers. In addition, a growing expatriate population and improved access to private healthcare facilities further support market expansion in urban and rural regions.
Key Helicobacter Pylori Diagnostics Company Insights
Some of the key market players include Thermo Fisher Scientific, Biohit Oyj, Quest Diagnostics Incorporated, Meridian Bioscience, Bio-Rad Laboratories, Alpha Laboratories Ltd, F. Hoffmann-La Roche Ltd, Coris BioConcept, Certest Biotec, Epitope Diagnostics, Inc. These players are undertaking various strategic initiatives to increase their share in the market. New product development, collaborations, and partnerships are some such endeavors.
Key Helicobacter Pylori Diagnostics Companies
The following key companies have been profiled for this study on the helicobacter pylori diagnostics market.
-
Thermo Fisher Scientific
-
Biohit Oyj
-
Quest Diagnostics Incorporated
-
Meridian Bioscience
-
Bio-Rad Laboratories
-
Alpha Laboratories Ltd
-
F. Hoffmann-La Roche Ltd
-
Coris BioConcept
-
Certest Biotec
-
Epitope Diagnostics, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well-Established Players (Thermo Fisher Scientific; Quest Diagnostics Incorporated; Meridian Bioscience; Bio-Rad Laboratories; F. Hoffmann-La Roche Ltd.)
- Focus on broadening H. pylori testing portfolios across immunoassays, molecular diagnostics, laboratory analyzers, and testing services. These companies typically leverage established hospital and laboratory relationships, global distribution networks, regulatory expertise, reagent-rental models, bundled product offerings, and cross-selling through wider infectious disease and gastrointestinal diagnostic portfolios.
- Strong brand recognition, extensive installed instrument bases, established quality systems, broad geographic reach, high research and development capacity, and the ability to support large-volume hospital and reference-laboratory customers.
- Large organizational structures may slow product-development and commercialization decisions. H. pylori diagnostics often represent a relatively small part of their wider business portfolios, which may limit dedicated investment and product specialization. Premium pricing, dependence on centralized laboratory infrastructure, and limited flexibility in addressing small or highly localized customer requirements can also constrain adoption.
Emerging Players (Biohit Oyj; Alpha Laboratories Ltd.; Coris BioConcept; Certest Biotec; Epitope Diagnostics, Inc.)
- Concentrate on specialized H. pylori assays, rapid tests, stool antigen testing, gastrointestinal diagnostics, and selected molecular or resistance-detection solutions.
- Greater specialization enables faster innovation, stronger focus on unmet diagnostic needs, and closer alignment with gastroenterology laboratories and niche customer groups.
- Limited financial resources, smaller sales and distribution networks, lower brand visibility, and dependence on third-party distributors can restrict commercial scale.
Recent Developments
-
In July 2023, Meridian Bioscience, Inc., a global leader in diagnostic solutions, received FDA clearance for its Premier HpSA FLEX, a non-invasive enzyme immunoassay for detecting Helicobacter pylori (H. pylori) antigens in both preserved and unpreserved stool samples. This innovation enhances diagnostic flexibility by allowing preserved stools in Cary-Blair and C&S media alongside fresh or frozen samples. This advancement complements Meridian's comprehensive H. pylori portfolio, including BreathID (urea breath test), Curian HpSA (fluorescent immunoassay), and ImmunoCard Stat! HpSA (rapid antigen test). H. pylori infections are a leading cause of upper gastrointestinal conditions, such as chronic gastritis, peptic ulcers, and gastric cancer, underscoring the significance of accessible and reliable diagnostics in improving patient outcomes.
-
In December 2023, Biomerica, Inc. announced that it had received FDA 510(k) clearance for its HP Detect Stool Antigen ELISA test (K232892), a new diagnostic tool designed to detect Helicobacter pylori (H. pylori) infection. With approximately 35% of the U.S. population infected and over 80% of gastric cancers linked to H. pylori, this test aims to aid in diagnosing and monitoring H. pylori infection, particularly after treatment. Gastric cancer, which is the third leading cause of cancer-related death globally, underscores the importance of early detection and effective management of H. pylori infections. This test provides physicians and medical centers with a reliable means to assess H. pylori presence and infection status, contributing to improved patient outcomes.
Helicobacter Pylori Diagnostics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 740.9 million
Estimated market size in 2026
USD 784.4 million
Projected market size by 2033
USD 1,106.4 million
Growth rate
CAGR of 5.0% from 2026 to 2033
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, technology, end use, Regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; and Kuwait
Key companies profiled
Thermo Fisher Scientific; Biohit Oyj; Quest Diagnostics Incorporated; Meridian Bioscience; Bio-Rad Laboratories; Alpha Laboratories Ltd; F. Hoffmann-La Roche Ltd; Coris BioConcept; Certest Biotec; Epitope Diagnostics, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Helicobacter Pylori Diagnostics Market Report Segmentation
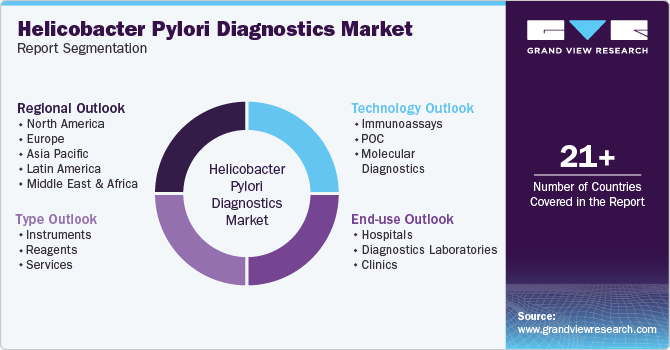
This report forecasts revenue growth and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global helicobacter pylori diagnostics market report based on type, technology, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Instruments
-
Reagents
-
Services
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Immunoassays
-
POC
-
Molecular Diagnostics
-
-
End-user Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Diagnostics Laboratories
-
Clinics
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Research Methodology
The helicobacter pylori diagnostics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each helicobacter pylori diagnostics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Type
Revenue capture definition
Instruments
Revenue is captured from the sale, lease, or replacement of diagnostic analyzers and supporting equipment used for H. pylori testing. This includes urea breath test analyzers, immunoassay analyzers, PCR systems, rapid test readers, sample-processing instruments, and associated automation platforms.
Reagents
Revenue is primarily derived from recurring sales of consumable products required to perform H. pylori diagnostic procedures. These include stool antigen test kits, serology reagents, urea breath test substrates, rapid urease test kits, molecular assay kits, PCR reagents, primers, probes, controls, calibrators, extraction materials, test cartridges, and other single-use laboratory consumables.
Services
Revenue is generated from diagnostic testing, laboratory processing, installation, equipment maintenance, technical support, assay validation, calibration, training, and outsourced molecular or susceptibility testing services.
Technology
Revenue capture definition
Immunoassays
Revenue is captured from the sale and use of immunoassay-based instruments, reagents, test kits, controls, and associated laboratory services used to detect H. pylori antigens or antibodies.
POC
Revenue is derived from rapid H. pylori diagnostic products used near the patient or within outpatient and clinical settings. This includes rapid stool antigen tests, rapid antibody tests, near-patient urea breath testing solutions, rapid urease tests, disposable cartridges, compact readers, and related service or support charges.
Molecular Diagnostics
Revenue is captured from PCR systems, nucleic acid extraction platforms, molecular assay kits, primers, probes, controls, sequencing consumables, and testing services used to detect H. pylori DNA.
End Use
Revenue capture definition
Hospitals
Revenue is generated from the procurement and use of H. pylori diagnostic instruments, reagents, consumables, and services within hospital laboratories, gastroenterology departments, endoscopy units, inpatient facilities, and outpatient departments.
Diagnostics Laboratories
Revenue is captured from centralized, independent, reference, and specialty laboratories performing high-volume H. pylori testing for hospitals, clinics, physicians, and other healthcare providers.
Clinics
Revenue is derived from H. pylori testing conducted or ordered by gastroenterology clinics, primary-care clinics, ambulatory centers, and specialist practices.
Estimation Model
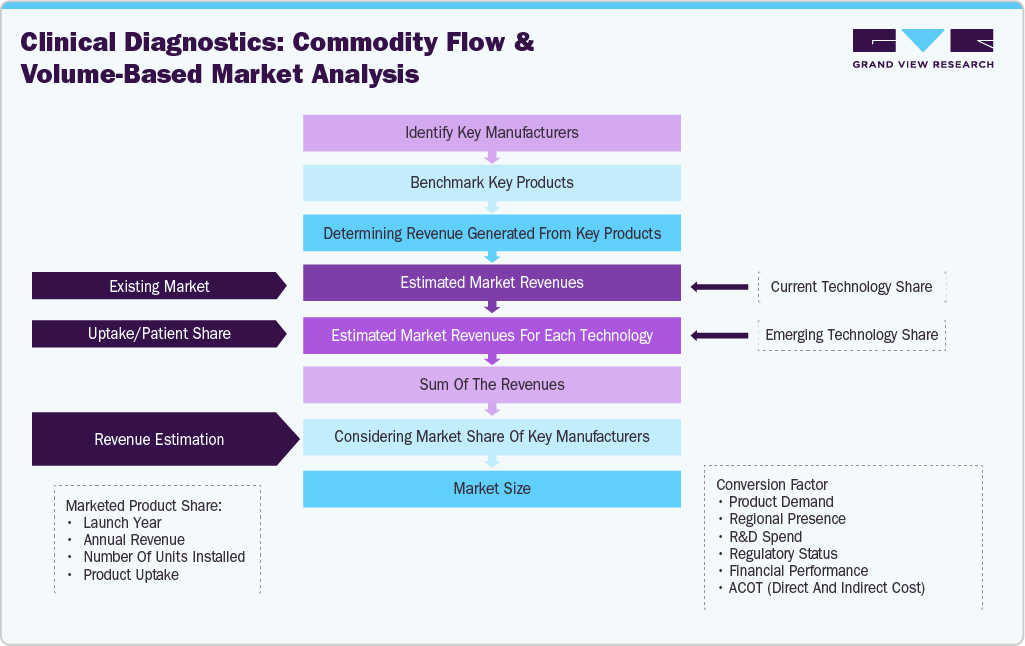
The Helicobacter Pylori diagnostics market size was estimated using a bottom up approach by identifying key manufacturers, benchmarking their Helicobacter Pylori diagnostics product portfolios, and assessing revenues generated from Helicobacter Pylori testing products across major technologies. Market revenues were further validated by analyzing technology wise adoption, patient testing volumes, and the market share of leading manufacturers, followed by aggregation of segment level revenues to derive the overall market size.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape & Technology Assessment – H. pylori Diagnostic Instruments, Reagents, Services, Immunoassays, Point-of-Care and Molecular Diagnostics
Assessed the competitive landscape across H. pylori diagnostic instruments, stool antigen assays, serology kits, urea breath testing systems, rapid urease tests, point-of-care kits, PCR assays, antibiotic-resistance mutation panels, and laboratory testing services. Evaluated the positioning of global diagnostic companies, specialized gastrointestinal testing manufacturers, reference laboratories, regional distributors, and emerging molecular diagnostic providers.
Enabled benchmarking of well-established and specialized market participants, identified differentiation across non-invasive, invasive, rapid, and molecular testing formats, and highlighted opportunities in stool-based active-infection testing, resistance-marker detection, decentralized diagnosis, laboratory automation, and post-eradication confirmation. Mapped competitive strengths across hospitals, diagnostic laboratories, gastroenterology clinics, and primary-care settings.
H. pylori Diagnostic Guidelines, Regulatory Requirements, Clinical Testing Pathways & Reimbursement Assessment
Analyzed current diagnostic and treatment-related testing recommendations, including patient eligibility, pre-test medication withdrawal, appropriate use of stool antigen and urea breath tests, post-treatment confirmation timelines, biopsy-based testing, and limitations of serology.
Supported regulatory and commercialization risk assessment by identifying barriers linked to false-negative results, medication interference, sample handling, inconsistent reimbursement, and variable diagnostic practices.
Comprehensive H. pylori Diagnostic Technology Assessment – Non-invasive Testing, POC, Molecular Detection and Antibiotic-Resistance Testing
Evaluated advancements in stool antigen immunoassays, urea breath testing, rapid lateral-flow tests, rapid urease testing, automated immunoassays, real-time PCR, multiplex molecular panels, sequencing-based approaches, and assays detecting clarithromycin- and fluoroquinolone-resistance-associated mutations.
Highlighted high-growth innovation areas, identified technologies improving diagnostic accuracy, turnaround time, patient convenience, and treatment selection, and assessed competitive positioning across conventional and advanced testing categories.
Frequently Asked Questions About This Report
Some key players operating in the helicobacter pylori diagnostics market include Thermo Fisher Scientific, Biohit, Quest Diagnostics, Meridian Bioscience, Bio-Rad Laboratories, Alpha Laboratories, F. Hoffmann-La Roche, Coris BioConcept, Certest Biotec, and Epitope Diagnostics.
Key factors that are driving the market growth include increasing demand for personalized antibiotic therapy and improving cost-effectiveness of diagnosis of helicobacter pylori infection.
The helicobacter pylori diagnostics market in Asia Pacific is driven by the high prevalence of H. pylori infections and increasing healthcare awareness across the region.
Based on type, the reagents segment led the market with the largest revenue share of 44.7% in 2025.
Based on technology, the Immunoassays segment led the market with the largest revenue share of 43.6% in 2025.
The development of molecular tests that can simultaneously detect Helicobacter pylori infection and antibiotic-resistance-associated mutations represents a significant growth opportunity for the H. pylori diagnostics market during the forecast period.
The hospitals segment led with a 44.6% revenue share in 2025, while the diagnostics laboratories segment is the fastest-growing.
The global helicobacter pylori diagnostics market size was valued at USD 740.9 million in 2025 and is estimated at USD 784.4 million for 2026.
The global helicobacter pylori diagnostics market is expected to grow at a CAGR of 5.0% from 2026 to 2033, reaching USD 1,106.4 million by 2033.
North America dominated the helicobacter pylori diagnostics market with a share of 47.8% in 2025. This is attributable to increasing healthcare expenditure, favorable reimbursement scenarios, and the presence of major players in the region.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


