
- Home
- »
- Medical Devices
- »
-
Hemodialysis & Peritoneal Dialysis Market Report, 2026 - 2033GVR Report cover

Hemodialysis And Peritoneal Dialysis Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Hemodialysis, Peritoneal Dialysis), By Product (Device, Consumables, Service), By End Use (Home-based, Hospital-based), By Region, And Segment Forecasts
Market Size, 2025
$119.5BMarket Estimate, 2026
$129.8BMarket Forecast, 2033
$250.4BCAGR, 2026–2033
9.8%Hemodialysis And Peritoneal Dialysis Market Summary
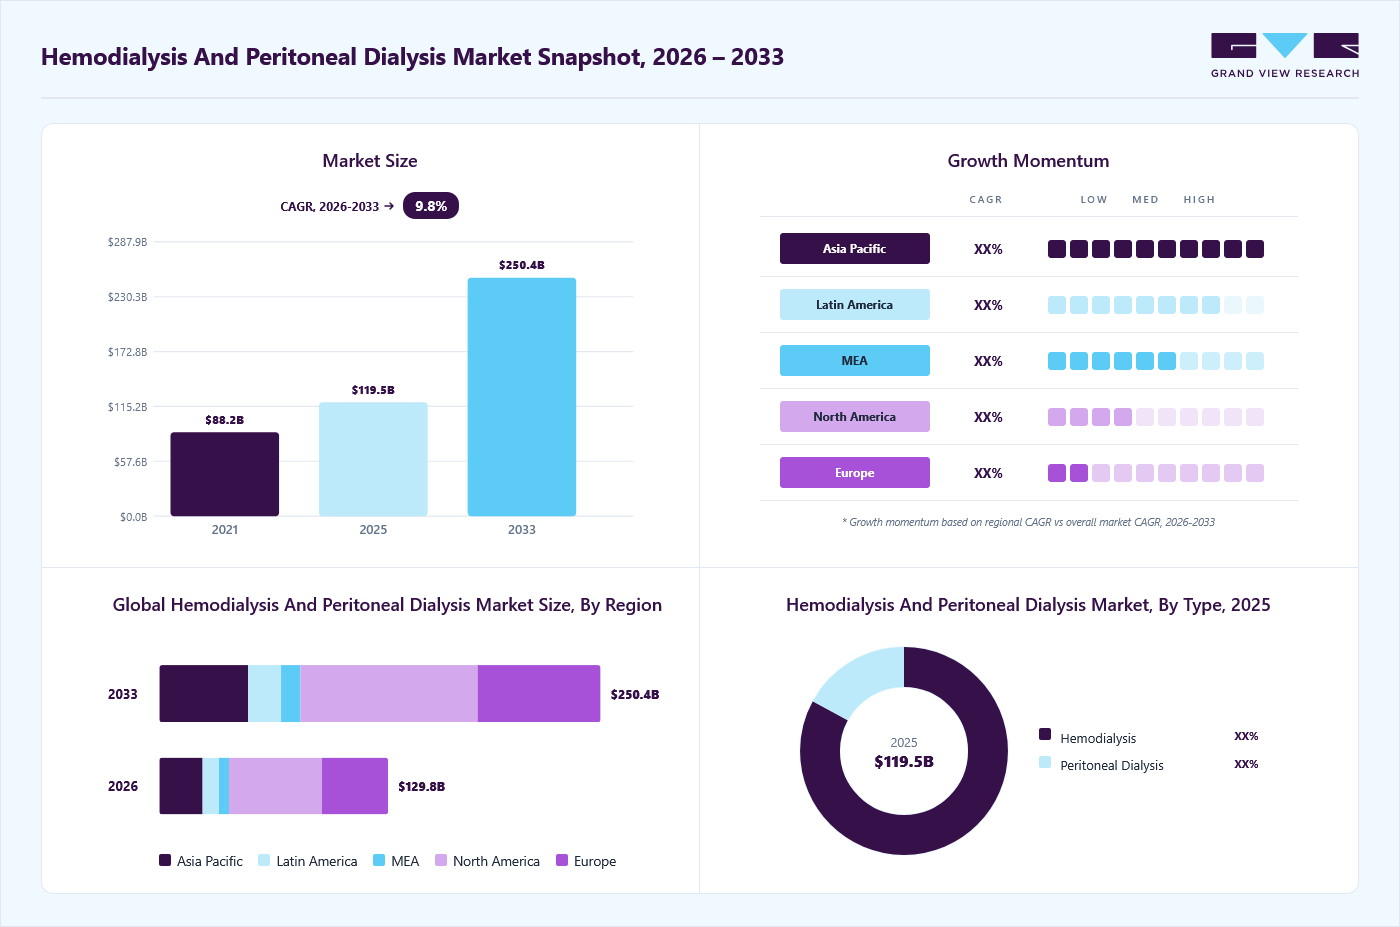
The global hemodialysis and peritoneal dialysis market size was valued at USD 119.5 billion in 2025 and is projected to grow from USD 129.8 billion in 2026 to USD 250.4 billion by 2033, at a CAGR of 9.8% from 2026 to 2033. North America held the largest share of 38.1% of the global market in 2025. The demand for hemodialysis and peritoneal dialysis is driven by several factors, including the rising incidence of acute kidney injury, the scarcity of organ donors, the risks associated with transplants, technological advancements, and initiatives by leading players to introduce advanced products and services.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Hemodialysis segment led the market with an 82.9% revenue share in 2025.
- By product: Services segment led the market with the largest share of 56.7% in 2025.
- By end-use: Hospital-based segment accounted for the largest share of 76.3% in 2025.
Regional Highlights
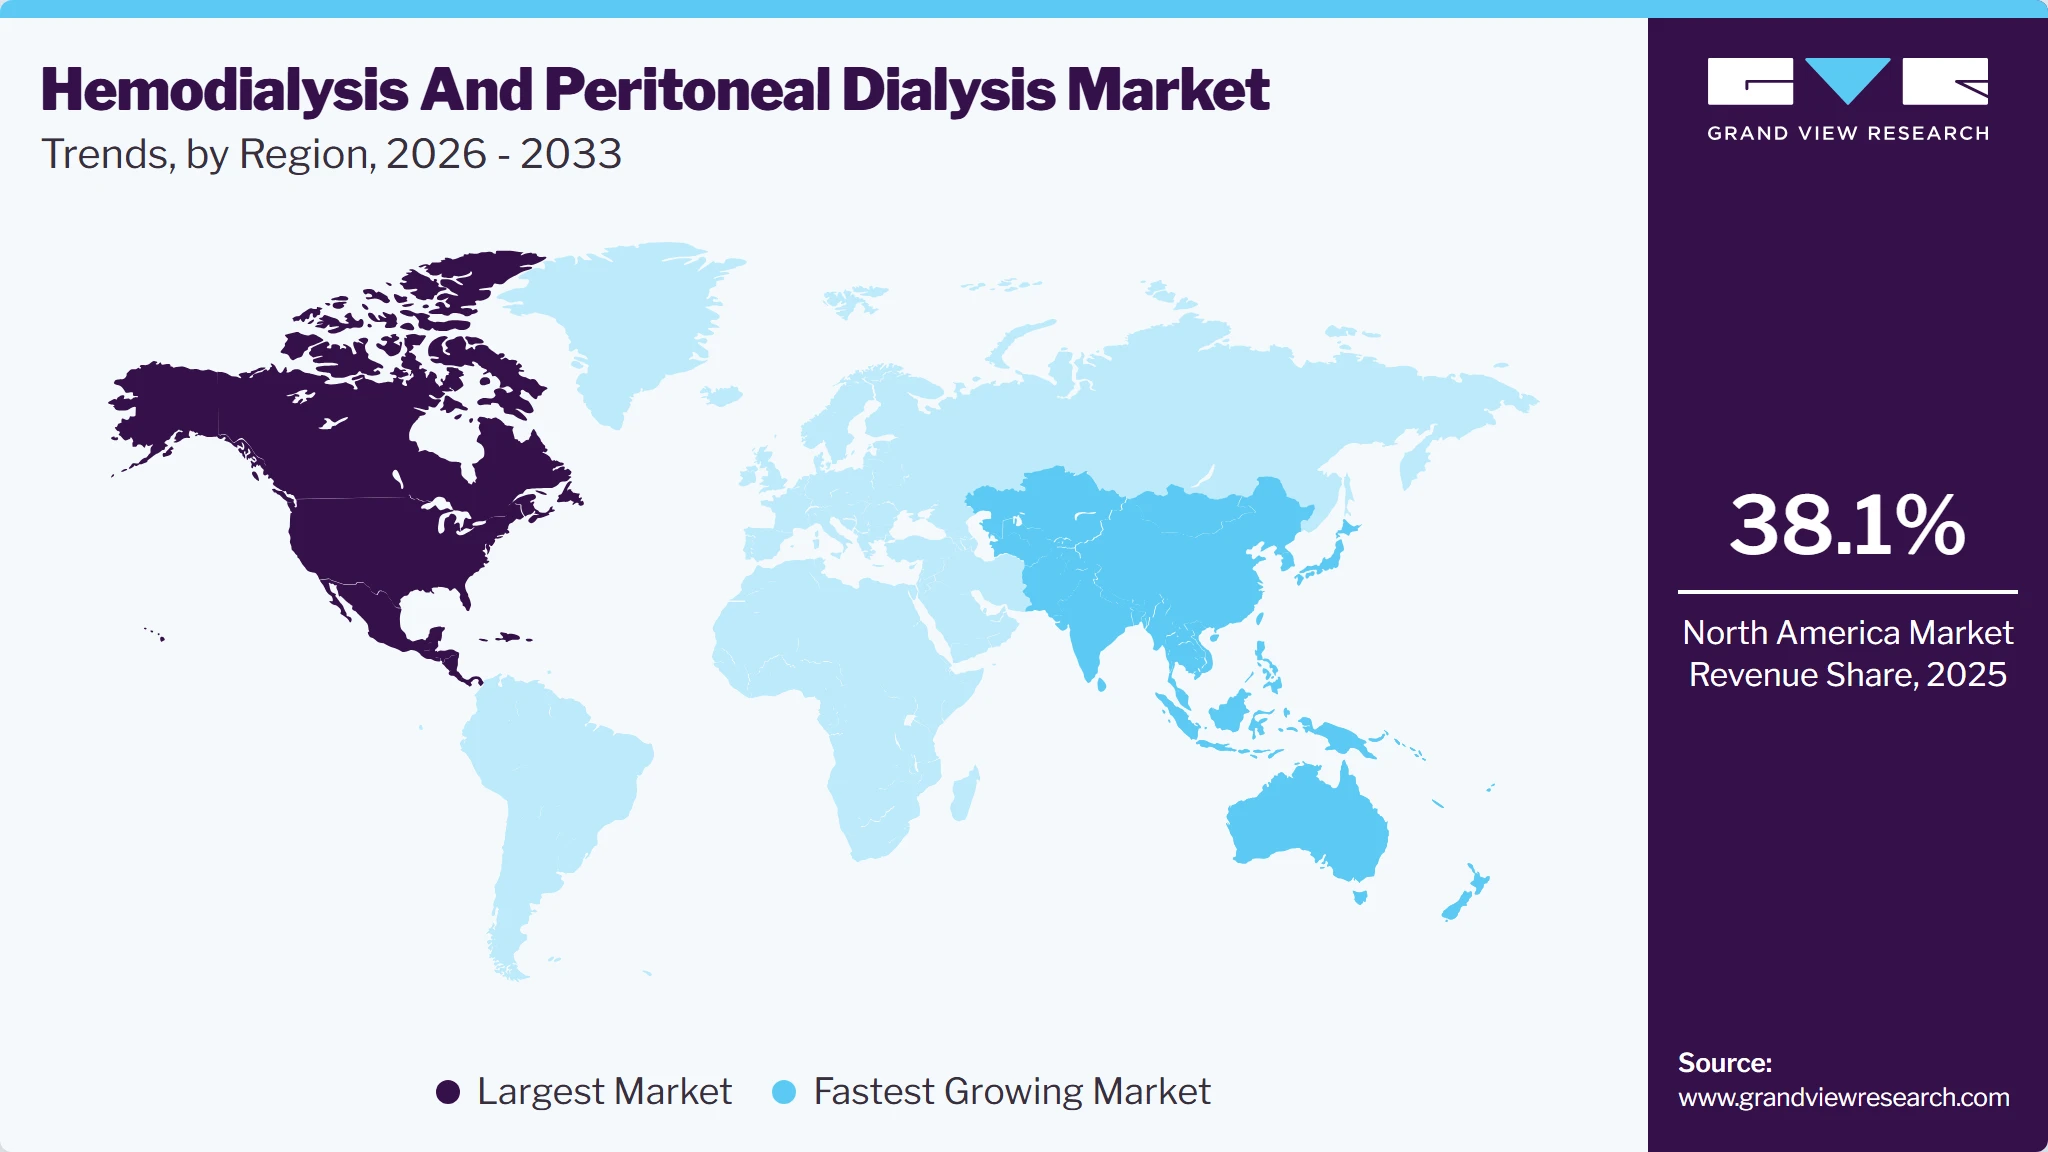
- Largest regional market: North America (38.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. is expected to grow significantly from 2026 to 2033
Market Size & Forecast
- Market size in 2025: USD 119.5 Billion
- Estimated market size in 2026: USD 129.8 Billion
- Projected market size by 2033: USD 250.4 Billion
- CAGR (2026-2033): 9.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Any condition with reduced kidney function leads to chronic kidney disease, which may develop into End-Stage Renal Disease (ESRD) over a period. An increase in the prevalence of CKD is expected to boost demand for dialysis products. The rising prevalence of chronic kidney disease is becoming a major global health concern, significantly contributing to the growth of the hemodialysis and peritoneal dialysis market. CKD prevalence is expanding due to the rapid increase in lifestyle-related disorders such as diabetes, hypertension, and obesity, which are the leading causes of kidney damage. Moreover, CKD often progresses silently with minimal symptoms in its early stages, leading to late diagnosis and a higher likelihood of patients advancing to end-stage renal disease (ESRD), where dialysis becomes unavoidable. Improved screening programs and greater awareness are now identifying more cases, thereby expanding the pool of diagnosed patients. Environmental factors, including exposure to toxins and poor water quality in certain regions, are also contributing to the increase in CKD cases.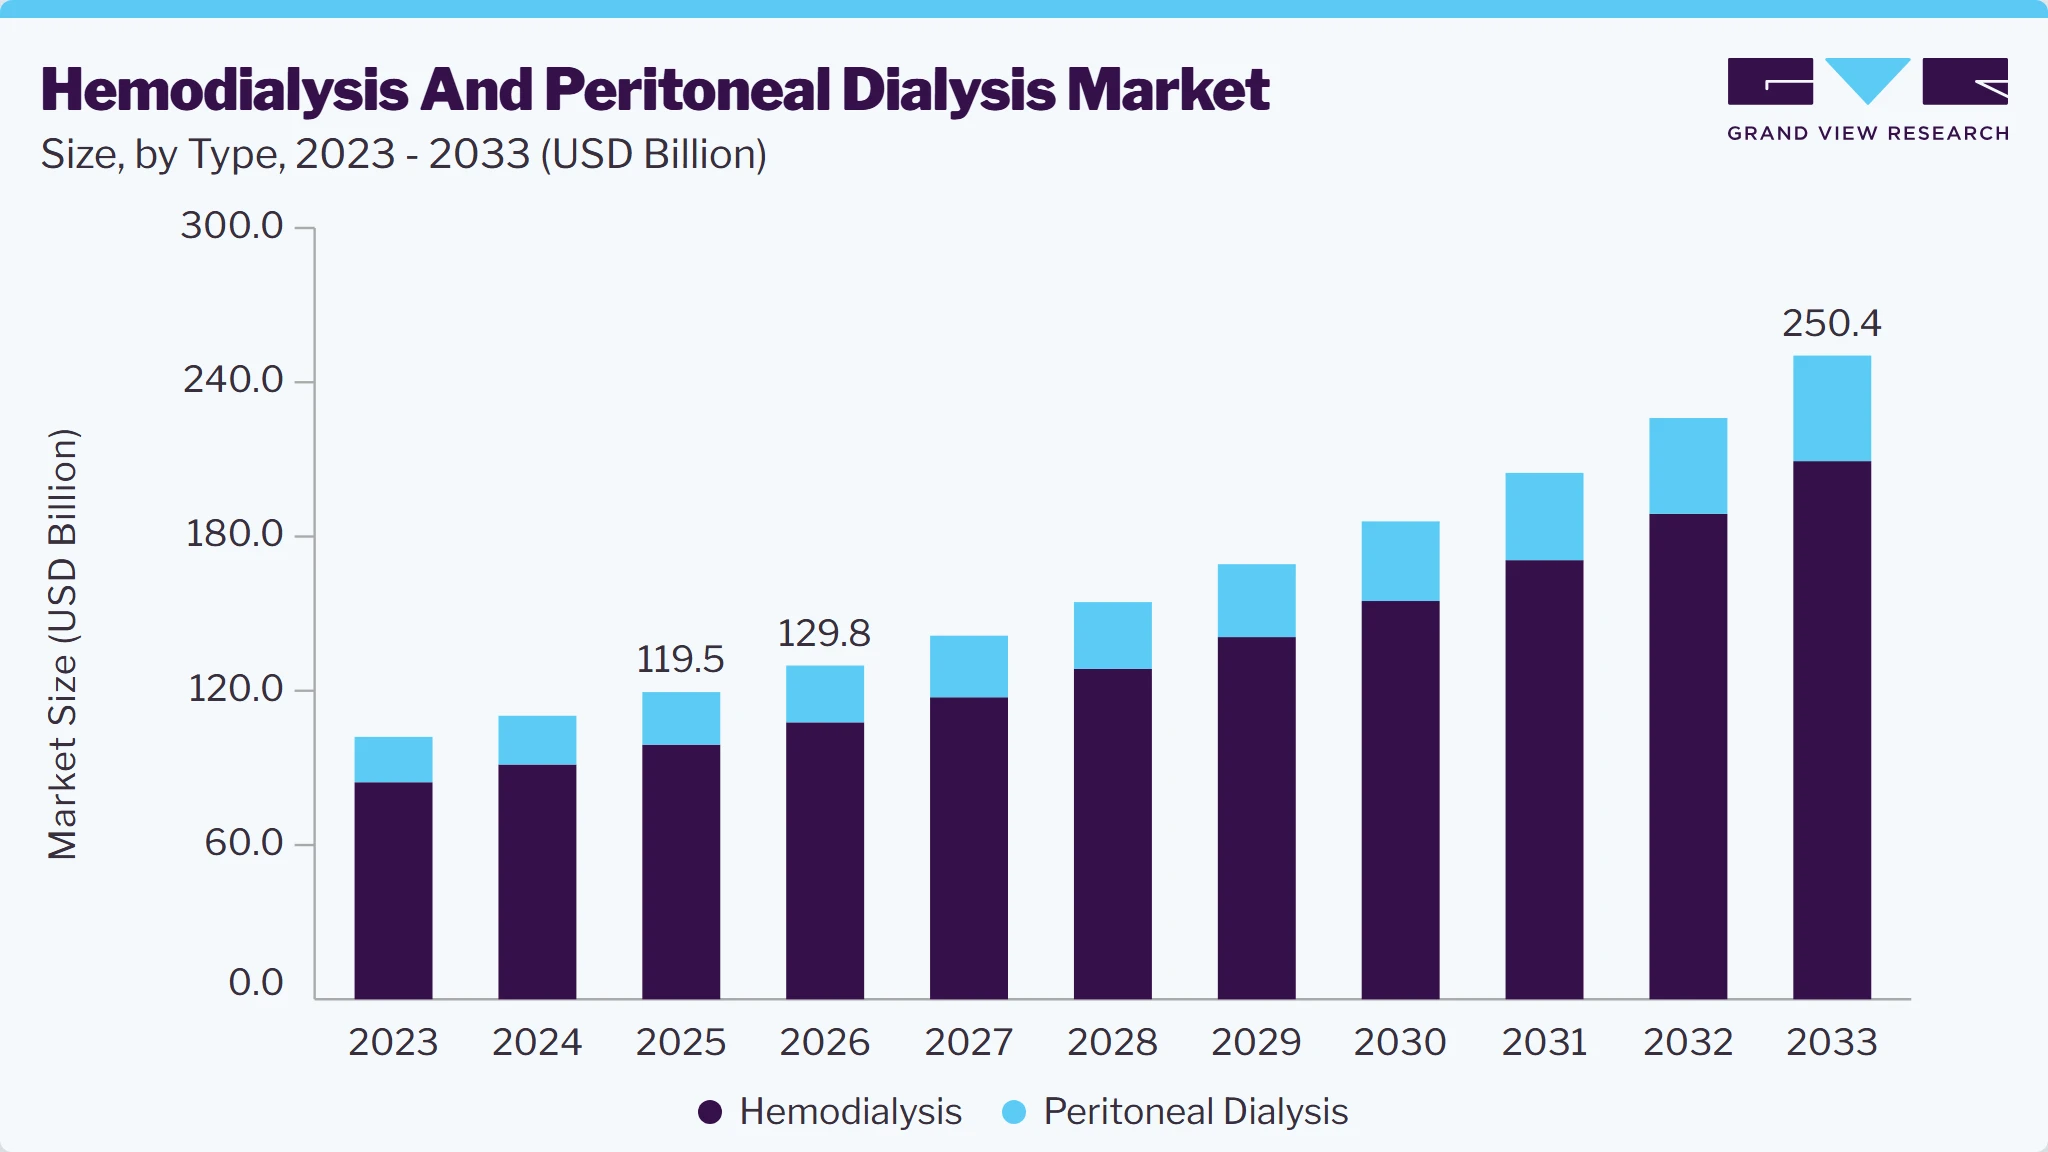 To learn more about this report, Download Free Sample Report
As the number of CKD patients continues to grow, the demand for long-term renal replacement therapies such as hemodialysis and peritoneal dialysis rises proportionally. This trend is driving investments in dialysis infrastructure, home-based treatment options, and advanced technologies, ultimately fueling sustained market growth. The following table shows the prevalence and mortality of chronic kidney disease in adults aged ≥20 years by socio-demographic index in 2023.
Prevalence and Mortality of Chronic Kidney Disease (CKD) in Adults Aged ≥20 Years by Socio-Demographic Index (SDI), 2023
Region
Prevalence Count (thousands), 2023
Age-standardized Prevalence (%), 2023
Deaths Count (thousand), 2023
Global
788,000
14.2%
1,480
Low SDI
111,000
15.2%
200
Low-middle SDI
106,000
16.1%
185
Middle SDI
96,800
16.3%
207
High-middle SDI
185,000
15.1%
282
High SDI
283,000
12.2%
594
Source: The Lancet, 2025
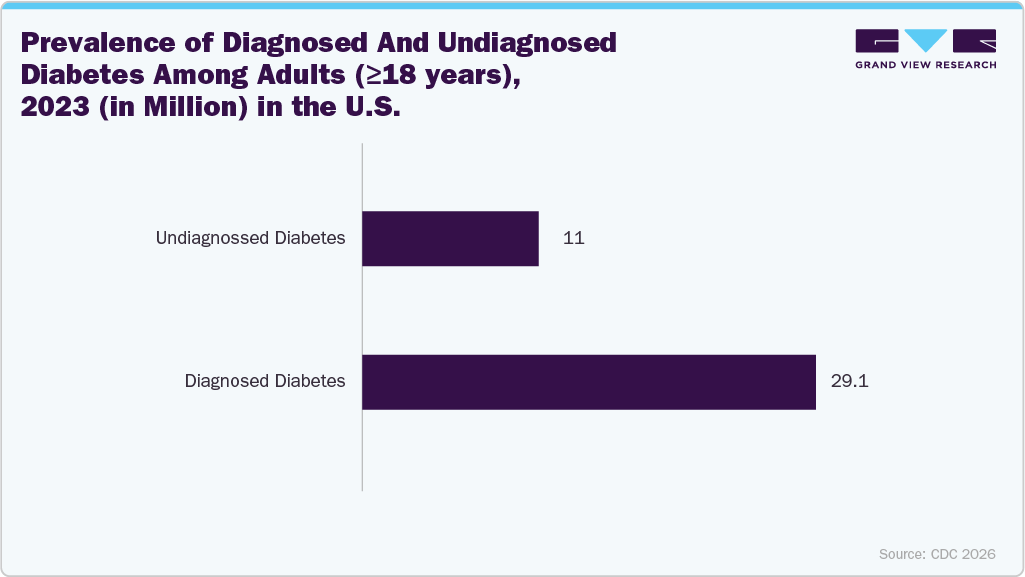
The growing burden of lifestyle-related diseases is a major factor accelerating the hemodialysis and peritoneal dialysis market, as these conditions are closely linked to kidney damage and eventual renal failure. Diseases such as Diabetes Mellitus and Hypertension are among the leading causes of chronic kidney disease, as prolonged high blood sugar levels and elevated blood pressure gradually impair kidney function over time. The increasing prevalence of obesity, physical inactivity, unhealthy diets, and smoking further exacerbates the risk of kidney complications, leading to a steady rise in CKD cases globally. According to the International Diabetes Federation in 2024, the global burden of Diabetes Mellitus is rapidly increasing, with approximately 589 million adults currently affected, a figure projected to reach 853 million by 2050, and notably, over 4 in 5 (81%) of these individuals residing in low- and middle-income countries.
“Diabetes is the number one cause of kidney disease; so, because more patients have diabetes, we’re seeing more kidney disease,” - Randy Luciano, MD, a Yale Medicine nephrologist.
 To learn more about this report, Download Free Sample Report
As more patients with these lifestyle-related conditions progress to advanced stages of kidney disease, the demand for renal replacement therapies such as hemodialysis and peritoneal dialysis increases significantly. In addition, the earlier onset of these diseases in younger populations extends the duration of dialysis dependency, thereby increasing long-term treatment demand. This growing patient pool is driving the expansion of dialysis centers, greater adoption of home-based peritoneal dialysis, and increased use of dialysis consumables and equipment.
The hemodialysis and peritoneal dialysis market is growing due to continuous technological advancements in dialysis equipment, which are improving treatment efficiency, patient comfort, and clinical outcomes. Innovations such as high-flux dialyzers, portable and wearable hemodialysis machines, and automated peritoneal dialysis (APD) systems are making dialysis more convenient and accessible, especially for home-based care. Advanced monitoring features, real-time data tracking, and integration with digital health platforms enable better patient management and reduce complications associated with long-term dialysis. For instance, in 2025, Fresenius Medical Care AG, a leading provider of renal care products and services, is showcasing new research highlighting that hemodiafiltration (HDF) is linked to improved patient outcomes. The company is also emphasizing the role of artificial intelligence (AI) innovations in helping clinicians manage patients more effectively and in a data-driven way.
In addition, the development of biocompatible materials and infection-resistant catheters is enhancing patient safety and reducing the risk of adverse events. These technological improvements are encouraging higher adoption of both hemodialysis and peritoneal dialysis, supporting the shift toward home care settings, and prompting healthcare providers to upgrade existing infrastructure, thereby significantly contributing to market growth.
“This research reflects Fresenius Medical Care’s commitment to patient-centered innovation, demonstrating how advanced therapies like hemodiafiltration can be tailored to improve outcomes in real-world settings.” - Frank Maddux, MD, Global Chief Medical Officer
Market Dynamics
The hemodialysis and peritoneal dialysis market is primarily driven by the rising global burden of End-Stage Renal Disease (ESRD), fundamentally associated with the increasing prevalence of diabetes, hypertension, and an aging population. The growing demand for long-term renal replacement therapy is driving dialysis adoption across both hospital- and home-based settings. Hemodialysis remains the dominant modality due to established infrastructure and clinical preference, while peritoneal dialysis is gaining traction for its flexibility, reduced dependence on healthcare facilities, and suitability for home care. Technological advancements in dialysis machines, dialyzers, and peritoneal solutions, along with improving reimbursement frameworks in developed countries, are further supporting growth.
The rising prevalence of chronic kidney disease and end-stage renal disease is a major factor driving growth in the hemodialysis and peritoneal dialysis market. Increasing cases of diabetes, hypertension, and obesity are contributing to the faster progression of kidney damage, leading to a higher number of patients requiring renal replacement therapy. As CKD remains undiagnosed until advanced stages, many patients are diagnosed when dialysis becomes immediately necessary, boosting demand for both hemodialysis and peritoneal dialysis treatments. This growing patient pool is increasing utilization of dialysis services across hospitals, dialysis centers, and home-care settings. In addition, improved survival rates of CKD patients are extending treatment duration, further supporting recurring demand for dialysis consumables and equipment.
- According to Kidney Care UK, in 2025, chronic kidney disease affected an estimated 7.2 million people in the UK. It is a lifelong and life-changing condition, placing significant illness and treatment burdens on people and families, and on the health service.
High treatment costs associated with dialysis procedures, equipment, and long-term consumables significantly limit access, especially in low- and middle-income countries. Hemodialysis requires expensive infrastructure, skilled healthcare professionals, and frequent hospital visits, which increases the economic burden on healthcare systems and patients. Peritoneal dialysis, while more flexible, is associated with risks such as peritonitis and other infections, which can reduce patient adoption and treatment continuity. Limited availability of dialysis centers in rural and underserved regions further restricts market penetration. In addition, complications such as cardiovascular issues, hypotension during hemodialysis, and catheter-related infections pose clinical challenges. Patient non-compliance, lack of awareness about early-stage kidney disease management, and shortages of trained nephrology professionals also act as barriers to market growth.
Technological advancements in dialysis machines are significantly driving the growth of the hemodialysis and peritoneal dialysis market by making treatment more efficient, accessible, and patient-friendly. Innovations such as portable and automated dialysis systems are enabling patients to receive therapy at home or in decentralized care settings, reducing reliance on hospital-based dialysis centers. This shift is increasing treatment adoption, especially among the elderly and patients with chronic kidney disease who prefer convenience and flexibility. Enhanced features as improved fluid control, real-time monitoring, and AI-enabled safety systems are improving clinical outcomes and reducing complications, thereby boosting physician confidence in prescribing dialysis therapies. In addition, technological improvements are helping optimize treatment time and operational efficiency, allowing healthcare providers to serve more patients. Thus, these advancements are expanding the dialysis patient base and accelerating market growth for both hemodialysis and peritoneal dialysis solutions globally.
- January 2026, Outset Medical announced that its next-generation Tablo Hemodialysis System received FDA 510(k) clearance. The updated platform is the first hemodialysis system to meet the FDA’s most rigorous cybersecurity standards introduced in 2025. It features enhanced hardware, an upgraded operating system, and improved software to strengthen performance, reliability, and user experience.
Market Concentration & Characteristics
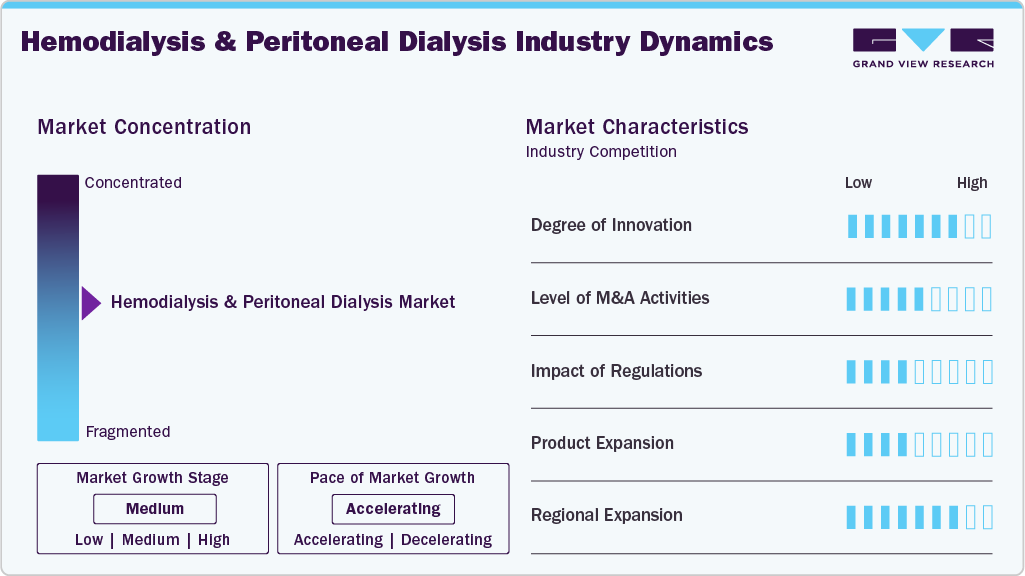
The hemodialysis and peritoneal dialysis market is characterized by a limited number of dominant players that account for a significant share of global revenue. The industry is highly integrated, with key participants involved across the value chain, including the production of dialysis equipment and consumables, and the delivery of treatment services. High barriers to entry, such as strict regulatory requirements, substantial capital investment, advanced technological expertise, and well-established distribution networks, limit new entrants' participation. The market operates on a recurring revenue model, driven by the continuous demand for dialysis consumables and long-term patient care. It is also characterized by a strong reliance on in-center dialysis services, though home-based dialysis is gradually increasing due to technological advancements and patient preference for convenience. In addition, regional and emerging players are contributing to competitive dynamics by offering cost-effective solutions and expanding access in developing regions.
The increasing degree of innovation is significantly driving the growth of the hemodialysis and peritoneal dialysis market by enhancing treatment efficiency, patient convenience, and clinical outcomes. Continuous advancements in dialysis technologies, such as high-flux membranes, hemodiafiltration systems, and biocompatible dialysis fluids, are improving toxin removal and reducing treatment-related complications. Integrating digital health solutions, including artificial intelligence and remote monitoring, enables personalized treatment plans and improved patient management, particularly in home-based settings. The development of portable and wearable dialysis devices is further transforming care delivery by increasing patient mobility and reducing dependency on in-center treatments. In addition, innovations focused on infection control, automation, and user-friendly interfaces are improving safety and adherence, encouraging wider adoption.
 To learn more about this report, Download Free Sample Report
- In January 2026, researchers at the Artificial Kidney Innovation Lab announced the completion of the CORDIAL clinical trial evaluating a novel peritoneal dialysis device, the WEAKID (Wearable Artificial Kidney), with the final patient studies concluding at the end of 2025.
Regulations are significantly contributing to the growth of the hemodialysis and peritoneal dialysis market by ensuring standardized, safe, and high-quality treatment practices while expanding patient access. Regulatory bodies such as the U.S. Food and Drug Administration enforce strict approval processes for dialysis machines, dialyzers, and consumables, ensuring product safety and performance, which drives innovation among manufacturers. Similarly, the Centers for Medicare & Medicaid Services supports market growth through reimbursement frameworks such as the End-Stage Renal Disease (ESRD) Prospective Payment System, which improves affordability and access to dialysis care. In Europe, the EU Medical Device Regulation mandates rigorous clinical evaluation and post-market surveillance, encouraging the development of safer and more effective dialysis technologies. In addition, global standards from the International Organization for Standardization, such as ISO 23500 for dialysis water quality, ensure consistent treatment quality and patient safety. These regulations collectively promote technological advancement, increase adoption of home dialysis, and enhance healthcare delivery, thereby accelerating market growth.
-
In December 2025, Nephrodite developed the Holly implantable dialysis system, which received FDA Breakthrough Device Designation in the same month. This device is designed to function continuously inside the body, mimicking natural kidney function and significantly improving patient mobility and quality of life compared to conventional dialysis.
The level of mergers and acquisitions (M&A) activities is significantly contributing to the growth of the hemodialysis and peritoneal dialysis market by enabling companies to expand their service networks, enhance technological capabilities, and strengthen market presence. Large players are acquiring smaller, regional dialysis providers to expand their footprint, particularly in emerging markets, thereby improving patient access to treatment services. These strategic acquisitions also allow companies to integrate advanced technologies, streamline operations, and achieve economies of scale, resulting in cost efficiencies and improved service delivery. In addition, M&A activities are facilitating the transition toward value-based care models and accelerating the adoption of home dialysis solutions by combining clinical expertise with digital and innovative capabilities. Partnerships and acquisitions are also helping companies diversify their product portfolios and enter new geographic regions more efficiently.
-
In August 2025, Quest Diagnostics announced the completion of its acquisition of select clinical testing assets from Fresenius Medical Care, enhancing its capability to deliver dialysis-related laboratory services across the U.S.
Regional expansion is playing a crucial role in driving the growth of the hemodialysis and peritoneal dialysis market by increasing access to treatment and strengthening healthcare infrastructure across underserved and emerging regions. Companies are actively expanding into Asia-Pacific, Latin America, the Middle East, and Africa, where the burden of chronic kidney disease is rising, but dialysis penetration remains relatively low. This expansion involves establishing new dialysis centers, forming partnerships with local healthcare providers, and investing in training and infrastructure development, collectively improving patient access to life-saving treatments. In addition, regional expansion allows companies to tap into large patient pools, diversify revenue streams, and reduce dependence on mature markets. Governments in many regions are also supporting dialysis expansion through public healthcare initiatives and reimbursement programs, further accelerating adoption. As a result, increasing geographic reach is enhancing treatment availability, improving early diagnosis and care, and significantly contributing to market growth.
-
In July 2025, Fresenius Medical Care announced a collaboration with the Coordination of National Institutes of Health and Specialty Hospitals to expand access to high-volume hemodiafiltration therapy for patients across multiple treatment centers in Mexico.
Analyst Perspective
The hemodialysis and peritoneal dialysis market is witnessing steady growth, driven by the rising global prevalence of end-stage renal disease (ESRD) and increasing incidence of diabetes and hypertension, which are key risk factors for chronic kidney failure. Market participants are increasingly focusing on improving dialysis efficiency, patient comfort, and treatment flexibility through advanced hemodialysis machines, high-performance dialyzers, automated peritoneal dialysis (APD) systems, and biocompatible solutions. The shift from in-center dialysis toward home-based and self-care dialysis models is gaining momentum, supported by cost containment pressures and the growing need for patient-centric care delivery. In addition, innovations in wearable and portable dialysis technologies, along with digital remote monitoring platforms, are expected to enhance treatment adherence and clinical outcomes while expanding long-term market opportunities.
Type Insights
Based on type, the hemodialysis segment led the market with an 82.9% revenue share in 2025 and is expected to grow at the fastest CAGR over the forecast period. In addition, the hemodialysis segment is further fragmented into conventional, short daily hemodialysis, and nocturnal hemodialysis. Hemodialysis is the process of removing excess fluids and waste products from the body using a hemodialyzer. When the blood flows through the filter, it encounters dialysate, which is identical to body fluid but contains pollutants. This type of dialysis is more complex than others, with strict guidelines for treatment and limited options for patients' time, mobility, and transportation. A dialysis catheter, an AV fistula, or an AV graft in the arm or groin is an example of vascular access that must be established and maintained to obtain the high blood flow necessary for dialysis.
The peritoneal dialysis segment is further sub-segmented into Continuous Ambulatory Peritoneal Dialysis (CAPD) and Ambulatory Peritoneal Dialysis (APD). The segment is growing due to several important factors, including an increase in the number of patients with end-stage renal disease (ESRD), a rise in the elderly population with kidney illnesses, and an increase in the incidence of diabetes and hypertension. According to a report released by the WHO in March 2025, approximately 1.28 billion people worldwide suffer from hypertension. Consequently, the increasing number of patients with comorbidities is expected to drive demand for hemodialysis.
Product Insights
Based on product, the services segment led the market with the largest revenue share of 56.7% in 2025. In 2025, the service is dominating the hemodialysis and peritoneal dialysis market. This dominant share is attributed both to the prevalence of ESRD and the increased number of dialysis service providers. Segment growth is anticipated to be aided by the opening and acquisition of new dialysis centers by several major dialysis service providers, which aim to broaden their service offerings globally. The market is expected to grow further driven by technological developments and initiatives from various manufacturers. For instance, DaVita incorporated secured telehealth technology, DaVita Care Connect, into its home dialysis sector. It was one of the many connective technologies in its suite of services aimed at improving treatment and outcomes for patients who choose to treat themselves at home.
The consumables are expected to grow at the fastest CAGR over the forecast period. Over the projection period, the segment is anticipated to be driven by significant government investments to improve patient safety, patient-centered care, and efficacy. Companies produce catheters made of advanced materials that are resistant to chemicals, including alcohol, iodine, and peroxides. This can lessen the likelihood of a catheter malfunction and help it last longer. There is a growing need for catheters coated with antimicrobial agents to reduce bloodstream infections. In contrast, the expansion of the consumable market is positively impacted by novel dialyzer production technologies, such as enhanced surface contact and cutoff membrane dialyzers, which improve diffusion. The market for consumables has been further divided into categories such as catheters, concentrates, bloodlines, and others.
End Use Insights
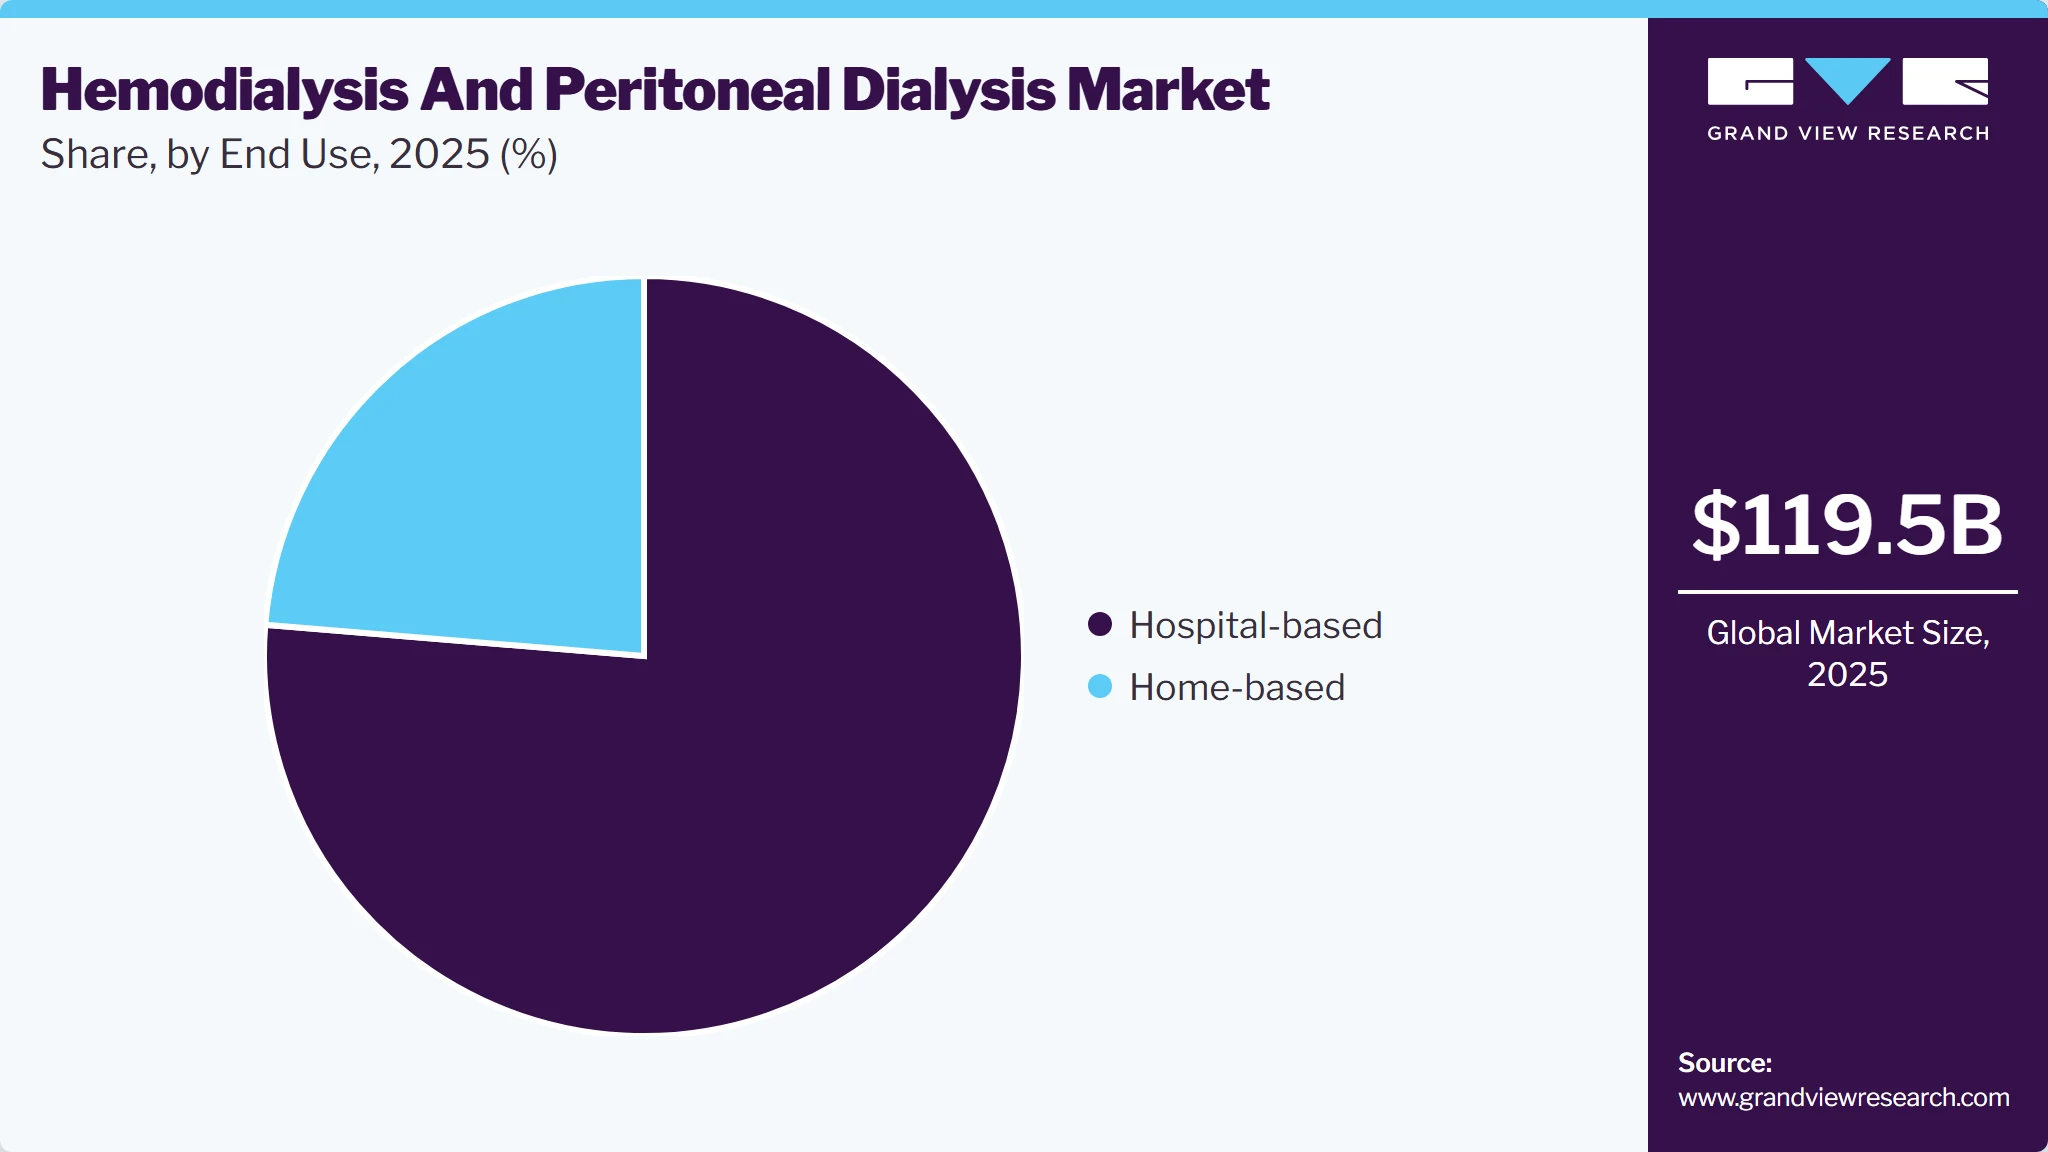
Based on end-use, the hospital-based segment accounted for the largest revenue share of 76.3% in 2025. Segmental dominance is likely to remain strong in the coming years, given the significant availability of highly qualified and experienced healthcare personnel in hospitals. The presence of a professional, experienced renal care team ensures optimal treatment and improved dialysis outcomes in healthcare settings such as dialysis centers and hospitals. In addition, the growing focus of players on building independent dialysis centers and the high adoption of in-center dialysis by patients are among the factors projected to drive segment growth. Moreover, companies are focusing on developing customized hemodialysis machines through various interventions.
 To learn more about this report, Download Free Sample Report
However, the home-based segment is projected to grow at the fastest CAGR over the forecast period. The adoption rate of home dialysis is expected to increase in the years ahead due to its many benefits, including improved quality of life, reduced travel expenses, greater flexibility, and easier patient mobility. Similarly, an increase in the older population's preference for home dialysis therapy due to various renal dysfunctions may further enhance segment income. More patients are preferring this type of dialysis to preserve their independence and high functional status, driven by the development of smaller, nightstand-sized dialysis machines and simpler blood tubing and dialyzer connections.
Regional Insights
North America dominated the hemodialysis and peritoneal dialysis industry, with the largest revenue share of 38.10% in 2026. Important industry players, significant government funding for the development of cutting-edge medical equipment, and a fair reimbursement environment all contribute to the region's market expansion. Dialysis is becoming more necessary as the prevalence of kidney failures and chronic kidney diseases rises. A few key factors driving market expansion include rising healthcare costs, government initiatives, and increased disposable income. Also, increasing incidences of diabetes and obesity lead to kidney disorders, which boost industry growth.
 To learn more about this report, Download Free Sample Report
U.S. Hemodialysis and Peritoneal Dialysis Market Trends
The rising prevalence of chronic kidney disease in the U.S. is a major driver of growth in the hemodialysis and peritoneal dialysis market. A large and growing number of CKD patients progress to end-stage renal disease (ESRD), where dialysis becomes essential for survival. This increasing disease burden is strongly linked to the high and rising incidence of diabetes, hypertension, and obesity in the country, all of which are leading causes of kidney damage. As more patients advance to later stages of CKD, the demand for renal replacement therapies continues to rise.
This growing patient pool is driving increased utilization of both in-center hemodialysis and home-based peritoneal dialysis. Healthcare providers are expanding dialysis infrastructure, including treatment centers, advanced dialysis machines, and consumables, to manage the rising caseload. There is a gradual shift toward peritoneal dialysis due to its convenience, reduced hospital dependence, and growing support for home-based care models. The expanding CKD burden is creating sustained demand and long-term growth opportunities for the U.S. dialysis market.
Percentage of US adults aged 18 years and older with CKD by age, sex, and race-ethnicity 2023
Age, Sex, and Race-Ethnicity
Percentage
95% CI
Est. Number (in Millions)
95% CI
18-44
5.6
4.3-7.3
6.4
4.8-8.0
45-64
12.9
11.0-15.0
10.1
8.2-11.9
65+
34.2
31.1-37.6
20.1
18.5-21.6
Men
14.1
12.4-15.9
16.9
14.9-18.9
Women
14.7
12.7-17.0
19.7
17.6-21.8
Non-Hispanic White
13.1
11.6-14.7
23.2
21.0-25.5
Non-Hispanic Black
22
16.5-28.6
6.3
5.0-7.7
Non-Hispanic Asian
16.4
12.6-21.0
2.4
1.7-3.2
Hispanic
12.1
9.3-15.5
4.6
3.6-5.5
Source: CDC 2026
Europe Hemodialysis and Peritoneal Dialysis Market Trends
The Europe hemodialysis and peritoneal dialysis market is experiencing steady and strong growth, driven primarily by the rising burden of chronic kidney disease (CKD) and end-stage renal disease (ESRD) across the region. The increasing prevalence of diabetes, hypertension, and an aging population is significantly expanding the patient pool requiring renal replacement therapies. As more patients progress to advanced stages of kidney failure, demand for both in-center hemodialysis and home-based peritoneal dialysis continues to rise consistently. For instance, in Europe, an estimated 93.1 million adults have CKD, of whom 750,000 are on Kidney Replacement Therapy (KRT), and 210,000 people (one every 2.5 minutes) die from CKD. Of relevance for public health planning, diabetes and hypertension accounted for ≤ 30% of prevalent KRT in Europe.
In addition, Europe’s well-established healthcare infrastructure, strong reimbursement systems in several countries, and growing adoption of home dialysis therapies are supporting market expansion. Hemodialysis remains the dominant treatment due to its widespread clinical availability, while peritoneal dialysis is gaining traction for its convenience, reduced hospital dependency, and alignment with patient-centric care models.
The UK hemodialysis and peritoneal dialysis market is experiencing expansion, primarily driven by the rising burden of chronic kidney disease (CKD), diabetes, hypertension, and an aging population that is increasing demand for long-term renal replacement therapies. Within the NHS framework, a significant proportion of patients rely on in-center hemodialysis, while peritoneal dialysis is gradually gaining importance due to its suitability for home-based care and improved patient convenience. The market is also being shaped by the UK healthcare system’s strategic push toward home dialysis adoption, supported by remote patient monitoring technologies, training programs, and policies aimed at reducing hospital dependency and improving quality of life for patients. At the same time, investments in advanced dialysis machines, portable systems, and automated peritoneal dialysis (APD) solutions are improving treatment efficiency and accessibility. However, challenges such as high treatment costs, staffing constraints, and regional variation in service access continue to influence adoption patterns, making the market a mix of strong demand growth and operational constraints within the NHS renal care ecosystem.
 To learn more about this report, Download Free Sample Report
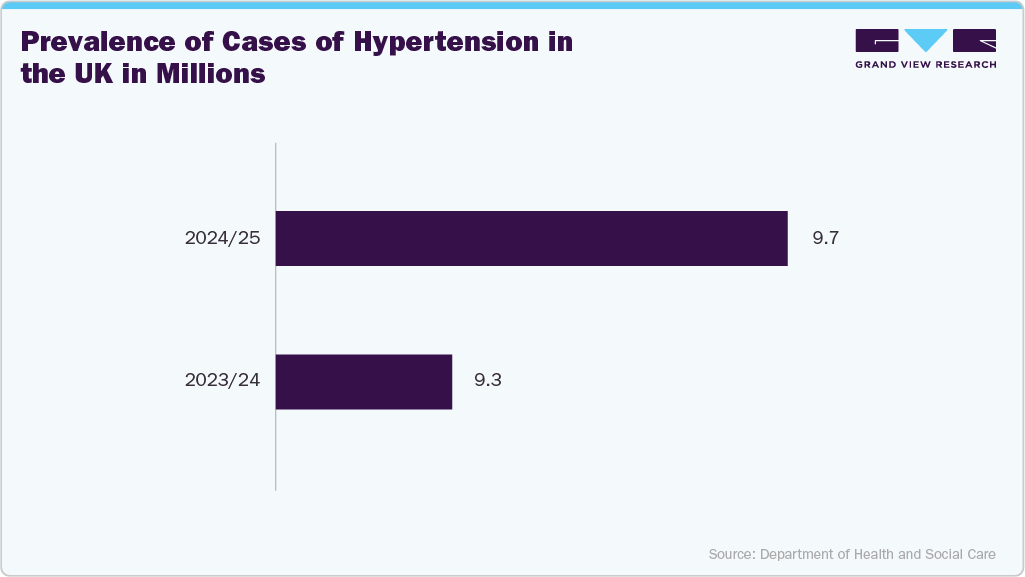
The Germany hemodialysis and peritoneal dialysis market rising prevalence of hypertension in is a major driver of growth in the hemodialysis and peritoneal dialysis market, as uncontrolled high blood pressure is one of the leading causes of chronic kidney disease and end-stage renal disease. Persistent hypertension gradually damages the small blood vessels in the kidneys, reducing their ability to filter blood effectively and leading to progressive loss of kidney function, a condition known as hypertensive nephrosclerosis. Over time, this irreversible damage significantly increases the likelihood of kidney failure, where patients require dialysis, most commonly hemodialysis, for survival. As the hypertensive population continues to grow due to aging demographics, sedentary lifestyles, obesity, and dietary factors, more patients are progressing to advanced kidney disease stages in Germany.
-
According to the International Society for Pharmacoeconomics and Outcomes Research, Inc., for the year 2025, our model predicts the prevalence figures to increase to 17.3M in Germany
Asia Pacific Hemodialysis and Peritoneal Dialysis Market Trends
Asia Pacific is anticipated to grow at the fastest CAGR over the forecast period. Growing rates of renal failure, an aging population, and increased research and development of cutting-edge technologies are expected to drive market growth over the projected period. In addition, according to the IDF, there are already 88 million adults in Southeast Asia who have diabetes, and by 2045, that figure is predicted to rise to 153 million. In addition, a few other factors driving market expansion are expanding government initiatives, CKD awareness programs, technologically advanced products, and the availability of recently built, modern healthcare facilities in the area.
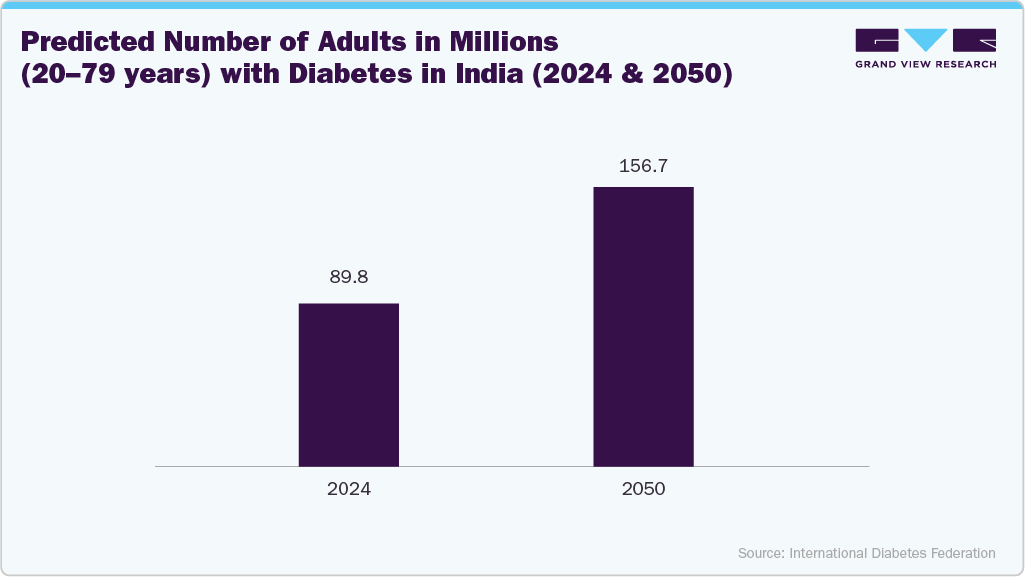
The hemodialysis and peritoneal dialysis market in Indi a is witnessing growth due to a rising number of diabetes patients in the country. Diabetes is one of the leading causes of chronic kidney disease and end-stage renal disease. Long-standing uncontrolled blood sugar levels damage the tiny blood vessels and filtering units (glomeruli) in the kidneys, a condition known as diabetic nephropathy. Over time, this damage reduces the kidneys’ ability to filter waste, excess fluids, and toxins from the blood, eventually leading to severe kidney failure that requires dialysis for survival. As diabetes prevalence continues to increase rapidly in India due to urbanization, sedentary lifestyles, unhealthy diets, and rising obesity rates, a growing proportion of patients are progressing to advanced kidney disease stages. This is significantly increasing demand for hemodialysis, which is the most widely used treatment for ESRD, while also supporting the gradual adoption of peritoneal dialysis as a home-based alternative.
 To learn more about this report, Download Free Sample Report
The Japan hemodialysis and peritoneal dialysis market is strongly driven by its rapidly aging population, which is among the highest in the world. A large share of Japan’s population is aged 65 and above, and this demographic group is more vulnerable to chronic kidney disease due to age-related decline in kidney function, reduced regenerative capacity, and higher prevalence of comorbidities such as diabetes and hypertension. As people age, kidney filtration efficiency naturally decreases, and long-term health conditions further accelerate kidney damage, increasing the likelihood of progression to end-stage renal disease that requires dialysis. This expanding elderly population has significantly increased the demand for long-term renal replacement therapies, particularly hemodialysis, which remains the dominant treatment due to its effectiveness and strong clinical infrastructure in Japan.
- According to the World Economic Forum, Japan's Ministry of Internal Affairs and Communications reported that, as of 2024, the country had a record 36.25 million people aged 65 and over, accounting for 29.3% of the total population. This share is projected to rise to 34.8% in 2040 and 36.3% in 2045. Japan's proportion of elderly residents is already far higher than second-ranked Martinique (25.3%), making it the world's most aged society.
Latin America Hemodialysis and Peritoneal Dialysis Market Trends
The increasing prevalence of chronic kidney disease in Latin America is a key driver of the hemodialysis and peritoneal dialysis market, as more patients progress to end-stage renal disease that requires ongoing dialysis treatment. CKD is rising in the region mainly due to high rates of diabetes, hypertension, obesity, and delayed diagnosis, which allow kidney damage to advance unchecked until later stages. As kidney function deteriorates, a growing number of patients require renal replacement therapy, significantly increasing demand for both hemodialysis and peritoneal dialysis services. Limited awareness and unequal access to early-stage care in several countries further contribute to the late presentation of CKD, reinforcing the need for dialysis interventions.
- According to a 2025 study published by the National Library of Medicine, 72,486 participants from 21 observational studies reported CKD prevalence in Latin American populations. The pooled CKD prevalence was 17.14% with high heterogeneity. Age-stratified analysis revealed a prevalence of 11.66% in younger adults and 28.29% in older adults. Women showed a higher prevalence (19.23%) compared to men (16.75%)
Middle East & Africa Hemodialysis and Peritoneal Dialysis Market Trends
The Middle East and Africa region is experiencing growth in the hemodialysis and peritoneal dialysis market, driven by the increasing prevalence of chronic kidney disease and end-stage renal disease, primarily associated with rising cases of diabetes, hypertension, and obesity. In several countries across the region, limited awareness of early-stage kidney disease and delayed diagnosis lead to faster progression of CKD, resulting in a higher number of patients requiring dialysis treatment. This growing disease burden is increasing demand for both hemodialysis and peritoneal dialysis services. Governments and private healthcare providers are investing in expanding dialysis infrastructure, including new dialysis centers, advanced equipment, and improved access to renal care services. For instance, under Saudi Vision 2030, the Saudi Arabian Government plans to invest over $65 billion to develop the country's healthcare infrastructure, reorganize and privatize health services and insurance, launch 21 health clusters across the country, and expand the provision of e-health services. In addition, it aims to increase the private sector's contribution from 40 percent to 65 percent by 2030, targeting the privatization of 290 hospitals and 2,300 primary health centers.
Key Hemodialysis and Peritoneal Dialysis Company Insights
The key players are focusing on growth strategies, such as new product launches, regulatory approvals, expansion, collaborations, acquisitions, and partnerships. Moreover, key industry players are also involved in enhancing R&D for hemodialysis. For instance, in April 2023, Outset Medical, Inc., with its Tablo Hemodialysis System, decided to lower the cost and complexity of dialysis. At the National Kidney Foundation Spring Clinical Meetings, the company will present five new abstracts that offer promising findings on the clinical and economic advantages of home hemodialysis (HHD), gender biases against female nephrologists, and other topics related to kidney disease.
Key Hemodialysis And Peritoneal Dialysis Companies:
The following key companies have been profiled for this study on the hemodialysis and peritoneal dialysis market.
-
Baxter
-
B. Braun SE
-
Fresenius Medical Care AG
-
Medtronic
-
Asahi Kasei Medical Co., Ltd.
-
Nipro Corp.
-
DaVita (Optum)
-
BD
-
Nikkiso Co., Ltd.
-
Cantel Medical (STERIS plc)
-
Diaverum (M42)
-
vivISOL
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Baxter, B. Braun SE, Fresenius Medical Care AG, Medtronic, Asahi Kasei Medical Co., Ltd., Nipro Corp., DaVita (Optum), BD, Nikkiso Co., Ltd., Diaverum (M42))
- Invest in advanced hemodialysis and peritoneal dialysis technologies to expand home-based treatment options and improve patient outcomes globally.
- Expand dialysis clinic networks, strengthen distribution channels, and enhance integrated care services to increase market penetration worldwide.
- Extensive global dialysis infrastructure, established brand recognition, and comprehensive product portfolios enable strong market presence and customer loyalty.
- Significant R&D capabilities, regulatory expertise, and broad distribution networks support continuous innovation and large-scale market access.
- High operational and manufacturing costs can reduce profitability and limit the ability to respond to pricing pressures.
- Large organizational structures may slow innovation cycles and delay adaptation to emerging technologies and evolving patient needs.
Emerging Players (Derma Sciences (vivISOL, Quanta Dialysis Technologies, Outset Medical, Toray Medical Co., Ltd.)
- Focus on developing innovative, portable, and home-based dialysis technologies that improve convenience, accessibility, and the patient experience.
- Establish strategic partnerships with healthcare providers and distributors to accelerate commercialization and expand market reach efficiently.
- Agile development processes enable faster innovation and rapid adoption of advanced dialysis technologies tailored to evolving patient needs.
- A strong focus on portable, home-based, and user-friendly solutions differentiates the offerings from traditional dialysis systems.
- Limited financial resources and smaller commercial networks can restrict market expansion and large-scale product adoption.
- Lower brand recognition and fewer established customer relationships may slow acceptance among healthcare providers and patients.
Recent Developments
-
January 2026, Baxter International Inc. announced a multi-year strategic partnership with MUSC Health to transform bedside care delivery through connected healthcare technologies. The collaboration focuses on integrating advanced digital and connected care solutions to improve hospital workflows, particularly in nursing environments. The initiative is designed to address key healthcare challenges, including nursing workload, documentation burden, and care efficiency, while enhancing patient safety and clinical outcomes.
-
January 2026, Outset Medical announced that its next-generation Tablo Hemodialysis System received FDA 510(k) clearance, marking a major regulatory milestone. The updated platform is the first hemodialysis system to meet the FDA’s most rigorous cybersecurity standards introduced in 2025. It features enhanced hardware, an upgraded operating system, and improved software to strengthen performance, reliability, and user experience.
-
In June 2025, Fresenius Medical Care announced the broader U.S. commercialization of its updated 5008X CARE system, following U.S. FDA 510(k) clearance for the next-generation hemodiafiltration-capable dialysis device. The system is part of the company’s initiative to introduce high-volume hemodiafiltration therapy for patients with chronic kidney disease across the U.S. This advanced dialysis approach is already widely used in Europe and is being positioned as a new standard of care in the U.S.
Hemodialysis And Peritoneal Dialysis Market Report Scope
Report Attribute
Details
Market size in 2025
USD 119.5 billion
Estimated Market size in 2026
USD 129.8 billion
Projected Market size by 2033
USD 250.4 billion
Growth rate
CAGR of 9.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, product, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
Baxter International Inc. (Vantive), B. Braun SE, Fresenius Medical Care AG, Medtronic plc, Asahi Kasei Medical Co., Ltd., Nipro Corporation, DaVita Inc. (Optum), Becton, Dickinson and Company (BD), Nikkiso Co., Ltd., Diaverum (M42), Vivisol, Quanta Dialysis Technologies Ltd., Toray Medical Co., Ltd., Outset Medical, Inc.
Customization scope
Free report customization (equivalent to up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Hemodialysis And Peritoneal Dialysis Market Report Segmentation
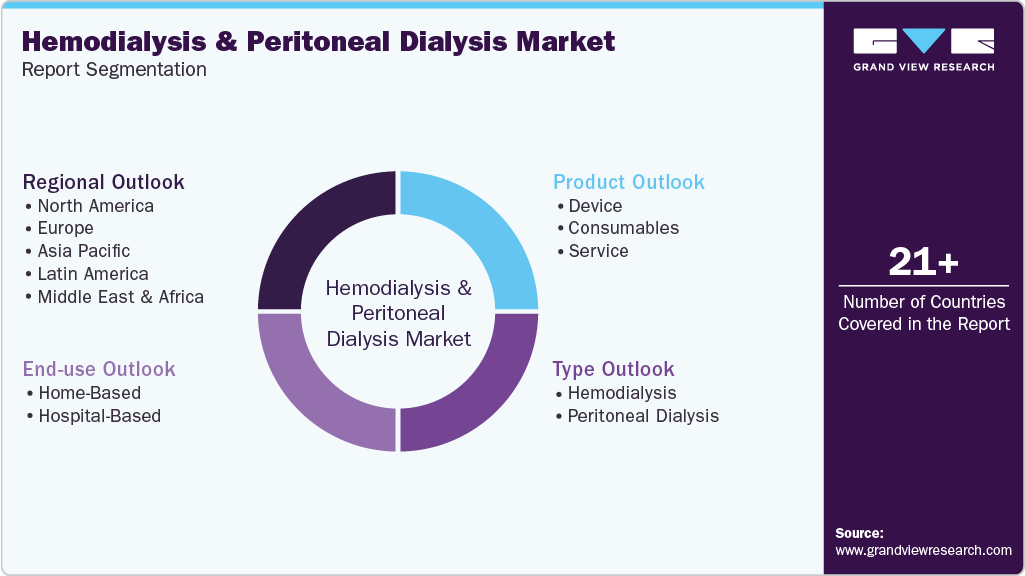
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global hemodialysis and peritoneal dialysis market report based on type, product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Hemodialysis
-
Conventional hemodialysis
-
Short daily hemodialysis
-
Nocturnal hemodialysis
-
-
Peritoneal Dialysis
-
Continuous Ambulatory Peritoneal Dialysis (CAPD)
-
Automated Peritoneal Dialysis (APD)
-
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Device
-
Machine
-
Dialyzer
-
Water treatment system
-
Others
-
-
Consumables
-
Bloodline
-
Concentrates
-
Catheters
-
Others
-
-
Service
-
- End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Home-Based
-
Hospital-Based
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The hemodialysis and peritoneal dialysis market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hemodialysis and peritoneal dialysis segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Device
Revenue is generated by selling or leasing high-flux dialysis machines to clinics. Facilities generate income per treatment session by using these units, bundling equipment costs into long-term service contracts or capitalizing on recurring per-procedure reimbursement models.
Consumables
This stream drives continuous revenue through the sale of single-use dialyzers, bloodlines, fistulas, and concentrates. Clinics recapture these ongoing costs via specialized insurance billing codes mapped directly to the specific disposable items consumed during each session.
Services
Providers secure revenue by delivering specialized clinical care, including nursing supervision, machine setup, and vascular access maintenance. Revenue is captured through comprehensive, per-treatment healthcare reimbursement bundles paid by government insurers or private medical plans.
Estimation Model
Estimation Approach
Description
Bottom-Up Epidemiological Modeling
Dialysis patient population estimation across CKD stages using prevalence, incidence, and progression rates. Incorporates modality uptake (HD vs PD), treatment duration, and regional demographic adjustments.
Top-Down Revenue Triangulation
Analyzing total dialysis market revenues reported by key industry players, investors, and health authorities and allocating shares to HD and PD segments based on modality mix trends.
Demand-Side Care-Setting Modeling
Assessing dialysis volumes across care settings (in-center, home, self-care, assisted PD), factoring in patient preferences, clinical suitability, reimbursement policies, and infrastructure availability.
Supply-Side Capacity & Utilization Modeling
Evaluating installed dialysis capacity, machine utilization rates, and provider network density to estimate achievable treatment volumes and identify capacity-constrained vs. underpenetrated geographies.
Data Triangulation & Market Reconciliation
Synthesizing outputs from multiple models with primary research, payer claims, regulatory data, and expert insights to ensure robust, validated market size estimates.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
ASP and volume analysis (historical and forecast)
Comprehensive ASP (Average Selling Price) and volume analysis for hemodialysis and peritoneal dialysis products across 2021–2033, segmented by product type (machines, dialyzers, consumables) modality (in-center hemodialysis, home hemodialysis, CAPD, APD), and geography. Includes historical trend analysis, current pricing dynamics, and forward-looking projections based on demand, reimbursement shifts, and technology adoption curves.
Enables long-term revenue forecasting, pricing strategy optimization, identification of high-growth product segments, and supports investment decision-making through visibility into ASP compression/expansion trends and volume-driven market expansion.
Disease epidemiology and patient population analysis
Detailed epidemiological assessment covering prevalence, incidence, and patient segmentation of chronic kidney disease (CKD) and end-stage renal disease (ESRD), including treatment distribution across hemodialysis, peritoneal dialysis, and conservative care across key geographies.
Enables accurate demand forecasting, supports dialysis capacity planning, reimbursement strategy development, and strengthens long-term market sizing for dialysis therapies and consumables.
Product share analysis by manufacturer and product type
Revenue and volume-based market share estimation at product level - including hemodialysis machines, dialyzers, bloodlines, concentrates, peritoneal dialysis cyclers, dialysis solutions, and catheters - segmented by manufacturer.
Provides insights into competitive positioning, technology leadership, procurement trends, and growth opportunities across in-center and home dialysis segments.
Frequently Asked Questions About This Report
Key factors include increasing incidence of chronic kidney disease, the availability of advanced dialysis, machines disposables and replacement fluids, and rising government initiatives to increase the accessibility of dialysis treatment and growing adoption of home hemodialysis.
Asia Pacific is the fastest-growing region over the forecast period.
North America dominated the hemodialysis and peritoneal dialysis market, accounting for 38.1% of revenue in 2025.
The global hemodialysis and peritoneal dialysis market size was valued at USD 119.5 billion in 2025 and is expected to reach USD 129.8 billion in 2026.
The services segment led with a 56.7% revenue share in 2025, while the consumables segment is the fastest-growing.
The hospital-based segment led with a 76.3% revenue share in 2025, while the home-based segment is the fastest-growing segment.
The global hemodialysis and peritoneal dialysis market is expected to grow at a compound annual growth rate of 9.8% from 2026 to 2033, reaching USD 250.4 billion by 2033.
Key players include: Baxter International Inc. (Vantive), B. Braun SE, Fresenius Medical Care AG, Medtronic plc, Asahi Kasei Medical Co., Ltd., Nipro Corporation, DaVita Inc. (Optum), Becton, Dickinson and Company (BD), Nikkiso Co., Ltd., Diaverum (M42), Vivisol, Quanta Dialysis Technologies Ltd., Toray Medical Co., Ltd., and Outset Medical, Inc., among others
The hemodialysis segment led with an 82.9% revenue share in 2025 and is the fastest-growing segment.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


