
- Home
- »
- Pharmaceuticals
- »
-
Herbal Medicine Market Size And Share Report, 2026-2033GVR Report cover

Herbal Medicine Market (2026 - 2033)
Size, Share & Trends Analysis Report By Intervention (Ayurveda, Traditional Chinese Medicine), By Product Form (Tablet/Capsules, Powder), By Source, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$107.7BMarket Estimate, 2026
$133.5BMarket Forecast, 2033
$630.0BCAGR, 2026–2033
24.8%Herbal Medicine Market Summary
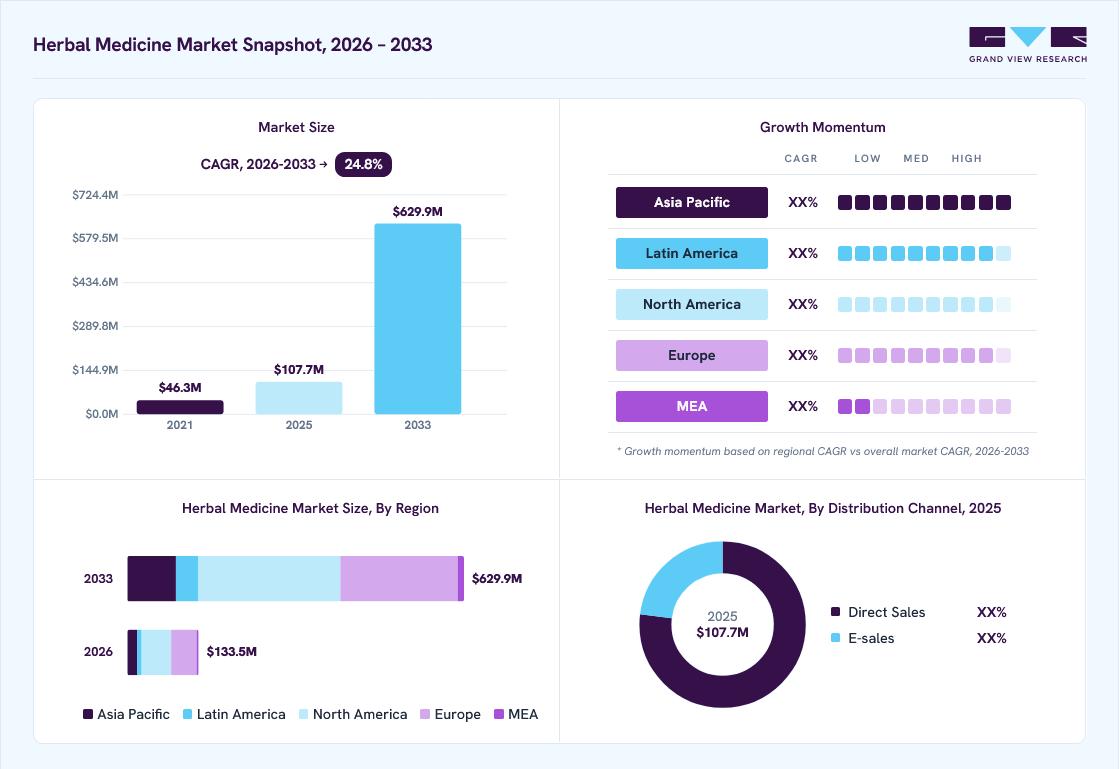
The global herbal medicine market size was valued at USD 107.7 billion in 2025 and is projected to grow from USD 133.5 billion in 2026 to USD 630.0 billion by 2033, growing at a CAGR of 24.8% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 41.2% in 2025. This growth is majorly due to rising health consciousness, increasing consumer preference for natural remedies, and technological advancements in the extraction and formulation of herbal medicines.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By intervention: Traditional chinese medicine segment held the largest share of 37.0% in 2025.
- By product form: Tablets/capsules segment held the largest revenue share of 41.6% in 2025.
- By source: Roots segment led the market with the largest revenue share of 38.0% in 2025.
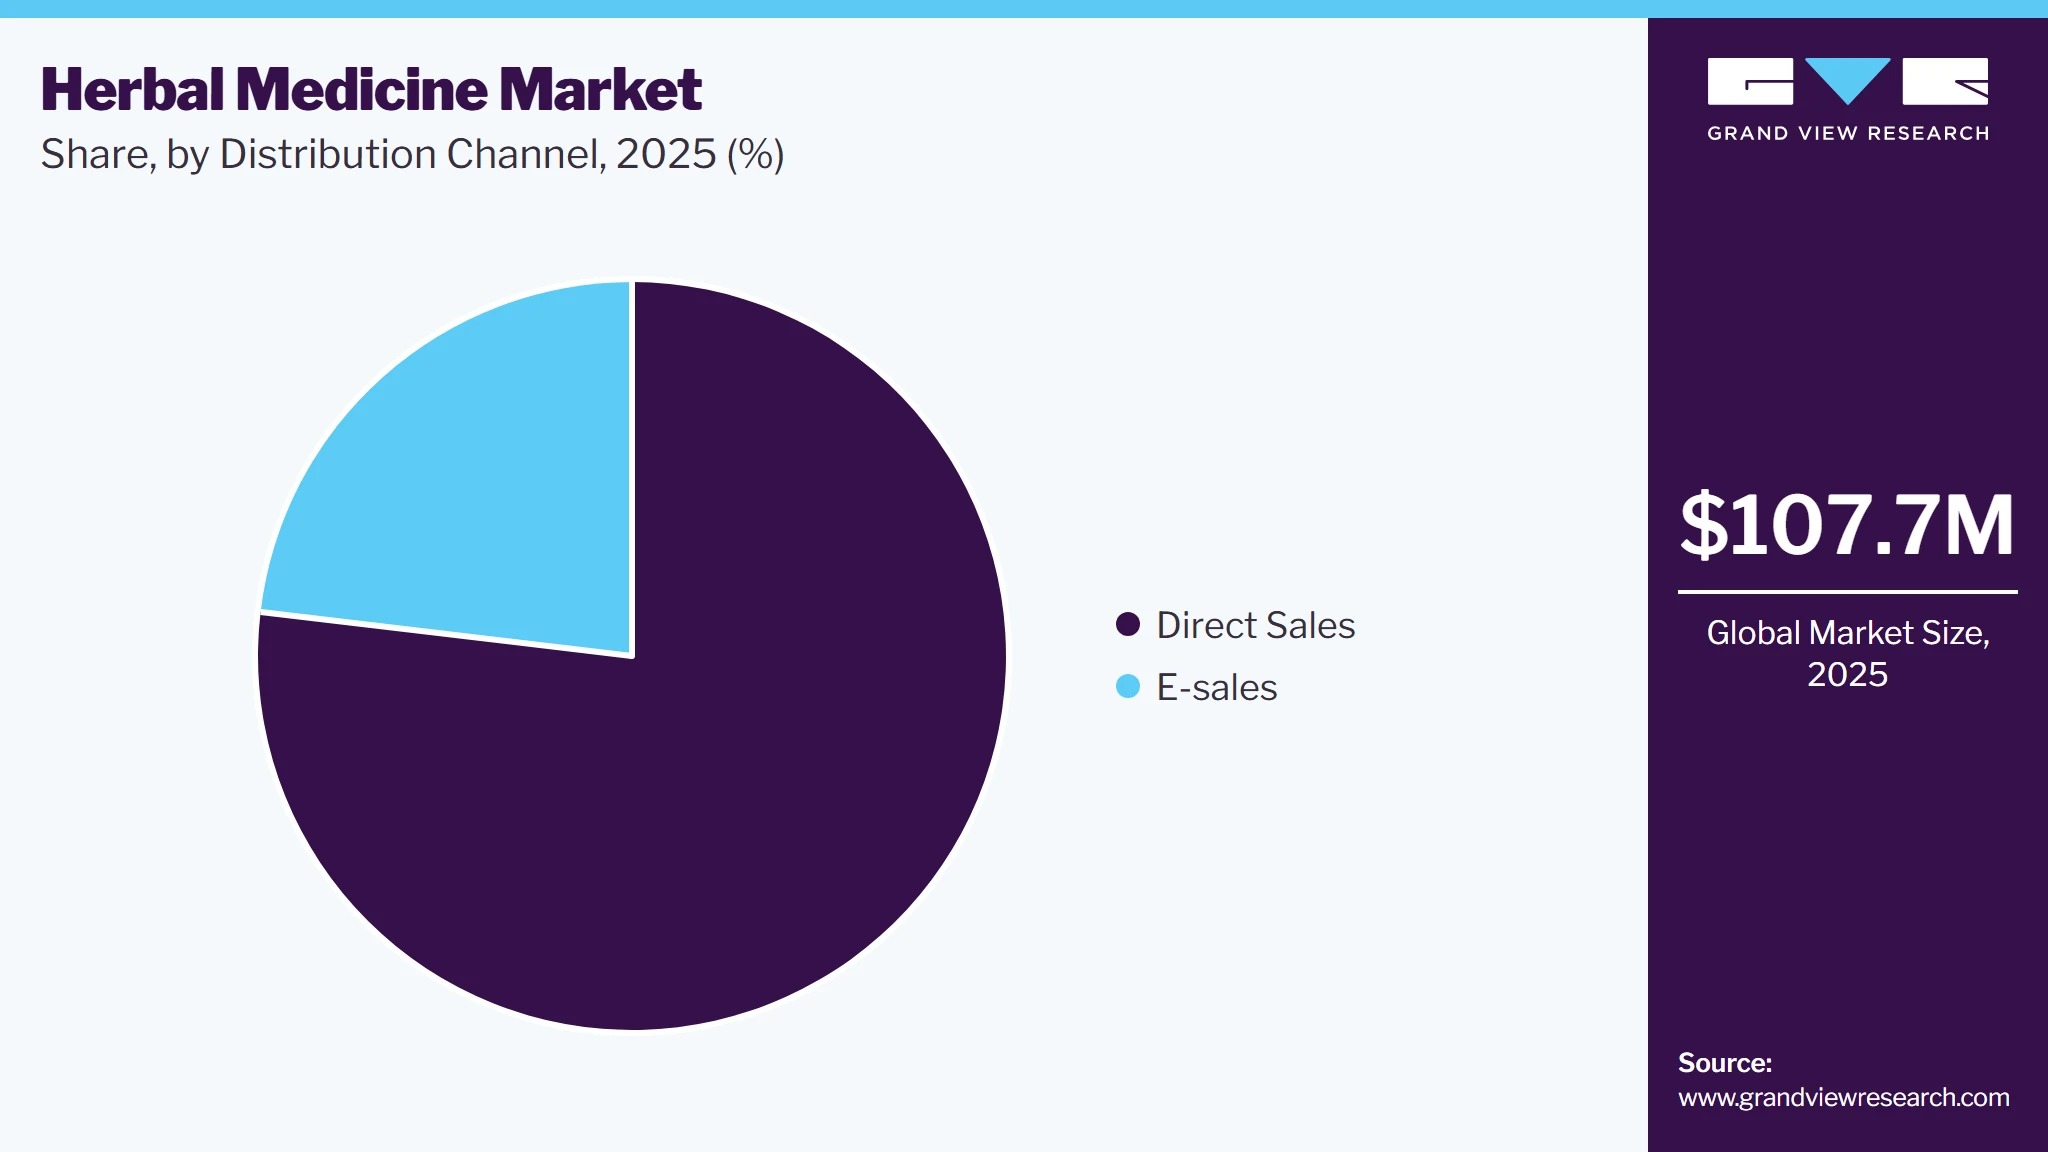
- By distribution channel: Direct sales segment held the largest share of 76.9% in 2025
Regional Highlights
- Largest regional market: North America (41.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 107.7 Billion
- Estimated market size in 2026: USD 133.5 Billion
- Projected market size by 2033: USD 630.0 Billion
- CAGR (2026-2033): 24.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Consumers are increasingly seeking plant-based solutions due to concerns over the adverse effects of synthetic drugs, aligning with a broader shift towards holistic wellness and preventive healthcare. According to the World Health Organization (WHO), 80% of the world's population which is approximately 4 billion people, use herbal medicine for some aspect of primary health care.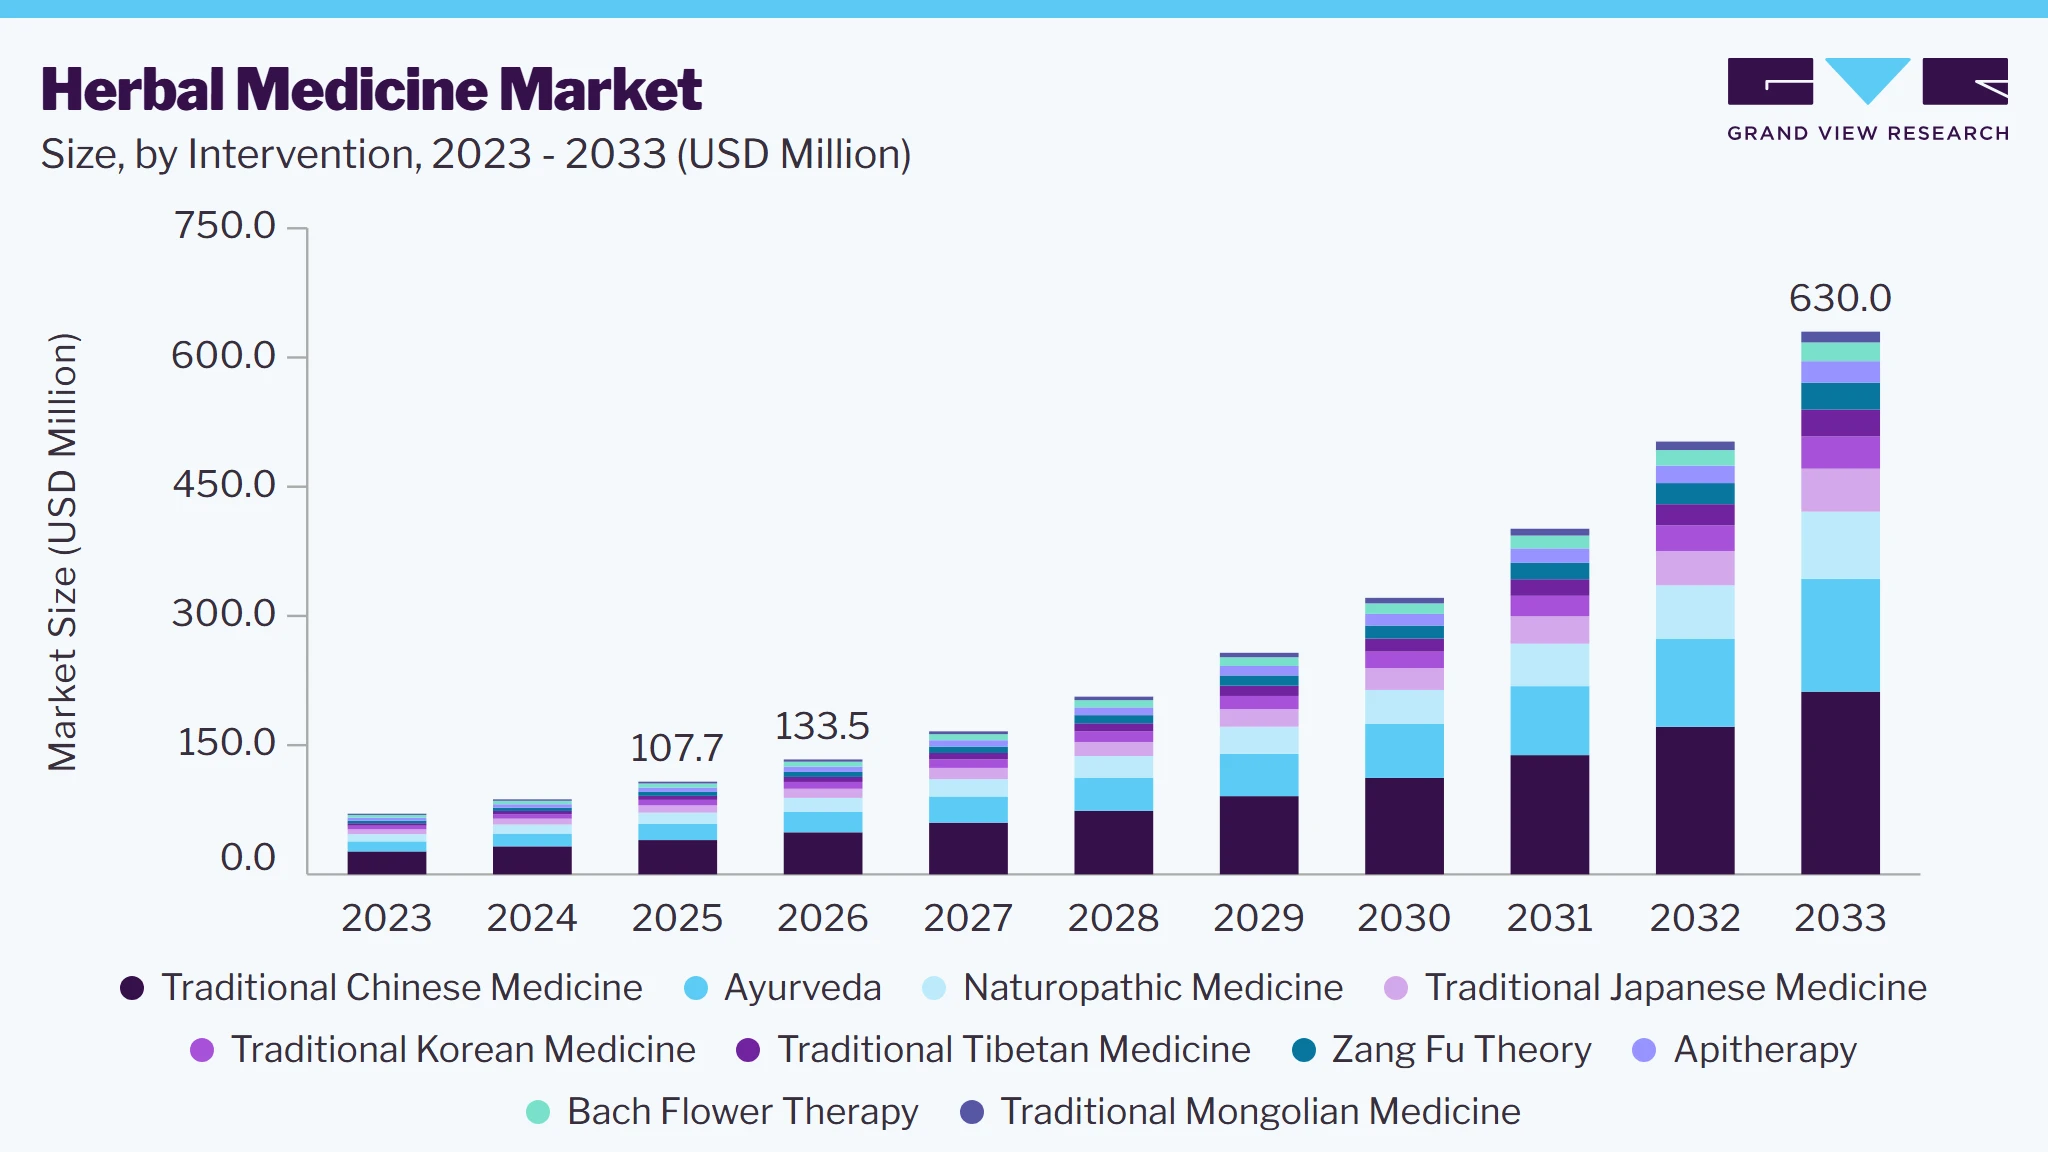 To learn more about this report, Download Free Sample Report
The rising demand for organic and ethically sourced ingredients in various products, including herbal remedies, highlights the market's growth. Traditional medicine systems like Ayurveda and Traditional Chinese Medicine (TCM) also contribute to expanding the market as their holistic approaches gain global recognition. Moreover, the trend towards personalized healthcare and wellness tourism further fuels the demand for botanicals tailored to individual needs, promising continued market expansion in the forecast period.
Herbal medicines come in various forms, from basic preparations like tinctures and extracts to more refined products such as tablets and capsules. Countries have varying regulatory frameworks for these medicines; some classify them separately, while others include them within broader categories like "natural health products" alongside vitamins and minerals. Botanicals contain active ingredients which are often unknown. Practitioners believe that using an active ingredient in isolation can lose its impact or become less safe. For instance, salicylic acid, found in meadowsweet, is used to make aspirin, which can cause stomach lining bleeding. However, meadowsweet contains other compounds to prevent irritation from salicylic acid.
Some of the herbal supplements and their uses are listed below:
Herbal Supplements And Uses
Herbal Supplements
Description
Echinacea
Used for prevention against cold and flu
Hawthorn
Used for prevention of several heart-related conditions. It is also supportive in treating high blood pressure, atherosclerosis, angina and heart failure.
St. John's Wort
Helps to treat mental disorders and recommended for mild to moderate depression.
Evening Primrose
Helpful in reducing symptoms of premenstrual syndrome and arthritis.
Feverfew
Used for migraine headaches and menstrual cramps.
The demand for herbal medicines increased due to the increasing consumer focus on preventive healthcare and immunity-boosting products during the COVID-19 pandemic. The lockdowns and social distancing measures led to a shift in consumer behavior towards natural and organic products, including Ayurveda supplements and herbal medicines. Moreover, the growing awareness about the benefits of botanicals in managing stress and anxiety levels also contributed to the market growth during COVID-19.
The advancements in extraction and formulation technologies have improved the effectiveness and consistency of herbal medicines, leading to novel dosage forms like Nano emulsions and sustained-release formulations. Analytical techniques like chromatography, spectroscopy, and DNA barcoding enable accurate identification, authentication, and quality control of herbal raw materials and finished products, preventing adulteration and ensuring product integrity. National Institutes of Health also launched HerbList, an app for research-based information about the safety and effectiveness of botanical products to help consumers navigate information about popular herbs and supplements.
Researchers increasingly explore traditional knowledge systems and ethnobotanical practices to identify new medicinal plants and bioactive compounds. This interdisciplinary approach fosters collaboration between traditional healers, scientists, and healthcare professionals to validate traditional remedies and discover novel therapeutic agents. With the growing use of these medicines alongside conventional drugs, there's a promoted focus on understanding potential herb-drug interactions. Research in this area aims to identify interactions that may affect drug metabolism, efficacy, or safety, leading to better-informed prescribing practices.
Market Dynamics
The herbal medicine market is experiencing steady growth due to increasing consumer preference for plant-based healthcare products, growing awareness of preventive health management, and wider acceptance of traditional medicine systems such as Ayurveda, Traditional Chinese Medicine, and herbal supplements. Demand is supported by the rising use of herbal products for immune health, digestive disorders, stress management, respiratory conditions, and general wellness. Manufacturers are expanding product portfolios through standardized extracts, scientifically validated formulations, and convenient dosage forms including capsules, tablets, powders, and liquid preparations. The market is also benefiting from the expansion of e-commerce platforms and broader retail availability of herbal products. Regulatory efforts focused on product quality, safety, and labeling standards are encouraging greater consumer confidence in herbal medicines. In addition, ongoing research on bioactive plant compounds and increasing investments in botanical drug development are supporting product innovation, creating opportunities for both established pharmaceutical companies and specialized herbal product manufacturers across global markets.
The herbal medicine market is primarily driven by increasing consumer preference for natural healthcare products and preventive wellness approaches. Consumers are increasingly incorporating herbal supplements, botanical extracts, and traditional medicinal products into their daily health routines to support immunity, digestive health, stress management, metabolic health, and overall well-being. Rising awareness regarding the benefits of plant-based formulations, coupled with growing interest in traditional healthcare systems such as Ayurveda, Traditional Chinese Medicine, and other botanical therapies, has expanded the adoption of herbal medicines across both developed and emerging economies. In addition, the availability of herbal products through pharmacies, health stores, supermarkets, and e-commerce platforms has improved product accessibility. Manufacturers are also focusing on introducing scientifically standardized formulations and expanding their herbal healthcare portfolios to address growing demand. For instance, in February 2025, Dabur India Ltd. expanded its healthcare portfolio through the launch of new Ayurvedic and herbal healthcare products under its health supplements portfolio, strengthening its presence in preventive healthcare and natural wellness categories. The increasing focus on self-care and preventive health management continues to support long-term market growth across multiple therapeutic and wellness categories.
A major restraint affecting the herbal medicine market is the lack of consistent product standardization and regulatory harmonization across different countries. Herbal formulations often contain multiple botanical ingredients whose active compound concentrations can vary depending on cultivation conditions, harvesting methods, geographical origin, and manufacturing processes. This variability can create challenges in maintaining consistent product quality, efficacy, and safety. In addition, regulatory requirements for herbal medicines differ significantly between regions, resulting in complex product registration and compliance processes for manufacturers operating internationally. The absence of universally accepted clinical evidence standards for many traditional herbal formulations can also limit acceptance among healthcare professionals and institutional healthcare systems. Furthermore, concerns related to adulteration, contamination, inaccurate labeling, and inconsistent ingredient quality continue to affect consumer confidence in certain markets. Although manufacturers are investing in advanced testing technologies, quality assurance systems, and standardized extraction methods, these challenges remain significant barriers to broader integration of herbal medicines into mainstream healthcare practices.
Strategic acquisitions and portfolio expansion initiatives are creating significant opportunities within the herbal medicine market. Companies are increasingly acquiring established herbal and natural health brands to strengthen their presence in preventive healthcare, dietary supplements, and botanical wellness categories. Growing consumer demand for plant-based health products has encouraged pharmaceutical, nutraceutical, and consumer healthcare companies to diversify beyond traditional offerings and establish stronger positions within the herbal medicine sector. These acquisitions provide access to established product portfolios, specialized manufacturing capabilities, distribution networks, and loyal consumer bases. For instance, in February 2025, Apotex Inc. acquired CanPrev Natural Health Products Ltd., a Canadian manufacturer of natural health, herbal, and nutritional supplements. The acquisition expanded Apotex's consumer health portfolio and strengthened its position in the herbal and wellness products segment. In addition, increasing investments in botanical research, ingredient standardization, and product development are supporting the introduction of scientifically validated herbal formulations. Expansion into adjacent categories such as herbal supplements, functional foods, natural health products, and wellness solutions is further broadening growth opportunities. As industry participants continue to strengthen their capabilities through strategic transactions, the market is benefiting from improved product availability, broader geographic reach, and increased consumer awareness of herbal healthcare products.
Market Concentration & Characteristics
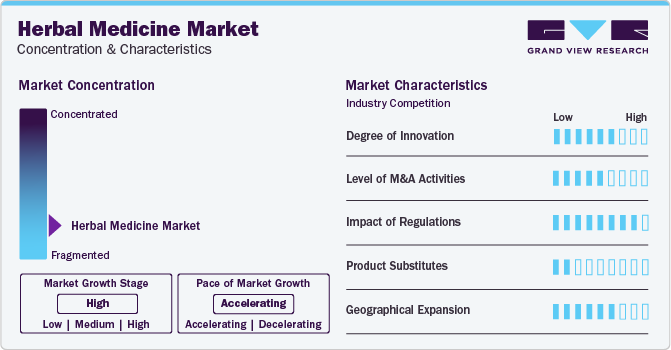
The market is undergoing significant innovation in extraction methods, formulation techniques, and product delivery systems. This has led to more efficient herbal extracts and improved potency and efficacy. Research into medicinal plant therapeutic properties and novel bioactive compounds has also led to new products with enhanced health benefits. Phytopharmaceuticals involve developing medicines with scientifically validated therapeutic properties.
 To learn more about this report, Download Free Sample Report
The market is characterized by a moderate level of merger and acquisition (M&A) activity by the leading players driven by the growing demand for natural and organic products, consolidation in the industry, and the need to expand geographical reach. The acquisition of emerging herbal medicine manufacturers by larger pharmaceutical companies enables access to new distribution channels and strengthens research and development capabilities. For instance, in November 2022, Mankind Pharma, an Indian pharmaceutical company, acquired a majority stake in Upakarma Ayurveda Private Limited, which manufactures, develops, and sells Ayurvedic and herbal products. This acquisition aims to expand Upakarma Ayurveda's range of products and services by utilizing Mankind Pharma's strong distribution network.
Regulatory frameworks govern herbal medicines' production, distribution, and marketing, ensuring consumer safety and product quality. Some countries have stringent regulations requiring botanicals to undergo rigorous testing and clinical trials to demonstrate safety and efficacy before they can be marketed to consumers. Evolving regulatory landscapes, such as the implementation of Good Manufacturing Practices (GMP) and Herbal Medicine Compendium (HMC), aim to standardize quality control measures and enhance consumer confidence in herbal medicines. In Europe, European Herbal and Traditional Medicine Practitioners Association (EHTPA), British Herbal Medicine Association (BHMA) and the Medicine and Healthcare products Regulatory Agency (MHRA) develop and regulate set of practice and training standards for herbal medicine.
Herbal medicines might face competition from alternative treatment modalities, including conventional pharmaceutical drugs and dietary supplements. In some cases, consumers may opt for synthetic drugs over botanicals due to perceived efficacy, convenience, or physician recommendations. Growing consumer interest in preventive healthcare and natural remedies drives demand for herbal medicines as substitutes for synthetic drugs, particularly in the treatment of chronic conditions and lifestyle-related diseases.
Regional expansion plays a significant role in shaping the competitive landscape of the global market, allowing companies to expand their product portfolios, enter new markets, and achieve economies of scale. Companies are establishing partnerships or distribution agreements with local firms to penetrate new markets and adapt products to meet regional preferences and regulatory requirements. Increasing globalization and cross-border trade facilitate the expansion of herbal medicine manufacturers into new territories, focusing on regions experiencing demographic shifts, rising disposable incomes, and growing awareness of natural healthcare solutions.
Analyst Perspective
The herbal medicine market is evolving from a traditionally fragmented industry into a more structured and commercially organized healthcare segment, supported by increasing consumer preference for plant-based products, growing acceptance of traditional medicine systems, and improvements in product standardization. The market is increasingly centered around companies with established expertise in botanical formulations, raw material sourcing, and regulatory compliance. Bionorica SE and Pascoe Natural Medicine continue to strengthen their positions through scientifically supported herbal products, while LKK Health Products Group Limited and Sheng Chang Pharmaceutical Company leverage strong traditional medicine portfolios and regional market presence. Meanwhile, emerging participants are expanding opportunities through specialized formulations, personalized wellness solutions, and direct-to-consumer distribution channels.
Intervention Insights
Based on intervention, the traditional chinese medicine segment led the market with the largest revenue share of 37.0% in 2025. This growth is driven by increased awareness and adoption of Ayurveda and growing consumer demand for natural and holistic healthcare solutions. The market is leveraging technology to improve product quality, increase efficiency, and enhance the consumer experience. For instance, the Indian government launched a digital platform called the Ayurveda Health and Wellness Centre to provide telemedicine and e-consultation services to patients. Companies in the market are forming partnerships and collaborations to expand their reach and capabilities. For instance, Dabur India Ltd. joined Amazon to sell its Ayurvedic products online. This partnership enabled Dabur to reach a broader consumer base and leverage Amazon's logistics and distribution network.
The apitherapy segment is anticipated to grow at a significant CAGR over the forecast period, due to the broader acceptance among the medical community owing to the growing scientific evidence supporting the therapeutic benefits of honeybee products. Apitherapy uses products derived from honeybees, such as honey, bee venom, and beeswax, for medical purposes and has been growing in popularity as people seek natural and alternative therapies for various health concerns. The apitherapy market is leveraging technology to improve product quality, safety, and efficacy. For instance, a Canadian company called Apiterra uses artificial intelligence and machine learning to identify the most effective strains of honeybees for producing high-quality honey and other bee products.
As the apitherapy market grows, there has been increased regulatory scrutiny to ensure the safety and efficacy of honeybee products. For instance, the U.S. FDA issued warning letters to companies that make unsubstantiated claims about the health benefits of their apitherapy products. In July 2022, the FDA issued warning letters to four companies, Shopaax.com, MKS Enterprise LLC, Thirstyrun LLC (also known as US Royal Honey LLC), and 1 am USA Incorporated dba Pleasure Products USA, for illegally selling honey-based products that may cause a health risk to consumers.
Product Form Insights
Based on product form, the tablets/capsules segment led the market with the largest revenue share of 41.6% in 2025. The increasing preference for convenient dosage forms among consumers played a pivotal role in driving the demand for tablets and capsules. These forms offer ease of consumption, precise dosing, and portability, catering to the busy lifestyles of modern consumers. In addition, advancements in formulation technologies have enhanced the efficacy, stability, and bioavailability of herbal ingredients in tablet and capsule formulations, bolstering their acceptance among health-conscious individuals.
The powder form segment is expected to grow with the significant CAGR during the forecast period, due to its versatility and ease of consumption. Powdered forms offer flexibility in dosage, allowing consumers to customize their intake based on individual needs and preferences. Moreover, powdered products often boast higher bioavailability than other dosage forms, leading to faster absorption and potentially enhanced efficacy. This factor has attracted health-conscious consumers seeking efficient and potent natural remedies. In addition, the growing trend towards DIY healthcare and home remedies has spurred the demand for powdered herbs, empowering individuals to create personalized formulations for various health concerns.
Source Insights
Based on source, the roots segment led the market with the largest revenue share of 38.0% in 2025, owing to their traditional use in herbal remedies and various formulations. In addition, the increasing scientific validation of the pharmacological benefits of multiple root extracts has bolstered their appeal among modern consumers seeking evidence-based natural remedies. Research studies highlighting the anti-inflammatory, antioxidant, immune-modulating, and adaptogenic properties of root-derived compounds have further propelled their utilization in herbal medicine formulations, catering to various health concerns. The growing trend towards sustainable and ethically sourced ingredients has heightened interest in wildcrafted and organically cultivated roots, ensuring quality, purity, and environmental responsibility throughout the supply chain. Furthermore, the expanding availability of roots-based products through traditional and online retail channels has facilitated consumer access and market penetration, driving robust growth within the segment.
The leaves segment is expected to grow at the fastest CAGR during the forecast period. The widespread recognition of leaves' therapeutic properties, including antioxidant, anti-inflammatory, and detoxifying effects, has fueled their increasing utilization in herbal remedies. Leaves offer a rich source of bioactive compounds such as polyphenols, flavonoids, and essential oils, contributing to their appeal among health-conscious consumers seeking natural alternatives. The versatility of leaves allows for diverse applications in herbal formulations, including teas, extracts, tinctures, and topical preparations, catering to a broad spectrum of health needs. Furthermore, growing consumer awareness of the benefits of plant-based diets and holistic wellness practices has spurred demand for leaves-based herbal products, driving market expansion.
Distribution Channel Insights
Based on distribution Channel, the direct sales segment led the market with the largest revenue share of 76.9% in 2025. The increased awareness about the benefits of herbal medicines has led to a surge in demand, effectively catered by companies using direct sales channels. Direct sales channels enable companies to offer personalized recommendations and customized products based on individual consumer needs. This level of customization enhances the overall consumer experience and drives higher sales through direct channels.
 To learn more about this report, Download Free Sample Report
The e-sales segment is expected to grow at the fastest CAGR during the forecast period. The integration of technology in the herbal medicine sector has made it easier for consumers to access information about the herb and product, contributing to the market growth of the e-sales segment in the global market. This is strongly supported by many factors, such as increasing investments in the improvement of internet connectivity, rising adoption of mobile devices, and awareness created through social media. E-commerce platforms have played a significant role in expanding their reach globally. For instance, in February 2022, Amazon India announced a dedicated storefront on its marketplace solely focused on herb-based Ayurvedic medicines and supplements. This storefront aims to increase the visibility of Ayurveda products, which include a wide range of immunity boosters, oils, and other supplements from small businesses and D2C brands.
Regional Insights
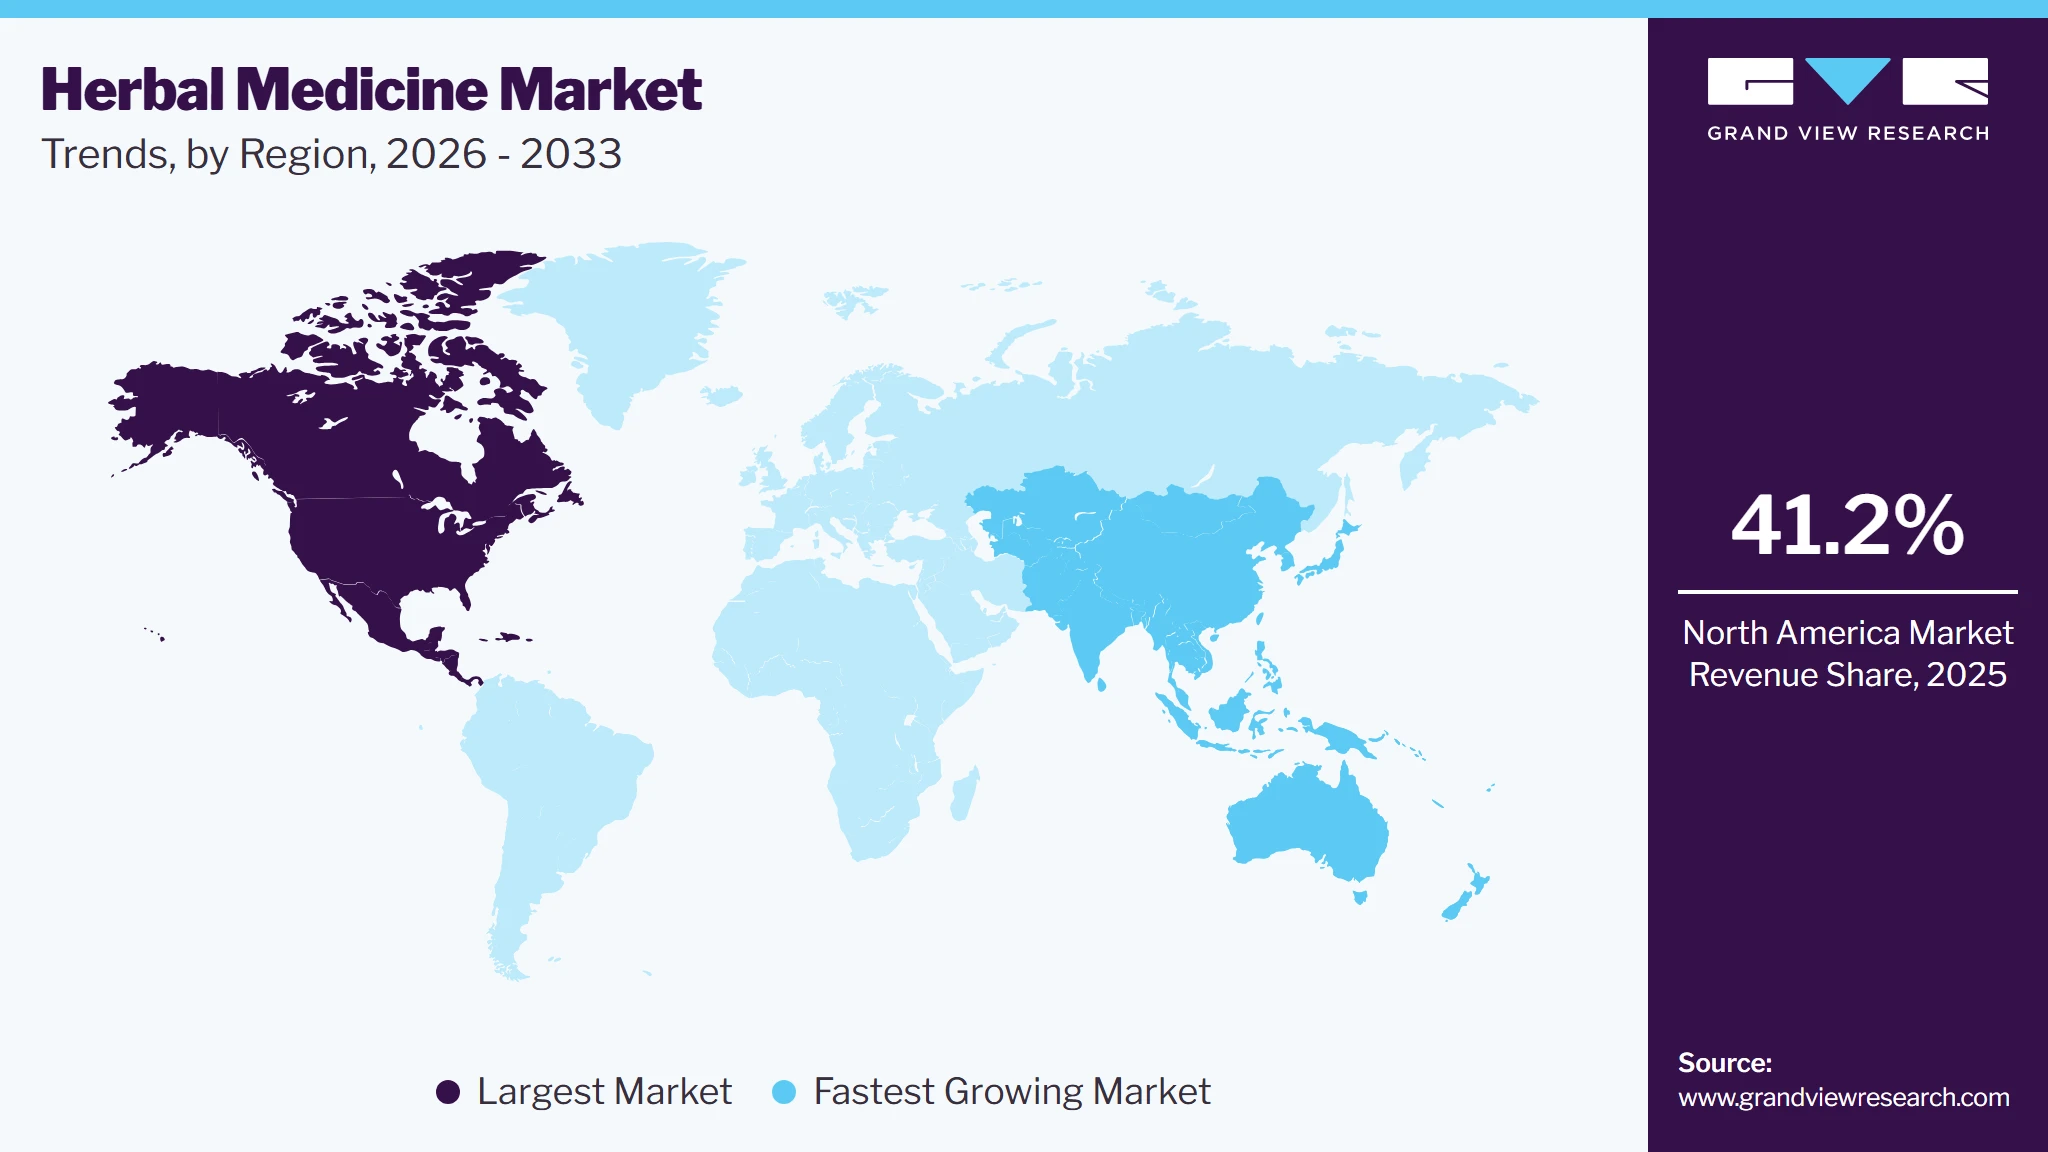
North America dominated the herbal medicine market with the largest revenue share of 41.2% in 2025. The herbal medicine market in North America is experiencing steady growth, driven by factors such as increasing consumer awareness regarding natural remedies, a rising preference for preventive healthcare, and a growing demand for organic products. The expansion of product offerings by major players, a focus on research and development for novel formulations, and the integration of herbal supplements into mainstream healthcare is driving the market growth.
 To learn more about this report, Download Free Sample Report
U.S. Herbal Medicine Market Trends
The herbal medicine market in the U.S. held the largest share in the North America region in 2025. The herbal medicine market in the U.S. is expected to grow at the fastest CAGR over the forecast period, due to the growing health consciousness, rising healthcare costs, and a favorable regulatory environment for herbal supplements. For instance, the Herbal Medicines Compendium (HMC) is an online resource by the U.S. Pharmacopeial Convention provides standards for herbal ingredients used in medicines. It is primarily expressed in monographs, which contain general information, definitions, and specifications for critical quality attributes.
Europe Herbal Medicine Market Trends
Europe held the second largest revenue share of 35.7% in 2025. This growth is influenced by rising geriatric population, increasing prevalence of chronic diseases, and a growing preference for plant-based therapies. The adoption of traditional remedies, integration of herbs into mainstream healthcare, and emphasis on quality assurance and safety standards with a long history of herbal traditions, Europe represents a mature yet evolving market, characterized by moderate growth and a diverse array of products. In Europe, herbal remedies fall into three categories. The most rigorously controlled are prescription drugs, which include injectable forms of phytomedicines and those used to treat life-threatening diseases. The second category is OTC phytomedicines, similar to American OTC drugs. The third category is traditional herbal remedies, products that typically have not undergone extensive clinical testing but are judged safe on the basis of generations of use without serious incident.
The herbal medicine market in the UK is driven by increasing awareness of the benefits of herbal remedies, and rising consumer preference for sustainable products. The growing popularity of herbal teas and supplements, emergence of boutique brands, and integration of herbs into functional foods and beverages is driving the market growth. Despite regulatory challenges, the UK herbal medicine market continues to grow as consumers seek natural alternatives for their healthcare needs.
The France herbal medicine market has a strong cultural affinity and the increasing adoption of preventive healthcare and a growing demand for premium herbal products are driving the market growth. In France, traditional medicines can be sold with labeling based on traditional use, which requires licensing by the French Licensing Committee and approval by the French Pharmacopoeia Committee.
The herbal medicine market in Germany is fueled by high healthcare expenditure, an aging population, and a growing interest in alternative medicine. The expansion of pharmacies, the popularity of standardized herbal extracts, and the increasing use of herbal supplements for immune support are driving the market growth for herbal medicines. With a robust regulatory framework and widespread acceptance of natural therapies, Germany remains a leading European market.
Asia Pacific Herbal Medicine Market Trends
The herbal medicine market in Asia Pacific is characterized by rapid growth and is expected to grow at the fastest CAGR during the forecast period, driven by factors such as a long history of traditional medicine, increasing consumer awareness of natural remedies, and rising healthcare costs. Traditional herbal practices deeply rooted in countries like India, China, and Japan contribute to the market's growth. The growing acceptance of supplements, expansion of distribution channels, and government initiatives promoting traditional medicine is driving the market growth. With a diverse range of botanical remedies and a large consumer base, the Asia Pacific region is a significant contributor to the global market.
The India herbal medicine market is experiencing robust growth, propelled by factors such as a rich tradition of Ayurveda, increasing demand for natural and organic products, and government support for traditional medicine systems. For instance, in March 2022, an agreement was signed by the Government of India and the World Health Organization (WHO) to launch the WHO Global Centre for Traditional Medicine. This center aims to use technology and modern science to mobilize the potential of traditional medicine from around the world to improve people’s health. The Government of India has invested USD 250 million to support the establishment of this global knowledge center for traditional medicine.
The herbal medicine market in China is expected to grow at the fastest CAGR over the forecast period, due to factors such as a long history of traditional Chinese medicine (TCM), government initiatives promoting herbal remedies, and increasing consumer demand for natural healthcare solutions. The growing acceptance of TCM globally, expansion of product exports, and investment in research and development for herbal formulations. With a deep-rooted tradition and a large domestic market, China continues to lead the way in the herbal medicine industry.
The Japan herbal medicine market is expected to grow at the substantial CAGR over the forecast period. The integration of traditional Japanese herbal practices into modern medicine, expansion of product offerings, and government support for research and development is expected to drive the market growth. With a strong focus on quality and safety, Japan's market offers opportunities for growth and innovation.
Latin America Herbal Medicine Market Trends
The herbal medicine market in Latin America is characterized by factors such as a rich tradition of indigenous medicine, increasing consumer awareness of natural remedies, and growing demand for plant-based therapies. The popularity of herbal remedies in traditional healing practices, expansion of product availability, and government initiatives promoting the use of medicinal plants is driving the market growth. The National Health Surveillance Agency (ANVISA) in Brazil regulates herbal medicines under the heading of "phytotherapeutic medicines". Herbal remedies in Mexico are governed by the Federal Commission for Protection against Sanitary/Health Risk (COFEPRIS), which classifies them as "natural products". In Argentina, the National Administration of Drugs, Food, and Medical Devices (ANMAT) regulates herbal medicines under the heading of "medicinal plants".
The Brazil herbal medicine market is one of the largest market for healthcare in the Latin America region and is driven by various government initiatives, medical tourism, and high cost of conventional medicine. In April 2024, the Brazilian Health Regulatory Agency announced a public notice of selecting startups involved in R&D in order to provide regulatory support.
MEA Herbal Medicine Market Trends
The herbal medicine market in Middle East & Africa is expected to grow at a significant CAGR over the forecast period, due to growing interest in traditional healing practices, rising healthcare costs, and increasing consumer awareness of natural remedies. With a rich heritage of herbal remedies and a growing market for natural healthcare solutions, the MEA region offers opportunities for growth and development in the herbal medicine industry.According to the World Health Organization (WHO), more than 80% of the African population, relies on traditional medicine for its medical requirements. Due to its accessibility, perceived low toxicity, and low cost, traditional medicine has continued to gain acceptance throughout Africa.
The Saudi Arabia herbal medicine market is expected to at a significant CAGR over the forecast period. With a population increasingly inclined towards holistic wellness, the demand for herbal remedies has seen a notable rise in the country. According to the study published by the National Library of Medicines, in Saudi Arabia, traditional medicine is frequently relied upon for treating conditions like hypertension, diabetes, infertility, and osteoporotic fractures. Local communities in the Saudi Arabia utilize over 25 plants for addressing different health issues, with herbal remedies being especially popular among women. Studies have shown that traditional medicine is widely embraced, with a reported usage rate as high as 69.9% among the population.
Key Herbal Medicine Company Insights
In the competitive landscape of the global market, several leading players for market dominance. Key players such as Sheng Chang Pharmaceutical Company, Nordic Nutraceuticals, AYUSH Ayurvedic Pte Ltd. and Bionorica SE employ a range of strategies to maintain their competitive edge. These strategies include continuous investment in new product development, securing patent protection for their innovations, obtaining regulatory approvals, and fostering collaborations and partnerships to expand their market reach and enhance product offerings.
There are notable competitors in the market such as KindCare Medical Center, Sinomedica, Herb Pharm, and LKK Health Products Group Limited. These emerging players employ diverse strategies to bolster their presence in the market. Strategies such as a relentless focus on innovation to differentiate their products, expanding their geographic footprint to tap into new markets, and forging strategic partnerships to leverage complementary strengths help these companies in achieving their growth objectives. As competition intensifies, the ability to innovate, adapt to evolving regulatory landscapes, and forge strategic alliances will be pivotal for both established and emerging players to maintain and expand their market share in the dynamic landscape of Herbal Medicine
Key Herbal Medicine Companies
The following key companies have been profiled for this study on the herbal medicine market.
-
Sheng Chang Pharmaceutical Company
-
Nordic Nutraceuticals (now a part of Oy Verman Ab)
-
AYUSH Ayurvedic Pte Ltd.
-
Herbal Hills
-
Herb Pharm
-
LKK Health Products Group Limited
-
International Chinese Body Care Houses
-
KindCare Medical Center
-
Pascoe Natural Medicine
-
Bionorica SE
-
Ming Chen Clinic
-
The Center for Natural and Integrative Medicine
-
Sinomedica
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Bionorica SE, Pascoe Natural Medicine, LKK Health Products Group Limited, Sheng Chang Pharmaceutical Company, Sinomedica)
- Focus on expanding herbal medicine portfolios through standardized botanical formulations, clinical research, traditional medicine integration, and international market expansion.
- Strengthen relationships with healthcare practitioners, traditional medicine providers, pharmacies, and wellness centers through educational initiatives and evidence-based product development.
- Strong brand recognition within herbal and traditional medicine markets.
- Established manufacturing infrastructure, extensive product portfolios, regulatory expertise, and broad distribution networks across multiple countries.
- Long operating histories support customer trust and practitioner acceptance.
- Higher operating costs associated with quality assurance, regulatory compliance, clinical validation, and global distribution.
- Large organizational structures may reduce flexibility in responding to rapidly changing consumer preferences and emerging herbal health trends.
Emerging Players (Herb Pharm, AYUSH Ayurvedic Pvt. Ltd., Herbal Hills, Nordic Nutraceuticals (part of Oy Verman Ab), International Chinese Body Care Houses, KindCare Medical Center, Ming Chen Clinic, The Center for Natural & Integrative Medicine)
- Focus on specialized herbal therapies, Ayurveda-based products, practitioner-led treatment models, personalized wellness programs, and direct-to-consumer sales channels.
- Emphasize product differentiation through organic ingredients, traditional formulations, niche therapeutic applications, and digital marketing strategies.
- Ability to rapidly introduce targeted herbal products addressing specific health conditions and wellness needs.
- Strong focus on personalized care, specialized treatment approaches, ingredient transparency, and consumer engagement.
- Greater flexibility in adopting emerging herbal health trends and alternative medicine practices.
- Limited financial resources and smaller research budgets compared with established herbal medicine companies.
- Restricted manufacturing scale, lower brand visibility, and narrower distribution networks may constrain geographic expansion and access to larger healthcare and retail channels.
Recent Developments
-
In April 2024, Mitsui & Co., Ltd. announced that it will acquire 100% shares in Eu Yan Sang International Ltd, a Singapore-based company that manufactures and sells traditional Chinese medicines. The shares will be valued at around 88 billion yen
-
In March 2024, the Federal Government unveiled 4 herbal products developed by the Nigeria Natural Medicine Development Agency (NNMDA) for the management of sickle cell disease, diabetes, reducing fast ageing and treatment of upper respiratory tract infections
-
In January 2024, the National Integrated Research Program on Medicinal Plants (NIRPROMP) announced the preparation to introduce three additional herbal medicines to the market. Yerba Buena, Ulasimang Bato, and Akapulko, initially among the ten herbal medicines endorsed by the Department of Health (DOH), are poised for launch
-
In February 2023, FXB Rwanda and National Industrial Research and Development Agency (NIRDA) initiated the Phyto social enterprise (POSE) project, aiming to boost the production of herb based medicines and goods for regional and local consumption
Herbal Medicine Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 107.7 billion
Market size value in 2026
USD 133.5 billion
Revenue forecast in 2033
USD 630.0 billion
Growth rate
CAGR of 24.8% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Intervention, product form, source, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Sheng Chang Pharmaceutical Company; Nordic Nutraceuticals (now a part of Oy Verman Ab); Herb Pharm; AYUSH Ayurvedic Pvt. Ltd.; Herbal Hills; LKK Health Products Group Limited; International Chinese Body Care Houses; KindCare Medical Center; Pascoe Natural Medicine; Bionorica SE; Ming Chen Clinic; The Center for Natural; Integrative Medicine, Sinomedica
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Herbal Medicine Market Report Segmentation
This report forecasts revenue growth at, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the herbal medicine market report based on intervention, product form, source, distribution channel and region:
-
Intervention Outlook (Revenue, USD Million, 2021 - 2033)
-
Ayurveda
-
Apitherapy
-
Bach Flower Therapy
-
Naturopathic Medicine
-
Traditional Chinese Medicine
-
Traditional Korean Medicine
-
Traditional Japanese Medicine
-
Traditional Mongolian Medicine
-
Traditional Tibetan Medicine
-
Zang Fu Theory
-
-
Product Form Outlook (Revenue, USD Million, 2021 - 2033)
-
Powder
-
Liquid/Gel
-
Tablets/Capsules
-
Others
-
-
Source Outlook (Revenue, USD Million, 2021 - 2033)
-
Barks
-
Leaves
-
Roots
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Direct Sales
-
E-sales
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Sweden
-
Denmark
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
South Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The herbal medicine market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each herbal medicine segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Intervention
Revenue capture definition
Ayurveda
Herbal medicinal products formulated according to Ayurvedic principles using plant-derived ingredients, herbal extracts, and traditional preparations intended to maintain health, prevent disease, or manage specific health conditions.
Apitherapy
Herbal medicine products that utilize bee-derived substances such as honey, propolis, royal jelly, bee pollen, or bee venom as the primary therapeutic component for health maintenance or disease management.
Bach Flower Therapy
Herbal remedies prepared from flower essences following the Bach Flower methodology and intended to support emotional, psychological, and behavioral well-being.
Naturopathic Medicine
Herbal medicinal products prescribed or recommended within naturopathic healthcare systems and based on Western botanical medicine principles, excluding formulations classified under Ayurveda, Traditional Chinese Medicine, Traditional Korean Medicine, Traditional Japanese Medicine, Traditional Mongolian Medicine, and Traditional Tibetan Medicine.
Traditional Chinese Medicine
Herbal formulations based on Traditional Chinese Medicine principles that utilize single herbs or multi-herb combinations to restore physiological balance and manage health conditions.
Traditional Korean Medicine
Herbal medicinal products developed according to Traditional Korean Medicine principles and composed of botanical ingredients used to maintain health or address specific medical conditions.
Traditional Japanese Medicine
Standardized herbal formulations prepared according to Kampo medicine practices and consisting of defined combinations of medicinal plants used for therapeutic applications.
Traditional Mongolian Medicine
Herbal products formulated according to Traditional Mongolian Medicine principles using medicinal plants and natural substances intended for preventive and therapeutic healthcare applications.
Traditional Tibetan Medicine
Herbal medicinal formulations based on Traditional Tibetan Medicine practices that utilize botanical ingredients and traditional preparation methods for disease management and health maintenance.
Zang Fu Theory
Herbal formulations specifically categorized according to the Zang Fu organ-based diagnostic framework within Traditional Chinese Medicine, where product selection is determined by organ function patterns and corresponding herbal treatment principles.
Segment - Product
Revenue capture definition
Powder
Herbal medicinal products supplied in dry powdered form for oral consumption, reconstitution, mixing with food or beverages, or preparation into traditional remedies.
Liquid/Gel
Herbal medicines formulated as liquids, syrups, tinctures, suspensions, extracts, gels, or semi-solid preparations intended for oral, topical, or localized administration.
Tablets/Capsules
Herbal medicinal products manufactured as compressed tablets, coated tablets, softgels, hard capsules, or other unit-dose solid oral dosage forms.
Others
Herbal medicine dosage forms not classified as powders, liquids/gels, or tablets/capsules, including lozenges, granules, sprays, medicated patches, suppositories, and similar formulations.
Segment - Source
Revenue capture definition
Barks
Herbal medicinal products in which the primary active botanical ingredient is derived from the bark of medicinal trees or woody plants.
Leaves
Herbal medicinal products in which the principal therapeutic ingredient is obtained from the leaves of medicinal plants, shrubs, or trees.
Roots
Herbal medicinal products in which the primary medicinal component is extracted or prepared from plant roots, rhizomes, tubers, or underground stems.
Others
Herbal medicinal products derived primarily from botanical sources other than bark, leaves, or roots, including flowers, fruits, seeds, stems, rhizomes, bulbs, resins, algae, fungi, and whole-plant materials.
Segment - Distribution Channel
Revenue capture definition
Direct Sales
Herbal medicinal products distributed through physical channels directly to end users, including manufacturer-owned outlets, practitioner clinics, wellness centers, pharmacies, specialty stores, and authorized distributors.
E-sales
Herbal medicinal products purchased through digital commerce channels, including company websites, online pharmacies, e-commerce marketplaces, mobile applications, and other internet-based sales platforms.
Estimation Model
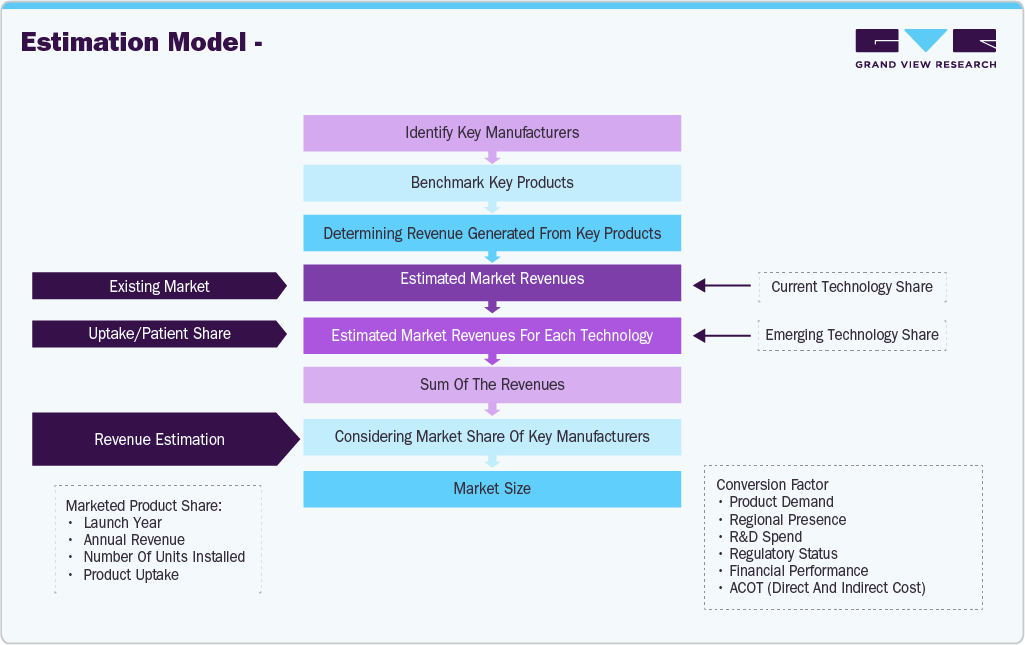
The herbal medicine market was estimated using a commodity flow and revenue-based market analysis approach. The methodology began with the identification of major manufacturers, traditional medicine producers, herbal supplement companies, and botanical product suppliers operating across global markets. Key product categories including Ayurvedic medicines, Traditional Chinese Medicine formulations, herbal supplements, botanical extracts, apitherapy products, and other traditional herbal preparations were benchmarked. Production capacities, product portfolios, manufacturing footprints, raw material sourcing practices, and distribution networks were evaluated to establish the overall market supply. Market revenues were estimated using company disclosures, annual reports, trade statistics, industry publications, government databases, and primary interviews with manufacturers, distributors, and herbal medicine practitioners. Revenue contributions were mapped across intervention types, product forms, source categories, and distribution channels to derive segment-level estimates.
 To learn more about this report, Download Free Sample Report
Market estimates were further validated through an assessment of downstream demand across healthcare, preventive wellness, dietary supplements, personal care, and traditional medicine applications. Consumption patterns were analyzed using herbal product utilization rates, retail sales data, traditional medicine adoption trends, e-commerce sales activity, and practitioner-based dispensing practices across key regions. Data triangulation was performed by comparing manufacturer revenues, product availability, trade flow analysis, distribution channel performance, and end-use consumption trends to ensure consistency across market calculations. Forecast projections incorporated growing consumer preference for plant-based healthcare products, increasing adoption of traditional medicine systems, expansion of herbal product portfolios, rising investment in botanical research, and wider availability of herbal medicines through retail and digital sales channels.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Herbal Medicine Competitive Landscape & Product Portfolio Assessment
Conducted a targeted assessment of the global herbal medicine market, evaluating leading manufacturers, traditional medicine providers, botanical product portfolios, distribution strategies, therapeutic focus areas, and regional market positioning. The study analyzed key participants including Bionorica SE, Pascoe Natural Medicine, LKK Health Products Group Limited, Sheng Chang Pharmaceutical Company, Herb Pharm, and AYUSH Ayurvedic Pvt. Ltd., along with emerging trends across Ayurveda, Traditional Chinese Medicine, naturopathic medicine, and botanical wellness products.
Helped the client identify high-growth therapeutic categories, evaluate competitive positioning, benchmark product differentiation strategies, and assess expansion opportunities across traditional medicine and plant-based healthcare segments.
Herbal Medicine Product Benchmarking & Innovation Assessment
Delivered a comprehensive benchmarking analysis of herbal medicine products, focusing on formulation types, botanical ingredient profiles, dosage forms, scientific validation, manufacturing standards, and practitioner adoption. The assessment compared established herbal product portfolios with emerging botanical innovations, evaluating product differentiation, quality assurance practices, regulatory positioning, and consumer preference trends across major markets.
Enabled the client to assess product competitiveness, identify innovation gaps, benchmark formulation strategies, and prioritize investments in scientifically supported herbal products and emerging botanical healthcare categories.
Herbal Medicine Manufacturing & Supply Chain Feasibility Assessment
Conducted a strategic assessment of the herbal medicine manufacturing ecosystem, evaluating raw material sourcing, cultivation networks, botanical ingredient supply chains, extraction technologies, production capabilities, quality control systems, and regulatory compliance requirements. The study analyzed manufacturing bottlenecks, supplier reliability, regional production hubs, and distribution infrastructure supporting commercial-scale herbal medicine production.
Supported strategic manufacturing planning by identifying qualified sourcing partners, assessing supply chain risks, evaluating production scalability, and strengthening long-term procurement and distribution strategies across global herbal medicine markets.
Frequently Asked Questions About This Report
The global herbal medicine market size was valued at USD 107.7 billion in 2025 and is estimated at USD 133.5 billion for 2026.
The global herbal medicine market is expected to grow at a CAGR of 24.8% from 2026 to 2033, reaching USD 630.0 billion by 2033.
Market growth is majorly due to rising health consciousness, increasing consumer preference for natural remedies, and technological advancements in the extraction and formulation of herbal medicines.
The traditional chinese medicine segment led with a 37.0% revenue share in 2025.
The tablets/capsules segment led with a 41.6% revenue share in 2025.
The roots segment led with a 38.0% revenue share in 2025, while the leaves segment is the fastest-growing.
North America dominated with a 41.2% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Key players include Key players includes Sheng Chang Pharmaceutical Company; Nordic Nutraceuticals (now a part of Oy Verman Ab); Herb Pharm; AYUSH Ayurvedic Pvt. Ltd.; Herbal Hills; LKK Health Products Group Limited; International Chinese Body Care Houses; KindCare Medical Center; Pascoe Natural Medicine; Bionorica SE; Ming Chen Clinic; The Center for Natural; Integrative Medicine, Sinomedica.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


