
- Home
- »
- Electronic & Electrical
- »
-
Home Appliances Market Size & Share Report, 2026-2033GVR Report cover

Home Appliances Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Major Appliances, Small Appliances), By Distribution Channel (Hypermarkets & Supermarkets, Electronic Stores, Online), By Region, And Segment Forecasts
Market Size, 2025
$523.6BMarket Estimate, 2026
$546.9BMarket Forecast, 2033
$788.6BCAGR, 2026–2033
5.4%Home Appliances Market Summary
The global home appliances market size was valued at USD 523.6 billion in 2025 and is projected to grow from USD 546.9 billion in 2026 to USD 788.6 billion by 2033, at a CAGR of 5.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 45.1% in 2025. The industry is experiencing significant growth, driven by factors such as rising disposable incomes, urbanization, a focus on convenience, and technological advancements.
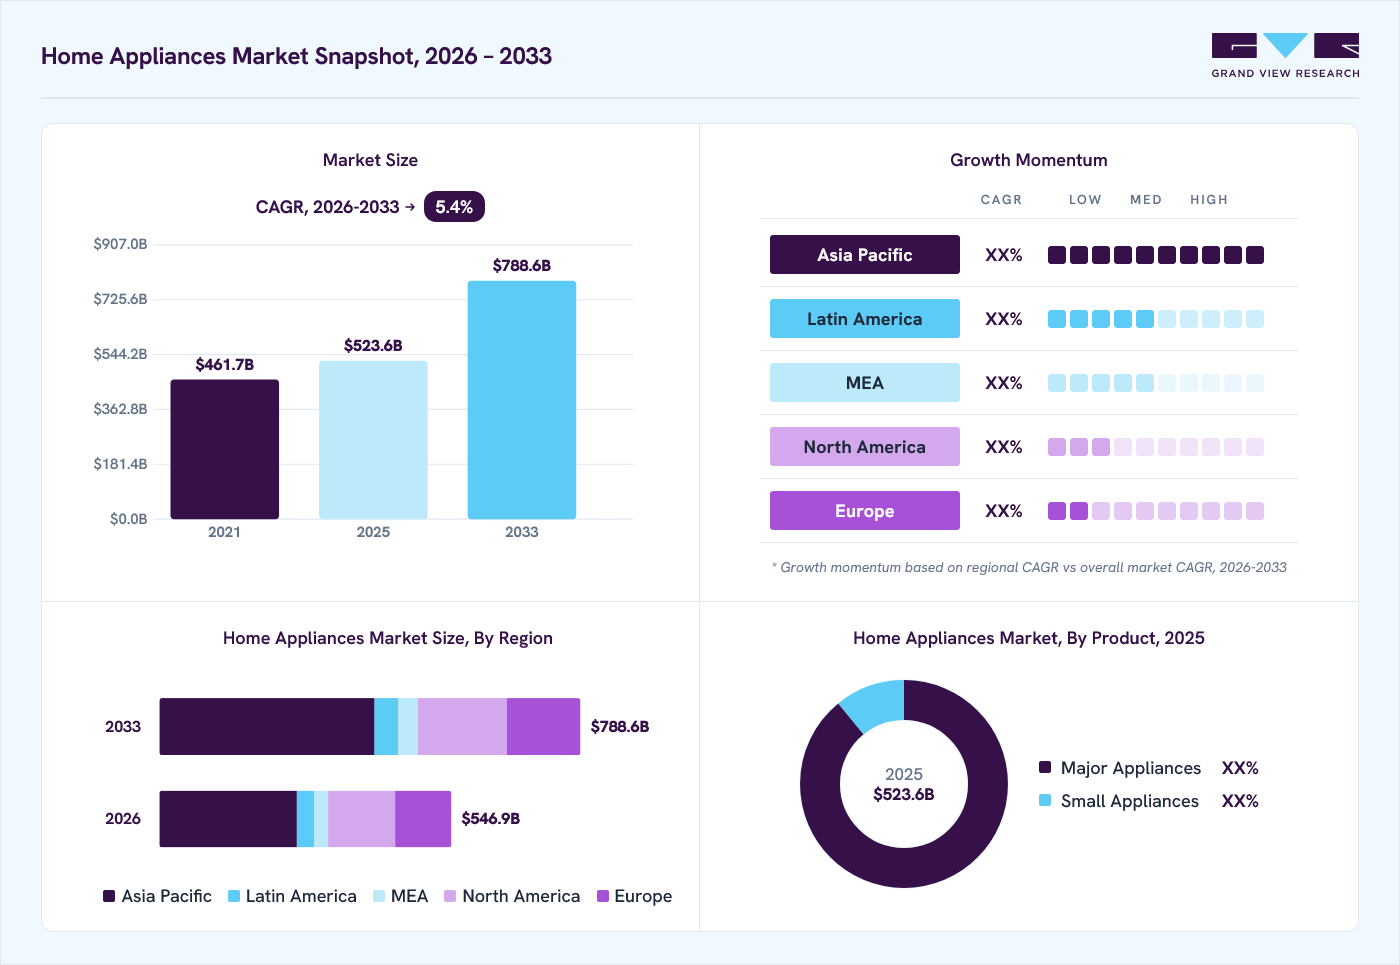 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Under major appliances, the cooktop, cooking range, microwave, and oven segment led the market with the largest revenue share of 22.8% in 2025.
- By distribution channel: Electronic stores segment led the market with the largest revenue share of 45.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (45.1% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 523.6 Billion
- Estimated market size in 2026: USD 546.9 Billion
- Projected market size by 2033: USD 788.6 Billion
- CAGR (2026-2033): 5.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These trends, coupled with evolving consumer lifestyles and heightened awareness of energy efficiency, are accelerating the demand and market expansion for home appliances worldwide. A key factor driving this growth in the industry is the rise in disposable incomes and living standards, especially in emerging economies across Asia Pacific, Latin America, and parts of Africa. As more households gain financial stability, they’re investing in modern appliances that enhance convenience and improve quality of life. This shift is particularly strong in urban areas, where busy lifestyles encourage the adoption of appliances that save time, such as washing machines, dishwashers, and microwaves. Urbanization also brings smaller living spaces, which has led to demand for compact, multifunctional, and energy-efficient appliances.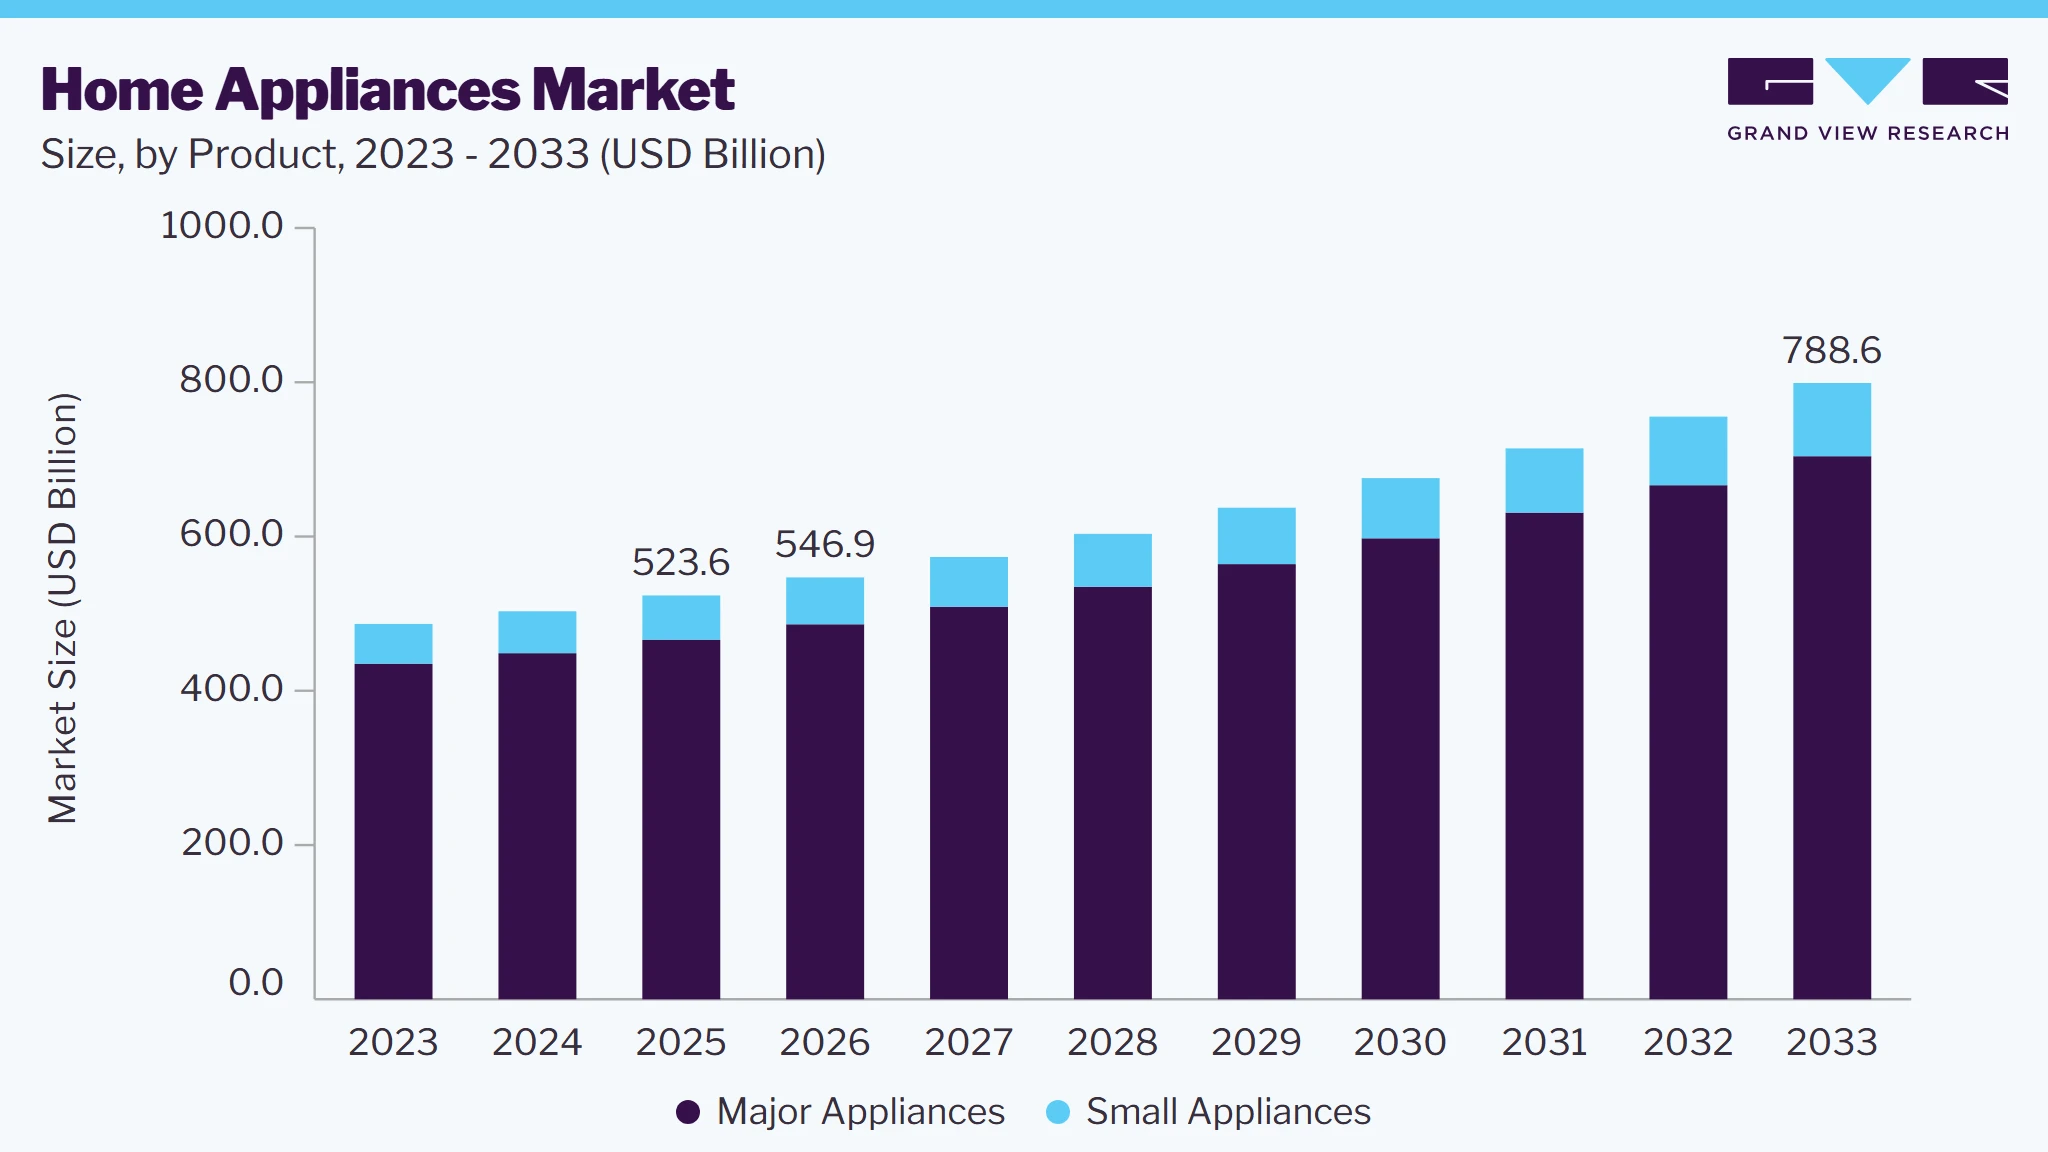 To learn more about this report, Download Free Sample Report
A key factor driving this growth in the industry is the rise in disposable incomes and living standards, especially in emerging economies across Asia Pacific, Latin America, and parts of Africa. As more households gain financial stability, they’re investing in modern appliances that enhance convenience and improve quality of life. This shift is particularly strong in urban areas, where busy lifestyles encourage the adoption of appliances that save time, such as washing machines, dishwashers, and microwaves. Urbanization also brings smaller living spaces, which has led to demand for compact, multifunctional, and energy-efficient appliances.
The surge in smart technology is another major contributor. Modern home appliances increasingly feature smart capabilities, allowing users to control and monitor devices remotely via smartphones or integrate them with other devices for enhanced functionality. Smart refrigerators, for instance, can track groceries and suggest recipes, while smart washing machines can be programmed from afar. This growing interest in smart homes aligns with the demand for appliances that can simplify tasks, offering added convenience and customization options that appeal to tech-savvy consumers.
Sustainability and energy efficiency are also critical factors influencing the home appliance industry. With increased awareness of environmental issues and rising energy costs, many consumers are choosing appliances that consume less energy and are environmentally friendly. Governments and organizations worldwide support this shift by implementing energy efficiency standards and providing incentives, such as tax credits or rebates, for purchasing eco-friendly appliances. As a result, manufacturers are prioritizing energy-efficient models and using sustainable materials to attract environmentally conscious buyers.
Market Dynamics
The home appliances market is experiencing steady expansion driven by rising urbanization, increasing disposable incomes, and growing consumer preference for convenience-driven, energy-efficient, and smart home solutions. Home appliances such as refrigerators, washing machines, air conditioners, microwaves, dishwashers, vacuum cleaners, and small kitchen appliances are becoming essential components of modern households. The integration of smart technologies, IoT-enabled devices, and automation features is transforming traditional appliances into connected ecosystems that allow remote monitoring, predictive maintenance, and energy optimization. Additionally, growing awareness of sustainability and energy conservation is encouraging adoption of eco-friendly appliances, supporting long-term market growth.
The increasing rate of urbanization and fast-paced lifestyle changes are significantly driving demand for home appliances globally. With more dual-income households and busy work schedules, consumers are increasingly relying on appliances that reduce manual effort and save time in daily household chores. Products such as automatic washing machines, robotic vacuum cleaners, microwave ovens, and smart refrigerators are witnessing strong adoption due to their convenience and efficiency. Rising disposable incomes, particularly in emerging economies, are further enabling households to upgrade from basic appliances to advanced, feature-rich models. In addition, growing electrification and improved access to retail and e-commerce channels are making appliances more accessible across both urban and semi-urban regions. As a result, home appliances are increasingly viewed as essential lifestyle products rather than discretionary purchases.
Despite strong demand, the home appliances market faces constraints due to the relatively high upfront cost of advanced and smart appliances. Energy-efficient models, IoT-enabled systems, and premium branded products often come at significantly higher price points, limiting adoption among price-sensitive consumers. Additionally, maintenance costs, repair complexity, and dependency on specialized technicians for smart and integrated appliances can create hesitation among buyers. In developing regions, inconsistent electricity supply and lack of adequate after-sales service infrastructure further restrict market penetration. Moreover, rapid technological upgrades can lead to faster product obsolescence, discouraging some consumers from investing in high-end models.
The expansion of smart home ecosystems and increasing focus on energy efficiency present substantial growth opportunities in the home appliances market. Consumers are increasingly adopting connected appliances that integrate with smartphones, voice assistants, and home automation platforms, enabling seamless control and improved energy management. Technologies such as AI-powered load optimization in washing machines, smart temperature regulation in air conditioners, and sensor-based energy saving in refrigerators are gaining traction. Additionally, government initiatives promoting energy-efficient appliances and sustainable living are encouraging manufacturers to innovate in eco-friendly product design. The rapid growth of e-commerce platforms is also enabling broader market access, allowing consumers to compare features, prices, and energy ratings more easily. These trends are expected to accelerate adoption of intelligent, energy-efficient, and connected home appliances in the coming years.
Analyst Perspective
The home appliances market sits at a pivotal intersection of structural tailwinds few consumer durables segments can match accelerating urbanization, rising disposable incomes, rapid electrification of households, and a fast-expanding middle-class population increasingly oriented toward convenience, automation, and energy efficiency. The shift from manual household management to smart, connected living is further reinforced by the proliferation of IoT-enabled ecosystems, where appliances are no longer standalone products but integrated components of digitally controlled homes. In parallel, sustainability mandates and rising energy costs are pushing both consumers and manufacturers toward energy-efficient, low-emission appliance portfolios.
Product Insights
Based on product, under major appliances the cooktop, cooking range, microwave, and oven segment led the market with the largest revenue share of 22.8% in 2025. The growing urban population and expanding middle-class demographic are major factors driving the demand for major appliances like refrigerators, washing machines, and air conditioners. As urbanization increases, more households are investing in essential home appliances to improve their living standards and convenience. This trend is particularly notable in emerging markets such as India, China, and Brazil, where rising disposable incomes and changing lifestyles are encouraging consumers to purchase modern appliances.
The small appliances market is expected to grow at a CAGR of 6.4% from 2025 to 2033. The growing demand for convenience in households is a major factor driving the small appliances market. Consumers are seeking products that can reduce time and effort in everyday tasks, leading to the rising popularity of small appliances like blenders, coffee makers, toasters, and hair dryers. The shift toward busy lifestyles, especially in urban areas, has accelerated the adoption of these devices, as they provide quick solutions to cooking, cleaning, and personal care needs.
Distribution Channel Insights
Based on distribution channel, the electronic stores segment led the market with the largest revenue share of 45.4% in 2025. Electronic stores have emerged as a prominent distribution channel in the major appliances industry due to their unique ability to blend traditional retail strengths with modern technological advancements. Established Indian retailers like Vijay Sales, Croma, and Reliance Digital have demonstrated resilience and adaptability in the face of rising e-commerce competition. These stores offer a comprehensive shopping experience that combines the tactile benefits of in-store shopping with the convenience of online access. With an extensive range of high-quality appliances, expert staff, and personalized customer service, they provide a more immersive and informative shopping experience than many online platforms.
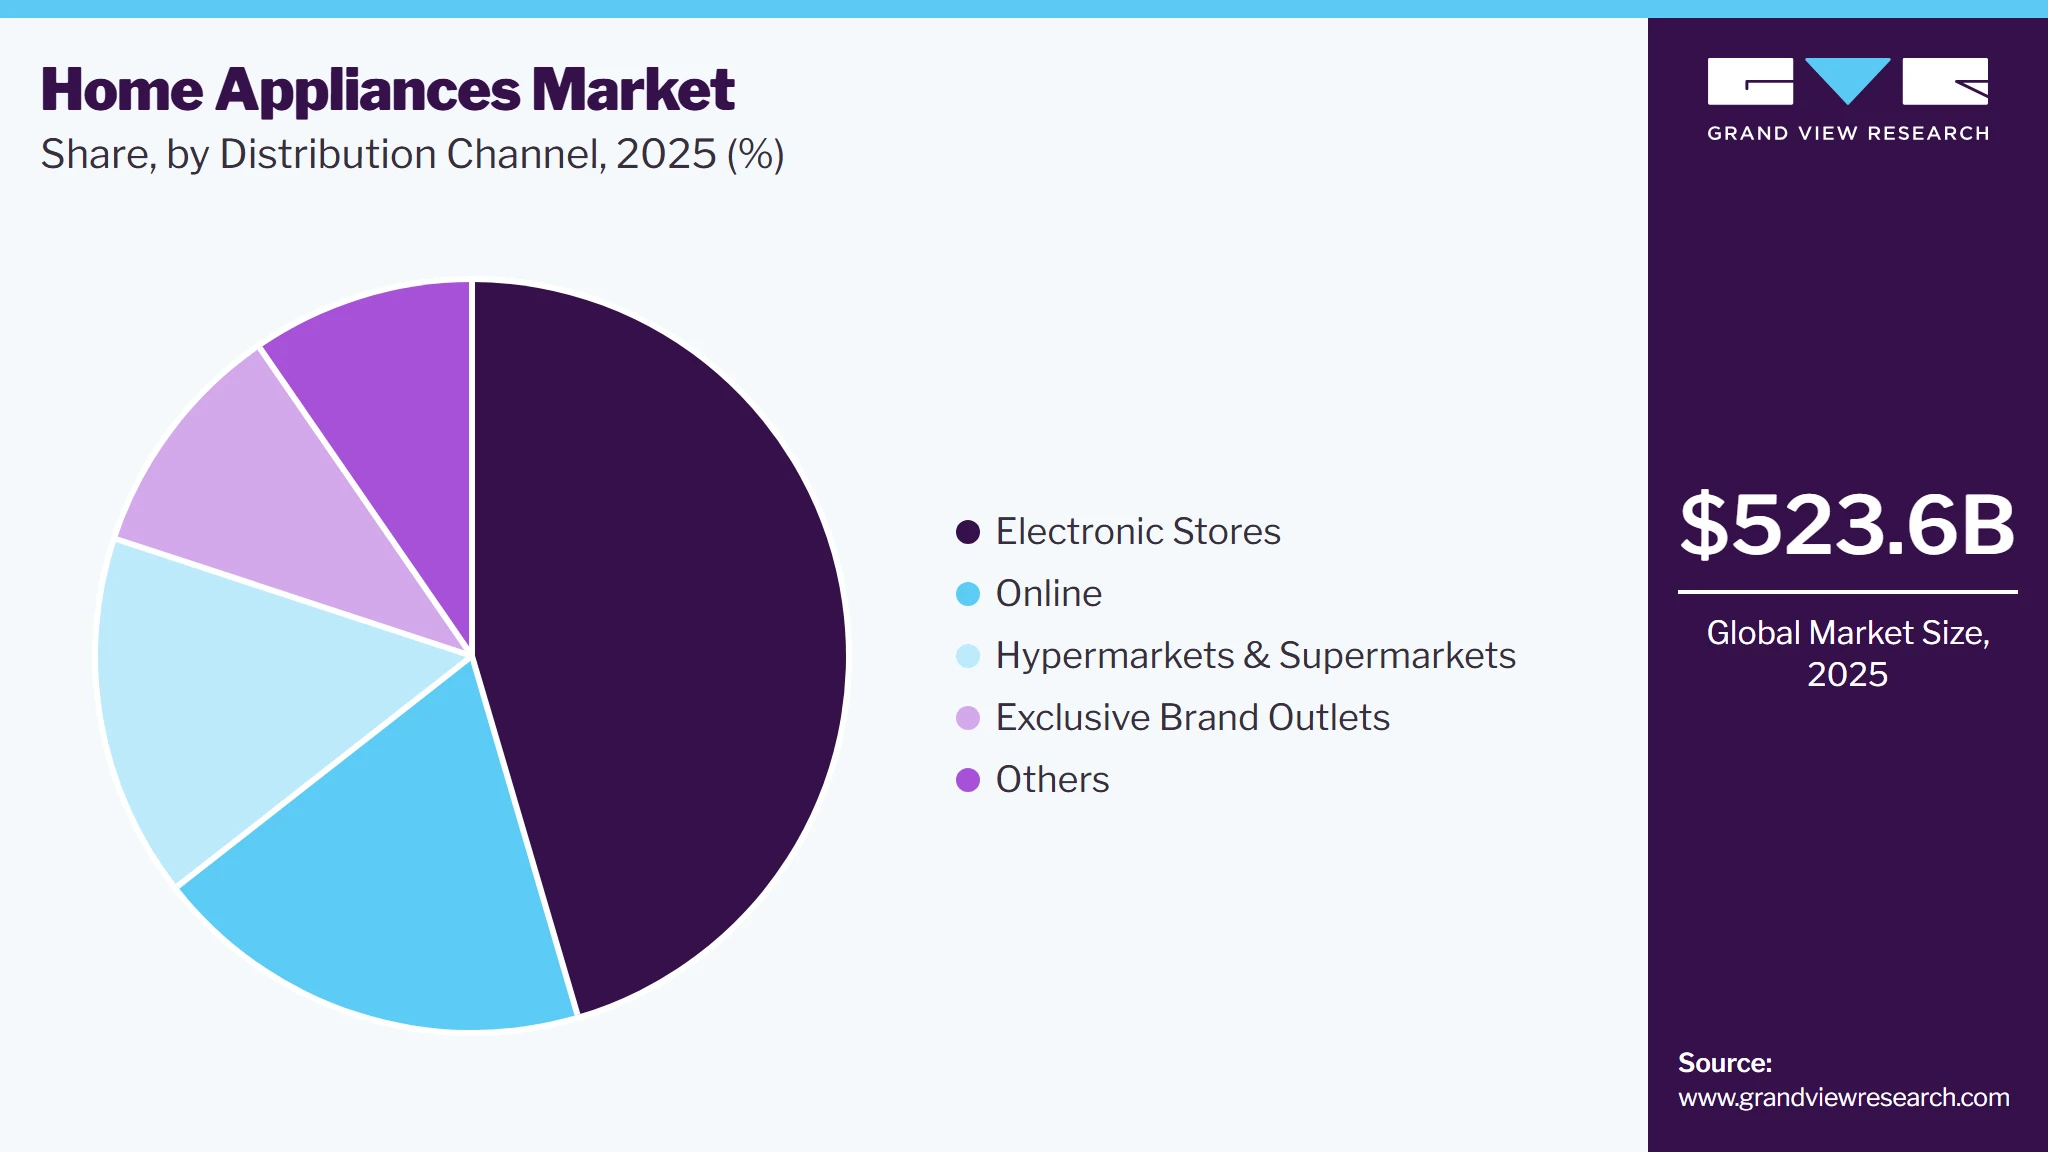 To learn more about this report, Download Free Sample Report
Sales of home appliances through online channels are expected to grow with a CAGR of 6.1% from 2025 to 2033. This segment is witnessing significant growth, driven by a shift in consumer behavior toward digital shopping. According to Adtaxi's 2024 Ecommerce Survey, 78% of Americans are now comfortable purchasing major appliances online, an increase from 73% reported the previous year. This growing acceptance reflects broader trends in online shopping, where convenience and the ability to compare products and prices easily have become paramount. With 93% of American adults engaging in online shopping and a notable increase in daily online shoppers, the online channel has become a critical platform for major appliances, offering an efficient way to reach a vast audience.
Regional Insights
North America home appliances market is expected to grow at a CAGR of 3.8% from 2025 to 2033. The North America market is characterized by its maturity and homogeneity, primarily driven by demand from a growing housing industry and increasing disposable incomes. In the U.S., the high costs associated with manufacturing have prompted many companies to offshore their production to other countries.
This shift has been further influenced by the strengthening of the U.S. dollar, resulting in a market that relies more on imports than exports. Despite these challenges, the rise in disposable income and the robust housing market have helped offset some of the adverse effects of the stronger dollar. In Canada, the major home appliance market is experiencing moderate growth, but the rising manufacturing costs are leading many companies to move their production facilities to the U.S., where labor costs are lower.
U.S. Home Appliances Market Trends
The home appliances market in the U.S. is expected to grow at a CAGR of 3.8% from 2025 to 2033. Recent innovations in the refrigerator and dishwasher markets are aimed at enhancing functionality and sustainability. Refrigerators now feature advanced technologies to improve food preservation and reduce waste, while dishwashers are being designed with variable pressure settings to enhance cleaning performance. These innovations reflect manufacturers' efforts to stay competitive by introducing new, advanced products that attract consumers.
Europe Home Appliances Market Trends
Europe home appliances market is expected to grow at a CAGR of 4.0% from 2025 to 2033. European consumers are becoming increasingly conscious of energy efficiency and environmental impact. This awareness has fueled demand for energy-efficient appliances that reduce electricity consumption and lower carbon footprint. The European Union's stringent regulations on energy efficiency, such as the Energy Labeling Regulation and the Ecodesign Directive, have further encouraged the adoption of energy-efficient appliances.
Asia Pacific Home Appliances Market Trends
Asia Pacific dominated the home appliances market with the largest revenue share of 45.1% in 2025. The region is home to some of the fastest-growing cities globally, with countries like China, India, Indonesia, and Vietnam experiencing substantial urban expansion. This urban growth is often accompanied by a surge in housing and infrastructure development, which in turn drives demand for household appliances. The home appliances market in the China held the largest share in the Asia Pacific region in 2025.
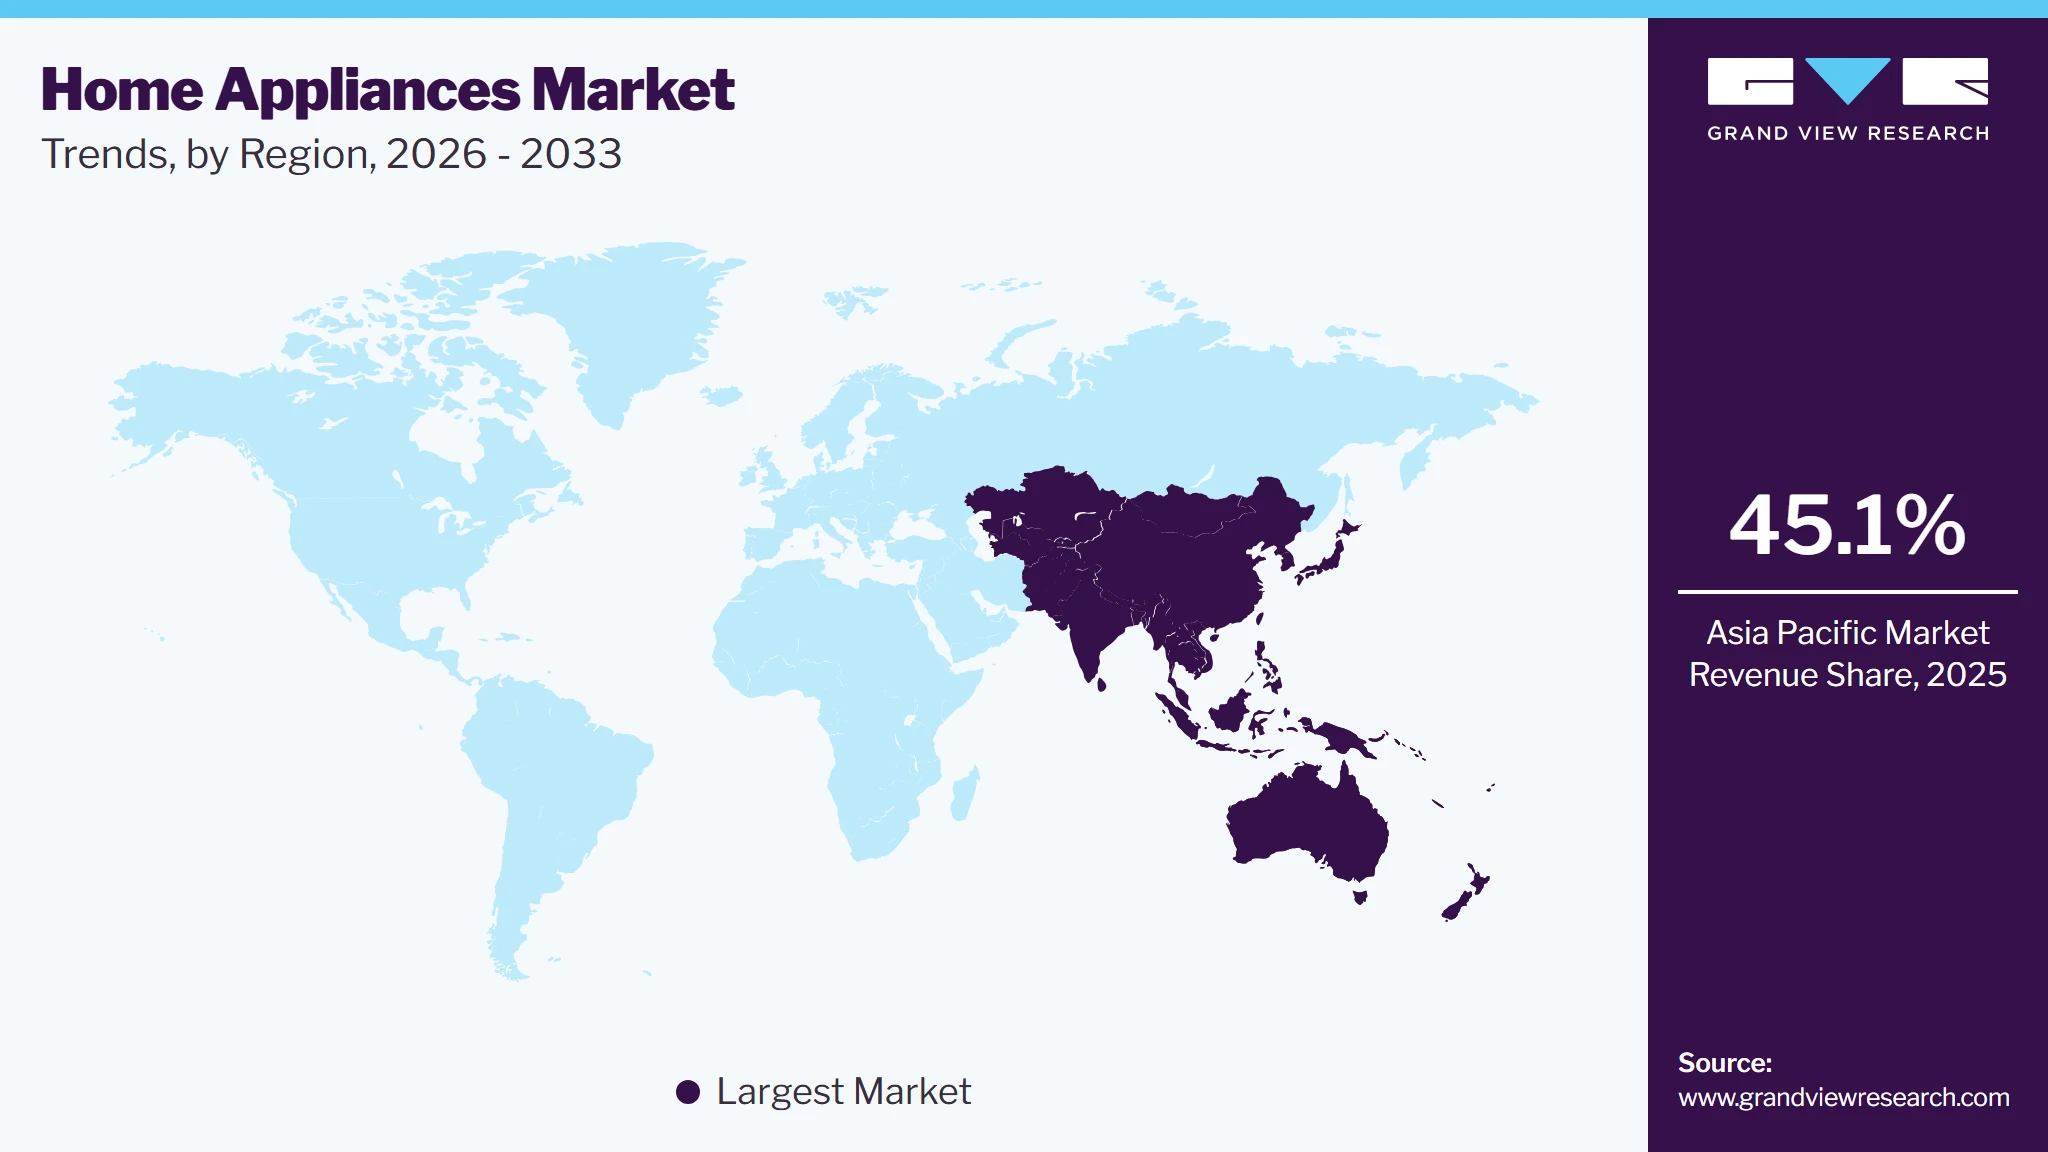 To learn more about this report, Download Free Sample Report
As more people move to urban areas, the need for modern homes equipped with essential appliances increases. Newly built apartments and houses are often designed to accommodate contemporary lifestyles, requiring appliances that offer convenience, efficiency, and space-saving solutions. This trend is particularly evident in densely populated cities where living spaces are often smaller, necessitating the use of compact and multifunctional appliances.
Key Home Appliances Company Insights
The industry is characterized by numerous well-established and emerging players. Manufacturers are engaging in a variety of strategic initiatives to keep pace with evolving consumer demands and market trends. For instance, in January 2024, Groupe SEB announced the launch of a state-of-the-art professional equipment hub in Shaoxing, China. This facility aims to enhance the group's production capabilities and strengthen its global supply chain by focusing on innovative manufacturing processes. The hub will support the growing demand for high-quality kitchen and home appliances while fostering local employment and contributing to the region's economy.
Key Home Appliances Companies
The following key companies have been profiled for this study on the home appliances market.
-
Whirlpool Corporation
-
Samsung Electronics Co. Ltd.
-
Robert Bosch GmbH
-
LG Electronics Inc.
-
Electrolux AB
-
Haier Smart Home Co., Ltd.
-
Panasonic Corporation
-
Sharp Corporation
-
Miele
-
Midea Group
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Samsung Electronics, LG Electronics, Whirlpool, Bosch, Haier, Panasonic, Electrolux)
- Focus on smart and IoT-enabled appliances, expand premium product portfolios, invest heavily in R&D for energy efficiency, strengthen omnichannel distribution (especially e-commerce), and increase localization of manufacturing to reduce costs and align with government incentives and regional demand shifts.
- Strong global brand equity, advanced technological capabilities in smart appliances, extensive distribution and after-sales service networks, economies of scale in manufacturing, and ability to drive innovation cycles in refrigerators, ACs, and washing machines.
- High exposure to raw material price volatility (steel, copper, semiconductors), intense price competition from regional and low-cost manufacturers, and margin pressure in commoditized segments such as basic refrigerators and washing machines.
Emerging Players (Godrej Appliances, Voltas, IFB Industries, Havells, Blue Star, Dixon Technologies, Atomberg, Livpure, Midea, Haier regional subsidiaries)
- Target value-conscious and mid-income consumers through affordable innovation, expand D2C and online-first sales models, introduce energy-efficient and smart-featured appliances at lower price points, leverage contract manufacturing and PLI schemes, and aggressively scale presence in tier-2 and tier-3 markets.
- Strong adaptability to local market needs, competitive pricing advantage, faster product iteration cycles, growing trust in domestic brands, and increasing strength in niche categories such as air conditioners, small appliances, and water purifiers.
- Limited global brand recognition compared to multinational leaders, weaker R&D depth in advanced smart ecosystems, dependence on imported components in some categories, and challenges in scaling premium positioning across markets.
Recent Developments
-
In August 2024, Samsung Electronics Co. Ltd. introduced 10 large-capacity Bespoke AI washing machines for Indian consumers, reinforcing its commitment to smart, energy-efficient appliances. These new models feature AI-driven technologies like AI Wash, which enhances water and detergent usage based on load weight and fabric type, and AI EcoBubble for improved cleaning performance with energy savings. The machines are also equipped with Wi-Fi connectivity, enabling users to control and monitor wash cycles remotely through the SmartThings app. This launch is part of Samsung's strategy to enhance convenience, sustainability, and personalization in the home appliance sector in India.
-
In January 2024, Bosch introduced innovations in its line of dishwashers in 2023 to enhance the user experience. These improvements include sleek touch controls, anti-fingerprint design, and advanced features like the PowerControl spray arm technology for better cleaning performance. The Home Connect app offers remote monitoring, customization options for different cycles, safety alerts, and other convenient features for a seamless dishwashing experience. Bosch aims to provide users with a range of dishwasher models across different series to meet various needs and budgets.
Home Appliances Market Report Scope
Report Attribute
Details
Market size in 2025
USD 523.6 billion
Estimated market size in 2026
USD 546.9 billion
Projected market size by 2033
USD 788.6 billion
Growth rate
CAGR of 5.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, Distribution Channel, Region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Germany; Italy; Spain; Poland; Portugal; Sweden; China; Japan; India; South Korea; Australia; Hong Kong; Indonesia; Phillipines; Singapore; Taiwan; Thailand; Vietnam; Brazil; South Africa; Egypt; Saudi Arabia; Turkey; UAE
Key companies profiled
Whirlpool Corporation; Samsung Electronics Co. Ltd.; Robert Bosch GmbH; LG Electronics Inc.; Electrolux AB; Haier Smart Home Co., Ltd.; Panasonic Corporation; Sharp Corporation; Miele; Midea Group
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Home Appliances Market Report Segmentation
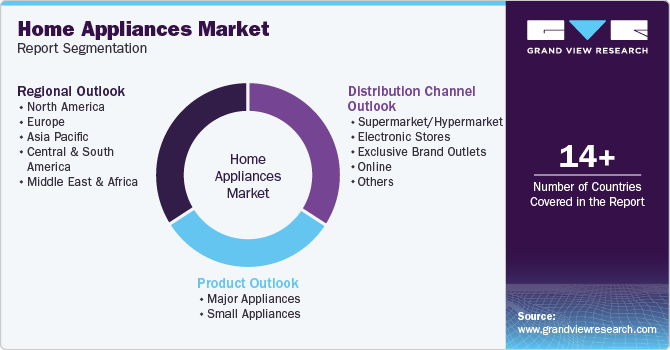
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global home appliances market report based on the product, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Major Appliances
-
Water Heater
-
Dishwasher
-
Refrigerator
-
Cooktop, Cooking Range, Microwave, and Oven
-
Vacuum Cleaner
-
Washing Machine and Dryers
-
Air Conditioner
-
-
Small Appliances
-
Coffee Makers
-
Toasters
-
Juicers, Blenders and Food Processors
-
Hair Dryers
-
Irons
-
Deep Fryers
-
Space Heaters
-
Electric Trimmers and Shavers
-
Air Purifiers
-
Humidifiers & Dehumidifiers
-
Rice Cookers & Steamers
-
Air Fryers
-
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Supermarket/Hypermarket
-
Electronic Stores
-
Exclusive Brand Outlets
-
Online
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia & New Zealand
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
-
Research Methodology
The home appliances market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each home appliances segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Distribution Channel
Revenue capture definition
Hypermarkets & Supermarkets
This segment covers the revenues generated through the sales of home appliances via large-format retail stores that offer a wide assortment of consumer goods under one roof. These channels typically include high-footfall retail environments where consumers can physically evaluate products such as refrigerators, washing machines, microwaves, and small kitchen appliances before purchase. Real-life examples include large retail chains like hypermarket stores offering electronics sections where brands such as LG, Samsung, Whirlpool, and Bosch are displayed alongside other household goods.
Electronic Stores
This segment covers the revenues generated through specialized retail outlets focused exclusively on consumer electronics and home appliances. These stores provide expert guidance, product demonstrations, and after-sales support, making them a preferred channel for high-value appliance purchases. Real-life examples include dedicated electronics retailers such as Croma, Reliance Digital, and Vijay Sales, where consumers can compare models of air conditioners, washing machines, televisions, and kitchen appliances.
Exclusive Brand Outlets
This segment covers the revenues generated through single-brand retail stores owned or operated by home appliance manufacturers. These outlets showcase a brand’s full product portfolio, offering a controlled environment for customer experience, brand positioning, and premium product display. Real-life examples include Samsung Smart Cafés, LG Brand Shops, and Whirlpool Exclusive Stores, where consumers can explore the latest appliances directly from the manufacturer.
Online
This segment covers the revenues generated through digital sales channels including e-commerce platforms and brand-owned websites that enable consumers to purchase home appliances with home delivery and installation services. These platforms offer product comparisons, discounts, customer reviews, and easy financing options. Real-life examples include Amazon, Flipkart, Reliance Digital Online, and official brand websites such as those of LG, Samsung, and Haier.
Others
This segment covers the revenues generated through alternative distribution channels such as direct sales, institutional sales, multi-brand dealers, local independent retailers, and home improvement stores. These channels often serve niche customer segments or rural and semi-urban markets where organized retail penetration is lower. Real-life examples include local appliance dealers, wholesale distributors, builder supply contracts for bulk housing projects, and home improvement chains like Home Centre or regional appliance marts.
Estimation Model
01. Epidemiology Layer
02. Digital Access Layer
03. Behavioural Layer
04. Monetisation Layer
Who has a relevant need?
Who can be reached digitally?
Who actively buys home appliances?
How much revenue is generated?
Households, urban families, and commercial users seeking essential and smart home appliances for daily convenience. Demand is assessed based on household formation, urbanization, replacement needs, income levels, and adoption of modern home appliances.
Consumers reachable through e-commerce platforms, brand websites, online retail stores, and digital advertisements. The addressable audience is evaluated using internet penetration, digital shopping adoption, online product discovery, and access to digital retail channels.
Middle- to high-income consumers purchasing energy-efficient, smart, and durable appliances for household use. Purchase behavior is assessed based on replacement cycles, disposable income, brand preferences, energy efficiency, product features, financing availability, and consumer buying patterns.
Revenue comes from sales of refrigerators, washing machines, air conditioners, microwaves, and other home appliances through offline retail and online channels, driven by replacement demand and smart appliance adoption. Market revenue is calculated using unit sales, average selling prices (ASPs), product mix, and regional pricing variations.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Smart Home Integration & Energy Efficiency Trends
Conducted a focused analysis of home appliances covering smart appliance adoption, IoT-enabled devices, energy-efficient product demand, inverter technology, and sustainability-driven innovation across refrigeration, washing machines, air conditioners, and kitchen appliances.
Helps stakeholders identify high-growth smart appliance segments, evaluate consumer shift toward energy-saving solutions, and assess opportunities in connected home ecosystems and green technology adoption.
Urbanization, Lifestyle Shift & Premium Appliance Adoption Trends
Evaluated consumer behavior trends driven by urbanization, rising disposable incomes, and evolving lifestyles, including increased demand for multifunctional appliances, compact designs for urban homes, and premium feature-rich products with automation and convenience capabilities.
Provides insights into emerging consumer needs, product positioning strategies, and commercialization opportunities in mid-to-high-end appliance categories across fast-growing residential markets.
Digital Transformation, E-commerce & After-Sales Service Ecosystem Assessment
Assessed the growing role of online retail channels, direct-to-consumer models, subscription-based maintenance services, and AI-enabled predictive maintenance systems, along with challenges in supply chain efficiency and after-sales service networks.
Supports investment and expansion strategies by identifying digital sales opportunities, improving customer retention models, and strengthening long-term service and warranty-driven revenue streams in the appliance ecosystem.
Frequently Asked Questions About This Report
The global home appliances market size was valued at USD 503.0 billion in 2024 and is estimated at USD 547.0 billion for 2026.
The global home appliances market is expected to grow at a CAGR of 5.2% from 2025 to 2030, reaching USD 675.7 billion by 2030.
Some key players operating in home appliances market include Whirlpool Corporation, Samsung Electronics Co. Ltd., Robert Bosch GmbH, LG Electronics Inc., Electrolux AB, and others.
Small appliances are expected to growth with a CAGR of 6.4% from 2025 to 2030. The integration of smart technologies in small appliances is reshaping the market. Devices that can connect to Wi-Fi, be controlled through mobile apps, or work with voice assistants like Alexa and Google Assistant are increasingly popular. For instance, smart coffee makers can be programmed to brew coffee at specific times. These innovations align with the broader trend of smart home ecosystems, where consumers are adopting appliances that provide enhanced functionality, efficiency, and convenience.
Key factors that are driving the market growth include rising consumer demand for energy-efficient appliances and rising technological advancements
About the Author(s)
Electronic & Electrical Research Team
Consumer Goods · Electronic & ElectricalThis report was authored by the electronic & electrical research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the electronic & electrical segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


