
- Home
- »
- Medical Devices
- »
-
Immuno-oncology Clinical Trials Market Size Report, 2033GVR Report cover

Immuno-oncology Clinical Trials Market (2026 - 2033)
Size, Share & Trends Analysis Report By Phase (Phase I, Phase II, Phase III, Phase IV), By Study Design, By Indication, By Therapy, By Sponsor, By Value Chain, By Region, And Segment Forecasts
Market Size, 2025
$9.4BMarket Estimate, 2026
$10.6BMarket Forecast, 2033
$21.0BCAGR, 2026–2033
10.3%Immuno-oncology Clinical Trials Market Summary
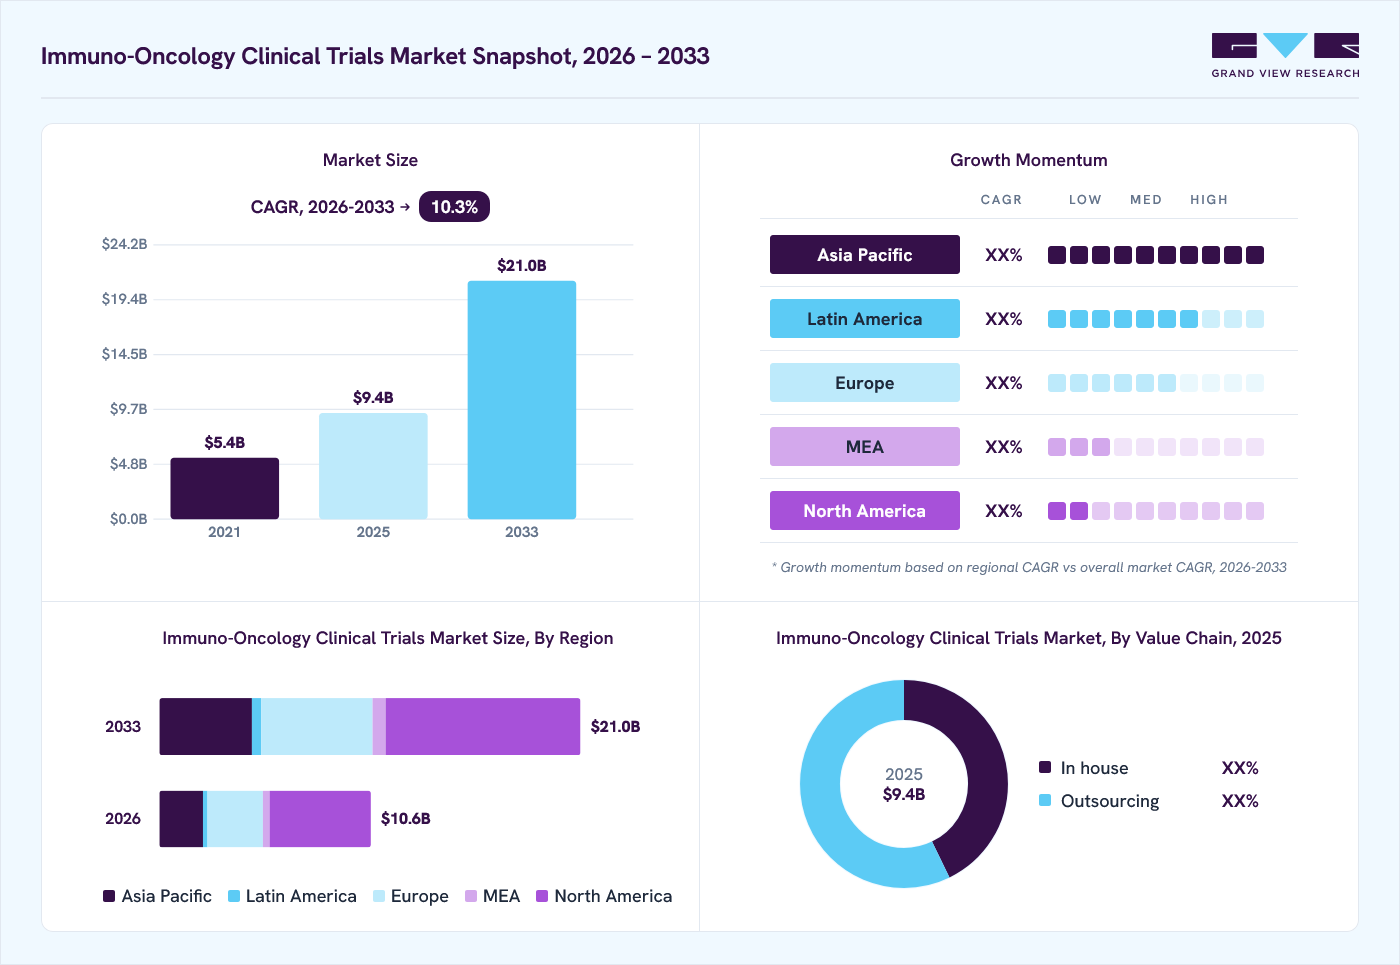
The global immuno-oncology clinical trials market size was valued at USD 9.4 billion in 2025 and is projected to grow from USD 10.6 billion in 2026 to USD 21.0 billion by 2033, at a CAGR of 10.3% from 2026 to 2033. The market in North America dominated with a revenue share of 48.1% in 2025. The growth of the market is due to expanding clinical development of combination immunotherapies and novel therapeutic modalities, increasing adoption of biomarker-guided patient selection and precision oncology and growing pharmaceutical R&D investment and outsourcing of immuno-oncology clinical trials.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By phase: Phase III segment held the largest market share of 54.2% in 2025.
- By study design: Interventional segment held the largest market share of 76.5% in 2025.
- By indication: Solid tumors segment held the largest market share of 55.9% in 2025.
- By therapy: Immune checkpoint inhibitors segment held the largest market share of 20.2% in 2025.
- By sponsor: Pharmaceutical and biopharmaceutical companies segment held the largest market share of 76.6% in 2025.
- By value chain: Outsourcing segment held the largest market share of 57.2% in 2025.
Regional Highlights
- Largest regional market: North America (48.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 9.4 Billion
- Estimated market size in 2026: USD 10.6 Billion
- Projected market size by 2033: USD 21.0 Billion
- CAGR (2026-2033): 10.3%
Prism AI by Grand View Research Free to tryAsk a question about the immuno-oncology clinical trials marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →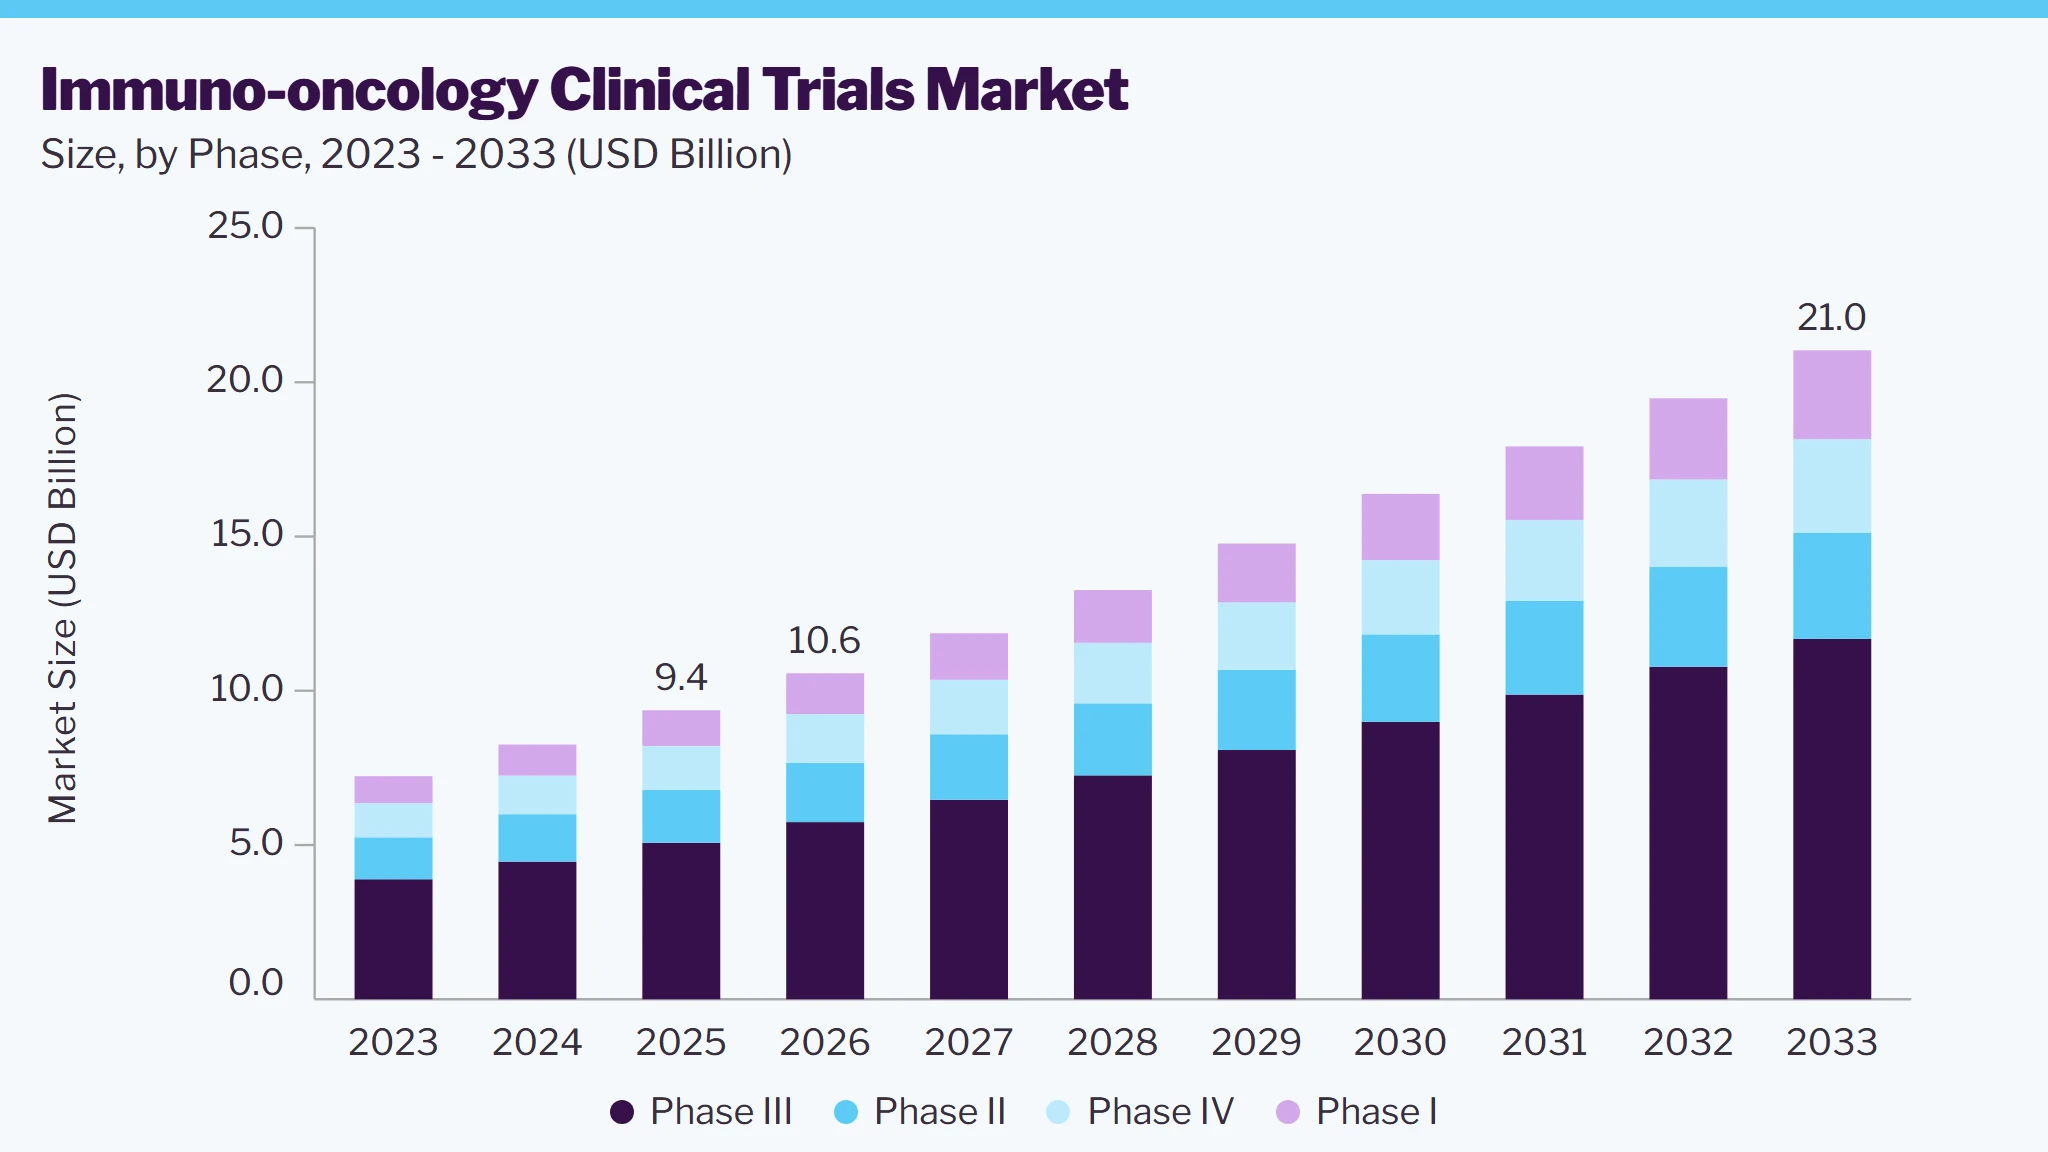 To learn more about this report, Download Free Sample Report
Market Dynamics
The immuno-oncology clinical trials market is driven by increasing cancer incidence, expanding immunotherapy pipelines, growing investment in combination therapies, and demand for personalized cancer treatments. Besides this, development of checkpoint inhibitors, adoptive cell therapies, and therapeutic cancer vaccines is increasing clinical research activity across solid tumors and hematological malignancies. For instance, in August 2026, Merck and Moderna announced positive Phase III INTerpath-001 results for individualized mRNA therapy combined with pembrolizumab in melanoma, supporting further clinical development.
In addition, high clinical trial expenditure, complex manufacturing requirements, stringent regulatory standards, and prolonged patient recruitment remain major market restraints. The biomarker-based eligibility criteria, immune-related adverse events, and limited availability of specialized oncology research centers create additional operational challenges.
In addition, technological advancements in artificial intelligence (AI), genomic profiling, adaptive trial designs, and immune monitoring are improving patient selection, treatment evaluation, and clinical development efficiency. Besides this, growing adoption of decentralized trial components and specialized contract research services creates opportunities for pharmaceutical sponsors and CROs.
Furthermore, increasing research into novel immune targets, combination regimens, and treatment-resistant malignancies presents opportunities for clinical pipeline expansion. However, uncertain clinical outcomes, competition for eligible patients, and evolving regulatory evidence requirements continue to influence trial timelines, development expenditure, and market growth prospects.
The immuno-oncology clinical trials market is driven by expanding development of combination immunotherapies, increasing investigation of novel immune targets, and growing clinical activity across solid tumors and hematological malignancies. Besides this, pharmaceutical and biotechnology companies are advancing checkpoint inhibitor combinations, therapeutic cancer vaccines, adoptive cell therapies, and cytokine-based treatments to address treatment resistance and improve clinical outcomes. These developments increase demand for specialized clinical research services, biomarker testing, patient recruitment, and multicenter trial management.
In addition, market is also witnessing growth due to strategic initiatives. For instance, in June 2025, Teva Pharmaceutical Industries and Fosun Pharma entered a strategic partnership to develop TEV-56278, an investigational anti-PD-1 and interleukin-2 fusion therapy targeting solid tumors. Such a collaboration supports clinical development across multiple Asian markets. Such developments increase requirements for specialized clinical sites, genomic profiling, immune monitoring, and regulatory coordination. Furthermore, continued expansion of combination immunotherapy pipelines is expected to generate additional clinical trial expenditure and outsourcing opportunities, supporting immuno-oncology clinical trials market growth.
High clinical development expenditure and complex operational requirements are significant restraints affecting the immuno-oncology clinical trials market. Immunotherapy studies involve specialized treatment administration, extensive biomarker assessments, immune response monitoring, and prolonged patient follow-up, increasing expenditure across clinical phases. In addition, advanced therapeutic modalities, including CAR-T cell therapies, personalized cancer vaccines, and bispecific antibodies, require specialized manufacturing coordination, trained clinical personnel, and dedicated research infrastructure. Besides this, multicenter Phase III studies increase expenditure through patient recruitment, site activation, clinical monitoring, data management, and regulatory compliance activities.
In addition, patient selection based on molecular biomarkers adds screening costs and limits eligible populations, particularly for studies targeting specific genetic alterations or immune characteristics. Besides this, immune-related adverse events and cytokine release syndrome require specialized clinical management, additional laboratory assessments, and potential hospitalization. Some of the complex treatment protocols and combination regimens can increase trial duration, operational workload, and protocol amendment requirements. In addition, smaller biotechnology companies face additional financial constraints when conducting multinational studies involving specialized investigational therapies. These factors can delay trial initiation, restrict clinical development programs, and increase dependence on external research funding. Thus, escalating operational expenditure and infrastructure requirements may limit trial expansion and constrain overall market growth.
The growing development of precision immunotherapies and strategic partnerships presents substantial opportunities for the immuno-oncology clinical trials market. Besides this, increasing research into personalized cancer vaccines, immune checkpoint combinations, and tumor-specific immunomodulators is creating demand for specialized clinical development services.
Some of the pharmaceutical companies are exploring novel treatment mechanisms to address resistance to existing immunotherapies and improve outcomes in patients with limited therapeutic options. These activities create opportunities for CROs, molecular diagnostic providers, and specialized oncology research centers to support complex clinical programs. For instance, in June 2025, Teva Pharmaceutical Industries and Fosun Pharma established a strategic partnership to accelerate clinical development of TEV-56278, an investigational anti-PD-1 and interleukin-2 fusion therapy targeting multiple cancers. This agreement provides development opportunities across China and selected Southeast Asian markets, facilitating broader clinical data generation.
In addition, in January 2026, the Cancer Research Institute collaborated with 10x Genomics to launch an AI-driven immuno-oncology research initiative involving more than 20,000 biological samples. This initiative integrates single-cell and spatial profiling technologies to identify immune response mechanisms and treatment resistance, creating opportunities for biomarker discovery, precision immunotherapy development, and future clinical trial programs.
Market Concentration & Characteristics
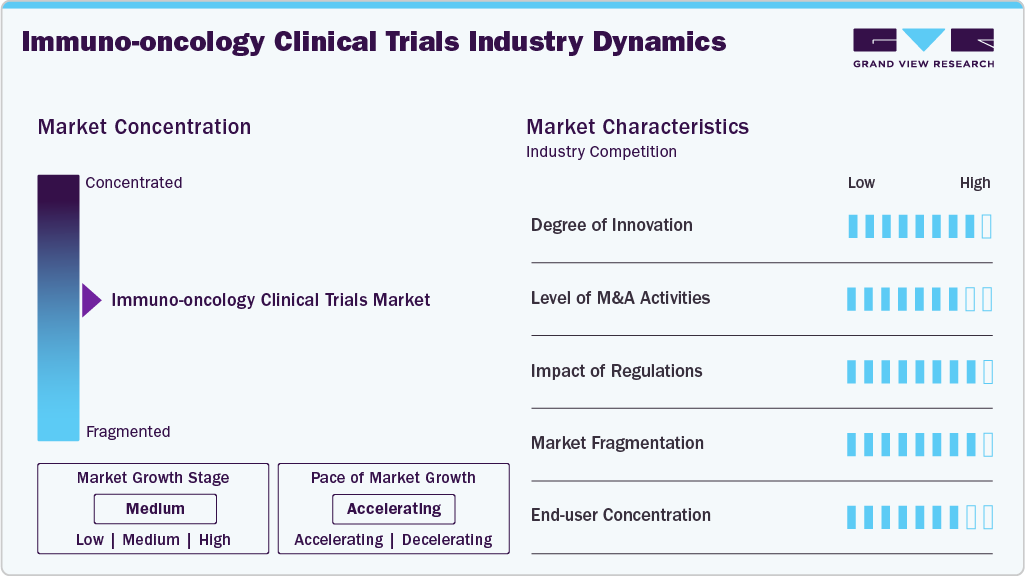
The immuno-oncology clinical trials market is characterized by intensive research investment, complex therapeutic development, stringent regulatory requirements, and increasing clinical outsourcing. The growing investigation of checkpoint inhibitors, adoptive cell therapies, and combination immunotherapies drives innovation. In addition, biomarker-based patient selection, specialized clinical infrastructure, and prolonged development timelines influence trial expenditure, competitive intensity, sponsor collaboration, and global market expansion across cancer indications.
The immuno-oncology clinical trials market demonstrates a high degree of innovation, driven by advancements in adoptive cell therapies, cancer vaccines, bispecific antibodies, and immune checkpoint inhibitors. Integration of artificial intelligence, genomic profiling, and adaptive trial designs is improving clinical development capabilities across indications. For instance, in September 2026, AstraZeneca highlighted advancements in patient-derived tumor models, Phase 0 studies, and AI-powered digital twins to improve immunotherapy response prediction, biomarker identification, and clinical trial optimization.
 To learn more about this report, Download Free Sample Report
The immuno-oncology clinical trials market experiences considerable merger and acquisition activity as pharmaceutical companies seek innovative therapeutic pipelines, specialized technologies, and clinical development capabilities. Acquisitions involving biotechnology companies, cell therapy developers, and immunotherapy platforms facilitate portfolio diversification and research expansion. For instance, in June 2026, Biogen announced an agreement to acquire RayThera for up to USD 1 billion, expanding its immunology pipeline with anti-inflammatory assets, including a Phase I candidate.
Regulatory frameworks significantly influence immuno-oncology clinical trial development through requirements governing patient safety, investigational therapies, clinical protocols, and evidence generation. Authorities including the FDA and EMA oversee trial authorization, manufacturing quality, pharmacovigilance, and ethical compliance. Advanced cell therapies and combination immunotherapies face additional regulatory considerations, increasing documentation requirements, operational expenditure, and development timelines across multinational clinical research programs globally.
The immuno-oncology clinical trials market exhibits moderate fragmentation, comprising multinational pharmaceutical companies, biotechnology developers, academic institutions, and specialized contract research organizations. Established companies maintain extensive clinical pipelines and research infrastructure, while emerging biotechnology firms investigate novel therapeutic mechanisms. Competition centers on clinical development expertise, patient recruitment capabilities, biomarker technologies, geographic presence, and specialized trial management services across therapeutic categories globally.
End user concentration in the immuno-oncology clinical trials market is influenced by pharmaceutical and biopharmaceutical companies, academic research institutions, and government funded organizations. Large pharmaceutical sponsors account for substantial clinical development expenditure through multinational research programs and extensive immunotherapy pipelines. Academic cancer centers contribute investigator initiated studies, while smaller biotechnology companies increasingly engage specialized research providers for clinical development activities globally.
Analyst Perspective
The immuno-oncology clinical trials market is expected to witness sustained growth, driven by expanding therapeutic pipelines, increasing investment in precision oncology, and growing adoption of combination immunotherapies. Clinical development is shifting toward biomarker-guided patient selection, personalized cancer vaccines, and next-generation cellular therapies. Pharmaceutical companies are expanding collaborations with biotechnology developers, academic institutions, and specialized CROs to manage trial complexity and accelerate development timelines. However, high operational costs, recruitment challenges, and stringent regulatory requirements remain significant constraints. Some of the advancements in AI-assisted trial design, molecular profiling, and adaptive protocols are anticipated to improve clinical efficiency and support market expansion.
Impact of U.S. Tariffs on Immuno-oncology Clinical Trials Market
U.S. tariffs on imported pharmaceutical inputs, laboratory equipment, and clinical research supplies could increase operational expenditure across the immuno-oncology clinical trials market. Clinical studies involving adoptive cell therapies, cancer vaccines, and checkpoint inhibitors require specialized reagents, analytical instruments, diagnostic kits, and temperature-controlled logistics. Higher import costs for tariff-covered products may increase clinical site budgets, laboratory testing expenditure, and investigational therapy manufacturing costs. Multinational sponsors may face additional procurement complexities when sourcing materials across international research networks.
However, the September 2026 U.S. tariff provisions established a 0% additional pharmaceutical tariff for eligible products and ingredients imported exclusively for clinical trials, research, and other noncommercial applications. This exemption reduces direct tariff exposure for qualifying investigational medicines, although laboratory equipment, consumables, and certain ancillary supplies may remain subject to separate duties.
Tariff-related uncertainty may encourage sponsors and contract research organizations to diversify suppliers, expand domestic procurement, and establish regional clinical supply networks. Smaller biotechnology companies could face greater financial pressure from procurement adjustments and logistical disruptions. Thus, tariffs may increase selected operating costs and complicate trial planning, while research-specific exemptions could moderate their overall impact on immuno-oncology clinical trial expenditure and market growth.
Technological Advancements
 To learn more about this report, Download Free Sample Report
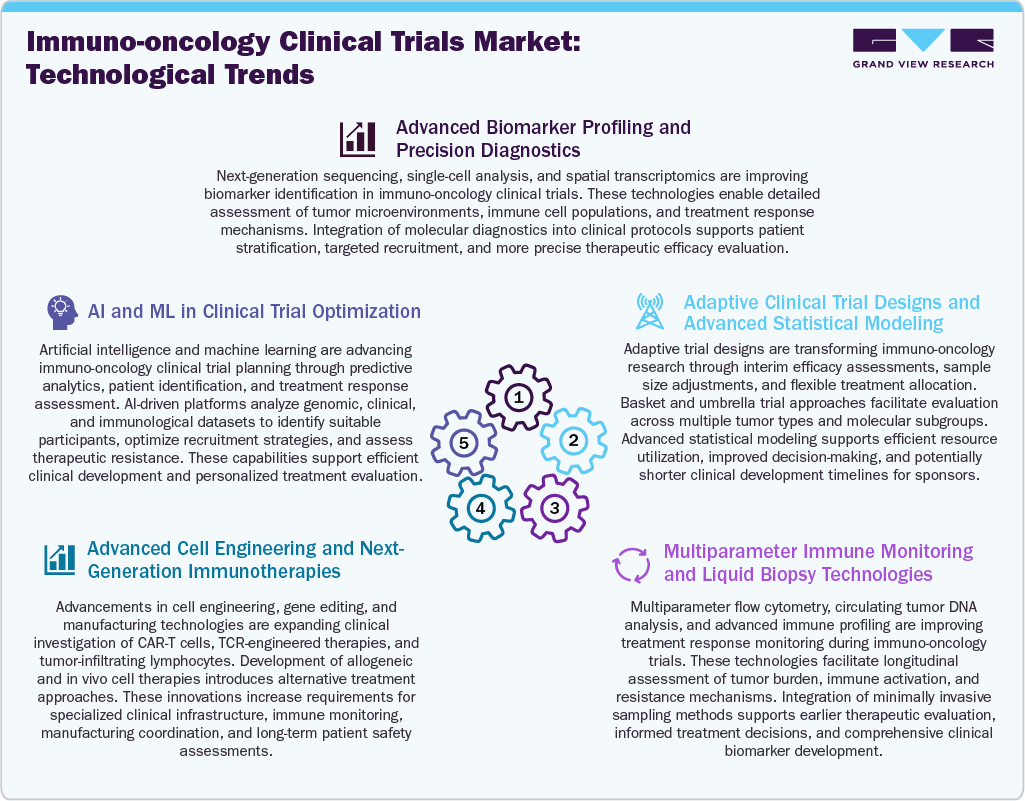
Technological advancements in AI, molecular diagnostics, adaptive trial designs, cell engineering, and immune monitoring are improving clinical research capabilities across the immuno-oncology clinical trials market. AI and ML facilitate patient identification, recruitment optimization, predictive modeling, and treatment response assessment through analysis of genomic and clinical datasets. In addition, next-generation sequencing, single-cell analysis, and spatial transcriptomics enable detailed characterization of tumor microenvironments, supporting biomarker discovery and precision patient selection. In addition, adaptive clinical trial designs, including basket and umbrella studies, facilitate investigation of multiple therapeutic approaches and cancer indications within structured research protocols. Interim data assessments and advanced statistical modeling improve clinical development efficiency and resource allocation. Furthermore, advancements in gene editing and cell engineering are expanding clinical investigation of CAR-T cells, TCR-engineered therapies, and tumor-infiltrating lymphocytes, increasing demand for specialized manufacturing and clinical infrastructure.
Moreover, multiparameter flow cytometry, circulating tumor DNA analysis, and liquid biopsy technologies support longitudinal monitoring of immune responses, disease progression, and therapeutic resistance. Integration of these technologies into clinical protocols is expected to improve patient stratification, strengthen clinical evidence generation, optimize trial operations, and create additional opportunities for specialized research service providers globally.
Pricing Model Analysis
 To learn more about this report, Download Free Sample Report
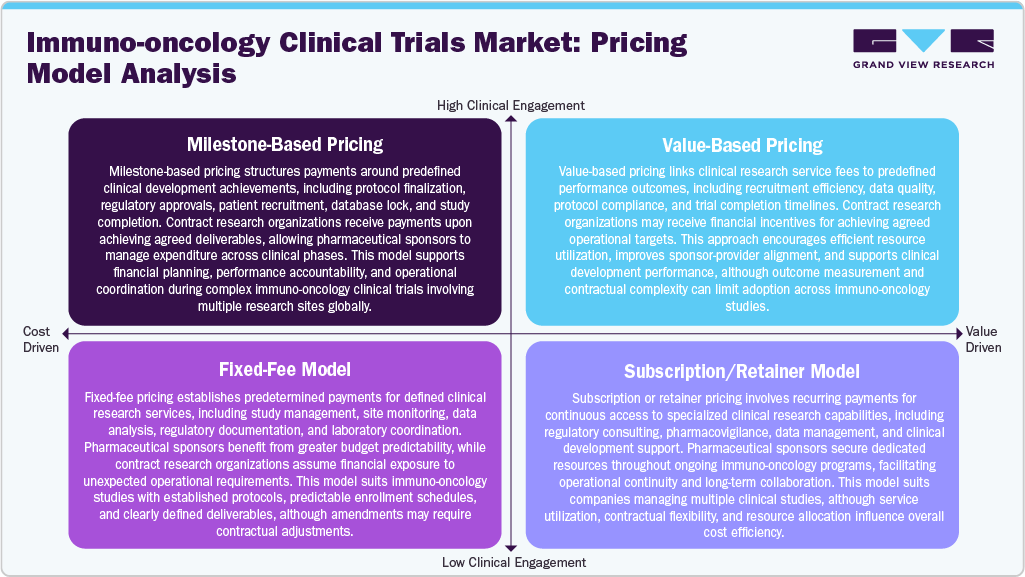
Pricing structures in the immuno-oncology clinical trials market include milestone-based, value-based, fixed-fee, and subscription or retainer models, depending on study complexity, service requirements, and contractual arrangements. Milestone-based pricing links payments to predefined achievements, including protocol development, patient recruitment, regulatory approvals, and study completion. This approach supports expenditure management and accountability throughout clinical development.
Value-based pricing connects service fees with measurable operational outcomes, including recruitment efficiency, data quality, protocol compliance, and trial timelines. Performance incentives encourage contract research organizations to achieve agreed objectives while maintaining clinical research standards.
Fixed-fee arrangements establish predetermined payments for specified services, including clinical monitoring, data management, laboratory coordination, and regulatory documentation. These contracts provide budget predictability but may require adjustments following protocol amendments, recruitment delays, or additional safety assessments.
Subscription and retainer models involve recurring payments for continuous access to specialized clinical research capabilities, including pharmacovigilance, regulatory consulting, and clinical operations support. These arrangements facilitate long-term sponsor-provider relationships across multiple immuno-oncology development programs. Pricing model selection influences financial predictability, operational flexibility, risk allocation, and overall clinical trial expenditure across therapeutic modalities and development phases globally.
Phase Insights
On the basis of phase, phase III represented the largest segment with a share of 54.2% in 2025, owing to substantial patient enrollment, extensive multicenter operations, and higher expenditure on clinical monitoring and treatment administration. Besides this, pharmaceutical companies invest heavily in confirmatory studies evaluating immune checkpoint inhibitors, cancer vaccines, and combination regimens. These trials frequently involve international research networks, prolonged follow-up, and comprehensive efficacy assessments. Increasing regulatory requirements for comparative clinical evidence and survival outcomes contribute to substantial Phase III spending, maintaining the segment's leading revenue position within the immuno-oncology clinical trials market.
Phase I segment is anticipated to register the fastest growth over the forecast period, supported by increasing first-in-human investigations of novel immunotherapeutic mechanisms. The emerging biotechnology companies are advancing engineered cytokines, immune cell engagers, and tumor-targeted immunomodulators into early clinical development. Besides this, dose escalation, pharmacokinetic characterization, and preliminary safety assessments require specialized clinical facilities and intensive patient monitoring. In addition, growing interest in evaluating biological activity through expansion cohorts is increasing protocol complexity. Expanding early-stage pipelines and investment in translational oncology research are expected to accelerate segment growth during the forecast period.
Study Design Insights
On the basis of study design, the interventional accounted for the largest revenue segment with a share of 76.5% in 2025, due to extensive evaluation of investigational immunotherapies across solid tumors and hematological malignancies. These studies involve controlled treatment administration, predefined clinical endpoints, and systematic assessment of therapeutic efficacy and safety. In addition, randomized protocols frequently require comparator arms, centralized laboratory testing, and independent data monitoring. Increasing investigation of novel drug combinations generates demand for specialized clinical operations and statistical analysis. Furthermore, regulatory requirements for demonstrating treatment benefits further sustain interventional research expenditure, maintaining the segment's dominant position in the market globally.
The observational segment is expected to record the fastest growth, driven by increasing demand for real-world evidence concerning immunotherapy effectiveness, treatment sequencing, and long-term patient outcomes. in addition, healthcare institutions are expanding prospective registries and retrospective database studies to evaluate immune-related adverse events and treatment durability. The electronic health records and oncology registries facilitate longitudinal assessment across heterogeneous patient populations. Whereas, growing interest in understanding outcomes among elderly patients and individuals with comorbidities supports observational research, creating opportunities for data analytics, epidemiological services, and post-treatment evidence generation activities.
Indication Insights
On the basis of indication, solid tumors segment accounted for the largest revenue share of 55.9% in 2025, supported by extensive clinical investigation across lung, melanoma, colorectal, renal, and gastrointestinal cancers. In addition, high disease prevalence and substantial therapeutic heterogeneity generate demand for multiple immunotherapy development programs. The ongoing clinical studies investigate treatment combinations targeting immune resistance within the tumor microenvironment. For instance, in October 2026, AbbVie received FDA Breakthrough Therapy Designations for telisotuzumab adizutecan in colorectal and lung cancers. Thus, expanding clinical research across earlier treatment settings contributes to sustained segment expenditure globally.
The hematological cancers segment is expected to register the fastest growth, supported by increasing clinical investigation of CAR-T therapies, bispecific antibodies, and other immune-directed treatments. Some of the clinical research involving leukemia, lymphoma, and multiple myeloma requires specialized cellular therapy centers and advanced hematological monitoring. In addition, clinical programs assess strategies addressing treatment resistance and relapse following established therapies. For instance, in June 2025, TuHURA Biosciences acquired Kineta, adding a VISTA-inhibiting antibody intended for further investigation in hematological malignancies. Expanding therapeutic pipelines support additional clinical research investment globally.
Therapy Insights
On the basis of therapy, immune checkpoint inhibitors accounted for the largest revenue share of 20.2% in 2025, due to extensive clinical development of PD-1, PD-L1, and CTLA-4 targeted therapies. In addition, established treatment efficacy across multiple cancers encourages investigation of additional indications, treatment combinations, and earlier disease stages. Pharmaceutical sponsors conduct large randomized studies assessing survival benefits and optimal treatment duration. The segment’s is growing due to research also examines resistance mechanisms and predictive biomarkers to improve treatment selection. In addition, broad clinical application, established development infrastructure, and continued investigation of combination regimens sustain substantial expenditure within this therapeutic segment globally.
Oncolytic virus therapies are anticipated to register the fastest growth over the forecast period of 2026-2033, driven by increasing investigation of genetically modified viruses capable of selectively targeting malignant cells and stimulating antitumor immunity. Besides this, clinical development focuses on improving intratumoral delivery, viral replication selectivity, and immune activation. The combination studies with checkpoint inhibitors seek to enhance responses in immunologically resistant tumors. Specialized manufacturing, viral shedding assessments, and biosafety monitoring contribute to distinctive research requirements. Advancements in viral engineering and increasing early-stage clinical investigations are expected to generate additional segment opportunities globally.
Sponsor Insights
On the basis of sponsor, pharmaceutical and biopharmaceutical companies accounted for the largest revenue share of 76.6% in 2025 and are anticipated to register the fastest growth over the forecast period. Their substantial development budgets support multicountry trials, advanced therapeutic platforms, and extensive clinical pipelines. Some of the companies increasingly pursue licensing agreements and acquisitions to access differentiated immunotherapy candidates. For instance, in June 2025, TuHURA Biosciences completed its acquisition of Kineta, expanding its immuno-oncology portfolio with a VISTA-targeting antibody. Increasing investment in proprietary clinical assets and strategic partnerships supports continued expansion of pharmaceutical-sponsored immunotherapy research programs globally.
Academic and research institutions are expected to register the second-fastest growth, due to expanding investigator-initiated studies and government-funded translational oncology programs. In addition, universities and specialized cancer centers investigate emerging immunological mechanisms, treatment resistance, and novel therapeutic combinations. Their research frequently addresses scientific questions outside immediate commercial development priorities. For instance, in January 2026, the Cancer Research Institute announced an AI-driven immuno-oncology initiative involving 10x Genomics technology. Increasing access to molecular profiling capabilities and collaborative research funding supports academic clinical investigation and segment growth.
Value Chain Insights
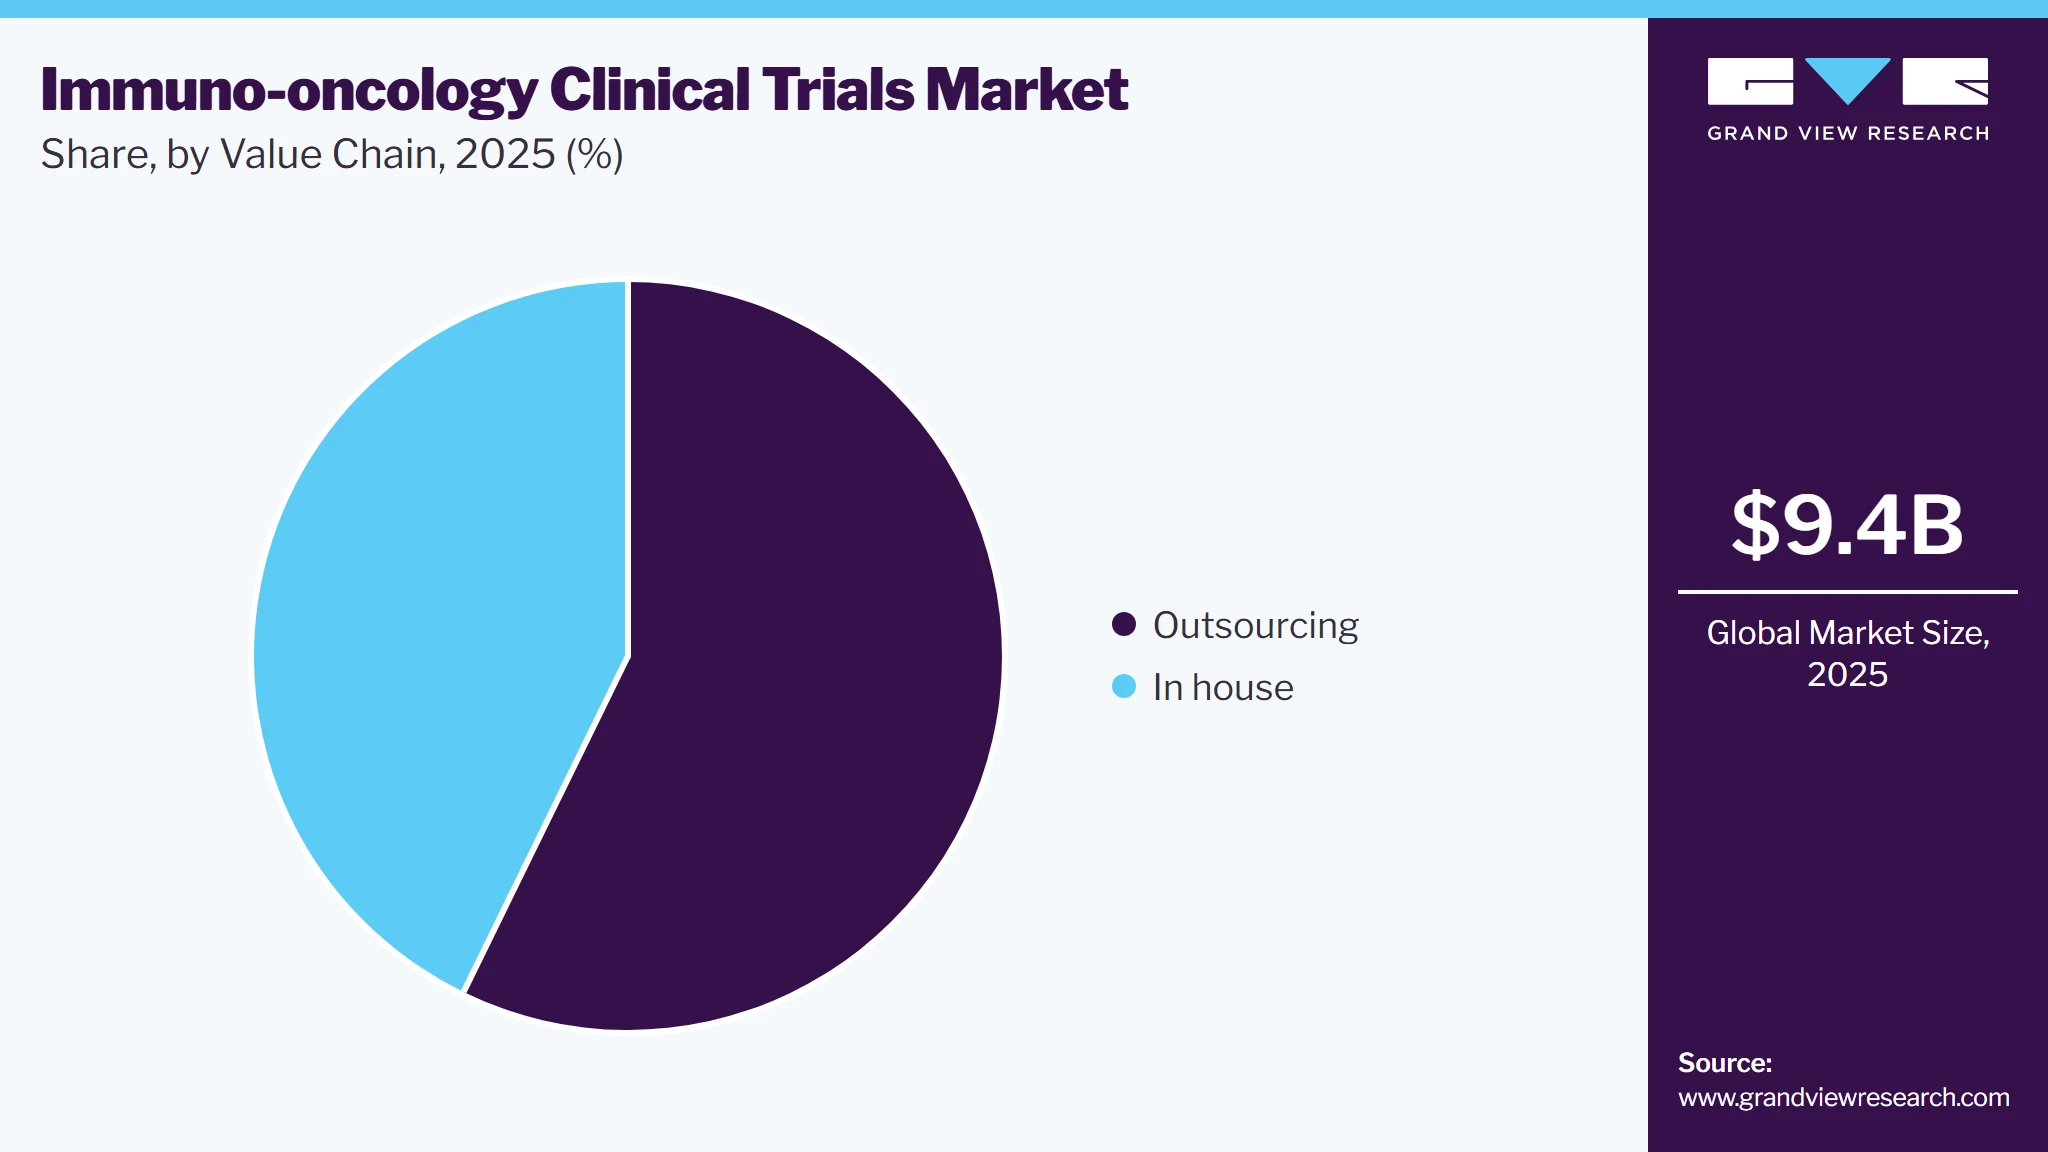
On the basis of value chain, the outsourcing segment accounted for the largest revenue share of 57.2% and is expected to register the fastest growth over the forecast period of 2026-2033, driven by increasing demand for specialized clinical research services. Pharmaceutical sponsors engage CROs for patient recruitment, site management, pharmacovigilance, data management, and regulatory coordination. Complex immunotherapy protocols require therapeutic expertise and geographically distributed clinical networks. Some of the key companies including IQVIA, ICON, and Medpace compete through oncology-focused operational capabilities. In addition, growing adoption of decentralized monitoring technologies and multinational trial execution supports outsourcing expenditure, particularly among biotechnology developers with limited internal infrastructure.
 To learn more about this report, Download Free Sample Report
The in-house segment is projected to register the second-fastest growth, supported by pharmaceutical companies maintaining direct control over strategically important clinical development activities. Internal teams manage protocol design, therapeutic strategy, clinical governance, and proprietary biomarker development. In addition, sponsors with established oncology infrastructure retain specialized capabilities for complex cellular therapies and confidential early-stage research. Whereas, direct coordination between clinical development and translational research teams facilitates timely scientific decisions. Continued investment in internal research platforms and clinical operations supports segment expansion, particularly among large pharmaceutical organizations worldwide.
Regional Insights
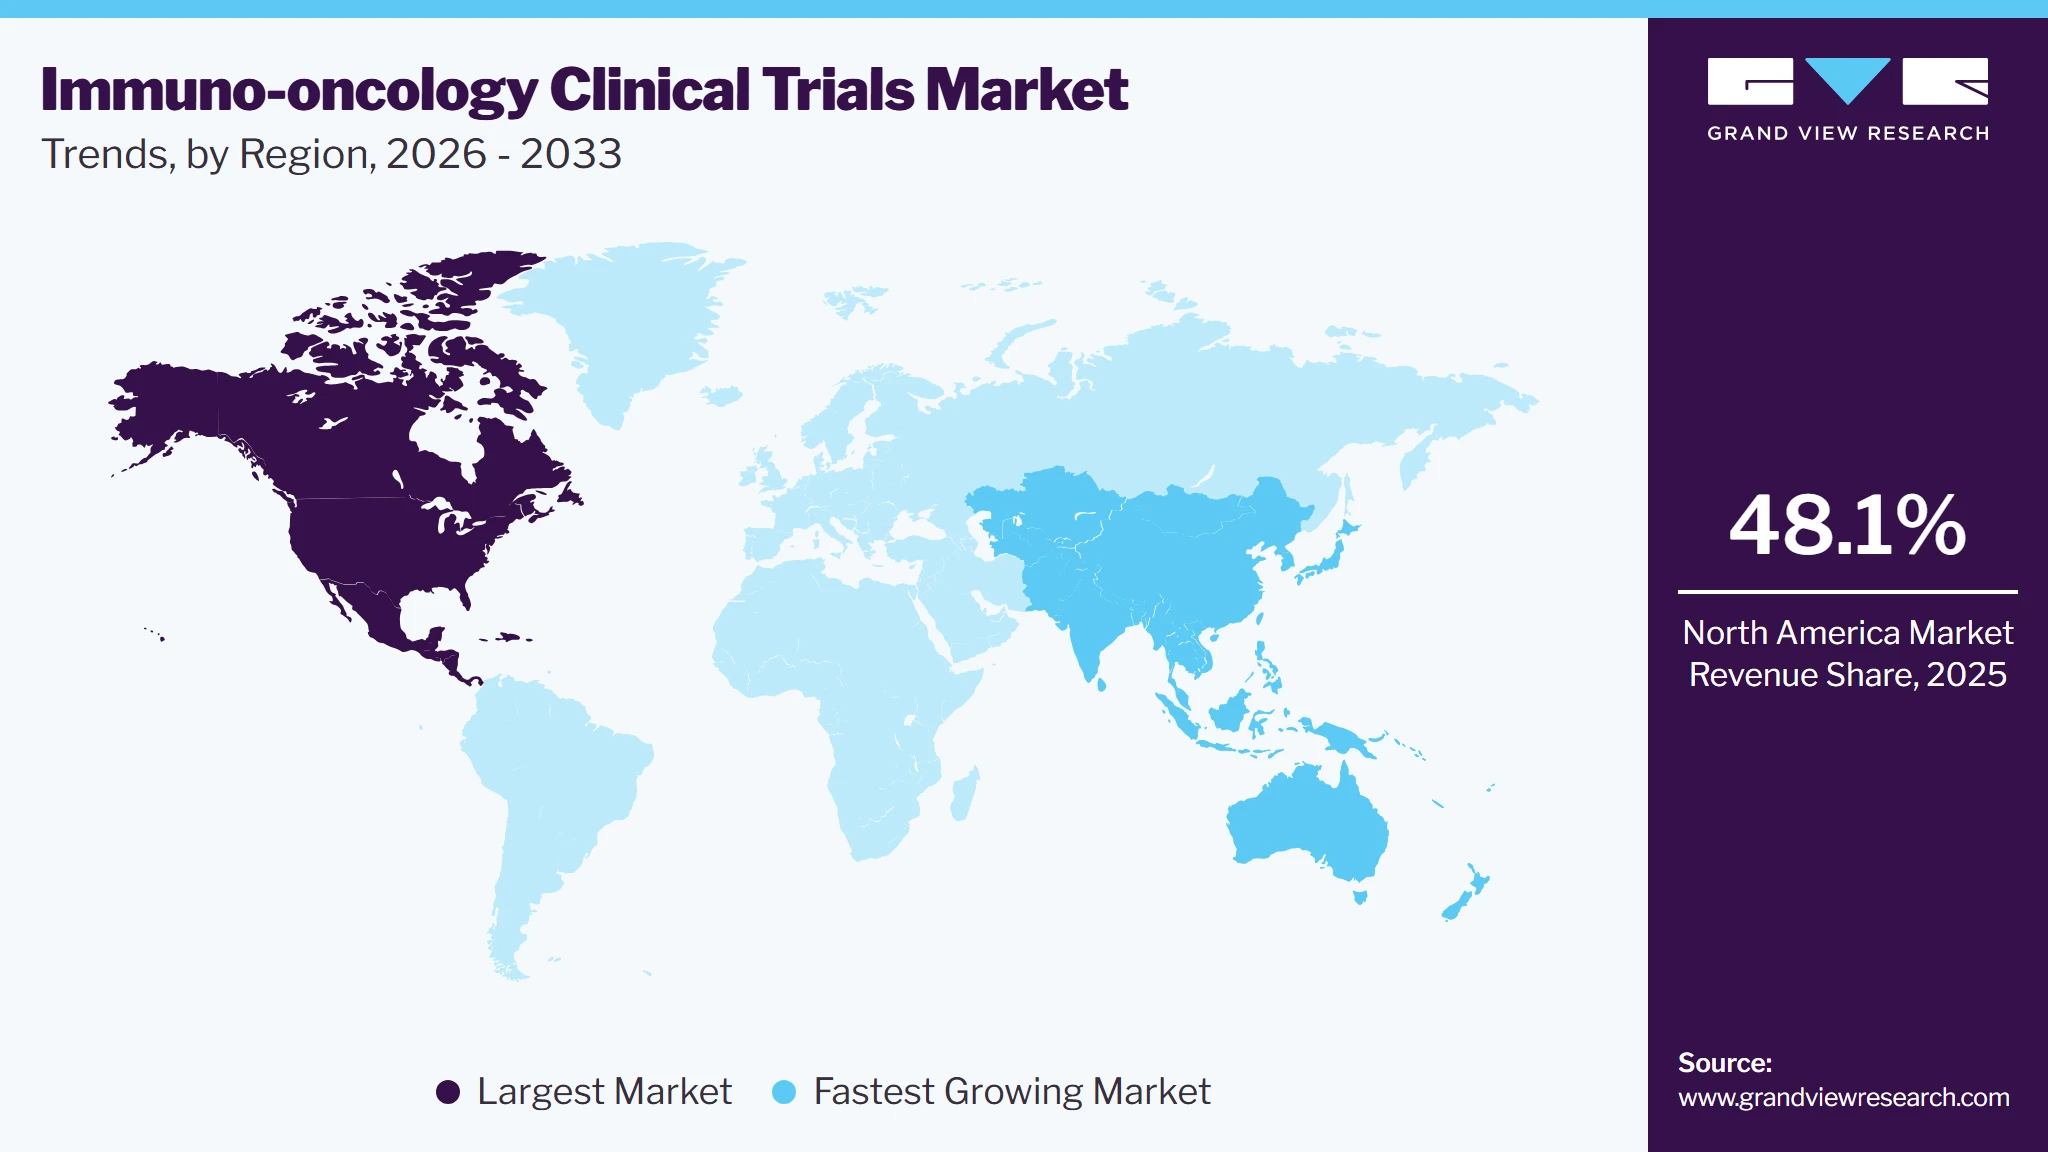
North America held the largest segment share of 48.1% in immuno-oncology clinical trials market in 2025, driven by high pharmaceutical research investment, established cancer centers, and early adoption of advanced immunotherapies. U.S. supports substantial clinical activity involving personalized cancer vaccines, checkpoint inhibitors, and adoptive cell therapies. Some of the major sponsors, such as Merck, Bristol Myers Squibb, and AstraZeneca, compete through differentiated pipelines, combination studies, and partnerships with specialized CROs. In addition, academic institutions contribute investigator-initiated research and biomarker development.
 To learn more about this report, Download Free Sample Report
U.S. immuno-oncology clinical trials market is driven by increasing biopharmaceutical R&D investment, rising research programs, and growing development of personalized cancer vaccines. In addition, leading cancer centers, including MD Anderson and Memorial Sloan Kettering, support early-phase clinical research and translational studies. The country is facing competition increasing on centers for biomarker-guided patient recruitment, differentiated therapeutic mechanisms, and specialized clinical trial execution capabilities across major oncology research networks nationwide. For instance, in October 2026, AbbVie received two FDA Breakthrough Therapy Designations for telisotuzumab adizutecan (Temab-A), an investigational c-Met-directed antibody-drug conjugate targeting colorectal cancer and non-small cell lung cancer.
The immuno-oncology clinical trials market in Canada benefits from publicly funded cancer research networks, provincial oncology programs, and increasing investigation of cellular immunotherapies. The country is advancing as multinational pharmaceutical sponsors collaborate with academic hospitals and specialized biotechnology developers. Such a coordinated cancer research infrastructure facilitates multicenter recruitment and translational research. In addition, growing interest in domestic cell therapy development creates opportunities for specialized clinical manufacturing, immune monitoring, and outsourced research services across provincial healthcare systems.
Europe Immuno-oncology Clinical Trials Market Trends
The immuno-oncology clinical trials market in Europe is supported by cross-border research networks, public oncology funding, and established pharmaceutical development centers. The increasing prevalence of various types of cancer, including melanoma, lung cancer, and breast cancer, is driving the demand for innovative and effective treatment options. Substantial investments in research and development by pharmaceutical and biotechnology companies in the region further accelerate this growth. In addition, competition involves biomarker-guided studies, bispecific antibodies, and multinational research partnerships.
UK immuno-oncology clinical trials marketheld a significant share in 2025. The country’s market growth is supported by the well-established research infrastructure, rising funding, and specialized early-phase oncology trial networks. NHS patient recruitment pathways facilitate studies investigating checkpoint inhibitors, therapeutic vaccines, and combination regimens. Key company such as, AstraZeneca maintains a significant competitive presence, while academic institutions and biotechnology companies advance novel immunotherapy candidates. Besides this, competition involves access to biomarker-characterized patient populations, clinical trial delivery capabilities, and translational research partnerships.
The immuno-oncology clinical trials market in Germany is anticipated to grow significantly over the forecast period. Germany benefits from established pharmaceutical research capabilities, specialized university hospitals, and growing investigation of mRNA-based cancer immunotherapies. In addition, Cancer Research Center in Germany collaborates support tumor immunology research and molecular patient characterization. The country is equipped with advanced laboratory infrastructure and molecular diagnostics capabilities facilitate complex immunotherapy studies, supporting demand for biomarker testing, clinical monitoring, and specialized research services across German oncology centers.
Asia Pacific Immuno-oncology Clinical Trials Market Trends
Asia Pacific immuno-oncology clinical trials market is expected to grow at fastest rate over the forecast period, driven by expanding biotechnology sector, specialized oncology research capabilities, and increasing clinical development activities. Besides this, domestic manufacturers compete through innovative checkpoint combinations, cell therapies, and partnerships with multinational pharmaceutical sponsors. In addition, regional CROs benefit from growing demand for patient recruitment and multicountry trial coordination.
The immuno-oncology clinical trials market in China is expected to grow over the forecast period. The growth of the market is due to expanding domestic biotechnology pipelines, substantial oncology patient populations, and increasing development of bispecific antibodies and checkpoint inhibitor combinations. In addition, domestic clinical research organizations support multicenter trial execution and patient recruitment. Besides this, increasing participation in multinational oncology programs creates opportunities for clinical data generation and specialized research services.
Japan's Immuno-oncology clinical trials market is witnessing significant growth over the forecast period. The growth of the market is due to established oncology research institutions, precision medicine initiatives, and increasing investigation of immunotherapies for gastric and other prevalent cancers. Some of the pharmaceutical companies such as Ono Pharmaceutical, Takeda, and Daiichi Sankyo participate in oncology development through domestic research programs and international collaborations. Furthermore, specialized cancer hospitals and established clinical research networks support complex studies, creating opportunities for targeted patient recruitment and advanced immunological assessment services.
India immuno-oncology clinical trials market is witnessing considerable growth supported by expanding oncology hospital networks, competitive clinical operating costs, and increasing availability of specialized cancer treatment centers. In addition, growing interest in affordable CAR-T therapies creates opportunities for domestic clinical development and academic collaboration. ImmunoACT and research institutions, including Tata Memorial Centre, contribute to cellular immunotherapy research. In addition, multinational pharmaceutical sponsors and domestic biotechnology developers compete through patient recruitment capabilities, clinical infrastructure, and cost-efficient research operations.
Latin America Immuno-oncology Clinical Trials Market
The immuno-oncology clinical trials market in Latin America is projected to grow over the forecast period. The region’s growth is supported by rising demand for broader access to investigational cancer treatments, competitive clinical operating costs, and recruitment opportunities across diverse patient populations. In addition, competition focuses on established hospital networks, recruitment capabilities, and CRO partnerships with international pharmaceutical companies. Furthermore, regulatory modernization may improve research planning and sponsor participation, supporting regional clinical development expenditure and market expansion.
The immuno-oncology clinical trials market in Brazil is driven by substantial cancer patient population, established oncology treatment institutions, and increasing participation in multinational pharmaceutical studies. In addition, growing demand for investigational cancer treatments creates opportunities for expanded clinical research partnerships and localized immunotherapy development programs.
Middle East and Africa Immuno-oncology Clinical Trials Market Trends
Middle East & Africa is developing and benefits from expanding oncology infrastructure, government healthcare investment, and increasing participation in international research programs. In addition, the countries are developing specialized cancer treatment capabilities and established clinical research institutions with diverse recruitment populations. In addition, competition involves multinational pharmaceutical sponsors, regional hospitals, and CROs seeking oncology trial partnerships.
South Africa immuno-oncology clinical trials market is witnessing growth due to established clinical research capabilities, diverse patient populations, and increasing demand for advanced cancer treatment options. In addition, limited access to advanced immunotherapies creates opportunities for clinical trial participation, while infrastructure disparities influence recruitment. In addition, growing oncology research collaborations support specialized trial services and clinical development expenditure.
Saudi Arabia immuno-oncology clinical trials market is driven by healthcare transformation initiatives, expanding oncology infrastructure, and government investment in biotechnology research. The country witnesses competitive activity through international pharmaceutical companies, domestic healthcare institutions, and emerging biotechnology partnerships. Furthermore, increasing investment in specialized cancer centers, clinical research infrastructure, and international collaborations creates opportunities for immunotherapy trial expansion and localized clinical development services. For instance, in February 2026, ImmunityBio partnered with Biopharma and Cigalah Healthcare to commercialize ANKTIVA in Saudi Arabia following SFDA approvals for bladder and lung cancer indications, expanding regional immunotherapy access.
Key Immuno-oncology Clinical Trials Company Insights
The immuno-oncology clinical trials market features established pharmaceutical companies, biotechnology developers, and CROs. Merck, Bristol Myers Squibb, Roche, AstraZeneca, and Novartis maintain significant clinical development portfolios. IQVIA, ICON, Medpace, and Syneos Health compete in outsourced trial services. Market positioning depends on therapeutic innovation, clinical capabilities, and strategic partnerships. For instance, in June 2025, TuHURA Biosciences completed its acquisition of Kineta, adding TBS-2025, a Phase II-ready VISTA-inhibiting monoclonal antibody targeting immunotherapy resistance, to its immuno-oncology development pipeline.
Key Immuno-oncology Clinical Trials Companies
The following key companies have been profiled for this study on the immune-oncology clinical trials market:
-
Medpace
-
Novartis AG
-
AstraZeneca
-
Syneos Health
-
BioNTech SE
-
IQVIA
-
ICON plc
-
Merck & Co., Inc.
-
Bristol-Myers Squibb Company
-
F. Hoffmann-La Roche Ltd.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Medpace
- Mature players in the immuno-oncology clinical trials market prioritize diversified therapeutic pipelines, strategic acquisitions, and multinational clinical development programs.
- Companies such as Merck, Roche, and Bristol Myers Squibb pursue combination immunotherapies, biomarker-driven trials, and academic collaborations. Partnerships with CROs support patient recruitment, operational efficiency, and specialized clinical research capabilities.
- Mature players benefit from substantial R&D budgets, established regulatory expertise, extensive clinical trial networks, and diversified immunotherapy portfolios. Their financial resources support large Phase III studies and complex multinational programs.
- Established relationships with oncology institutions, access to biomarker technologies, and experience managing regulatory submissions strengthen their competitive positioning globally.
- Mature players face substantial clinical development expenditure, lengthy trial timelines, and increasing competition from biotechnology companies developing differentiated immunotherapies.
- Large organizational structures can delay decision-making and protocol modifications.
Emerging Players- Syneos Health
- Emerging players in the immuno-oncology clinical trials market focus on developing differentiated therapeutic candidates, establishing collaborations, securing financing.
- Companies prioritize early-phase clinical studies, biomarker-driven patient selection, and strategic licensing agreements. Partnerships with specialized CROs and academic institutions facilitate clinical development while limiting internal infrastructure expenditure and operational complexity.
- They benefit from specialized therapeutic expertise, flexible research operations, and targeted development pipelines. Their focus on novel immune checkpoints, personalized cancer vaccines, and next-generation cellular therapies supports differentiation from established competitors. Smaller organizational structures facilitate faster decision-making, while collaborations with academic researchers provide access to specialized technologies and translational capabilities.
- Emerging players face financial constraints, limited clinical infrastructure, and dependence on external funding for trial execution.
- Smaller development portfolios increase exposure to clinical failures and regulatory setbacks.
Recent Developments:
-
In October 2026, Roche molecule Tecentriq received an FDA label expansion for stage III mismatch repair-deficient (dMMR) colon cancer, extending immunotherapy use into an earlier treatment setting. This development could stimulate additional clinical investigations involving adjuvant immunotherapy, biomarker-defined populations, and treatment combinations, supporting trial activity and expenditure across colorectal cancer research programs.
-
In September 2026, AstraZeneca highlighted patient-derived tumor models, Phase 0 studies, and AI-powered digital twins to improve immunotherapy response prediction and biomarker identification. These technologies could improve patient selection, support clinical trial design, and reduce unsuccessful development decisions, contributing to greater efficiency in the immuno-oncology clinical trials market.
-
In January 2026, the Cancer Research Institute partnered with 10x Genomics to develop AI-driven immuno-oncology datasets covering over 20,000 samples using single-cell and spatial technologies. This initiative could accelerate biomarker discovery, improve understanding of treatment resistance, and increase demand for molecular profiling and specialized clinical research services.
Immuno-oncology Clinical Trials Market Report Scope
Report Attribute
Details
Market size in 2025
USD 9.4 billion
Estimated market size in 2026
USD 10.6 billion
Projected market size by 2033
USD 21.0 billion
Growth rate
CAGR of 10.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Phase, study design, therapy, indication, sponsor, value chain, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar
Key companies profiled
Medpace; Novartis AG; AstraZeneca; Syneos Health; BioNTech SE; IQVIA; ICON plc; Merck & Co., Inc.; Bristol-Myers Squibb Company; F. Hoffmann-La Roche Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Immuno-oncology Clinical Trials Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global immuno-oncology clinical trials market based on phase, study design, therapy, indication, sponsor, value chain, and region.
-
Phase Outlook (Revenue, USD Million, 2021 - 2033)
-
Phase I
-
Phase II
-
Phase III
-
Phase IV
-
-
Study Design Outlook (Revenue, USD Million, 2021 - 2033)
-
Interventional
-
Observational
-
Expanded Access
-
-
Therapy Outlook (Revenue, USD Million, 2021 - 2033)
-
Adoptive Cell Therapies
-
Cancer Vaccines
-
Immune Checkpoint Inhibitors
-
Cytokine Based Therapies
-
Oncolytic Virus Therapies
-
Other Therapies
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Solid Tumors
-
Hematological Cancer
-
-
Sponsor Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceutical & Biopharmaceutical Companies
-
Academic & Research Institutions
-
Others
-
-
Value Chain Outlook (Revenue, USD Million, 2021 - 2033)
-
In-house
-
Outsourcing
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Oman
-
Qatar
-
-
Research Methodology
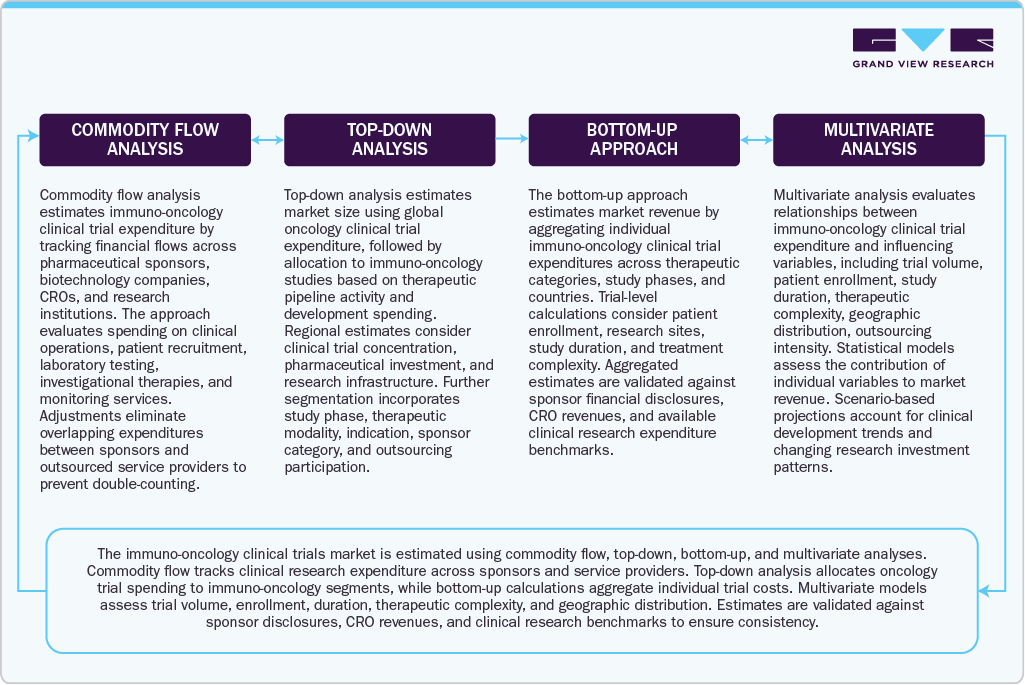
The immune-oncology clinical trials market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each immune-oncology clinical trials segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Phase
Revenue Capture Definitions
Phase I
It captures expenditure associated with initial human immuno-oncology trials, including dose escalation, safety assessments, pharmacokinetic studies, early efficacy evaluation, patient recruitment, clinical monitoring, laboratory testing, and trial management activities across sponsors.
Phase II
It captures expenditure generated through immuno-oncology trials evaluating preliminary therapeutic efficacy, dose optimization, safety profiles, biomarker responses, patient enrollment, clinical site operations, data management, regulatory compliance, and specialized research services globally.
Phase III
It captures expenditure associated with large scale immuno-oncology trials assessing comparative efficacy, treatment safety, survival outcomes, patient recruitment, multicenter operations, investigational therapies, clinical monitoring, statistical analysis, and regulatory submission activities worldwide.
Phase IV
It captures expenditure associated with postmarketing immuno-oncology clinical trials evaluating long term safety, therapeutic effectiveness, additional indications, treatment outcomes, patient monitoring, pharmacovigilance, observational assessments, and regulatory commitments following product approval globally.
Study Design
Revenue Capture Definitions
Interventional Trials
It captures expenditure from immuno-oncology studies involving assigned therapeutic interventions, including investigational drug administration, randomized treatment allocation, clinical procedures, patient recruitment, monitoring, biomarker testing, data collection, and trial management services worldwide.
Observational Trials
It captures expenditure associated with noninterventional immuno-oncology studies assessing treatment outcomes, real world effectiveness, safety patterns, patient characteristics, longitudinal followup, registry management, electronic health records, data analysis, and research coordination services globally.
Expanded Access Trials
It captures expenditure associated with expanded access programs providing investigational immuno-oncology therapies outside conventional trials, including patient eligibility assessments, treatment administration, safety monitoring, regulatory documentation, and program coordination activities across participating institutions.
Therapy
Revenue Capture Definitions
Adoptive Cell Therapies
It captures expenditure associated with clinical trials investigating CAR T cells, TCR engineered cells, tumor infiltrating lymphocytes, including cell processing, specialized manufacturing, patient conditioning, treatment administration, safety monitoring, and followup assessments.
Cancer Vaccines
It captures expenditure associated with clinical trials evaluating therapeutic cancer vaccines, including peptide, dendritic cell, mRNA, and DNA platforms, covering vaccine preparation, administration, immune response assessments, patient monitoring, and trial operations.
Immune Checkpoint Inhibitors
It captures expenditure associated with clinical trials investigating PD1, PDL1, CTLA4, and other checkpoint inhibitors, including drug administration, biomarker testing, patient recruitment, safety monitoring, efficacy assessments, and multicenter clinical operations globally.
Cytokine Based Therapies
It captures expenditure associated with clinical trials investigating interleukins, interferons, and engineered cytokine therapies, including investigational drug administration, immune response monitoring, toxicity management, laboratory assessments, patient recruitment, and clinical operations worldwide.
Oncolytic Virus Therapies
It captures expenditure associated with clinical trials investigating genetically modified or naturally occurring oncolytic viruses, including viral product preparation, administration, biosafety procedures, tumor response assessments, patient monitoring, and clinical research operations.
Other Therapies
It captures expenditure associated with clinical trials investigating bispecific antibodies, T cell engagers, innate immune agonists, macrophage targeted agents, and emerging immunomodulators, including administration, safety monitoring, biomarker testing, and research operations.
Indication
Revenue Capture Definitions
Solid Tumors
It captures expenditure associated with immuno-oncology clinical trials targeting solid malignancies, including lung, breast, colorectal, melanoma, and other cancers, covering investigational treatments, patient recruitment, tumor assessments, monitoring, and clinical research activities worldwide.
Hematological Cancer
It captures expenditure associated with immuno-oncology clinical trials targeting leukemia, lymphoma, multiple myeloma, and other hematological malignancies, including investigational treatments, specialized diagnostics, patient monitoring, safety assessments, and clinical research operations globally.
Sponsor
Revenue Capture Definitions
Pharmaceutical & Biopharmaceutical Companies
Captures clinical trial expenditure funded or managed by pharmaceutical and biotechnology companies developing immuno-oncology therapies, including internal research operations, outsourced clinical services, investigational treatments, regulatory activities, and trial management globally.
Academic & Research Institutions
Captures clinical trial expenditure managed by universities, academic hospitals, cancer centers, and research institutes conducting immuno-oncology studies, including investigator initiated research, patient recruitment, laboratory assessments, monitoring, and research coordination activities.
Others
Captures clinical trial expenditure managed by government agencies, nonprofit foundations, cooperative oncology research groups, patient advocacy organizations, and independent sponsors conducting immuno-oncology studies, including research administration, monitoring, and clinical operations globally.
Value Chain
Revenue Capture Definitions
In house
It captures expenditure on immuno-oncology clinical trial activities performed internally by sponsors, including protocol development, clinical operations, research personnel, data management, regulatory affairs, safety monitoring, and internal trial administration services globally.
Outsourcing
It captures revenue generated by external clinical research organizations and service providers delivering immuno-oncology trial activities, including patient recruitment, site management, laboratory testing, monitoring, data management, pharmacovigilance, and regulatory support services globally.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following in-depth customizations
Client Request
Customization Delivered
Value Adds
Therapy-Wise Clinical Pipeline and Competitive Assessment
It provides detailed assessment of adoptive cell therapies, cancer vaccines, immune checkpoint inhibitors, cytokine-based therapies, oncolytic virus therapies, and other emerging immunotherapies. Customization includes phase-wise pipeline distribution, therapeutic mechanisms, clinical indications, and competitive development activity across major pharmaceutical and biotechnology sponsors.
This enables identification of high-activity therapeutic categories, emerging clinical mechanisms, and potential areas of competitive differentiation. The analysis examines clinical development concentration across solid tumors and hematological malignancies, helping clients evaluate pipeline competition and therapeutic diversification opportunities. Sponsor-level comparisons support assessment of development priorities, strategic collaborations, and licensing prospects. Additional evaluation of combination immunotherapies and biomarker-directed treatment approaches helps clients identify areas attracting clinical investment, supporting portfolio planning, business development decisions, and therapeutic research prioritization.
Clinical Trial Cost Benchmarking and Expenditure Assessment
It provides development of customized clinical trial expenditure benchmarks across Phase I, Phase II, Phase III, and Phase IV studies. The assessment considers enrollment, trial duration, number of research sites, therapeutic modality, biomarker testing, investigational treatment requirements, and operational complexity, subject to available cost information
This supports clinical development budgeting, expenditure forecasting, and resource allocation across immuno-oncology research programs. Phase-wise and therapy-specific cost comparisons help identify major expenditure components, including patient recruitment, laboratory assessments, clinical monitoring, and specialized treatment administration. The analysis distinguishes reported trial expenditures from modeled estimates and identifies assumptions where direct financial information is unavailable. Clients can evaluate cost variation across therapeutic approaches and geographic locations, assess outsourcing economics, and develop more informed financial scenarios for clinical research investment, trial planning, and portfolio management decisions.
Country-Level Clinical Trial Landscape Assessment
It provides customized analysis of immuno-oncology clinical trial activity across the U.S., Canada, UK, Germany, China, Japan, India, Brazil, South Africa, and Saudi Arabia. The assessment covers Phase I–IV studies, recruitment status, therapeutic modalities, and sponsor participation using ClinicalTrials.gov records.
This provides country-specific insights into clinical development concentration, research infrastructure, patient recruitment opportunities, and competitive intensity. Identifies established and emerging clinical research destinations, enabling pharmaceutical sponsors and CROs to prioritize geographic expansion. Country-level comparisons help evaluate trial feasibility, site availability, and development opportunities. The analysis also examines differences in clinical research maturity and oncology capabilities, supporting informed decisions regarding multinational trial planning, regional partnerships, and allocation of clinical development resources across established and emerging markets.
Frequently Asked Questions About This Report
Based on phase, phase III segment held the largest market share of 54.2% in 2025.
The global immuno-oncology clinical trials market size was valued at USD 9.4 billion in 2025 and is estimated at USD 10.6 billion for 2026.
North America immuno-oncology clinical trials market held the largest share of 48.1% of the global market in 2025.
Asia Pacific is the fastest growing region in the market over the forecast period of 2026-2033.
Based on study design, interventional segment held the largest market share of 76.5% in 2025.
On the basis of therapy, immune checkpoint inhibitors accounted for the largest revenue share of 20.2% in 2025.
Some key players operating in the immuno-oncology clinical trials market include Medpace, Novartis AG, AstraZeneca, Syneos Health, BioNTech SE, IQVIA, ICON plc, Merck & Co., Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd.
Key factors that are driving the immuno-oncology clinical trials market growth include expanding clinical development of combination immunotherapies and novel therapeutic modalities, increasing adoption of biomarker-guided patient selection and precision oncology and growing pharmaceutical R&D investment and outsourcing of immuno-oncology clinical trials.
The global immuno-oncology clinical trials market is expected to grow at a CAGR of 10.3% from 2026 to 2033, reaching USD 21.0 billion by 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


