
- Home
- »
- IT Services & Applications
- »
-
Independent Software Vendors Market Report, 2026-2035GVR Report cover

Independent Software Vendors Market (2026 - 2035)
Size, Share & Trends Analysis Report By Deployment, By Enterprise Size (Large Enterprises and Small & Medium Enterprises (SMEs)), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$2.5BMarket Estimate, 2026
$2.9BMarket Forecast, 2035
$12.2BCAGR, 2026–2035
17.2%Independent Software Vendors Market Summary
The global independent software vendors (ISV) market size was valued at USD 2.5 billion in 2025 and is projected to grow from USD 2.9 billion in 2026 to USD 12.2 billion by 2035, at a CAGR of 17.2% from 2026 to 2035. North America dominated the market, accounting for the largest revenue share in 2025. The industry growth is driven by companies that develop, market, license, and support software applications that operate on third-party computing platforms, cloud infrastructure, and operating systems.
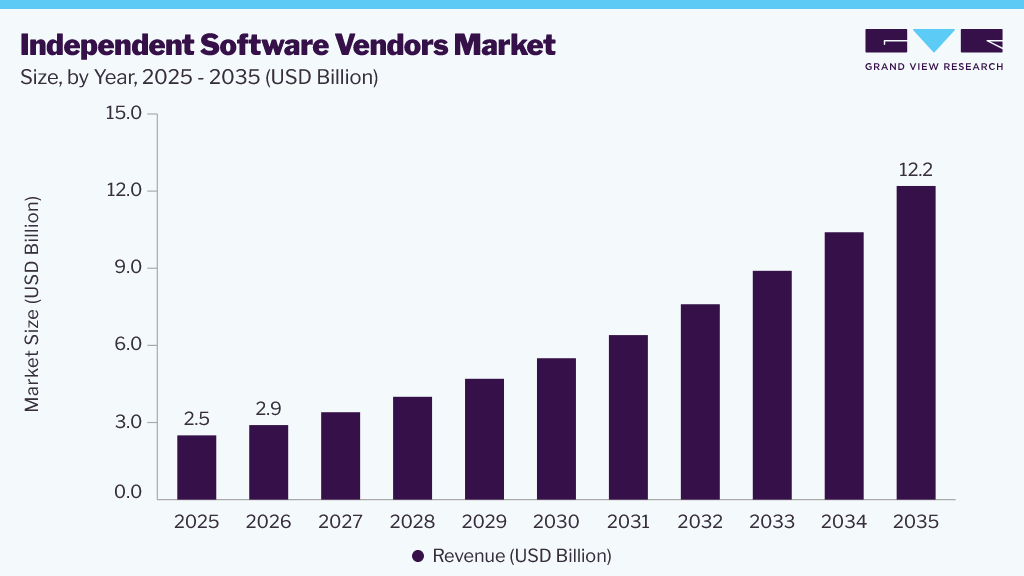 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By deployment: Cloud segment held the largest market share in 2025.
- By enterprise size: Large enterprise segment held the largest market share in 2025.
- By end use: Information technology & telecommunication segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (largest revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2035)
Market Size & Forecast
- Market size in 2025: USD 2.5 Billion
- Estimated market size in 2026: USD 2.9 Billion
- Projected market size by 2035: USD 12.2 Billion
- CAGR (2026-2035): 17.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2035 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The services offered by these providers include a wide range of enterprise and vertical-industry-oriented solutions, including customer relationship management (CRM), enterprise resource planning (ERP), cybersecurity, collaboration tools, analytics, human capital management, and artificial intelligence-powered applications. The growing shift toward cloud computing, SaaS, hybrid and multi-cloud architectures, and subscription-based software solutions has led to a much greater contribution by ISVs in helping enterprises modernize and achieve digital transformation. Collaboration with hyperscale cloud providers such as Microsoft Azure, Amazon Web Services (AWS), Google Cloud, Oracle Cloud Infrastructure, and Salesforce has enabled greater progress in software interoperability and global market reach.The market is projected to experience robust growth due to rising enterprise spending on AI, automation, big data analysis, cybersecurity, and low-code/no-code development environments. Cloud-first and AI-based software is increasingly adopted by enterprises in the BFSI, healthcare, manufacturing, retail, government, and education sectors to enhance operational efficiency and improve customer experience, regulatory compliance, and decision-making. ISVs are investing in automation, generative AI, cybersecurity, and data analytics to strengthen product differentiation and support new use cases.
Analyst Perspective
The global independent software vendors (ISV) market is experiencing steady growth, supported by increasing use of AI-enabled, cloud-native, and industry-specific software solutions. In addition, the movement toward traditional application development that embeds generative AI, automation, and advanced analytics into its offerings enables organizations to improve productivity and decision-making. Furthermore, alliances with hyperscale clouds are enabling ISVs to accelerate product adoption, expand into new markets, and generate recurring revenue through subscriptions. The development of the commercial marketplace by Microsoft and Salesforce's investments in AI-enabled partner ecosystems are clear indications that cloud platforms are emerging as vital growth drivers for ISVs.
Deployment Insights
The cloud segment held the largest market share in 2025. This dominance is driven by the increasing adoption of Software-as-a-Service (SaaS), hybrid and multi-cloud environments, and subscription-based software delivery models across enterprises. Cloud deployment enables independent software vendors to deliver scalable, continuously updated, and cost-efficient applications while reducing infrastructure management for customers. The widespread availability of cloud marketplaces offered by providers such as Microsoft Azure, Amazon Web Services (AWS), Google Cloud, and Oracle Cloud has further accelerated software distribution and customer acquisition.
Growing demand for AI-powered applications, remote collaboration, and API-driven integration continues to reinforce the cloud segment's leadership in the ISV market. For instance, in February 2025, Proximus Group selected Amazon Web Services (AWS) as its strategic cloud provider to accelerate the development and commercialization of AI-powered software solutions. As part of the collaboration, Proximus Global joined the AWS ISV Accelerate Program and plans to expand its Software-as-a-Service (SaaS) offerings through the AWS Partner Network and AWS Marketplace. This initiative enables faster deployment of cloud-native applications, strengthens API-based integrations, and creates new revenue opportunities for Independent Software Vendors (ISVs).
The on-premises segment is expected to grow at the fastest CAGR over the forecast period. Growth is primarily supported by organizations operating in highly regulated industries such as government, defense, banking, healthcare, and critical infrastructure, where stringent data sovereignty, security, and compliance requirements necessitate local software deployment. Many enterprises also continue to invest in modernizing existing on-premises environments by integrating AI capabilities, advanced analytics, and hybrid cloud architectures while retaining full control over sensitive business data. Furthermore, increasing concerns surrounding cybersecurity, regulatory compliance, and low-latency application performance are expected to sustain demand for on-premises software deployments throughout the forecast period.
Enterprise Size Insights
The large enterprise segment held the largest market share in 2025. This dominance is attributed to the extensive adoption of enterprise software for managing complex business operations, large-scale digital transformation initiatives, and substantial investments in cloud computing, artificial intelligence (AI), cybersecurity, and data analytics. Large organizations increasingly rely on ISVs to deliver scalable, integrated, and industry-specific software solutions that enhance operational efficiency, regulatory compliance, and customer engagement. Furthermore, the growing adoption of multi-cloud environments, enterprise-wide automation, and AI-driven decision-making platforms continues to strengthen demand for advanced ISV solutions among large enterprises.
The small and medium enterprises (SMEs) segment is expected to grow at the fastest CAGR over the forecast period. The growth is driven by the increasing affordability and accessibility of cloud-based Software-as-a-Service (SaaS) solutions, enabling SMEs to deploy enterprise-grade applications without significant upfront infrastructure investments. Rising digitalization, expanding e-commerce activities, and growing awareness of AI-enabled business applications are encouraging SMEs to adopt software for customer relationship management, financial management, collaboration, and workflow automation. In addition, flexible subscription-based pricing models, rapid implementation capabilities, and increasing support from cloud providers and ISV partner ecosystems are expected to accelerate software adoption among SMEs throughout the forecast period.
End Use Insights
The information technology & telecommunication segment held the largest market share in 2025, driven by the continuous demand for cloud-native applications, enterprise software, cybersecurity solutions, collaboration platforms, and AI-powered automation tools to support digital transformation initiatives. The deployment of 5G networks, expansion of hybrid and multi-cloud environments, and investments in AI, data analytics, and edge computing are further increasing demand for scalable, API-enabled, and cloud-based ISV solutions. For instance, in June 2025, Google Cloud and Ericsson announced Ericsson On-Demand, a cloud-native 5G Core-as-a-Service platform that enables communication service providers to deploy and scale 5G core services using Google Cloud infrastructure and Google Kubernetes Engine (GKE).
The healthcare segment is expected to register the fastest CAGR over the forecast period, supported by the digitalization of healthcare systems and the rising adoption of EHRs, telehealth, AI-assisted diagnostics, remote patient monitoring, and cloud-based healthcare solutions. Increasing investments in interoperable health information systems and connected healthcare ecosystems are creating opportunities for ISVs to improve clinical workflows, patient engagement, and operational efficiency. For instance, in June 2025, Oracle announced the general availability of Oracle Health Community Care, a cloud-based mobile extension of Oracle Health Foundation EHR that enables healthcare professionals to access and update patient records across home, mobile, and rural care settings, including areas with limited or no network connectivity.
Regional Insights
The North America independent software vendors (ISV) market accounted for the largest revenue share in 2025, driven by the strong presence of global software vendors, hyperscale cloud providers, and a mature enterprise IT ecosystem. Significant investments in cloud computing, artificial intelligence (AI), cybersecurity, and digital transformation initiatives have accelerated the adoption of enterprise software across industries such as BFSI, healthcare, manufacturing, retail, and government facilities. Furthermore, the widespread adoption of Software-as-a-Service (SaaS), advanced developer ecosystems, and strategic collaborations between ISVs and cloud platform providers such as Microsoft, Amazon Web Services (AWS), Google Cloud, and Oracle continue to strengthen the region's market position.
Ongoing innovation in generative AI, cloud-native applications, and enterprise automation is expected to sustain North America's dominance throughout the forecast period. In March 2025, NVIDIA announced the NVIDIA AI Data Platform at its GTC 2025 conference. The platform provides a customizable reference design that enables enterprise infrastructure providers to build AI infrastructure for generative AI inference using NVIDIA accelerated computing, networking, and enterprise software. The solution supports cloud-native AI applications, intelligent automation, and real-time enterprise data processing.
Asia Pacific Independent Software Vendors (ISV) Market Trends
The independent software vendors (ISV) market in the Asia Pacific is expected to grow at the fastest CAGR over the forecast period. The region’s growth is fueled by rapid digital transformation, expanding cloud infrastructure, increasing adoption of AI-powered enterprise applications, and accelerating investments in smart manufacturing and digital government initiatives. Countries such as China, India, Japan, South Korea, Singapore, and Australia are witnessing rising demand for cloud-based business software as organizations modernize legacy IT systems and embrace digital-first operating models.
In addition, supportive government policies promoting digital economies, the rapid expansion of small and medium-sized enterprises (SMEs), increasing adoption of public cloud services, and the emergence of regional technology startups are creating significant growth opportunities for independent software vendors across the Asia Pacific region. For instance, in May 2024, Amazon Web Services (AWS) announced an additional SGD 12 billion investment in Singapore’s cloud infrastructure through 2028 and launched the AWS AI Spring Singapore initiative. As part of the initiative, AWS signed a Memorandum of Understanding (MoU) with Singapore’s national health technology agency, Synapxe, to accelerate AI adoption in the public sector, and a Memorandum of Intent (MoI) with the Infocomm Media Development Authority (IMDA) to help local enterprises adopt generative AI using Amazon Bedrock, Amazon SageMaker, and Amazon Q. These initiatives are strengthening the cloud and AI ecosystem and creating opportunities for ISVs to develop AI-enabled and cloud-based solutions.
Key Independent Software Vendors Company Insights
The independent software vendors (ISV) industry features a range of global, regional, and local players, making it a competitive market. Leading market players are using partnerships, collaborations, acquisitions, mergers, and agreements as strategies to withstand the intense competition and increase their market share.
Key Independent Software Vendors Companies
The following key companies have been profiled for this study on the independent software vendors market:
-
Microsoft
-
Oracle
-
Salesforce, Inc.
-
SAP SE
-
Intuit Inc.
-
ServiceNow
-
Workday, Inc.
-
Atlassian
-
Zoom Communications, Inc.
-
HubSpot, Inc.
Recent Developments
-
In September 2025, Microsoft launched the reimagined Microsoft Marketplace, unifying Azure Marketplace and Microsoft AppSource into a single platform for cloud solutions, AI applications, and agents. The update introduced enhanced solution discoverability, simplified purchasing, expanded channel and reseller opportunities, and new commercialization capabilities for partners, enabling ISVs to reach enterprise customers more efficiently and expand their software distribution and revenue opportunities.
-
In May 2025, Salesforce announced an agreement to acquire Informatica for approximately USD 8 billion in equity value, net of Salesforce’s existing investment. The acquisition is intended to combine Informatica’s cloud data management, governance, metadata management, data integration, and Master Data Management (MDM) capabilities with Salesforce’s AI-powered CRM platform, creating a trusted data foundation for enterprise AI applications.
-
In March 2025, Oracle launched Oracle AI Agent Studio for Fusion Applications, a platform that enables customers and partners to create, customize, deploy, and manage AI agents for enterprise workflows. The solution allows Oracle partners and software vendors to build industry-specific AI agents that integrate with Oracle Fusion Cloud Applications, supporting the development of specialized AI capabilities and expanding opportunities within the enterprise software ecosystem.
Independent Software Vendors Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.5 billion
Estimated market size in 2026
USD 2.9 billion
Projected market size by 2035
USD 12.2 billion
Growth rate
CAGR of 17.2% from 2026 to 2035
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2035
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2035
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Deployment, enterprise size, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Microsoft; Oracle; Salesforce, Inc.; SAP SE; Intuit Inc.; ServiceNow; Workday, Inc.; Atlassian Corporation; Zoom Communications, Inc.; HubSpot, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Independent Software Vendors Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2035. For this study, Grand View Research has segmented the global independent software vendors market report based on deployment, enterprise size, end use, and region:
-
Deployment Outlook (Revenue, USD Billion, 2021 - 2035)
-
On-Premise
-
Cloud
-
-
Enterprise Size Outlook (Revenue, USD Billion, 2021 - 2035)
-
Large Enterprise
-
Small & Medium Enterprise (SEMs)
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2035)
-
Information Technology & Telecommunication
-
Banking, Financial Services, and Insurance (BFSI)
-
Healthcare
-
Others
-
Regional Outlook (Revenue, USD Billion, 2021 - 2035)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
France
-
Germany
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia & New Zealand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
South Africa
Saudi Arabia
UAE
-
-
Frequently Asked Questions About This Report
The global independent software vendors market size was valued at USD 2.5 billion in 2025 and is estimated at USD 2.9 billion for 2026.
The global independent software vendors market is expected to grow at a CAGR of 17.2% from 2026 to 2035, reaching USD 12.2 billion by 2035.
North America dominated with the largest revenue share in 2025.
The cloud segment accounted for the largest revenue share in 2025.
Key players in the market include Microsoft, Oracle, Salesforce, Inc., SAP SE, Intuit Inc., ServiceNow, Workday, Inc., Atlassian Corporation, Zoom Communications, Inc., and HubSpot, Inc., and others.
About the Author(s)
IT Services & Applications Research Team
Technology · IT Services & ApplicationsThis report was authored by the it services & applications research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the it services & applications segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


