
- Home
- »
- Pharmaceuticals
- »
-
India GLP-1 Receptor Agonist Market Size Report, 2026-2033GVR Report cover

India GLP-1 Receptor Agonist Market (2026 - 2033) Size, Share & Trends Analysis Report By Product (Semaglutide, Tirzepatide, Dulaglutide), By Application (Type 2 Diabetes Mellitus, Cardiovascular Risk), By Route Of Administration, By Distribution Channel, And Segment Forecasts
India GLP-1 Receptor Agonist Market Summary
The India GLP-1 receptor agonist market size was valued at USD 150.8 million in 2025 and is projected to grow from USD 240.5 million in 2026 to USD 1,004.9 million by 2033, at a CAGR of 22.7% from 2026 to 2033. The market is witnessing strong expansion, driven by the rising prevalence of type 2 diabetes and obesity, alongside increasing clinical adoption of advanced incretin-based therapies. Semaglutide and dulaglutide remain the most widely prescribed molecules, supported by established efficacy in glycemic control and weight reduction benefits.
Key Market Trends & Insights
- By product, the semaglutide (ozempic, wegovy, rybelsus) segment held the largest market share of 59.2% in 2025.
- By application, the type 2 diabetes mellitus (T2DM) segment held the largest market share in 2025.
- By route of administration, the oral segment held the largest market share in 2025.
- By distribution channel, the hospital pharmacies segment held the largest market share in 2025.
Market Size & Forecast
- 2025 Market Size: USD 150.8 Million
- 2026 Market Size: USD 240.5 Million
- 2033 Projected Market Size: USD 1,004.9 Million
- CAGR (2026-2033): 22.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Urban healthcare centers and endocrinology-led clinics account for the majority of prescriptions, as awareness of metabolic disease management improves across Tier 1 and Tier 2 cities. Building on this expanding demand base, competitive dynamics in the India GLP-1 market are intensifying with the presence of both multinational innovators and domestic pharmaceutical companies. Novo Nordisk and Eli Lilly maintain a strong position through semaglutide and tirzepatide offerings, particularly in premium urban segments. At the same time, Indian companies such as Sun Pharma, Dr. Reddy’s Laboratories, Cipla, and Biocon are actively strengthening their presence through biosimilar development and anticipated post-patent entry strategies. This competitive environment is expected to significantly reshape pricing structures, especially as semaglutide patent protections approach expiry in India. Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The India GLP-1 receptor agonist market is expected to transition toward broader accessibility and volume-driven growth, particularly in the post-patent period. Tirzepatide is emerging as a key growth driver due to its dual GIP and GLP-1 mechanism, offering enhanced weight-loss outcomes compared to traditional therapies. Meanwhile, expanding awareness of obesity as a chronic disease is gradually increasing uptake beyond diabetes-focused treatment, particularly in urban private-pay segments. Price reductions anticipated from generic semaglutide entries are expected to further accelerate market penetration across Tier 2 and Tier 3 cities. Overall, the market is evolving from a specialist-driven niche therapy space into a more mainstream metabolic treatment category, supported by stronger physician adoption, improving affordability, and widening patient eligibility across India’s healthcare system.
Market Dynamics
The rising prevalence of type 2 diabetes and obesity significantly drove the growth of the India GLP-1 Receptor Agonist Market. Increasing urbanization, unhealthy dietary habits, sedentary lifestyles, and reduced physical activity have raised the incidence of metabolic disorders across the country. GLP-1 receptor agonists gained strong adoption due to their effectiveness in glycemic control and weight management. Growing awareness regarding obesity-related complications, including cardiovascular diseases and hypertension, further accelerated market demand. Additionally, increasing physician recommendations and expanding diabetes care infrastructure supported the adoption of advanced therapies in India. For instance, in March 2025, Eli Lilly had launched Mounjaro (tirzepatide) in India after receiving regulatory approval. The report highlighted that India had nearly 101 million people living with diabetes, while Mounjaro was introduced at a monthly cost of INR 14,000 to INR 17,500 (approximately USD 168 to USD 210), depending on dosage strength, demonstrating the growing commercial potential of GLP-1 receptor agonist therapies in India.
The high cost of GLP-1 receptor agonist therapies remained a significant restraint for the India GLP-1 Receptor Agonist Market. Although the prevalence of diabetes and obesity continued to rise, the premium pricing of advanced injectable therapies limited accessibility among middle-income and rural populations. Long-term treatment dependency, high out-of-pocket healthcare expenditure, and limited reimbursement coverage further restricted widespread adoption across the country. In addition, unequal access to specialty endocrinology and obesity care centers constrained market penetration in semi-urban and rural regions. Patients often faced affordability challenges due to the recurring monthly costs of GLP-1 therapies. For instance, in June 2025, the Novo Nordisk Wegovy India Launch Report reported that Novo Nordisk had launched Wegovy in India, where the 1.7 mg monthly dose was priced at INR 24,280 (approximately USD 284), and the 2.4 mg dose cost INR 26,015 (approximately USD 304), highlighting affordability concerns in India’s price-sensitive healthcare market.
The increasing focus on obesity management and preventive healthcare created significant growth opportunities for the India GLP-1 Receptor Agonist Market. Rising awareness regarding obesity-related complications, including cardiovascular diseases, hypertension, and metabolic disorders, encouraged greater adoption of advanced weight management therapies. Increasing physician acceptance of GLP-1 receptor agonists for chronic weight control and growing investments by pharmaceutical companies further supported market expansion. Additionally, expanding access to innovative therapies, improving healthcare infrastructure, and rising demand for personalized obesity treatment solutions strengthened commercial opportunities across India. The growing popularity of medically supervised weight-loss programs and the increasing consumer preference for effective, long-term metabolic health management are expected to accelerate market growth. Furthermore, the expansion of private healthcare facilities and increasing penetration of specialty diabetes and obesity clinics are likely to create favorable conditions for GLP-1 receptor agonist manufacturers operating in India’s evolving healthcare sector.
Market Concentration & Characteristics
The India GLP-1 receptor agonist market is characterized by a moderate to high degree of innovation, largely driven by global advancements in incretin-based therapies, including next-generation molecules such as semaglutide and tirzepatide. Key innovations, particularly once-weekly and emerging oral formulations, are improving treatment convenience and supporting broader adoption in urban patient segments. The development of dual- and multi-receptor agonists reflects a global shift toward enhanced weight-loss and cardiometabolic outcomes, which is gradually influencing clinical practice in India. While domestic pharmaceutical companies are increasingly investing in peptide synthesis and complex formulation capabilities in anticipation of patent expiries, much of the near-term innovation remains externally driven. Overall, innovation continues to shape competitive positioning and future growth potential, although India’s role is currently more aligned with adoption and manufacturing scale-up rather than early-stage molecule development.
The industry presents moderate to high barriers to entry due to patent protection surrounding key molecules such as semaglutide and tirzepatide, which currently limit generic competition. The development and manufacturing of peptide-based therapies involve significant R&D complexity, specialized production capabilities, and stringent regulatory approval requirements. In addition, companies must invest in cold-chain logistics and distribution infrastructure, particularly for injectable formulations. Strong physician preference for established multinational brands, along with specialist-driven prescribing patterns, further increases entry challenges for new participants. However, India’s expanding biopharmaceutical manufacturing capabilities and anticipated patent expiries may gradually improve opportunities for domestic manufacturers over the forecast period.
 To learn more about this report, Download Free Sample Report
The India GLP-1 receptor agonist industry is shaped by a multi-layered regulatory framework governed primarily by the Central Drugs Standard Control Organization (CDSCO), which oversees approval pathways for peptide-based and injectable metabolic therapies. Regulatory expectations around clinical efficacy, safety validation, and Good Manufacturing Practice (GMP) compliance contribute to extended development and approval timelines, particularly for novel entrants and complex biologic-like molecules. In parallel, intellectual property protection for key GLP-1 molecules such as semaglutide and tirzepatide plays a critical role in delaying immediate generic or biosimilar entry, thereby sustaining a concentrated competitive environment in the near term. Pricing controls by India’s National Pharmaceutical Pricing Authority (NPPA), especially for essential diabetes medicines, can further affect affordability and limit pricing flexibility post-launch. Collectively, these regulatory and policy mechanisms ensure high standards of product quality and patient safety while simultaneously shaping market structure by influencing entry timing, competitive intensity, and the pace of broader patient access.
The market faces moderate substitution pressure from established diabetes therapies such as metformin, SGLT2 inhibitors, insulin, and DPP-4 inhibitors, which remain widely used due to lower cost and strong clinical familiarity. In obesity management, lifestyle interventions and bariatric surgery also serve as important non-pharmacologic substitutes in selected patient groups. These alternatives are preferred in many cases due to affordability and long-standing treatment experience, particularly in cost-sensitive segments. However, GLP-1 receptor agonists are gaining traction owing to their differentiated benefits in both glycemic control and weight reduction, which are not fully addressed by traditional therapies. As clinical awareness and guideline adoption increase in India, substitution is gradually shifting toward GLP-1 agents, although price sensitivity continues to limit broader uptake.
The India GLP-1 receptor agonist market exhibits moderate end-user concentration, primarily driven by specialist-led prescribing patterns in endocrinology and diabetology care. Demand is largely concentrated within urban tertiary care hospitals, private multi-specialty hospitals, and specialized diabetes clinics, which collectively account for the majority of GLP-1 prescriptions. End-users are predominantly endocrinologists and internal medicine specialists, reflecting the need for clinical expertise in managing complex metabolic conditions. Patient adoption is currently skewed toward high-income and urban populations, given the premium pricing of GLP-1 therapies. However, gradual expansion into Tier 2 cities and corporate hospital networks is broadening the end-user base. Overall, while access is expanding, prescribing and consumption remain relatively concentrated within specialist-driven urban healthcare ecosystems.
Product Insights
The semaglutide (ozempic, wegovy, rybelsus) segment dominated the market with the largest revenue share of 59.2% in 2025, supported by its strong clinical efficacy in improving glycemic control and promoting significant weight loss among patients with type 2 diabetes and obesity. Increasing physician preference for advanced GLP-1 therapies, rising awareness regarding obesity management, and expanding diagnosis rates of metabolic disorders contributed to segment growth. The availability of once-weekly injectable formulations and oral options such as Rybelsus improved patient convenience and treatment adherence. In addition, rising healthcare expenditure, increasing urban obesity prevalence, and the growing adoption of innovative diabetes therapies across private healthcare facilities supported market expansion. Favorable clinical trial outcomes and strong brand recognition further strengthened semaglutide’s leading market position in India.
The tirzepatide (mounjaro, zepbound) segment is projected to grow at the fastest CAGR of 28.4% over the forecast period, fueled by its dual GIP and GLP-1 receptor agonist mechanism, which delivers enhanced glycemic control and superior weight reduction compared to conventional GLP-1 therapies. Rising prevalence of obesity and type 2 diabetes in India, increasing demand for advanced metabolic disorder treatments, and growing physician interest in next-generation incretin therapies are expected to support market growth. Expanding awareness regarding obesity management, improving access to innovative biologics, and favorable clinical trial outcomes demonstrating significant cardiovascular and metabolic benefits are further accelerating adoption. In addition, increasing healthcare expenditure, rising penetration of private specialty clinics, and anticipated product availability across major urban markets are expected to strengthen the segment’s growth trajectory during the forecast period.
Application Insights
The type 2 diabetes mellitus (T2DM) segment dominated the market with the largest revenue share of 92.6% in 2025, driven by the country’s rising diabetic population and increasing adoption of incretin-based therapies in clinical practice. GLP-1 receptor agonists are increasingly used as adjunct treatments to traditional antidiabetic therapies due to their dual benefits in glycemic control and weight reduction. The segment remains primarily concentrated in urban tertiary care hospitals and endocrinology-led clinics, where specialist-driven prescribing dominates. Recent developments indicate an emerging shift toward improved patient convenience and expanded access through novel formulations. For instance, in April 2026, Dr. Reddy’s Laboratories launched an oral semaglutide formulation in India, signaling early movement toward more patient-friendly GLP-1 delivery formats in T2DM management. Overall, the segment remains the primary demand driver of the GLP-1 market in India, supported by a large untreated patient pool and evolving treatment paradigms.
The cardiovascular risk segment is projected to grow at a CAGR of 42.3% over the forecast period, supported by the increasing prevalence of cardiovascular diseases among patients with type 2 diabetes and obesity in India. Growing clinical evidence demonstrating the cardiovascular benefits of GLP-1 receptor agonists, including reduction in major adverse cardiovascular events, is driving physician confidence and adoption. Rising awareness of preventive cardiometabolic care, increasing demand for therapies with multi-benefit outcomes, and expanding recommendations in clinical treatment guidelines are further driving segment growth. In addition, the growing geriatric population, sedentary lifestyles, unhealthy dietary habits, and increasing incidence of hypertension and dyslipidemia are accelerating demand for advanced diabetes therapies with cardiovascular protection benefits. Expanding access to innovative biologics and rising healthcare expenditure are also expected to support market expansion.
Route Of Administration Insights
The oral segment dominated the market with the largest revenue share of 59.2% in 2025, driven by increasing patient preference for non-invasive treatment options and improved convenience of oral formulations. The growing adoption of oral semaglutide therapies, particularly among patients reluctant to use injectable medications, significantly supported segment growth. Rising prevalence of type 2 diabetes, increasing awareness regarding early disease management, and improving access to advanced oral anti-diabetic therapies further accelerated demand. In addition, enhanced patient adherence, ease of administration, and reduced dependency on clinical supervision contributed to wider acceptance across urban healthcare settings. Expanding physician recommendations, strong commercial availability, and increasing healthcare expenditure also supported market penetration. Favorable clinical outcomes demonstrating effective glycemic control and weight management further strengthened the oral segment’s leading position in India.
The injectable / parenteral segment is projected to grow at a significant CAGR of 18.1% during the forecast period, driven by the increasing adoption of highly effective injectable GLP-1 receptor agonists for the treatment of type 2 diabetes and obesity. Strong clinical efficacy in glycemic control, substantial weight reduction outcomes, and growing physician preference for long-acting injectable therapies are supporting segment expansion. The rising prevalence of obesity-related metabolic disorders, increasing awareness regarding advanced diabetes management, and expanding availability of once-weekly injectable formulations are further accelerating demand. In addition, favorable clinical trial results demonstrating cardiovascular and metabolic benefits, along with increasing recommendations in treatment guidelines, are contributing to market growth. Improving healthcare infrastructure, rising healthcare expenditure, and growing penetration of specialty diabetes and obesity clinics across urban India are also expected to strengthen the segment’s growth trajectory.
Distribution Channel Insights
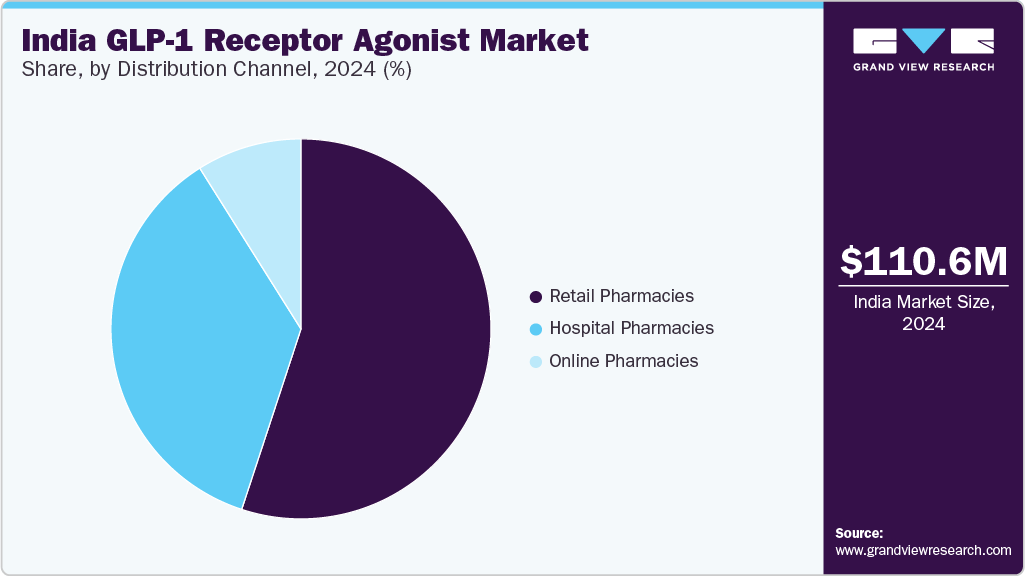
The hospital pharmacies segment dominated the market, accounting for the largest revenue share of 58.9% in 2025, primarily driven by the increasing number of patients seeking diabetes and obesity treatment at hospitals and specialty care centers. Strong availability of prescription-based GLP-1 therapies, access to endocrinologists and diabetes specialists, and growing preference for supervised treatment management contributed significantly to segment growth. Hospital pharmacies also benefit from greater patient trust, improved access to medications, and integrated disease management services. In addition, rising hospitalization rates associated with obesity-related complications, cardiovascular disorders, and uncontrolled diabetes supported prescription volumes through hospital channels. Expanding healthcare infrastructure, increasing adoption of advanced biologic therapies, and growing collaborations between hospitals and pharmaceutical companies further strengthened the segment’s leading position. Improved access to reimbursement and patient counseling services also contributed to sustained market demand.
 To learn more about this report, Download Free Sample Report
The online pharmacies segment is projected to grow at the fastest CAGR of 26.2% over the forecast period, supported by the rapid adoption of digital healthcare platforms and telemedicine services. This channel primarily facilitates prescription fulfillment and repeat dispensing of GLP-1 therapies used in type 2 diabetes and obesity management. Its role is particularly relevant in urban and semi-urban regions, where digitally enabled patients seek convenience in accessing chronic care medications. Online platforms support treatment continuity through home delivery services and improved refill management. However, their use remains strictly prescription-dependent, as GLP-1 receptor agonists require physician supervision and regulated dispensing. Compared to hospital and retail pharmacies, online channels currently account for a smaller share of overall distribution.
Key India GLP-1 Receptor Agonist Company Insights
Novo Nordisk A/S and Eli Lilly and Company continue to dominate the India GLP-1 receptor agonist market through established and next-generation incretin-based therapies, including semaglutide and tirzepatide, supported by strong clinical efficacy in type 2 diabetes and obesity management. Sun Pharmaceutical Industries Ltd, Dr. Reddy’s Laboratories Ltd, and Zydus Lifesciences are actively strengthening their positions through post-patent strategies and preparation for potential entry into generic and biosimilar GLP-1 opportunities, particularly in the semaglutide segment. Cipla Limited, Lupin Limited, and Torrent Pharmaceuticals Ltd are expanding their metabolic disease portfolios and evaluating future participation in incretin-based therapies through pipeline development and strategic collaborations. Emcure Pharmaceuticals Ltd is gradually diversifying its chronic disease portfolio, with long-term interest in metabolic therapy adjacencies. Abbott Laboratories continues to support the ecosystem through diabetes diagnostics and monitoring solutions that complement GLP-1-based treatment pathways. Overall, the market remains highly competitive, driven by patent expiry expectations, rising obesity and diabetes prevalence, and increasing physician adoption of advanced incretin-based therapies.
Key India GLP-1 Receptor Agonist Companies
-
Novo Nordisk A/S
-
Eli Lilly and Company
-
Sun Pharmaceutical Industries Ltd
-
Dr. Reddy’s Laboratories Ltd
-
Zydus Lifesciences
-
Lupin Limited
-
Torrent Pharmaceuticals Ltd
-
Cipla Limited
-
Emcure Pharmaceuticals Ltd
-
Abbott Laboratories
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Novo Nordisk A/S
- Mature players focused on expanding GLP-1 receptor agonist portfolios, increasing manufacturing capabilities, strengthening physician engagement, and securing regulatory approvals across India.
- They also invested in obesity management programs, advanced clinical research, and strategic collaborations to maintain long-term leadership in diabetes and metabolic disorder treatment markets nationwide.
- Mature players maintained strong competitive advantage through established diabetes care portfolios, advanced research capabilities, extensive physician networks, and strong brand recognition.
- Their large-scale manufacturing infrastructure, innovative product pipeline, and financial strength enabled rapid commercialization, broader therapy accessibility, and sustained leadership within India’s growing obesity and diabetes treatment market.
- Mature players faced challenges including high research and development expenditures, premium therapy pricing, and increasing competitive pressure from biosimilar manufacturers.
- Regulatory complexities, affordability concerns, and supply chain constraints also limited broader patient accessibility, particularly across rural and semi-urban regions within India’s expanding diabetes treatment landscape.
Emerging Players: Biocon
- Emerging players prioritized biosimilar development, affordable manufacturing strategies, and regional expansion to strengthen their position in India’s GLP-1 receptor agonist market.
- They also emphasized strategic partnerships, localized production, and investment in next-generation metabolic therapies to accelerate commercialization opportunities and improve accessibility among price-sensitive patient populations.
- Emerging players gained competitive advantage through cost-efficient manufacturing, strong domestic pharmaceutical presence, and growing expertise in biologics and biosimilars.
- Their ability to provide affordable therapeutic alternatives, rapidly expand regional distribution networks, and address unmet healthcare needs strengthened their market positioning within India’s highly price-sensitive healthcare sector.
- Emerging players often faced limited global brand recognition, restricted investment capacity for large-scale clinical trials, and lower access to proprietary GLP-1 technologies.
- They also experienced difficulties related to scaling biologics manufacturing, obtaining regulatory approvals, and competing against multinational pharmaceutical companies with stronger commercial infrastructure and financial resources.
Recent Developments
-
In March 2026, Dr. Reddy’s Laboratories Ltd launched its semaglutide product “Obeda” in India, marking a key entry into the GLP-1 receptor agonist segment and expanding access to affordable diabetes and obesity therapies.
-
In November 2025, Novo Nordisk A/S entered a strategic collaboration with Emcure Pharmaceuticals Ltd to market its obesity therapy semaglutide (Wegovy) under the brand “Poviztra” in India, aimed at expanding patient access in the country’s obesity treatment segment.
India GLP-1 Receptor Agonist Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 150.8 million
Market size value in 2026
USD 240.5 million
Revenue forecast in 2033
USD 1,004.9 million
Growth rate
CAGR of 22.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Product, application, route of administration, distribution channel
Country scope
India
Key company profiled
Novo Nordisk A/S; Eli Lilly and Company; Sun Pharmaceutical Industries Ltd; Dr. Reddy’s Laboratories Ltd; Zydus Lifesciences; Lupin Limited; Torrent Pharmaceuticals Ltd; Cipla Limited; Emcure Pharmaceuticals Ltd; Abbott Laboratories
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
India GLP-1 Receptor Agonist Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the India GLP-1 receptor agonist market report based on product, application, route of administration, and distribution channel:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Semaglutide (Ozempic, Wegovy, Rybelsus)
-
Tirzepatide (Mounjaro, Zepbound)
-
Dulaglutide (Trulicity)
-
Liraglutide (Victoza, Saxenda)
-
Others (Byetta, Bydureon, SOLIQUA)
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Type 2 Diabetes Mellitus
-
Obesity / Chronic Weight Management
-
Cardiovascular Risk
-
-
Route of Administration Outlook(Revenue, USD Million, 2021 - 2033)
-
Injectable / Parenteral
-
Oral
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Online Pharmacies
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
India GLP-1 Receptor Agonist Market Entry & Commercial Opportunity Assessment
Conducted a comprehensive assessment of the India GLP-1 receptor agonist market focusing on obesity and type 2 diabetes treatment demand. The study evaluated patient population trends, physician prescribing behavior, pricing analysis, regulatory approvals, reimbursement landscape, distribution channel dynamics, and competitive benchmarking of Novo Nordisk, Eli Lilly, and domestic pharmaceutical manufacturers operating in India.
Helped the client identify high-growth therapeutic opportunities, optimize commercialization strategy, evaluate competitive positioning, and prioritize investment decisions across obesity and diabetes management segments. The assessment also supported market expansion planning by identifying pricing opportunities, patient accessibility challenges, and regional demand potential within India’s evolving metabolic disorder treatment market.
GLP-1 Biosimilar Development & Competitive Benchmarking Study
Delivered a detailed benchmarking assessment of Indian and global companies developing GLP-1 receptor agonist biosimilars and next-generation metabolic therapies. The study analyzed product pipelines, manufacturing capabilities, regulatory pathways, partnership strategies, clinical trial activity, intellectual property positioning, and commercialization readiness among leading domestic and multinational pharmaceutical companies.
Enabled the client to identify strategic collaboration opportunities, assess biosimilar competition risks, evaluate manufacturing scalability, and strengthen long-term product development planning. The analysis also supported investment prioritization by identifying companies with strong biologics expertise, cost-efficient production capabilities, and favorable positioning within India’s rapidly growing obesity and diabetes therapy market.
India Obesity Management & Specialty Care Infrastructure Assessment
Conducted an in-depth analysis of obesity management trends, specialty diabetes care infrastructure, and treatment accessibility across India. The study evaluated endocrinology clinic expansion, physician adoption trends, patient affordability, healthcare spending patterns, private hospital networks, and emerging demand for medically supervised weight management therapies in urban and semi-urban regions.
Supported strategic expansion planning by identifying high-demand treatment regions, accessibility gaps, and emerging obesity care opportunities across India. The assessment helped the client strengthen distribution strategy, improve patient outreach planning, and identify partnerships with specialty clinics and healthcare providers to enhance long-term commercial growth potential in the GLP-1 receptor agonist market.
Frequently Asked Questions About This Report
The India GLP-1 receptor agonist market size was estimated at USD 150.8 million in 2025
The India GLP-1 receptor agonist market is projected to reach USD 1,004.9 million by 2033, growing at a CAGR of 22.7% from 2026 to 2033.
Based on Product Type, the semaglutide (ozempic, wegovy, rybelsus) segment dominated the market with the largest revenue share of 59.2% in 2025, supported by its strong clinical efficacy in improving glycemic control and promoting significant weight loss among patients with type 2 diabetes and obesity.
The type 2 diabetes mellitus (T2DM) segment dominated the market with the largest revenue share of 92.6% in 2025, driven by the country’s rising diabetic population and increasing adoption of incretin-based therapies in clinical practice. GLP-1 receptor agonists are increasingly used as adjunct treatments to traditional antidiabetic therapies due to their dual benefits in glycemic control and weight reduction.
The oral segment dominated the market with the largest revenue share of 59.2% in 2025, driven by increasing patient preference for non-invasive treatment options and improved convenience associated with oral formulations.
The hospital pharmacies segment dominated the market with the largest revenue share of 58.9% in 2025, primarily supported by the increasing number of patients seeking diabetes and obesity treatment through hospitals and specialty care centers.
A few of the key players operating in the market are Novo Nordisk A/S, Eli Lilly and Company, Sun Pharmaceutical Industries Ltd, Dr. Reddy’s Laboratories Ltd, Zydus Lifesciences
The rising prevalence of type 2 diabetes and obesity significantly drove the growth of the India GLP-1 Receptor Agonist Market. Increasing urbanization, unhealthy dietary habits, sedentary lifestyles, and reduced physical activity raised the incidence of metabolic disorders across the country.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


