
- Home
- »
- Pharmaceuticals
- »
-
Influenza Vaccine Market Size & Share Report, 2026-2033GVR Report cover

Influenza Vaccine Market (2026 - 2033)
Size, Share & Trends Analysis Report By Vaccine Type (Inactivated, Live Attenuated), By Indication, By Age Group (Pediatric, Adults), By Route Of Administration (Injection, Nasal Spray), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$8.9BMarket Estimate, 2026
$9.5BMarket Forecast, 2033
$14.8BCAGR, 2026–2033
6.5%Influenza Vaccine Market Summary
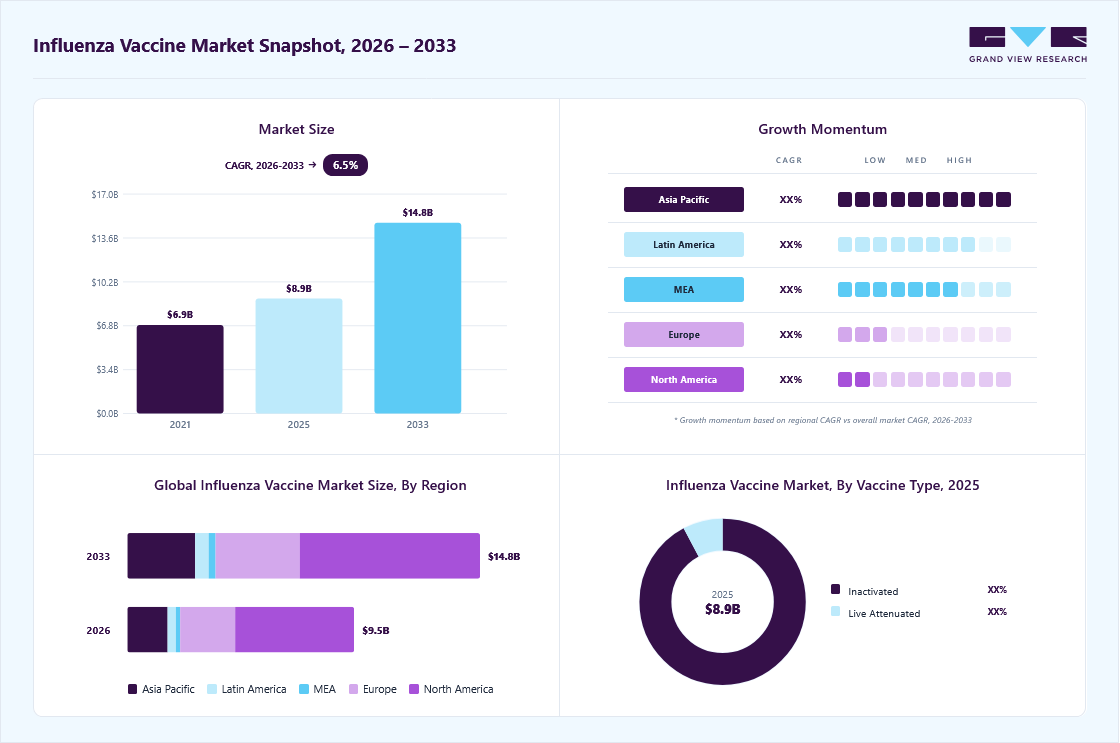
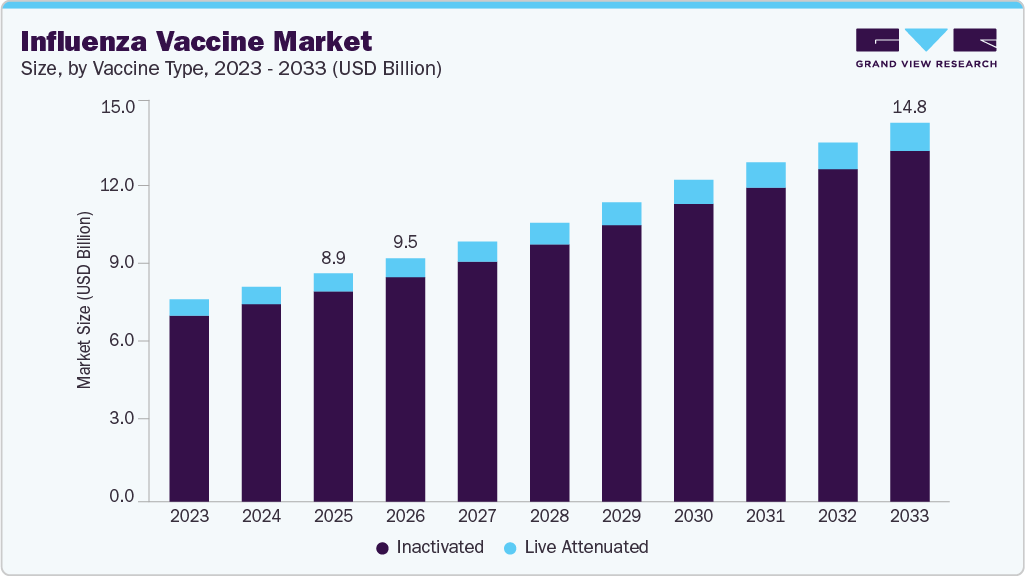
The global influenza vaccine market size was valued at USD 8.9 billion in 2025 and is projected to grow from USD 9.5 billion in 2026 to USD 14.8 billion by 2033, at a CAGR of 6.5% from 2026 to 2033. The North America held the largest share of 52.7% of the global market in 2025. The influenza vaccine sales are expected to increase throughout the forecast period due to an increase in the incidence of seasonal flu and increased recommendations for vaccination against the disease.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By vaccine type: Inactivated vaccines segment held the largest share of 92.1% in 2025.
- By indication: Quadrivalent segment held the largest revenue share of 87.5% in 2025.
- By age group: Adults segment held the largest revenue share of 78.1% in 2025.
Regional Highlights
- Largest regional market: North America (52.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. led the North America market in 2025.
Market Size & Forecast
- Market size in 2025: USD 8.9 Billion
- Estimated market size in 2026: USD 9.5 Billion
- Projected market size by 2033: USD 14.8 Billion
- CAGR (2026-2033): 6.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to the WHO, influenza cases have significantly increased as of early 2026, with the US experiencing a severe season, with estimates of over 15 million cases, 180,000 hospitalizations, and 7,400 deaths.According to the CDC’s estimates published in October 2023, nearly one billion cases of seasonal influenza are reported globally, including around 3-5 million cases with complications. In addition, a surge in surveillance and government support for vaccination at the country and global levels to monitor vaccine distribution, supply, and administration is one of the growth drivers for the influenza vaccine industry.The global influenza vaccine industry continues to demonstrate stable and essential growth in the post-pandemic period, supported by sustained awareness of respiratory infectious diseases and the normalization of annual immunization programs. While the surge witnessed during COVID-19 has moderated, vaccination uptake remains higher than pre-pandemic levels in several countries, driven by improved public health awareness and institutional preparedness. According to the CDC, the 2023–2024 influenza season resulted in an estimated 28–35 million illnesses, 310,000–390,000 hospitalizations, and 20,000–25,000 deaths in the U.S., highlighting the continued burden of disease and the critical role of vaccination.
 To learn more about this report, Download Free Sample Report
Innovation remains a key growth driver in the influenza vaccine market, particularly with the advancement of next-generation and combination vaccines. Companies are increasingly investing in mRNA-based and recombinant technologies to enhance vaccine efficacy and reduce production timelines. For instance, in October 2023, Moderna, Inc. announced positive Phase 1/2 data for its mRNA-1083 combination vaccine targeting both COVID-19 and influenza, demonstrating a strong immune response against multiple strains. Additionally, Pfizer and BioNTech continued progressing their mRNA-based influenza and combination vaccine candidates into mid-stage clinical trials in 2024.
The market is supported by strong regulatory backing and expanding immunization guidelines globally. Organizations such as the World Health Organization (WHO) continue to update biannual recommendations on strain composition, ensuring vaccine effectiveness against circulating variants. In 2024, the WHO emphasized the inclusion of updated influenza A (H1N1 and H3N2) and influenza B strains in seasonal vaccines. Governments worldwide are also strengthening stockpiling strategies and public vaccination campaigns to mitigate seasonal outbreaks and potential co-infections with other respiratory viruses.
Market Concentration & Characteristics
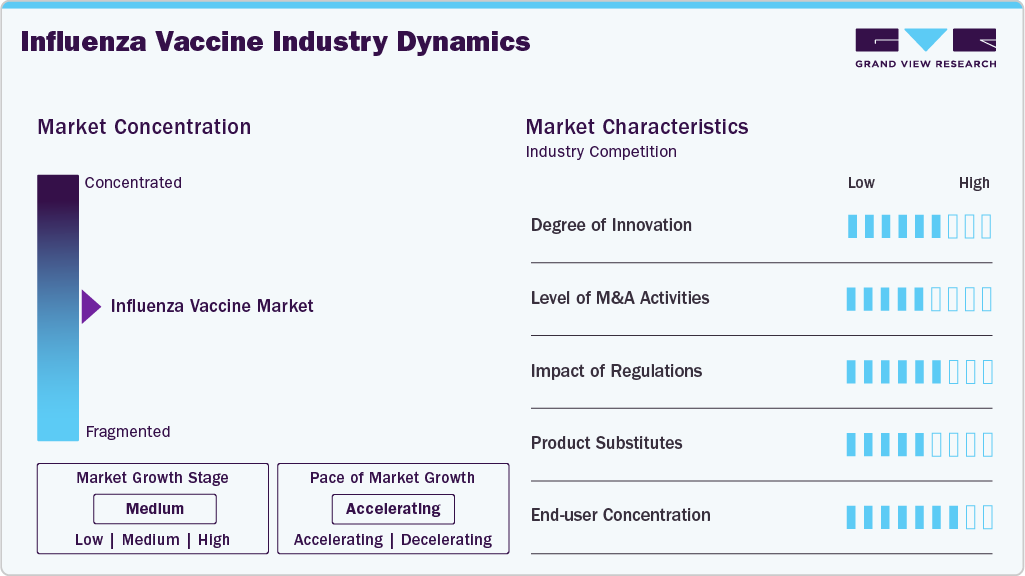
Innovation in the influenza vaccine market remains high, driven by continuous advancements in vaccine technologies and the growing focus on improving efficacy, production speed, and strain coverage. The market is increasingly characterized by the development of next-generation platforms such as mRNA, recombinant, and cell-based vaccines, which offer advantages over traditional egg-based approaches. These innovations aim to address challenges such as strain mismatch and long manufacturing timelines. In July 2024, CureVac entered into a strategic agreement with GSK, granting global rights to develop and commercialize mRNA-based influenza and combination vaccines, highlighting the industry’s shift toward advanced platforms. Additionally, the ongoing development of combination vaccines targeting both influenza and COVID-19 is further strengthening the innovation landscape and expanding future growth opportunities.
The market exhibits a moderately concentrated competitive structure, dominated by a few global pharmaceutical players with strong manufacturing and distribution capabilities. Key companies such as Sanofi, GSK plc, CSL Seqirus, and AstraZeneca (through legacy platforms and partnerships) hold significant market shares, supported by established product portfolios and long-standing government supply contracts. The market is characterized more by strategic collaborations, supply agreements, and product enhancements rather than aggressive consolidation. In April 2024, Sanofi initiated shipments of its seasonal influenza vaccine portfolio, including high-dose vaccines for older adults in the U.S., reinforcing its strong commercial presence. Similarly, manufacturers continue to secure early supply commitments with governments and healthcare providers, ensuring steady revenue streams and high entry barriers for new entrants.
 To learn more about this report, Download Free Sample Report
The regulatory landscape plays a pivotal role in shaping the influenza vaccine market, with global health authorities closely guiding vaccine composition, approval, and distribution. Organizations such as the World Health Organization (WHO) and the U.S. Food and Drug Administration (FDA) regularly update strain recommendations to ensure alignment with circulating virus variants. In February 2024, the WHO updated the strain composition for the 2024–2025 Northern Hemisphere influenza vaccines, recommending a shift to trivalent formulations by removing the B/Yamagata lineage, a move later supported by the FDA’s advisory committee in March 2024. These regulatory decisions significantly influence manufacturing strategies, supply chains, and product standardization across markets. However, stringent approval requirements and annual reformulation cycles increase development complexity and operational costs for manufacturers.
The market demonstrates low to moderate substitutability, as influenza vaccines remain the most effective preventive measure against seasonal influenza, with limited direct alternatives. While antiviral drugs and supportive treatments exist, they do not replace the role of vaccination in disease prevention. Internal substitution is observed across vaccine types, including inactivated, live attenuated, recombinant, and emerging mRNA-based vaccines, depending on patient demographics, availability, and clinical recommendations. Additionally, the development of combination and universal influenza vaccines is expected to further reshape the competitive landscape by reducing the need for frequent vaccinations and enhancing broad-spectrum protection.
Vaccine Type Insights
The inactivated vaccines segment dominated the influenza vaccine industry, accounting for 92.11% of the revenue share in 2025. This dominance is primarily attributed to the high global burden of influenza, strong demand for proven and safe immunization solutions, and the widespread presence of established manufacturers offering large-scale production capabilities. Inactivated vaccines, which use killed virus particles to stimulate an immune response, are widely preferred due to their strong safety profile across all age groups, including pediatric and elderly populations. Additionally, continuous improvements in formulation and manufacturing processes are enhancing their effectiveness and accessibility. In April 2024, Sanofi began shipping its updated inactivated influenza vaccine portfolio, including high-dose formulations for older adults in the U.S., highlighting sustained commercial reliance on this vaccine type.
The live attenuated vaccine segment is anticipated to grow at a significant CAGR over the forecast period, driven by innovations to improve delivery and patient compliance. Live attenuated influenza vaccines (LAIV), which contain weakened forms of the virus, offer the advantage of non-invasive administration through nasal sprays, making them particularly attractive for pediatric and needle-averse populations. In 2026, FluMist, a live attenuated nasal spray influenza vaccine, was introduced in Australia for the seasonal immunization program, marking an important step toward expanding its global footprint and improving accessibility. Furthermore, emerging innovations such as PROTAC-based live attenuated vaccine development are expected to enhance efficacy and stability, supporting the segment’s long-term growth potential.
Indication Insights
The quadrivalent segment dominated the influenza vaccine market, accounting for 87.46% of the total share in 2025, and is expected to register the fastest growth over the forecast period. This strong position is attributed to its broader protection against four influenza strains, two influenza A and two influenza B lineages, making it highly effective in reducing infection risk across diverse populations. The widespread preference for quadrivalent vaccines among healthcare professionals, coupled with their easy availability across hospitals, clinics, and pharmacies, continues to support segment growth. In addition, government-backed immunization programs and bulk procurement strategies have significantly boosted adoption. For instance, according to NHS England and the UK Health Security Agency (UKHSA) in January 2023, large-scale influenza vaccine orders were placed for pediatric immunization programs, ensuring continued access through GP services and pharmacies, reinforcing the segment’s dominance through structured vaccination campaigns.
The trivalent segment is anticipated to grow steadily over the forecast period, particularly following recent regulatory and industry shifts favoring streamlined vaccine compositions. Trivalent vaccines, which protect against three strains (two influenza A and one influenza B lineage), are gaining renewed attention due to cost optimization and simplified manufacturing processes. This shift has been further accelerated by evolving global recommendations. In February 2024, the World Health Organization (WHO) updated its guidance for the 2024–2025 Northern Hemisphere influenza season, recommending the removal of the B/Yamagata lineage and effectively transitioning toward trivalent vaccine formulations, a move later supported by regulatory bodies such as the FDA.
Age Group Insights
The adult segment held the largest revenue share of 78.10% in 2025, primarily driven by strong immunization initiatives and high procurement volumes by global organizations such as UNICEF, GAVI, and PAHO. Increasing awareness regarding the severe impact of influenza among high-risk populations, particularly the elderly, has significantly boosted vaccination rates within this segment. Adults, especially those aged 65 years and above, remain highly susceptible to complications, leading to increased hospitalizations and mortality. According to the CDC, during the 2022–2023 influenza season, adults aged 65+ had the highest hospitalization rate in the U.S., at 187.3 per 100,000 population, reinforcing the importance of targeted vaccination strategies. In addition, advancements in high-dose and adjuvanted vaccines specifically designed for older adults are further strengthening segment growth. In December 2024, the U.S. FDA granted Fast Track designation to Sanofi’s influenza-COVID-19 combination vaccine candidates for individuals aged 50 years and above, highlighting the continued focus on enhancing protection for the adult population and reducing disease burden.
The pediatric segment is anticipated to grow at the fastest CAGR over the forecast period, driven by increased emphasis on early immunization and expanding vaccination coverage across global healthcare systems. Regulatory bodies such as the CDC and WHO strongly recommend annual influenza vaccination for children aged 6 months and above, driving consistent demand in this segment. Rising birth rates in developing countries, particularly in the Asia Pacific region, such as India and China, are further contributing to increased vaccine uptake. The burden of influenza among children remains significant, with CDC estimates reporting 174 laboratory-confirmed pediatric deaths in the U.S. between October 2022 and September 2023, marking one of the highest recorded figures. In February 2026, Centivax initiated Phase 1 clinical trials of its universal influenza vaccine candidate, enrolling healthy volunteers across different age groups, including younger populations, reflecting growing efforts to develop broader and longer-lasting protection for pediatric cohorts.
Route Of Administration Insights
The injection segment dominated the influenza vaccine market, accounting for 91.92% of the total revenue share in 2025, driven by the widespread use of intramuscular vaccine formulations in national immunization programs. Injectable vaccines, including inactivated and recombinant types, are preferred due to their strong efficacy, well-established safety profiles, and suitability for large-scale administration across diverse populations. The presence of an extensive product portfolio from leading manufacturers further supports segment growth, along with consistent government procurement and distribution through hospitals and pharmacies. In May 2025, CSL Seqirus initiated shipments of its trivalent injectable influenza vaccines for the 2025–2026 U.S. season, underscoring the continued reliance on injectable formats for efficient, large-scale vaccine deployment.
The nasal spray segment is anticipated to register the fastest CAGR over the forecast period, driven by increasing demand for non-invasive, patient-friendly vaccination options. Intranasal vaccines offer advantages such as ease of self-administration, improved compliance among pediatric populations, and the ability to generate both mucosal and systemic immune responses. These benefits are particularly relevant in expanding vaccination coverage in homecare settings and among needle-averse individuals. In addition, growing investments in advanced intranasal technologies are accelerating innovation. In February 2023, the Access to Advanced Health Institute received USD 9.9 million in funding from the Medical CBRN Defense Consortium to develop an RNA-based intranasal influenza vaccine, highlighting ongoing efforts to expand access to the next-generation delivery platforms.
Distribution Channel Insights
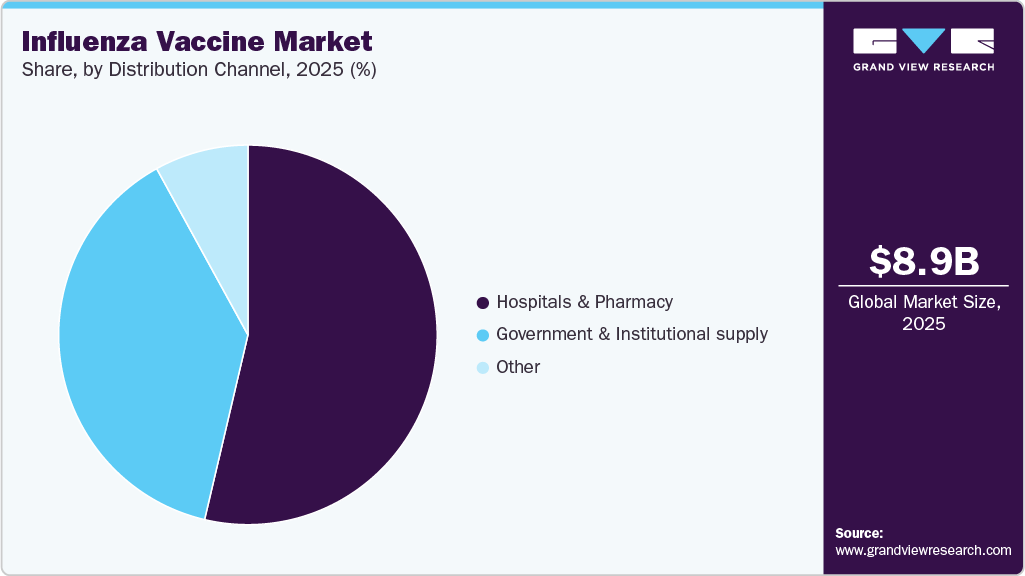
Hospitals & pharmacy held the largest revenue share of 53.68% in 2025, driven by their central role in vaccine storage, administration, and accessibility. These channels benefit from strong patient footfall, established cold-chain infrastructure, and integration with national immunization programs, enabling efficient large-scale vaccine distribution. Increasing influenza cases and related hospitalizations further drive higher vaccine demand in these settings. Additionally, pharmacies have become key vaccination points due to convenience and extended service hours. In June 2025, GSK initiated shipments of its trivalent influenza vaccines, including Fluarix and Flulaval, to U.S. pharmacies and healthcare providers following regulatory approvals, reinforcing the importance of these channels in ensuring timely vaccine availability.
 To learn more about this report, Download Free Sample Report
The government & institutional supply segment is anticipated to grow at the fastest CAGR over the forecast period, supported by expanding public immunization programs and increasing global focus on preventive healthcare. Governments and international organizations play a crucial role in procuring and distributing vaccines, particularly in low- and middle-income countries, to improve coverage among high-risk populations. Bulk procurement strategies and subsidized or free vaccination initiatives are key drivers of this segment. In September 2024, the World Health Organization (WHO) issued updated influenza vaccine recommendations for the Southern Hemisphere, guiding large-scale procurement and distribution efforts by governments and public health agencies, highlighting the growing influence of institutional frameworks in shaping vaccine demand and accessibility worldwide.
Regional Insights
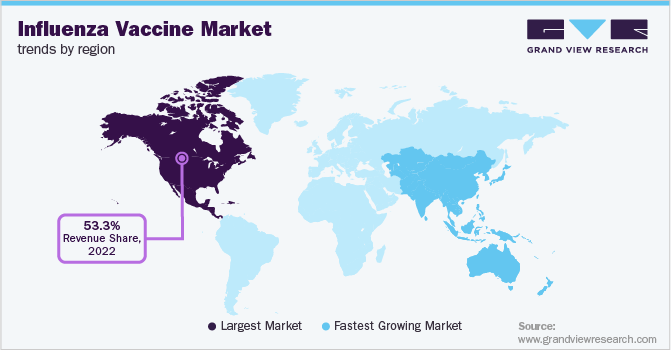
North America dominated the global influenza vaccine market, accounting for a 52.66% revenue share, supported by high vaccination coverage, advanced healthcare infrastructure, and strong government-backed immunization programs. The region benefits from early adoption of updated vaccine formulations and the presence of leading manufacturers, including Sanofi, GSK, and CSL Seqirus. The increasing seasonal influenza burden and greater awareness of preventive healthcare further drive demand. In March 2025, the U.S. FDA announced updated strain recommendations for the 2025–2026 influenza season, including revised H3N2 components, highlighting the region’s proactive regulatory approach and its influence on global vaccine production and supply strategies.
 To learn more about this report, Download Free Sample Report
U.S. Influenza Vaccine Market Trends
The U.S. represents the largest market within North America, driven by strong policy support, high public awareness, and extensive distribution networks across hospitals and pharmacies. Annual vaccination campaigns led by the CDC, in partnership with private players, ensure wide accessibility. In addition, continuous innovation and pipeline advancements strengthen market growth. In February 2026, the FDA issued a refusal-to-file letter for Moderna’s mRNA-based influenza vaccine application for adults aged 50+, while indicating a review timeline upon resubmission, reflecting both the regulatory rigor and ongoing innovation shaping the U.S. influenza vaccine landscape.
Europe Influenza Vaccine Market Trends
Europe holds a substantial share in the influenza vaccine industry, supported by well-established public healthcare systems and strong vaccination recommendations across countries. Regional growth is driven by coordinated efforts from organizations such as the European Centre for Disease Prevention and Control (ECDC) and national health agencies. Increasing focus on elderly immunization and cross-border healthcare initiatives further supports demand. In February 2024, the World Health Organization (WHO) recommended updated strain compositions for the Northern Hemisphere influenza vaccines, influencing vaccine production and procurement strategies across European countries, ensuring alignment with circulating virus strains.
The UK influenza vaccine market is driven by structured national immunization programs and strong government support through the National Health Service (NHS). Seasonal vaccination campaigns target vulnerable populations, including children, older adults, and individuals with underlying conditions. The country emphasizes accessibility through GP services and pharmacies. In January 2023, NHS England and the UK Health Security Agency (UKHSA) expanded influenza vaccine procurement for pediatric immunization programs, ensuring availability through March 2023, reflecting proactive efforts to enhance vaccination coverage and reduce disease burden.
The influenza vaccine market in Germany is expected to grow during the forecast period. Germany is a key market in Europe, supported by robust healthcare infrastructure, high healthcare expenditure, and strong regulatory frameworks. The country focuses on increasing vaccination rates among high-risk populations, particularly older adults, through public awareness initiatives and reimbursement policies. Adoption of advanced vaccine technologies is also increasing. The WHO and regional health authorities are aligning Germany’s influenza vaccination strategies with updated strain recommendations, ensuring consistency with broader European immunization efforts and strengthening preparedness against seasonal outbreaks.
Asia Pacific Influenza Vaccine Market Trends
Asia Pacific is anticipated to register the fastest CAGR over the forecast period, driven by expanding healthcare infrastructure, rising awareness, and large target populations across countries such as China and India. Increasing government initiatives and investments in vaccine development are further supporting regional growth. In July 2025, Centivax raised approximately USD 45 million in Series A funding to advance its universal influenza vaccine candidate into clinical development, reflecting growing innovation and investment momentum within the broader Asia-Pacific and global vaccine ecosystem.
The Japan influenza vaccine market holds a significant share in Asia Pacific, supported by high healthcare standards, an aging population, and strong government vaccination policies. The country maintains consistent vaccination coverage, particularly among elderly populations, to reduce hospitalization rates. Technological advancements and the adoption of improved vaccine formulations further drive market growth.
The influenza vaccine market in China is rapidly growing, driven by rising healthcare spending, a large population, and increasing awareness of preventive healthcare. Government-led immunization programs and expansion of domestic manufacturing capabilities are key growth drivers. The country is also witnessing increasing participation from local and global players. In 2026, Sino Biological launched a panel of recombinant antigens for the 2026–2027 Northern Hemisphere influenza strains, supporting vaccine manufacturers in China and globally in accelerating the development of next-generation influenza vaccines.
Latin America Influenza Vaccine Market Trends
Latin America is experiencing steady growth in the influenza vaccine industry, supported by expanding public immunization programs and increasing efforts to improve vaccine accessibility. Governments in countries such as Brazil and Mexico are focusing on large-scale procurement and distribution through national healthcare systems. The region also benefits from support by international health organizations. In 2024, the WHO issued updated influenza vaccine composition recommendations for the Southern Hemisphere, guiding procurement and vaccination strategies across Latin American countries and ensuring preparedness for seasonal outbreaks.
Middle East & Africa Influenza Vaccine Market Trends
The Middle East & Africa region is witnessing gradual growth in the influenza vaccine industry, driven by improving healthcare infrastructure and increasing awareness regarding preventive vaccination. Government initiatives and partnerships with global health organizations are enhancing vaccine access, particularly in underserved areas. However, challenges such as limited healthcare access and lower vaccination rates persist.
Key Influenza Vaccine Company Insights
Some of the leading players operating in the influenza vaccine market include Pfizer Inc., Sanofi, and GSK plc. Companies focus on capturing the market by increasing their presence using various business initiatives, such as partnerships & collaborations with government. Moreover, these companies have well-established product portfolios that help them capture significant market share.
SINOVAC, EMERGENT, and OSIVAX are some of the emerging participants in the influenza vaccine industry. Developing & launching new and improved products that deliver faster results, higher accuracy, and easier usability are prevalent operating strategies for these companies. The players may face challenges in penetrating the market due to competition and regulatory hurdles.
Key Influenza Vaccine Companies:
The following key companies have been profiled for this study on the influenza vaccine market.
- GSK plc
- Sanofi
- Pfizer Inc
- Vaxess Technologies Inc
- Merck & Co., Inc.
- Viatris Inc.
- OSIVAX
- AstraZeneca
- SINOVAC
- CSL Limited
- EMERGENT
- EMERGEX VACCINES
Recent Development
-
In March 2026, CIDRAP expanded its Universal Influenza Vaccine Technology Landscape by adding multiple new candidates such as UniFluVec (Capricorn), NIAID’s H5 mRNA-LNP, and recombinant VLP-based platforms.
-
In November 2025, Merck announced a strategic transaction involving Cidara Therapeutics to acquire CD388 for approximately USD 9.2 billion, a long-acting influenza prophylactic candidate currently in Phase 3 development, targeting high-risk populations.
-
In May 2024, Sanofi and Novavax announced a partnership to co-commercialize Novavax's protein-based COVID-19 vaccine and develop combination COVID-19–influenza vaccines using Novavax’s Matrix-M adjuvant.
Influenza Vaccine Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.9 billion
Estimated market size in 2026
USD 9.5 billion
Projected market size by 2033
USD 14.8 billion
Growth rate
CAGR 6.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Vaccine type, indication, age group, route of administration, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; Thailand; South Korea; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
GSK plc; Pfizer Inc.; Sanofi; Vaxess Technologies Inc.; Merck & Co., Inc.; Viatris Inc.; OSIVAX; AstraZeneca; SINOVAC; CSL Limited; EMERGENT; EMERGEX VACCINES
Customization scope
Free report customization (equivalent to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Influenza Vaccine Market Report Segmentation
This report forecasts revenue growth and provides an analysis on the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global influenza vaccine market report based on vaccine type, indication, age group,route of administration, distribution channel, and region:
-
Vaccine Type Outlook (USD Million, 2021 - 2033)
-
Inactivated
-
Live Attenuated
-
-
Indication Outlook (USD Million; 2021 - 2033)
-
Quadrivalent
-
Trivalent
-
-
Age Group Outlook (USD Million; 2021 - 2033)
-
Pediatric
-
Adults
-
-
Route of Administration Outlook (USD Million; 2021 - 2033)
-
Injection
-
Nasal Spray
-
-
Distribution Channel Outlook (USD Million; 2021 - 2033)
-
Hospitals & pharmacy
-
Government & Institutional Supply
-
Other
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global influenza vaccine market size was valued at USD 8.9 billion in 2025 and is estimated at USD 9.5 billion for 2026.
The global influenza vaccine market is expected to grow at a CAGR of 6.5% from 2026 to 2033, reaching USD 14.8 billion by 2033.
Key players include GSK plc; Pfizer Inc.; Sanofi; Vaxess Technologies Inc.; Merck & Co., Inc.; Viatris Inc.; OSIVAX; AstraZeneca; SINOVAC; CSL Limited; EMERGENT; EMERGEX VACCINES.
The rising incidence of influenza, increasing recommendations for vaccination, increasing awareness among people about vaccination against life-threaten diseases, and betterment in national immunization programs are the major factors driving the influenza vaccine market growth over the forecast period.
Asia Pacific is the fastest-growing region over the forecast period.
The adults segment led with a 78.1% revenue share in 2025, while pediatric is the fastest-growing age group.
Injection segment held the largest share (over 91.0%) in 2025, while nasal spray is the fastest-growing segment.
The inactivated vaccines segment led with a 92.1% revenue share in 2025.
The quadrivalent segment dominated the influenza vaccine market, accounting for 87.5% of the total share in 2025, and is expected to register the fastest growth over the forecast period. This strong position is attributed to its broader protection against four influenza strains, two influenza A and two influenza B lineages, making it highly effective in reducing infection risk across diverse populations.
North America dominated the influenza vaccine market, accounting for a 52.7% revenue share, supported by high vaccination coverage, advanced healthcare infrastructure, and strong government-backed immunization programs. The region benefits from early adoption of updated vaccine formulations and the presence of leading manufacturers such as Sanofi, GSK, and CSL Seqirus. Increasing seasonal influenza burden and awareness regarding preventive healthcare further drive demand.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


