
- Home
- »
- Advanced Interior Materials
- »
-
Iron And Steel Market Size And Share Report, 2026-2033GVR Report cover

Iron And Steel Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Iron Ore, Steel), By Region (North America, Europe, Asia Pacific, Central & South America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$2.0TMarket Estimate, 2026
$2.1TMarket Forecast, 2033
$2.7TCAGR, 2026–2033
3.8%Iron And Steel Market Summary
The global iron and steel market size was valued at USD 2.0 trillion in 2025 and is projected to grow from USD 2.1 trillion in 2026 to USD 2.7 trillion by 2033, at a CAGR of 3.8% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 60.0% in 2025. Rising investment in residential construction is expected to augment the market growth over the forecast period.
Key Market Trends & Insights
- By product: The iron ore segment held the largest market share of about 90.0% in 2025.
- By end use: The building & construction segment held the largest market share of over 45.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (60.0% revenue share, 2025)
- Fastest-growing regional market: Middle East & Africa (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 2.0 Trillion
- Estimated market size in 2026: USD 2.1 Trillion
- Projected market size by 2033: USD 2.7 Trillion
- CAGR (2026-2033): 3.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Iron & steel products possess a high strength-to-weight ratio, allowing them to bear heavy loads and resist compression, tension, and bending forces. This characteristic makes it ideal for supporting the weight of tall buildings and transferring the load to the foundation. The products are highly durable and resistant to corrosion, weathering, and pests. This durability ensures the building's longevity and reduces the need for frequent maintenance and repairs, making it a cost-effective choice for the construction industry.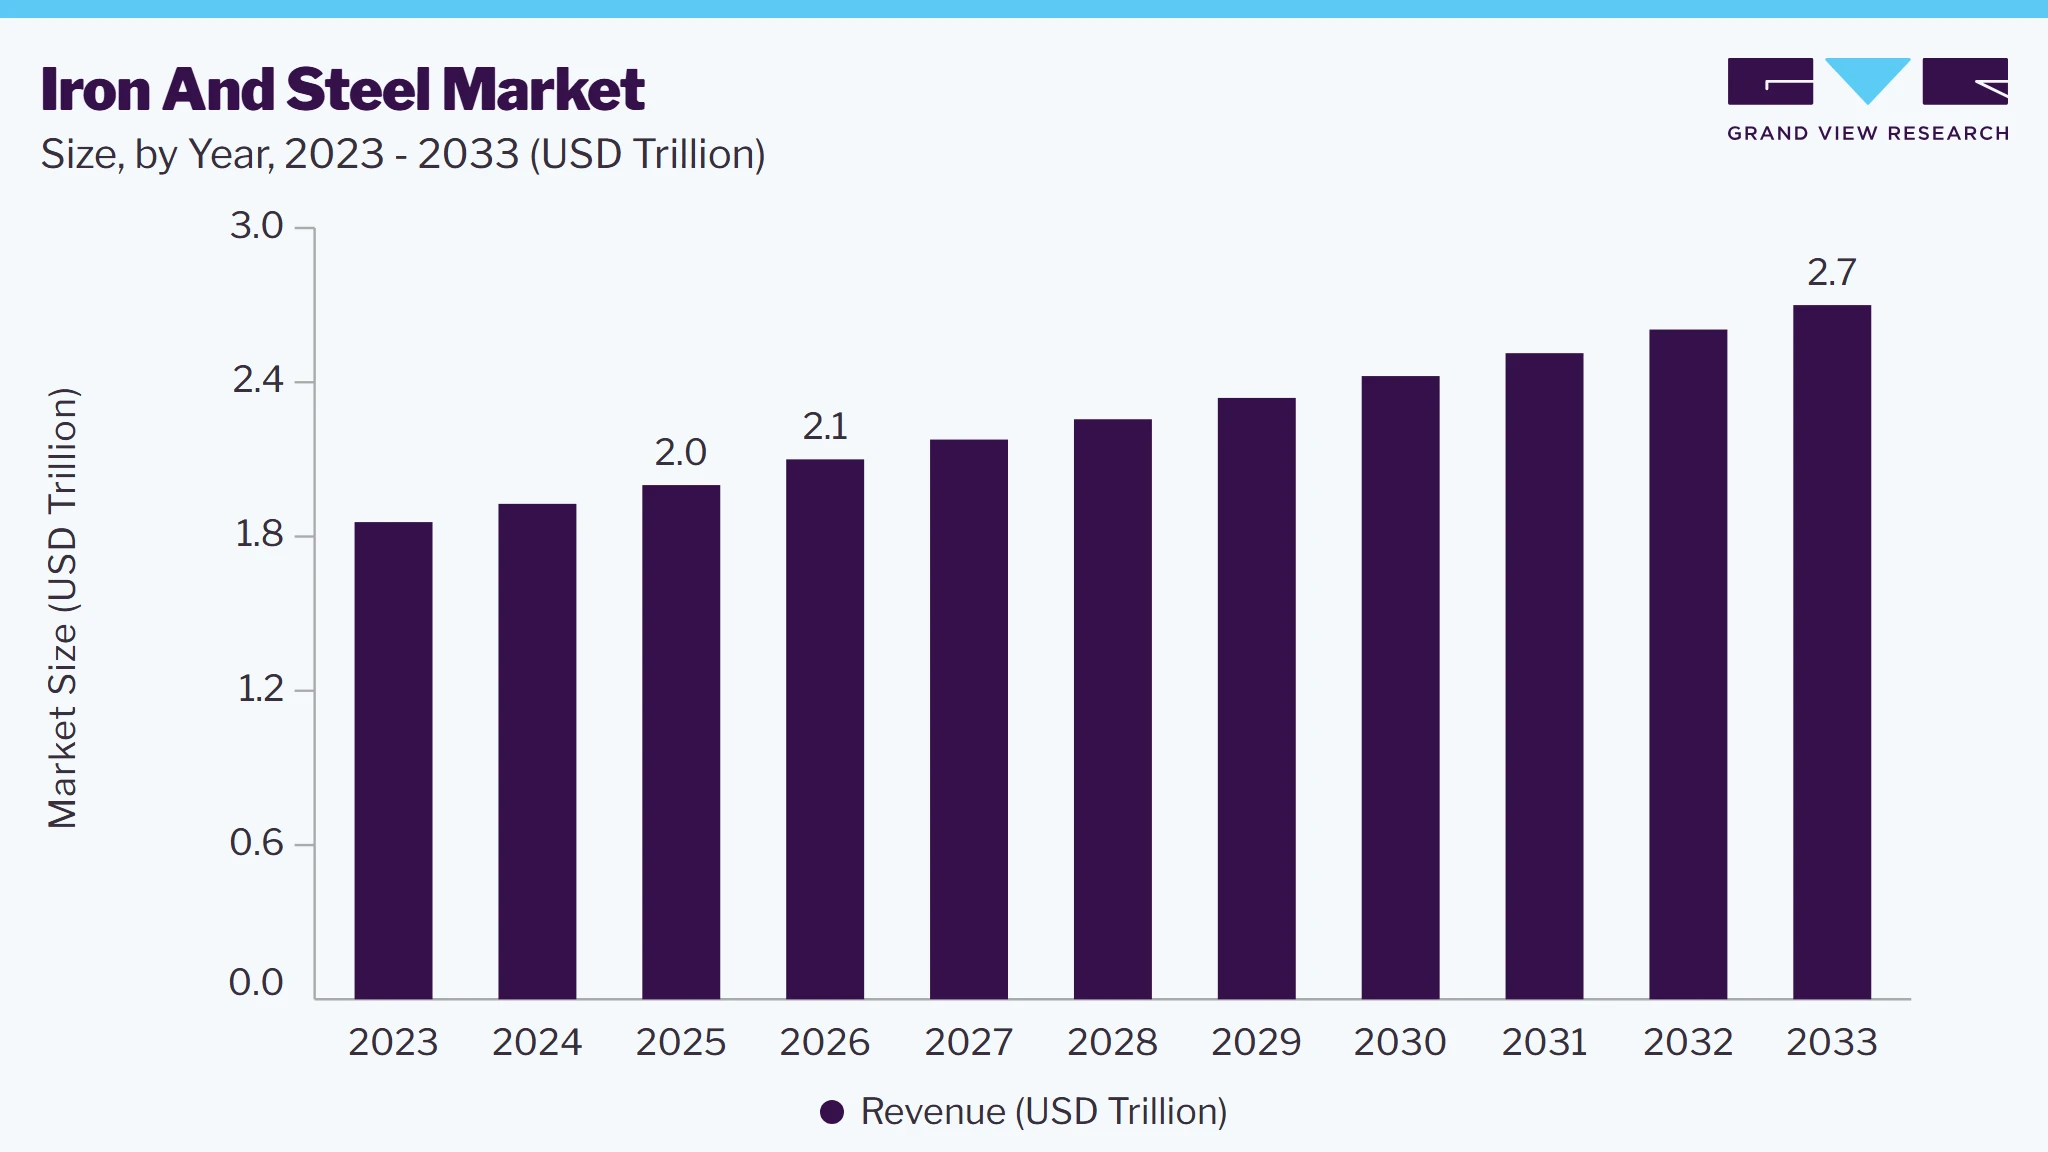 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The U.S. is one of the largest consumers of iron & steel in North America, driven by rising demand from end-use industries such as construction & infrastructure, automotive & transportation, heavy machinery, and consumer goods. Furthermore, rising demand for heavy machinery is expected to drive product consumption over the forecast period. For instance, the new order of manufactured durable goods in May 2023 increased by 1.7%, and transportation equipment increased by 3.9% compared to April 2023.
The ongoing conflict between Russia and Ukraine has indeed had a detrimental effect on the iron & steel industry, leading to a significant rise in prices for these commodities. The United Nations Conference on Trade and Development reported that global energy prices rose sharply due to the reduced supply of oil, gas, and coking coal from Russia. Consequently, this has led to a decline in the consumption of various products across different end uses.
Market Dynamics
The iron and steel industry is experiencing steady growth driven by rising infrastructure investment, urbanization, and expanding construction activity in both developing and developed economies. The growing demand from the automotive, manufacturing, and energy sectors is providing an additional boost to market expansion. In addition, advances in steel production technologies and the increasing adoption of eco-friendly processes have created new opportunities for this market.
The iron and steel industry is experiencing growth driven by ongoing infrastructure development and rising urbanization worldwide. Many governments, both developed and developing, are dedicating substantial investment to this industry. These investments focus on improving various economic and public factors, such as communication and transport systems, smart cities, and housing. These construction processes are highly dependent on the use of iron and steel as raw materials, as they are reliable and strong. The migration of citizens from rural to urban areas in search of a better lifestyle contributes to the ever-increasing demand for infrastructure, which will be built with steel. Developing economies in Asia and the Middle East are witnessing extensive construction activity, driven by government-supported investments and policies.
The unpredictability of prices for essential raw materials, such as iron ore and coking coal, is the most substantial restraint on the expansion of the iron and steel industry. A sudden price hike can strain manufacturers' profit margins and disrupt production schedules. The availability of the above raw materials, whether directly or indirectly, depends on imbalances between supply and demand, trade restrictions, and changing environmental conditions. High uncertainty about the price of raw materials affects long-term contracts and investment planning, making it harder for firms to implement a fixed-pricing strategy. Furthermore, this uncertainty makes it difficult for smaller manufacturers to operate in the market. Unstable raw-material prices negatively affect production efficiency, thereby limiting market growth.
Growing attention towards sustainable development and CO2 emission reduction provides major opportunities for the iron and steel market. Due to governments, industries, and end consumers' focus on environmentally friendly production, the market for green and low-carbon steel products is growing significantly. Steel manufacturers are investing in emerging technologies that enable low-carbon production, such as hydrogen-based steelmaking and electric arc furnaces. This trend is fueled by growing awareness of strict emission standards and environmentally friendly materials. Furthermore, sectors such as the automotive industry are seeking sustainable materials to meet their sustainability goals and are increasingly preferring eco-friendly steel products. The shift is further stimulated by supportive government policies and incentives focused on clean manufacturing.
Analyst Perspective
The iron and steel industry is entering a period of transformation, driven by infrastructure development, industrial growth, and the shift toward lower-carbon production. While demand from construction, automotive, energy, and transportation remains fundamental, the next phase of competition is likely to be shaped by how efficiently producers manage energy use and raw materials. The growing adoption of recycled steel and circular manufacturing practices is gradually reshaping cost structures and supply chains. In the coming years, companies that invest in cleaner technologies, secure access to quality scrap, and build low-emission production capabilities are likely to strengthen their competitive position. As sustainability has become a purchasing and regulatory priority, green steel is expected to evolve from a niche offering into a key source of long-term value creation.
Product Insights
The iron ore segment held the largest market share of about 90.0% in 2025 and is expected to grow at a significant CAGR over the forecast period. Around 96% of the iron ore is used in the production of crude steel globally. Thus, fluctuation in steel demand impacts its consumption. For instance, increased consumption of iron ore for crude steel production in China, driven by higher scrap prices, is expected to lead to higher iron ore imports over the next three years.
The steel market is expected to grow at the fastest CAGR over the forecast period, driven by rising demand from the building & construction industry. For instance, in June 2023, Adel Hassan's AMHT Group unveiled its new real estate venture, Viola, in El Banafseg city, New Cairo, Egypt. The project, worth around EGP 600 million (~USD 19.42 million), will feature a versatile four-story building spanning 14,000 square meters.
Iron Ore Application Insights
The steel segment led the market with the largest revenue share of 95.0% in 2025. Rising construction activity is projected to drive segment growth; to meet this demand, manufacturers are expanding production capacity. For instance, in December 2025, Jindal Steel, an Indian industrial corporation, announced the expansion of its steel manufacturing capabilities in Raigarh, Chhattisgarh, India. This expansion was expected to double the share of steel production.
The other segment is expected to register at the fastest CAGR over the forecast period. The segment comprises black iron oxide, powdered iron, iron blue, and iron 59. Powdered iron is widely used as a raw material in manufacturing processes. It is frequently combined with other substances to form alloys or used in powdered metallurgy techniques to produce components such as gears, magnets, and sintered parts.
Steel End-Use Insights
The building & construction segment led the market with the largest revenue share of 45.0% in 2025. The rising investment in construction is expected to boost demand for steel products during the forecast period. For instance, in April 2023, Hiranandani Group announced an INR 1,000.0 crore (USD 120.7 million) investment to construct a housing project in Mumbai, India. The company's objective is to create a residential space of 1 million square feet in this project, encompassing approximately 700 units.
The automotive & transportation segment is expected to grow at a notable CAGR over the forecast period. The American Iron and Steel Association reports that steel makes up approximately 54% of the overall composition of an average vehicle. The product is vital in producing various automotive components, including door panels, chassis, frames, and support beams. For instance, in April 2025, NITI Aayog released its report named "Automotive Industry: Powering India's Participation in Global Value Chains". The report noted that production volumes of automotive and auto parts were on the rise and required significant quantities of specialty steel and flat steel products.
The product is used in various consumer goods, including refrigerators, air conditioners, and microwaves. Rising investment in expanding consumer goods production is expected to augment the market growth over the forecast period.
Regional Insights
The iron and steel market in North America is expected to register at a notable CAGR over the forecast period. Rising investment in electric vehicle production is expected to drive demand for iron powder, electric steel, and other components over the coming years.
 To learn more about this report, Download Free Sample Report
Asia Pacific Iron & Steel Market Trends
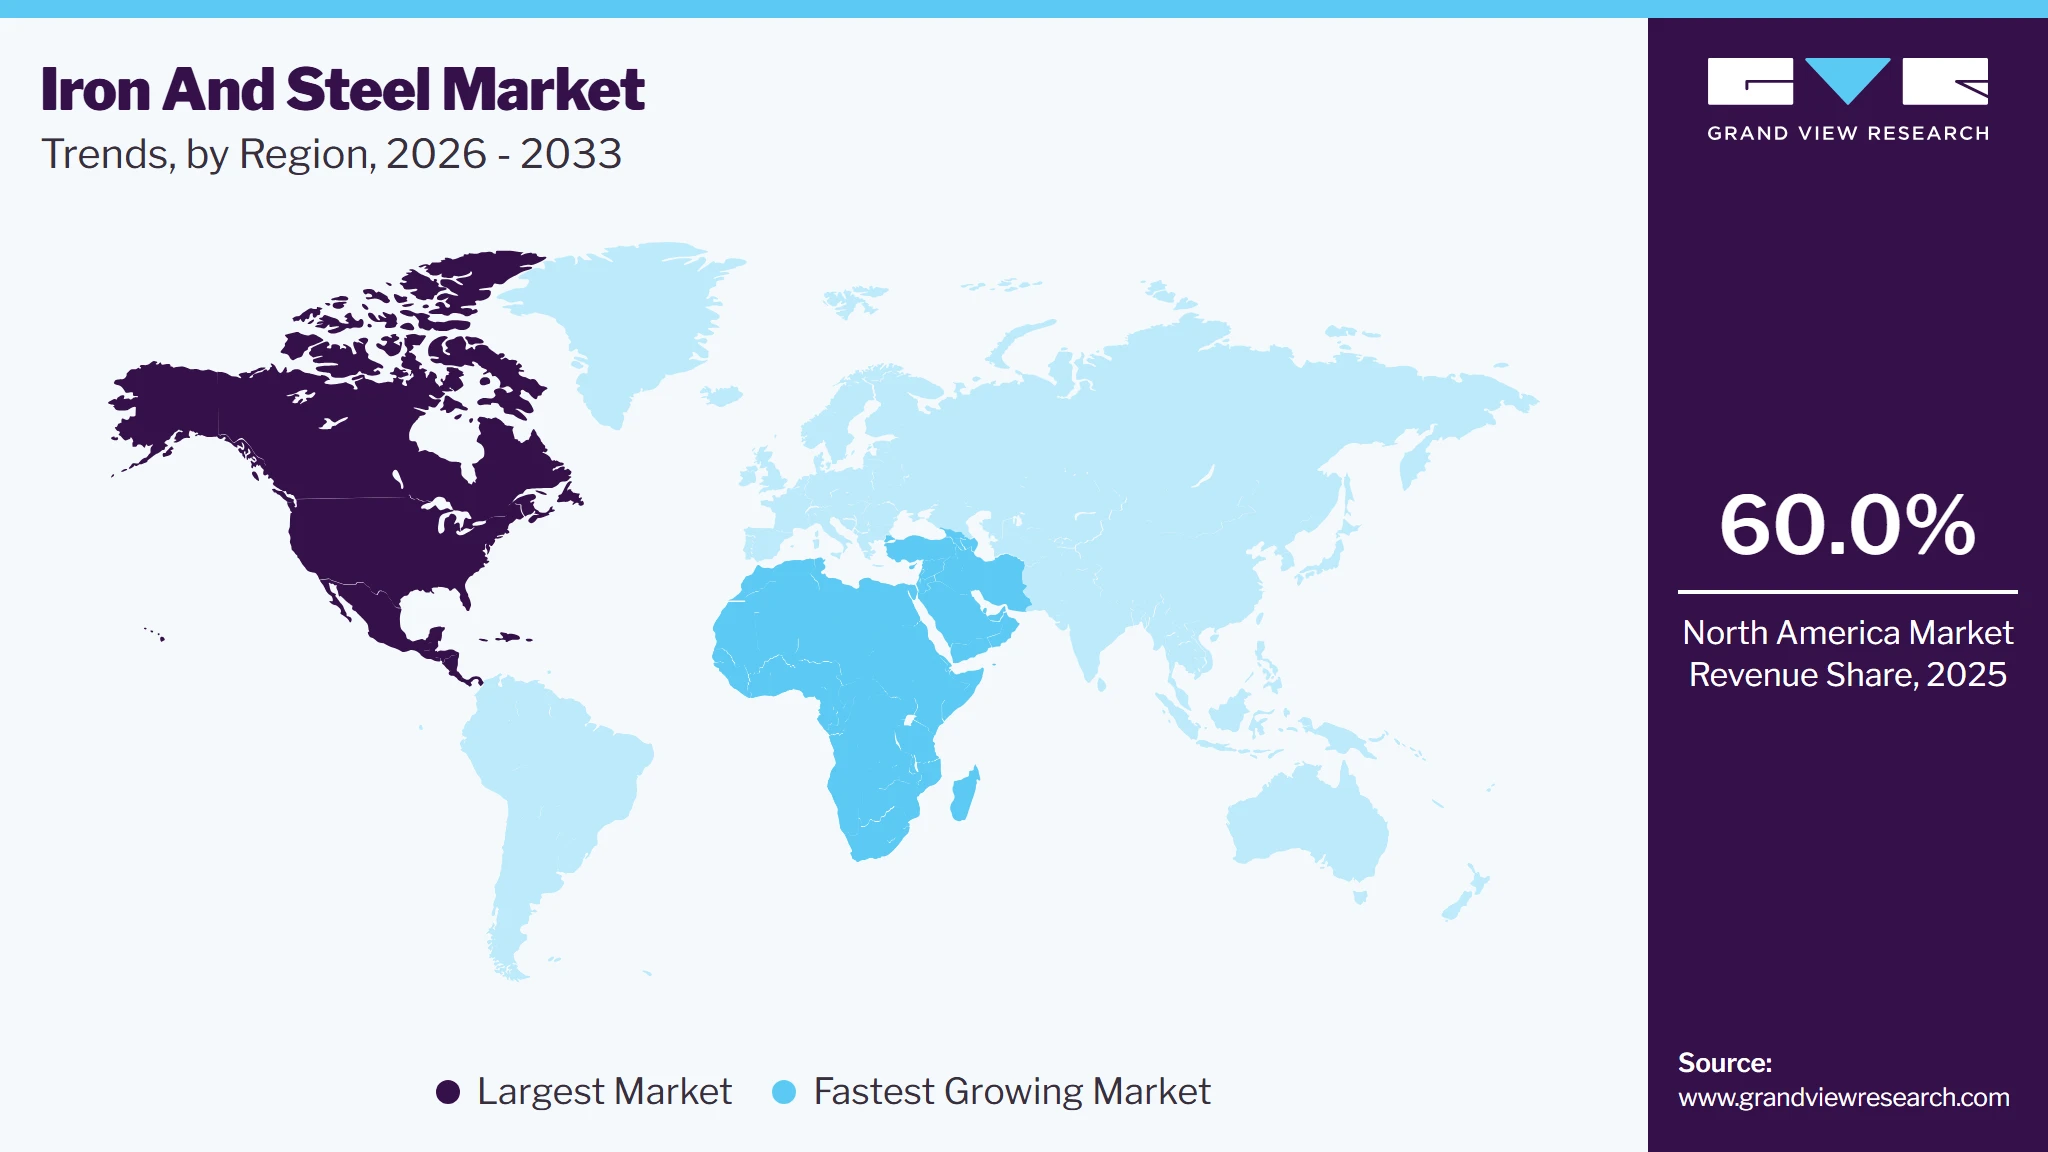
Asia Pacific dominated the global iron and steel market with the largest revenue share of approximately 60.0% in 2025. Market growth will likely be augmented by increased investments in the housing and commercial sectors of developing economies such as China and India. For instance, according to a January 2026 report by CBRE, investments in India’s real estate sector reached an all-time high of USD 14.3 billion in 2025, a 25% increase from the previous year, while land and development sites accounted for more than 46% of total investments.
Middle East & Africa Iron & Steel Market Trends
The iron and steel market in the Middle East & Africa is expected to grow at the fastest CAGR over the forecast period. The region's growth can be attributed to rising investments by both government and private entities across industries such as tourism, construction, manufacturing, and infrastructure. The countries in the region are undergoing rapid industrialization and urbanization, driving their development.
Key Iron And Steel Companies Insights
The iron and steel industry comprises many companies, both small and large, operating across different parts of the world. These companies aim to expand their global presence through acquisitions and increase their production capacity.
Key Iron And Steel Companies
The following key companies have been profiled for this study on the iron and steel market.
-
Arcelor Mittal S.A.
-
China BaoWu Steel Group Corporation Limited
-
Nippon Steel Corporation
-
HBIS Group
-
Jiangsu Shagang Group
-
POSCO HOLDINGS INC.
-
Tata Steel Limited
-
JFE Steel Corporation
-
Shougang Group
-
Nucor Corporation
-
JSW
-
NLMK
-
Techint Group
-
Vedanta Group
-
United States Steel Corporation
Recent Developments
-
In April 2026, POSCO signed a Joint Venture Agreement with JSW Steel to establish an integrated steel plant in India, with co-management and a 50:50 stake each. This joint venture will primarily cater to the enormous growth in demand in India and across global supply chains.
-
In December 2025, Tata steel, a pioneer in steel manufacturing in India, in a press release affirmed the long-term growth strategy for India stating their primary objectives of investments as in the volume growth, in value added downstream portfolio, in identified mining assets and infrastructure to serve the needs of the India business, in low carbon low capital intensity process technologies for sustainable steel making of the future.
Iron and Steel Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.0 trillion
Estimated market size in 2026
USD 2.1 trillion
Projected market size by 2033
USD 2.7 trillion
Growth rate
CAGR of 3.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product (iron ore application, steel end use), and region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand, South Korea; Brazil; Argentina, South Africa, UAE
Key companies profiled
Arcelor Mittal S.A.; China BaoWu Steel Group Corporation Limited; Nippon Steel Corporation; HBIS Group; Jiangsu Shagang Group; POSCO HOLDINGS INC.; Tata Steel; JFE Steel Corporation; Shougang Group; Nucor Corporation; JSW; SAIL; NLMK; Techint Group; U.S. Steel Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Iron and Steel Market Report Segmentation
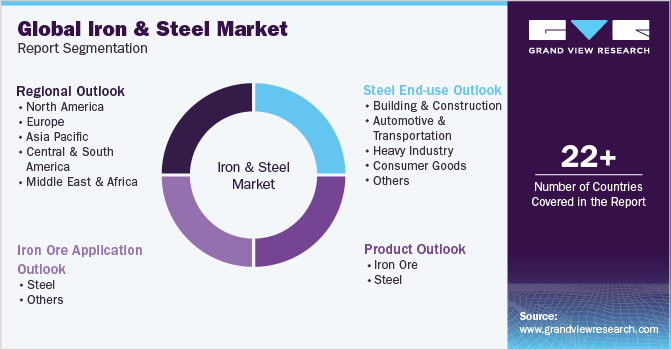
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global iron and steel market report based on product, iron ore application, steel end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Iron Ore
-
Steel
-
-
Iron Ore Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Steel
-
Other
-
-
Steel End Use Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Building & Construction
-
Automotive & Transportation
-
Heavy Industry
-
Consumer Goods
-
Other
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Spain
-
Italy
-
Russia
-
Turkey
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Iran
-
-
Frequently Asked Questions About This Report
The global iron and steel market size was valued at USD 2.0 trillion in 2025 and is estimated at USD 2.1 trillion for 2026.
The global iron and steel market is expected to grow at a CAGR of 3.8% from 2026 to 2033, reaching USD 2.7 trillion.
Key players include Arcelor Mittal S.A.; China BaoWu Steel Group Corporation Limited; Nippon Steel Corporation; HBIS Group; Jiangsu Shagang Group; POSCO HOLDINGS INC.; Tata Steel; JFE Steel Corporation; Shougang Group; Nucor Corporation; JSW; SAIL; NLMK; Techint Group; U.S. Steel Corporation
Asia Pacific dominated with a 60.0% revenue share in 2025.
Iron ore dominated the iron and steel market with a share of 90.0% in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


