
- Home
- »
- Communication Services
- »
-
K-12 Education Market Size & Share Report, 2026-2033GVR Report cover

K-12 Education Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Elementary School (K-5), Middle School (6-8), High School (9-12)), By Institution (Public, Private), By Delivery Mode (Online, Offline), By Region, And Segment Forecasts
Market Size, 2025
$3,127.4BMarket Estimate, 2026
$3,512.1BMarket Forecast, 2033
$8,160.7BCAGR, 2026–2033
12.8%K-12 Education Market Summary
The global K-12 education market size was valued at USD 3,127.4 billion in 2025 and is projected to grow from USD 3,512.1 billion in 2026 to USD 8,160.7 billion by 2033, growing at a CAGR of 12.8% from 2026 to 2033. North America dominated the global market with the largest revenue share of 35.8% in 2025. The market is driven by rising demand for artificial intelligence, adaptive learning platforms, and data-driven assessment tools in K-12 education, enabling personalized learning experiences and real-time tracking of academic progress.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: High school (9-12) segment led the market with the largest revenue share of 46.9% in 2025
- By institution: Public segment led the market with the largest revenue share of 58.7% in 2025.
- By delivery mode: Offline segment led the market with the largest revenue share of 96.2% in 2025.
Regional Highlights
- Largest regional market: North America (35.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3127.4 Billion
- Estimated market size in 2026: USD 3512.1 Billion
- Projected market size by 2033: USD 8160.7 Billion
- CAGR (2026-2033): 12.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, the integration of advanced technologies, such as artificial intelligence, which enables personalized tutoring and real-time feedback, and virtual/augmented reality, creates immersive learning environments. Additionally, there is an increase in government initiatives globally, with a focus on increased funding for K-12 education, STEM education, and the implementation of educational reforms aimed at enhancing teaching methods and overall education quality.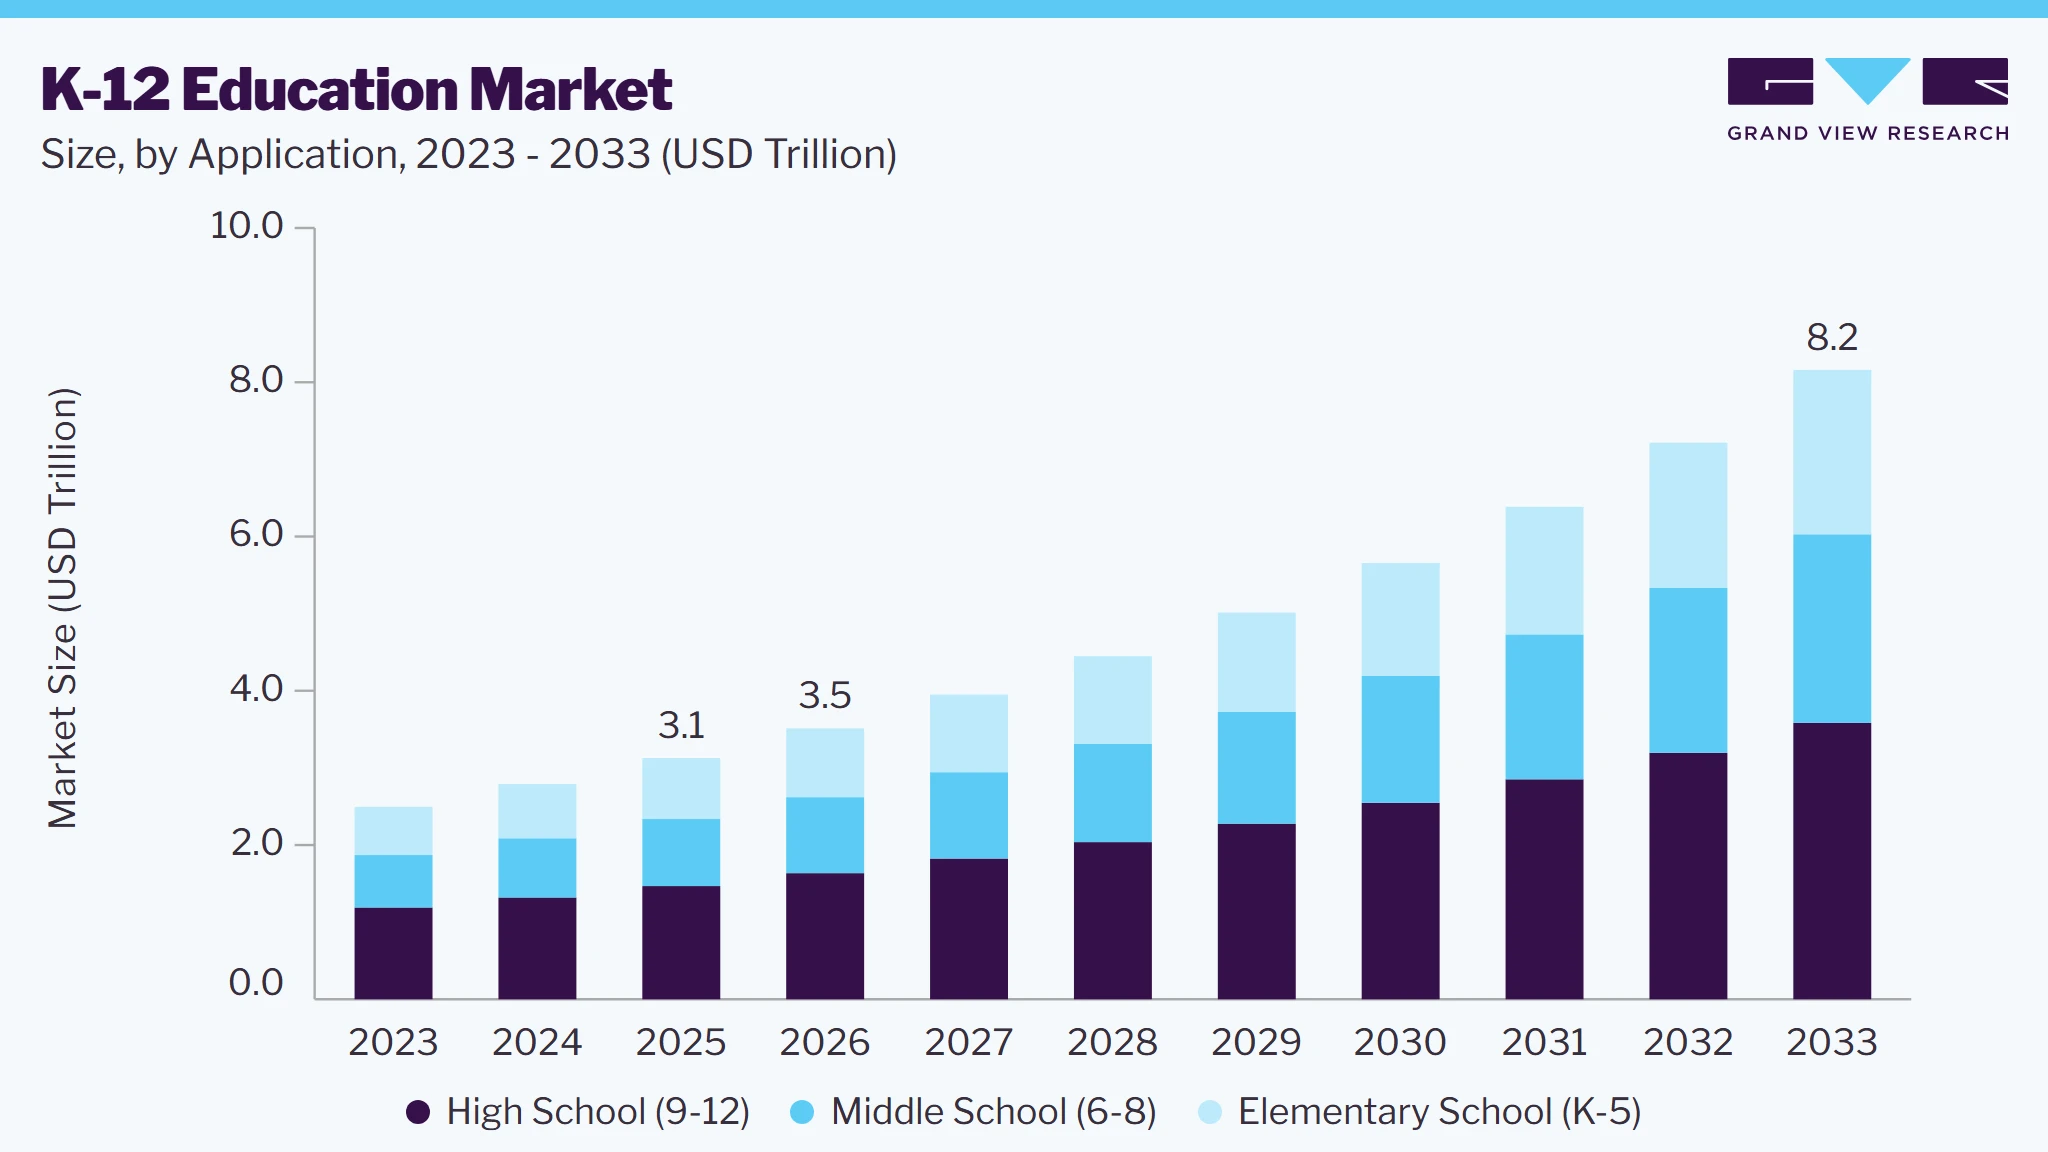 To learn more about this report, Download Free Sample Report
EdTech solutions are increasingly being adopted for K-12 education to overcome challenges regarding student learning and make students more independent and self-directed. EdTech is transforming K-12 education through personalized learning platforms, interactive tools, and real-time feedback, addressing challenges, and enhancing the learning experience. For instance, in November 2021, a survey conducted by the National Center for Education Statistics (NCES) stated that about 35% of the public schools agreed that technology helped students’ self-pace their courses. The data also suggested that 40% of the schools mentioned their students learned more actively, and another 27% claimed technology increased critical thinking capabilities.
Increased government investment in K-12 education is a major driver of market growth, funding schools with additional resources for teachers, technology, and educational materials. This enhanced funding results in improved infrastructure, curriculum development, and teacher training, thus attracting more students and families to the education system. Governments are strategically allocating funds to specific areas such as early childhood education, STEM education, and vocational training, generating new demand for specialized services and products within the market. Furthermore, increased government funding often encourages private-sector partnerships, providing opportunities for businesses including educational technology companies, content creators, and service providers to meet the expanding needs of schools and students.
Market Dynamics
The K-12 education market is expanding due to the increasing integration of digital learning technologies that support personalized instruction, interactive classrooms, and hybrid education models. Rising investments in school infrastructure, learning management platforms, and connected devices are improving access to quality education across public and private institutions. Governments and educational organizations are also emphasizing curriculum modernization and digital literacy, encouraging schools to adopt technology-enabled teaching methods that enhance student engagement and learning outcomes.
The growing adoption of digital and hybrid learning models is a major factor driving the K-12 education market, as schools increasingly combine classroom instruction with online learning to improve flexibility and accessibility. Educational institutions are investing in learning management systems, digital content platforms, and connected devices to support continuous learning and enhance student engagement. These technologies enable teachers to deliver personalized instruction, monitor student progress, and provide interactive learning experiences across different subjects.
The expansion of reliable internet connectivity and cloud-based education platforms has further accelerated the adoption of hybrid learning in both urban and rural schools. Governments and private institutions are also supporting digital education initiatives through funding programs, teacher training, and curriculum modernization, encouraging long-term integration of technology into K-12 classrooms. This sustained transition toward technology-enabled learning environments continues to increase demand for digital education solutions and related services across the K-12 ecosystem.
Many K-12 schools, particularly public institutions and those in rural or underserved regions, operate under constrained budgets that limit their ability to invest in advanced educational technologies. The adoption of digital classrooms, AI-enabled learning platforms, interactive displays, student devices, and secure IT infrastructure requires substantial upfront capital, making large-scale implementation difficult for many school systems. In addition to initial investments, schools must allocate ongoing funding for software subscriptions, system maintenance, cybersecurity, teacher training, and technology upgrades. These regular expenses can delay technology adoption and widen the digital gap between well-funded and resource-constrained schools.
Artificial intelligence creates significant opportunities in the K-12 education market by enabling personalized learning experiences focused on individual student needs, learning pace, and academic performance. AI-powered platforms analyze learning patterns and provide adaptive content, automated assessments, and targeted recommendations, helping educators improve student engagement and achievement.
As schools continue to invest in digital transformation, demand for intelligent tutoring systems, AI-assisted lesson planning, and predictive analytics is increasing. Technology providers have an opportunity to collaborate with educational institutions to develop scalable, curriculum-aligned AI solutions that enhance learning outcomes while supporting teachers with data-driven instructional insights.
Market Concentration & Characteristics
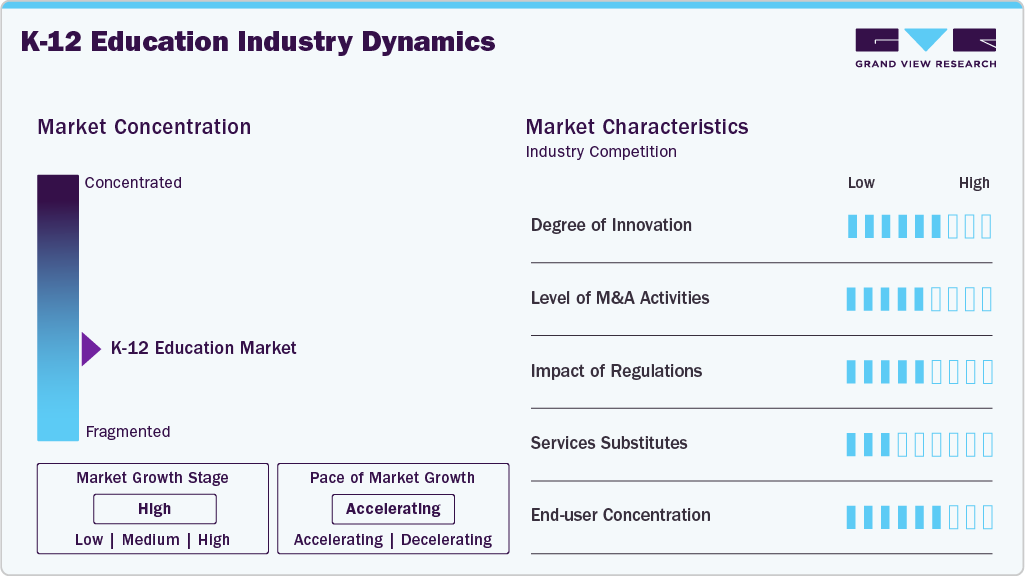
Innovation remains a defining characteristic of the K-12 education market as schools increasingly adopt AI-powered personalized learning, adaptive assessments, gamification, and immersive technologies such as AR and VR. Cloud-based collaboration platforms, digital content, and analytics-driven teaching tools continue to reshape classroom experiences. Vendors are investing heavily in research and development to improve learning outcomes and enhance teacher productivity.
 To learn more about this report, Download Free Sample Report
The K-12 education market has a relatively high level of end-user concentration, with public school systems, private school networks, and educational districts representing the primary customer base. Large-scale procurement by governments and school authorities accounts for a substantial share of technology adoption and purchasing decisions. As institutions increasingly invest in digital learning infrastructure, vendors continue to focus on long-term contracts and enterprise-wide deployments.
Analyst Perspective
The K-12 education market is entering a phase where long-term value is shifting from standalone digital learning tools to integrated education ecosystems that combine curriculum delivery, learning management, assessment, collaboration, and AI-driven personalization on a single platform. Rising investments in digital classrooms, government-led education modernization initiatives, and increasing demand for hybrid learning models are expanding technology adoption across schools. The defining competitive advantage, however, belongs to providers that seamlessly connect student learning data, teacher workflows, administrative functions, and personalized instruction into a unified ecosystem, enabling continuous academic support, measurable learning outcomes, and sustained institutional engagement rather than isolated classroom solutions.
Application Insights
Based on application, the high school (9-12) segment led the market with the largest revenue share of 46.9% in 2025 and is expected to grow at a significant CAGR over the forecast period. The segment's growth is driven by an increased focus on college and career readiness, prompting a demand for programs that cultivate critical skills such as problem-solving and communication. The integration of technological advancements, significantly in educational technology tools, places high schools at the forefront of personalized learning and academic improvement. Diversification in educational pathways, including vocational programs and internships, attracts a broader student base, while the pressure of standardized testing and college admissions fuels demand for test preparation services. Additionally, government initiatives investing in high school education contribute to the segment’s growth.
The middle school (6-8) segment is predicted to foresee significant growth in the forecast period. The rising demand for quality education is driving the segment's growth as parents increasingly recognize its crucial role in their children's academic achievement. Thus, the increased awareness leads to a greater demand for well-designed and effective educational programs. Moreover, the middle school segment benefits from the growing emphasis on STEM (science, technology, engineering, and mathematics) education globally, playing a key role in fostering strong STEM programs by introducing students to these subjects at an early stage. Thus, quality education and STEM education allow the middle school segment to expand in the forecast years substantially.
Institution Insights
Based on institution, the public segment led the market with the largest revenue share of 58.7% in 2025, propelled by government initiatives such as Sarva Shiksha Abhiyan (SSA) and the Right to Education (RTE) Act, aiming to universalize access to quality education. Increased funding for public schools has enhanced infrastructure, teacher training, and learning materials. Public schools offer education at a lower cost than private schools, specifically benefitting rural areas and low-income families. Furthermore, a focus on equity and inclusion, standardized curriculum, and quality control measures contribute to the growth of public schools, supported by government investments in teacher training programs for a more professional and competent teaching workforce.
The private segment is poised for significant growth, driven by a rising demand for quality education among parents who seek alternatives to public schools. Private schools, offering smaller class sizes, experienced teachers, and curriculum, appeal to parents aiming for academic excellence for their children. Private schools emphasize individualized learning, offering flexibility in curriculum and teaching methods to cater to each student's unique needs and learning styles. Furthermore, the private sector's focus on extracurricular activities and integration of educational technologies is driving the segment's growth in the market.
Delivery Mode Insights
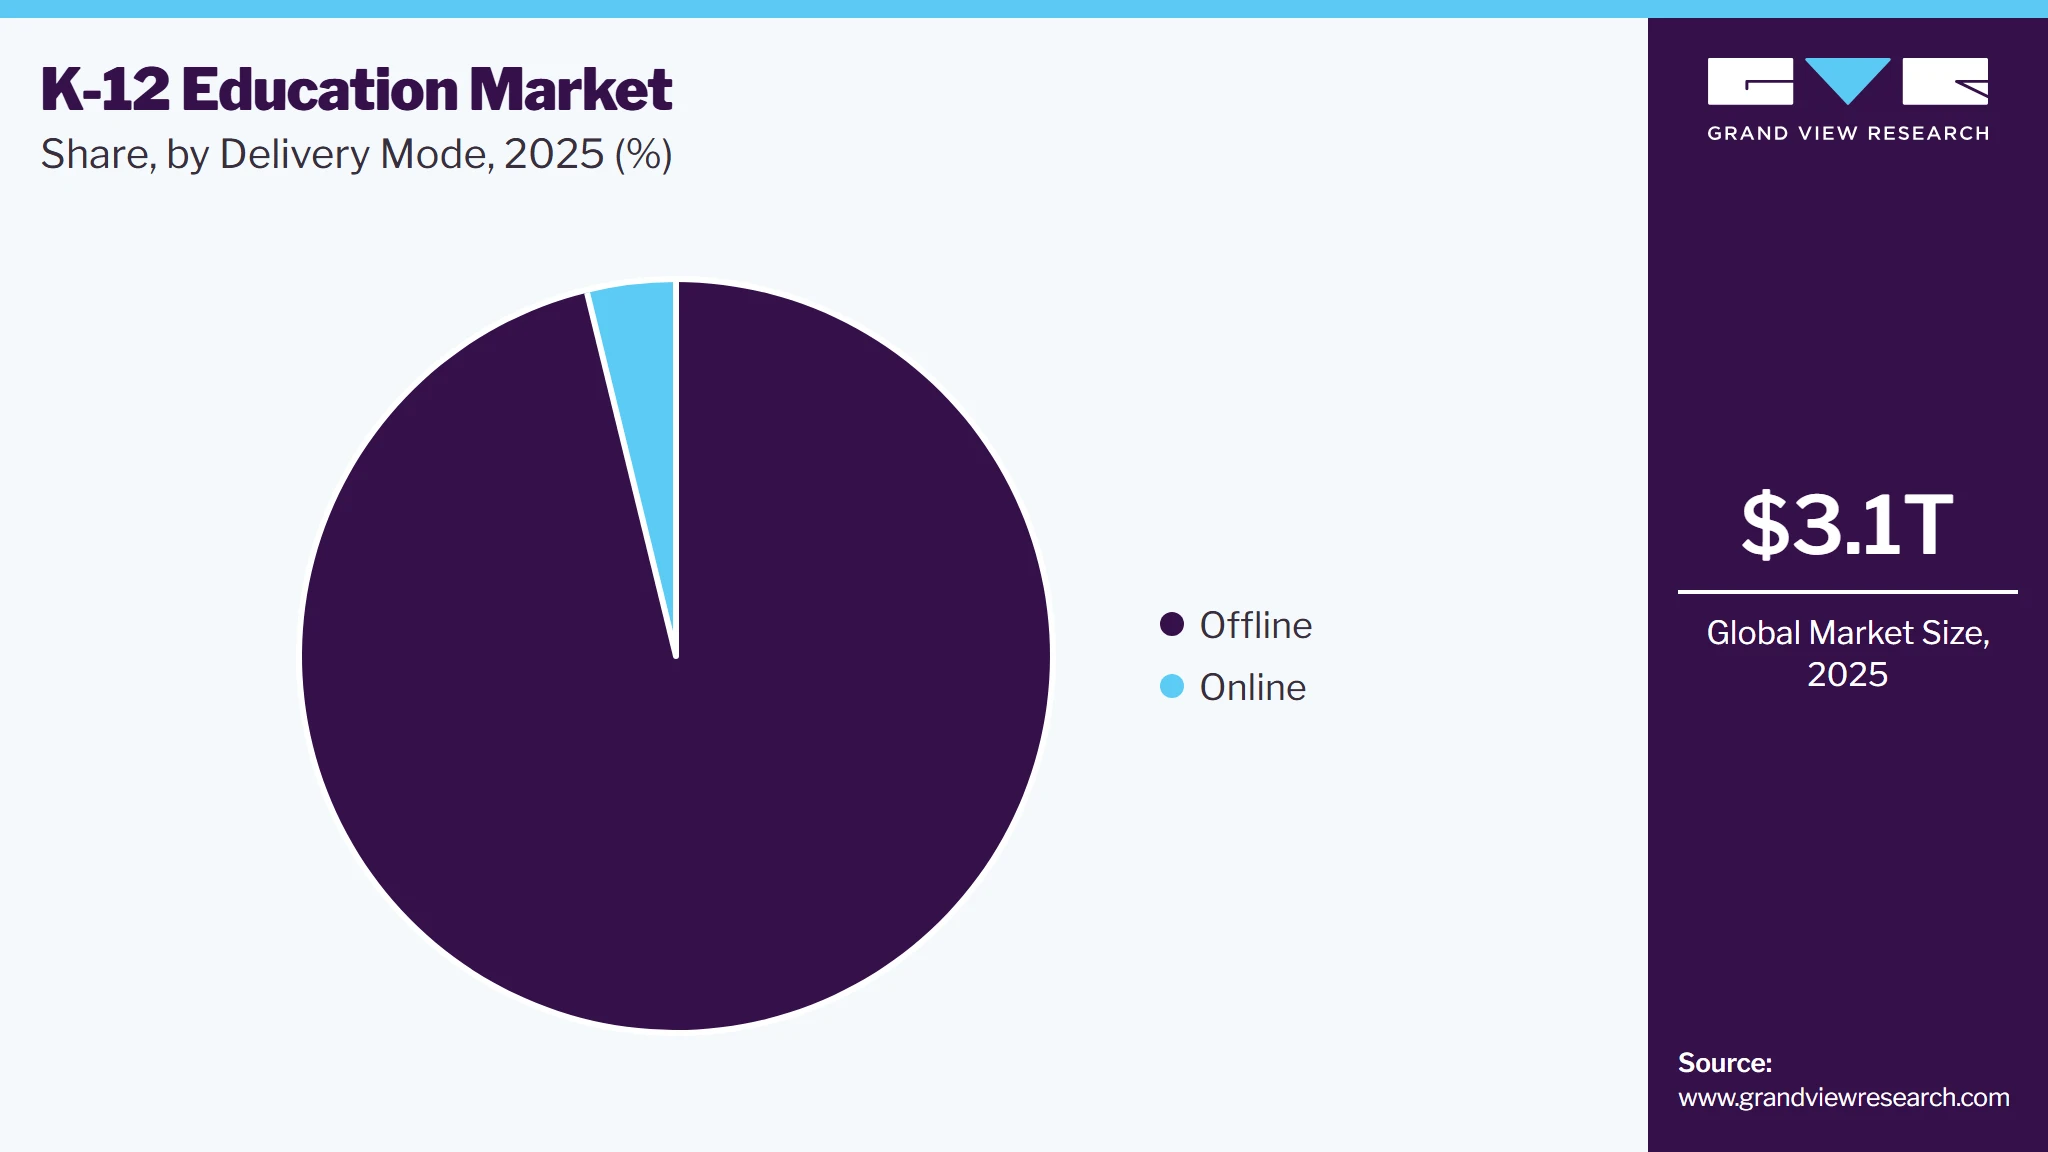
Based on delivery mode, the offline segment led the market with the largest revenue share of 96.2% in 2025 and is expected to grow at a significant CAGR over the forecast period. Traditional offline classrooms play a crucial role in the social and emotional development of the K-12 age group, facilitating peer interaction, relationship building, and hands-on learning experiences. Parental preferences for the structure of traditional classrooms, concerns about online safety, and challenges related to regulatory compliance and accreditation contribute to the continued dominance of the offline segment. Additionally, the established infrastructure of offline schools and financial barriers for families to afford online courses further support the prominence of the offline education model.
 To learn more about this report, Download Free Sample Report
The online segment is projected to witness significant growth in the coming years. Increased internet penetration and affordability are expanding access to online learning platforms, transcending geographical and socioeconomic boundaries. Growing awareness among parents and educators about the benefits of online learning, including personalized experiences, convenience, flexibility, and access to a diverse range of courses, is fueling the demand. Moreover, the COVID-19 pandemic has accelerated the demand for online education as a viable and preferable alternative to traditional classroom settings. Additionally, the online sector offers a broader array of specialized courses and accommodates diverse learning styles, further contributing to its anticipated growth.
Regional Insights
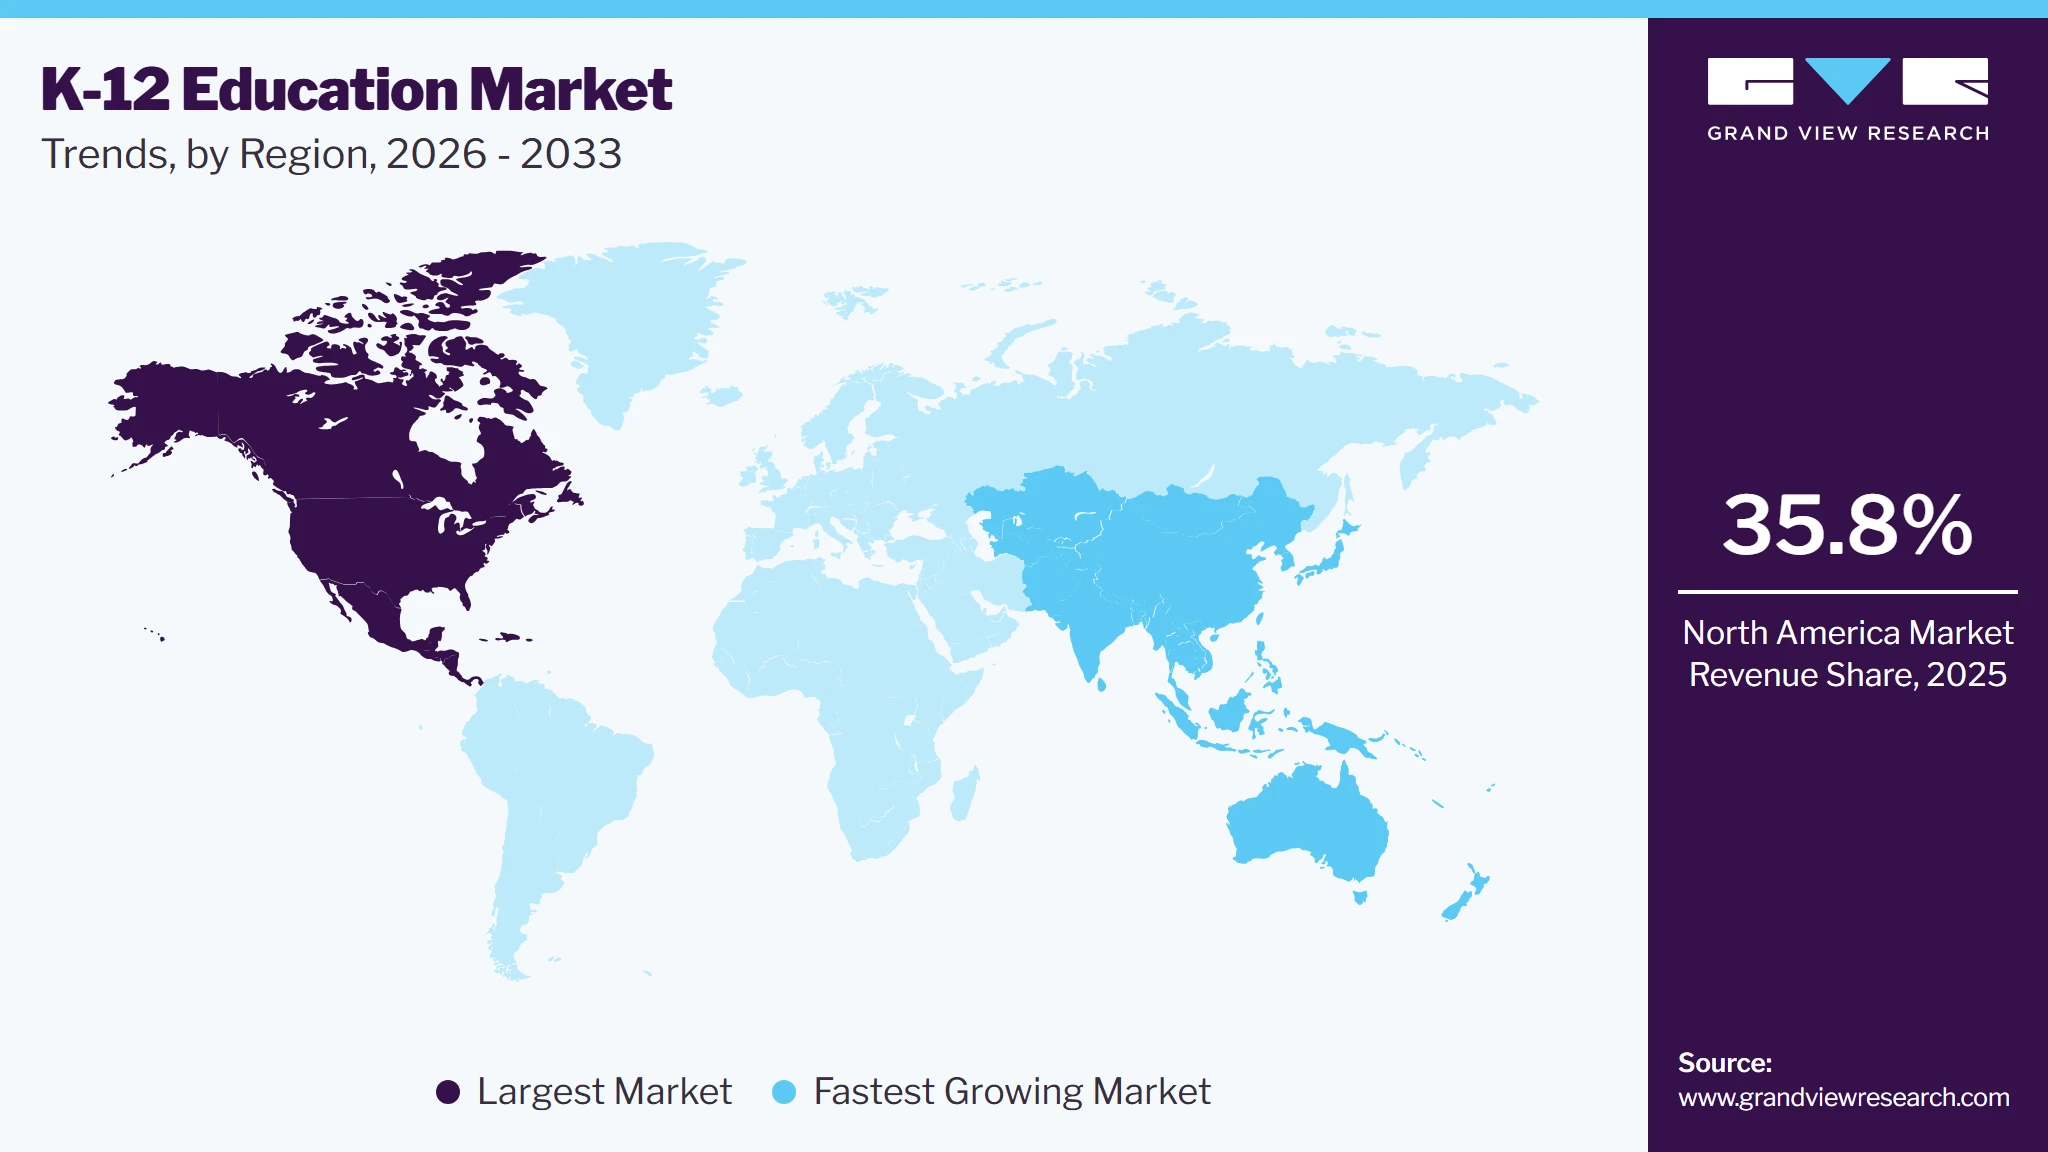
North America dominated the K-12 education market with the largest revenue share of 35.8% in 2025. The region stands at the forefront of technological advancements in education, actively integrating digital tools and platforms such as interactive whiteboards and adaptive learning software. Investment in EdTech companies, supported by substantial venture capital and government funding, fosters innovation and diverse educational solutions. High internet penetration and digital infrastructure enable widespread access to technology, facilitating online learning opportunities, resource sharing, and remote collaboration.
 To learn more about this report, Download Free Sample Report
U.S. K-12 Education Market Trends
The K-12 education market in the U.S. held the largest share in the North America region in 2025.
Asia Pacific K-12 Education Market Trends
Asia Pacific is anticipated to register the fastest CAGR over the forecast period, driven by a vast and rapidly growing population, specifically in countries such as India and China. The surge in population fuels the demand for educational opportunities at all levels, with a focus on K-12 education. The region has witnessed increased internet and mobile device penetration, accelerated by the impact of the COVID-19 pandemic, resulting in the widespread adoption of cost-effective and accessible e-learning solutions in K-12 education. Additionally, several Asian governments actively invest in K-12 education improvement through initiatives such as curriculum modernization, teacher training programs, and digital infrastructure development, further supporting the growth of the K-12 education market.
Key Companies & Market Share Insights
Some of the key players operating in the market include BYJU’S; Microsoft Corporation; Adobe Inc; Pearson; Samsung Electronics Co., Ltd.
-
BYJU'S operates its business mainly through its mobile app, where it provides specified educational content according to the learning phase of students. BYJU'S functions as a brand name for Think and Learn Private Ltd. The company's primary offering includes educational content for school students from classes 1 to 12 (primary to higher secondary).
-
Microsoft, a global technology provider, has a substantial presence in the market, offering a range of products and solutions tailored to enhance learning experiences. The company provides a comprehensive suite of education-focused tools and applications, such as Microsoft 365, Teams, and OneNote Class Notebook. These tools facilitate collaborative learning, content creation, and communication among students and educators.
-
Nearpeer focuses on providing affordable, high-quality online courses in Pakistan and the Middle East. They offer various test prep courses, skill-based courses, and high-school and intermediate-school curricula.
- Coding with Kids is a coding academy for kids and teens aged 5-18, offering educational programs both online and in-person at various locations across the U.S.
Key K-12 Education Companies:
The following key companies have been profiled for this study on the k-12 education market.
-
Oracle
-
Pearson
-
Samsung Electronics Co., Ltd.
-
Adobe Inc.
-
Microsoft
-
D2L Corporation
-
IBM Corporation
-
McGraw Hill LLC
-
Dell Inc.
-
BYJU'S
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Oracle; Pearson; Samsung Electronics Co., Ltd.; Adobe Inc; Microsoft; IBM Corporation; McGraw Hill LLC; Dell Inc.)
- Focus on integrated digital learning ecosystems combining hardware, software, cloud services, and educational content.
- Expand through strategic partnerships with schools, governments, and education institutions while continuously enhancing AI-enabled learning solutions.
- Strong global brand recognition and extensive distribution networks across education systems.
- Broad product portfolios supported by large R&D investments and long-term institutional relationships.
- Large organizational structures can extend product development and deployment timelines.
- Premium pricing and complex solution portfolios may limit adoption among budget-constrained institutions.
Emerging Players (BYJU'S; D2L Corporation)
- Focus on specialized learning platforms, personalized education, and cloud-native learning management solutions.
- Expand through subscription-based models, digital-first delivery, and partnerships with educational institutions.
- Agile product innovation and faster adoption of new educational technologies.
- Strong focus on user experience and niche learning requirements enables targeted market penetration.
- Limited global reach and smaller customer bases compared with established competitors.
- Financial and operational constraints can affect large-scale expansion and long-term market competitiveness.
Recent Developments
-
In June 2026, Microsoft Corporation announced new AI-powered teaching and learning tools alongside the release of its third annual AI in Education Report. The tools are designed to improve learning outcomes, student engagement, and critical thinking while supporting educators in adopting AI responsibly in school environments.
K-12 Education Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3,127.4 billion
Estimated market size in 2026
USD 3,512.1 billion
Projected market size by 2033
USD 8,160.7 billion
Growth rate
CAGR of 12.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, institution, delivery mode, region
Regional scope
North America, Asia Pacific; Europe; MEA; Latin America
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; New Zealand; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Oracle; Pearson; Samsung Electronics Co., Ltd.; Adobe Inc.; Microsoft; D2L Corporation; IBM Corporation; McGraw Hill LLC; Dell Inc.; BYJU'S
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global K-12 Education Market Report Segmentation
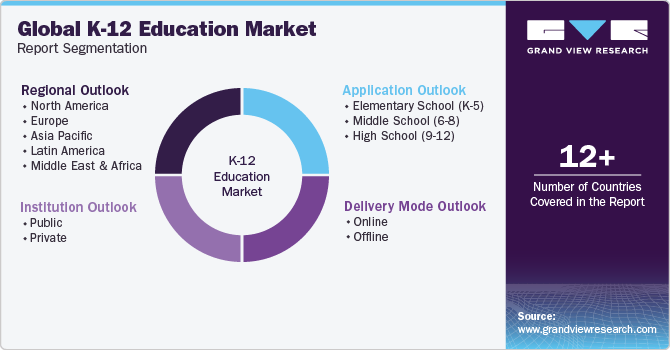
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global K-12 education market report based on application, institution, delivery mode, and region:
 To learn more about this report, Download Free Sample Report
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Elementary School (K-5)
-
Middle School (6-8)
-
High School (9-12)
-
-
Institution Outlook (Revenue, USD Billion, 2021 - 2033)
-
Public
-
Private
-
-
Delivery Mode Outlook (Revenue, USD Billion, 2021 - 2033)
-
Online
-
Offline
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
U.K.
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
New Zealand
-
-
Latin America
-
Brazil
-
Mexico
-
-
MEA
-
Kingdom of Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The k-12 education market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each k-12 education segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Application
Revenue capture definition
Elementary School (K-5)
Revenue for this segment includes digital learning platforms, foundational literacy and numeracy solutions, interactive classroom tools, and educational content designed for early childhood and primary education. It also covers teacher support applications and assessment solutions used in elementary schools.
Middle School (6-8)
This segment captures revenue generated from subject-specific learning platforms, collaborative classroom software, STEM education tools, and student assessment solutions for middle school learners. It includes applications supporting academic progression and skill development across core subjects.
High School (9-12)
Revenue in this segment comprises advanced learning platforms, college and career readiness solutions, virtual laboratories, test preparation applications, and curriculum management systems used in secondary education. It also includes digital tools supporting personalized learning and academic performance tracking.
Segment - Institution
Revenue capture definition
Public
Revenue from the public segment is generated through government-funded schools and district-wide digital education initiatives, including learning platforms, classroom technologies, and curriculum solutions. Large-scale procurement and long-term technology adoption support consistent market demand.
Private
The private segment captures revenue from independent schools investing in premium digital learning tools, personalized education platforms, and advanced classroom technologies. Greater flexibility in technology spending supports the adoption of innovative educational solutions.
Segment - Delivery Mode
Revenue capture definition
Online
The online segment captures revenue from virtual learning platforms, live instructor-led classes, self-paced digital courses, and subscription-based educational services delivered through internet-enabled devices. Revenue also includes learning management systems, digital assessments, and interactive educational content.
Offline
The offline segment generates revenue through classroom-based instruction delivered in public and private schools, supported by physical learning materials and in-person teaching. It also includes income from tuition fees, textbooks, laboratory activities, and campus-based educational services.
Estimation Model
Layer Name
Key Questions
Description
Student Population Layer
Who requires K-12 education?
Identify the school-age population eligible for kindergarten through grade 12 education. This establishes the total addressable student base across public, private, and alternative schooling systems.
Enrollment Layer
How many students are enrolled?
Apply enrollment and school attendance rates to estimate the number of students actively participating in K-12 education. This converts the eligible population into the active learner base.
Delivery Mode Layer
How is education delivered?
Measure the distribution of students across offline classroom learning, online learning, and hybrid education models. This reflects the adoption of different education delivery channels within the market.
Monetization Layer
How much revenue is generated?
Apply the average annual spending per student, including tuition, digital learning platforms, educational content, assessment services, and related school expenditures, to estimate total market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Market Entry & Expansion Assessment
Regional demand sizing and forecasting
Customer segmentation and buying behavior analysis
Competitive landscape benchmarking
Regulatory and distribution channel assessment
Identified high-growth market opportunities
Supported go-to-market strategy development
Highlighted investment priorities and risks
Enabled data-driven expansion planning
Channel Partner & Distribution Study
Dealer/distributor network analysis
Channel performance benchmarking
Margin and profitability assessment
Route-to-market evaluation
Optimized channel strategy
Identified distribution gaps
Improved partner engagement approach
Enhanced market penetration planning
Customer & End-User Insights Study
Consumer awareness and adoption analysis
Purchase decision journey mapping
Satisfaction and loyalty assessment
Usage pattern and pain-point evaluation
Revealed key adoption drivers and barriers
Supported customer-centric product development
Improved targeting and engagement strategy
Identified opportunities for retention and upselling
Frequently Asked Questions About This Report
Some key players operating in the K-12 education market include Oracle; Pearson; Samsung Electronics Co., Ltd.; Adobe Inc.; Microsoft; D2L Corporation; IBM Corporation; McGraw Hill LLC; Dell Inc.; BYJU'S
Asia Pacific is the fastest-growing region over the forecast period.
The High School (9-12) segment led with a 46.9% revenue share in 2025, while Middle School (6-8) is the fastest growing segment.
public held the largest revenue share in 2025, while private is the fastest growing segment.
Offline held the largest revenue share in 2025, while online is the fastest growing segment.
The global k-12 education market size was valued at USD 3,127.4 billion in 2025 and is projected to grow from USD 3,512.1 billion in 2026
The global k-12 education market is expected to grow at a CAGR of 12.8% from 2026 to 2033, reaching USD 8,160.7 billion by 2033
North America dominated the market and accounted for a 35.8% in 2025. The region stands at the forefront of technological advancements in education, actively integrating digital tools and platforms such as interactive whiteboards and adaptive learning software. Investment in EdTech companies, supported by substantial venture capital and government funding, fosters innovation and diverse educational solutions.
The market is driven by rising demand for artificial intelligence, adaptive learning platforms, and data-driven assessment tools in K-12 education, enabling personalized learning experiences and real-time tracking of academic progress.
About the Author(s)
Communication Services Research Team
Technology · Communication ServicesThis report was authored by the communication services research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the communication services segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


