
- Home
- »
- Food Additives & Nutricosmetics
- »
-
Lactulose Market Size, Share & Trends Report, 2026-2033GVR Report cover

Lactulose Market (2026 - 2033)
Size, Share & Trends Analysis Report By Form (Syrup/Liquid, Powder, Crystalline), Function (Sweetening Agent, Laxative, Hepatic Encephalopathy), By Application (Food & Beverage, Pharmaceutical), By Region, And Segment Forecasts
Market Size, 2025
$536.2MMarket Estimate, 2026
$568.9MMarket Forecast, 2033
$897.8MCAGR, 2026–2033
6.7%Lactulose Market Summary
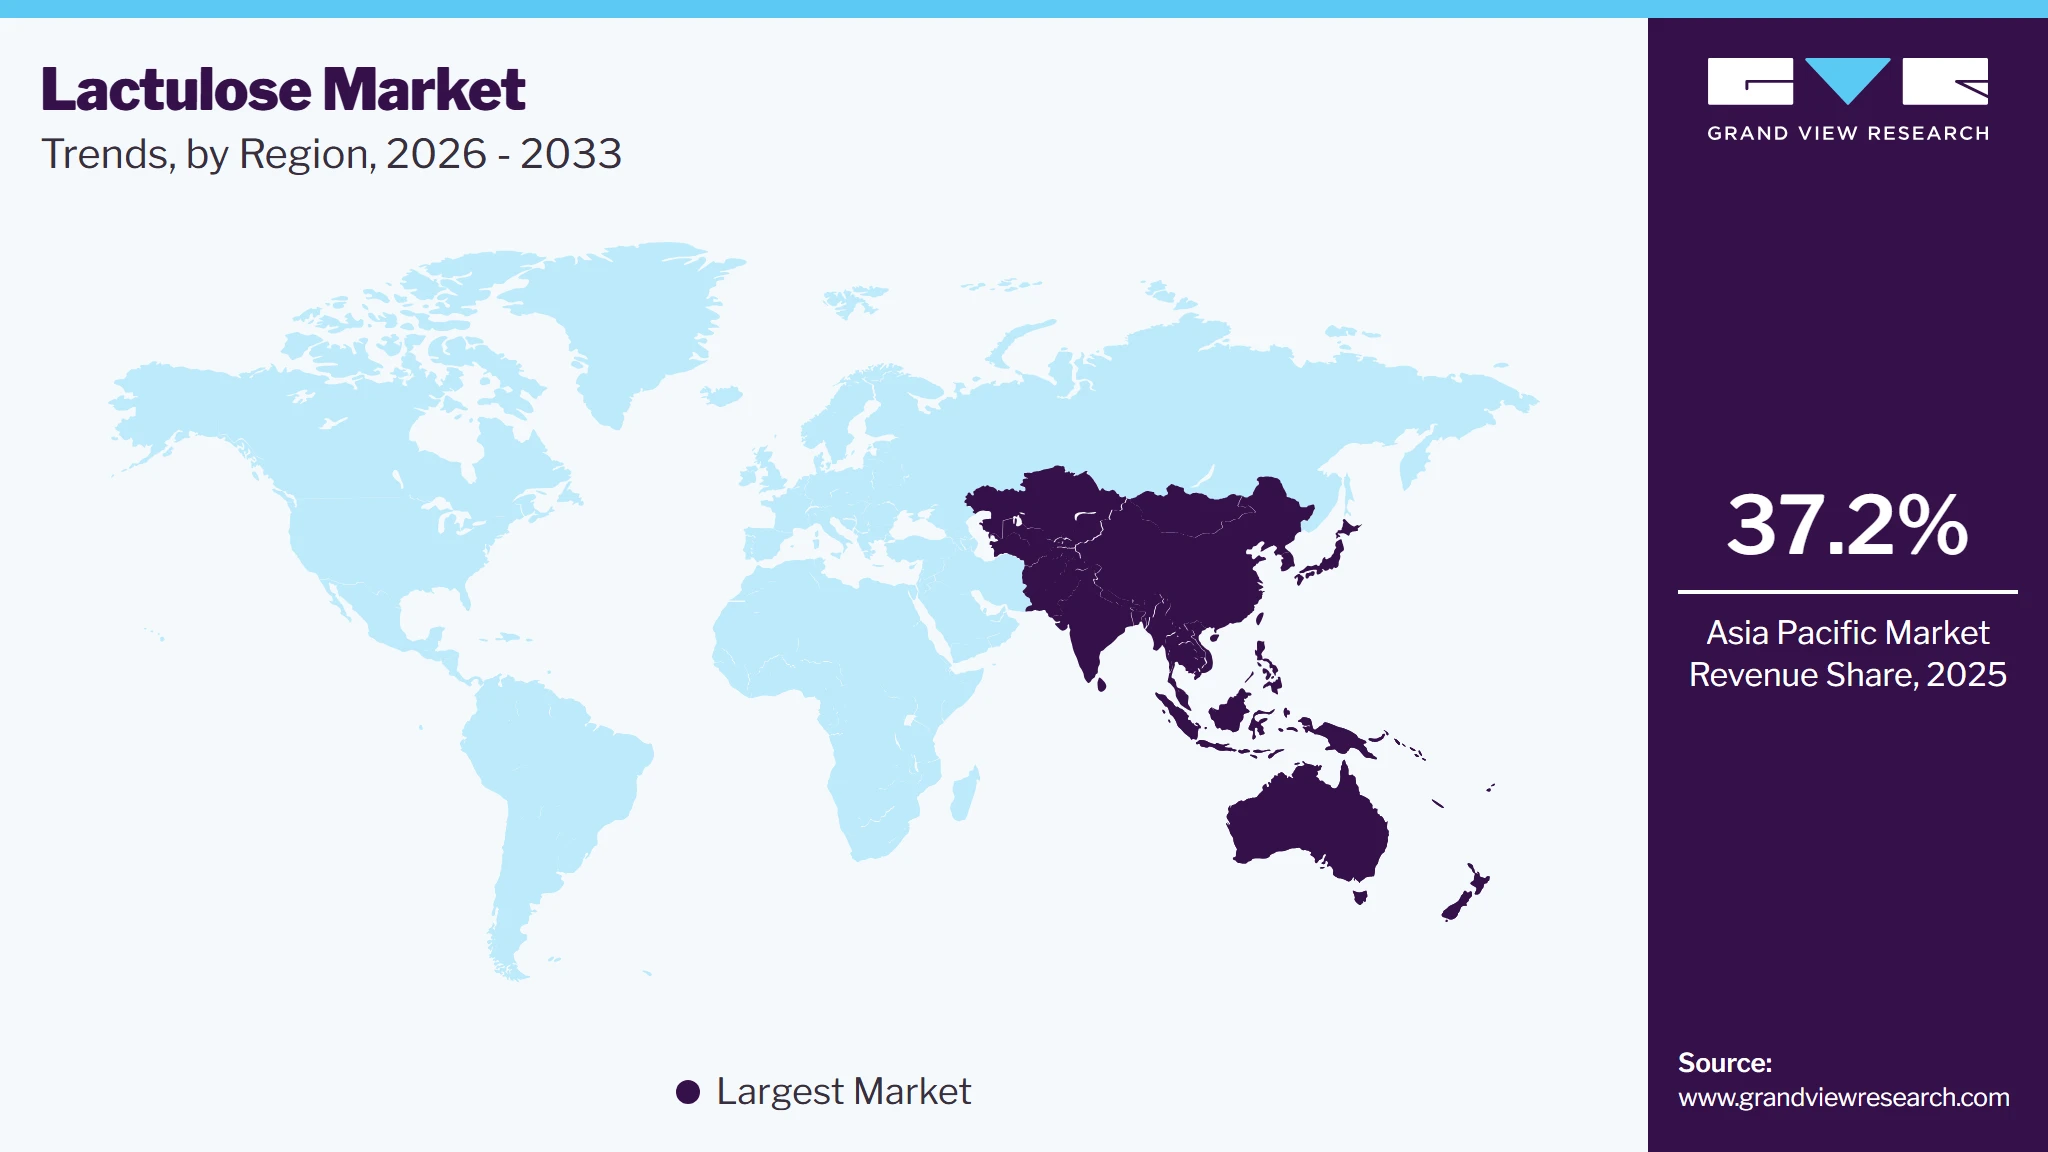
The global lactulose market size was valued at USD 536.2 million in 2025 and is projected to grow from USD 568.9 million in 2026 to USD 897.8 million by 2033, growing at a CAGR of 6.7% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest global share of 37.2% in 2025. The lactulose market is growing due to rising demand for digestive health solutions and increasing cases of constipation and liver-related issues.
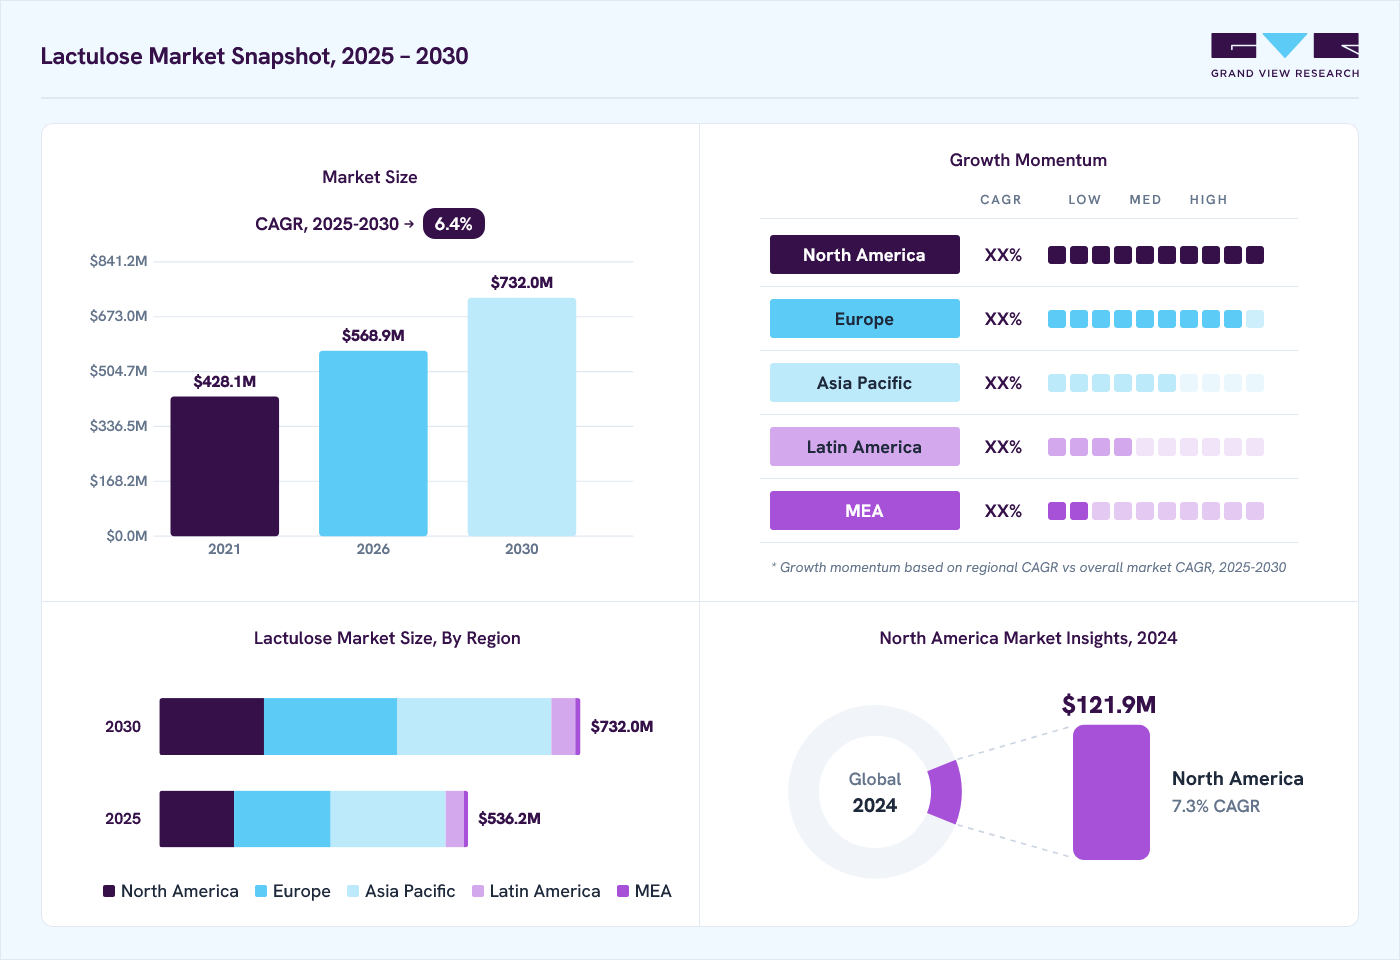 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By form: Syrup/liquid segment dominated the market with a share of 57.5% in 2025.
- By function: Laxative segment held the largest share of 69.8% in 2025.
- By application: Pharmaceutical segment held the largest share of 77.5% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (37.2% revenue share, 2025)
- By country: The China held the largest share of Asia Pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 536.2 Million
- Estimated market size in 2026: USD 568.9 Million
- Projected market size by 2033: USD 897.8 Million
- CAGR (2026-2033): 6.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Its role as a safe and effective treatment, especially for laxative and hepatic uses, supports this trend. Growing awareness about gut health and the benefits of prebiotics also adds to its demand. As people seek better health management, lactulose continues to see steady use in both medical and nutritional areas.
The increasing awareness of gut health and its impact on overall well-being has driven the demand for prebiotic ingredients like lactulose. As a non-digestible sugar, lactulose reaches the colon intact, where it serves as food for beneficial gut bacteria, such as bifidobacteria and lactobacilli. With the rise in digestive disorders like irritable bowel syndrome (IBS), bloating, and constipation, consumers are actively seeking functional foods and supplements that support gut microbiota balance.
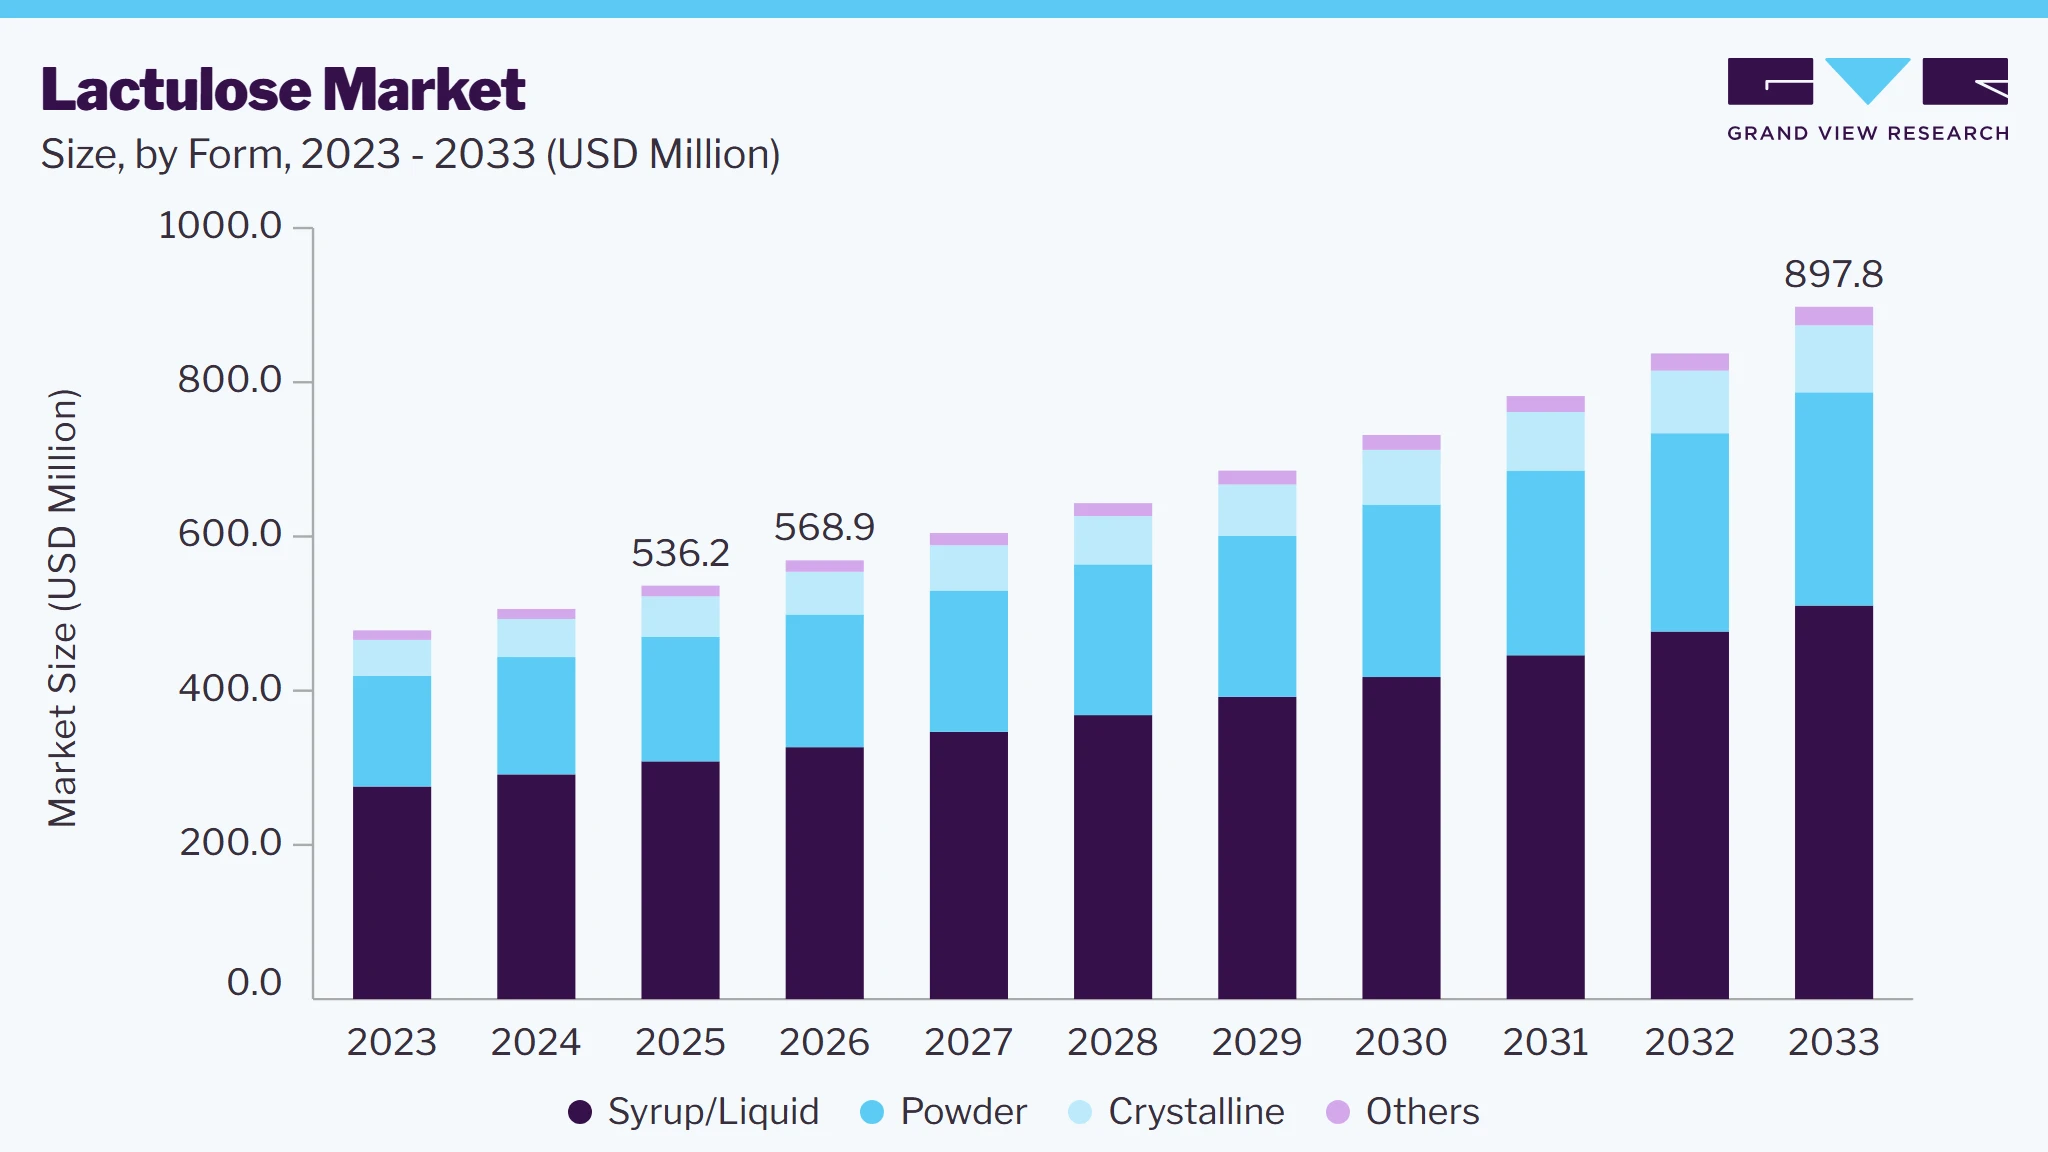 To learn more about this report, Download Free Sample Report
Companies have responded by incorporating prebiotic ingredients into their products, including fermented dairy, functional beverages, and dietary supplements. For instance, lactulose has been added to probiotic yogurt formulations in Japan to enhance the effectiveness of live cultures, leading to better digestion and nutrient absorption. The global functional food market, valued at over USD 200 billion, is expanding rapidly due to the growing demand for natural solutions to improve gut health, making lactulose an attractive ingredient for manufacturers.
Lactulose plays a critical role in the treatment of hepatic encephalopathy (HE), a severe neurological condition caused by liver failure, where toxins like ammonia accumulate in the blood and affect brain function. Patients with cirrhosis, a major cause of HE, rely on lactulose to reduce ammonia levels by promoting its excretion through frequent bowel movements. The World Journal of Hepatology highlights lactulose as a first-line treatment for HE, often prescribed alongside antibiotics like rifaximin. For example, in the United States, where over 4.5 million adults suffer from chronic liver disease, hospitals frequently administer lactulose to prevent HE-related complications, such as confusion and coma.
The lactulose market is fragmented, with several global and regional players competing. Dominated by pharmaceutical and nutraceutical sectors, the market sees steady demand growth, driven by rising gastrointestinal disorders and increased awareness of gut health and prebiotic benefit.
Market Dynamics
The lactulose market is experiencing steady growth, driven by the increasing prevalence of chronic constipation and hepatic encephalopathy, rising awareness of gastrointestinal health, and expanding demand for effective osmotic laxatives. Lactulose is widely used in the treatment of constipation by promoting bowel movements and in managing hepatic encephalopathy by reducing blood ammonia levels. The growing geriatric population, increasing incidence of digestive disorders, and improved access to healthcare services are supporting market expansion. In addition, ongoing improvements in pharmaceutical formulations and rising healthcare expenditure across emerging economies are expected to further boost demand for lactulose during the forecast period.
The increasing incidence of chronic constipation and liver-related disorders is a major driver of the lactulose market. Sedentary lifestyles, poor dietary habits, aging populations, and rising rates of gastrointestinal disorders have significantly increased the demand for safe and effective laxatives. Lactulose remains one of the preferred treatment options due to its proven efficacy, favorable safety profile, and suitability for long-term use, including among elderly and pediatric patients.
The growing burden of chronic liver diseases has increased the use of lactulose in managing hepatic encephalopathy by lowering ammonia absorption in the intestines. Expanding healthcare infrastructure, improved diagnosis rates, and greater physician awareness are further contributing to sustained market growth.
The availability of alternative treatments for constipation, including polyethylene glycol, stimulant laxatives, fiber supplements, and newer prescription medications, poses a challenge to the lactulose market. In many regions, healthcare providers and patients may opt for these alternatives depending on treatment effectiveness, cost, and patient preference.
Lactulose may cause side effects such as bloating, flatulence, abdominal discomfort, and diarrhea, particularly during the initial stages of treatment or when consumed in higher doses. These adverse effects may reduce patient compliance and limit its adoption in certain cases. Pricing pressures from generic products and reimbursement challenges in some healthcare systems may also restrain market growth.
Rising healthcare investments and improving access to medical services in emerging economies present significant opportunities for the lactulose market. Increasing awareness of digestive health, expanding pharmaceutical distribution networks, and higher diagnosis rates of gastrointestinal and liver disorders are supporting greater adoption of lactulose-based therapies.
The rapidly growing geriatric population, which is more susceptible to chronic constipation and liver-related complications, is expected to generate sustained demand for lactulose. Additionally, continued product innovations, improved oral formulations, and expanding applications in preventive gastrointestinal care are creating new growth opportunities for manufacturers. As healthcare systems increasingly focus on improving quality of life for aging populations, the lactulose market is expected to witness steady expansion throughout the forecast period.
Market Concentration & Characteristics
The market is fragmented, with global players such as Abbott, Fresenius, Morinaga Milk Industry Co., Ltd., Illovo, and Daiichi Sankyo holding significant shares due to strong distribution networks and brand trust. However, regional players and emerging brands are entering the space with competitively priced alternatives, especially in developing countries, leading to healthy competition and innovation.
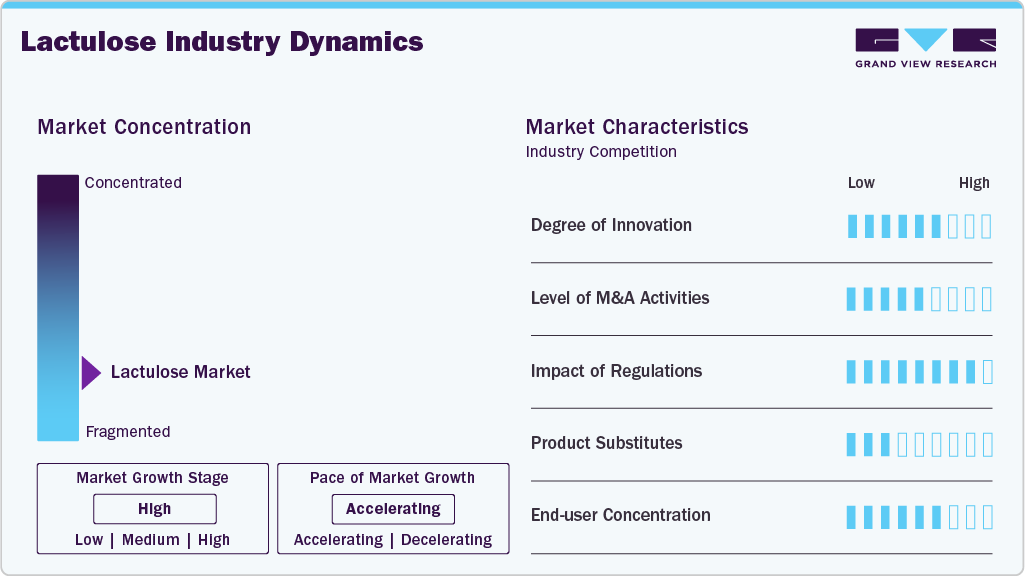 To learn more about this report, Download Free Sample Report
The lactulose market is characterized by its strong alignment with the pharmaceutical and nutraceutical sectors, as it is primarily used as a synthetic disaccharide for treating constipation and hepatic encephalopathy. Derived from lactose, lactulose functions as a non-digestible sugar that promotes colonic acidification and osmotic effects, stimulating bowel movements. The market is heavily prescription-driven, particularly in developed regions like North America, Europe, and Japan, where healthcare systems actively support therapeutic use of lactulose-based formulations.
Analyst Perspective
The global lactulose market is positioned for steady growth, driven by the rising prevalence of chronic constipation and hepatic encephalopathy, increasing awareness of gastrointestinal health, and expanding access to healthcare services worldwide. Lactulose syrup continues to account for a significant share of the market owing to its established clinical efficacy, favorable safety profile, and widespread use in treating constipation and reducing blood ammonia levels in patients with liver disorders. Furthermore, the growing geriatric population, increasing incidence of digestive disorders, and expanding pharmaceutical manufacturing capacity are supporting market demand. Continuous advancements in pharmaceutical formulations, broader adoption of prebiotic ingredients in functional foods, and rising healthcare investments in both developed and emerging economies are expected to further strengthen the growth of the lactulose market during the forecast period.
Form Insights
Syrup/liquid dominated the product type segment at a revenue share of 57.5% in 2025. This dominance is largely due to its extensive use in the pharmaceutical industry, particularly for the treatment of constipation and hepatic encephalopathy. Lactulose syrup is a widely prescribed laxative, especially for elderly patients, children, and individuals with chronic digestive issues. For example, in countries with aging populations such as Japan, Germany, and the United States, the demand for gentle, effective laxatives has increased significantly.
The powder segment is expected to grow fastest with a CAGR of 6.9% from 2025-2030 during the forecast period. The growth of this segment is driven primarily by its suitability for industrial and bulk applications, especially in nutraceuticals, functional foods, and dietary supplements. Unlike the syrup form, lactulose powder is favored in the food and beverage industry, where manufacturers require ingredients with longer shelf life, higher stability, and easy integration into powdered formulations like infant nutrition products, prebiotic drinks, and supplement capsules.
Function Insights
Laxative segment held the largest share of 69.8% in 2025. This dominance is due to its long-standing and widespread use in treating constipation, especially in chronic and age-related cases. Lactulose is a non-absorbable sugar that draws water into the colon, softening stools and stimulating bowel movements. It is preferred over harsher laxatives because of its gentle action and safety, even for infants, pregnant women, and the elderly.
The sweetening agents segment is expected to grow fastest with a CAGR of 7.3% during the forecast period. Although this is a relatively small segment, it plays a specific and valuable role in health-focused food and beverage applications. Lactulose is a low-calorie sweetener with prebiotic properties, making it attractive for functional foods, diabetic-friendly products, and infant nutrition. It provides mild sweetness while promoting gut health by stimulating the growth of beneficial bacteria like Bifidobacteria in the colon.
Applications Insights
Pharmaceutical projected for the largest market share of 77.5% in 2025. This segment is primarily driven by the two major therapeutic uses of lactulose: as a laxative and in the treatment of hepatic encephalopathy (HE). Lactulose’s role as a laxative is well-established, widely prescribed, and available over-the-counter for treating chronic constipation, particularly in the elderly, pregnant women, and children due to its gentle, non-irritating mechanism. Its effectiveness, safety profile, and ability to restore healthy bowel movements have made it a staple in both home and hospital settings.
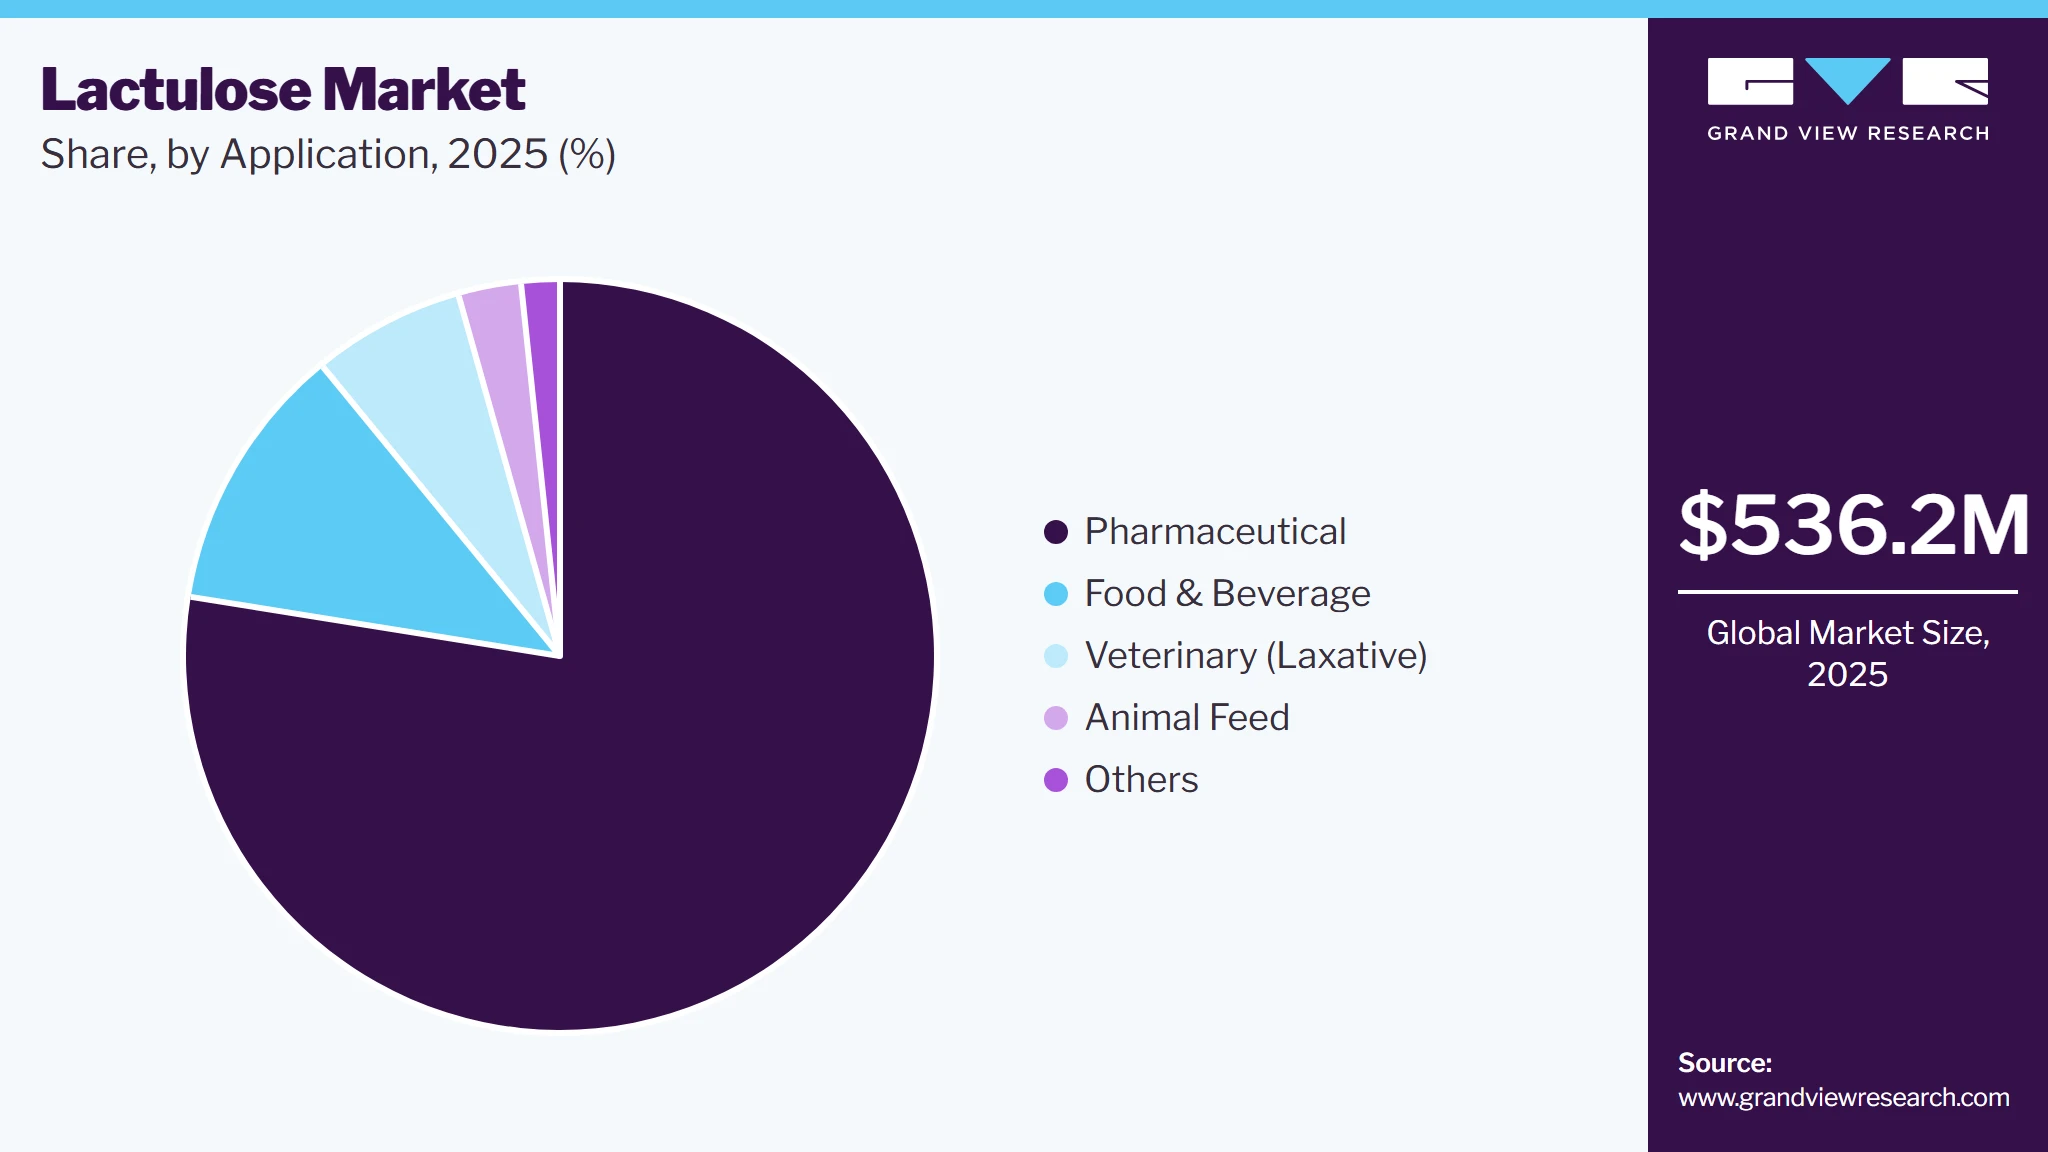 To learn more about this report, Download Free Sample Report
Animal feed is expected to grow the fastest with a CAGR of 8.0% during the forecast period. Lactulose is used as a dietary supplement and functional additive in animal feed, especially for young livestock like calves and piglets, where it promotes the development of beneficial gut bacteria, improving digestion and nutrient absorption. Its prebiotic effect helps maintain gut flora balance, reduce pathogenic bacteria, and enhance immune response, which is crucial in high-density farming environments.
Regional Insights
Asia Pacific accounted for 37.2% of the lactulose market revenue in 2025, making it the largest regional market. This growth is largely driven by the sheer population size, urbanization, and rising awareness of gut and liver health. Countries like China, India, and Japan are the primary growth hubs due to large aging populations, expanding middle-class healthcare spending, and a rise in lifestyle-related digestive disorders.
 To learn more about this report, Download Free Sample Report
China Lactulose Market Trends
China held the highest market revenue share in Asia Pacific in 2025. China lactulose marketis driven primarily by the increasing prevalence of gastrointestinal disorders, particularly chronic constipation and hepatic conditions like hepatic encephalopathy. China's aging population, which is expected to exceed 400 million aged 60+ by 2035, is particularly prone to such conditions, boosting demand for effective and safe laxatives such as lactulose. Growing health awareness and an expanding middle-class population are fueling demand for digestive health supplements, functional foods, and OTC pharmaceuticals.
Europe Lactulose Market Trends
The growth of Europe lactulose market is driven by the region’s aging population - by 2030, over 25% of the EU population will be aged 65 or older, leading to a higher incidence of chronic constipation and hepatic encephalopathy (HE). Countries like Germany, France, Italy, and the UK are leading consumers due to well-established healthcare systems and high pharmaceutical usage. Lactulose is widely used as an over-the-counter laxative and is included in several national clinical guidelines for treating HE. The European Food Safety Authority (EFSA) has approved lactulose as a prebiotic ingredient, boosting its use in functional foods and infant nutrition, particularly in markets like the Netherlands and Scandinavia, where digestive health products are popular.
North America Lactulose Market Trends
The North America lactulose market also sees strong demand in pediatric care, with liquid formulations like 10g/15ml syrup commonly used for children due to their mild effect and sweet taste. In Canada, the rise in digestive health supplements has made lactulose a notable prebiotic in food and nutraceuticals. Meanwhile, Mexico’s expanding generic drug industry and improvements in healthcare coverage are driving accessibility. North America also leads in veterinary use, with lactulose being prescribed for cats and dogs suffering from constipation or liver issues. Increasing consumer awareness, insurance reimbursements, and high per capita healthcare expenditure make this region highly lucrative for both domestic manufacturers and exporters of lactulose-based products.
The U.S. lactulose market is characterized by advanced medical facilities and a high diagnosis rate, which supports the consistent usage of lactulose. Additionally, a growing emphasis on gut health, prebiotic supplementation, and functional foods contributes to the compound's popularity in over-the-counter products and food applications. Increased cases of chronic constipation due to sedentary lifestyles and poor dietary habits also support the drug’s widespread usage.
Latin America Lactulose Market Trends
Latin America lactulose market’s growth is driven by rising healthcare awareness, increasing access to pharmaceutical products, and expanding food supplement use across countries like Brazil, Argentina. Brazil is the largest contributor in the region, backed by its well-established dairy and pharmaceutical sectors. With a population exceeding 200 million, increasing digestive health issues, and a growing focus on geriatric and pediatric care are fueling lactulose demand. The country also serves as a hub for whey-based product innovation, offering scope for lactulose manufacturing from dairy by-products.
Middle East & Africa Lactulose Market Trends
The Middle East & Africa lactulose market is the smallest regional market, supported by improving healthcare systems, increasing pharmaceutical imports, and greater awareness of digestive and liver health. Saudi Arabia and the United Arab Emirates lead demand due to their high healthcare expenditure and better access to medications like lactulose, commonly prescribed for constipation and hepatic encephalopathy. These countries also show rising demand in veterinary applications, especially in livestock health, due to large-scale farming operations.
Key Lactulose Company Insights
Some key players operating in the market include Abbott and Fresenius Kabi.
-
Abbott, a U.S.-based global healthcare company, operates in diagnostics, medical devices, nutrition, and branded generics. It is a Fortune 500 company with a massive international presence and strong consumer trust. Its nutrition division includes globally recognized brands like Ensure and Similac. In pharmaceuticals, Abbott offers various therapeutic products, including gastrointestinal drugs. Abbott manufactures and markets lactulose syrup formulations under different brand names used in the treatment of chronic constipation and hepatic encephalopathy. The company’s robust distribution channels and R&D support ensure widespread accessibility and high standards. Abbott's lactulose is a part of its larger gastrointestinal and liver health treatment portfolio.
-
Fresenius Kabi is a global healthcare company headquartered in Germany, focusing on lifesaving medicines and technologies for infusion, transfusion, and clinical nutrition. It serves hospitals and outpatient care with a wide range of injectable drugs, infusion therapies, and nutritional products. The company operates across over 100 countries and is a subsidiary of Fresenius SE & Co. KGaA. In the lactulose space, Fresenius Kabi manufactures oral liquid formulations used for treating chronic constipation and hepatic encephalopathy. These products are widely distributed in global pharmaceutical markets and are recognized for their consistent quality, regulatory compliance, and therapeutic reliability in digestive and liver-related disorders.
Illovo and Biofac, are some of the emerging market participants in the market.
-
Illovo Sugar Africa, a subsidiary of Associated British Foods, is the largest sugar producer in Africa. Headquartered in South Africa, the company operates sugar mills and refineries across several African nations. Besides sugar, Illovo manufactures downstream products like ethanol, furfural, and specialty health ingredients. One such specialty is lactulose, derived from lactose-rich substrates through fermentation. Illovo supplies this lactulose to pharmaceutical and nutraceutical companies for use in laxative formulations and prebiotic health products. With its strong agribusiness integration and production capacity, Illovo is a key regional supplier of lactulose ingredients in bulk, particularly within the African and European markets.
-
Biofac is a Danish pharmaceutical company specializing in fermentation-based and bioactive products for pharmaceutical, nutraceutical, and veterinary applications. It is known for its high-purity ingredients and advanced production technologies. Biofac’s product portfolio includes vitamins, amino acids, and specialty carbohydrates like lactulose. The company produces lactulose in both syrup and crystalline forms, serving global pharmaceutical manufacturers who formulate laxatives, hepatic therapies, and gut health products. Biofac’s emphasis on quality, traceability, and regulatory compliance makes it a preferred supplier in Europe and other regulated markets. Its lactulose offerings are positioned for high-value segments, including both human and veterinary health solutions.
Key Lactulose Companies
The following key companies have been profiled for this study on the lactulose market.
- Fresenius Kabi
- Orion Lifescience
- Morinaga Milk Industry Co., Ltd.
- Abbott
- Illovo
- Biofac
- Daiichi Sankyo
- Inalco SpA
- Casca Remedies
- Enrich Pharma
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Fresenius Kabi; Morinaga Milk Industry Co., Ltd.; Abbott; Daiichi Sankyo; Illovo)
- Expand production capacity for pharmaceutical-grade lactulose to meet growing demand for gastrointestinal and hepatic encephalopathy treatments.
- Invest in advanced fermentation, purification, and quality-control technologies to improve product consistency and regulatory compliance.
- Strengthening global market presence through strategic collaborations, licensing agreements, and expansion of manufacturing and distribution networks.
- Diversify product portfolios by developing high-purity lactulose formulations for pharmaceutical, nutraceutical, and functional food applications.
- Well-established global manufacturing infrastructure and extensive distribution channels.
- Strong regulatory expertise and compliance with international pharmaceutical quality standards.
- Significant R&D capabilities supporting product innovation and formulation improvements.
- Established relationships with hospitals, healthcare providers, pharmaceutical companies, and retail pharmacy networks.
- High manufacturing and regulatory compliance costs associated with pharmaceutical-grade production.
- Dependence on raw material availability and fluctuations in lactose prices.
- Lengthy regulatory approval processes for new formulations and market expansion.
- Intense competition from generic manufacturers and regional pharmaceutical companies.
Emerging & Regional Players (Orion Lifescience; Biofac; Inalco SpA; Casca Remedies; Enrich Pharma)
- Expand regional market share by supplying cost-effective lactulose formulations for pharmaceutical and healthcare applications.
- Develop customized formulations and packaging solutions tailored to local regulatory requirements and customer preferences.
- Increase investments in manufacturing capacity, quality certifications, and contract manufacturing services.
- Strengthening partnerships with regional distributors, hospitals, pharmacies, and healthcare providers to improve market penetration.
- Strong understanding of regional healthcare markets and regulatory environments.
- Greater operational flexibility, enabling faster product customization and response to local demand.
- Competitive pricing is supported by localized manufacturing and lean operations.
- Ability to build strong customer relationships through focused regional distribution networks.
- Limited global presence and brand recognition compared with multinational pharmaceutical companies.
- Smaller R&D budgets may restrict innovation and new product development.
- Greater dependence on regional demand and domestic regulatory environments.
- Increasing competition from multinational companies expanding into emerging healthcare markets.
Recent Developments
-
In March 2025, Cadila Pharmaceuticals launched Cadilose, a lactulose-based solution targeting constipation and hepatic encephalopathy (HE). Cadilose acts as an osmotic laxative and prebiotic, improving bowel movement and supporting gut health. It reduces colonic pH and ammonia absorption, addressing cognitive symptoms of HE. This launch reinforces Cadila’s focus on innovative GI care.
Lactulose Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 536.2 million
Market size value in 2026
USD 568.9 million
Revenue forecast in 2033
USD 897.8 million
Growth rate
CAGR of 6.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Form, function, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; South Korea, Brazil, Argentina, Saudi Arabia, South Africa.
Key companies profiled
Fresenius Kabi; Orion Lifescience; Morinaga Milk Industry Co., Ltd.; Abbott; Illovo; Biofac; Daiichi Sankyo; Inalco SpA; Casca Remedies; Enrich Pharma.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Lactulose Market Report Segmentation
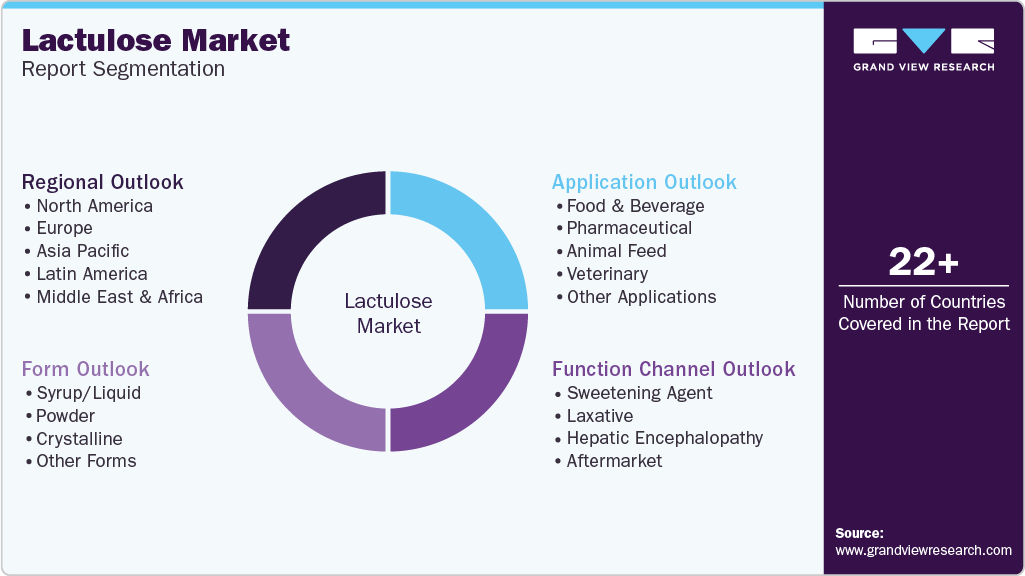
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global lactulose market report based on form, function, application, and region.
 To learn more about this report, Download Free Sample Report
-
Form Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Syrup/Liquid
-
Powder
-
Crystalline
-
Other Forms
-
-
Function Channel Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Sweetening Agent
-
Laxative
-
Hepatic Encephalopathy
-
Aftermarket
-
-
Lactulose Applications Outlook (Revenue, USD Million, 2021 - 2033)
-
Food & Beverage
-
Pharmaceutical
-
Animal Feed
-
Veterinary
-
Other Applications
-
-
Regional Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
-
Research Methodology
The Lactulose market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Lactulose segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Form
Revenue capture definition
Syrup/Liquid
Revenue is generated from liquid lactulose formulations primarily used in pharmaceutical syrups for the treatment of constipation and hepatic encephalopathy, as well as in select food applications.
Powder
Includes sales of powdered lactulose utilized in dietary supplements, functional foods, and pharmaceutical formulations where enhanced stability and ease of handling are required.
Crystalline
Covers revenue derived from crystalline lactulose products supplied for specialized pharmaceutical, nutraceutical, and research applications requiring high purity and extended shelf life.
Other Forms
Encompasses earnings from alternative lactulose formats, including granules, blends, and customized formulations developed for niche industrial and healthcare applications.
Segment - Function
Revenue capture definition
Sweetening agent
Represents revenue from lactulose used as a low-calorie sweetening ingredient and prebiotic component in functional food and beverage products.
Laxative
Captures sales of lactulose formulations prescribed or sold over the counter for relieving chronic and occasional constipation through their osmotic laxative action.
Hepatic encephalopathy
Accounts for income generated from lactulose products administered to reduce blood ammonia levels in patients with hepatic encephalopathy associated with liver disease.
Other Functions
Includes revenue from emerging and specialized therapeutic or nutritional uses of lactulose beyond its primary laxative and hepatic encephalopathy indications.
Segment - Application
Revenue capture definition
Pharmaceutical
Measures revenue generated from lactulose incorporated into prescription medicines, OTC products, and hospital formulations for gastrointestinal and liver-related treatments.
Food & Beverage
Covers sales are associated with the incorporation of lactulose into functional foods, beverages, dairy products, and nutritional formulations to deliver prebiotic health benefits.
Veterinary (Laxative)
Reflects revenue from lactulose products formulated for veterinary use to manage constipation and digestive disorders in companion and farm animals.
Animal Feed
Includes income from lactulose incorporated into animal feed and feed additives to support gut health, digestive efficiency, and overall animal well-being.
Other Applications
Encompasses revenue from additional applications, including research, specialty nutrition, and other industrial uses not classified under the primary application segments.
Estimation Model
Layer Name
Key Question
Description
Lactulose Production Layer
What forms is the supply base?
Identify global lactulose production capacity based on the availability of raw materials such as lactose, manufacturing technologies, fermentation processes, purification capabilities, production infrastructure, quality standards, regulatory compliance, and manufacturing facilities. This layer establishes the global supply base serving pharmaceutical, food & beverage, veterinary, and animal nutrition industries.
Application Adoption Layer
Where is lactulose utilized?
Estimate the proportion of lactulose consumed across pharmaceuticals, functional foods & beverages, dietary supplements, veterinary medicines, animal feed, and other applications by evaluating end-use demand, healthcare trends, product innovation, regulatory approvals, and regional consumption patterns.
Consumption Intensity Layer
How much lactulose is used?
Analyze lactulose consumption across therapeutic, nutritional, and industrial applications by assessing dosage requirements, prescription volumes, production output, patient population, product formulations, and end-user demand to determine annual lactulose consumption across key industries and geographic regions.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the sale of lactulose in syrup, liquid, powder, crystalline, and other formulations supplied to pharmaceutical manufacturers, hospitals, retail pharmacies, food & beverage producers, veterinary healthcare providers, animal feed manufacturers, and other end-use industries worldwide.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis
Detailed cross-segmentation assessment evaluating the relationship between form, function, and application segments in the lactulose market. The analysis identifies lactulose consumption patterns, therapeutic use, dosage trends, formulation preferences, and revenue contribution across intersecting segments, such as syrup formulations for hepatic encephalopathy, liquid lactulose as a laxative in pharmaceutical applications, and powder lactulose as a prebiotic ingredient in food & beverage products.
Supports product portfolio optimization and market prioritization by identifying the most attractive form–function–application combinations, enabling improved resource allocation, product development, commercialization strategies, and long-term growth planning across the lactulose value chain.
Competitive Benchmarking
Comparative evaluation of leading lactulose manufacturers based on product portfolio, manufacturing capabilities, production capacity, quality standards, geographic footprint, regulatory compliance, innovation capabilities, distribution network, strategic partnerships, and recent business developments across key regional markets.
Assists competitive intelligence, partnership evaluation, and supplier assessment by providing greater visibility into market positioning, manufacturing strengths, product differentiation, operational efficiency, regulatory expertise, and competitive advantages.
Opportunity Assessment
Comprehensive assessment of emerging opportunities associated with expanding pharmaceutical demand, increasing prevalence of gastrointestinal disorders, growing geriatric population, rising adoption of functional foods and prebiotics, veterinary applications, and healthcare expansion in emerging economies, along with advancements in high-purity lactulose formulations.
Helps identify high-growth investment areas, emerging therapeutic and nutritional applications, product development priorities, geographic expansion opportunities, and commercialization strategies, supporting long-term revenue growth and stronger competitive positioning throughout the lactulose value chain.
Frequently Asked Questions About This Report
Some key players operating the lactulose market include Fresenius Kabi, Orion Lifescience, Morinaga Milk Industry Co., Ltd., Abbott, Illovo, Biofac, Daiichi Sankyo, Inalco SpA, Casca Remedies, and Enrich Pharma.
The lactulose market is growing due to rising demand for digestive health solutions and increasing cases of constipation and liver-related issues. Its role as a safe and effective treatment, especially for laxative and hepatic uses, supports this trend. Growing awareness about gut health and the benefits of prebiotics also adds to its demand. As people seek better health management, lactulose continues to see steady use in both medical and nutritional areas.
The Syrup/Liquid segment dominated the lactulose market in 2025, accounting for 57.5% of the total market share. Its leadership is attributed to its widespread clinical use, ease of administration, and strong adoption for treating constipation and hepatic encephalopathy.
The laxative segment held the largest market share of 69.8% in 2025, driven by the increasing prevalence of chronic constipation, a growing elderly population, and the established safety and efficacy of lactulose as an osmotic laxative.
The pharmaceutical segment dominated the market with a 77.5% share in 2025, supported by the extensive use of lactulose in prescription and over-the-counter products for managing constipation and hepatic encephalopathy.
North America is expected to be the fastest-growing regional market, registering a CAGR of 7.3% during the forecast period, owing to rising awareness of digestive health, increasing cases of gastrointestinal and liver disorders, and expanding healthcare investments.
The global lactulose market is expected to grow at a compound annual growth rate of 6.7% from 2025 to 2030 to reach USD 897.8 million by 2033.
Asia Pacific dominated the lactulose market with a share of 37.2% in 2025. This growth is largely driven by the sheer population size, urbanization, and rising awareness of gut and liver health. Countries like China, India, and Japan are the primary growth hubs due to large aging populations, expanding middle-class healthcare spending, and a rise in lifestyle-related digestive disorders.
The global lactulose market size was valued at USD 536.2 million in 2025 and is estimated at USD 568.9 million in 2026.
About the Author(s)
Food Additives & Nutricosmetics Research Team
Specialty & Chemicals · Food Additives & NutricosmeticsThis report was authored by the food additives & nutricosmetics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the food additives & nutricosmetics segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


