
- Home
- »
- Medical Devices
- »
-
Medical Device Contract Sales Organizations Market Report, 2033GVR Report cover

Medical Device Contract Sales Organizations Market (2026 - 2033)
Size, Share & Trends Analysis Report By Service (Personal/Direct Commercial Promotion, Non-Personal / Indirect Commercial Support) By Therapeutic Area, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$3.4BMarket Estimate, 2026
$3.6BMarket Forecast, 2033
$5.7BCAGR, 2026–2033
6.9%Medical Device Contract Sales Organizations Market Summary
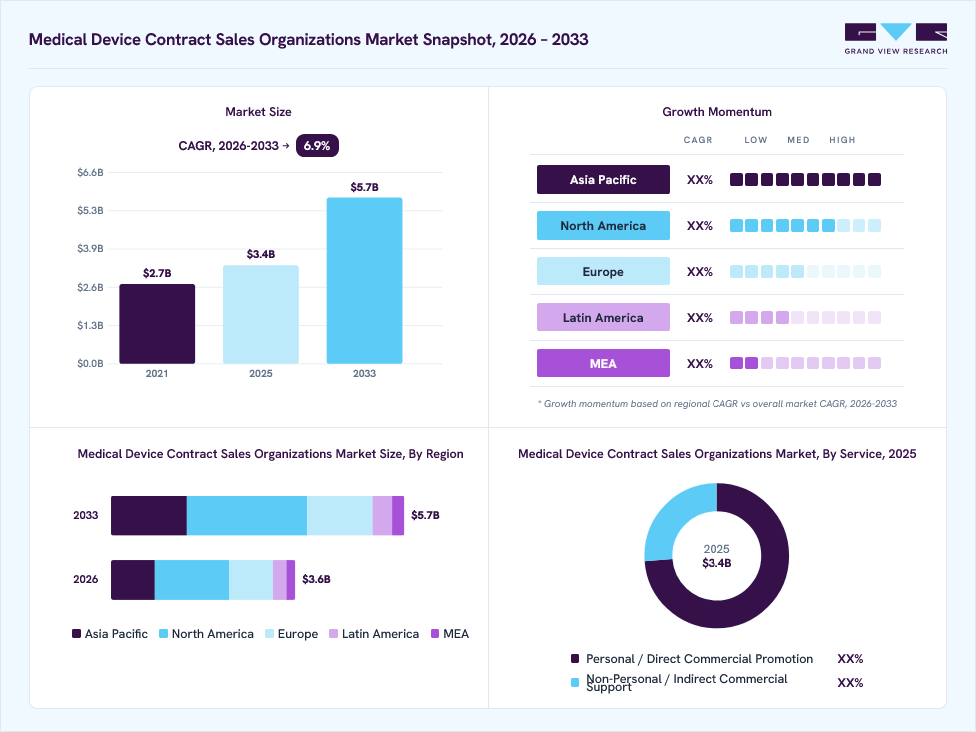
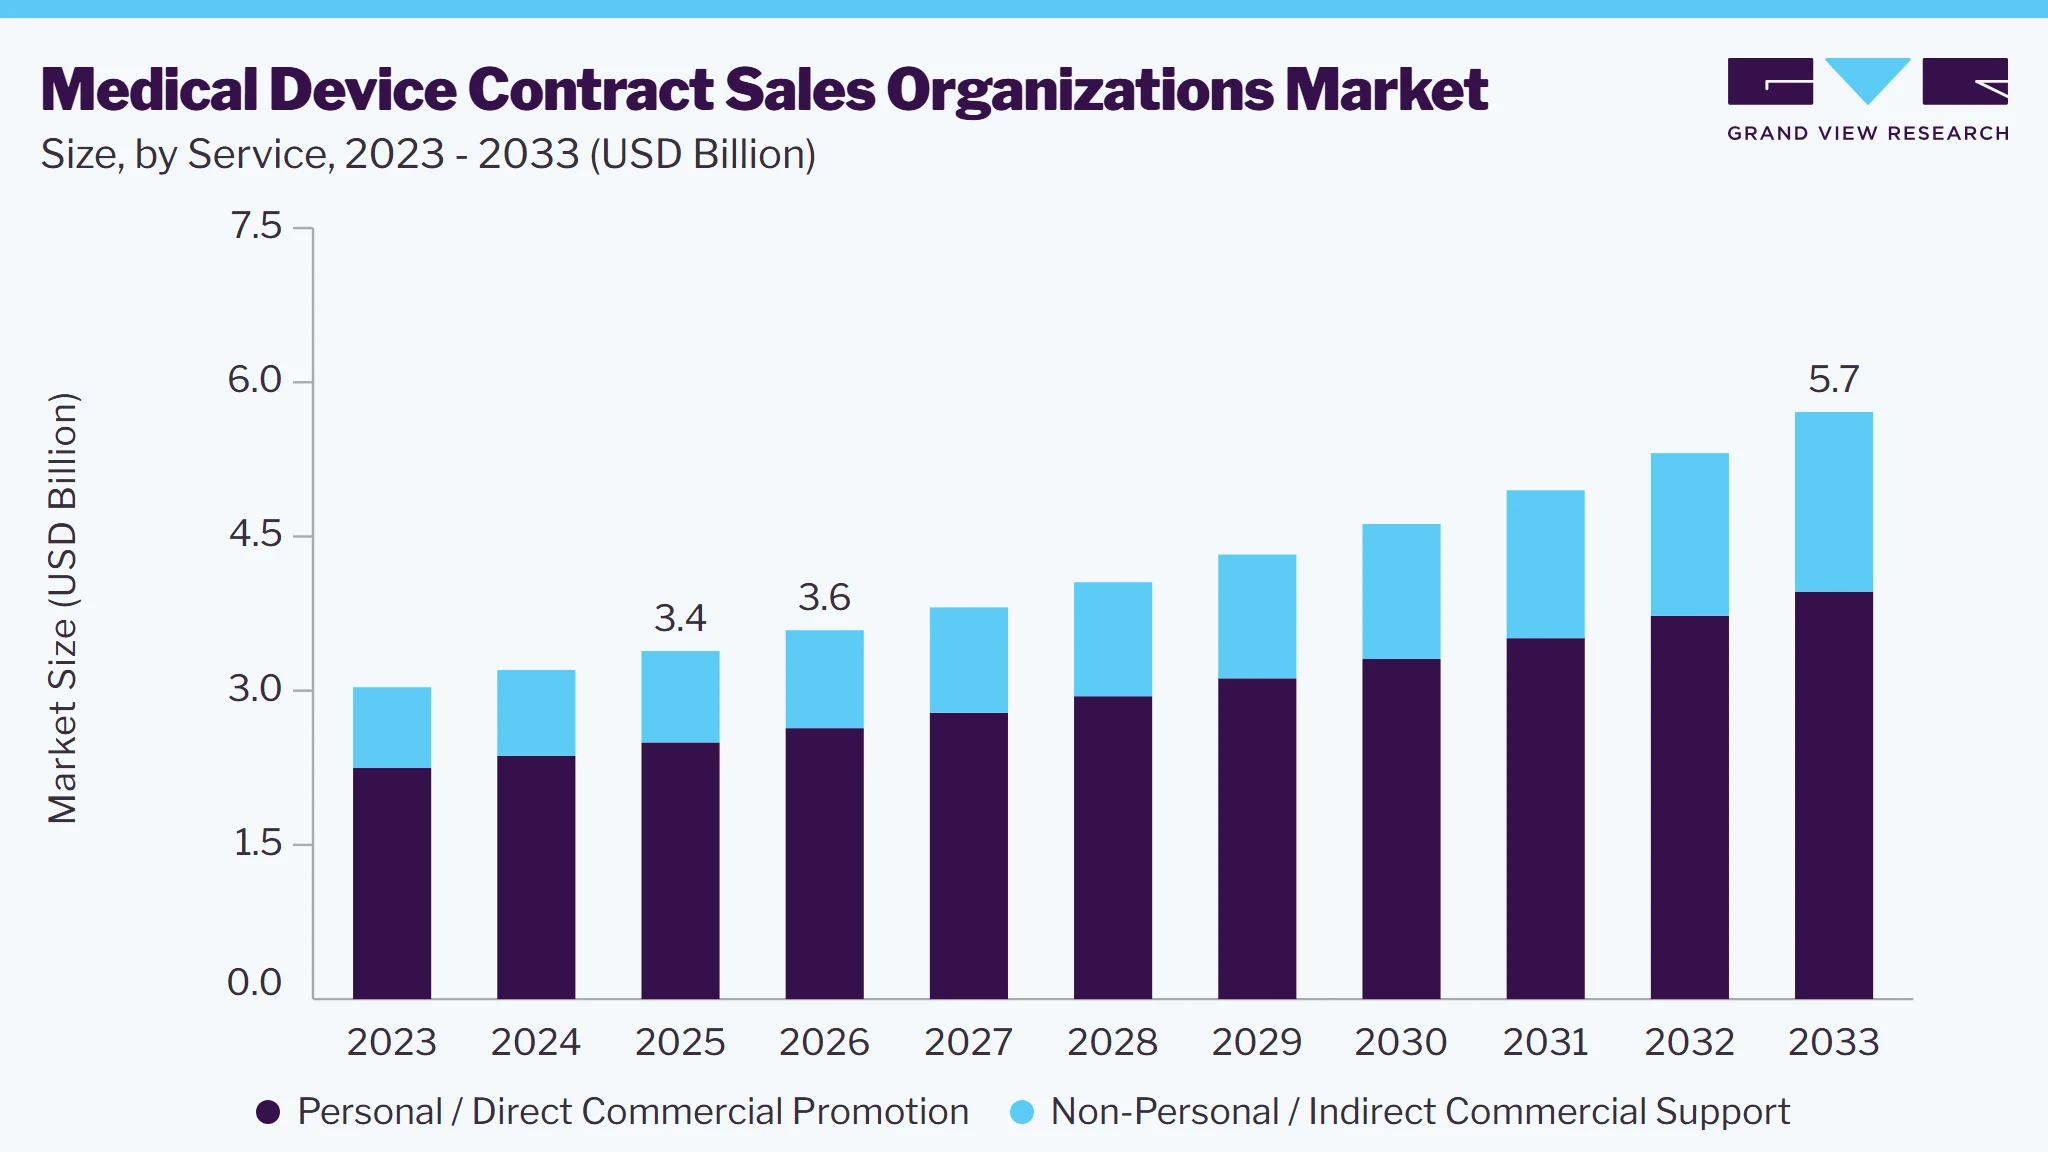
The global medical device contract sales organizations market size was valued at USD 3.4 billion in 2025 and is projected to grow from USD 3.6 billion in 2026 to USD 5.7 billion by 2033, at a CAGR of 6.9% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 40.4% in 2025. The medical device contract sales organizations market is growing owing to increasing outsourcing of commercial activities, rising complexity of healthcare provider and hospital purchasing processes, expansion of medical device portfolios, growing demand for flexible field sales and clinical support teams, and increasing adoption of outsourced market-entry and distribution models.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By service: Personal/direct commercial promotion services segment led the market with the largest revenue share of 73.7% in 2025.
- By therapeutic area: Cardiovascular segment led the market with the largest revenue share of 23.5% in 2025.
- By end use: Large medical device companies segment led the market with the largest revenue share of 52.8% in 2025.
Regional Highlights
- Largest regional market: North America (40.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.4 Billion
- Estimated market size in 2026: USD 3.6 Billion
- Projected market size by 2033: USD 5.7 Billion
- CAGR (2026-2033): 6.9%
Prism AI by Grand View Research Free to tryAsk a question about the medical device contract sales organizations marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The growing need to control commercial operating costs while maintaining specialized sales coverage is encouraging medical device manufacturers to engage external commercial partners. The expansion of medical device markets across emerging economies is further creating demand for regional sales teams, distributor management, and localized commercial support.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The increasing outsourcing of medical device sales and commercial activities continues to be a significant growth driver for the market. Medical device manufacturers face complex purchasing structures that involve physicians, surgeons, hospitals, integrated delivery networks, group purchasing organizations, and other healthcare stakeholders, thereby increasing the need for specialized commercial teams. The expansion of medical device markets across the Asia Pacific and other emerging regions is further supporting demand for regional contract sales and commercial outsourcing services. Medical device manufacturers entering fragmented markets require local sales personnel, healthcare provider engagement, distributor management, and market access capabilities to address differences in healthcare systems and purchasing structures. The growing scale of regional healthcare markets is therefore creating opportunities for both multinational CSOs and specialized regional commercial providers.
However, market growth is constrained by reliance on specialized sales personnel, client-specific training requirements, regulatory compliance costs, and challenges in maintaining consistent commercial execution across fragmented healthcare systems. The expansion of medical device portfolios, increasing adoption of flexible outsourced sales models, growing demand for clinical and technical sales support, and increasing commercial activity across the Asia Pacific and other emerging markets are expected to create significant opportunities for medical device contract sales organizations.
The increasing outsourcing of medical device sales activities is a major driver of growth in the medical device contract sales organizations market. Medical device manufacturers are increasingly engaging specialized commercial service providers to manage field sales, account management, clinical sales support, and market development activities without establishing and maintaining equivalent internal sales infrastructure. The outsourcing model enables manufacturers to access trained sales personnel and established relationships with healthcare providers, while providing greater flexibility in managing commercial resources across product launches, geographic expansions, and changing sales requirements. The growing number of medical device manufacturers with specialized products and geographically dispersed customer bases is further increasing demand for external sales teams with experience in hospital, physician, and healthcare network engagement.
Complex healthcare purchasing structures and regulatory requirements remain significant restraints on the medical device contract sales organizations market. Medical device sales often involve multiple stakeholders, including physicians, surgeons, hospital procurement teams, integrated delivery networks, group purchasing organizations, and distributors, with purchasing procedures varying across healthcare systems and countries. Contract sales organizations must therefore maintain specialized personnel capable of complying with medical device promotion requirements, institutional procurement policies, product communication standards, and local regulations. The need for extensive client-specific training and continuous compliance monitoring can increase operating costs and extend deployment timelines. These requirements may also limit the ability of smaller contract sales organizations to expand across highly regulated markets.
The expansion of medical device commercialization across emerging markets presents a significant opportunity for the medical device contract sales organizations market. Medical device manufacturers entering Asia Pacific, Latin America, the Middle East, and Africa increasingly require local commercial capabilities to access hospitals, physicians, distributors, and healthcare networks. Regional contract sales organizations can provide local sales personnel, market development capabilities, distributor coordination, and clinical support without requiring manufacturers to establish a complete local commercial infrastructure. The growing participation of international and emerging medical device companies in developing healthcare markets is expected to drive demand for flexible sales teams and market entry services, particularly in markets where fragmented healthcare systems and diverse procurement practices increase the need for localized commercial execution.
Market Concentration & Characteristics
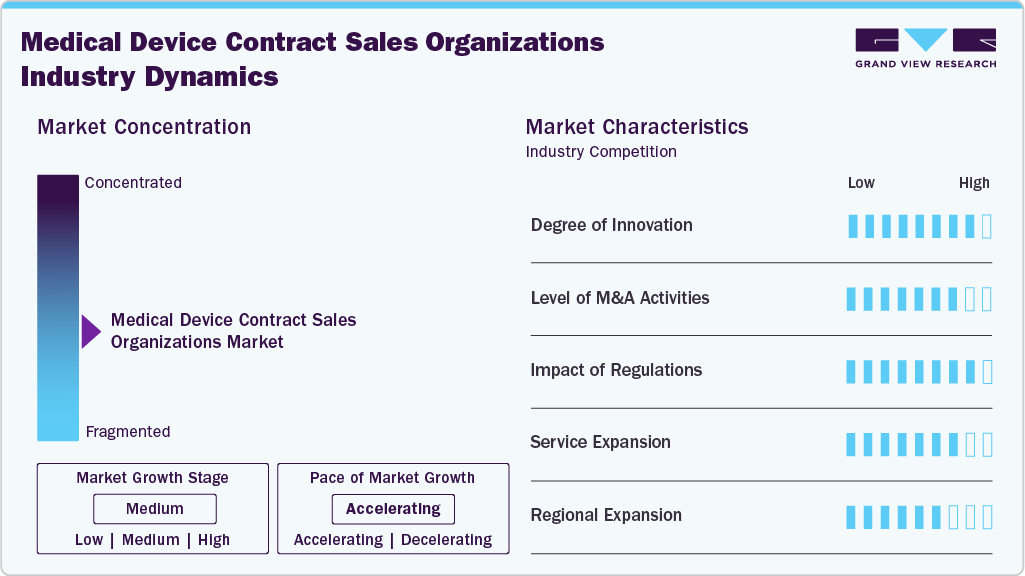
The medical device contract sales organizations market growth stage is medium, and growth is accelerating. The market is characterized by the degree of innovation, level of M&A activities, regulatory impact, service expansion, and regional expansion.
Innovation remains an important competitive factor in the Medical Device Contract Sales Organizations Market, with service providers adopting advanced CRM platforms, sales analytics, artificial intelligence, remote engagement tools, digital product education, and integrated commercial reporting systems. Increasing demand for specialized medical device sales is encouraging CSOs to develop technology-enabled models that improve territory management, account prioritization, customer engagement, and sales-force productivity. Providers with capabilities spanning field sales, clinical support, remote engagement, and commercial analytics can address a broader range of manufacturer requirements.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions influence the medical device contract sales organizations market by expanding geographic coverage, strengthening commercial capabilities, and broadening access to healthcare provider networks. Strategic transactions among healthcare commercial service providers can add field sales personnel, account management capabilities, market access expertise, and technology platforms. Consolidation can also enable providers to serve multinational medical device manufacturers across multiple markets while improving their ability to manage large-scale outsourced commercial programs.
Regulatory requirements remain an important factor shaping the medical device contract sales organizations market because outsourced commercial teams operate within medical device promotion, product communication, healthcare compliance, and institutional purchasing requirements. Contract sales organizations require appropriate training and monitoring to ensure representatives communicate approved product information and comply with applicable regulations. Requirements related to healthcare professional interactions, product claims, data handling, and promotional activities can increase training and program management requirements, particularly for specialized clinical and technical sales teams.
Medical device contract sales organizations are expanding their service portfolios beyond traditional field sales to address broader commercial requirements across the product lifecycle. Providers increasingly offer key account management, clinical and technical sales support, inside and remote sales, sales training, product education, distributor support, sales analytics, and commercial reporting. The expansion allows manufacturers to outsource multiple commercial activities through a single provider while supporting product launches, geographic expansion, account development, and ongoing sales coverage.
Regional expansion remains an important competitive strategy as medical device manufacturers seek commercial coverage across established and emerging healthcare markets. Contract sales organizations are expanding their field networks, local partnerships, and distributor capabilities across North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. Regional capabilities enable providers to address differences in healthcare purchasing structures, hospital networks, reimbursement environments, and regulatory requirements, while supporting manufacturers entering markets without a complete internal sales infrastructure.
Analyst Perspective
The medical device contract sales organizations market is experiencing steady growth, driven by increasing outsourcing of commercial activities, expanding medical device portfolios, and the need for specialized sales and clinical support capabilities. The growing adoption of outsourced field sales, key account management, clinical and technical sales support, inside sales, product education, and channel management is increasing demand for specialized CSO providers. Furthermore, the expansion of advanced medical devices across cardiovascular, orthopedic, neurological, oncology, and general surgery applications, along with increased market entry by emerging manufacturers, is expected to support continued market growth.
Impact of U.S. Tariffs on Medical Device Contract Sales Organizations Market
The current U.S. tariff environment has a moderate and indirect impact on the global medical device contract sales organizations market, as tariffs primarily affect the cost structure and commercial priorities of medical device manufacturers rather than the direct cost of outsourced sales services. Higher import costs for medical devices, components, electronic systems, diagnostic equipment, and related products can increase manufacturers' landed costs and place greater pressure on commercial budgets, particularly for companies with significant exposure to imported products. Medical device manufacturers may respond by reassessing sales territories, product launch schedules, distributor strategies, and external commercial service requirements to manage changes in product economics.
The impact is likely to vary across medical device categories and companies based on manufacturing location, sourcing structure, and dependence on international trade. Manufacturers facing higher product costs may prioritize high-value accounts, optimize field sales coverage, and increase the use of flexible or shared contract sales teams rather than maintaining a fixed internal commercial infrastructure. Such models can provide greater flexibility when manufacturers adjust sales-force requirements across products or territories. Contract sales organizations serving multinational medical device companies may therefore experience changes in project volumes and deployment requirements as clients adjust commercial strategies in response to tariff-related cost pressures.
The tariff environment can also create opportunities for contract sales organizations as manufacturers seek more flexible market expansion and channel strategies. Companies may increase the use of local sales representatives, distributor support, and regional commercial partners when entering or expanding within markets where direct commercial infrastructure is less cost-effective. The growing need to manage product portfolios, account coverage, and market access across changing trade conditions can therefore support demand for outsourced sales and commercial support services. However, prolonged tariff-related cost pressures could constrain manufacturers' commercial budgets and delay certain product launches, resulting in mixed effects on market growth.
Technological Advancements
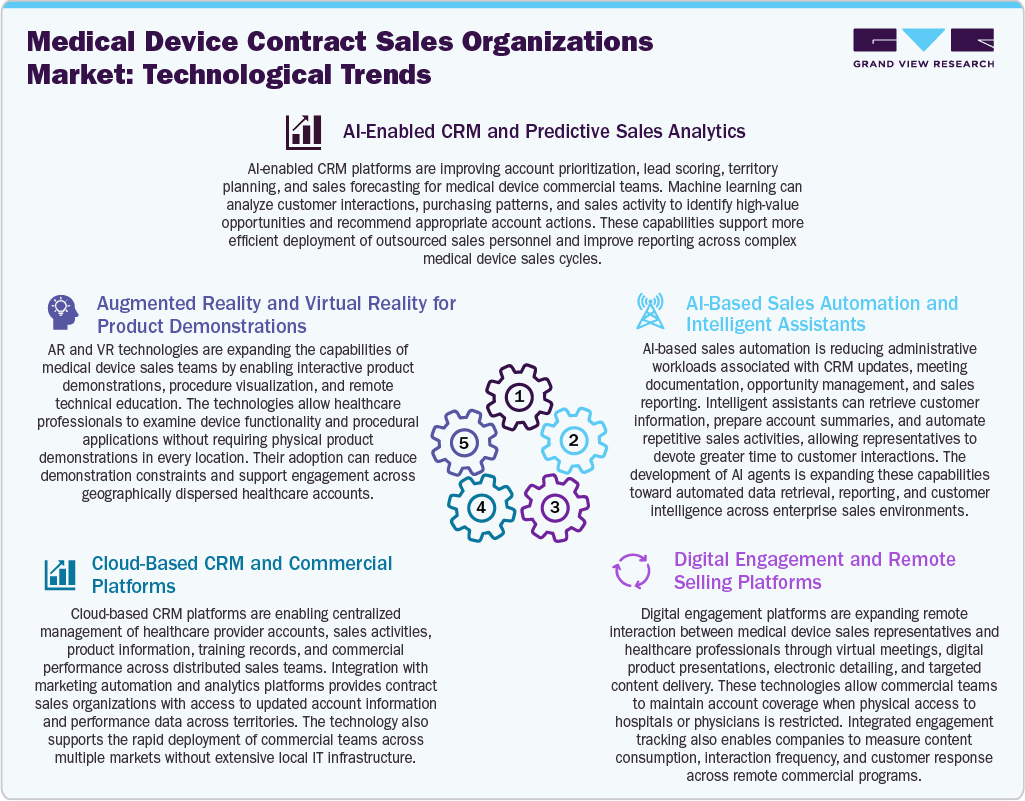
Technological advancement is changing the operating model of medical device contract sales organizations by increasing the use of connected commercial platforms, data-driven decision making, and digitally enabled customer engagement. The growing integration of CRM, analytics, automation, and artificial intelligence is improving visibility across distributed sales teams and enabling service providers to coordinate field representatives, account managers, clinical specialists, and remote sales personnel through centralized systems. The development of AI-enabled analytics is also creating greater opportunities for account prioritization, territory optimization, and sales forecasting, thereby improving resource allocation across complex hospital and healthcare provider networks.
 To learn more about this report, Download Free Sample Report
AR and VR technologies are expanding product education and demonstration capabilities, particularly for specialized devices that require detailed procedural understanding. Cloud-based platforms are supporting faster deployment across multiple geographic markets while reducing dependence on locally maintained technology infrastructure. Digital engagement tools are further expanding the range of interactions available to healthcare professionals and enabling commercial programs to combine physical and virtual engagement. The adoption of these technologies is expected to increase demand for technology-capable CSO providers with integrated sales, analytics, and engagement capabilities. However, differences in technology maturity, data integration, cybersecurity requirements, and training needs may influence adoption across smaller medical device manufacturers and regional CSOs.
Pricing Model Analysis
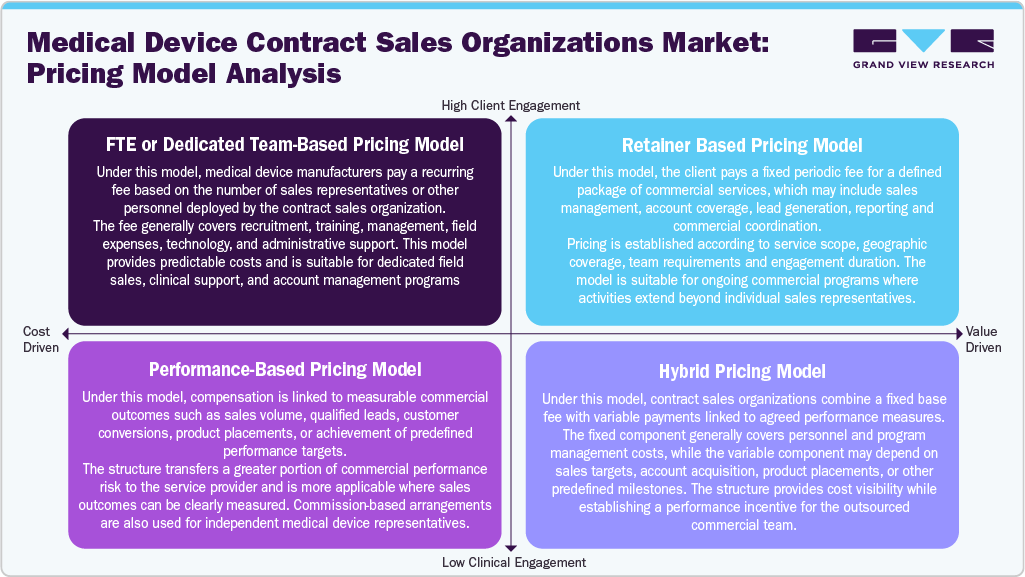
Pricing structures in the medical device contract sales organizations market are determined by the scope of outsourced activities, personnel requirements, sales complexity, geographic coverage, and degree of commercial responsibility transferred to the service provider. FTE and recurring retainer arrangements are particularly suitable for long-term sales-force deployment because manufacturers can establish defined budgets for commercial resources and program management. Performance-based structures become more relevant where sales outcomes, customer acquisition, or product placements can be measured against agreed targets.
 To learn more about this report, Download Free Sample Report
Hybrid arrangements provide greater flexibility for programs combining stable commercial infrastructure with variable performance requirements, making them suitable for product launches, geographic expansion, and account development initiatives. The pricing structure can also vary according to whether the engagement involves dedicated representatives, shared sales teams, clinical specialists, account managers, or distributor support. Higher technical complexity and specialized clinical requirements can increase the cost of outsourced programs because service providers require personnel with relevant products and procedural expertise. Geographic dispersion can further affect pricing through travel, local staffing, and management requirements. Overall, the market is characterized by flexible commercial arrangements rather than a single standardized pricing mechanism, with contract terms generally structured around resource deployment, service scope, performance requirements, and engagement duration.
Service Insights
Based on service, the personal/direct commercial promotion services segment led the market with the largest revenue share of 73.7% in 2025, driven by the continued demand for outsourced field sales teams, sales force deployment, key account management, and clinical and technical sales support. Medical device manufacturers increasingly engage external sales teams to access trained commercial personnel and healthcare provider networks without maintaining equivalent internal infrastructure. The segment also benefits from product launches, geographic expansion, hospital account coverage, and specialized clinical selling requirements, particularly for complex medical devices that require direct interaction with physicians and healthcare decision-makers.
The non-personal / indirect commercial support segment is projected to be the fastest-growing segment over the forecast period, supported by increasing adoption of sales training, product education, distributor support, commercial reporting, and other outsourced support activities. The growing complexity of medical device portfolios and expansion across fragmented healthcare markets are increasing demand for specialized commercial capabilities beyond direct field selling. In addition, manufacturers are seeking flexible support models that can complement internal sales teams and improve distributor effectiveness, creating further opportunities for indirect commercial services.
Therapeutic Area Insights
Based on therapeutic area, the cardiovascular segment led the market with the largest revenue share of 23.5% in 2025, driven by the broad range of cardiovascular devices requiring specialized sales and clinical support, including cardiac rhythm management devices, interventional cardiology products, vascular devices, and cardiovascular monitoring systems. The large installed base of cardiovascular technologies and continued product development support demand for dedicated sales teams, key account management, and clinical and technical sales support. The need for direct engagement with cardiologists, hospitals, and specialized cardiac centers further supports the segment's leading position.
The oncology segment is projected to be the fastest-growing therapeutic area over the forecast period, supported by increasing adoption of oncology-focused medical technologies, targeted treatment platforms, diagnostic systems, radiation therapy equipment, and minimally invasive technologies. The growing complexity of oncology products is driving demand for specialized sales representatives and clinical education programs that can effectively communicate product applications to oncologists, surgeons, hospital administrators, and other healthcare decision-makers. In addition, continued development of advanced cancer treatment and diagnostic technologies is expected to expand outsourcing requirements for specialized commercial teams.
End Use Insights
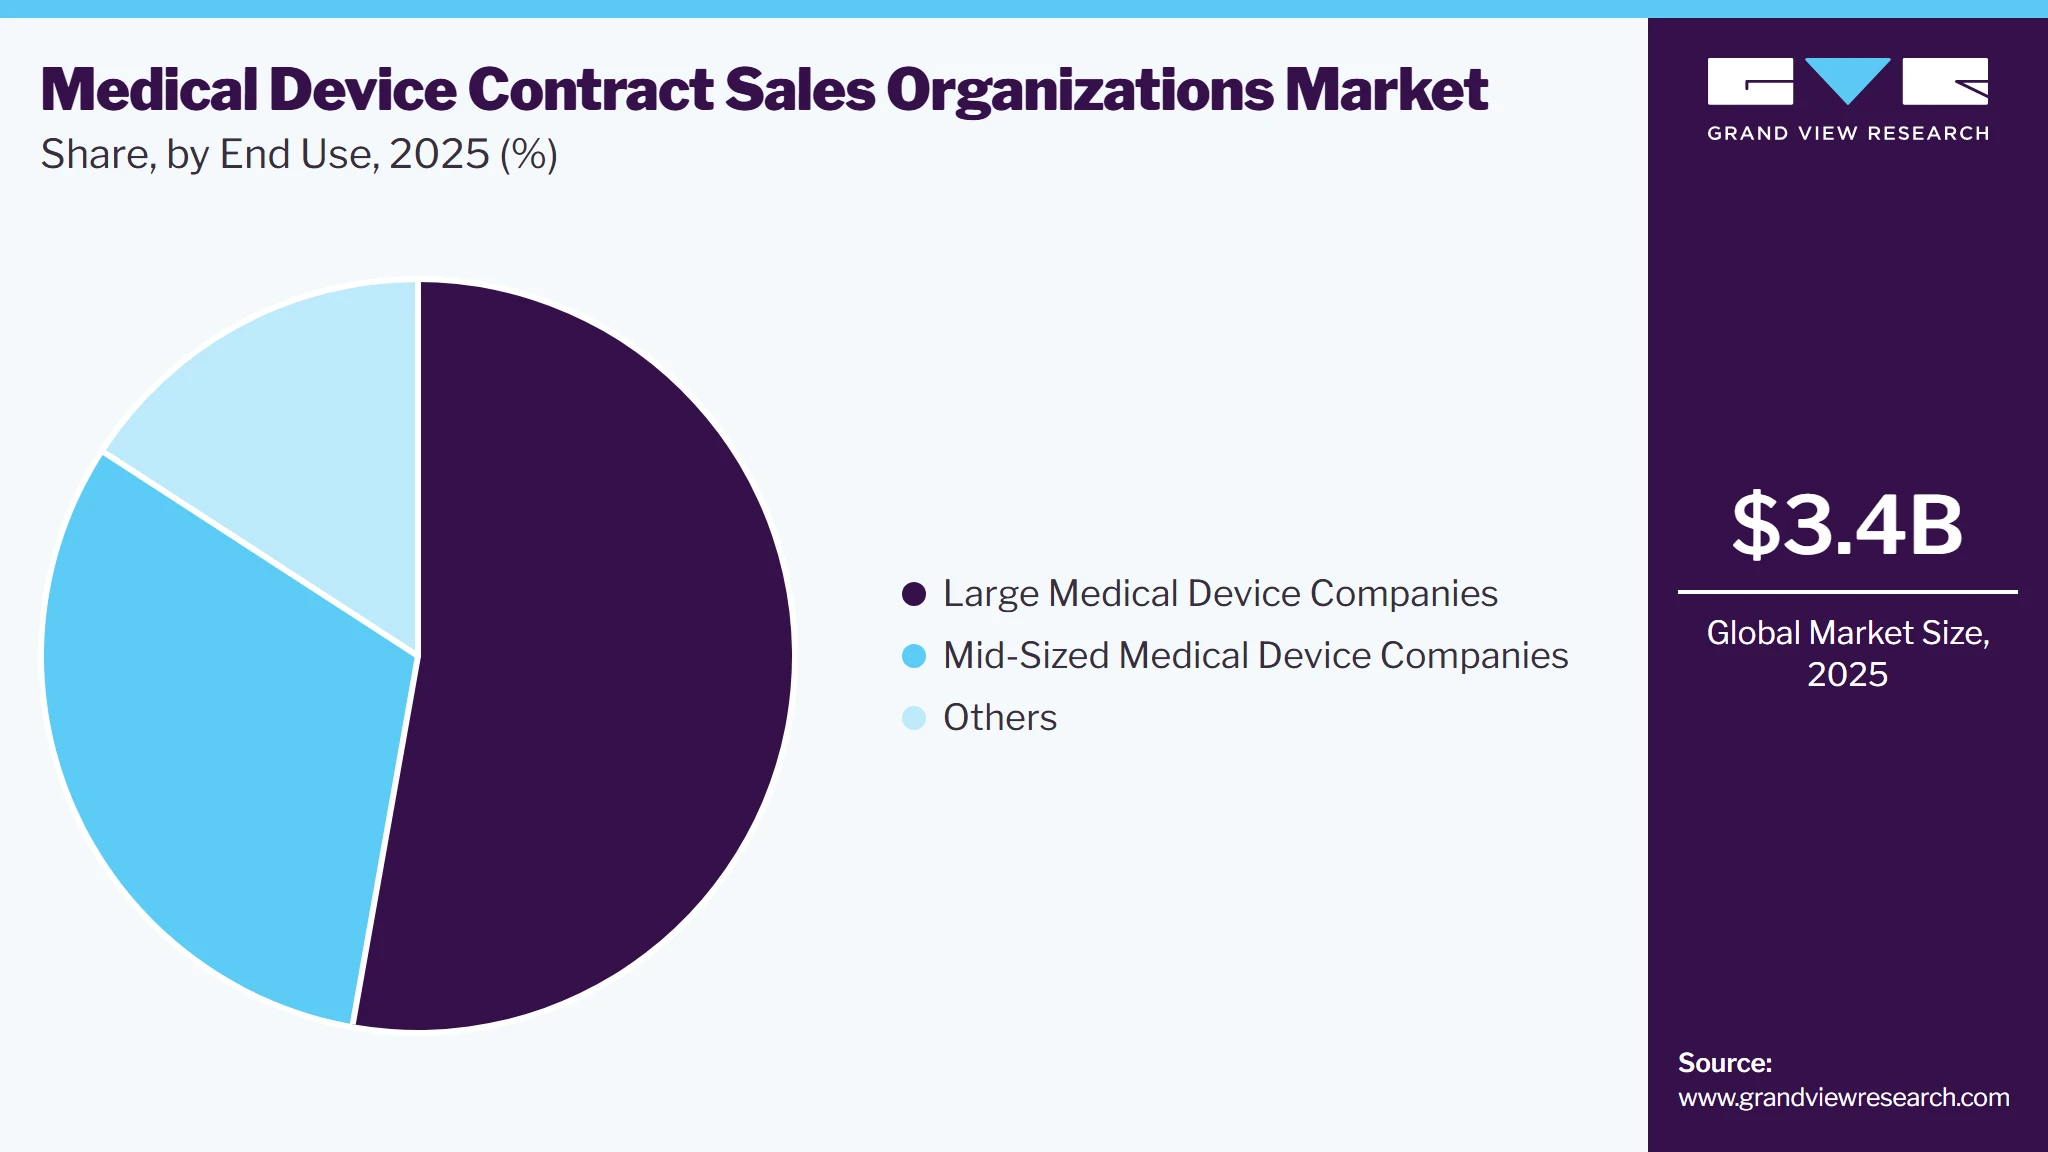
Based on end use, the large medical device companies segment led the market with the largest revenue share of 52.8% in 2025, driven by their extensive product portfolios, broad geographic presence, and greater requirement for dedicated commercial teams across hospitals, healthcare networks, and specialized clinical accounts. These companies also have greater outsourcing requirements for product launches, sales force deployment, key account management, and clinical support, particularly when managing multiple device categories across different markets.
 To learn more about this report, Download Free Sample Report
The mid-sized medical device companies segment is expected to register significant growth over the forecast period, supported by increasing adoption of outsourced commercial models among manufacturers seeking to expand market coverage without establishing large internal sales organizations. These companies increasingly use contract sales organizations for product launches, geographic expansion, specialized clinical selling, distributor management, and access to established healthcare provider networks. The growing number of specialized medical device manufacturers entering niche therapeutic and procedural markets is expected to create further demand for flexible outsourced commercial support.
Regional Insights
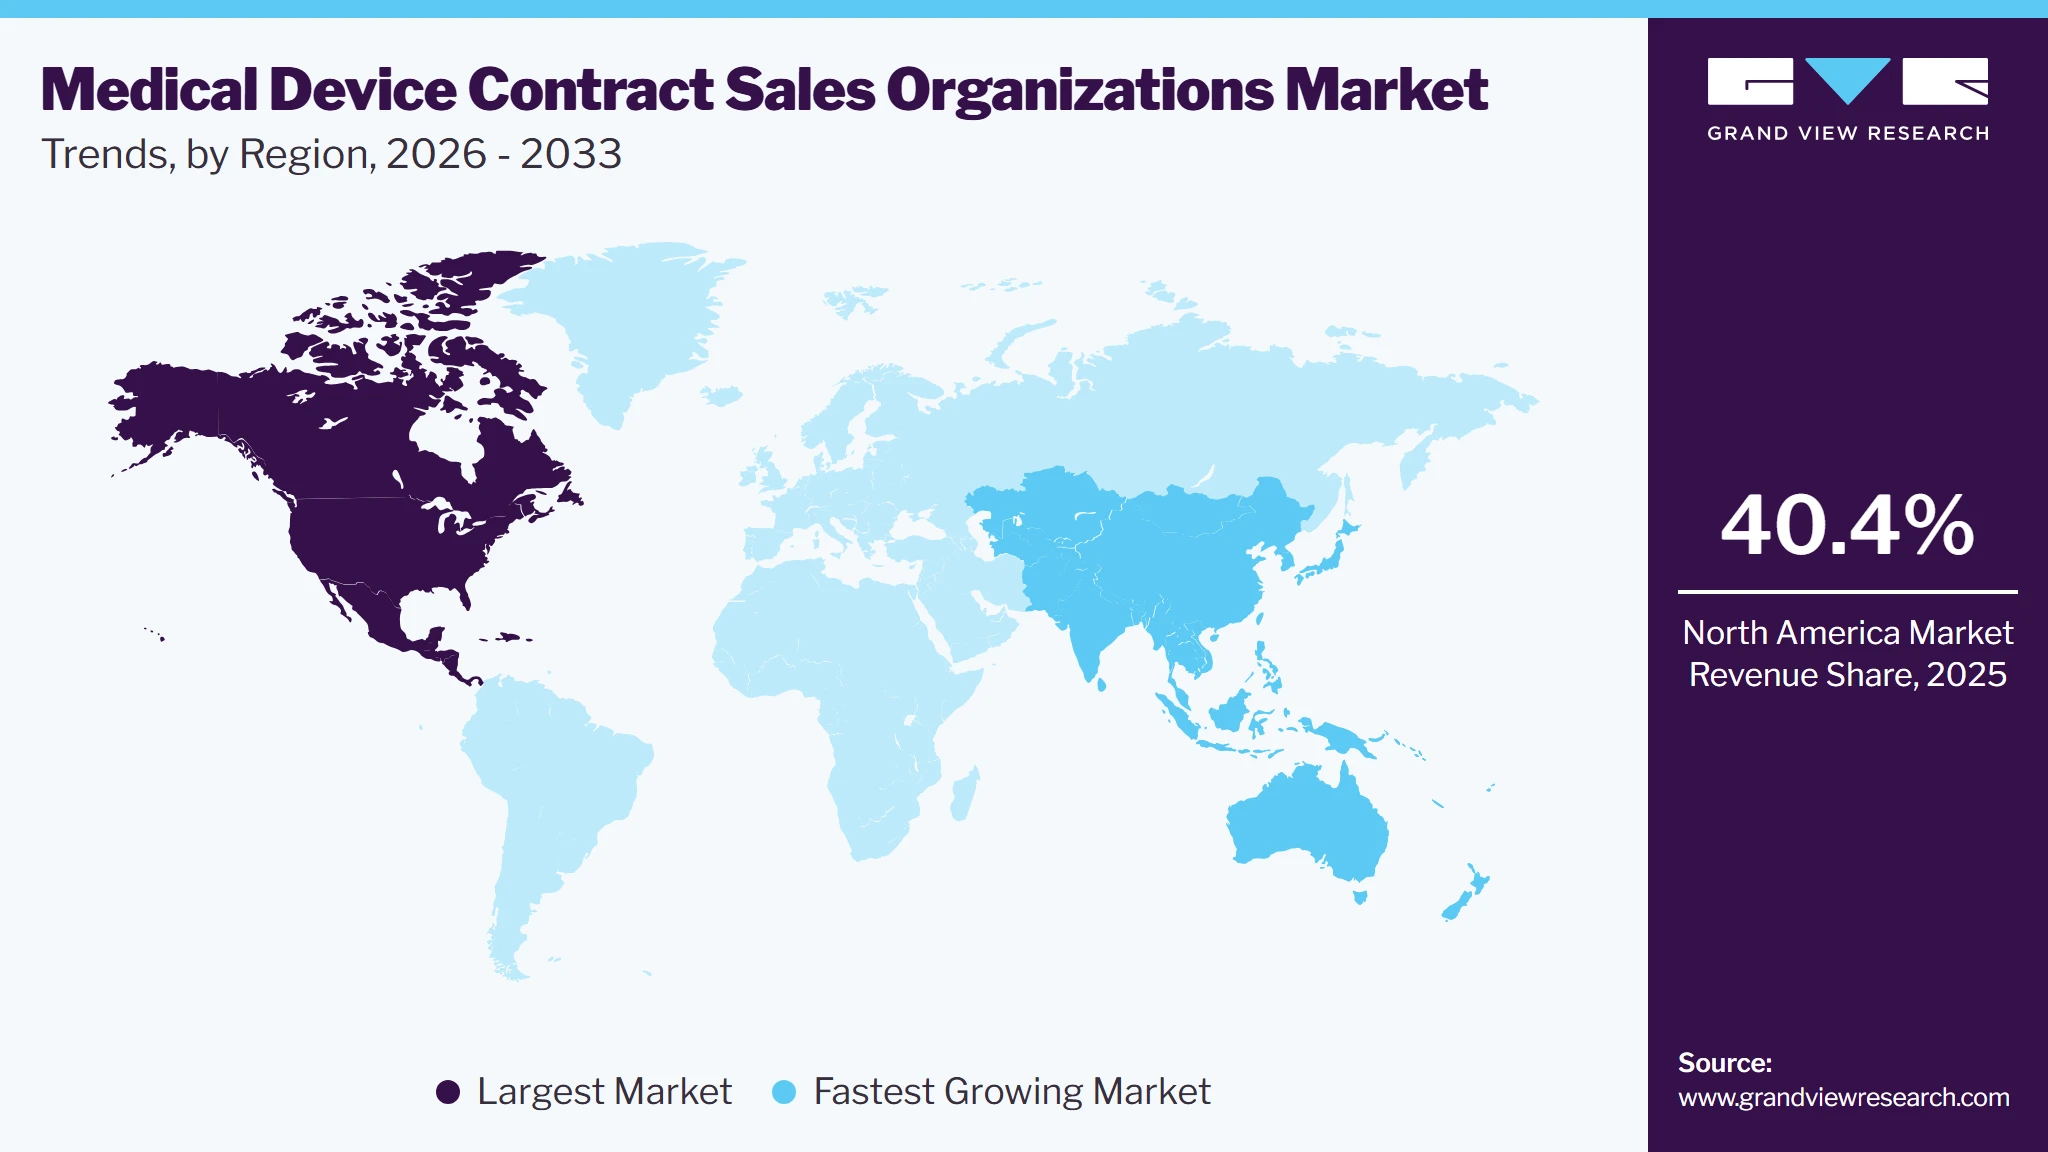
North America dominated the medical device contract sales organizations market with the largest revenue share of 40.4% in 2025. The market is expected to maintain a leading position, supported by the region's large medical device industry, extensive hospital networks, high adoption of outsourced commercial models, and demand for specialized field and clinical sales teams. The presence of established contract sales organizations with dedicated MedTech capabilities further supports market development. For instance, IQVIA provides outsourced MedTech field solutions across the U.S. and Canada, with more than 2,200 W2 employees supporting commercial, clinical, education, and sales activities. The availability of scalable sales teams, inside sales capabilities, clinical educators, and technical personnel support continued outsourcing among medical device manufacturers.
 To learn more about this report, Download Free Sample Report
U.S. Medical Device Contract Sales Organizations Market Trends
The medical device contract sales organizations market in the U.S. held the largest share in the North America region in 2025, supported by a large and diverse medical device industry, complex hospital purchasing structures, and strong adoption of outsourced commercial services. Medical device manufacturers increasingly use external teams for field sales, inside sales, clinical education, technical support, and product launches. IQVIA's U.S. MedTech Field Solutions include recruiting, training, deployment, sales support, analytics, and flexible staffing programs, while its broader contract sales platform provides dedicated, syndicated, and flexible customer-facing teams.
The Canada medical device contract sales organizations market is expected to grow steadily, supported by demand for specialized commercial personnel, increasing healthcare system complexity and the need for broader coverage across geographically dispersed healthcare facilities. Medical device manufacturers can use outsourced field sales, clinical education, and technical support teams to expand customer coverage without establishing equivalent internal infrastructure. IQVIA's MedTech commercial field network specifically covers both the U.S. and Canada and provides scalable sales, education, clinical, and field service capabilities, supporting the development of outsourced commercial models in the Canadian market.
Europe Medical Device Contract Sales Organizations Market Trends
The Europe medical device contract sales organizations market is expected to experience steady growth, supported by a large medical device manufacturing base, diverse healthcare systems, increasing demand for specialized commercial personnel and growing use of outsourced sales models. The fragmented nature of European healthcare markets creates demand for local market knowledge, account management, distributor coordination, and clinical support. Contract sales providers are expanding flexible field- and remote-engagement models to address differences in healthcare systems and purchasing structures across European countries. The presence of specialized MedTech commercial providers in the region is also creating opportunities for manufacturers seeking market entry and regional sales support. Avem Market Solutions, for instance, provides contract technical sales and commercial operations solutions for B2B medical technology suppliers across European, UK, and the U.S. markets.
UK Medical Device Contract Sales Organizations Market held a significant share in 2025 in the European region. The market is expected to grow significantly over the forecast period, supported by a developed healthcare system, established medical device sector, and demand for access to NHS trusts, private hospitals, and healthcare networks. Medical device companies increasingly require specialized sales and clinical personnel to support product adoption across complex healthcare environments. The market also benefits from specialist commercial providers offering local market access and distribution capabilities.
The Medical Device Contract Sales Organizations Market in Germany is anticipated to grow significantly over the forecast period. The market is expected to expand steadily, supported by the country's strong medical technology industry, extensive hospital network, and demand for specialized product education and clinical sales support. Medical device manufacturers require trained commercial personnel capable of engaging physicians, hospitals, procurement stakeholders, and other healthcare decision makers for technically complex products. The presence of regional commercial providers serving Germany and broader European markets is supporting outsourced market-entry and sales activities. Increasing demand for local account coverage and distributor coordination is expected to create further opportunities for contract sales organizations serving domestic and international medical device manufacturers.
Asia Pacific Medical Device Contract Sales Organizations Market Trends
The Asia Pacific medical device contract sales organizations market is expected to register strong growth, supported by rising healthcare expenditure, expanding medical device adoption, growing multinational manufacturer presence, and increasing demand for local sales and distribution capabilities. The region's diverse healthcare systems and fragmented purchasing structures create demand for local commercial expertise, distributor management, clinical education, and account development. Regional providers are also developing commercial networks that support manufacturers across multiple Asian markets, while multinational CSOs are expanding their MedTech capabilities. The combination of direct sales, outsourced field teams, and distributor-supported models is expected to create substantial opportunities across the region.
The Medical Device Contract Sales Organizations Market in China is expected to grow over the forecast period. The market is expected to experience strong growth, supported by the expansion of the domestic medical device industry, the expansion of healthcare infrastructure, and the rising adoption of advanced medical technologies. The size and geographic diversity of the Chinese healthcare market create demand for regional sales teams, distributor management, and specialized account coverage. Domestic and international medical device companies can use outsourced commercial providers to navigate differences across healthcare institutions and geographic markets. The growing number of domestic medical technology companies and the continued introduction of advanced devices are expected to generate further demand for sales-force deployment, product education, and channel management services.
Japan Medical Device Contract Sales Organizations Market is witnessing significant growth over the forecast period. The market is expected to grow steadily, supported by an advanced healthcare system, an established medical device industry, and demand for specialized commercial personnel. Medical device manufacturers require detailed product education and clinical engagement because many products involve specialized procedures and technical applications. The aging population and increasing demand for advanced diagnostic, surgical, and cardiovascular technologies are creating additional commercial requirements. Outsourced sales organizations can provide manufacturers with local account coverage, healthcare professional engagement, and product education capabilities, particularly for international companies seeking to expand their presence without establishing extensive internal commercial infrastructure.
The India Medical Device Contract Sales Organizations Market is expected to grow significantly, supported by increasing healthcare infrastructure, expansion of private hospitals, rising adoption of advanced medical technologies, and growing presence of international and domestic medical device manufacturers. The country's geographically dispersed healthcare system creates demand for regional sales coverage, distributor management, and clinical product education. Contract sales organizations can provide flexible commercial teams for manufacturers seeking expansion across metropolitan and emerging healthcare markets without establishing extensive internal infrastructure. Increasing adoption of cardiovascular, orthopedic, diagnostic, and surgical technologies is expected to create additional opportunities for specialized outsourced sales and clinical support services.
Latin America Medical Device Contract Sales Organizations Market Trends
The Latin America medical device contract sales organizations market is expected to grow steadily, supported by increasing healthcare investment, expansion of private healthcare providers, and growing demand for advanced medical devices. Manufacturers operating across the region require local commercial expertise because healthcare purchasing, reimbursement, and distribution structures vary considerably between countries. Contract sales organizations and specialized commercial partners can support market entry through field sales, distributor coordination, account development, and product education. The increasing presence of international medical device manufacturers and the growing demand for specialized technologies are expected to support the adoption of outsourced commercial services across major Latin American markets.
The Medical Device Contract Sales Organizations market in Brazil is expected to grow over the forecast period. The market is expected to maintain a leading position in Latin America, supported by the country's large healthcare market, extensive private hospital sector, and growing demand for advanced medical technologies. Brazil's geographic scale creates demand for distributed sales networks and local commercial partners capable of reaching hospitals, physicians, distributors, and healthcare networks. Contract sales organizations can support international and domestic manufacturers through field sales, key account management, clinical education, and distributor coordination. Increasing adoption of cardiovascular, orthopedic, diagnostic, and surgical devices is expected to create additional demand for specialized commercial sales capabilities.
Middle East and Africa Medical Device Contract Sales Organizations Market Trends
The medical device contract sales organizations market in the Middle East and Africa is expected to expand gradually, supported by healthcare infrastructure development, increasing medical technology adoption, and growing demand for specialized healthcare products. Manufacturers entering the region often require local commercial partners to navigate distributor networks, hospital procurement structures, and country-specific market requirements. Outsourced sales organizations can provide field sales, account management, clinical education, and channel support without requiring manufacturers to establish extensive local teams. The development of healthcare infrastructure in Gulf markets and increasing participation of international medical device companies are expected to create further opportunities for specialized commercial service providers.
The South Africa Medical Device Contract Sales Organizations Market is witnessing steady growth, supported by increasing healthcare infrastructure investment, rising adoption of advanced medical technologies, and growing participation of international medical device manufacturers. The country's healthcare market requires commercial providers capable of navigating public and private healthcare systems, hospital procurement structures, and regional distribution networks. Increasing demand for cardiovascular, orthopedic, diagnostic, and surgical devices is creating opportunities for outsourced field sales, clinical and technical support, account management, and distributor services. Furthermore, the need for broader geographic sales coverage and localized market expertise is encouraging medical device companies to engage external commercial partners for market expansion and product commercialization.
The Saudi Arabia medical device contract sales organizations market is expected to expand, supported by healthcare infrastructure development under Vision 2030, increasing adoption of advanced medical technologies, and growing efforts to develop the domestic medical device industry. The expansion of hospitals, specialized healthcare facilities, and diagnostic infrastructure is creating demand for commercial teams capable of engaging healthcare professionals, procurement organizations, and hospital networks. Increasing participation of international medical device manufacturers is also creating requirements for local sales representation, distributor management, product education, and clinical support. Furthermore, initiatives focused on healthcare localization and private-sector participation are expected to create additional opportunities for outsourced commercial service providers to support medical device market entry and expansion.
Key Medical Device Contract Sales Organizations Company Insights
The key players operating across the market are adopting strategic initiatives such as service launches, mergers & acquisitions, partnerships & agreements, and expansions to gain a competitive edge in the market. Companies are investing in AI-enabled testing, biocompatibility assessment, digital validation, and strategic acquisitions to strengthen their global presence. Long-term partnerships with medical device manufacturers and compliance with international quality standards remain key competitive differentiators.
Key Medical Device Contract Sales Organizations Companies
The following key companies have been profiled for this study on the medical device contract sales organizations market.
-
IQVIA Inc.
-
Syneos Health, Inc.
-
Inizio Engage / Inizio
-
Promoveo Health
-
MTMC / MedTech MedCare
-
Maxtown Medical
-
Greystone Medical Technologies
-
QFR Solutions, LLC
-
Cermax Healthcare
-
Axxelus
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (IQVIA, Inizio Engage)
Established players focus on providing scalable outsourced commercial teams for medical device manufacturers, covering field sales, sales force deployment, key account management, clinical and technical support, inside sales, product education, and commercial analytics. These companies leverage large healthcare professional networks, standardized recruitment and training processes, and multi-country operating capabilities to support product launches, market expansion, and ongoing sales coverage.
Established players benefit from broad geographic coverage, large, well-trained commercial workforces, established relationships with healthcare providers, and experience supporting multinational medical device manufacturers. Their ability to deploy dedicated or flexible sales teams across multiple markets, combined with technology-enabled reporting, account management, and clinical support capabilities, enables them to manage large and complex commercial programs.
Established players face higher operating and personnel costs associated with maintaining large commercial organizations and extensive geographic infrastructure. Large organizational structures can also lead to longer implementation processes, higher minimum engagement requirements, and reduced flexibility for smaller medical device manufacturers seeking highly customized or limited-scale programs.
Emerging Players (Greystone Medical Technologies)
Specialized and emerging players primarily focus on medical device sales representation, dedicated and shared sales teams, key account management, clinical and technical sales support, distributor management, product education, and market expansion. Many target specific therapeutic areas, customer groups, geographic markets, or medical device categories, and provide flexible commercial teams that can be scaled according to manufacturer requirements.
Specialized players gain competitive advantages through focused medical device expertise, flexible engagement structures, localized healthcare provider relationships, and faster deployment of commercial teams. Their narrower operating structures allow greater customization of sales programs, targeted geographic coverage, and specialized support for manufacturers that may not require the extensive infrastructure of large global CSOs.
Specialized players generally have smaller sales workforces, narrower geographic coverage, and fewer resources for large multinational programs compared with established providers. Limited financial resources, dependence on selected therapeutic areas or customers, and lower international coverage can restrict their ability to manage large multi-country commercial programs.
Recent Developments
-
In July 2026, Inizio Engage launched Connected Insights as an expansion of its global Medical Information capabilities, combining global expertise with AI-enabled technology to connect medical information interactions across markets and generate actionable intelligence. The new capability expands Inizio Engage's technology-enabled engagement portfolio and strengthens its ability to support life sciences companies across medical and commercial activities. The development is consistent with the market's shift toward technology-enabled customer engagement and broader outsourced commercial support beyond traditional field sales.
-
In May 2026, Syneos Health announced new and expanded strategic partnerships with KAI Conversations, Sageforce.ai, and causaLens to strengthen its AI-enabled commercial capabilities. The collaboration with KAI Conversations provides AI-powered conversation intelligence to convert field interactions between sales teams and healthcare professionals into actionable commercial insights, while the partnership with Sageforce.ai supports AI-powered field teams, including virtual sales representatives and AI-enabled medical science liaisons. In addition, causaLens provides causal AI agents for healthcare professionals, targeting engagement optimization, territory planning, and commercial decision-making. These developments expand Syneos Health's technology-enabled commercial services and strengthen its capabilities in data-driven HCP engagement and outsourced commercial execution.
Medical Device Contract Sales Organizations Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.4 billion
Estimated market size in 2026
USD 3.6 billion
Projected market size by 2033
USD 5.7 billion
Growth rate
CAGR of 6.9% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Service, therapeutic area, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar
Key companies profiled
IQVIA Inc.; Syneos Health, Inc.; Inizio Engage / Inizio; Promoveo Health; MTMC / MedTech MedCare; Maxtown Medical; Greystone Medical Technologies; QFR Solutions, LLC; Cermax Healthcare; Axxelus
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Device Contract Sales Organizations Market Report Segmentation
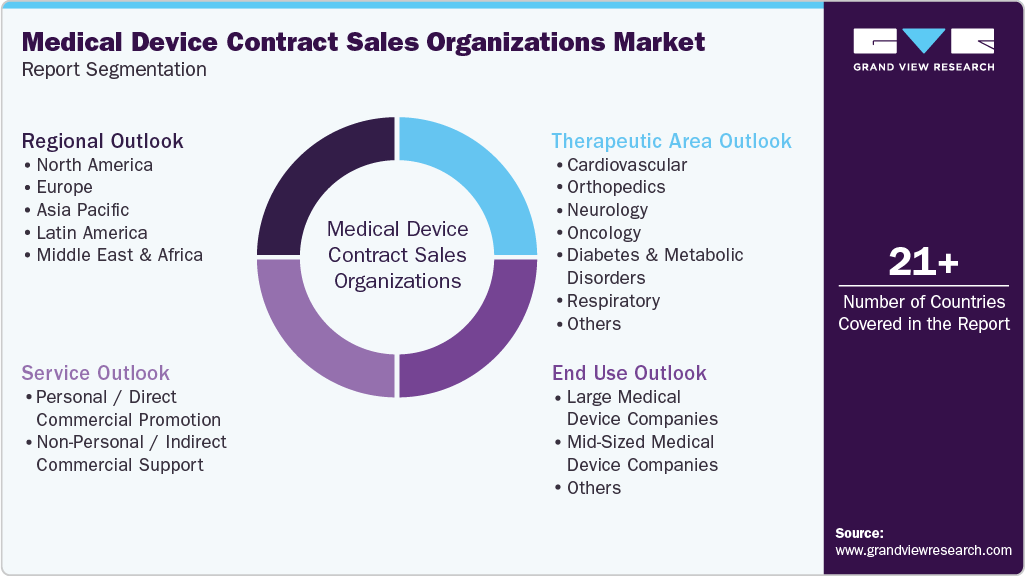
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global medical device contract sales organizations market report based on service, therapeutic area, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Service Outlook (Revenue, USD Million, 2021 - 2033)
-
Personal / Direct Commercial Promotion
-
Field Sales & Sales Force Outsourcing
-
Key & Strategic Account Management
-
Clinical & Technical Sales Support
-
Inside & Remote Sales
-
-
Non-Personal / Indirect Commercial Support
-
Sales Training & Product Education
-
Channel & Distributor Support
-
Other Services
-
-
-
Therapeutic Area Outlook (Revenue, USD Million, 2021 - 2033)
-
Cardiovascular
-
Orthopedics
-
Neurology
-
Oncology
-
Diabetes & Metabolic Disorders
-
Respiratory
-
General Surgery
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Large Medical Device Companies
-
Mid-Sized Medical Device Companies
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Oman
-
Qatar
-
-
Research Methodology
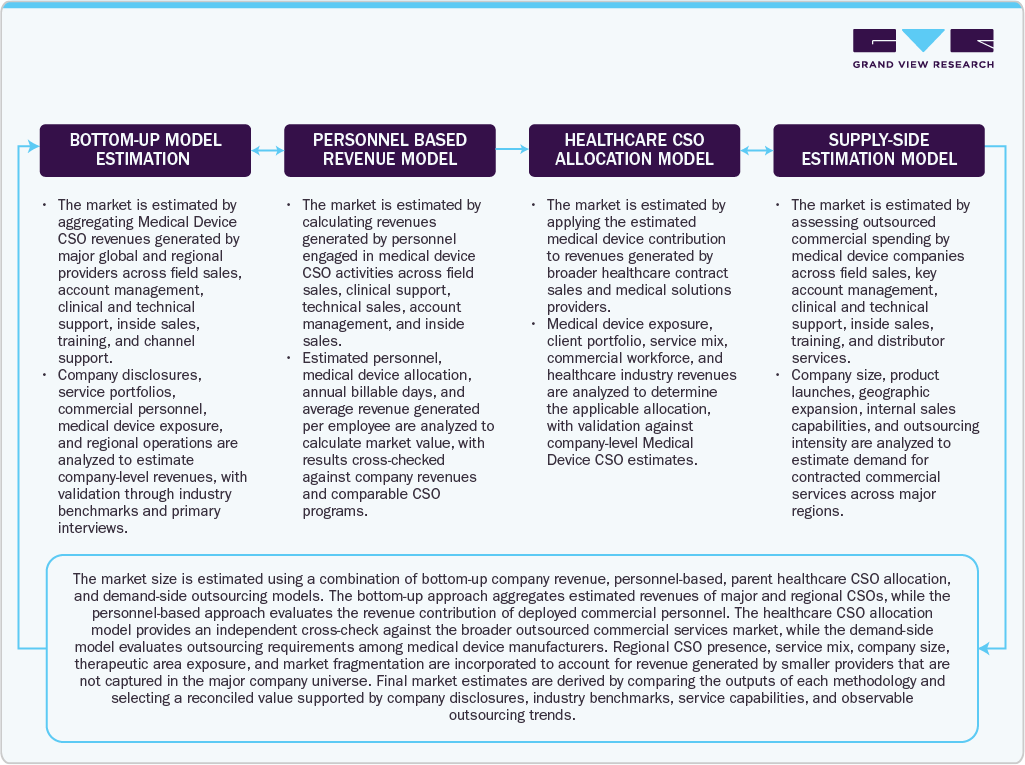
The medical device contract sales organizations market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical device contract sales organizations segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Service
Revenue capture definition
Personal / Direct Commercial Promotion
The segment captures revenue generated by outsourced commercial activities involving direct interaction with healthcare professionals, healthcare institutions, purchasing organizations, distributors, or other target customers on behalf of medical device companies. Services include field sales and outsourced sales-force deployment, key and strategic account management, clinical and technical sales support, product demonstrations, case and procedure coverage, and inside or remote sales activities. The segment covers customer-facing activities undertaken to promote medical devices, develop and manage accounts, support product adoption, generate sales, expand market presence, and maintain ongoing commercial relationships.
Field Sales & Sales Force Outsourcing
The segment captures revenue generated by outsourced field sales and sales-force services provided to medical device companies, including dedicated, shared, syndicated, flexible, and interim sales teams responsible for direct customer engagement and product promotion. Services include territory sales coverage, vacancy or interim sales-force replacement, sales representative deployment, account prospecting, customer visits, product promotion, sales execution, and sales-force expansion for medical devices across healthcare providers, hospitals, health systems, and other target accounts.
Key & Strategic Account Management
The segment captures revenue generated by outsourced management of key, strategic, and high-value customer accounts for medical device companies. Services include hospital and health-system account management, strategic account planning, IDN and GPO engagement, customer relationship management, account development, contract and purchasing-group engagement, stakeholder coordination, and retention and expansion of high-value medical device accounts.
Clinical & Technical Sales Support
The segment captures revenue generated by outsourced clinical and technical commercial support provided during the evaluation, adoption, demonstration, and use of medical devices. Services include clinical specialist support, technical product support, clinical education, product demonstrations, procedure and case coverage, healthcare professional in-service training, device application support, and technical engagement with clinicians and other healthcare professionals, particularly for complex, procedural, implantable, surgical, and technology-intensive medical devices.
Inside & Remote Sales
The segment captures revenue generated by outsourced sales activities conducted through telephone, virtual, remote, and other non-face-to-face channels. Services include inside sales representatives, remote sales teams, virtual customer engagement, telephone-based product promotion, lead follow-up, account outreach, customer qualification, sales conversion, and remote coverage of healthcare providers and other target customers for medical devices.
Non-Personal / Indirect Commercial Support
The segment captures revenue generated by outsourced commercial activities that support medical device sales and commercialization without constituting the primary direct customer-facing sales interaction. Services include sales-force training and product education, channel and distributor support, sales operations, CRM and reporting, sales analytics, performance monitoring, commercial intelligence, and other ancillary commercial activities that facilitate sales execution, market expansion, and channel performance.
Sales Training & Product Education
The segment captures revenue generated by outsourced training and education services designed to improve sales-force effectiveness and product knowledge for medical device companies. Services include sales representative training, product and technology training, sales methodology training, clinical product education, customer education, training material development, onboarding, continuing education, and training related to the commercial introduction and adoption of medical devices.
Channel & Distributor Support
The segment captures revenue generated by outsourced commercial support for medical device distribution and channel networks. Services include distributor management, channel development, distributor recruitment and coordination, partner relationship management, distributor training, channel performance monitoring, territory and account coordination, distribution support, and management of commercial relationships between medical device manufacturers, distributors, and healthcare customers.
Other Services
The segment captures revenue generated by other outsourced commercial and sales-support activities for medical device companies that are not classified under field sales, account management, clinical and technical support, inside and remote sales, training, or channel and distributor support. Services include sales operations, CRM administration, sales reporting, performance monitoring, sales analytics, territory planning, commercial intelligence, sales-force effectiveness support, commercial strategy, and other ancillary activities directly supporting outsourced medical device sales and commercialization.
Segment: Therapeutic Area
Revenue Capture Definition
Cardiovascular
The segment captures revenue generated from medical device CSO services supporting cardiovascular products, including cardiac monitoring systems, interventional cardiology devices, vascular devices, electrophysiology products, structural heart devices, and other cardiovascular technologies.
Orthopedics
The segment captures revenue generated from medical device CSO services supporting orthopedic products, including joint replacement systems, trauma devices, spinal products, surgical instruments, orthopedic implants, and other musculoskeletal technologies.
Neurology
The segment captures revenue generated from medical device CSO services supporting neurological products, including neurosurgical devices, neurostimulation systems, deep brain stimulation technologies, neurological monitoring systems, and other devices used in neurological care.
Oncology
The segment captures revenue generated from medical device CSO services supporting oncology-related medical devices, including radiation therapy systems, surgical oncology devices, tumor ablation systems, biopsy systems, cancer diagnostic technologies, and other devices used in cancer diagnosis and treatment.
Diabetes & Metabolic Disorders
The segment captures revenue generated from medical device CSO services supporting diabetes and metabolic disease products, including glucose monitoring systems, continuous glucose monitoring devices, insulin delivery systems, insulin pumps, and other related technologies.
Respiratory
The segment captures revenue generated from medical device CSO services supporting respiratory care products, including ventilators, oxygen therapy systems, respiratory monitoring devices, sleep apnea devices, inhalation technologies, and other respiratory equipment.
General Surgery
The segment captures revenue generated from medical device CSO services supporting general surgical products, including surgical instruments, energy devices, laparoscopic systems, robotic surgical technologies, surgical stapling systems, and other devices used across general surgical procedures.
Others
The segment captures revenue generated from medical device CSO services supporting therapeutic areas outside cardiovascular, orthopedics, neurology, oncology, diabetes and metabolic disorders, respiratory, and general surgery, including ophthalmology, urology, gynecology, dermatology, dental, and other specialized medical device categories.
Segment - End Use
Revenue capture definition
Large Medical Device Companies
The segment captures revenue generated from CSO contracts with large medical device manufacturers having broad product portfolios, established commercial operations, and substantial geographic coverage requirements. Services include dedicated sales force outsourcing, key account management, clinical support, product education, channel management, and multi-market commercial programs.
Mid-Sized Medical Device Companies
The segment captures revenue generated from CSO contracts with mid-sized medical device manufacturers seeking outsourced commercial capabilities to expand market coverage, enter new geographic markets, launch products, or supplement internal sales organizations. Services include dedicated and shared sales teams, clinical support, account management, distributor support, and sales training.
Others
The segment captures revenue generated from CSO services provided to smaller medical device manufacturers, emerging companies, startups, specialty device companies, and other organizations that require outsourced commercial support. Services include targeted sales programs, product launch support, market entry assistance, distributor management, clinical education, and flexible sales force deployment.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Industry Outlook, Value Chain, and Business Model Assessment
Conducted a comprehensive assessment of the Medical Device Contract Sales Organizations ecosystem, covering medical device manufacturers, contract sales organizations, field sales representatives, clinical and technical sales teams, key account managers, distributors, healthcare providers, hospitals, IDNs, GPOs, and other commercial stakeholders. Evaluated outsourcing models, dedicated and shared sales teams, sales force deployment, channel support, clinical education, product demonstrations, customer engagement, CRM and reporting, revenue streams, pricing structures, and regional operating models across the medical device commercial lifecycle.
Provides a comprehensive understanding of market structure, revenue pools, outsourcing penetration, commercial service models, and value creation opportunities, enabling medical device manufacturers, CSOs, and investors to identify attractive service areas, customer segments, partnership opportunities, and geographic expansion opportunities.
Technology, Commercial Model, and Service Innovation Assessment
Assessed the adoption of CRM platforms, sales reporting systems, remote and inside sales, digital HCP engagement, data analytics, performance monitoring, virtual product demonstrations, AI enabled commercial tools, and technology supported field force management within Medical Device CSO operations. Evaluated the transition from traditional field sales toward hybrid commercial models combining physical and digital engagement.
Helps stakeholders identify technology driven service opportunities, improve sales force productivity, evaluate digital commercial models, and determine areas where technology can expand customer coverage and improve commercial execution.
Regulatory and Healthcare Market Access Assessment
Evaluated regulatory and commercial requirements affecting outsourced medical device sales activities across major markets, including product promotion requirements, healthcare professional engagement, distributor and channel requirements, hospital and IDN access, tender participation, and compliance considerations affecting commercial representatives. Regional differences in medical device regulations and healthcare procurement structures were also assessed.
Enables medical device manufacturers and CSOs to understand market specific commercial requirements, reduce compliance risks, structure appropriate sales models, and develop market entry strategies aligned with local healthcare and procurement environments.
Frequently Asked Questions About This Report
The global medical device contract sales organizations market size was valued at USD 3.4 billion in 2025 and is estimated at USD 3.6 billion in 2026.
The global medical device contract sales organizations market is expected to grow at a CAGR of 6.9% from 2026 to 2033, reaching USD 5.7 billion.
Key factors include the increasing outsourcing of commercial activities, rising complexity of healthcare provider and hospital purchasing processes, expansion of medical device portfolios, growing demand for flexible field sales and clinical support teams, and increasing adoption of outsourced market-entry and distribution models. The growing need to control commercial operating costs while maintaining specialized sales coverage is encouraging medical device manufacturers to engage external commercial partners. The expansion of medical device markets across emerging economies is further creating demand for regional sales teams, distributor management, and localized commercial support.
North America dominated with a 40.4% revenue share in 2025.
Asia Pacific is also the fastest-growing region over the forecast period.
The personal/direct commercial promotion service segment led with a 73.7% revenue share in 2025.
The cardiovascular segment led with a 23.5% revenue share in 2025.
The large medical device companies segment held the largest revenue share of 52.8% in 2025.
Key players include IQVIA Inc., Syneos Health, Inc., Inizio Engage / Inizio, Promoveo Health, MTMC / MedTech MedCare, Maxtown Medical, Greystone Medical Technologies, QFR Solutions, LLC, Cermax Healthcare, and Axxelus, among others.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


