
- Home
- »
- Medical Devices
- »
-
Medical Devices Reimbursement Market Report, 2026-2033GVR Report cover

Medical Devices Reimbursement Market (2026 - 2033)
Size, Share & Trends Analysis Report By Claim (Underpaid, Full Paid), By Payer (Public, Private), By Service Provider (Hospitals), By Region, And Segment Forecasts
Market Size, 2025
$832.7BMarket Estimate, 2026
$891.7BMarket Forecast, 2033
$1,520.2BCAGR, 2026–2033
7.9%Medical Devices Reimbursement Market Summary
The global medical devices reimbursement market size was valued at USD 832.7 billion in 2025 and is projected to grow from USD 891.7 billion in 2026 to USD 1,520.2 billion by 2033, at a CAGR of 7.9% from 2026 to 2033. The market in North America dominated with a revenue share of 46.1% in 2025. Increasing prevalence of cardiovascular diseases and technological advancements in the field of medical devices reimbursement are factors anticipated to boost market growth.
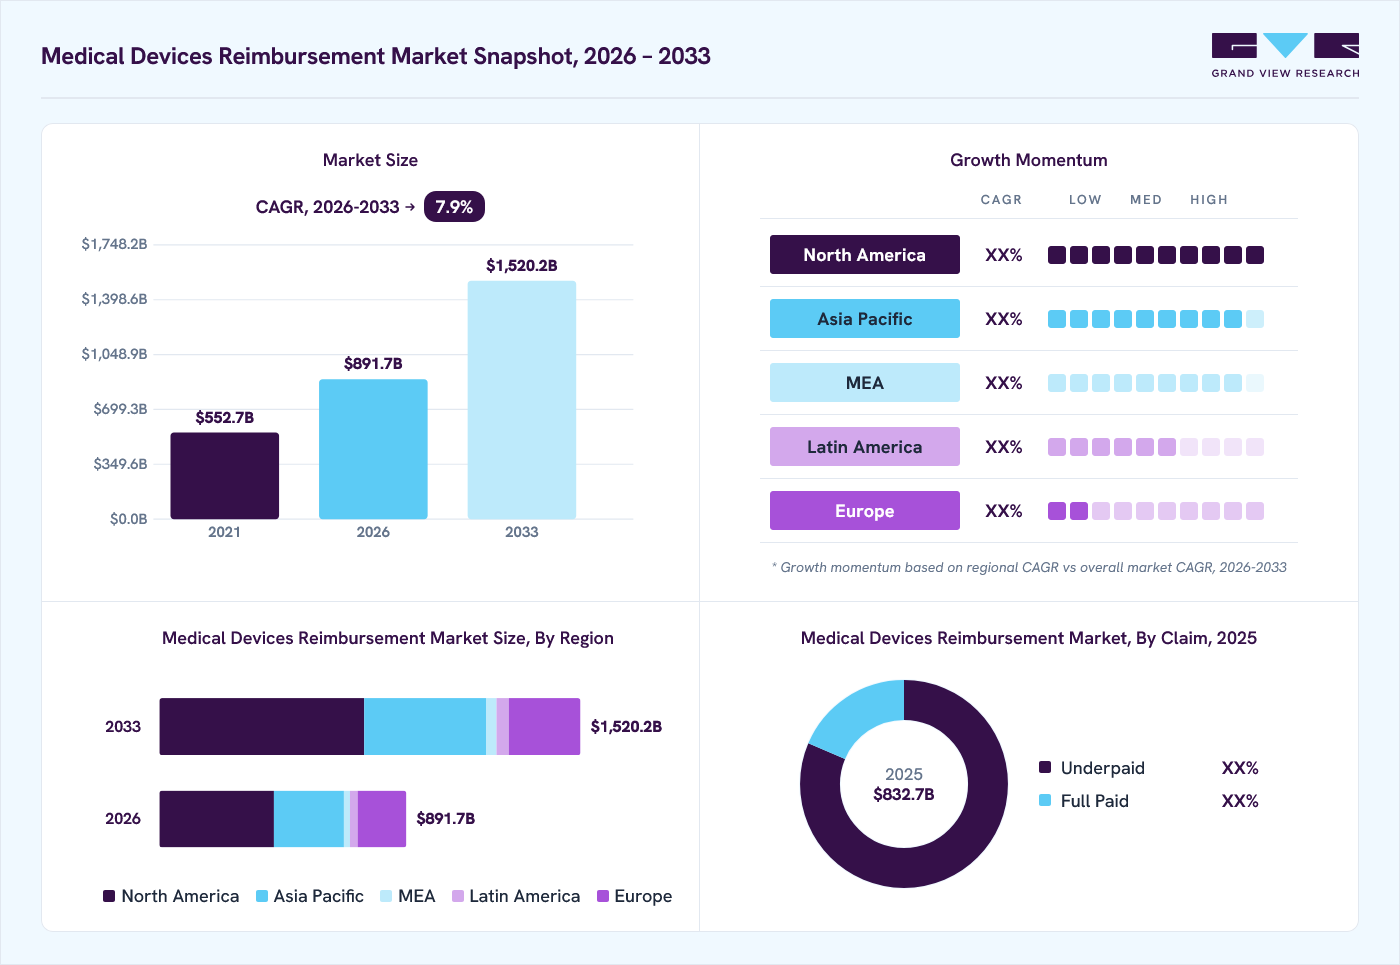 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By claim: Underpaid segment held the largest market share of 81.3% in 2025.
- By payer: Public payers segment held the largest market share of 65.9% in 2025.
- By service provider: Physician office segment held the largest market share of 47.4% in 2025.
Regional Highlights
- Largest regional market: North America (46.1% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 832.7 Billion
- Estimated market size in 2026: USD 891.7 Billion
- Projected market size by 2033: USD 1,520.2 Billion
- CAGR (2026-2033): 7.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to the World Health Organization's World Health Statistics 2024 report, Noncommunicable Diseases (NCDs) account for approximately 71% of all deaths worldwide, with cardiovascular diseases alone responsible for 17.9 million deaths annually. The rising prevalence of these conditions has led to an increased demand for medical devices such as insulin pumps, cardiac monitors, and dialysis machines. This surge necessitates comprehensive reimbursement strategies to ensure patient access to essential technologies. This is likely to add to market growth.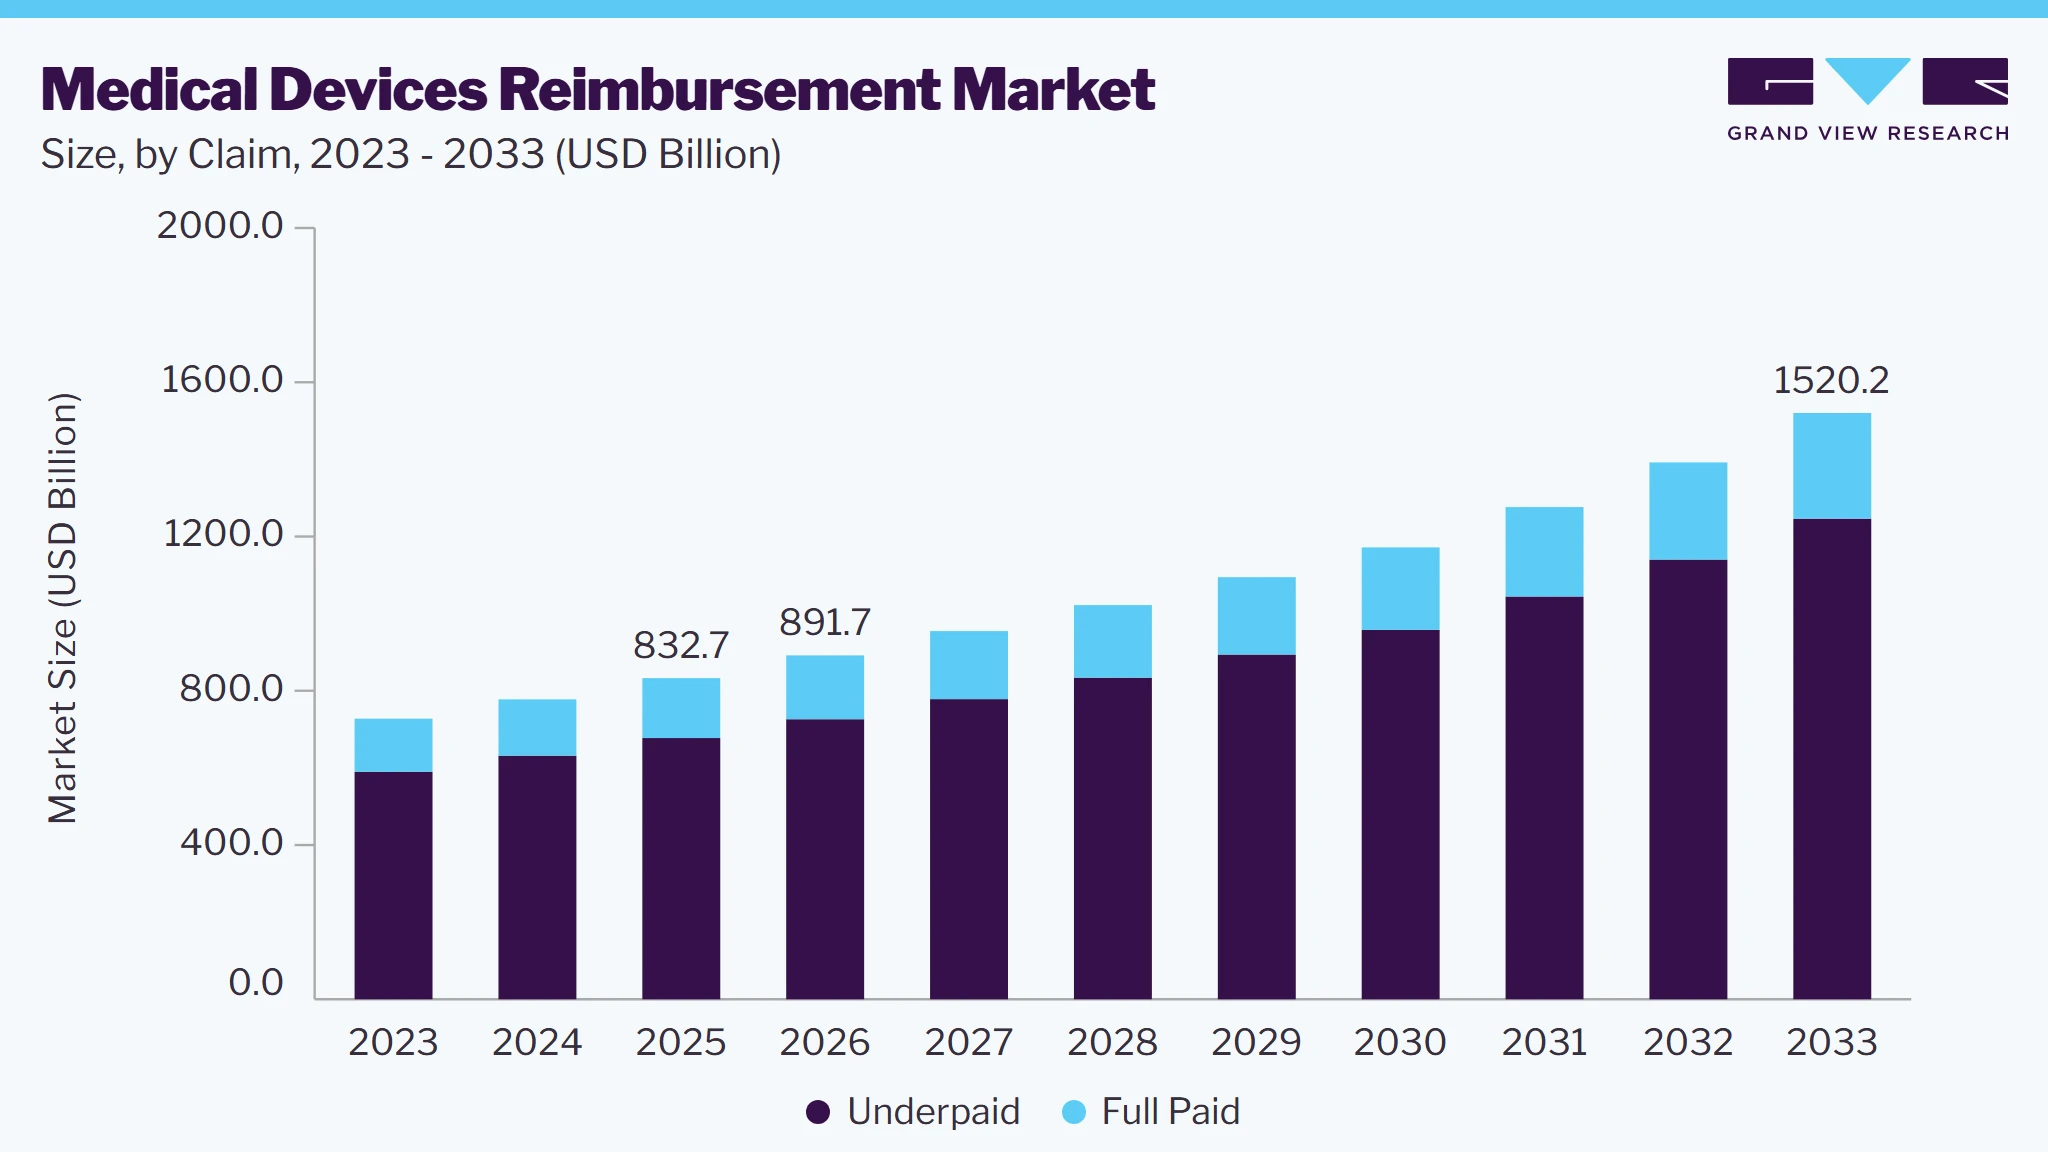 To learn more about this report, Download Free Sample Report
In addition, healthcare industry is experiencing a paradigm shift from traditional Fee-for-Service (FFS) models to Value-based Care (VBC) frameworks. This transition emphasizes patient outcomes and cost-efficiency, rewarding healthcare providers based on the quality rather than the quantity of care delivered. In 2022, nearly 70% of Medicare Advantage enrollees opted for providers participating in VBC models, reflecting a growing patient preference for such approaches. For medical device manufacturers, the shift to VBC necessitates the demonstration that their products contribute to improved patient outcomes and cost savings. Devices that can provide measurable improvements in health metrics are more likely to be favored in reimbursement decisions within VBC frameworks.
The Centers for Medicare & Medicaid Services (CMS) has established comprehensive policies governing the reimbursement of medical devices under the Medicare program. These policies are designed to ensure that beneficiaries have access to necessary medical technologies while maintaining fiscal responsibility. For instance, medicare provides coverage for DMEPOS, which includes items such as wheelchairs, prosthetic limbs, orthotic braces, and other medically necessary equipment. Payment for most DMEPOS items is determined by a fee schedule, where Medicare typically covers 80% of the approved amount and the beneficiary is responsible for the remaining 20%, along with any unmet Part B deductible. Payment amounts are established for items under the DMEPOS Competitive Bidding Program through a bidding process among suppliers.
Moreover, the U.S. Affordable Care Act (ACA) focuses on decreasing the costs of healthcare for patients. The main purpose of this Act is to reduce medical device costs and make affordable healthcare insurance available to every person in the country. In addition, the Center for Medicaid and Medicare is working toward providing high-quality medical devices and making health insurance available for billions of people. Medicaid spending in the U.S. increased by 9.2% in 2021. In addition, according to a report published by the American Medical Association, USD 4.3 trillion is estimated to have been spent on healthcare reimbursement in 2021 in the U.S.
Market Dynamics
The medical devices reimbursement market is experiencing significant growth, driven by the increasing prevalence of chronic diseases, rising healthcare expenditures, and growing adoption of advanced medical technologies. Reimbursement frameworks play a critical role in improving patient access to medical devices by reducing out-of-pocket costs and supporting the utilization of diagnostic, therapeutic, and monitoring devices across healthcare settings. The growing burden of cardiovascular diseases, diabetes, orthopedic disorders, and neurological conditions, coupled with an aging population requiring long-term medical care, is contributing to market expansion.
According to the World Health Organization's (WHO) World Health Statistics 2024 report, Noncommunicable Diseases (NCDs) account for approximately 71% of all deaths worldwide, with cardiovascular diseases alone responsible for 17.9 million deaths annually. The rising prevalence of these conditions has led to an increased demand for medical devices such as insulin pumps, cardiac monitors, and dialysis machines. This surge necessitates comprehensive reimbursement strategies to ensure patient access to essential technologies. The prevalence of cancer has significantly increased. For instance, according to the American Cancer Society estimates, in 2024, approximately 2,001,140 new cancer cases were diagnosed, and 611,720 cancer-related deaths occurred in the U.S. High prevalence of these diseases is anticipated to increase the need for affordable and quality healthcare.
Top 10 cancer types in the U.S. by estimated new cases, 2024
Rank
Cancer Type
Estimated New Cases (Both Sexes, 2024)
Male
Female
1
Breast
313,510
-
313,510
2
Prostate
299,010
299,010
-
3
Lung & Bronchus
234,580
116,310
118,270
4
Colon & Rectum
152,810
81,420
71,390
5
Melanoma of the Skin
100,640
60,480
40,160
6
Bladder
82,290
62,420
19,870
7
Non-Hodgkin Lymphoma
80,620
43,390
37,230
8
Kidney & Renal Pelvis
81,610
52,520
29,090
9
Uterine Corpus
67,880
-
67,880
10
Leukemia (All Types)
62,770
36,240
26,530
Source: American Cancer Society, Inc., Grand View Research
Medical device reimbursement is a complex process in many regions, with minimal participation from industry stakeholders. This limited engagement can be a significant constraint, as industry often holds proprietary data and evidence about devices unavailable in the public domain or through peer-reviewed publications. The payers of health insurance have a range of healthcare reimbursement plans and have contracts with health systems and individual practices. This means there can be a single price for services that exist in a health care system, which are contracted with a payer, and another price for services outside that system. For instance, the CMS mainly uses G-codes under the Medicare Physician Fee Schedule (MPFS) for Image-guided Radiation Therapy (IGRT) and Intensity-modulated Radiation Therapy (IMRT). Meanwhile, some non-Medicare payers may report using CPT codes in freestanding centers as per their own assigned value for CPT code 77387 or fee schedules or using one of the IGRT G-codes.
The path to claim payment is complex; hence, some providers have dedicated resources to fighting claims denied for various reasons, not just registration. This process includes understanding payer rejections and amending and submitting the claim again within a stated time frame. A company can deny a claim, declaring that “timely filing limitations” have been surpassed. The service is then written as the “patient is not liable.”
In addition, the price charged by a provider for a specific service is not the retail price. Payers have a maximum payment allowed for each Common Procedural Technology (CPT) code, which is the initial point of determining what the payers will pay. The payer then regulates the maximum payment allowed with “claim edits,” which disqualifies payment for some services, and “payment rules,” which usually minimize payments for some services.
The growing emphasis on improving patient outcomes and reducing long-term healthcare costs presents a significant opportunity for the medical device’s reimbursement market. Governments, public payers, and private insurers are increasingly expanding reimbursement coverage for innovative medical technologies, including remote patient monitoring devices, wearable health technologies, minimally invasive devices, and home healthcare equipment. As healthcare systems shift toward value-based care models, manufacturers that generate strong clinical and economic evidence demonstrating cost-effectiveness and improved patient outcomes will be better positioned to secure favorable reimbursement approvals and accelerate market adoption.
Market Concentration & Characteristics
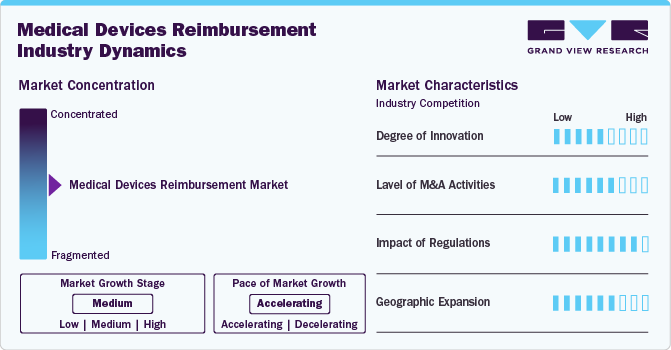
The medical devices reimbursement industry is experiencing a medium level of degree of innovation driven by the development of emerging technologies, such as 3D-printed implants and digital therapeutics, are driving new coverage considerations. Various regulatory initiatives are undertaken aimed at improving access to medical technologies, which can influence reimbursement policies and practices globally. In July 2024, the World Health Organization (WHO) launched the Medical Devices Information System (MeDevIS), an online platform designed to enhance global access to medical technologies and devices. MeDevIS serves as the first global open-access clearinghouse for information on medical devices, aiming to standardize data and improve transparency in the medical device sector.
 To learn more about this report, Download Free Sample Report
The level of M&A activities is moderate in the market. Mature players are acquiring emerging players to strengthen their position. For instance, in August 2024, IQVIA acquired MCRA, a prominent medical device advisory firm. This strategic acquisition enhanced IQVIA's capabilities in the medical device sector by integrating MCRA's expertise in regulatory affairs, clinical research, reimbursement, and quality assurance. MCRA, now operating as an IQVIA business, continues to offer comprehensive support to clients, assisting them throughout the entire technology lifecycle from research and development to commercialization.
Government initiatives play a vital role in boosting medical reimbursement market growth. For instance, the Affordable Care Act (ACA), implemented in the U.S., focuses on expanding health insurance coverage to low-income individuals. The act aims to improve the quality of healthcare services and reduce the cost of care. The expanding insurance coverage is expected to increase the number of reimbursements as well as denials.
Several market players are expanding their business by introducing new services. For instance, in June 2024, Endotronix, Inc. received FDA Premarket Approval (PMA) for its Cordella Pulmonary Artery (PA) Sensor System designed to treat patients with New York Heart Association (NYHA) Class III heart failure. The Cordella System includes an implantable PA sensor that remotely monitors pulmonary artery pressure, a key indicator of heart failure status. It also enables reimbursement for implantation and ongoing management through existing reimbursement pathways.
Analyst Perspective
The medical devices reimbursement market is benefiting from the increasing adoption of advanced medical technologies, rising prevalence of chronic diseases, and growing demand for affordable access to innovative healthcare solutions. Expanding healthcare coverage, evolving reimbursement frameworks, and the shift toward value-based care models are encouraging broader utilization of medical devices across diagnostic, therapeutic, and monitoring applications. In addition, the growing aging population and increasing burden of cardiovascular, orthopedic, neurological, and metabolic disorders are driving demand for reimbursable medical devices.
Claim Insights
Based on claim, the underpaid segment led the market with the largest revenue share of 81.3% in 2025 and is expected to grow at the fastest CAGR over the forecast period. Underpaid claims occur when healthcare providers receive lower reimbursements than expected for medical devices due to coding errors, policy changes, or administrative delays. This issue affects hospitals, clinics, and manufacturers, leading to financial strain and disputes with payers. Many providers struggle to recover lost revenue, as the appeals process can be complex and time-consuming. In the U.S., a significant portion of medical device claims are underpaid due to discrepancies in billing codes and shifting insurance policies. Recent data suggests that automation and AI-driven claim review systems are helping providers identify and challenge underpaid claims more efficiently.
The full paid segment is expected to grow significantly over the forecast period. Full paid claims represent successful reimbursement transactions where healthcare providers receive the due amount for medical devices. These claims indicate a well-functioning reimbursement system, allowing hospitals and device manufacturers to maintain financial stability. In the U.S., the Centers for Medicare & Medicaid Services (CMS) has introduced new policies to streamline reimbursements for innovative medical devices, ensuring full payments for eligible products. The FDA’s approval of new breakthrough medical devices has recently led to increased reimbursement approvals, benefiting manufacturers and healthcare providers.
Payer Insights
Based on payer, the public payers segment led the market with the largest revenue share of 65.9% in 2025. The demand for public payers is increasing due to the rising prevalence rate of chronic diseases globally and the need for cost-effective procedures in healthcare settings. An increase in the adoption of public payer services in emerging & developed markets and the introduction of advanced medical devices along with reimbursement facilities are further driving segment growth. For instance, in July 2024, the Centers for Medicare & Medicaid Services (CMS) introduced the Transitional Coverage for Emerging Technologies (TCET) program. This initiative aims to expedite Medicare coverage for FDA-designated breakthrough medical devices, enhancing patient access to innovative technologies. The TCET program seeks to streamline the coverage process, balancing the need for rapid access with patient safety and clinical effectiveness
The private payer segment is expected to grow at the fastest CAGR over the forecast period owing to the presence of a large number of private players in the market. The rising prevalence of cancer & diabetes and increasing demand for better treatment are factors expected to drive segment growth over the forecast period. Private players reimburse a medical device that has been approved by the FDA. In addition, with the increasing prevalence of respiratory diseases, the demand for expensive medical devices, such as ventilators, is increasing. Therefore, the demand for private payer services is expected to grow over the forecast period.
Service Provider Insights
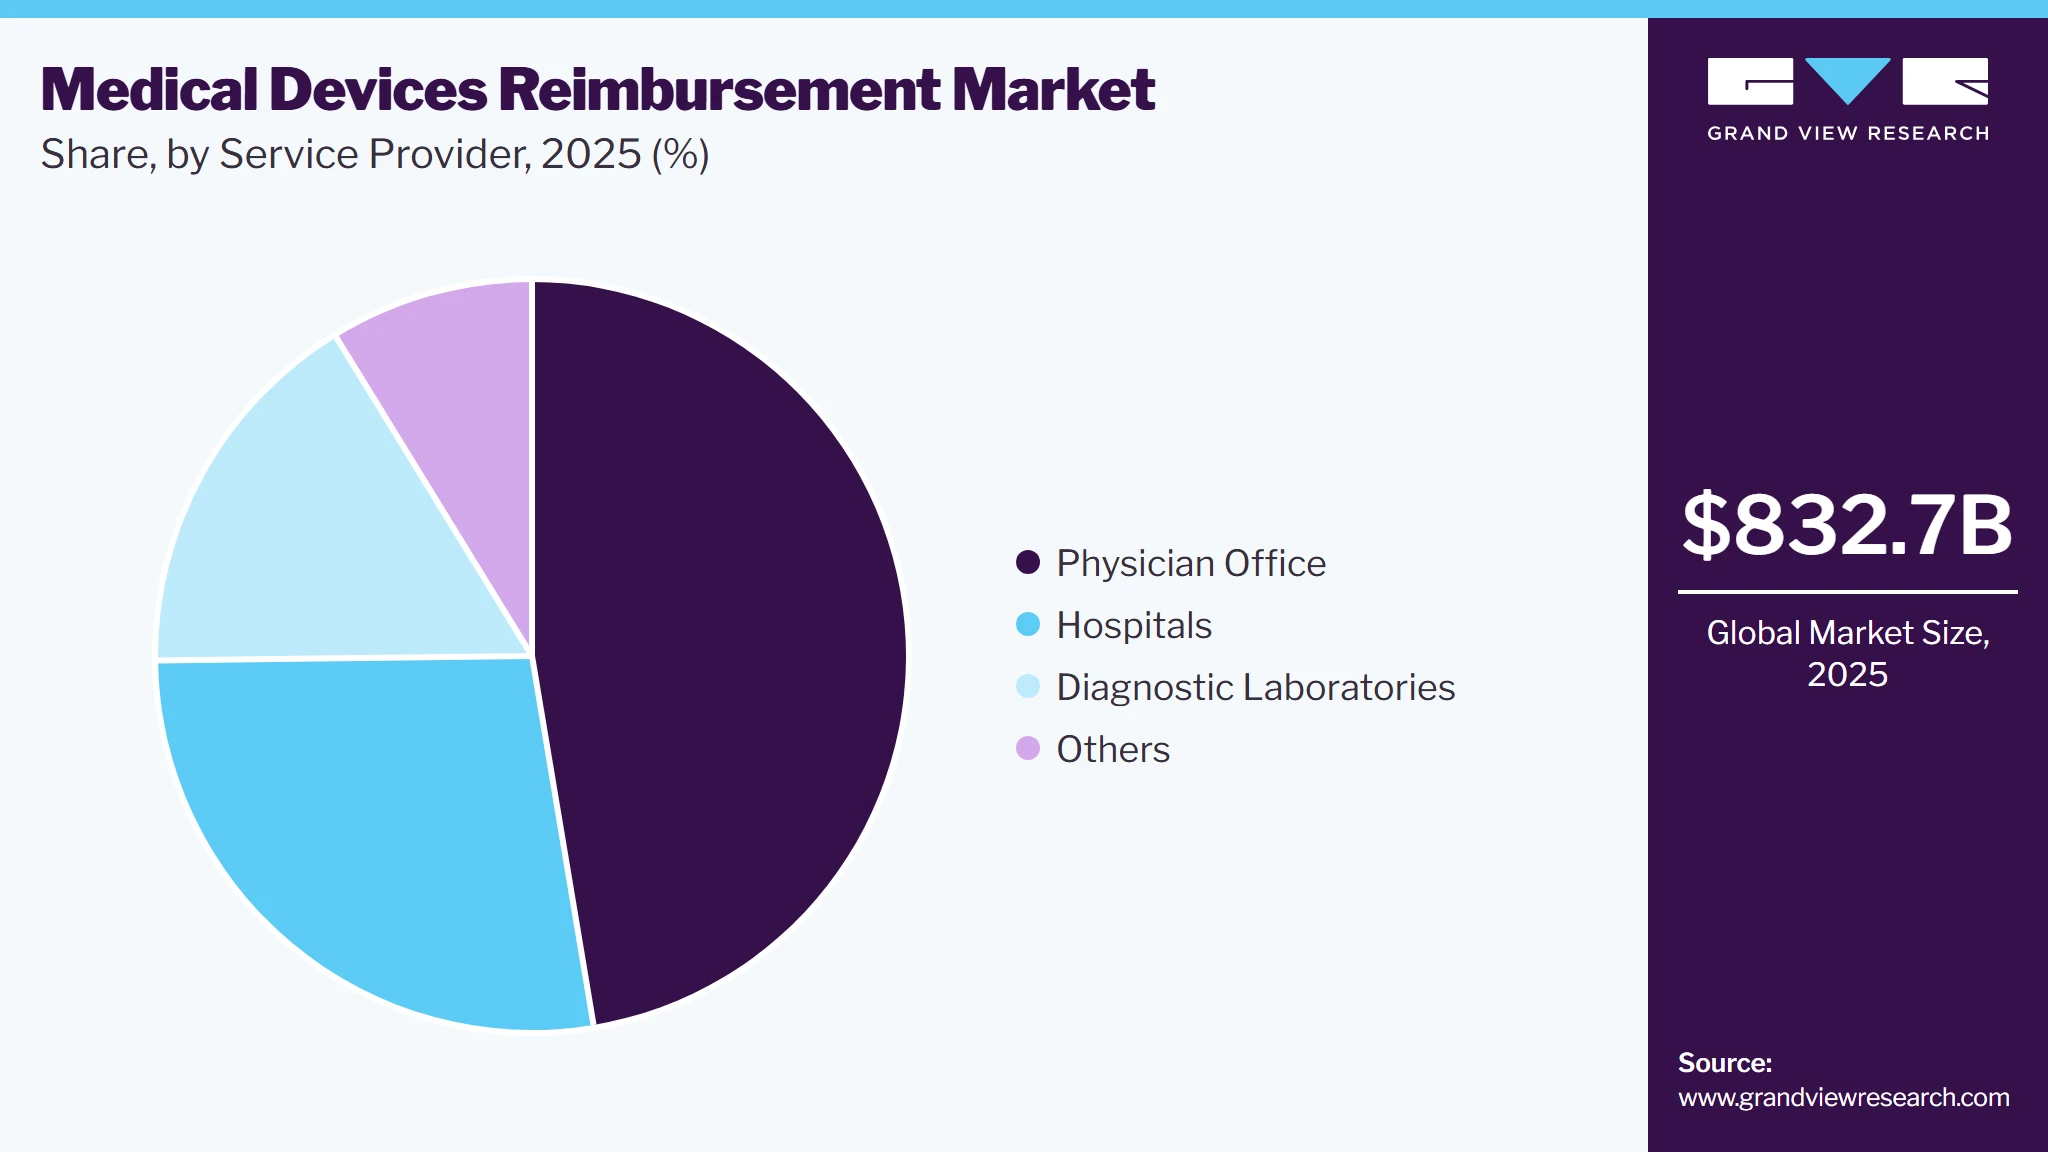
Based on service provider, the physician office segment led the market with the largest revenue share of 47.4% in 2025 owing to the frequent use of various medical devices for diagnosis, treatment, and patient management. Devices such as diagnostic tools, monitoring equipment, and therapeutic devices are commonly used in outpatient settings. Reimbursement for these devices is typically processed through private insurance providers, Medicare, or Medicaid, depending on the country’s healthcare system.
 To learn more about this report, Download Free Sample Report
Hospitals are expected to grow at a significant CAGR over the forecast period, serving as primary end-users that rely on reimbursement policies to manage costs and ensure patient access to advanced medical technologies. Reimbursement frameworks directly impact hospitals' purchasing decisions, particularly for high-cost devices such as implantable cardiac devices, surgical robotics, diagnostic imaging equipment, and AI-driven monitoring systems. Many hospitals operate under Diagnosis-Related Groups (DRGs), bundled payments, or fee-for-service models, where reimbursement rates determine the financial feasibility of adopting new medical technologies.
Regional Insights
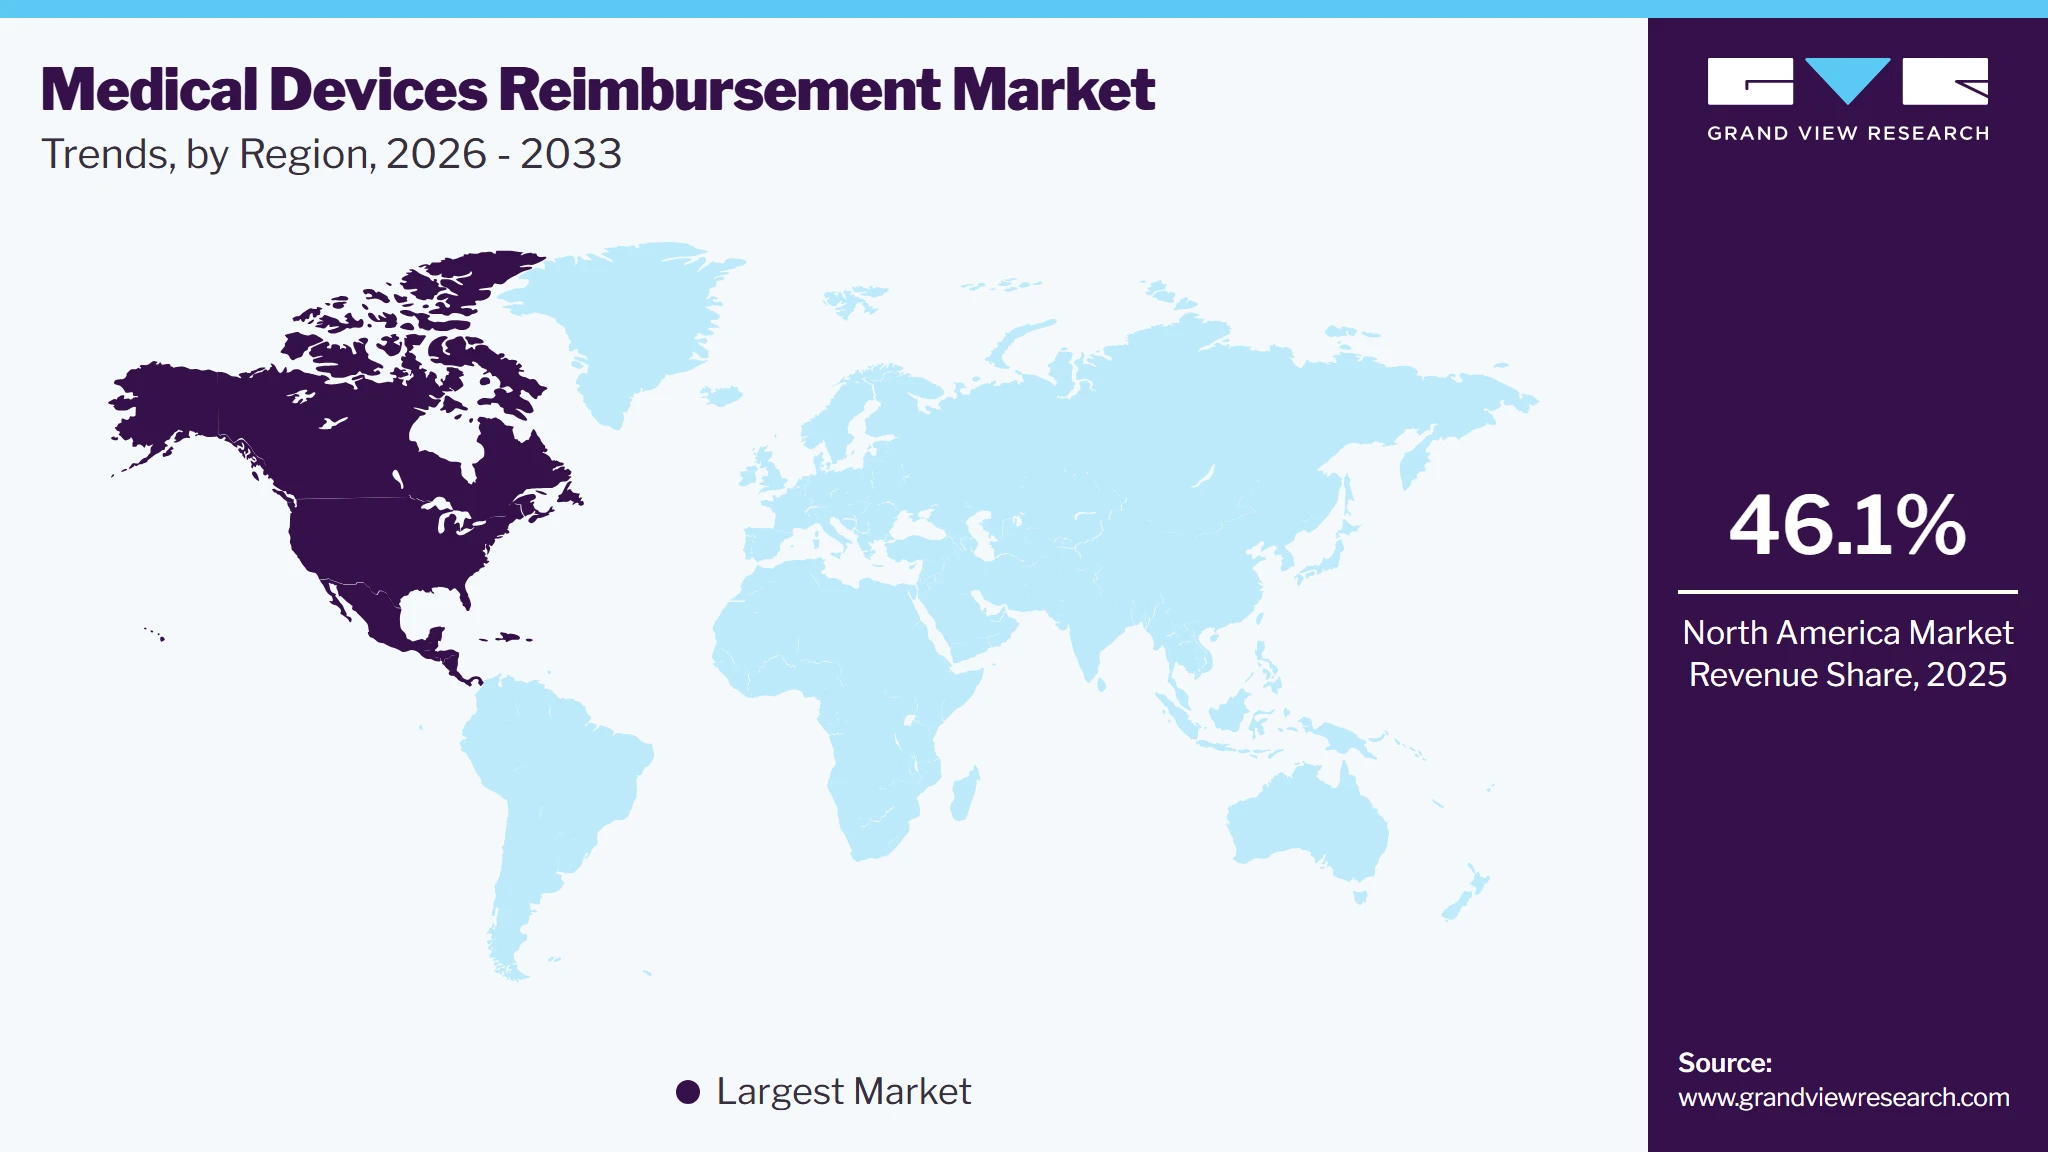
North America dominated the medical devices reimbursement market with the largest revenue share of 46.1% in 2025 and is expected to maintain its position during the forecast period. owing to favorable regulatory policies and robust reimbursement structure. Provisions for medical device reimbursement are also well-established in the region. The rising prevalence of chronic diseases, coupled with increasing demand for medical devices, is expected to augment market growth in this region over the forecast period.
 To learn more about this report, Download Free Sample Report
U.S. Medical Devices Reimbursement Market Trends
The market in the U.S. held the largest share in the North America region in 2025, due to technological advancements and the recent reimbursement approvals of many medical devices. The U.S. Affordable Care Act helps regulate and reduce healthcare expenses by distributing the cost of specific services across a broad patient base. This legislation has made healthcare more accessible to a larger population by promoting innovative approaches to delivering medical care at lower costs. In addition, the Centers for Medicare & Medicaid Services (CMS) implements effective strategies to enhance the healthcare system by ensuring the provision of high-quality, reliable care and expanding health insurance coverage nationwide. These supportive policies contribute significantly to the dominant share of the medical device reimbursement market.
Europe Medical Devices Reimbursement Market Trends
Europe held a substantial revenue share of the global medical devices reimbursement industry. The UK, France, Germany, Italy, and Spain are the main markets in this region. Growing R&D activities in the pharma and biotech sector in developed countries, such as the UK, Germany, Italy, & France, and the presence of high unmet needs in Eastern Europe are some of the factors anticipated to drive growth over the forecast period. The increasing prevalence of chronic diseases due to lifestyle changes is a major factor likely to drive the market. Other factors contributing to the growth of this region are the local presence of major market players, technological advancements, and growth in business activities, such as the launch of new products and mergers & acquisitions.
Germany dominated the Europe medical devices reimbursement market owing to the presence of advanced healthcare system. The country has around 100 statutory health insurers, with the National Association of Statutory Health Insurance Funds (GKV) being the largest payer institution. However, on the basis of the number of persons insured, Techniker Krankenkasse (TK) is the largest single health insurance funding entity in Germany; it provided insurance to around 11.3 million individuals in 2023.
The UK is one of the largest markets for medical devices reimbursement in Europe and is expected to witness lucrative growth. Rising incidence & prevalence of chronic diseases are some of the major factors contributing to this growth. In addition, the geriatric population in the UK has significantly increased in the past five decades, which is further likely to add to the market demand. For instance, according to a report by the UK parliament, over one-fifth of the people in the country are above 65 years of age.
Asia Pacific Medical Devices Reimbursement Market Trends
The medical devices reimbursement market in Asia Pacific is expected to register significant growth over the forecast period. The evolving business landscape and the increasing costs of medical devices are key factors driving the demand for medical device reimbursement services in countries such as India and China.
China dominated the Asia Pacific medical devices reimbursement market. China is a major medical device reimbursement market due to its cost-effectiveness and the growing pharmaceutical industry. Due to cost-efficient services provided by the Chinese healthcare industry as compared to the U.S. and European countries, there is an increasing demand for medical device reimbursement market services. Increasing awareness regarding medical devices reimbursement process is further expected to boost the market during the forecast period.
India is expected to register significant growth over the forecast period in Asia Pacific medical devices reimbursement market. India faces significant healthcare challenges, particularly with the rising incidence of cancer. It is projected that one in nine Indians will receive a cancer diagnosis in their lifetime, making it imperative to enhance access to effective medical care. The limited availability of medical equipment, especially in Tier 2 and Tier 3 cities, has severely impacted on the quality of healthcare services. This situation necessitates innovative solutions to bridge the gap in healthcare infrastructure.
Latin America Medical Devices Reimbursement Market Trends
The medical devices reimbursement market in Latin America is expected to register considerable growth over the forecast period owing to its proximity to the U.S., which reduces monitoring costs associated with reimbursement services. Presence of medical devices reimbursement rise in investments in R&D research and increase in regulatory guidelines are among factors expected to drive the medical devices reimbursement industry in the region.
Middle East & Africa Medical Devices Reimbursement Market Trends
The medical device reimbursement market in the Middle East & Africa (MEA) is driven by rising healthcare expenditure, government initiatives, and expanding insurance coverage. Several Gulf Cooperation Council (GCC) countries, such as Saudi Arabia, the UAE, and Kuwait, have universal healthcare schemes that support the reimbursement of medical devices. In addition, increasing private health insurance penetration in these countries is improving access to advanced medical technologies. Countries such as South Africa are implementing National Health Insurance (NHI) programs, aiming to expand coverage and integrate medical device reimbursement into their healthcare frameworks.
Key Medical Devices Reimbursement Company Insights
Key companies in the market are engaged in adopting strategies such as mergers and acquisitions, new service launches, partnerships, collaborations, and expansion to strengthen their position in the market.
Key Medical Devices Reimbursement Companies:
The following key companies have been profiled for this study on the medical devices reimbursement market.
-
MCRA (IQVIA)
-
WellCare Health Plans, Inc.
-
BNP Paribas
-
Boston Scientific
-
Humana
-
Cigna Healthcare
-
Anthem Insurance Companies, Inc. (Elevance Health)
-
Abbott Laboratories
-
Ethicon (J & J Medtech)
-
AdvaMed
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., MCRA (IQVIA), Humana, Cigna Healthcare, Anthem Insurance Companies (Elevance Health), WellCare Health Plans)
- Expand reimbursement management platforms, strengthen payer-provider partnerships, enhance claims analytics capabilities, and support value-based care initiatives. Invest in automation, AI-driven claims processing, regulatory consulting, and reimbursement advisory services to improve payment efficiency and coverage decisions.
- Strong relationships with payers, providers, and regulatory bodies; extensive healthcare data assets; broad market presence; and deep expertise in reimbursement policies and claims management. Ability to influence reimbursement pathways and support large-scale healthcare networks.
- Complex regulatory environments, dependence on evolving healthcare policies, high operational costs, and challenges associated with integrating diverse payer systems. Large organizations may face slower implementation of innovative reimbursement solutions.
Emerging Players (e.g., BREG, Inc., Fillauer LLC, McDavid, Weber Orthopedic LP, Frank Stubbs Company Inc.)
- Focus on generating clinical and health-economic evidence to secure favorable reimbursement coverage for innovative medical devices. Leverage digital health technologies, patient access programs, provider education initiatives, and specialized reimbursement support services to drive adoption.
- Greater agility in addressing specific reimbursement challenges for emerging technologies, strong focus on innovation, and ability to develop targeted market access strategies for high-growth device segments.
- Dependence on payer approval processes, limited influence over reimbursement policy decisions, significant evidence-generation costs, and uncertainty regarding coverage and payment timelines for new technologies.
Recent Developments
-
In August 2025, The Centers for Medicare and Medicaid Services (CMS) issued a National Coverage Determination (NCD) to provide reimbursement for Implantable Pulmonary Artery Pressure Sensors (IPAPS) used in heart failure management. The decision falls under the Coverage with Evidence Development (CED) framework. As part of this NCD, the CardioMEMS CED study received CMS approval, ensuring that all Medicare beneficiaries, including those who were previously denied under Medicare Advantage plans, can access the CardioMEMS HF System, provided they meet the NCD criteria.
-
In February 2025, The French National Authority for Health released seven recommendations regarding the add-on reimbursement of medical devices and medical aids. These recommendations, developed by the National Commission for Evaluation of Medical Devices and Health Technologies (CNEDiMTS), pertain to the inclusion or modification of devices in the List of Reimbursable Products and Services (LPPR). The devices evaluated span various medical fields, including neurovascular, neuromodulation, endocrine, ophthalmology, orthopedics, and medical aid.
-
In May 2023, Humana announced partnerships with two national DME providers, AdaptHealth Corp. and Rotech Healthcare Inc., to enhance access to DME for its Medicare Advantage HMO members. These partnerships operate under a value-based structure, with each provider serving specific regions. This initiative aimed to streamline the DME acquisition process, improve service quality, and contribute to better health outcomes for members. It also simplified the ordering process for healthcare providers, ensuring timely delivery of necessary equipment.
Medical Devices Reimbursement Market Report Scope
Report Attribute
Details
Market size in 2025
USD 832.7 billion
Estimated market size in 2026
USD 891.7 billion
Projected market size by 2033
USD 1,520.2 billion
Growth rate
CAGR of 7.9% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Claim, payer, service provider, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
MCRA (IQVIA), WellCare Health Plans, Inc., BNP Paribas, Boston Scientific, Humana, Cigna Healthcare, Anthem Insurance Companies, Inc. (Elevance Health), Abbott Laboratories, Ethicon (J & J MedTech), AdvaMed.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchasse. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Devices Reimbursement Market Report Segmentation
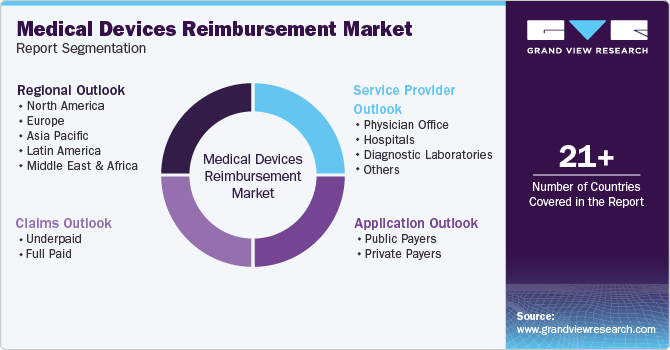
This report forecasts revenue growth and provides at global, regional, and country levels an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this report, Grand View Research has segmented the global medical devices reimbursement market report-based on claim, payer, service provider, and region:
 To learn more about this report, Download Free Sample Report
-
Claims Outlook (Revenue, USD Billion; 2021 - 2033)
-
Underpaid
-
Full Paid
-
-
Application Outlook (Revenue, USD Billion; 2021 - 2033)
-
Public payers
-
Private payers
-
-
Service Provider Outlook (Revenue, USD Billion; 2021 - 2033)
-
Physician Office
-
Hospitals
-
Diagnostic Laboratories
-
Others
-
-
Regional Outlook (Revenue, USD Billion; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The medical devices reimbursement market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical devices reimbursement segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Claim
Revenue capture definition
Underpaid
Reimbursement claims where the payment received is lower than the amount eligible under payer contracts, fee schedules, or reimbursement policies.
Full Paid
Reimbursement claims where the healthcare provider receives the complete eligible payment amount as defined by reimbursement guidelines and payer agreements.
Segment - Payer Type
Revenue capture definition
Public Payers
Government-funded reimbursement programs, such as Medicare, Medicaid, and national health insurance schemes, that cover medical device-related expenses.
Private Payers
Commercial insurance providers and private health plans that reimburse healthcare providers for medical devices and associated services.
Segment - Service Provider
Revenue capture definition
Physician Office
Revenue generated from medical device reimbursement claims submitted and processed through physician practices and outpatient clinics.
Hospitals
Revenue captured through reimbursement for medical devices used in inpatient, outpatient, surgical, and emergency care settings within hospitals.
Diagnostic Laboratories
Revenue derived from reimbursement for medical devices and equipment utilized in diagnostic testing, screening, and laboratory procedures.
Others
Revenue generated through reimbursement claims from ambulatory surgery centers, home healthcare providers, rehabilitation centers, and other healthcare facilities.
Estimation Model
Pillars of Market Estimation
1. Secondary Market Research
Data Sources:
-
Government & Health Agency Reports: OECD Health Statistics, WHO Global Health Expenditure Database, Centers for Medicare & Medicaid Services (CMS), NHS Digital, and Japan’s MHLW reimbursement tariffs.
-
Regulatory & Policy Databases: National Health Authority (India), European Commission Health Technology Assessment (HTA) frameworks, NICE reimbursement guidelines, and U.S. Medicare Fee Schedule archives.
-
Company Filings & Annual Reports: Medtronic, Boston Scientific, Abbott, Johnson & Johnson MedTech, Siemens Healthineers, and Philips disclosures—particularly on reimbursement strategies and payer mix.
-
Industry Associations: AdvaMed (U.S.), MedTech Europe, Asia Pacific Medical Technology Association (APACMed), and Latin American Medical Device Associations for national-level reimbursement patterns.
-
Academic & Clinical Publications: Peer-reviewed journals analyzing device reimbursement efficiency, underpayment rates, and DRG-based payment variations.
Analysis Focus:
-
Mapping device-level reimbursement rates and coverage trends under national health schemes.
-
Tracking payer mix evolution (public vs. private reimbursement).
-
Evaluating HTA-driven adoption barriers, co-pay changes, and price caps by device class.
-
Benchmarking claim settlement ratios across service providers.
2. Primary Market Intelligence
2.1 Online Survey Program
Survey Coverage:
Healthcare administrators, payers, and device billing staff across 23 countries.Survey Modules:
-
Claim success ratio (underpaid vs. full paid)
-
Payment delays and average approval cycles
-
Payer preference (public vs. private) for device categories
-
Provider-level dependency on reimbursement
-
Share of denied or reprocessed claims
Completed Survey (by year):
Year
Number of Survey’s Conducted
2021
~3,200
2022
~3,860
2023
~4,230
2024
~4,650
2025
~3,140 (till Q3)
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Reimbursement Coverage Analysis by Device Category
Developed a comprehensive assessment of reimbursement coverage across major medical device categories, including cardiovascular devices, orthopedic devices, diagnostic equipment, diabetes management devices, and remote patient monitoring solutions. The study evaluates reimbursement rates, coverage policies, payer mix, claim approval trends, and regional variations.
Enables stakeholders to identify high-reimbursement device segments, optimize market access strategies, prioritize product investments, and improve reimbursement success rates across key markets.
Patient Access & Reimbursement Journey Analysis
Developed a patient-centric assessment tracking the reimbursement journey from diagnosis and device prescription to claim submission, approval, payment, and ongoing coverage. The study incorporates payer requirements, patient affordability factors, provider participation, reimbursement timelines, and coverage barriers.
Provides actionable insights for improving patient access, reducing reimbursement delays, enhancing claim approval rates, and strengthening payer-provider engagement strategies.
Reimbursement Policy & Market Access Assessment
Conducted an in-depth evaluation of evolving reimbursement policies, coding frameworks, value-based care initiatives, and coverage requirements for innovative medical devices. The study benchmarks reimbursement pathways, policy changes, payer adoption trends, and competitive positioning.
Helps stakeholders identify reimbursement opportunities, strengthen market access planning, support evidence-generation initiatives, and accelerate commercialization of innovative medical technologies.
Frequently Asked Questions About This Report
North America dominated with a 46.1% revenue share in 2025.
The public payers segment led with a 65.9% revenue share in 2025, while the private payers segment is the fastest-growing payer.
The physician office segment led with a 47.4% revenue share in 2025.
The global medical devices reimbursement market size was valued at USD 832.7 billion in 2025 and is estimated at USD 891.7 billion for 2026.
Some key players operating in the medical devices reimbursement market include MCRA (IQVIA), WellCare Health Plans, Inc., BNP Paribas, Boston Scientific, Humana, Cigna Healthcare, Anthem Insurance Companies, Inc. (Elevance Health), Abbott Laboratories, Ethicon (J & J Medtech), AdvaMed.
Key factors driving the medical devices reimbursement market growth include increased cost of devices, enhanced strategic planning on part of medical device manufacturers, the introduction of reforms and new bills by governments, and shift of healthcare providers to form accountable care organizations (ACOs).
The underpaid segment led with a 81.3% revenue share in 2025 and is the fastest-growing claim.
The global medical devices reimbursement market is expected to grow at a CAGR of 7.9% from 2026 to 2033, reaching USD 1,520.2 billion by 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


