
- Home
- »
- Medical Devices
- »
-
Medical Service Robots Market Size Report, 2026-2033GVR Report cover

Medical Service Robots Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Disinfection Robots, Robotics Nurse Assistant, Medical Telepresence Robots, Delivery Robots), By Region, And Segment Forecasts
Market Size, 2025
$1.4BMarket Estimate, 2026
$1.6BMarket Forecast, 2033
$3.9BCAGR, 2026–2033
13.9%Medical Service Robots Market Summary
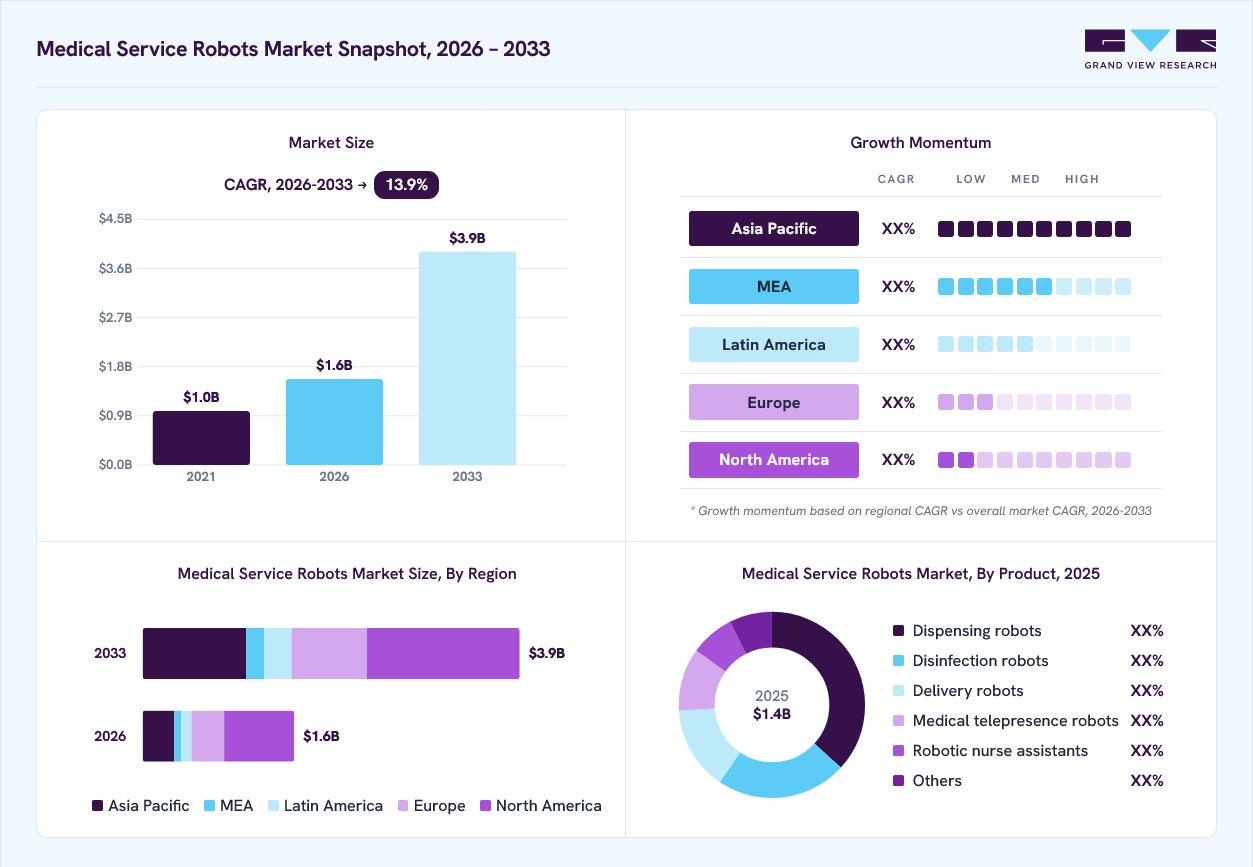
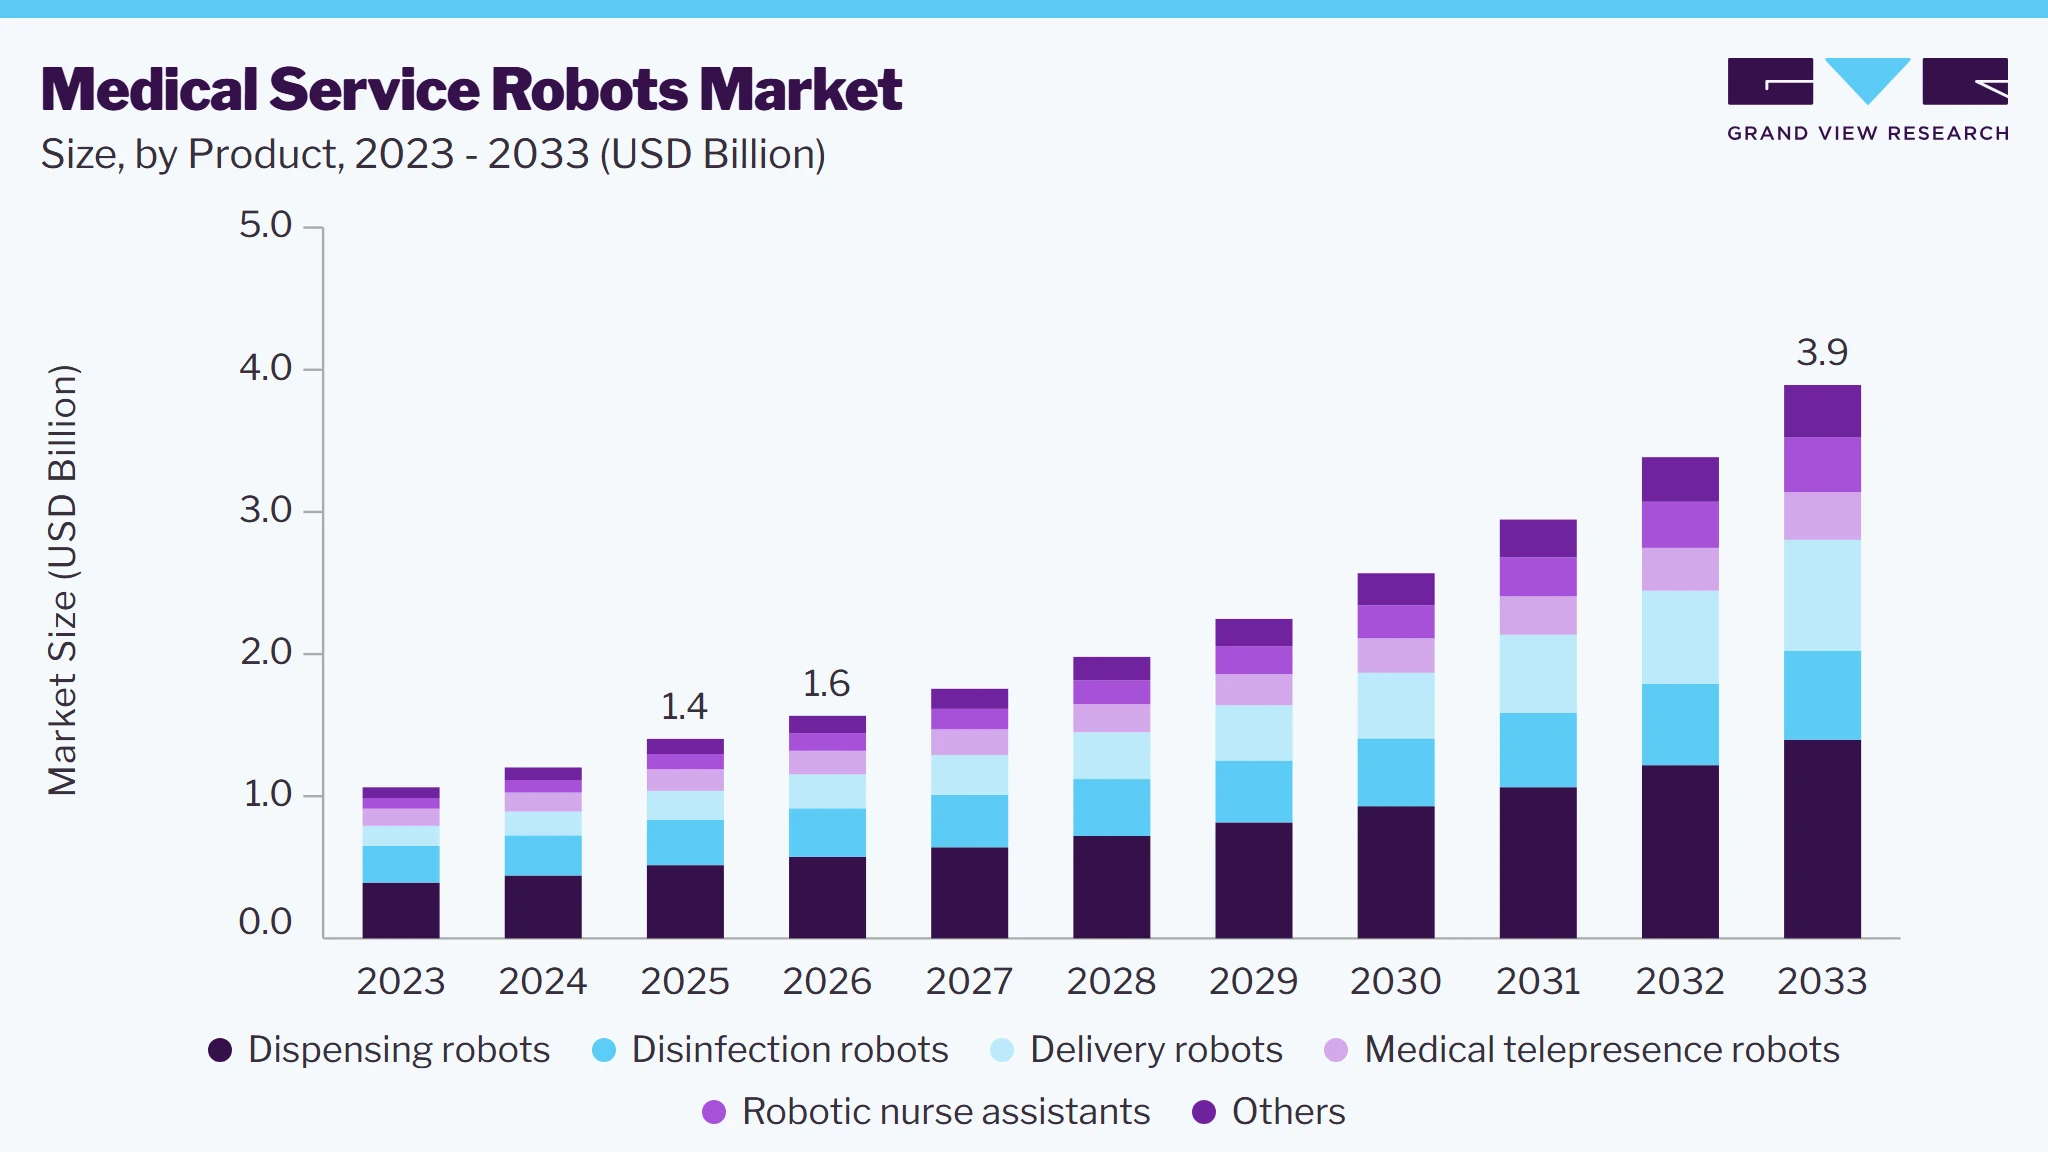
The global medical service robots market size was valued at USD 1.4 billion in 2025 and is projected to grow from USD 1.6 billion in 2026 to USD 3.9 billion by 2033, at a CAGR of 13.9% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 47.0% in 2025.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Dispensing robots segment held the largest revenue share of 36.9% in 2025
Regional Highlights
- Largest regional market: North America 47.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. dominated North America with the largest revenue share in 2025
Market Size & Forecast
- Market Size in 2025: USD 1.4 Billion
- Estimated Market Size in 2026: USD 1.6 Billion
- Projected Market Size by 2033: USD 3.9 Billion
- CAGR (2026-2033): 13.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
Market Dynamics
The increasing demand for pharmacy automation and medication dispensing robots is a major driver of the global medical service robots market. Rising prescription volumes, expanding hospital pharmacies, and growing emphasis on medication safety are encouraging healthcare providers to automate dispensing processes. Dispensing robots improve prescription accuracy, automate medication storage and retrieval, reduce dispensing errors, and optimize inventory management. Integration with electronic health records (EHRs), computerized physician order entry (CPOE), and hospital pharmacy information systems further enhances workflow efficiency and traceability. These capabilities enable healthcare facilities to improve patient safety while reducing operational costs and manual workload. For instance, in September 2025, ST Engineering Aethon and Oracle announced an integrated solution that automates hospital inventory transport and management by linking Aethon’s autonomous mobile robots and vision-based logistics with Oracle Fusion Cloud Advanced Inventory Management.
“We’re excited to deliver this integration to our healthcare customers, marking a new era of automation where real-time data, intelligent robotics, and advanced inventory management work seamlessly together to enhance patient care and drive operational excellence. Built on Oracle Cloud SCM and powered by Oracle Advanced Inventory Management, this solution gives hospitals a unified platform to streamline supply chain processes, maintain accurate inventory, and respond faster to changing demands.”
-Kristen Miles, vice president, healthcare product strategy, Oracle
Growing shortages of pharmacists and healthcare personnel, coupled with increasing demand for efficient medication management, are accelerating the adoption of dispensing robots across hospitals and healthcare institutions. Automated dispensing systems allow pharmacy staff to focus on clinical services while minimizing repetitive manual tasks and improving turnaround times. In addition, advances in artificial intelligence, barcode verification, robotic vision, and automated inventory tracking have further strengthened the performance and reliability of these systems. As healthcare providers continue investing in digital pharmacy infrastructure and smart hospital initiatives, the deployment of dispensing robots is expected to increase significantly, supporting the sustained growth of the medical service robots market.
The high cost of medical service robots remains a significant restraint to market growth, particularly for small and medium-sized healthcare facilities. Acquiring disinfection robots, robotic nurse assistants, medical telepresence robots, delivery robots, and dispensing robots requires substantial capital investment. Beyond the initial purchase, healthcare providers incur expenses for installation, software integration, infrastructure modifications, staff training, maintenance, and periodic system upgrades. These costs increase the total cost of ownership and often delay procurement decisions, especially in budget-constrained hospitals and healthcare institutions in developing economies.
Company
Product/Model
Price
Disinfection Robots
Blue Ocean Robotics
UVD Robot
USD 80,000–90,000
TMiRob
TMiRob UVD Robot
USD 30,000–50,000
Keenon Robotics
Keenon M2
USD 15,000–25,000
Youibot
Youibot ARIS K2
USD 20,000–35,000
OrionStar
OrionStar UV-C Sterilizer
USD 18,000–28,000
LionsBot (distributed in China)
LionsBot UV CleanBot
USD 22,000–35,000
Dispensing Robots
Galbot
Galbot G1
USD 93,000–103,000
Source: Secondary Research, Grand View Research Analysis
Moreover, ongoing operational expenses further limit the widespread adoption of medical service robots. Healthcare organizations must invest in preventive maintenance, cybersecurity, software licensing, battery replacement, and technical support to ensure uninterrupted performance and regulatory compliance. Integration with hospital information systems, pharmacy management platforms, and electronic health records also requires specialized implementation services, increasing deployment complexity and costs. Although declining hardware prices, advances in robotics manufacturing, and Robotics-as-a-Service (RaaS) business models are expected to improve affordability over time, high capital and lifecycle costs continue to restrain broader market penetration across global healthcare facilities.
Market Concentration & Characteristics
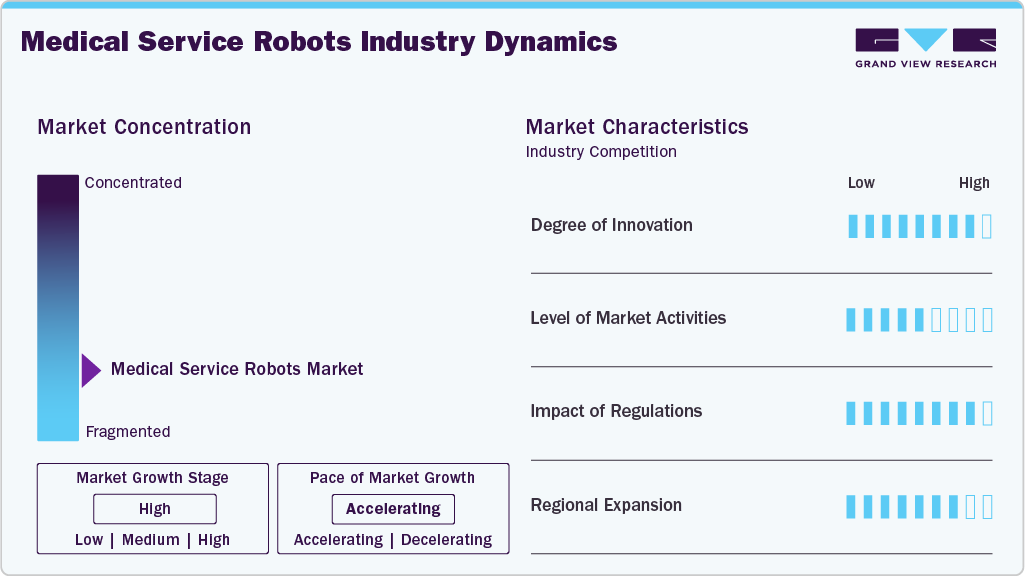
The medical service robots market experiences a high degree of innovation driven by advancements in artificial intelligence, autonomous navigation, computer vision, and sensor technologies. Manufacturers are continually enhancing disinfection robots, robotic nurse assistants, medical telepresence robots, delivery robots, and dispensing robots with AI-enabled decision support, remote monitoring, and workflow automation. For instance, in October 2025, Diligent Robotics unveiled Moxi 2.0, a next‑generation AI‑powered mobile manipulator for hospitals and senior living, built on NVIDIA’s IGX Thor (Blackwell‑class) edge AI platform.
The industry is experiencing a moderate-to-high level of merger and acquisition activities undertaken by several key players. This is driven by the need to strengthen robotics capabilities, expand healthcare automation portfolios, and accelerate commercialization across hospitals and healthcare facilities. Companies are also entering strategic partnerships to integrate artificial intelligence, cloud connectivity, and hospital information systems into medical service robots, thereby expanding product capabilities and geographic reach.
 To learn more about this report, Download Free Sample Report
The impact of regulations is high, with various regional regulatory authorities governing the development and commercialization of medical service robots. Regulatory agencies such as the U.S. FDA, the European Commission (EU MDR), MHRA, and PMDA establish requirements for device safety, software validation, cybersecurity, quality management, and post-market surveillance. Compliance with these regulatory frameworks is essential to ensure product safety, clinical performance, and reliable deployment across healthcare environments while increasing development timelines and certification requirements.
The industry is witnessing strong regional expansion driven by rising demand for healthcare automation and smart hospital initiatives across both developed and emerging markets. Companies are strengthening their global presence by expanding distribution networks, establishing regional partnerships, and increasing commercial operations. Expansion into Asia Pacific, Latin America, and the Middle East is supported by rising healthcare infrastructure investments, government digital health initiatives, and growing adoption of AI-enabled robotic technologies across hospitals and healthcare facilities.
Analyst Perspective
The medical service robots market is witnessing strong growth as healthcare providers increasingly adopt intelligent robotic platforms to improve hospital operations and patient care. Rising healthcare workforce shortages, growing patient volumes, and increasing emphasis on infection prevention are key factors driving demand. Service robots are being widely deployed for hospital logistics, pharmacy automation, telepresence, disinfection, and caregiver support. These solutions help reduce manual workloads, improve operational efficiency, enhance patient safety, and optimize resource utilization. The market is also benefiting from expanding investments in smart hospitals and digital healthcare infrastructure. Advances in artificial intelligence, autonomous navigation, cloud connectivity, and fleet management are improving robot performance and functionality. Integration with hospital information systems is enabling seamless workflow automation and data exchange. Established automation companies and specialized robotics firms are continuously introducing innovative application-specific solutions. As healthcare facilities move toward connected and automated environments, demand for scalable and interoperable robotic platforms is expected to increase. Vendors offering AI-enabled solutions with proven operational and clinical benefits are likely to strengthen their market position.
Product Insights
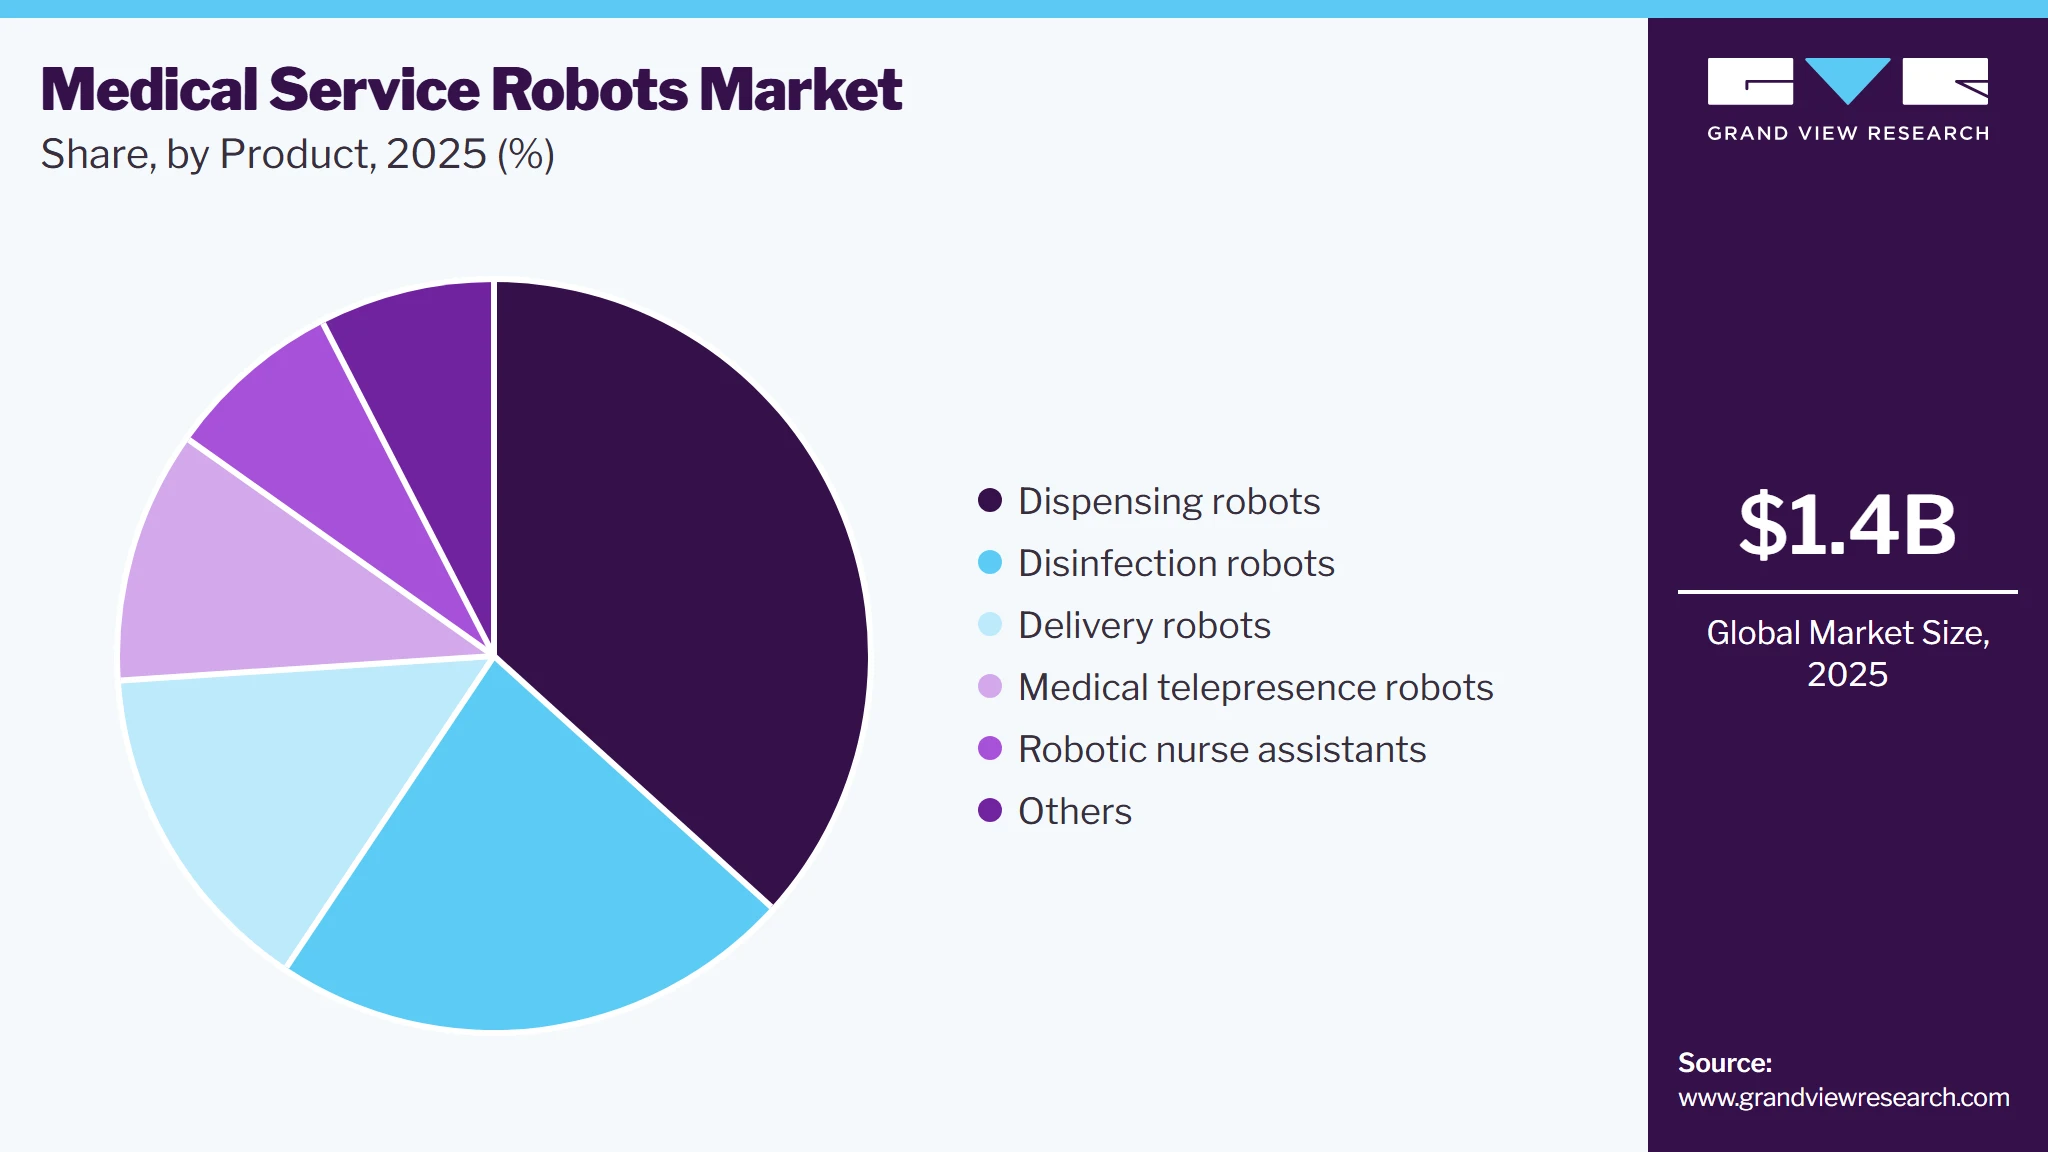
The dispensing robots segment led the market with the largest revenue share of 36.9% in 2025. Dispensing robots plays a critical role in improving medication management by automating the storage, dispensing, packaging, and verification of pharmaceuticals across hospitals, retail pharmacies, and long-term care facilities. These systems reduce medication errors, improve inventory accuracy, enhance prescription turnaround time, and support regulatory compliance through automated documentation and traceability. For instance, in June 2026, Queue launched fully autonomous robotic pharmacy prescription kiosks utilizing computer vision to fulfill, verify, and deliver medications at a 96% lower operational cost.
Moreover, integration with hospital information systems, electronic health records, and barcode verification technologies further strengthens workflow efficiency, medication safety, and operational productivity, supporting continued growth of the dispensing robots segment.
 To learn more about this report, Download Free Sample Report
Delivery robots segment is expected to grow at the fastest CAGR over the forecast period. Delivery robots transport medications, laboratory specimens, medical supplies, linens, and sterile equipment across hospitals using autonomous navigation technologies. By minimizing staff involvement in routine transportation tasks, delivery robots enable healthcare professionals to focus on direct patient care while improving workflow efficiency and reducing operational costs. Integration with hospital infrastructure, elevators, and access control systems enhances reliability and continuous operation. Rising investments in smart hospitals and healthcare automation are expected to further drive segment growth globally.
Regional Insights
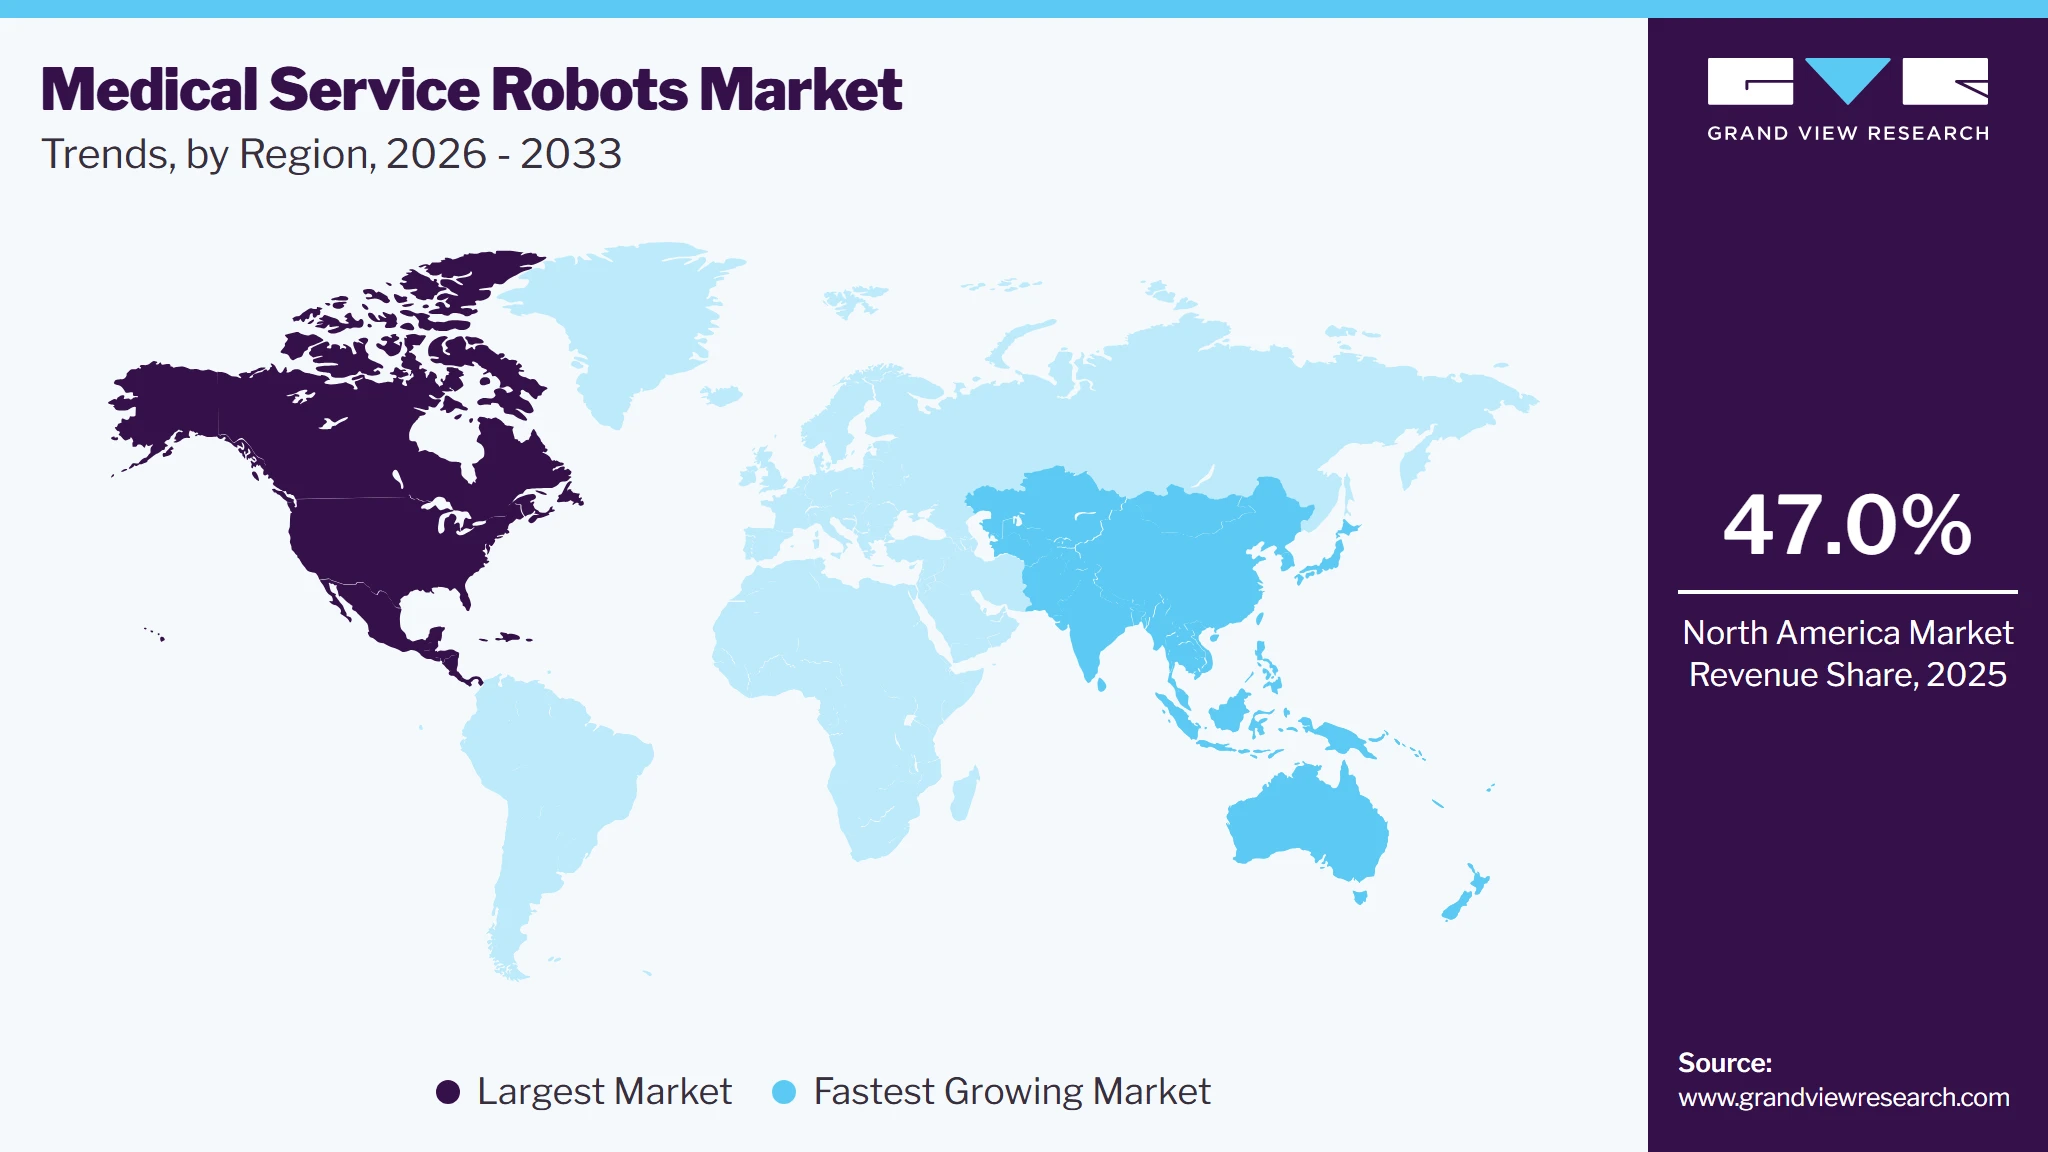
North America dominated the medical service robots market with the largest revenue share of 47.0% in 2025 driven by increasing healthcare automation, rising labor shortages, and strong investments in hospital digitalization. Healthcare providers are adopting medical service to improve operational efficiency, infection prevention, and patient care. The presence of established robotics manufacturers, favorable reimbursement environments for healthcare technologies, and continuous investments in artificial intelligence and autonomous robotics further support regional market growth. For instance, in January 2026, Xenex Disinfection Services' LightStrike6 UV-C whole-room sanitizing robot received Health Canada registration, making Xenex the first and only company with UV-C room disinfection technology authorized for healthcare use in North America.
 To learn more about this report, Download Free Sample Report
U.S. Medical Service Robots Market Trends
Medical service robots market in the U.S. is experiencing significant growth, driven by increasing adoption of hospital automation technologies and the need to address shortages of healthcare professionals. stringent infection prevention protocols continue to accelerate adoption of disinfection robots across healthcare facilities. For instance, Diligent Robotics Inc. has currently deployed its Moxi robot across more than 25 hospitals across the U.S. to help nurses and pharmacy staff with routine tasks, such as delivering medications and lab samples. Moreover, the company is planning its expansion into the senior living sector with its participation in the AgeTech Collaborative from AARP accelerator program.
Europe Medical Service Robots Market Trends
The medical service robots market in Europe is expected to grow rapidly, driven by increasing healthcare digitalization, rising demand for operational efficiency, and growing emphasis on patient safety. Healthcare providers across the region are investing in robotic solutions to automate pharmacy operations, material transport, environmental disinfection, and remote patient communication. Supportive regulatory frameworks, expanding smart hospital initiatives, and increasing investments in healthcare automation continue to strengthen the adoption of medical service robots across European healthcare systems.
The medical service robots market in the UK is expected to grow over the forecast period, driven by increasing investments in National Health Service (NHS) digital transformation programs and rising demand for healthcare automation. Rising workforce shortages and increasing pressure on hospital resources are encouraging the deployment of robotic nurse assistants, telepresence robots, delivery robots, and dispensing robots. Continuous investments in artificial intelligence and connected healthcare technologies are further supporting market expansion.
Medical service robots market in Germany held the largest market share in 2025 in the European market. Growth is supported by advanced healthcare infrastructure, strong medical technology manufacturing capabilities, and increasing adoption of automated hospital workflows. Healthcare providers are implementing disinfection robots, pharmacy automation systems, and autonomous delivery robots to improve efficiency and maintain high standards of patient safety. Government support for healthcare innovation and Industry 4.0 initiatives further supports market growth.
Asia Pacific Medical Service Robots Market Trends
The medical service robots market in the Asia Pacific is projected to grow at the fastest CAGR from 2026 to 2033, driven by expanding healthcare infrastructure, rising healthcare expenditure, and the rapid adoption of robotics across hospitals. Governments across the region are promoting digitalization and artificial intelligence in healthcare to address workforce shortages and improve access to healthcare. Rising investments in hospital automation and the growing deployment of dispensing, delivery, telepresence, and disinfection robots are expected to accelerate regional market growth.
Medical service robots market in Japan is expected to grow significantly over the forecast period. The country's rapidly aging population, persistent shortage of healthcare workers, and well-established robotics industry are driving the adoption of medical service robots. Hospitals and elderly care facilities are increasingly implementing medical service robots to improve care delivery and operational efficiency. Government initiatives promoting robotics adoption continue to support market expansion.
Medical service robots market in China held the largest revenue share in 2025 in the Asia Pacific market. Growth is supported by expanding healthcare infrastructure, government initiatives promoting artificial intelligence and robotics, and increasing domestic manufacturing capabilities. Healthcare institutions are adopting disinfection robots, dispensing robots, and autonomous delivery systems to improve hospital efficiency and strengthen infection control. For instance, in March 2026, China’s first pharmacy robot, Galbot G1, began 24/7 service in a Beijing Haidian District retail pharmacy, autonomously locating, picking, packaging, and dispensing non‑prescription medicines into a smart pickup cabinet.
Latin America Medical Service Robots Market Trends
Latin America medical service robots market is anticipated to grow at a significant CAGR over the forecast period, driven by increasing investments in healthcare infrastructure and growing awareness regarding hospital automation. Healthcare providers are gradually adopting medical service robots to improve operational efficiency, reduce manual workloads, and strengthen infection prevention measures. Expansion of private healthcare facilities and modernization initiatives are expected to support market growth throughout the forecast period.
Middle East and Africa Medical Service Robots Market Trends
Middle East and Africa medical service robots market is expected to grow at a significant CAGR over the forecast period. The market is characterized by increasing investments in healthcare modernization, smart hospital development, and digital healthcare infrastructure. The growing demand for automated disinfection, pharmacy automation, hospital logistics, and remote patient communication solutions is driving adoption across healthcare facilities. Government initiatives to strengthen healthcare capacity and improve operational efficiency are expected to create favorable opportunities for the deployment of medical service robots.
Key Medical Service Robots Company Insights
Key players operating in the medical service robots market are undertaking various initiatives to strengthen their market presence and increase the reach of their products and services. Strategies such as new product launches and partnerships are playing a key role in propelling the market growth.
Key Medical Service Robots Companies
The following key companies have been profiled for this study on the medical service robots market:
-
UVD Robots
-
Hstar Technologies
-
Diligent Robotics
-
Ava Robotics
-
TelepresenceRobots.com
-
Aethon, Inc.
-
Relay Robotics
-
Swisslog Healthcare
-
BD (Becton Dickinson, BD Rowa)
-
Omnicell, Inc.
-
Dassault Systèmes
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Swisslog Healthcare, BD (Becton Dickinson, BD Rowa), Omnicell, Inc., Dassault Systèmes)
Expand medical service robotics portfolios through strategic acquisitions, partnerships with hospitals, pharmacies, and healthcare systems, and integration with hospital automation platforms. Invest in autonomous mobile robots (AMRs), pharmacy automation, medication dispensing systems, logistics robots, AI-driven fleet management, digital twins, and smart hospital technologies to optimize healthcare operations and improve workflow efficiency.
Strong global market presence, extensive healthcare customer base, and comprehensive portfolios spanning pharmacy automation, hospital logistics, and digital healthcare infrastructure. Robust R&D capabilities, established regulatory expertise, large-scale deployment experience, and seamless integration with hospital information systems (HIS), electronic health records (EHR), and warehouse management systems support enterprise-wide automation initiatives.
High capital investment requirements, complex implementation processes, and integration with legacy hospital infrastructure may limit adoption among smaller healthcare facilities. Long procurement cycles, significant maintenance costs, and dependence on large institutional contracts may affect deployment speed and pricing flexibility.
Emerging & Specialized Players (UVD Robots, Hstar Technologies, Diligent Robotics, Ava Robotics, TelepresenceRobots.com, Aethon, Inc., Relay Robotics)
Focus on specialized medical service robots for disinfection, autonomous delivery, telepresence, robotic nurse assistance, and patient engagement. Leverage AI-powered navigation, autonomous mobility, cloud-based fleet management, computer vision, and strategic collaborations with hospitals and long-term care facilities to expand adoption across targeted healthcare applications.
Greater agility in product innovation and the ability to develop application-specific robotic solutions for infection control, material transport, telemedicine, and caregiver support. Faster product development cycles, flexible deployment models, and customer-centric innovation enable rapid adoption across hospitals, outpatient facilities, and senior care environments.
Limited financial resources, smaller installed base, and narrower global distribution networks compared with established healthcare automation companies. Limited product portfolios, fewer enterprise integration capabilities, and dependence on strategic partnerships for scaling commercial operations may restrict penetration into large healthcare systems.
Recent Developments:
-
In June 2026, BayCare Health System expanded its autonomous delivery fleet with two new Relay Robots, “Stork” and “Miles,” at Winter Haven Hospital and Winter Haven Women’s Hospital in Florida. The robots automate 24/7 transport of lab specimens, medications, and supplies, handling 500+ deliveries per month and saving an estimated 150+ clinical hours monthly, enabling nurses to focus more on bedside patient care.
-
In March 2026, VSee unveiled the VSee AI Robot at HIMSS 2026, describing it as the world’s first fully autonomous telehealth AI robot for hospitals. It uses LiDAR navigation and 30× optical/infrared vision to reach patient bedsides without onsite staff, enabling remote rounding, telestroke response, and multisite specialist coverage.
-
In September 2025, Swisslog Healthcare, a leading provider of hospital transport and pharmacy automation, announced a strategic alliance with Diligent Robotics to bring autonomous last‑mile delivery robots to U.S. hospitals. The partnership integrated Diligent’s Moxi autonomous mobile manipulation robots with Swisslog’s existing automation, including TransLogic pneumatic tube systems, to create end‑to‑end logistics for medications, supplies, and specimens.
"For our customers who have been asking for reliable, efficient last-mile delivery robots that integrate seamlessly with existing workflows, this cooperative effort with Diligent Robotics allows us to connect them with a proven solution for smarter and safer deliveries that staff and patients trust,"
-Ray Castro, Director of Strategic Programs for Transport Automation at Swisslog Healthcare
-
In September 2024, Hitachi Ltd. successfully finalized the purchase of MA micro automation GmbH, a prominent company specializing in robotic and automation solutions.
Medical Service Robots Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 1.4 billion
Estimated market size in 2026
USD 1.6 billion
Projected market size in 2033
USD 3.9 billion
Growth rate
CAGR of 13.9% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
UVD Robots; Hstar Technologies; Diligent Robotics; Ava Robotics; TelepresenceRobots.com; Aethon, Inc.; Relay Robotics; Swisslog Healthcare; BD (Becton Dickinson, BD Rowa); Omnicell, Inc.; Dassault Systèmes
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Medical Service Robots Market Segmentation
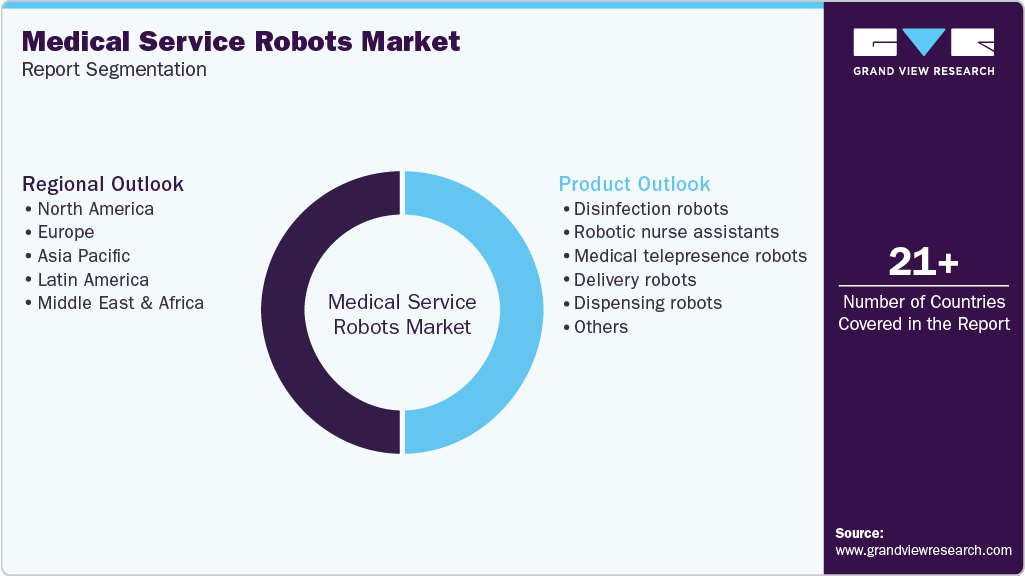
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global medical service robots market report based on product and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Disinfection robots
-
Robotic nurse assistants
-
Medical telepresence robots
-
Delivery robots
-
Dispensing robots
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
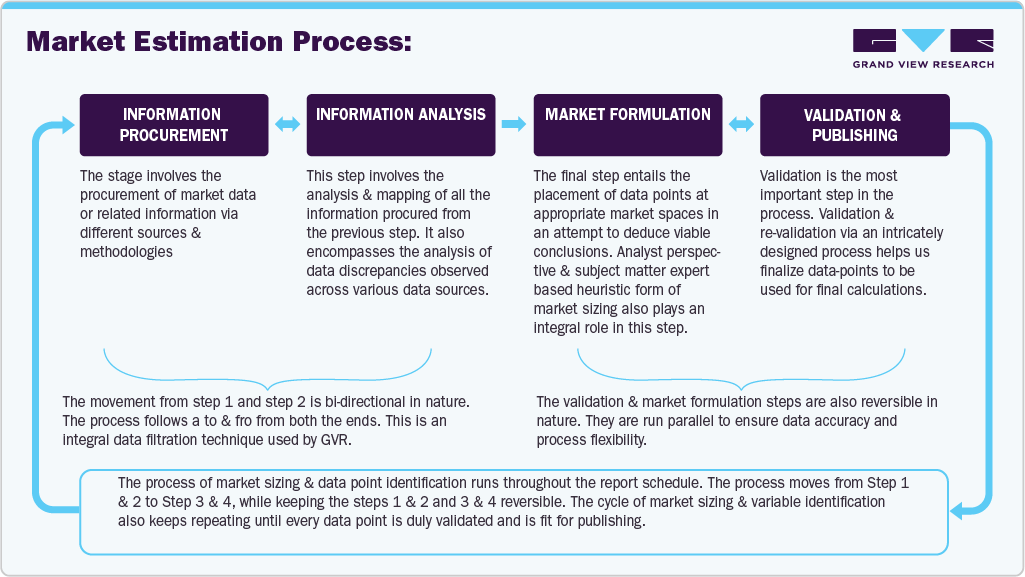
The medical service robots market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical service robots segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Disinfection Robots
Autonomous or semi-autonomous robots that utilize ultraviolet-C (UV-C) light, hydrogen peroxide vapor, or other automated disinfection technologies to sanitize patient rooms, operating theaters, intensive care units, laboratories, and other healthcare environments. These robots help reduce healthcare-associated infections (HAIs), improve environmental hygiene, and minimize manual cleaning efforts.
Robotic Nurse Assistants
Service robots designed to assist nursing staff with routine patient care and non-clinical tasks, including patient monitoring, mobility assistance, medication reminders, transporting supplies, and patient interaction. These robots improve workflow efficiency, reduce caregiver workload, and support healthcare facilities facing nursing staff shortages.
Medical Telepresence Robots
Mobile robotic platforms equipped with cameras, microphones, displays, sensors, and wireless communication technologies that enable remote interaction between healthcare professionals and patients. They facilitate virtual consultations, specialist collaboration, ward rounds, patient monitoring, and telemedicine services while reducing the need for physical presence.
Delivery Robots
Autonomous mobile robots used to transport medications, laboratory specimens, blood products, medical supplies, meals, linens, and other materials within healthcare facilities. These robots streamline hospital logistics, reduce manual transportation tasks, improve operational efficiency, and enable healthcare staff to focus on patient care.
Dispensing Robots
Automated robotic systems that accurately store, prepare, package, and dispense medications in hospital pharmacies, retail pharmacies, and healthcare facilities. These systems improve dispensing accuracy, reduce medication errors, enhance inventory management, and increase pharmacy workflow efficiency.
Others
Includes other healthcare service robots such as rehabilitation support robots, patient lifting and transfer robots, concierge and reception robots, laboratory automation robots, waste management robots, inventory management robots, and multipurpose service robots that enhance healthcare operations, patient safety, and facility management.
Estimation Model
 To learn more about this report, Download Free Sample Report
Market-specific Research Models:
Consensus-Based Estimates & Forecasting
The medical service robots market presents emerging to dominant opportunities, featuring global key players such as UVD Robots; Hstar Technologies; Diligent Robotics; Ava Robotics; TelepresenceRobots.com; Aethon, Inc.; Relay Robotics; Swisslog Healthcare; BD (Becton Dickinson, BD Rowa); Omnicell, Inc.; Dassault Systèmes. To ensure a holistic approach, the GVR research team adopted a comprehensive methodology, considering multiple companies worldwide and utilizing various variables for data accuracy.
Our methodology included:
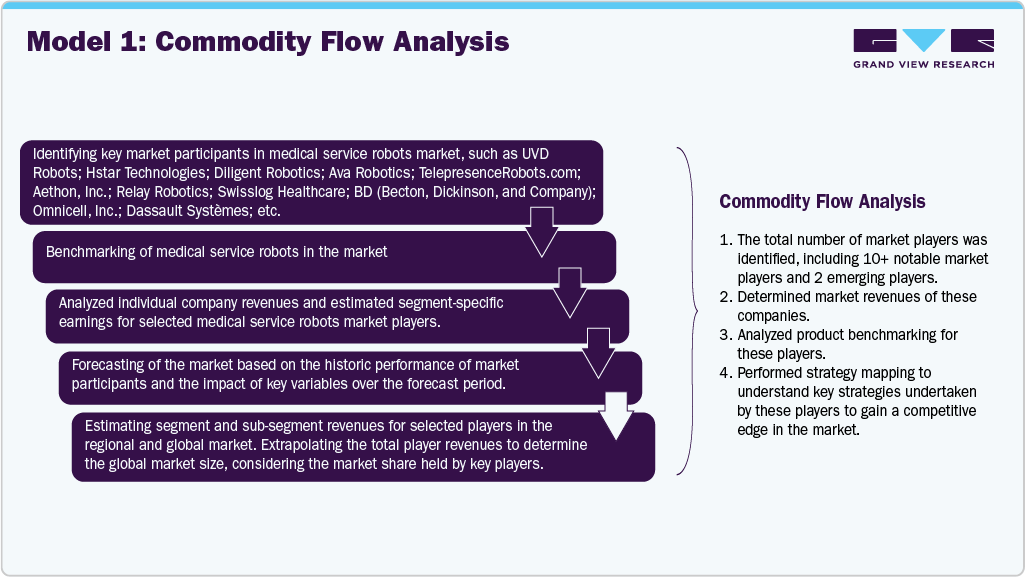
Model 1: Commodity Flow Analysis - For public players, annual reports were referenced. For private players, premium paid data sources such as S&P Global, Crunchbase, ZoomInfo, RocketReach, etc., were used for the latest revenue insights.
Model 2: Parent Market Analysis
Model 3: Country-level Multivariate Analysis Assumptions
Model 4: Segment-level Multivariate Analysis Assumptions
Model 5: Medical Service Robots Market CAGR Calculations
 To learn more about this report, Download Free Sample Report
Commodity flow analysis was employed to track the movement of medical service robots through the value chain, from technology providers to end users. This analysis provided insights into demand generation points, intermediary roles, and ultimate consumption patterns.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Medical Service Robots Adoption & Healthcare Automation Analysis
Developed a tailored analysis of the global medical service robots market focused on disinfection robots, robotic nurse assistants, medical telepresence robots, autonomous delivery robots, medication dispensing robots, and other healthcare service robots. The study assessed adoption trends across hospitals, ambulatory surgical centers (ASCs), rehabilitation centers, long-term care facilities, pharmacies, and healthcare networks while evaluating workforce shortages, increasing hospital automation, infection prevention initiatives, and the growing demand for contactless healthcare services driving market growth.
Enables stakeholders to understand evolving healthcare automation trends, identify high-growth service robot categories, assess adoption opportunities across clinical and non-clinical workflows, and evaluate the impact of robotics on operational efficiency, patient safety, staff productivity, and long-term market expansion.
Healthcare Robotics, AI-Enabled Workflow Automation & Smart Hospital Assessment
Delivered a customized evaluation of medical service robot utilization across hospital disinfection, medication dispensing, pharmacy automation, logistics and material transport, telepresence consultations, patient monitoring, and nursing assistance. The analysis assessed advancements in artificial intelligence (AI), autonomous navigation, computer vision, machine learning, IoT connectivity, cloud-based fleet management, and human-robot collaboration. Additionally, it evaluated technology innovations, workflow optimization, and deployment strategies from leading companies including UVD Robots, Hstar Technologies, Diligent Robotics, Ava Robotics, TelepresenceRobots.com, Aethon, Inc., Relay Robotics, Swisslog Healthcare, BD (BD Rowa), Omnicell, Inc., and Dassault Systèmes.
Provides actionable insights into commercially attractive healthcare robotics segments, emerging automation technologies, evolving hospital operational requirements, and growth opportunities associated with intelligent logistics, infection control, medication safety, remote patient interaction, optimized workforce utilization, and smart hospital transformation.
Healthcare Robotics Ecosystem, Regulatory Environment & Competitive Landscape Assessment
Conducted a focused assessment of the medical service robots ecosystem, including robotic hardware manufacturing, AI software platforms, hospital information system integration, pharmacy automation infrastructure, cloud connectivity, cybersecurity, regulatory compliance requirements, and competitive positioning. The analysis evaluated implementation challenges, capital investment requirements, interoperability standards, technology adoption barriers, service and maintenance models, strategic partnerships, and competitive differentiation initiatives among leading market participants such as UVD Robots, Hstar Technologies, Diligent Robotics, Ava Robotics, TelepresenceRobots.com, Aethon, Relay Robotics, Swisslog Healthcare, BD (BD Rowa), Omnicell, and Dassault Systèmes.
Supports strategic planning for robotic platform commercialization, healthcare digital transformation, hospital automation initiatives, technology investments, regulatory compliance, geographic expansion, and market entry strategies by identifying adoption drivers, operational challenges, infrastructure requirements, revenue opportunities, innovation priorities, and competitive advantages across the global medical service robots value chain.
Frequently Asked Questions About This Report
The global medical service robots market size was valued at USD 1.4 billion in 2025 and is estimated at USD 1.6 billion for 2026.
Some of the major market players are UVD Robots, Hstar Technologies, Diligent Robotics, Ava Robotics, TelepresenceRobots.com, Aethon, Inc., Relay Robotics, Swisslog Healthcare, BD (Becton Dickinson, BD Rowa), Omnicell, Inc., and Dassault Systèmes.
Continuous advancements in technology such as robotic catheter control systems (CCS), data recorders, data analytics, remote navigation, motion sensors, 3D-Imaging, and HD surgical microscopic cameras are projected to drive the market growth.
Asia Pacific is the fastest-growing region over the forecast period.
The dispensing robots segment led with a 36.9% revenue share in 2025.
The global medical service robots market is expected to grow at a CAGR of 13.9% from 2026 to 2033, reaching USD 3.9 billion by 2033.
North America dominated with a revenue share of 47.0% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


