
- Home
- »
- Automotive & Transportation
- »
-
Micro Fulfillment Market Size, Share & Growth Report, 2033GVR Report cover

Micro Fulfillment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Hardware, Services), By End Use (E-commerce, Manufacturers), By Type (Store-integrated/In-store, Standalone), By Region, And Segment Forecasts
Market Size, 2025
$8.8BMarket Estimate, 2026
$11.8BMarket Forecast, 2033
$84.5BCAGR, 2026–2033
32.4%Micro Fulfillment MarketSummary
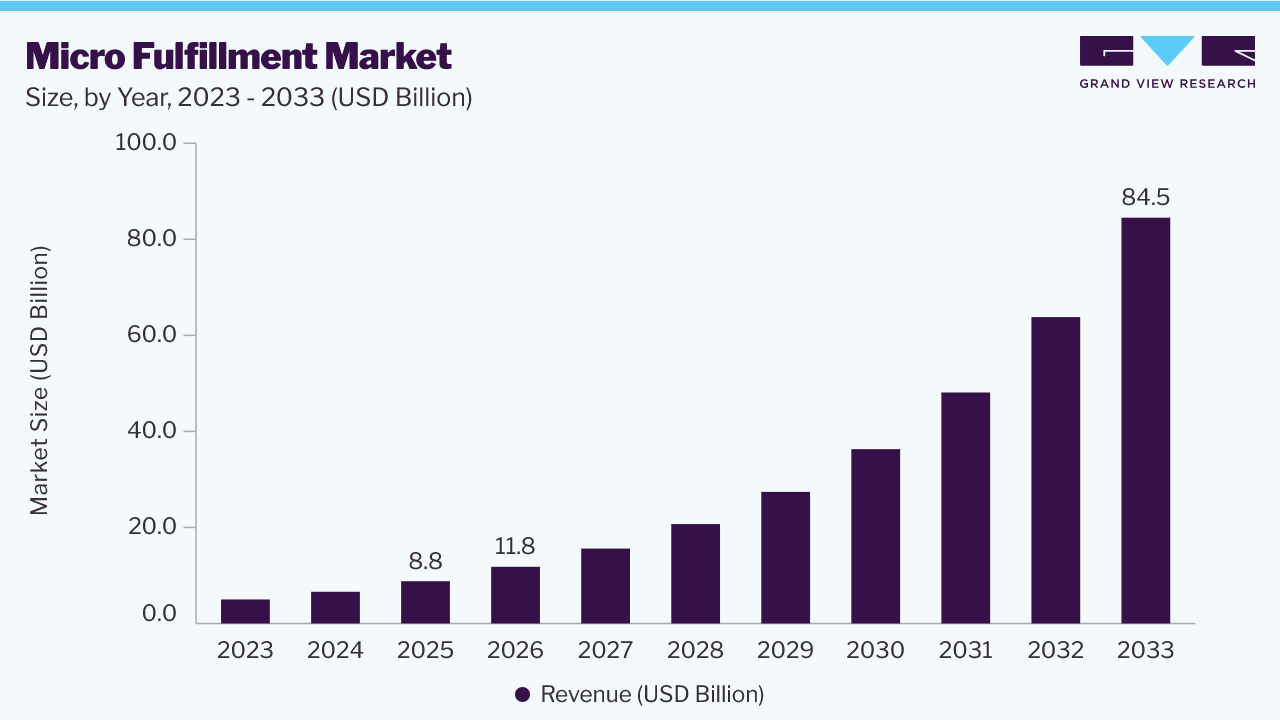
The global micro fulfillment market size was valued at USD 8.8 billion in 2025 and is projected to grow from USD 11.8 billion in 2026 to USD 84.5 billion by 2033, at a CAGR of 32.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 35.0% in 2025. The rising adoption of micro fulfillment centers (MFCs) by the e-grocery industry has bolstered market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By components: The service segment held the largest market share in 2025.
- By type: The store-integrated/in-store segment held the largest market share of 45.0% in 2025.
- By end use: The traditional retailers & distributors segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (35.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 8.8 Billion
- Estimated market size in 2026: USD 11.8 Billion
- Projected market size by 2033: USD 84.5 Billion
- CAGR (2026-2033): 32.4%
Prism AI by Grand View Research Free to tryAsk a question about the micro fulfillment marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →In addition, factors such as customization and personalization offered by service providers for MFC layouts are fueling market growth. The e-grocery industry embraces micro-fulfillment as a strategic response to rapidly growing demand for online grocery shopping. Consumers are increasingly seeking the convenience and time-saving benefits of ordering groceries online, and businesses in this sector are recognizing the need to optimize their operations to meet these evolving customer preferences.
Micro fulfillment solutions present a compelling opportunity for e-grocery businesses by enabling efficient and rapid order processing and delivery. Micro Fulfillment Centers (MFCs) are specifically designed to optimize the order fulfillment process. They utilize automation technologies, robotics, and advanced software systems to accelerate picking, packing, and shipping operations. As a result, order processing becomes faster and more accurate, reducing turnaround times and enhancing customer satisfaction.
In addition, micro fulfillment solutions integrate seamlessly with omnichannel strategies, allowing businesses to fulfill online orders, offer click-and-collect services, and support various other fulfillment options. This integration creates a consistent and unified shopping experience across different sales channels, including e-commerce, traditional retail, and distribution networks, thereby strengthening customer engagement and loyalty.
Furthermore, the growth of e-commerce has significantly impacted the target market. More consumers are turning to online platforms to purchase everyday items, groceries, and other products, increasing the demand for efficient and speedy order fulfillment — a demand that MFCs are well-equipped to meet.
Traditional large-scale warehouses can be expensive to operate, as they require substantial space, labor, and infrastructure investments. In contrast, MFCs are smaller and can be more cost-effective to establish and run. However, high implementation costs remain a challenge in the market. The initial investment required to set up an MFC is considerable and may deter some companies from adopting this solution. Factors such as acquiring or leasing a suitable facility and purchasing necessary equipment, such as racking systems, conveyor belts, sorting systems, robots, and automated picking technologies, can incur high costs.
The size and complexity of MFCs will affect overall expenses, as they rely heavily on advanced technology systems for inventory management, order processing, and warehouse automation. Investing in software solutions, hardware infrastructure, and system integration represents a significant initial expenditure.
Market Dynamics
The market for micro-fulfillment centers (MFCs) is growing rapidly due to the widespread adoption of e-commerce and consumer demand for faster, more convenient delivery. Retailers are building highly automated fulfillment centers closer to the end consumer to increase order accuracy and improve delivery speed. Warehouse automation and robotics, coupled with the widespread adoption of omnichannel retail, further fuel market growth.
E-commerce growth and increasing consumer delivery expectations are significantly driving the market growth. The demand for same-day, faster delivery is pressuring retailers to locate inventory closer to customers and to streamline their supply chains. Micro fulfillment centers enable retailers to fulfill online orders in urban areas more effectively, thereby minimizing transit time and transportation costs. Furthermore, the spread of buy-online-pick-up-in-store (BOPIS), curbside pickup, and omnichannel models requires faster fulfillment capabilities to handle high order volumes accurately. Labor shortages and rising warehouse operating costs are encouraging retailers to adopt automation technologies such as robotics and artificial intelligence. Demand is also expected to increase significantly as online sales of groceries, consumer electronics, apparel, and other consumer goods continue to grow rapidly.
A significant barrier to the growth of the micro-fulfillment market is the substantial capital required to implement and operate them in the initial phase. The implementation of automated fulfillment solutions requires investment in robotic technologies, automated storage and retrieval systems, warehouse management systems(WMS), and AI systems. The capital expenditure required to implement these system changes may act as a barrier for small and medium retailers. Complexities associated with integrating micro-fulfillment technologies with existing legacy systems, inventory management systems, and omnichannel presence create another blockage. Businesses may face disruptions to operations and employee training, and difficulty understanding technical aspects, all affecting efficiency. Moreover, there is no standardized implementation methodology and a lack of certainty about Return on Investment (ROI). This may discourage many potential adopters.
The increasing adoption of automated fulfillment solutions within urban retail and grocery sectors presents a significant opportunity for the micro fulfillment industry. Rising population in metropolitan areas and growing consumer preference for on-demand delivery are encouraging retailers to establish compact fulfillment centers closer to customers. Grocery retailers, in particular, are investing in micro fulfillment technologies to efficiently manage high volumes of online orders while maintaining product freshness and reducing picking errors. The integration of advanced technologies such as artificial intelligence, robotics, machine learning, and real-time inventory tracking is enabling retailers to scale their fulfillment capabilities. Furthermore, the continued expansion of omnichannel retail models, including click-and-collect and same-day delivery services, is creating new deployment opportunities.
Analyst Perspective
The micro fulfillment industry is evolving as retailers and e-commerce companies increasingly focus on faster delivery, inventory efficiency, and localized order processing. Instead of relying solely on large, centralized warehouses, businesses are investing in smaller, automated fulfillment centers closer to end consumers to reduce delivery times and improve operational flexibility. This shift is becoming particularly important in grocery, quick commerce, and urban retail environments where speed and order accuracy directly influence customer satisfaction. Companies with strong automation capabilities, warehouse software expertise, and scalable fulfillment solutions are likely to strengthen their market position. In the coming years, competitive advantage will depend on the ability to optimize last-mile logistics, manage inventory efficiently, and support high-volume order fulfillment while maintaining cost efficiency and delivery reliability.
Component Insights
The hardware segment accounted for the largest market revenue share in 2025. MFCs require specialized hardware components to facilitate efficient order picking, packing, and sorting processes. This includes automated storage and retrieval systems (AS/RS), conveyor belts, sortation systems, robotic arms, shelving units, and other equipment. These sophisticated technologies involve complex engineering, precision manufacturing, and software integration, which contribute to higher costs.
The service segment is anticipated to grow at the fastest CAGR over the forecast period. This can be attributed to the increasing demand for expertise & consultation, technology integration & software solutions, maintenance & support, and scalability & flexibility. For instance, in June 2025, Dematic implemented a new advanced automation solution that will support Scentsy's fulfillment operations. The new system integrates AutoStore with Dematic WES, with Dematic providing the software integration and continued operational support beyond the hardware. Implementing a micro fulfillment system requires specialized knowledge and expertise in areas such as automation, robotics, software integration, and operational efficiency. Service providers offer consulting services to help businesses assess their requirements, design customized solutions, and optimize operational workflows.
Type Insights
The store-integrated/in-store segment led the market with the largest revenue share of 45.0% in 2025. Retailers with physical stores can leverage their existing brick-and-mortar locations to fulfill online orders. For instance, in November 2025, Amazon introduced a new "store-within-a-store" concept at its Whole Foods Market location in Plymouth Meeting, Pennsylvania. Created by Amazon's automated 10,000 sq. ft. micro-fulfillment center. Rhis facility will allow the brick-and-mortar store to efficiently process and fulfill online delivery and pickup orders while simultaneously accommodating brick-and-mortar customers. This approach allows them to utilize their store space and inventory, potentially reducing the need for separate dedicated fulfillment centers.
Retailers can efficiently serve in-store shoppers and online customers by integrating micro fulfillment capabilities into their stores. The store-integrated micro fulfillment model can also create synergies between online and in-store shopping experiences. Retailers can offer options such as buy-online-pick-up-in-store (BOPIS), allowing customers to conveniently collect their online orders and make additional purchases in-store. This can drive increased foot traffic and boost overall sales.
The dark stores segment is anticipated to grow at a significant CAGR over the forecast period. The rapid growth of e-commerce has increased demand for efficient, fast order fulfillment. Dark stores are specifically designed for online order processing and do not serve in-store customers. With the continuous rise in online shopping, the demand for dark stores is expected to grow significantly. Attabotics is a warehouse automation solution provider that offers a vertical storage and retrieval system for MFCs and dark stores to optimize space utilization and streamline the fulfillment process.
End Use Insights
The e-commerce segment accounted for the largest market revenue share in 2025. The exponential growth of e-commerce has transformed the retail landscape. Consumers are adopting online shopping due to convenience, wider product selection, and competitive pricing. This surge in online orders necessitates efficient fulfillment processes, thereby driving demand for micro-fulfillment solutions.
The traditional retailers & distributors segment is anticipated to grow at the fastest CAGR over the forecast period. Traditional retailers and distributors often have an established network of physical stores, warehouses, and distribution centers. This existing infrastructure can be leveraged for micro fulfillment operations. For instance, in February 2025, Dematic collaborated with Transcend Retail Solutions, part of Tesco Group, to develop its proven micro-fulfillment center (MFC) for grocers.
Tenure of this partnership is 5 years, with plans to deploy MFC within Tesco's existing retail network, allowing conventional grocers to fulfill online orders closer to the customer by using available space within or near their existing store base. Traditional retail spaces often have unused or underutilized areas that can be repurposed for MFCs. By converting a portion of the store or using backroom space, offline traders can optimize their space utilization and create a dedicated area for efficient order fulfillment. This approach maximizes the use of existing assets and minimizes the need for additional warehousing space.
Regional Insights
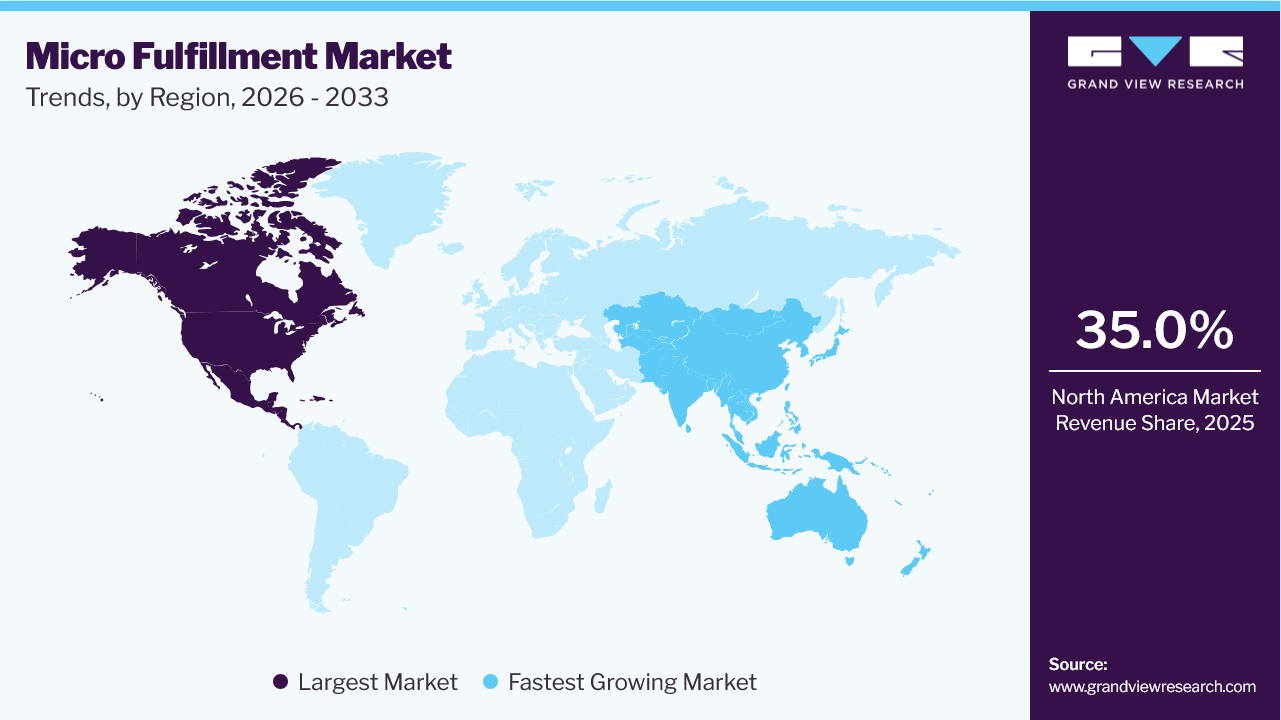
North America dominated the global micro fulfillment market with the largest revenue share of around 35.0% in 2025. The region is known for its technological advancements and innovation. North American companies have been at the forefront of developing and implementing cutting-edge technologies in the micro fulfillment space. This includes automation, robotics, artificial intelligence, and data analytics, which have significantly improved the efficiency and scalability of micro fulfillment operations. In addition, North America has witnessed significant growth in e-commerce adoption, with many consumers embracing online shopping.
 To learn more about this report, Download Free Sample Report
Asia Pacific Micro Fulfillment Market Trends
The micro fulfillment market in the Asia Pacific is expected to grow at the fastest CAGR over the forecast period. Asia Pacific is home to a large and rapidly growing population, particularly in countries such as China and India. This dense population and rapid urbanization create a need for efficient last-mile delivery solutions. MFCs strategically located in urban areas can meet the growing demand for fast, convenient order fulfillment, driving market growth in the region.
Key Micro Fulfillment Company Insights
The market has a fragmented competitive landscape featuring various global and regional players. Leading industry players are adopting strategies such as partnerships, collaborations, mergers & acquisitions, and agreements to survive the highly competitive environment and expand their business footprints. Moreover, some micro fulfillment providers offer micro fulfillment-as-a-service (MFaaS) models that provide turnkey solutions for retailers. With MFaaS, retailers can outsource their micro fulfillment operations to specialized providers, allowing them to focus on core business activities while benefiting from established infrastructure, technology, and expertise in micro fulfillment.
Key players are engaging in various growth strategies. For instance, in March 2023, Dematic expanded its presence by opening a new office in Abu Dhabi to enhance customer support in the UAE and across the Gulf Cooperation Council (GCC). The UAE is a significant logistics hub due to its strategic location between Asia, Europe, and Africa. By expanding operations in the UAE, Dematic can leverage its proximity to various markets and enhance its ability to serve customers across the region.
Key Micro Fulfillment Companies
The following key companies have been profiled for this study on the global micro fulfillment market:
-
Alert Innovation, Inc.
-
Dematic
-
Honeywell International Inc.
-
OPEX Corp.
-
Swisslog Holding AG
-
AutoStore
-
Exotec SAS
-
Takeoff Technologies Inc.
-
TGW Logistic Group GmbH
-
Get Fabric, Inc.
Recent Developments
- In March 2026, AutoStore launched the CubeVerse platform featuring AI-powered analytics, cloud-based software, and robotic workflow optimization capabilities designed to improve fulfillment efficiency and warehouse throughput. The platform enables automated process optimization and enhanced order preparation within existing fulfillment systems without requiring additional hardware investments.
- In May 2026, Amazon announced the expansion of its ultra-fast delivery service, Amazon Now, to an additional 100 cities across India. To support the expansion, the company planned to scale its fulfillment infrastructure to more than 1,000 micro-fulfillment centers, thereby strengthening rapid-delivery capabilities and expanding direct-to-consumer distribution networks.
Micro Fulfillment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.8 billion
Estimated market size in 2026
USD 11.8 billion
Projected market size by 2033
USD 84.5 billion
Growth rate
CAGR of 32.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, type, end use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; UK; Germany; France; China; India; Japan; Australia, South Korea; Brazil; Argentina, South Africa, UAE
Key companies profiled
Alert Innovation, Inc.; Dematic; Honeywell International Inc.; OPEX Corporation; Swisslog Holding AG; AutoStore; Exotec SAS; Takeoff Technologies Inc.; TGW Logistic Group GMBH; Get Fabric, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Micro Fulfilment Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global micro fulfillment market report based on component, type, end use, and region:
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
Automated Storage and Retrieval Systems (AS/RS)
-
Automated Guided Vehicles/Autonomous Mobile Robot (AGV/AMR)
-
Conveyor Systems
-
Sortation Systems
-
-
Software
-
Warehouse Management System
-
Order Management
-
Asset Management
-
Delivery & Transport Management
-
-
Services
-
Professional Services
-
Managed Services
-
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Standalone
-
Store-integrated/in Store
-
Dark Stores
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
E-commerce
-
Traditional Retailers & Distributors
-
Manufacturers
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East & Africa
-
Kingdom of Saudi Arabia (KSA)
-
UAE
-
South Africa
-
-
Frequently Asked Questions About This Report
The global micro fulfillment market size was valued at USD 8.8 billion in 2025 and is estimated at USD 11.8 billion for 2026.
The global micro fulfillment market is expected to grow at a CAGR of 32.4% from 2026 to 2033, reaching USD 84.5 billion.
North America dominated with an over 35.0% revenue share in 2025.
The hardware segment accounted for the largest revenue share in 2025.
Key players in the market include Riceland Foods, Inc., Wilmar International Limited, Archer Daniels Midland Company, Hindustan Animal Feeds, Astra Alliance, Siemer Milling Company, Didion Inc., Grain Millers Inc., Grain Processing Corporation, and others.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


