
- Home
- »
- Healthcare IT
- »
-
Middle East And Africa Telehealth Market Size Report, 2033GVR Report cover

Middle East And Africa Telehealth Market (2026 - 2033) Size, Share & Trends Analysis Report By Product Type (Hardware, Software, Services), By Disease Area, By Delivery Mode (On-Premises, Web-Based, Cloud-Based), By End-use, By Country, And Segment Forecasts
Market Size, 2025
$2.6BMarket Estimate, 2026
$3.0BMarket Forecast, 2033
$7.7BCAGR, 2026–2033
14.4%Middle East And Africa Telehealth Market Summary
The Middle East and Africa telehealth market size was estimated at USD 2.6 billion in 2025 and is projected to reach USD 7.7 billion by 2033, growing at a CAGR of 14.4% from 2026 to 2033. The rising prevalence of chronic conditions such as diabetes and cardiovascular disease is driving strong demand for remote monitoring and virtual consultations, while government-led initiatives and national digital health programs are accelerating the integration of telehealth services.
Key Market Trends & Insights
- South Africa dominated the Middle East and Africa telehealth market with the largest revenue share of 23.3% in 2025.
- The telehealth market in the UAE is anticipated to grow at the fastest CAGR during the forecast period.
- By product, the services segment accounted for the largest market revenue share in 2025.
- By delivery mode, the web-based segment accounted for the largest market revenue share in 2025.
Market Size & Forecast
- 2025 Market Size: USD 2.6 Billion
- 2033 Projected Market Size: USD 7.7 Billion
- CAGR (2026-2033): 14.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Advancements in technologies such as artificial intelligence, remote patient monitoring tools, and mobile health applications are enhancing the quality and convenience of care, supported by growing smartphone usage and improved internet connectivity.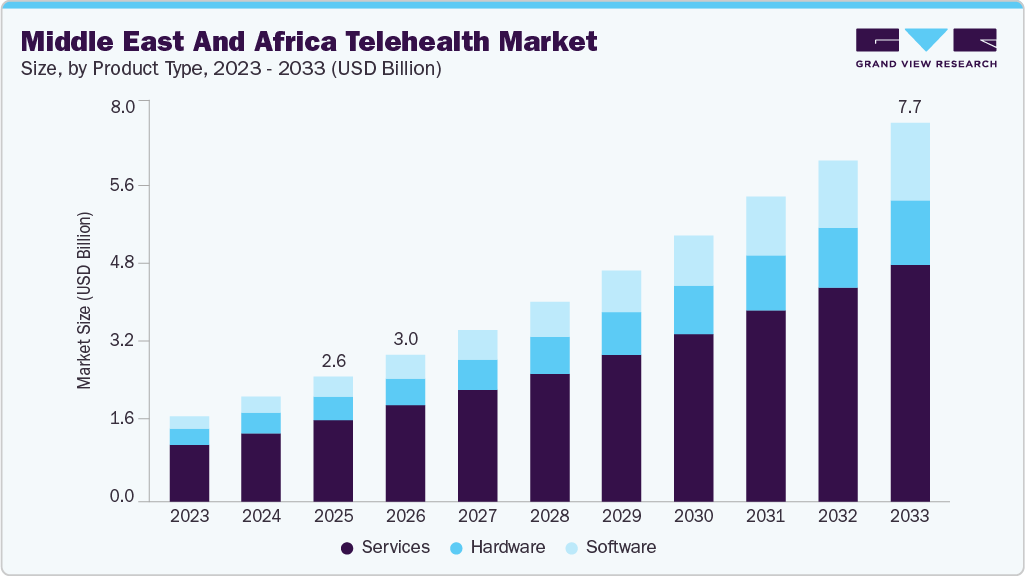 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Thus, the demand for cost-effective, time-saving healthcare solutions is encouraging patients and providers to shift toward teleconsultations and home-based care models, helping reduce hospital visits and address challenges related to healthcare accessibility and workforce shortages, thereby driving market growth.
Market Dynamics
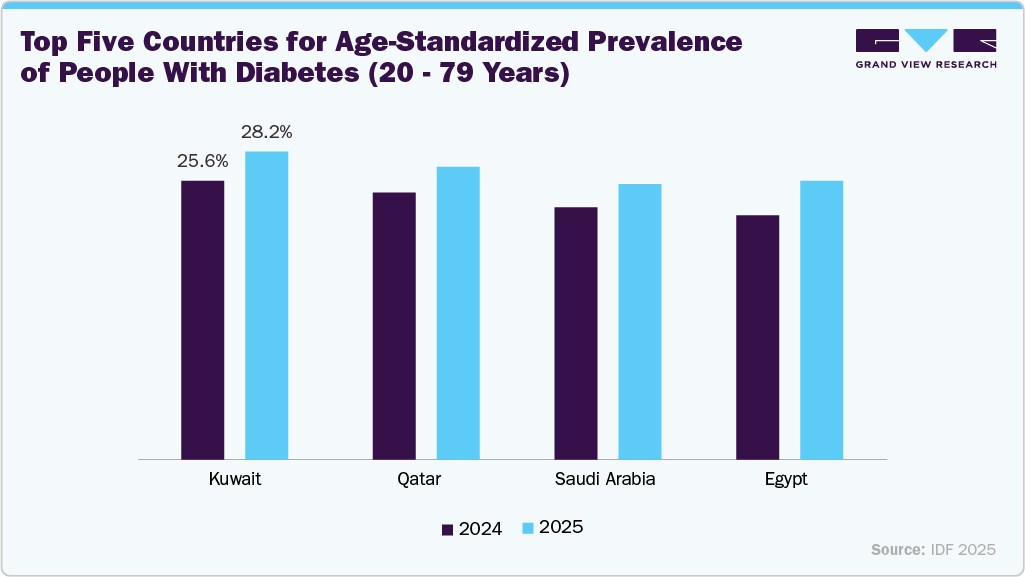
The rising prevalence of chronic diseases such as diabetes mellitus is significantly driving the market growth by increasing the need for continuous monitoring, timely interventions, and long-term disease management. Patients with diabetes require regular tracking of blood glucose levels, medication adherence, and lifestyle adjustments, which telehealth platforms enable through remote monitoring tools, mobile health applications, and virtual consultations. This reduces the need for frequent hospital visits while ensuring consistent medical supervision, particularly for patients in remote or underserved areas. In addition, telehealth solutions support early detection of complications, personalized treatment plans, and improved patient engagement, leading to better health outcomes and lower healthcare costs. As the burden of diabetes continues to rise across the region, healthcare providers and governments are adopting telehealth technologies to enhance access to care, optimize resource use, and manage the growing patient population more efficiently.
“We have seen an alarming rise in diabetes over the past three decades, which reflects the increase in obesity, compounded by the impacts of the marketing of unhealthy food, a lack of physical activity, and economic hardship. To bring the global diabetes epidemic under control, countries must urgently take action. This starts with enacting policies that support healthy diets and physical activity, and, most importantly, health systems that provide prevention, early detection, and treatment.”
- WHO Director-General Dr Dr. Tedros Adhanom Ghebreyesus.
 To learn more about this report, Download Free Sample Report
Government Support and Healthcare Digitalization Initiatives Accelerating Adoption
Rising government initiatives and funding are significantly driving the growth of the Middle East and Africa market by strengthening digital healthcare infrastructure and accelerating the adoption of virtual care services. Governments across the region are actively investing in telemedicine platforms, electronic health records, and remote patient monitoring technologies to improve healthcare accessibility and efficiency. Supportive regulatory frameworks, including telehealth guidelines and reimbursement policies, are encouraging healthcare providers to integrate virtual consultations into routine care delivery. In addition, increased public spending and partnerships with private technology providers are enabling the development of centralized digital health ecosystems and virtual care networks. These efforts are helping to expand healthcare reach in underserved and remote areas, reduce pressure on physical healthcare facilities, and promote cost-effective treatment solutions, thereby contributing to sustained market growth.
- According to the U.S.-Saudi Business Council’s report in 2025, Government healthcare spending has steadily increased in Saudi Arabia, with the Ministry of Finance allocating SAR260 billion (USD 69 billion) for ‘Health and Social Development’ in its official 2025 budget, the same figure as 2024. According to the latest information furnished by the MoH, its budget accounted for 41 percent or SAR105 billion ($28 billion) of the ‘Health and Social Development’ sector in 2023, compared to 35 percent in 2010, steadily growing both in absolute terms and as a percentage of total government spending.
"We have moved from treatment after illness, to prevention before illness, and from investing in pain to investing in hope. This orientation towards prevention and population health is reshaping how capital is being deployed across the sector."
- Saudi Arabia’s Minister of Health, H.E. Fahad bin Abdulrahman Aljalajel- In October 2024, the Saudi Food and Drug Authority launched a licensing initiative for medical software to support digital health adoption, enabling the use of software in diagnosis, treatment, and clinical decision-making. The initiative aims to accelerate innovation and investment in digital health technologies while advancing AI-driven care and modern healthcare delivery systems.
Cybersecurity and privacy concerns represent a major restraint for the telehealth industry, as the increasing reliance on cloud-based platforms, connected medical devices, and digital health ecosystems expands exposure to sensitive patient data. The growing integration of telehealth platforms with electronic health records (EHRs) and remote monitoring solutions has heightened vulnerabilities to cyber threats, including ransomware attacks, unauthorized access, and system disruptions. These risks are further intensified by limited cybersecurity budgets, a shortage of skilled IT professionals, and reliance on legacy healthcare IT infrastructure, which collectively challenge the secure and scalable deployment of telehealth services.
Challenge: Infrastructure and Connectivity Challenges
The Middle East and Africa telehealth industry faces significant infrastructure and connectivity challenges that limit large-scale adoption across rural and underserved regions. Several countries within Sub-Saharan Africa continue to experience inadequate broadband penetration, unstable electricity supply, and limited access to smartphones or connected healthcare devices, restricting the delivery of real-time teleconsultation and remote patient monitoring services. Healthcare systems in many developing economies also face shortages of trained digital health professionals capable of managing telehealth platforms, electronic health records, and virtual care workflows. Inconsistent reimbursement structures and fragmented regulatory policies across countries further create uncertainty for healthcare providers and technology vendors seeking long-term investment opportunities.
The rapid rise in smartphone and mobile user penetration is significantly driving the market growth by making digital healthcare services more accessible and convenient for a larger population. With widespread use of smartphones, patients can easily access teleconsultation platforms, mobile health applications, and remote monitoring tools from anywhere, enabling real-time interaction with healthcare providers without the need for physical visits. This increased connectivity supports continuous disease
According to the World Economic Forum, in 2025, the Middle East is one of the most youthful regions in the world: more than half of the population is under 25, and the median age is 22, compared to 28 globally. These young people have grown up as digital natives, immersed in technologies that make their lives easier. They are early adopters of new products and services, especially when offered by brands that share their values and do good. Bahrain, for example, is a country with a youthful population of early adopters. The country has a mobile penetration rate of 137% as of 2023, and the highest internet penetration rate in the world, with almost its entire population connected to the internet.
Market Concentration & Characteristics
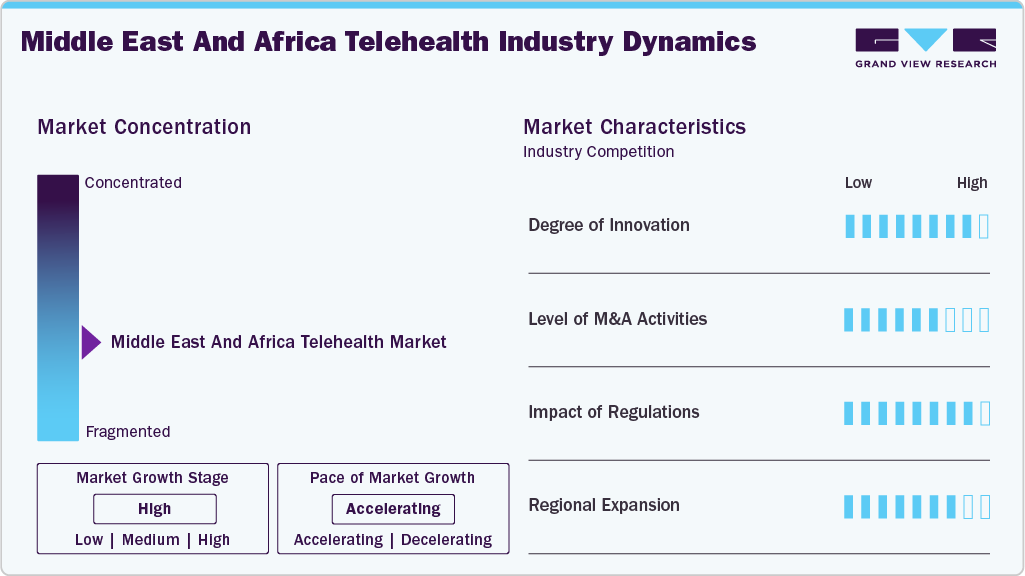
The Middle East and Africa telehealth industry is characterized by a diverse mix of regional healthcare providers, international technology companies, and emerging digital health startups, creating a competitive, evolving industry landscape. Large healthcare organizations and global tech firms are expanding their footprint through strategic collaborations, service diversification, and integration of advanced digital platforms, while local players are focusing on customized solutions to address region-specific healthcare needs.
The Middle East and Africa telehealth industry is experiencing innovation driven by the rapid adoption of digital technologies across healthcare systems. Providers are incorporating artificial intelligence, machine learning, and cloud-based platforms to improve diagnosis, streamline consultations, and enhance patient management. At Global Health 2025, SEDCO’s Telehealth Pod is a smart medical hub in a private space that can be installed in pharmacies, rural clinics, and hotels. Equipped with advanced medical tools, it allows patients to connect with doctors via secure video consultations and complete full check-ups remotely. The pod helps reduce travel time and waiting, eases congestion, and brings healthcare closer to patients.
 To learn more about this report, Download Free Sample Report
Regulations play a crucial role in shaping the Middle East and Africa market by establishing standards for safety, data privacy, service quality, and clinical practice. Regulatory approvals and licensing requirements can influence the speed at which new platforms and technologies enter the market, sometimes delaying smaller players while ensuring quality control. For instance, the Dubai Health Authority (DHA) Telehealth Standards framework mandates that all telehealth providers and platforms must obtain prior licensing approval and comply with updated service standards, including data privacy, cybersecurity, and physician licensing requirements.
The market is witnessing merger and acquisition (M&A) activity as healthcare providers, technology companies, and digital health startups seek to expand their capabilities and regional presence. Established healthcare groups are acquiring or partnering with telemedicine platforms to strengthen their digital service offerings, while global health tech firms are entering the region through strategic investments and acquisitions to tap into growing demand for virtual care. For instance, in 2025, PureHealth Holding PJSC announced the successful completion of its USD 860 million acquisition of a 60% stake in Hellenic Healthcare Group, a leading private healthcare provider in Greece and Cyprus. The deal values HHG at approximately USD 1.40 billion (100% equity value).
The regional expansion of the market is driven by the rapid adoption of digital healthcare solutions across key countries, including South Africa and Saudi Arabia, where governments and private providers are actively scaling virtual care infrastructure. South Africa, Saudi Arabia, and the UAE dominate adoption due to advanced healthcare systems, high internet penetration, and strong investment in digital health platforms, while emerging markets such as Egypt and Jordan are expanding telehealth access to improve healthcare delivery in rural and underserved populations.
Product Type Insights
The services segment led the market with the largest revenue share of 65.1% in 2025, owing to healthcare providers’ dependence on end-to-end support offerings, including virtual consultation management, remote patient monitoring, platform integration, technical maintenance, and clinical assistance. Many hospitals and healthcare systems prefer service-based models because they lack fully developed in-house digital health capabilities and require continuous operational and technical support to run telehealth systems efficiently. Services also play a vital role in ensuring uninterrupted patient engagement, chronic disease management, and coordination between doctors and patients across digital platforms.
The software segment is anticipated to grow at the fastest CAGR during the forecast period, driven by increasing demand for advanced digital platforms such as virtual consultations, electronic health records, mobile health applications, and AI-driven healthcare solutions. Healthcare providers are rapidly adopting cloud-based, interoperable software systems to improve efficiency, enhance the patient experience, and enable real-time access to medical data. The growing integration of artificial intelligence, machine learning, and predictive analytics is further enhancing diagnostic accuracy and personalized treatment planning.
Delivery Mode Insights
The web-based delivery mode segment led the market with the largest revenue share of 40.9% in 2025, offering easy accessibility, minimal installation requirements, and compatibility across devices such as desktops, laptops, and tablets. Healthcare providers prefer web-based platforms because they can be quickly deployed within existing hospital systems without requiring complex infrastructure changes. These platforms enable seamless virtual consultations, appointment scheduling, and patient record management through browser-based interfaces, making them highly practical for hospitals, clinics, and government healthcare systems.
The cloud-based segment is anticipated to grow at the fastest CAGR during the forecast period, driven by scalability, flexibility, and support for advanced digital healthcare applications. Cloud-based platforms enable real-time data sharing between patients, doctors, and healthcare institutions, improving coordination and continuity of care. They also support integration of advanced technologies such as artificial intelligence, remote monitoring, and predictive analytics, which enhance clinical decision-making and patient outcomes.
Disease Area Insights
The psychiatry segment accounted for the largest market revenue share in 2025, within the disease area category, due to the rising prevalence of mental health conditions such as anxiety, depression, and stress-related disorders, along with increasing social acceptance of seeking psychological support through digital platforms. Telehealth is particularly well-suited for psychiatry because it allows patients to access confidential consultations from the comfort of their homes, reducing stigma and improving willingness to seek care. In addition, the limited availability of mental health specialists in certain parts of the region and long waiting times for in-person consultations have further increased reliance on virtual psychiatric services. The convenience, privacy, and accessibility offered by telepsychiatry platforms have made them a preferred choice for both patients and healthcare providers.
The oncology segment is anticipated to grow at the fastest CAGR during the forecast period, as cancer cases continue to rise and demand for continuous, long-term care increases. Telehealth is being used in oncology for follow-up consultations, treatment monitoring, second opinions, and post-therapy care, reducing the need for frequent hospital visits by patients undergoing intensive treatment. Digital platforms also enable better coordination between oncologists, radiologists, and other specialists, improving treatment planning and patient outcomes. Furthermore, the integration of remote monitoring tools and AI-based analytics is helping to detect complications early and to personalize treatment.
End Use Insights
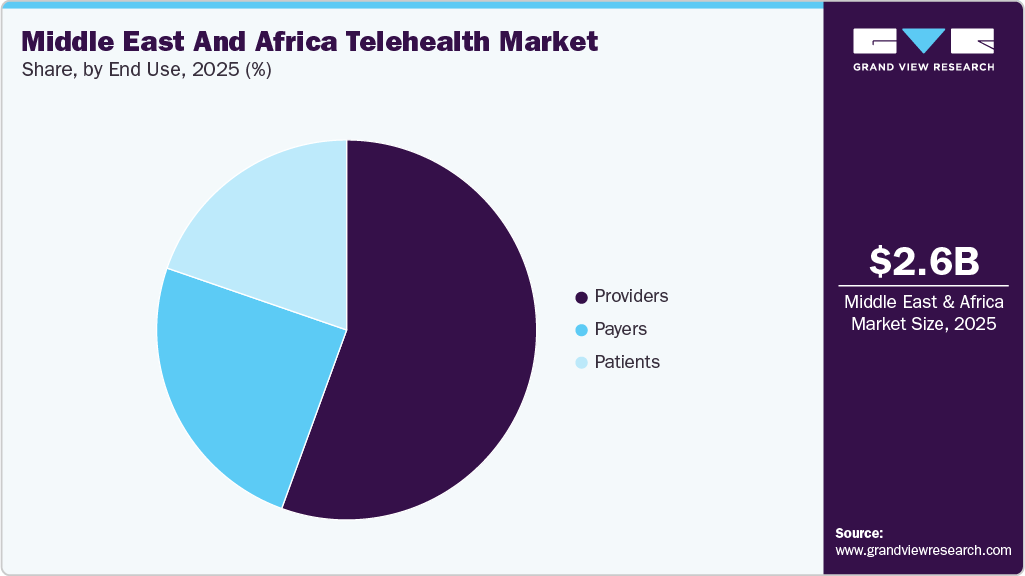
The providers segment led the market with the largest revenue share of 55.5% in 2025, as hospitals, clinics, and physician networks are the primary adopters and operators of telehealth services. Healthcare providers are integrating virtual care platforms into their existing clinical workflows to offer remote consultations, chronic disease management, and follow-up care. This dominance is driven by the need to expand patient reach, reduce hospital congestion, and improve operational efficiency. Providers also benefit from telehealth by optimizing resource utilization and enabling continuous patient monitoring without requiring physical visits.
 To learn more about this report, Download Free Sample Report
The payers segment is anticipated to grow at the fastest CAGR during the forecast period, as insurance companies and government healthcare funding bodies incorporate telehealth services into coverage plans and reimbursement models. Payers are adopting digital health solutions to reduce overall healthcare costs by minimizing unnecessary hospital admissions and encouraging early intervention through virtual consultations. Telehealth also enables payers to improve population health management by monitoring patient outcomes and promoting preventive care programs.
Country Insights
South Africa Telehealth Market Trends
South Africa dominated the Middle East and Africa telehealth market with the largest revenue share of 23.3% in 2025, driven by a dual healthcare system and uneven access to medical services, with a well-developed private sector offering advanced specialist care. At the same time, the public system serves a larger population but faces capacity constraints. This imbalance creates strong demand for telehealth in primary care, specialist consultations, and follow-ups, particularly outside major cities such as Johannesburg, Cape Town, and Durban. Infrastructure disparities further shape adoption. Urban areas benefit from strong connectivity, while rural regions face access limitations, though mobile-based delivery is expanding due to high smartphone penetration.
Saudi Arabia Telehealth Market Trends
The telehealth market in Saudi Arabia is anticipated to grow at a significant CAGR during the forecast period. The rapid development of healthcare infrastructure and digital health initiatives in Saudi Arabia is a major driver of market growth, as it is transforming how healthcare services are delivered and accessed. Significant investments in hospitals, specialty clinics, and smart healthcare facilities are complemented by the integration of advanced digital systems, including electronic health records, telemedicine platforms, and AI-enabled diagnostic tools. This combination is enabling healthcare providers to extend care beyond physical facilities through virtual consultations, remote monitoring, and digital follow-ups, thereby improving accessibility and reducing pressure on hospitals. The expansion of high-speed internet connectivity, cloud-based healthcare systems, and nationwide digital health networks is enhancing data sharing and coordination among patients, physicians, and healthcare institutions.
-
According to the U.S.-Saudi Business Council in 2025, Employees working as physicians, dentists, nurses, pharmacists, and other allied health personnel in Saudi Arabia totaled 545,574 in 2023. The government accounted for 67 percent of healthcare employment, with 255,975 Saudis and 107,894 non-Saudis. Total employment in the health sector grew at a 4.4 percent CAGR between 2016 and 2023.
-
The Sehhaty app, launched by the MOH, is a prime example of innovation. This app provides virtual consultations, prescription services, and access to medical records, particularly benefiting patients in remote areas. Sehhaty facilitated over 5 million telemedicine consultations, underscoring the Kingdom’s commitment to leveraging digital solutions to enhance access and efficiency. In addition, the program focuses on preventive care to combat the high prevalence of NCDs, such as diabetes and cardiovascular conditions, which account for a significant proportion of morbidity and mortality in Saudi Arabia.
UAE Telehealth Market Trends
The UAE telehealth market is anticipated to grow at the fastest CAGR during the forecast period. The rapid expansion of telehealth platforms in the UAE is significantly driving the market's growth by making healthcare services more accessible, efficient, and patient-centric. A growing number of hospitals, startups, and digital health companies are launching advanced telemedicine platforms that offer virtual consultations, remote diagnostics, electronic prescriptions, and integrated health record systems. Both public and private healthcare providers are adopting these platforms to enhance patient reach and reduce waiting times, especially in urban centers with high patient demand. In addition, strong government support for digital health transformation and regulatory frameworks that encourage licensed telemedicine services are accelerating platform adoption. The integration of technologies such as artificial intelligence, cloud computing, and mobile health applications is further improving service quality and enabling seamless communication between doctors and patients.
- In May 2025, Practo announced the launch of its platform in the UAE, marking a major international expansion into the Middle East healthcare market. The company reported that it already had over 50,000 monthly active users in the UAE, along with access to more than 3,000 clinics and 31,000+ doctors on its platform. Practo also highlighted that it was on track to achieve approximately 10% annual adoption in Dubai. At launch, Practo also disclosed that its UAE operations had reached an annual GMV run rate of 80-100 crore, reflecting early market traction.
Key Middle East And Africa Telehealth Company Insights
The Middle East and Africa telehealth industry is highly competitive, with key players holding significant market share. Major companies are pursuing a range of organic and inorganic strategies, including new product development, collaborations, acquisitions, mergers, and regional expansion, to address unmet customer needs.
Key Middle East And Africa Telehealth Companies:
- Altibbi
- Vezeeta
- Okadoc
- Cura
- Alma Health
- Yodawy
- DoctorUna
- WebTeb
- Babylon Health
- Careem Health
- Medisense
- Tabeebak
- Sehat Kahani
- MyDoctor (Egypt)
- Healthigo
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Altibbi
- Develop integrated virtual care ecosystems combining teleconsultation, remote monitoring, and hospital system integration to strengthen clinical adoption.
- Benefit from established clinical credibility and deep integration with hospital IT systems, creating higher switching costs and strong provider dependence.
- Face high operational complexity and integration challenges due to legacy systems and large-scale enterprise deployments.
Emerging Players: MyDoctor
- Prioritize direct-to-consumer digital-first models with seamless user experience to drive accessibility and rapid patient acquisition.
- Gain advantage through consumer-centric platforms with superior user experience, enabling rapid adoption and high patient engagement.
- Limited by narrow service scope and lack of full care integration, restricting the ability to manage complex clinical cases.
Recent Developments
-
April 2026, Upwyde Developments signed a strategic agreement with Vezeeta to operate an integrated medical facility within the “Prk Vie” project in New Cairo’s Fifth Settlement. Under the agreement, Vezeeta was tasked with managing and operating the medical building, which combined in-person healthcare services with digital tools for appointment booking and service management, reflecting a hybrid healthcare delivery model.
-
September 2025, the Ministry of Health launched a digital link between the Seha Virtual Hospital and the Syrian Ministry of Health in a ceremony attended by senior officials from both countries. The initiative was announced in Riyadh and marked a major advancement in Saudi-Syrian health cooperation by strengthening digital health infrastructure and enabling direct integration between health platforms. It enabled 24/7 remote consultations, diagnosis, and treatment, improving access to immediate healthcare support.
-
February 2025,Sidra Medicine, a member of Qatar Foundation, signed a Memorandum of Understanding (MOU) with Rasmal Ventures, Qatar’s first venture capital firm, to accelerate digital health innovation in Qatar. The partnership was announced at Web Summit Qatar 2025 in Doha and aimed to connect Sidra Medicine with high-potential e-health startups and support the integration of innovative healthcare technologies into clinical practice.
Middle East And Africa Telehealth Market Report Scope
Report Attribute
Details
Market size value in 2026
USD 3.0 billion
Revenue forecast in 2033
USD 7.7 billion
Growth rate
CAGR of 14.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, delivery mode, end use, disease area, country
Regional scope
Middle East & Africa
Country scope
South Africa; Saudi Arabia; UAE; Kuwait; Oman; Qatar
Key companies profiled
Altibbi; Vezeeta; Okadoc; Cura; Alma Health; Yodawy; DoctorUna; WebTeb; Babylon Health; Careem Health; Medisense; Tabeebak; Sehat Kahani; MyDoctor (Egypt); Healthigo
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to the country & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Middle East And Africa Telehealth Market Report Segmentation
This report forecasts country-level revenue growth and analyzes the latest industry trends and opportunities across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the Middle East and Africa telehealth market report based on product, delivery mode, end use, disease area, and country:
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
Monitors
-
Medical Peripheral Devices
-
Blood Pressure Meters
-
Blood Glucose Meters
-
Weighing Scales
-
Pulse Oximeters
-
Peak Flow Meters
-
ECG Monitors
-
Others
-
-
-
Software
-
Integrated Software
-
Standalone Software
-
-
Services
-
Remote Patient Monitoring
-
Real-Time Interactions
-
Store and Forward
-
Other Services
-
-
-
Delivery Mode (Revenue, USD Million, 2021 - 2033)
-
On-Premises
-
Web-Based
-
Cloud-Based
-
-
Disease Area (Revenue, USD Million, 2021 - 2033)
-
Psychiatry
-
Substance Use
-
Radiology
-
Endocrinology
-
Dermatology
-
Gastroenterology
-
Neurological Medicine
-
ENT
-
Cardiology
-
Oncology
-
Dental
-
Gynecology
-
General Medicine
-
Others
-
-
End Use (Revenue, USD Million, 2021 - 2033)
-
Payers
-
Providers
-
Patients
-
-
Country Outlook (Revenue, USD Million, 2021 - 2033)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Oman
-
Qatar
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Telehealth Infrastructure & Digital Connectivity Assessment
Conducted a comprehensive evaluation of telehealth infrastructure across the Middle East & Africa region, including internet penetration, mobile health accessibility, cloud-based healthcare integration, digital consultation capabilities, cybersecurity readiness, and interoperability with hospital information systems. The study further analyzed rural connectivity challenges and regional digital health investment trends.
Supports strategic expansion planning, identifies high-potential markets for telehealth deployment, enables prioritization of scalable digital healthcare models, and strengthens long-term infrastructure investment decisions across emerging healthcare ecosystems.
Public vs. Private Healthcare Telehealth Penetration Assessment
Developed an in-depth evaluation of telehealth adoption across government healthcare systems, private hospitals, clinics, and insurance-supported healthcare networks within the MEA region.
Helps clients understand payer dynamics, evaluate partnership opportunities, and optimize go-to-market strategies across public and private healthcare ecosystems.
Country-Level Telehealth Adoption Analysis Across MEA
Conducted detailed country-wise assessment of telehealth adoption trends across key Middle East & African countries, including analysis of virtual consultation demand, healthcare access gaps, smartphone penetration, and patient preference trends.
Helps identify high-growth countries, supports regional expansion planning, and enables prioritization of investment opportunities across emerging digital healthcare markets.
Frequently Asked Questions About This Report
Key factors that are driving the market growth include improving internet connectivity and increasing smartphone penetration is supporting the digitalization of healthcare.
South Africa dominated the Middle East and Africa telehealth market with a share of 23.3% in 2025, driven by a dual healthcare structure and uneven access to medical services, with a well-developed private sector offering advanced specialist care.
Some key players operating in the Middle East and Africa telehealth market include Altibbi, Vezeeta, Okadoc, Cura, Alma Health, Yodawy, DoctorUna, WebTeb, Babylon Health, Careem Health, Medisense, Tabeebak, Sehat Kahani, MyDoctor (Egypt), Healthigo, and others
The Middle East and Africa telehealth market size was estimated at USD 2.6 billion in 2025 and is expected to reach USD 3.0 billion in 2026.
The Middle East and Africa telehealth market is expected to grow at a compound annual growth rate of 14.3% from 2026 to 2033 to reach USD 7.7 billion by 2033.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


