
- Home
- »
- Next Generation Technologies
- »
-
Neural Processor Market Size And Share Report, 2026-2033GVR Report cover
![Neural Processor Market (2026 - 2033)Report]()
Neural Processor Market (2026 - 2033)
Size, Share & Trends Analysis Report By Operation (Training, Inference), By Application (Autonomous Vehicles, Robotics & Drones), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$334.0MMarket Estimate, 2026
$397.2MMarket Forecast, 2033
$1,424.4MCAGR, 2026–2033
20.0%Neural Processor Market Summary
The global neural processor market size was valued at USD 334.0 million in 2025 and is projected to grow from USD 397.2 million in 2026 to USD 1,424.4 million by 2033, at a CAGR of 20.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 33.9% in 2025. The region's leadership is driven by the widespread adoption of artificial intelligence (AI) and machine learning (ML) technologies across consumer electronics, data centers, automotive, healthcare, and industrial automation.

Key Market Trends & Insights
- By operation: The inference segment held the largest market share of 66.1% in 2025.
- By application: The smartphones and tablets segment held the largest market share of 23.8% in 2025.
Regional Highlights
- Largest regional market: North America (33.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 334.0 Million
- Estimated market size in 2026: USD 397.2 Million
- Projected market size by 2033: USD 1,424.4 Million
- CAGR (2026-2033): 20.0%
Growing demand for high-performance AI computing, increasing deployment of edge AI devices, and the rapid integration of neural processing units (NPUs) in smartphones, PCs, autonomous vehicles, and IoT devices are fueling market growth. This growth is primarily driven by the increasing demand for AI-enabled edge devices across sectors such as automotive, healthcare, and consumer electronics. Advancements in deep learning and neural network algorithms are prompting the need for highly efficient and specialized processing units, boosting market expansion. Moreover, the proliferation of smart devices and the push for real-time inference capabilities further accelerate the adoption of neural processors globally.The market is growing due to the rapid expansion of artificial intelligence (AI) and machine learning (ML) applications across various sectors. These technologies require specialized hardware capable of processing complex algorithms efficiently, which traditional CPUs and GPUs struggle to handle. Neural processors are specifically designed to manage AI workloads, providing faster performance and greater energy efficiency. This increased capability makes them essential for autonomous vehicles, real-time analytics, and natural language processing applications. As AI becomes more prevalent in healthcare, finance, and manufacturing industries, the demand for neural processors continues to rise.
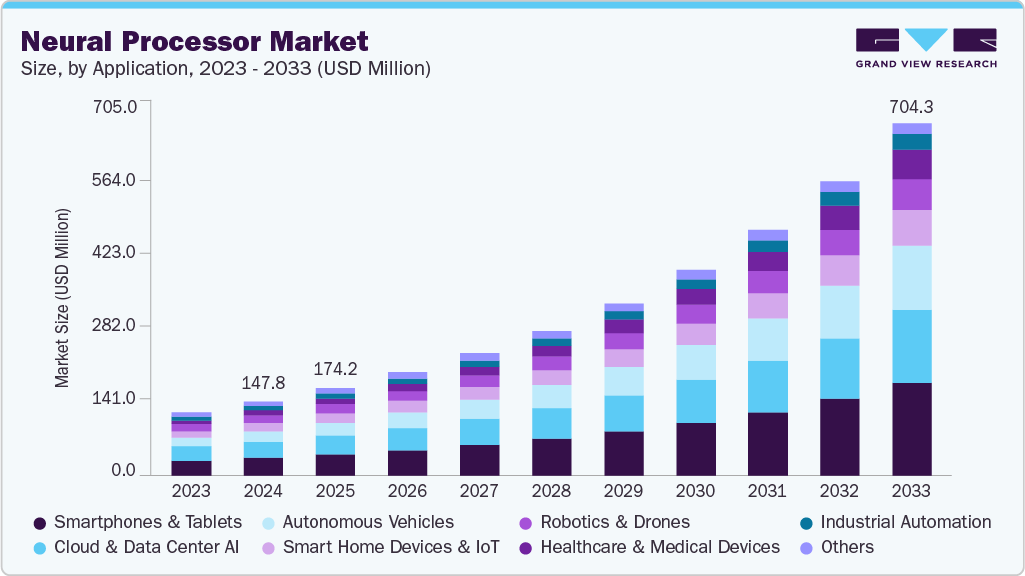
Consumer electronics are another key area contributing to the market's rise. Devices such as smartphones, smart speakers, and home automation systems increasingly incorporate AI features to enhance user experiences. Neural processors enable these devices to perform tasks such as voice recognition, image processing, and personalized recommendations more efficiently. Manufacturers are integrating neural processors to meet this demand as more consumers seek AI-powered functionalities in their devices. This trend has led to significant market growth, especially as companies compete to offer the most advanced AI-enabled products.
Improvements in semiconductor manufacturing have significantly enhanced the efficiency and scalability of neural processor production, reducing costs and improving performance. These advancements enable the integration of neural processors into a wider range of devices, from smartphones to autonomous systems. Combined with rising consumer demand for intelligent and responsive technologies, this has created strong momentum for adoption. As a result, both tech giants and emerging players are rapidly investing in neural processor development to gain a competitive edge. This synergy between manufacturing innovation and market demand fuels sustained market growth.
The growing reliance on cloud computing and edge computing has further accelerated the demand for neural processors. Cloud service providers increasingly offer AI-as-a-service solutions that depend on neural processors to deliver high-speed, scalable AI capabilities. These processors are critical for managing large volumes of data and performing complex AI computations in real time. In edge computing, neural processors help process data closer to the source, reducing latency and improving decision-making for applications such as autonomous vehicles and smart cities. This decentralization of AI processing requires powerful neural processors to ensure smooth and efficient operations. As both cloud and edge computing grow, neural processors are becoming indispensable for enabling AI in a wide range of scenarios.
Market Dynamics
The neural processor market is witnessing substantial growth, driven by the rapid proliferation of artificial intelligence (AI) and machine learning (ML) applications across consumer electronics, automotive, healthcare, industrial automation, telecommunications, and cloud computing. As AI models become increasingly complex and computationally intensive, organizations are adopting dedicated neural processors, including Neural Processing Units (NPUs) and AI accelerators, to deliver high-performance computing with lower power consumption and minimal latency. The growing adoption of edge AI, generative AI, computer vision, natural language processing (NLP), robotics, and autonomous systems is significantly increasing demand for specialized AI hardware. Additionally, continuous advancements in semiconductor technology, heterogeneous computing architectures, and on-device AI capabilities are accelerating market expansion. However, high semiconductor development costs, manufacturing complexities, and supply chain challenges remain key constraints. Despite these challenges, increasing investments in edge computing, AI-enabled consumer devices, autonomous mobility, and intelligent industrial systems are expected to create significant growth opportunities during the forecast period.
The neural processor market is experiencing robust growth owing to the increasing demand for dedicated AI acceleration across edge and cloud computing environments. Neural processors enable faster execution of AI workloads while delivering superior energy efficiency compared to traditional CPUs and GPUs for inference-intensive applications. The rapid integration of NPUs into smartphones, AI-enabled PCs, autonomous vehicles, robotics, surveillance systems, healthcare devices, and industrial IoT equipment is driving widespread adoption. Furthermore, the growing deployment of generative AI, computer vision, speech recognition, large language models (LLMs), and real-time analytics is encouraging semiconductor manufacturers to develop advanced neural processing architectures capable of supporting increasingly sophisticated AI workloads while minimizing latency and power consumption.
Despite strong growth prospects, the neural processor market faces several challenges associated with designing and manufacturing next-generation AI processors. Developing advanced neural processors requires substantial investments in research and development, access to leading-edge semiconductor fabrication technologies, and sophisticated chip design expertise. In addition, dependence on advanced foundries, limited fabrication capacity, supply chain disruptions, and geopolitical uncertainties continue to impact production and component availability. Rapid advancements in AI algorithms and evolving software frameworks also require continuous hardware optimization, increasing product development complexity and time-to-market for semiconductor vendors.
The rapid expansion of on-device AI and edge computing is creating significant opportunities for the neural processor market. Increasing consumer demand for intelligent smartphones, AI PCs, wearable devices, smart home systems, autonomous drones, robotics, and connected industrial equipment is accelerating the integration of dedicated neural processors capable of executing AI workloads locally. On-device AI enables enhanced privacy, lower latency, reduced cloud dependency, and improved energy efficiency, making neural processors essential for next-generation intelligent devices. Moreover, growing investments in Industry 4.0, autonomous transportation, smart healthcare, edge data centers, and multimodal generative AI applications are expected to drive sustained demand for high-performance neural processors, creating substantial long-term growth opportunities for market participants.
Market Concentration & Characteristics
The neural processor market is moderately concentrated, with competition driven by established semiconductor manufacturers, AI hardware developers, and emerging neuromorphic computing companies. Market participants compete based on AI processing performance, power efficiency, edge computing capabilities, scalability, chip architecture, and integration with AI software ecosystems. Continuous investments in advanced semiconductor process technologies, on-device AI acceleration, heterogeneous computing architectures, and low-power neural processing units (NPUs) are shaping the competitive landscape. Strategic collaborations, product innovations, investments in AI research, and advancements in edge AI, generative AI, robotics, and autonomous systems are further strengthening market competitiveness.
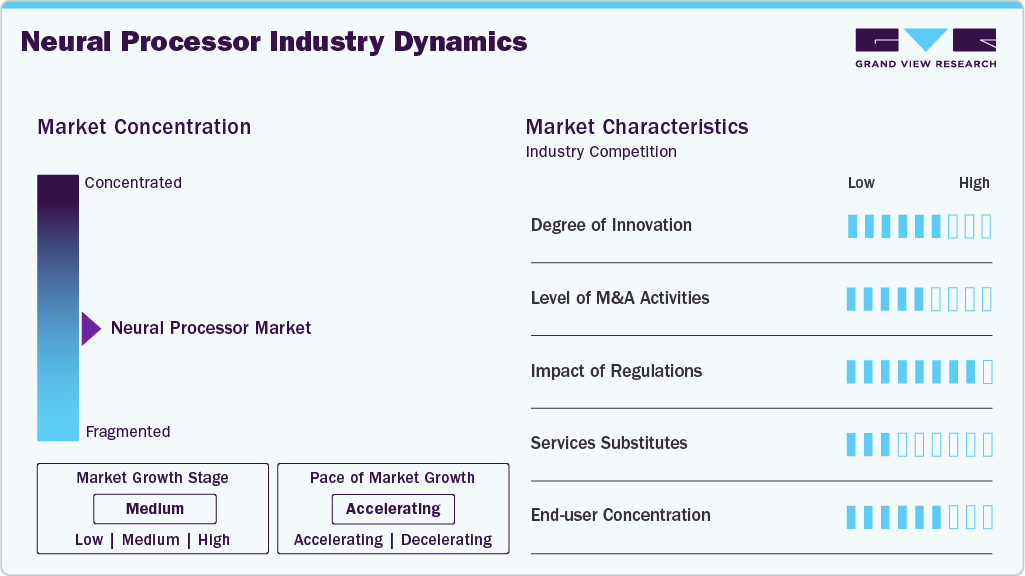
Key market participants include Advanced Micro Devices, Inc., Arm Limited, Aspinity, Inc., Bitbrain Technologies, BrainChip, Inc., BrainCo, Inc., General Vision, Inc., Google LLC, Halo Neuroscience, Intel Corporation, NVIDIA Corporation, Qualcomm Inc., and Samsung Electronics Co., Ltd. These companies are focused on developing next-generation neural processors, AI accelerators, neuromorphic computing platforms, and energy-efficient chip architectures for applications across consumer electronics, automotive, healthcare, industrial automation, robotics, edge computing, and cloud AI infrastructure. Their strategies emphasize expanding AI hardware portfolios, enhancing on-device intelligence, optimizing AI inference performance, and strengthening partnerships across the global AI ecosystem.
Analyst Perspective
The Neural Processor Market is emerging as a foundational component of the AI computing ecosystem, driven by the increasing demand for high-performance, energy-efficient processing across edge devices, cloud infrastructure, and intelligent systems. As artificial intelligence workloads become more complex, industries are increasingly adopting neural processors to accelerate AI inference and training while reducing latency, power consumption, and dependence on cloud-based computing. The market is benefiting from rapid advancements in neural processing units (NPUs), AI accelerators, heterogeneous computing architectures, and neuromorphic technologies, enabling enhanced performance for applications such as generative AI, computer vision, natural language processing (NLP), robotics, autonomous vehicles, and smart consumer devices. As investments in edge AI, semiconductor innovation, and intelligent automation continue to grow, neural processors are expected to play a pivotal role in enabling next-generation AI applications, creating significant opportunities for technological innovation and sustained market expansion over the forecast period.
Operation Insights
Based on Operation, the Inference segment led the market with the largest revenue share of 66.1% in 2025. The increasing need for real-time AI decision-making drives the growth of inference operations in the market. Inference involves the application of trained AI models to new data, enabling devices to make predictions or take actions instantly. As AI-powered applications such as speech recognition, facial recognition, and autonomous systems become more widespread, the demand for faster and more efficient inference grows. Neural processors are optimized for handling these inference tasks, providing better performance and lower power consumption compared to traditional hardware. This makes them essential for a wide range of AI-driven technologies in various industries.
The training segment will benefit significantly from the increasing complexity of AI models and the growing demand for AI-driven applications. Training involves teaching AI models to recognize patterns and make predictions based on vast datasets, requiring high computational power. As industries such as healthcare, finance, and autonomous vehicles invest more in AI technologies, the need for specialized hardware to support training processes is expanding. Optimized for these intensive tasks, Neural processors are becoming crucial for efficiently training complex models. This surge in AI development and adoption is anticipated to drive market growth.
Application Insights
Based on application, the Smartphones and Tablets segment led the market with the largest revenue share of 23.8% in 2025. Smartphones and tablets dominate the market because of their widespread use and growing integration of AI-driven features. These devices rely heavily on neural processors to enhance performance for tasks like facial recognition, voice assistants, and real-time language translation. The increasing demand for AI-enhanced applications, such as augmented reality and advanced photography, requires the efficient processing power that neural processors provide. Manufacturers constantly push for more powerful AI capabilities in mobile devices to meet consumer expectations. As a result, smartphones and tablets have become the primary applications for neural processors, driving their dominance in this market.

The autonomous vehicle sector is growing rapidly due to AI, sensor technology, and neural processors. These vehicles rely on AI-powered systems for real-time decision-making, such as object detection, navigation, and collision avoidance. Neural processors are crucial in processing vast amounts of data from sensors, cameras, and radar systems efficiently and quickly, enabling the vehicle to respond to its environment. The push for safer, more reliable autonomous driving solutions has led to increased investment and innovation in this sector. As regulatory frameworks evolve and consumer interest rises, the demand for autonomous vehicles continues to expand.
Regional Insights
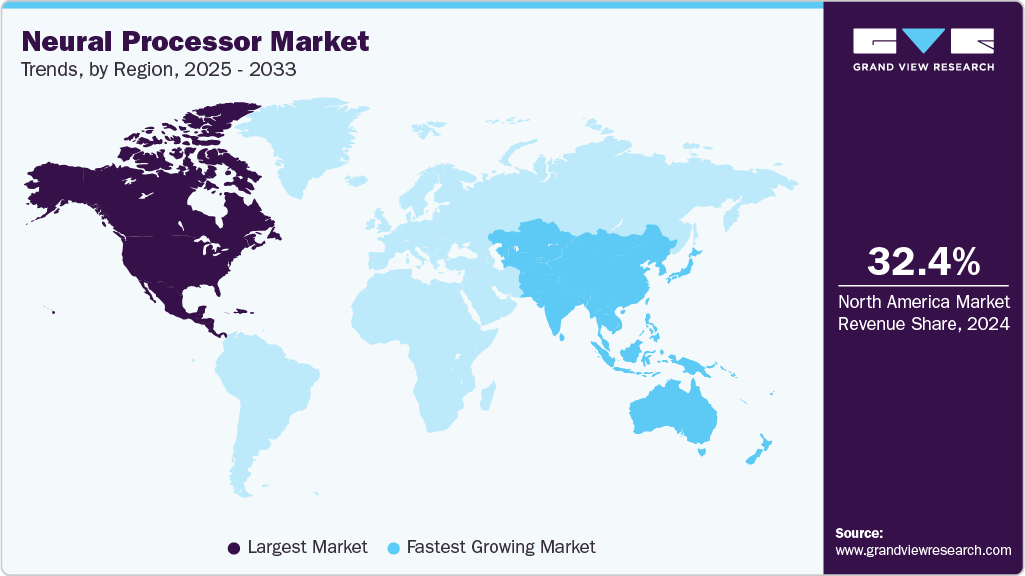
North America dominated the neural processor market with the largest revenue share of 33.9% in 2025. The North American market is experiencing significant growth, driven by the increasing demand for advanced artificial intelligence applications. The proliferation of cloud computing and edge devices is propelling the adoption of neural processors across various industries, including healthcare, automotive, and finance. Moreover, key players in the region are investing heavily in research and development to enhance the capabilities and performance of neural processors. The market is also trending towards integrating machine learning algorithms, enabling faster data processing and decision-making.
U.S. Neural Processor Market Trends
The neural processor market in the U.S. held the largest share in the North America region in 2025. The neural processor market in the U.S. is characterized by rapid advancements in technology, particularly in the fields of deep learning and natural language processing. Major technology companies are launching new neural processor models, enhancing computational power and energy efficiency. The growing emphasis on smart devices and the Internet of Things (IoT) further fuels market growth, as these applications require efficient processing capabilities.
Europe Neural Processor Market Trends
The neural processor market in Europe is witnessing a surge in demand due to increased investments in artificial intelligence and machine learning technologies. Government initiatives to promote digital transformation are driving the adoption of neural processors in various sectors, including manufacturing and automotive. Moreover, the region focuses on developing sustainable and energy-efficient processing solutions, aligning with its broader environmental goals. Established tech hubs in countries such as Germany, France, and the UK foster innovation and competition within the market.
Asia Pacific Neural Processor Market Trends
The neural processor market in Asia Pacific is anticipated to register the fastest CAGR over the forecast period. The market is experiencing rapid expansion, fueled by the region's strong emphasis on technological innovation and digital transformation. Countries such as China, Japan, and India are leading the charge, investing heavily in artificial intelligence research and development to enhance their competitiveness in the global market. The rise of smart cities and the Internet of Things (IoT) initiatives also drives demand for high-performance neural processors across various industries, including transportation and healthcare. Furthermore, collaborations between tech companies and research institutions foster advancements in neural processor capabilities, promoting the development of more efficient and powerful solutions.
Key Neural Processor Company Insights
Some key companies in the neural processor industry are Advanced Micro Devices, Inc., Intel Corporation, NVIDIA Corporation, and Qualcomm Inc.
-
Advanced Micro Devices, Inc. is a leading global semiconductor company known for its high-performance computing, graphics, and visualization technologies. In recent years, Advanced Micro Devices, Inc. has expanded its focus into artificial intelligence and machine learning applications, including developing neural processing capabilities. Advanced Micro Devices, Inc. is integrating AI accelerators and neural engines into its product portfolio to support edge and data center AI workloads through its acquisition of Xilinx and investments in adaptive computing. The company’s neural processors are designed to optimize deep learning inference and training, offering high performance with energy efficiency.
-
NVIDIA Corporation is a global leader in visual computing technologies, widely recognized for its pioneering role in graphics processing units (GPUs) and AI computing. The company’s neural processing capabilities are primarily driven by its Tensor Core GPUs, which are optimized for deep learning training and inference. NVIDIA Corporation’s dedicated AI platform, including the NVIDIA Jetson and Drive series, integrates neural processors to enable real-time AI at the edge and in autonomous systems. Additionally, its CUDA and cuDNN software ecosystems support scalable deployment of neural networks across industries.
Key Neural Processor Companies:
The following key companies have been profiled for this study on the neural processor market.
-
Advanced Micro Devices, Inc.
-
Arm Limited
-
Aspinity, Inc.
-
Bitbrain Technologies
-
BrainChip, Inc.
-
BrainCo, Inc.
-
General Vision, Inc.
-
Google LLC
-
Halo Neuroscience
-
Intel Corporation
-
NVIDIA Corporation
-
Qualcomm Inc.
-
Samsung Electronics Co. Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players: Advanced Micro Devices, Inc.; Arm Limited; Google LLC; Intel Corporation; NVIDIA Corporation; Qualcomm Inc.; Samsung Electronics Co., Ltd.
- Focus on developing high-performance neural processors, AI accelerators, and heterogeneous computing architectures for edge and cloud AI applications. These companies invest heavily in advanced semiconductor manufacturing, AI software ecosystems, chip design innovations, and strategic collaborations with OEMs, cloud service providers, and automotive manufacturers to expand AI capabilities across consumer electronics, data centers, autonomous vehicles, and industrial automation.
- Strong global market presence, extensive semiconductor expertise, robust R&D capabilities, advanced fabrication technologies, comprehensive AI hardware and software ecosystems, established customer relationships, and large-scale manufacturing and distribution networks
- High R&D and fabrication costs, dependence on advanced semiconductor foundries, supply chain disruptions, geopolitical risks, rapid technology evolution, and intense competition from both established chipmakers and emerging AI hardware companies.
Emerging Players: Aspinity, Inc.; Bitbrain Technologies; BrainChip, Inc.; BrainCo, Inc.; General Vision, Inc.; Halo Neuroscience
- Focus on developing specialized low-power neural processors, neuromorphic computing platforms, edge AI chips, and AI-enabled brain-computer interface (BCI) technologies for robotics, IoT, healthcare, wearable devices, and industrial automation. These companies emphasize innovation in energy-efficient AI processing, event-driven computing, and application-specific AI hardware to address emerging intelligent edge computing requirements.
- Strong innovation capabilities, expertise in neuromorphic computing and edge AI, agile product development, differentiated AI architectures, low-power processing technologies, and the ability to address niche AI applications with optimized performance.
- Limited manufacturing scale, smaller customer base, dependence on external fabrication partners and strategic collaborations, constrained financial resources compared to leading semiconductor vendors, and challenges in achieving broad commercial adoption and global market expansion.
Recent Developments
-
In May 2025, Semidynamics introduced Cervell, a fully programmable and scalable Neural Processing Unit (NPU) built on the open RISC-V architecture. Combining tensor processing and CPU vector in a unified design, Cervell delivers up to 256 TOPS and supports configurations from C8 to C64, catering to both edge AI and datacenter-scale applications like large language models.
-
In March 2025, Allegro DVT introduced its first AI-based Neural Video Processing IP, the NVP300, showcasing its commitment to advancing video processing with AI technologies. The NVP300 enables real-time 4K video processing through an optimized hardware design, ensuring high performance within minimal silicon area and power consumption. Tailored for embedded applications, the solution reflects Allegro DVT’s strategic move toward integrating AI for enhanced video quality.
-
In September 2024, Intel Corporation released its Core Ultra 200V processors, which are the company's most power-efficient laptop chips to date. The chips include a neural processing unit optimized for running artificial intelligence models, which is four times faster than the previous generation. This new architecture enhances overall efficiency while maximizing computational power.
-
In June 2024, Advanced Micro Devices Inc. introduced its artificial intelligence processors, including the MI325X accelerator, at the Computex technology trade show. The company also detailed its new neural processing units (NPUs), designed to handle on-device AI tasks in AI PCs, as part of a broader strategy to enhance its product lineup with significant performance improvements. The MI350 series is expected to achieve 35 times better inference capabilities compared to its predecessors.
Neural Processor Market Report Scope
Report Attribute
Details
Market size in 2025
USD 334.0 million
Estimated market size in 2026
USD 397.2 million
Projected market size by 2033
USD 1,424.4 million
Growth rate
CAGR of 20.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Operation, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; Japan; India; South Korea; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
Advanced Micro Devices, Inc.; Arm Limited, Aspinity, Inc.; Bitbrain Technologies; BrainChip, Inc.; BrainCo, Inc.; General Vision, Inc.; Google LLC; Halo Neuroscience; Intel Corporation; NVIDIA Corporation; Qualcomm Inc.; Samsung Electronics Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Neural Processor Market Report Segmentation
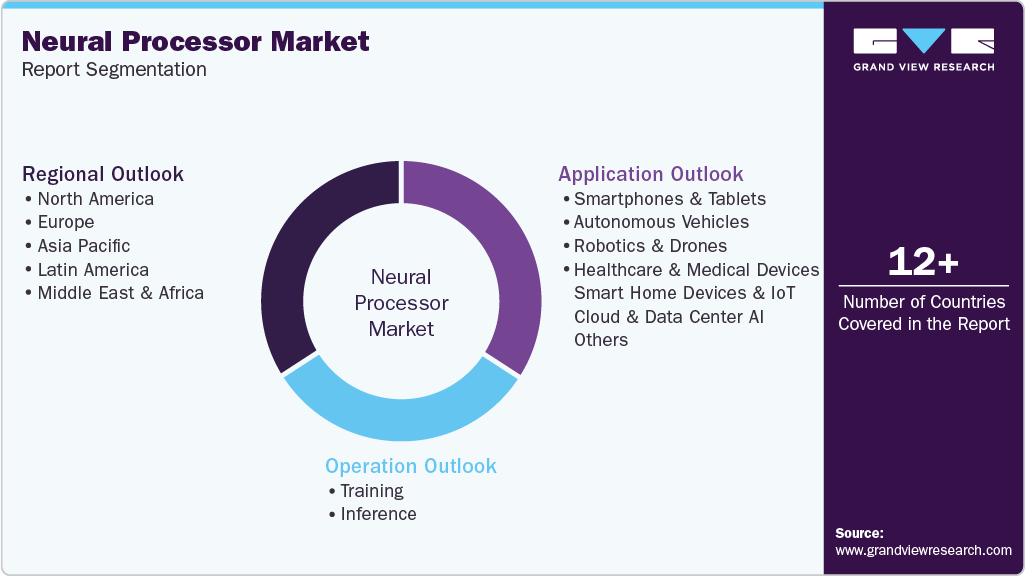
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global neural processor market report based on operation, application, and region:
-
Operation Outlook (Revenue, USD Million, 2021 - 2033)
-
Training
-
Inference
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Smartphones and Tablets
-
Autonomous Vehicles
-
Robotics and Drones
-
Healthcare and Medical Devices
-
Smart Home Devices and IoT
-
Cloud and Data Center AI
-
Industrial Automation
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The neural processor market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each neural processor segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Operation
Revenue capture definition
Training
Revenue in this segment is generated through the development and optimization of neural processor training technologies that enable AI models to learn from large datasets and improve their accuracy and performance. These technologies leverage high-performance neural processing units (NPUs), AI accelerators, and parallel computing architectures to efficiently train deep learning, machine learning, computer vision, and natural language processing (NLP) models.
Inference
Revenue in this segment is generated through the deployment and execution of trained AI models on neural processors to perform real-time predictions and decision-making across a wide range of applications. Neural processors accelerate AI inference workloads by efficiently processing tasks such as image and speech recognition, natural language processing (NLP), object detection, recommendation engines, and generative AI while minimizing latency and power consumption. These processors are extensively integrated into smartphones, personal computers, autonomous vehicles, IoT devices, industrial equipment, healthcare systems, and edge computing platforms to enable fast, secure, and energy-efficient on-device AI processing without relying heavily on cloud infrastructure.
Segment - Application
Revenue capture definition
Smartphones and Tablets
Revenue in this segment is generated through the integration of neural processors into smartphones and tablets to enable on-device artificial intelligence (AI) capabilities and enhance overall device performance. Neural processors accelerate AI workloads such as image and video processing, computational photography, facial recognition, voice assistants, natural language processing (NLP), real-time translation, augmented reality (AR), and generative AI applications while optimizing power efficiency and reducing latency
Autonomous Vehicles
Revenue in this segment is generated through the integration of neural processors into autonomous and advanced driver-assistance system (ADAS) vehicles to enable real-time artificial intelligence (AI) processing for safe and intelligent driving. Neural processors accelerate workloads such as object detection, sensor fusion, lane detection, traffic sign recognition, driver monitoring, path planning, and decision-making by efficiently processing data from cameras, LiDAR, radar, and other onboard sensors.
Robotics and Drones
Revenue in this segment is generated through the deployment of neural processors in robots and drones to enable real-time artificial intelligence (AI) capabilities, autonomous decision-making, and intelligent navigation. Neural processors accelerate AI workloads such as computer vision, object detection, simultaneous localization and mapping (SLAM), motion planning, obstacle avoidance, speech recognition, and predictive analytics while delivering low-latency, energy-efficient processing.
Healthcare and Medical Devices
Revenue in this segment is generated through the integration of neural processors into healthcare systems and medical devices to enable real-time artificial intelligence (AI) processing for clinical decision support, diagnostics, and patient monitoring. Neural processors accelerate AI workloads such as medical image analysis, disease detection, predictive analytics, speech recognition, patient data processing, and remote monitoring while ensuring low-latency and energy-efficient performance.
Smart Home Devices and IoT
Revenue in this segment is generated through the integration of neural processors into smart home devices and Internet of Things (IoT) systems to enable real-time artificial intelligence (AI) processing and intelligent automation. Neural processors accelerate AI workloads such as voice recognition, facial recognition, gesture detection, anomaly detection, predictive maintenance, and environmental monitoring while delivering low-latency, energy-efficient on-device processing
Estimation Model
Layer Name
Key Question
Description
Addressable End-user Base Layer
Which industries generate demand for neural processors?
Identify the global addressable base of industries adopting neural processors to accelerate AI workloads. Include consumer electronics manufacturers, automotive OEMs, healthcare providers, industrial automation companies, robotics manufacturers, cloud service providers, telecommunications companies, aerospace & defense organizations, and smart home and IoT device manufacturers deploying AI-enabled products and intelligent computing systems.
Application Layer
Which AI applications drive neural processor adoption?
Assess demand across key applications including AI inference, AI model training, computer vision, natural language processing (NLP), speech recognition, facial recognition, autonomous driving, predictive maintenance, robotics, edge AI, generative AI, recommendation systems, and intelligent analytics deployed across edge devices and cloud environments.
Technology Adoption Layer
How extensively are neural processors utilized?
Estimate technology adoption based on the deployment of neural processing units (NPUs), AI accelerators, neuromorphic processors, tensor processing architectures, edge AI processors, heterogeneous computing platforms, and low-power AI chipsets integrated into smartphones, AI PCs, autonomous vehicles, medical devices, robotics, IoT devices, industrial equipment, and data center infrastructure.
Revenue Generation Layer
How much revenue is generated?
Calculate market revenue by assessing shipments and sales of neural processors, AI accelerator chips, integrated system-on-chip (SoC) solutions, development platforms, and associated software ecosystems. Revenue is generated through processor sales, semiconductor licensing, AI software development kits (SDKs), hardware integration, system design services, firmware, maintenance, and strategic partnerships supporting AI inference.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Intelligence & Market Positioning Assessment
Performed an in-depth evaluation of major neural processor manufacturers, semiconductor companies, AI accelerator developers, and neuromorphic computing vendors. Assessed market positioning, processor architectures, AI computing capabilities, product portfolios, strategic partnerships, technology innovations, acquisitions, manufacturing capabilities, regional presence, and recent developments across the neural processor ecosystem.
Enables stakeholders to identify key market participants, benchmark competitive positioning, evaluate technology capabilities, assess strategic partnerships and acquisition opportunities, and gain insights into the evolving competitive landscape of the Neural Processor Market.
End-user Demand Patterns & Application-Specific Analysis
Analyzed adoption trends across key applications including AI training, AI inference, computer vision, natural language processing (NLP), generative AI, robotics, autonomous vehicles, healthcare, industrial automation, smartphones, AI PCs, and smart IoT devices. Evaluated deployment patterns, investment priorities, AI hardware requirements, and technology adoption across consumer electronics, automotive, healthcare, manufacturing, cloud computing, and telecommunications industries.
Provides actionable insights into end-user demand, application-specific adoption trends, emerging growth opportunities, and investment priorities, supporting informed decisions related to product development, market expansion, technology investments, and commercialization strategies.
Technology Advancements & Future Growth Potential Evaluation
Assessed the impact of neural processing units (NPUs), AI accelerators, neuromorphic computing, heterogeneous computing architectures, edge AI, advanced semiconductor manufacturing technologies, and next-generation AI chip designs on market development. Identified emerging innovation areas, evolving AI workloads, and high-growth opportunities across edge computing, cloud AI infrastructure, autonomous systems, and intelligent devices.
Supports long-term strategic planning by identifying attractive investment opportunities, prioritizing semiconductor and AI hardware innovation, uncovering future revenue streams, and understanding the key technological trends shaping the evolution of the Neural Processor Market
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region with a CAGR of 22.4% from the forecast period of 2026 to 2033.
Inference leads the operation segment with revenue share of 66.1% in 2025 & is the fastest growing operation segment in the market.
Smartphones and tablets lead the end use segment with a revenue share of 23.8% in 2025, while autonomous vehicles is the fastest-growing end use segment in the region.
The U.S. leads the North America region with a revenue share of 68.6% in 2025, while Canada is the fastest-growing country in the market.
The global neural processor market is expected to grow at a CAGR of 20.0% from 2026 to 2033, reaching USD 1,424.4 million by 2033.
North America dominated the neural processor market with a revenue share of 33.9% in 2025. This is attributable to its strong adoption of advanced technologies, significant investments from key players in the AI sector, and the increasing demand for neural processors across various industries, including healthcare, finance, and retail.
The global neural processor market size was valued at USD 334.0 million in 2025 and is estimated at USD 397.2 million for 2026.
Some key players operating in the neural processor market include Advanced Micro Devices Inc., Arm Limited, Aspinity, Inc., Bitbrain Technologies, BrainChip, Inc., BrainCo, Inc., General Vision, Inc., Google LLC, Halo Neuroscience, Intel Corporation, NVIDIA Corporation, Qualcomm Inc., and Samsung Electronics Co. Ltd.
Key factors that are driving the market growth include the increasing demand for artificial intelligence applications across various industries, advancements in machine learning algorithms, and the proliferation of edge computing technologies.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs — add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


