
- Home
- »
- Advanced Interior Materials
- »
-
Nickel Pig Iron Market Size & Share Report, 2026-2033GVR Report cover

Nickel Pig Iron Market (2026 - 2033)
Size, Share & Trends Analysis Report By Grade (Low-grade, Medium-grade, High-grade), By End-use (Building & Construction, Automotive & Transportation), By Region, And Segment Forecasts
Market Size, 2025
$18.8BMarket Estimate, 2026
$19.5BMarket Forecast, 2033
$28.9BCAGR, 2026–2033
5.8%Nickel Pig Iron Market Summary
The global nickel pig iron market size was valued at USD 18.8 billion in 2025 and is projected to grow from USD 19.5 billion in 2026 to USD 28.9 billion by 2033, at a CAGR of 5.8% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 79.1% in 2025. Nickel pig iron (NPI) is a low-cost, high-impurity nickel alloy primarily used in stainless steel production.
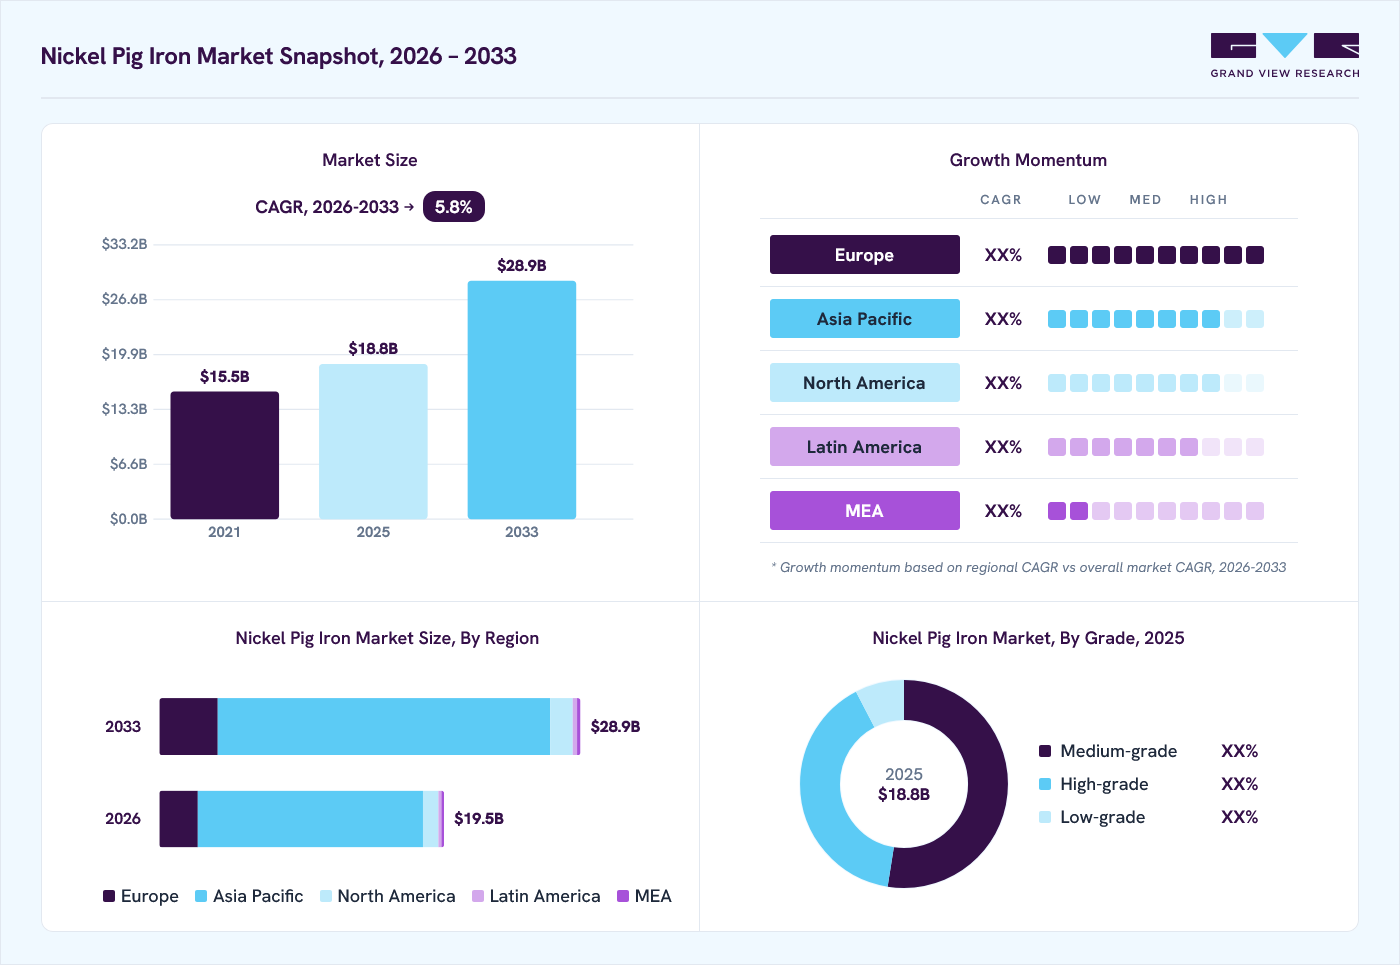 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By end use: Consumer goods segment led the market with the largest revenue share of 38.3% in 2025.
- By grade: Medium-grade segment led the market with the largest revenue share of 52.5% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (79.1% revenue share, 2025)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 18.8 Billion
- Estimated market size in 2026: USD 19.5 Billion
- Projected market size by 2033: USD 28.9 Billion
- CAGR (2026-2033): 5.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
It is anticipated to remain a key substitute for refined nickel, particularly in China and Indonesia. Production is expected to be driven by abundant laterite ore reserves and increasing smelting capacities. Prices are likely to be influenced by Indonesian export policies and shifts in global stainless steel demand. Environmental concerns and carbon footprint considerations are anticipated to shape future investment in NPI processing technologies.
Nickel pig iron (NPI) is a low-grade ferro-nickel alloy primarily used in stainless steel manufacturing due to its cost advantages over refined nickel. Its production relies on laterite nickel ore, predominantly sourced from Indonesia and the Philippines, where abundant reserves support large-scale smelting operations. The rise of NPI has reshaped the global nickel market, particularly by reducing dependence on traditional Class 1 nickel. As a result, it has become a key component in meeting the rising stainless steel demand, particularly in China, the world's largest producer and consumer.
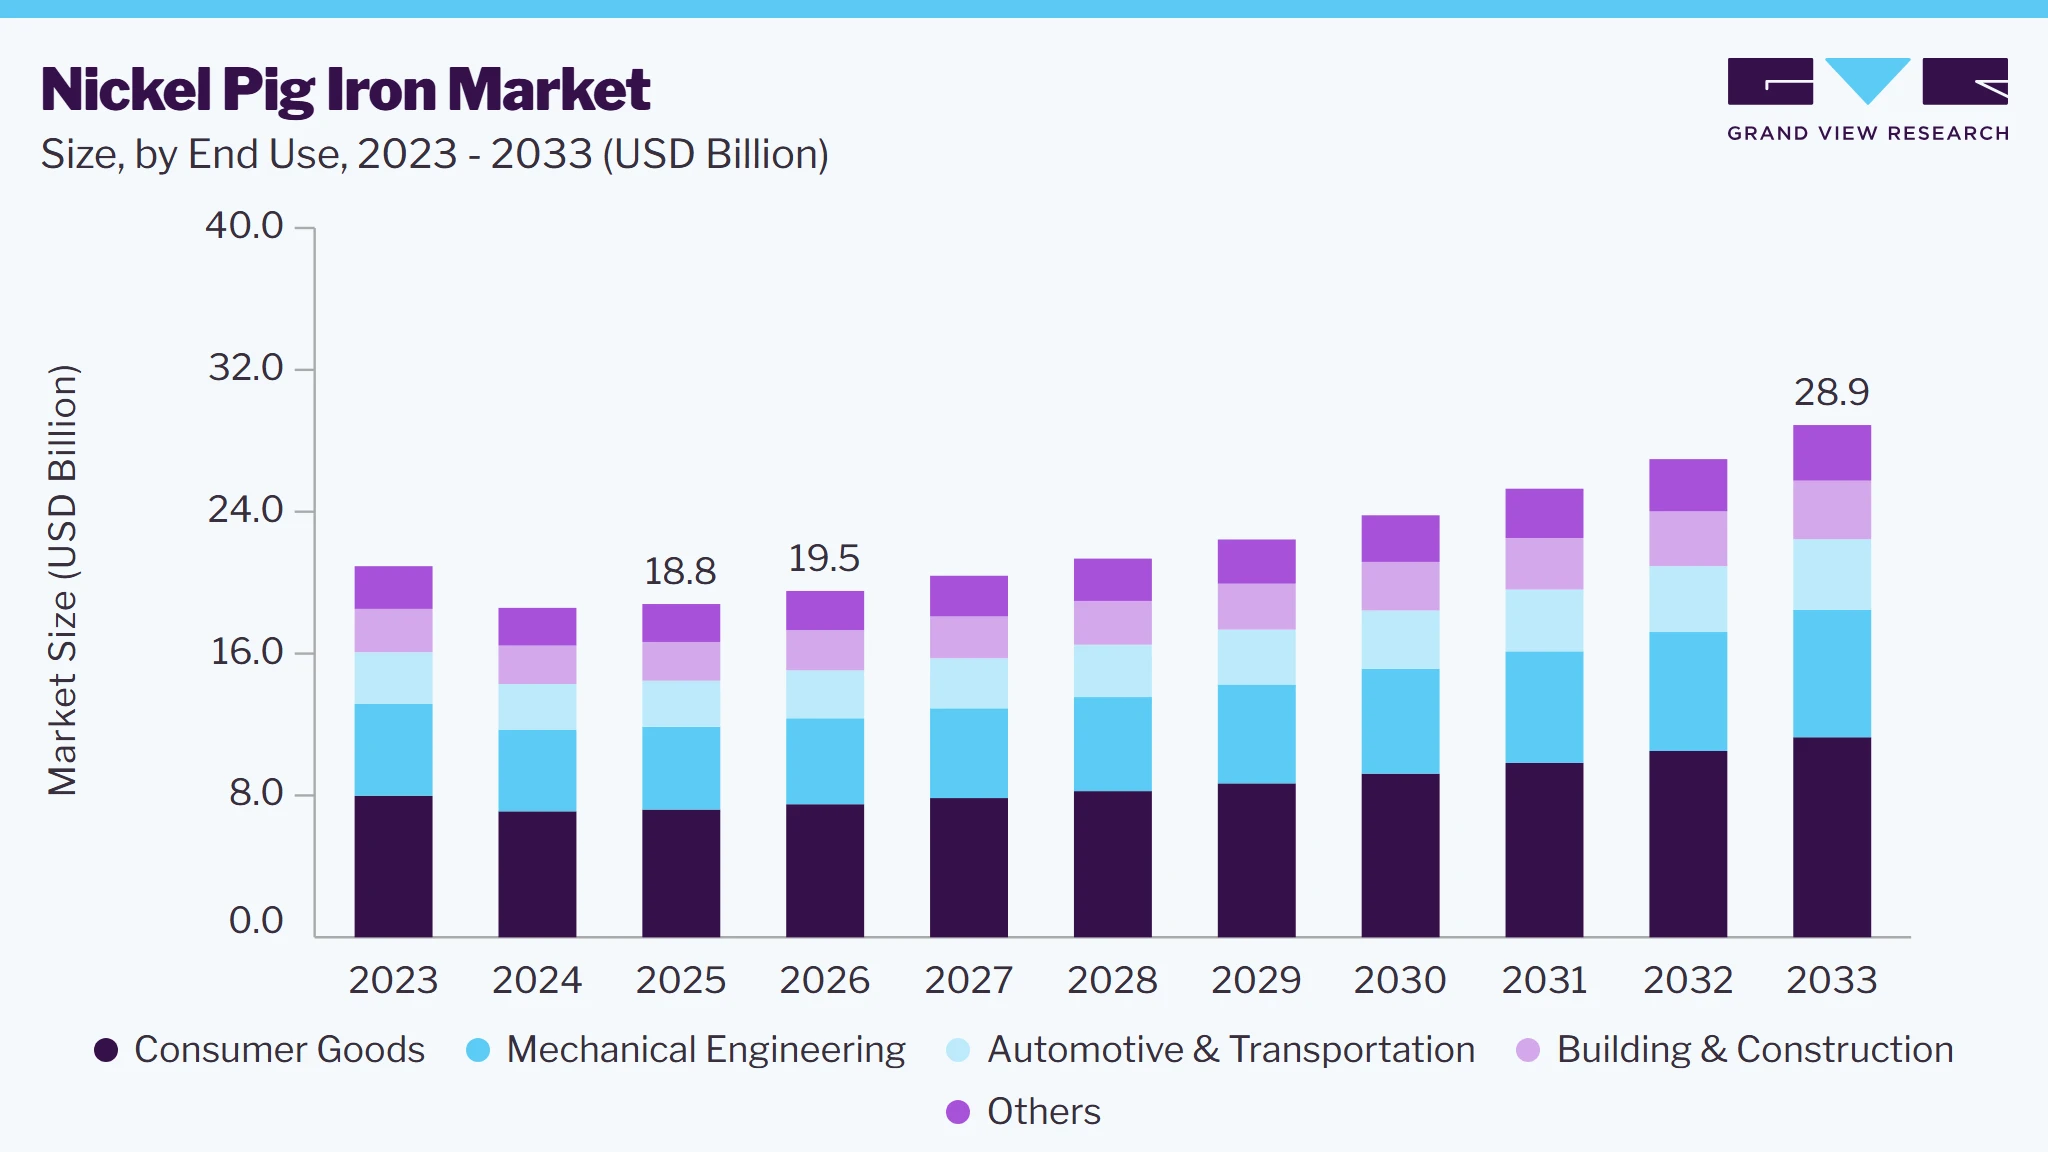 To learn more about this report, Download Free Sample Report
The global nickel pig iron industry is expected to evolve with shifting supply dynamics, regulatory changes, and technological advancements. Indonesia, having imposed a nickel ore export ban, is projected to maintain its dominance in NPI production, encouraging investments in domestic processing facilities. Meanwhile, technological improvements in smelting and refining are anticipated to enhance production efficiency and reduce environmental impact.
Market Dynamics
The growth of the nickel pig iron (NPI) market is primarily driven by the sustained expansion of the global stainless steel industry, which accounts for the majority of NPI consumption. Nickel pig iron serves as a cost-effective alternative to refined nickel in the production of austenitic stainless steel, enabling manufacturers to reduce raw material costs while maintaining required performance characteristics. Rising investment in residential, commercial, and industrial construction, along with increasing demand for durable, corrosion-resistant stainless steel products in transportation, consumer goods, and infrastructure projects, continues to support NPI consumption. Strong stainless steel production in China, Indonesia, and other Asian economies continues to be a major contributor to market growth.
The increasing production of stainless steel is one of the most significant growth drivers for the NPI market. Nickel pig iron is widely used as a cost-effective source of nickel in the production of austenitic stainless steel, which accounts for the largest share of global stainless steel output. As demand for stainless steel continues to rise across construction, automotive, industrial machinery, consumer appliances, and food processing equipment, steel manufacturers are expanding production capacities and increasing their use of NPI to optimize raw material costs. The ability of NPI to replace a substantial portion of refined nickel in stainless steel manufacturing has made it an essential feedstock, particularly in regions where cost competitiveness is a key factor.
The rapid expansion of stainless steel production in the Asia Pacific, especially in China and Indonesia, has further accelerated demand for nickel pig iron. Growing investments in infrastructure development, urban housing, transportation networks, renewable energy projects, and manufacturing facilities are increasing demand for stainless steel in corrosion-resistant and high-strength applications. At the same time, stainless steel producers are seeking reliable, economical sources of nickel to improve profitability amid fluctuations in global nickel prices. This combination of rising stainless steel output, expanding industrial applications, and the continued preference for cost-effective raw materials is expected to sustain strong demand for nickel pig iron over the coming years.
Changes in mining regulations, export restrictions, royalty policies, weather related disruptions, and geopolitical uncertainties in key producing countries such as Indonesia and the Philippines can significantly affect ore availability and pricing. These fluctuations increase production costs, reduce profit margins for smelters, and create uncertainty in long term procurement strategies. In addition, inconsistent raw material supply can disrupt production schedules and limit capacity utilization, making it difficult for manufacturers to maintain stable output and competitive pricing in the global nickel pig iron market.
Rapid industrialization, urbanization, and infrastructure development across countries in Asia, Africa, Latin America, and the Middle East are driving investments in new stainless steel production facilities and capacity expansions. As manufacturers seek cost-efficient raw materials to remain competitive, nickel pig iron is increasingly being adopted as an economical substitute for refined nickel in stainless steel production. Government initiatives supporting domestic manufacturing, rising foreign direct investment, and growing demand for stainless steel in construction, transportation, consumer goods, and industrial equipment are expected to further strengthen NPI consumption and create long-term growth opportunities for producers.
Analyst Perspective
The nickel pig iron market is expected to witness steady long-term growth, supported by the continued expansion of global stainless steel production and the increasing need for cost-effective nickel-bearing raw materials. Nickel pig iron has become a preferred alternative to refined nickel, particularly in the Asia Pacific, where large-scale stainless steel manufacturing continues to drive demand. Rapid urbanization, infrastructure development, industrial expansion, and rising consumption of stainless steel across construction, consumer goods, automotive, and mechanical engineering applications are expected to strengthen market fundamentals.
End-use Insights
Based on end use, consumer goods segment led the market with the largest revenue share of 38.3% in 2025. The consumer goods sector, which includes appliances, kitchenware, and decorative stainless steel products, is likely to contribute steadily to global NPI demand. Rising disposable incomes and increasing preference for durable, corrosion-resistant products are expected to support stainless steel usage, benefiting NPI consumption. Expanding middle-class populations, particularly in Asia, are projected to drive market expansion.
The building and construction industry is expected to remain a significant consumer of nickel pig iron (NPI), driven by its role in stainless steel production for structural components, roofing, and cladding. Rapid urbanization and infrastructure development in emerging economies are projected to sustain demand for stainless steel, indirectly supporting NPI consumption.
Grade Insights
Medium-grade segment led the market with the largest revenue share of 52.5% in 2025. The medium-grade nickel pig iron (NPI) segment, typically containing 8-12% nickel, is expected to remain a crucial choice for stainless steel manufacturers seeking a balance between cost and performance. Its production is anticipated to be driven by increasing investments in advanced smelting technologies that enhance nickel recovery from laterite ores.
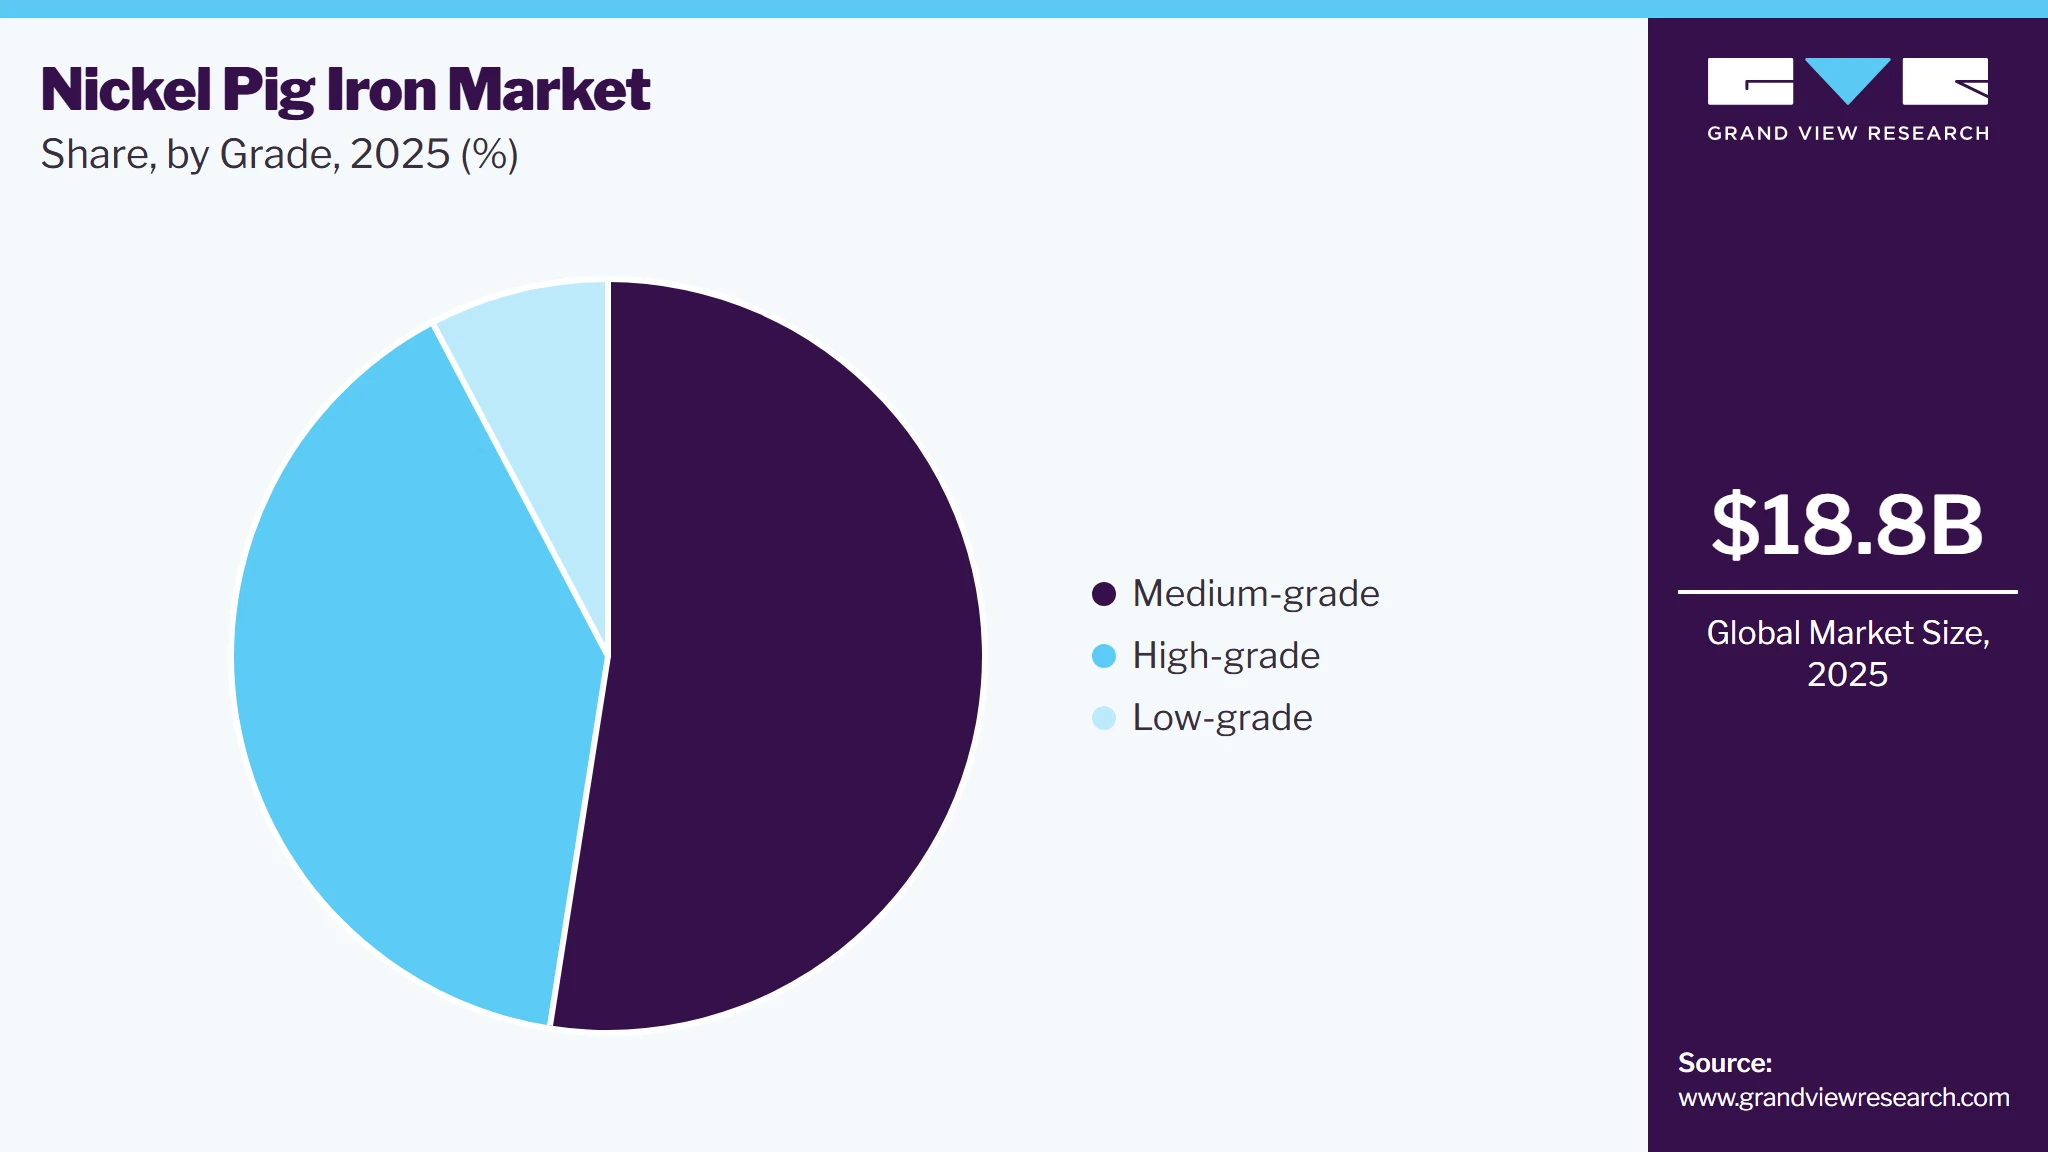 To learn more about this report, Download Free Sample Report
Low-grade NPI, with nickel content below 8%, is likely to retain relevance as a cost-effective alternative for lower-end stainless steel applications. Its affordability is expected to support continued adoption, particularly in price-sensitive markets. Potential shifts toward higher-nickel-content materials in response to evolving steel quality requirements could limit long-term demand growth for this segment.
Regional Insights
The nickel pig iron market in North America is anticipated to grow at the fastest CAGR during the forecast period. North America’s NPI consumption is projected to remain limited due to its preference for high-purity Class 1 nickel and limited domestic production. The United States and Canada primarily rely on stainless steel imports, with the region consuming approximately 2.5 million metric tons of stainless steel annually.
Asia Pacific Nickel Pig Iron Market Trends
Asia Pacific dominated the nickel pig iron market with the largest revenue share of 79.1% in 2025, driven by strong stainless steel demand and significant production capacities. Indonesia and China collectively accounted for over 95% of global NPI output in 2023, reinforcing the region’s leadership.
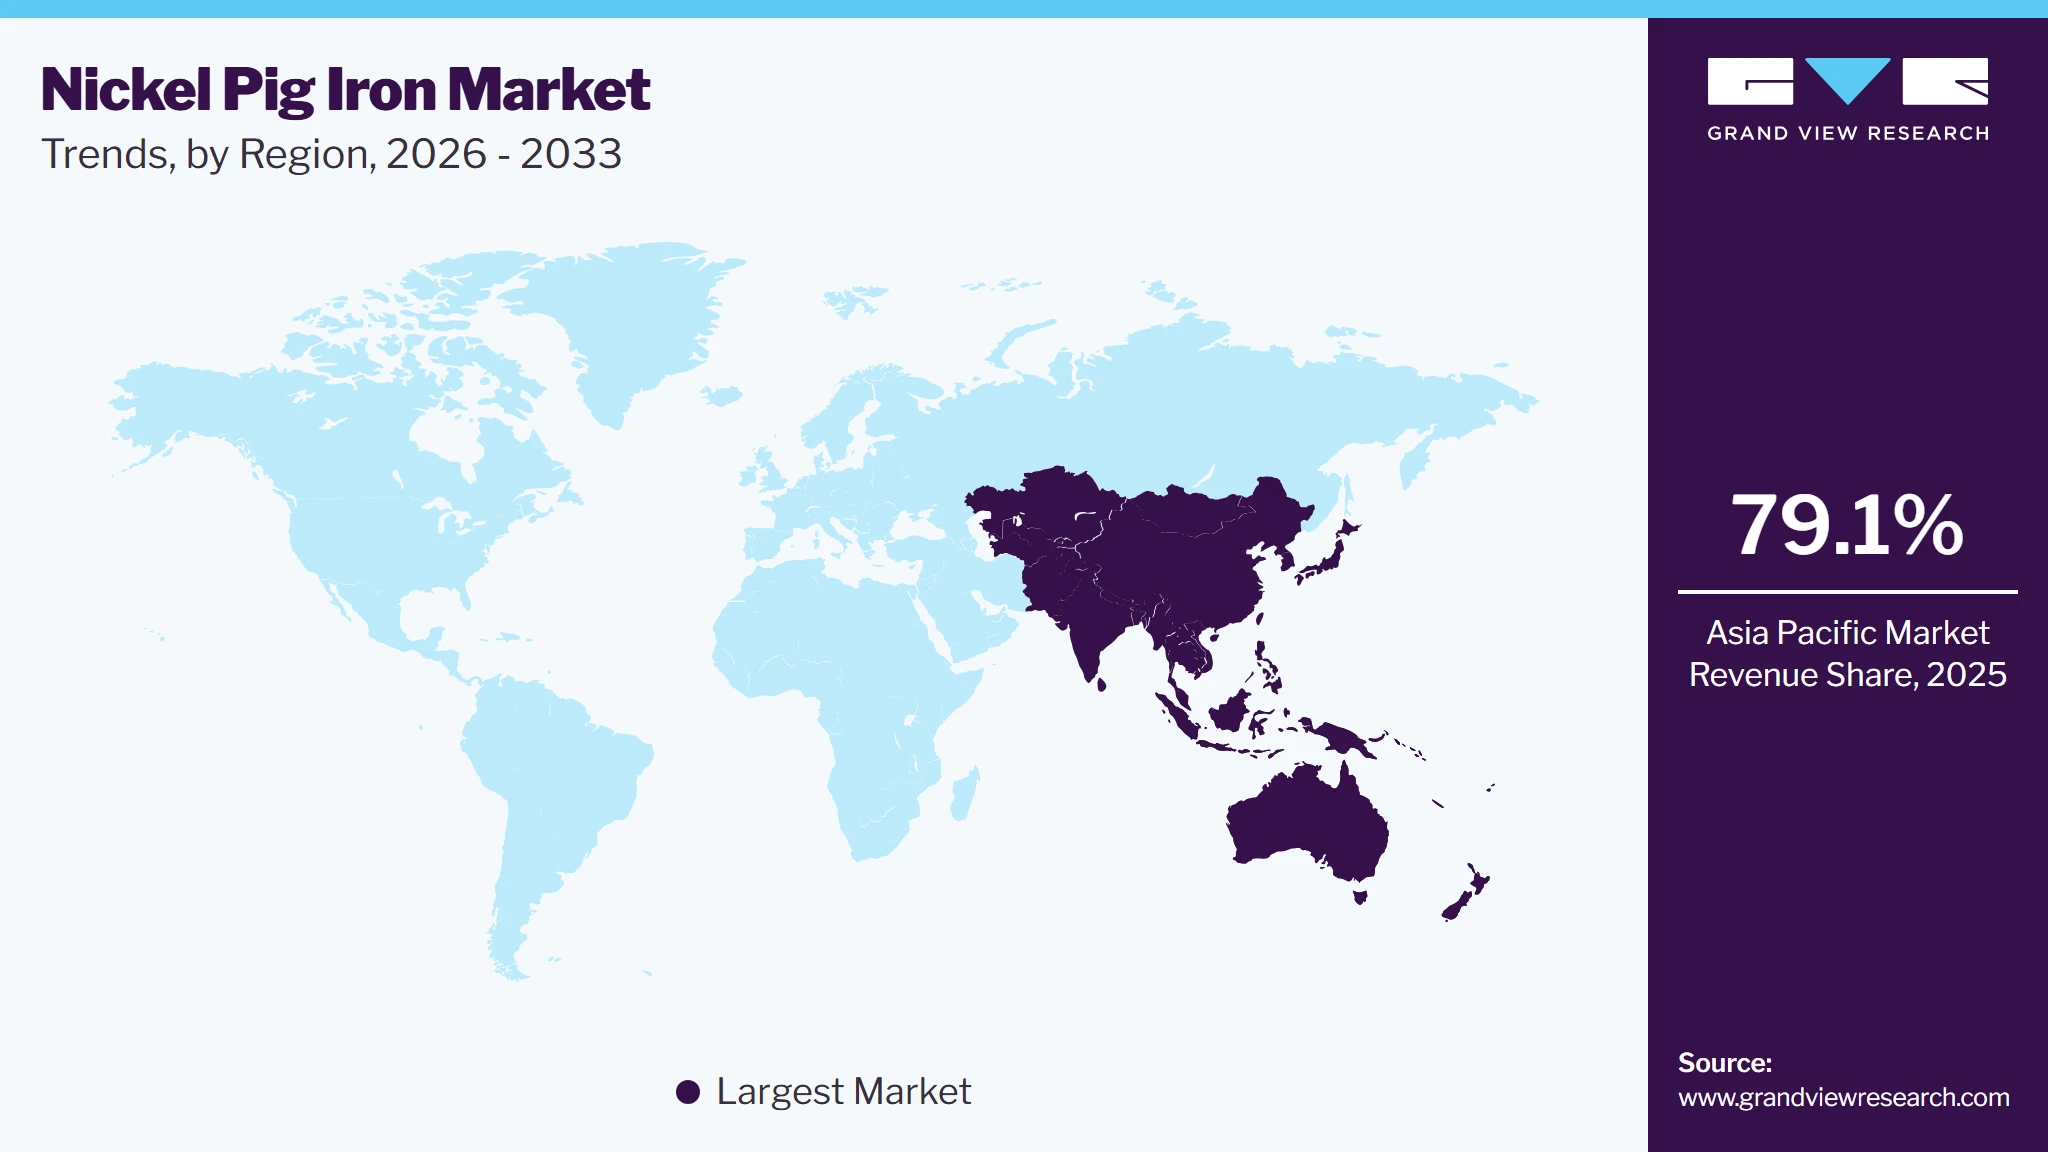 To learn more about this report, Download Free Sample Report
The nickel pig iron market in the China held the largest share in the Asia Pacific region in 2025. China, the world’s largest stainless steel producer, is expected to remain the dominant consumer of NPI, with annual stainless steel output exceeding 30 million metric tons in recent years. Domestic NPI production has been gradually declining due to stricter environmental policies, prompting increased reliance on Indonesian imports.
The Indonesia nickel pig iron market is anticipated to grow at a significant CAGR during the forecast period. Indonesia has emerged as the leading NPI producer, with output exceeding 1.5 million metric tons in 2023, following the country’s nickel ore export ban. Large-scale investments in smelting projects, including those backed by Chinese firms, are anticipated to drive further growth.
Europe Nickel Pig Iron Market Trends
The nickel pig iron market in Europe is anticipated to grow at a substantial CAGR during the forecast period. Europe’s NPI market is expected to remain constrained, as the region prioritizes sustainable and low-carbon nickel sources. The European Union’s stringent environmental regulations and carbon border tax mechanisms are projected to limit imports from high-emission producers.
Key Nickel Pig Iron Company Insights
Some of the key players operating in the market include Eramet, Tsingshan Group, and Nickel Industries Limited.
-
Nickel Industries Limited, listed on the Australian Securities Exchange, is a significant producer of nickel pig iron (NPI) and nickel matte, essential for stainless steel manufacturing and the electric vehicle supply chain.
-
Tsingshan Group, the world’s largest stainless steel producer, is a leading player in the global nickel pig iron (NPI) market, with extensive operations in Indonesia. The company has developed large-scale NPI smelting facilities in Morowali and Weda Bay, significantly contributing to Indonesia’s dominance in nickel production.
Key Nickel Pig Iron Companies
The following key companies have been profiled for this study on the nickel pig iron market.
-
Eramet
-
New Yaking Pte. Ltd
-
Nickel Industries Limited
-
PT MERDEKA BATTERY MATERIALS TBK
-
PT. Growth Java Industry
-
PT. Gunbuster Nickel Industry (GNI)
-
Shandong Xinhai
-
Tsingshan Group
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g. Tsingshan Group, Nickel Industries Limited)
- Mature participants in the nickel pig iron (NPI) market primarily focus on vertically integrated operations that combine laterite nickel mining, ferronickel smelting, nickel pig iron production, and downstream stainless steel manufacturing.
- These companies emphasize securing long term nickel ore supplies through captive mining assets and strategic procurement agreements while optimizing blast furnace and rotary kiln electric furnace operations.
- Established players possess significant competitive advantages through their integrated mining and smelting operations, extensive production capacities, and secure access to laterite nickel ore resources.
- Their control over the upstream supply chain enables greater cost stability, improved raw material security, and consistent nickel pig iron quality.
- Despite their strong market positions, mature players face challenges related to fluctuations in nickel ore prices, energy costs, and environmental compliance requirements.
- Nickel pig iron production is highly energy intensive and requires substantial investments in furnaces, pollution control systems, and supporting infrastructure.
Emerging & Regional Players (e.g., PT Growth Java Industry, New Yaking Pte. Ltd.)
- Emerging participants in the nickel pig iron market generally focus on developing regional smelting capacity, improving production efficiency, and securing strategic nickel ore supplies.
- Rather than competing directly with established producers on production scale, these companies emphasize modern furnace technologies, localized manufacturing, and partnerships with stainless steel producers.
- Emerging companies benefit from operational flexibility and the ability to establish production facilities using modern smelting technologies without extensive legacy infrastructure.
- Their newer plants often incorporate advanced automation, digital monitoring systems, and energy efficient equipment that improve productivity, reduce operating costs, and support compliance with evolving environmental standards.
- Emerging participants face significant challenges related to limited production capacity, restricted financial resources, and dependence on external nickel ore suppliers.
- Competing against established producers with integrated mining operations, extensive smelting infrastructure, and long standing customer relationships can be difficult, particularly during periods of nickel price volatility.
Recent Developments
- In March 2023, Jindal Stainless Limited, an India-based stainless steel producer, announced an agreement with New Yaking Pte. Ltd for the construction of a nickel pig iron facility in Indonesia. Under this agreement, Jindal acquired 49% equity stakes at USD 157 million.
Nickel Pig Iron Market Report Scope
Report Attribute
Details
Market definition
The market size represents the apparent consumption of nickel pig iron-in various applications.
Market size in 2025
USD 18.8 billion
Estimated market size in 2026
USD 19.5 billion
Projected market size by 2033
USD 28.9 billion
Growth rate
CAGR of 5.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, and region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; Italy; Spain; China; India; Japan; South Korea; Brazil
Key companies profiled
Tsingshan Group; Nickel Industries Limited; PT MERDEKA BATTERY MATERIALS TBK; PT. Growth Java Industry; PT. Gunbuster Nickel Industry (GNI); New Yaking Pte. Ltd; Shandong Xinhai; Eramet
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Nickel Pig Iron Market Report Segmentation
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global nickel pig iron market report based on the grade, end-use, and region.
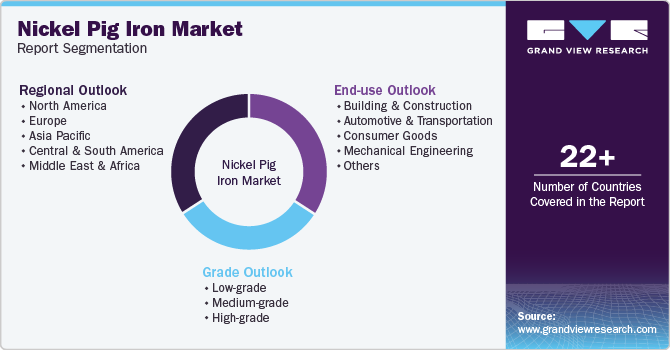 To learn more about this report, Download Free Sample Report
-
Grade Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Low-grade
-
Medium-grade
-
High-grade
-
-
End-use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Building & Construction
-
Automotive & Transportation
-
Consumer Goods
-
Mechanical Engineering
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
-
Research Methodology
The nickel pig iron market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each nickel pig iron segment quantified using the revenue-capture definitions in the table below.
Segment Definition
End Use
Revenue Capture Definition
Building & Construction
The building and construction segment captures revenue generated from nickel pig iron used in the production of stainless steel for structural components, reinforcement materials, roofing, cladding, piping, and architectural applications.
Automotive & Transportation
The automotive and transportation segment represents revenue generated from nickel pig iron used in stainless steel production for vehicle exhaust systems, structural components, rail infrastructure, commercial vehicles, and marine applications.
Consumer Goods
The consumer goods segment includes revenue generated from nickel pig iron used in manufacturing stainless steel for household appliances, kitchenware, cookware, furniture, and consumer electronics. Nickel pig iron provides an economical raw material for producing corrosion resistant stainless steel products with long service life and aesthetic appeal.
Mechanical Engineering
The mechanical engineering segment captures revenue generated from nickel pig iron used in the production of stainless steel components for industrial machinery, manufacturing equipment, pumps, valves, fasteners, and process engineering systems.
Others
The others segment represents revenue generated from nickel pig iron used in stainless steel production for industries such as energy, chemical processing, food processing, healthcare, aerospace, and marine engineering. These applications require stainless steel with excellent mechanical strength, corrosion resistance, and long term reliability.
Grade
Revenue Capture Definition
Low-grade
The low grade segment captures revenue generated from nickel pig iron containing relatively low nickel content, typically used in the production of cost competitive stainless steel for general purpose applications. This grade offers an economical alternative to refined nickel in large volume steelmaking processes.
Medium-grade
The medium grade segment represents revenue generated from nickel pig iron with moderate nickel content, providing a balance between cost efficiency and metallurgical performance. It is widely used in the production of a broad range of stainless steel grades for industrial, construction, and consumer applications.
High-grade
The high grade segment includes revenue generated from nickel pig iron with higher nickel content, offering improved alloying efficiency and superior metallurgical characteristics for premium stainless steel production.
Estimation Model
Layer Name
Key Question
Description
Stainless Steel Demand Base Layer
What forms the demand base?
Identify global demand from major stainless steel consuming industries including building & construction, automotive, consumer goods, industrial machinery, energy, and transportation. Assess stainless steel production volumes, infrastructure investments, and manufacturing activity to establish the total addressable demand for nickel pig iron as a primary nickel bearing raw material.
Nickel Pig Iron Application Penetration Layer
Where is nickel pig iron utilized?
Estimate the penetration of nickel pig iron across key applications including austenitic stainless steel production, alloy steel manufacturing, and specialty steel applications. Analyze the adoption of low grade, medium grade, and high grade nickel pig iron across electric arc furnaces and integrated stainless steel manufacturing facilities in different regions.
Nickel Pig Iron Consumption Intensity Layer
How much nickel pig iron is consumed?
Analyze nickel pig iron consumption intensity based on stainless steel production volumes, nickel content requirements, steel grade specifications, and production technologies. Evaluate NPI usage as a substitute for refined nickel and ferronickel in stainless steel manufacturing. Consumption intensity varies according to nickel prices, alloy composition, furnace technology, and raw material availability.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of low grade, medium grade, and high grade nickel pig iron supplied to stainless steel and alloy steel manufacturers. Revenue generation is driven by stainless steel production, nickel demand, and the cost competitiveness of NPI compared with refined nickel products. Market value is influenced by nickel ore prices, energy costs, nickel content, production volumes, and regional supply demand dynamics.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed regional analysis of the nickel pig iron (NPI) market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. Included evaluation of NPI production capacity, laterite nickel ore availability, stainless steel manufacturing, electric arc furnace investments, import dependency, government mining policies, and downstream stainless steel demand influencing regional market dynamics.
Identified major NPI production hubs, stainless steel manufacturing centers, and emerging demand regions. Enabled strategic expansion planning based on nickel resource availability, steel production growth, and regional investment trends. Supported regional demand forecasting and supply chain optimization.
Trade Assessment
Evaluation of global nickel pig iron and nickel intermediate trade flows, export import trends, country level trade balances, logistics routes, international sourcing patterns, tariff impacts, and regional manufacturing competitiveness. Included assessment of laterite nickel ore trade, NPI shipments, ferronickel trade, and evolving supply chain dynamics supporting global stainless steel production.
Highlighted export opportunities, sourcing risks, and supply diversification options. Supported strategic procurement decisions, supply chain resilience planning, compliance assessment, and international market expansion initiatives.
Opportunity Assessment
Identification of high growth opportunities across stainless steel manufacturing, integrated nickel smelting projects, energy efficient NPI production technologies, low carbon smelting, laterite ore processing, industrial infrastructure development, and downstream nickel value addition.
Enabled prioritization of high return investment opportunities and emerging regional markets. Supported long term capacity expansion, technology modernization, downstream integration, and strategic business development initiatives aligned with evolving global stainless steel and nickel industries.
Frequently Asked Questions About This Report
The global nickel pig iron market size was estimated at USD 18.58 billion in 2024 and is expected to reach USD 18.79 billion in 2025.
The global nickel pig iron market is expected to grow at a compound annual growth rate of 4.8% from 2025 to 2030 to reach USD 23.79 illion by 2030.
The consumer goods segment dominated the market with a revenue share of over 38% in 2024.
Some of the key vendors of the global nickel pig iron market are Tsingshan Group; Nickel Industries Limited; PT MERDEKA BATTERY MATERIALS TBK; PT. Growth Java Industry; PT. Gunbuster Nickel Industry (GNI); New Yaking Pte. Ltd; and others.
The nickel pig iron (NPI) market is driven by rising global stainless steel production, particularly in China and Indonesia, which heavily rely on NPI as a cost-effective nickel source.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


