
- Home
- »
- Advanced Interior Materials
- »
-
North America Wood Flooring Market Size Report, 2033GVR Report cover

North America Wood Flooring Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Solid Wood, Engineered Wood), By Wood Type (Red Oak, White Oak, Maple), By Application, By End Use, And Segment Forecasts
Market Size, 2025
$7.3BMarket Estimate, 2026
$7.5BMarket Forecast, 2033
$10.6BCAGR, 2026–2033
5.0%North America Wood Flooring Market Summary
The North America wood flooring market size was valued at USD 7.3 billion in 2025 and is projected to grow from USD 7.5 billion in 2026 to USD 10.6 billion by 2033, at a CAGR of 5.0% from 2026 to 2033. The market is expected to grow at a robust pace over the forecast period, owing to growing demand for highly durable and aesthetically superior flooring products. Moreover, rising expenditure on renovation and remodeling of old housing structures is expected to have a significant impact on market growth in the upcoming period.
Key Market Trends & Insights
- By product: Engineered wood flooring was the largest segment, accounting for 50.1% of revenue share in 2025.
- By wood type: The red oak segment dominated the market in 2025 with a revenue share of 35.2%.
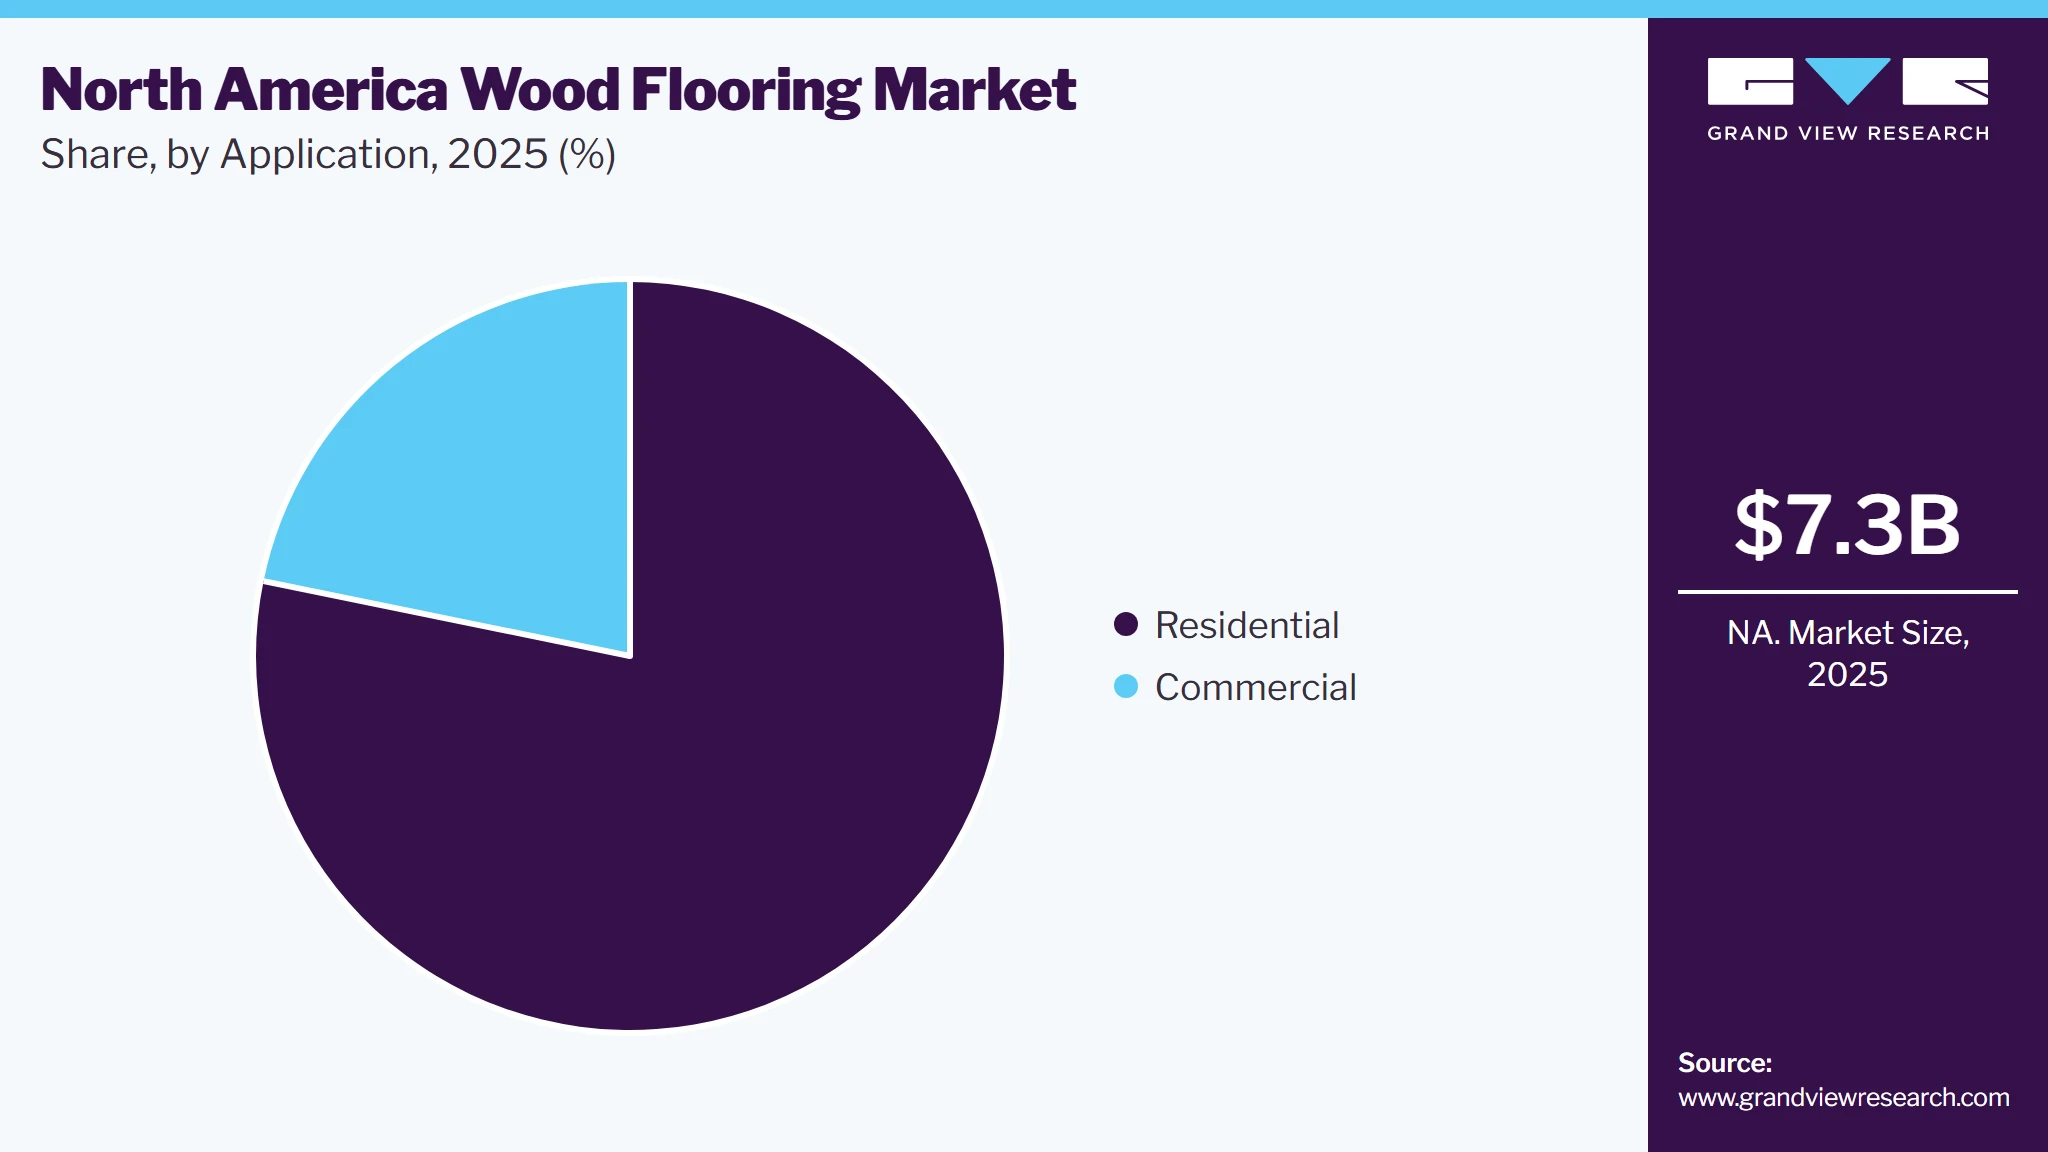
- By application: The residential segment accounted for the largest revenue share of 78.2% in 2025.
Regional Highlights
- Largest market: U.S. (80.1% revenue share in 2025)
- Fastest growing market: Mexico (highest CAGR from 2026 to 2033)
Market Size & Forecast
- Market size in 2025: USD 7.3 Billion
- Estimated market size in 2026: USD 7.5 Billion
- Projected market size by 2035: USD 10.6 Billion
- CAGR (2026-2033): 5.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The expanding remodeling and renovation sector, supported by aging housing stock and increasing investments in residential upgrades, is expected to fuel the market demand. Consumers are replacing traditional flooring materials with hardwood and engineered wood flooring due to their durability, premium appearance, and ease of maintenance. Rising disposable incomes and changing interior design preferences continue to support demand for customized flooring solutions. Growth in multi-family housing developments and commercial infrastructure projects further contributes to market expansion.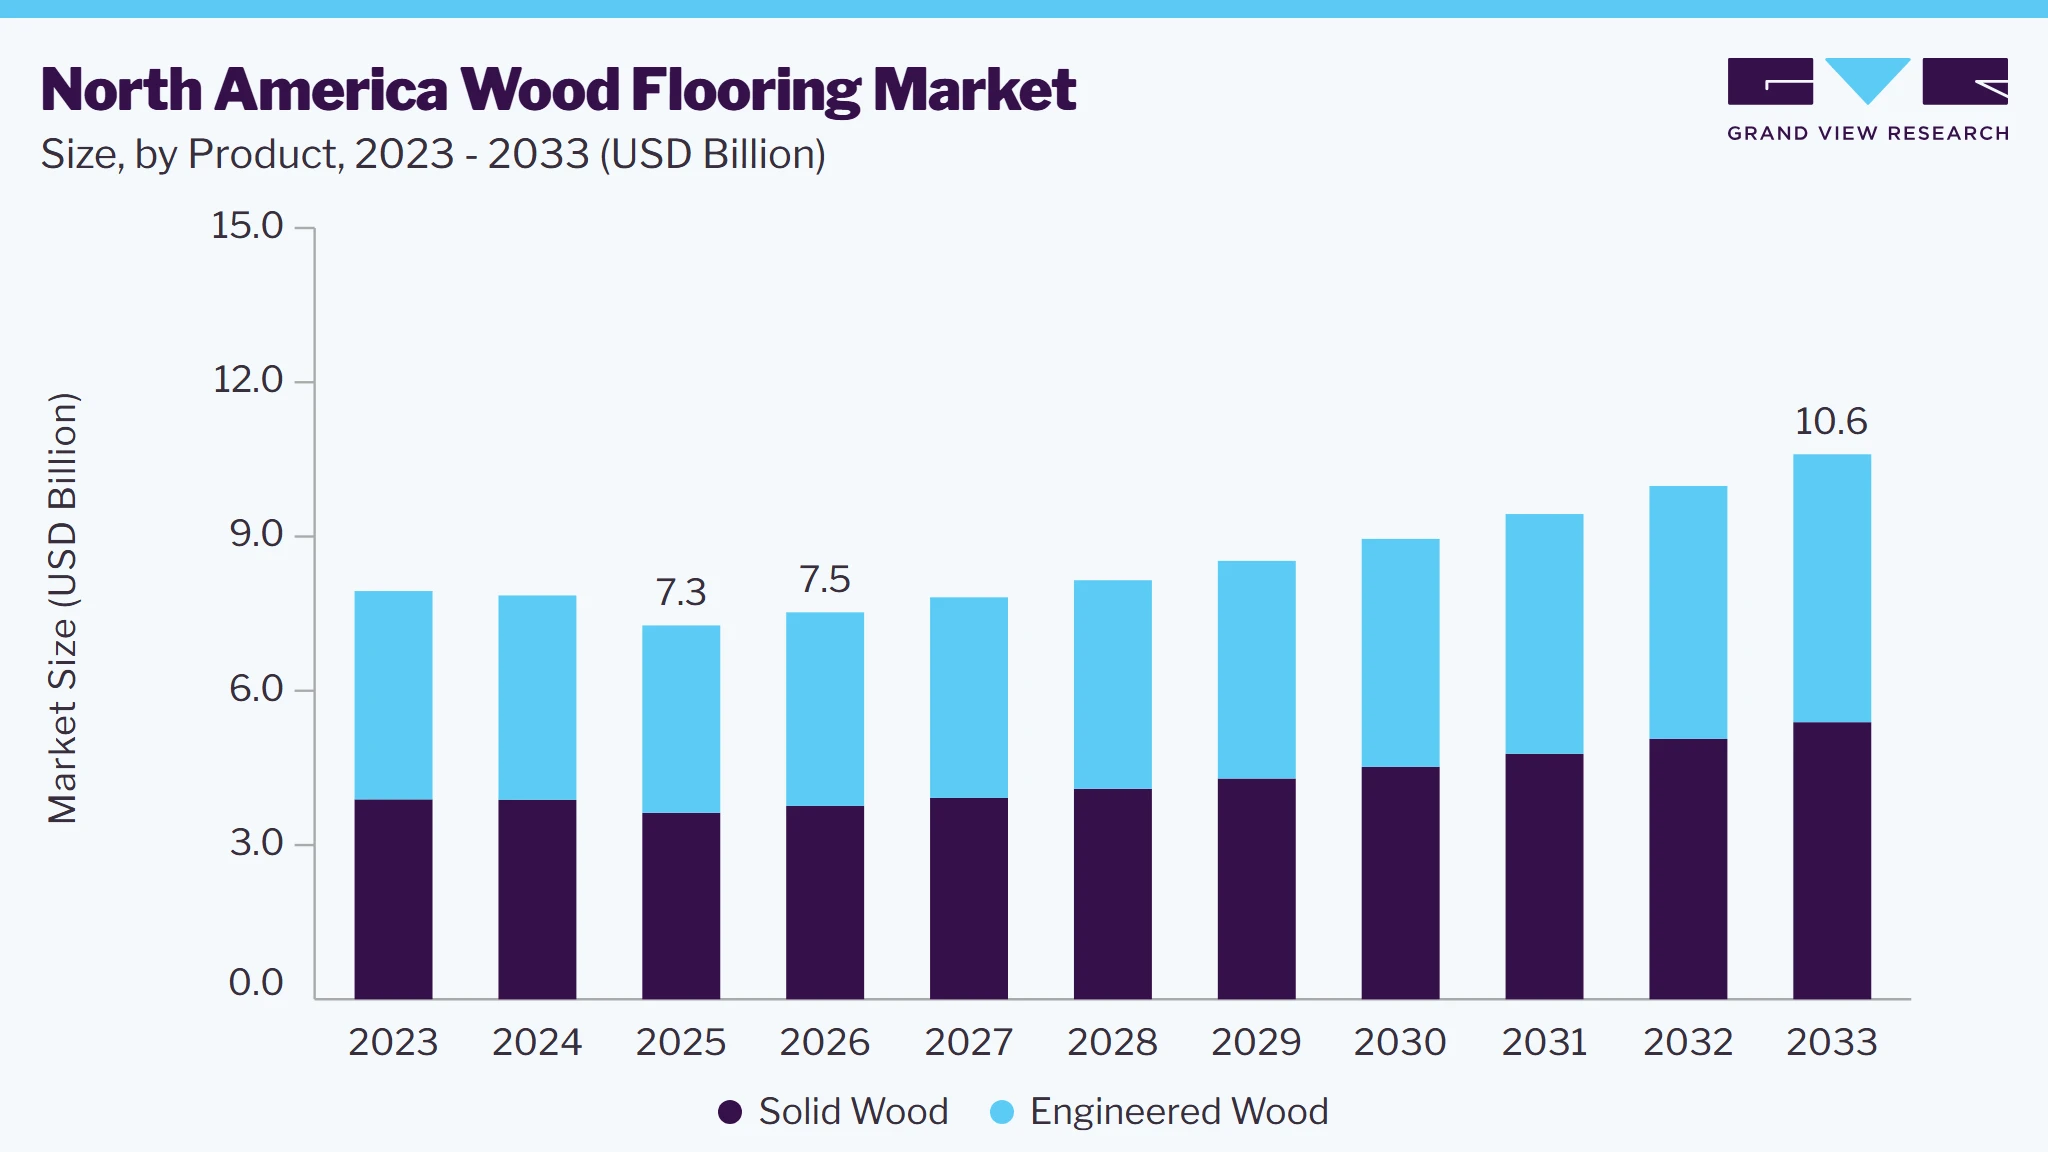 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Government initiatives promoting sustainable forestry management and green building practices are positively influencing the market. Regulations encouraging responsible timber harvesting and certification programs have increased the adoption of legally sourced wood materials. Building codes emphasizing energy-efficient and environmentally responsible construction support the use of renewable flooring products. Public investments in housing and institutional infrastructure also contribute to flooring demand across educational, healthcare, and government buildings. Incentives supporting sustainable construction practices further encourage manufacturers to develop environmentally friendly flooring solutions.
Awareness among North America’s consumers pertaining to environmental conservation has led to high demand for eco-friendly flooring products such as bamboo, glass, rubber, cork, linoleum, and hardwood. Installing flooring is a difficult and time-consuming task, but now companies have developed products that do not require glue to stick to the floor. The materials are made in such a way that tiles can get interlocked with each other. This is a major development in the flooring industry in North America as the cost of installing such materials is reduced drastically.
Key players in North America are focusing on achieving optimal operational costs, enhancing product quality, maximizing production output, and acquiring smaller players to sustain competition. These players are increasingly focusing on mergers & acquisitions, joint ventures, and agreements.
Market Dynamics
The continued expansion of the construction industry across North America is a major factor driving the demand for wood flooring. Rising investments in residential housing, commercial buildings, hospitality projects, and institutional infrastructure have increased the need for aesthetically appealing and durable flooring materials. Wood flooring remains a preferred option due to its premium appearance, long service life, and ability to enhance property value. As construction activity continues to expand, the installation of hardwood and engineered wood flooring is increasing across both new developments and renovation projects. The residential sector remains the largest contributor to wood flooring demand, supported by strong homebuilding activity and ongoing remodeling projects. Consumers are increasingly investing in interior upgrades that improve comfort, sustainability, and resale value, making wood flooring a preferred choice over conventional flooring materials. In addition, multi-family housing developments and luxury residential projects are incorporating premium wood flooring to meet evolving consumer preferences. This trend is creating sustained demand for both solid hardwood and engineered wood flooring products across North America.
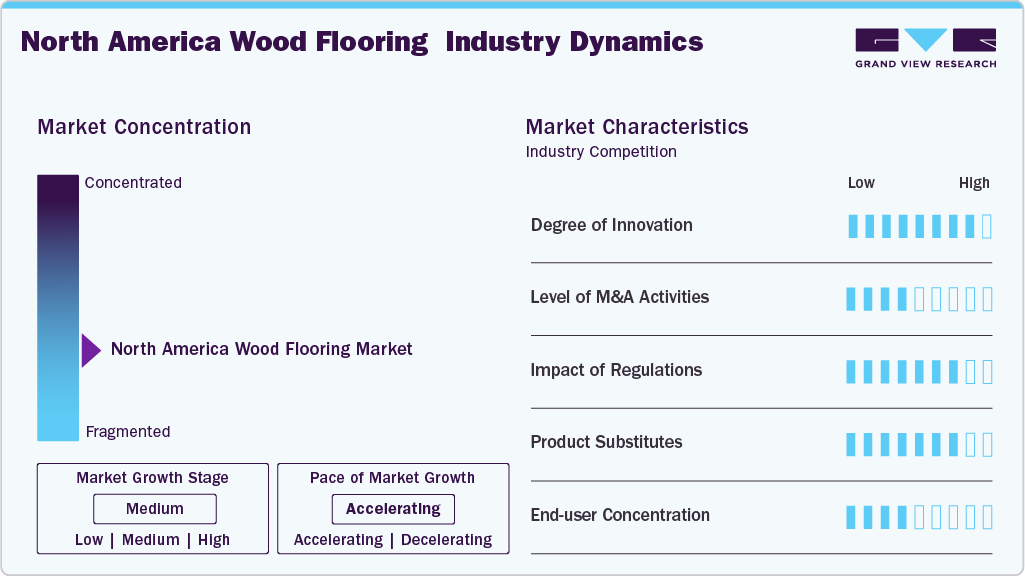
The North American markets for solid and engineered wood flooring are facing increasing competition from a growing range of substitute materials, including ceramic tiles, stone flooring, vinyl flooring, and particularly luxury vinyl tiles (LVTs). These alternatives, known for their affordability, durability, and design flexibility, are gaining traction as practical and cost-effective options for both residential and commercial settings.
The growing emphasis on sustainable construction, green building practices, and premium residential renovation presents significant opportunities for the North American industry. Manufacturers are increasingly developing responsibly sourced, certified wood flooring products with low-emission finishes and recyclable materials to meet evolving environmental standards and consumer preferences. Rising investments in luxury housing, commercial infrastructure, and remodeling projects are driving demand for engineered wood flooring that offers enhanced durability, moisture resistance, and design flexibility. Continuous innovation in surface technologies, digital manufacturing, and sustainable forestry practices, along with expansion into high-value renovation and institutional construction projects, is expected to create substantial long-term growth opportunities for market participants.
Market Concentration & Characteristics
The industry is moderately fragmented, comprising global flooring manufacturers, regional producers, specialty hardwood suppliers, and local distributors. Large companies compete through broad product portfolios, established dealer networks, and investments in sustainable manufacturing, while regional manufacturers differentiate themselves through customized designs and locally sourced wood species. Strategic partnerships with builders, contractors, and home improvement retailers strengthen market reach. Product innovation, brand reputation, and certification compliance remain critical competitive factors.
 To learn more about this report, Download Free Sample Report
Wood flooring faces competition from luxury vinyl tile, laminate flooring, ceramic tiles, bamboo flooring, cork flooring, polished concrete, and carpet solutions. Luxury vinyl flooring has gained significant popularity because of its water resistance, affordability, and design versatility. Laminate flooring offers a cost-effective alternative while closely replicating the appearance of natural wood. Ceramic tiles dominate moisture-prone environments due to their durability and ease of maintenance. Nevertheless, genuine wood flooring continues to maintain strong demand owing to its natural appearance, longevity, refinishing capability, and positive impact on property value, helping it retain a premium position despite substitute products.
Analyst Perspective
The North America wood flooring market is supported by rising residential renovation activity, increasing demand for premium interior finishes, and growing preference for sustainable building materials. Engineered wood flooring is expected to outperform traditional solid wood products due to its superior dimensional stability, moisture resistance, and ease of installation. Manufacturers are focusing on certified wood sourcing, low-VOC finishes, and innovative surface technologies to align with evolving environmental regulations and consumer preferences. Continued investments in automation, digital sales channels, and value-added product offerings are expected to strengthen competitiveness and create long-term growth opportunities across both residential and commercial applications.
Product Insights
Engineered wood flooring was the largest product segment in North America, accounting for 50.1% of revenue share in 2025. Engineered wood is less prone to expansion as well as do not shrink with humidity and temperatures when compared to solid wood. Additionally, engineered wood is widely used as a deck flooring on account of its enhanced features such as reliability, abrasion resistance, and dimensional accuracy.
Engineered wood is also known as composite wood and consists of a number of wooden products manufactured by binding wood-based panels such as plywood and wood veneer together with adhesives so as to form composite materials. They are modeled to supreme design requirements as per the specifications of end users or clients and are tested in order to meet international and national standards.
The solid wood product segment is expected to grow at the highest CAGR of 5.3% over the forecast period. The product offers an option to choose from a wide variety of dent and scratch-resistant wood species, which is expected to increase the demand for solid wood floors in North America. In addition, it has a superior ability to provide protection against stains along with a well-polished nature. Solid wood floors can be sanded and refinished multiple times over their lifetime on account of their top-to-bottom solid core. High durability and easy installation are among the characteristic attributes of solid wood floors. Solid wood floors come in narrower plank sizes and exhibit very tight seams between boards. Furthermore, solid wood flooring is highly preferred for its durability and longevity.
Wood Type Insights
The red oak segment emerged as the largest wood type segment, accounting for 35.2% revenue share in 2025. Abundant domestic availability of the red oak timber, coupled with its affordable cost and moderate to heavy graining, was responsible for the segment growth and is further expected to increase the demand for the product. Red oak is widely used in the wooden flooring industry owing to its relatively lower cost. Further characteristics, which are increasing the demand for red oak for the production of wooden floors, include straight graining pattern, coarse texture, and superior durability with a Janka value of 1290. Red oak wood is relatively easy to work with and can be easily machined and nailed to the subfloor.
The white oak segment is expected to grow at a significant rate over the forecast period. White oak or the Quercus alba is one of the most commonly used hardwood timber species native to the Eastern and Central North America region. The name of this species comes from the color of the finished wood obtained from it. Moreover, it is mostly straight-grained and exhibits a medium to coarse texture, and longer rays than red oak.
White oak hardwood flooring is more water-resistant than other types of floors, making it a good option for use in kitchens, along with entryways, dining rooms, and bedrooms. Furthermore, this type of floorings are available in a smooth and homogenous texture, which is expected to pave the way for use in the North America flooring industry over the forecast period.
End-use Insights
The replacement segment led the market with a 53.8% share in 2025, and is expected to grow at a CAGR of 5.2% over the forecast period. Growing expenditure on repairs and renovation of existing housing structures. Additionally, replacement of existing flooring, such as terrazzo, vinyl, carpet with wood flooring, is expected to drive the product demand over the forecast period. Continued investment in the repair and renovation of existing housing structures was the primary factor driving the segment growth. Wooden floors, on account of their elegant looks, have an aspirational value attached it. As a result, more and more people are replacing their existing flooring with wooden floors, thereby increasing the demand for wood flooring in the North American replacement sector.
The new construction segment is expected to grow at a significant rate over the forecast period. Increasing new residential as well as commercial construction in North America is fueling the new construction sector, which in turn is expected to propel the demand for wooden flooring products over the forecast period.
Application Insights
The residential application segment dominated the market in 2025 with a 78.2% share of total revenue. The rising number of single-family houses in the U.S. post the great recession of 2008-2009 has played an important role in increasing the usage of wooden floor covering materials in the residential segment. Additionally, increasing renovation and refurbishment activities in North America to maintain the structural integrity of buildings and to ensure the safety of the residents have triggered a number of redevelopment projects related to residential as well as commercial sectors in developed countries of North America, such as the U.S., Canada, and Mexico.
 To learn more about this report, Download Free Sample Report
The growing rate of domestic as well as international migration and high urbanization in North America are expected to drive product growth of the residential application segment over the forecast period. Additionally, engineered wood flooring is increasingly replacing the traditional solid wood flooring in the residential sector owing to its cost-effective, ease of installation, and superior moisture resistance property.
The commercial segment includes commercial buildings, hotels, restaurants, cafes, retail stores, offices, gymnasiums, basketball courts, and hospitals. Wooden floors are widely used in commercial applications owing to their long lifecycle. Growing demand for sustainable building materials from the commercial construction industry within the U.S. and Mexico is expected to boost the demand for the wooden floors in North America over the forecast period.
Increasing investment in the development and renovation of tourism infrastructure within several countries of North America, such as the U.S. and Mexico, is further projected to drive the product growth in the future. Furthermore, wooden floors absorb sound waves, thus making them an ideal option for commercial buildings such as offices and hospitals where acoustic solutions are highly required.
Country Insights
North America's wood flooring market is driven by strong demand for solid hardwood and engineered wood flooring across residential renovation, new housing, and commercial construction projects. Engineered wood flooring is witnessing faster adoption due to its superior dimensional stability, compatibility with underfloor heating systems, and suitability for varying climatic conditions. Consumers increasingly prefer wide-plank, textured, and prefinished wood flooring that offers faster installation and lower maintenance. Sustainability remains a major purchasing factor, encouraging the use of FSC- and PEFC-certified wood, low-VOC finishes, and responsibly sourced timber.
U.S. Wood Flooring Market Trends
The wood flooring market in the U.S. is driven by high spending on home renovations, replacement flooring projects, and new residential construction. Demand for engineered wood flooring continues to rise as homeowners seek products offering improved moisture resistance, easy installation, and premium aesthetics. Manufacturers are investing in automation, digital retail channels, and environmentally friendly production technologies to meet evolving consumer preferences. Strong builder partnerships, expanding luxury housing developments, and increasing adoption of sustainable flooring materials continue to support long-term market growth.
Canada wood flooring market is supported by residential construction, renovation activities, and strong consumer preference for natural wood products. The country's abundant forestry resources and focus on sustainable forest management encourage the production and use of certified wood flooring materials. Growing adoption of engineered hardwood flooring is driven by its ability to perform well under varying climatic conditions and indoor heating systems. Rising investments in green buildings and energy-efficient homes are further creating demand for environmentally responsible and high-performance flooring solutions.
The wood flooring market in Mexico is growing due to rapid urbanization, expanding residential construction, and increasing investments in commercial infrastructure. Rising disposable incomes and changing consumer lifestyles are encouraging the adoption of premium flooring materials in both new buildings and renovation projects. The country is also strengthening its role within the regional wood products supply chain through growing manufacturing capabilities and trade integration with North America. Increasing awareness of sustainable construction practices and demand for aesthetically appealing interiors are expected to support continued market expansion.
Key North America Wood Flooring Companies Insights
The key players operating in the North America wood flooring market include Mohawk Industries, Inc., Shaw Industries Group, Inc., Mannington Mills, Inc., Pergo, Flooring Innovations, EGGER Group, Goodfellow, Inc., Bruce Evans Flooring, LLC and Somerset Hardwood Flooring, Inc. The industry is characterized by strong competition owing to the presence of prominent manufacturers. Manufacturers holding major share in North America have established a channel of distribution across various countries. Additionally, manufacturers are also establishing strong online presence for the sake of gaining competitive edge in North America.
Key North America Wood Flooring Companies
The following key companies have been profiled for this study on the North America wood flooring market.
-
Mohawk Industries, Inc.
-
Shaw Industries Group, Inc.
-
Mannington Mills, Inc.
-
Pergo
-
Flooring Innovations
-
EGGER Group
-
Goodfellow, Inc.
-
Bruce Evans Flooring, LLC
-
Somerset Hardwood Flooring, Inc.
-
Home Legend, LLC
-
DuChateau
-
Provenza Floors, Inc.
-
Launstein Hardwood Floors
-
QEP Co., Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players: Mohawk Industries, Inc., Shaw Industries Group, Inc., Mannington Mills, Inc., Pergo, EGGER Group, Goodfellow, Inc.
- Focus on expanding engineered hardwood flooring portfolios with sustainable and premium product offerings.
- Invest in advanced manufacturing technologies, digital sales channels, and nationwide dealer and retail partnerships.
- Strengthen market presence through product innovation, acquisitions, and environmentally certified wood sourcing.
- Strong brand recognition and extensive distribution networks across North America.
- Broad product portfolios covering solid hardwood, engineered wood, laminate, and resilient flooring solutions.
- Large-scale manufacturing capabilities and established relationships with builders, retailers, and contractors.
- Premium pricing may limit penetration in price-sensitive market segments.
- High dependence on residential construction and remodeling cycles impacts revenue stability.
- Large operational structures may slow response to rapidly changing design trends and niche customer requirements.
Emerging Players: Flooring Innovations, Bruce Evans Flooring, LLC, Somerset Hardwood Flooring, Inc., Home Legend, LLC, DuChateau, Provenza Floors, Inc., Launstein Hardwood Floors, QEP Co., Inc.
- Focus on premium hardwood collections, customized flooring solutions, and specialty installation products.
- Target luxury residential, boutique commercial, and regional markets through differentiated designs and value-added services.
- Expand product offerings with sustainable materials, innovative finishes, and direct partnerships with designers and flooring installers.
- Greater flexibility in responding to evolving design trends and customized customer requirements.
- Strong differentiation through premium craftsmanship, specialty wood species, and innovative surface finishes.
- Ability to introduce new collections and product innovations more rapidly than larger competitors.
- Limited brand visibility and smaller distribution networks compared to established market leaders.
- Lower production capacity and marketing investments restrict large-scale market expansion.
- Greater exposure to fluctuations in raw material availability and premium hardwood pricing.
Recent Developments
-
In June 2025, Mohawk introduced the Floorward Collection, a next-generation vinyl flooring range featuring glue-free installation, recycled and bio-based materials, enhanced durability, and circular design to strengthen its sustainable resilient flooring portfolio.
-
In December 2024, Engineered Floors launched its PureGrain Digital Luxury Vinyl Tile (DLVT) line at its Dalton, Georgia facility. Utilizing Hymmen direct digital printing technology, the new line offers enhanced visual patterns and reduced repetition, addressing previous limitations in LVT aesthetics. The company plans to introduce 132 new SKUs across its hard surface categories in 2025.
North America Wood Flooring Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.3 billion
Estimated market size in 2026
USD 7.5 billion
Projected market size by 2033
USD 10.6 billion
Growth rate
CAGR of 5.0% from 2026 to 2033
Base year for estimation
2025
Actual estimates/Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in Million Square Meters; revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Volume & revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, wood type, application, end-use, country
Regional scope
North America
Country scope
U.S.; Canada; Mexico
Key companies profiled
Mohawk Industries, Inc.; Shaw Industries Group, Inc.; Mannington Mills, Inc.; Pergo; Flooring Innovations; EGGER Group; Goodfellow, Inc.; Bruce Evans Flooring, LLC; Somerset Hardwood Flooring, Inc.; Home Legend, LLC; DuChateau; Provenza Floors, Inc.; Launstein Hardwood Floors; QEP Co., Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
North America Wood Flooring Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the North America wood flooring market report on the basis of product, wood type, application, end-use, and country:
-
Product Outlook (Volume, Million Square Meters; Revenue, USD Million, 2021 - 2033)
-
Solid Wood
-
Engineered Wood
-
-
Wood Type Outlook (Volume, Million Square Meters; Revenue, USD Million, 2021 - 2033)
-
Red Oak
-
White Oak
-
Maple
-
Others
-
-
Application Outlook (Volume, Million Square Meters; Revenue, USD Million, 2021 - 2033)
-
Residential
-
Commercial
-
-
End-use Outlook (Volume, Million Square Meters; Revenue, USD Million, 2021 - 2033)
-
Replacement
-
New Construction
-
-
Country Outlook (Volume, Million Square Meters; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Research Methodology
The North America wood flooring market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each North America wood flooring segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Solid Wood
Revenue generated from the sale of solid hardwood flooring manufactured from a single piece of natural timber, widely used in residential and commercial buildings for its durability, timeless appearance, refinishing capability, and long service life.
Engineered Wood
Revenue generated from the sale of engineered wood flooring consisting of a real hardwood veneer bonded to multiple plywood or high-density core layers, offering enhanced dimensional stability, moisture resistance, and installation flexibility.
Segment - Wood Type
Revenue capture definition
Red Oak
Revenue generated from the sale of red oak wood flooring, valued for its distinctive grain patterns, durability, affordability, and widespread use in residential and commercial flooring applications.
White Oak
Revenue generated from the sale of white oak wood flooring, preferred for its superior hardness, moisture resistance, contemporary appearance, and suitability for premium residential and commercial interiors.
Maple
Revenue generated from the sale of maple wood flooring used in residential, commercial, and sports flooring applications due to its smooth grain, high wear resistance, and light natural color.
Others
Revenue generated from the sale of other wood flooring species, including hickory, walnut, cherry, ash, birch, and exotic hardwoods, selected for their unique aesthetics, durability, and specialized architectural applications.
Segment - Application
Revenue capture definition
Residential
Revenue generated from the installation and sale of wood flooring used in single-family homes, apartments, condominiums, and residential renovation projects to enhance aesthetics, durability, and property value.
Commercial
Revenue generated from the installation and sale of wood flooring for offices, retail stores, hotels, restaurants, educational institutions, healthcare facilities, and other commercial buildings requiring durable and visually appealing flooring solutions.
Segment - End Use
Revenue capture definition
New Construction
Revenue generated from the sale and installation of wood flooring in newly constructed residential, commercial, institutional, and mixed-use buildings as part of original building development.
Replacement
Revenue generated from the replacement, renovation, and refurbishment of existing flooring with new solid or engineered wood flooring in residential and commercial properties to improve appearance, performance, and property value.
Estimation Model
Layer Name
Key Question
Description
Residential & Commercial Construction Activity
Where is wood flooring demand generated?
Estimates demand based on new residential construction, home renovation and remodeling, commercial building development, hospitality projects, office spaces, and institutional infrastructure across major North American markets.
End-use Demand Assessment
Which sectors consume wood flooring?
Evaluates wood flooring consumption across residential homes, apartments, commercial offices, retail spaces, hotels, restaurants, educational institutions, healthcare facilities, and other non-residential buildings where premium flooring solutions are required.
Product & Material Penetration
Which wood flooring products are being adopted?
Assesses market demand by product type including solid wood and engineered wood, along with wood species such as red oak, white oak, maple, and other hardwoods based on durability, aesthetics, installation requirements, sustainability, and end-use preferences.
Revenue Validation & Market Assessment
What is the total revenue generated from wood flooring?
Consolidates regional demand, construction activity, renovation spending, product pricing, manufacturer sales, distribution channels, import-export trends, retail sales, and company revenues to validate the overall North America wood flooring market size and forecast.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Supply chain and value chain assessment
Detailed evaluation of raw material sourcing, hardwood processing, flooring manufacturing, distribution channels, retail networks, and installation ecosystem across North America.
Helps identify supply chain efficiencies, sourcing risks, and opportunities for operational optimization.
Sustainability and regulatory landscape analysis
Comprehensive analysis of certified wood sourcing, environmental regulations, green building standards, and sustainability trends impacting wood flooring manufacturers.
Supports compliance planning, ESG initiatives, and development of sustainable product portfolios.
Technology and innovation assessment
Detailed review of advancements in engineered wood flooring, surface finishing technologies, click-lock installation systems, digital manufacturing, and moisture-resistant flooring solutions.
Enables identification of innovation opportunities, product differentiation strategies, and future technology investments.
Frequently Asked Questions About This Report
Some of the key players operating in the North America wood flooring market include Mohawk Industries, Inc., Shaw Industries Group, Inc., Mannington Mills, Inc., Pergo, Flooring Innovations, EGGER Group, Goodfellow, Inc., Bruce Evans Flooring, LLC, and Somerset Hardwood Flooring, Inc.
The key factors that are driving the North America wood flooring market includes growth of construction activities coupled with rising expenditure on renovation and remodeling of old housing structures in developed countries such as U.S. and Mexico.
U.S. held the highest revenue share of 80.1% in 2025 in the North America wood flooring market.
The residential segment is the fastest-growing application in the North America wood flooring market.
Red oak is the fastest-growing wood type segment in the North America wood flooring market.
The engineered wood segment accounted for the largest revenue share of 50.1% in 2025, driven by its superior dimensional stability, moisture resistance, ease of installation, and increasing preference in residential renovation and new construction projects across North America.
The North America wood flooring market size was valued at USD 7.3 billion in 2025 and is expected to reach USD 7.5 billion in 2026.
The North America wood flooring market is expected to grow at a compound annual growth rate of 5.0% from 2026 to 2033 to reach USD 10.6 billion by 2033.
Red Oak emerged as the largest wood type segment in the North America wood flooring market in 2025, with revenue of USD 2.6 billion, owing to its growing adoption, propelled by its low cost, durability, and aesthetic attributes
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


