
- Home
- »
- Pharmaceuticals
- »
-
Opioid Analgesics Market Size, Share & Trends Report, 2033GVR Report cover

Opioid Analgesics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Drug Type (Morphine, Codeine, Oxycodone, Hydrocodone, Hydromorphone), By Application, By Route of Administration, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$26.2MMarket Estimate, 2026
$27.2MMarket Forecast, 2033
$37.1MCAGR, 2026–2033
4.5%Opioid Analgesics Market Summary
The global opioid analgesics market size was valued at USD 26.2 billion in 2025 and is projected to grow from USD 27.2 billion in 2026 to USD 37.1 billion by 2033, at a CAGR of 4.5% from 2026 to 2033. North America dominated the market, accounting for the revenue share of 41.2% in 2025. Opioid analgesics are medicines used to manage moderate to severe pain by acting on opioid receptors in the central nervous system.
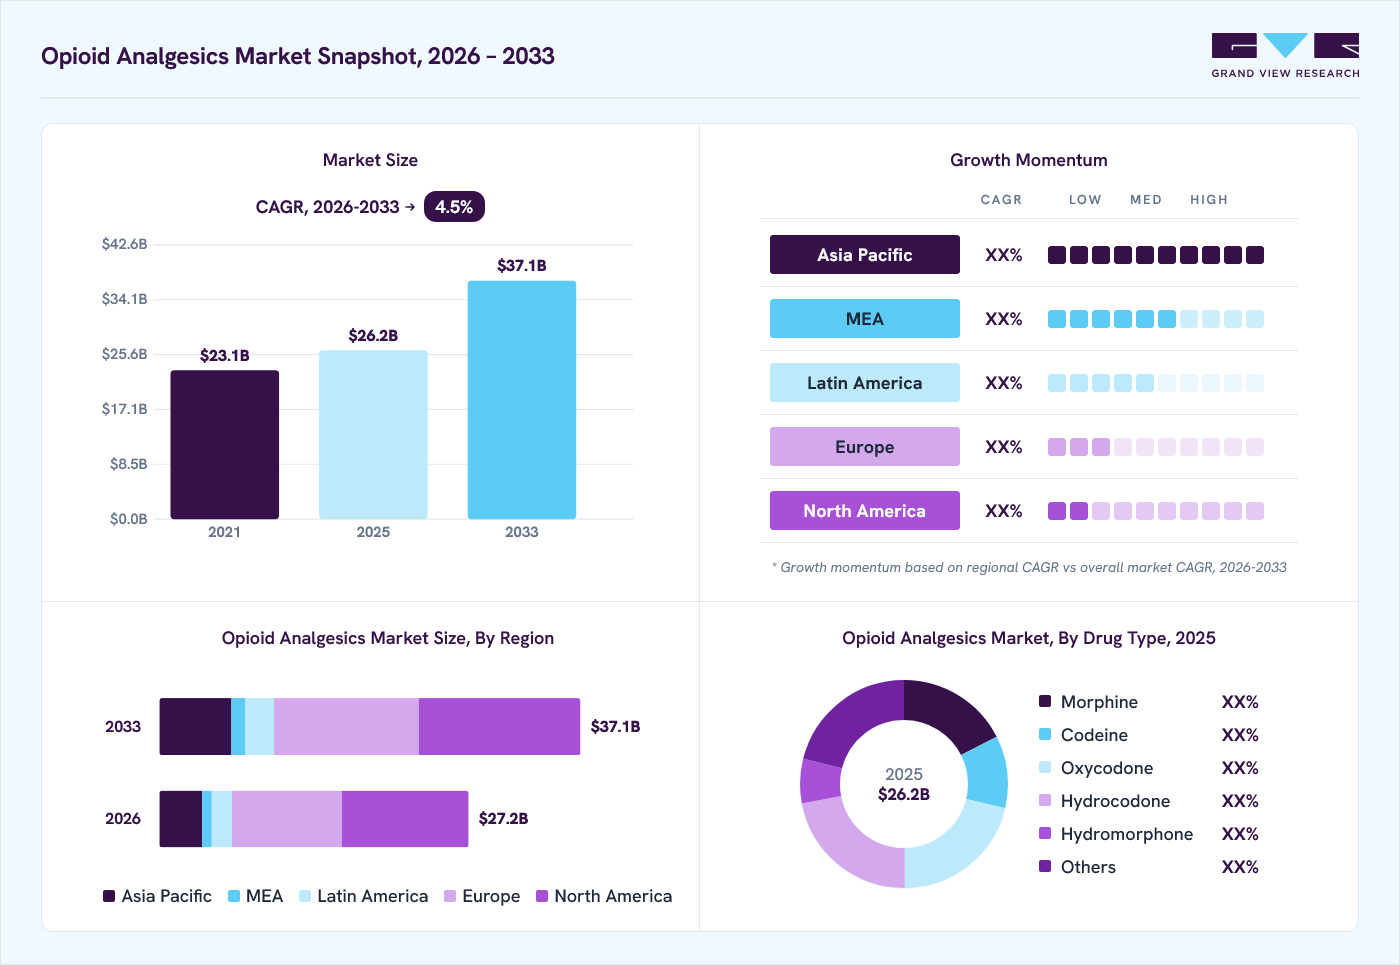 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drug type: The hydrocodone segment held the largest market share of 22.1% in 2025.
- By application: The acute pain segment accounted for the largest market revenue share of 55.8% in 2025.
- By route of administration: The oral segment led the market with the largest revenue share of 64.7% in 2025.
- By distribution channel: The retail pharmacies segment dominated the market with the largest revenue share of 60.1% in 2025.
Regional Highlights
- Largest regional market: North America (41.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. dominated North America with the largest revenue share in 2025
Market Size & Forecast
- Market size in 2025: USD 26.2 Billion
- Estimated market size in 2026: USD 27.2 Billion
- Projected market size by 2033: USD 37.1 Billion
- CAGR (2026-2033): 4.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market includes morphine, codeine, oxycodone, hydrocodone, hydromorphone, and other opioid medicines used in pain management. These drugs are prescribed for conditions such as postoperative pain, cancer-related pain, traumatic injuries, and selected chronic pain conditions. Their use depends on pain severity, patient health, treatment history, and clinical guidance. Opioid analgesics are available in oral, parenteral, transdermal, and other formulations to meet different treatment requirements. However, their use requires careful medical assessment because of the risks of respiratory depression, physical dependence, and misuse. These factors influence prescribing practices, product selection, and access to opioid medicines across healthcare systems.The need for pain management in surgical care, cancer treatment, emergency medicine, and palliative care supports the use of opioid analgesics. Drug selection varies according to the type and severity of pain, the required duration of treatment, and the patient's response to therapy. Morphine and hydromorphone are used in different acute and severe pain conditions, while oxycodone and hydrocodone are prescribed for selected pain indications, subject to local approvals. Codeine also serves as an option for pain relief in eligible patients. Oral formulations support outpatient treatment, while parenteral products are used when injectable administration is required. Transdermal formulations provide sustained drug delivery for selected patients. At the same time, clinical guidelines encourage appropriate prescribing, patient monitoring, and consideration of non-opioid treatments when suitable.
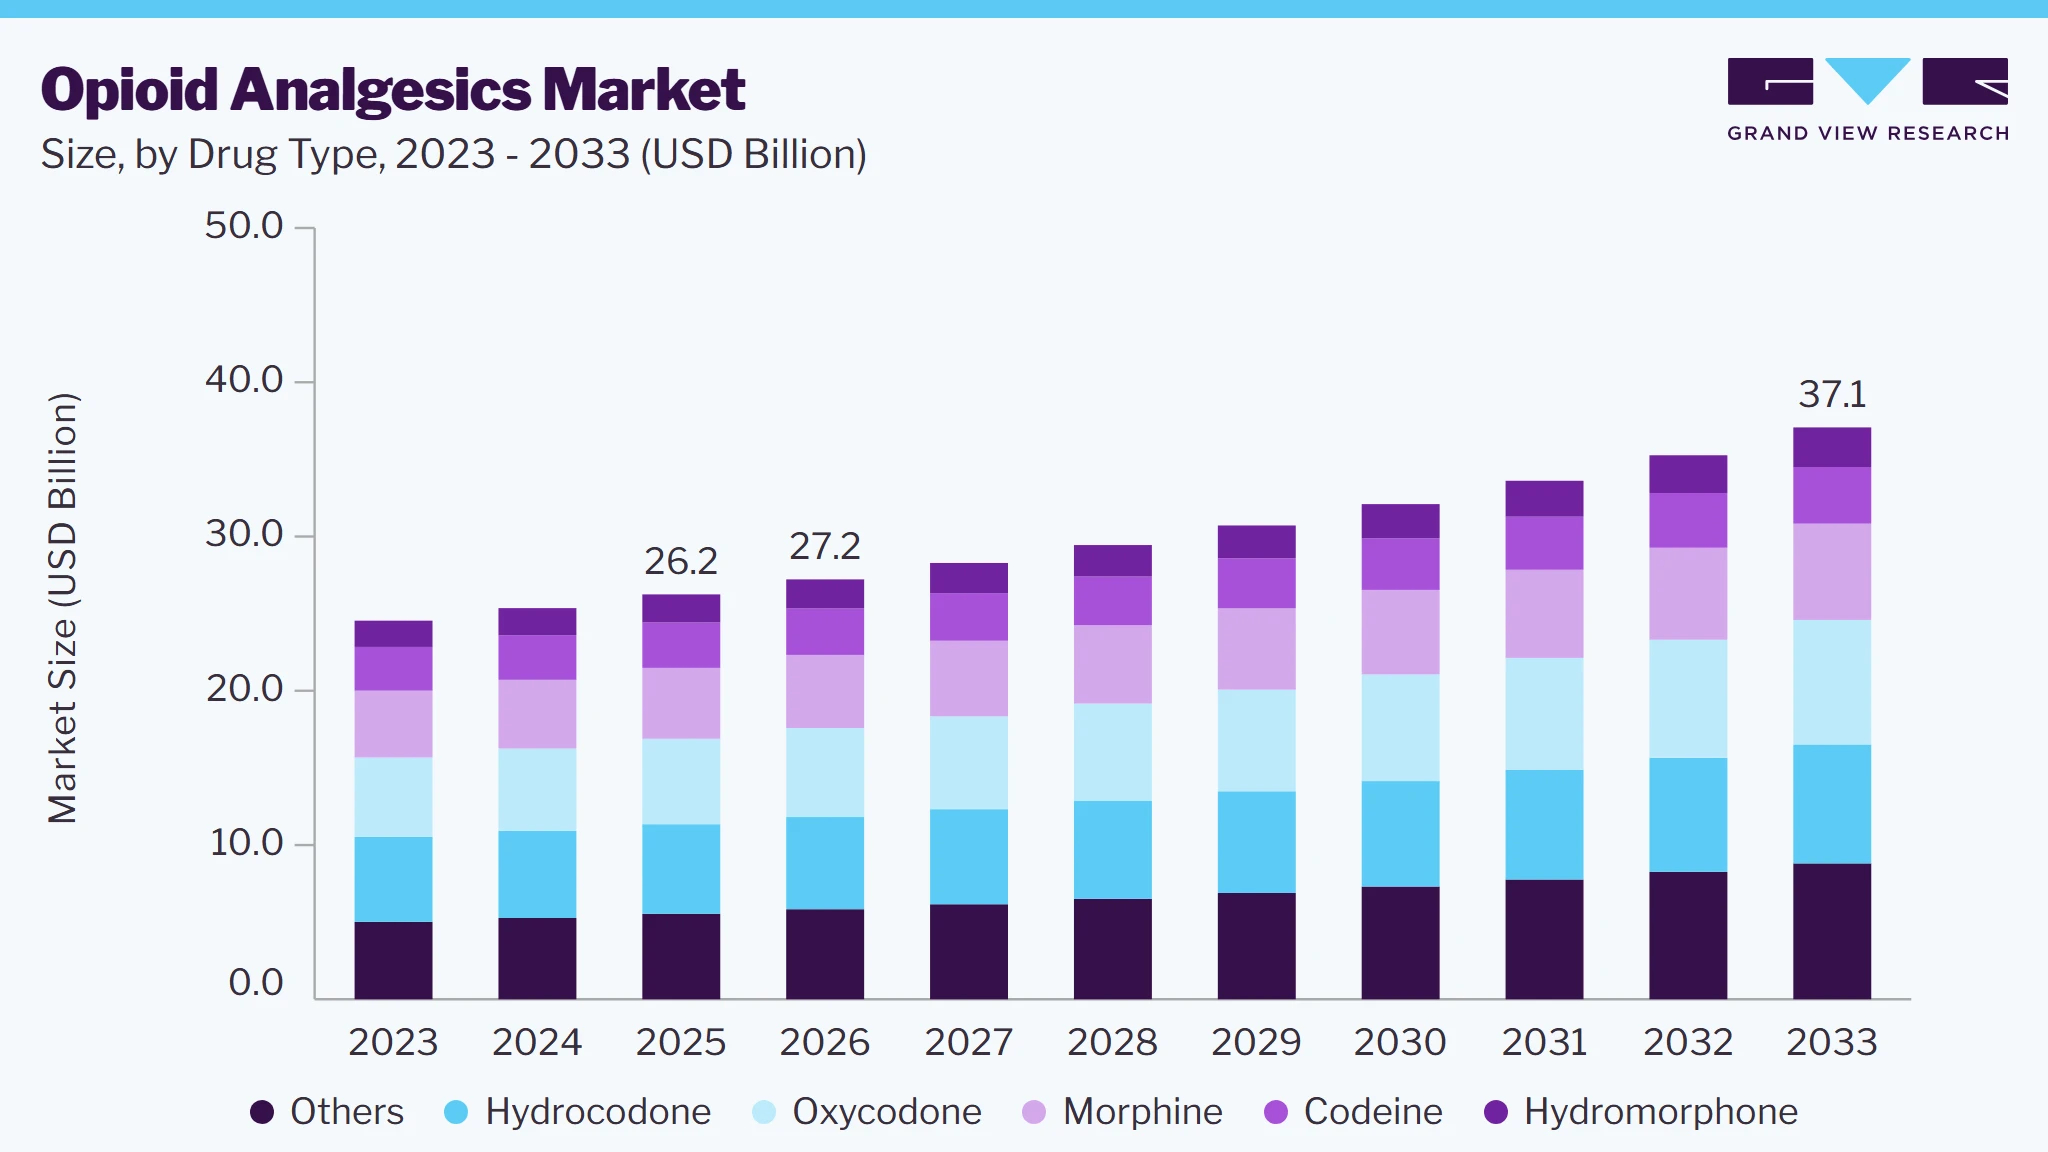 To learn more about this report, Download Free Sample Report
The opioid analgesics industry is shaped by national prescribing regulations, drug safety requirements, healthcare access, and the availability of alternative pain treatments. Controlled-substance status varies by medicine and country, while over-the-counter access is limited to specific products in jurisdictions where regulations permit such use. Hospital pharmacies supply opioid medicines for inpatient care, retail pharmacies dispense outpatient prescriptions, and online pharmacies operate under applicable dispensing and prescription requirements. Demand also varies by application, with acute pain management generally involving short-term treatment, while chronic pain management requires ongoing evaluation of treatment benefits and risks. Regulatory controls, concerns about opioid misuse, and the availability of non-opioid treatments continue to influence prescribing decisions and patient access across healthcare systems.
Market Dynamics
The need to manage moderate-to-severe pain supports the use of opioid analgesics across surgical care, cancer treatment, traumatic injuries, and palliative care. These medicines are used when pain severity requires opioid treatment and other medicines do not provide adequate relief. Different treatment needs arise based on clinical condition, patient response, and prescribing guidance. Injectable formulations support pain management in hospitals, while oral formulations are used in inpatient and outpatient care. Transdermal products provide sustained drug delivery for selected patients who require continued pain control. The need for effective pain relief also supports the use of opioids in acute pain management following surgery or injury. In chronic pain treatment, prescribing decisions require regular assessment of treatment benefits, adverse effects, and the risk of dependence. Although non-opioid medicines are used when suitable, opioid analgesics remain an option for selected patients whose pain requires this treatment. Their use therefore depends on clinical need, patient safety, and appropriate prescribing practices.
The risks of dependence, misuse, respiratory depression, and overdose restrict the use of opioid analgesics across healthcare systems. These risks require healthcare providers to assess patient history, pain severity, current medicines, and the need for continued treatment before prescribing opioids. Long-term use requires regular monitoring, while concerns about misuse can limit prescribing for selected chronic pain conditions. National regulations also govern prescription requirements, dispensing, product labeling, and distribution. These controls increase compliance responsibilities for manufacturers, healthcare providers, and pharmacies. In addition, the availability of non-opioid treatments provides alternatives for patients whose pain can be managed without opioid medicines. This can reduce opioid use in certain acute pain applications and influence treatment selection. Concerns about opioid-related harm also affect patient acceptance and prescribing practices. Although these measures support safer medicine use, they can restrict access when prescription controls, healthcare resources, or monitoring requirements create barriers to treatment. The combined effect of safety risks, regulatory requirements, and alternative therapies limits the use of opioid analgesics in some patient groups.
The development of abuse-deterrent and extended-release opioid formulations provides an opportunity to address specific treatment needs while improving medicine design. Abuse-deterrent formulations are designed to make certain forms of manipulation more difficult, although they do not eliminate the risks of misuse, dependence, or overdose. Extended-release products provide controlled drug delivery over a longer period and are used for selected patients who require continued pain management. Product development can focus on formulation design, dosage consistency, drug delivery, and patient safety while meeting regulatory requirements. Oral formulations remain relevant to outpatient treatment, while other delivery formats serve specific clinical needs. Manufacturers can also assess opportunities to improve existing products through formulation changes and product lifecycle development. However, the clinical value of these products depends on approved indications, safety evidence, patient selection, and prescriber guidance. Their use is not suitable for every patient or pain condition. Commercial opportunities therefore depend on demonstrated clinical need, regulatory approval, healthcare provider acceptance, and access to appropriate treatment.
Market Characteristics & Concentration
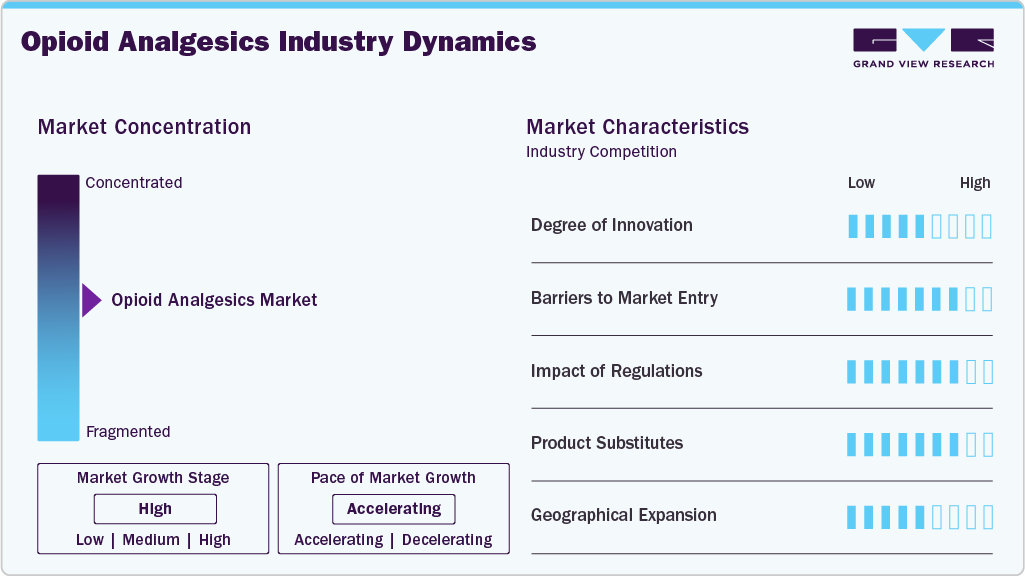
The degree of innovation is moderate, as product development mainly focuses on formulation changes, drug delivery, dosage design, and measures intended to reduce misuse. Established medicines such as morphine, oxycodone, and hydromorphone continue to serve pain management needs, limiting the need for entirely new active ingredients across every product category. Manufacturers develop extended-release formulations for prolonged drug delivery and abuse-deterrent formulations designed to make certain forms of manipulation more difficult. These products require development work, supporting evidence, and regulatory review. Innovation also includes improvements in dosage forms and product usability for selected patient groups. However, safety concerns, regulatory requirements, and competition from non-opioid treatments influence research priorities. Much of the development activity centers on existing medicines and formulation improvements rather than new mechanisms of action.
Barriers to market entry are high, as new participants must meet requirements for pharmaceutical manufacturing, product approval, quality, and controlled-substance compliance. Companies need appropriate manufacturing capabilities and must demonstrate product quality, safety, and efficacy in accordance with applicable regulations. Manufacturing facilities must follow good manufacturing practices, while suppliers and distributors must comply with requirements for handling, storage, security, and movement of controlled medicines. Additional obligations may apply to production volumes, recordkeeping, and distribution. Developing specialized products, such as extended-release and abuse-deterrent formulations, can require further investment in research and supporting evidence. Generic manufacturers also face competition from established suppliers and must maintain reliable production and distribution. Requirements differ by country and product category, creating operational and financial challenges for companies entering the market.
 To learn more about this report, Download Free Sample Report
The impact of regulations is high, as national authorities control product approvals, prescribing, manufacturing, labeling, and distribution of opioid analgesics. Manufacturers must comply with quality standards, safety reporting, and applicable requirements for controlled medicines. Healthcare providers must follow prescribing rules and assess patient suitability, treatment duration, and the risk of adverse effects. Pharmacies must also meet relevant dispensing and record-keeping obligations. Differences in national policies affect product availability, market access, and the time required to introduce medicines. Safety concerns can lead to changes in prescribing guidance, product labeling, and monitoring requirements. These controls support appropriate medicine use but can increase compliance costs and restrict access in some markets. Regulatory changes can therefore affect product supply, prescribing practices, and the commercial operations of manufacturers and distributors.
The availability of product substitutes is high, as several non-opioid medicines and other pain management methods can address specific pain conditions. Alternatives include paracetamol, nonsteroidal anti-inflammatory drugs, selected medicines for neuropathic pain, local anesthetics, and non-pharmacological treatments such as physiotherapy. The suitability of each option depends on pain severity, underlying disease, patient history, and treatment goals. For some acute pain conditions, non-opioid medicines provide adequate relief and reduce the need for opioid exposure. In chronic pain management, clinicians may combine medicines with physical rehabilitation or other supportive treatments. However, these alternatives do not replace opioids in every clinical situation, particularly when severe pain does not respond adequately to other treatments. Concerns about dependence, overdose, and adverse effects also support consideration of alternative therapies.
Geographical expansion is moderate, as entry into new countries depends on regulatory approvals, controlled-substance policies, healthcare infrastructure, and access to pharmaceutical distribution channels. Companies must comply with local requirements for product registration, prescribing, manufacturing, importation, and distribution. Differences in national policies affect which opioid medicines are available and how they are supplied to hospitals and retail pharmacies. Demand also varies with access to surgery, cancer care, palliative care, and other pain management services. In some countries, limited access to essential opioid medicines restricts treatment availability, while strict controls can affect supply and dispensing. Manufacturers must establish compliant distribution arrangements and maintain product quality across supply chains. Generic medicines provide opportunities in established drug categories, but expansion depends on regulatory approval and local healthcare requirements.
Analyst Perspective
The opioid analgesics industry is supported by demand for pain management across surgical care, cancer treatment, and trauma care. Prescription medicines account for most market activity due to controlled-substance regulations and medical supervision requirements. Oral formulations support outpatient treatment, while transdermal products serve selected chronic pain applications. However, safety concerns, prescribing restrictions, and non-opioid alternatives affect demand. Market growth is influenced by pain management needs, product availability, prescribing regulations, and access to healthcare services.
Drug Type Insights
The hydrocodone segment dominated the market with the largest revenue share of 22.1% in 2025, supported by its use in moderate-to-severe pain management, availability in combination formulations with acetaminophen, established prescribing practices, oral dosage options, use in acute pain treatment, and supply through prescription channels. Hydrocodone combination medicines provide an option for patients requiring opioid-based pain relief when alternative treatments are inadequate. Demand also depends on surgical care, injury treatment, product availability, and prescribing requirements across countries. Generic competition supports product availability but creates pricing pressure among suppliers. Regulatory controls and safety concerns continue to influence prescribing decisions and patient access. These factors support hydrocodone's leading revenue contribution within the drug type segment, although its use varies by country and clinical indication.
The oxycodone segment is projected to grow at the fastest CAGR of 4.9% during the forecast period, supported by demand for postoperative pain management, cancer-related pain treatment, availability of immediate-release and extended-release formulations, generic product availability, and its use in selected moderate-to-severe pain conditions. Growth is also supported by various dosage strengths and combination products, which provide treatment options tailored to clinical requirements. Generic competition can improve product availability and expand access through prescription channels. However, prescribing controls, safety concerns, and non-opioid alternatives influence the use of oxycodone. Product availability also varies across countries according to regulatory approvals and prescribing requirements. These factors support growth in the oxycodone segment, although the rate of growth depends on clinical demand, product supply, and national controls on opioid prescribing and distribution.
Application Insights
The acute pain segment held the largest revenue share of 55.8% in 2025, supported by opioid use following surgical procedures, treatment of traumatic injuries, hospital-based pain management, emergency care requirements, postoperative recovery, and the need for short-term pain relief when other medicines provide inadequate results. Morphine, oxycodone, hydromorphone, and hydrocodone are used in selected acute pain conditions, depending on clinical requirements and national prescribing guidelines. Injectable formulations support pain management in hospitals, while oral medicines provide options for patients requiring treatment after discharge. Demand also depends on surgical volumes, access to emergency medical services, and the availability of approved opioid formulations. However, non-opioid medicines are used when clinically suitable, while safety concerns and prescribing controls influence treatment selection across healthcare facilities.
The chronic pain segment is expected to grow at the fastest CAGR of 4.9% during the forecast period, supported by the need for continued pain management in selected patients, use of extended-release formulations, demand for sustained drug delivery, availability of different oral dosage forms, and treatment requirements when alternative medicines provide inadequate relief. Extended-release opioid formulations provide longer dosing intervals for eligible patients who require continuous pain control, while formulation development focuses on maintaining drug delivery and addressing certain forms of misuse. The segment also benefits from established treatment options for selected cancer-related and other persistent pain conditions. However, long-term opioid therapy requires regular assessment because of dependence, overdose, and other safety risks. Prescribing guidance, patient selection, and the availability of non-opioid treatments will influence the growth rate during the forecast period.
Route of Administration Insights
The oral segment led the market with the largest revenue share of 64.7% in 2025, supported by ease of administration, availability of multiple dosage strengths, suitability for outpatient treatment, established prescribing practices, availability of generic formulations, and distribution through retail and hospital pharmacies. Oral tablets and capsules support pain management across acute and chronic conditions, depending on the prescribed medicine and formulation. Immediate-release products are used when pain relief is required for a shorter period, while extended-release formulations provide sustained pain control in eligible patients. Oral administration also avoids the need for injections, supporting its use outside hospital care. Generic competition contributes to product availability across healthcare channels. These factors support the leading position of oral formulations within the route of administration segment, although product selection depends on clinical needs and prescribing guidance.
The transdermal segment is anticipated to grow at the fastest CAGR of 4.5% during the forecast period, supported by demand for sustained drug delivery, reduced dosing frequency, convenience for selected patients requiring continued pain management, and use in chronic pain treatment. Transdermal opioid formulations deliver medicine through the skin over an extended period, supporting treatment continuity for eligible patients who require ongoing analgesia. These products also provide an option for patients who experience difficulty swallowing oral medicines. Their use depends on the specific drug, approved indication, patient condition, and clinical assessment. Growth is further linked to the need for alternative dosage forms in long-term pain management. However, delayed onset, skin reactions, dose adjustment requirements, and risks associated with opioid exposure influence product selection. These factors shape demand for transdermal formulations across appropriate pain management applications.
Distribution Channel Insights
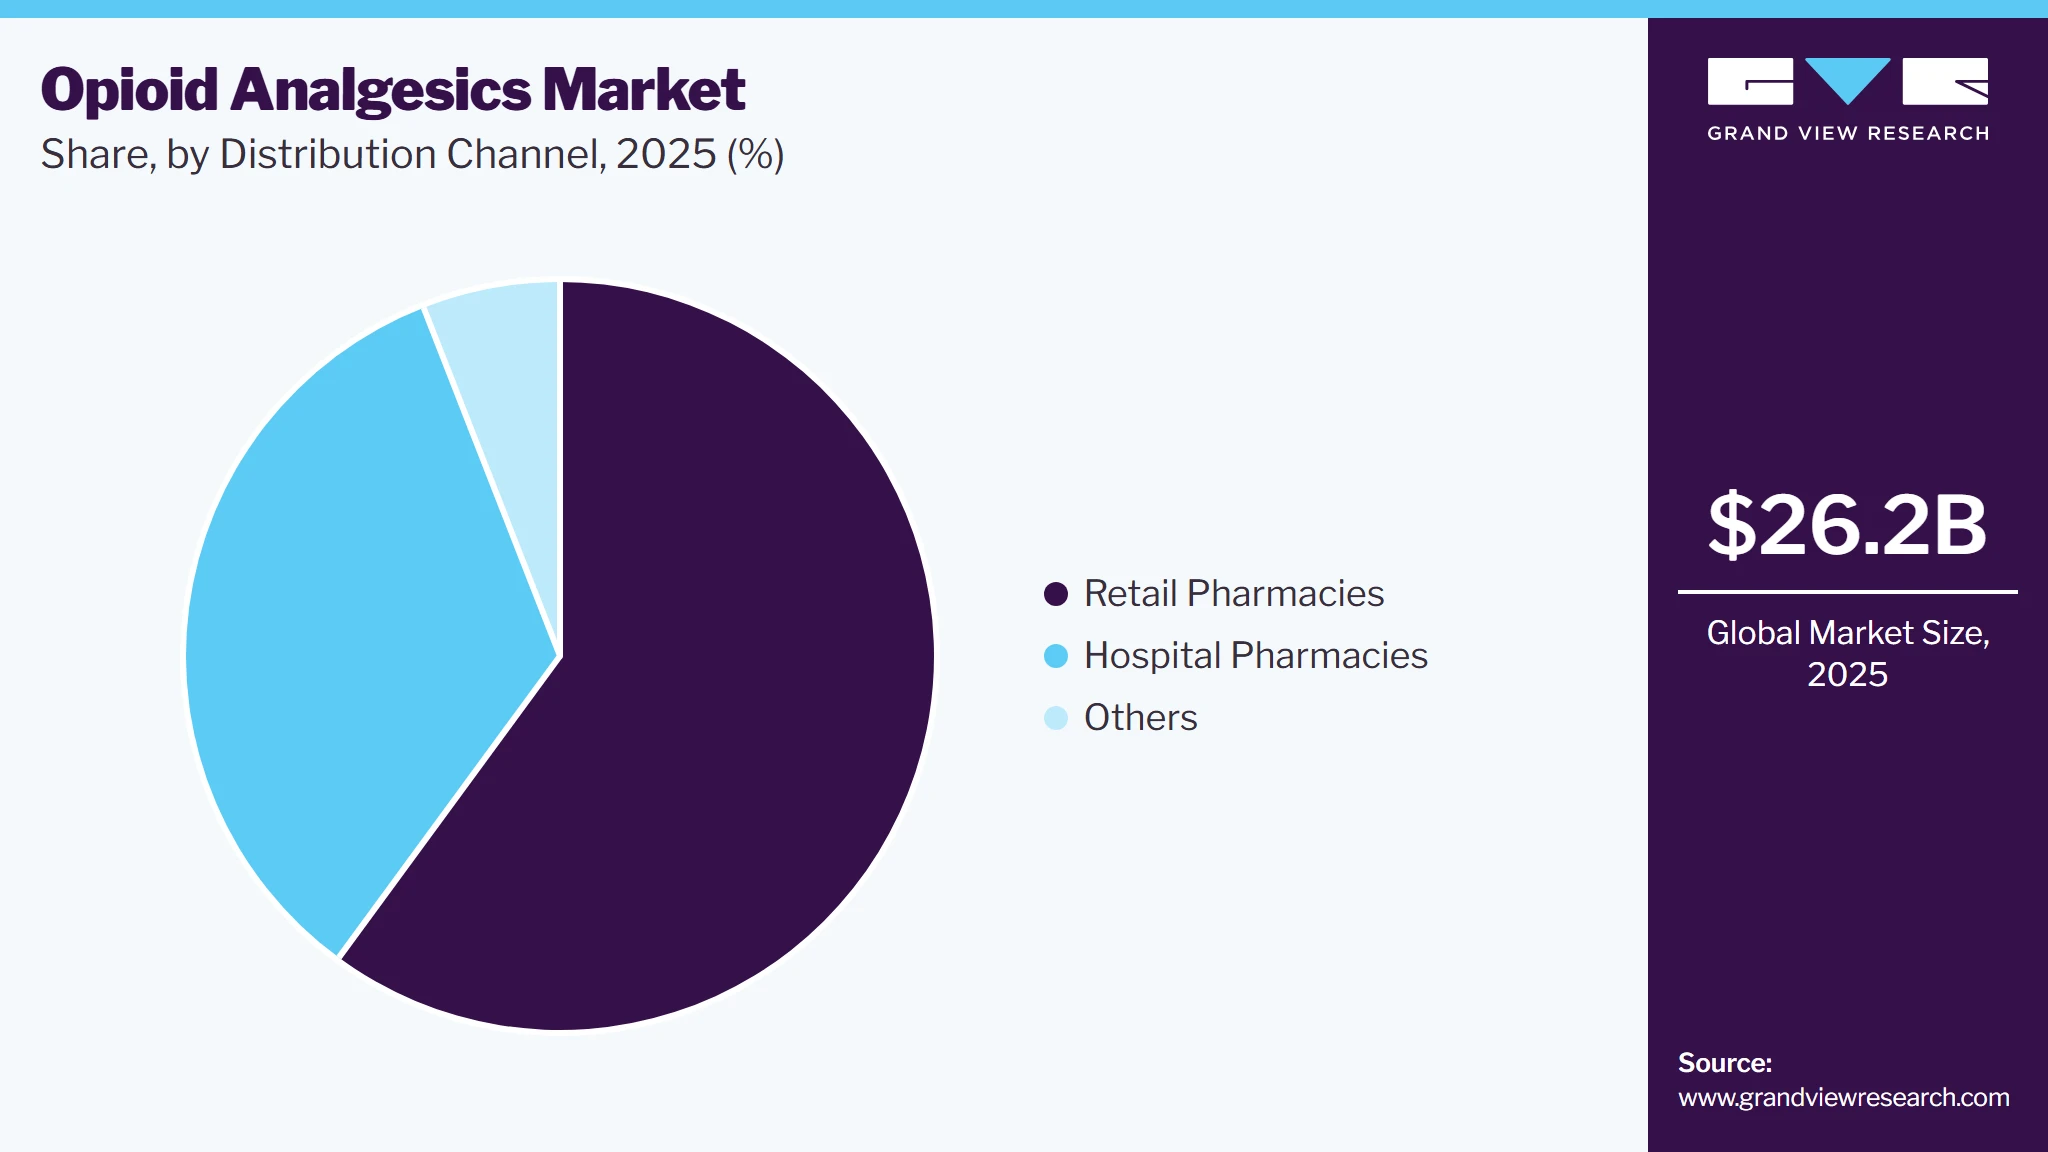
The retail pharmacies segment dominated the market with the largest revenue share of 60.1% in 2025, supported by prescription dispensing for outpatient pain management, the accessibility of local pharmacies, the availability of generic opioid medicines, established pharmacist-patient interactions, repeat prescription services, and the distribution of oral formulations. Retail pharmacies serve patients recovering from surgery, managing injuries, and receiving treatment for selected chronic pain conditions. Their role in dispensing prescription medicines supports access to opioid analgesics outside hospital care. Product availability and pharmacy distribution networks also contribute to segment revenue. However, dispensing remains subject to prescription validation and national controlled substance regulations. Continued demand for outpatient pain treatment supports the role of retail pharmacies in supplying opioid analgesics, while product availability and dispensing practices vary across countries according to regulatory requirements.
 To learn more about this report, Download Free Sample Report
The hospital pharmacies segment is projected to grow at the fastest CAGR of 4.8% during the forecast period, supported by the use of opioid analgesics in inpatient care and hospital-managed treatment. Hospitals administer these medicines to manage moderate-to-severe pain following surgical procedures, traumatic injuries, and other medical interventions. The need for injectable opioids, including morphine and hydromorphone, also supports demand through hospital pharmacies, particularly when patients require rapid pain relief or cannot take oral medicines. In addition, hospital pharmacies operate under controlled dispensing procedures and medical supervision, supporting the use of opioid analgesics in acute care. The growing demand for surgical services, cancer-related pain management, and emergency treatment further contributes to segment growth. Hospitals also require reliable access to approved opioid formulations to support treatment continuity. These factors support the role of hospital pharmacies in the distribution of opioid analgesics during the forecast period.
Regional Insights
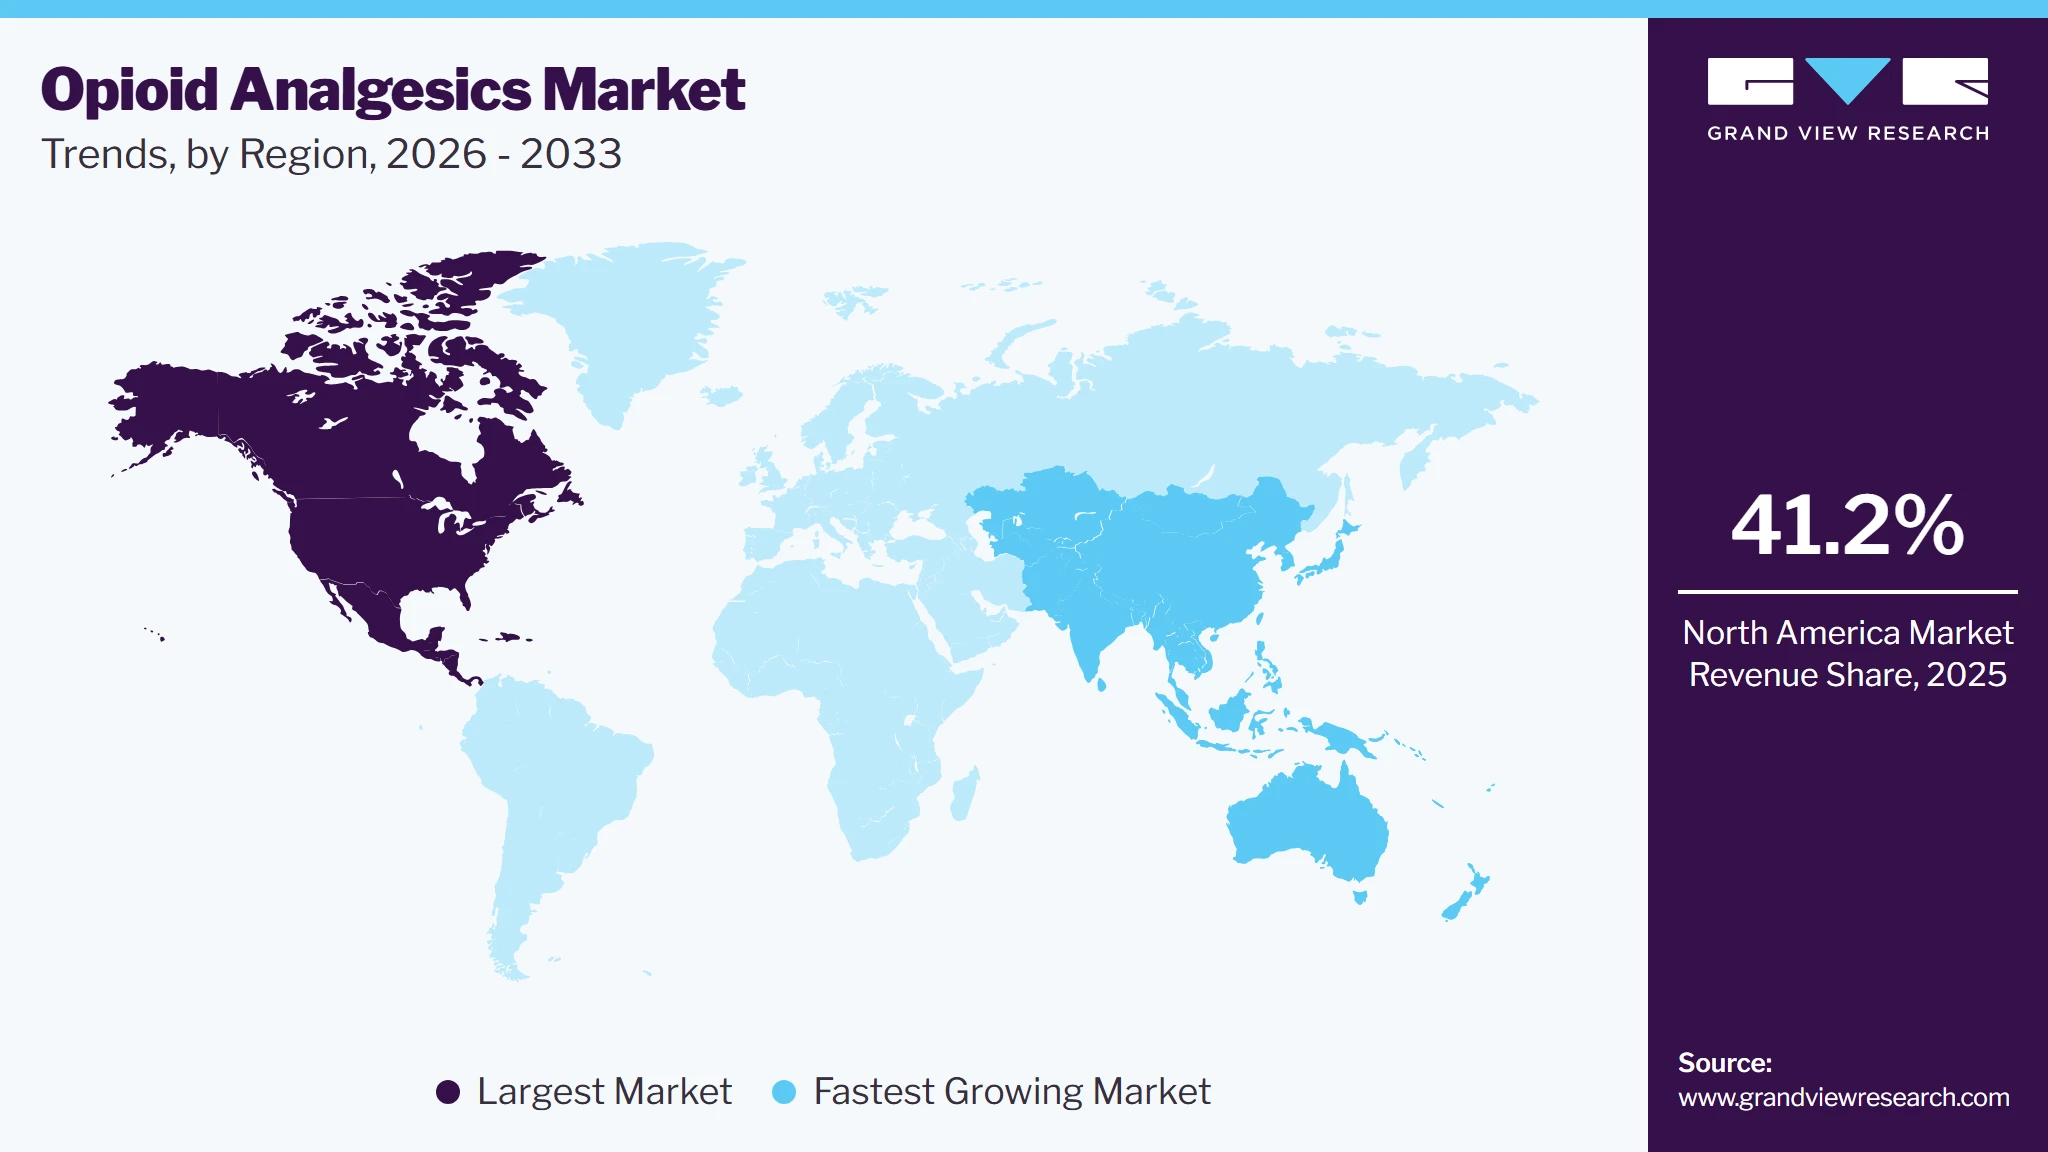
The North America opioid analgesics market held the largest revenue share of 41.2% in 2025, supported by demand for pain management across surgical care, cancer treatment, and trauma care. The region has an established pharmaceutical distribution network serving hospitals, retail pharmacies, and outpatient facilities. The use of prescription opioids in acute pain treatment contributes to regional demand. Access to different formulations, including oral and injectable medicines, supports treatment across clinical settings. However, concerns about dependence, overdose, and misuse influence prescribing practices. Regulatory controls and the use of non-opioid treatments also shape product demand across the region.
 To learn more about this report, Download Free Sample Report
U.S. Opioid Analgesics Market Trends
The opioid analgesics market in the U.S. accounted for the largest market revenue share in 2025, supported by demand for postoperative pain relief, cancer-related pain management, and treatment of severe injuries. Hospitals and retail pharmacies provide access to a range of prescription opioid formulations. Generic medicines support product availability across established drug categories, including morphine, oxycodone, and hydrocodone. The presence of specialized pain management services also contributes to medicine use across inpatient and outpatient care. However, opioid-related harm and prescribing restrictions influence treatment decisions. Demand depends on clinical need, product availability, and compliance with controlled-substance requirements.
Europe Opioid Analgesics Market Trends
The opioid analgesics market in Europe is supported by demand for pain control in cancer care, surgery, palliative care, and trauma treatment. Hospitals remain an important distribution channel for injectable opioids used in acute and severe pain. Oral formulations support treatment after hospital discharge and in outpatient care. Access to opioid medicines varies across countries according to prescribing practices, healthcare infrastructure, and national regulations. Generic medicines contribute to supply across established product categories. Safety monitoring and the use of non-opioid treatments influence prescribing decisions throughout the region.
The UK opioid analgesics market is driven by the need for postoperative pain management, cancer pain relief, and treatment of selected chronic pain conditions. Hospital services use injectable and oral opioids according to clinical requirements. Retail pharmacies support the dispensing of prescription medicines for outpatient treatment. Prescribing guidance and monitoring requirements influence the selection and duration of opioid therapy. Concerns about dependence and long-term use encourage healthcare providers to assess treatment benefits and risks. Demand also depends on access to palliative care, pain management services, and suitable alternative medicines.
The opioid analgesics market in Germany is supported by demand for pain management in surgical procedures, cancer treatment, and palliative care. Hospital pharmacies supply injectable formulations for patients requiring supervised treatment. Oral medicines support pain control after discharge and during outpatient care. Established pharmaceutical distribution channels support the availability of branded and generic opioid products. Prescribing decisions depend on clinical need, patient condition, and applicable controlled-substance requirements. Safety monitoring and the availability of alternative pain treatments influence product selection across healthcare facilities.
The France opioid analgesics market is driven by demand for pain relief following surgery, during cancer treatment, and in palliative care. Hospitals use opioid medicines when patients require treatment for moderate-to-severe pain. Oral formulations support outpatient pain management, while injectable products serve patients requiring administration under medical supervision. Retail pharmacies provide access to prescribed medicines under applicable dispensing rules. Prescribing guidance and safety monitoring influence treatment duration and product selection. The availability of non-opioid medicines also affects opioid use across acute and chronic pain applications.
Asia-Pacific Opioid Analgesics Market Trends
The opioid analgesics market in the Asia Pacific is projected to grow at the fastest CAGR of 7.7% during the forecast period, supported by expanding access to surgical care, cancer treatment, and pain management services. Growth in hospital infrastructure and pharmaceutical distribution supports the supply of opioid medicines across the region. Increasing access to generic formulations also contributes to product availability in price-sensitive healthcare markets. Demand varies across countries according to healthcare access, clinical practices, and the availability of essential pain medicines. Regulatory controls and concerns about dependence influence prescribing and dispensing. The regional growth rate also depends on improvements in diagnosis, treatment access, and pain management services.
The Japan opioid analgesics market is supported by demand for pain control in cancer treatment, surgical care, and palliative care. Hospitals use injectable opioids for selected patients requiring supervised pain relief. Oral formulations support continued treatment outside hospital care. The availability of prescribed medicines through established healthcare and pharmacy channels contributes to product access. Clinical assessment and safety monitoring influence opioid selection and treatment duration. Demand also depends on the management of chronic pain and access to specialist pain services.
The opioid analgesics market in China is driven by demand for pain management in cancer care, surgery, and trauma treatment. Hospital-based care remains an important source of opioid use, particularly for injectable medicines and severe pain conditions. Domestic pharmaceutical manufacturing supports the supply of selected generic opioid products. Expanding access to cancer diagnosis and treatment also contributes to the need for pain relief. Controlled-substance regulations affect prescribing, distribution, and product availability. Differences in healthcare access across urban and rural areas continue to influence the use of opioid medicines.
Latin America Opioid Analgesics Market Trends
The opioid analgesics market in Latin America is supported by demand for postoperative pain management, cancer care, trauma treatment, and palliative care. Hospitals account for an important part of opioid use in acute and severe pain conditions. Retail pharmacies support access to prescribed oral formulations in outpatient care. Generic medicines contribute to supply in price-sensitive healthcare markets. Access varies across countries according to healthcare infrastructure, medicine availability, and prescribing practices. Regulatory controls and concerns about opioid misuse influence product distribution and treatment decisions.
The Brazil opioid analgesics market is driven by demand for pain management in surgery, cancer treatment, and emergency care. Hospitals use opioid medicines for patients requiring treatment for severe pain. Oral formulations support outpatient treatment, while injectable products serve hospital-based care. Pharmaceutical distribution networks influence the availability of generic and branded medicines. Prescribing and dispensing requirements affect patient access to controlled medicines. Demand also depends on access to cancer care, trauma services, and palliative care across the country.
Middle East & Africa Opioid Analgesics Market Trends
The opioid analgesics market in the Middle East & Africa is anticipated to grow at a significant CAGR during the forecast period. Hospitals are important suppliers of injectable opioids for patients requiring supervised treatment. Oral formulations support pain management outside hospital care where prescribed medicines are available. Regional demand varies with healthcare infrastructure, medicine supply, and access to specialist services. Controlled substance regulations influence prescribing and distribution across countries. Limited access to essential pain medicines in some areas also affects the availability and use of opioid analgesics.
The Saudi Arabia opioid analgesics market is supported by demand for postoperative pain relief, cancer-related pain management, and treatment of severe injuries. Hospitals use injectable and oral opioids according to patient needs and clinical guidance. The expansion of specialized medical services contributes to demand for pain management products. Hospital pharmacies play an important role in dispensing medicines for inpatient care. Prescribing controls and monitoring requirements influence access to opioid medicines. Demand also depends on the availability of palliative care, specialist treatment services, and suitable pain management options.
Key Opioid Analgesics Company Insights
The opioid analgesics industry is moderately fragmented, as competition differs across drug categories and countries. Teva Pharmaceutical Industries Ltd., Pfizer Inc., Hikma Pharmaceuticals plc, Mallinckrodt plc, Collegium Pharmaceutical, Inc., Grünenthal GmbH, Mundipharma International Limited, Purdue Pharma L.P., Amneal Pharmaceuticals, Inc., and Viatris Inc. compete in the branded and generic opioid medicines market. Competition varies by product portfolio, manufacturing capacity, regulatory approvals, pricing, and geographical presence.
Generic manufacturers contribute to product availability and price competition, while companies offering specialized formulations, including extended-release and abuse-deterrent products, serve specific treatment requirements. Competitive conditions also depend on prescribing regulations, controlled substance requirements, and access to hospital and retail pharmacy channels. Companies with broad product portfolios, established distribution networks, and the ability to meet regulatory requirements maintain a presence across different drug categories and regional markets.
Key Opioid Analgesics Companies
The following key companies have been profiled for this study on the opioid analgesics market.
-
Teva Pharmaceutical Industries Ltd.
-
Pfizer Inc.
-
Hikma Pharmaceuticals plc
-
Mallinckrodt plc
-
Collegium Pharmaceutical, Inc.
-
Grünenthal GmbH
-
Mundipharma International Limited
-
Purdue Pharma L.P.
-
Amneal Pharmaceuticals, Inc.
-
Viatris Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Pfizer Inc.
- Maintain branded and generic opioid portfolios across key drug types, including morphine, oxycodone, hydrocodone, and hydromorphone.
- Expand oral, injectable, and other approved formulations to address hospital and outpatient pain management needs.
- Maintain manufacturing quality, regulatory compliance, and distribution networks to support product supply across approved markets.
- Established manufacturing capabilities and distribution networks serving hospitals, wholesalers, and retail pharmacies.
- Broad product portfolios covering multiple opioid drug types and pain management applications.
- Experience in regulatory compliance, generic medicine production, and prescription drug supply across markets.
- Generic competition creates pricing pressure for established opioid medicines.
- Controlled-substance regulations increase manufacturing, distribution, and compliance requirements.
- Safety concerns and non-opioid alternatives can affect prescribing practices and product demand.
Emerging Players: Collegium Pharmaceutical Inc.
- Focus on pain management medicines and selected opioid formulations for specific clinical requirements.
- Develop differentiated products, including extended-release and abuse-deterrent formulations where applicable.
- Strengthen relationships with healthcare providers, pharmacies, and wholesalers to support product availability.
- Focused experience in pain management and selected opioid treatment categories.
- Formulation design and approved indications help address specific treatment needs.
- Prescription drug marketing and distribution experience supports access to healthcare channels.
- Focused product portfolios can increase dependence on selected medicines.
- Specific products face risks from generic competition and changes in prescribing practices.
- Regulatory controls, safety concerns, and non-opioid alternatives can limit product demand.
Recent Developments
-
In June 2026, Mallinckrodt plc agreed to sell its Percocet and Endocet businesses to Par Health, subject to closing conditions. The transaction involved two opioid combination-product businesses and marked a shift in the company's product portfolio.
-
In February 2026, Hikma Pharmaceuticals plc launched generic tapentadol immediate-release tablets in the U.S. for the treatment of acute pain requiring opioid therapy when alternative treatments were inadequate.
-
In July 2025, Hikma Pharmaceuticals plc launched morphine sulfate injection in prefilled syringes in the U.S. The product was available in concentrations of 2 mg/mL and 4 mg/mL for pain requiring opioid treatment.
Opioid Analgesics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 26.2 billion
Estimated market size in 2026
USD 27.2 billion
Projected market size by 2033
USD 37.1 billion
Growth rate
CAGR of 4.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Drug type, application, route of administration, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key company profiled
Teva Pharmaceutical Industries Ltd.; Pfizer Inc.; Hikma Pharmaceuticals plc; Mallinckrodt plc; Collegium Pharmaceutical, Inc.; Grünenthal GmbH; Mundipharma International Limited; Purdue Pharma L.P.; Amneal Pharmaceuticals, Inc.; Viatris Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Opioid Analgesics Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global opioid analgesics market report based on drug type, application, route of administration. distribution channel, and region:
-
Drug Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Morphine
-
Codeine
-
Oxycodone
-
Hydrocodone
-
Hydromorphone
-
Others
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Acute Pain
-
Chronic Pain
-
-
Route of Administration Outlook (Revenue, USD Billion, 2021 - 2033)
-
Oral
-
Parenteral
-
Transdermal
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
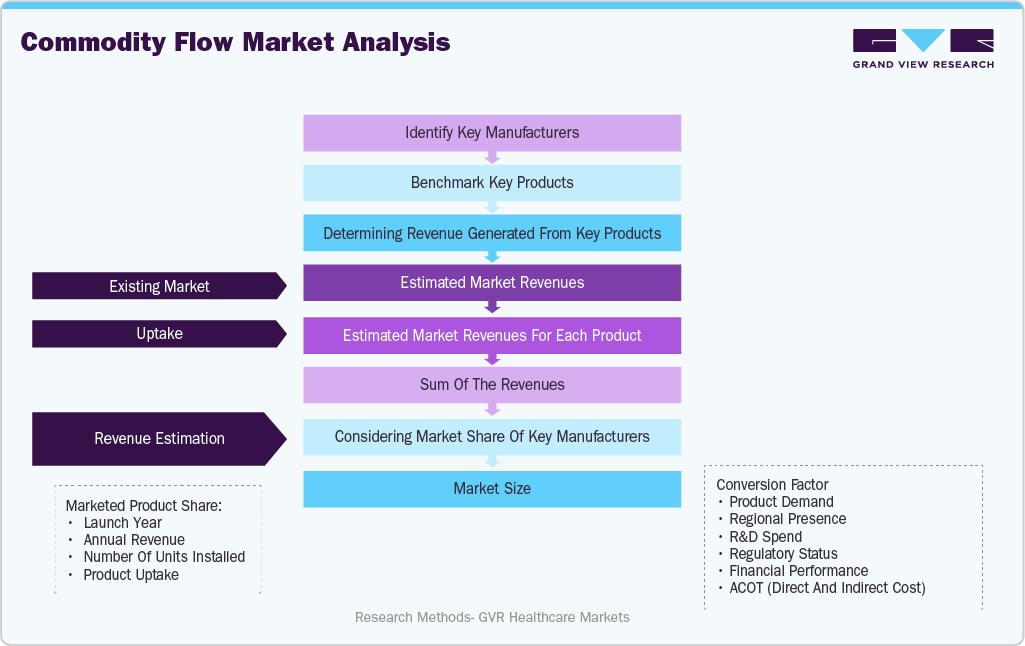
The opioid analgesics market is estimated using a commodity flow approach, supported by product-level revenue assessment and market share analysis. The study identifies key manufacturers and their opioid analgesic portfolios across morphine, codeine, oxycodone, hydrocodone, hydromorphone, and other drug types. The analysis tracks the flow of opioid medicines from manufacturers through distributors, hospitals, retail pharmacies, and other permitted channels to estimate product availability and sales. Product pricing, sales volumes, company disclosures, annual reports, and verified product information are used to assess market value. For companies that do not report opioid-specific revenue, estimates are derived from product availability, pricing, sales information, and geographic presence. The analysis considers application, Route of Administration, and distribution channel to prevent double counting. Product-level estimates are aggregated and validated against available company revenue, market share information, and country-level data before finalizing the market size estimate.
Segment Definition
Segment - Drug Type
Revenue capture definition
Morphine
Includes opioid analgesic products containing morphine as the active opioid ingredient, supplied in oral, injectable, and other approved formulations for pain management.
Codeine
Includes opioid analgesic products containing codeine as the active opioid ingredient, supplied as single-ingredient or combination products for approved pain relief indications.
Oxycodone
Includes opioid analgesic products containing oxycodone as the active opioid ingredient, including immediate-release, extended-release, and approved combination formulations used for pain management.
Hydrocodone
Includes opioid analgesic products containing hydrocodone as the active opioid ingredient, including single-ingredient and combination formulations approved for pain relief.
Hydromorphone
Includes opioid analgesic products containing hydromorphone as the active opioid ingredient, supplied in approved dosage forms for the treatment of pain.
Others
Includes opioid analgesic products containing other active ingredients, such as fentanyl, tramadol, tapentadol, methadone, and other opioids approved for pain management.
Segment - Application
Revenue capture definition
Acute Pain
Includes opioid analgesics used for short-term pain associated with surgery, traumatic injuries, medical procedures, and other sudden-onset conditions requiring opioid treatment.
Chronic Pain
Includes opioid analgesics used for persistent or recurring pain associated with cancer and other long-term conditions when opioid treatment is clinically indicated.
Segment - Route of Administration
Revenue capture definition
Oral
Includes opioid analgesics administered through the mouth as tablets, capsules, solutions, suspensions, and other approved oral dosage forms.
Parenteral
Includes opioid analgesics administered by injection or infusion through routes such as intravenous, intramuscular, and subcutaneous administration.
Transdermal
Includes opioid analgesics delivered through the skin using approved medicated patches or other transdermal systems that release the active ingredient for absorption.
Others
Includes opioid analgesics administered through other approved routes, including buccal, sublingual, transmucosal, rectal, and intranasal formulations used for pain relief.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Includes opioid analgesics dispensed by hospital pharmacies for inpatient treatment and hospital-managed outpatient care.
Retail Pharmacies
Includes opioid analgesics dispensed through physical community pharmacies and other retail pharmacy outlets for outpatient treatment.
Others
Includes opioid analgesics dispensed through authorized channels other than hospital pharmacies and physical retail pharmacies, including licensed online pharmacies and other eligible dispensing services.
Estimation Model
 To learn more about this report, Download Free Sample Report
Customization Table
Client Request
Customization Delivered
Value Adds
Opioid Analgesics Market Assessment
Assessed drug types, prescription status, applications, routes of administration, and distribution channels. Evaluated market drivers, restraints, opportunities, pricing factors, prescribing requirements, and product availability.
Supported market sizing, segment evaluation, and assessment of demand patterns across opioid drug categories and pain management applications.
Competitive Benchmarking
Evaluated market participants based on product portfolios, formulations, manufacturing capabilities, distribution networks, operating strategies, competitive positioning, and business strengths and weaknesses.
Helped assess competitive positioning, product differentiation, portfolio coverage, and key factors affecting competition between branded and generic opioid medicines.
Market Opportunity Assessment
Analyzed pain management requirements, product availability, prescribing practices, healthcare access, regulatory controls, and pharmaceutical distribution channels. Assessed factors affecting opioid use across acute and chronic pain applications.
Supported the identification of market opportunities, evaluation of demand patterns, and assessment of factors affecting product access, prescribing practices, and market growth.
About the Author(s)
Pharmaceuticals Research Team
· PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the industry. All findings are based on proprietary databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


