
- Home
- »
- Medical Devices
- »
-
Oral Wound Dressing Market Size & Share Report 2026-2033GVR Report cover

Oral Wound Dressing Market (2026 - 2033) Size, Share & Trends Analysis Report By Product (Bioadhesive Gels, Oral Rinses/Mouthwashes), By Material Type, By Application (Surgical Wounds, Traumatic Lesions), By End Use, By Distribution Channel, And Regional Segment Forecasts
Market Size, 2025
$2.5BMarket Estimate, 2026
$2.8BMarket Forecast, 2033
$5.3BCAGR, 2026–2033
9.7%Oral Wound Dressing Market Summary
The global oral wound dressing market size was valued at USD 2.5 billion in 2025 and is projected to grow from USD 2.8 billion in 2026 to USD 5.3 billion by 2033, growing at a CAGR of 9.7% from 2026 to 2033. North America dominated the oral wound dressing industry, accounting for the largest revenue share of 40.20% in 2025. The market is primarily driven by the increasing prevalence of oral ulcers, periodontal diseases, and oral mucositis associated with cancer therapies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- The oral wound dressing market in the U.S. accounted for the largest share of North American revenue in 2025.
- By product, bioadhesive gels oral wound dressings led the market with the largest revenue share in 2025.
- By material type, natural biopolymer-based led the market with the largest revenue share in 2025.
- By application, surgical wounds accounted for the largest revenue share in 2025.
- By end use, the dental clinics & group practices segment led the market with the largest revenue share in 2025.
Market Size & Forecast
- 2025 Market Size: USD 2.5 Billion
- 2026 Market Size: USD 2.8 Billion
- 2033 Projected Market Size: USD 5.3 Billion
- CAGR (2026-2033): 9.7%
Prism AI by Grand View Research Free to tryAsk a question about the oral wound dressing marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Rising volumes of dental implant procedures, tooth extractions, and other oral surgeries are creating greater demand for products that accelerate healing and reduce post-operative complications. In addition, advancements in bioadhesive hydrogels, collagen-based dressings, and antimicrobial wound care technologies are improving clinical outcomes and supporting wider adoption across hospitals and dental clinics.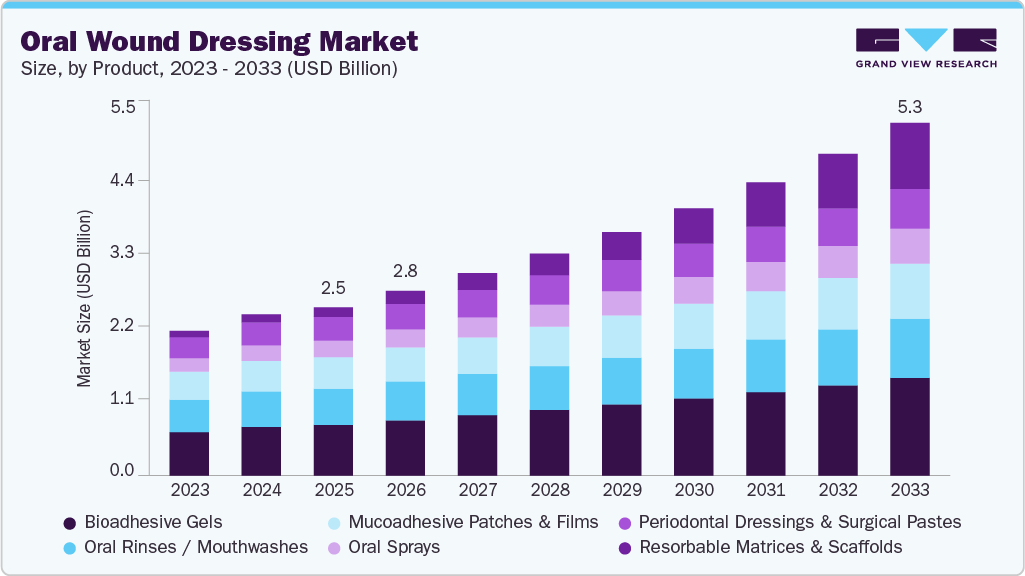 To learn more about this report, Download Free Sample Report
The growing global burden of oral diseases, affecting approximately 3.7 billion people worldwide, is increasing the number of patients requiring treatment for oral ulcers, periodontal conditions, and surgical wounds. This expanding patient population is driving demand for oral wound dressings that promote faster healing, reduce pain, and protect oral tissues from infection and further injury.
Key Statistics from WHO Oral Health Fact Sheet (2025)
Statistic
Value
People affected by oral diseases globally
~3.7 billion people
Global population affected by oral diseases
Nearly 45-50% of the world's population
People affected by untreated dental caries (tooth decay)
~2.5 billion people
People affected by severe periodontal (gum) disease
~1 billion people
People experiencing complete tooth loss (edentulism)
~350 million people
Annual new oral cancer cases
~380,000 cases
Population affected living in middle-income countries
3 out of 4 people (75%)
Increase in oral disease cases over the last 30 years
~1 billion additional cases
Global spending on major oral diseases (2019)
>USD380 billion
Most common health condition globally
Untreated dental caries in permanent teeth
Source: WHO
The rising incidence of oral cancer is a significant market driver, as patients frequently undergo surgical resections, radiation therapy, and chemotherapy that result in painful oral wounds and mucosal damage. These treatments increase the need for advanced wound dressings that can protect tissues, reduce pain, prevent infection, and accelerate healing. In addition, the growing number of oral cancer cases worldwide is driving demand for bioadhesive, antimicrobial, and regenerative oral wound care products across hospitals and oncology centers.
Estimated Number of New Oral Cancer Cases and Deaths by Sex, U.S., 2025
Cancer Type
Estimated New Cases (Both Sexes)
Male
Female
Estimated Deaths (Both Sexes)
Male
Female
Oral Cavity & Pharynx
59,660
42,500
17,160
12,770
9,130
3,640
Tongue
20,040
14,120
5,920
3,270
2,210
1,060
Mouth
15,730
9,090
6,640
3,360
2,090
1,270
Pharynx
21,640
17,800
3,840
4,590
3,630
960
Other Oral Cavity
2,250
1,490
760
1,550
1,200
350
Source: American Cancer Society
Advancements in bioadhesive and regenerative technologies are significantly driving the market by improving the effectiveness and retention of wound care products within the moist oral environment. Innovations such as collagen-based dressings, hydrogels, nanofiber scaffolds, and growth factor-infused materials promote faster tissue regeneration, reduce pain, and enhance healing outcomes. These next-generation solutions are adopted in dental surgeries, oral ulcer management, and cancer-related oral wound care, supporting overall market growth.
-
Rivelin-CLO (Dermtreat) utilizes bioadhesive patch technology that adheres to oral mucosa and delivers medication directly to lesions, improving localized treatment and patient compliance.
-
Hyaluronic acid hydrogels are used in periodontal and oral surgery applications because they promote angiogenesis, tissue regeneration, and accelerated wound healing.
-
Advanced hyaluronic acid-based biomaterial systems are emerging as next-generation oral wound dressings for managing extraction wounds, implant procedures, and oral ulcers.
-
Collagen-based regenerative dressings and matrices are gaining adoption in periodontal regeneration and dental implant procedures due to their ability to support cellular migration and tissue repair.
Market Dynamics
The increasing prevalence of oral diseases, including periodontal disease, oral ulcers, oral mucositis, dental caries, and oral cancers, is a major market driver. The growing incidence of these conditions has led to a higher number of dental procedures and oral surgeries that require effective wound management solutions. In addition, aging populations, tobacco use, poor oral hygiene, and rising chronic disease burden are contributing to the demand for advanced oral wound care products. As healthcare providers focus on improving healing outcomes and patient comfort, the adoption of oral wound dressings continues to expand globally.
The availability of alternative treatment options acts as a restraint on the market. Many oral wounds and lesions can be managed with conventional therapies, such as antiseptic mouth rinses, topical analgesics, corticosteroid gels, antimicrobial agents, and systemic medications, often at lower cost. In mild-to-moderate cases, healthcare professionals prefer these readily available treatments over specialized wound dressings. This reduces demand for advanced oral wound care products and can limit market growth, particularly in regions with lower awareness of the benefits of oral wound dressings.
Market Concentration & Characteristics
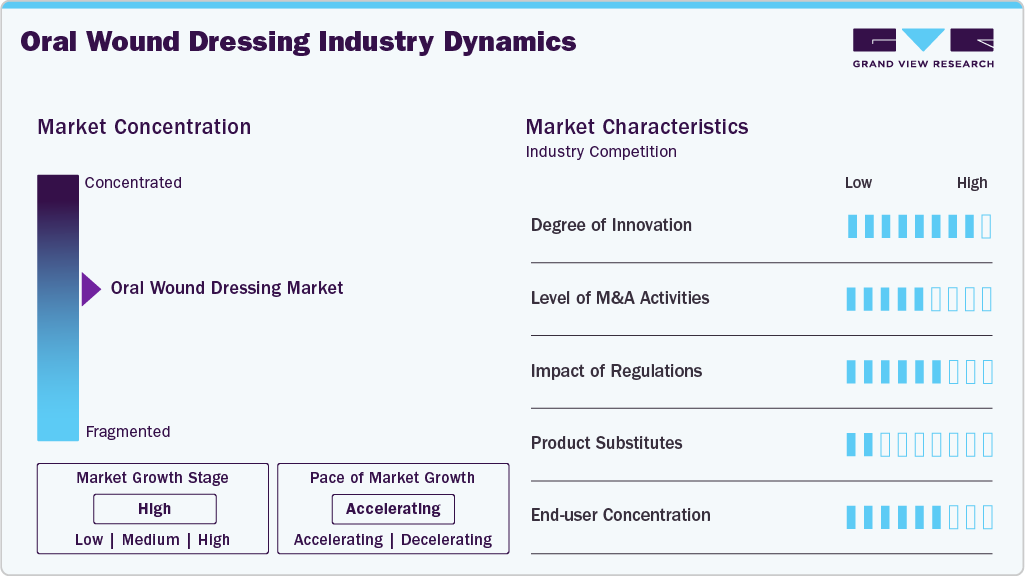
The degree of innovation in the oral wound dressing industry is moderate to high, supported by continuous advancements in bioactive and regenerative wound care technologies. For instance, Ora-Aid has developed a self-adhesive oral wound dressing that protects surgical and traumatic oral wounds while enhancing patient comfort. In addition, Sunstar offers GUM AftaClear products designed to create a protective barrier over oral lesions and ulcers. In addition, research institutions and manufacturers are exploring collagen- and hyaluronic acid-based, as well as antimicrobial, dressings that promote tissue regeneration and reduce healing time. The emergence of drug-loaded mucoadhesive patches and biodegradable oral wound dressings further demonstrates the market’s ongoing innovation toward more effective post-surgical and wound management solutions.
The level of mergers and acquisitions in the oral wound dressing industry is moderate, with consolidation activity primarily driven by larger wound care and dental product companies seeking to expand their advanced wound management portfolios. Market participants are increasingly acquiring specialized biomaterials, regenerative medicine, and oral care businesses to strengthen their technological capabilities and geographic presence. M&A activity is also focused on gaining access to innovative products such as collagen-based dressings, antimicrobial formulations, and tissue regeneration technologies. As demand for post-surgical oral wound care grows, strategic acquisitions are expected to increase, particularly among companies looking to enhance their presence in the broader wound care and dental markets.
 To learn more about this report, Download Free Sample Report
Regulations have a high impact on the oral wound dressing industry, as products must comply with stringent medical device and biocompatibility standards before commercialization. Regulatory requirements from organizations such as the U.S. Food and Drug Administration, European Commission, and other national health authorities ensure product safety, sterility, and clinical effectiveness. While these regulations increase development costs and extend approval timelines, they also enhance product quality and patient confidence. In addition, stricter standards are encouraging manufacturers to invest in advanced materials, clinical validation, and quality management systems, supporting long-term market growth.
The oral wound dressing industry exhibits moderate to high end-use concentration, with demand primarily driven by hospitals, dental clinics, oral surgery centers, and specialty dental practices. Hospitals and dental clinics account for the largest share of consumption due to the high volume of tooth extractions, implant procedures, periodontal surgeries, and treatment of oral lesions. However, the growing availability of easy-to-use oral wound care products is gradually expanding in homecare settings. Despite this trend, professional healthcare facilities remain the dominant end users, resulting in a relatively concentrated demand structure.
Product Insights
Bioadhesive gels dominated the market in 2025 due to their ability to firmly adhere to moist oral mucosa, ensuring prolonged retention at the wound site and sustained therapeutic action. These gels provide a protective barrier against mechanical irritation, reduce pain, support faster tissue regeneration, and improve patient comfort and compliance. Their mucoadhesive properties enable localized delivery of active ingredients, enhancing treatment effectiveness for oral ulcers, surgical wounds, and mucosal lesions. Growing demand for non-invasive, easy-to-apply wound care solutions further strengthened the adoption of bioadhesive gel formulations in oral healthcare.
Resorbable matrices and scaffolds are expected to be the fastest-growing segment of the market during the forecast period, due to their ability to support tissue regeneration and accelerate wound healing without requiring removal. These advanced biomaterials provide a temporary three-dimensional structure that promotes cell migration, vascularization, and new tissue formation in oral surgical and traumatic wounds. Increasing adoption of regenerative dentistry, periodontal procedures, and biomaterial-based wound management solutions is driving demand for resorbable scaffolds. Their biodegradability, reduced risk of secondary trauma, and improved clinical outcomes further contribute to rapid market growth.
Material Type Insights
Natural biopolymer-based oral wound dressings dominated the market in 2025 due to their excellent biocompatibility, biodegradability, and ability to promote a favorable healing environment. Materials such as collagen, chitosan, alginate, and hyaluronic acid are widely used because they support tissue regeneration, maintain moisture balance, and reduce inflammation in oral wounds. Their low toxicity and minimal risk of adverse reactions make them highly suitable for managing oral ulcers, surgical sites, and mucosal injuries. The growing preference for bioactive, naturally derived wound care solutions further strengthened the adoption of natural biopolymer-based dressings across dental and oral healthcare settings.
Hybrid/composite materials are expected to be the fastest-growing segment in the market during the forecast period, driven by their ability to combine the advantages of both natural and synthetic biomaterials. These advanced dressings offer enhanced mechanical strength, controlled biodegradation, improved adhesion, and superior wound-healing performance compared to single-material products. Their multifunctional properties enable effective moisture management, antimicrobial protection, and sustained delivery of therapeutic agents in complex oral wounds. Increasing research in tissue engineering and regenerative oral care is further accelerating the adoption of hybrid and composite wound dressing technologies.
Application Insights
Surgical wounds dominated the market in 2025, driven by the rising volume of dental surgeries, tooth extractions, periodontal procedures, implant placements, and oral reconstructive interventions. These wounds require specialized dressings to control bleeding, protect healing tissues, reduce infection risk, and support rapid mucosal regeneration. The growing adoption of advanced oral surgical procedures and increasing demand for effective post-operative care contributed significantly to segment growth. In addition, healthcare providers increasingly preferred bioactive, absorbable dressings to improve healing outcomes and patient comfort after oral surgery.
Regenerative procedures are expected to be the fastest-growing application segment in the market during the forecast period, driven by increasing adoption of tissue engineering, bone grafting, and periodontal regeneration therapies. These procedures require advanced wound dressings that support cell proliferation, angiogenesis, and tissue remodeling while protecting the healing site. The growing demand for dental implants, guided tissue regeneration, and minimally invasive oral surgeries is accelerating the adoption of bioactive and regenerative wound care products. In addition, advancements in biomaterials and scaffold technologies are enhancing clinical outcomes and fueling segment growth.
End Use Insights
Dental clinics and group practices dominated the market in 2025 due to the high volume of routine and advanced dental procedures performed in these settings, including tooth extractions, implant placements, periodontal surgeries, and soft tissue treatments. These facilities are primary users of oral wound dressings to manage post-operative healing, reduce complications, and improve patient outcomes. The growing number of private dental practices and expanding dental service organizations further strengthened product demand. In addition, increasing patient preference for outpatient dental care supported the segment’s leading market position.
Specialty oral surgery centers are expected to be the fastest-growing end user segment in the market during the forecast period, driven by the increasing number of complex procedures such as dental implant surgeries, maxillofacial reconstructions, bone grafting, and periodontal regenerative treatments. These centers require advanced wound management solutions to support faster healing, minimize complications, and improve surgical outcomes. The growing shift toward specialized outpatient surgical care and rising demand for minimally invasive oral procedures are further boosting segment growth. In addition, greater adoption of bioactive and regenerative dressings in specialty settings is accelerating market expansion.
Distribution Channel Insights
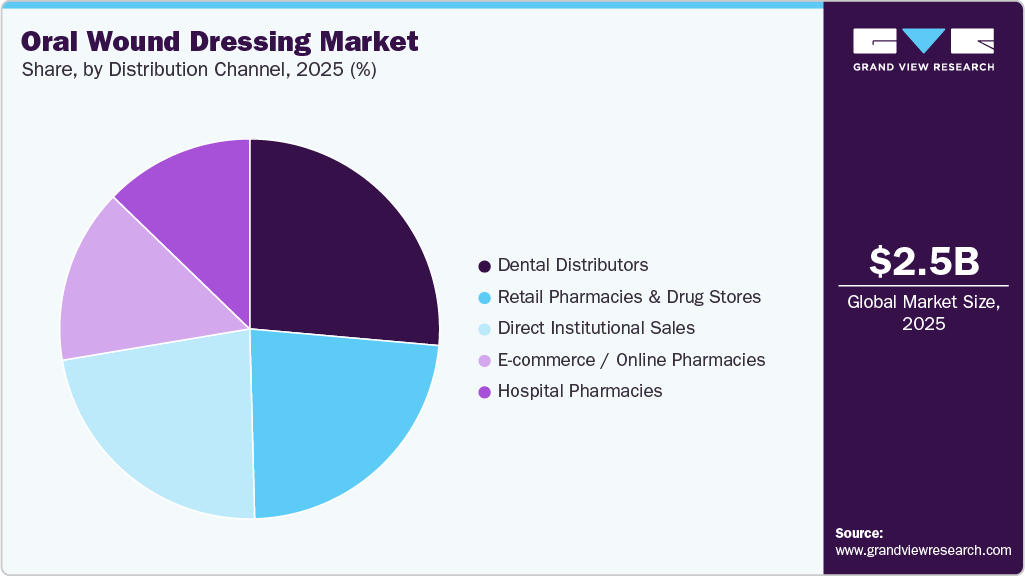
Dental distributors dominated the market in 2025 due to their extensive supply networks, established relationships with dental clinics, group practices, and specialty oral surgery centers, and their ability to ensure timely product availability. These distributors offer a broad portfolio of wound care products, enabling healthcare providers to access multiple brands and advanced dressing solutions through a single procurement channel. Their strong logistics capabilities, inventory management services, and value-added support further strengthened their market position. In addition, the increasing demand for efficient procurement and reliable supply chains contributed to the dominance of dental distributors.
 To learn more about this report, Download Free Sample Report
E-commerce and online pharmacies are expected to be the fastest-growing distribution channels in the market during the forecast period, driven by increasing digitalization of healthcare purchasing and growing consumer preference for convenient online access to medical products. These platforms offer a wide range of oral wound care solutions, competitive pricing, and home delivery services, enhancing product accessibility for both patients and healthcare providers. The expansion of telehealth services and rising internet penetration are further supporting online sales growth. In addition, improved product visibility, customer reviews, and streamlined procurement processes are accelerating adoption through digital channels.
Regional Insights
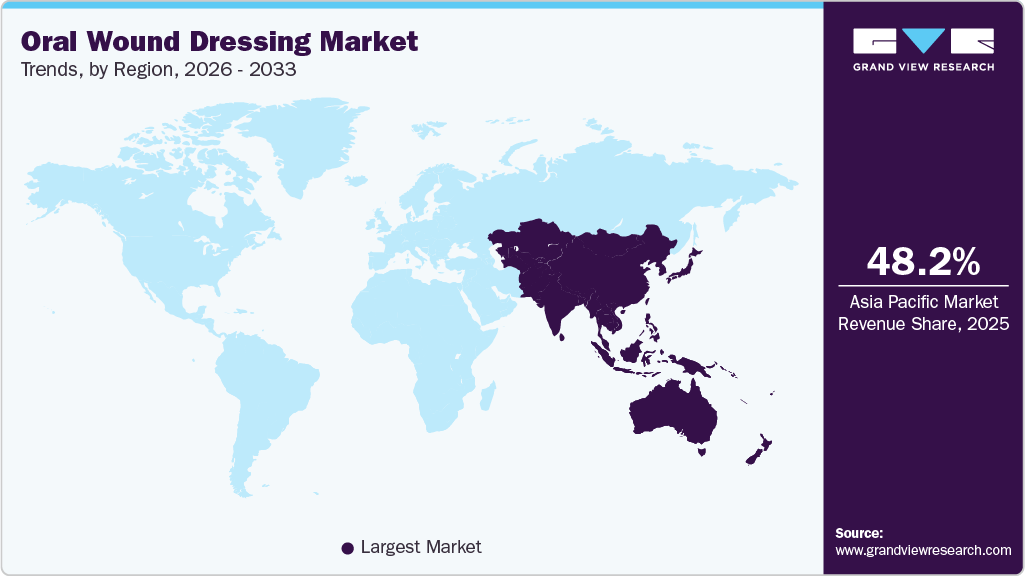
The North America oral wound dressing market accounted for the highest market share of 40.20%, driven by rising numbers of dental implant procedures, tooth extractions, and oral surgeries. The region is also experiencing rising adoption of advanced wound care products, including bioactive, collagen-based, and mucoadhesive dressings that enhance healing outcomes. In addition, strong healthcare infrastructure, high oral health awareness, and continuous product innovation are supporting market expansion across the region.
 To learn more about this report, Download Free Sample Report
U.S. Oral Wound Dressing Market Trends
The oral wound dressing market in the U.S. is driven by rising volumes of dental surgeries, periodontal treatments, and dental implant procedures. Market trends indicate increasing adoption of advanced oral wound care solutions, including collagen-based, antimicrobial, and bioactive dressings that accelerate healing and reduce post-operative complications. In addition, strong investment in dental innovation and growing patient preference for minimally invasive procedures are supporting demand for specialized oral wound management products.
Europe Oral Wound Dressing Market Trends
The oral wound dressing market in Europe is characterized by growing demand for advanced wound care products supported by increasing dental implant placements, oral surgeries, and an aging population. Market trends show rising adoption of biocompatible, collagen-based, and antimicrobial dressings that improve post-operative healing and patient outcomes. In addition, stringent regulatory standards and strong emphasis on innovative dental care solutions are encouraging the development and commercialization of high-performance oral wound dressings across the region.
The UK oral wound dressing market is witnessing increased demand due to the growing number of dental implant procedures, periodontal treatments, and oral surgeries. There is a rising preference for advanced wound management solutions, including collagen-based and antimicrobial dressings, to improve healing outcomes and reduce post-operative complications. Furthermore, increasing awareness of oral health and continued adoption of innovative dental care technologies are supporting market growth in the country.
The oral wound dressing market in France is experiencing significant growth, driven by rising dental procedures and oral surgeries, as well as increasing awareness of post-operative wound management. Demand for advanced oral dressings incorporating collagen, hyaluronic acid, and antimicrobial technologies is increasing as healthcare providers focus on improving healing outcomes and patient comfort. In addition, strong healthcare infrastructure and the growing adoption of innovative dental treatments are supporting market expansion in France.
Asia Pacific Oral Wound Dressing Market Trends
The oral wound dressing market in the Asia Pacific is witnessing rapid growth due to increasing dental tourism, rising oral healthcare awareness, and a growing number of dental implant and oral surgery procedures. Demand for cost-effective and advanced wound care solutions is increasing across countries such as China, Japan, and India. In addition, expanding healthcare infrastructure and greater adoption of innovative dental technologies are supporting market development throughout the region.
Japan oral wound dressing market is driven by the country's aging population, which is increasing the demand for dental procedures, oral surgeries, and post-operative wound management solutions. Market trends indicate growing adoption of advanced oral wound dressings featuring biocompatible, antimicrobial, and regenerative materials to enhance healing and patient comfort. In addition, Japan’s strong focus on healthcare innovation and high standards of dental care continue to support market growth.
Latin America Oral Wound Dressing Market Trends
The oral wound dressing market in Latin America is experiencing steady growth, driven by improved access to dental care services, rising oral surgery procedures, and greater awareness of oral health. Demand for advanced wound management products is gradually increasing, particularly in countries such as Brazil and Mexico, where investments in healthcare infrastructure and dental tourism are expanding. In addition, the adoption of cost-effective oral wound care solutions is driving market growth across the region.
MEA Oral Wound Dressing Market Trends
The oral wound dressing market in MEA is witnessing gradual growth, driven by increasing investments in healthcare infrastructure, expanding dental care services, and rising awareness of oral health. Demand for oral wound management products is growing in countries such as Saudi Arabia, the UAE, and South Africa, driven by the rising number of dental procedures and oral surgeries. In addition, the adoption of advanced wound care technologies is significantly improving across the region.
Key Oral Wound Dressing Company Insights
The market is moderately consolidated, with market share concentrated among established manufacturers offering specialized oral care and wound management products. Competitive positioning is primarily driven by product innovation, clinical effectiveness, distribution reach, regulatory compliance, and the development of advanced bioactive, antimicrobial, and mucoadhesive wound dressing technologies.
Key Oral Wound Dressing Companies
The following key companies have been profiled for this study on the oral wound dressing market.
-
TBM Co.
-
AD Surgical.
-
SUNSTAR Suisse S.A.
-
PULPDENT
-
Septodont Holding
-
Ethicon Inc. (Johnson & Johnson)
-
ZimVie Inc.
-
Ricerfarma s.r.l.
-
BIOINICIA
-
Jiangsu Yenssen Biotech Co.
-
Hager Worldwide
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Septodont Holding
- Mature companies focus on expanding their product portfolios with collagen-based dressings, hyaluronic acid formulations, bioadhesive gels, and regenerative wound-healing solutions to address a broad range of oral surgical and mucosal conditions.
- Established players utilize extensive dental distributor networks, dental service organizations (DSOs), hospitals, and academic partnerships to strengthen market penetration and clinician adoption.
- Established companies benefit from long-standing relationships with dental professionals, extensive clinical validation, and recognized brands that support higher adoption rates.
- Mature players possess well-developed sales networks, regulatory approvals, and distribution channels across multiple countries, enabling broad market access and consistent product availability.
- Large organizational structures and complex approval processes can delay the development and commercialization of new oral wound dressing technologies.
- Extensive manufacturing facilities, global regulatory requirements, and large sales networks increase operational expenses and limit pricing flexibility.
Emerging Players: TBM Co.
- Emerging companies focus on niche technologies such as bioadhesive patches, nanofiber dressings, localized drug-delivery systems, and dissolvable oral wound barriers to differentiate themselves from larger competitors.
- Rather than competing globally at once, they enter high-growth regional markets through local distributors, OEM collaborations, and strategic licensing agreements.
- Emerging companies often introduce differentiated solutions such as bioadhesive oral patches, nanofiber dressings, and advanced drug-delivery systems that address specific unmet clinical needs.
- Smaller organizational structures allow emerging players to respond quickly to market trends, customer feedback, and technological advancements.
- Newer companies often struggle to build clinician trust and compete with well-established dental and healthcare brands.
- Compared with multinational competitors, emerging players typically have smaller sales networks and fewer international regulatory approvals, limiting market penetration.
Recent Developments
-
In May 2026, Yenssen Biotech Co., Ltd., a China-based biotechnology healthcare manufacturer, expanded its global distribution initiative to recruit medical device distributors across North America, Europe, the Middle East, Southeast Asia, and Latin America. The initiative focused on promoting its CE-marked and FDA-registered product portfolio, including the Dermlin wound healing series, Ulceloocin oral ulcer patch, and bone defect repair solutions. This expansion reflects the growing international demand for advanced, cost-effective wound care products and strengthens the company's presence in the global oral wound care and regenerative medicine markets.
-
In October 2025, Bioinicia highlighted its collaboration with Dermtreat A/S, a Denmark-based biopharmaceutical company focused on developing innovative therapies for mucosal diseases. The partnership focused on developing the Rivelin patch, an advanced mucoadhesive drug-delivery platform designed for the localized treatment of Oral Lichen Planus, a chronic condition affecting approximately 1-2% of the population. The technology represents a novel approach to delivering therapeutic agents directly to damaged oral mucosal tissue, supporting advancements in oral wound care and mucosal disease management.
Oral Wound Dressing Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 2.5 billion
Market size value in 2026
USD 2.8 billion
Revenue forecast in 2033
USD 5.3 billion
Growth rate
CAGR of 9.7% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Billion/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, material type, application, end use, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Norway; Italy; Denmark; Sweden; Spain; China; Japan; India; South Korea; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
TBM Co.; AD Surgical.; SUNSTAR Suisse S.A.; PULPDENT; Septodont Holding; Ethicon Inc. (Johnson & Johnson); ZimVie Inc.; Ricerfarma s.r.l.; BIOINICIA; Jiangsu Yenssen Biotech Co.; Hager Worldwide
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Oral Wound Dressing Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global oral wound dressing market report based on product, material, application, end user, distribution channel, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Mucoadhesive Patches & Films
-
Bioadhesive Gels
-
Oral Rinses / Mouthwashes
-
Oral Sprays
-
Periodontal Dressings & Surgical Pastes
-
Resorbable Matrices & Scaffolds
-
-
Material Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Natural Biopolymer-Based
-
Synthetic Polymer-Based
-
Hybrid / Composite Material
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Surgical Wounds
-
Inflammatory & Ulcerative Lesions
-
Traumatic Lesions
-
Regenerative Procedures
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Dental Clinics & Group Practices
-
Hospitals
-
Ambulatory Surgical Centers (ASCs)
-
Specialty Oral Surgery Centers
-
Home Care Settings
-
-
Distribution Channel Outlook (Revenue, USD Million; 2021 - 2033)
-
Direct Institutional Sales
-
Dental Service Organizations (DSOs)
-
Large Hospital Networks
-
Group Purchasing Organizations (GPOs)
-
-
Hospital Pharmacies
-
Retail Pharmacies & Drug Stores
-
Dental Distributors
-
E-commerce / Online Pharmacies
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Detailed competitive landscape assessment for oral wound dressing manufacturers
Company-level market share analysis, product benchmarking, distribution channel mapping, and strategic positioning of leading and emerging players by region.
Enables identification of market leaders, competitive gaps, partnership opportunities, and region-specific growth strategies.
Granular product segmentation and pricing analysis of oral wound dressing products
SKU-level product mapping by dressing type (bioadhesive gels, patches, periodontal dressings), average selling price (ASP) analysis, and application-wise revenue estimation.
Supports product portfolio optimization, pricing strategy development, and high-growth segment identification.
Country-specific demand and adoption analysis for oral wound management solutions
Country-wise market sizing, procedure volume analysis, reimbursement assessment, regulatory landscape review, and end-user adoption trends.
Facilitates market entry planning, investment prioritization, regulatory preparedness, and targeted commercial expansion strategies.
Frequently Asked Questions About This Report
North America dominated with a 40.2% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Bioadhesive Gels led with a 30.1% revenue share in 2025, while resorbable matrices & scaffolds is the fastest-growing segment.
Natural biopolymer-based held the largest revenue share in 2025, while hybrid / composite material is the fastest-growing area.
Dental distributors held the largest share (over 26.4%) in 2025 and E-commerce / online pharmacies is the fastest-growing.
The global oral wound dressing market size was valued at USD 2.5 billion in 2025 and is estimated at USD 2.8 billion for 2026.
The global oral wound dressing market is expected to grow at a CAGR of 9.7% from 2026 to 2033, reaching USD 5.3 billion in 2033.
Surgical Wounds held the largest share in 2025 and regenerative procedure is the fastest-growing application.
Key players include TBM Co., AD Surgical., SUNSTAR Suisse S.A., PULPDENT, Septodont Holding, Ethicon Inc. (Johnson & Johnson), ZimVie Inc., Ricerfarma s.r.l., BIOINICIA, Jiangsu Yenssen Biotech Co., Hager Worldwide
The oral wound dressing market is primarily driven by the increasing prevalence of oral ulcers, periodontal diseases, and oral mucositis associated with cancer therapies.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


