
- Home
- »
- Pharmaceuticals
- »
-
Organ Transplant Immunosuppressant Drugs Market Report, 2033GVR Report cover

Organ Transplant Immunosuppressant Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Drug Class (Calcineurin Inhibitors, Antiproliferative Agents), By Transplant Type (Kidney, Heart, Liver, Pancreas), By Region, And Segment Forecasts
Market Size, 2025
$5.8BMarket Estimate, 2026
$6.0BMarket Forecast, 2033
$8.3BCAGR, 2026–2033
4.7%Organ Transplant Immunosuppressant Drugs Market Summary
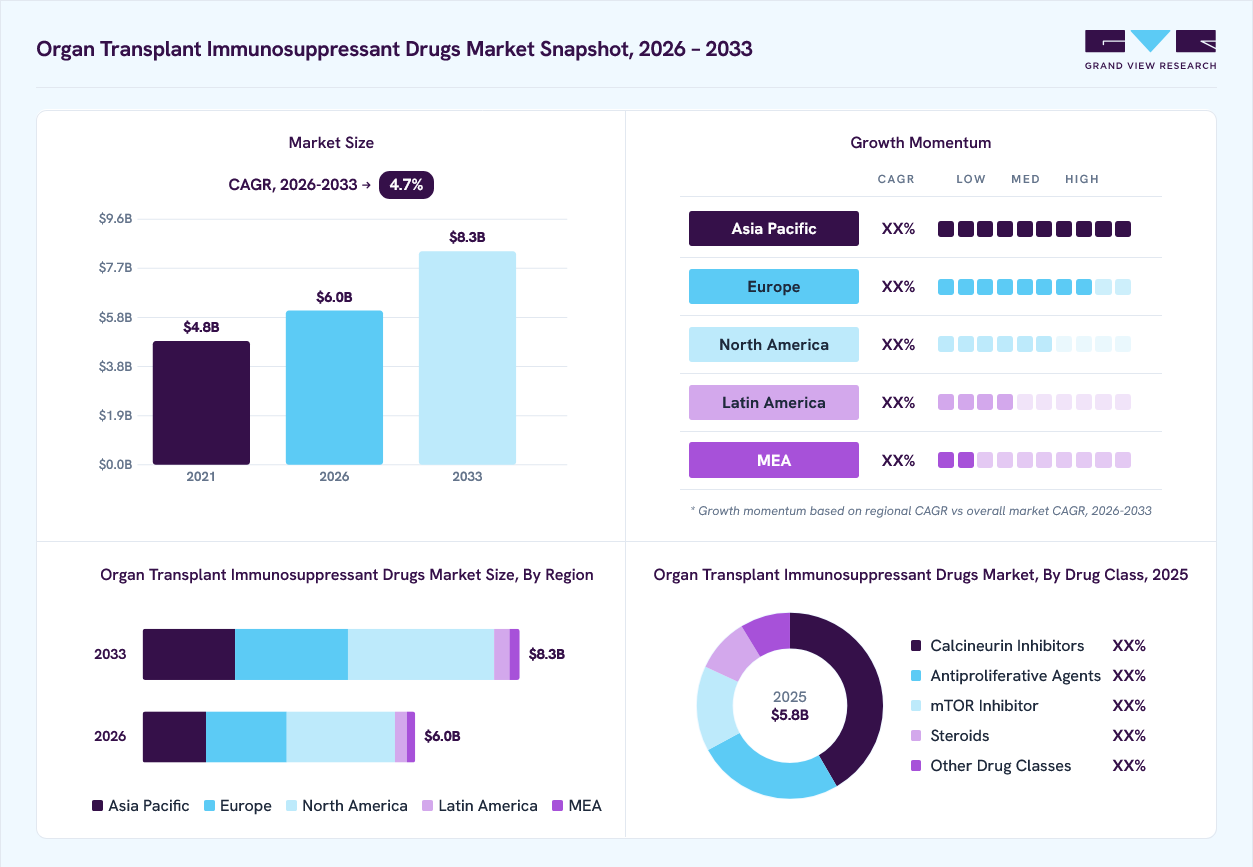
The global organ transplant immunosuppressant drugs market size was valued at USD 5.8 billion in 2025 and is projected to grow from USD 6.0 billion in 2026 to USD 8.3 billion by 2033, at a CAGR of 4.7% from 2026 to 2033. The market in North America dominated with a revenue share of 39.8% in 2025. The increasing prevalence of chronic diseases that drive the need for organ transplants, the rising proportion of the geriatric population that is more prone to chronic diseases, and the advancements in technologies that enable organ transplants are likely to drive demand in the market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drug class: Calcineurin inhibitors segment held the largest market share of 41.6% in 2025.
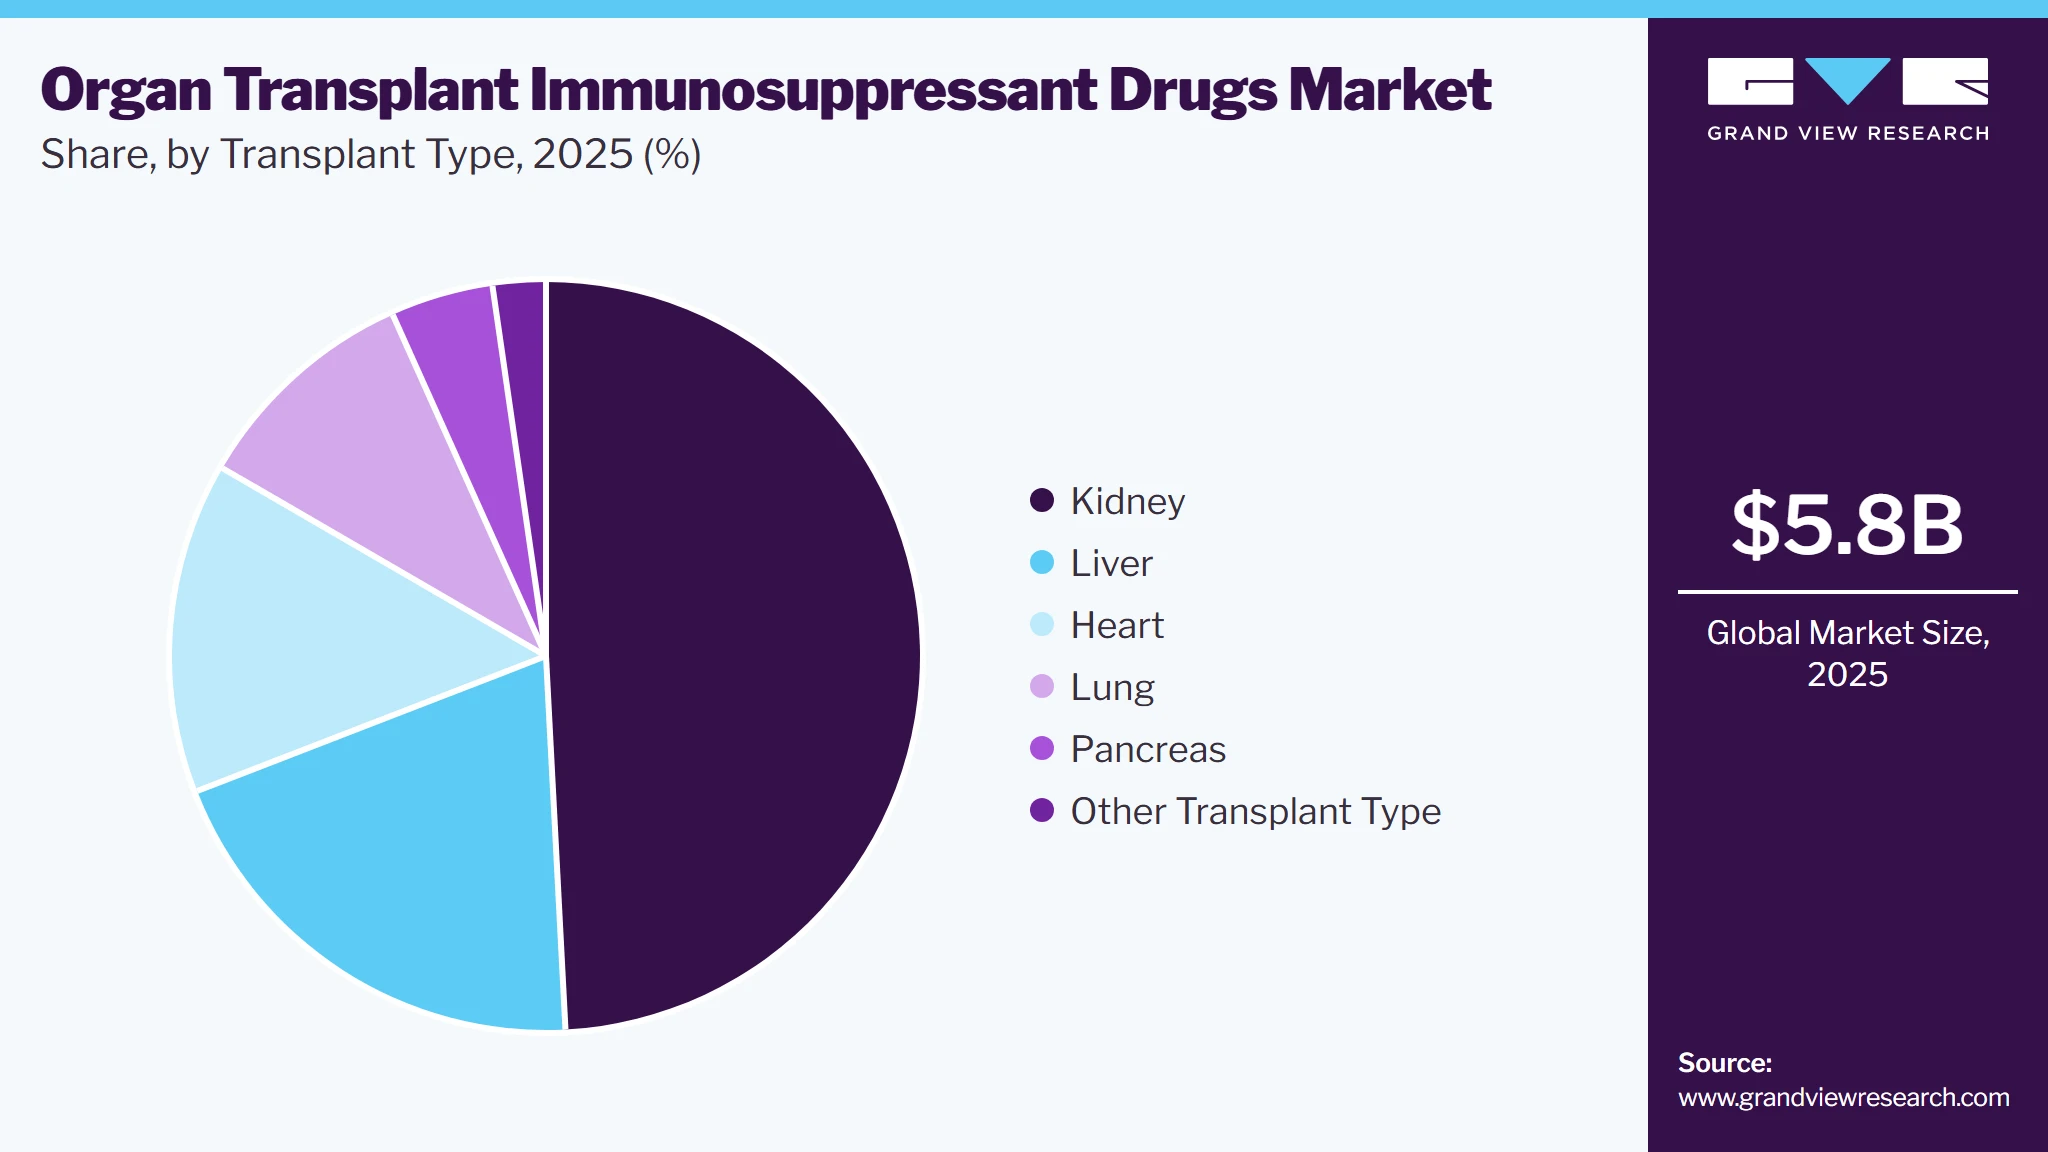
- By transplant type: Kidney segment held the largest market share of 49.2% in 2025.
Regional Highlights
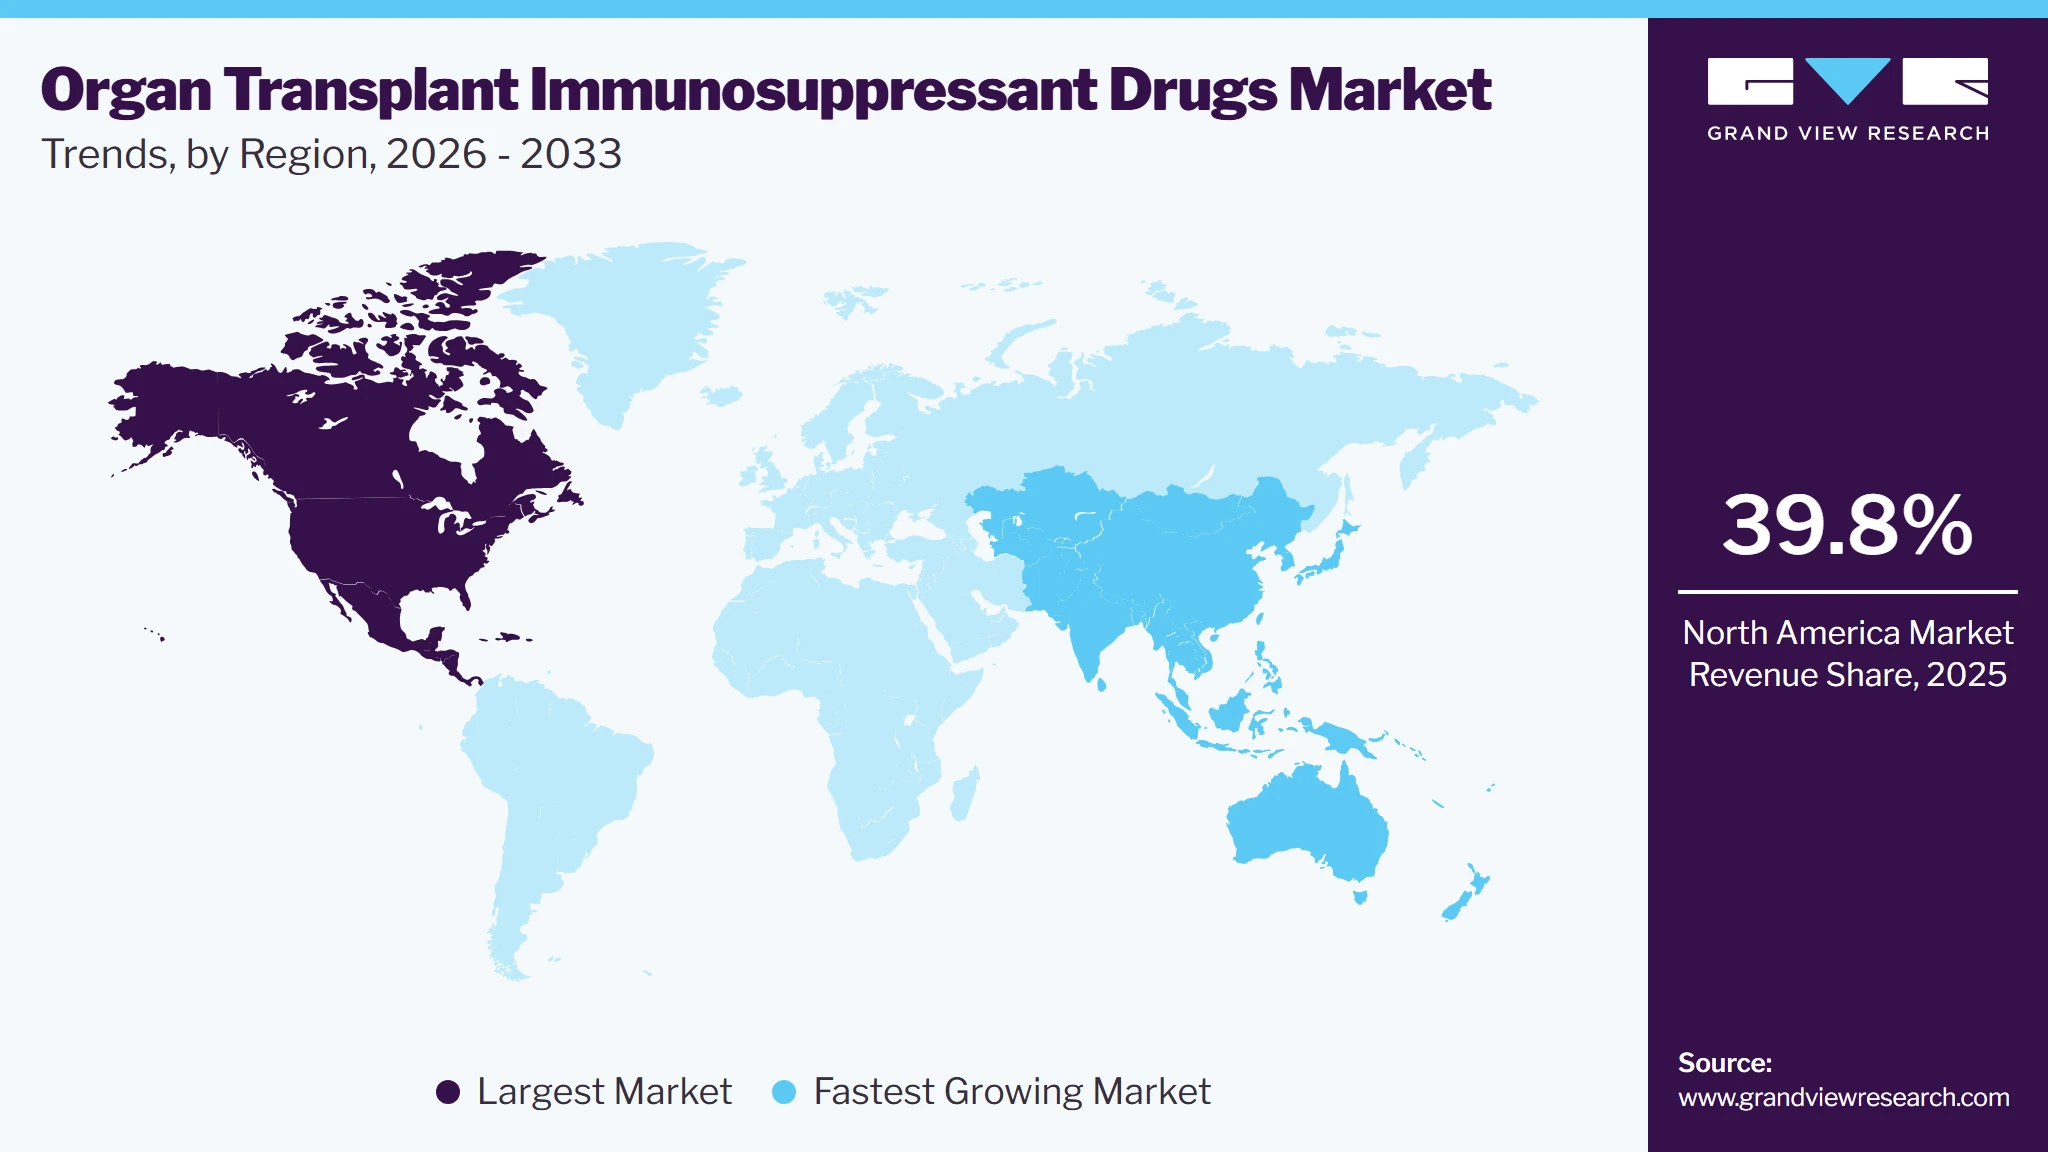
- Largest regional market: North America (39.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 5.8 Billion
- Estimated market size in 2026: USD 6.0 Billion
- Projected market size by 2033: USD 8.3 Billion
- CAGR (2026-2033): 4.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to the information published by the World Health Organization in September 2023, Noncommunicable diseases (NCDs) lead to the death of approximately 41 million people annually, which is equivalent to 74% of all deaths worldwide. These include cardiovascular diseases, kidney diseases, cancers, respiratory diseases, and others. The advancements in organ transplants and the development of immunosuppressant drugs can help in controlling the deaths caused by these diseases and drive market growth.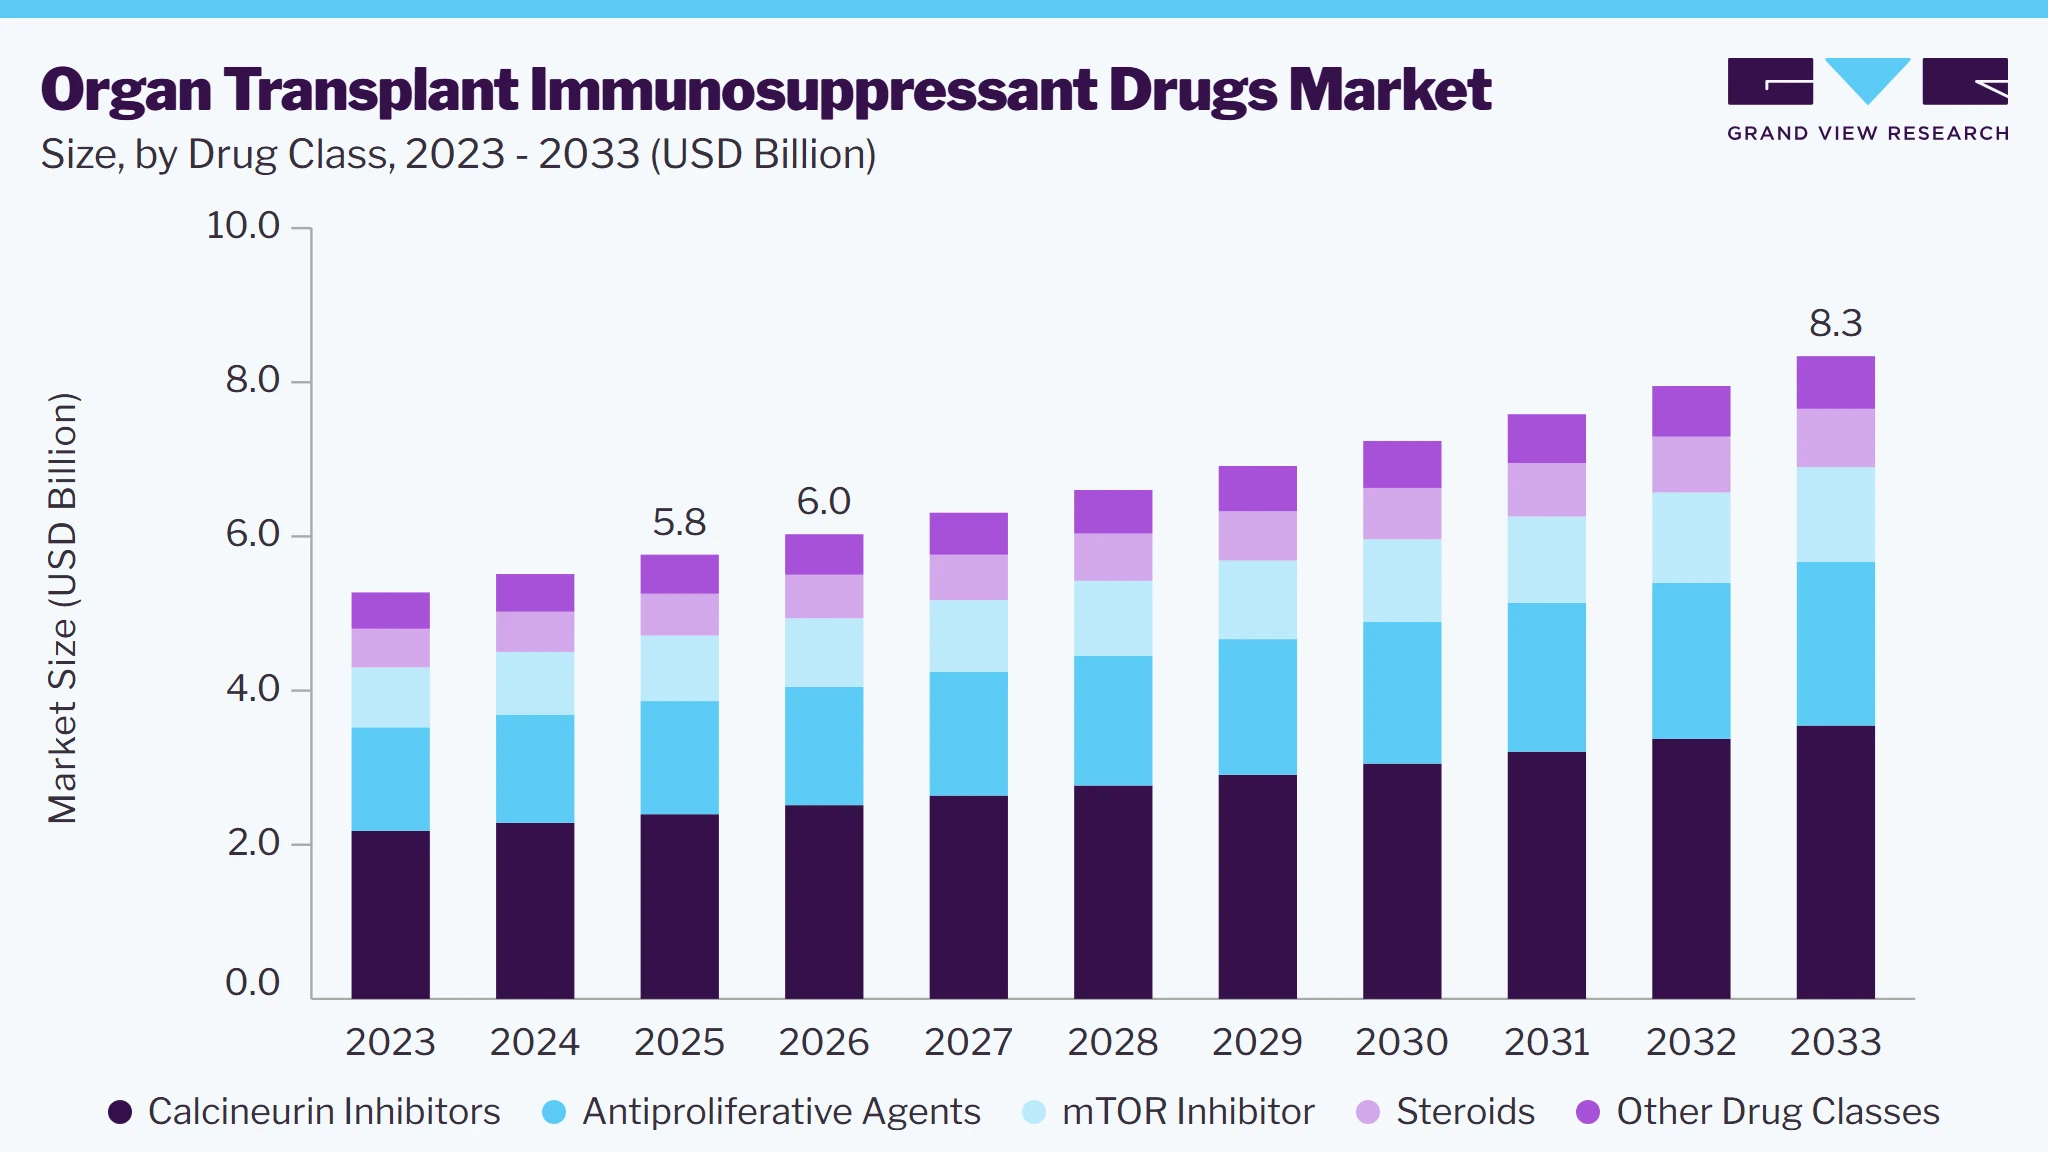 To learn more about this report, Download Free Sample Report
According to the statistics presented by the United Network for Organ Sharing, there were 46,630 transplants in the U.S. in 2023, and 104,541 people needed a lifesaving organ transplant. This rising demand for organ transplants is likely to drive the demand for organ transplant immunosuppressant drugs over the forecast period.
The immune system can reject a newly transplanted organ, such as a kidney, liver, heart, or lung, which can often lead to transplant failure and the requirement for immediate removal of the organ from the recipient. Immunosuppressant drugs can help in preventing this rejection, which is likely to drive their market growth with the rising number of organ transplants worldwide.
Market Dynamics
The organ transplant immunosuppressant drugs market is driven by the growing number of patients living with transplanted organs and requiring lifelong maintenance therapy. Demand remains closely tied to transplant volumes, particularly kidney transplantation, which accounts for the largest share of immunosuppressant use globally. Tacrolimus-based regimens continue to form the foundation of maintenance therapy across kidney, liver, heart, and lung transplantation and remain the largest source of market revenue. However, widespread availability of generic tacrolimus, cyclosporine, azathioprine, and mycophenolate products has limited pricing growth across established drug classes. As a result, pharmaceutical companies are increasingly focusing on differentiated formulations, improved treatment adherence, and therapies that address specific causes of graft failure. Another important market trend is the growing focus on long-term graft preservation. Physicians are placing greater emphasis on reducing complications associated with chronic immunosuppression, including nephrotoxicity, infections, cardiovascular disorders, and post-transplant malignancies. This has increased interest in treatment approaches that maintain graft function while reducing long-term safety concerns. In parallel, drug development efforts are increasingly targeting antibody-mediated rejection, which remains one of the leading causes of late graft loss despite advances in maintenance therapy. Going forward, market growth is expected to be supported by increasing transplant procedures, longer graft survival, and the introduction of therapies designed to improve long-term transplant outcomes.
The organ transplant immunosuppressant drugs market is benefiting from continuous improvements in graft survival rates across kidney, liver, heart, and lung transplantation. Advances in donor-recipient matching, transplant surgery, post-transplant monitoring, and maintenance treatment protocols have enabled patients to retain functioning grafts for longer periods than in previous decades. This trend has a direct impact on the market because immunosuppressive therapy is required for as long as the transplanted organ remains functional. Unlike many chronic disease treatments where therapy duration may vary, transplant recipients generally require lifelong treatment with drugs such as tacrolimus, mycophenolate, corticosteroids, and mTOR inhibitors to prevent graft rejection. As the number of patients living with functioning transplanted organs continues to increase, the cumulative demand for maintenance immunosuppressants also rises. The market is further supported by ongoing investments aimed at improving long-term graft outcomes. For instance, in June 2025, Sanofi announced that the U.S. FDA granted Orphan Drug Designation to riliprubart for the treatment of antibody-mediated rejection in solid organ transplantation. The development highlights the increasing focus on preserving graft function and reducing long-term transplant failure. As healthcare providers place greater emphasis on extending graft lifespan and improving post-transplant outcomes, demand for both established and emerging immunosuppressive therapies is expected to remain strong throughout the forecast period.
One of the key challenges facing the organ transplant immunosuppressant drugs market was the widespread availability of generic versions of core maintenance therapies. Drugs such as tacrolimus, cyclosporine, azathioprine, and mycophenolate had served as the cornerstone of post-transplant care for many years and were manufactured by multiple generic suppliers across major markets. While the availability of generics improved patient access and helped reduce overall treatment costs, it also intensified pricing pressure across established immunosuppressive drug categories. In many healthcare systems, hospital procurement organizations, reimbursement agencies, and transplant centers increasingly favored lower-cost generic alternatives when they demonstrated clinical outcomes comparable to branded products. As a result, revenue growth within mature immunosuppressive segments lagged behind the growth in transplant procedures and the expanding transplant recipient population. This trend was particularly evident across North America and Europe, where generic substitution had become a standard component of transplant maintenance protocols. Although demand for immunosuppressive therapy remained stable due to its lifelong treatment requirement, sustained generic competition continued to restrict pricing flexibility and limited revenue growth opportunities for manufacturers operating within traditional maintenance immunosuppressant categories. Furthermore, the increasing purchasing power of hospital networks and centralized procurement systems strengthened price negotiations, making it difficult for branded manufacturers to maintain premium pricing. Consequently, companies increasingly focused on differentiated formulations, novel mechanisms of action, and rejection-specific therapies to create value beyond conventional maintenance immunosuppressive treatments.
A major opportunity within the organ transplant immunosuppressant drugs market lies in the development of therapies specifically designed to address antibody-mediated rejection (AMR), which remains one of the leading causes of chronic graft dysfunction and late graft failure. Although current maintenance therapies have significantly reduced the incidence of acute rejection, many transplant recipients continue to experience immune-mediated complications that gradually affect graft performance over time. Existing treatment approaches for AMR often involve combinations of plasmapheresis, intravenous immunoglobulin, corticosteroids, and other immune-modulating therapies, but treatment outcomes remain inconsistent across patient populations. This has created a clear need for more targeted therapeutic options capable of addressing the underlying immune pathways responsible for graft injury. Pharmaceutical companies increasingly invested in this area as they sought opportunities beyond traditional maintenance immunosuppressants, where generic competition remained high. Growing clinical attention toward long-term graft preservation and the management of chronic rejection further strengthened interest in therapies targeting specific immune mechanisms involved in graft damage. As transplant centers increasingly focused on improving long-term graft survival rather than solely preventing acute rejection, therapies targeting antibody-mediated rejection emerged as an important area of development, creating new revenue opportunities and expanding the treatment landscape within transplant immunology.
Analyst Perspective
The organ transplant immunosuppressant drugs market is driven by sustained demand for lifelong therapies that prevent graft rejection and improve long-term transplant outcomes. Competition focuses on graft survival, reducing complications, and improving patient adherence. Pharmaceutical companies are strengthening their positions through clinical evidence, formulation improvements, cost-effective therapies, and expanded market access. Growing focus on antibody-mediated rejection, chronic graft dysfunction, and personalized immunosuppression is expected to drive innovation and market growth.
Drug Class Insights
Based on drug class, the calcineurin inhibitors segment led the market with the largest revenue share of 41.6% in 2025 and is projected to grow at the fastest CAGR of 5.0% over the forecast period. This growth can be attributed to using this class of immunosuppressants in effectively managing various autoimmune disorders, such as lupus nephritis, atopic dermatitis, idiopathic inflammatory myositis, interstitial lung disease, and solid organ transplantation. For instance, Cyclosporine is approved by the U.S. Food and Drug Administration (FDA) to prevent allogeneic organ transplant rejection when used with glucocorticoids.
The antiproliferative agents segment is expected to grow at a significant CAGR over the forecast period. Antiproliferative agents include Mycophenolic acid and Azathioprine, which are used as the cornerstone of antirejection maintenance therapy in solid organ transplants. They are also used in autoimmune and cancer research owing to their role in disrupting cellular replication, which is further expected to drive their demand.
Transplant Type Insights
Based on transplant type, the kidney segment led the market with the largest revenue share of 49.2% in 2025. The increasing prevalence and incidence of kidney diseases worldwide and the demand for kidney transplants are major drivers for segment growth. For instance, according to the information published by the National Institutes of Health, approximately one in seven or about 37 million people in the U.S. are affected by Chronic kidney disease (CKD). In addition, about 1 in every three people with diabetes and 1 in 5 people with high blood pressure also suffer from kidney diseases. The rising prevalence of these diseases is expected to drive the segment growth.
 To learn more about this report, Download Free Sample Report
Lung diseases are expected to grow at the fastest CAGR over the forecast period. This growth can be attributed to the increasing instances of respiratory diseases, increasing research and development related to lung transplants, and a rising number of transplants. For instance, according to the information published by the Centers for Disease Control and Prevention (CDC), approximately 147,382 deaths were caused by Chronic lower respiratory diseases (including asthma) deaths in the U.S. in 2022.
Regional Insights
North America dominated the organ transplant immunosuppressant drugs market with the largest revenue share of 39.8%in 2025. attributed to the increasing number of chronic diseases, increasing proportion of geriatric populations, and advanced treatment options. According to the information published by Statistics Canada in September 2023, approximately 45.1% of Canadians lived with at least one major chronic disease in 2021. The increasing prevalence of chronic diseases is likely to add to the market growth over the forecast period.
 To learn more about this report, Download Free Sample Report
U.S. Organ Transplant Immunosuppressant Drugs Market Trends
The organ transplant immunosuppressant drugs market in the U.S. held the largest share in the North America region in 2025 in North America organ transplant immunosuppressant drugs market. The availability and access to advanced transplant treatments and the increasing number of transplants are major drivers for the market growth in the country. For instance, according to the information published by the Health Resource and Services Administration, 27,332 patients received kidney transplants in the U.S. in 2023.
Europe Organ Transplant Immunosuppressant Drugs Market Trends
The European organ transplant immunosuppressant drugs market is expected to grow significantly over the forecast period owing to well-established healthcare infrastructure, a rising number of organ transplants, and supportive government policies and initiatives supporting organ donation and transplantation. For instance, the European Day for Organ, Tissue, and Cell Donation initiative works towards increasing awareness of organ, cell, and tissue donation. Such campaigns are likely to create awareness regarding organ transplants and add to the demand for associated immunosuppressant drugs in the region.
The UK organ transplant immunosuppressant drugs market is expected to grow significantly over the forecast period. Rising chronic illnesses, such as kidney, liver, and heart diseases, drive the growing demand for transplants. In addition, the initiatives and supportive policies developed by the government in the country are further expected to drive market growth. For instance, the country has implemented the opt-out system for organ donation, which considers every individual to have agreed to donate their organs post their death unless they opt out of it. This has led to an increase in the availability of organ donations, which is further expected to drive market growth.
The Germany organ transplant immunosuppressant drugs market held the largest market share in 2024. The country's well-established healthcare system and the increasing prevalence of chronic conditions such as kidney disease and liver failure are driving the demand for transplants and immunosuppressive therapies. Treatment advancements are also likely to drive the market over the forecast period.
Asia Pacific Organ Transplant Immunosuppressant Drugs Market Trends
The Asia Pacific organ transplant immunosuppressant drugs market is anticipated to grow at the fastest CAGR over the forecast period. The increasing prevalence of chronic diseases and the rising number of transplants in the region are driving the growth of this market. In addition, increasing initiatives to create awareness regarding organ donations and regional advancements are expected to add to the market's growth over the forecast period. For instance, in August 2024, Mankind Pharma introduced the campaign ‘Spreading Kindness’ in India to increase awareness regarding organ donation in the country.
The China organ transplant immunosuppressant drugs market accounted for a significant market share in 2024 due to the healthcare reforms and significant investments in the country to improve transplant services and accessibility. The increasing incidence of chronic diseases, such as kidney and liver conditions, is further driving demand for organ transplants and, subsequently, immunosuppressive therapies. For instance, according to the National Institute of Health, approximately 8.2% of people above the age of 40, or 43 million people, suffer from COPD in China.
The India organ transplant immunosuppressant drugs market is expected to grow significantly owing to the advancements in the healthcare sector, increasing awareness regarding organ transplants, and increasing number of transplants. For instance, in October 2024, Rela Hospital, Chennai, India, performed a lung transplant on an 18-year-old girl. Such developments increase the availability and accessibility of the treatment option, driving the market growth.
Key Organ Transplant Immunosuppressant Drugs Company Insights
Some of the key companies operating in the organ transplant immunosuppressant drugs market include Astellas Pharma d.o.o., GlaxoSmithKline plc., Hoffmann-La Roche Ltd., Sanofi, Accord Healthcare, Novartis AG, and Viatris Inc. These players are focusing on developing advanced immunosuppressant drugs, expanding, and mergers and acquisition activities to gain a competitive edge in the market.
-
GlaxoSmithKline plc. is a global company engaged in developing, manufacturing, and distributing various pharmaceuticals, vaccines, and consumer health products. The company offers pharmaceutical solutions to address a variety of medical conditions, including HIV, respiratory diseases, cancer, and inflammatory and immune disorders. The company also provides over-the-counter (OTC) solutions for pain management, oral health, skin health, nutrition, and gastrointestinal issues.
-
F. Hoffmann-La Roche Ltd (Roche) is a global biotechnology company that develops pharmaceuticals and diagnostic solutions for various health conditions. The company's drug portfolio includes treatments for cancer, autoimmune disorders, central nervous system diseases, infectious conditions, and respiratory ailments. The company provides the Elecsys Immunosuppressive Drug Assay Panel, which is used for organ transplant patients.
Key Organ Transplant Immunosuppressant Drugs Companies
The following key companies have been profiled for this study on the organ transplant immunosuppressant drugs market.
-
Astellas Pharma d.o.o.
-
Sanofi
-
Accord Healthcare
-
Novartis AG
-
Viatris Inc.
-
F. Hoffmann-La Roche Ltd
-
GlaxoSmithKline plc.
-
Veloxis Pharmaceuticals, Inc.
-
Bristol-Myers Squibb Company
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Transplant Immunosuppressant Market Leaders (Astellas Pharma d.o.o., Sanofi, Novartis AG, F. Hoffmann-La Roche Ltd, GlaxoSmithKline plc., Bristol-Myers Squibb Company)
- Focus on maintaining market position through lifecycle management of established immunosuppressive therapies, expansion of clinical evidence supporting long-term graft survival, and development of therapies addressing graft rejection and transplant-related immune complications.
- Strategic priorities include strengthening relationships with transplant centers, supporting physician education initiatives, and investing in therapies targeting antibody-mediated rejection and chronic graft dysfunction. Companies in this category also emphasize regulatory expansion and long-term outcome studies to reinforce product adoption across major transplant markets.
- Strong physician familiarity, extensive clinical data supporting long-term use, established relationships with transplant centers, broad regulatory expertise, and well-developed commercial infrastructure.
- Their ability to support large-scale clinical studies and generate long-term graft survival data strengthens market credibility and facilitates continued access across healthcare systems. These companies also benefit from diversified immunology capabilities and significant resources for research and product development.
- Exposure to generic competition across mature maintenance immunosuppressive therapies, particularly within widely used treatment regimens.
- Revenue growth is often constrained by pricing pressure from procurement organizations, reimbursement agencies, and hospital systems. Dependence on established products and longer development cycles may also reduce flexibility in responding to emerging treatment approaches and evolving transplant care requirements.
Specialized and Generic-Focused Transplant Therapy Providers (Veloxis Pharmaceuticals, Inc., Accord Healthcare, Viatris Inc.)
- Focus on expanding market share through differentiated formulations, cost-efficient manufacturing, and broader access to maintenance immunosuppressive therapies.
- Growth strategies are centered on improving treatment convenience, supporting medication adherence, and supplying cost-competitive alternatives through hospital procurement channels and transplant networks. Companies in this category primarily compete by addressing affordability requirements while ensuring reliable product availability across healthcare systems.
- Strong positioning in cost-sensitive markets through competitive pricing, manufacturing efficiency, focused transplant expertise, and responsiveness to procurement requirements.
- Their specialized product focus enables quicker adaptation to market demand and allows them to compete effectively in established maintenance therapy categories. In addition, expertise in formulation development and generic manufacturing supports wider market penetration.
- Limited product diversification and greater dependence on a smaller number of transplant-focused therapies compared with larger pharmaceutical companies.
- Business performance is often highly sensitive to pricing pressure, tender-based procurement systems, and margin compression resulting from generic competition. Lower brand recognition and fewer resources for large-scale clinical development may also limit expansion into emerging transplant treatment segments.
Recent Developments
-
In April 2024, United Therapeutics announced the first successful xenothymokidney transplant into a living human using FDA-approved immunosuppressive medicines.
-
In June 2023, Dr. Reddy’s Laboratories Ltd. announced it had successfully completed the Phase I study of its proposed biosimilar of immunosuppressive drugs.
-
In February 2022, Veloxis Pharmaceuticals Inc. announced that VEL-101, which is an investigational maintenance immunosuppressive agent developed by the company for prophylaxis of renal allograft rejection in patients receiving a kidney transplant, received fast-track designation by the U.S. FDA.
Organ Transplant Immunosuppressant Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.8 billion
Estimated market size in 2026
USD 6.0 billion
Projected market size by 2033
USD 8.3 billion
Growth rate
CAGR of 4.7% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Drug class, transplant type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Astellas Pharma d.o.o., Sanofi, Accord Healthcare, Novartis AG, Viatris Inc., F. Hoffmann-La Roche Ltd, GlaxoSmithKline plc., Veloxis Pharmaceuticals, Inc., Bristol-Myers Squibb Company
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Organ Transplant Immunosuppressant Drugs Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global organ transplant immunosuppressant drugs market report based on drug class, transplant type, and region:
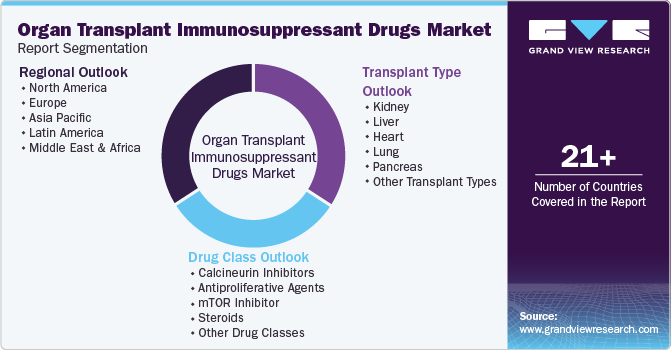 To learn more about this report, Download Free Sample Report
-
Drug Class Outlook (Revenue, USD Million, 2021 - 2033)
-
Calcineurin Inhibitors
-
Antiproliferative Agents
-
mTOR Inhibitor
-
Steroids
-
Other Drug Classes
-
-
Transplant Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Kidney
-
Liver
-
Heart
-
Lung
-
Pancreas
-
Other Transplant Types
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The organ transplant immunosuppressant drugs market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each organ transplant immunosuppressant drugs segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Drug Class
Revenue capture definition
Calcineurin Inhibitors
Includes revenue generated from calcineurin inhibitor-based immunosuppressive therapies used for the prevention and management of organ rejection following solid organ transplantation. This segment covers tacrolimus, cyclosporine, extended-release tacrolimus formulations, and related branded and generic products. Revenue is recognized from the sale of calcineurin inhibitor therapies only and excludes antiproliferative agents, mTOR inhibitors, corticosteroids, biologics, induction therapies, and other immunosuppressive drug classes.
Antiproliferative Agents
Includes revenue generated from antiproliferative immunosuppressive therapies prescribed as part of transplant maintenance regimens. This segment covers mycophenolate mofetil, mycophenolic acid, azathioprine, and related branded and generic formulations. Revenue is derived exclusively from antiproliferative agents used in transplant recipients and excludes calcineurin inhibitors, mTOR inhibitors, corticosteroids, biologics, and other immunosuppressive therapies.
mTOR Inhibitors
Includes revenue generated from mammalian target of rapamycin (mTOR) inhibitor therapies used for transplant immunosuppression. This segment covers everolimus, sirolimus, and related formulations utilized for maintenance therapy, calcineurin inhibitor minimization strategies, or graft preservation protocols. Revenue is recognized solely from mTOR inhibitor products and excludes calcineurin inhibitors, antiproliferative agents, corticosteroids, biologics, and other immunosuppressive drug classes.
Steroids
Includes revenue generated from corticosteroid-based therapies used for transplant induction, maintenance, and rejection management. This segment covers prednisone, prednisolone, methylprednisolone, and other corticosteroid formulations prescribed in transplant settings. Revenue is attributed exclusively to steroid therapies and excludes calcineurin inhibitors, antiproliferative agents, mTOR inhibitors, biologics, and other immunosuppressive agents.
Calcineurin Inhibitors
Includes revenue generated from calcineurin inhibitor-based immunosuppressive therapies used for the prevention and management of organ rejection following solid organ transplantation. This segment covers tacrolimus, cyclosporine, extended-release tacrolimus formulations, and related branded and generic products. Revenue is recognized from the sale of calcineurin inhibitor therapies only and excludes antiproliferative agents, mTOR inhibitors, corticosteroids, biologics, induction therapies, and other immunosuppressive drug classes.
Segment - Transplant Type
Revenue capture definition
Kidney
Includes revenue generated from immunosuppressive drugs prescribed for kidney transplant recipients across induction, maintenance, and rejection treatment settings. Revenue is assigned based on the end-use of immunosuppressive therapies in kidney transplantation and includes all applicable drug classes. Revenue attributable to liver, heart, lung, pancreas, and other transplant procedures is excluded.
Liver
Includes revenue generated from immunosuppressive drugs prescribed for liver transplant recipients during induction, maintenance, and rejection management. Revenue is captured based on therapeutic use within liver transplantation only and excludes immunosuppressive therapies used in kidney, heart, lung, pancreas, or other transplant procedures.
Heart
Includes revenue generated from immunosuppressive drugs prescribed for heart transplant recipients. This segment covers all immunosuppressive therapies used for rejection prevention and long-term graft management following heart transplantation. Revenue attributable to other transplant indications is excluded.
Lung
Includes revenue generated from immunosuppressive drugs prescribed for lung transplant recipients. The segment captures revenue associated with maintenance therapy, rejection prevention, and rejection treatment specific to lung transplantation. Revenue generated from all other transplant types is excluded.
Pancreas
Includes revenue generated from immunosuppressive drugs prescribed for pancreas transplant recipients, including pancreas-alone transplantation and combined pancreas transplantation procedures. Revenue is assigned exclusively to therapies utilized in pancreas transplantation and excludes all other transplant indications.
Other Transplant Types
Includes revenue generated from immunosuppressive drugs prescribed for transplant procedures not included under kidney, liver, heart, lung, or pancreas transplantation. This segment covers intestinal transplantation, multivisceral transplantation, composite tissue allotransplantation, and other less common transplant procedures. Revenue is allocated to this segment only when it does not belong to the predefined transplant categories above.
Estimation Model
The Organ Transplant Immunosuppressant Drugs Market was estimated using a commodity flow and revenue-based market analysis approach. The methodology began with the identification of key manufacturers and commercially available immunosuppressive therapies used across solid organ transplantation. Major products within calcineurin inhibitors, antiproliferative agents, mTOR inhibitors, steroids, and other immunosuppressive drug classes were benchmarked based on annual revenues, prescription trends, product uptake, pricing, patent status, and geographic presence. Revenue generated from leading products was assessed using company annual reports, investor presentations, regulatory filings, transplant registries, healthcare procurement data, and industry publications. Product-level revenues were aggregated to estimate market revenues across individual drug classes and transplant indications, including kidney, liver, heart, lung, pancreas, and other transplant types.
The market estimates were further validated through an assessment of transplant procedure volumes, active transplant recipient populations, treatment duration, and long-term maintenance therapy requirements. Current treatment patterns, therapy utilization rates, and drug adoption trends across transplant centers were analyzed to determine demand-side dynamics. Market shares of leading manufacturers were evaluated based on product portfolios, commercial presence, and penetration within transplant care settings. Data triangulation was performed by comparing manufacturer revenues, prescription volumes, and treatment utilization trends to ensure consistency across market estimates. Forecast projections incorporated transplant volume growth, graft survival improvements, generic penetration, pricing trends, and the adoption of emerging therapies targeting antibody-mediated rejection and long-term graft preservation.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Advanced Immunosuppressant Therapy Adoption Analysis
Assessment of adoption trends across calcineurin inhibitors, antiproliferative agents, mTOR inhibitors, corticosteroids, biologic immunosuppressants, and emerging transplant therapies. Analysis includes prescribing patterns, maintenance versus induction therapy utilization, treatment sequencing, and usage trends across kidney, liver, heart, lung, and other organ transplant settings.
Helps identify high growth therapeutic segments, evolving prescribing trends, and commercialization opportunities across the organ transplant immunosuppressant drugs market.
Treatment Pathway and Patient Journey Assessment
Analysis of patient progression from transplant evaluation and organ transplantation through induction therapy, maintenance immunosuppression, long term monitoring, and management of graft rejection risks. Includes assessment of treatment switching patterns, adherence challenges, adverse event management, and factors influencing therapy selection.
Supports identification of unmet clinical needs, patient retention opportunities, and market expansion strategies across different stages of post transplant care.
Diagnostic and Transplant Monitoring Landscape Evaluation
Evaluation of diagnostic and monitoring approaches including therapeutic drug monitoring, biomarker testing, donor specific antibody assessment, graft surveillance protocols, molecular diagnostics, and transplant rejection monitoring technologies. Assessment includes factors influencing treatment optimization and long term graft survival.
Tracks opportunities related to earlier rejection detection, improved treatment outcomes, enhanced patient management, and expansion of the addressable patient population requiring long term immunosuppressive therapy.
Pipeline and Innovation Landscape Assessment
Assessment of emerging immunosuppressive therapies, novel mechanisms of action, cell based therapies, tolerance induction strategies, next generation biologics, biosimilar competition, and ongoing clinical development activities relevant to organ transplantation.
Identifies future growth opportunities, competitive differentiation factors, and innovation driven areas expected to influence market evolution.
Competitive Benchmarking and Portfolio Analysis
Comparative assessment of approved immunosuppressant drugs, clinical evidence, market positioning, pricing strategies, reimbursement access, pipeline strength, lifecycle management initiatives, and strategic activities of leading market participants in the organ transplant immunosuppressant drugs market.
Supports competitive intelligence, partnership evaluation, product positioning, investment planning, and strategic decision making within the organ transplant immunosuppressant drugs industry.
Frequently Asked Questions About This Report
The global organ transplant immunosuppressant drugs market size was valued at USD 5.8 billion in 2025 and is estimated at USD 6.0 billion for 2026.
The calcineurin inhibitors segment led the market with a 41.6% revenue share in 2025 and is also expected to register the fastest growth during the forecast period.
Key players include Astellas Pharma d.o.o., Sanofi, Accord Healthcare, Novartis AG, Viatris Inc., F. Hoffmann-La Roche Ltd., GlaxoSmithKline plc., Veloxis Pharmaceuticals, Inc., and Bristol-Myers Squibb Company.
North America dominated the global organ transplant immunosuppressant drugs market with a 39.8% revenue share in 2025.
Asia Pacific is the fastest-growing regional market over the forecast period, driven by increasing transplant procedures, improving healthcare infrastructure, and growing awareness of organ donation.
The kidney transplant segment accounted for the largest revenue share of 49.2% in 2025, supported by the high volume of kidney transplant procedures and lifelong maintenance therapy requirements.
The U.S. accounted for the largest market share in 2025, supported by high transplant volumes, advanced transplant infrastructure, favorable reimbursement, and broad access to immunosuppressive therapies.
Key factors include the increasing number of organ transplant procedures, rising prevalence of chronic diseases leading to end-stage organ failure, improving graft survival rates that require lifelong immunosuppressive therapy, advancements in transplant technologies, and growing development of therapies targeting antibody-mediated rejection and long-term graft preservation.
The global organ transplant immunosuppressant drugs market is expected to grow at a CAGR of 4.7% from 2026 to 2033, reaching USD 8.3 billion by 2033.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


