
- Home
- »
- Digital Media
- »
-
Pay TV Market Size, Share & Growth Report, 2026-2033GVR Report cover

Pay TV Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Cable TV, Satellite TV, IPTV), By Application (Commercial, Residential), By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$284.2BMarket Estimate, 2026
$295.0BMarket Forecast, 2033
$365.3BCAGR, 2026–2033
3.1%Pay TV Market Summary
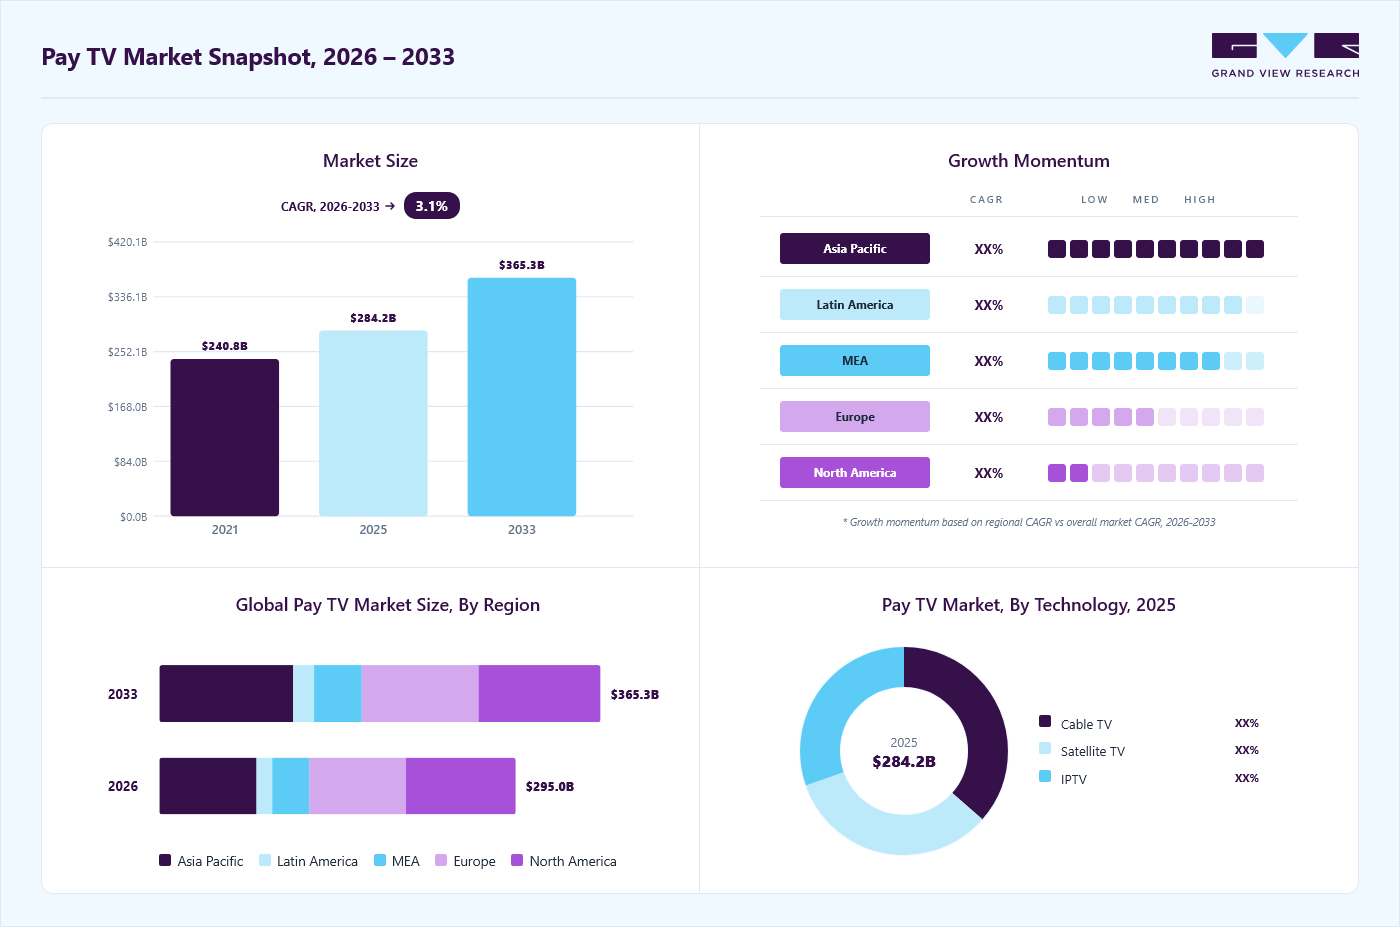
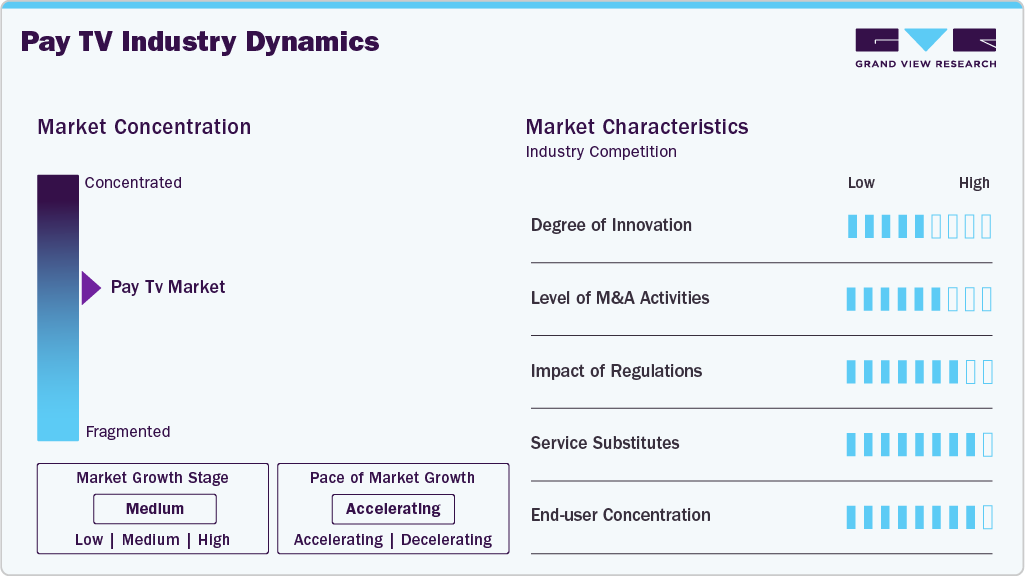
The global pay TV market size was valued at USD 284.2 billion in 2025 and is projected to grow from USD 295.0 billion in 2026 to USD 365.3 billion by 2033, at a CAGR of 3.1% from 2026 to 2033. North America dominated the market with a revenue share of 31.2% in 2025. The global pay TV industry is evolving as providers integrate streaming services with traditional television offerings.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Residential segment held the largest market share of 85.0% in 2025.
- By technology: Cable TV segment held the largest market share of 36.4% in 2025.
Regional Highlights
- Largest regional market: North America (31.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 284.2 Billion
- Estimated market size in 2026: USD 295.0 Billion
- Projected market size by 2033: USD 365.3 Billion
- CAGR (2026-2033): 3.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Additionally, the continuously growing penetration of the internet and smartphones is promoting the demand for TV on the go and thus supporting the market growth. Growing consumer demand for high-quality content, higher picture resolution, and flexible viewing options is creating new opportunities in the pay TV market. Consumers increasingly expect convenient access to on-demand and diverse content, prompting service providers to invest in advanced platforms and user-centric offerings. Access to content from multiple providers through a single platform at competitive prices remains a key market driver. Pay TV operators are also expanding their value-added services through customizable channel packages, discounted subscription plans, internet connectivity, and bundled offerings tailored to consumer preferences. The growing popularity of live sports, including soccer, football, basketball, and tennis, continues to support subscriptions as providers offer dedicated sports and entertainment channel packs. Companies such as DISH and DIRECTV are focusing on content variety, competitive pricing, and service enhancements to improve customer retention and attract new subscribers.
 To learn more about this report, Download Free Sample Report
At the same time, the global shift toward streaming and over-the-top (OTT) platforms is intensifying competition for traditional pay TV providers. The growing prevalence of cord-cutting has encouraged operators to integrate OTT services and adopt hybrid distribution models that combine traditional television with digital streaming. Partnerships with OTT platforms can expand content libraries, improve accessibility, and provide consumers with a unified viewing experience. For instance, in September 2024, ZTE Corporation announced a collaboration with Netgem to develop a Pay TV OTT ecosystem, including high-performance dongles, set-top boxes (STBs), and TV sticks with open operating systems and pre-installed streaming platforms such as Disney+, Netflix, and Amazon Prime Video.
Despite increasing competition from streaming services, pay TV continues to offer advantages such as access to premium and exclusive content, digital video recording (DVR), reliable service, and consistent viewing quality in areas with limited internet connectivity. These benefits remain particularly relevant in rural and emerging markets where broadband infrastructure may be inadequate for uninterrupted streaming. In addition, service providers are increasingly introducing ultra-high-definition (UHD) content, program download capabilities, and mobile applications that enable subscribers to manage accounts, customize channel packages, and access programming remotely. The combination of traditional pay TV services with digital features and flexible content offerings helps providers adapt to evolving consumption preferences and maintain market relevance.
Market Dynamics
The pay TV market is evolving in response to changing consumer preferences and shifting media consumption patterns. Service providers are increasingly refining content delivery models to enhance accessibility, improve service efficiency, and address diverse viewing preferences. Growing competition from alternative digital platforms is also influencing pricing strategies, content offerings, and service differentiation. Meanwhile, advancements in broadcasting, connectivity, and digital technologies are enabling more efficient content distribution and improved user experiences. These developments are prompting pay TV providers to adapt their service portfolios and delivery strategies to align with evolving demand across the broader media and entertainment landscape.
Advancements in broadcasting technologies are improving content delivery efficiency, signal quality, and service reliability across television platforms. Service providers are upgrading transmission infrastructure and adopting enhanced broadcasting standards to support clearer signals, higher-quality viewing experiences, and more consistent service performance across regions. These developments are helping minimize interruptions, improve stability during periods of high demand, and strengthen overall content distribution capabilities. Continued improvements in transmission technologies are also expanding service reach and supporting greater consistency in content delivery.
Advancements in streaming technologies are improving content accessibility, flexibility, and quality across connected devices. Service providers are investing in scalable digital infrastructure, enhanced content delivery networks, and advanced compression technologies to enable smoother playback and more reliable streaming across varying network and bandwidth conditions. These developments are enabling users to access content more consistently across multiple devices while enhancing the viewing experience. Ongoing innovations in streaming and content delivery technologies are expected to further enhance platform performance, scalability, and service reliability.
Increasing competition from over-the-top (OTT) and digital streaming platforms is placing pressure on traditional pay TV subscriptions as consumers increasingly shift toward on-demand and flexible viewing services. The growing preference for internet-based content delivery is reducing reliance on conventional television packages and creating challenges for pay TV providers to maintain stable subscription revenues. Changes in media consumption patterns are also influencing subscription renewal rates and customer retention, prompting operators to reassess their service offerings and pricing strategies.
The availability of low-cost, ad-supported streaming services is further accelerating the transition to digital platforms. Consumers are increasingly seeking greater convenience, personalized content, and broader programming choices, which can make traditional bundled television packages less attractive. The continued expansion of digital content ecosystems is intensifying competition across global markets, encouraging pay TV operators to integrate streaming services, diversify content offerings, and enhance value propositions to remain competitive.
Growing demand for personalized and on-demand content is driving the adoption of advanced recommendation platforms across pay TV and digital entertainment services. These platforms enable service providers to improve content discovery by delivering more relevant viewing recommendations based on user preferences and consumption patterns. By organizing extensive content libraries according to individual interests, recommendation systems can help reduce content overload, simplify content selection, and enhance the overall viewing experience across connected devices and services. Improved personalization is also contributing to higher user engagement and more efficient content consumption.
Recommendation platforms provide service providers with greater insights into viewing behavior and content preferences, supporting more targeted content delivery and customer engagement strategies. These capabilities can strengthen customer retention by enabling providers to offer more relevant programming and personalized experiences. In addition, increasing adoption of data analytics and artificial intelligence (AI) is improving the accuracy of recommendation algorithms and enabling more effective user segmentation and targeting. Continued advancements in personalization technologies are expected to create further opportunities for pay TV and streaming service providers.
Market Concentration & Characteristics
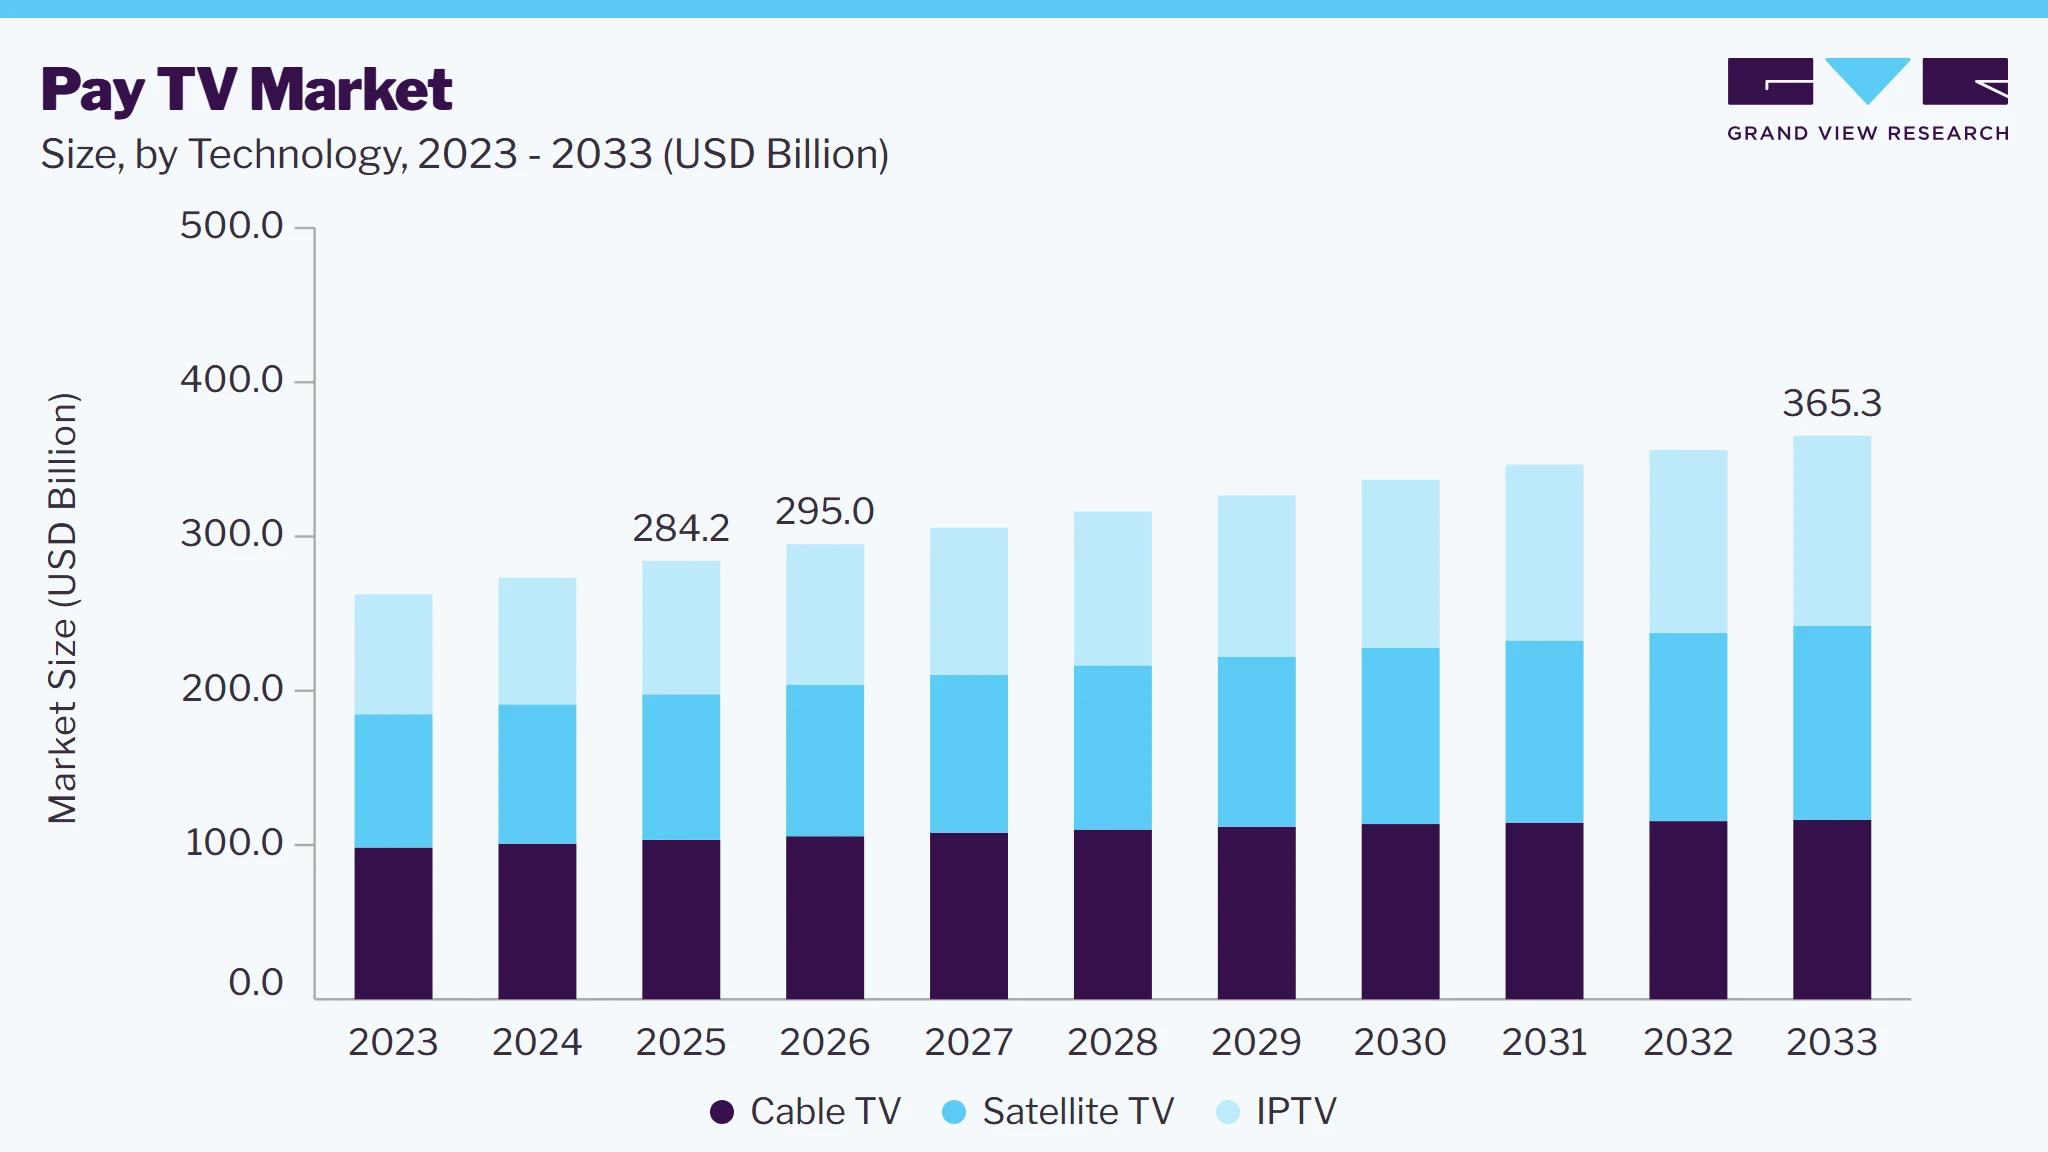
The pay TV market exhibits a moderate to moderately high level of concentration, with a limited number of large operators accounting for a substantial share of subscribers and revenue. These providers benefit from established distribution networks, strong content portfolios, long-term content rights agreements, bundled service offerings, economies of scale, and well-established brand presence across major markets. At the same time, regional and niche providers continue to serve specific geographic and customer segments by offering localized content and tailored services. The market structure remains diverse, although consolidation, strategic partnerships, and the geographic expansion of major operators are contributing to a gradual increase in market concentration.
 To learn more about this report, Download Free Sample Report
The market is characterized by subscription-based revenue models, bundled service packages, and demand for curated programming, particularly live television, sports, and entertainment content. However, shifting consumer preferences toward flexible, on-demand viewing are encouraging greater integration with streaming platforms and connected devices. Increasing competition from digital media services is also prompting pay TV providers to invest in advanced content delivery infrastructure, personalized viewing experiences, and hybrid service models to strengthen subscriber retention. These developments are gradually driving the market toward more integrated, digital-centric entertainment ecosystems.
Analyst Perspective
The pay TV market is evolving as digitalization reshapes the entertainment industry and consumer viewing habits. Service providers are focusing on content differentiation, service innovation, and enhanced viewing experiences to retain subscribers. The growing adoption of Internet Protocol television (IPTV) is reshaping competitive dynamics by enabling flexible, technology-driven content delivery models. Strategic collaborations between content owners and distribution platforms are expanding content portfolios and integrated service offerings. Operators are also investing in digital infrastructure, personalized services, and hybrid delivery models to remain competitive. Continued shifts toward on-demand and internet-based entertainment will drive further adaptation, with long-term development depending on sustainable revenue models and the ability to meet evolving consumer expectations.
Technology Insights
The cable TV segment accounted for the largest revenue share of 36.4% in 2025, supported by continued demand for bundled and unbundled channel packages and reliable access to live television content. Live sports and major events remain important use cases for cable TV, as viewers continue to value consistent broadcast quality and broad channel availability. However, increasing adoption of streaming platforms and improvements in internet infrastructure are contributing to a gradual shift away from conventional cable services. The growing preference for flexible, on-demand content is placing pressure on traditional cable operators, limiting segment expansion despite continued demand for live programming and established television services.
The satellite TV segment accounted for a substantial share of the global pay TV market in 2025, supported by extensive channel packages, premium programming, international content, and live coverage of sports and major events. Satellite television continues to serve customers in regions where broadband infrastructure and alternative viewing options may be limited. To address increasing competition from streaming platforms, satellite operators are expanding their digital and hybrid service offerings by integrating streaming capabilities with traditional television services. These developments are enabling providers to broaden access to content, improve service flexibility, and address changing consumer viewing preferences.
Meanwhile, the internet protocol television (IPTV) segment is expected to register the fastest CAGR during the forecast period, driven by increasing internet penetration, technological advancements, and rising demand for flexible content delivery. IPTV combines live television with on-demand programming and enables users to access content across devices such as smart TVs, tablets, and smartphones. The ability to personalize channel selections and content categories further supports adoption among consumers seeking greater control over their viewing experience. In addition, the integration of 5G, artificial intelligence (AI), and advanced recommendation technologies is enhancing IPTV functionality by supporting higher-quality streaming, personalized content discovery, and more responsive user interfaces. Continued investment in digital infrastructure and AI-enabled services is expected to support IPTV's expansion during the forecast period.
Application Insights
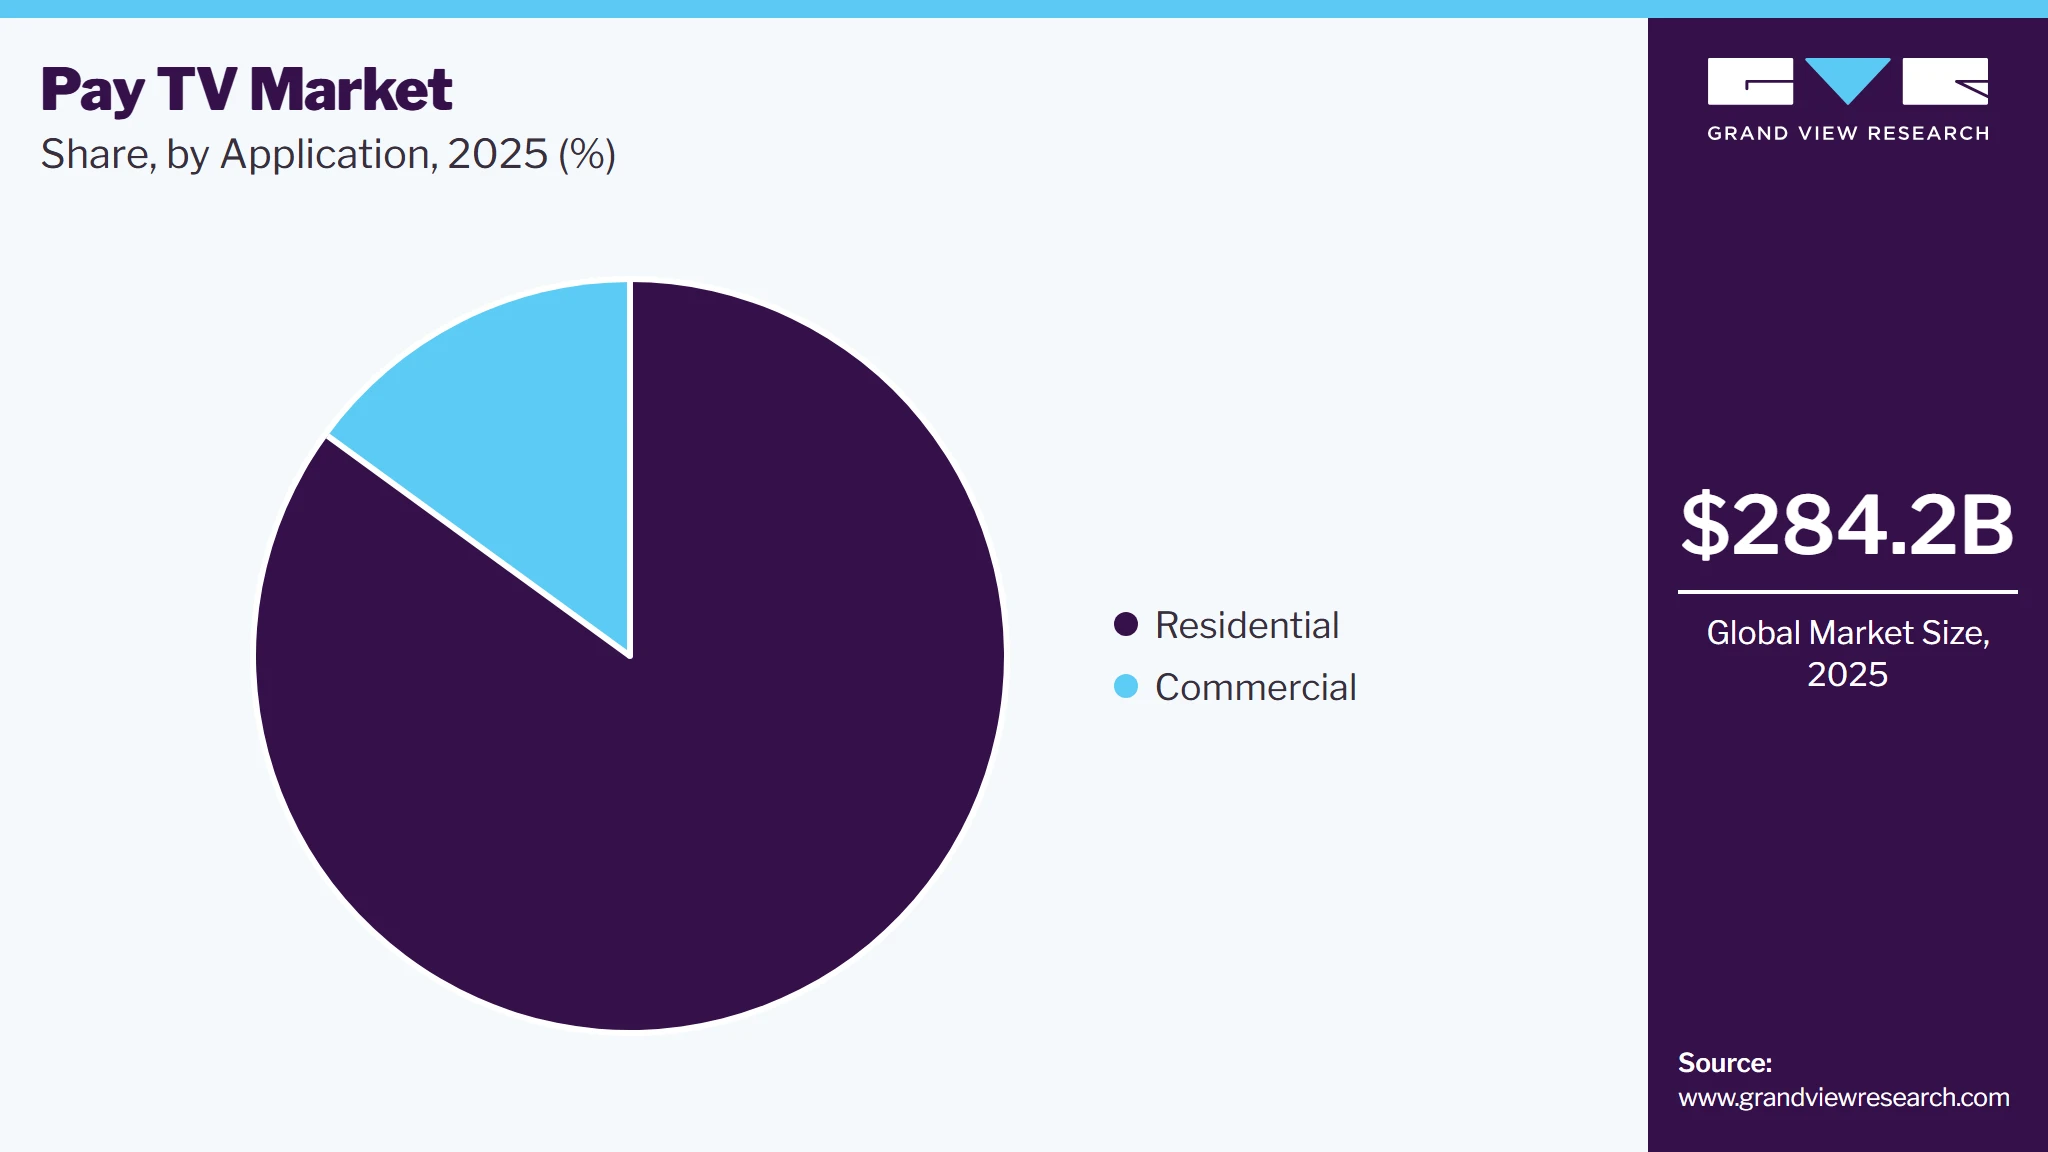
The residential segment dominated the pay TV industry, accounting for a revenue share of 85.0% in 2025, supported by increasing adoption of pay TV services, particularly in developing economies. Consumers are increasingly seeking high-resolution programming, diverse channel options, and intuitive menus and controls that enhance the overall viewing experience. Pay TV also offers a broad range of programming suitable for different age groups, supporting its continued use among family households. To retain subscribers amid changing viewing preferences, service providers are increasingly integrating streaming capabilities and expanding their content offerings. However, the growing shift toward alternative digital entertainment platforms is expected to moderate the segment growth.
 To learn more about this report, Download Free Sample Report
The commercial segment is projected to grow at the fastest CAGR from 2026 to 2033, driven by increasing demand for premium entertainment services across hotels, restaurants, pubs, and other commercial establishments. Businesses are increasingly using pay TV to provide customers with access to live sports, news, and entertainment programming, with major sporting events such as football, soccer, cricket, and basketball helping attract and retain patrons. Live broadcasts can also support event-based promotions and increase customer engagement, creating opportunities for businesses to drive spending on food, beverages, merchandise, and other services. In addition, commercial installations typically require appropriate content licensing, specialized equipment, and professional installation to support multiple screens and deliver consistent, high-quality viewing experiences. These requirements are contributing to the demand for tailored pay TV solutions in commercial environments.
Regional Insights
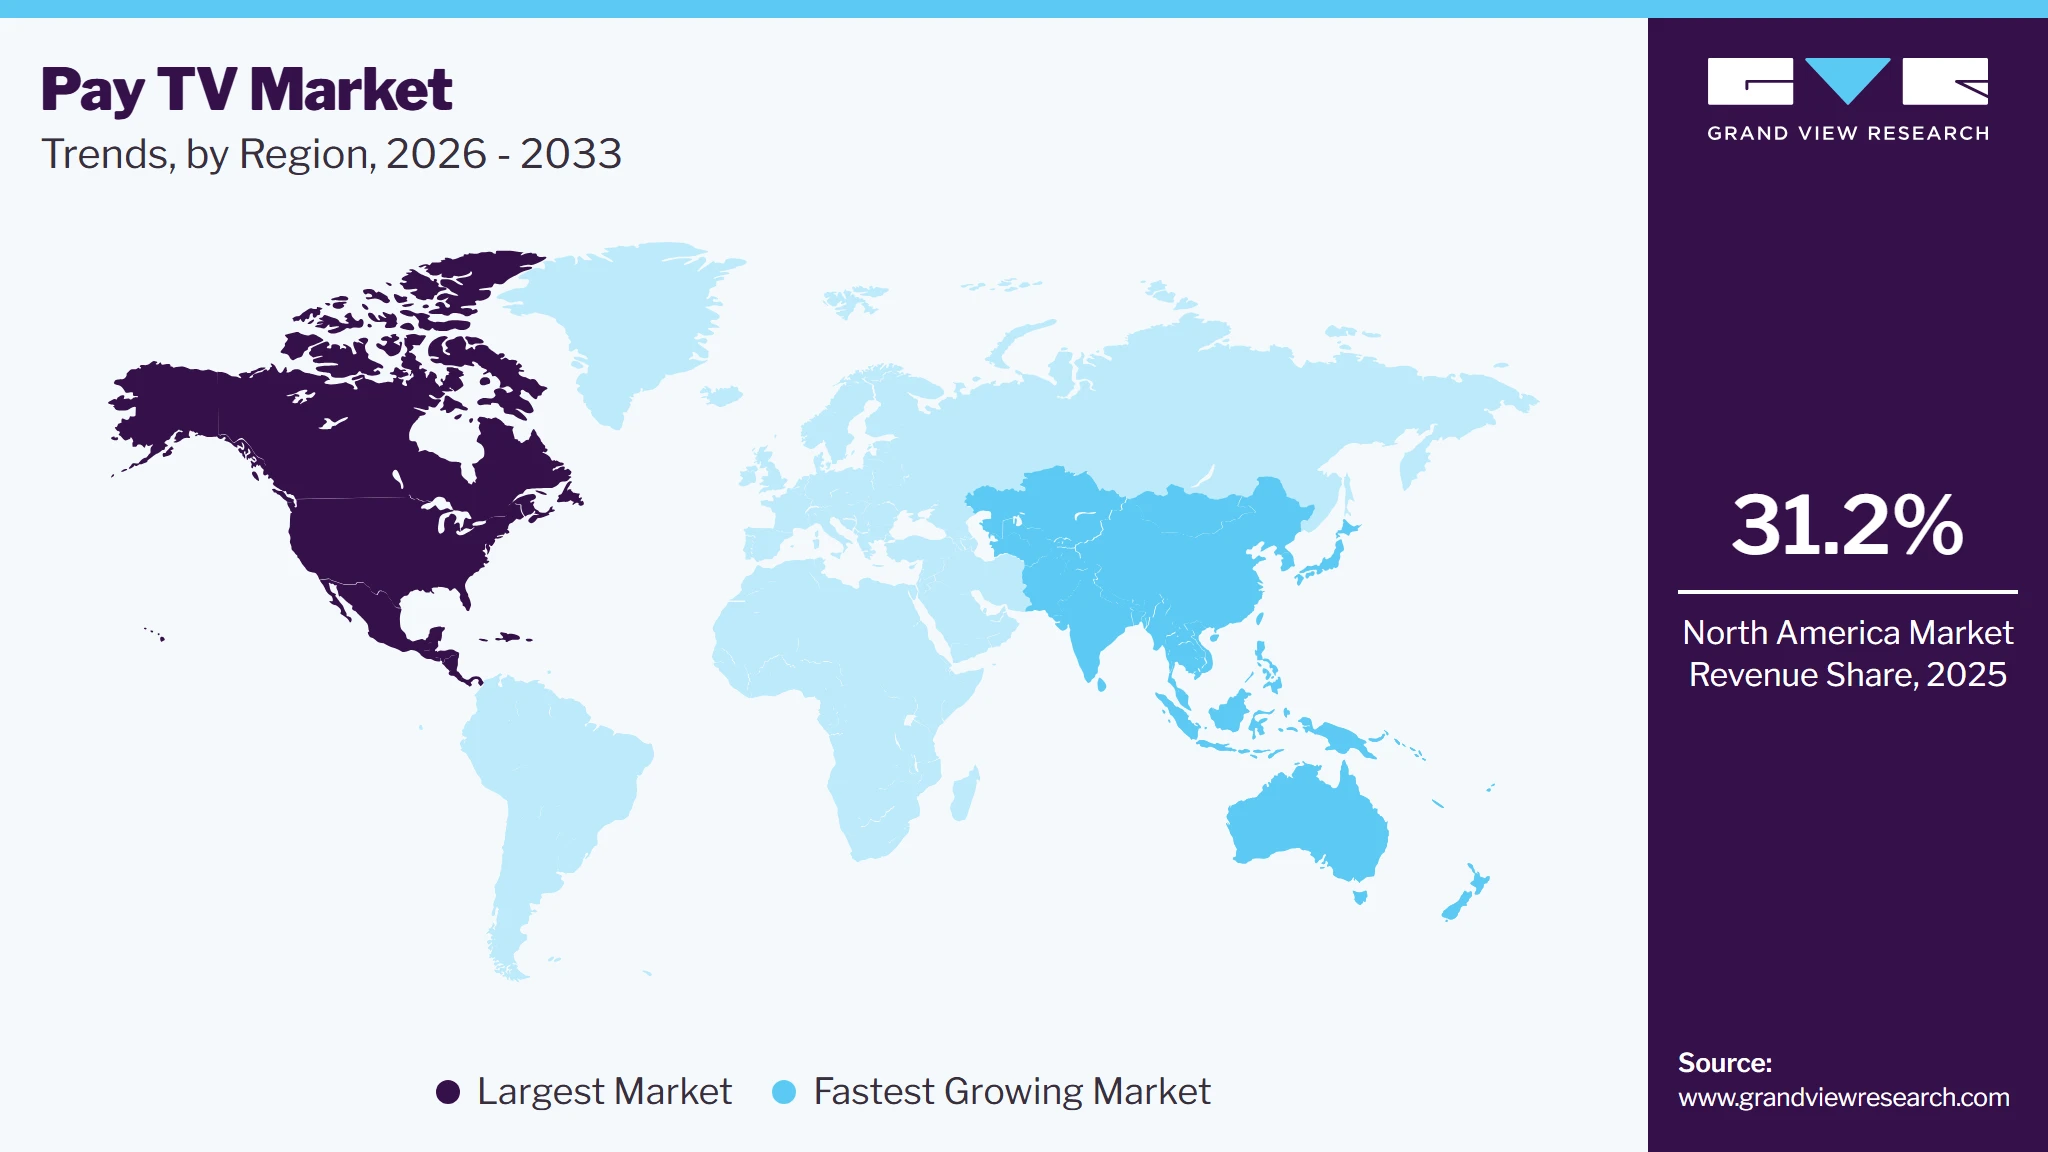
North America accounted for the largest revenue share of 31.2% in 2025, supported by widespread adoption of television and internet services and the presence of established pay TV operators. The region’s competitive landscape includes major providers such as Charter Communications, DIRECTV, and Cox Communications, which are investing in service innovation, content offerings, and advanced delivery technologies. In addition, increasing interest among regional operators in Integrated Broadband-Broadcast (IBB) systems is supporting the development of more integrated content delivery models and is expected to create further opportunities for market growth.
 To learn more about this report, Download Free Sample Report
The U.S. pay TV market accounted for the largest share of North America in 2025, supported by high household penetration of television services and the continued presence of multiple-TV households. The market is evolving in response to technological advancements, increasing competition from streaming platforms, and changing consumer viewing preferences. Although pay TV maintains a substantial subscriber base, the growing adoption of over-the-top (OTT) services and increased access to content through smartphones and other connected devices are placing pressure on traditional television services. In response, providers are introducing value-added services, flexible packages, and competitively priced offerings to strengthen subscriber retention and attract new customers.
Europe Pay TV Market Trends
The Europe pay TV industry represents a substantial share of the global industry, supported by the widespread availability of cable, satellite, and Internet Protocol television (IPTV) services. Market performance varies across individual countries, reflecting differences in consumer preferences, broadband infrastructure, and the adoption of digital entertainment platforms. The increasing penetration of over-the-top (OTT) services, including Netflix, Amazon Prime Video, and Disney+, is intensifying competition for traditional pay TV providers and reshaping viewing behavior. Consumers are increasingly seeking flexible access to live and on-demand content across multiple devices, encouraging operators to adapt their service offerings. In response to these changing preferences, European pay TV providers are increasingly adopting hybrid service models that combine traditional television with streaming capabilities. These integrated offerings enable operators to provide broader content libraries, greater viewing flexibility, and access to both live programming and on-demand content through a single platform. Continued investments in digital infrastructure, content aggregation, and personalized viewing services are expected to support the evolution of the Europe market as providers adapt to the increasing digital media landscape.
Asia Pacific Pay TV Market Trends
The Asia Pacific pay TV industry is projected to grow at the fastest CAGR from 2026 to 2033, supported by increasing demand for high-definition (HD) video content and continued digitalization across major economies such as China, India, and Japan. The region’s large subscriber base and expanding television penetration provide a strong foundation for market development. In addition, the growing adoption of Internet Protocol television (IPTV) is creating new opportunities as consumers increasingly seek flexible, on-demand, and internet-based content delivery. Continued investments in broadband infrastructure and digital entertainment platforms are expected to further support regional market expansion.
The India pay TV market is expected to account for a significant share of Asia Pacific over the coming years, supported by rising television penetration in rural areas and a competitive service provider landscape. The availability of diverse pay TV offerings and the continued expansion of digital television services are supporting market development across the country. However, increasing adoption of lower-cost streaming platforms and other digital entertainment alternatives is expected to place pressure on traditional pay TV services. In response, service providers are likely to focus on flexible packages, value-added services, and integrated television and streaming offerings to maintain subscriber engagement and address evolving consumer preferences.
Key Pay TV Company Insights
Some of the major companies involved in the global pay TV market include DIRECTV, Foxtel, and Comcast.
-
DIRECTV is a leading provider of digital television entertainment services in the U.S. The company has become a prominent player in the pay TV industry, offering satellite television services and a variety of programming options. DIRECTV provides a wide range of satellite TV packages, including local and national channels, premium networks, and specialty channels. Its Genie DVR system allows users to record multiple shows simultaneously and store hundreds of hours of programming.
-
Foxtel is a major Australian subscription television provider known for delivering a wide range of entertainment, sports, and news programming. The company is a joint venture between News Corp Australia and Telstra Corporation and offers Pay TV services, streaming services such as Kayo Sports and Binge, and on-demand content.
Key Pay TV Companies
The following key companies have been profiled for this study on the pay TV market.
-
Fetch TV Pty Limited
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weakness
Mature Players: Comcast; Charter Communications; DISH Network L.L.C; DIRECTV, LLC
- Focus on bundled services, large-scale infrastructure, and long-term content contracts to retain subscribers and maintain market share.
- Strong brand presence, large subscriber base, and extensive bundled service ecosystems supported by premium content rights and advanced infrastructure.
- High operating costs, slower adaptability to changing consumer preferences, and dependency on traditional subscription models.
Emerging Players: Tata Play; d2h; Fetch TV Pty Limited
- Focus on cost-efficient models, flexible pricing, and targeted expansion to grow the subscriber base and improve competitiveness.
- Lower pricing, flexible service offerings, and agility in adopting digital-first and niche content strategies to attract targeted customer groups.
- Limited scale, weaker content portfolios, and lower bargaining power with content providers and infrastructure partners.
Recent Developments
-
In June 2025, Charter expanded its agreement with The Walt Disney Company to include Hulu with Ads at no additional cost for Spectrum TV Select customers, alongside Disney+ and the forthcoming ESPN streaming service. The agreement also restored several Disney-owned networks to Spectrum’s linear lineup, reflecting the growing integration of streaming and traditional pay TV offerings.
-
In February 2025, DIRECTV introduced new Genre Packs and Mini-Packs that allow customers to select specific categories of programming rather than subscribing to traditional large channel bundles. The offering builds on DIRECTV’s earlier MySports and MyFree DIRECTV services and includes access to streaming services alongside live programming.
-
In September 2024, DIRECTV and The Walt Disney Company announced an agreement that has led to the latter's full linear suite of networks being restored to customers of DIRECTV, DIRECTV STREAM, and U-verse. This will allow DIRECTV to broadcast Disney’s sports, entertainment, and news programming from its extensive portfolio, which includes ESPN networks, ABC-owned Television Stations, Disney-branded channels, FX networks, and National Geographic channels. Moreover, Disney's direct-to-consumer streaming services, including Disney+, Hulu, and ESPN+, would also be included in select DIRECTV packages.
Pay TV Market Report Scope
Report Attribute
Details
Market size in 2025
USD 284.2 billion
Estimated Market size in 2026
USD 295.0 billion
Projected market size by 2033
USD 365.3 billion
Growth rate
CAGR of 3.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market position analysis, competitive landscape, growth factors, and trends
Segments covered
Technology, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; Australia; South Korea; Brazil; KSA; UAE; South Africa
Key companies profiled
DIRECTV, LLC; DISH Network L.L.C.; Foxtel; Comcast; Fetch TV Pty Limited; Rostelecom PJSC; Charter Communications; Tata Play; d2h; Cox Communications, Inc.
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Pay TV Market Report Segmentation
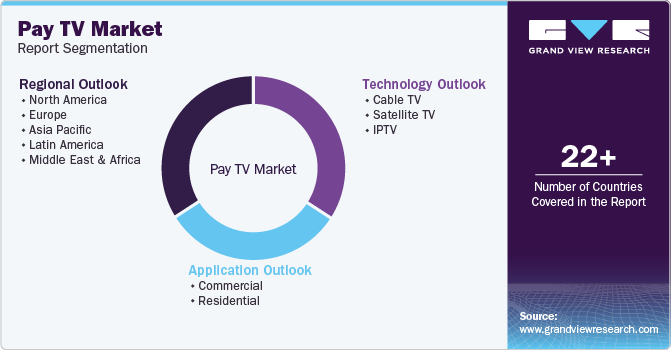
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pay TV market report based on technology, application, and region:
 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cable TV
-
Satellite TV
-
IPTV
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Commercial
-
Residential
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
MEA
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Scope & Research Methodology
The pay TV market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing, reconciling supply-side and demand-side estimates, and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pay TV segment quantified using the revenue-capture definitions in the table below.
The pay TV market is segmented into three levels, namely, technology, application, and region. In the first level, the market has been split by technology, as follows:
• Cable TV: Cable TV revenue capture is driven by subscription-based pricing structures, where operators earn income through packaged channel offerings delivered over wired infrastructure. Additional revenue is generated from regional advertising and bundled service arrangements with broadband or telephony services.
• Satellite TV: Satellite TV revenue capture is primarily based on direct-to-home subscription fees, with operators monetizing through tiered channel packages and premium content access. Pay-per-view services and long-term subscription contracts further contribute to revenue generation.
• IPTV: IPTV revenue capture relies on internet-based delivery models, where income is generated through subscription plans, on-demand content access, and interactive service features. Operators also benefit from personalized content offerings and add-on digital services that enhance monetization potential.
Based on application, the market has been segmented into commercial and residential:
• Commercial: Revenue capture in the commercial segment is derived from business and institutional customers such as hotels, offices, hospitals, and retail spaces. Operators secure income through enterprise-level contracts that often include customized channel packages and bulk service agreements. Additional value-added services further enhance revenue streams in this segment.
• Residential: Revenue capture in the residential segment is generated from household subscribers using Pay TV services for personal entertainment needs. Income is primarily structured around recurring subscription fees and bundled content packages. Optional premium channels and on-demand content purchases contribute to incremental revenue growth.
Based on region, the market has been segmented into North America, Europe, Asia Pacific, Latin America, and Middle East & Africa:
• North America: The North America regional market includes the markets of the U.S., Canada, and Mexico.
• Europe: The Europe regional market includes the markets of the UK, Germany, and France.
• Asia Pacific: The Asia Pacific regional market includes the markets of China, India, Japan, Australia, and South Korea.
• Latin America: The Latin America market includes the markets of Brazil.
• Middle East & Africa: The MEA regional market includes the markets of the UAE, Saudi Arabia, and South Africa
Estimation Model
Layer Name
Key Question
Description
Household & User Base Layer
Who creates demand for Pay TV services?
Identify total residential households and commercial establishments such as hotels, offices, and institutions with television access. This layer defines the overall potential user base for Pay TV services across regions.
Pay TV Subscriber Layer
Which users actively subscribe to Pay TV services?
Filter the total user base based on subscription penetration, income levels, digital access, and content consumption behavior. This layer represents active Cable TV, Satellite TV, and IPTV subscribers.
Service Consumption Layer
What Pay TV services and content are consumed?
Estimate consumption across channel packages, premium content, sports subscriptions, and on-demand offerings. Service mix varies across Cable TV, Satellite TV, and IPTV platforms.
Revenue Capture Layer
How is revenue generated in the Pay TV ecosystem?
Calculate revenue through subscription fees, bundled packages, advertising income, and premium content monetization across Cable TV, Satellite TV, and IPTV distribution channels.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Entry & Expansion Assessment
Chann
Regional subscriber opportunity assessment
Pay TV penetration and adoption analysis
Competitive landscape evaluation
Distribution network and market access assessment
Identified attractive growth markets
Supported expansion strategy development
Highlighted competitive risks and opportunities
Improved market prioritization decisions
Customer & End-User Insights Study
Subscriber behavior and viewing preference analysis
Content consumption pattern assessment
Customer satisfaction and retention evaluation
Household and commercial user segmentation
Identified key subscriber expectations
Supported customer-focused service enhancements
Improved retention and engagement strategies
Revealed opportunities for revenue growth
Product Positioning & Competitive Intelligence
Service package benchmarking
Pricing structure analysis
Content portfolio comparison
Competitive strategy assessment
Strengthened service differentiation
Supported pricing optimization initiatives
Identified competitive advantages and gaps
Enhanced market positioning and subscriber acquisition efforts
Frequently Asked Questions About This Report
The global pay TV market size was valued at USD 284.2 billion in 2025 and is expected to reach USD 295.0 billion in 2026.
The global pay TV market is expected to grow at a compound annual growth rate of 3.1% from 2026 to 2033 to reach USD 365.3 billion by 2033.
North America dominated the Pay TV market with a share of 31.2% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The residential segment dominated the pay TV market with a share of around 85.0% in 2025, while the commercial is the fastest-growing segment.
Key factors that are driving the market growth include technological advancements in the pay-TV industry, improved value-added services, and demand for HD and SD content delivered by pay-TV providers.
The U.S. dominated the global Pay TV market in 2025, accounting for the largest revenue share due to its extensive subscriber base, high service penetration, strong content ecosystem, and widespread adoption of premium television services.
The cable TV segment dominated the global pay TV market with a share of 36.4% in 2025.
Some of the key players in the global pay TV market include DIRECTV, LLC; DISH Network L.L.C.; Foxtel; Comcast; Fetch TV Pty Limited; Rostelecom PJSC; Charter Communications; Tata Play; d2h; Cox Communications, Inc.
About the Author(s)
Digital Media Research Team
Technology · Digital MediaThis report was authored by the digital media research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the digital media segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


