
- Home
- »
- Medical Devices
- »
-
Pediatric Home Healthcare Market Size Report, 2026-2033GVR Report cover

Pediatric Home Healthcare Market (2026 - 2033)
Size, Share & Trends Analysis Report By Service (Skilled Nursing Services, Personal Care Assistance, Rehabilitation Therapy Services), By Region (North America, Asia Pacific), And Segment Forecasts
Market Size, 2025
$44.5BMarket Estimate, 2026
$48.0BMarket Forecast, 2033
$82.7BCAGR, 2026–2033
8.1%Pediatric Home Healthcare Market Summary
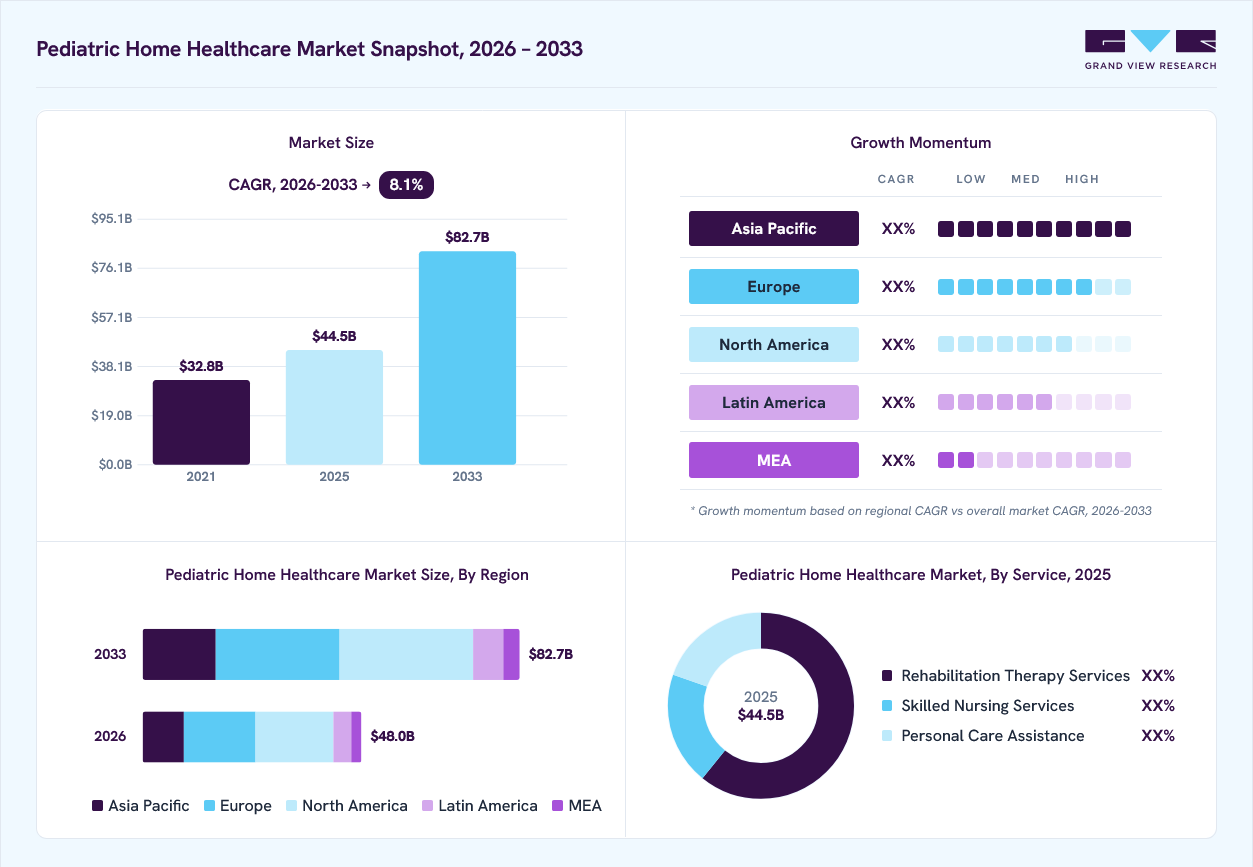
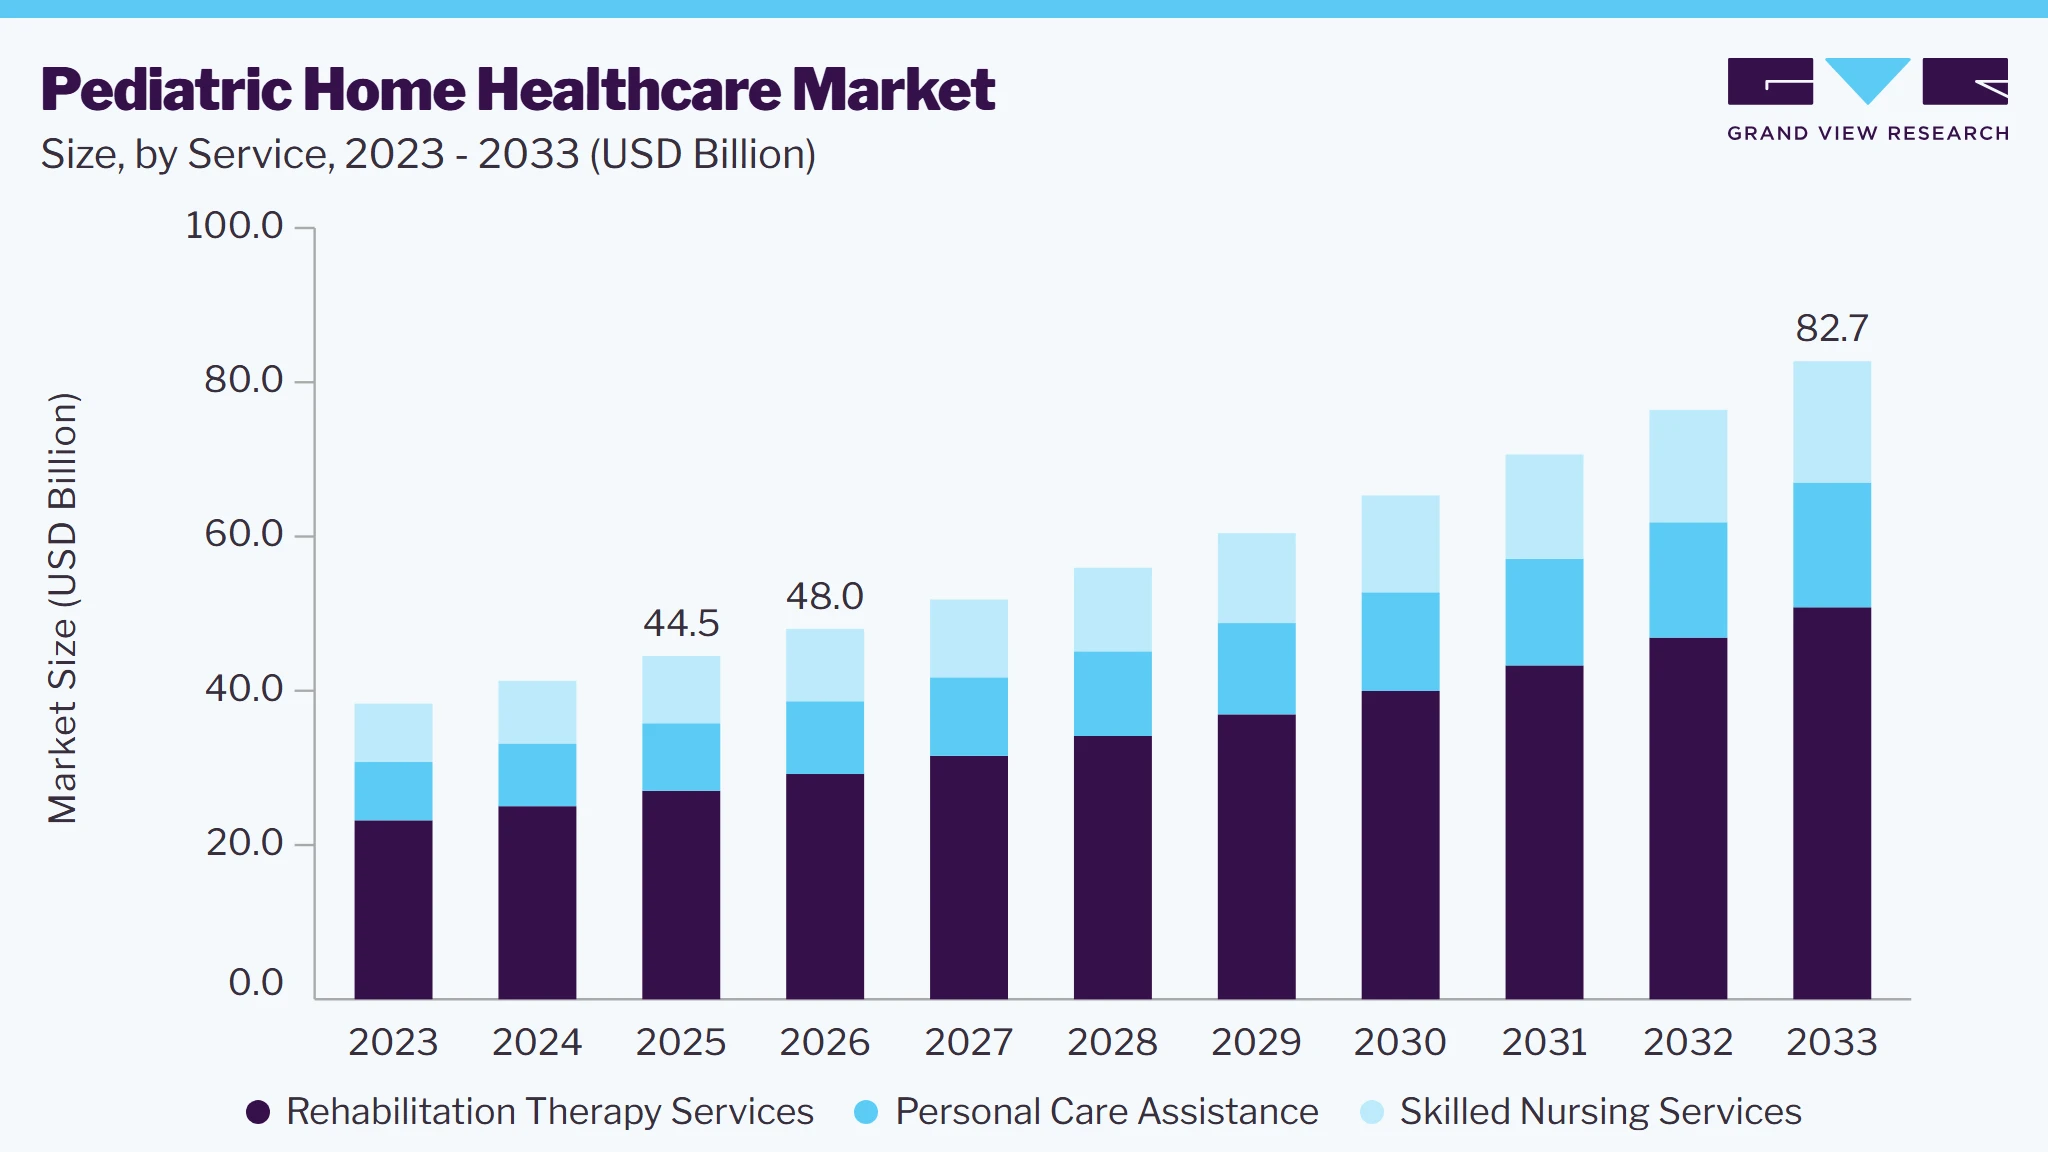
The global pediatric home healthcare market size was valued at USD 44.5 billion in 2025 and is projected to grow from USD 48.0 billion in 2026 to USD 82.7 billion by 2033, at a CAGR of 8.1% from 2026 to 2033. North America dominated the pediatric home healthcare market with the largest revenue share of 35.6% in 2025. The use of advanced technologies to provide medical assistance and continuous care at home for children with medical complexities (CMC) is expected to boost market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By service: Rehabilitation therapy services segment held the largest market share of 60.7% in 2025.
Regional Highlights
- Largest regional market: North America (35.6% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 44.5 Billion
- Estimated market size in 2026: USD 48.0 Billion
- Projected market size by 2033: USD 82.7 Billion
- CAGR (2026-2033): 8.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These technologies facilitate life-sustaining home healthcare services in a comfortable setting, reducing hospital stays for infants with respiratory disorders, neurological, and complex cardiac conditions. According to the National Survey of Children with Special Healthcare Needs, in 2019-2020, nearly 1 in 5 children (19.4%) in the United States had special healthcare needs, totaling 14.1 million children.
 To learn more about this report, Download Free Sample Report
As the number of children with special healthcare needs (CSHCN) continues to increase, pediatric home healthcare services can enhance their quality of life and significantly decrease their medical expenses. In addition, improved medical interventions have resulted in an extended lifespan for premature babies, leading to a greater need for pediatric care services at home. Infants who are born prematurely and weigh less than 1 pound often experience multiple chronic conditions, requiring additional care from an early stage. The availability of assistive devices and equipment, such as gastric, CPAP machines, ventilators, apnea monitors, and nebulizers, have enabled infants with complex illnesses to be discharged from neonatal intensive care units and receive ongoing medical assistance through pediatric nursing care in their own homes.
The rising number of children with chronic diseases has created investment opportunities in pediatric home healthcare. A study by Lero and colleagues (2021) found that over 625,000 Canadian families with preschoolers had at least one parent working non-standard hours, but only 2% of childcare centers offered care during those hours. Increasing availability of childcare options is expected to benefit parents seeking specialized healthcare for their children with chronic diseases. With more flexible childcare centers, parents can access healthcare services while managing their work. This is expected to drive the growth of the market, as parents can confidently seek specialized care for their children.
Favorable insurance policies are expected to drive the growth of the market. The American Academy of Pediatrics states that Medicaid covers essential services like primary care, hospice care, personal care assistance, and nursing care for children. Medicaid primarily covers the majority of pediatric expenses, while private insurance also contributes to the remaining costs. For instance, insurance providers, such as Texas Star Kids, CHIP, Community First Healthcare Plans, Texas Children’s Health Plan, and Children’s Medical Center Health Plan, accept Pediatric Home Healthcare, a Texas-based company that offers various programs.
This increased coverage is expected to boost the demand for pediatric healthcare services. The COVID-19 pandemic had both positive and negative effects on the global market. On the positive side, the pandemic increased the demand for pediatric home healthcare services. These services allow medical treatment to be provided in the comfort of patients’ homes, which is beneficial in times of restricted movement and social distancing measures. Furthermore, home healthcare services help minimize the spread of COVID-19 by reducing the need for patients to visit healthcare facilities.
Market Dynamics
The pediatric home healthcare market is witnessing steady growth due to the rising prevalence of chronic and complex pediatric conditions, increasing demand for cost-effective home-based care, and growing preference for personalized treatment outside hospital settings. Advances in telehealth, remote patient monitoring, favorable reimbursement policies, and government support for home healthcare services are further driving market growth. In addition, increasing healthcare expenditure and the need for long-term care for medically fragile children continue to create significant opportunities for market participants.
The use of advanced technologies to provide medical assistance and continuous care at home for children with medical complexities (CMC) is expected to boost market growth. These technologies facilitate life sustaining home healthcare services in a comfortable setting, reducing hospital stays for infants with respiratory disorders, neurological, and complex cardiac conditions. A study published in American Heart Association Journal Circulation in August 2024 found that nearly 2% of children in a large Colorado insurance database were diagnosed with congenital heart defects (CHDs), almost double previous estimates. In addition, congenital heart defects are the most common birth defect in the U.S., with previous estimates placing the number at about 40,000 babies each year, or 1% of all births nationally. The findings highlight the growing need for long-term pediatric healthcare and home-based care services for children with complex medical conditions and associated chronic disorders.
Case Study Published by EIIC in October 2024: Improving Pediatric Emergency Care Increases Life Expectancy and Reduces Costs
Background:
Emergency departments (EDs) are often the first point of contact for critically ill or injured children. However, not all EDs in the United States are adequately equipped or trained to deliver high-quality pediatric care. In response, the National Pediatric Readiness Project (NPRP) was developed to assess and improve pediatric emergency preparedness across hospitals nationwide.
Study Overview:
A landmark study led by Stanford Medicine, in collaboration with the Emergency Medical Services for Children (EMSC) Innovation & Improvement Center, analyzed data from 747 emergency departments in 11 U.S. states. This encompassed nearly 8 million pediatric visits. The goal was to quantify the impact of enhancing pediatric readiness on child health outcomes and cost-effectiveness.
Findings:
- Emergency departments scoring 88/100 or higher in pediatric readiness saw up to 76% lower child mortality rates.
- Improving readiness levels across all hospitals to this threshold could result in:
- 76,800 additional life years gained
- 69,100 quality-adjusted life years (QALYs)
- An estimated 2,143 pediatric deaths are prevented annually
- The average cost per QALY gain was USD 9,300, far below the widely accepted threshold of USD 50,000, making the investment highly cost-effective.
- The cost per life saved was calculated at approximately USD 244,000, with an estimated implementation cost ranging from USD 0 to USD 12 per child per year depending on the state.
Implications for the Pediatric Healthcare Market
This case study provides clear evidence that systemic improvements in pediatric emergency care not only increase life expectancy for children but also represent a financially sound investment. The findings support broader integration of pediatric-specific training, equipment, and coordination roles (e.g., Pediatric Emergency Care Coordinators) across EDs.
The shortage of skilled pediatric home care nurses remains a major challenge for the market, limiting the ability of providers to deliver timely, high-quality care to children with complex medical needs. Pediatric home healthcare requires specialized expertise in ventilator support, tracheostomy care, feeding tube management, and chronic disease management, making recruitment and retention difficult. Workforce shortages, caregiver burnout, and inadequate reimbursement have resulted in reduced service capacity, delayed hospital discharges, and increased reliance on family caregivers, thereby restricting market growth.
In November 2025, the American Academy of Pediatrics (AAP) released an updated policy highlighting that many children requiring home healthcare receive only about half of their approved home nursing hours because of workforce shortages and funding gaps. The AAP noted that these shortages contribute to delayed hospital discharges, unnecessary hospitalizations, and reduced access to essential pediatric home healthcare services.
The expansion of telehealth and remote patient monitoring (RPM) presents a significant opportunity for the pediatric home healthcare market by enabling continuous, high-quality care for children with chronic and medically complex conditions in their homes. Digital health technologies allow healthcare providers to remotely monitor vital signs, manage treatment plans, conduct virtual consultations, and intervene early when complications arise, reducing hospital admissions and improving patient outcomes. These technologies also enhance care coordination between pediatric specialists, home healthcare providers, and caregivers, making home-based care more efficient and accessible, particularly in rural and underserved areas.
In June 2026, Medtronic expanded its acute care & monitoring portfolio in the U.S. through an exclusive distribution agreement with Corsano Health for the FDA-cleared Corsano multi-parameter wearable. The wrist-worn device continuously monitors vital signs such as heart rate, respiratory rate, oxygen saturation (SpO₂), skin temperature, and activity, enabling clinicians to remotely track patients from the hospital to the home. By supporting continuous remote patient monitoring and early clinical intervention, the partnership strengthens hospital-at-home and home healthcare models, demonstrating the growing role of digital health technologies in improving patient outcomes and expanding access to home-based care.
Analyst Perspective
The pediatric home healthcare market is growing due to the rising prevalence of chronic pediatric conditions, increasing demand for home-based care, advancements in remote patient monitoring and medical technologies, and supportive reimbursement policies. Families and healthcare providers are increasingly opting for home healthcare to improve patient outcomes, enhance comfort, and reduce hospitalization costs.
The key competitive advantage will belong to providers offering comprehensive pediatric care, skilled multidisciplinary teams, advanced digital health solutions, and strong partnerships with hospitals and payers. Investments in workforce expansion, technology integration, and family-centered care will be critical to strengthening market position and driving long-term growth.
Service Insights
Based on service, the rehabilitation therapy services segment dominated the market with the largest revenue share of 60.7% in 2025 and anticipated to grow at the fastest CAGR from 2026 to 2033. The segment is expected to witness the fastest growth over the forecast period. The high probability of premature infants experiencing neurological and muscular challenges is anticipated to increase the demand for rehabilitation therapy services during the forecast period. Many service providers currently offer different types of rehabilitation therapies, including speech, physical, and occupational therapies, for children with conditions like cerebral palsy, autism, muscular atrophy, and ADD/ADHD.
 To learn more about this report, Download Free Sample Report
Skilled nursing services held a significant market share due to the rising number of children with complex medical conditions like epilepsy, asthma, cerebral palsy, and cystic fibrosis. These services have effectively decreased the inpatient expenses for children with medical complexities. An article published in Health Affairs journal in June 2019 revealed that the cost of home nursing care in rural areas can be as low as USD 19 to USD 21 per hour, compared to USD 23 to USD 38 per hour for hospital nursing care.
Pediatric home care providers face significant difficulties retaining qualified nursing staff to deliver excellent care for children with special healthcare needs. Market players are implementing strategic initiatives to address these challenges to enhance their capabilities. For instance, in July 2022, Pediatric Home Services acquired Craig HomeCare, a provider of pediatric nursing services, and Cherub Medical Supply, a medical equipment provider. With this acquisition, both providers will collaborate with PHS to improve the efficiency of care for children with complex medical conditions, aiming to streamline their treatment and support.
Regional Insights
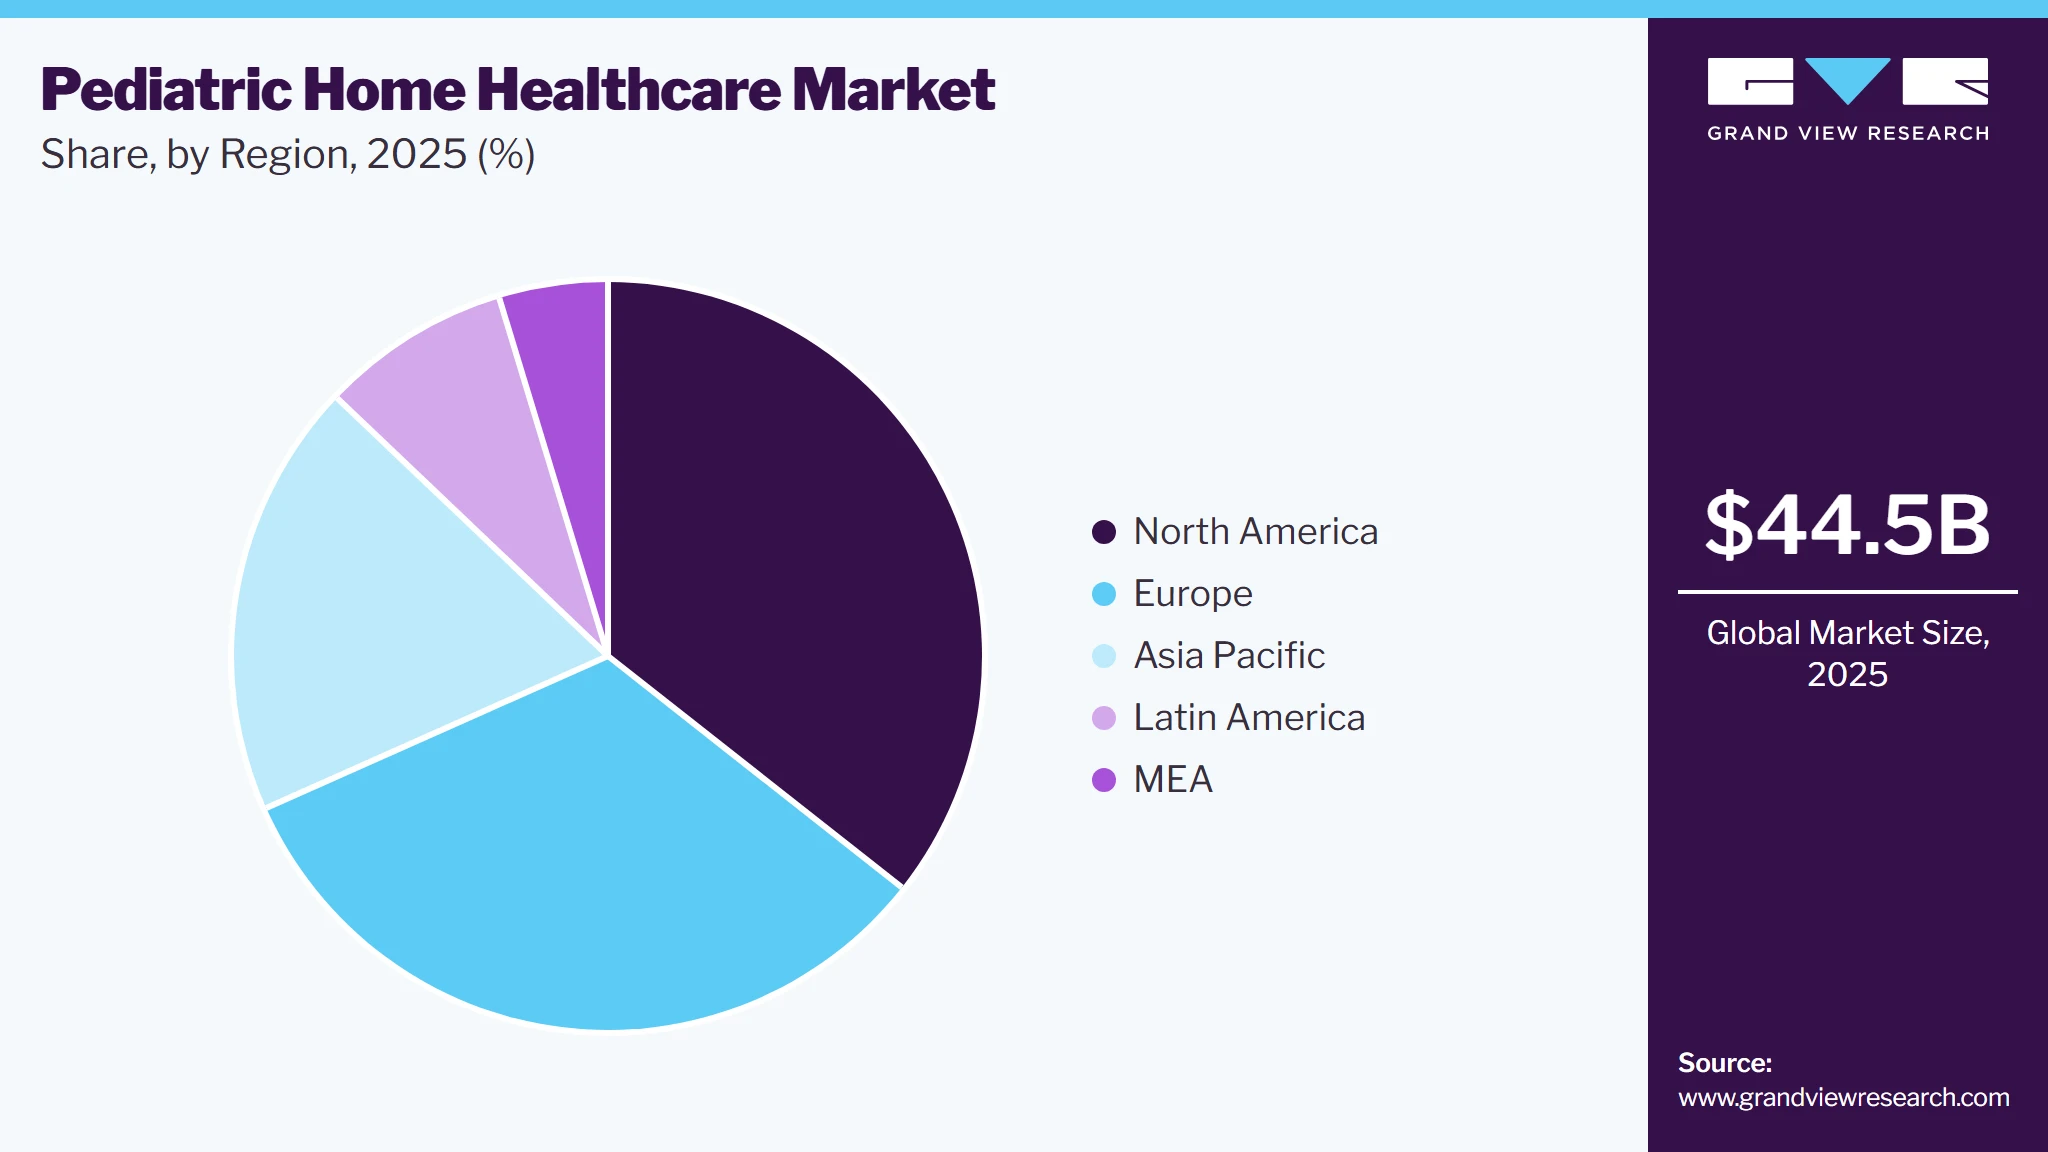
North America dominated the pediatric home healthcare market with the largest revenue share of 35.6% in 2025. Prolonged hospital stays can be expensive, but pediatric home-based services offer a cost-effective solution that improves patient care efficiency. As a result, many providers in the United States are offering a range of services to meet the growing demand for pediatric home healthcare. The market growth in North America is further supported by the increasing coverage for children and youth with special healthcare needs. A report published by the Medicaid and CHIP Payment and Access Commission in 2023 revealed that approximately 18.9% of U.S. children and youth aged 0 to 17 years with special healthcare needs are covered under various insurance plans.
Specifically, 37.8% are covered by Medicaid, 50.9% by private insurance, and 7.6% have private insurance and Medicaid coverage. This expanded coverage is expected to drive the growth of the regional market. Asia Pacific is anticipated to register the fastest CAGR during the forecast period. With improved survival rates for neonatal babies and premature infants, there is a growing demand for in-home pediatric care due to the higher risk of neurological and physical disorders in children. Recognizing this need, BAYADA Home Health Care has launched pediatric services in India and South Korea. Moreover, ongoing technological progress and supportive government initiatives fuel the market expansion throughout the region.
Key Companies & Market Share Insights
Major players are undertaking various strategic initiatives, such as collaborations, mergers & acquisitions, geographical expansions, and services expansions, to gain higher market share. For instance, in April 2022, Pediatric Home Healthcare, LLC acquired Vila Children Therapy, a provider of pediatric physical, speech, and occupational therapy. This acquisition aims to strengthen the company's position in both national and international markets. Some of the prominent players in the global pediatric home healthcare market include:
Key Pediatric Home Healthcare Companies:
The following key companies have been profiled for this study on the Pediatric Home Healthcare Market.
-
Pediatric Home Healthcare, LLC
-
Aveanna Healthcare, LLC.
-
BAYADA Home Health Care
-
Tendercare Home Health
-
BrightStar Care
-
Angels of Care Pediatric Home Health
-
New England Home Health Services
-
EnViva Paediatric Care
-
Interim HealthCare Inc.
-
eKidzCare
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Aveanna Healthcare, BAYADA Home Health Care, Enhabit, Inc., Pediatric Home Service)
Expand pediatric home nursing and therapy services across multiple regions, strengthen referral partnerships with children's hospitals and physicians, invest in remote patient monitoring and care coordination technologies, enhance caregiver training and clinical quality programs, and pursue acquisitions to broaden geographic presence and specialized pediatric capabilities.
Extensive clinical expertise, established referral networks, strong payer relationships, comprehensive service portfolios, accredited care standards, experienced multidisciplinary care teams, broad geographic coverage, and the ability to manage medically complex pediatric cases at home.
Higher operating and labor costs, dependence on reimbursement policies, challenges in recruiting and retaining qualified pediatric nurses and therapists, operational complexity across multiple service lines, and slower expansion into underserved rural markets.
Emerging Players (regional pediatric home healthcare providers, specialty pediatric nursing agencies, technology-enabled home healthcare companies)
Focus on specialized pediatric nursing services, personalized family-centered care, telehealth integration, niche chronic disease management, home infusion and respiratory care, and expansion into underserved communities through flexible care delivery models.
Greater operational flexibility, personalized patient engagement, faster service deployment, specialized expertise in niche pediatric conditions, innovative digital care platforms, and the ability to customize care plans for individual patient needs.
Limited geographic footprint, smaller clinical workforce, lower brand recognition, fewer contracts with large healthcare systems and insurers, constrained financial resources for expansion, and greater vulnerability to workforce shortages and reimbursement fluctuations.
Pediatric Home Healthcare Market Report Scope
Report Attribute
Details
Market size in 2025
USD 44.5 billion
Estimated market size in 2026
USD 48.0 billion
Projected market size by 2033
USD 82.7 billion
Growth rate
CAGR of 8.1% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Service, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Mexico; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Pediatric Home Healthcare, LLC; Aveanna Healthcare, LLC.; BAYADA Home Health Care; Tendercare Home Health; BrightStar Care; Angels of Care Pediatric Home Health; New England Home Health Services; EnViva Paediatric Care; Interim HealthCare Inc.; eKidzCare
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchasse. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pediatric Home Healthcare Market Report Segmentation
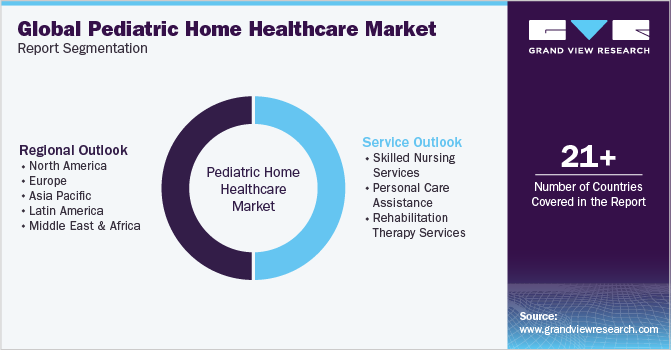
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pediatric home healthcare market report on the basis of service and region:
 To learn more about this report, Download Free Sample Report
-
Service Outlook (Revenue, USD Million, 2021 - 2033)
-
Skilled Nursing Services
-
Personal Care Assistance
-
Rehabilitation Therapy Services
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The pediatric home healthcare market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pediatric home healthcare segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Service
Revenue capture definition
Rehabilitation Therapy Services
Therapeutic interventions are specifically designed to address the unique needs of children, promoting their physical, cognitive, or emotional development and helping them reach their maximum potential.
Skilled Nursing Services
Specialized medical care provided by licensed nurses to manage and support the healthcare needs of children, including administering medication, monitoring vital signs, managing medical equipment, and coordinating care with other healthcare professionals.
Personal Care Assistance
Individualized support services that assist children with activities of daily living, such as bathing, dressing, feeding, mobility assistance, and providing a safe and nurturing environment for their overall well-being.
Estimation Model
Model Details:
This research methodology outlines the process for estimating the size of the global pediatric home healthcare market for the period from 2021 to 2033. The study covers key service segments including skilled nursing services, home infusion therapy, respiratory therapy, rehabilitation therapies (physical, occupational, and speech therapy), personal care assistance, palliative & hospice care, and other pediatric home healthcare services across major geographic regions including North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
The objective is to develop a robust and defensible market estimate through a combination of bottom-up and top-down approaches supported by primary industry validation.
A triangulated market sizing approach was used, combining:
-
Bottom-Up Analysis based on the number of pediatric patients receiving home healthcare services, service utilization rates, frequency of care visits, and average annual spending per patient.
-
Top-Down Validation using pediatric population statistics, prevalence of chronic and medically complex pediatric conditions, healthcare expenditure, birth rates, hospitalization trends, and home healthcare adoption rates.
- Primary Research with pediatric home healthcare agencies, children's hospitals, home nursing providers, physicians, pediatric specialists, rehabilitation therapists, healthcare administrators, insurers, and industry experts.
Step-by-Step Market Estimation Process:
Pediatric Patient Utilization Model
This model estimates market size by calculating the number of pediatric patients utilizing home healthcare services and the associated annual spending.
Step 1
Country-level data for pediatric population, prevalence of chronic pediatric diseases, medically fragile children, premature births, congenital disorders, and long-term pediatric care requirements were collected from government health agencies, children's hospitals, international healthcare organizations, and public health databases for 2021-2025.
Step 2
A pediatric home healthcare utilization rate was applied to estimate the percentage of eligible pediatric patients receiving home-based medical care. Utilization rates were derived from healthcare utilization studies, insurance claims data, government reports, published literature, and primary interviews.
Step 3
Average annual spending per pediatric patient was estimated using reimbursement schedules, provider billing data, payer information, service pricing benchmarks, and interviews with pediatric home healthcare providers.
Step 4
Market size was calculated by multiplying:
Number of Pediatric Patients Receiving Home Healthcare × Average Annual Spending per Patient
Step 5
Country-level market estimates were aggregated to regional and global levels.
Step 6
Historical and forecast growth rates incorporated factors such as increasing survival of medically complex children, rising prevalence of chronic pediatric diseases, technological advancements in home-based medical devices, caregiver preference for home care, healthcare cost optimization, and supportive reimbursement policies.
Pediatric Home Healthcare Provider Revenue Model
This model estimates market size based on revenues generated by pediatric home healthcare service providers.
Step 1
The number of pediatric home healthcare providers operating in each country was identified through company disclosures, healthcare directories, licensing authorities, government registries, and industry associations.
Step 2
Average annual revenue per provider was estimated using financial statements, annual reports, private company benchmarks, industry databases, and interviews with service providers.
Step 3
Provider revenues were adjusted for regional variations in reimbursement rates, labor costs, service mix, nursing intensity, and healthcare funding structures.
Step 4
Country-level market size was calculated by multiplying:
Number of Pediatric Home Healthcare Providers × Adjusted Average Annual Revenue per Provider
Step 5
Regional and global market values were obtained through aggregation of country-level estimates.
Step 6
Annual adjustments accounted for provider network expansion, mergers and acquisitions, reimbursement changes, workforce availability, technological adoption, and increasing demand for home-based pediatric care.
Service Utilization & Care Delivery Model
This model estimates market size based on the utilization of different pediatric home healthcare services.
Step 1
Service utilization data was collected from pediatric home healthcare agencies, hospitals, insurance claims databases, government reports, clinical studies, and primary interviews.
Step 2
Services were categorized into:
-
Skilled Nursing Services
-
Home Infusion Therapy
-
Respiratory Therapy
-
Physical Therapy
-
Occupational Therapy
-
Speech Therapy
-
Personal Care Assistance
-
Pediatric Palliative & Hospice Care
-
Other Pediatric Home Healthcare Services
Step 3
Average service frequency, duration of care, reimbursement levels, and annual treatment costs were established using provider data, payer schedules, healthcare utilization studies, and expert interviews.
Step 4
Revenue generated by each service category was calculated by multiplying:
Number of Pediatric Patients × Average Annual Service Utilization × Average Revenue per Service
Step 5
Service-level revenues were aggregated to estimate country, regional, and global market sizes.
Step 6
Forecast assumptions incorporated rising home healthcare adoption, increasing pediatric chronic disease burden, advancements in remote patient monitoring, improved caregiver education, expanding insurance coverage, and favorable government initiatives supporting home-based care.
Geographic Demand Potential Index (GDPI) Validation Model
In addition to the core triangulation models, a Geographic Demand Potential Index (GDPI) was developed to benchmark pediatric home healthcare demand across countries and regions.
The model incorporated five macroeconomic and healthcare indicators:
- Pediatric Population Size
- Prevalence of Chronic and Medically Complex Pediatric Conditions
- Healthcare Expenditure per Capita
- Availability of Home Healthcare Infrastructure
- Health Insurance Coverage and Reimbursement Support
Each country's GDPI score was normalized to estimate its relative share of global pediatric home healthcare services demand.
The resulting scores served as a validation framework for the estimates generated through Models 1-3, ensuring consistency with regional disease burden, healthcare accessibility, service utilization patterns, and reimbursement environments.
Final Market Triangulation
The final global pediatric home healthcare market size was derived through triangulation of:
- Pediatric Patient Utilization Model
- Pediatric Home Healthcare Provider Revenue Model
- Service Utilization & Care Delivery Model
- Geographic Demand Potential Index (GDPI) Validation Model
The weighted average of these models, validated through extensive primary interviews and secondary industry sources, was used to generate the final historical market estimates (2021-2025) and forecast projections (2026-2033) for the global pediatric home healthcare market.
This triangulated methodology ensures that the final market estimates accurately reflect patient demand, provider revenues, healthcare utilization, reimbursement structures, and regional differences in pediatric home healthcare adoption.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
AI-Enabled Pediatric Home Healthcare & Remote Monitoring Assessment
Developed an in-depth assessment of AI-enabled pediatric home healthcare solutions, including remote patient monitoring (RPM), predictive analytics, telehealth platforms, medication adherence tools, and AI-assisted care coordination. The study benchmarked technology adoption across leading pediatric home healthcare providers.
Enables stakeholders to identify emerging digital care technologies, evaluate AI-driven patient management solutions, optimize care delivery, and prioritize investments in next-generation pediatric home healthcare services.
Pediatric Patient Journey & Caregiver Experience Analysis
Conducted a comprehensive assessment of the pediatric home healthcare journey, from hospital discharge and referral to home care initiation, ongoing treatment, caregiver engagement, and long-term disease management. The study evaluated caregiver satisfaction, service accessibility, and key decision-making factors.
Provides actionable insights to improve patient and caregiver experience, strengthen care coordination, enhance service quality, and increase patient retention through family-centered care models.
Referral Network & Hospital Partnership Analysis
Assessed referral patterns among children's hospitals, NICUs, pediatricians, specialty clinics, and home healthcare providers, including discharge planning practices and partnership models.
Enables providers to strengthen referral networks, improve patient acquisition strategies, and enhance continuity of care through strategic healthcare partnerships..
Frequently Asked Questions About This Report
North America dominated the pediatric home healthcare market with the largest revenue share of 35.6% in 2025.
Some key players operating in the pediatric home healthcare market include Pediatric Home Healthcare, LLC; Aveanna Healthcare, LLC.; BAYADA Home Health Care; Tendercare Home Health; BrightStar Care; Angels of Care Pediatric Home Health; New England Home Health Services; EnViva Paediatric Care; Interim HealthCare Inc.; and eKidzCare.
Key factors that are driving the pediatric home healthcare market growth include the availability of advanced technologies for providing continuous care and medical assistance at home to Children with Medical Complexities (CMC).
Asia Pacific is the fastest-growing region over the forecast period.
The global pediatric home healthcare market size was estimated at USD 44.5 billion in 2025 and is projected to reach USD 48.0 billion in 2026.
The global pediatric home healthcare market is expected to grow at a compound annual growth rate of 8.1% from 2026 to 2033 to reach USD 82.7 billion by 2033.
The rehabilitation therapy services segment dominated the market with the largest revenue share of 60.7% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


