
- Home
- »
- Pharmaceuticals
- »
-
Peptide Drug Conjugates Market Size Report, 2026-2033GVR Report cover

Peptide Drug Conjugates Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (OctreoScan, Lutathera, Pluvicto, Illuccix), By Type (Diagnostic, Therapeutic), By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$5.3BMarket Estimate, 2026
$6.6BMarket Forecast, 2033
$14.5BCAGR, 2026–2033
11.8%Peptide Drug Conjugates Market Summary
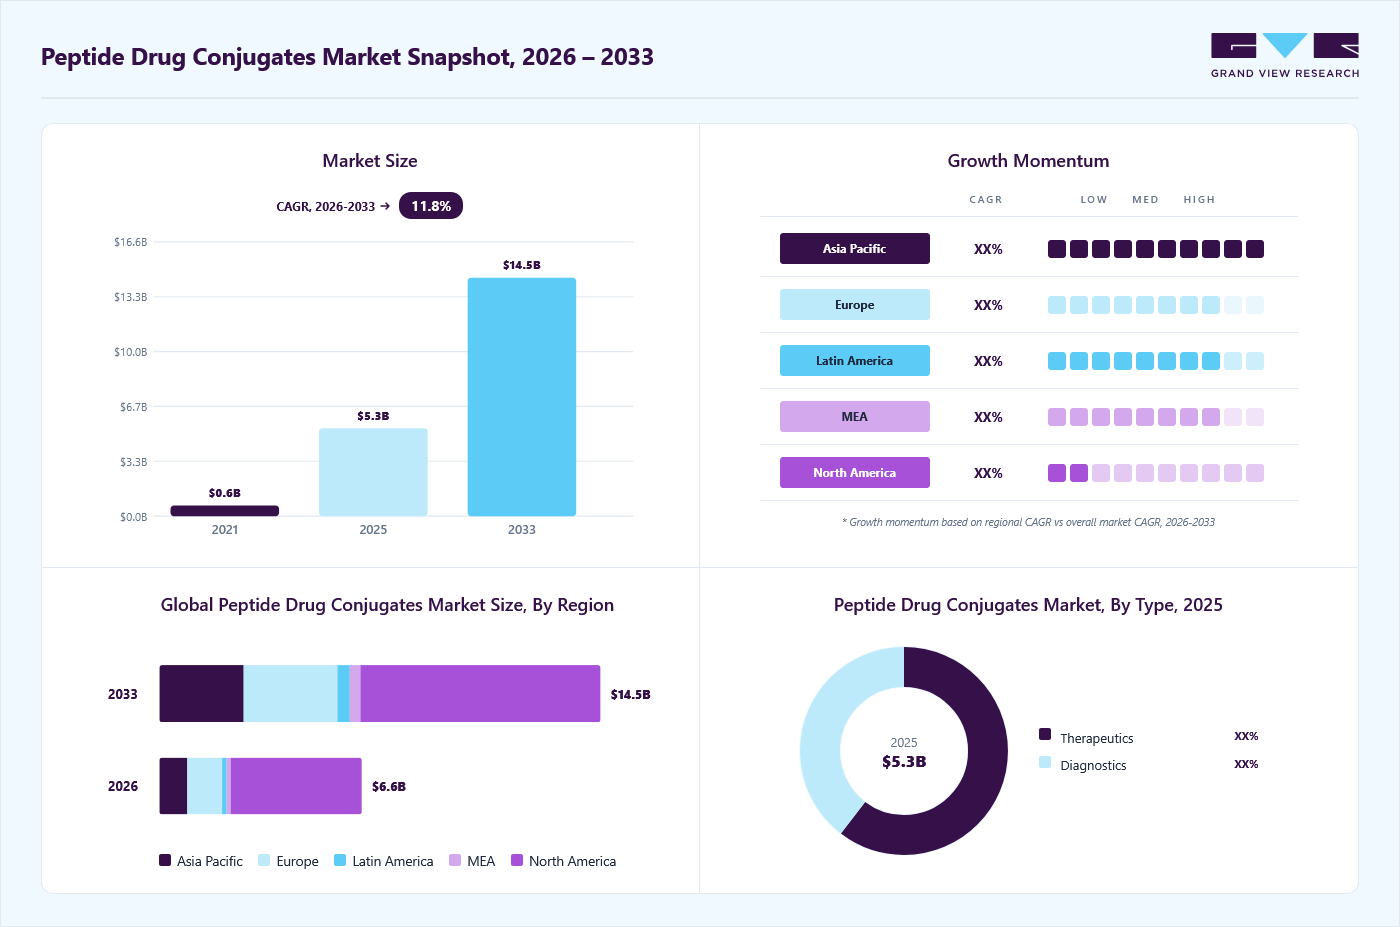
The global peptide drug conjugates market size was valued at USD 5.3 billion in 2025 and is projected to grow from USD 6.6 billion in 2026 to USD 14.5 billion by 2033, at a CAGR of 11.8% from 2026 to 2033. North America dominated the market with the largest revenue share of 66.5% in 2025. The industry is driven by increasing cancer prevalence, growing demand for targeted therapies, and advancements in peptide synthesis technologies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Pluvicto segment led the market with the largest revenue share of 41.6% in 2025.
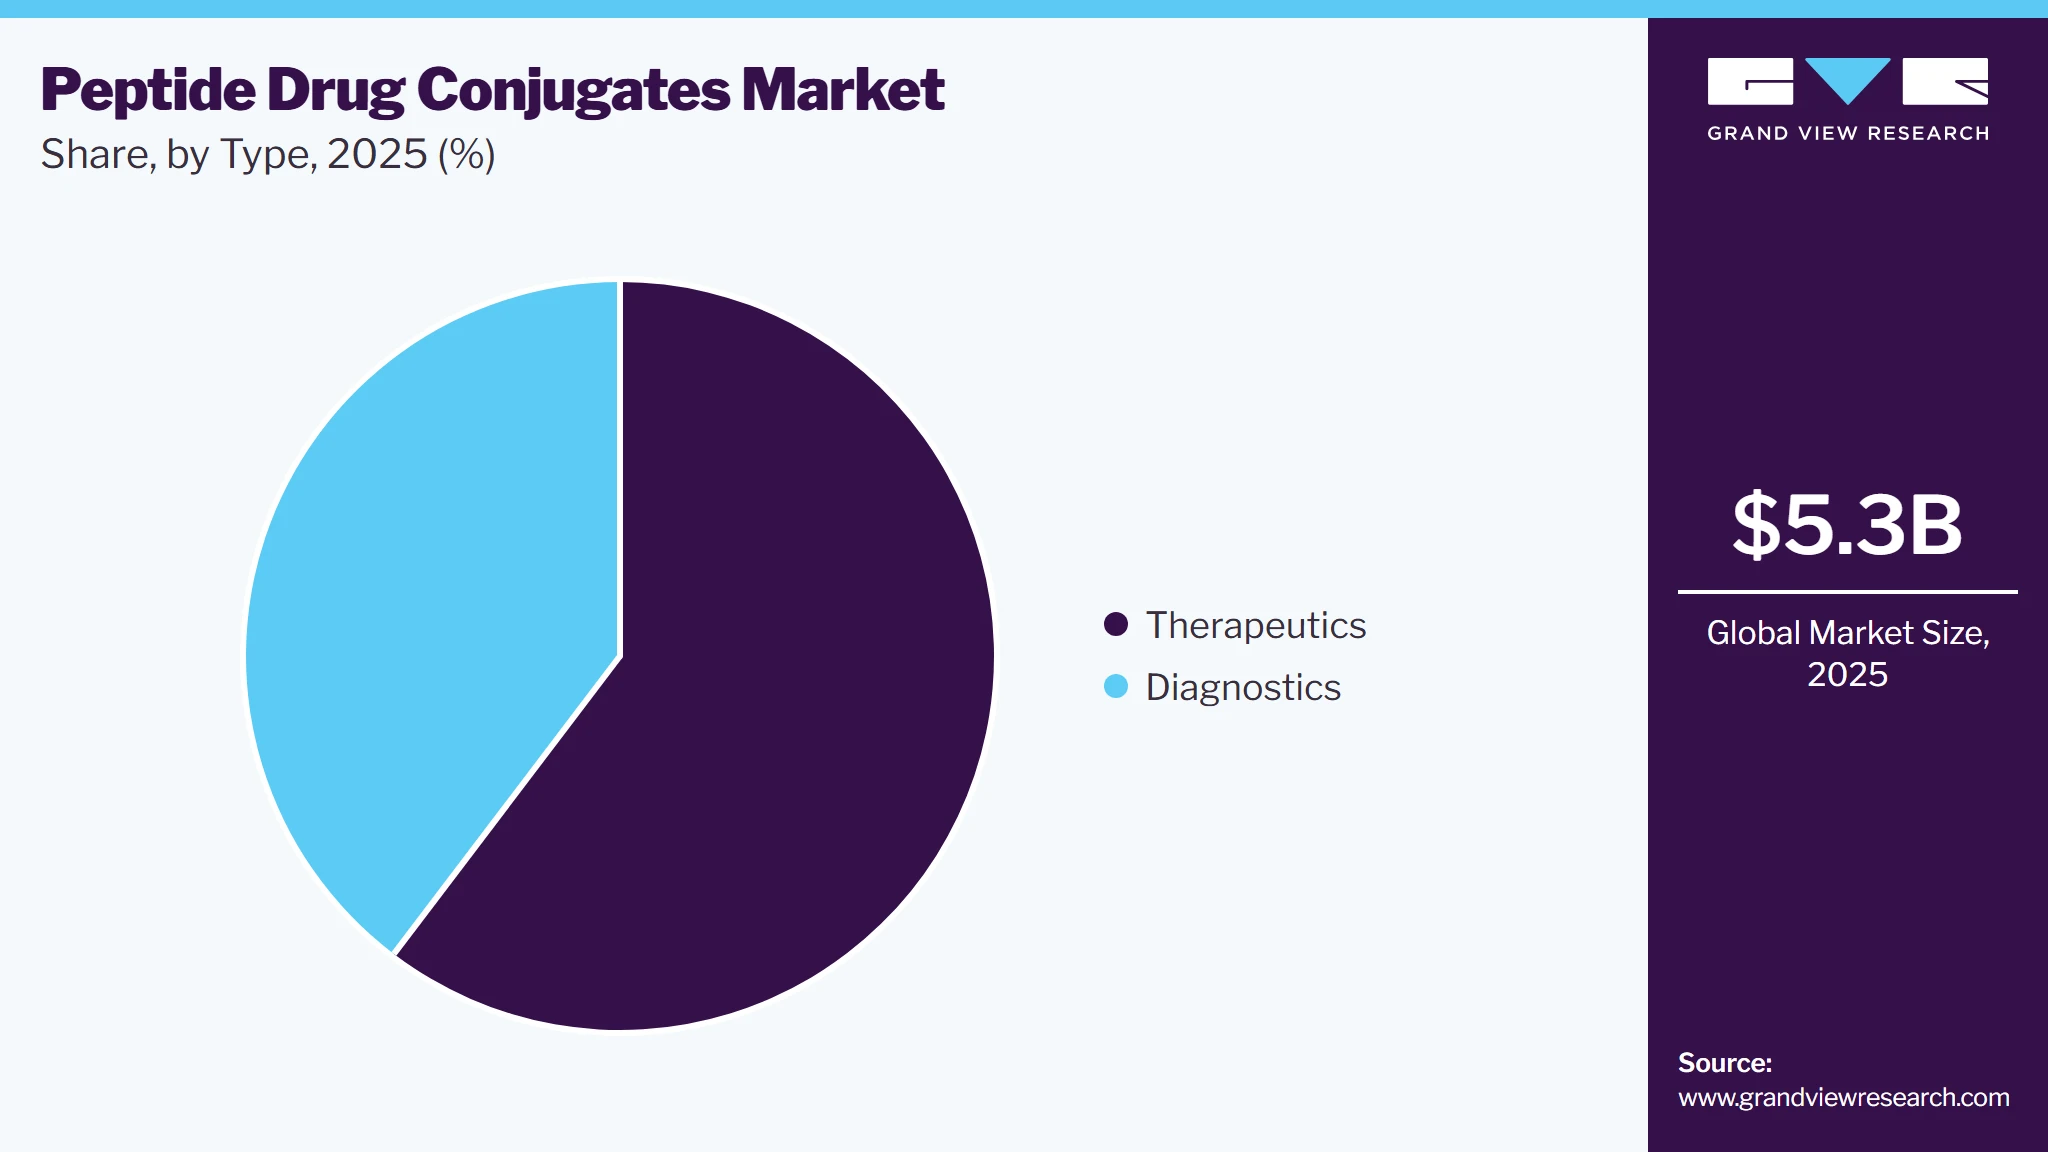
- By type: Therapeutics segment led the market with the largest revenue share of 60.3% in 2025.
Regional Highlights
- Largest regional market: North America (66.5% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 5.3 Billion
- Estimated market size in 2026: USD 6.6 Billion
- Projected market size by 2033: USD 14.5 Billion
- CAGR (2026-2033): 11.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
PDCs offer enhanced drug delivery, improved specificity, and reduced toxicity, making them attractive for oncology and chronic disease treatments. Rising investments in research and development, coupled with regulatory support and strategic collaborations, further propel industry growth. Additionally, expanding applications beyond oncology into infectious and metabolic diseases contributes to sustained demand.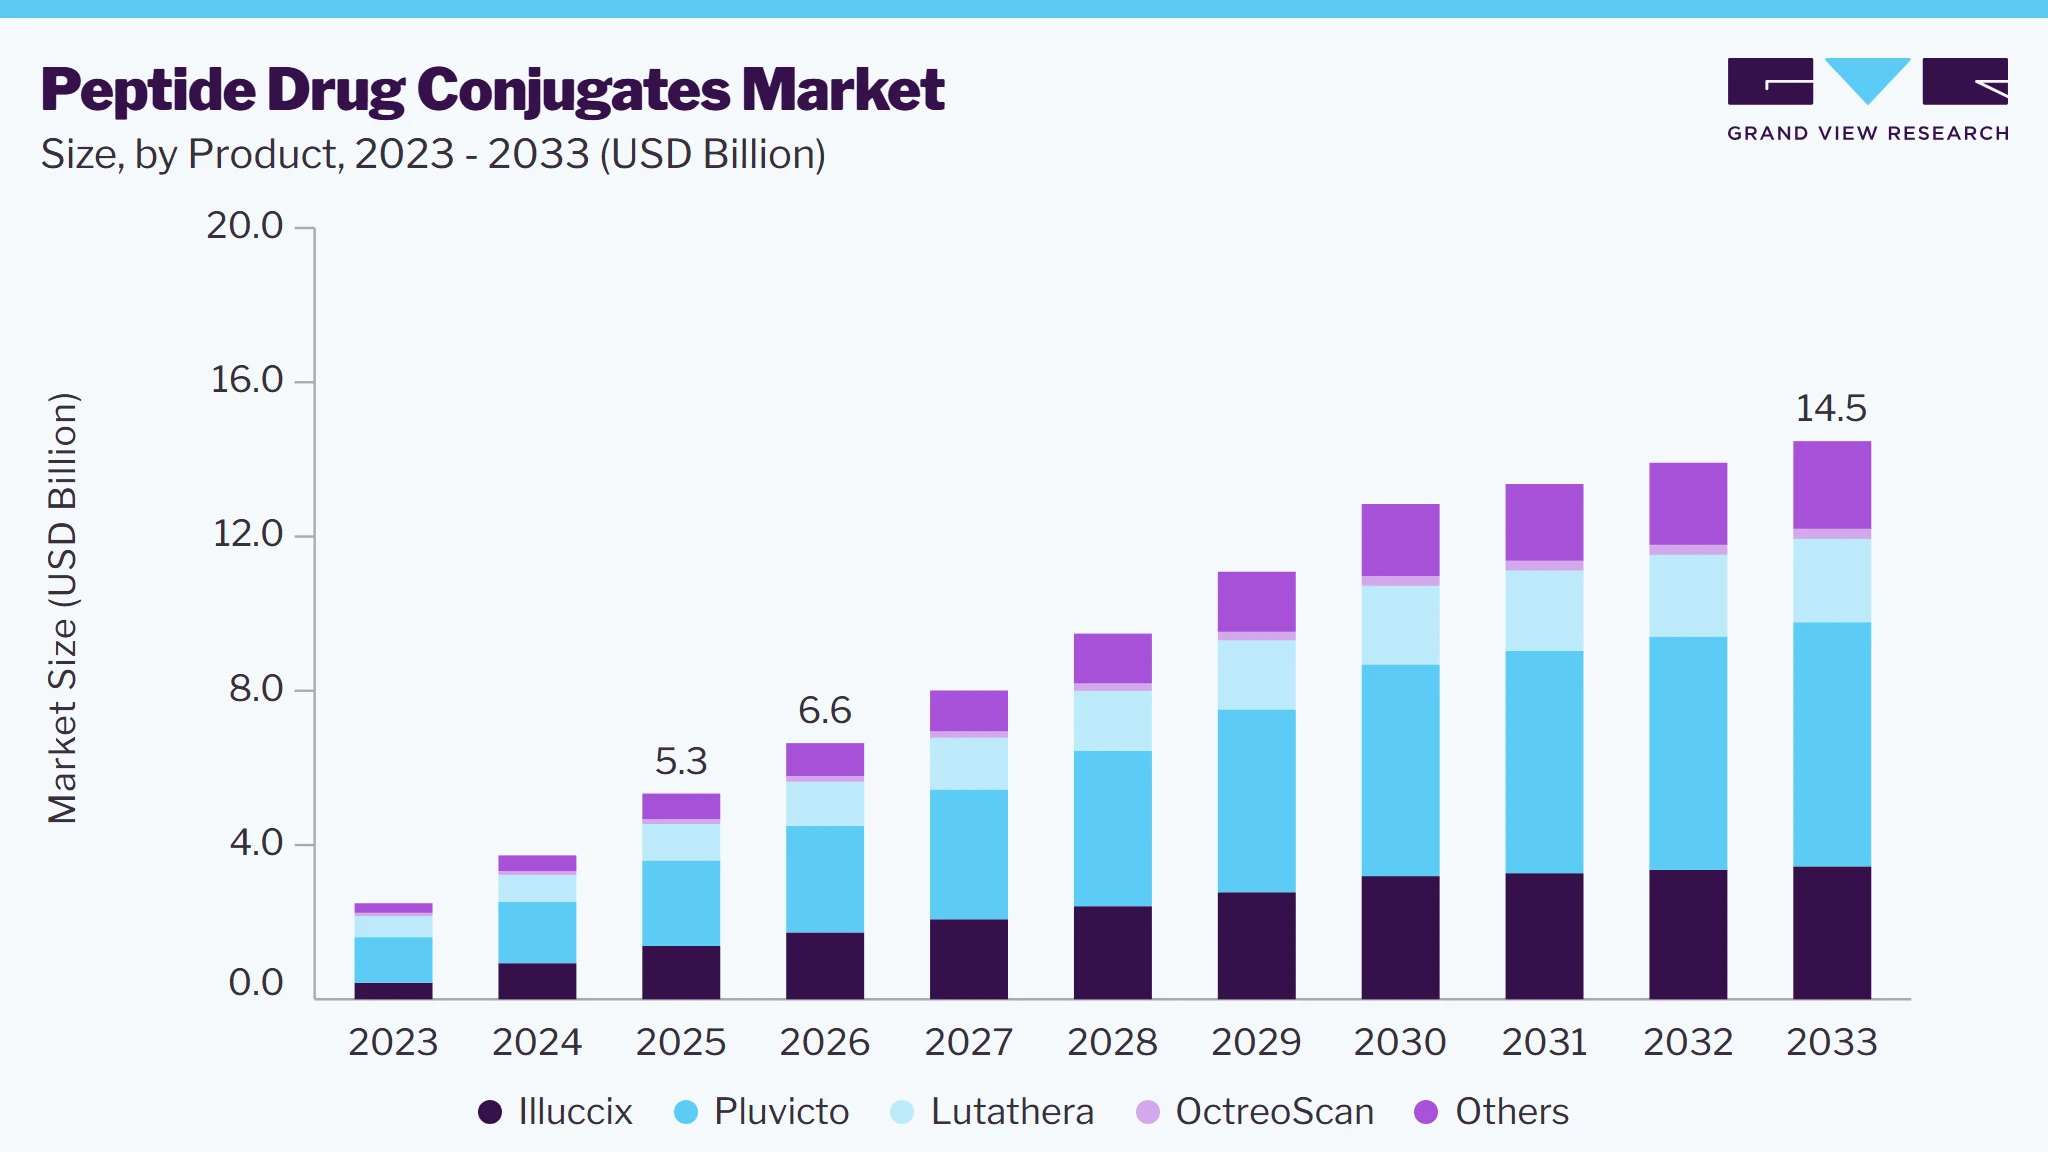 To learn more about this report, Download Free Sample Report
Chronic diseases such as cancer, diabetes, and autoimmune disorders present significant treatment challenges due to their complex nature and difficulty in targeting specific cells or tissues. Peptide drug conjugates (PDCs) offer a more precise approach, enhancing drug delivery while minimizing side effects. The rising prevalence of chronic diseases is driving the demand for PDCs. According to the WHO, chronic diseases account for 71% of global deaths, with cardiovascular diseases alone causing 17.9 million deaths annually. Similarly, the American Hospital Association reports that nearly 133 million Americans-almost 50% of the population-have at least one chronic illness, a number expected to reach 170 million by 2030.
Market Dynamics
The peptide drug conjugates market is experiencing steady growth driven by increasing demand for targeted therapeutics and the expanding application of peptide-based delivery systems in oncology and other chronic disease treatments. Peptide drug conjugates combine the targeting capability of peptides with the therapeutic activity of drug payloads, enabling improved efficacy and reduced systemic toxicity. Rising investments in precision medicine and advancements in peptide engineering are supporting product development and clinical adoption. For instance, in 2025, several biotechnology and pharmaceutical companies continued to advance peptide conjugate candidates through clinical trials, reflecting growing industry confidence in targeted drug delivery technologies. Increasing prevalence of cancer and metabolic disorders is further strengthening demand for innovative treatment options. At the same time, complex manufacturing processes, regulatory requirements, and high development costs remain key challenges for market participants. Continued collaboration between biotechnology firms and pharmaceutical companies is expected to support commercialization efforts and broaden the therapeutic scope of peptide drug conjugates across global healthcare markets.
The peptide drug conjugates market is experiencing growth due to increasing clinical development activities focused on targeted oncology therapies. Peptide drug conjugates provide a combination of selective tumor targeting and therapeutic efficacy, enabling drug delivery directly to cancer cells while reducing systemic toxicity. The growing preference for precision medicine and personalized treatment approaches has encouraged pharmaceutical and biotechnology companies to invest in peptide based drug delivery platforms. Advancements in peptide engineering, linker technologies, and payload optimization have improved the stability and effectiveness of these therapies, supporting their progression through clinical development. Increasing prevalence of cancer worldwide and the need for therapies with improved safety profiles are further driving interest in peptide drug conjugates. As clinical evidence continues to demonstrate favorable outcomes, companies are expanding their research programs and accelerating pipeline development to address unmet needs across multiple oncology indications. These factors are contributing to stronger market adoption and increasing investment in peptide drug conjugate technologies. For instance, in September 2024, Cybrexa Therapeutics announced positive final Phase 1 results for its peptide drug conjugate CBX 12. The study reported a 40% response rate among 10 TOP1 naïve ovarian cancer patients and a 43% response rate among 7 TOP1 naïve hormone receptor positive HER2 negative breast cancer patients. The company also reported activity across six tumor types and initiated a Phase 2 study in platinum resistant ovarian cancer during the third quarter of 2024, demonstrating growing clinical validation of peptide drug conjugate technologies.
Complex manufacturing and purification requirements continue to restrain the growth of the peptide drug conjugates market. Production of peptide drug conjugates involves sophisticated peptide synthesis, conjugation chemistry, purification processes, and rigorous quality control measures to achieve the purity and consistency required for clinical and commercial applications. Scaling up production while maintaining product quality remains challenging due to the complexity of peptide molecules and the sensitivity of conjugation processes. These factors contribute to higher manufacturing costs, extended development timelines, and increased dependence on specialized facilities and technical expertise. In addition, regulatory requirements related to product characterization and process validation further increase operational burdens for manufacturers. Limited large scale manufacturing capacity can also create supply constraints that affect commercialization plans. As a result, many companies face difficulties in efficiently transitioning from clinical development to commercial production. For instance, in October 2025, SK pharmteco announced a USD 6.1 million investment in its Rancho Cordova, California facility to expand solid phase peptide synthesis and purification capabilities. The company stated that efficiently converting complex peptide molecules into high purity large volume batches remained a major industry challenge and that purification bottlenecks frequently resulted in supply delays, highlighting the manufacturing complexities that continue to affect the peptide therapeutics sector.
The expansion of global peptide manufacturing infrastructure is creating significant opportunities for the peptide drug conjugates market. Growing demand for peptide-based therapeutics across oncology and other disease areas is encouraging contract development and manufacturing organizations as well as pharmaceutical companies to increase production capacity and invest in advanced manufacturing technologies. Expanded infrastructure can help address existing supply constraints, improve scalability, and support the increasing number of peptide drug conjugates progressing through clinical and commercial stages. Enhanced manufacturing capabilities also provide biotechnology companies with access to specialized peptide synthesis and purification services, reducing barriers to market entry and accelerating development timelines. As peptide-based therapies become more widely adopted, increased manufacturing capacity is expected to strengthen supply chain reliability and support broader commercialization efforts. For instance, in March 2026, Neuland Laboratories announced that its commercial peptide manufacturing facility in Hyderabad would become operational in summer 2026. The first manufacturing module secured approximately USD 30 million in customer commitments and was designed to add 6,370 liters of solid phase and liquid phase peptide synthesis capacity. The facility was planned as the first of four manufacturing modules and was intended to support production from clinical scale development to multi ton commercial manufacturing, reflecting growing investment in infrastructure that can support future peptide drug conjugate commercialization.
Analyst Perspective
The peptide drug conjugates market is gaining momentum as targeted drug delivery becomes increasingly important in oncology and other complex disease areas. Peptide drug conjugates offer advantages such as improved tissue selectivity, enhanced tumor penetration, and reduced systemic toxicity compared with conventional therapies. Growing investments in precision medicine, peptide engineering, and novel payload technologies are supporting pipeline expansion and clinical development activity. The market is also benefiting from increasing interest in radioligand therapies and receptor targeted therapeutics. However, manufacturing complexity and regulatory requirements remain key challenges. Continued innovation, strategic partnerships, and expanding clinical evidence are expected to support long term market growth.
Table 1 U.S. estimated new cancer cases by cancer type in 2025
Cancer Type
Estimated New Cases (2025)
Breast
319,750
Prostate
313,780
Lung and Bronchus
226,650
Colorectal
154,270
Melanoma of the Skin
112,690
Colon
107,320
Lymphoma
89,070
Urinary Bladder
84,870
Kidney and Renal Pelvis
80,980
Uterine corpus
69,120
Pancrease
67,440
Leukemia
66,890
Oral Cavity & pharynx
59,660
Thyroid
44,020
Liver
42,240
Myeloma
36,110
Stomach
30,300
Pipeline Analysis
The industry is witnessing significant growth, driven by an expanding clinical trial pipeline focused on advancing targeted therapies for cancer, autoimmune disorders, and metabolic diseases. As pharmaceutical companies and biotech firms invest heavily in clinical research, the growing number of PDC candidates in various stages of clinical trials is accelerating innovation and commercialization. In April 2024, Novartis AG invested another USD 180 million into its radioligand therapy program, expanding its Peptide-Drug Conjugate (PDC) collaboration with PeptiDream. This investment highlights the increasing focus on targeted peptide-based therapies in oncology and beyond. Novartis' significant funding will fast-track ongoing Phase II and Phase III trials, particularly in oncology, where radioligand therapy and PDCs are proving to be highly effective for targeted tumor destruction. With increasing success in prostate cancer and neuroendocrine tumors, this investment will help expand clinical applications to other hard-to-treat malignancies, improving patient access to innovative treatments.
Table 2 Peptide Drug Conjugates Pipeline Overview
Candidate
Phases
Company
Illuccix
PHASE3
Angiochem Inc.
BT5528-100
PHASE2
Bicycle Therapeutics
Zelenectide pevedotin (Zele, formerly BT8009)
PHASE2/3
Others
PHASE2
OPD5
EARLY PHASE 1
Oncopeptides AB
OPDC3
EARLY PHASE 1
Gliopep
EARLY PHASE 1
CBX-12
PHASE2
Cybrexa
CBX-13
EARLY PHASE 1
CBX-15
EARLY PHASE 1
Sudocetaxel zendusortide (TH1902)
PHASE1
Theratechnologies Inc.
One of the primary drivers behind the robust PDC clinical pipeline is the rising demand for precision medicine in oncology. With cancer accounting for nearly 9.7 million deaths in 2022, according to WHO, pharmaceutical companies are increasingly focusing on peptide-based therapies that offer high specificity and reduced toxicity compared to traditional chemotherapy. Leading biotech firms are actively developing novel PDCs targeting hematologic malignancies, solid tumors, and hard-to-treat cancers, such as triple-negative breast cancer and glioblastoma.
In addition to oncology, clinical trials are expanding into autoimmune diseases and metabolic disorders, leveraging peptides' high target selectivity and biocompatibility. Several promising candidates are in Phase II and III trials, demonstrating strong efficacy and safety profiles. The increasing number of regulatory approvals for Investigational New Drug (IND) applications highlights growing confidence in PDCs as next-generation therapeutics.
Product Insights
Based on product, the pluvicto segment led the market with the largest revenue share of 41.6% in 2025. The success of Pluvicto (lutetium-177 vipivotide tetraxetan), a PSMA-targeted radioligand therapy developed by Novartis, is a significant driver influencing the peptide drug conjugates (PDC) market. While Pluvicto itself is not a PDC, its mechanism of selectively targeting PSMA-expressing prostate cancer cells aligns with the growing demand for precision oncology treatments, including peptide-based drug delivery systems. The increasing adoption of targeted therapies like Pluvicto underscores the demand for highly specific, biomarker-driven treatments, paving the way for PDCs that conjugate cytotoxic drugs to PSMA-targeting peptides.
Illuccix is projected to grow at a significant CAGR over the forecast period. Illuccix, a diagnostic radiopharmaceutical developed by Telix Pharmaceuticals, has significantly impacted the Peptide Drug Conjugates Market, particularly in prostate cancer imaging. As a ^68Ga-labeled PSMA-11 injection, Illuccix is used in positron emission tomography (PET) scans to detect prostate-specific membrane antigen (PSMA)-expressing prostate cancer lesions. Its introduction has been instrumental in advancing prostate cancer diagnostics, thereby influencing the PDCs market dynamics. In February 2025, Telix Pharmaceuticals Limited announced that the UK Medicines and Healthcare Products Regulatory Agency (MHRA) has approved the Marketing Authorization Application (MAA) for Illuccix (gallium-68 gozetotide injection). Illuccix is a PET imaging agent used for detecting and localizing PSMA-positive lesions in prostate cancer patients. This approval enables wider clinical adoption in the UK, improving prostate cancer diagnosis and treatment planning. This approval indirectly impacts the PDC market by strengthening PSMA-targeted diagnostics. As precision oncology advances, accurate biomarker-based imaging like Illuccix helps in selecting patients for PSMA-targeted therapies, including potential peptide-based drug conjugates. The expansion of PSMA-targeting strategies in oncology supports the broader adoption of peptide-based therapeutics, driving research and investment in the PDC market.
Type Insights
Based on type, the therapeutics segment led the market with the largest revenue share of 60.3% in 2025. The therapeutics segment is expected to experience significant growth due to the presence of approved PDCs, such as Lutathera and Pluvicto. Numerous clinical trials are evaluating PDCs like Illuccix, BT5528, and Others, which function as targeted therapies against tumor cells. Beyond oncology, pharmaceutical companies are developing PDCs for metabolic disorders and other conditions, further driving market expansion.
 To learn more about this report, Download Free Sample Report
Diagnostics hold a significant share in the market, driven by their expanding role in cancer detection and monitoring. PDCs, particularly those conjugated with radionuclides, are increasingly utilized for precise tumor localization through imaging techniques like PET and SPECT. Radiolabeled PDCs, targeting tumor-specific receptors, enable early diagnosis, thereby improving treatment outcomes. FDA-approved diagnostic PDCs, such as Detectnet (64Cu oxodotreotide), Illuccix (68Ga PSMA-11), and Netspot (68Ga oxodotreotide), exemplify the growing adoption of these technologies. This trend, coupled with advancements in radioligand therapy, underscores the diagnostics segment’s contribution to market growth.
Regional Insights
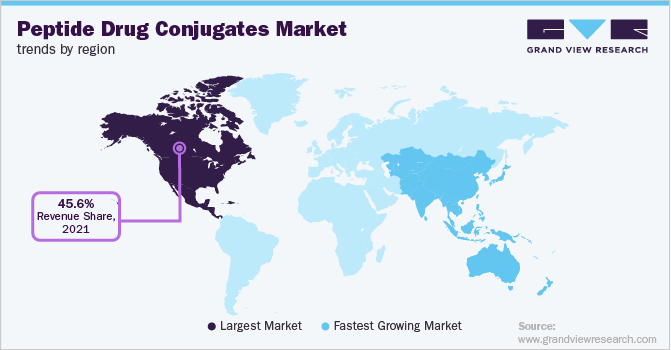
North America dominated the peptide drug conjugates market with the largest revenue share of 66.5% in 2025. The growth is driven by a high prevalence of cancer and chronic diseases, increased adoption of targeted therapies, and advancements in peptide synthesis technologies. The region benefits from significant biopharmaceutical investments, early regulatory approvals, and the growing use of RNAi-based therapeutics. Hospital pharmacies dominate distribution, while retail and online pharmacies are witnessing increasing demand for chronic disease treatments.
 To learn more about this report, Download Free Sample Report
U.S. Peptide Drug Conjugates Market Trends
The peptide drug conjugates market in the U.S. held the largest share in the North America region in 2025. The rising utilization of PDCs in oncology and metabolic disorders is accelerating market growth. Innovations in peptide-linker technologies and expanding clinical trials are enhancing drug efficacy and safety profiles. Hospital pharmacies remain the primary distribution channel, with retail pharmacies gaining traction.
Europe Peptide Drug Conjugates Market Trends
The peptide drug conjugates market in Europe is experiencing steady growth, with Germany, France, and the UK leading the region. Strong clinical research infrastructure and government support for biotechnology innovation are key growth drivers. Increased adoption of PDCs targeting cancer and autoimmune diseases is observed, along with rising applications in metabolic disorders. Hospital pharmacies hold the largest distribution share, with online pharmacy penetration improving patient access.
The UK peptide drug conjugates market is driven by increasing biopharmaceutical R&D funding and a focus on personalized medicine. Clinical trials targeting oncology and chronic diseases are expanding, with hospital pharmacies dominating distribution channels. Retail pharmacies are gradually strengthening their role in chronic disease management.
The peptide drug conjugates market in Germany is backed by advanced manufacturing capabilities and robust biotech investments. Demand for targeted therapies in oncology and metabolic disorders is increasing. Hospital pharmacies maintain a significant market share, with a growing online pharmacy presence enhancing treatment accessibility.
France peptide drug conjugates market is supported by the adoption of PDCs for autoimmune and inflammatory diseases. Regulatory advancements and public healthcare initiatives are driving market expansion, with hospital pharmacies leading the distribution segment.
Asia-Pacific Peptide Drug Conjugates Market Trends
The peptide drug conjugates market in Asia-Pacific is experiencing rapid growth due to the rising prevalence of cancer, expanding healthcare access, and increasing local manufacturing. China, Japan, and India are leading markets, supported by government initiatives and growing clinical trial activity. Innovations in peptide-linker technology are improving market penetration.
Japan peptide drug conjugates market is expanding through government-funded research in peptide-based therapies and a growing focus on age-related chronic diseases. Hospital pharmacies dominate distribution channels, with retail pharmacies enhancing access to targeted treatments.
The peptide drug conjugates market in China is growing rapidly, driven by significant R&D investments, biopharma manufacturing expansion, and healthcare reform initiatives. Demand for PDCs in oncology and metabolic disorder treatments is rising, with online pharmacies facilitating broader patient access.
Latin America Peptide Drug Conjugates Market Trends
The peptide drug conjugates market in Latin America is witnessing growth due to increasing healthcare expenditure and rising awareness of targeted therapies. Brazil leads the region with government healthcare initiatives and investments in local biopharmaceutical production.
Brazil peptide drug conjugates market is driven by high cancer prevalence and efforts to improve healthcare outcomes. Investments in biopharma manufacturing and collaborations with international companies are enhancing the availability of innovative PDCs.
Middle East & Africa Peptide Drug Conjugates Market Trends
The peptide drug conjugates market in the Middle East and Africa is expanding with improvements in healthcare infrastructure and the increasing prevalence of chronic diseases. Government-driven initiatives in countries like Saudi Arabia are boosting demand for targeted therapies.
Saudi Arabia peptide drug conjugates market is underpinned by healthcare modernization efforts and increased biotechnology research funding. Rising cancer incidence and government focus on advanced therapies are driving the adoption of PDCs.
Key Peptide Drug Conjugates Company Insights
Leading players in the peptide drug conjugates market include Bicycle Therapeutics plc, Oncopeptides AB, Theratechnologies Inc., Cybrexa Therapeutics, Angiochem Inc., Novartis AG, and Telix Pharmaceuticals Limited. Market growth is supported by increased demand for targeted therapies, advancements in peptide-linker technology, and growing adoption in oncology and metabolic disorder treatments.
Key Peptide Drug Conjugates Companies:
The following are the leading companies in the peptide drug conjugates market. These companies collectively hold the largest market share and dictate industry trends.
-
Novartis AG
-
AstraZeneca
-
Oncopeptides AB
-
Bicycle Therapeutics
-
Cybrexa
-
Angiochem Inc.
-
Soricimed Biopharma
-
Theratechnologies Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Large Integrated Pharmaceutical Companies (Novartis AG, AstraZeneca)
Expand peptide drug conjugate and peptide radioligand therapy portfolios through clinical development, indication expansion, and global commercialization. Invest in targeted delivery technologies, radiopharmaceutical infrastructure, and combination therapies across oncology indications. Strengthen market position through strategic collaborations, acquisitions, licensing agreements, and integration of peptide conjugates into broader precision oncology strategies.
Strong global commercial networks, extensive regulatory expertise, large scale manufacturing capabilities, and substantial financial resources. Ability to conduct large multicenter clinical trials, support global product launches, and leverage established oncology franchises. Broad research platforms and diversified product portfolios enable sustained investment in next generation peptide conjugate technologies.
High development and manufacturing costs associated with peptide based therapeutics and radiopharmaceutical products. Exposure to complex regulatory requirements, reimbursement challenges, and pricing pressures across global markets. Large organizational structures may reduce flexibility and slow decision making in emerging niche therapeutic areas.
Peptide Drug Conjugate and Radiopharmaceutical Specialists (Oncopeptides AB, Bicycle Therapeutics, Cybrexa, Angiochem Inc., Soricimed Biopharma, Theratechnologies Inc.)
Focus on the discovery, development, and commercialization of peptide targeted therapeutics and peptide drug conjugate platforms. Prioritize innovation in peptide engineering, receptor targeting, blood brain barrier penetration technologies, and novel payload delivery approaches. Pursue strategic partnerships, licensing agreements, and co-development collaborations to advance clinical programs and expand market access.
Deep scientific expertise in peptide biology, targeted drug delivery, and specialized therapeutic platforms. Strong innovation capabilities, focused research strategies, and organizational agility support rapid advancement of novel candidates. Ability to address niche indications and unmet medical needs through differentiated peptide conjugate technologies.
Limited commercial infrastructure and financial resources compared to multinational pharmaceutical companies. Greater dependence on a small number of clinical stage assets increases exposure to development, regulatory, and commercialization risks. Reliance on external manufacturing partners and strategic collaborations may limit scalability and long term market reach.
Recent Developments
-
In January 2025, Oncopeptides AB announced that the positive reimbursement decision for its drug Pepaxti (melflufen) had been officially published in the Italian Official Journal (Gazetta Ufficiale). This marks the final regulatory milestone for Pepaxti’s commercialization in Italy, paving the way for its first sales in H1 2025.
-
In May2024, Oncopeptides AB announced that the first hospital in Spain has begun treating patients with Pepaxti, marking a significant milestone in the drug’s commercial rollout in the country.
-
In April 2024, Novartis AG injected USD 180 million into its radioligand therapy program, expanding its Peptide-Drug Conjugate (PDC) collaboration with PeptiDream. This investment highlights the increasing focus on targeted peptide-based therapies in oncology and beyond.
Peptide Drug Conjugates Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.3 billion
Estimated market size in 2026
USD 6.6 billion
Projected market size by 2033
USD 14.5 billion
Growth rate
CAGR of 11.8% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, product, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
Novartis AG; AstraZeneca; Oncopeptides AB; Bicycle Therapeutics; Cybrexa; Angiochem Inc.; Soricimed Biopharma; Theratechnologies Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Peptide Drug Conjugates Market Report Segmentation
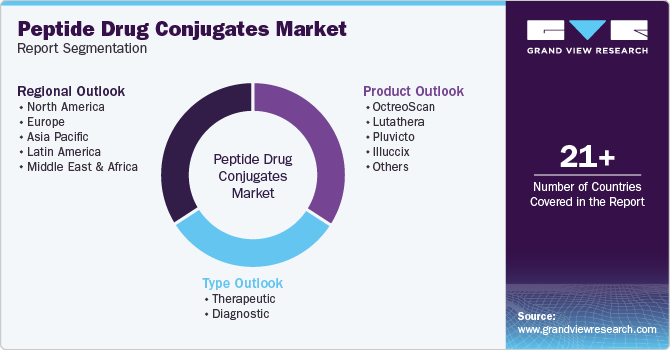
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global peptide drug conjugatesmarket report on the basis of product, type, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
OctreoScan
-
Lutathera
-
Pluvicto
-
Illuccix
-
Others
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Therapeutic
-
Diagnostic
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
Segment Definition
Segment - Product
Revenue capture definition
OctreoScan
Revenue generated from OctreoScan (indium In 111 pentetreotide), a peptide based radiopharmaceutical diagnostic agent used for somatostatin receptor scintigraphy in neuroendocrine tumors and other somatostatin receptor expressing malignancies. This segment includes all sales associated with OctreoScan for approved diagnostic applications. Revenue attributable to OctreoScan is reported exclusively within this segment.
Lutathera
Revenue generated from Lutathera (lutetium Lu 177 dotatate), a peptide receptor radionuclide therapy (PRRT) product used for the treatment of somatostatin receptor positive gastroenteropancreatic neuroendocrine tumors. This segment includes all revenue derived from Lutathera across approved therapeutic indications and future label expansions. Revenue is assigned exclusively to this segment.
Pluvicto
Revenue generated from Pluvicto (lutetium Lu 177 vipivotide tetraxetan), a PSMA targeted peptide radioligand therapy indicated for prostate cancer. This segment includes all sales generated from approved prostate cancer indications and any future approved applications. Revenue attributable to Pluvicto is classified solely within this segment.
Illuccix
Revenue generated from Illuccix (gallium Ga 68 gozetotide), a PSMA targeted peptide based diagnostic radiopharmaceutical used for PET imaging in prostate cancer patients. This segment includes all commercial revenue associated with Illuccix across approved diagnostic applications. Revenue is reported exclusively within this category.
Others
Revenue generated from all peptide drug conjugate and peptide radioligand products not separately identified above. This includes products such as Netspot, SomaKit TOC, Detectnet, Copper Cu 64 Dotatate based products, emerging peptide receptor radionuclide therapies, investigational commercial launches, and future peptide conjugate products introduced during the forecast period. Revenue is allocated to this segment only when it does not belong to the predefined product categories above.
Segment - Type
Revenue capture definition
Therapeutic
Revenue generated from peptide drug conjugates and peptide radioligand therapies intended for disease treatment through targeted delivery of therapeutic payloads, including radioactive isotopes, cytotoxic agents, or other therapeutic compounds. This segment includes products such as Lutathera, Pluvicto, and other approved or commercialized therapeutic peptide conjugates. Revenue is attributed to this segment when the primary clinical purpose of the product is treatment rather than diagnosis.
Diagnostic
Revenue generated from peptide based diagnostic agents used for disease detection, patient selection, staging, monitoring, and treatment planning through molecular imaging techniques such as PET, SPECT, or scintigraphy. This segment includes products such as OctreoScan, Illuccix, and other peptide based diagnostic imaging agents. Revenue is assigned exclusively to this segment when the product's primary intended use is diagnostic imaging rather than therapeutic intervention.
Estimation Model
The market size of the Peptide Drug Conjugates (PDCs) Market was estimated using a combination of secondary research, primary research, and bottom up as well as top down validation approaches. The study began with the identification of commercially available peptide drug conjugates and peptide targeted radioligand therapies, including products such as Lutathera, Pluvicto, OctreoScan, Illuccix, and other emerging peptide conjugate therapies. Secondary research involved the analysis of annual reports, investor presentations, regulatory filings, clinical trial databases, scientific publications, company press releases, healthcare databases, and industry association reports to assess product revenues, pipeline progression, adoption trends, and therapeutic utilization.
A bottom up approach was employed by collecting product specific revenue data, prescription volumes, treatment penetration rates, average selling prices, and regional sales performance across major markets. Revenue contributions were aggregated at the product level and subsequently mapped across therapeutic and diagnostic segments. In parallel, a top down assessment was conducted by evaluating the broader targeted therapeutics, radiopharmaceuticals, and peptide based therapeutics markets, followed by estimation of the proportion attributable to peptide drug conjugates.
Primary interviews with pharmaceutical executives, peptide drug developers, oncologists, nuclear medicine specialists, contract manufacturing organizations, distributors, and industry experts were conducted to validate market assumptions, utilization rates, pricing trends, competitive dynamics, and future growth prospects. Data triangulation and cross verification across multiple sources were performed to ensure accuracy and consistency. The final market estimates were generated by integrating validated revenue data, clinical adoption trends, product pipeline assessments, regulatory developments, and regional demand patterns, with forecasts developed through analysis of expected product launches, indication expansions, technological advancements, and commercialization timelines.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Peptide Drug Conjugates Competitive Landscape & Pipeline Assessment
Conducted a targeted assessment of the global Peptide Drug Conjugates (PDCs) market, evaluating approved products, clinical stage candidates, peptide targeting platforms, payload technologies, linker innovations, and pipeline maturity. The study analyzed key participants including Novartis AG, AstraZeneca, Bicycle Therapeutics, Oncopeptides AB, Cybrexa, AngioChem Inc., SciSonic Biopharma, and Theratechnologies Inc., while assessing emerging therapeutic targets, clinical development trends, and competitive positioning across oncology and other targeted therapy applications.
Helped the client identify high-potential therapeutic targets, evaluate competitive threats, benchmark pipeline differentiation, and prioritize licensing, acquisition, and partnership opportunities within the evolving peptide drug conjugates ecosystem.
Peptide Drug Conjugate Technology Platform Benchmarking Study
Delivered a comprehensive benchmarking analysis of peptide drug conjugate technologies, focusing on peptide targeting mechanisms, linker designs, payload selection strategies, receptor expression approaches, bond breaking/cleaving plans, and clinical performance. The assessment compared commercially advanced and emerging PDC technologies, evaluating scalability, safety profiles, intellectual property positioning, therapeutic efficacy, and platform differentiation across key competitors.
Enabled the client to assess technology competitiveness, identify platform gaps, benchmark innovation strategies, and prioritize investments in next-generation peptide conjugate development programs and proprietary delivery technologies.
Peptide Drug Conjugates Manufacturing & Commercialization Feasibility Assessment
Conducted a strategic assessment of the peptide drug conjugate manufacturing ecosystem, evaluating peptide synthesis capabilities, conjugation technologies, payload integration processes, purification approaches, analytical testing development, and outsourcing opportunities. The study analyzed contract manufacturing options and manufacturing scalability, vendor landscape, and readiness supporting clinical and commercial scale peptide conjugate production.
Supported strategic manufacturing planning by identifying qualified production partners, mitigating supply chain risks, evaluating outsourcing strategies, and strengthening global manufacturing scalability and commercialization readiness across global markets.
Frequently Asked Questions About This Report
The peptide drug conjugates market is driven by increasing cancer prevalence, growing demand for targeted therapies, and advancements in peptide synthesis technologies. PDCs offer enhanced drug delivery, improved specificity, and reduced toxicity, making them attractive for oncology and chronic disease treatments.
Key players operating in the market are Novartis AG; AstraZeneca; Oncopeptides AB; Bicycle Therapeutics; Cybrexa; Angiochem Inc.; Soricimed Biopharma; Theratechnologies Inc.
North America dominated the peptide drug conjugates market with the largest revenue share of 66.5% in 2025.
Pluvicto segment led the market with the largest revenue share of 41.6% in 2025.
Therapeutics segment led the market with the largest revenue share of 60.3% in 2025.
The global peptide drug conjugates market size was estimated at USD 5.3 billion in 2025 and is projected to grow from USD 6.6 billion in 2026.
The global peptide drug conjugates market is expected to grow at a compound annual growth rate of 11.8% from 2026 to 2033 to reach USD 14.5 billion by 2032.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


