
- Home
- »
- Machinery & Equipment
- »
-
Pet Food Packaging Machinery Market Report, 2026-2033GVR Report cover

Pet Food Packaging Machinery Market (2026 - 2033)
Size, Share & Trends Analysis Report By Machine Type (Filling Machines, Sealing Machines), By Packaging Type (Bags, Pouches, Cans, Boxes), By Automation (Fully Automatic, Semi-automatic, Manual), By End User, By Region, And Segment Forecasts
Market Size, 2025
$2.4BMarket Estimate, 2026
$2.5BMarket Forecast, 2033
$3.8BCAGR, 2026–2033
6.0%Pet Food Packaging Machinery Market Summary
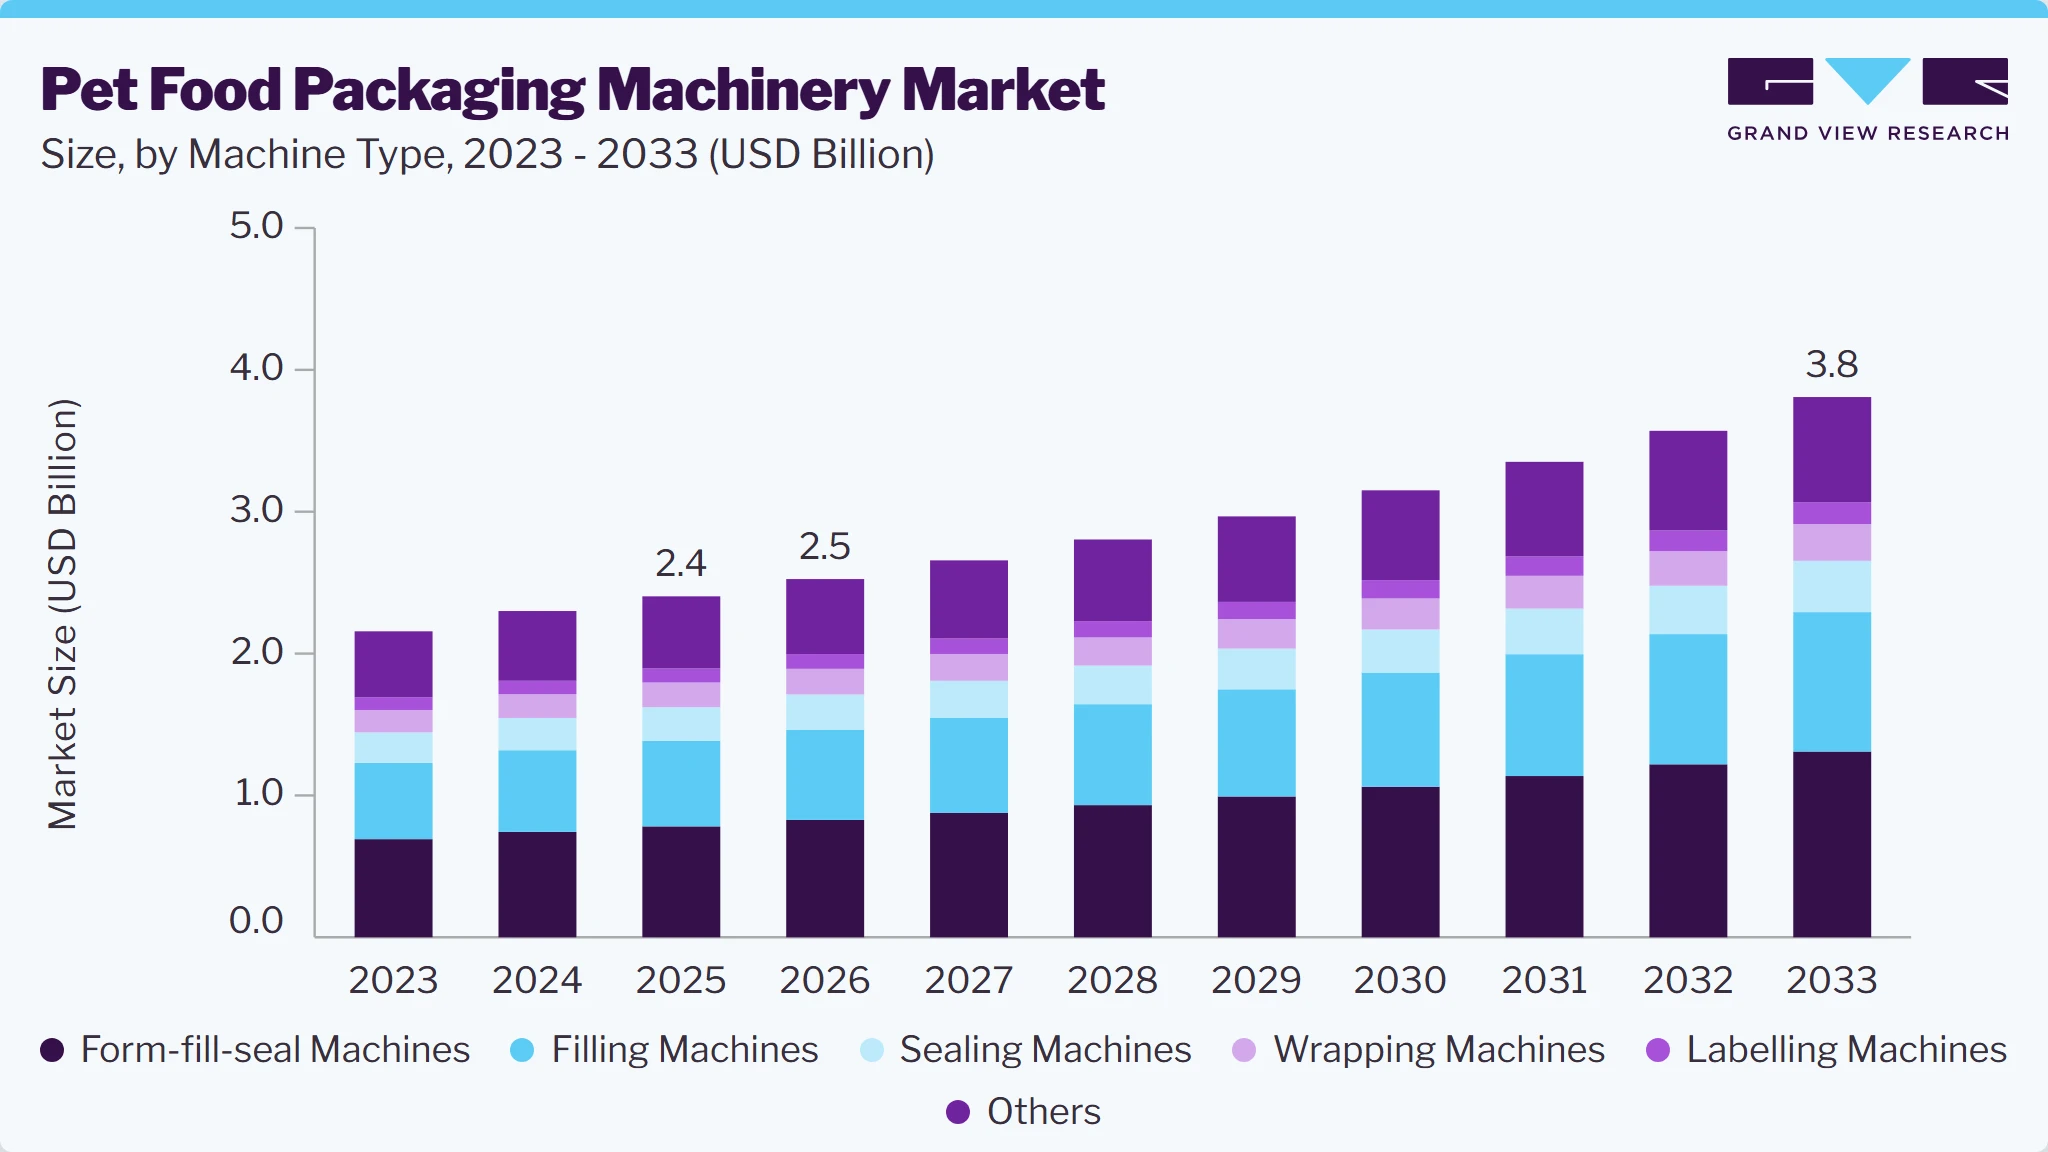
The global pet food packaging machinery market size was valued at USD 2.4 billion in 2025 and is projected to grow from USD 2.5 billion in 2026 to USD 3.8 billion by 2033, at a CAGR of 6.0% from 2026 to 2033. North America held the largest revenue share of 36.8% in 2025. The pet food packaging machinery industry is significantly driven by the sustained growth in global pet ownership and the large-scale expansion of pet food manufacturing capacities.
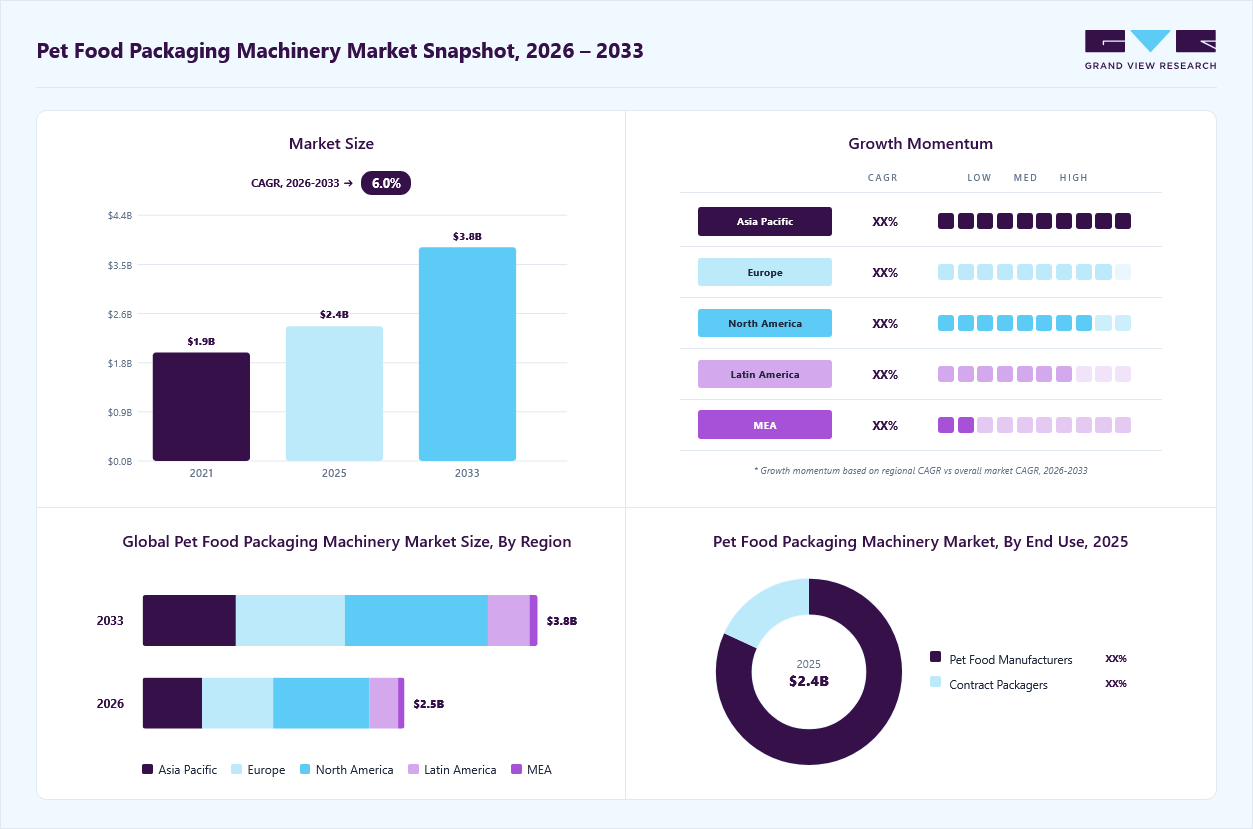 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By machine type: Form-fill-seal machines held the largest revenue share of 32.5% in 2025.
- By packaging type: Bags held the largest revenue share of 36.5% in 2025.
- By automation: Fully automatic accounted for the largest revenue share of 49.0% in 2025.
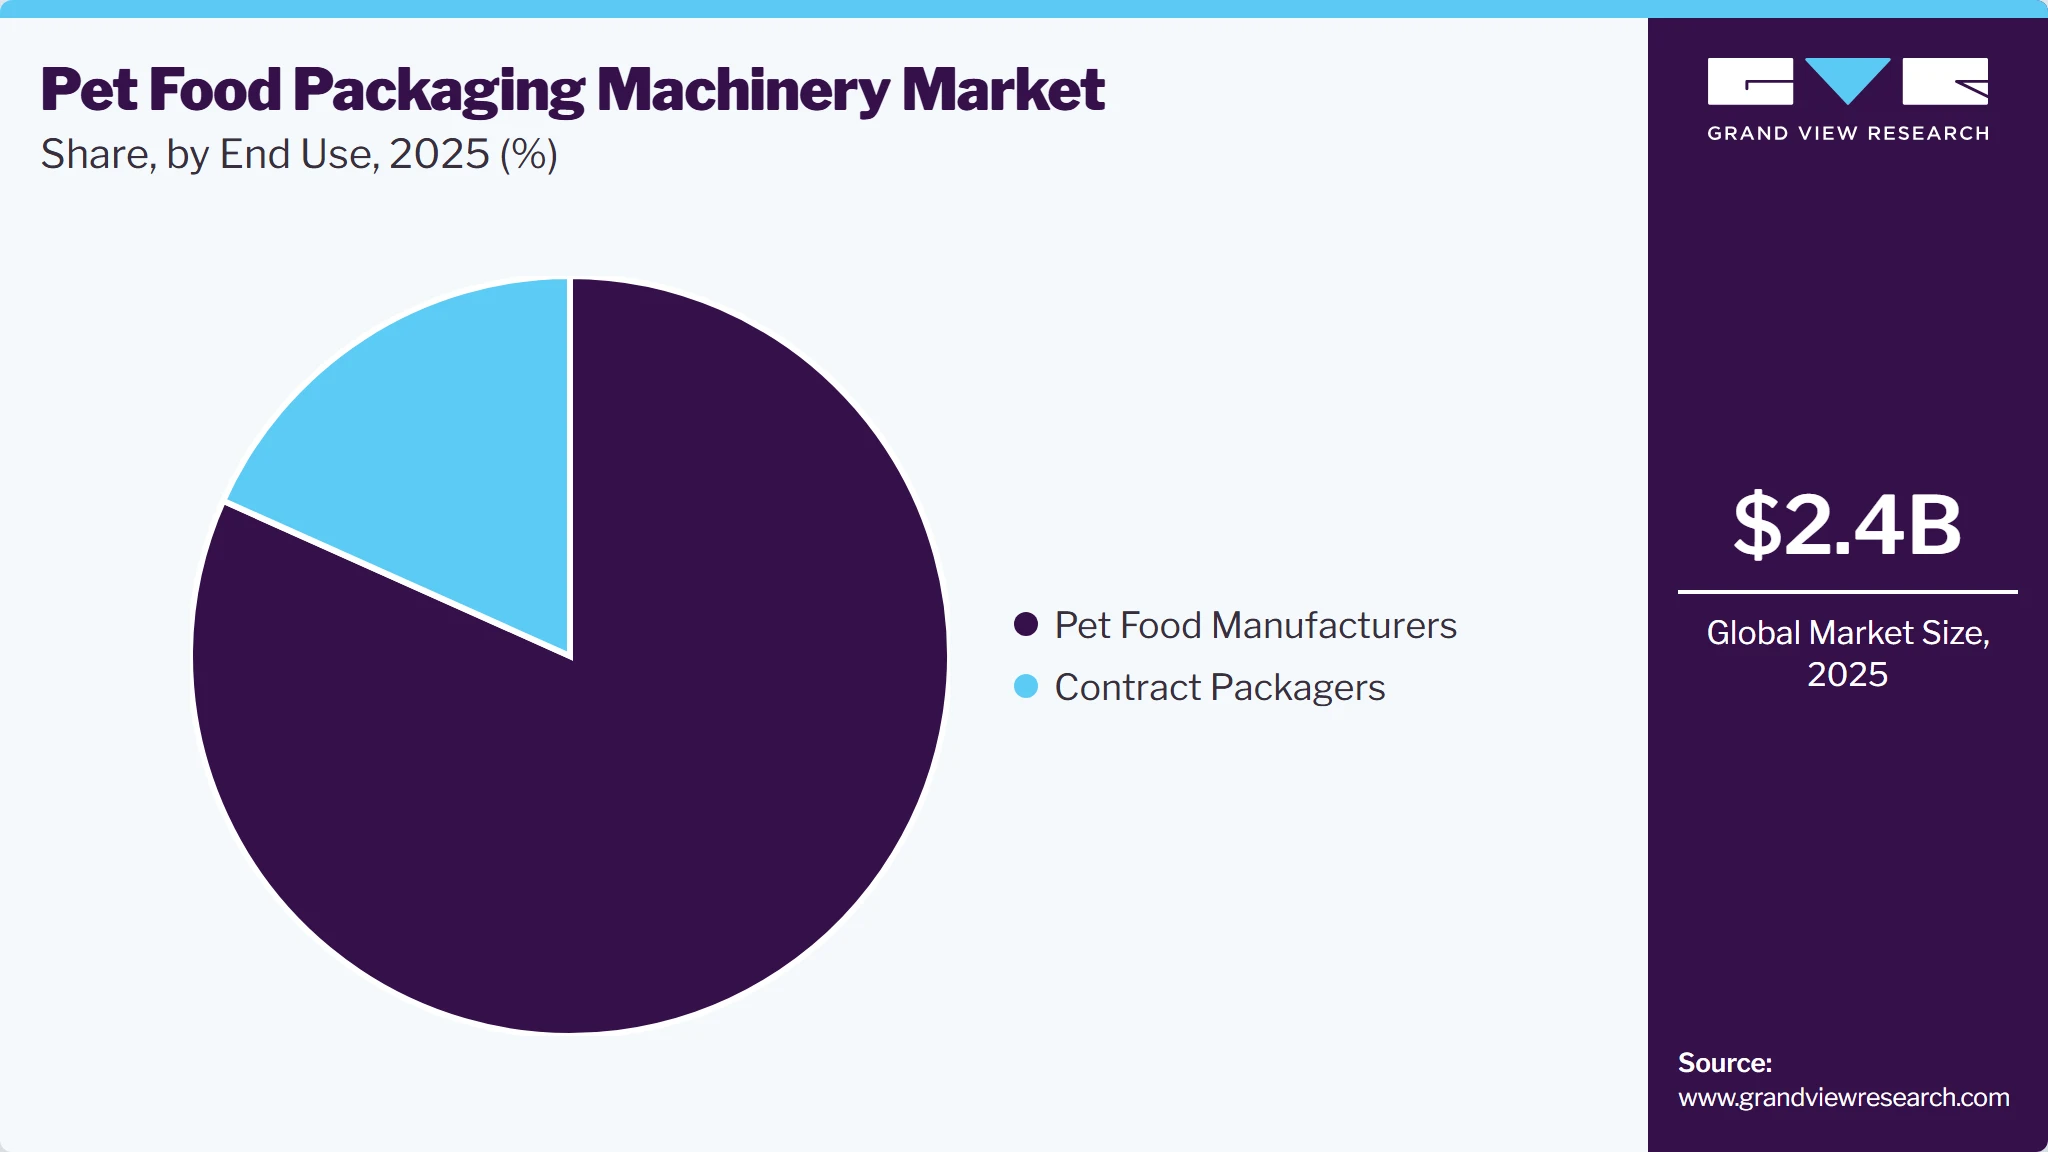
- By end user: Pet food manufacturers held the largest revenue share of 81.7% in 2025.
Regional Highlights
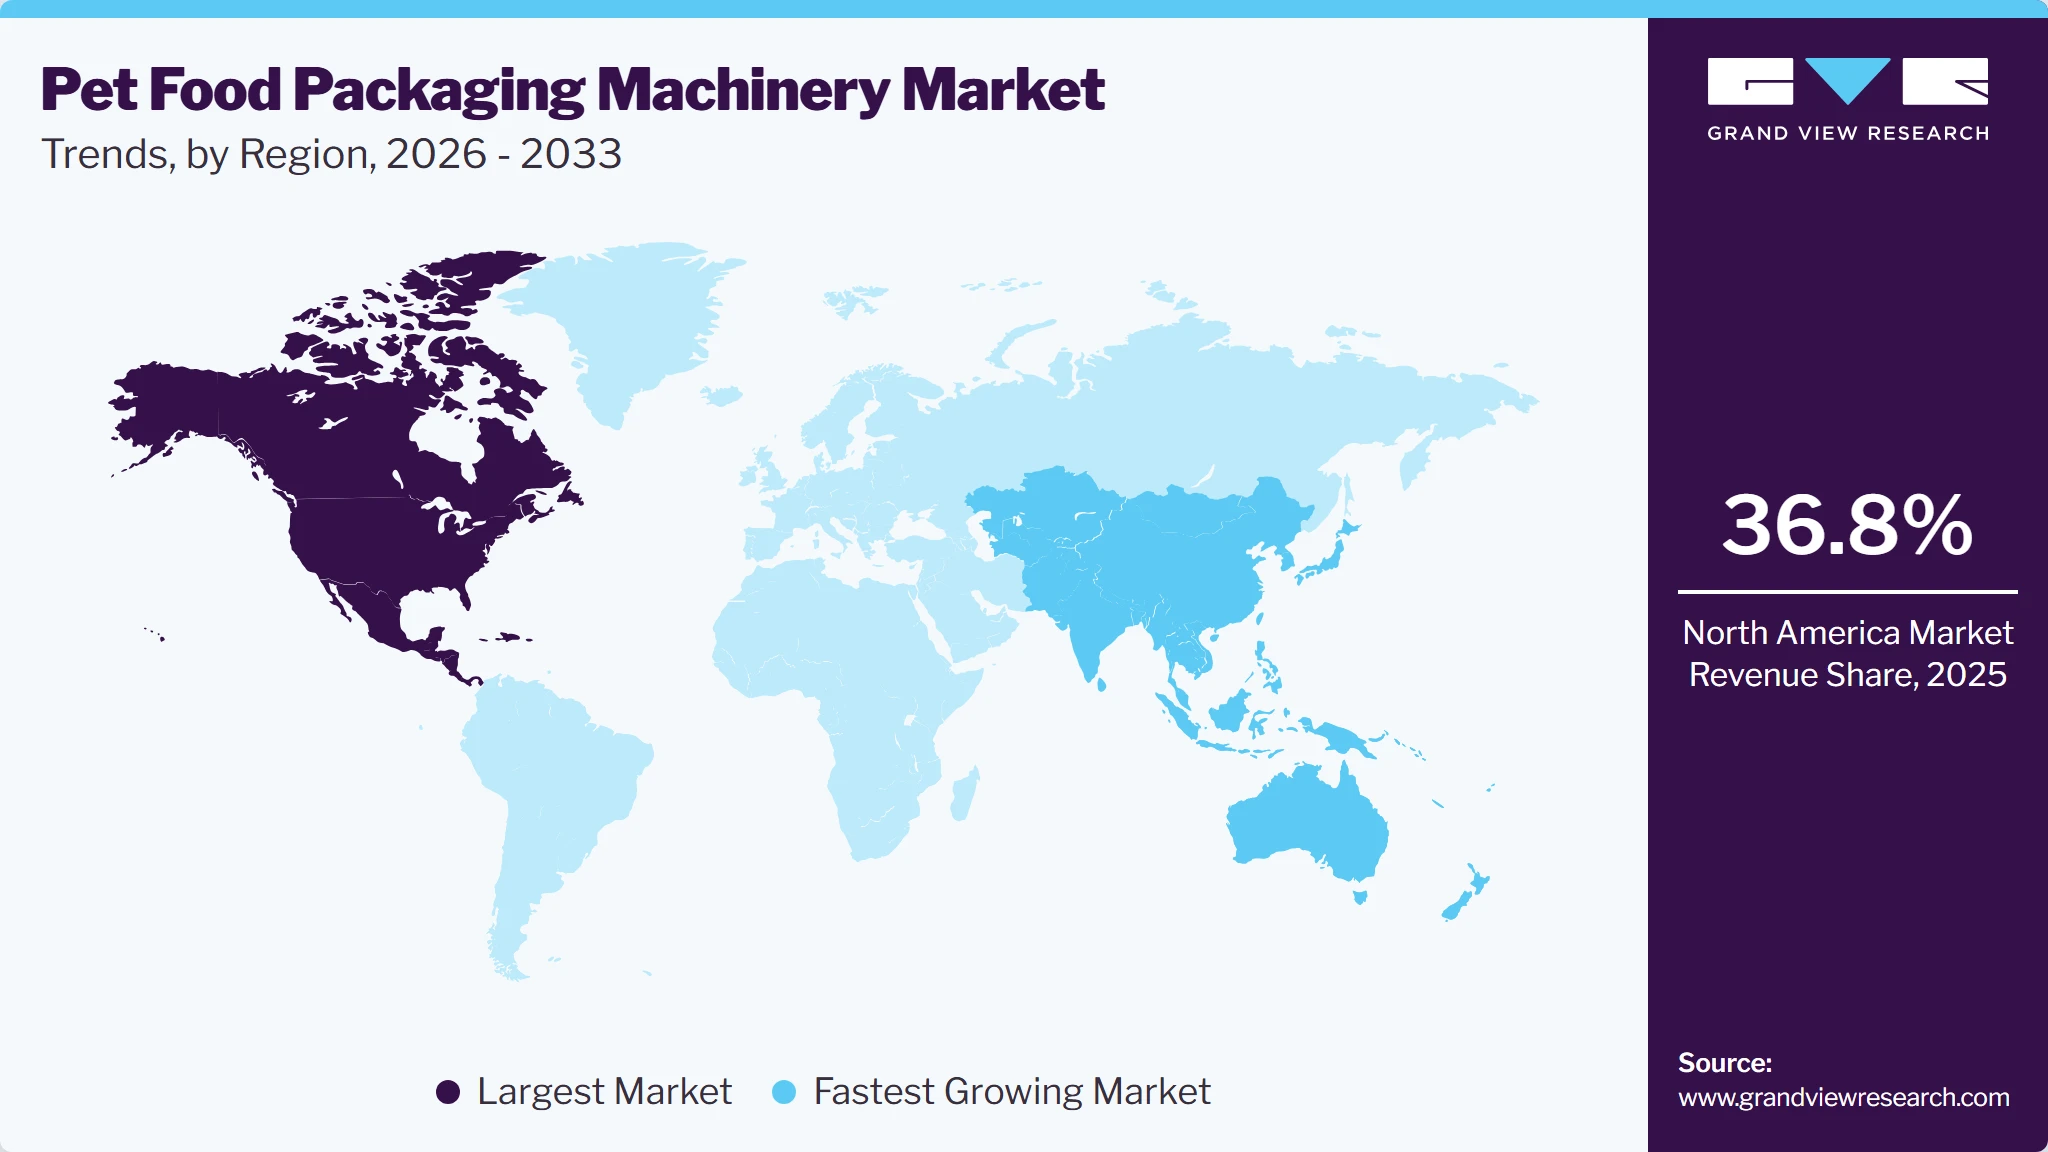
- Largest regional market: North America (36.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.4 Billion
- Estimated market size in 2026: USD 2.5 Billion
- Projected market size by 2033: USD 3.8 Billion
- CAGR (2026-2033): 6.0%
Prism AI by Grand View Research Free to tryAsk a question about the pet food packaging machinery marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Pet ownership continues to rise across both developed and emerging economies, supported by demographic shifts, increasing disposable incomes, urbanization, and the growing humanization of pets. According to HealthforAnimals, families in the U.S., the European Union, and China alone account for more than 496 million dogs and cats.Online retail channels have expanded significantly as pet owners increasingly prefer the convenience of home delivery, subscription-based pet food services, and direct purchases from brand websites. This shift has encouraged pet food manufacturers to diversify product offerings, introduce smaller pack sizes, premium formulations, and customized nutrition products tailored to specific pet needs.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The pet food packaging machinery market is driven by increasing pet ownership, rising demand for premium and specialized pet food products, and growing adoption of automated packaging technologies. Manufacturers are investing in high-speed, flexible machinery to improve production efficiency and accommodate diverse packaging formats, including pouches, bags, and recyclable materials. Sustainability initiatives are encouraging the use of eco-friendly packaging solutions, creating demand for advanced equipment. However, high equipment costs and maintenance requirements can limit adoption among small manufacturers. Technological advancements, including smart packaging systems and Industry 4.0 integration, are enhancing operational efficiency and supporting long-term market growth.
The rapid growth of e-commerce and direct-to-consumer (DTC) pet food sales is emerging as a key driver for the pet food packaging machinery market. Online retail channels have expanded significantly as pet owners increasingly prefer the convenience of home delivery, subscription-based pet food services, and direct purchases from brand websites. This shift has encouraged pet food manufacturers to diversify product offerings, introduce smaller pack sizes, premium formulations, and customized nutrition products tailored to specific pet needs. As a consequence, packaging operations are becoming more complex and require greater flexibility to accommodate a wider range of packaging formats.
Long replacement cycles of industrial packaging equipment act as a key restraint for the pet food packaging machinery market. Packaging machines represent significant capital investments and are typically designed to operate for 8 to 20 years or longer with proper maintenance and periodic upgrades. As a consequence, pet food manufacturers often prioritize refurbishments, retrofits, and component replacements over complete equipment replacement, limiting the frequency of new machinery purchases.
Rising labor costs and persistent workforce shortages are accelerating the adoption of advanced automation technologies across the pet food packaging industry, creating significant growth opportunities for packaging machinery manufacturers. Technologies such as automated filling, sealing, labeling, and palletizing systems help improve production efficiency, reduce labor dependence, and ensure consistent packaging quality. In addition, the adoption of smart technologies, including robotics and IoT-enabled monitoring, allows manufacturers to increase throughput, minimize downtime, and reduce waste. As companies continue to focus on productivity and cost optimization, demand for advanced packaging machinery is expected to grow, creating significant opportunities for market expansion.
Market Concentration & Characteristics
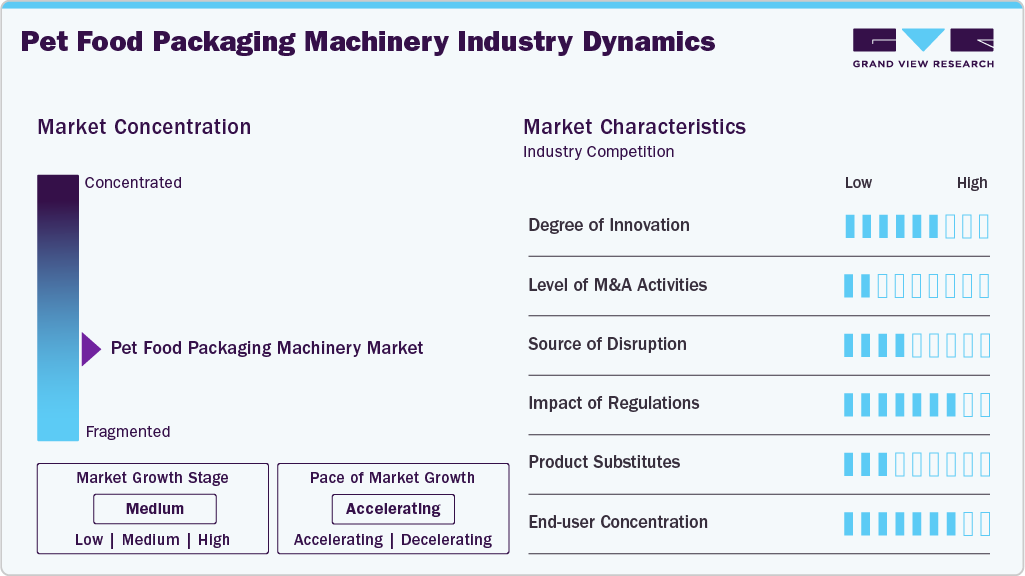
The pet food packaging machinery market is fragmented, with the presence of numerous global and regional manufacturers offering specialized packaging solutions. Companies compete through technological innovation, automation capabilities, customization, and after-sales services. The market includes suppliers focused on filling, sealing, labeling, and end-of-line equipment for different pet food formats. Regional players maintain strong positions by catering to local production needs and cost-sensitive customers, while established multinational companies expand through product development and strategic partnerships.
The pet food packaging machinery market is undergoing rapid technological advancement driven by increasing automation requirements, stricter food safety standards, sustainability initiatives, and the growing premiumization of pet food products. As pet food formulations become more diverse and packaging formats continue to evolve, manufacturers are moving beyond conventional mechanical systems toward highly automated, digitally connected, and flexible packaging solutions.
 To learn more about this report, Download Free Sample Report
Regulatory initiatives such as the European Union's Packaging and Packaging Waste Regulation (PPWR) are accelerating the adoption of recyclable mono-material plastics, paper-based packaging, and other environmentally friendly formats. These materials often exhibit different sealing and handling characteristics than traditional multilayer laminates, prompting machinery manufacturers to incorporate servo-driven motion controls, advanced web tension management systems, and adaptive sealing technologies.
Analyst Perspective
The pet food packaging machinery market is expected to grow, driven by rising global pet ownership and increasing demand for premium pet nutrition products. Manufacturers are investing in automated and flexible packaging systems to improve efficiency and accommodate diverse packaging formats. Sustainability initiatives are encouraging the adoption of machinery compatible with recyclable and lightweight materials. Technological advancements, including smart manufacturing and digital monitoring capabilities, are enhancing operational performance and reducing downtime. Emerging markets present significant opportunities as pet food production expands. Competitive differentiation through innovation, customization, and after-sales service is expected to remain a key success factor for market participants.
Machine Type Insights
The form-fill-seal machines segment dominated the pet food packaging machinery industry in 2025. The shift toward sustainable packaging is another important growth factor, as manufacturers invest in FFS machines compatible with recyclable, mono-material, and lightweight packaging films. Expanding pet ownership, increasing expenditure on premium pet nutrition, and the growth of e-commerce sales are encouraging pet food producers to enhance packaging efficiency and product protection.
The filling machines segment is expected to grow significantly during the forecast period at a CAGR of 6.4%. The expansion of pet food manufacturing facilities in emerging markets and capacity upgrades in established regions are expected to support long-term demand for filling machines, making this segment a key contributor to the growth of the market for pet food packaging machinery.
End User Insights
The pet food manufacturers segment dominated the pet food packaging machinery market in 2025. Manufacturers are increasing production capacities for dry food, wet food, treats, and specialized diets, creating demand for advanced packaging machinery that can improve throughput and maintain consistent product quality. For instance, in March 2026, Nestlé Purina invested USD 473.6 million in its new wet pet food facility in Brazil. This investment will fuel demand for pet food packaging machinery by expanding production capacity for canned and pouch-based products.
 To learn more about this report, Download Free Sample Report
The contract packagers segment is projected to grow significantly at 6.7% CAGR during the forecast period. Many established and emerging pet food companies rely on contract packagers to handle packaging requirements without investing in dedicated packaging infrastructure. This has encouraged contract packaging companies to expand their capabilities by adopting advanced packaging machinery that efficiently processes a wide range of pet food products and packaging formats.
Packaging Type Insights
The bags segment held a significant share of the pet food packaging machinery industry in 2025. E-commerce growth has increased the need for durable and lightweight packaging that protects products during transportation while reducing logistics costs. Sustainability initiatives are further influencing machinery demand, as manufacturers adapt production lines to process recyclable and eco-friendly packaging materials.
The pouches segment is expected to grow at 6.6% CAGR during the forecast period. Pouches are lightweight and require less storage and transportation space than rigid containers, improving supply chain efficiency and lowering logistics costs. As global pet food production expands and manufacturers seek greater packaging flexibility and operational efficiency, investments in automated pouch packaging equipment are expected to increase, supporting the long-term growth of the pouches segment.
Automation Insights
The fully automatic segment dominated the pet food packaging machinery market in 2025. The expansion of large-scale pet food manufacturing facilities and organized retail distribution networks is contributing to demand for fully automatic packaging equipment. These systems can handle multiple packaging formats and support continuous production with minimal downtime, improving overall productivity.
The semi-automatic segment is projected to grow at 5.8% CAGR during the forecast period. Semi-automatic systems are well-suited for handling these changing requirements while supporting efficient small-batch production. The development of the pet food industry in emerging economies is further strengthening this segment. Many local manufacturers are upgrading from manual packaging operations to improve product quality, reduce packaging errors, and meet evolving retail and food safety standards.
Regional Insights
North America is a dominant market for pet food packaging machinery with a revenue share of 36.8% in 2025, supported by a highly developed pet care industry and widespread adoption of commercial pet food products. Strong demand for premium, functional, and specialized pet food formulations has increased the need for advanced packaging solutions that ensure product safety, freshness, and extended shelf life. Manufacturers continue to invest in high-speed filling, sealing, and form-fill-seal technologies to improve operational efficiency and accommodate diverse packaging formats.
 To learn more about this report, Download Free Sample Report
U.S. Pet Food Packaging Machinery Market Trends
The U.S. pet food packaging machinery industry’s growth is supported by a large-scale pet food manufacturing sector and strong demand for packaged pet nutrition products. Growing consumer preference for premium, functional, and specialized pet food continues to encourage manufacturers to expand production capacity and modernize packaging operations. According to the American Feed Industry Association (AFIA), U.S. dog and cat food sales reached USD 51.7 billion in 2024, with production volumes totaling nearly 9.8 million tons and utilizing more than 600 plant and animal-derived ingredients.
The pet food packaging machinery market in Mexico is driven by rising pet ownership, increasing demand for commercial pet food products, and ongoing investments in domestic manufacturing capabilities. The country's pet food industry is undergoing significant expansion as manufacturers focus on strengthening local production and reducing reliance on imports. This growth is creating substantial demand for advanced filling, sealing, labeling, and form-fill-seal machinery capable of supporting higher production volumes and a broader range of packaging formats.
Europe Pet Food Packaging Machinery Market Trends
Europe maintains a strong position in the pet food packaging machinery industry, owing to its established pet food manufacturing sector and emphasis on product quality and regulatory compliance. The region's growing preference for premium pet nutrition products has increased demand for sophisticated packaging systems that ensure product integrity, traceability, and food safety throughout the supply chain.
The Germany pet food packaging machinery market is one of the most significant markets in Europe, supported by a large pet population, strong demand for commercial pet food products, and a well-established pet care industry. The country's pet food manufacturers continue to invest in product innovation, premium nutrition offerings, and efficient production processes to meet evolving consumer preferences. These developments are creating sustained demand for advanced filling, sealing, form-fill-seal, and labeling machinery capable of supporting high-volume production while maintaining stringent quality standards.
The pet food packaging machinery market in the UK is significant, supported by strong demand for premium pet nutrition products, rising pet humanization trends, and ongoing product innovation across the pet care sector. Manufacturers are increasingly focusing on functional, natural, and specialized pet food offerings, creating demand for advanced packaging solutions that enhance product protection, convenience, and shelf appeal.
Asia Pacific Pet Food Packaging Machinery Market Trends
The Asia Pacific pet food packaging machinery industry is anticipated to grow at the fastest CAGR of 6.6% over the forecast period, driven by rising pet ownership, higher disposable incomes, and greater consumer awareness of pet health and nutrition. The rapid expansion of the commercial pet food industry is creating significant opportunities for packaging machinery manufacturers as producers scale up operations to meet increasing demand.
The China pet food packaging machinery market is the largest in Asia Pacific, supported by a rapidly expanding pet economy, rising pet ownership, and increasing consumer expenditure on pet care products. Pet food manufacturers are continually expanding production capacity to meet the growing demand for premium, functional, and specialized pet nutrition products. This growth is creating substantial demand for advanced machinery capable of supporting large-scale production while ensuring product quality and packaging efficiency.
The pet food packaging machinery market in India is high-growth, supported by changing consumer attitudes toward pet care, rising disposable incomes, and increasing demand for commercially prepared pet food products. The market is witnessing a gradual shift from traditional feeding practices toward packaged, nutritionally balanced pet food, prompting manufacturers to enhance production capabilities and improve packaging efficiency.
Middle East & Africa Pet Food Packaging Machinery Market Trends
The Middle East & Africa pet food packaging machinery industry is experiencing gradual growth, driven by rising demand for packaged pet food products and the ongoing development of the food processing industry. Rising consumer awareness regarding pet nutrition and the expanding availability of commercial pet food products are creating favorable conditions for market expansion.
Increasing pet ownership, changing consumer lifestyles, and the expansion of the domestic pet care industry are fueling the market growth in Saudi Arabia. Rising urbanization and higher disposable incomes are encouraging demand for premium pet food products, including dry food, wet food, and specialized diets, creating the need for efficient packaging solutions. Manufacturers are investing in advanced packaging machinery to improve production capacity and maintain product quality across various packaging formats such as bags, pouches, and cans.
Latin America Pet Food Packaging Machinery Market Trends
Latin America is emerging as a promising market for pet food packaging machinery due to the increasing consumption of commercially packaged pet food products and the ongoing modernization of food manufacturing facilities. Growing awareness of pet nutrition and the rising popularity of branded pet food products are encouraging manufacturers to expand production capacities and invest in more efficient packaging solutions.
The expanding pet population in Brazil and rising expenditure on premium pet nutrition are encouraging manufacturers to expand production capacity for dry, wet, and pet treat products. This expansion is driving demand for advanced packaging machinery that can improve productivity and ensure consistent packaging quality.
Key Pet Food Packaging Machinery Company Insights
Some of the key players operating in the market include GEA Group, Coesia S.p.A., and IMA Group.
-
GEA Group Aktiengesellschaft is a global technology and engineering company specializing in process equipment, industrial machinery, and integrated production systems for the food, beverage, pharmaceutical, and related industries. The company’s key verticals include food processing, packaging, separation, refrigeration, mixing, drying, and automation solutions that enhance manufacturing efficiency and product quality.
-
Coesia S.p.A. is a global provider of industrial automation and packaging solutions, serving industries including food, pet food, consumer goods, healthcare, and pharmaceuticals. The company operates through a portfolio of specialized businesses offering packaging machinery, processing systems, robotics, digital printing, inspection technologies, and end-of-line automation solutions.
Key Pet Food Packaging Machinery Companies
The following key companies have been profiled for this study of the pet food packaging machinery market.
-
Ishida Co., Ltd.
-
GEA Group Aktiengesellschaft
-
Multivac Inc.
-
Coesia S.p.A.
-
IMA Group
-
Pro Mach, Inc.
-
Barry-Wehmiller Companies
-
Syntegon Technology GmbH
-
ULMA Packaging
-
Schubert Group
-
Collingwood Packaging Machinery, S.L.U.
-
Concetti S.p.A.
-
Cama Group
-
Omori Machinery Co., Ltd.
-
KRONEN GmbH
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (e.g., GEA Group, Coesia S.p.A., Multivac Inc., IMA Group)
- Focus on expanding automated pet food packaging machinery portfolios for dry, wet, and treat products.
- Invest in high-speed, flexible, and smart packaging technologies to improve efficiency.
- Strengthen partnerships with pet food manufacturers and integrate sustainable packaging capabilities.
- Strong engineering expertise and comprehensive packaging solutions.
- Extensive global sales, service, and distribution networks.
- Established customer relationships and advanced automation capabilities.
- High research, development, and manufacturing costs.
- Dependence on capital investments by large pet food producers.
- Longer product development and installation cycles for customized systems.
Emerging & Regional Players (e.g., ULMA Packaging, Schubert Group, Collingwood Packaging Machinery, S.L.U., Concetti S.p.A., Cama Group)
- Focus on customized and application-specific packaging machinery for niche pet food segments.
- Expand regional presence through tailored solutions and local partnerships.
- Develop flexible equipment compatible with evolving packaging formats and sustainable materials.
- Competitive pricing and high customization capabilities.
- Ability to respond quickly to changing customer requirements.
- Strong presence in regional and specialized packaging applications.
- Limited financial resources for large-scale innovation and expansion.
- Smaller international sales and after-sales service networks.
- Lower participation in large, high-volume pet food packaging projects.
Recent Developments
-
In May 2026, GEA enhanced its packaging equipment portfolio with the launch of the PowerPak 5000, a thermoforming solution designed for flexible food packaging applications. The system supports multiple packaging styles on a single platform and features a modular design that allows future upgrades.
-
In October 2025, Syntegon recently introduced its SVX series vertical packaging machine to the Indian market, expanding its portfolio of flexible packaging solutions for food manufacturers.
Pet Food Packaging Machinery Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.4 billion
Estimated market size in 2026
USD 2.5 billion
Projected market size by 2033
USD 3.8 billion
Growth rate
CAGR of 6.0% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Machine type, packaging type, end user, automation, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Spain; Italy; Russia; China; Japan; India; Australia; South Korea;Thailand; Malaysia; Indonesia; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Ishida Co., Ltd.; GEA Group Aktiengesellschaft; Multivac Inc.; Coesia S.p.A; IMA Group; ProMach, Inc.; Barry-Wehmiller Companies; Syntegon Technology GmbH; ULMA Packaging; Schubert Group; Collingwood Packaging Machinery S.L.U., Concetti S.p.A.; Cama Group; Omori Machinery Co., Ltd.; KRONEN GmbH
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pet Food Packaging Machinery Market Report Segmentation
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pet food packaging machinery market report based on machine type, packaging type, end user, automation, and region:
-
Machine Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Filling Machines
-
Sealing Machines
-
Form-fill-seal Machines
-
Wrapping Machines
-
Labeling Machines
-
Others
-
-
Packaging Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Bags
-
Pouches
-
Cans
-
Boxes
-
Others
-
-
Automation Outlook (Revenue, USD Billion, 2021 - 2033)
-
Fully Automatic
-
Semi-automatic
-
Manual
-
-
End User Outlook (Revenue, USD Billion, 2021 - 2033)
-
Pet Food Manufacturers
-
Contract Packagers
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Spain
-
UK
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Thailand
-
Malaysia
-
Indonesia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The pet food packaging machinery market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pet food packaging machinery segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Machine Type
Revenue capture definition
Filling Machines
Revenue is generated from the sale of filling machines used to accurately dispense pet food products into various packaging formats.
Sealing Machines
Revenue is generated through the sale of sealing machines used to securely close pet food packages and preserve product quality.
Form-fill-seal Machines
Revenue is derived from the sale of form-fill-seal machines used to form, fill, and seal pet food packages in a single operation.
Wrapping Machines
Revenue is generated from the sale of wrapping machines used to enclose pet food products with protective packaging materials.
Labeling Machines
Revenue is generated from the sale of labeling machines used to apply branding, product, and regulatory labels to pet food packages.
Others
Revenue is generated through the sale of specialized pet food packaging machinery, including coding, inspection, cartooning, and checkweighing systems.
Segment - Packaging Type
Revenue capture definition
Bags
Revenue is derived from the sale of packaging machinery used to fill and seal pet food in bag packaging.
Pouches
Revenue is generated from the sale of packaging machinery used to package pet food in pouch formats.
Cans
Revenue is generated from the sale of packaging machinery used to fill and seal canned pet food products.
Boxes
Revenue is generated from the sale of packaging machinery used to pack pet food into boxes and cartons.
Others
Revenue is generated from the sale of packaging machinery used for trays, tubs, cups, sachets, and other specialty packaging formats.
Segment - Automation
Revenue capture definition
Fully Automatic
Revenue is generated through the sale of fully automatic packaging machines.
Semi-automatic
Revenue is generated from the sale of semi-automatic packaging machines that combine automated operations with manual involvement.
Manual
Revenue is derived from the sale of manual packaging machines used for low-volume pet food packaging operations.
Segment - End User
Revenue capture definition
Pet Food Manufacturers
Revenue is generated from the sale of packaging machinery to companies engaged in the production and packaging of pet food products.
Contract Packagers
Revenue is generated from the sale of packaging machinery to third-party service providers that package pet food for brand owners.
Estimation Model
Layer Name
Key Question
Description
Pet Food Production Layer
Which industries generate demand for pet food packaging machinery?
The estimation begins by evaluating global pet food production across dry, wet, frozen, treats, and specialty nutrition products. Growth in pet ownership, premiumization, and commercial pet food manufacturing establishes the base market demand.
Packaging Format Adoption Layer
Which packaging formats drive machinery demand?
This layer refines demand by assessing the adoption of bags, pouches, cans, boxes, and other packaging formats. Consumer preferences, product shelf-life requirements, convenience features, and sustainability trends influence packaging selection.
Machinery and Automation Deployment Layer
What determines packaging machinery installations?
Market demand is estimated through the adoption of filling, sealing, form-fill-seal, wrapping, labeling, and other packaging machines across fully automatic, semi-automatic, and manual operations. Production capacity expansion, modernization, and equipment replacement further support demand.
Revenue Layer
How is total market revenue calculated?
Revenue is estimated by aggregating packaging machinery sales across machine types, packaging formats, automation levels, end users, and regional markets. Pet food production investments, packaging line expansions, replacement cycles, and manufacturer revenues are incorporated to validate the total market size.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed regional analysis covered North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, with country-level assessment of key markets. The study evaluated pet food production, packaging industry development, automation adoption, manufacturing capacity expansions, consumer preferences, and investments in food processing infrastructure, influencing pet food packaging machinery demand.
Helped identify high-growth regions, country-specific opportunities, and evolving demand trends across the pet food and packaging industries, supporting market entry strategies, regional expansion planning, and identification of emerging manufacturing hubs.
Competitive Benchmarking
Comprehensive benchmarking assessed major participants based on product portfolio, packaging machinery technologies, engineering capabilities, manufacturing strength, automation features, regional presence, and distribution networks. The study also compared established and emerging players in the pet food packaging machinery market.
Assisted in evaluating competitor positioning, technological capabilities, and market gaps while supporting strategic planning, partnership opportunities, product differentiation, and investment decisions across pet food packaging applications.
Opportunity Assessment
In-depth opportunity assessment analyzed growth in premium pet food production, sustainable packaging adoption, automation investments, flexible packaging demand, and expansion of pet food manufacturing facilities. The study identified emerging opportunities in high-speed packaging systems, smart packaging technologies, and machinery compatible with recyclable packaging materials.
Enabled clients to identify high-growth investment areas, prioritize regional expansion, and evaluate future revenue opportunities while supporting product development, technology adoption, and long-term growth strategies in the pet food packaging machinery market.
Frequently Asked Questions About This Report
The global pet food packaging machinery market size was estimated at USD 2.4 billion in 2025 and is expected to be USD 2.5 billion in 2026.
The global pet food packaging machinery market, in terms of revenue, is expected to grow at a compound annual growth rate of 6.0% from 2026 to 2033 to reach USD 3.8 billion by 2033.
The form-fill-seal machines segment dominated the market and accounted for a share of 32.5% in 2025.
The bags segment dominated the market and accounted for a share of 36.5% in 2025.,
Which automation segment accounted for the largest global pet food packaging machinery market share?The fully automatic segment dominated the market and accounted for a share of 49.0% in 2025.
The pet food manufacturers segment dominated the market and accounted for a share of 81.7% in 2025.
North America region dominated the market and accounted for a share of 36.8% in 2025.
Some of the key players operating in the global pet food packaging machinery market include Ishida Co., Ltd., GEA Group Aktiengesellschaft, Multivac Inc., Coesia S.p.A., IMA Group, ProMach, Inc., Barry-Wehmiller Companies, Syntegon Technology GmbH, ULMA Packaging, Schubert Group, Collingwood Packaging Machinery, S.L.U., Concetti S.p.A., Cama Group, Omori Machinery Co., Ltd., KRONEN GmbH.
The global pet food packaging machinery market is driven by rising pet ownership, increasing demand for premium and packaged pet food, growing automation in food processing, and the need for efficient, high-speed packaging solutions. Sustainability trends, innovative packaging formats, stringent food safety regulations, and expanding pet food production capacities further support market growth.
About the Author(s)
Machinery & Equipment Research Team
Machinery & Manufacturing · Machinery & EquipmentThis report was authored by the machinery & equipment research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the machinery & equipment segment of the machinery & manufacturing industry. All findings are based on proprietary machinery & manufacturing databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


