
- Home
- »
- Advanced Interior Materials
- »
-
Pet Food Processing Market Size, Share Report, 2026-2033GVR Report cover

Pet Food Processing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Equipment Type (Mixing & Blending, Forming, Baking & Drying, Coating), By Form (Wet, Dry), By Region (North America, Asia Pacific, Europe, Latin America, Middle East and Africa), And Segment Forecasts
Market Size, 2025
$5.9BMarket Estimate, 2026
$6.3BMarket Forecast, 2033
$9.4BCAGR, 2026–2033
6.0%Pet Food Processing Market Summary
The global pet food processing market size was valued at USD 5.9 billion in 2025 and is projected to grow from USD 6.3 billion in 2026 to USD 9.4 billion by 2033, at a CAGR of 6.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 33.7% in 2025. The market growth can be attributed to the increasing demand for specialized and premium pet food products, fueled by pet humanization trends.
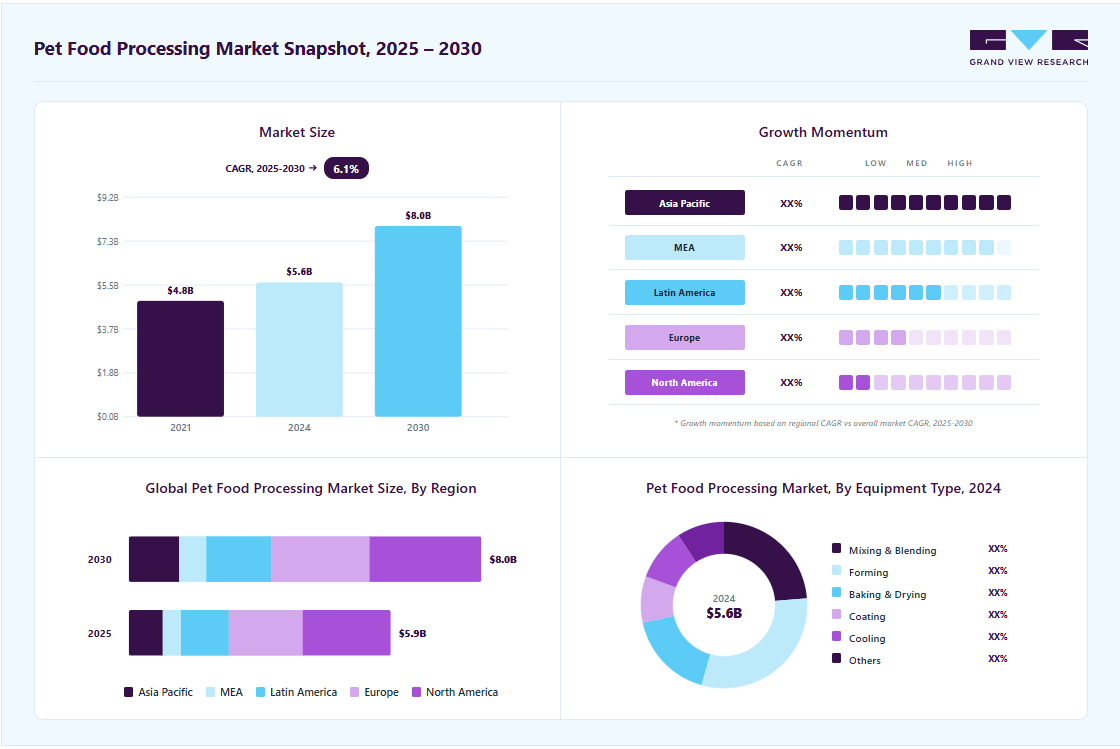 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By equipment type: Forming segment led the market with the largest revenue share of 30.9% in 2025.
- By form: Dry segment led the market with the largest revenue share of 71.1% in 2025
Regional Highlights
- Largest regional market: North America (33.7% revenue share, 2025)
- By country: The US held the largest share in 2025
Market Size & Forecast
- Market Size in 2025: USD 5.9 Billion
- Estimated Market Size in 2026: USD 6.3 Billion
- Projected Market Size by 2033: USD 9.4 Billion
- CAGR (2026-2033): 6.0%
Prism AI by Grand View Research Free to tryAsk a question about the pet food processing marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
In addition, pet owners are prioritizing health benefits and convenience, leading to a rise in automation and advanced processing technologies. Furthermore, urbanization and rising disposable incomes, particularly are enhancing market expansion. To learn more about this report, Download Free Sample Report
Pet food pricing refers to the cost associated with purchasing food for pets, which can vary based on factors such as quality, ingredients, and packaging. In recent years, there has been a noticeable increase in pet adoption rates, largely driven by individuals seeking companionship to combat feelings of loneliness and enhance their mental well-being. As people lead increasingly busy lives, the emotional support provided by pets has become invaluable. This growing trend has led to a heightened focus on ensuring that pets receive the best possible care, particularly when it comes to nutrition.
In addition, many pet owners are opting to buy pet food in larger quantities, necessitating high-quality packaging solutions that maintain freshness and appeal. This shift contributes significantly to expanding the pet food processing market. Furthermore, there is a burgeoning demand for various pet food options tailored to specific dietary needs and preferences. The availability of diverse shapes and sizes of pet food allows owners to select products that best suit their pets' requirements, fostering a competitive landscape among manufacturers who are investing heavily in attractive packaging.
Moreover, the increasing awareness surrounding pet health is prompting owners to educate themselves about nutrition and well-being through accessible online resources. This knowledge empowers them to make informed choices about what they feed their pets, further driving demand for nutritionally rich and visually appealing food products. In response, companies are upgrading their processing technologies to meet these evolving consumer expectations.
Market Dynamics
The global pet food processing market is driven by the expanding pet population, growing consumer preference for premium and functional pet nutrition, and increasing investment in automated processing technologies that improve product quality, consistency, and food safety. Manufacturers are adopting advanced extrusion, mixing, drying, coating, and packaging systems to support the production of specialized formulations such as grain-free, high-protein, and veterinary diets while meeting stringent regulatory and hygiene standards. At the same time, fluctuations in raw material prices, high capital investment requirements for advanced equipment, and evolving regulatory compliance create challenges for processors. Nevertheless, ongoing innovation in energy-efficient machinery, digital process monitoring, and sustainable production practices continue to strengthen long-term market opportunities.
Increasing pet humanization and higher spending on companion animal health are encouraging manufacturers to produce premium, functional, and customized pet food formulations. This is accelerating investments in advanced processing equipment, including extrusion, mixing, drying, and coating technologies that ensure consistent product quality, nutritional value, and production efficiency. The expansion of organized retail and e-commerce channels has also increased the availability of premium pet food products, encouraging processors to expand production capacity. Furthermore, demand for breed-specific, life-stage-specific, and therapeutic diets is prompting manufacturers to adopt flexible processing systems capable of handling diverse product formulations.
The adoption of modern pet food processing equipment requires substantial upfront investment in automated machinery, plant infrastructure, and quality control systems. In addition, energy consumption, equipment maintenance, and compliance with stringent food safety regulations increase operating expenses, posing challenges for small and medium-sized manufacturers. Frequent equipment upgrades to meet evolving production requirements further increase capital expenditure. Volatility in the prices of meat, grains, and other raw materials also affects production planning and overall profitability.
The growing focus on operational efficiency and environmental sustainability is creating opportunities for equipment manufacturers to develop energy-efficient, automated, and digitally connected processing systems. The adoption of IoT-enabled monitoring, predictive maintenance, AI-assisted process optimization, and technologies that support alternative protein ingredients is enabling pet food producers to enhance productivity while reducing waste and resource consumption. Increasing interest in insect protein, plant-based ingredients, and upcycled raw materials is encouraging the development of processing solutions tailored to emerging formulations.
Analyst Perspective
The pet food processing market is expanding steadily as manufacturers increase investments in advanced processing technologies to meet the growing demand for high-quality, nutritionally balanced, and premium pet food products. The increasing trend toward pet humanization is encouraging the production of specialized formulations, including grain-free, organic, functional, and high-protein diets, which require precise and efficient processing equipment. In addition, manufacturers are focusing on automation, digital process control, and hygienic equipment designs to improve production efficiency, ensure product consistency, and comply with stringent food safety regulations. The integration of energy-efficient systems and smart manufacturing technologies is further enhancing operational performance while reducing production costs. As global pet ownership continues to grow and product innovation accelerates, suppliers offering automated, high-capacity, and application-specific pet food processing equipment are expected to benefit from sustained long-term market growth.
Equipment Type Insights
Based on equipment type, the forming segment led the market with the largest revenue share of 30.9% in 2025. This growth can be attributed to the increasing demand for premium pet food options, which has led manufacturers to adopt advanced extrusion technologies essential for producing high-quality products. In addition, growing awareness of pet health and nutrition encourages consumers to seek specialized food items, further boosting the need for efficient forming equipment. Furthermore, technological advancements in processing machinery enable greater flexibility and automation, allowing producers to meet diverse consumer preferences and enhance production efficiency.
The coating equipment segment is expected to grow at a CAGR of 7.1% from 2025 to 2030, owing to the increasing consumer preferences for enhanced flavors and textures in pet food. In addition, the trend toward premiumization encourages manufacturers to utilize coating technologies to improve product appeal and nutritional value. Furthermore, advancements in coating techniques allow for better application of functional ingredients, catering to health-conscious pet owners. Moreover, this segment is expected to expand as companies seek to differentiate their offerings in a competitive market landscape.
Form insights
Based on form, the dry segment led the market with the largest revenue share of 71.1% in 2025, driven by its convenience, extended shelf life, and health benefits. In addition, pet owners favor dry food for its ease of storage and feeding, especially among busy urban dwellers. Furthermore, it promotes better oral health due to its texture, which helps reduce tartar buildup. Moreover, the increasing adoption of pets and a growing awareness of their nutritional needs further enhance the demand for dry pet food products in the market.
 To learn more about this report, Download Free Sample Report
The wet pet food segment is expected to grow at a CAGR of 6.5% over the forecast period, owing to its palatability and moisture content, which appeals to pets and their owners alike. In addition, wet food is often perceived as more nutritious and is preferred for its ability to cater to pets with specific dietary needs. Furthermore, the rise in pet humanization trends, where pets are treated as family members, drives demand for high-quality wet food options. Moreover, packaging and formulation innovations enhance wet pet food's appeal in the competitive market.
Regional Insights
North America dominated the pet food processing market with the largest revenue share of 33.7% in 2025. This growth can be attributed to the increasing trend of pet humanization, where pets are viewed as family members. This has led to a surge in demand for premium and specialized pet food products. In addition, rising awareness about pet health and nutrition also encourages manufacturers to innovate and comply with stringent food safety standards. Furthermore, the robust distribution networks, including e-commerce platforms, further facilitate access to diverse pet food options, contributing to market expansion.
 To learn more about this report, Download Free Sample Report
U.S. Pet Food Processing Market Trends
The pet food processing market in the U.S. held the largest share in the North America region in 2025, primarily driven by high pet ownership rates and a growing focus on health-conscious consumer behavior. In addition, the demand for organic and premium pet foods is rising as owners prioritize quality. Innovations in processing technologies, such as microfiltration and high-pressure processing, enhance product appeal by preserving flavor and nutrition. Furthermore, strategic initiatives such as mergers and acquisitions among manufacturers are fostering competitive growth in this lucrative market.
Asia Pacific Pet Food Processing Market Trends
The Asia Pacific pet food processing market is expected to grow at a CAGR of 6.8% over the forecast period, owing to rising disposable incomes and urbanization, leading to increased pet ownership. In addition, the growing trend of pet humanization drives demand for high-quality and specialized pet food products. Furthermore, cultural shifts towards viewing pets as companions rather than property are influencing purchasing decisions. Moreover, the expansion of retail channels, including online platforms, supports accessibility to diverse pet food options, further propelling market growth.
The pet food processing market in China dominated Asia Pacific with the largest revenue share in 2024, driven by a significant increase in pet ownership among urban populations. In addition, the rising middle class is driving demand for premium and nutritious pet food products that cater to health-conscious consumers. Furthermore, increasing investments in local manufacturing capabilities and distribution networks enhance product availability. The growing trend of pet humanization also influences consumer preferences toward high-quality ingredients and innovative formulations in pet food.
Europe Pet Food Processing Market Trends
The Europe pet food processing market is expected to witness substantial growth over the forecast period, owing to an increasing focus on sustainability and natural ingredients in pet food products. In addition, consumers are becoming more aware of their pets' nutritional needs, leading to a demand for premium offerings. Regulatory frameworks promoting food safety also encourage manufacturers to invest in advanced processing technologies. Furthermore, the rise of e-commerce platforms provides convenient access to various pet food options, further supporting market growth.
The growth of the pet food processing market in Germany is expected to be driven by benefits from a strong culture of pet ownership and increasing expenditures on premium pet products. Furthermore, the demand for high-quality ingredients and transparency in sourcing drives manufacturers to innovate in product development. Moreover, the growing popularity of natural and organic pet foods aligns with consumer preferences for healthier options.
Key Pet Food Processing Company Insights
Key companies in the global pet food processing industry include GEA Group, Buhler Holding AG, The Middleby Corporation, and others. These players adopt numerous strategies to improve their competitive edge. Strategic partnerships are formed to leverage complementary strengths, improve product offerings, and expand distribution networks. In addition, mergers and acquisitions enable companies to consolidate resources, enter new markets, and diversify their product lines. Furthermore, new product launches focus on innovation and meeting evolving consumer preferences, allowing companies to capture market share and respond effectively to pet nutrition and health trends.
-
ANDRITZ manufactures a wide range of machinery, including extruders, conditioners, and coating systems, designed to enhance the efficiency of pet food production. Operating within the pet food processing segment, the company delivers innovative solutions that improve productivity while ensuring optimal food safety and quality, helping manufacturers meet pets' growing nutritional demands.
-
Bakery Perkins Ltd. manufactures machinery such as mixers, ovens, and dryers tailored for dry and wet formulations. The company focuses on the pet food processing segment and enhances operational efficiency and product quality for its clients. Its expertise in baking technology and process engineering enables it to deliver customized solutions that cater to the diverse needs of the pet food industry.
Key Pet Food Processing Companies:
The following key companies have been profiled for this study on the pet food processing market.
-
ANDRITZ
-
GEA Group
-
Buhler Holding AG
-
The Middleby Corporation
-
Baker Perkins LTD.
-
PFI
-
Clextral SAS
-
Reading Bakery Systems
-
Mepaco Group
-
F.N. Smith Corporation
-
Selo
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., ANDRITZ, GEA Group, Buhler Holding AG, The Middleby Corporation, Baker Perkins LTD., Clextral SAS)
- Strong investments in automated pet food processing technologies and high-capacity production systems
- Expansion of extrusion, drying, coating, mixing, and packaging solutions for premium pet food applications
- Focus on energy-efficient processing systems, digital monitoring, and smart manufacturing integration
- Strong global brand recognition and diversified food processing equipment portfolios
- Advanced technological expertise in extrusion and continuous processing systems
- High production efficiency, automation capabilities, and process reliability
- High equipment and installation costs compared to regional suppliers
- Dependence on capital expenditure trends in the food processing industry
- Longer sales and project implementation cycles
Emerging & Regional Players (e.g., AES Arabia Ltd., INTECH, Integrated Flow Solutions LLC, Petroserve International, Carotek Inc.)
- Focus on customized pet food processing and niche production solutions
- Increasing emphasis on flexible manufacturing systems and small-to-medium production facilities
- Strengthening regional distributor partnerships and application-specific engineering capabilities
- Competitive pricing and flexibility in customized equipment solutions
- Strong responsiveness to customer-specific production requirements
- Growing adoption among mid-sized pet food manufacturers
- Comparatively lower global market penetration and brand visibility
- Limited financial scale for large R&D and international expansion investments
- Lower diversification compared to multinational food processing equipment providers
Recent Developments
-
In August 2024, Big Idea Ventures and Mars Petcare introduced the Next Gen Pet Food Program to foster innovation in sustainable pet food processing. This initiative was expected to invite start-ups to develop novel proteins and fats that can help in the reduction of carbon emissions in pet food production. Collaborating with AAK and Bühler, the program aimed at innovative solutions such as upcycling food waste and advanced extraction methods.
-
In July 2023, Hill's Pet Nutrition unveiled new products, presenting MSC-certified Alaskan Pollock and insect protein. These products were aimed at pets with sensitive stomachs and skin. This initiative highlighted the company's commitment to sustainable pet food processing by using traceable, wild-caught seafood and innovative insect protein. The new formulas were expected to promote digestive health and support skin nourishment, aligning with consumer demand for environmentally friendly options in pet nutrition.
Pet Food Processing Market Report Scope
Report Attribute
Details
Market Size in 2025
USD 5.9 billion
Estimated Market Size in 2026
USD 6.3 billion
Projected Market Size by 2033
USD 9.4 billion
Growth rate
CAGR of 6.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Equipment type, form, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; China; India; Japan; Australia; Germany; UK; France; Italy; Brazil; Argentina; UAE; Saudi Arabia
Key companies profiled
ANDRITZ; GEA Group; Buhler Holding AG; The Middleby Corporation; Baker Perkins LTD.; PFI; Clextral SAS; Reading Bakery Systems; Mepaco Group; F.N. Smith Corporation; Selo
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Pet Food Processing Market Report Segmentation
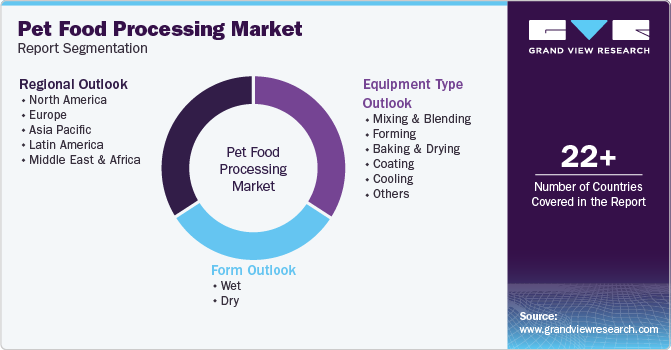
This report forecasts revenue growth at global, regional, and country levels and analyzes the latest industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global pet food processing market report based on equipment type, form, and region:
 To learn more about this report, Download Free Sample Report
-
Equipment Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Mixing & Blending
-
Forming
-
Baking & Drying
-
Coating
-
Cooling
-
Others
-
-
Form Outlook (Revenue, USD Million, 2021 - 2033)
-
Wet
-
Dry
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
UAE
-
Saudi Arabia
-
-
Research Methodology
The pet food processing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each pet food processing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Equipment
Revenue Capture Definition
Mixing & Blending
The segment captures revenue generated from the sale of pet food mixing and blending equipment used to combine ingredients into uniform formulations for wet, dry, and specialty pet food production.
Forming
The segment captures revenue generated from the sale of pet food forming equipment designed to shape products into kibbles, pellets, treats, patties, or other specified formats before further processing.
Baking & Drying
The segment captures revenue generated from the sale of baking and drying equipment used to remove moisture, improve product stability, and achieve the required texture and shelf life of pet food products.
Coating
The segment captures revenue generated from the sale of coating equipment used to apply fats, oils, flavors, vitamins, minerals, and palatability enhancers to finish pet food products.
Cooling
The segment captures revenue generated from the sale of cooling equipment designed to reduce product temperature after baking, drying, or coating to maintain product quality and prepare it for packaging.
Others
The segment captures revenue generated from the sale of other pet food processing equipment, including conveying, grinding, extrusion support, cutting, sieving, and ancillary processing systems used across pet food manufacturing facilities.
Segment - Form
Revenue Capture Definition
Wet
The segment captures revenue generated from the sale of pet food processing equipment specifically designed for the production of wet pet food, including mixers, cookers, fillers, sterilization systems, and related processing machinery.
Dry
The segment captures revenue generated from the sale of pet food processing equipment used in the production of dry pet food, including extrusion, drying, coating, cooling, and associated processing systems for kibble manufacturing.
Estimation Model
Layer Name
Key Question
Description
Pet Food Production Demand Layer
Where is pet food processing equipment required?
Analyze demand across dry pet food, wet pet food, treats, and specialty pet food manufacturing facilities. Assess pet food production volumes, product mix, processing requirements, and manufacturing capacity to establish the addressable demand for pet food processing equipment.
Manufacturing Capacity Expansion Layer
Where is new equipment demand being created?
Evaluate investments in pet food manufacturing plants, production line expansions, automation initiatives, and facility modernization. Assess greenfield projects, capacity additions, and replacement of aging processing equipment that drive procurement of new pet food processing machinery.
Product Adoption Layer
Which processing equipment is being deployed?
Segment demand by equipment type, processing stage, product form (dry and wet), and end-use application. Apply adoption rates based on production capacity, product formulation, automation level, energy efficiency, hygiene standards, and processing requirements. Assess the increasing adoption of integrated, automated, and high-throughput processing systems to improve production efficiency and product consistency.
Revenue Generation Layer
How much market revenue is generated?
Estimate annual shipments of pet food processing equipment by equipment type, product form, application, and region. Quantify revenues generated exclusively from the sale of new pet food processing equipment supplied to pet food manufacturers and contract processors. The scope excludes installation, maintenance, spare parts, consumables, refurbishment, and aftermarket services.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Competitive Benchmarking
Detailed benchmarking of leading pet food processing equipment manufacturers based on product portfolio, automation capabilities, energy efficiency, regional presence, and strategic partnerships.
Enable competitive intelligence and technology benchmarking. Support product positioning, partnership evaluation, and innovation strategy development. Assist stakeholders in identifying market leaders and competitive gaps.
Regional Segmentation
Detailed market estimates and forecasts for the Pet Food Processing Market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. Country-level demand analysis covering dry pet food, wet pet food, treats, specialty nutrition products, and premium pet food applications.
Identify high-growth regional markets and pet ownership trends. Support regional expansion planning, distributor network optimization, and demand forecasting.
Opportunity assessment
Identification of emerging growth opportunities driven by rising pet humanization trends, premium pet nutrition demand, customized pet diets, automation in food processing, and increasing investments in pet food manufacturing facilities.
Prioritize high-growth applications and investment opportunities. Support innovation roadmap development and long-term strategic planning.
Frequently Asked Questions About This Report
Based on equipment type, the forming segment led the market with the largest revenue share of 30.9% in 2025.
Based on form, the dry segment led the market with the largest revenue share of 71.1% in 2025
The wet pet food segment is expected to witness the highest growth rate in the pet food processing market, registering a CAGR of 6.7% from 2026 to 2033.
The coating equipment segment is expected to witness the highest growth rate in the pet food processing market, registering a CAGR of 7.1% from 2026 to 2033.
North America dominated the pet food processing market with the largest revenue share of 33.7% in 2025
The global pet food processing market size was estimated at USD 5.9 billion in 2025 and is projected to grow from USD 6.3 billion in 2026 .
The global pet food processing market is expected to grow at a compound annual growth rate of 6.0% from 2026 to 2033 to reach USD 9.4 billion by 2033.
Some key players operating in the pet food processing market include ANDRITZ, GEA Group, Buhler Holding AG, The Middleby Corporation, Baker Perkins LTD., Precision Food Innovations, Clextral SAS, Reading Bakery Systems, Mepaco Group, Precision Food Innovations, F.N. Smith Corporation, and Selo.
Key factors that are driving the market growth include increasing demand for specialized and premium food products on account of the growing inclination of pet owners towards purchasing products that offer superior health benefits.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


